Small Cap Value Report (Mon 9 Sept 2024) - BBSN, SRC, CCR

Good morning from Paul & Graham!
That's it for today, see you tomorrow!
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
** New SCVR summary spreadsheet for calendar 2024 ** This is the live one! (updated 6/9/2024)
Archive - SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia.
Companies Reporting
Summaries
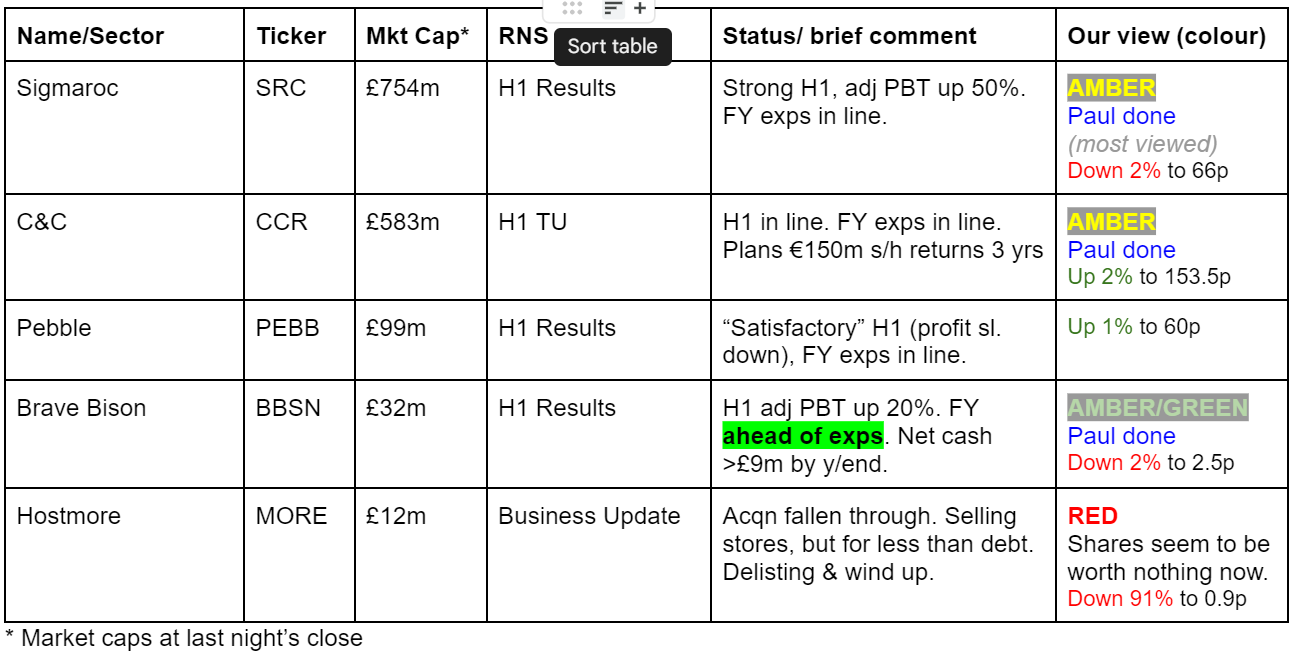
Brave Bison (LON:BBSN) - up 2% to 2.6p (£34m) - H1 Results - Paul - AMBER/GREEN
A strong result for H1, and ahead of expectations for FY 12/2024. However, there's little organic growth, so this looks more about cost control than growth. Sound balance sheet with plenty of net cash, expected to rise to >£9m by year end. I still like it, but shift down from green to AMBER/GREEN, due to the lack of any significant organic growth. Low tax charges seem to be flattering EPS.
Sigmaroc (LON:SRC) - down 5% to 64p (£716m) - H1 Results - Paul - AMBER
Rapid revenue, and good profit growth from this consolidator of European lime quarries. Debt has soared from its latest deals, but seems well within the bank covenants. Very capital-intensive business, as you would expect from quarrying & processing minerals. An unfamiliar sector, so this has to go in my don't know tray, with another AMBER.
C&C (LON:CCR) - up 2% to 153.7p (£595m) - H1 Trading Update - Paul - AMBER
H1 performance has been in line with expectations, and FY guidance confirmed. Reaffirms shareholder returns of E150m over next 3 years. Plan is to raise margins in future years. Overall it looks OK, low margin business in a competitive sector, so doesn't madly interest me.
Paul’s Section:
C&C (LON:CCR)
Up 2% to 153.7p (£595m) - H1 Trading Update - Paul - AMBER
Dublin-headquartered drinks group has performed in line with expectations in H1 -
“Dublin, London, 9 September 2024: C&C Group plc ('C&C' or the 'Group') announces that earnings in the first half of the financial year to 31 August 2024 have been in line with expectations…
Underlying Operating Profit is expected in the range of €39m-€41m, in line with our expectations, principally reflecting the phased rebuilding of our Distribution business profitability following last year's ERP disruption.”
More detail is given about the different brands and business units which I would summarise as: mixed.
Outlook -
“While current market conditions remain challenging, improving efficiencies, business simplification, winning customers and brand distribution remain our top priorities. We remain confident on achieving our operating profit target for the current financial year and making progress towards the operating profit target of €100m by FY2027.”
Shareholder returns - uses the word “reaffirms”, so doesn’t sound price-sensitive info -
“The Board reaffirms its intention to distribute at least €150million to shareholders over three years while maintaining the Group's financial leverage target of approximately 1x EBITDA on a pre-IFRS16 basis. The second €15m tranche of our share buyback programme will commence today, 9 September 2024.”
Paul’s opinion - it looks an OK business, nothing remarkable really - eking out quite low margins from selling cider and other drinks in competitive markets.
Checking my previous notes, I was amber before, and flagged accounting problems on 7/6/2024 which caused the CEO to resign (as he had been previously CFO when the problems happened). Shares today are about the same price as then, so the market seemed to agree with my assessment that those issues were not very important.
Broker forecasts have been dropping steadily for CCR, and it talks about some difficult markets. So I can’t muster much enthusiasm for this share I’m afraid. The forward PER of 13.2x looks about right to me, once you factor in the net debt (not excessive though). Divis are OK at 4.2% yield, plus buybacks.
It’s got to be another AMBER from me - which is OK, bear in mind that our performance stats show ambers collectively do well, only slightly below amber/greens. So I do urge people to look at everything from amber upwards.
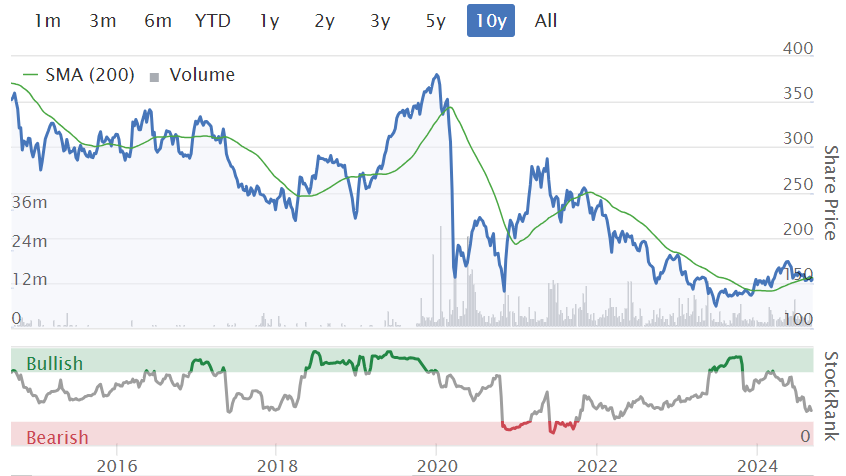
The 10 year chart shows a poor long-term track record I'm afraid. So why would that suddenly change?
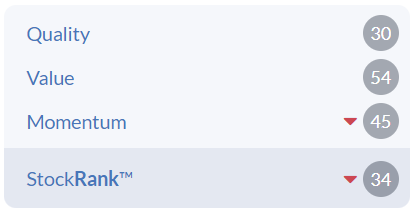
Stockopedia doesn't like it, with a low StockRank. Although I note that the negative quality scores come from exceptional losses booked in last year's accounts.
Sigmaroc (LON:SRC)
Down 5% to 64p (£716m) - H1 Results - Paul - AMBER
SigmaRoc, the European lime and minerals group, announces unaudited results for the six months ended 30 June 2024 ('H1 2024').
We don’t usually cover things in the natural resources sector here, but I started looking at SRC earlier this year, so might as well carry on. It’s buying up lime & limestone quarries, and this seems to be used in numerous sectors - agriculture, building products, and some environmental things like producing batteries, and other industrial uses.
Previously our thoughts on SRC were -
12/4/2024 - AMBER at 64p - AGM TU - In line Q1 2024 trading. Lot of acquisitions, but both share count and debt have risen significantly.
30/7/2024 - AMBER at 69p - H1 TU - ahead of exps, but FY 12/2024 exps unchanged.
H1 results to 30/6/2024 are out today, and look pretty good (as indicated previously) -
“Strong first half performance underpins confidence in our full year expectations”
Some numbers for H1 -
Revenue up 60% to £469m
Improved EBITDA margin rises 240bps to 21.3%, and EBITDA up 82% to £100m
Adj PBT up 50% to £49.1m
Adj EPS down 20% to 3.18p
Net debt rockets 190% to £534m (incl IFRS 16 leases of £34m), so £499m net bank debt (mainly Santander).
That’s a huge increase in debt, as I flagged last time. It again raises the question of whether these acquisitions are adding shareholder value, given that finance charges are shooting up from debt soaring, and adj EPS actually fell. These are the adjusted numbers too, presenting the most favourable picture they can.
It also provides pro forma numbers, which show the run rate of revenue & profit if acquisitions had been included for the full year. This comes out at a higher adj EPS of 4.27p - if we double this for a full year, then 8.5p = PER 7.5x - not that cheap when you consider net bank debt is 70% of the market cap.
Balance sheet - huge fixed assets of £1.25bn, plus growing intangibles of £436m, funded by over £600m of gross debt.
For me the high debt makes this close to uninvestable. Although the ratio is not dangerous, with the covenant at 3.95x, and actuals being well below that -
“Covenant Leverage at 2.57x with pro-forma5 leverage 2.29x, on target to close the year below 2.3x”
Outlook -
“Trading conditions in Europe present both head and tailwinds which the Board is actively managing. Industrial minerals will see areas of outperformance and possible challenges in relation to expected softness in automotive demand. Environmental markets have been consistently strong in the food and agricultural segments, with weather-related pockets of lower demand in power generation. A rebound in residential construction has not yet materialised given prevailing high interest rates and relatively low new planning applications although we are well placed for market recovery.
The Board remains confident in the Group's ability to deliver on the integration of the Polish assets, and to continue to build on SigmaRoc's position as a European leader in lime and limestone.
The Board's current outlook for FY24 remains unchanged with EBITDA in line with consensus1.
1. Consensus expectations for SigmaRoc, being the average of forecasts for the year ending 31 December 2024 provided by Analysts covering the Company, are revenue of £1,060.0m and underlying EBITDA of £219.3m.
Synergies should mean further improvement in EBITDA margins, assuming everything else remains the same -
“Our synergy program, initially targeting €30m-€60m by 2027, has been increased to €35m to €60m, even before allowing for potential benefits from the Polish lime business. We are now targeting €15m and €25m to be delivered in 2025 and 2026 respectively, rising to €35m in 2027. We expect to report further progress following the integration of the Polish assets.”
Paul’s opinion - where do we start with this? I know literally nothing about lime, its markets, or the competition, etc. So I don’t have any confidence that I would be able to pick winning shares in this sector.
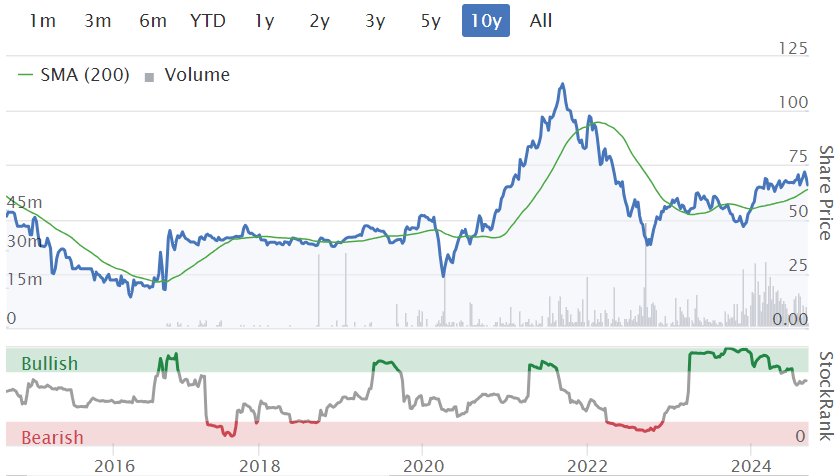
SRC has grown rapidly from repeated acquisitions, building a £1bn+ revenues group from almost nothing, but that’s been done by issuing a lot of new shares, and taking on c.£500m in net bank debt, delivering very little share price appreciation in 10 years - probably a negative return if we factor in 10 years' inflation. And of course, no divis paid.
It stands to reason that construction, infrastructure, and industrial demand in Europe could pick up as (hopefully) economies recover from the twin shocks of the pandemic, and energy crisis.
This is a long shot, but do we have any lime industry experts in the house who can give a more informed view on SRC and its sector?
My inspection of the numbers brings me to a conclusion that it’s a capital-intensive business, with heavy ongoing capex. After paying finance charges too, there’s nothing left for shareholders, so no divis. The hope being that once it’s stopped the rapid series of acquisitions, then there could be a strongly cash generative business that can reduce debt, and start paying divis.
There’s no way I can assess its future prospects, so I have little choice other than to stick at AMBER - which in this case is a don’t know. My main concern is the scale of the net debt, but it’s not dangerous providing EBITDA holds up at levels keeping it well within the bank covenants. If something untoward were to happen, then debt might become an issue.
The only lime I know about is the stuff we squeeze into our cocktails, so I'll leave this share for someone else.
Brave Bison (LON:BBSN)
Up 2% to 2.6p (£34m) - H1 Results - Paul - AMBER/GREEN
Both Graham and I have looked at BBSN earlier this year, and in both cases we viewed it positively, with GREEN.
BBSN tried to launch a takeover for Mission (LON:TMG) earlier this year, but was thwarted by TMG management, who declined a mostly paper offer, and refused to provide access for due diligence. So BBSN withdrew.
Moving on to today’s news -
“Brave Bison, the digital advertising and technology services company, today reports its unaudited interim results for the six months ended 30 June 2024.”
Positive headlines -
“20% increase in adjusted profit before tax
FY24 trading ahead of market expectations”
Although note that the 20% profit increase has all come from margins/costs, there’s no top line revenue growth -
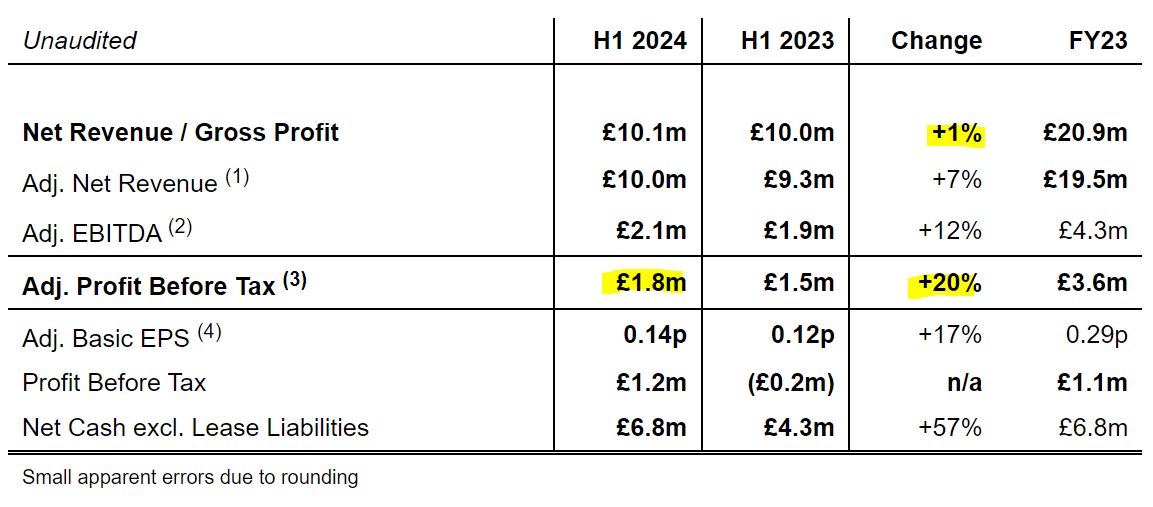
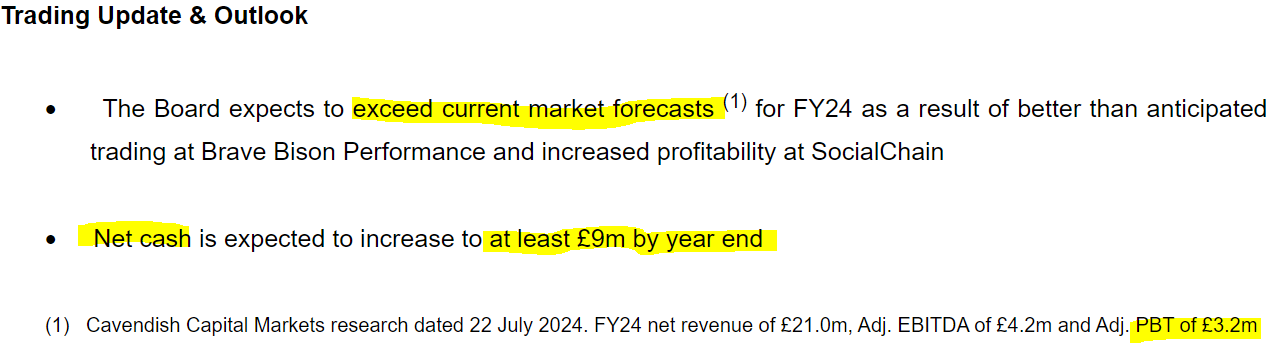
Broker upgrade - Cavendish ups FY 12/2024 from adj PBT of £3.2m, to £3.7m, but this is based on no change to forecast revenue of £21.0m.
New forecast for FY 12/2025 is a modest increase to £21.7m revenue, and slightly higher at £3.8m adj PBT (0.28p adj EPS).
My problem with this is that improving margins through cost control is a one-off gain. There needs to be top line growth, which seems to be lacking here. So it’s actually a lot less exciting than it originally looked from the headlines.
Although it says there has been some growth, masked by shutting down US operations -
“Brave Bison did not renew a number of large, low margin / loss-making client contracts serviced from New York and has mothballed operations in the US. Excluding these mothballed operations, net revenue grew by 7% year-on-year on a like-for-like basis”
TMG aborted acquisition - pleasingly, they only spent £33k in costs, so no harm done, because the due diligence gravy train for advisers didn’t leave the station, being refused access by TMG.
With large retained previous losses, it looks as if BBSN might be benefiting from a low or negative tax charge, which boosts EPS. So that needs careful checking, as EPS could drop once normalised tax charges are incurred.
Outlook -
Balance sheet - looks good. I’ll eliminate £14.0m in goodwill and deferred tax assets & liabilities, so that takes NAV down from £20.0m to £6.0m - which is adequate for a people business with modest physical fixed assets of £2.2m.
Net cash is healthy at £6.7m, and it says this will go up to over £9m by year end.
Cashflow statement - not very good, because profits were sucked into increased working capital. Something similar happened last year in H1, but it reversed in H2, so let’s hope a similar outcome happens this year. The company sounds confidence about cashflow, saying its net cash should rise to >£9.0m by year end, so that will need checking when the FY figures come out in spring 2025. I don’t see any cause for alarm, it’s fairly normal for working capital to fluctuate.
Paul’s opinion - this is a good performance from BBSN, although it’s looking as if the revenue & profit growth of recent years is now reducing. Growth has been previously fuelled by acquisitions, but that’s also meant big increases in the share count, from 613m average in 2020, to 1.29bn today. I think investors are less excited about digital advertising agencies these days, as the seemingly limitless growth potential of a few years ago has changed to it being a more mainstream activity now. Look at what a disaster Sir Martin Sorrell’s debt-fuelled acquisition frenzy turned out to be at S4 Capital (LON:SFOR).
BBSN is trading fairly well, and has sound finances, with a forward PER of only about 9.0x, although I think earnings are being flattered with low or negative tax charges. Normalising corporation tax to 25%, for 2024 forecast, I get 0.215p adj EPS, which gives a PER of 12.1x, not quite so cheap, but still reasonably-priced.
It’s an ahead of expectations update, and by year end there should be over a quarter of the market cap in net cash. Hence this share remains attractive I think. It’s reasonably priced now, and is really a bet on management using the cash pile (and maybe some future borrowings?) wisely to make further acquisitions. Hence checking the background and previous experience/performance of management is likely to determine whether or not they know what they’re doing re acquisitions. We don’t want to see them making an expensive mistake. The proposal to acquire TMG was audacious, and made a lot of sense to me, but was rejected.
On balance I think shifting down a little to AMBER/GREEN makes sense for the time being. So still positive, but it doesn’t strike me as a compelling buy for me personally.
I’d also like to learn more about what the company actually does. Digital marketing is a large space with any number of competing companies, so what (if anything) makes BBSN stand out?
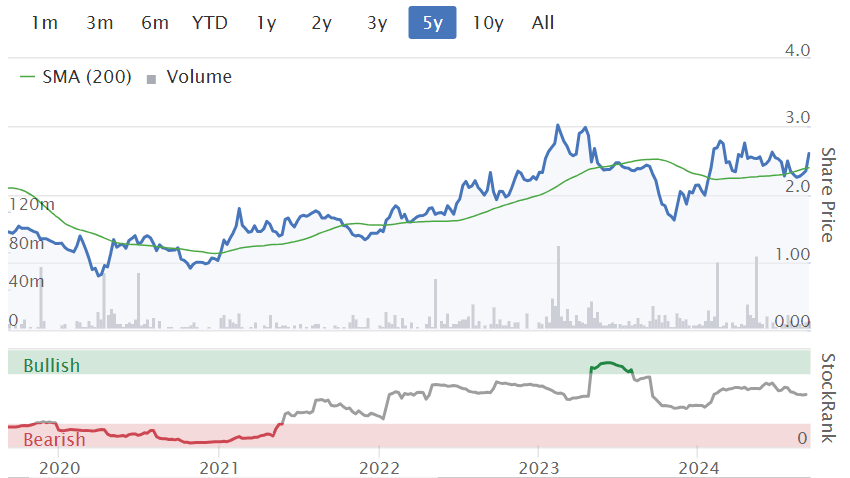
Shares have done quite well in recent years - and it currently has a middling StockRank of 57 -
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

71 comments
Warpaint London (LON:W7L) is a top 5 holding of mine. I try to make decisions based on business updates rather than price movements. Their interims are on Tuesday next week and hopefully Paul/Graham will cover them here.
Returning to XP Factory (LON:XPF) I listened to the Interview with ceo over the weekend and he was emphasising the fact that there had been no price increases on the games in their pursuit for growth in footfall which has occurred.
margins are very tight but ifthey could increase prices who knows.
I remain concerned for head office costs
Yes listened to the same podcast and thought he was credible and clear. Very much like the model they’ve got, visited their Cardiff branch last year and found it in need of investment - buckets catching drips everywhere so had to be careful where you placed your glass so as to not get an unwanted mixer. That experience (otherwise good) has left me on the fence. I wondered if this was one of their franchised venues or owner operated.
NWF (LON:NWF)
4 year low today on no recent news. Amber / Green back at the end of July. Too cheap or a problem that isn't in the public domain? We even had a moderate director buy recently.
NWF (LON:NWF) , yes interesting ChrisR. It's on my watchlist but thankfully not dipped my toe in yet. The share price has been super weak. Forecasts have been cut. On the surface it looks good, but maybe another forecast cut yet to come?
Median broker target price of 250p. I can't see anything overly negative in the last results, other than challenging general market conditions over the last year. Signed off with 'we remain confident about the Group's future prospects'.
Lymedale should be close to operating at full capacity. Puzzling one this, especially as the general market today was positive.
I don't hold, but I keep lowering the price alerts and they keep getting triggered. If it had a higher quality rank, I would have probably bitten.
Sigmaroc (LON:SRC) (I hold).
I can't help feeling Paul is being a little harsh on SRC - even if it's a 'dont know' on his part rather than a 'dont like'. I've been encouraged by the company's ability to manage their exposure to the very cyclical housing industry and indeed by the prospect of that cycle turning in their favour. I've also noted the many industry segments where lime is required and SRC's increasing exposure to the much steadier Industrial and Manufacturing segment. I tentatively suggest that while additional knowledge never hurts, its probably ok for the average investor not to know much more about lime than that!
The debt should surely only be a worry if there were significant risks in relation to their ability to pay it down quickly. The high levels of FCF are leading brokers to see rapid deleveraging, reducing from 2.6x to below 1.5x by the the end of FY26. This in turn leads them to set price targets in the range of 120-160p on the basis of DCF analysis and a PE of around 11x, comparable with competitors such as Breedon, despite their playing to fewer end markets. Perhaps I'm being a little naïve, swallowing the brokers' analysis, but it feels like the risk-reward balance is firmly in the company's favour.
Anybody else follow Simon Cawkwell/Vince Hit/Mark Watson-Mitchell on Master Investor? No posts there since 9th August. Hope everything's okay.
On holiday back in Autumn
10% drop today for Inspecs (LON:SPEC) . Results tomorrow, hoping this is not careless whispers as I hold.
Massive one near Liverpool Street also Paul that's worth a visit, but Spoons aside I look forward to the day when on the next bull run you cash out and install yourself as the new landlord of The Lord Aberconway on Liverpool Street.
It is often difficult to judge the quality of management particularly in small caps so i find that I am sensitive to small signals. In this regard today’s update from Brave Bison (LON:BBSN) there are some encouraging signs. As Paul has commented the Mission Group takeover proposal was dealt with cheaply, and unlike many managements there was no getting carried away with the bidding. Making a firm bid and then withdrawing it when the target tries to move it up, will stand them in good stead for the future. Also I am impressed that they were able to draw a line under the US business, too many firms go on throwing good money after bad at these expansions and get a sort of personal commitment to them rather than making it an unemotional business decision.
Alongside this there is the encouraging addition of some good new customers such as Primark, Sony Pictures and Greene King. I am continuing to hold
Hercules Site Services (LON:HERC) - despite tough markets HERC shares have doubled in 2024. They have also just boosted their balance sheet to take advantage of opportunities: in a new note today we raise our Fair Value to 60p/share. Read it here: https://www.equitydevelopment....
For those pondering Luke Johnson turning up as chairman at Revolution Bars (LON:RBG) today, I recommend reading this piece he wrote in the wake of the Patisserie Valerie debacle:
https://riskcapitalpartners.co...
I'm not trying to make any point here whatsoever (other than observing that we can all be victims of fraud regardless of our expertise, so diversify) & I have no personal exposure, just adding some human interest colour to our day.
Whilst nothing to do with the causes of the Patisserie Valeria situation, following an experienced hand like Luke Johnson is no guarantee - Hostmore (LON:MORE) had Harwood supporting and thinking it incredibly good value, but even they get things wrong.
An interesting read for us investors who lost money in the Patisserie Valerie fraud ! However, we shouldn’t feel too sorry for Luke Johnson. According to my research at the time, and I’m happy to be corrected, he and his wife as selling shareholders at the IPO in May 2014 received £23m. In June 2015 he sold 9.5% of his 48.1% holding at a share price of £3.12 netting £12.6m. I appreciate he lost a lot more when the fraud was discovered and the business failed despite his attempts to use his own money to save it. The real villains here are the directors charged with fraud by the SFO. Apparently the trial is scheduled for April 2026! In the meantime those directors are probably spending their ill gotten gains as fast as they can. Various LTIP options exercisable at 170p and 199p, granted shortly after IPO, were issued to certain directors and employees. These were exercised at fraudulently inflated share prices (well in excess of £3 ) netting millions for the directors involved . One assumes that none of money will find its way back to investors when the case eventually gets to trial - 8 years after the fraud was discovered and the shares were suspended
The unbelievably tardy application of justice in Patisserie Valerie contrasts sharply with the US. FTX went bust in November 2022, by December12 2022 Sam Bankman-Fried was charged with fraud, found guilty in December 2023 and started 25 years in jail in March 2024. And he had to cough up $11billion. Where do we mess this up?
Team Internet (LON:TIG) (I hold) has today announced a £19mm share buyback, which I believe to be a complete waste of effort, if they are trying to boost the share price. This company has spent a huge amount of time, energy and money not doing the one thing that would make a difference to their credibility (ask Paul for confirmation!). The market, rightly or wrongly, does not spend much time figuring out this company's prospects but it has always had cash flow concerns at the heart of comments, especially in relation to the level of borrowing. The company pleads that the borrowing is well able to handle its debt load - I believe this to be true, but it is clearly utterly irrelevant to market conviction. The company paid a small dividend - the market was not looking for it, and could care less, (and it is a choice which lowers cash allocation flexibility for the future). It has done buybacks to use up cash - the market has little interest in their choice of cash allocation at this stage of the company's development.
The company needs to direct all its spare cash to bringing down debt - absolutely nothing else makes any difference to the market and it baffles me as to why this is not apparently understood. The only possible answer (and I don't like it ) is that buybacks give a subtle way for Kestrel to increase its holding without a issue of an RNS, at least I think that is the way the law works.
BRBY Just a quick mention because it happens to have caught my eye. Shares dropped 5% today to 572p, making its lowest valuation since Nov 2009. Barclays analysts downgraded it.
I was also watching a vid which said that BRBY had considerable negative employee sentiment, implying a bearish outlook.
Burberry (LON:BRBY) - (perhaps unsurprisingly) Boston Consulting are currently all over them doing a massive project to restore profitability
I listened to a podcast over the weekend (there are other podcasts than Paul’s altho possibly not as good :)) interviewing Nick Train, he was non committal re Burberry (LON:BRBY) and was waiting until speaking with new management which was due to be this week sometime, that’ll be an interesting result. Presumably he can buy more at this level ,as the value in his fund is less, if new management impress or if he’s not impressed then Harry honkers and he’s out.
Dear Ox 2906. What was the name of the Podcast interviewing Nick Train?
AJ Bell Money & Markets
BRBY Following-up a little ...
On 7 July 2024, BRBY had a staff meeting over Zoom saying that impacted employees would either face redundancy or reapply for their positions. I can't imagine that going down well.
I'm not sure how that fits in with UK employment law. Seems a little iffy to make staff reapply for their positions.
More generally, I saw a vid covering luxury goods.
In terms of cyclicality of luxury brands, one should expect that in a 10-year period, there will be 7 years of robust growth, 2 years of so-so growth, and 1 tough year (in a recession).
There are 3 driving forces behind luxury:
1. signalling of status
2. "Womenomics". Women influence the majority of spending decisions, and their influence will grow. There are more women working, their wages are higher and the gender pay gap is narrowing. Marriage rates are falling, the median age of married women is rising. Women also like to splurge out on luxury goods.
3. Asia is likely to increase in significance. It is expected that Asia Asia will contribhute 55% to global growth over the next decade. Incomes are expected to rise. There are expected to be 3.5b Asians in the middle class by 2030, compared to 1.4b in 2015.
Hope you all find that interesting.Redundancy/reapplying for remaining roles is all part of usual UK employment law.
When you want to cut headcount due to trading conditions, you identify the "roles" and "numbers of" that need to be downsized.
ie - lets say in the Finance team, you currently have 26 junior FP&A analysts. You want to rightsize to 15.
You then issue notice of redundancy to ALL 26 junior FP&A analysts. You give them a choice; either go through an application and interview process for the remaining 15 positions, or they can immediately accept the redundancy package.
The company should then fairly evaluate all applicants for those 15 roles. Once they have selected their 15, everyone leftover (from the 26) gets offered a redundancy package to leave the company.
In addition, those that are given notice of redundancy, are allowed to apply for any other internal role too.
Meh, I'm not so sure. I had a look at the Wikipedia page for for UK redundancy law. https://en.wikipedia.org/wiki/...
Section 139 of the Employment Rights Act 1996 defines the two situations in which a redundancy may occur:
This is sorta my understanding from my accountancy days before the 1990s, too. To simplify, if you make someone redundant, it means that the position is no longer needed by the company. So if you sack someone and make them reapply for their job, logically the position is still required. So it's not redundancy, even if it's called redundancy.
No doubt they would have consulted their legal department, but offhand, I'd say it was wrongful dismissal.
I think the issue is that they are applying for a similar job rather than their own. Even if the JD is the same. Clearly 26 into 15 doesn't go. Personally the employment terms will be the same
Sigmaroc (LON:SRC) an AIM stock and well within the size category until recently. However should still be interesting to readers/contributors here.
Reported Ints today and clearly a little disappointing because some volumes softer and SP fell 2%+ though full year guidance unchanged.
Any thoughts Paul/Graham other contributors. Work in progress with the recent take over of CRH (LON:CRH) European recent assets.
Just looking for some expert views. Warpaint London (LON:W7L) W7L, I had a big holding and decided to take profits as the graph was turning down a little. I am now considering going back in before results on 17th Sep. The 1 yr relative strength figure is very strong at 76.2% but the 1 month figure of -10.2% concerns me. Am I right to be concerned at this, is my question. Any views gratefully received. Charles
Hello cafcash49, re your comment on Warpaint London (LON:W7L) and now its gone up around 5-6% today. No reason that I can see, nor for the drop although profit taking. understandable with CGT muttering alive and well. I did write a review a few days ago of RNS's for the period Sept to Jan a year ago. No TU news before the Sept results, then a series of very positive TUs every couple of months after that. Very late year focussed - or was last time. Cant expect perhaps the same level of positives, but hopefully a similar pattern because many of gains in the major stores for Xmas and repeats after that, especially US based. We will see.
I also hold Warpaint London (LON:W7L) . I was not tempted to sell during the recent downturn - according to my spreadsheet at Friday close it was 15.3% below its high point. It is pretty normal for multibagger shares to experience dips - see Ed's multibagger webinar. I'm not Mystic Meg, but I see no reason to sell the share yet - there has been no bad news, so I hold in expectation of further rises.
Hello Charles, I also hold Warpaint London (LON:W7L) having first purchased at a price of 324 (which I thought was far too late to the party at the time) topped up on two other occasions and never sold. I am far from an expert but I have no plans to sell. I have noted the share struggles to go over 600 and hold and or increase over that price. My plan at the moment is hold but if the share price can push through 600 and keep going I will again top up with a large commitment. Wish I had a crystal ball!!
I also hold W7L and have for a long time, some concerns, but no plans to sell a, but any yet but as confused as others going forward, sorry nothing concrete to add
Hi cafcash49, looking at the chart Warpaint London (LON:W7L) is still well clear of the 30 week moving average (I use this as per Stan Weinstein) and is still in an uptrend. I think the recent knock has also been due to some of the US listed Make-up companies reporting soft trading, let's hope that is due to Warpaint taking market share! As others have stated nothing has changed for my reasons of investing, but I agree it is hard to see pullbacks and not ask yourself if something is up.
It seems Rua Life Sciences (LON:RUA) has bought a small French company out of administration on the request of a major customer. Financially it looks a good deal and could be very worthwhile medium term for Rua Life Sciences (LON:RUA) if they can understand one another
Quick question to whoever...in comments, how do I add a company name in blue as a Stockopedia link?
Thank you
Below the comment box is the following tip . So it's the @ Sign type that and a pop up box appears where you enter the share "ticker", as in BBSN for Brave Bison
Scroll down below the reply box and read the tip.
To put the company name in type @ and a box will pop up to put the company name or ticker in.
...and a reminder to all - as it says in the heading please put the company name in otherwise those who dont read in threaded mode won't have a clue what you are talking about.
Just put the @ symbol in first then start typing the company name. So if you type"@Diploma" you will get Diploma (LON:DPLM)
Here is the link to the show tonight and you will get 50% off with the code MM50
MelloMonday, 9th September 2024 – Mello Events
MelloMonday, 9th September 2024, 5.00pm - 8.30pm
Programme
5.00pm Interview with Rosemary Banyard, VT Downing Unique Opportunities, Fund Manager, Downing LLP
5:40pm Company presentation from Cohort plc
6.20pm Mello Autumn Events
6:30pm Company presentation from European Green Transition
7.00pm Educational Presentation
7:20pm BASH Panel featuring Damian Cannon and Mark Simpson (CAU)
Wow. Hostmore (LON:MORE) more like Toast(more). Well done to the team here for having this well flagged. Feels like the end of an era.
What happens to the TGI Fridays chain in the UK? I haven't been following the minutiae of the travails of Hostmore (LON:MORE) but it looks like by "winding up" it will go into an orderly insolvency process?
Hi Boon,
My understanding of this morning's RNS from Hostmore (LON:MORE) is they are going ahead with a sale of the restaurants to unknown buyer(s), but that this will only generate proceeds which are less than the bank debt.
Therefore that will leave an insolvent holding company, which is the bit that's being delisted and wound up.
Presumably, I imagine there will be some loss-making restaurants that buyers are not interested in buying. So these presumably go into administration, and become the landlords' problems.
A sad, but not surprising end, as the writing has been clearly on the wall here for some time, as we've flagged with our consistent RED reviews.
I wonder if the buyer(s) of the company owned sites will re-brand them, in order to avoid having to pay the frachisor to use the TGI Fridays name, which these days feels old & tired, and not worth paying a brand fee to use.
Regards, Paul.
HMRC and tax problems mostly stem from bad politics not an inability to form a strategy. HMRC need a lot more resources to support and investigate plus help from a massive legislative effort to simplify, digitise and update laws and support their enforcement but this hard for any Government to do.
Hiring more tax inspectors costs a lot upfront and the right wing press will go crazy and inevitably find individual cases of hardship caused by tax (My small business is going bust because....). However, many small businesses only survive or flourish because they don't pay the right tax. (This not to say many others do pay correctly, picking up an extra tax burden to compensate for those that don't in the process!)
So big companies and multi-nationals move money and have smart accountants with schemes to avoid taxes; small businesses avoid and evade taxes or frankly can't manage the complexity of compliance; politicians chose to focus on other issues - not many votes in tax collection.
The problem is clear. The solution is not.
Political parties always say they want to simplify things but every year the Red Book gets longer and longer. Radically reducing and simplifying tax rules would have dual effect of making life easier for tax payers and less for the tax inspector to check/query. Wholesale change for the better is probably cloud cuckoo land but taskingTreasury to find and bring an agreed number to Commons Select Committee every session might make a start.
Tax simplification is the answer such as fixed rate tax based on turnover for small business. The HRMC has a wealth of info to fix the rates for different types of businesses
Someone in HMRC is likely getting very excited at the idea of using AI to root out ....... tax returns. Ah lovely!
https://news.sky.com/story/mon...
Employees aged 18 to 24 are working from the office more than their older colleagues, a study has found.
Good move. You will never build your career and get your face known by working from home.
Exactly LG, in fact you might find you are replaced by a worker in a cheaper location also working from home.
Was always the way when I started working had to show willing
Brave Bison (LON:BBSN) loooking forward to your thoughts Paul. The Green bros appear to be delivering.
Sceptisism at "yet another didital marketing outfit" appears to be overdone.
FY to exceed. Cavendish upgrade. Appears to be too cheap now.
Norman Broadbent (LON:NBB) interim results out today.
Growth challenged by macro & strong H123 comparatives.
Recruitment companies are always a good bellwether, they say,
"While the timing of a recovery remains hard to predict, there are some positive signs beginning to emerge across the industry. Our average monthly retainer income in Q3 2024 is already slightly up on both Q1 and Q2 2024, in line with reports that the contraction of the labour market is easing."
Do joint us for today's 11am webinar. Register here.
Synectics (LON:SNX) signs an additional $3.2m contract to an existing customer. That’s about 6% of their current revenue and 10% of their market cap. Good news after the sad news the other week of their CEO Paul Webb passing away.
Synectics (LON:SNX) Shore Capital released a note
"We note that the vast majority of this contract is anticipated to be completed in FY25F. As a consequence, we make no changes to any of our forecasts, at this stage, but would highlight there is a high degree of underpinning to both this year and next, in our view."
Small businesses dodge £4.4bn of UK tax each year
Small businesses are responsible for the vast majority of tax evasion in the UK but HM Revenue & Customs does not have a strategy to combat the problem, according to the parliamentary spending watchdog.
https://archive.ph/wbsiV
I’m sure there’s plenty of evasion but there are many other reasons for underpayment - lack of awareness, lack of help and support from HMRC nor HMRC scrutiny and challenge (how many subscribers have ever been challenged by HMRC? This seems to happen most often when honestly disclose large gains or claim large losses and suddenly you find yourself subject to an “investigation”).
Tax Policy Associates have an interesting article trying to quantify the underlying causes and possible remedies for underpayment of taxes by smaller companies >>>>>>
https://taxpolicy.org.uk/2024/..
Yes sadly... just found out last week that I'm being investigated for the 2nd time in 3 years for large donations to charity... the worst part is that it takes a minimum of 4 months whilst they have your tax rebate sitting on deposit at 5% +...
Two of my friends were investigated when they, quite properly, disclosed 7-figure capital gains.
You then often need professional advice at your own expense.
The inconsistency is that claims for EIS relief - including for loss claims - I’m convinced are barely checked, even when they are in 6 figures.
I can identify with that one regarding Gift Aid. Plenty of useless correspondence with HMRC repeating questions that I'd already answered comprehensively.
In the end I got so fed up I printed of several years worth of my current account statements and posted the whole lot in.
Investigation was closed pretty quickly after that.
That must be the famous Monte Carlo strategy!
How do they know that £4.4bn has been lost in tax evasion?
Its like saying London transport is losing £2m in fare dodging every year. It has always puzzled me how people arrive at these figures?
Interesting podcast this weekend Paul, particularly your insights into OnlyFans - I have no idea how you came away from the site with your take on what it actually does, but it was hilarious nonetheless :-)
LOL glad it gave you a laugh! I need to polish up my Hyacinth Bucket impression though, that was lame. More than the usual dose of silliness in this week's podcast, but why not!!
Have you got the link for the bikinied girl working out by the pool, asking for a friend
Morning Paul, Keeping Up Appearances was the name of the programme you were searching for. Keep working on the voice, they might do a remake one day.
Had me chuckling too: also the image of you inspecting the crockery in the Mary Shelley and the reference to the Rugby players. Great stuff as always. Thank you.
Thanks ChrisHM!
Actually I'm up in London at the moment, and plan on mystery shopping the large new 'Spoons at Waterloo station - it's in that white elephant of a shopping/leisure area called The Sidings, which was previously the Eurostar terminal before they moved it to St Pancras. So I might take a short video and post it tomorrow.
Am having to leave London as we've had no broadband for 4 days - apparently some plonker crashed his car into the nearby green utilities box, so has taken out the local broadband. Hence today's SCVR is coming to you via a tethered hotspot on my my mobile phone, which is working remarkably well I have to say!
Regards, Paul.
By the bye , heard on The Times Radio a few days ago that the UK ranks quite low on its 4 & 5G mobile connectivity (circa 50th I believe). Shows how all the talk of productivity, and infrastructure investment seems fairly academic
Hi Paul I really enjoy your podcasts with the added spice of your dry English humour. I appreciate you are very busy, but quick review of the upcoming weeks results would be very helpful as a guide for weekend research