Small Cap Value Report (Monday 24 April 2023) - De-listings, MGP, MIND, LOK, CKT, SPSY, CARD, CNIC

Good morning from Paul (I'm back at work now) and Graham.
Mello Monday is tonight, starting at 17:00. There are 3 interesting companies reporting, that we've reported on here recently. Also a session on ChatGPT, and finally a panel discussion on the disastrous delisting of iEnergizer (LON:IBPO) so all very topical & interesting I think.
Delistings
Again this topic rears its ugly head. We often flag this here in the SCVRs as a sudden and brutal way that shareholder value can be destroyed, at least for small shareholders like us. I expect the tiniest companies, that have effectively failed in their business models, to delist, and frankly good riddance - I'd happily see several hundred micro caps disappear, and we largely ignore most of the obviously rubbish ones here at the SCVRs anyway. However, last week shocked everyone with a much larger company, iEnergizer (LON:IBPO) (over £500m market cap before the announcement, a lot less now), and highly profitable & dividend paying, suddenly announcing it was intending to delist, and it's a done deal given the CEO controls it with an 83% shareholding.
I was discussing IBPO with some investor friends over the weekend, and for me the conclusion is to reinforce my policy of not investing in any company where one individual has such extreme shareholder dominance (83% held by Anil Aggarwal). Or at least I would never invest in any AIM-listed company where such a ridiculous share ownership structure exists, because AIM has inadequate controls over the behaviour of a dominant shareholders. AIM allows companies to float with a clearly inadquate free float, and also allows the dominant shareholder to de-list any time they like, if they're above 75%, or can get there with the agreement of others. Surely we need a new rule to require at least 50% free float before companies are allowed to list on AIM? And maybe we should copy other international markets, where a dominant shareholder is restricted from voting in a delisting? Companies need to be forced to commit to a listing, even if it ceases to be convenient for a controlling shareholder.
However, this idea conflicts with my preference (following a lot of very successful investors) for family-run and controlled companies, which are often very good performers long-term. It was pointed out to me that both VP (LON:VP.) and Goodwin (LON:GDWN) are excellent companies, but have dominant individual or family shareholders. So does it boil down to whether or not we trust a dominant shareholder? VP & GDWN are however fully listed, not on AIM, so perhaps a full listing provides more protection? I haven't looked up the relevant rules, so if any readers are up to speed on the differences between a full listing, and an AIM listing, with regard to delisting, then please leave a comment.
Were there any warning signs at IBPO? Not really. It's been listed since 2010, and other than recent NED resignations, the dominant shareholder appears to have acted fairly (as far as I can tell) towards outside shareholders - with modest salaries & no share options I believe, and no dilution, it's had 190m shares in issue for the last 6 years, shown on the StockReport. So this delisting news appears to have come out of the blue, as a bombshell.
I also have a policy of not investing in AIM companies that operate overseas, as that has historically been a disaster area - with many overseas fraudsters deliberately choosing AIM to rip-off UK investors, since there won't be any consequences. Hence all the Chinese frauds on AIM - almost all of those that listed were blatant frauds. No capital punishment for fleecing UK investors though, they probably got a round of applause in China!
Which brings us back to IBPO. It doesn't look to me as if the 83% shareholder has done anything untoward. He's given it 13 years as a listed company on AIM, and has now decided the costs/hassle outweigh the benefits. In conclusion, I think the onus is on AIM to tighten its rules in this area - it must not allow dominant shareholders to list a tiny sliver of the equity and then delist whenever they like. As for us? It's just caveat emptor. Nobody is forced to buy any share, and personally I wouldn't go anywhere near any AIM share with a massively dominant controlling party/parties. IBPO just reinforces the importance of having this kind of rule governing our portfolios. Hindsight eh! Although we do tend to flag up if we see a very dominant controlling party in these SCVRs, and we'll redouble our efforts on that score, and ask readers to also flag any similar situations when they crop up here, so that we can all make informed decisions, being aware of the risks.
EDIT: Graham has also added his thoughts on delistings & takeover bids in his section below on Mind Gym (LON:MIND)
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Summaries
(with more detail in main sections below)
Medica (LON:MGP) - up 33% to 212p (£269m) - Paul - GREEN
An interesting company, has received a cash takeover bid at 33% premium, from IK Investment Partners (private equity). I consider below whether it’s enough to seal the deal? (maybe not, with only 20% support). This seems a good company, pity to see it potentially disappearing into private hands.
Mind Gym (LON:MIND) - up 0.8% to 64p (£64m) - Graham - AMBER -
Trading Update - in line. This corporate training provider is pleased with a strong H2 performance. All broker PBT estimates are unchanged. Has disappointed since the 2018 IPO, but at this valuation it’s more interesting than ever.
Lok'n Store (LON:LOK) - down 0.2% to 870p (£262m) - Graham - AMBER -
H1 results come out as expected and with a confident outlook statement for the year ahead. Higher rates have hurt property valuations but this remains an impressive founder-led business. Probably priced right.
Checkit (LON:CKT) - 28p (unchanged) (£30m) - Graham - RED -
H1 results are published which look in line with previously raised expectations. ARR is £11.5m and cash is £15m after around £9m was burned during the year. Potential for high rewards but these ones usually don’t work out.
Quick(ish) Comments
I’m struggling to get back up to speed today, after a week off, so let’s do some short sections to finish off -
Spectra Systems (LON:SPSY)
Down 13% to 160p - Paul - GREEN
News of the seemingly abrupt resignation of its CFO. No replacement has been found as yet, but the financial controller is stepping up to cover. I don’t have any particular insights over this, although as the 13% drop in share price today shows, some investors react negatively to CFOs in particular suddenly resigning. SPSY is a previous mystery share in my (Paul) podcast, so I have a favourable view of the company. Let’s hope nothing untoward is going on behind the scenes to trigger the CFO’s departure. I tend not to ask companies for more colour, as usually they just tell you any old garbage, to shut you up. After all, if something is wrong, they're not going to tell us, are they?!
Card Factory (LON:CARD)
Up 8% to 110.4p - Paul - GREEN
publication of accounts is delayed, announced today, moving from 25 April, to 3 May 2023. The reason? KPMG need more time to complete the audit, but it is stressed that this is routine, and a standard audit. Is this a concern to me? Actually not, because we’re seeing plenty of perfectly good companies say they need more time to complete audits - the accountancy firms are apparently short-staffed, presumably as the pandemic would have disrupted & delayed the usual flow of new graduate trainees each year? Don’t get me wrong, it’s not a good thing, but I’d say it’s understandable, providing we’re being told the complete truth of course. I see CARD as being a truthful company, so I’m not worried.
Why is the share price up today then? It’s because the slipped in a positive upward move in guidance for FY 1/2023, again. It’s now saying £463.4m revenues, and PBT of £52m+. Ignore EBITDA, as that’s a nonsense number of £112m.
This compares favourably with previous guidance (TU of 10 Jan 2023) of £48m PBT. So it looks as if the CFO has found an additional £4m profit down the back of the sofa after the year end - remember this audit adjustments, not improved trading. This suggests to me that policy on provisions, etc, could be nicely conservative. All good CFOs keep a bit of extra profit tucked away (creditors on the balance sheet), which can be released to the P&L as profit, to deliver a post year-end flourish! (or to cover up any mistakes that are identified during the audit sometimes! I’m speaking from experience here!). A lot of CFOs cheerfully admit they don't really understand IFRS 16, so adjustments there could boost or trim actual audited results.
Paul’s opinion - CARD is performing really well, and I’m delighted I included it in my runners-up watchlist for 2023 - where it’s the top-performing share, up 36% year-to-date. This list was 12 value/garp shares that almost made it onto my top 20 list here. They’re beating the small caps indices nicely, so as long as that remains the case, I’ll keep putting in the link here!!! ;-) If it all goes quiet, you’ll know something ghastly has happened to one of my picks! So far so good anyway.
I think CARD shareholders are on to a winner here. The finances are not completely sorted out yet, but that pales into insignificance given the strength of the P&L, and cash generation. Weak balance sheets are only a concern when those other measures are poor.
CentralNic (LON:CNIC)
Down 6% to 115p (£330m) - Paul - AMBER (almost red)
Q1 update today shows continued growth, and sounds upbeat saying, “the Directors remain confident that the Group will continue to trade at least in line with current market expectations.”
We’re told that a partnership with Microsoft is good news. Also something about ChatGPT.
Paul’s view - I’ve just reviewed the FY 12/2022 accounts, which we didn’t report on here previously. I just don’t like the numbers at all. In particular, how massive EBITDA actually turns into a negative lower down, at the profit after tax level. So all the profit above ($86m EBITDA) disappears by the time you reach the bottom. That scares me off, as I like clean accounts with no funnies, not a valuation that’s all based on adjustments.
Also the balance sheet is awful, with very big negative NTAV. Lots of cash, but lots more debt, so even though year end net debt seems reasonable, it looks window-dressed to me.
Staggering growth, but are profits sustainable? What happens when cookies are phased out? Tiny dividend yield suggests there isn’t much genuine cash generation to me.
It all mounts up to too many question marks, and a business model I don’t understand. Hence for me personally, it’s an avoid, but that’s just what suits me - you may understand it better, and be more bullish. The low PER is certainly superficially attractive. Good luck whatever you decide!
Paul's Section:
Medica (LON:MGP)
Recommended cash offer at 212p - £269m valuation
This share cropped up in a very interesting podcast with Ken Wooton, on Citywire, here - well worth a listen. I recall listening to it 2-3 weeks ago, as I’ve been catching up on my podcast backlog of listens, and being struck by what an interesting theme he’s identified - buying structural growth companies at modest valuations, as these are not only good investments, but also areas where private equity are looking for takeover bid candidates. He specifically mentioned Medica as an under-priced structural growth company. I got back to my holiday flat, did some research, and noted down Medica on my pad with green highlighter as “LOOKS QUITE GOOD”. Wootton pointed out that similar companies had been bought by private equity at up to twice Medica’s current valuation. My only concern was that deals done in 2021-2 might have been at over-valuations?
Today’s 33% premium, at 212p looks a fair, but not excessive bid.
It only has 20% support so far, and note that management has negligible shareholdings. So I suspect this bid might have to be raised to persuade enough shareholders to back it?
The quandary for private investors is whether to hold out for a better price, risking the loss of the bid premium if the bid falls through.
Paul’s opinion - in this case, if I held (unfortunately I didn’t buy any, but was tempted), I wouldn’t be selling any in the market at this stage. I think a higher bid looks a fairly decent possibility, given the quality of the company, and that I don’t think the bid from IK Investment Partners is generous enough at 212p. Medica share price peaked at more than 212p about 6 years ago, when the company was only about a third of its current revenue & profitability. So this bid looks to be opportunistic, trying to take advantage of depressed public market valuations right now.
Overall, I like the theme of finding undervalued structural growth companies - it’s a good way to invest, and is likely to see takeover bids, as private equity tend to look in that area (whereas they seem uninterested in cheap, ex-growth value shares).
I did mention Medica in a recent podcast this month actually, but can’t remember which episode. Pity we didn’t put anything much into the SCVRs about it though, I was limbering up to report on it at the next results.
What do holders think? Are you tempted to sell up now for a nice profit, or sit tight for a better bid? Or prepared to forego the 32% bid premium (or some of it anyway) if this bid falls through?
Once again, it’s a pity to see private equity picking off the higher quality companies, and all too often leaving us with the dross!
Graham’s Section:
Mind Gym (LON:MIND)
Share price: 64p (+0.8%)
Market cap: £64m
This is a “global provider of human capital and business improvement solutions”. In simple English, it’s a corporate training company.
This morning we have a full-year update for FY March 2023.
Key points:
Revenues in excess of £54.7m, up 12% (but only up 4% at constant FX).
H2 saw stronger growth than H1.
PBT “broadly in line with expectations”.
“Broadly in line” usually signifies a slight miss, but in this case the company’s broker has left its PBT estimates for every year unchanged.
These PBT estimates are £2.9m in FY 2023, £6.8m in FY 2024, and £7.9m in FY 2025.
Net cash at year-end was £7.6m, slightly ahead of expectations, and it has an undrawn £10m debt facility.
The Board are “confident” and describe performance as “robust”:
The significant framework agreements won in H1 FY23 contributed to Group performance in H2 FY23. The second half also saw the award of a large framework agreement with a global automotive manufacturer, which is initially expected to deliver at least £2m over the next 18 months. Revenues from these framework contracts are expected to continue into FY24 and beyond.
Graham’s view
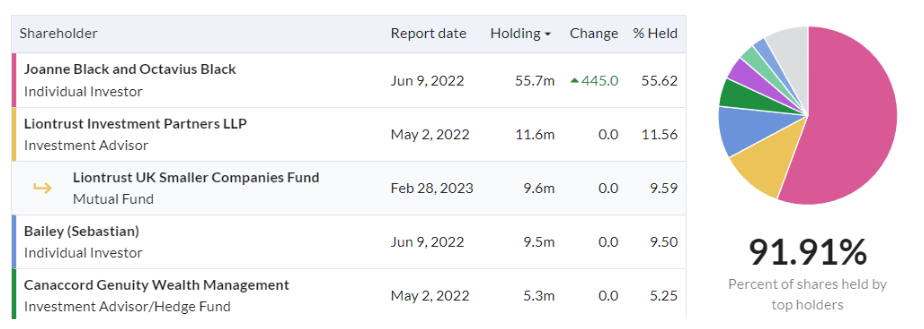
Given the events of the past week, it may be worth reminding everyone that this company has a majority shareholder in the form of the CEO, and the free float is very limited when you exclude the top holders:
For me, the question of a majority shareholder comes down to specific questions around who that shareholder is, their intentions and their abilities.
When I’ve been involved in companies that are majority owned by one individual, I’ve made a lot of effort to understand that person. Ideally, if it’s possible, I’d like to meet them.
There’s also the question of the company itself, separate from that individual, and the nature of my investment in it. Was I planning or hoping to sell my holding in it soon? If not, how important is the stock market listing?
Yes, liquidity is very valuable, but sometimes it’s not the most critical factor. There can be worse fates in life than owning shares in a private company! Especially if the risk surrounding the investment has already been managed through diversification, through not using too much leverage, etc.
For me, the most important factors are a) is the company still an attractive investment (whether it’s public or private), and b) do I still trust and like the people making the decisions, even after they make the decision to delist?
Sadly, there are many instances where poor-quality companies make the decision to delist because they’ve simply failed to make sufficient use of their listing, and now they can’t justify the expenses associated with it. These ones are often close to insolvency.
There are other instances where opportunistic majority shareholders use the stock market to sell an overpriced slice of their business in an IPO. They delist some time later, when the hype has died down and there is no further point to the listing.
But again, I would reiterate that the fundamental problems here are not the delistings per se. The problems are that the stocks were overvalued or worthless in the first place!
Let’s turn back to Mind Gym (LON:MIND) and remind ourselves of the state of play. It IPO’d in 2018 at a float price of 146p:
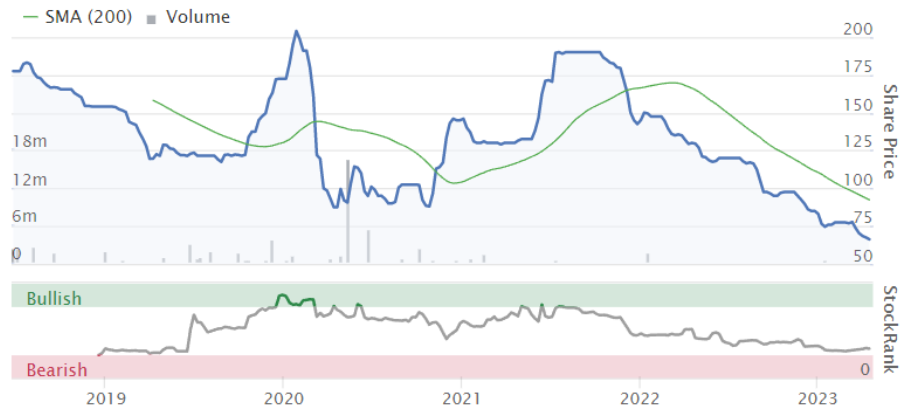
The shares are therefore down by over 50% in five years. Prior to Covid, they paid a few dividends, but not enough to write home about.
My rule is to assume that IPO valuations tend to be at least double fair value. With these shares down by more than half, I’m more open to the idea that they are approaching a reasonable number.
The P/E ratio has come back to a reasonable level:
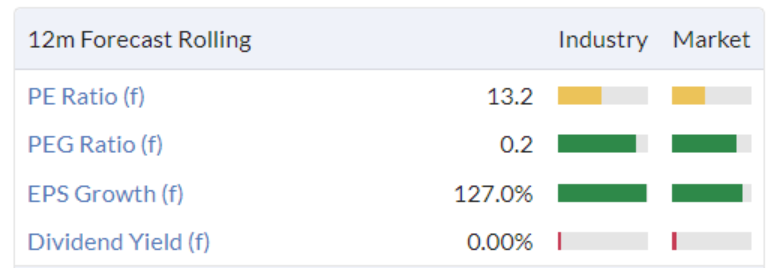
If it does hit the PBT estimates I mentioned above, then I believe we can start to think about it as a value stock.
Long-term revenue growth has been solid, despite a Covid interruption: from £37m in 2018 to £55m in 2023.
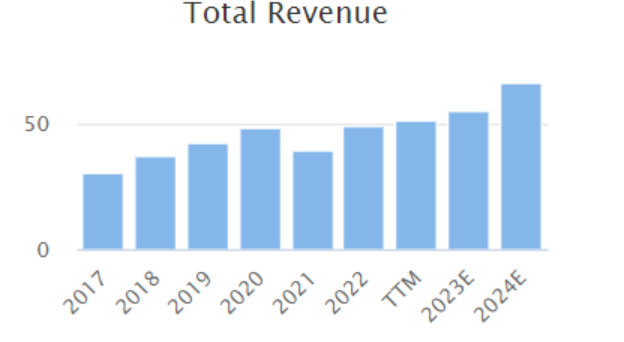
Browsing their corporate website, I am impressed by how they sell their training services - in a very modern and “scientific” way. I am also bullish on the general outlook for corporate training as a sector, although I’m unsure as to how to predict the winners in the sector.
On balance, I’m (Graham) going to stay neutral on this stock. It does look to have some interesting features, and is probably better value than it has ever been before. So it could be worth reviewing in greater detail.
Lok'n Store (LON:LOK)
Share price: 870p (-0.2%)
Market cap: £262m
I covered most of the bases surrounding this stock in February. That was at the time of an H1 update.
Today we have the corresponding H1 results for the period to January 2023.
This company operates in a niche with exciting growth prospects, has an excellent track record of growth and profitability, and is led by a committed founder-CEO with a 17% shareholding, so I think it’s worth keeping an eye on.
As a reminder, the key points about the H1 performance are:
Same-store occupied space +2.6%
Pricing up 9.2% per square foot
Same-store revenues +11.2% (even better than reported in the update?)
All of this is good and confirms the strong demand for the company’s storage space, but then adjusted operating profits come in at £5.24m, which is actually down 9.3%.
We can explain the fall in operating profits like this.
Firstly, despite the strong growth in same-store revenues, total revenues only grew by a few percentage points. This is due to the disposal of sites (a strategy that keeps the company’s gearing levels very low).
Secondly, we have an increase in operating costs, probably a large chunk of which is just general inflation. The net result is that adjusted EBITDA falls slightly, from £8m to £7.9m.
Then we have a slightly higher depreciation charge and a slightly higher charge relating to share-based compensation.
So in the end, we get a fall in adjusted operating profits.
Movement in property valuation: the company reports the change in property valuations “below the line”, i.e. in a separate section below the main part of the income statement.
For H1, they have reduced the fair value of their property portfolio by £16.1m, to reflect higher interest rates.
As a result, the valuation of freeholds and leaseholds is now £261m. Add in sites in development and the entire property portfolio is thought to be worth just below £300m (pre-tax - significant tax liabilities would be triggered on disposal!)
The balance sheet has limited gearing for a company of this type and the company calculates its LTV as 8.9%. The average cost of debt during the period was 4.13%.
Adjusted NAV per share is £9.15, down from £9.72 six months previously.
If you include the potential cost of deferred taxes that would be triggered in a liquidation, NAV per share is much lower at c. £6.45 (my own calculation).
Outlook
Early trading in a new Bedford store is “excellent”:
This underpins our confidence that our pipeline of new stores will add further to sales and earnings growth. We are managing the current cost increases and expect the rate of growth of costs to recede in the medium term… Our robust margins, strong balance sheet and flexible business model enables Lok'nStore to confidently look through the current external market turbulence.
Three other stores are opening this year, and the total pipeline will grow trading space by 32.5%. Sounds good.
Graham's view
I think that if this company went “on sale” it could make for a very nice buy-and-hold investment candidate.
At its current level, however, it’s trading near its adjusted NAV per share and at a significant premium to its actual NAV per share.
I still prefer it to many other property-related stocks, but the pricing reflects its quality.
If the shares were to drift lower for another year or two, I would get more interested:
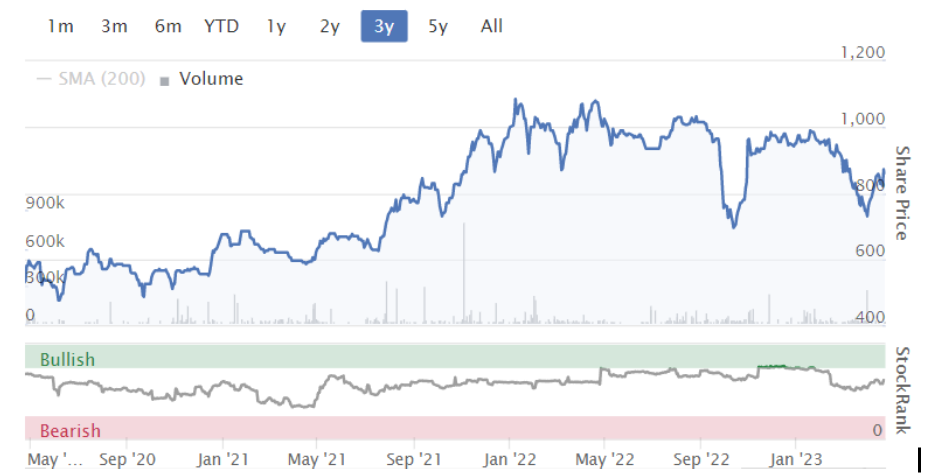
Checkit (LON:CKT)
Share price: 28p (unch.)
Market cap: £30m
This “intelligent operations platform for the deskless worker” says that its FY January 2023 results are ahead of expectations. However, it already announced that it was ahead of expectations in February, and the numbers haven’t changed since then.
Annualised recurring revenue is now £11.5m, having grown by 28%.
The phrase “path to profitability” is mentioned nine times in today’s results statements. The operating loss in FY 2023 is £12.4m, up from £8.5m in the prior year, and the cash burn was in the ballpark of £9m.
Cash at the year-end was £15m, so the clock is ticking on its path to profitability.
Outlook
FY24 has started well, with continued sales momentum in line with the Board's expectations. We continue to execute against our growth strategy and develop our technology, while progressing further operating efficiencies and accelerating our path to profitability.
The Board expects to meet market expectations for FY24 and remains confident that the Group is well positioned to deliver strong, sustainable organic growth in the years ahead.
Looking for more detail on how it’s going to achieve profitability, I find the following:
…we have weighed our growth ambitions with an increased emphasis on cost efficiency, as we execute an accelerated path to profitability. This is demonstrated by an increased gross margin of 63% (FY22: 54%), as well as operational cost savings across the business. Our cash burn peaked in H1 and has reduced by 17% in H2.
Graham's view
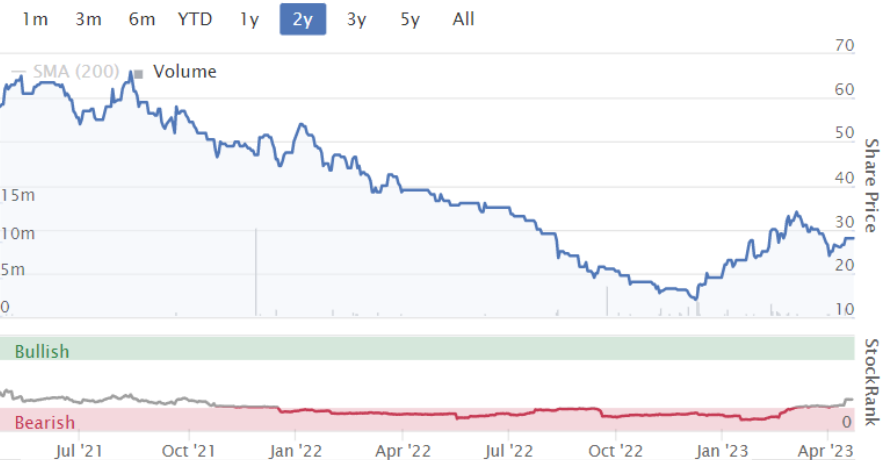
The ARR multiple (market cap divided by ARR) is pushing 3x, which is not an outrageous price to pay if you think this is a high-quality technology business.
Or if you’re willing to deduct cash from the market cap and use the enterprise value instead, then the ARR multiple is much lower. I do think that the cash balance could help to support this company’s market cap in the short-term. But I don’t have confidence that the cash balance is going to last, so I would use market cap rather than enterprise value when calculating earnings multiples.
Overall, this one has the appearance of a long-odds bet where the most likely outcome is another year, maybe two, of high cash burn. High risk, with the potential for high reward, but it gets the thumbs down from me.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

101 comments
I'm very late in getting round to looking at the Checkit (LON:CKT) results.
But there is a big red flag.
If so then that is a really anemic rate of growth. My guess is that they need to get to around £18.5m to start breaking even. ARR currently is £11.5m, so another +61% growth needs to be found. Before their cash pile runs out.
I think this is looking like a tall order... hard to see a £26m market cap.
CARD mention here in an interview I did with Paul Hill on Vox. Includes a number of stocks and a reference to Paul Scot's interview with Mike Raybould, CEO of PMP
https://www.youtube.com/watch?v=tgM9631JnT8&t=143s
Medica (LON:MGP) piqued my interest a year or so ago when it was highlighted in the Slater growth screen. After doing some further research it seemed a well run company and decided to invest. My strategy tends to be buy and hold (forever sometimes) - in part because I am not particularly good at selling. Glad that this has had a bid, but 20% premium seems a little on the low side given that it's a much better/bigger company now.
I held Medica for three years or so. About a fortnight back IC Alpha were very downbeat on it, the final sentence of the report saying "Expect little in terms of total shareholder return." I wasn't sure but decided to sell out and go elsewhere. Last week.
Hi
The last news announcement by Gulf Keystone Petroleum (LON:GKP) was 31 March saying shutdown would be about two weeks, nothing since, have checked both the company website and Stocko? Sorry late night question so will post again tomorrow am as well, just in case someone has something that has come via email or another source?
Thanks
Tommy
Oxford Instruments (LON:OXIG) is rising nicely (i hold) - but what is more important is that Spectris (LON:SXS) has risen even more. Spectris abandoned a bid in march last year at £31 due to Ukraine conflict uncertainty. Conflict is still on - but is the uncertainty the same?
Spectris' paper is worth about 40% more now. £27->38
I just wanted to say thank you to Rusty2 and Ken Mitchell for their link and information on the dividend information website.
It is much appreciated.
Tommy
Hi Tommy, could you dirct me to the dividend info website please... I appear to be unable to find Ken or Rusty2s link. TVM.
No problem
https://www.dividenddata.co.uk...
Cheers
Tommy
Thanks Tommy
I’m pleased you found it useful and it’s very good of you to post to say so.
Any thoughts on Gulf Marine Services (LON:GMS) results please Paul? You have previously indicated that you hold .
Medica (LON:MGP) now trading slightly above the cash offer of 212p at 214p to sell so it seems the market thinks there is a reasonable chance of an increased bid.
My guess is that IK Inv Partners may sweeten the bid towards 220/225p if no-one else comes out of the woodwork as I suspect that's likely to get them over the line. A bidding war could see 250-270p and I'd imagine there are PE houses out there running the rule over the economics now given the bid is no more than on the reasonable but stingy side.
Hi Paul
re your CentralNic (LON:CNIC) comment:
"Staggering growth, but are profits sustainable? What happens when cookies are phased out?"
The Zeus report on Research Tree today comments:
'CentralNic’s Online Marketing division (particularly TONIC) can source, qualify and deliver high conversion traffic to advertisers without the use of cookies.'
Not withstanding your commentary about the balance sheet, etc. I suspect that the difficulty in understanding this business, and in particular both the threats and opportunities to CNIC's business, does not help, particularly during a less optimistic time towards the technology sector.
Hi Matin VT
I would also just add to your answer to Paul that on the AGM today CentralNic (LON:CNIC) stated that this year would be the year of Net Profit. That does align with the forecasts shown on Stockopedia, so will be keeping a watch. I have been impressed with the InvestorMeet Companies meetings with CentralNIC and took an initial position today.
Card Factory (LON:CARD) Plenty to play for over the next few years: "According to a report by ResearchAndMarkets.com, the European Greeting Cards Market was valued at $11.5 billion in 2020 and is expected to reach $13.4 billion by 2026, growing at a CAGR of 2.4% during the forecast period. Germany is the largest market for greetings cards in Europe, followed by France, Italy, and Spain."
I'm annoyed with myself as was going to buy at 92p the other day, missed it and thought I'd wait for a slightly better opportunity. Will hold off now - it has had a good rise so I will wait for it to settle but accept I may miss the boat on it
Helpful comments on CentralNic (LON:CNIC) Paul. I haven't had a chance to look at the full accounts yet but do you, or anyone else, know if the EBITDA translating into a negative profit at the after tax level can be explained by acquisitions or whether the bulk of the problem are other issues?
Hi Patrick,
Re CentralNic (LON:CNIC) -
do you, or anyone else, know if the EBITDA translating into a negative profit at the after tax level can be explained by acquisitions or whether the bulk of the problem are other issues?
Every item is big. But to be fair, a large element is the amortisation of acquired intangibles (ie related to acquistions, of which CNIC has done a huge amount). There's also at least $5m share options charges each year. Then a hefty interest charge, due to large gross borrowings. Then there's also a hefty tax charge - I don't know why, maybe amortisation charges might be disallowable?
Overall, I'm not saying there's anything definitely wrong, just that I don't like the look of those numbers, just a personal opinion.
Regards, Paul.
Hi Paul, You make some excellent points, but surely it's about cash flow? Also, with less M&A ahead with a new focus on "shareholder returns", hence the share buyback, the introduction of the maiden dividend and debt reduction. It refinanced its debt in October on much better terms.
Mulberry (LON:MUL) As Graham mentioned SCVR 20.04.23 these shares are illiquid yet seemed quite positive.
"These shares rose 7% yesterday, in advance of today’s full-year trading update.
That might just be random white noise, however; the shares are illiquid as the company is 90% owned by the Ong family and by Mike Ashley’s Frasers (LON:FRAS). "
Is this one to stay clear of?
Research note on Shanta Gold (LON:SHG) (I hold) out from Tamesis on research tree following the mixed TU this morning. Target of 30p maintained, NAV of 41p @ gold price of $1800.
Re: Medica
I've held this for a couple of years and think it's a good company with much potential. I certainly won't be accepting the current 33% premium bid - opportunistic and doesn't represent the full value of the company.
Re Medica (LON:MGP. I held from start of 2020 but the shares traded sideways in a fairly narrow band for 2 years + when the Covid situation should have been good for their business model. I eventually threw the towel for a small loss in in July 2022 as couldn't see things improving. Yet again an example of my selling a share only to see someone come along a few months to a year later and make a takeover bid at a premium to my sale price. It seems to happen rather too often for shares I have held & sold. I am clearly not a good judge of an acquisition target!!
Card Factory (LON:CARD)
have just released this RNS , detailing a short delay to FY23 results due to KPMG needing more time but also an upgrade to previous guidance which is now REV £462.4 EBITDA at least £112m and PBT of at least £52m. Which is about a 10% increase in PBT. Looks good to me.
https://www.investegate.co.uk/...
Hi Paul. Medica (LON:MGP) I hold having bought on 06/03/2023 at 163.3p. I am currently resisting my strong urge to sell, because a better offer might be made. If the price continues to sit around the bid price, then I will sell. But if the price were to rise above the bid price, then I would hold on because the share price would be indicating that a better offer was likely.
Hi WarrantStar,
Well done you, good to hear you've made a nice (and fast!) profit on Medica (LON:MGP)
It's interesting to hear what readers are intending to do with their shares (i.e. wait for a better deal, sell in the market now to lock in a guaranteed profit). Everyone has to make their own decisions, based on our individual risk appetite, size of position, etc.
Although just to throw an idea into the pot, I personally quite like selling half. That way I can convince myself that it was a good decision whatever subsequently happens! Bid falls through? No problem, I sold half at a higher profit. Better bid comes in? No problem - I'll benefit from the higher bid, and I de-risked things along the way too.
As mentioned in the main report though, I think MGP is an excellent company, and the bid is not generous. So in this case my guess (and it's only a guess) is that there's probably a decent chance of a higher competing bid, and maybe even a bidding war up to say 250p?
Also it's a nice growth company, so would be a good share to hold, even if the bid falls through. As always though, just a personal opinion, based on fairly limited research by me! So ignore me, and do what feels best for you :-)
Regards, Paul.
Thanks Paul. I agree that selling half can be quite a good idea, especially when one is not sure how it will pan out. For the moment I will keep holding.
I sold Medica (LON:MGP) at a fraction below the offer price to realise a profit. However, if it falls through, I'll be buying back in - hopefully at a lower price than today.
Thanks for the report on Mind Gym (LON:MIND). I don't hold but keeping an eye on it. Was interested to see that 3 directors spent £1m on shares between them in Oct and Dec 2020. (Not sure what that tells us about them or the company.)
Medica (LON:MGP)
Have held for a year or so from around the 150p level so a 40% + dividend uplift in that time is ok but not exciting. I think the business is worth 240-270p so I think this is opportunistic.
Hoping for a counter bid (similar to Network recently) so not selling. If the deal didn't go through I'd hold it anyway.
Just a note but Private Equity has so much cash and so little good deal flow that private valuations are well in excess of public market valuations at the moment, hence why we are seeing so many takeovers. A bit worrying in a way as those quality companies are not being replaced on public markets at the same rate. On the plus side it does mean that other PE will likely be looking at Medica (LON:MGP) as PE firms are competing against each other.
Morning Paul
Although Kape Technologies (LON:KAPE) are no longer a small cap they are also now going to be taken private by Sagi. He originally had 54% of the equity but now has aquired and has commitments to get him to 76%. The price being paid is extremely low and opportunistic. The share price could easily be double and be OK. Whats galling is that there was a fund raise to aquire ExpressVPN at £3.35 in December 2021 and now he gets that business and the original for £2.90. We've only had one set of FY results in March including the enlarged business which transforms the Stockopedia stats. Very opportunistic of Sagi, but why oh why was the share price so supressed to give him that opportunity in the first place.
Bear market, especially for anything tech related.
key director sales back at £4 didn't help install confidence - if you know what is being discussed ... another lesson. Management saying one thing but doing another!
regarding Goodwin (LON:GDWN) and VP (LON:VP.) specifically and takeover more generally - the following applies (taken from https://insightplus.bakermcken...)
"Takeover bids in the UK are made by way of a contractual offer, which may be a voluntary offer or a mandatory offer, or by way of a statutory, court approved scheme of arrangement. Under a scheme of arrangement, a takeover can be effected by the passing of resolutions by the shareholders of the target company and with the approval of the court. A scheme requires the approval of a majority in numbermrepresenting 75% in value of the target shareholders voting on the necessary resolutions. However, once approved, all shareholders are bound by the scheme. A scheme is a process promoted and undertaken by the target, requiring the full co-operation of the target and cannot, therefore, be used in hostile situations.
The majority of takeover bids in the UK are implemented by way of a scheme of arrangement, as are the vast majority of take-private transactions because once the requisite 75% approval has been obtained the bidder acquires 100% from the scheme becoming effective. This eliminates the risk of minority shareholders that could, for example, challenge the re-registration of the target as a private limited company, which is essential for security to be granted to lenders."
Morning Paul,
Just to reply on Medica (LON:MGP. I have sold my small position this morning. Following an article in Shares magazine got my interest and then did my research using Stockopedia and watched the last results. I only took up my position exactly a week ago on the basis I would top up on any share price weakness. If the deal does not go through I will look to buy back in. Cheers
Sold mine for same reason.
Medica (LON:MGP) I was invested in this for a couple of years until I was told by someone who runs the Radiology department at a big university hospital that this company would eventually be put out of business by AI. The person in question had no axe to grind as they used the companies services quite happily. I think this explains why this share has always looked cheap and, after some initial enthusiasm, the share price has tracked sideways for a few years. I have no idea whether another bid will materialise but it's possible that the bidder may not be looking beyond a five year exit strategy and that there may not be any interest from other bidders. I sold several years ago at a small profit so my post isn't sour grapes - just a warning that this share has always appeared cheap because of concerns about it being overtaken by technology
does AIM actually employ anyone that promotes itself and explains its rules and virtues? I listen to lots of podcasts etc., watch lots of presentations etc., but I can't remember once in the last couple of years hearing something from one of their staff. Anyone know different?
I've seen the Aquis exchange tried something.
AIM put up someone senior to answer questions on a BBC radio programme after a series of frauds had raised serious concerns about the controls in the AIM market. His defence (as I remember it) was
1. you win some and you lose some
2. some companies fail
neither of which was an adequate response to the fact that the AIM companies being discussed were not company failures but frauds in which the reported results were pure inventions.
Does anyone remember the AIM listed Chinese company that disappeared completely without trace a few years ago. The explanation made by the company directors before they disappeared - all the company's accounting records disappeared when the van in which they were kept was stolen
which company was that?
Wai Van Go
Naibu, I think. I have never met with any AIM management team from outside of the UK, US or Ireland who I've considered trustworthy - this is just my opinion. If they are from outside the UK, then the first question is always "why list on AIM?"
There were lots "More than 80 Chinese enterprises have joined Aim since 2005 " 2015 extract from FT
I'm certain I was the ONLY commentator at the time who said AVOID ALL the Chinese AIM floats (frauds)
Also I was the commentator who wrote 29 articles pointing out the fraud at Globo - over many years - I saved it all - here is the link.
Medica (LON:MGP) Solid company with a good future IMV that I have held for some years. Slightly disappointed by the takeover but it nets me a decent profit, hence only slightly. I will not sell in the market therefore and will happily continue to hold should be bid fail. Sounds like it is pretty much a done deal unless a counter bid arises though.
Hi Monty9,
Re Medica (LON:MGP) takeover bid, you said -
Sounds like it is pretty much a done deal unless a counter bid arises though.
I'm not so sure. Today's announcement indicates only 20% support so far, which is quite low. Appendix 3 of today's announcement shows that the Directors who have agreed the deal collectively hold a negligible 0.3% of the company.
Only one institution, the largest holder, Gresham House Inv Mgt has agreed the deal, holding 19.7%.
This means that the other institutions have (I presume) refused to give an irrevocable undertaking to support this deal. It's usual for them to be taken inside, and asked to support a deal, which it looks like they've not done (at this stage anyway). Hence I suspect this deal may not be a done deal as yet. It depends on whether the institutions change their mind, and decide to back it. The way I see it, the "for sale" sign is now clearly up, and might attract other bidders.
Also note that "irrevocable" agreements to the deal cease to become irrevocable if someone else comes along and bids 222.6p+ for Medica.
So everything to play for here, I think. Hence why I think a higher bid is a distinct possibility!!
Regards, Paul.
Thank you Paul, encouraging. Disappointment reduces in the inverse ratio to the price!
There are times when I wish I could give two, three or four thumbs up to Paul for sharing his knowledge and thoughts. Today is one of them. Thank you Paul for making us a little wiser and big condolences to holders of IBPO.
Dear Santawani,
There are times that I could feast upon your lovely comments! How marvellous - thank you!
I'm so sorry if you were caught on IBPO. What a terrible situation.
Best wishes, Paul.
React (LON:REAT)
A combo of acquisitions and covid volatility obscure trends. But since the current management team took over old React business in 2019 they are on course to have doubled revenue in fy23. React was at £3.2m revenue in fy19, Fidelis acquired in Apr 21 had c.£3.3m annual revenue and LaddersFree acquired in May 22 had c.£3m annual revenue.
So simple arithmetic is £9.5m annual revenue from the three pieces. H1 23 they are reporting £9.3m. That's pretty impressive top line growth rate and its better than a rate of100% over 4 years given Fidelis acquired 2 years ago and LaddersFree 1 year ago.
Looking forward they need to prove either that through continued investment in growth (sales) they can keep the top line growing at a good clip or that significant operational leverage comes through to the bottom line. Do either of these things and the share price is too cheap...and if they can do both then its very cheap...and as the revenue grows to more significant scale they should also move beyond being 'too small' dead end micro cap to more respectable micro cap status which means off of a stub end p/e
I wonder why Aggarwal didn't start selling shares leading up to this over the past year, I can see from the director dealings the last time he bought/sold was in 2015? Surely he's just shot himself in the foot if he wanted to make an extremely profitable exit ?
I think Aggarwal may have used an IPO, if there was one, of his company on AIM to give it a massive kickstart and for no other reason than this.
I think this needs to be highlighted as an extremely important case study about pulling the wool over British investors eyes - I've done some more research on this firm - most of their offices are in India, not a single one in the UK, and listed in Guernsey, and most of the entirety of their products are "digital process management" - this one would have been extremely hard for the ordinary retail investor to spot as red flags given just how well it has hidden itself in its strong numbers, dividend etc. I would have certainly been susceptible to investing in this ...
iEnergizer (LON:IBPO) What Investors missed and it incluudes me was the appointment of NED both from Gurensey.Look at the list of their existing appointments.One for the mrmory bank.
Re iEnergizer (LON:IBPO) Aggarwal extracted all his value a few years back when he paid a huge dividend funded via a massive loan. It was clear to me at the time that this dividend was for the sole purpose of extracting value for the majority shareholder without disposing of his holding. It seemed such an unusual transaction to load the company up with debt solely to pay out a huge dividend that I resolved to steer clear
Do we know roughly how much that dividend he paid himself was ? - I can see a 64 mill director dealing near the IPO … still , i find it surprising he would not continue to extract money out over the past 7 years by selling shares …
50p
Re iEnergizer (LON:IBPO) in FY21 the company took on over £100 million of debt purely so that it could pay out a dividend of 49.40p to shareholders when the share price was around 220p. The main beneficiary of this largess was, of course, Mr Aggarwal. I was surprised at the time that PIs were so happy with this arrangement as it struck me then that this was an unusual transaction that significantly increased the risk of investing in the company. It also showed me for who's benefit the company was run - and it wasn't minority shareholders.
iEnergizer (LON:IBPO)
Were there any warning signs at IBPO? Not really. It's been listed since 2010, and other than recent NED resignations, the dominant shareholder appears to have acted fairly (as far as I can tell) towards outside shareholders - with modest salaries & no share options I believe, and no dilution...
Paul,
There was a problem with governance and dilution at IBPO. Aggarwal issued himself a substantial proportion of the company at a 78%+ discount. Disregard for the rights of others tends to be a perpetual personality trait. The below is from a comment [with additions] I made in SCVR 21.ii.22 which I linked to yesterday:
Here is a link to an RNS from the 7th July 2015. When such a large percentage of a company is owned by a dominant shareholder, private investors are not able to prevent this sort of thing. A 49% discounted placing exclusively to the CEO (NED at the time)/dominant shareholder...prevented me from wanting to become involved here...And then this happened RNS 17.viii.15: LINK
.....placing of 22,000,008 new ordinary shares of 1 pence each ("New Ordinary Shares") with EICR Cyprus Limited ("EICR") a company of which Mr Anil Aggarwal, Non-executive Director of the Company, is the ultimate shareholder.
The Placing Price represents a discount of approximately 78.72 per cent. to the closing price of 23.5 pence per share on 14 August 2015, (being the last practical date prior to the announcement of the Placing).
The Placing Shares will, when issued, rank equally in all respects with the existing ordinary shares and will represent approximately 11.57 per cent. of the entire issued share capital of the Company immediately following Admission.
In accordance with the relationship agreement entered into by the company, EICR, Mr Aggarwal and others at the time of IPO, this transaction was entered into at arms length and on commercial terms. The transaction represents continued confidence of EICR in the Company.
How interesting, thanks laurie.
I seem to recall that IBPO almost went bust a few years ago, and the chart confirms this - down to about 12p at one point, then a 40-bagger!
So maybe the CEO's placing was an emergency fundraise at the time?
iEnergizer (LON:IBPO)
I am guessing that the bank demanded a pre-payment on a debt facility; that was what was done with at least some of the cash. Yes, it looks like it was an emergency which may have made it difficult to find other investors. On the other hand, a 78% discount is quite extreme.
Morning Paul and Graham. Market not thrilled by CentralNic (LON:CNIC) announcing results would be “at least in line with expectations”. There’s no pleasing some people. Online marketing growth seems to have stalled, which may account for the lack of enthusiasm. I’d be grateful if you could take a look as this is one issue you have covered regularly in the past. Many thanks
I think you only need to look at google/facebook/amazon and others to see the current state of online marketing. The P/E p/FCF on this is very attractive in my opinion
CentralNic (LON:CNIC) I want to buy this but I couldn't get my head around why the forecast eps is 6* higher than any previously reported. I decided (no doubt wrongly!) that it was because the market didn't believe the forecasts.
CentralNic (LON:CNIC) I want to buy this but I couldn't get my head around why the forecast eps is 6* higher than any previously reported.
I’m confused by your statement, According to Refinitiv data, the forecast eps is only 6% higher than in FY22. For me, the fundamental investment case is based entirely around strong FCF generation, and an extremely attractive FCF yield.
CentralNic (LON:CNIC) I was thinking of buying around September when forecast was 16p (as per the "Print" drop-down in Stocko). Even now, unless I don't understand the column headings on Stocko, the estimate for 2023 (2023E) is 20.7, for 2022 the actual was 3.22. Everybody comes at investing in their own particular way, but for me the 50 year studies in What Works on Wall Street show that in the long run high relative strength plus 1) low price/sales or 2) high eps% increase are two of the best factors to look for.
The biggest factor seems to be some substantial director sells recently, although the individuals still hold a substantial percentage of the company.
Personally I remain a holder - it seems the recent level of growth (or near to it) will continue for some time yet and eventually that will be reflected fairly in the price.
CentralNic (LON:CNIC)
There is a note from Zeus on Research Tree which I must admit I'll need to find time to do some work on to see if I agree. But they are saying YoY absolute growth in Online Marketing gross profit started to fall in Q4 2022 and went negative in Q1 2023, which may be spooking the market.
I'm also beginning to wonder if some seasonality is showing through for the first time which was previously hidden by explosive growth and M&A.
Medica (LON:MGP)
Paul Hill came under some flack here last week but his videos can contain interesting points. Not long ago he talked with Ken Wotton of Gresham who said that MGP was trading at EV/EBITDA (the multiple PE buyers look at) of 9x and a close competitor had been bought at 15x so if the stock market doesn't re-rate the business to reflect the growth profile then..............
Vox Markets Fund Manager Series - Ken Wotton, Managing Director at Gresham House
Deserves to be on a PE of nine as its only a e-locum agency. Most of its business provided by a monopoly (the NHS). Has changed ownership more times than I've had hot dinners.
It's changed ownership once (in 2017 when it floated). Where are you seeing that it's changed ownership multiple times please?
Perhaps maillotapoisrouges never has hot dinners
RE: Medica (LON:MGP)
The point being, presumably, that they've just received a bid ... ?
https://www.investegate.co.uk/...
timarr
Medica (LON:MGP)
Yes, or rather that what he said (3 months ago) was somewhat prophetic. He goes on to say that as the largest shareholder if they weren't happy with the price they would say no but I see that for MGP they have given an irrevocable undertaking to accept.
Hi sharw,
I've just seen your comment, and funnily enough I flagged above in the main article a similar podcast (but with Citywire) that Ken Wootton did in Jan 2023, which sparked my interest in Medica. It was certainly a very shrewd call by Mr Wootton, so he looks a sensible investor, well worth listening to.
I flagged his podcast as being good, in one of my own podcasts earlier this month incidentally.
Regards, Paul.
Spectra Systems (LON:SPSY) . CFO resigns to 'explore other opportunities'. Have just quit SPSY too as am nervous if CFO quits. I remember an interview with the CEO and he said they couldn't have an AGM because they couldn't raise a forum' - always stuck in my mind of curious governance. Other than that it is a great company...
RE: Spectra Systems (LON:SPSY)
I sold recently. I couldn't understand the why the net interest received was so low based on the cash at hand. It's probably something to do with fixed term interest or something, but given how opaque the business I decided to move on.
timarr
Spectra Systems (LON:SPSY)
I've been a big fan for quite a while now.
However, I (regrettably?) sold out on Friday after finally receiving a long-awaited response from the broker about why the 2022 interest income had decreased ($40k in 2021 vs $17k in 2022) even though cash balances had increased ($16,775k in 2021 vs $17,496k in 2022).
They tried to explain the mismatch on the timing of FED interest rate changes, but it didn't really make sense to me given that FED rates started rising in Feb 2022.
The only possible explanation I could think of was that company cash was held on long (i.e. >12 months) fixed deposits. However, the 2021 Annual Report clearly states that cash is "highly liquid investment purchases with a maturity of 90 days or less."
I erred on the side of caution and sold.
A
However, I (regrettably?) sold out on Friday after finally receiving a long-awaited response from the broker about why the 2022 interest income had decreased ($40k in 2021 vs $17k in 2022) even though cash balances had increased ($16,775k in 2021 vs $17,496k in 2022).
Hi abtan,
I don’t really understand why there should be a causal relationship between the year end cash balance (and lets remember it’s the cash balance held on that day only), and the amount of interest earned over a 12 month period? You’d need to know much more about the profile of the cash balance over the year to draw any meaningful conclusion in that regard. The one thing we know about the business is that incoming cash is inherently lumpy given the nature of the contracts it signs.
All the best, Si
RE: Spectra Systems (LON:SPSY)
I don’t really understand why there should be a causal relationship between the year end cash balance (and lets remember it’s the cash balance held on that day only), and the amount of interest earned over a 12 month period?
While that's undoubtedly true the lack of interest suggests that almost no cash was on account earning during the year, in which case the year end cash balance management is pretty extraordinary. I can't think of any particular reason why Spectra's clients would be paying them en-masse at the company's year end either.
I imagine there's some realistic explanation, but given the opacity of the business I preferred not to wait around to find out.
timarr
I imagine there's some realistic explanation, but given the opacity of the business I preferred not to wait around to find out.
Of course, that’s fine, and the right thing to do if you’re concerned, but if you’re implying there’s a good chance of a fraud taking place and that the cash may not really exist as shown in the accounts (a la Patisserie Valerie) then it would be dead easy to fix the interest earned in the accounts too. Even with my poor accounting skills I could manage that to cover my tracks :) Anyway, it looks like something spooked the horses today!
RE: Spectra Systems (LON:SPSY)
Anyway, it looks like something spooked the horses today!
Probably the CFO departing without so much as a thanks for their efforts?
FWIW I also noted De La Rue (LON:DLAR) moaning about the decreasing demand for banknotes due to central banks having overordered during CV-19 times. It's unclear how Spectra's earnings are linked to banknote production but in the projects I worked on (now over a decade ago) prices of security features were set on the volumes used. Normally those are fairly predictable, but maybe not right now?
Lot of moving parts, and although I'd be staggered if there's fraud involved here, given the client base, it's always been tricky analysing the business, and this is just another layer of complexity. There's plenty of value lying around in markets at the moment, no need to tax my increasingly febrile wits on something I clearly don't understand.
timarr
Probably the CFO departing without so much as a thanks for their efforts?
Maybe she was just crap at her job. It happens. Looking at her Linked-In she’s not stayed in any job for very long since she left Covidien in 2015 following the takeover by Medtronic. They certainly didn’t want to retain her services. Tbh I find the gushing send off RNSes when someone has jumped before they were pushed really fake.
Spectra Systems (LON:SPSY)
Hi Si
Interestingly it was Patisserie Valerie that came to mind when I saw the low interest income in the Spectra accounts.
Having said that, when I made my decision to sell I didn't actually assign a high probability to fraud. But after today's events - the CFO abruptly leaving - that % has ticked up a little.
It's a strangely timed coincidence given that the broker finally responded to me (after 3 attempts over the last month) on Friday.
---
I think Timarr has responded with the rest of my thoughts, especially the assertion that interest income should not be that low, even if the annual cash balances were highest at the end of December.
The reported cash balances at FY21 Year End, FY22 Interims and FY22 Year End were $16.8m, $18.0m and $17.5m respectively.
A 2% interest on an average $17m cash balance = $340k
For comparative purposes (and apologies for stating the obvious) a 2% interest on an average $5m cash balance = $100k
And yet the interest income in 2022 was only $17k.
And the FED rate at the end of 2022 was already 4.25% - 4.50%
Something just doesn't look right.
---
I was hoping that the broker would come back to me with a plausible explanation for this, for example, that the majority of the cash is restricted with zero interest income, or that restricted balances were much higher in 2022 vs 2021, etc....
But their response wasn't really convincing, with a mention of there being a lag, which doesn't make sense when I'm asking about a period of 24 months, and that the forecast direction of interest income is upwards, which I can't really see from looking at the accounts.
---
Everything could of course be fine, but for now I'm happy to wait on the side lines.
A
Interestingly it was Patisserie Valerie that came to mind when I saw the low interest income in the Spectra accounts.
Having said that, when I made my decision to sell I didn't actually assign a high probability to fraud. But after today's events - the CFO abruptly leaving - that % has ticked up a little.
We’re just speculating here but the two could be connected and it’s possible that the CFO was allowed to resign (rather than being sacked) for the good of her CV because of poor cash management i.e. leaving cash in non-interest bearing accounts. She certainly had no previous experience of being a CFO of a listed company and the low interest income period covers the entire time she was with the company. I guess time will tell if Spectra Systems (LON:SPSY) is some kind of fraud as you and timarr seem to be implying, or whether they just need to do very much better with the new CFO appointment.
Spectra Systems (LON:SPSY)
Abtan,
Ditto I also contacted them 3 times about the same query (both to company direct & WH Ireland) and eventually received an answer after a couple of weeks - on 6th April (so think your response may not coincide with departure of CFO just down to slow response) saying that it was due to lag in rates, as you mentioned, but also down to the fact that ‘Restricted cash (CD) account with locked-in higher interest rate decreased by 50% in late 2021 as customer’s requirements eased.’
In terms of lag to funds rate the explanation may explain why they got a slightly higher interest in 2021 than fed funds rate but historically they have always had a interest income slightly under but not as much as in 2022
year/ interest income /effective percentage/fed funds rate that year
2022 : 17 (17,496) 0.01% (0.08-4.3%)
2021 : 40 (16,775) 0.2% (0.09%)
2020 : 114,628 (14,038,295) 0.8% (1.5- 0.9%)
2019 : 197,497 (14,250,353) 1.3% (2.4-1.5%)
2018 157,630 (12,662,410) 1.2% (1.5- 2.4%)
2017 60,480 (11,180,578) 0.5% (0.6 – 1.4%)
On the restricted cash part they were referring to this was , according to annual report a ‘ certificate of deposit held as collateral for certain performance requirements in accordance with terms of a services contract. As of both December 31, 2021 and 2020, a service contract required that US$500,000 be maintained as collateral for contract performance. As of December 31, 2021 and 2020, the Company collateralized the service contract with a certificate of deposit of US$500,000 and US$1,099,021, respectively, whose maturity exceeded 90 days at the date of acquisition.’
Obviously this represents $500,000 less in this higher interest but (obviously) still leaves an apparent almost $17m languishing with limited interest , so still leaves you scratching your head a bit?
I am a holder of Spectra Systems (LON:SPSY) - corporate governance is definitely an issue. I view it very much as the Nabil Lawandy show. There is definitely “key person” risk with this company - both in terms of needing to trust him and risk of being run over by the proverbial bus.
The CFO has not been a board position at Spectra. CEO Lawandy is the only executive on the board - which means the NEDs are only hearing (at least in a formal sense) from a single voice from the coal face. The board is commendably small (at five) but was until Sept 2022 all male and apart from one change (caused by a death), there had been no turnover in the board since listing, as far as I am aware. In Sep 2022, Barbara Paldus was appointed as a fresh face as an NED.
The RNS on the departure of the CFO is curt and as Mr C would say “Colleen Hamill is not thanked”. This is in contrast to the RNS (Mat 2022) on the departure of the previous CFO, Brian McLean.
As far as the non-holding of an AGM is concerned, I have heard Lawandy on a webinar say how frustrated he was that shareholders do not seem bothered enough to make the AGM quorate. That he has spent some effort to get an AGM held and also that largest shareholder, Slater had been making efforts too. But all to no avail. I do not know Delaware law well enough to judge whether this is a realistic explanation for there being no AGM.
Correct me if I'm wrong but I think 'Delaware Law' is an oxymoron..it's where all the US dodgy trusts are registered for 'tax' purposes
Correct me if I'm wrong but I think 'Delaware Law' is an oxymoron..it's where all the US dodgy trusts are registered for 'tax' purposes
Yes, but Apple, Walmart, Starbucks, and just about every other large US corporation are registered in Delaware. In that regard your comment is highly misleading.
I base that on the book Treasure Islands: Tax havens and the Men who Stole the World. It's an eye opener for how companies (big and small) operate and there is quite a lot of info on why companies register in Delaware
I base that on the book Treasure Islands: Tax havens and the Men who Stole the World. It's an eye opener for how companies (big and small) operate and there is quite a lot of info on why companies register in Delaware
Yes and it’s very well known and has been for years. However, you were implying there is something improper about Spectra Systems (LON:SPSY) being registered in Delaware, when that is not necessarily the case since many large reputable companies are also registered there.
Spectra Systems (LON:SPSY)
Lawandy wants the AGM to be held in the USA. US based individual investors are not permitted to directly hold UK shares. It isn't surprising that there isn't a quorum.
Does he want the AGM to be held in the USA, or does he want no AGM? I held briefly, then just presumed he wanted the latter and got out.
Somero Enterprises (LON:SOM) can raise a quorum in the USA for AGM and they're listed in UK - it's difficult but not insurmountable
Morning Wimbledonsprinter
A difficult call, but I decided on balance to sell at a small profit and move on, triggered by this morning's announcement. I have recycled some of the proceeds into other holdings that I feel I can better understand where management are more accessible.
There is a lot to like about Spectra Systems (LON:SPSY), but I kept asking myself do I sufficiently understand the company and came to the conclusion that it is a little too opaque, to borrow a word from Timar's post and as you say the Nabil Lawandy 'show' with the potential risks that brings..
I have added modestly to my holdings in Volex (LON:VLX) and Sigmaroc (LON:SRC) this morning. I like the management of both companies and have personally met the latter on a few occasions. Time will tell if this is a good call.
I wish you well and hope your investment in Spectra Systems (LON:SPSY) prospers.
Hi
For those interested in Sigmaroc (LON:SRC)
Investor Presentation
Investor Meet Company on 25(th) April at 9:00am BST
SigmaRoc (AIM: SRC), the quarried materials group, is pleased to announce that
its Chairman, David Barrett, its Chief Executive Officer, Max Vermorken, and
its Deputy Chief Financial Officer, Dean Masefield, will provide a live
presentation relating to a Q1 trading update and ESG report to be published
tomorrow via Investor Meet Company on 25th April 2023 at 9:00am BST.
The presentation is open to all existing and potential shareholders. Questions
can be submitted pre-event via your Investor Meet Company dashboard up until
9am the day before the meeting or at any time during the live presentation.
Investors can sign up to Investor Meet Company for free and add to meet
SIGMAROC PLC via:
https://www.investormeetcompany.com/sigmaroc-plc/register-investor
(https://www.investormeetcompany.com/sigmaroc-plc/register-investor)
I hold.
Regards
Howard
My morning smallcap tweet: Taking the butcher's cleaver to the body of news
£OTAQ Insig Ai (LON:INSG) Medica (LON:MGP) CentralNic (LON:CNIC) Asimilar (LON:ASLR) Mind Gym (LON:MIND) Christie (LON:CTG) Checkit (LON:CKT), React (LON:REAT)
◄OTAQ (OTAQ)► final Q broadly in line with management’s expectations. This Q1 in line. [SP=NA Cap=NA]
◄Insig AI (INSG)► guides FY-Mar ev £2m+. In line? This FY has started positively. [SP=17.9 Cap=17m]
◄Medica (MGP)► rec offer of 212p, a 33% premium. [SP=NA Cap=NA]
◄CentralNic (CNIC)► trading at least in line with market expectations. [SP=122.54 Cap=351m]
◄Asimilar (ASLR)► delayed finals. Trading restored. Proposed delisting from AIM to save costs. [SP=1.88 Cap=2m]
◄Mind Gym (MIND)► guides FY-Mar rev up 12% (4% at const FX) and pretax broadly in line with expectations. Cash at hand £7.6m, ahead of expectations. [SP=64.19 Cap=64m]
◄Christie (CTG)► FY-Dec rev up 13%, pretax up 13%.FY div 3.75p (3p). Outlook positive. [SP=124 Cap=32m]
◄Checkit (CKT)► FY-Jan ahead of market expectations. Rev up 23%, pretax loss £12.3m (£8.5m). ARR up 28%. Guides FY24 in line. [SP=28.77 Cap=30m]
In line: REAT
React (LON:REAT) - Record half year (new research note with audio summary: https://www.equitydevelopment.... )
The indicative H1 outcome, as suggested within the pre-close trading update, sees revenues, gross profit, and EBITDA at record levels, with the latter close to FY22 levels. The pipeline of opportunities remains strong, thereby underpinning FY23 expectations for adj. PBT and net cash. The cross-selling of services to the clients of LaddersFree is bearing fruit, with a focus on higher gross margins and recurring revenues providing better visibility. With estimates unchanged, we see little reason to adjust our fair value, suggesting a re-rating remains likely. We use DCF and peer group comparison models to determine the fair value of the shares. Taking an average of the two suggests an unchanged 1.7p / share.
Morning Paul, thanks for flagging Medica (LON:MGP) , I bought about 2 weeks ago and now a bid!
Medica (LON:MGP) It seems too low a price to me; I won't be supporting it. I hold.
Thanks Nanotrader09!
I vaguely recall mentioning Medica (LON:MGP) in one of my podcasts, I got the idea from another podcast by Ken Wootton. Seeing as you mentioned it, can you remember when it was I mentioned Medica? I think it was 1st or 2nd week of April, as I recall listening to Wootton's podcast when walking along a dry & dusty road back from Malsalforn in Gozo, and thinking what an interesting podcast it was!!
Medica was the best stock idea in Wootton's podcast I thought. If I'd had any spare cash, would have bought some myself.
Regards, Paul.