Small Cap Value Report (Part 1) - Thu 25 May 2017 - FEVR, RBG, EHG, BLV, MMX, BOOT, FLO, REDX

Good morning! It's Paul here.
I'm meant to be having a day off today, concentrating on moving house. However, I've done my usual morning scan of the RNS, so thought I'd put up some brief comments. Graham is planning on doing some more in depth reporting later today.
Founders cashing in
The list is growing of companies where founders are cashing in significant portions of their stakes. Coming after huge moves up in share prices, this is another sign that the market for growth companies is clearly getting toppy.
Actually, I think we're possibly now into the final, "euphoria" stage of a bull market. Whilst that may sound alarming, this is also a time when fortunes can be made. The trick is obviously to cash out before the market eventually corrects, or crashes.
Off the top of my head, I can think of £G4M and Purplebricks (LON:PURP) (both of which I hold personally) where Directors have taken a fair chunk off the table. Yesterday Directors of Keywords Studios (LON:KWS) did the same.
Today it is Fevertree Drinks (LON:FEVR) - a founder Director Charles Rolls intended to sell 2.5m shares, but "due to significant institutional demand" (lol!) he ended up kindly selling them 4.5m shares, but took a haircut on price - selling at 1625p per share. That's £73.1m he's banked - not bad going! Mr Rolls still holds 12.9m shares though, so still has acres of skin in the game.
Should we begrudge Directors taking advantage of an extremely buoyant market, and cashing in some chips? Possibly not - I'd probably do the same in their shoes. However, when you see Directors cashing in at many companies, then it clearly points to a market that is expensive. If there are willing buyers though, then maybe these share prices could go even higher? In some cases I suspect we might already seeing the "greater fool theory" in play.
As regards Fevertree Drinks (LON:FEVR) I briefly bought some for my Stockopedia portfolio, Beam Me Up Scotty, but got cold feet after the last trading update. For me, the bull case rested on the likelihood that broker forecasts look far too pessimistic (as has proven the case historically). However, the last update indicated the company is "comfortably ahead of current market expectations". Whilst clearly good news, I'm not convinced it's good enough to justify the share price rising further, for now? Hence I ditched my real life & fantasy portfolio position in the company. That may have been a mistake, but if in doubt, I sell out.
Revolution Bars (LON:RBG)
A correspondent tells me that my name is being taken in vain at the lower end of the bulletin board spectrum, due to my incorrectly positive stance on this share, which has since dropped by about 50%. A few points;
- Everyone gets plenty of stock picks wrong, including me, and I've never claimed otherwise.
- The performance of BMUS shows that I get a helluva lot more right than wrong. Nobody would read this blog if that were not the case. Are there any fund managers whose ungeared, long-only small caps portfolio is up 200% in the last 2 years? BMUS is. OK, it will be tough to impossible to repeat that performance in future, and pride comes before a fall, so I'd probably better shut up about this point for now!
- Profit warnings are not something to get uptight about, it's quite normal in the small caps space. If you can't cope with that, then get out of the pool!
- Bears on RBG are obviously enjoying their moment, and crowing about it, which is fine. However, I've not seen any evidence to suggest that anyone predicted the reason for the profit warning - significant cost over-runs. So bears were right by accident, and who cares anyway?! My focus is on the facts & figures, not on internet squabbling.
- I remain of the view (which may turn out to be right or wrong, we'll find out in due course) that RBG's problems are fixable, hence it could be a good recovery stock.
- Reflecting on things, I was definitely over-confident about this share. My mistake was to place too much reliance on broker forecasts, and management reassurances. Also, I didn't think enough about the potential downsides. In my defence though, it was reasonable to assume that experienced management like this would have been able to budget correctly for obvious & known cost increases. So it's mainly management that have screwed up here, not forecasters or commentators.
- With a net debt free balance sheet, and generating tons of cashflow, this is still a very nice business, now dirt cheap. So let's see what happens.
- The latest Numis note gives more detail on the specific cost over-runs. However, it also has a frightening statistic that each 1% drop in LFL sales knocks 10% off EPS. I didn't factor into my calculations this level of extreme operational gearing, which was a mistake. So if you think consumer spending on discretionary things like cocktails is likely to drop, then clearly this share is not for you.
- I'm more sanguine about the macro picture, and specific self-help measures RBG is already taking, which I believe could mean LFL sales hold up, or increase. Specifically, an App to order food & drinks is close to launch. Plus the food offering (previously seen as poor) is being revamped. If that works, then who knows, we could see a nice recovery in performance & investor sentiment later this year.
- The self-funded, debt-free roll-out continues. So even if existing sites struggle, the company is bolting on more profitable units (on highly attractive rents at c.6% of turnover for new sites), which should help shore up EBITDA at the current £15m level. For the avoidance of doubt, I only see EBITDA as a starting point for considering cashflows. We then have to subtract maintenance capex, tax, etc. The business is still a cash cow, which I like.
- Takeover potential - I see it as being a potential takeover target at the current bombed out valuation. A trade buyer in particular could strip out a load of costs. Drinks purchasing is based on volumes, so as part of a larger group, RBG's profitability could be increased a fair bit.
- Overall, an interesting situation. We never give recommendations here, as everyone knows. The focus of the site is on providing tools to help investors DYOR. Also, these reports are just mine & Graham's personal opinions. Sometimes we'll be right, sometimes wrong.
- In this case though, I was definitely over-confident about this share, which might have influenced some people. So an apology is in order, and I'll try to rein in my enthusiasm a bit in future. If it's any consolation, I've incurred a hefty paper loss on this one. Sorry if readers also took a hit, and were influenced by me.
- I don't see how any of us could have foreseen that management would fail to properly control costs, and fail to budget prudently. These seem basic mistakes, and it's no wonder that confidence in management has taken a big knock - reflected in the share price roughly halving in the last few weeks.
- Anyway, we live & learn. I always carefully ponder every mistake/loss, as it's so vital to learn from each one. That's the way we improve our performance in the long term. So brushing losses under the carpet is the worst thing to do.
- Above all, please DYOR. It's vital to think independently, and take responsibility for your own investing decisions & performance.
Elegant Hotels (LON:EHG)
I see that 12.5% shareholder Luke Johnson is the biggest shareholder in this group of freehold hotels in Barbados. Also of course, he's a remarkable entrepreneur, so is someone I follow.
He's been appointed as a NED. That's good news I think - adding such a high profile & experienced entrepreneur to the Board can only help.
I've been dithering about this share for a while. I like the company, but have 2 specific reservations;
- Forex movements - about 70% of the company's revenues comes from UK tourists. So the post-Brexit plunge in sterling likely to be very unhelpful.
- TripAdvisor reviews for most of the company's hotels indicate problems with maintenance capex - i.e. they're not up to scratch for the prices being charged, seems a recurring theme from genuine-sounding reviews.
On chatting to a couple of friends who visit Barbados every year, they all said that the forex movements wouldn't stop them visiting. It's already very expensive, so it costing a couple of thousand more, didn't seem to bother them.
On balance, I think the financials look quite attractive here, and I'm limbering up to buying an opening size long position in it. This breaks my usual rule of not touching any overseas AIM companies. In this case though, it looks a bona fide company.
The dividend yield looks too generous to me. I'd rather they cut back on divis, and spent more on improving the condition of their hotels.
As a quick sense test, I note the StockRank of 87 is strong, and the new StockRank Styles rates it highly, as a "Super Stock". Jolly good - I always like it when the Stockopedia computers tell me that the probability is things are leaning in my favour.
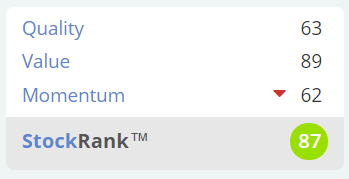
Note the attractively low PER, high divi yield, and it's even trading at a discount to NTAV. So decent value characteristics, reflected in the Value score above of 89.
The momentum score has a down arrow next to it, which I assume means the momentum score has fallen - a useful pointer.
Sure enough, broker forecasts have come down a fair bit in the last 12 months;
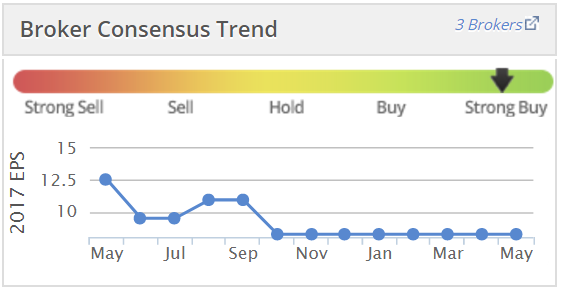
Actually, I find that quite reassuring - because it shows that brokers have factored in reduced earnings from the issue with UK tourists & forex, which is bound to have some effect.
My opinion - Overall, I'm not 100% sure about this share, but am sufficiently comfortable now to open a modest opening long position. When I say modest, ballpark between 1-2% of my total portfolio. I like to get comfortable with shares over a period of time, and then scale up positions where my confidence level is increasing. Or ditch the ones where my interest fades - driven by newsflow, and deeper research. For me, researching a share is a continuous process, not a one-off event.
Belvoir Lettings (LON:BLV)
This small property lettings business says at its AGM trading update;
Trading during the first quarter of the current financial year has been in line with the Board's expectations. Group revenue was up 19% on the prior year, mainly reflecting the acquisition of Northwood in June 2016.
Various other details are given, but this bit caught my eye, as it is likely to have wider read-across for the sector;
...there is a healthy pipeline of further opportunities as some of the smaller independent lettings agents choose to withdraw from the sector in the face of a ban on tenant fees and increased legislation.
Overall, this looks quite an interesting little company, and there's an outstanding dividend yield of 6.9%. Mind you, when a divi yield is that high, it's possibly the market signalling that this level of payout might not be sustainable - so the figures would need checking.
Minds + Machines (LON:MMX)
Strategic Review - this company, which operates in the internet domain names sector, has put itself up for sale, and is considering other options too. This is because the sector is fragmented, and the company has had "a number of informal approaches from external parties".
It says that domain registrations are up 40% year to date. It sounds like that refers to quantity of, rather than value of domain registrations - which could be very different figures!
I've never really understood how to value this company.
It's only had a couple of blips of investor interest in 2010 and 2014, but apart from that the share price trend has been sideways.
I don't see any evidence that these top level domains such as .VIP are taking off. People just search for a company name on Google. The domain name seems largely irrelevant these days.
Henry Boot (LON:BOOT)
There's a positive trading update today from this property development company. The share price is up 5% today in response.
This all sounds positive;
Property trading and development activity levels since the beginning of 2017 have been very encouraging and the Group's three business segments; land promotion, property investment and development and construction are trading strongly.
Henry Boot is, fundamentally, a transactions driven business and there is always a degree of uncertainty with regard to the timing of these deals within a particular financial period. We are pleased to report that any uncertainty created by the current UK general election process is not having an impact on our business.
Given the strong start we have made in 2017, and anticipating no major changes to the underlying economic conditions in which we operate, we now anticipate the Group's performance for the current financial year ending 31 December 2017 will be comfortably ahead of the Board's existing expectations.
Good news for holders there. I don't normally analyse companies like this, as it's too time-consuming to properly research them.
Flowtech Fluidpower (LON:FLO)
This update today reads quite well in my view. So I'm a bit surprised to see the share price down 2% in response. The key part says;
"In summary, the Directors remain confident about the future; we fully expect our underlying performance to deliver another year of solid progress and, we remain on track to meet current market expectations for the year ending 31 December 2017.
This is a nice little niche business, at a reasonable price, in my view. So worth a closer look, possibly.
Redx Pharma (LON:REDX)
A total disaster here - amazingly the company has been put into Administration, by a creditor who is owed £2m plus interest. Yet the company raised £12m in fresh capital just 2 months ago, in Mar 2017.
Mind you, it's incurring huge losses, so that money seems to have largely gone. It made a loss of £9.8m in the half year to 31 Mar 2017.
This appears to be a story of amazing management incompetence (or worse?). They seem to have tried to string along a creditor, with a payment plan, and then been made insolvent.
This is a great reminder of why I NEVER invest in massively cash burning drug discovery companies. They nearly all fail, and the decent ones get bought out before shareholders see much upside.
Right, this was only meant to be a quick report, but ended up ballooning!
I'm off to dismantle my furniture now, and box up the last remaining items, before removal men come tomorrow morning. So I'll be out of action all day tomorrow.
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

74 comments
Wish I had some. Looked at them so many times and thought too expensive.But there again I do have plenty of BOO-some from below 30p. Perhaps if I was a G&T man -but prefer real ale and red wine.
I'm drink the same but don't have any shares in real ale. Yes Fevertree Drinks (LON:FEVR) always look expensive but growth is still there that's one lesson I have learnt in the last year.
RBG is also up today. broker finnCap currently have a GBX 180.00 target price on company and have upgraded to a buy rating.
I bought some this morning as I was waiting for the share to turn towards a bullish direction before I got in.
Fevertree Drinks (LON:FEVR). "For me, the bull case rested on the likelihood that broker forecasts look far too pessimistic (as has proven the case historically). However, the last update indicated the company is "comfortably ahead of current market expectations".
Sounds like they were being modest, today's interims are way ahead of forecasts. I also sold out after the previous update but I'm back in this morning.
Which stock herbie?
Sorry that was Fevertree Drinks (LON:FEVR).
Herbie47 - Re Fevertree Drinks (LON:FEVR) I agree today's HY results tell me that they will almost certainly exceed broker forecasts. I bought back too after selling out last year.
Key performance metrics are not looking too outrageous when you consider adj. eps growth of 106%
- PE 52 ; PEG 0.5
- ROCE 35%
- FCF/ Sales near 20%
- 130% operational gearing
- no debt; surplus cash £47m
On the other hand, I suppose a P/S = 13 is a little toppy, but it has come down from 19.7
Regarding Elegant Hotels (LON:EHG) I stayed at their Crystal Cove hotel two years ago, as we had access to all the Hotels in the group we had a good look around all of them on Barbados (not including Waves). I would definitely say the Hotels were in decent condition and if we ever went back we would stay there. I didn't realise they were listed until Paul mentioned them in a previus small caps report, I'm now watching closely. It may also be a good way to play a recovery in the pound.
Paul,
No apologies needed.
You got me into Boohoo at 39p!
Am staying long with RBG.
Regards and Thanks
Hi Paul,
Back in your report for 16 November 2016, you predicted correctly that Eagle Eye (£EYE) would need an injection of cash at some stage to sustain it's growth and it might then be an interesting investment following a successful fund raising. This has now happened (see last week's news) and I wondered if you now had a view on it's prospects. I have made a second small investment following the announcement.
Regards and thanks,
Nick
Hi Hedgecutter,
Yes, I was reading up on Eagle Eye Solutions (LON:EYE) recently, as it was featured in SCSW, with a positive article about the outlook.
The valuation looks very aggressive to me. However, we're in a bull market, and the company does seem to have quite exciting potential, and with big name, real clients, already using its electronic vouchers system.
SCSW say the exiting upside could come from potentially ASDA turning into a Walmart contract. Plus upside from transactional-based revenue streams, e.g. from product promotions.
On that basis, I've opened a small long position in the share. As you say, it now has cash in the bank to fund losses for now. There seems to be a lot of optimism around the company.
It's not the usual thing that I would touch in normal markets, but as we're in a roaring bull market, then jam tomorrow shares can explode upwards. The trick is obviously selling out before the market turns, and they all come back down again! So speculative, but interesting, I would say.
Most people like a little fizz in their portfolios!
Regards, Paul.
Thanks Paul for looking into EYE. I don't have access to the SCSW, so hadn't made the Walmart connection, but if that were to happen, the impact on the company's future and share price would be pretty enormous.
I am sure you are right to point out the potential for the SP to be "pumped up" and then to burst at the first negative news. Let's see how it goes and prepare the parachute!
Revolution Bars (LON:RBG) - I never bought this having a deal of scepticism about the industry from an investing viewpoint. Despite reading everything Paul wrote, and thinking it is probably another one that got away as it kept on rising. I haven't formulated a view on what to do now either. The interview with Paul suggested a reality that has proved inaccurate. They should have known. Maybe they did and were hoping it would turn round. Maybe they didn't. Dishonest or incompetent? Did they all know the same things, or just the FD. Was the pious act about FD leaving just an act by one or both?
I don't know the answers so I can't work out a buy price. I assume that the operational gearing statement from Numis is wrong with - it would be uninvestable if true. If it is anything like true, I can see why the PE sellers left it without gearing. The historic cash flow must be fairly accurate; might have created a few future skeletons though stated policies suggest not. But a lot of adjustments to profit figures, but and that always suggests things have been made to look better than they are. The report of them opening a bar, finding it uneconomic and closing within a year worries me too: it means a low level of confidence that planned openings means profit growth; could be losses.
Paul - I always read and value your columns. I don't mind if your opinions are right or wrong (though I hope they are right enough to keep you going). We all get things right, we all get things wrong. I highly value your comments which often point out things not said elsewhere and do it usually in a very timely way. I have no problem with days when you don't comment because my opinion doesn't depend on them; very useful when I have them but happy to trundle on happily enough when I don't.
I agree completely about the importance of position size. I'd find it interesting if you could comment on your BMUS decisions on position size. In this column, you mostly refer to a small starter and putting more in as you become more comfortable.
I suppose the bulletin board trolls miss the point that it is also possible to make good money by selective investments led by Paul's ideas, with additional due diligence. That would be their loss.
My Boohoo holding is showing as +784% currently. I have top sliced a couple of times.
I almost doubled my money on Purpllebricks, but seem to have sold out too soon.
There are a couple of minor losses, but since Boohoo is up so much, it would need 100% losses of 7 similar sized positions to drag me back to break even. The magnitude of the upside is important. Actually even Paul himself often refers to the percentage of winning trades, when the upside on the good ones is at least as important.
I still say the way to deal with non-constructive trolls is to ignore the boards on which they reside & kick them off this one.
Anyone who has constructive logical ideas for or against the investment proposal should be welcome. Those who are purely critical without adding any reasoning just waste time.
As for myself, when I do see an attractive opportunity like Boohoo, I need to check it out more carefully & then take a bigger position & be slower to top slice.
Elegant hotels have just purchased treasure beach hotel on the west coast this is after they bought waves last year.
They now own turtle beach on the south coast, colony club, crystal cove, and tamarind on the west along with the other two, making them the largest hotel owners in barbados.
Paul,
After a couple of years when my portfolio floundered, I personally can't thank you enough for the informative views you provide. Of course, like most of us I don't always get it right! Indeed the losses I'm currently nursing are legacy (pre-Stockopia days). However, a combination of your research, applying and constantly revising stop losses has helped turn things around.
Indeed I was so disillusioned with investing, I'd have happily given the lot to a fund manager for ten years. You've stopped that, I now trade less and make more. Thanks
Hope the move goes OK.
Matthew S
Actually I don't think there are many saying much about Paul at all....maybe one or two max....and he has a lot of support even from those who are way down on the stock. Cannot get them all right.
I am a bear and see 80p or lower.
Not sure I accept the reasons given.....feeble excuses. I reckon things are very bad here in fact. If RBG is actually going to make a loss what then? It has few assets to back up a 60 million mkt cap.....just a few leases that may look expensive in a year, a lot of liabilities and so on. A competitive market with more and more "offers" around.
Paul,
Just a note to echo many of the sentiments above - you have absolutely nothing to apologise for. As a very small scale private investor, I find your reports easy to digest, comprehensive and I genuinely enjoy reading them. They do most definitely help shape my opinions on small cap companies, but ultimately I am responsible for my own decisions regarding which companies I invest in. Sometimes I do a little more research, and decide a company you like is not for me - and sometimes I've missed out on significant returns, other times I've dodged a bullet.
However, overall you have helped me put together a profitable SIPP, which is returning far, far more over the last few years than any of my other, institutionally managed, pension funds. And what's more - I've really enjoyed doing it.
So - no apology EVER necessary. You provide your own opinions, and it's up to me to decide whether I agree or not. I also hugely respect the fact that you put your money where your mouth is, and back your own judgement financially.
Thank you - and please do keep up the great work, it's much appreciated.
Experience teaches nothing, it is only by reflecting on experience that we learn.
I learnt a few years ago that bulletin boards were worse than a waste of time, they skewed my thinking and invoked multiple negative biases which affected my performance.
Stocko build a presence with methodological rigour, top class tools and insightful commentators such as yours Paul which are the nucleus of a community with shared values and modus operandi.
Sometimes staying out of the gutter allows one to better see the stars.
Re RBG - It's probably no longer debt free as you refer to. The slower maturity of new de Cubas means capex needs to be funded ahead of cash flow – finncap estimate that FY17 net debt will be close to £4m. Only 10% gearing though..
Hi TheJudge,
Yes that's true, Revolution Bars (LON:RBG) might pick up a little net debt over the next year. However, the numbers are chicken feed really. £15m EBITDA, and banks usually happy to lend 2x, so capacity to borrow £30m. Therefore £4m net debt won't worry anyone.
One of the key reasons I seek out companies with little to no debt, and a strong balance sheet, is that they usually tend to recover from any mishaps. The reason being that they don't need to raise any equity, and management have a free rein to concentrate on improving the business, instead of worrying and time-consuming fundraising efforts.
Thanks for all the supportive comments above, from everyone. We've built a smashing community here, and thank goodness we don't have all the background noise & general nastiness that is prevalent on other, lower quality discussion boards.
Regards, Paul.
Amen about the fact that stocko doesn't run a low quality discussion board.
I would cheekily suggest that with Revolution Bars (LON:RBG) , Paul and others (including myself) seem to have forgotten the wise words Ed put out in "the anatomy of a profit warning". So far it's following the pattern that was suggested almost perfectly.
This suggests we have at least 18 months to wait to get our money back, I'm not sure I have the patience.
Cheers
CT
Paul, just wanted to say I probably wouldn't be on stockopedia if it wasn't to read your reports, its where I learn the most from, the way you break down the figures and your analysis is a great learning curve for me.
thanks
When shares go up people crow how clever they are and when they go down they look for someone else to blame. Remember Disraeli's quote "never apologise, never explain and walk on. Your enemies will never understand and your friends love you anyway."
You are a great guy and do walk tall
Tom
On RBG the bars I have visited are generally very busy with the drinks of high quality so whilst the profit warning was unexpected there appears to be nothing wrong with the core business. I did invest after the profit warning so hopefully will have picked up a bargain with the added potential of a future bid as the business would be attractive to a trade buyer or a private equity company. Paul Scott does an excellent job in pulling out information and analysing reports and its up to the individual investor to do their own analysis before investing. You have to balance up the winners with the odd loser so as long as it movers overall in the right direction there is nothing to worry about
Hi Paul,
I'm a newbie investor and I had a 10% of portfolio position on RBG, based on my own research but admittedly mostly spurred on by your blog, however I conducted that transaction myself so no blame to be passed around and no apology necessary from you.
Thanks for an informative and enjoyable blog, I'll keep reading (here and elsewhere) and keep learning.
Regards
Matt
I echo the comments above, no fence sitting Paul! If you feel strongly about a share please feel free to let your feelings known. Its up to us to decide for ourselves whether we agree with you or not and hit the buy button. I confess I did take a few RBG shares after you highlighted them and to be honest based on the information at hand at the time, I believe it was quite a compelling buy! Hindsight is a wonderful thing but sometimes things happen that are unforeseen. Unless you have inside knowledge, there was no way to know that management were failing to manage costs. I only had a small position as the one concern I had at the time was the low share price. I know that seems illogical but 'm often somewhat sceptical when on the outside all looks well yet the share price is unusually low, it seemed such a bargain that I wondered why the appetite for the share wasn't there. If it looks too good to be true and all that. I've found that I have more success buying shares that are slightly on the expensive side. My logic being that its expensive for a reason!
I only subscribe to this site because of the quality of the information and ease of use and because of your analysis Paul.
I find it a sad reflection on the modern world when people troll just for the sake of it.
I mentioned the other day that I had bought some RBG...because the Cambridge branch is still busy..and talking to the staff there saw nothing nasty in the custard.
I said that I expected to get a 15% return over the next 12 months...as either (in my view) they will be snapped...particularly bearing in mind the exchange rate at present or...I think they will recover sufficiently to meet my goal.
I was immediately told that setting an arbitrary objective was pointless....and so on.
Ultimately I may be right..I may be wrong....but it was only meant to be a social comment!!
DYOR should be the most important four letters of all....and in doing so....reading your column Paul is enjoyable, educational and informative..as well as being thought provoking at times.
So thank you
So far, Revolution Bars (LON:RBG) is playing out pretty much exactly as per Stockopedia's Profit Warning Survival Guide http://www.stockopedia.com/books/profit-warnings/ i.e. it was far better to get out immediately as the price has continued to sink after the day of the warning. The Guide is well worth a read/refresher.
I have no problem with founders of sensationally successful businesses like Fevertree Drinks (LON:FEVR) selling chunks of their holdings to free up cash. If a founder cannot sell some now, when pretty much every shareholder who has ever been involved has made significant money, then when? No impact on the company or dilution for other holders so I see no problem at all with it.
I agree that LJ's involvement with EHG looks very interesting albeit there are risks with the business.
He's bought his shares, had a closer look and decided to get more involved - i think that can only mean he sees much more potential. That might mean reducing divi to fund development, or raising funds to expand more rapidly which may not necessarily mean this is a share price low but we can be reasonably certain he sees a bigger business in a few years time.
The chart pattern has be very supportive of a recovery for some time so seems to be a steady increase in 'believers'
I am a holder from the start of the year and am happy with some overseas earnings FX exposure as my portfolio is underweight in that at the moment.
The performance of BMUS shows that I get a helluva lot more right than wrong. Nobody would read this blog if that were not the case.
Here is a quick rundown on BMUS on a stock-by-stock basis. Essentially BMUS has held a total of 64 different shares in its lifetime, 37 of which have made money and 27 of which have lost money. The average gain of the 64 is 26%.
(Sorry about the formatting, but I can't be bothered to fiddle around with the table editor)
The number against each share is the % gain/(loss) for that share based on the total amount invested versus the total sale proceeds plus the current value of any shares still held. Dividends and costs have been ignored. Shares marked with * are still held in BMUS:
Avesco AVS 349.6
Gear4music Holdings* G4M 249.8
Purplebricks* PURP 208.8
Somero Enterprises Inc SOM 179.7
Boohoo.Com* BOO 167.7
Best Of The Best* BOTB 153.2
MySale* MYSL 108.5
Lavendon LVD 80.0
Proactis Holdings PHD 75.0
Punch Taverns PUB 59.7
accesso Technology ACSO 52.6
Johnston Press JPR 48.8
Versarien VRS 41.2
Home Retail HOME 38.6
WANdisco WAND 38.5
French Connection FCCN 37.9
Focusrite* TUNE 32.6
Debenhams DEB 29.8
Kainos KNOS 27.3
Treatt* TET 26.6
Journey JNY 22.8
Altitude* ALT 17.3
T Clarke CTO 17.1
Flybe FLYB 16.5
EI EIG 16.0
Patisserie Holdings* CAKE 14.8
Fulham Shore* FUL 14.0
Accsys Technologies AXS 13.4
Essenden ESS 11.6
Oxford Metrics OMG 9.5
Bayerische Motoren Werke AG BMW 8.4
Lakehouse LAKE 6.9
Persimmon PSN 6.0
Andrews Sykes ASY 3.3
dotDigital DOTD 3.1
Gattaca* GATC 3.1
Fevertree Drinks FEVR 1.9
Utilitywise UTW (2.0)
Crawshaw CRAW (2.3)
Poundland PLND (2.3)
Cambridge Cognition Holdings COG (2.5)
FreeAgent Holdings FREE (2.8)
SkyePharma SKP (3.1)
LoopUp LOOP (3.3)
Tungsten TUNG (9.7)
Sports Direct International SPD (9.9)
DX (Group) DX. (10.8)
easyJet EZJ (12.5)
Fairpoint FRP (12.5)
Shoe Zone SHOE (12.5)
SCISYS SSY (13.0)
Tasty* TAST (13.2)
Seeing Machines SEE (16.0)
Bowleven BLVN (19.8)
Safestay SSTY (21.1)
Spaceandpeople SAL (25.8)
Indigovision IND (30.1)
Cloudcall CALL (32.8)
Revolution Bars* RBG (36.6)
Mobile Streams* MOS (37.0)
Laura Ashley Holdings ALY (39.5)
Cyanconnode Holdings CYAN (42.9)
Richoux RIC (50.0)
Mercantile Ports & Logistics MPL (81.0)
Are there any fund managers whose ungeared, long-only small caps portfolio is up 200% in the last 2 years? BMUS is.
You should start a real fund.
Not many people hold their performance up so transparently for all to see and Paul is to be commended for 1) doing so, and 2) delivering such great performance.
Well done on the value and insight you've brought all of us, especially over the last couple years. Chapeau!
Hi TMFMayn,
Wow! That must have taken you ages to pull together all those stats on BMUS!
Thanks though, it's really interesting.
The reason that BMUS has done a 200% gain in 2 years is simple - I concentrated the money into the big winners. There's a certain amount of luck involved in that.
So the losses were small percentages. The big winners like BOO, G4M and AVS were pretty big holdings. That's the trick, I think.
It's no good putting 3% into everything. I think, to out-perform, you have to put 20% into the best 3 or 4 ideas.
I can't see any point in doing it otherwise.
Regards, Paul.
Everyone loves to crow when they get it right - bears included. Just like the worst bullies in the playground the most insecure ones feel the need to drag others down to make themselves look better. Ignore them and be confident in your record - this is a great site! Enjoy whats left of your day off - its beautiful out there!
As for taking money off the table - I can’t quite bring myself to do that - BOO up 650% for me at the moment, (small position - wish Id invested more), still feel it has a long way to run as long as there are no major hiccups. Same for G4M,PURP, KWS and SOM. Im in it for the long haul and whilst they may pull back a bit, there is nothing telling me that they lack potential. Clearly I can’t predict/time what they will do next, so will continue to hold and take advantage of any major drops in price to top up my holdings so long as the story remains.
On Revolution Bars (LON:RBG), I see it's declined more over the last few days on high volume so it looks like there's still big institutional selling going on. It's now down over 45% since the profit warning. Consequently, in my opinion, the market is telling me that this might not be a small and easily fixable problem.
Regarding bottom fishing, I think this quote from Minervini's book is pertinent - “The most dangerous time to trade is when a stock is trying to bottom. This tends to be a very volatile period for stocks. When a stock is searching for a bottom, it can whip back and forth violently. Trying to pick a low can be very frustrating and costly.”
Paul, I think you ability to analyse your decisions based on facts, admin when the initial analysis is wrong if needs be, is exactly why BMUS has performed so successfully - well done. We are all working with a portfolio of investments hoping that the overall result will be successful.
The fact that you share your ideas and analysis is fantastic and are brave and true enough to also share your mistakes shows your integrity.
As I commented when Graham wrote about his large HAT holding - it is helpfully honest when you share the level of your enthusiasm for any particular investment - what more disclosure does anyone want? it is very easy to criticise and in my experience such comments are driven by jealousy as they are certainly emotive and not analytical in nature.
pls excuse using SCVR to post other than about RNS but wanted to show support.
I'm amazed at why people ave criticised Paul for getting it wrong on RBG, but that's also a lesson in why you shouldn't blindly follow a tip and should do your own research.
For any company that it's possible for me to personally experience or see in action I will look out for it. In the case of Revolution my local branch at the time opened, stayed largely empty and after just short of a year shut down and re-branded. So personally I never understood the constant media hype around the business, based on what I saw. In my opinion, I don't think numbers alone are always enough for me to invest. It was a similar case with Sports Direct.
Paul, I don't agree with you regarding the future of gTLD's in which my family are involved. With regard to Minds + Machines their success to date is based on .vip which has taken off in a big way in China. Ironically this appears to have possibly been by accident. When they announced .vip I thought who would want that and I am sure they had no idea of the interest it would attract in China.
They also have an involvement in .London which has had considerable sales. On the other hand some of the domains they own such as .horse are laughable in my opinion. I was a shareholder initially but became disappointed with the domains they were acquiring and got out.
Many large companies are acquiring domains that fit in with their own name or activity. Adverts can then direct people to specific areas of their web sites. Other domains in which we are investing and creating web sites link words together for which there are already considerable number of searches and which are far superior to most of those held by MMX.
As others have rightly said, as investors we must take responsibility for our own decisions.
I don't think it's fair that Paul is slated because he got it wrong on Revolution Bars (LON:RBG). For me his fundamental analysis of small caps is still the best I've seen.
Keep up the good work Paul!
Paul, can I please add to the voices on here asking you not to apologise when things don't work out as anticipated. I was, but no longer am a holder. I did lose money on it, but as noted above its the "I" that did it not the "you". Please do not pull back from giving an insight on why you hold your view. I have read all of them, and I mean all of them, agreed with many and for me perhaps most helpfully formed my own view as to why I have disagreed with some, BUT your analysis and comment has been a catalyst for my enquiry and my action and therefore my responsibility. Hope the move goes/gone well!
Apology completely unnecessary. If Warren Buffet was judged on his worst performing investment, none of us would have anybody to look up to. If you do get tempted to respond to the trolls I'd remind them of the fact you backed £G4M before everyone else had jumped on the bandwagon. Bit of a cliche but you win some, you lose some and this is coming from someone who has a fair bit invested in Revolution Bars (LON:RBG) .
Paul, don't apologise simply because people don't understand the nature of what you are doing here. They should either learn or go elsewhere!! I am inclined to agree with your macro view. It is always difficult to understand how anyone would sell when things are looking good so perhaps now is the time.
No need to apologise Paul, I think most of us come here for your clear analysis and honest opinion, not instructions on how to run our portfolios.
Getting it wrong now and again is a statistical certainty in this game and so long as you are right more often than wrong then all is good (and your BMUS stats speak for themselves).
I would hate to think this episode will change the way you write as I value very much the work you put into these reports (Graham too of course) and it's one of the reasons I subscribe.
I personally was out of RBG before the big drop but probably due to chance and other stocks needing my limited funds.
Good afternoon all,
I too was warming to the Revolution Bars (LON:RBG) "story" but I felt at 200p+ the risks were meaningful and wider market toppy, so I held back, setting an alert for a sub 200p price. I use a the stocokopedia alerts a lot and I don't usually pile in (or out) when they are hit, but Iook at the numbers and the news again at that point and sometime act, but frequently set a fresh alert having considered the numbers, valuation metrics, news flow etc.
Fortunately for me, I now have what I believe to be a bargain entry point for Revolution Bars (LON:RBG) and have started to build a position. I beieve the yield is quite safe, the problems are fixable and the management, whilst humbled I hope, will learn. I also think it may be "in play" or will be soon at under 4x ebitda - assuming that this years outturn will in fact be close/similar to last years.
I've occasionally bought stocks after profit warnings and am well aware of the excellent research this site has done on this area. Many should be avoided, but slavishly following stockmarket "adages" like "never catch a falling knife" is to me as stupid as not studying the numbers and the news and substiuting silly rhymes with exercising rigorous judgement about valuation, and management ability. The last "falling knife" I caught was IG Index (at £4.66 / 7% yield) and this seems to be working out well and slightly proving the exception to the adage followers. I think Revolution Bars (LON:RBG) is in similar territory - overdone and now offering serious value but not without risk. I'd be happy to hold it without a substantial growth story, more as a value play and good yield. It's in the right place in premium bars and the upside from a revamp and fresh focus on food could be material.
Don't we all read this daily blog precicely because we want Paul to express his views. Without these is's just regurgitating the news. If anything it's refreshing that he too is as fallable as the rest of us. I say keep it up Paul!
I agree 100% with your comments Paul. The analysis here is outstanding & only the overall record should be considered.
As for boards, well there are too many rude people who make pointless criticisms. I suggest the way forward it to ignore other boards and kick them off this one, so we keep it constructive.
Re Minds + Machines (LON:MMX) the growth in the .vip domain is being driven by China.
Paul
Even the best don't always call it right, Warren Buffet with Tesco for example. I am sure I recollect Peter Lynch saying in one of his books, 'One Up on Wall Street' perhaps that if your investment decisions are more often right than wrong, you will do very well over time, getting 7 out of 10 comes to mind. So as difficult as it sometimes is just reflect on all the good calls that you have made and helped others make, Avesco being a formidable case in point.
One of the many things I like about Stockopedia is the quality of the discussion board, both in terms of the knowledge of the contributors and the respect shown. So no worries Paul onward and upward.
On the matter of Zytronic I suspect that a reason for the recent price movement may be a pending upgrade to eps for the year to end Sept, if you look at the TTM it suggest 30.2p as opposed to the 28.6p currently shown. This was alluded to in a recent review of the company by Phil Oakley.
Jonno
Actually you can do very well even if you lose on a majority of your positions, so long as your average profits exceed your losses by a nice margin.
Just a question on Fevertree Drinks (LON:FEVR) being 'comfortably' ahead of expectations. I am a bit unclear on the actual meaning of words like 'comfortably', 'materially', 'significantly' and 'substantially' in this context. I've discussed the difference between materially and significantly before (which is unclear!) but not 'comfortably'. I assumed 'comfortably' was pretty bullish i.e. better than 'materially' or 'significantly' but without being clear by how much, but Paul you seem to think otherwise? Just wondered what others understood by these terms in case I'm misinterpreting them...
There is no consensus agreement on what these terms actually mean, but someone suggested this in a SCVR comment last year:
That got Paul's seal of approval in the following day's SCVR.
I have to laugh because I've got the the same reference taken from the same SCVR. Not sure how accurate it is though because if you look through the RNS feed they have used 'comfortably' before:
15/05/2017
‘will be comfortably ahead of current market expectations.’
24/01/2017
‘Therefore the Board expects that the outcome for the full year will be materially ahead of its expectations.’
07/11/2016
‘will be materially ahead of current market expectations.’
19/05/2016
‘will be materially ahead of market expectations.’
14/03/2016
‘We have had an encouraging start to 2016 and look forward to the future with confidence.’
25/01/2016
‘Given the strong sales in the final two months of the year, the Board anticipates that the outcome for the full year will be comfortably ahead of its expectations.’
04/11/2015
‘Given the strong sales in the period to date, the Board anticipates that the results for the full year will be materially ahead of Board expectations.‘
08/07/2015
‘Given the strong sales in the first half of the year and in particular in June, the Board anticipates that the results for the full year will be materially ahead of board expectations’
I think that my over analysis of terms is ridiculous though; maybe they thought 'comfortably' sounded cool and they were sick to the back teeth of using the term materially conversely maybe their guidance is closer to market expectations than people want to believe, time will tell
Thanks for digging all this up. Yes agree the distinction maybe does not mean much in this case and shouldn't read too much into it ( though it seems materially may be vaguely more than comfortably in general)
Thanks for that - v helpful
Good luck there over the weekend Paul and thanks for the input today as always.
Just need to echo the above - RBG was one of my biggest holdings (c10% of portfolio), so am nursing a significant loss at the moment. BUT, i bought into this company based on my own research, and after taking your ruminations on board (along with another whose opinion I sometimes listen to - my father!).
I'm still delighted to say that my losses on RBG are significantly less than my gain on Avesco last year! Ignore the BBs (as you seem to be doing - although the temptation to feed the trolls must be great).
Good luck with the move.
Paul,
We all make our own decisions and should be able to live with them , your inputs are a valuable resource and I for one can say that my investment decisions would be a lot poorer without the benefit of your views. Keep up the good work and don't change your style.
I think you are far too quick to apologise Paul. If people rant and rave because they don't want to take responsibility for their own investing decisions or if they lose money because they can't be bothered to do their own research, well that reflects more on them than it does on you.
Making the occasional loss is part and parcel of the investment journey, particularly in small caps, so allowing for this needs to be built into the decision-making process through a clear understanding of risk-based position sizing and when to scale up or down. People following these principles would be able to accommodate a 40% hit on one investment without bringing a load of aggro on themselves.
I would hate to think your writing might become more 'fence-sitter' in style because you don't want to come across as too enthusiastic.
Paul,
It genuinely pains me to see you apologise - I've learnt so much from you over the years (as I'm sure many of your other followers have as well) and for this I am so grateful. No one - literally no one - gets the future right 100% of the time (unless you can time travel?!) and as I have learnt from yours and Ed's articles, investing is all about probabilities. Even if something has a 99% chance of succeeding, it still doesn't mean it will.
I haven't formed an opinion yet on RBG - the profit warning guide that was released by Stockopedia really resonated with me, so I don't hold a position in RBG (neither long nor short). Perhaps I will wait for another update/RNS whenever that may be and then will reassess.
Thank you for all you do.
Nick
I echo the sentiments already expressed here, and state again as I've done in the past I read the column mainly for the insight into your forensic analysis of the stocks you examine, in the hope I can pick up just a few of your skills. Keep up the good work, your are an educator and not a mere tipster.
On another note, the AGM update from Card Factory (LON:CARD) is positive, and the promise of a return of cash to shareholder later in the year is nice too. However I don't get how the statement, "after normalising for the impact of last year's leap year with the equivalent prior year period including one extra trading day" applies to the gift card business? Last time I asked, all my friends & family had the same number of birthdays in a leap year as any other year (I don't know many people born on 29th February). Also as far as I'm aware there are the same number of special occasions each year (Christmas, Easter, Mothers' day, Fathers' day, dogs' day, etc). If anything the extra day is an extra day of overheads for a card business. It is not like they sell food, drink or entertainment (all of which would benefit from another day in the period). Come on Card Factory, don't you know your own business?
(Long on CARD and RBG)
Happy to see Card Factory (LON:CARD) Factory projecting stable to upper end of expectations for results. My remaining portfolio performance is pretty marginal at the moment due to some market retrenchment and a few company wobbles.
The biggest issue seems to be non liquid stocks which have wobbled. They take you down hard.
Keeping a bit of cashed in profits on the sidelines.
Maybe after June 8th we may get a bit of a bounce?
Hi Paul
I hope you will also be apologising for the 99.9% of your reviews which are accurate and incisive (albeit without making any recommendations) and have no doubt helped readers make a great deal of money :-)
Your and Graham's daily articles plus David Smith's Economics articles in the Times and Sunday Times are about the only writings I view as absolute must reads, so long may they continue.
Thank you and Regards, Martin
I agree with what shanklin100 says about Paul. Unfortunately, I don't agree with some of David Smith's comments in the Sunday Times and I had an exchange of correspondence with him a few weeks ago when I considered that his headline statistics regarding trade between the UK and EU were extremely misleading. In fact the negative reponse the ST displayed towards Brexit last year when a positive attitude was required and the continual printing of reader's letters from people who can't get over it has this week lead to me cancelling a newspaper I have been buying for the past 40 years!
No apology and no change of style needed Paul.
Does anyone have any ideas as to why Zytronic (LON:ZYT) has popped up 4% today? It's not like it to move that much overnight, more of a plodder generally.
Hi Doug
I think Zytronic (LON:ZYT) is up as a delayed response to interim figures released on 16th May. These showed some much needed sales growth. It's also a superstock and technology companies are generally doing quite well at the moment. Maybe it has been tipped somewhere too.
doug, re: Zytronic (LON:ZYT) - these shares are pretty illiquid and it doesn't take much buying or selling to move the price. As you say, it is generally a quiet share with nothing much happening between reporting periods and dividend payouts (worth noting perhaps that the share price held up very well on the last ex-divi day) which I take as a huge positive. Worth following their Twitter feed as well which is far more active than any bulletin board discussions.
I didn't buy in to the Revolution Bars (LON:RBG) story and expressed my scepticism here so it's not as if the debate on this board was entirely one sided.
The worry now must be that management are not in fact that incompetent and that it's the underlying format that isn't strong enough to sustain the size of roll out planned in what has become a very crowded market place.
Very well said Paul, I like most took a hit on RBG but this pales into insignificance compared to the knowledge you and the rest of the team at Stockopedia have imparted on us.
People need to take responsibility for their decisions and if they don’t it’s their problem.
Keep up the great work..
Re. Revolution Bars (LON:RBG) Today's edition of Shares Magazine has a piece on Revolution Bars.
The headline says it all " Revolution Bars has a major credibility problem " " Two feeble excuses and one major cause for concern"
The major concern being the slow take-up of the new style Revolucion de Cuba bars.
The writer of the article doesn't rule out another profit warning.
As Paul says DYOR
Hi Ramridge,
I've not read the Shares mag article, but the points you mention are reasonable.
Mgt at Revolution Bars (LON:RBG) have definitely dented their credibility, quite seriously.
On the take-up of the Revolucion de Cuba bars, I think Shares mag has missed a key point there. The slower build up in profitability of new sites is down to cost over-runs. As stated in the profit warning, they're actually meeting the budgeted sales & margin levels. However, the format is proving more labour-intensive than previously thought.
I remain of the view that this is fixable. They clearly need to simplify the cocktails menu, focusing on the most popular, and quickest-to-make cocktails. That would also reduce what must be a considerable expense training staff in how to make dozens of different cocktails.
If mgt can't sort it out in the next year, then I think a new CEO would be in order.
A far worse problem to have, would be if LFL sales were falling. But they're not - they're still positive. Mgt need to really focus on controllable costs, and getting staff to work smarter & more efficiently, rather than just slashing rotas (which would damage the business).
So all fixable in my view. I've seen far worse problems. Whether this management are able to fix things, is in some doubt. They should be able to, but we'll have to see.
Regards, Paul.
Anyone who can't take personal responsibility for their own investment decisions shouldn't be investing. Anyone who doesn't take personal responsibility for their investment mistakes won't learn anything from those mistakes.
As Trident says above. We all seem to be adults here. We know that this is an information forum, not a tip sheet. We thank Paul and Graham for their insights, experience and comments but I believe that we take our own investment decisions and we accept responsibility for them.
Hi Paul,
As you say we all live and learn. Apart from being insightful and informed your comments are often also infused with humour; absolutely fantastic, keep it up!
With thanks,
Peter
Well said, well reasoned & well thought through, but please Paul - Absolutely no need to apologise - whatsoever! As you say, it is people's responsibility to research and be accountable when they themselves press the buy button! I say this as Revolution Bars (LON:RBG) was my largest portfolio position (~9%). I sold the day of the PW and moved on, but would never dream to try and pass the buck and deflect blame rather than look what I could have done better.
Paul
We are all grown ups, and no-one should blame you, if indeed they are. These are shared ideas, and we are grateful for that.
Bulls make money, bears make money, pigs get slaughtered.