Small Cap Value Report (Thu 1 April 2021) - BOTB, CARD, MEAL, D4T4, WEY

Good morning, it's Paul here with the SCVR for Thursday.
Timing - TBC
Agenda -
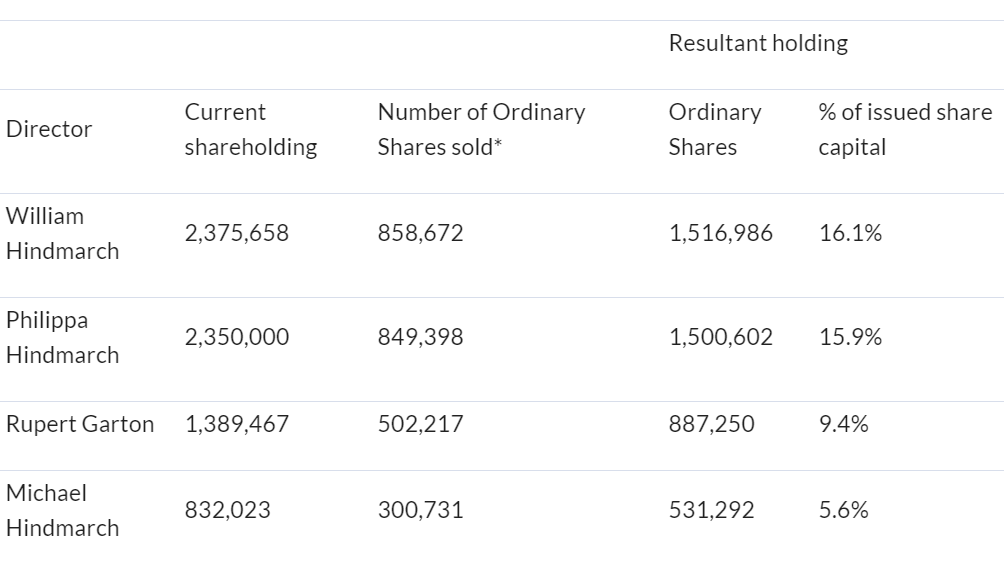
Best Of The Best (LON:BOTB) (I hold) - Secondary placing. Directors sell down about a third of their (unusually large) shareholdings at £24, a surprising discount.
Card Factory (LON:CARD) - banks grant another 1 month waiver of covenant breaches. Why has share price been so strong, when an equity fundraising is so badly necessary? Very high risk in my view.
Parsley Box (LON:MEAL) - I've reviewed the AIM Admission Document.
D4t4 Solutions (LON:D4T4) (I hold) - 6 contract wins & "comfortably ahead" trading update for FY 03/2021. Looks good.
Wey Education (LON:WEY) - Recommended takeover bid at 47.5p, a nice 46% premium.
.
Best Of The Best (LON:BOTB)
(I hold)
Share price: 2400p (placing price)
No. shares: 9.38m
Market cap: £225.1m
Proposed Secondary Placing - RNS issued at 18:00 yesterday
For anyone not aware, a secondary placing is where existing shares in the company are sold by a large shareholder(s) (often founders/management, or a cornerstone investor like a private equity firm). So the company itself doesn’t receive any money, and the number of shares in issue remain the same. This method is used when the market liquidity is too small to soak up the number of shares that the seller wants to sell. So it avoids market disruption, by placing large blocks of shares with institutions, in one go.
In this case, there were market rumours recently that, once the FSP (formal sales process) fell through without a deal, management might sell some of their very large shareholdings to institutions in a placing. So this secondary placing didn’t come as a surprise.
Details -
- 2.5m placing shares, at £24 per share, £60m worth. 26.7% of the total company.
- 41,666 shares at £24 = £1.0m also available via Primary Bid - very small, so just a fig leaf offer really. I think they should have done a lot more through Primary Bid, which would have improved liquidity by increasing the private investor shareholder base.
- Finncap organised the deal.
Result of Secondary Placing - RNS issued at 07:00 today
Placing was oversubscribed - they usually are, because people often apply for more than they actually want, expecting to be scaled back. Also the price discount here made this placing highly attractive - the market bid price was £28, so being able to buy at £24 is a complete no-brainer. I don’t understand why such a big discount was offered, I think they under-priced it.
Placed 2,469,352 shares, of the 2,500,000 - I’m not sure what the shortfall of 30,648 shares pertained to, I’ll ask around. Ah mystery solved, these seem to relate to an exercise of options, immediately sold. So the total is 2.5m, all the shares offered.
All the PrimaryBid 41,666 shares were sold. Judging from the comments last night in yesterday’s SCVR, there was a lot of demand, and people were complaining they couldn’t secure any shares on PrimaryBid.
As you can see, after this large secondary placing, Directors still hold 47% of the company, so they still have massive skin in the game.
.
My opinion - I certainly don’t begrudge the Directors banking some of their paper profits. I’ve held this share personally for all the time these SCVRs have been around, about 8 years. It’s been a major multi-bagger, rising c.20-fold in that time. Most of the gains have happened in the last year.
Being a passenger on this journey with management has been a real pleasure. You couldn’t wish to find a more open, honest, and ethical management team. They’ve always treated minority shareholders well, taking relatively modest remuneration for themselves, and sharing the spoils of success equally, with frequent special dividends. Also they’ve welcomed ideas from shareholders, on ways the competitions could be developed, etc.
Having put 20 years hard work into this project, and making us all a lot of money, I’m happy for the Directors that they’re taking some cash off the table. They also retain such large holdings, that this shouldn’t impact their level of motivation or commitment, so it’s fine by me. Worries that Capital Gains Tax (CGT) might rise in future, could have been part of the motivation to part-sell their holdings, possibly?
There are two issues that could have been handled better though, in my opinion -
- Price discount (£24/share) was about 20% to the mid-price of 3000p, which strikes me as excessive.
- Primary Bid - nice to see, but £1m out of £61m total seems little more than a fig leaf. I think there would have been more demand, and it’s left a trail of disgruntled punters who couldn’t get hold of stock.
Hopefully this should improve liquidity in the shares, which has been a big problem in the past.
I'm happy to keep holding my shares permanently. It's a "coffee can" holding for me (i.e. hold forever).
.
.
Card Factory (LON:CARD)
73.6p - mkt cap £251m
Liquidity Update - from yesterday
Card Factory, the UK's leading specialist retailer of greeting cards, dressings and gifts, today issues an update regarding its liquidity.
This share is a really bizarre one. In normal markets, this share would have collapsed to something minimal, say 10p or below. Why? Because the company is highly indebted, in breach of its banking covenants, and clearly needs an urgent equity fundraising, likely to be highly dilutive.
However, we’re not in normal markets. The unprecedented stimulus from QE, funding deficit spending on a scale not seen before in peacetime, and numerous support & guarantee schemes from the taxpayer, mean that many companies which would normally have gone bust, are able to limp on.
This seems to have emboldened some investors, who seem to be completely ignoring solvency & balance sheet risk. The frustrating thing is, that (for now anyway) it’s working - high risk punts have delivered great returns in the last 6 months. New investors are, in my opinion, learning very bad habits. I saw the same thing in 1998-2000, in the TMT (tech, media, telecoms) boom. The most ridiculous speculative shares became major multi-baggers. Anything with a story that sounded good, would rocket to the moon (why stop there?!). Fortunes were made, and then mostly lost, as the bubble burst in March 2000, and repeated downward plunges occurred, interspersed with powerful rallies that sucked people back in. By late 2002, many former tech darlings were down 99% or more. Some even traded at less than half their own net cash.
My point is that, having seen how a speculative bubble ends, it's important to remember that, and recognise that the buoyant conditions we're experiencing at the moment won't last forever. I think there are lots of opportunities to take advantage of, and make money right now, and I can't see any reason why speculative conditions would suddenly end. Maybe a correction, but I think we could have a couple of years more euphoria from the markets, because there's so much money sloshing around from QE & stimulus measures. And little to no chance of interest rates going up. However, I really hope newer investors realise that the current boom times are not normal, and at some point, will end badly - booms always do end badly.
CARD is limping along from one month to the next, with short term one month waivers from its banks being announced on the last day of each month. That’s a highly precarious position to be in.
Yesterday on 31 March 2021, the banks once again gave another month’s grace -
Further to our previous announcements, we are pleased to confirm that constructive discussions with our banking syndicate continue. The banks, who continue to be supportive, have provided further waivers in respect of anticipated covenant breaches through until 30 April 2021, taking account of the Company's cash flow projections, subject to certain conditions.
Logically, it does make sense for the banks to be supportive. Interest rates are very low, so rolling over problem debts incurs little cost. Also, with shops due to re-open shortly, it makes sense to keep the company trading, and hopefully begin to generate positive cashflows again, to reduce the debt pile.
We are hopeful that our stores are able to reopen for trading during April 2021 and look forward to welcoming our colleagues and customers back into our stores.
The key difference with the next re-opening, is that much of the adult population, and most vulnerable people, have now been vaccinated. Therefore, that changes peoples’ behaviour, and makes them more willing to venture out. Hence I completely understand why the banks would want to allow CARD more time to sort things out, and get its shops open again. Pulling the rug out from underneath the company at this point would be counter-productive.
However, in the background, we can be sure that the company will also be under a lot of pressure to do an equity fundraising, on who knows what terms? Logically, such an emergency equity raise would be at a deep discount, due to the risk. However, we’re not in a logical market, we’re in a roaring bull market where it doesn't take much to convince people of the upside case.
As mentioned before, I think the successful IPO of Moonpig (LON:MOON) might have been a game-changer for CARD. If it can convince investors that it has the opportunity to be the next Moonpig, with a chain of cash generative shops as well, then investors might have a punt on it, in a fundraising.
My opinion - to my mind, this share is priced illogically high, given the perilous state of CARD’s finances. Investors seem to be ignoring insolvency risk, and the risk of heavy dilution from an equity fundraising that seems inevitable. Even after it’s refinanced, CARD still has a lot of catching up to do with more advanced internet competition such as Moonpig.
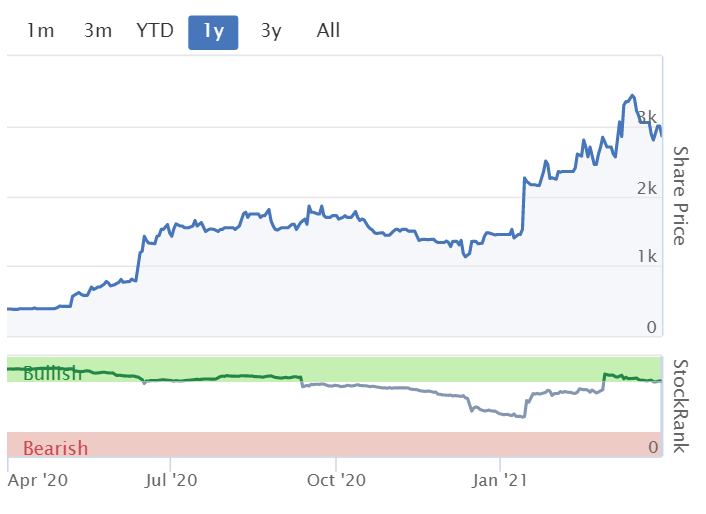
To me, risk:reward looks absolutely terrible with CARD shares, and I have no idea why this has happened to the share price (see chart below). Also, why is the StockRank so high? Maybe I’m missing something?
.

.
Parsley Box (LON:MEAL) (Parsley Box)
185p (floated at 200p this week) - mkt cap £76m
I skimmed through the AIM Admission Document for this new listing yesterday. They seem like daunting documents, typically 100-200 pages. However, with practice, you can skim through and ignore most of it, just homing in on the key points. I tend to read through most of the first section, about the business. Then have a quick read of the historic financial information, and that’s pretty much it - by that point I’ve usually formed a view on whether I want to research it further or not.
Key points I noted down -
AIM listing, at 200p
8.5m shares sold, split;
- 2.5m new shares - raising £3.9m net of fees [£1.1m fees! Ouch] for the company
- 6.0m existing shares sold
Total shares in issue after float: 41.9m, so only a small percentage of the total shares have been sold (6.0% new shares, 14.3% existing shares)
Finncap did the deal - who do a lot of smaller caps, and are private investor friendly I find
Market cap on float was £83.8m (200p * 41.9 total shares in issue)
About the business - providing ambient temperature, long-life ready meals & other food/beverage, direct to consumer via easy to use (in my opinion) website. Product can be stored in a cupboard for 6 months, serving a niche. Demographic is over 60s, and I think is probably more niche than that - maybe for people who are struggling to live independently, can’t go shopping or cook for themselves?
Product itself - I ordered a box of 10 ready meals. NB I am not the target demographic, as I found the portion sizes far too small, but apparently they suit elderly people. Taste was quite pleasant (apart from the fish pie, which was horrible). Strong savoury flavour, and quite salty, meat cut into tiny pieces, so I think they’ve clearly designed the product to suit the palate of older folk, which makes sense. Easy to store in a cupboard. Microwaves fast. Needs to be served with some veg I think, and my Mum & her neighbour also made this point. So if you’re going to microwave or boil some veg, then that undermines the whole point of having ready meals in the cupboard.
Very rapid revenue growth, from founding the business recently, in March 2017,as follows;
2017: £252k revenues
2018: 3,082k
2019: 6,111k
2020: 24,376k - huge growth, driven by massive marketing spend of £5.8m, and benefit from lockdowns
Now the bad news - it’s heavily loss-making, due to the big marketing spend. £3.2m loss for 2020.
Director remuneration increasing, from £105k pre-float, to £250k post, for CEO
Audit reports - were qualified for 3 years, due to auditors not attending stock counts. I can see why this might be an oversight in year 1 of a startup, but 3 years on the trot seems a bit sloppy.
Active customers 154k by Jan 2021. Selling 900k items per month currently.
My opinion - it’s an interesting niche, but I don’t think the business model has yet been proven - it’s making heavy losses. Personally I would rather wait to see what level of profitability can be sustained in future, with more normal levels of marketing spend?
Do customers repeat spend? I think it looks binary - people who like the product might enjoy the convenience of ordering from the internet, and not having to worry about use by dates, etc. But if you can order product online, why not just order proper groceries from any of the big supermarkets? Maybe MEAL customers might be relatives, ordering the meals for a vulnerable or sick loved one? It all feels a bit niche to me.
It will be interesting to see how it pans out over the next few years. How they arrived at £83m market cap, for a loss-making company, is anyone’s guess. There again, Deliveroo is loss-making too, and that’s valued in the billions.
Webinar is today at noon (apologies if you’re reading this too late, but I expect there will be a recording next week) - details here.
EDIT: Management come across really well on the webinar. They're on top of the numbers, and answering the questions in an open way. The re-order figures are impressive. £20 cost of customer acquisition, and they say payback in 6 months. Re-order size is larger at about £43, versus £23 for initial order. Strong emphasis on customer service. Looks good, I'm warming to this share, will add it to my watch list.
.
D4t4 Solutions (LON:D4T4)
(I hold)
320p (up 6% at 11:38) - mkt cap £129m
New Contract Wins & FY21 trading update
Companies issue contract win announcements all the time. The key point is whether they raise profit expectations as a result of the contract wins.In this case, they do raise expectations, so it’s a positive trading update.
Six new contract wins in key sectors
Revenue of c.£3m will be recognised in FY 03/2021
Justifies previous mgt confidence in the pipeline - true, D4T4 mgt has a good track record of confident outlook comments being followed through into decent contract wins & results, even when they had to recoup a lot in H2 after soft H1 periods.
Guidance upgraded -
This will result in the Group reporting results comfortably ahead of current market expectations for the year ended 31 March 2021 at the adjusted PBT* level and provide a healthy year-end increase to the Group's ARR** run rate as it begins FY22….
* The Board believes that consensus market expectations for 2021 prior to this announcement, were as follows: Revenue: £21.8m; Adjusted PBT £3.1m. Adjusted profit before tax is calculated before amortisation of intangibles, one-off reorganisation costs, foreign exchange gains/(losses) and share based payment charges.
** ARR (Annual Recurring Revenue) is the amount of revenue at a point in time that is expected to recur within the next twelve months.
Looking at the StockReport, it shows broker consensus which is consistent with these numbers, with EPS of 6.81p. Comfortably ahead, what does that mean? EPS of maybe 8-10p, or is that too aggressive? We’ll have to see what brokers upgrade their numbers to.
EDIT: Finncap has helpfully provided an update note, many thanks to them. Forecast revenue for FY 03/2021 is unchanged at £21.7m, Adj PBT is raised from £3.2m to £3.5m, and adj EPS goes up from 6.6p to 7.1p. Surprisingly modest increases, so the contract wins must have been in the original budget. Forex movements are noted as a drag. This gives a PER of 45 times FY 03/2021, so definitely not a cheap share! The market is clearly anticipating strong future earnings growth. End of edit.
Contract details - vague information is given (probably due to confidentiality agreements) about the customers concerned. They sound large, and international. I like that a lot, and place great emphasis on investing in companies which can demonstrate they’re winning business with big organisations, internationally. If contracts proliferate, that can then drive tremendous operationally geared increases in profit.
My opinion - this share is difficult to value, and looks expensive on a PER basis, and has had a variable track record.
However, it’s operating in a very much up & coming area, where customers achieve competitive advantage from using D4T4’s software to manipulate data and get commercial insights from that.
Therefore, I think it’s a really interesting share, and I’ve held for a while now. This announcement reinforces my conviction here. I don’t know what it’s worth, but want to continue holding, or buy more after this announcement today.
It’s one of my “coffee can” stocks - i.e. I’m planning on holding long-term, and ignoring day-to-day price movements, just focusing on the fundamentals & the long-term potential, rather than agonising over the valuation.
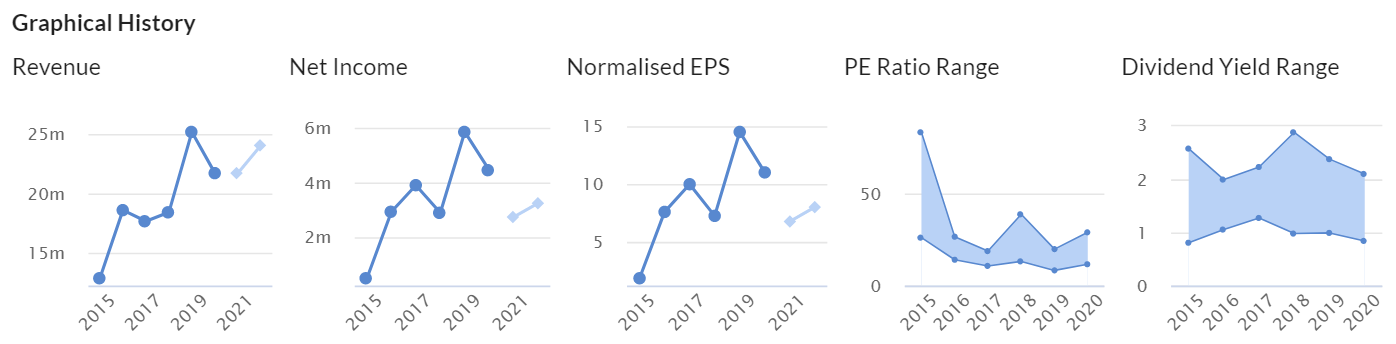
It's always profitable, but performance has been somewhat erratic, as you can see below.
.
.
Wey Education (LON:WEY)
46.5p (up 43%, at 12:45) - mkt cap £65m
Well done to shareholders here, Wey has agreed a 47.5p cash takeover bid, from larger Inspire Education Online Limited.
The price is a healthy 46% premium to yesterday’s close, which looks fair to me. I don’t think anyone can complain about this price, it’s a good price & a decent premium, which is paying up-front for several years’ future growth.
Support for the bid is 53.21%, so it looks like a done deal, probably, but you never know for sure - deals can fall through, or another bidder could emerge. Each situation is unique.
My opinion - Wey is certainly an interesting company, with good future potential. I was too tight to buy back shares I’d previously sold unfortunately, so missed out on this one. Well done to everyone here, this looks a good outcome. A bird in the hand, and all that!
.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

130 comments
Sorry what happens to my Wey shares. Not been following this one. Will I bep aid out & when. Excuse my ignorance.
CARD's Demise
I bought CARD early on convinced on their cradle to grave strategy of designing, making and selling cards. Unfortunately management became transfixed on opening more and more shops when foot fall was dropping in the market place. I wrote to directors saying as much and asking why they dont spend more on their online presence. Then Covid struck, I sold my shares at a huge loss but feel vindicated that they will either crash and burn or deleveraged by so much new capital as to be worthless. I am sad, they had a really good concept.
I share your concerns about Card Factory (LON:CARD) extending itself too far in these difficult times but, unlike you, will not attend the funeral at the very moment the company is being discharged from hospital.
Today is the first day of the release of lockdown and I am comforted that the expected rise of Covid cases predicted as schools returned did not happen. It may be that today's opening of barbers and other high street facilities will spike up more cases but by now, half the population has been immunised, at least partially and countless others have caught and ridden through covid and have natural antibodies.
Summer is on its way and here is a general air of expectation of cautious normality. I will be interested to see how the public responds to being released but, in general, I anticipate a return to spending on small ticket items. If we do see our high streets buzzing again, I'll be glad I held.
The Daily Mail carried this story yesterday.£Boo.I hold.
What annoyed me is the journalist said the difference in the price of the 2 coats was a difference of 150% when the correct figure was 50%.
The two prices were £27 and £18 a difference of £9.
Was this deliberately misleading or are most journalists very bad at simple arithmetic?
The BBC report said the coat was £34 more at Coast:
“Online retailer Boohoo is investigating why the same items of clothing were sold for higher prices across a number of its fashion labels.
The BBC discovered that Dorothy Perkins and Coast, which are both owned by Boohoo, sold exactly the same coat but it cost £34 more at Coast.
There are price disparities across a range of Boohoo brands, which also include Oasis and Warehouse.”
https://www.bbc.co.uk/news/bus...
I agree up to a point Paul, but I always thought it was customary to make some kind of token difference between the products to 'justify' the differential.
It is embarrassing to be caught out doing it in front of customers otherwise.
That seems to be borne out by the BBC's reports that Boohoo have reset the prices across the two sites (the first mentioned product is now £17 on both sites - whereas Coast was previously £34 more expensive - implying a 66% markup on an original price that was presumably profitable in its own right.
A significant cause for concern for me however would be that :
However the BBC article appears to show one garment with a neck label that says Dorothy Perkins at the bottom and a second identical garment (sold by Coast) with the same label but with the Dorothy Perkins label crudely cut off.
I say 'appears' because the image could have been doctored, although think what you will of the BBC that seems unlikely to me.
Unless that image is faked (and surely Boohoo should challenge it if so) then it would seem that Boohoo have chosen to use 'alternative facts' in order to rebuff this story.
I have been pretty much on the fence as to whether Boohoo are sufficiently crooked to make them un-investible I am now leaning quite heavily.
Boohoo (LON:BOO)
I agree up to a point Paul, but I always thought it was customary to make some kind of token difference between the products to 'justify' the differential.
I think you have to factor in here that boohoo only bought the dorothy perkins brand on 8th February - you have to expect that initial intengration with regard to brands and sales/stocking logistics will probably start out form a very crude position in that they just need to sell something under that brand name - also if there is surplus stock at that brand level that came as part of the acquisition that could be semi obsolete it wouldn't surprise me that they did what needs to be done to "get rid" of said stock and get some cash in - ie if dorothy pekins website wasnt up and running cut of brand name and sell elsewhere.
Unless that image is faked (and surely Boohoo should challenge it if so) then it would seem that Boohoo have chosen to use 'alternative facts' in order to rebuff this story.
I have been pretty much on the fence as to whether Boohoo are sufficiently crooked to make them un-investible I am now leaning quite heavily.
What a fantasic piece of detective work here - it does at face value make the comments seem contradictory to what one would expect - an obvious answer here is that boohoo itself acquired this stock as part of deal the deal on 8th February and perhaps was selling on Coast first as that brand was already established within boohooo and was only sold on the Dorothy Perkins site later on (may have been a matter of days). Note it was confirmed on 8th February they did acquire inventory as part of the purchase of the brand.
I have been pretty much on the fence as to whether Boohoo are sufficiently crooked to make them un-investible I am now leaning quite heavily.
Hi Gromley,
I have to say I don't normally disagree with you, let at least as strongly as I do on pricing of products by a company. Why is there such an outcry about this? What have Boohoo done wrong? As Paul has said, it is not illegal and if people are stupid enough not to shop around (so no surprise that a BBC journalist got a bad deal!) it's tough.
Far worse in my opinion is the exact opposite - price fixing. Why do all iPhones cost exactly the same no matter what retailer you go too? Why are they so much more expensive in the UK than the US? As it happens I need a replacement key for my car - why does it cost me £500 when it only costs two quid or less to make?
Everyone just blindly accepts this and yet it is much more fundamentally wrong and against the consumer's interest than some cheap crappy fake fur coat that Boohoo are selling for £27. The jury was out for me before, but now it's difficult to see beyond a clear agenda against Boohoo at the BBC. As a public service broadcaster they should not have internal left wing agendas and use their position (funded by us) to attack commercial enterprises like this.
All the best, Si
The jury was out for me before, but now it's difficult to see beyond a clear agenda against Boohoo at the BBC. As a public service broadcaster they should not have internal left wing agendas and use their position (funded by us) to attack commercial enterprises like this.
That seems like quite a jump. What other Boohoo stories have the BBC run that you’d disagree with? I don’t recall any Boohoo stories that were made up either on the BBC or elsewhere, they just keep making elementary errors that suggest a company that doesn’t have particularly good internal controls.
As research by UK in a Changing Europe has shown, articles on the BBC about Brexit were universally condemned by Leave supporters for being biased towards Remain. The exact same articles were also universally condemned by Remain supporters for being biased towards Leave. Basically people read into this stuff whatever they choose to. But in a country dominated by right-wing media even relatively unbiased reporting looks left wing, I guess.
But as regards Boohoo, their problems started when they failed to act on the Fixing Fashion report from the EAC in 2019. When the problems with CV-19 spikes in Leicester factories linked to Boohoo occurred that left them as easy targets. As it happens the EAC isn’t finished with Boohoo yet – the Chairman wrote to Kamani last month requesting more detail on their compliance program and suggesting that he and Kane should link their enormous bonuses to fixing those issues rather than driving up the share price:
https://committees.parliament.uk/publications/4939/documents/49396/default/
In the end this will all be forgotten if the reforms are properly implemented, the enquiries into modern slavery in the UK are proven unfounded and the US decides not to block imports from Boohoo. If all that happens and the company executes well then the share price will go up, regardless of what the wokey wonks of the left-wing media write.
timarr
That seems like quite a jump. What other Boohoo stories have the BBC run that you’d disagree with? I don’t recall any Boohoo stories that were made up either on the BBC or elsewhere, they just keep making elementary errors that suggest a company that doesn’t have particularly good internal controls.
Where did I say I disagreed with any stories? I don't FWIW. I thought it was clear from my post that it is the agenda I have a problem with, and whether this kind of journalism is really part of the BBC remit and the type of journalism they should be aspiring too - we're firmly in red top territory with this latest article. In a world full of sub-standard journalism the BBC should be doing better with license fee payers money.
As for the rest of your post... I've no idea why you've gone off at a tangent about Brexit? Let's all move on. It's happened. End of.
All the best, Si
As for the rest of your post... I've no idea why you've gone off at a tangent about Brexit?
I was making, I thought, a fairly straightforward point about how our preconceived biases affect the way we judge articles. I see no evidence of, as you say, "a clear agenda against Boohoo at the BBC", in fact I don't recall anything other than factual reporting from them, including the piece in question, poor though it is.
Where we can agree is that this type of red top article has no place on the BBC. Sadly, we can expect much more of this and much less investigative journalism into real issues like price fixing. The former is cheap and easy, the latter hard and expensive and with the corporation facing 20% budget cuts on top of a decade of reductions in real terms proper journalism at the Beeb is likely to be hard to come by in future.
timarr
I was making, I thought, a fairly straightforward point about how our preconceived biases affect the way we judge articles.
No. You were using Brexit to make the point that I had preconceived biases! You were addressing me by making an irrelevant general point. That is quite different. Like you, I've read all the books on that subject so am very aware of my own inherent biases before I put anything down in writing. Several years ago, I happened to be watching the BBC News channel when they were filming live from outside Cliff Richards house waiting for the police to arrive. And we know how that ended. So let's not all think the BBC are squeaky clean on matters like this.
I still don't see why this article, three days later, is still the main story on the BBC companies page? But maybe that's just me because I don't take anything the media do at face value. It's a trivial story based on what could be a fake premise i.e. a BBC employee bought the same coat as a friend from a different Boohoo label. Most women I know would be so embarrassed they'd certainly not want the fact they'd bought the same clothes as a friend on the BBC website! They really wouldn't care about a £10 price difference :)
Where we can agree is that this type of red top article has no place on the BBC. Sadly, we can expect much more of this and much less investigative journalism into real issues like price fixing. The former is cheap and easy, the latter hard and expensive and with the corporation facing 20% budget cuts on top of a decade of reductions in real terms proper journalism at the Beeb is likely to be hard to come by in future.
It's also cheaper and easier to continue with an ongoing agenda than it is to go and find interesting new stories. Lazy journalism is writ large across the BBC, the fact that this article originally published on Thursday has been reheated by a minor edit to make it look 1 day old tells you all you need to know. The amount of funding available is no excuse.
All the best, Si
Hi Si,
I obviously didn't really get my point across well.
I absolutely agree that differential pricing by channel, market, whatever is quite fine. However as I said it customary to obscure it somewhat as the price do love to have a rant about it if they uncover it.
However, that wasn't the point that concerned me here.
Boohoo are quoting as saying that the goods were originally Coast and then subsequently sold by Dotty Ps.
That creates a reasonable narrative , that they were clearing their 'premium brand' (Coast) through their lower channel.
A much better narrative than that they were ripping off their coast customers by selling Dotty P 'tat' for three times the price to their Coast customers.
However, the BBC article purported to show the two coats - one with a Dorothy Perkins label and the other with an identical label with the name Dorothy Perkins cut off the bottom of the label.
This suggests that Boohoo are just plain telling lies about it.
Maybe there is a more reasonable explanation for the labels, but it seems they would rather make stuff than tell us about it.
The issue itself is pretty trivial, but it's what this says about their culture that would make me nervous being a shareholder.
The issue itself is pretty trivial, but it's what this says about their culture that would make me nervous being a shareholder.
It's utterly trivial and no reason for an article on the main part of the BBC News website. Does it look good for the company no, but so what, this looks like a branding/pricing decision made by a low level minion rather than a sign of serious corporate skulduggery. My point is:
1. Does the BBC News website normally have articles about trivial retail price differences on its front page? - NO. And yet you could easily provide many much more egregious examples from companies other than Boohoo, including serious price fixing and cartel-like behaviour.
2. So what purpose does this article serve other than as part of a wider narrative against Boohoo? - None whatsoever!
I'm not one of those Boohoo apologists that post on here. I think they have made some serious mistakes but this is not one of them. This reflects more badly on the level of BBC journalism than it does on Boohoo IMO.
All the best, Si
Sadly I think the answer is actually YES. I think it was only a few days ago that they were running a piece on the fact that Supermarket's "own brand" and "value brand" products are often identical (made in the same factory, with the same ingredients, the same process, just in a different wrapper).
That's an equally irrelevant story - I am aware of people who know this but actively buy the high priced item so as not to appear "cheap".
The supermarkets responses to this were very vague and disingenuous, but I don't recall that they directly lied on the subject.
I agree with everything in your post Simoan. Selling the same thing at different prices is wrong. But other retailers have done it and probably still do, but it’s always BOO that the journalists single out. Also there are endless ploys Companies get up to increase sales and/or revenues. E.g Insurers ripping off loyal customers who don’t check renewal rates and sale prices that are higher than pre sale prices, or doubling the price in order to advertise it as a half price offer etc etc etc.
Ken,
Can you identify and evidence a specific quoted retailer other than Boohoo (LON:BOO) that has sold the identical garment under different brand names at different prices? I suspect not but, if you can, did they also do so in so crass a way as cutting the brand name off the label or blacking it out?
To my mind, these latest stories are consistent with the many previous in what they say about the culture at Boohoo; quite simply, it seems to be a business with a bad culture and that is a very hard thing to change, especially if that culture is driven from the top down.
There are several specific reasons why I would not invest in Boohoo, but its culture of at the core of all of them.
Effortless Cool
Off the top of my head it has happened several times but I didn’t make a note of it at the time. Paul Scott who knows the retail sector so well might confirm. There’s little difference in selling the same item under different brand names at different prices and the same item under one name at different prices imo. Here’s a Marks and Spencer and Ocado example:-
https://www.theguardian.com/business/2020/oct/18/m-and-s-and-ocado-cause-anger-with-different-pricing-on-same-items-price-online-in-store
Amazon charges all sorts of prices for the same items and change their prices regularly. Prices for the same holiday or same flight vary enormously too.
I agree to some extent with your comments about the culture at BOO but they are improving it. . But yet again why is it BOO that keeps getting singled out? Working conditions in factories abroad are often scandalous across the whole retail sector including the luxury brands, but it’s BOO suppliers in Leicester that have hit the headlines. And working conditions in Leicester even at their worst are nowhere near as foul as similar factories in places like Bangladesh. Remember that terrible factory fire there killing huge numbers partly because escape routes were blocked?
BOO will be squeakier cleaner than most other retailers as they are being forced to address these issues. Wouldn’t it be good if the scandalous conditions in factories abroad got highlighted by the journalists so keen to target BOO, along with campaigns to shame retailers and the relevant Governments to do something about it? It would mean higher prices across the board, but this is why we can buy clothes for next to nothing both online and in shops like Primark. Clothes prices now are way lower than 30 years ago. That’s largely because of the switch from UK suppliers to sweat shop labour abroad.
Finally the coat example was months ago. I’ve no idea whether it is still happening nor on what scale.
Thanks, Ken, but M&S and Ocado are two different businesses so, whilst the practice described is no doubt unacceptable, is certainly not a valid comparison with Boohoo (LON:BOO). Similarly, your Amazon and holiday examples are not really relevant either. Changing prices regularly is not the same as charging different prices for the same thing at the same time; similarly different companies charging different prices for the same product is not comparable either (it is normal, in fact).
As to why Boohoo? I suggest you start by considering the extraordinarily crass approach they have taken to exploiting differential pricing across their recently extended brand portfolio. In my opinion, there is something rotten about this business; perhaps the BBC and other media share that perception?
As to why Boohoo? I suggest you start by considering the extraordinarily crass approach they have taken to exploiting differential pricing across their recently extended brand portfolio. In my opinion, there is something rotten about this business; perhaps the BBC and other media share that perception?
I agree there's always been a certain whiff about the company going right back to the profit warning within a few months of the IPO. When I invested it was very much with a peg on my nose. I didn't mind doing that back then but avoid companies with such dodgy corporate governance now.
Personally, I was astonished that they sold the same tat across the different brands, forget the pricing differential. That just destroys the brand identity, but then maybe they don't care given they only paid chump change for Coast, Oasis et al. Unlike others, I don't like this multi-brand approach of buying up tired old names, some of which went bust for a good reason. Whereas the original Boohoo brands at least had a freshness with the low cost test and repeat model pumping out constant new styles and ranges, it seems now they are slowly becoming the Sports Direct of fashion retail.
All the best, Si
Thanks, Ken, but M&S and Ocado are two different businesses so, whilst the practice described is no doubt unacceptable, is certainly not a valid comparison with Boohoo (LON:BOO).
Except that was also the case with Boohoo until 2 months ago, and they have said:
"Stock of the item in question was purchased and live on site by Coast prior to The Boohoo Group's acquisition of the Dorothy Perkins brand."
More on Boohoo (LON:BOO)
Just as a follow up, the BBC is now running a second story based on a reader of the first story getting in touch.
This story features a 'Karen Millen' skirt bought from them turning out to actually be an Oasis skirt with one Oasis label blanked out with marker pen and another crudely cut out and covered with a Karen Millen label.
Whether this kind of thing goes on more regularly in the rag trade and elsewhere I don't think is either here nor there. If this story escalates , then they have potentially debased all of the brands they bought in the last few years.
In any case I am now settled in my view that I am happy to have nothing to do with this company as an investor.
Quite!
Even if you are not troubled by their business practises you might be disappointed at their lack of competence!
Ms Sikora said she bought her skirt in June 2020.
Makes you wonder why it took so long to become headline news....
AIUI Ms Sikora's intervention was just a "me too" moment responding to the original BBC article which was more recent.
Whether it is good journalism or bad is largely irrelevant - the fact is that more than one major media outlet has had yet another chance to take a pop at Boohoo £Boo and its business practices. Selling the same coat for different prices might be ok in theory, but when the media sees a practice that feels sharp and reinforces an existing perception, its going to have legs. Once again they come across as spivvy market traders not an ambitious multinational. Increasingly frustrated hold.
CEO at £Meal as a very young man was CEO of Orbital of dot com failure, on the basis that he should have learned a lot since then.
I just want to say as a new member of Stockopedia how useful and informative these reports are. I really only joined to get the stockreports, these are a welcome addition, thank you.
Boohoo (LON:BOO) Free publicity again. Boohoo to probe price differences for same clothing
I saw that latest BBC attack on BooHoo (I hold). Differential pricing of the same/similar products, between different brands, is perfectly legal & normal. That's the whole point of up-market brands - they can charge more for the same stuff, as cheaper, higher volume brands, because they've spent money on advertising to create a brand image that people perceive as higher quality.
A lot of the designer brand fashion labels have their product made in exactly the same factories in low wage Bangladesh as the High Street retailers! That was made clear in a recent BBC documentary about the fashion sector.
This is a nice, short video about garment manufacturing in Bangladesh. It's definitely helping the country develop, and 4 million people rely on garment factories for their livelihoods. Things may not be perfect, but they're improving, and us buying things from Bangladesh helps the country develop, a very positive thing in my opinion:
I have ordered Parsley Box ready meals in the past.Initially when the first lockdown began as a means of having enough food in the house to cover an emergency.Their ready meals last 6 months without having to be kept in a fridge.I have ordered twice since then.The food is nothing special but the boxes have improved and are practical.The company is well managed
I got an email from Parsley Box today, offering 3 meals for £5. That's a tempting offer, and I ended up buying 12 meals and a half bottle of merlot.
Had a chat with my Mum this evening, and she (unprompted) told me that she had just ordered from Parsley Box, because they're doing a 3 for £5 offer LOL!
I'm gradually warming to the idea of buying shares in £MEAL although I'm not convinced yet, and think the market cap is much too high. But they do seem to have an interesting niche. I'd prefer to wait until they've proven the business model can work, and pay divis, without having to spend over 20% of revenues on marketing, as they are at the moment.
Also, the product really isn't very good. It's OK, if you're hungry, and don't have anything else in. I think 3 meals for £5 is decent value though, so would be happy to keep re-ordering at that price.
Hi Paul,
Re Parsley Box (LON:MEAL) , I am not a shareholder but really like the meals. The All Day Breakfast is lovely.
Hope to meet you in person again at a seminar one of these days. Zoom meetings are fine, usually, but no real substitute for actual social contact. Or beer.
Steve
Again from the FT, Gillian Tett's article on the implications of the Archegos affair is accompanied by an interesting comment from Reagan explaining how risks are being magnified and hidden on banks balance sheets.
I know this isn't small company stuff per se, but these issues will be affecting small companies too. What Archegos and Greensill/Gupta have in common is balance sheets hiding high risks, deficiencies in due diligence, and their bubbles popping now.
Remarkably similar to Wirecard.
And the financial crisis.
The FT is reporting that some of the invoices Greensill held from Gupta are false. Impossible to know how many such situations exist ATM, but there's a lot of due diligence not being done.
Hi Paul,
I read your Small Cap report daily and find it very informative.
Could I request an update on the what the current holdings are in your portfolio/s, particularly those stocks you regard as your 'coffee tin' hold forever stocks such as Boohoo (LON:BOO) and Best Of The Best (LON:BOTB)?
Many thanks
John
Excellent output from Paul and Jack over the past few weeks and as ever, stimulating input from the readership here. Thank you all.
Here's wishing you all a happy easter and see you in the next financial year.
cheers
Francis
Do tell us Paul, your dog, did it like the fish?
Wey Education (LON:WEY) Paul, we have Inspired Education offering 47.5p at some number of weeks in the future for Wey Education. To sell this today the market makers are happy to give me 46p. In a situation like this will Inspired Education be likely to be buying at any price on the open market for <47.5p. Or would market makers be actively trying to hoover up stock, knowing they can sell them on in a few week for around a 3% premium. Although 3% doesn't seem much given what they do.
Oh and I know its off topic....but how's the SuperSix
As someone who worked at D4t4 Solutions (LON:D4T4) for over 5 years, their super star product is Celebrus which majority of the top 10 banks use including Chinese banks so that is saying something.
Why do banks love this product?
I disagree that Celebrus is unique. It is just a Customer Data Platform. While they have integrations, APIs, etc to collect first party data from any customer-facing interface, so do many many other CDPs.
However, I don't work in the financial services space, so maybe they have many out-of-the-box integrations that work very well with other financial software used so it is less onerous to implement?
Never said the product is unique. It just is superior to its competition more so in the financial world.
Banks especially large ones have massively complex technology infrastructure, complex and expensive software release cycles, and stringent regulatory requirements and this is where Celebrus stands out where it makes it easier to collect and analyse customer data in real time.
I don’t work for the company nor hold this stock (anymore) but work in top 6 bank so happy to shed more light on this if needed.
Cheers
Not a small cap, but I recommend any private investor reads and listens to the Next (LON:NXT) (I hold, hopefully forever) results announcement. It is clear and full of lessons for any retailer. I think they could generate another revenue stream showing other listed plc's how to communicate results and outlook.
https://www.nextplc.co.uk/inve...
An extra bonus is that the numbers presented are all ex-IFRS 16 so they make sense, at least until the Appendix on page 60
Some good news from Intercede (LON:IGP) new order worth $3.4m, shares are up around 12%.
oI like and hold D4T4 also. Paul is right to point out that this has had a pretty rocky history - after all, only a few years back it was showing an OP exceeding £6mn and we are still some way off that now. Like many of the smaller software companies it has been quite late in adopting SaaS - which seems to me basically taking contract revenues over a 3 year (?) period rather than an big upfront payment for the lot. This improves the quality of earnings over time but has meant a notional squeeze on margins. But the management have twice now come up with a much better - and as promised - H2 after a weak looking H1 which gives one some faith in their competence. The simple p/e does look high but the company appears to be growing nicely and I expect margins and returns to be on the up as the SaaS accounts become embedded. In short, I also intend to remain a holder for the foreseeable future.
What worries me about D4t4 Solutions (LON:D4T4) is that the market is valuing it as having SaaS-like ARR-like revenues. And while they are making strides to do so, it looks like potentially ARR as of FY Mar21 will be circa £11m.
Compared to FY21 Revenue of £21.8m, and FY22 revenue broker forecast of £24m.
Which means even by end of FY22, I would expect ARR-type revenue to only be 60%, 65% of total revenue.
Which means still a lot of dependency on one-off license, installation revenues. Which does not support a circa 40x Forward PE for FY22, given the risk of potential revenue miss due to contract lumpiness. I do think there is potentially a risk of a profit warning due to delayed contracts, etc... and so this has gone onto my watchlist to pick up some shares when that happens.
On Innovaderma (LON:IDP) there was a very interesting InvestorMeetCompany presentation yesterday, for the full year results.
What struck me was how many times eCommerce and Digital was mentioned. Clearly the new CEO's strategy is to turn it into a DTC, predominantly Online, company selling its products at a more premium margin to customers directly. In addition, there were hints of top-line growth via geographic expansion, starting with USA and Australia, using DTC eCommerce as the way.
If the company can pull off the transformation to do more of their sales online, and DTC, the valuation could really re-rate. From being a basket-case brand and product company, to a "sexy" online DTC beauty company.
This could potentially lead to a multi-bagger over the next two years, driven by:
Also - does anyone have access to Research Tree and the Finncap note, and happy to share any highlights from the note and/or EPS forecast for FY21, FY22?
(I hold and contemplating adding to my position, but the £7m market cap means I don't want to hold too much of too illiquid a share)
Hi dahokolomoki, you are able to register with Finncap through its website and access the broker notes free of charge.
Innovaderma (LON:IDP) FY21 estimates are -£1m Adj PBT and Adj EPS of -4.8; FY22 estimates are 0.3, Adj PBT and Adj EPS of 0.8. Target price is 90p. I must say I remain unconvinced and it seems a lot to be paying up right now for no real profit until FY23. I may well be missing something though so will give the presentation a listen; thanks for pointing it out!
I agree that Innovaderma (LON:IDP) could be a multi-bagger although it will take time (I hold). There's a new board in place, new CEO and a new focus on direct to consumer sales using their newly beefed up digital marketing capability. I have a small position and will add more as the recovery story unfolds. I don't know if Paul has the bandwidth to have a look at their results from earlier this week but to be honest, they represent the dismal past rather than their seemingly optimistic future.
cheers
Francis
The jury's still out for me with regards Innovaderma (LON:IDP) . The IMC presentation from Blake Hughes was professional and positive. It was also overtly critical of the previous management and rather than seeing much radically different the message I came away with was; 'the old management weren't that good, under new management, onwards and updwards.'
That's not far removed from what Kieran Callan said at Mello back in November 2018 at the last changing of the guard.
No disrespect intended to Mr Hughes, but I think I'll wait to see some evidence at this stage.
Innovaderma (LON:IDP) - skinny tan reviews on https://uk.trustpilot.com/revi...
are a bit "meh". Then again - you got to take the validity of these reviews with a pinch of salt.
Cash bid for Wey Education (LON:WEY) announced this morning, 47.5p.
Best Of The Best (LON:BOTB) Primary Bid was not too bad in fact. I was notified today that I have been allocated 75% of the shares I applied for (I applied for 200 at £24) . I had visions of getting 10% or something and this being a complete waste of time as it has been with other recent offers ( Trident Royalties (LON:TRR) was less than 20 per cent and others even less). However, it was mobile app only and my first three applications were rejected without explanation. So a few technical problems may have put many off. There have also been a stack of other PB offers recently .....and a number of them have started firmly in the red.
Likewise, I got 75% of BOTB shares I applied for, so I guess they shut the applications once they were that much over and then scaled back. Happy with that little bargain!
You guys where lucky. I got the sum total of FA squared.
Primary Bid told me I had successfully subscribed, after my first attempt was rejected (for no reason) then after the listing closed, my subscription disappeared and I am left wondering just what kind of two bit operation they are.
That was my first time using them and they were utterly shambolic. Judging by Twitter a lot of other people also had issues with the App not working or their payments being rejected. All round a very very poor showing from Primary bid.
It defeats the point in trying to attract more, and possibly 'bigger' or 'better' companies to use your platform for listings, if the platform fails so completely.
One very annoyed ex-Primary Bid user.
On the Primary Bid subscription for shares in Best Of The Best (LON:BOTB) - I tried three times but the app kept rejecting my application saying that the payment had been rejected. As far as I can see all my payment details were correct and my bank didn't reject the transaction (they usually call me if they suspect a transaction). Left frustrated but picked up a few earlier today (Thursday) when the share price dipped).
Card factory have very high share of the £1bn UK card market and far and away most cards are bought in store. As soon as they open they should be highly cash generative I would have thought. Is it certain a raise is required?
As a holder of Card Factory (LON:CARD), I naturally read Paul's reaction with interest. What comes over, above everything else, is his frustration. Seemingly, mug punters keep buying but will suffer in the end. For my part, all I see is a business that is about to benefit from a huge surge of relieved citizens, ripe to spend their pocket money on the very low ticket items that Card Factory (LON:CARD) is ideally placed to provide. Online shopping is fine but, as we can see from attendances at re-opened garden centres, we appear to be a nation of addicted shoppers and browsers. The public seems to be desperate to get back to a sense of normality, even to the point of foolhardiness.
All that, of course is subjective. More telling by far, for me, was a recent video presentation by Card Factory (LON:CARD) which revealed how much time and resources the company spent on researching their potential market. I had no idea how much detail they concerned themselves with. While they acknowledge that theirs is a historically, steadily dwindling market, their ability to fine tune what they offer was impressive. If there is a shilling out there to be attracted, it seemed to me, they would find it. As a card buyer myself, I rarely find anything in their shops that I like. I'm not the buyer they focus on and they're right. If they depended on me, they would go bust. They know exactly what they are up to.
So, for a while, and certainly as we are soon to see some floodgates reopen, I'm a modest but relaxed holder.
Great Comments on £CARD.
Just shows SCVR writers have as much idea about how the stock market works compared to the average punter, so recommend everyone does their own research and make their own choices.
Card Factory (LON:CARD) Clear not without risk but here a link to my valuation of the company.
https://www.stockopedia.com/co...
BSV
Hi TangoDoc,
My job here is to flag up the risks. A company limping along one month to the next, relying on last-minute bank waivers on covenants, is extremely high risk -both insolvency risk, but probably more importantly that a dilutive placing is extremely likely, and probably already underway is my guess.
Once I've flagged those risks to readers, then my job is done. People can then make up their own mind about risk/reward, armed with the facts. As we relentlessly say here, we want everyone to do their own research.
I've got no idea what short term share prices will do, that's dependent on market sentiment, which can ebb & flow. We're not trying to predict that in these reports. We're long-term investors/analysts, not traders.
Good luck with CARD. It will be interesting to see how this pans out.
Regards, Paul.
EDIT: by the way, I'm not saying people buying are mug punters, they could have some insight and may have decided that the risks are worth taking. I wouldn't say I'm frustrated either. You're very much putting words into my mouth there, which are not really accurate. I'd say I'm puzzled that the share price has doubled, when the company is so obviously financially distressed, and in urgent need of a placing. One possible explanation is the Moonpig effect, as I said. It doesn't really bother me anyway, because there's no way I would take the risks here. You only need one to go badly wrong, and it makes a nasty dent in your portfolio, as I discovered trying to bottom fish on Conviviality a while back, and ended up blowing £30k by ignoring risk, which wasn't that obvious there anyway. Hence why now I'd rather be cautious. Everyone has their own approach, hence why I just flag up the risks, then people can do whatever they want. We're not trying to tell anyone what to do, unlike journalists who give buy/sell recommendations, etc. I've always stressed that I think that's wrong. We just discuss facts & figures, and give an opinion, with it being entirely up to each reader to decide for yourself what to do.
Hi Paul, your CARD commentary is super helpful and prompted me to finally pull the plug today with the share price at a 12 month high. I am with you in thinking that the risks outweigh the balance of rewards.
Hi Berksbee,
Card Factory (LON:CARD) , There was me think this could one for the Coffee can.
Selling is probably the wiser choice
Bluesky, earlier today I was of the same mind, Card Factory (LON:CARD) was at 73.2 pence and going back to it at 3.30 pm the price has defied gravity and is at 74.5 pence. I resisted selling at a hefty loss and decided to keep it in mind that should an Open Offer come about I could throw as much cash to it as I liked since my shares aren't in a full-to-the-brim ISA. The final outcome will be interesting and hopefully I'll not fall into the same trap as I did like Paul, with Conviviality which still rankles.
Hi Sliver Moon,
If there is an Open offer, I will be filling my boots also.
All the best.
BSV
Hi Paul.
Thanks for the review of Parsley Box/ £MEAL . I participated in the IPO but pretty sanguine about the initial mark down in the share price. As you say, it’s loss making at the moment but they’re in a land grab for market share so marketing expense will weigh on the financials for a while. $64 million question is whether the spend converts into sticky repeat order customers loyal to the brand or whether the model is fundamentally flawed and it just burns cash with high customer turnover and no long term profitability.
One slight niggle in addition to the increased exec remuneration increases you mentioned was that the first company RNS after the IPO was to announce a MIP for the top three executives for an aggregate 1.8 million shares/£3.6m. Poor timing to say the least.
https://www.investegate.co.uk/...
As an aside did you have a look at the Samarkand (OFEX:SMK) IPO? Interesting business (marketing/logistics portal into China for overseas exporters with some bells and whistles) although timing maybe not ideal given some of the recent higher level diplomatic frictions. Also of interest that they chose to launch on the Aquis Exchange rather than AIM.
Gus.
Hi gus1065,
Thanks for the prompt re Samarkand (OFEX:SMK) - I've been meaning to look at it for a while. Looks potentially interesting, although China risk of course. Trouble is, my broker says none of the spread bet companies will touch it - I do a lot of business through Spreadex, as it means no paperwork or tax. So that leaves me limited options, He also said liquidity is very poor.
Regards, Paul.
Hi Paul.
I just put a link on the Coffee Can thread at the request of another subscriber to some information on the Samarkand (OFEX:SMK) IPO that may be of use to you. As you say, China risk but in a way that is part of the opportunity - it’s too big a market for exporters to ignore (it’s by some considerable magnitude the largest global market for internet retail) yet it’s also very difficult for all but the biggest companies to break into because of the need for “boots on the ground” to manage payments, logistics and marketing etc., and that know how the regulatory system works. The company appears to have the USP (don’t know just how “U” that is) of having a scalable infrastructure that is proven to work, approved of by the Chinese authorities and available for hire to the SME sector. Risky but huge potential IMO.
In terms of liquidity, the issue was heavily oversubscribed and even though it was increased from £10m to £17m much of it disappeared into the pockets of the institutions. A reasonable tranche was made available to retail but only those regarded as Qualified PI’s. I believe there were about 100 or so of these according to an RNS issued by the company. There was no general retail pitch available via Primary Bid. I was able to get an allocation via the IPO Lead Manager, VSA Capital. As the issue was made via the Aquis exchange I think it will take a while for liquidity to build up as most of the share platforms don’t trade the shares electronically and it doesn’t look as though the issue was heavily stagged so it may well be a lot of “buyers to hold” (probably me included). You can see how few shares have traded since launch via the attached link.
https://www.aquis.eu/aquis-sto...
Gus.
Looks like there's a bid for Wey Education (LON:WEY) at 47.5p. Congratulations to holders (assuming you think this is a good price). I could never get over the Waterloo station advertising debacle a few years ago so sadly never bought back in.
cheers
Francis
I wondered who would pay that much for Wey Education (LON:WEY) then found it was Inspired which is one of the investments of Oakley Capital Investments (LON:OCI) which I hold... Hey ho.
Perhaps they will benefit from being part of a real business.
JohnEustace
I am just reading the 2020 Oakley annual report, in which I own shares, and it states that Inspired was sold outright in April last year having initially acquired a holding in the business in 2013. So this means that, like you, when I receive the cash offer for Wey Education shares, Oakley will not be involved.
Kind regards
Phillip
From reading your 10 box tasting session of £MEAL I was wondering if you were considering a move to food blogging Paul? But please don't give up the day job where you are a hugely valued essential of my investing day!
LOL thanks Chris! What interests me about MEAL is that opinions on the product differs a lot. So it's good to spark a debate about it. I was quite surprised when my Mum said she had tried Parsley Box products, and quite liked them. Several readers also recently said that they, or relatives, enjoyed them too. I did like some of the products, and they are handy to have in the cupboard as a standby.
£MEAL (no position)
Hi Paul,
I hope you don't mind me asking but how did your mum find out about £MEAL ?
I've never really thought about the marketing strategy for wiser people.
Thanks
A
Re Parsley Box (LON:MEAL) .
Of course I can't answer for Paul or his mother, but the company advertises very heavily on TV channels aimed at us oldies such as ITV4 and Yesterday.
Disclosure: I am a happy customer but not a shareholder.
Gostevie
Thanks for that, it's much appreciated
Mum said that she's noticed Parsley Box adverts all over the place - including those local papers/magazines with property ads, and infomercials (?). I told her that I was researching the company, and could she give me her feedback (she's 83) and ask around amongst her friends & neighbours. Lots of them knew about the company, and Mum said to me,"They must be doing well, because their adverts are everywhere! They can't fail!"
I didn't mention to Mum that they're running at a hefty loss due to the £5.8m marketing spend in 2020, because that would have started one of our "heated debates"! :-)
But it is interesting to me that the marketing spend Parsley Box is doing, seems to be hitting the mark with the target demographic.
I am wondering if Parsley Box (LON:MEAL) might have identified an under-served niche, which supermarkets, and maybe Saga (LON:SAGA) could then exploit themselves more profitably in future? I think if MEAL was say £20-30m mkt cap, I'd take a punt on it. But £80m is just too rich for me, especially as the product is really very basic. I think the vast majority of pensioners would want much better quality/tasting food. This is quite niche, in my opinion , so the total market size probably not that great. Plus there are other companies targeting pensioners with ready meals too. People do have fridges & freezers too, so storing them in a cupboard isn't such a big advantage. Maybe as backup food only?
It's enjoyable to chat about consumer product shares I think.
Regards, Paul.
But it is interesting to me that the marketing spend Parsley Box is doing, seems to be hitting the mark with the target demographic.
That's a relief - I never heard of them until here, this week (speaking as a very young 60 year old).....
Same here, never seen any adverts for Parsley Box (LON:MEAL) either, but have seen several for HelloFresh and Sosandar (LON:SOS) though. Saga (LON:SAGA) adverts are everywhere. I think it is quite is clever to sponsor a program, so even if people don't watch the adverts, they will probably see your advert, as is at the start and end of each part of the program. Sanderson's do this one TV series.
So they are not reaching everyone over 60, not that I'm interested in buying such products anyway.
3 meals for a £5 sounds ok but not much profit in that. Some of the extras are a rip-off, IMO, such as cakes and biscuits. But it may work, Naked Wines (LON:WINE) did special offers, such as £60 off and they did pretty well although the lockdowns no doubt helped.
Go up market and use COOKS as they have well balanced meals for one or two people. Not M&S but half the price.
Macfarlane (LON:MACF) had an announcement today of a new acquisition:
"Carters Packaging (Cornwall) Limited is a well-established business, based in Redruth, Cornwall, and is the leading distributor of protective packaging in the South-West of England... Macfarlane Group UK Limited, has acquired 100% of Carters for a maximum cash consideration of £4.5 million (including an earn-out over two years of £1.5 million). The expected net assets on completion are £0.9 million. For the year ended 31 March 2020, Carters generated sales of £4.2 million and pre-tax profits of £0.5 million.
They had a very promising acquisition last month as well, and the last results predict bright future for this packaging business!
Hi donQ,
Indeed, I read the announcement about Macfarlane (LON:MACF) (I hold) making a small acquisition, and thought it looked a good deal - a nice fit with the larger group, and a sensible price. Too small to comment on in the main report though, hence why I left it out.
The key point with MACF is that they report the numbers very conservatively, leaving in the goodwill amortisation. When you adjust that out (as almost all other companies do) then MACF's earnings are actually about 19% (from memory) higher. Hence it is a lot cheaper than it looks! When I figured that out, I bought a starter-sized position myself! I normally buy things with an intention of holding for 2 years initially, to see how it pans out.
Regards, Paul.
Good morning, I hope you all find yourselves well and green this morning. I have a question please that i hope any of you would be able to answer? I am looking at stock LSE:CCT (CHARACTER GROUP PLC ORD 5P). What is the meaning of the repetitive swings in the chart? I want to look at giving it a go but I'm not sure what the chart is telling me? Any thoughts?
Hi Lee. I forget all the detail but I believe they make quite a large percentage of revenue from making Peppa Pig products under licence and there was concern at some point that the brand owner (Hasbro??) might take the licence off them when it expired and start doing in-house Peppa Pig. I may not be 100% accurate of my recollections but I think this is broadly correct. I believe that subsequently the brand owner extended the licence but again you would be advised to check out the RNS feeds for an accurate story. I also seem to recall other readers of this fine bulletin mentioning excessive director remuneration but I also don't have any facts to back that up. Good luck.
Hi Lee
Character (LON:CCT) Are you asking why the share price say on the 5-day chart on google goes up and down? If that is your question - then this is because the upper price is the offer price (what the stock is being offered at) and the lower price is the bid price (what the stock is will be bought from you at).
Not sure whether your answer is as simplistic as this.....hope that helps.
I think Lee's original question is related to the Character (LON:CCT) chart, it is a bit more obvious on Tradingview - so why is the price headbutting 480 day after day ?
Gb (LON:GBG)
A curious announcement of the sale of a subsidiary business which accounts for about 3% of total revenues but no mention of the sale price.
Maybe AIM rules don't require the price to be stated at this level of % and maybe there is some confidentiality at play, but it is a little strange.
Paul - spare a thought for comment on D4t4 Solutions (LON:D4T4) contract wins/update on ahead of expectations please?
Certainly some spread on Best Of The Best (LON:BOTB) today it has been over 10%. Stockopedia price has gone from 2400p to 2720p in the last few minutes.
Really Stockopedia needs to move away from the last trade price.
Yes I agree that using the last trade as the price is not ideal. That seems to happen on other websites too.
The pricing system for small caps is ridiculous. For example, the quoted prices for Best Of The Best (LON:BOTB) (I hold) are currently;
Bid: 2600p
Offer: 2900p
I just queried prices with my broker, who tells me that the real prices now are actually:
Bid: 2712p
Offer: 2720p
So a quoted spread of 300p, is actually a spread of just 8p!
Hence the stock market price quotes system is actually giving false prices for smaller caps. There is another system (RSPs) which is only available to brokers, which provides much more competitive prices inside the spread. The RSP prices narrow dramatically when there is lots of two-way activity going on, as there is today with BOTB.
We can find out the RSP prices though, by putting in a dummy trade on an internet dealing account. It then shows you the price improvement on the quoted spread, and you can then cancel the order. Or you can ring up a conventional broker, and just ask what the real prices are.
For this reason, an apparently wide spread should not put you off from transacting, because the real, hidden prices, are often far more competitive. This is also why I would never do any stock screening using share price spreads, because they're not the real prices you can actually transact at.
It's a terrible system, but we all need to be aware of all the above, in order to know how to work the system to our advantage.
Regards, Paul.
This has never made sense to me - why would they want to discourage trading?
Hi Paul, yes I fully understand your comments on the spread but I just find it very annoying that Stockopedia are based on the last trade, so if someone sells that is the price and then when someone buys the price shoots up. It is very misleading, I wish they would use mid price or sell price. Well according to Stockopedia there was a sale at 2400p on Best Of The Best (LON:BOTB) and I checked the buy price and it was 2720p.
The problem is the prices are bouncing around all over the place, on small caps, even when the actual prices have not gone up or down.
Best Of The Best (LON:BOTB) went from -16% to -4% just because the last trade was a buy.
I just want some consistency, base it on the same thing all the time.
Hi herbie,
Yes sorry, I did understand your point, and I agree with you about it not being ideal for Stockopedia showing the current price as being the latest trade. As you say correctly, this causes apparently wide price swings on smaller company shares. It would be much better for them to quote the mid-price as the current price.
My comment above then went off on a tangent re RSP prices, etc, so that wasn't directed at your specific point. Sorry, I should have made that more clear.
Best wishes, Paul.
Thanks for the valuable insight Paul!
Herbie, I share your frustrations, although I don't tend to notice it on Stockopedia, perhaps because Best Of The Best (LON:BOTB) is now in my portoflio and I've set that (using the settings cog in the top right corner) to show "Bid Price (for realistic valuations)". I use Yahoo Finance for at a glance prices on on my PF and watchlist - and this displays similar behaviour. I tend to investigate if things are moving 5 or 10% so I'm not sure it's going to be the best way for me to track BOTB - although I do like the interface and the ability to punch out and view daily movements in context. Open to suggestions if anyone has any.
I have also set mine to bid price, but this does not go on bid price, for the daily share price % movement. So the valuation of your folio, maybe based on bid prices, that does not tie up with the share price movements, which are based on the last trade price, this is the frustration.
If I select bid prices, then that is what I want the share prices movements to be based on, not last trade which is fairly meaningless, because it could be a sell or a buy.
I can see live prices on my brokers screens, but I don't want to be flitting between different sites all the time. I want to look down my folios on Stockopedia and see the real price movements.
Ah I see, I hadn't been using it for the daily % movements so I didn't notice the inconsistency.
I would love to see streaming live prices and Level 2 on Stockopedia. OK, I know that would mean a subscription price increase but I would then no longer need to pay Sharepad a large amount for my L2. Maybe live prices and L2 could be an optional extra for those that would like it?
I think that it would be a big step forward if Stokopedia was to also allow the use of MID prices both in valuing our portfolios, and in doing our screening. This would fix a lot of the problems around apparently massive changes in values depending on whether the last trade was a buy or a sell.
Re Stock report quoted prices
"I think that it would be a big step forward if Stockopedia was to also allow the use of MID prices both in valuing our portfolios, and in doing our screening ..."
Agreed, although any of Mid, Bid, Offer, or subscriber customisable would all be so much better than what we have at the moment. I tend to view last-traded-price on the Stockreport pages as non-information and therefore of little/no use.
I use IG, can you suggest an alternate 'conventional' broker? IG are just a helpdesk set-up - phoning them is a road to nowhere
For small traded companies like this the last price is almost irrelevant and I have to go elsewhere to see what the mid point is. Agree entirely
The acquisition of Nicholas Humphries by Belvoir (LON:BLV) looks to be a good purchase. It appears that the market is slowly acknowledging the value in the franchise model that Belvoir (LON:BLV) has grown over several years, although helped perhaps by the continuing buoyancy of the housing market. Nevertheless well done to the management team lead by Dorian Gonsalves for grasping the opportunities.
I hold and would welcome observations by Paul, Jack or other members of the Stockopedia community.
All the best
I tend to agree on £BLV.
Good growth, stock rank >90, qualifies for Joel Greenblatt Magic Formula screen, 3.7% divi = tuck away some in my SIPP.
Belvoir (LON:BLV) (I hold)
Hi Jonno
From the numbers alone, this seems like a decent acquisition.
Debt is back up to £7m, though it looks like underlying cash generation with the acquisition, will be >£6m on a 12 month basis, so it's nothing to worry about.
On further inspection there is one thing that I can't get my head around.
---
EDIT: Sorry, I've made some material edits to the original post. Here is the updated version:
Managed properties announced today is 71,787, which is c+3k higher than the last figure I made note of (69,000), This looks odd as today's announcement says there are c 6,500 new managed units being added.
Does this mean Belvoir (LON:BLV) lost c 3,500 since the last figure they mentioned? That seems quite worrying and doesn't make sense in the context of increased revenues over the last 12 months.
---
£2.8m additional revenue for c.6,500 new managed properties today implies £430 per new property per year.
That seems like a lot, especially in the context of the Nottingham Building Society deal last year where my notes indicate £30k additional revenue for 300 managed properties (=£100 per property per year.)
That's quite a difference.
---
Full year results out in a couple of weeks, so hopefully things will be clearer then.
Cheers
A
Morning, any chance of covering the Logistics Development (LON:LDG) results from earlier this week please?
I’d second that please, somewhat surprised to see a 20% + drop yesterday...ouch!!
I spoke to Best Of The Best (LON:BOTB) PR this morning to express my dissatisfaction.
A few things that they mentioned:
PIs are very important to them;
They mentioned that there may have been high demand @£24 but not so high @£28.
They are going to pass on my thoughts re why no open offer for those of us who solely work within ISA and SIPP frameworks - I also mentioned Primary Bid, but I guess (as Paul has said) that the few shares on offer would have been gone in seconds at that discount!
Glad I trimmed a few (around 11%) at over £30 now, but happy to hold the rest.
I think most of us who have held this a long time have trimmed in the last 12 months to some degree (there might be a few exceptions!.) I guess on that basis can we begrudge the owners from doing the same and diversifying their own portfolios.
I wonder whether they wanted to get it done quickly before the end of the tax year and that any reduction in sales price from doing it quickly can be offset for them in tax savings? Just a thought
Re Best Of The Best (LON:BOTB) , it would be very interesting to hear finnCap's perspective.
As I see it, the share price prior to the placing was lower than it should have been because of the seemingly very conservative broker forecasts, which assume that the recent strong growth virtually disappears going forward. One wonders why such conservative numbers were issued just before a placing... ...great for the City but not for the directors.
And then, as Paul says, there is the issue of the discount. Was there really no interest, in size, at a price above £24? I have never been involved in organising a placing and perhaps the institutions were that hard-nosed. It just seems an amazing contrast with say £ROO , where institutions fell over themselves to buy into a ludicrously over-priced IPO.
Re Best Of The Best (LON:BOTB)
I almost wonder if I believe any of these type of placing announcements.
“ Accordingly, the Selling Directors recognise that the composition of the Group's share register is important to ensure the business continues to benefit from its public listing and that having a strong and supportive institutional shareholder base is crucial to achieve this.”
Now, I am a bit of an old cynic, but I find it very hard to believe that they are selling all these shares for such altruistic reasons. I’ve nothing against them reaping the rewards of their success. But that’s what it is in my view. If they needed a wider shareholder base then they needed it just as much in the past. The difference now is that they can cash out at a high price.
The discount is strange. A mistake in the pricing or do they sense that the share price has risen far further than is justified and the current pricing is the high point for the time being? Or perhaps they’ve sniffed some regulatory headwinds coming their way that could strike at any time.
(No position)
The discount? Probably just those smart financial services boys spinning a tale to make maximum profit for themselves.
Best Of The Best (LON:BOTB) (No position) From offer Doc. As a result, pursuant to a number of investor meetings and indications of strong demand for the Company's shares from both existing and new institutional investors, the Selling Directors have decided to release a portion of their shareholdings in order to satisfy this demand, broaden the Company's shareholder base and improve liquidity.
To increase liquidity they could have had a 10:1 stock split.
I suspect that the formal sale process they have been in, which recently ended was they have trying to sell themselves. So is £24 for block sale really that big a discount in the big scheme of things? I wouldn't think so.
"To increase liquidity they could have had a 10:1 stock split."
This wouldn't have increased liquidity as the free-float would have remained unchanged at 26%.
Re: Best Of The Best (LON:BOTB) Placing
"Now, I am a bit of an old cynic, but I find it very hard to believe that they are selling all these shares for such altruistic reasons. I’ve nothing against them reaping the rewards of their success. But that’s what it is in my view. If they needed a wider shareholder base then they needed it just as much in the past. The difference now is that they can cash out at a high price."
- Exactly so. I asked £BOTB (via Paul Scott when he interviewed William Hindmarch) management several years ago whether they had plans to sell a chunk of their controlling stake and thereby increase the free-float. Hinchmarch batted the question away. I recognise that BOTB have, till now, treated outside shareholders well but I've been burned before in a similar circumstance (direct marketing group DM Plc, AIM: DM. for those who remember it - the chairman owned about 87% of the company and took it private the moment its share price tanked - my wonderful value play not so wonderful after all) and felt I'd be ignoring history if I invested in BOTB and thereby liable for history to repeat itself; so I never did take a position in BOTB - apart from the tiny free-float and large management controlling stake, I was as keen on it as Paul was. Good luck to Hindmarch and co., but how refreshing it would have been for them just to admit they are sitting on very large gains and would like to bag some of it.
I agree a discount sounds concerning. Should holders take that as a warning?
Good morning all,
More positive news for Belvoir (LON:BLV) this morning!
I hold.
Regards.
Oversubscribed placing for Duke Royalty (LON:DUKE)
https://www.londonstockexchang...
Looks like Primary Bid offer closed as well.
Hi Housemartin.
Re. the PrimaryBid offer for Duke Royalty (LON:DUKE) I believe it is still open as I’ve just (10.40am) subscribed for shares via their App which has been accepted (presumably subject to possible scale back). In theory the offer is open for another 5 days but may close early subject to demand.
Gus.
How times have changed. Going back to Nov 20, even at 20p, I would have considered this expensive for Duke Royalty (LON:DUKE) !
Michael
Thanks for that video link - I'll be watching that later. I found this video a few weeks ago discussing some of the same kind of issues or at least trying to discuss even if Harry Dent was a little shouty!
$10000 gold by 2025 according to James Rickards! Might sound a bit far fetched but he makes a good case out for it - that gold has in the past done multiple 100% increases and I think he mentions when it rose from $35 to over 2000% in one of the bull runs. Inflation has been used in the past to tackle the debt mountain and that will mean the devaluing of the dollar. I don't think the deflation that Harry Dent is expecting will happen or that Governments will allow that as it may mean another 1930s type great depression!
Some information on James Rickards he seems qualified to talk about this.
https://en.m.wikipedia.org/wik...
"James Rickards he seems qualified" - on Gold
Well, yes (it's one of his main interests) but he is and always has been a perma-bull on gold so just because he says it doesn't mean it's going to come to pass. He keeps saying it and by the law of averages eventually he will catch one of the bull runs.
Personally, I hope he's right as Gold (and silver) make up a substantial part of my portfolio.
Today's take on Gold from John Authers @ Bloomberg - https://www.bloomberg.com/opin...
May gold regain its throne. My junior miners have been in torment over the past month.
Although the title mentions gold that is a little misleading as it really is a discussion about macro-economics. So some of the issues discussed include currency devaluation, inflation, deflation, bubble stockmarkets, gold, economic recovery etc.
So when I said "he seems qualified to talk about this" I was referring to the wider topics discussed and not just gold and the link to his biography shows you the high level qualifications, work experience and US government involvement together with publications on a wide range of issues. Someone certainly to respect.
I have yet to listen to the other video posted but I did watch around 10 minutes this morning and the speaker seems to be suggesting that interest rates will not be used in the same way as in the past to control inflation. The US policy towards inflation has already changed as announced in August last year and the Fed will allow the economy to run hot.
With an expected weakening in the dollar over time then it may be prudent to hold some gold. Like you I have a fair bit in my portfolio and some commodities and and some oil.
The Dent and Rickards video mentions that the only 2 ways to tackle the debt is either through deflation where there is a massive defaulting of personal debt or inflation which shrinks the debt over time like the UK's WW2 debt. Do people agree that only these ways are possible as avenues (whether desirable or not) in tackling the huge debt mountains? If these are the only 2 ways then watch out for inflation imv! Some other issues discussed were pegging the dollar to gold as in the past and whether inflation would happen as Japan has failed in achieving it. Both speakers agreed on the demographics that there will be labour shortages in the US; Dent argued this would lead to deflation while Rickards believed it was inflationary!
Interesting arguments. It's all relevant to shares and investments so why I raised it.
My morning smallcap tweet:
Atlas Mara (LON:ATMA) Supply@Me Capital (LON:SYME) Chamberlin (LON:CMH) Infrastrata (LON:INFA) Gulf Marine Services (LON:GMS) Braemar Shipping Services (LON:BMS) Verditek (LON:VDTK) £PRO Thruvision (LON:THRU) Hemogenyx Pharmaceuticals (LON:HEMO) Galliford Try Holdings (LON:GFRD) 1Spatial (LON:SPA) Diaceutics (LON:DXRX) Belvoir (LON:BLV)
Atlas Mara (ATMA) in principle agreement with the majority of its creditors on key commercial terms of the previously announced debt restructuring. Discussions continue with ABCH (who?) creditors. [SP=0.36 Cap=53m]
Supply @ME Capital (SYME) gross origination of Client companies up 13% from Dec to Mar. Progress has been made with Quadrivio Group and the Captive Bank acquisition process. [SP=0.58 Cap=194m]
Chamberlin (CMH) expects to publish delayed FY20 and H1 accounts mid Apr and immediate unsuspension. [SP=7.4 Cap=5m]
Infrastrata (INFA) rev c. £6.5m in last 8 months (FY20: £1.4m). Further growth momentum expected this year. Cash breakeven within the cruise and ferry market maintained. [SP=39 Cap=32m]
Gulf Marine Services (GMS) banks agree new debt terms as mooted. [SP=6.9 Cap=24m]
Braemar Shipping Services (BMS) completes mooted sale of Wavespec engineering div for £2.635m. [SP=200 Cap=63m]
Verditek (VDTK) recent improvements to its solar panels means it needs new certification. Intergroup Mining order further delayed by component shortages. [SP=4.15 Cap=14m]
Pro Motion (PRO) recent float says its R-Amp process will leverage blockchain cloud knowledge to boost CBD sales. Also new LTIP could gift mgmt 24% if co if SP hits 104. [SP=45 Cap=NA]
Thruvision (THRU) warns FY(Mar) rev only c. £6.7m. Blames zero sales in aviation mkt in H2 and weak customs mkt. Profit Protection market performed extremely well. [SP=23.69 Cap=34m]
Hemogenyx Pharmaceuticals (HEMO) negotiations have commenced with a global pharma co regarding the form of licensing and further development of CDX toward clinical trials. [SP=6.85 Cap=31m]
Galliford Try (GFRD) appointed to Scottish Water's new £700m Non-Infrastructure Framework for the SR21-27 investment programme, in a JV with MWH Treatment. The 50:50 joint venture, known as ESD, support the capital delivery functions of Scottish Water. [SP=127 Cap=141m]
1Spatial (SPA) wins multiyear contract with Defra to provide a managed service for Rural Payments Agency's Customer Portal and Land Management System. Potentially worth over £0.9m. [SP=46.85 Cap=52m]
Diaceutics (DXRX) secures a data licensing agreement with a global pharmaceutical company to provide COVID-19 testing data insights in the US. Details confidential but it does not change FY mgmt exp. [SP=102 Cap=86m]
Belvoir (BLV) buys White Kite Limited and Nicholas Humphreys Franchise Limited for £4m. Immediately earnings enhancing. [SP=200 Cap=70m]
In line: £
Pro Motion looks like an interesting proposition and seems to capture the zeitgeist of the cryptocurrency space.
[deleted - bad formatting]
I confess I was baffled by the BOTB placing. "in order to satisfy strong institutional demand" and a 16% discount doesn't compute......
They always say that nowadays. PR spin seems to have taken over almost completely in RNS presentation. Of course that explanation "in order to satisfy strong institutional demand" is just nonsense. And actually the nonsense explanation just reduces trust. Why not just say that they wanted to take out some money to buy themselves a Ferrari or two?
The directors wanted to realise some of their very large gains. And why shouldn't they. Paul explains it very well (as always).
This is not so very different from the PR driven presentation of "Adjusted EBITDA" and the like. No it's not because these number more accurately reflect the performance of the business. It is to present the business in the best light to boost the share price. To quote Warren Buffett “Does management think the tooth fairy pays for capital expenditures?”
Best Of The Best (LON:BOTB) 's share price dropped quite significantly during the day before rallying. I wonder if that was some of the institutions making a quick turn on their discounted stock. So much for strong institutional demand.
BOTB I find it more interesting that free float is now 53%. IIRC this means the company can be counted in some indexes. They obviously want some money out of the company so sold some, and why not. Above less than 25% free float a lot of institutions will not invest. Dragon oil had this issue that it had a small free float but should of been counted in the FTSE 100 but could not as its float was too small.
Hi Paul,
Very interesting interview with Stephen Clapham and Russell Napier on inflation.