Small Cap Value Report (Thu 1 Dec 2022) - HOTC, CRL, PEEL, TRB, MAB1

Good morning from Paul & Graham!
Agenda
Paul's Section:
Hotel Chocolat (LON:HOTC) - preliminary results for FY 6/2022, suggest the accounts department operates at a leisurely pace, but the figures are in line. Outlook comments are vague, but seem to be a mild profit warning. Balance sheet seems OK, although inventories running high does introduce some risk of future write-downs. Overall, I'm struggling to see value here. Aggressive forecasts for next year & beyond mean more profit warnings could be a risk. The story seems a little stale.
Creightons (LON:CRL) - I have a quick skim through the H1 results. Profit has almost evaporated, due to high cost inflation, and difficulties passing that on to customers, as with so many manufacturers right now. Outlook comments suggest it's making some progress though, with a better H2 expected. Balance sheet seems just about OK. Over time I think CRL should probably at least partially recover, so maybe one to just tuck away & forget about?
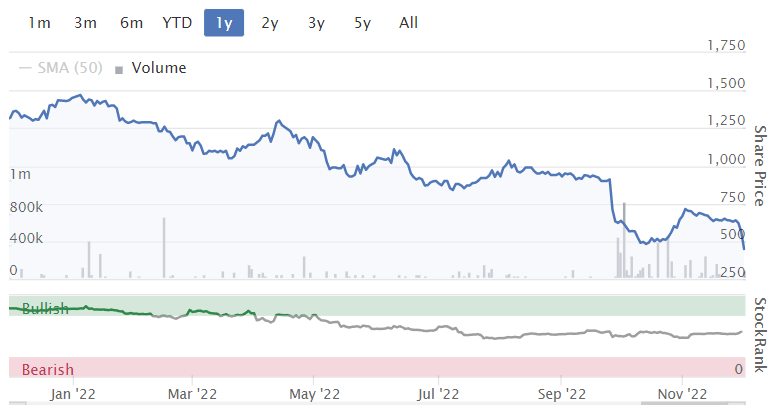
Tribal (LON:TRB) - noteworthy as shares have dropped 30% today, on news of a problem contract getting a lot worse. This means most of this year's profits are wiped out. Tribal has a history of erratic performance. It's difficult to see how a large contract could go so badly wrong. Shares might be attractive to a bidder, perhaps?
Graham's Section:
Peel Hunt (LON:PEEL) (£96m) - these H1 results are poor, as expected, but the company does succeed in achieving a breakeven result despite “multi-decade lows” in equity capital markets activity. The investment banking division saw a collapse in activity with only a handful of IPOs taking place in the UK market and with other fundraising deals only a fraction of what they were last year. The other revenue streams at Peel Hunt were more stable and thanks to a chunky reduction in pay/bonuses, this H1 result looks ok to me. I now think this share could be approaching value territory thanks to the strong balance sheet which includes £41m of cash and a very strong net current assets position.
Mortgage Advice Bureau (Holdings) (LON:MAB1) (£255m) - a profit warning is seen from this mortgage advice business. With the help of a franchise business model, it has earned excellent profits and returns in recent years. However, it is going to “slightly” miss its 2022 forecasts, and we now can’t expect it to make any progress in 2023, due to its having fewer mortgage advisers on its books and lenders imposing stricter criteria on new loans. Mortgage volumes have collapsed and MAB is hoping that this will recover by H2 of next year. I’m not sure when the recovery might happen but my perception is that this stock has some high-quality characteristics and could be a nice candidate for a recovery rally if and when normality resumes.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Hotel Chocolat (LON:HOTC)
145p (pre market open)
Market cap £199m
Hotel Chocolat Group plc, a premium British chocolate maker, today announces its preliminary results for the 52 weeks ended 26 June 2022 ("FY22").
It seems late, to be getting FY 6/2022 results, in early December. Also a long time since the last trading update in July. Although it has given us over 4 months to forget about the disastrous international expansion strategy, with the Japan JV being abandoned with heavy losses, and scaled back in the USA. Hence why the shares have rebased downwards, since it’s no longer an exciting international growth story, but instead now a UK-focused brand.
Japan - not a complete write-off it seems, with today’s update saying it is still trading, and may turn into a brand licensing model, which would be good to salvage something from the £30m write-off of previous investment.
FY 6/2022 results look as expected (from the July update) -
Revenue £226m
Underlying PBT £21.7m
Statutory loss of £(9.4)m, as expected due primarily to a big £30m write-off re Japan JV (as expected)
Current year trading/ Outlook - I don’t know about chocolate, this is more like fudge - and sounds like a profit warning to me -
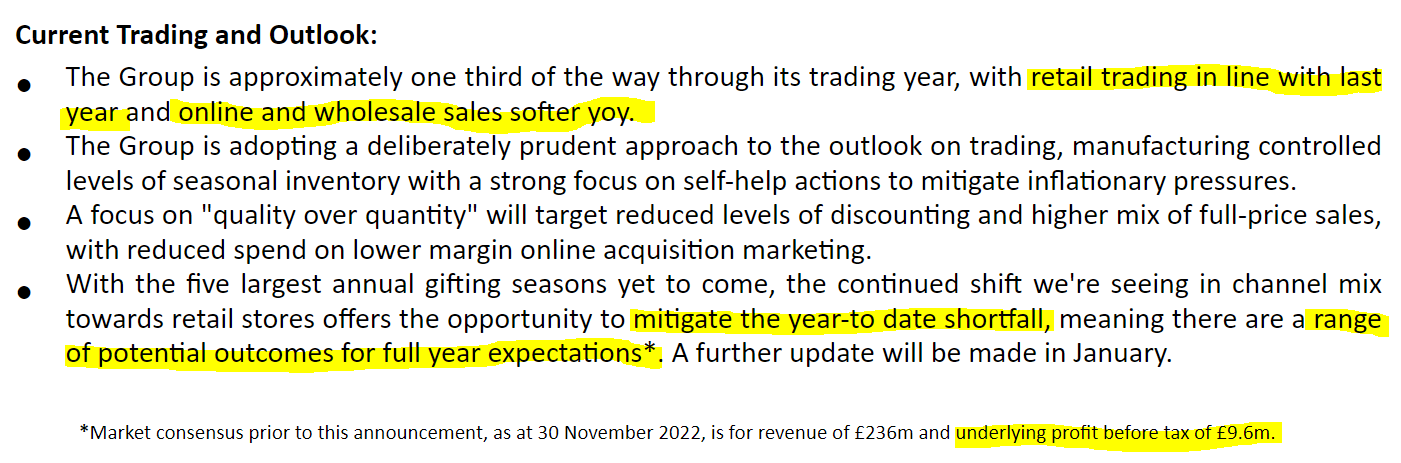
Excess inventories - this is a common problem with many retailers at the moment, as they stocked up when supply chains were stretched, and now need to wind down those excessive inventories.
I am a bit concerned about this, because when inventories become this high, there’s an elevated risk of a write-off being needed for slow-moving items. Also, it would be worth checking the use by dates, to see if any of this is perishable -

Broker update - many thanks for Liberum for a detailed note today. It trims forecast earnings for this year from 5.6p to 4.8p. So over 100p is a high PER. 145p currently looks very difficult to justify.
The progression of forecast profitability looks too aggressive to me, being -
FY 6/2023: £8.3m
FY 6/2024: £20.5m
FY 6/2025: £32.7m
I’d be very surprised if HOTC achieves anything like that profit growth, but time will tell. So it all depends whether you believe in the revised strategy or not.
Management changes - both the Chairman and CFO intend stepping down in 2023, which doesn’t exactly inspire confidence. If they saw exciting growth ahead, would they be leaving?
Going concern note - nothing worrying in this.
Balance sheet - looks OK to me. NTAV was £96.6m at 6/2022. This was boosted by a £40m equity raise in the year.
My opinion - there’s nothing madly exciting in today’s update. So I can’t see any reason to anticipate a big recovery in the shares.
Based on expected performance for the current year, FY 6/2023, the shares look expensive.
Forecasts beyond that look very challenging, given tough macro conditions - I find it difficult to anticipate profit more than doubling in FY 6/2024, hence it seems to me the risk of profit warnings could be high, but we don’t know, it’s all educated guesswork really, trying to predict the future performance of any company.
You either believe in the product/strategy, or you don’t. Personally, I don’t like the product, so would never invest in any consumer product that I find poor value for money, and unappealing in taste. There’s a branch in Islington, so I’ll mystery shop it this afternoon & report back. Do any readers like the product? We should probably do a poll.
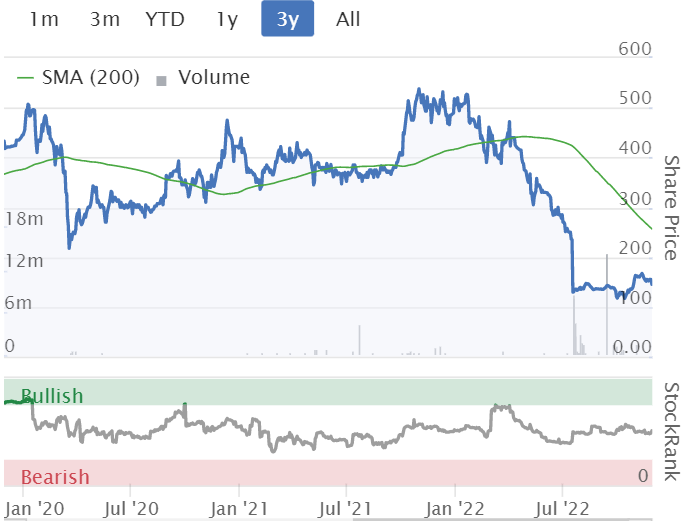
There's a danger of investors "anchoring" to previous, excessive share prices.
Also remember the share count has risen from 118m to 137m over the last 3 years.
.
Mystery shop - here is my experience of trying out Hotel Chocolat products in its Islington branch on 1 Dec. The short version - product is OK, average, nothing special, and too expensive. Exactly as I previously thought.
Creightons (LON:CRL)
29p (down 23% at 08:45)
Market cap £20m
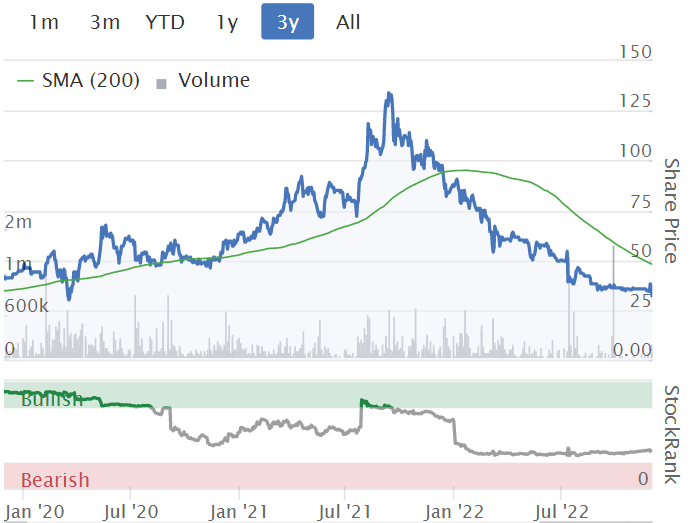
Shareholders have had a torrid time with this share over the past year, which continues today with another lurch down.
H1 key numbers are -
H1 revenue down about 1% to £29.7m
Operating profit largely disappeared, to £281k (H1 LY: £2.6m)
Profit after tax becomes a loss of £(385)k vs £2.0m last H1.
What’s gone wrong? It’s all about cost inflation, and struggling to pass this on to customers - a similar story we’re hearing from many manufacturers in lots of sectors. The way I’m thinking about this, is that over time, it should be possible to rebuild margins. That’s what usually happens after previous recessions, but it can take several years. More of a gradual rebuild, than a V-shaped profit recovery, is probably on the cards.
We can look back to 2008 for many examples of this, in company results generally improving over the next few years.
Outlook - it’s expecting an improved performance in H2, and the commentary mentions various initiatives to cut costs, improve efficiency, and cut supplies if customers refuse price rises - although that last one could be problematic if it means losing market share.
Is it going bust? Probably not - the going concern note doesn’t ring any alarm bells, although there is an element of marking their own homework with these notes, although I understand that auditors police them carefully.
In terms of financial strength -
Balance Sheet - NAV is £24.6m. Remove £13.7m intangibles (boosted by an unfortunately-timed series of acquisitions), and I’ll also remove £3.0m deferred tax, to give NTAV of £13.9m, which is probably adequate for the size of business. There’s quite a lot of working capital tied up in receivables and inventories though. Lease liabilities are modest.
Note 5 gives a breakdown of the £9.0m gross bank debt, of which £2.56m is a mortgage, which I usually disregard as it will be secured on freehold property, so that’s safe. Then there’s £4.1m in invoice financing, which looks reasonable compared with £14.5m receivables. So that leaves a fairly modest level of remaining debt. I’d like to see debt reduce, but it doesn’t look dangerous - particularly as the commentary says it has moved back into monthly profitability during H1. So the bank will be looking at an improving picture, hence probably not panicking.
Nothing is said about bank covenants, so that would need more research before considering a purchase of shares.
Dilution - note 3 shows what seems unreasonably high (over 10%) potential dilution from share options, so just a flag to check that out.
My opinion - neutral. I think CRL should be able to rebuild profits, so the question is how much, and how long will that take? If it gets back to historic peak profits, then £20m market cap would be great value. So it seems a credible recovery share, for patient investors, and I don’t see excessive risk here, providing it does turn in an improved H2 performance.
Who knows, at some point raw materials & energy prices could drop heavily, which would be exciting for this, and other companies. Although recent events have shown the flaws in their business models, in the vulnerability to supply & cost shocks.
Tribal (LON:TRB)
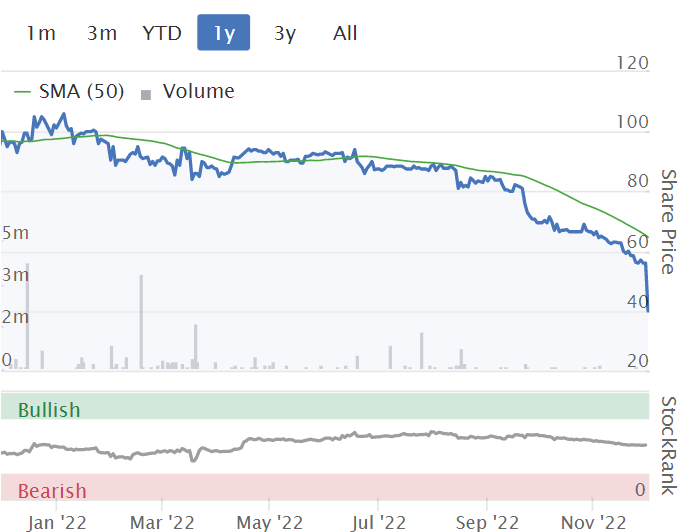
40p (down 29% at 09:23)
Market cap £85m
This has cropped up because it’s one of today’s top fallers - we try to cover big price movers every day, up or down, because that tends to be where the most noteworthy things are happening.
NTU Contract Update and Trading Outlook
Tribal (AIM: TRB), a leading provider of software and services to the international education market, today provides an update on the Nanyang Technology University ("NTU") contract and Group trading for the year ending 31 December 2022 ("FY22").
Trading for FY22, excluding the NTU contract, is in line with Board expectations.
NTU contract - sounds like it’s going badly wrong -
Expected to generate a £12m loss over the life of the contract (no specified how long)
Negotiations with client ongoing, not likely to be concluded this year.
£9m hit to EBITDA this year FY 12/2022
There’s also a profit warning for next year, FY 12/2023 -
The NTU contract combined with extra cost and wage inflation is expected to reduce anticipated EBITDA performance in the year ending 31 December 2023 by c£4m.
Some new contracts have been signed.
Expected to report reduced net debt at year end, and “comfortably within” bank facilities.
My opinion - Tribal has been accident-prone in the past, and it seems to have made a right mess of things with this big contract, so questions obviously need to be asked, how was this possible? Could it happen again? Management competence?
It’s got a weak balance sheet, with negative NTAV. Although software companies don't need much capital.
I wouldn’t touch it as a standalone investment, but software companies are often takeover targets at remarkably high valuations, since larger groups seem to value the way they are embedded, and mission-critical, to their clients.
So it’s anybody’s guess what happens in future.
Graham’s Section:
Peel Hunt (LON:PEEL)
Share price: 78p (-5.5%)
Market cap: £96m
Here are Peel Hunt’s results for the H1 period to September 2022:
- Revenues £41.4m (H1 last year: £71.4m).
- PBT £0.1m (H1 last year on an equivalent basis: £21.6m).
- Staff costs as percentage of revenue 58.5% (last year: 45.8%).
Based on these numbers, staff costs have reduced from £32m to £24m.
What I’m looking for with a stock in this industry is the ability to reduce variable pay aggressively so that in the tough years, they can at least avoid making a loss. Peel Hunt has just about managed to do this, despite what they describe as “a multi-decade low for equity capital markets activity”.
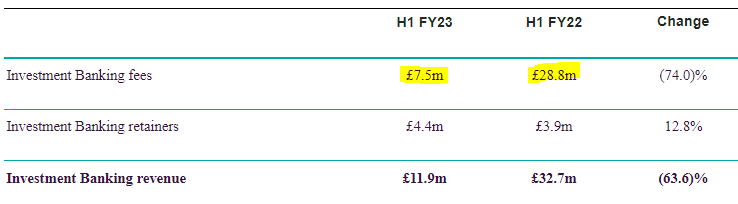
Most of the revenue reduction, predictably, was seen in the Investment Banking division:
But they are looking ahead to when corporate deal-making and equity issuance might be back in vogue:
We continue to receive new mandate enquiries and we have a number of pipeline deals that we expect to execute when market conditions permit. Our retained corporate clients typically transact every three to five years and challenging market conditions have resulted in delayed activity that may lead to deal flow as markets normalise.
The number of corporate clients has increased slightly to 165, of which 35 are in the FTSE-350.
Research Payments & Execution Commission revenue: this is down by a much more modest percentage amount (6.8%) to £13.7m, in a performance described as “resilient”.
These tend to be more stable activities - the demand for equity research and for trading in the secondary market is still there, even when there are very few IPOs taking place.
And the company continues to pick up awards for their equity research work:
Execution Services revenue: down by 35% to £15.5m. Even the market-makers feel the pain in falling, quiet markets with less trading activity taking place.
Balance sheet: another thing I look for with these stocks is a giant cash pile and a strong balance sheet. They need this for regulatory reasons anyway, but it’s also a good way to anchor the valuation.
Peel Hunt’s balance sheet shows net assets of £96m, nearly all of which are tangible.
Or another way of looking at it: net current assets (current assets minus current liabilities) are £106m. From that figure we could deduct the long-term portion of a loan outstanding (£18m) to get a financial net worth for the company of £88m.
So my own estimation of the balance sheet is that it’s worth in the region of £90m. If the market cap traded significantly below that level, while the balance sheet remained this strong, I’d start to think that we were being offered a bargain.
CEO comment: Peel Hunt’s CEO naturally points to the unusual decline in overall activity, which he argues is “due to several factors including investor redemptions, institutional investors building up cash positions and retail investors being more cautious as equity markets responded to rising inflation, the cost-of-living crisis and the possibility of a lengthy UK recession.”
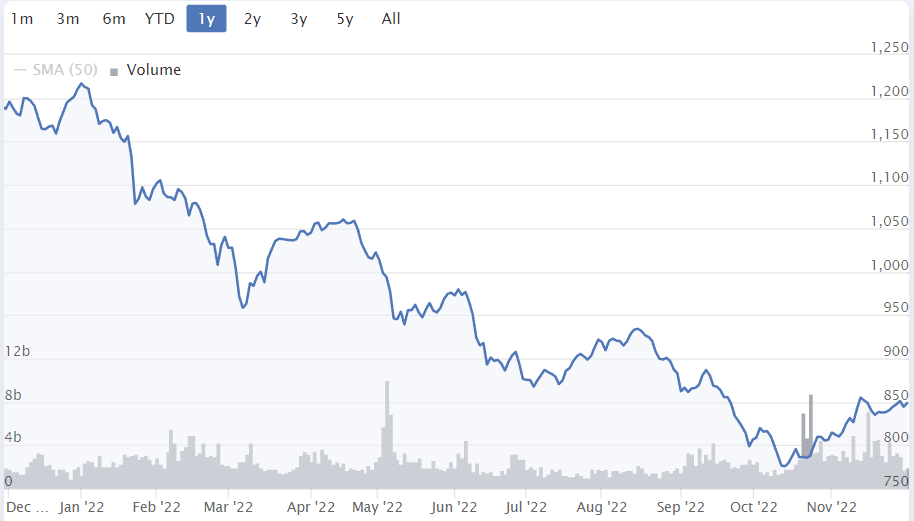
As a reminder, here is the performance of the FTSE Small-Cap Index this year:

And here is the AIM All-Share Index:
He notes that there were only five UK IPOs in the first six months of 2022 (vs. 37 in the same period last year). Fundraisings and other equity capital markets activity saw only 97 deals (vs. 257 deals in the same period last year).
He takes a positive medium-term view on the attractiveness of the UK equity market, arguing that higher rates spell the end of private equity dominance, that pension funds have abandoned equities and left them under-owned, and that HM Treasury and regulators are working to make UK financial markets more competitive and attractive.
While I agree with him that UK equities are “under-owned” and are attractive over the medium-term, nobody knows when this situation might correct itself - it could be 2 years, or it could be 5 years or longer!
My view: this stock listed in late 2021 at 228p, and is now at 78p. If there is one thing that Peel Hunt understands, it’s the equity markets - and they got the timing right when it came to making their IPO.
Looking forward, with the shares down by 66% from their IPO valuation, I think we could be getting close to value territory. I will always come back to that balance sheet value of around £90m (give or take).
The company has shown, at least in H1, that it was able to withstand terrible conditions and still just about avoid making a loss.
This provides some comfort that their net asset value is unlikely to deteriorate, at least not by much.
And as they enjoy a large surplus over their regulatory capital requirement, it’s reasonable to expect that future profits will get passed onto shareholders without difficulty (they have a target payout ratio for the basic dividend of 40% of profits).
With H1 out of the way, and the results not being so bad as they might have been, I’m now more comfortable with this stock than I was when I first looked at it in October. Around or below a market cap of c. £90m, I think it might be considered a value investment.
Mortgage Advice Bureau (Holdings) (LON:MAB1)
Share price: 448.6p (-20%)
Market cap: £255m
The Mortgage Advice Bureau (MAB) was at the epicentre of the recent drama in the mortgage market, which saw rates rise and products being pulled from the market overnight:
These extreme market and lending conditions severely impacted activity levels across all of the Group's product lines, with written business in October and November circa 50% below expected levels. The reduction in mortgage activity and new house sales is expected to persist until early 2023, after which activity levels are expected to start to slowly build.
Mortgage volumes are now at “exceptionally low levels”, and this is affecting recruitment: mortgage advisors are not being onboarded as planned, and leavers aren’t being replaced.
We also get some interesting colour on the latest state of the market:
Buyers with mortgages reserved prior to the mini budget are strongly motivated to complete their purchase at the lower mortgage rates they have secured. Where mortgage offers expire, typically after six months, there is a risk of some transactions aborting if they are not renegotiated. Pipelines are still holding together reasonably well, but we do now expect slightly higher fallout rates than usual.
Outlook
FY December 2022 is now expected to be “slightly below market expectations”, despite a growing market share of 7% (from 6.1% last year).
For next year, MAB acknowledges that H1 will be poor, due to lower adviser numbers, but expects “a second-half weighted recovery” - this seems like a courageous call. How can we be confident, as MAB claims, that the economic and interest rate outlook will be more stable then? I don’t think we can!
MAB can point to 1.8 million borrowers whose mortgage deals will expire in 2023, and this provides an opportunity for work on transfer deals.
As far as profits next year are concerned, we “may see no improvement on 2022”, even assuming that the H2 recovery materialises.
The September 2022 mini-budget gets the blame from MAB for what has happened. With their army of mortgage advisers no longer growing, and with stricter underwriting criteria for borrowers, it is going to be a tough year for the company to make any progress. MAB finds comfort in the knowledge that “transactions are delayed, they are not lost”.
My view
This company has, on the face of it, a very nice track record of profitability:
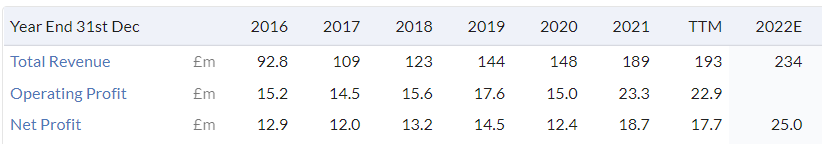
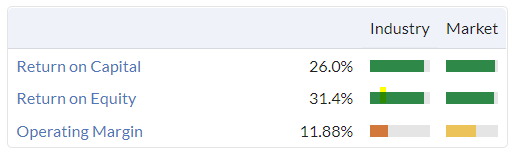
The quality metrics are very good too, which is probably related to the fact that MAB uses a franchise style model. The stock gets a QualityRank of 96.
So I wonder if the disruption caused by recent events might possibly provide a buying opportunity?
MAB was supposed to earn adjusted net income of £24-25m this year.
It will miss that, slightly, and could do worse again next year.
There will also be bigger adjustments to the numbers, after an acquisition: MAB bought 75% of mortgage broker Fluent Money in March, for a cash payment of £73m.
The integration of that company has been successful, but I wonder about the timing of the deal and the valuation. From the announcement RNS:
In the year to Mar-22E, Fluent is expected to generate £38.5m revenue (+45% yoy) and adjusted EBITDA of £4.2m (+118% yoy)
MAB said that they expected Fluent’s adjusted EBITDA to double this year, but it still feels like they paid a very heavy price for it.
On balance, I reckon it’s worth keeping an eye on this one: if they maintain their track record of profitability, despite the downturn, and are ready for the upturn when it eventually comes, then their shareholders could do very nicely indeed. The elimination of any short-term growth prospects is unfortunate but could be priced in already at these levels.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

60 comments
Personal Pension - Are there any stats on how many people have SIPP pots approaching the £1.073m lifetime limit and those who have exceeded it?
Not that I am aware of (or at least not accurately)....
1. The number varies for DC (Defined Contribution) schemes as markets fluctate, and for DB (Defined Benefit, a.k.a. Final Salary) schemes as inflation and wage inflation vary.
2. Individuals have different lifetime allowances as you could apply to "freeze" your allowance each time they changed the rules - provided you stopped contributing or didn't chnage pre-existing contributions (so-called fixed protection or individual protection, 2016 being the latest batch at £1.25m, in 2014 it was £1.5m. Some older folk have bespoke lifetime allowances from back when there was no LTA).
3. People have multiple pension pots - be that SIPPs or employment related DC/DB schemes. Your SIPP provider will not automatically be aware of your other pensions.
4. The rule for DB schemes is different - you multiply your expected pension at retirement age by 20x and subtract that from your LTA. That involves forecasting your final salary (or inflation if you are a deferred member)
5. The pensions dashboard where pension stats could be aggregated at the individual level isn't up & running yet
The Treasury probably has a guesstimate somewhere, but it will be more guess than estimate I suspect.
According to a report from Royal London in 2019, there were 290,000 above the limit at that point, with another 1.25m at risk of breaching it by the time they retire.
I suspect it is well above 290k now.
Hello, I put this up late yesterday re Strix (LON:KETL) - too late and once everyone had finished kicking the kettle around. So I've copy and pasted it here to see if got any takers on the points made. Thanks:-
I just looked quickly at Strix (LON:KETL) for first time - one I have avoided as didn't make sense in past. Some Qs and points:
1) Is there potential for debt covenant stress here? Its got to be at around 2.5x ebitda and above (particularly depending on how adjustments are taken)
2) I don't feel their narrative re what's gone wrong on revenue side makes a lot of sense. They are basically saying that covid zero has bitten them as people can't work and make stuff. IMO to date manufacturers/exporters have been able to negotiate this. Local and central govt is very aware of the need for maintenance of these sectors and the forex they bring in particularly as the domestic economy struggles with real estate very sick and infrastructure non productive (both grossly bloated part of GDP and so the pain is acute). It seems more realistic that something additional is happening -> my guess is that the kettle market must be v exposed to the inventory de-stocking we're seeing + which might be exaggerated by appliance makers perhaps over ordering parts like those that Strix supply when supplies were tight relative to exaggerated demand + strix is in a very narrow vertical so no chance to diversify out of it (I know they've diversified thro acquisition etc so my analysis is flawed)
3) Does 1 and 2 above put some pressure on capex plans. They way to make profit and keep covenants sweet would be to not spend so much on capex. Is this a positive or negative if they do that?
4) I have not view on their patents and their importance or defensibility thro superior production knowhow. However, the rather mad dash for growth thro other channels and acquisitions might be explained by concerns of impact of patents coming off? I'm not 100% sure where their capex goes but if into kettle switches then that could be they think they need automation to defend market share when more competition comes on after patent expiry and/or the need to invest in other products.
5) I was quite frustrated not to be able to find a regional split of sales easily on the company. But I suppose its near all China and then the finished product made by OEMs sold on. I was looking to see how much China is the end market for the products their parts are used in. Massive tea drinking country. With covid zero and quite harsh personal finances going on there I could imagine a fall in demand for appliances like kettles or water purifiers etc. Any views or data on that?
The above is quick very partially informed analysis. I'm interested in feedback and/or to be put right on matters
Re capex, Strix's 2020 and 2021 annual reports mention completion of construction of a new, more efficient factory in China, I think £20m. This explains the capex spike in recent years.
I agree, yesterday's trading update leaves an uneasy feeling about what is really going on with their core kettle controls business. In the reports I noticed they refered to distributing parts (stock?) in different areas in China to mitigate effects of their lockdowns. I also noticed they refered to getting up-front payments for kettle controls. (The later point at least suggests they have good negotiating power with customers.)
Although uneasy about the core kettle controls business, I think the main uncertainty is how the spate of acquisitions work out. £ketl has a stated aim of doubling turnover. Great if it all comes good, destructive of shareholder value if its a mad dash-for-growth. I don't get a real feel from the company's recent statements as to how this is going.
Thanks. I have Qs not views on Strix (LON:KETL) really...I can see something durable and valuable potentially...but I can also see a potential mess and even hints of structural problems visible to mgt that they have not relayed publicly (and why the super aggressive acquisition). Of course compensation can be a big part of this and haven't looked into that as its secondary to having a view on the biz...but mgt can gain from overextending and volatility in sp if they get easy resets...
...a superb example of this is Venture Life (LON:VLG) and imo its a disgrace that tipsters are promoting this cluster-f stock after the way they rode over shareholders -> mgt getting themselves a really lovely profitable exit and now the same team buy a bunch of new 'better' cos (seemingly as the core biz was crap) and reset their remuneration for another run at a profitable exit hoping that PIs helped along by likes of Paul Hill are on for the game again. He and mgt just abusing the gullibility of PIs. You might win by being early and playing a bit of greater fool...but there's always a risk that mgt have shown operational incompetence once and will do that again BEFORE you get the chance to exit.
I'm not saying that Strix is the same...just pointing out a little echo
Interesting Vox Markets podcast about Technology Minerals (LON:TM1) on Monday this week. Attracted my attention. This morning’s news also interesting. Any followers of their progress here?
Creightons (LON:CRL)
I was previously a holder. I emailed their management (only once, mind), and had no response, which I found irritating.
Emma Hardie is very much in the luxury space, and must enjoy very high gross margins. i think that is likely to be hiding a greater reduction in gross margin in the rest of the business.
I have used their other products in the past and though they were quite good. This was skuttlebutting though - they aren't particularly widely available, and the brand awareness for most products and Creightons itself is tiny.
I'd be interested on buying the shares again if they start to get very cheap, but they don't update the market often, and didn't respond to my question, so that's an issue for me. I really appreciate frequent updates from management
Apologies for straying off topic but probably still relevant.
I have been expecting two dividend payments this week, they have not arrived so i contacted HL and was told that these payments are sent by cheque and due to the postal situation the cheque is still in the post.
Do companies REALLY sent dividend payments by cheque ? If so there must be reason for it.
Richard
Very odd situation. I was also expecting some dividends to be paid in over the last 2 days ... was about to contact HL, so now I don't have to. Thanks for posting!
Do companies REALLY sent dividend payments by cheque ?
When you buy shares in a company the registrar is given only your name and address, not your bank details, so the answer is yes. However, every dividend cheque comes with a form begging you to give them your bank details to make the process more efficient. It's about time HL filled them in.
Sorry for not making myself clear but I was expecting the payment from HL, not direct from the Companies concerned. Apparently HL receive payment by cheque from these companies. There must be a reason for paying by cheque but it is escaping me ATM :-))
Bizarrely there are a few companies that still pay dividends by cheque. If you have a broker between you and the company the broker needs to get the cheque, get it cleared and settled and then administer the distribution, which all takes time. Some brokers are better than others but really it's the underlying company at fault.
Of course, when it happens, the companies get a lot of flack from people who want cheques:
https://www.thisismoney.co.uk/...
timarr
That sounds odd. I'm with HL as well but all my dividend payments are handled by HL by depositing into my account or automatically reinvesting (where I've stated to do so).
Suspect it's a minority of companies that work that way now. Could be worth contacting them directly to get clarification?
Next did their due diligence and then waited for a better time to buy Joules :https://www.stockopedia.com/sh...
Hotel Chocolat (LON:HOTC)
"Personally, I don’t like the product, so would never invest in any consumer product that I find poor value for money, and unappealing in taste. There’s a branch in Islington, so I’ll mystery shop it this afternoon & report back. Do any readers like the product?"
I like the product but find it poor value for money. I think Green & Black's and Lindt are just as good as Hotel Chocolat for a fraction of the price.
"we try to cover big price movers every day, up or down"
Well, after the horrors of Creightons (LON:CRL) and Tribal (LON:TRB) how about a look at Venture Life (LON:VLG) up 18%. on the announcement of an acquisition, 2 new distribution agreements for Gelclair (bought last year) and an inline trading statement. I think the market was relieved that we didn't have another company saying Chinese lockdowns were depressing sales there.
There is a report out from Cenkos https://www.cenkos.com/researc... which gives adjusted diluted eps of 4.53p this year and 6.02p next.
There have been some interesting moves in the background. Judith McKenzie is involved here and when there was a bad patch she expressed concerns about "checks and balances" - you can listen from 14 mins in here:
Since then the Chair has been replaced and all the other non-execs have decided to go. I detect the hand of Judith!
More on Venture Life (LON:VLG) - here is Paul Hill: https://www.linkedin.com/posts...
FYI I recently enquired why Next (LON:NXT) is in the Technology sector according to Stockopedia. Apparently, Refinitiv state it is because On-line sales exceed Off-line. Is it just me that thinks this is stupid and arbitrary? To make matters worse, Boohoo (LON:BOO) is not a technology company and yet 100% of sales are from On-line. Surely a technology company is one where the main product or service is technology-based? The whole thing is idiotic and makes screening based on sector a dangerous thing to do as some companies will be missed.
On another point, if you build a simple screen with a single rule asking it to returns members of the FTSE 100 index you only get 94 results. For the FTSE 250 it is even worse, only 194 results. Take care when using an index rule in your screens.
All the best, Si
How bizarre.
On the latter issue you don’t get that with Sharepad. You start with a list of 100 or 250 or whatever and go from there. I have done a quick comparison and the first by size not listed is £AAL. Could this be some sort of duel listing thing? I thought it might be. By ticking the include dual listing the FTSE 100 goes up from the FTSE 91 to the FTSE 94. I see that HALEON (LON:HLN) is not there. This, I think, spun out from GSK (LON:GSK) and listed on 22nd July. Under the stock report most companies have a field, after industry and before exchange, Index giving the index of which the stock is a constituent. HALEON (LON:HLN) does not even have the field title. Sounds like a data error somewhere from Refinitiv.
On the subject of sectors, Sharepad has:
Next (LON:NXT)
Sector: Retailers
Subsector: Diversified Retailers
Boohoo (LON:BOO)
Sector: Retailers
Subsector: Apparel Retailers
So it is all very odd.
Regards
Michael
Hi Simoan
This was Roberts reply:
regards
Hi Michael,
Well done on getting a reply so quickly. I raised this issue on 22nd November and have heard nothing since. Tbh I don’t agree with the response - you should be able to generate a list of index members as you can on Sharepad. It should be down to the user to choose to disregard any Trusts or other Collective Investments.
My subscription is renewing in two weeks and I should maybe consider cancelling and switching to Sharepad. I am finding just too many screen restrictions and data inaccuracies for my liking.
All the best, Si
Sharepad is night and day better for data crunching, not to mention far wider-ranging in its detailed coverage of quality names in the US and Europe under the basic fee. But I guess you’ll miss out on daily extensive analysis of collapsing internet retailing microcaps.
Sharepad is night and day better for data crunching, not to mention far wider-ranging in its detailed coverage of quality names in the US and Europe under the basic fee. But I guess you’ll miss out on daily extensive analysis of collapsing internet retailing microcaps.
Yes. I'm not sure my life would feel complete without the latter :-) I think in the end, I will probably stay because Sharepad is a desktop only tool and does not have a mobile app which I use far more than I thought I would. And now I'm retired I just don't have the time to make good use of both sites. There are so many things that niggle me though such as the dreadful formatting of the news items etc. I guess it's better than nothing, but not a lot!
All the best, Si
Sharepad is a desktop only tool and does not have a mobile app
You’re thinking of Sharescope. Sharepad is entirely mobile and tablet-friendly. I use it almost exclusively on my iPhone and two iPads, only rarely turning to the laptop. And it’s so configurable in terms of portfolios, filters and charts. What it lacks is Stocko’s algorithms but those show no interest in my defensive growth investing style, where stocks are always relatively highly valued. I’m only here for the thoughts and experience of Paul, Graham and other investors.
You’re thinking of Sharescope. Sharepad is entirely mobile and tablet-friendly. I use it almost exclusively on my iPhone and two iPads, only rarely turning to the laptop. And it’s so configurable in terms of portfolios, filters and charts. What it lacks is Stocko’s algorithms but those show no interest in my defensive growth investing style, where stocks are always relatively highly valued. I’m only here for the thoughts and experience of Paul, Graham and other investors.
Thanks for this. I didn’t realise it was mobile compatible. I will try it for a month and see how it goes.
All the best, Si
Confirmed, I also get 280 shares returned for the FTSE 350.
Edit: I am going to raise this as a separate thread to make it more widely known.
RE: Hotel Chocolat (LON:HOTC)
I am a bit concerned about this, because when inventories become this high, there’s an elevated risk of a write-off being needed for slow-moving items. Also, it would be worth checking the use by dates, to see if any of this is perishable -
As I'm not invested and live within a half-hour drive of the outlet shop in Huntingdon, I consider this a very good thing indeed. I will plan a visit to Huntingdon first thing sin the New Year :)
All the best, Si
Thanks for your Creightons (LON:CRL) comments Paul. There is a webinar at 11am this morning, and subsequently we will publish a recording. Register for the webinar here.
DSW Capital (LON:DSW) H1 2023 results were released this morning. The IPO has helped to drive their network growth. Revenue is up 34.5%, Adj PTP +12.5%. Strong operating cash confersion of 85.1% and they pay a dividend. The CEO & CFO are giving a results webinar with Q&A at 1pm today. Register for the webinar here.
Cerillion (LON:CER) FY22 results were released on Monday, they continue to perform exceptionally. Management are giving a results webinar with Q&A tomorrow 2 December, at 1pm. Register for the webinar here.
CER I am registered for Cerillion webinar at 12.00 . Is 1pm a time change?
#IPX Impax AM is a £1bn stock now, but for those of you who met them at Mello or ED a few years back and were lucky enough to invest, here is latest research after great FY results, with a £10 fair value: https://www.equitydevelopment....
I posted this late yesterday so my apologies to all if this seems like spamming the comments here but think the new service from Jake Taylor is genuinely a brilliant and unique tool for investors, which is not replicated anywhere else:
“I follow Jake Taylor @farnhamjake1 on Twitter and when I get the time listen/watch the Value:after hours podcast. Jake recently (I think yesterday) launched Journalytic and while I have only just signed up, it does look like the service I have been looking for and have tried to solve previously with a blog, OneNote, Evernote etc but never with great success.
Anyway as I thought it might be of interest to readers here.
It can be found at
https://journalytic.com/
Kind regards
Michael
Thanks Michael - I agree, this looks fantastic. Joined yesterday evening and have already logged rationale for recent purchase and reflections on the £ADF acquisition today. I've always known that I should be better at journaling my thoughts and decisions but have never really established a proper process to do this that makes it easy to go back and review.
The Checklist feature could be a real gamechanger for me with the ability to produce your own lists - or incorporate the many on the site.
I can't believe that it's free. Will they start to charge once we've made it into an essential tool I wonder?
T&Cs set out repeat fees process and how to cancel... but no mention of actual price, but I guess it is too early. At a later date, most of these products introduce new features for paying customers only. One has to invest time to see if it works for you.
In a reply to a Tweet Jake Taylor said that the he expects that the current feature set is likely to remain free (forever) of course he can change his mind but I would be content to pay a modest fee for the facilty, if I continue to use it as much as I expect to.
Regards
Michael
Hi Michael,
Journalytic looks interesting and I have signed up to try it out. Coincidentally I am 3 pages into a new physical notebook so good timing to transfer into journalytic if I can make it work for me. I haven't had time to check out all the features as I have been called away from my desk but interesting to see how other people use it. Thanks for posting the info
Regards,
Garth
There is something about physically writing down, modifying (I write in pencil) and updating a written Journal. Since moving to this method along side a small memo on ADVFN I have seen a marked improvement in my thought processes and decision making.
There is something about writing it down, it seems to imbed and rationalise.
TFI
Agree, I use a very similar process.
R
Interesting - I maintain something similar in Excel, with an entry every time I review a stock, go through the results or trade. I keep a snapshot of valuation metrics & similar stats at that date and then am able to review performance in absolute & index relative terms since that date.
By applying a filter to the ticker line I can immediately scan through my previous thoughts & actions over previous years and see what an idiot I've been.
Would I be willing to entrust this to a 3rd party app? I'm not sure I would to be honest - for two reasons:
1. Platform creators may have the best of intentions, but they can't stay free for ever (especially if they buy in data for historic charts & total return performance to make it really useful), and if they fail to monetise the platform eventually it goes out of business and potentially takes several years of your data with it (yes you can probably download back ups of your inputs, but can you easily resurrect the analysis)?
2. It would limit where I source data from. The joy of excel is that you can scrape most things from most places, often with the press of a button. Switching sources takes minutes, I'm never over a barrel if someone hikes their subscription or fails to price a security.
I wish them luck in becoming the Strava of the investment world, but as a keen Strava user I also keep the Garmin/Wahoo records as well just in case and occasionally dump it all to Excel (cyclists & runners will understand).
Good points though I would be surprised if they were to go out of business without giving you the opportunity to download the data in some vaguely readable format.
With regard to
"I wish them luck in becoming the Strava of the investment world, but as a
keen Strava user I also keep the Garmin/Wahoo records as well just in
case and occasionally dump it all to Excel (cyclists & runners will
understand)."
I have never seen the point of Strava (I don't subscribe) but love the data churned out my Garmin. That said I don't think becoming the Strava of the investment world is their aim.
Regards
Michael
Acquisition of Location One Ltd by Facilities by ADF (LON:ADF) looks a very good fit and consideration looks reasonable. The former provides ancillary services to high end TV and film production companies. Main details below.
I hold Facilities by ADF (LON:ADF) although well underwater at present. My perception is that the news will be received well by the market, but who knowns in the present climate.
Paul/Graham any thoughts/views please, if time permits
"Location One is an integrated TV and film location service and equipment hire company supporting location and production companies across the UK with its high-quality equipment and customer service levels. Location One's offering includes generators, water bowsers, lighting equipment, environmentally friendly battery-stores/other renewable solutions and other capital light consumables, all highly complementary additional products to the Group's existing premium serviced production facility offering."
Facilities by ADF (LON:ADF) and Location One are well known to each other having worked together on many occasions. The acquisition to be immediately earning enhancing.
"For the year ended 30 September 2022, Location One generated unaudited revenues of £9.24 million and an adjusted EBITDA of £2.08 million. The Acquisition is expected to be immediately earnings accretive. Location One's talented executive management, led by founder and MD Crispin Hardy, and other employees will be joining the Group."
Terms of the acquisition:
"Total consideration for the acquisition is £8.86 million, with 50 per cent. of the consideration payable in cash on completion, 30 per cent. payable in cash equally over three years, subject to EBITDA performance conditions, and 20 per cent. payable in ADF ordinary shares and subject to a 12 -month lock in . The cash consideration will be funded from ADF's existing cash resources. The acquisition is expected to be immediately earnings accretive."
Thanks for alerting us to the Facilities by ADF aquisition Jonno. I had a look at the ADF web site to find out more about the company and it says "Marsden Proctor (Managing Director) has a strategic plan for the business" which I guess should be comforting but perhaps I am being stupid, but I couldn't find anywhere on the web site (or internet) explaining what this strategic plan is. Does anyone know where this strategic plan is available? I was hoping it might involve more aquisitions as I imagine the area in which ADF works is quite fragmented so there could be scope for a serial aquirer to prosper.
Any analysis of Creightons (CRL) please?
Stong results from Duke Royalty (LON:DUKE) .
Total cash revenue* of £10.4 million, up 34% from the prior
period.
Recurring cash revenue**, also £10.4 million, increased 67%
Free cash flow of £6.6 million, up 44%
Net profit generated of £10.3 million, a 66% increase
The interesting thing for me on Duke Royalty (LON:DUKE) is the yield which now sits at what, around 5.6p annually = 16% ?? This appears to be covered by cash generated too.
Critics hit out at the companies penchant for raising cash to invest whilst paying dividends. I understand that point but I think Duke Royalty (LON:DUKE) would point to the idea that capital lent/invested is done so on a long term basis and thus new equity goes into new income generating investments and comes out as dividends. A bit like an AUM model.
The other thing investors haven't liked is the conversion to equity ownership of the companies they lend to. There is a risk of it being NAV destructive. That's also fair but it could equally be significantly NAV accretive. I guess you need to take a view on the managements ability to sell out of holdings as well as accumulate them through a cycle.
The interesting thing for me on Duke Royalty (LON:DUKE) is the yield which now sits at what, around 5.6p annually = 16% ?? This appears to be covered by cash generated too.
Somehow you've doubled the dividend. It is 2.8p and the yield is still a respectable 8.2%.
All the best, Si
lol - yes you're quite right Is - not sure what planet I was on when I got up this morning :)
But yes 2.8p and 8%+ and growing is indeed respectable.
Joules (LON:JOUL)
Sky News
South African fashion and homeware retailer TFG TFGJ.J is
close to securing an agreement to buy the majority of collapsed
fashion retailer Joules' JOUL.L stores and assets under a
rescue deal.
Just seen that Joules (LON:JOUL) has been taken over by NEXT
https://www.bbc.co.uk/news/bus...
Any views of Foresight group (LON:FSG)? Seem a well performing growing group at a cheap price.
Looks another excellent update Foresight group (LON:FSG) with continued strong flows. Along with Gresham House (LON:GHE) they seem to be in a real sweet spot, with a focus on infrastructure and sustainable assets - strong investor demand, recurring revenues and far less impacted by short term market volatility than the mainstream fund managers. On top of that it's fairly cheap on roughly 13 times earnings, and pays a good dividend. The only mytsery is why it gets virtually zero attention on this forum, but thanks for highlighting.
Totally agree Bouden54. Never gets any coverage since I’ve been a stockopedia subscriber, and haven’t seen it discussed much either. Looks a far better long term investment than the vast majority of company’s which are heavily covered here.
I would like the undoubted analytical skills of Paul and Graham to be redeployed to shares which stand a chance of getting some of my investment money. Looking at my portfolio there are very few UK small caps in there, certainly no retailers, and all the better for it. I really am very tired of hearing about Joules and the like, they are a waste of my time and my time is precious to me (if not to anyone else!).
A very good comment and I totally agree. I want to hear about good companies with a bright future. Rubbish companies is of interest only to the current shareholders who should sell out and move on.
Some retail shares have done quite well in November, quite a few up over 30%,:so I would not dismiss that sector completely.
Paul and Graham cover many different stocks, which ones do you want them to cover?
I have had direct dealings with Foresight recently and I have good contacts in the forestry industry .Gresham have a great reputation and are the largest forestry investment group in the UK, with the hidden upside of. Windfarm developments . Good established company with credible long term reputation .
Foresight I have to say are quite the opposite and currently have issues in terms of long term management and credibility .
Both parties but particularly foresight have overpaid i for assets in the past 18 months based on valuing “carbon credits” and adding to the land / forestry values causing a big spike in prices.
However the carbon credit rules were modified so that effectively commercial conifer planting is excluded and carbon credits limited to the less commercial broadleaf .
I have 200 hectares of planting land in south Scotland and on our initial calculation the carbon credits valuation attributed was circa 300k around 25% of the value of the property , with the rule change this value has dropped off . Furthermore even if you went ahead with a forestry plan incorporating carbon credits with broadleaf , that limits you to sticking to that plan for the life of the project so it is something the forestry managers intensely dislike as they are limited to that plan .
Furthermore foresight and Gresham had a huge outflow of funds following the liz truss pension crisis and are currently much more limited on being able to complete transactions .
Gresham are the star player with history and knowledge and longevity .
The real interesting play is going to when Gresham manages to entwine the energy storage area with their wind farms on their huge forestry land bank - the first company to be able to effectively store their energy produced by windfarm will have a golden ticket .
Interesting insight on the forestry side of the business, although worth noting it makes up only a small part of their business, being fairly new entrants in this area. The LDI fiasco will have created a bit of a wobble too as pension funds look to offload some of their less liquid assets, but think the long term trajectory remains very favourable.
They seem to have a good diversified model, with a global footprint. The Australian acquisition seems to have really kicked things on too. Fundamentals look outstanding on stockopedia
Planetx - Following on from your comment about combining energy storage + wind + forestry, and looking at Gresham, would you suggest Gresham House (LON:GHE) or Gresham House Energy Storage Fund (LON:GRID) as the most levered play on this combination? Perhaps with some Crestchic (LON:LOAD) as a pair?