Small Cap Value Report (Thu 1 Feb 2024) - SAAS, BAG, MTEC, RNK, IHC, LSL

Good morning from Paul & Graham!
Today's report is now finished.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
.
Other mid-morning movers (with news) -
B90 Holdings (LON:B90) - down 12% on TU. We dropped coverage here in 2019, serial loss-maker.
Superdry (LON:SDRY) - up 14% to 22.4p - no news, but I’ve just looked at the last accounts, which confirm my view that equity probably worth zero, and CVA only realistic option, shareholders will be lucky if they salvage anything in my view. Newco (Dunkerton + fresh backers?) most likely maybe?
Everyman Media (LON:EMAN) - Blue Coast (biggest s/holder, linked to NED M Rosehill) buys 3.75m at 56p. Now holds 25.1m, 28.3%. Interesting move. I wonder if they might bid for all of it?
Argentex (LON:AGFX) - up 5% to 58p - man of the moment Richard Steveley of Rockwood Strategic discloses a purchase, taking him from undiscloseable up to 3.5%
CAP XX (LON:CPX) - down 21% to 0.75p - Interim results. Looks bust to me without an imminent fundraise. Patent loss legal case being appealed. Commendable quick reporting of Dec 2023 H1 results though.
Summaries
Microlise (LON:SAAS) - 132p (£152m) - FY 12/2023 Trading Update [slightly ahead] - Paul - AMBER/GREEN
Rarer than hen's teeth - a 2021 IPO that actually looks quite good, and hasn't collapsed in price! I've circled back to look at this telematics company's recent update, as it drove a c.30% rise in share price. I can see why, this looks a really interesting company. Not cheap though, but performing well, and seems to have nice growth potential too, albeit in a crowded market. Worth a closer look I reckon.
A G Barr (LON:BAG) - up 2% to 579p (£649m) - Trading Update - Graham - GREEN
Profits are coming in slightly ahead of expectations which the company attributes to “positive underlying brand momentum” despite wet summer weather in Q3. Cost inflation seems to be cooling down, which bodes well for the restoration of profit margins. I remain positive.
Made Tech (LON:MTEC) - down 21% to 10.3p (£15m) - Trading Update - Paul - AMBER/RED
It's not actually a profit warning, and the H1 highlights seem OK, but slow order intake and worries about the general election sound like we're being warmed up for a poor H2. No broker forecast changes at this stage. The one good feature is a strong balance sheet, with plenty of cash. Although note it's burning cash due to heavy capitalised development spend (payroll that's put on the balance sheet instead of being expensed). Not a serious investment, but might be a fun punt for a rebound at some point maybe?
Rank (LON:RNK) - up 3% to 72.7p (£340m) - Half-Year Report - Graham - GREEN
The full-year outlook (FY June 2024) is in line with expectations as this gambling operator posts its full-year results. The investment thesis appears to be playing out with a high degree of operating leverage visible. Revenues continue to grow while cost inflation has cooled.
Inspiration Healthcare (LON:IHC) - Bank covenant waiver granted - Paul - AMBER
Good to see that the required bank covenant waiver flagged in yesterday's SCVR has now been granted (no other detail provided). So as mentioned yesterday, once this was granted, I've moved up from amber/red, to AMBER. It wasn't really in any doubt, but shareholders should get a better night's sleep tonight!
Inspiration Healthcare Group plc (AIM: IHC), the global medical technology company pioneering best-in-class, specialist neonatal intensive care medical devices, announces that further to the announcement on 31 January 2024, the Company's lender has granted a covenant waiver in respect of the 31 January 2024 covenant test date.
LSL Property Services (LON:LSL) - Up 4% to 275p (£285m) - Trading Update [in line] - Paul - AMBER/GREEN
I like things like this as cyclical recovery candidates. Doesn't look obviously cheap at this stage, but they never do when earnings are at a low point. 2023 is in line with expectations, and increased earnings in 2024 are expected. Has switched to a franchise model. Net cash. Quite interesting potential I think, but has risen 27% already in last 6 weeks, so I'll bide my time.
Paul’s Section:
Microlise (LON:SAAS)
132p (£152m) - FY 12/2023 Trading Update [slightly ahead] - Paul - AMBER/GREEN
Microlise Group plc (AIM: SAAS), a leading provider of transport management software to fleet operators, provides the following unaudited trading update covering the expected results for the year ending 31 December 2023 ("the Period"). The Group expects to publish its full year results for the Period in early April 2024.
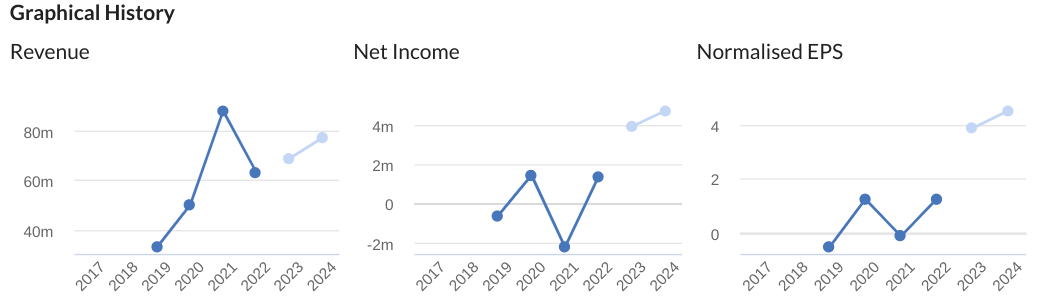
I can’t remember anything about Microlise, and we didn’t look at it in 2023. So starting from scratch, what’s it’s track record like? Looks a bit patchy, but with strong revenue growth, and good forecast profits for 2023 & 2024 - although bear in mind it only floated in mid-2021, so pre-IPO numbers are often not comparable (since private companies typically minimise profits to reduce tax) -
Latest news - highlights for FY 12/2023 sound impressive -
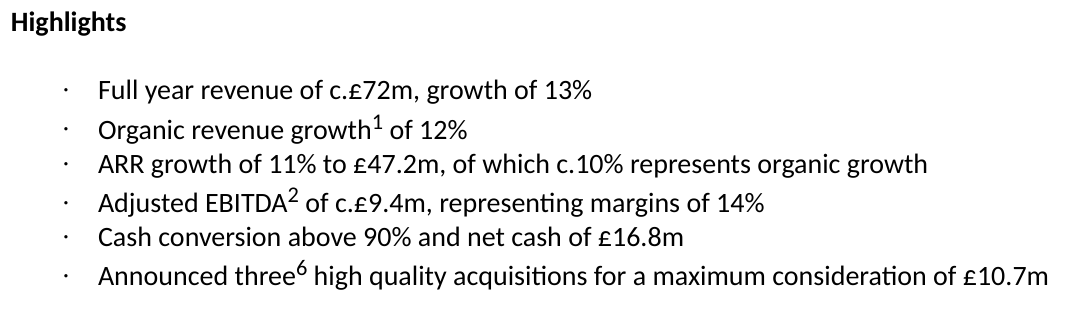
SAAS says FY 12/2023 adj EBITDA was slightly ahead of expectations (£9.4m actual, vs analysts range of £9.1 - 9.2m)
Key question - how much of EBITDA turns into real profit?
Many thanks to analysts Tom & Harold at Singers, who crunch the numbers for us (incredibly helpful, and I know a lot of work goes into these notes). They reckon £9.4m adj EBITDA above turns into £5.5m adj PBT and 4.3p adj EPS (my two preferred measures, but the hardest ones to actually find, usually missing from most companies’ trading updates!)
Hence at 132p, SAAS shares are currently valued at a PER of 30.7x FY 12/2023 earnings (after this latest upgrade to forecasts) - a punchy rating, so the outlook needs to be very good to justify that.
Analysts flag the key bull points as being -
Mission-critical product
Minimal customer churn (although that depends how it’s calculated - some companies offset negative churn against other customers buying more licences)
Big customer wins
Undervalued relative to peers.
Recurring revenues gives visibility - ARR ended 2023 at £47m (with 10% organic growth)
Net cash was £16.8m at end 2023, unchanged from a year earlier.
Balance sheet? Surprisingly threadbare! NTAV is slightly negative, with the business seemingly funded by up-front customer payments, but that’s normal in the software sector, so not a concern. With more acquisitions happening, I think management need to be a little careful not to overstretch their balance sheet in future. Although arguably a reliably profitable recurring revenue business like this could even take on a bit of bank debt, and at present it has none, so I’m probably fussing unnecessarily here.
Dividends? There aren’t any. So looks like it’s focusing on growth, rather than income for investors. They’ve managed to achieve a PER of c.30x, so arguably more value has been created for shareholders through that, than through potential divis!
IPO - It floated on AIM in July 2021 (oh dear!) at 135p. Given that’s almost the current share price, this has to be seen as a rare success relative to its 2021 peer group.
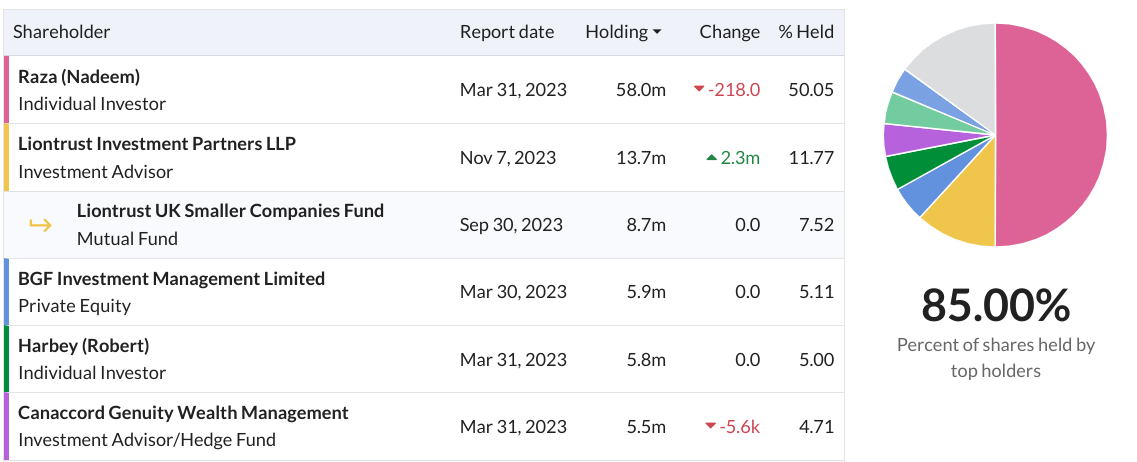
Who owns it? - looks like a founder CEO, which I like, but 50% is a bit too high for my liking. Other shareholders are just along for the ride, with no say in how anything is done. So additional checks are always needed in this type of situation I think (eg lockins, share options, remuneration, track record of key management etc) -
Customers - this sounds impressive, and ultimately is what determines success or failure - offering a product that customers want, which benefits their business. Some impressive brand names here -
The Group added 450 new customers during the year with key customer wins including McCulla, BCA/ECM, LF&E and two significant customer wins in Australia, further cementing our position in one of our key target markets. Microlise also extended its relationships with numerous existing customers including Tesco, Culina and Bidfood. The Company continues to have high rates of customer retention, experiencing very low churn of 0.7% during the Period, reflecting the strength of our customer relationships and the value our product offering brings to customers.
Outlook - fairly general, but sounds positive to me -
Microlise expects to deliver strong revenue growth in FY24, driven by further organic growth and recent M&A. To service a growing pipeline and deliver an improved proposition, the Group has commenced its investment programme into its TMS offering following the acquisitions of Vita Software and ESS as planned. Looking ahead, the Board sees an opportunity for organic growth to improve from current levels as we move through the year supported by a healthy orderbook and pipeline of opportunities across OEM and direct customer divisions. Operating margins are expected to trend upwards in FY24 and beyond, as we focus on careful management of the cost base and efficiently scaling the Group…
"The three acquisitions made during the period have resulted in an improved and expanded offering which is already having a positive effect on trading momentum and pipeline. This, together with the resolution of the microchip supply crisis, gives us confidence in the Group's continued success."
Paul’s opinion - not an obvious value share, and I’m unfamiliar with the company, but for my first proper look at it, I have to say this looks a nice growth company.
It’s just an initial review, but I’m leaning positively towards SAAS shares, which I think are worth investors taking a closer look with some proper research.
Hence I’ll go with AMBER/GREEN.
Made Tech (LON:MTEC)
Down 21% to 10.3p (£15m) - Trading Update - Paul - AMBER/RED
Made Tech, a leading provider of digital, data and technology services to UK public services, is pleased to provide a half year update on trading for the six months ended 30 November 2023 (the "Period"). The Group expects to publish its half-year results for the Period on 26 February 2024.
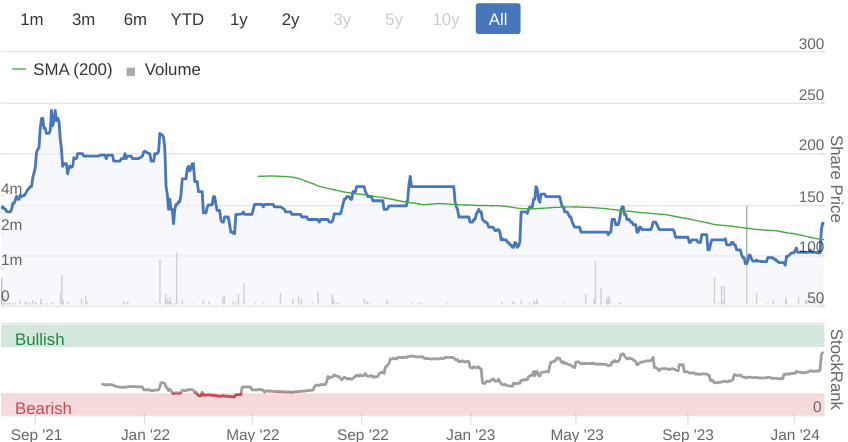
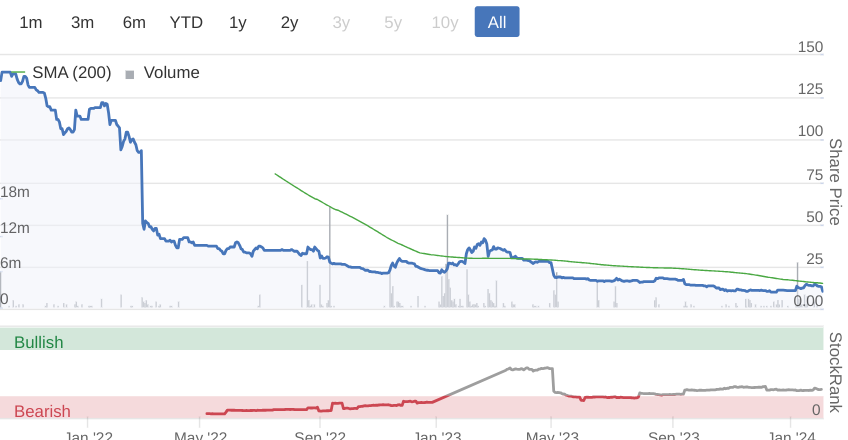
A disastrous Sept 2021 float. The story was of lucrative public sector IT work, but the reality has turned out to be that it’s much harder to make money from this than they thought.
Graham turned red here on 2/5/2023 and since we both think it’s a crock, we haven’t looked at it since. I have to look today, to get it into the system as a profit warning. Although it’s not actually a specific profit warning - no FY 5/2024 guidance is given by the company, and the Singers analyst has left forecasts unchanged today. Although slow order intake in H1, and comments about a slowdown caused by the general election does sound like it’s warming us up for a profit warning later this year maybe? The 20% drop in share price suggests that’s how other people have interpreted this update too.
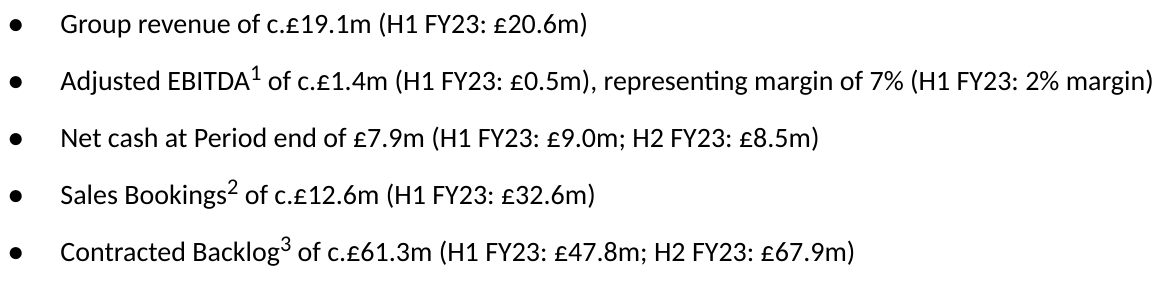
H1 highlights look OK - EBITDA has risen, and a decent order book, plus half market cap in net cash -
Outlook -
Management continues to focus on further productivity and cost control measures to further improve margin performance over time….
The Board anticipates that the procurement market will be impacted by the uncertainty created by the upcoming General Election in the short term. Notwithstanding this temporary market backdrop the strong improvements made to Made Tech's operating model and margins, the investment in its commercial offering, combined with its strong balance sheet and Contracted Backlog, position the Group well to execute on its growth strategy.
We have a promising pipeline of new business opportunities, although the market is undoubtedly challenging right now and we expect this to remain so ahead of the general election. The medium term drivers of demand in our market remain strong and we are focused on making further improvements to the business and putting all the necessary building blocks in place to enable us to capitalise on the increase in trading momentum that we expect post the election. "
This is the first company in our universe which has blamed the forthcoming election for poor order intake, but given that it’s targeting public sector organisations, there might be some credibility in that I suppose. Although MTEC projects are not exactly major, or controversial projects, and given that the same civil servants run the country before and after elections, it might be stretching credibility a little.
Share based payment charges in the last 2 years full accounts are a sick joke - over £2m pa.
Balance sheet at May 2023 is actually very good indeed. This is a well-financed small business, with £10m positive working capital, and no debt.
Paul’s opinion - much to my surprise, this is actually quite interesting, due to the cash asset backing, supporting about half the market cap. That’s proper cash as well, not just money up-front from customers.
Real profits are not far below EBITDA, if you can persuade management to keep their hands out of the share options till. Ah, no they’re not! I’ve just spotted that it capitalised £3m of payroll into intangible assets in FY 5/2023, so scrub that. The cash pile is falling, and forecast to continue falling, which suggests it’s burning cash, not generating it. So that’s killed off any early signs of interest from me.
Bottom line, it looks a low quality business, probably tendering for Govt work where there’s little prospect of making genuine profits/cashflows.
On the upside it has an unusually strong balance sheet, so insolvency/dilution risk seems very low. For that reason, the shares might be a fun trading punt (maybe a 20-50% tradeable spike up in price to quickly sell into? As happened a year ago), with the downside fairly well protected by that strong balance sheet. But as a serious investment? Nah, I wouldn’t waste any time on it.
LSL Property Services (LON:LSL)
Up 4% to 275p (£285m) - Trading Update [in line] - Paul - AMBER/GREEN
Estate agents chain updates us today - only in line, but the update might have interesting read-across of wider interest.
2023 results in line with expectations
LSL issues a pre-close trading update for the 12-month period ending 31 December 2023.
“Positive final quarter”
Group Underlying Operating Profit in the second half of the year showed a material improvement on H1.
The switch to a franchise model seems to have gone well -
Following the conversion of our Estate Agency network to a wholly franchise model during H1, the Division continues to perform ahead of plan for both revenue and profits, with second half operating margin of c.30%.
Outlook - this sounds as if they’re not factoring in much general market recovery, so I wonder if there might be possible upside on current forecasts? -
…and at this early stage we remain comfortable with delivering profits in 2024 materially ahead of 2023…
The Group's trading in January was in line with management expectations and ahead of 2023. At this early stage of the year, we remain on track to deliver a material increase in profit for 2024 compared to 2023 due mainly to the benefits of improved performance in Surveying, as well as a full year of operating the franchising model. A further update on current trading and outlook will be shared with the release of our preliminary results.
Cash looks healthy, although I would need to see the whole balance sheet before being sure -
Strong balance sheet with Net Cash of £34.9m at 31 December 2023 (31 December 2022: £40.1m), providing flexibility for future deployment of capital.
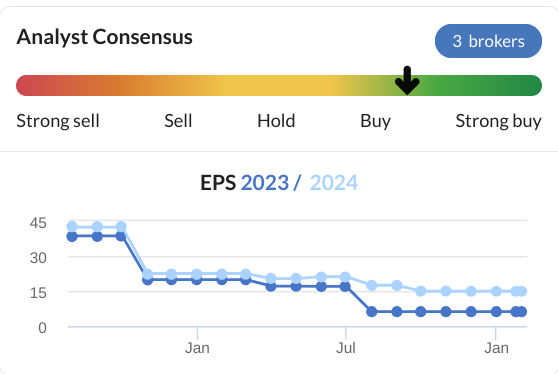
Earnings upgrades - nothing has started yet, but notice below that 2024 is already more than double the 2023 greatly lowered forecasts. Although Zeus points out in a helpful update note today that 2023 results were suppressed by one-off costs re the changeover to franchise model.
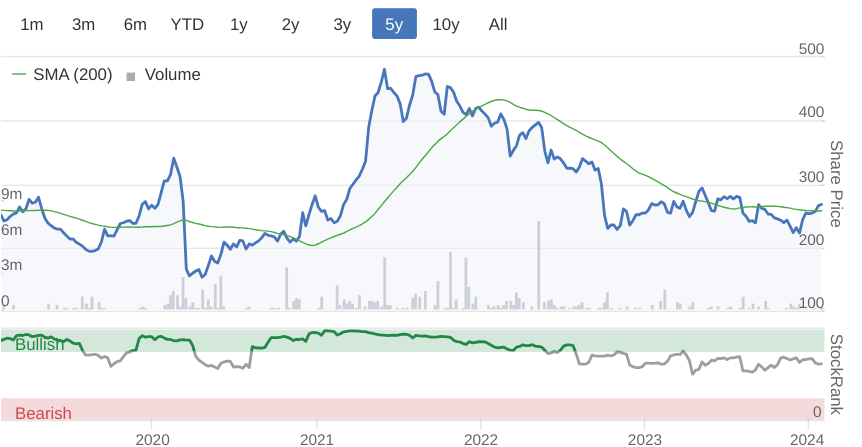
As investors we want to get in before the earnings upgrade cycle starts, I would suggest, and often the PERs look quite high at this stage in the cycle because forecasts are low in absolute terms (but could have multi-bagging upside in a recovery) -
Paul’s opinion - I think this is an interesting time generally to be looking for cyclical recovery shares. Given everything that’s happened with the housing market, and the seemingly positive outlook for at least some level of recovery in transactions, then estate agents would be an area of considerable interest to me at the moment.
LSL doesn’t seem obviously cheap, and the share price has had a 27% bounce in the last 6 weeks, hence I don’t see any rush to get involved personally in the short-term. But I would happily place a 50p bet with anyone that this share ends 2024 higher than it is now.
Graham’s Section:
A G Barr (LON:BAG)
Share price: 579p (+2%)
Market cap: £649m
This is an update for the year ended 28th January 2024.
AG Barr is an old soft drinks company which I’ve included in my favourite ideas list for the past two years. Thankfully, the news today is positive:
Revenue c. £400m, up 26% year-on-year including the impact of an acquisition, up 7.6% on a like-for-like basis.
Adjusted PBT £49.5m, up 13.8%, and slightly ahead of expectations.
Brief explanation:
Despite the wet summer weather which impacted Q3 market conditions, our positive underlying brand momentum ensured a strong H2 Group performance.
The company has some non-soft drink operations:
Cocktails: strong performance in the off trade, but the on trade channel “remains variable”, with reduced footfall at late night venues.
MOMA Foods: this subsidiary makes porridge and oat drinks, and has posted double-digit sales growth.
Inflation
The key theme in the soft drinks sector has been inflation. By putting BAG (and NICL) in my best ideas lists, I’ve been betting that inflation will continue to feed through to consumer prices and that pre-inflation operating margins might again be achieved by these companies.
A.G. Barr says that inflation continues to “drive value growth” while also impacting volumes; i.e. revenues are going up while the amount of product actually being sold is going down.
Fortunately, there are signs that inflation might be levelling off (note that UK CPI is currently 4.0%):
We continue to experience cost inflation albeit at a less significant level than in the prior year. Our supply chain capital investment programme is on track supporting the in-sourcing of the Boost and Rio brands. The associated operational leverage and synergy benefits are supporting the acceleration of our margin rebuild programme.
Graham's view
Here are the company’s operating margins and ROCE figures from 2018 (left-hand-side) to now:
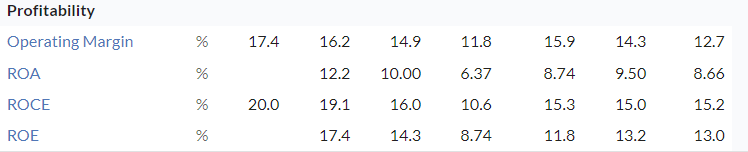
A return to pre-Covid operating margins and ROCE would provide a nice boost to earnings and in my view would easily justify the current valuation:
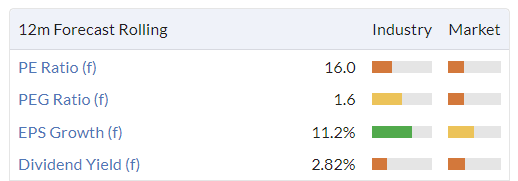
I am therefore going to stay optimistic and positive on this one even though the share price is already up 13% year-to-date.
New CEO: existing CEO Roger White is stepping down after twenty years for a well-earned rest. Hopefully A.G. Barr is one of those businesses that is so wonderful that any idiot could run it.
Rank (LON:RNK)
Share price: 72.7p (+3%)
Market cap: £340m
I’m keeping an eye on this for signs of a return to former glory. In the past, when there has been a favourable mix of a) tourists and business travellers wishing to splash bets, and b) moderate cost inflation, profits at this casino group have soared.
Here are the interim results to December 2023:
Like-for-like net gaming revenue +9%
Like-for-like underlying operating profit £21.7m (last year: £2.7m), “reflecting both the growth in NGR and the operating leverage of the group”.
Wage inflation of 8% (costs up by £8.3m) were offset by declining energy prices (costs down by £5.4m).
At first glance, the investment thesis appears to be playing out. Cost inflation has cooled down, giving the company the chance to make meaningful profits as revenues take off.
Outlook - there was a “good performance” over Christmas and New Year, which were “busy”. Full-year like-for-like profits for the current year (FY June 2024) remain in line with expectations.
Financial KPIs: the core “venues” division (i.e. casinos and bingo halls) has seen faster revenue growth (10%) than the non-core “digital” division (8%).
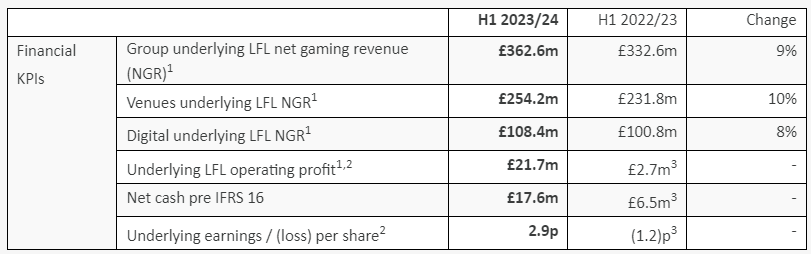
Debt: the company is carrying net debt of £145m under current accounting rules but if you’re happy to look past leases, then it’s actually in net cash of £18m.
I like this statement of confidence re: the company’s financial strength:
The Group's strong financial position is enabling ongoing investment in our venues and digital businesses and positions the Group to take full advantage of any future improvement in the macro-economic climate and the planned and much needed reforms in the UK Government's review of gambling legislation.
Dividend: none are being paid currently, but Rank “expects to recommence dividend payments as soon as circumstances permit”. Maybe soon? The StockReport suggests that dividends are forecast at the end of the current financial year.
CEO comment: excited on two fronts, both the operational leverage and the regulatory reforms:
"After what has been a very challenging few years for Rank due to a wide range of external macro factors, we are starting to build revenues and, with our strong operational leverage, we are improving our profitability, with the Group delivering revenue and operating profit growth across all businesses.
Grosvenor casinos - fewer high net-worth tourists are visiting the UK, which is holding back spend per visit. But overall casino visitor numbers are still up 8%.
Mecca bingo halls - the estate has reduced to 55 as another loss-making venue has been closed. Twenty venues have shut down post-Covid, leaving a smaller, more focused estate. Mecca is now trading around breakeven (previously loss-making) and is expected to be profitable by the year-end.
Graham’s view
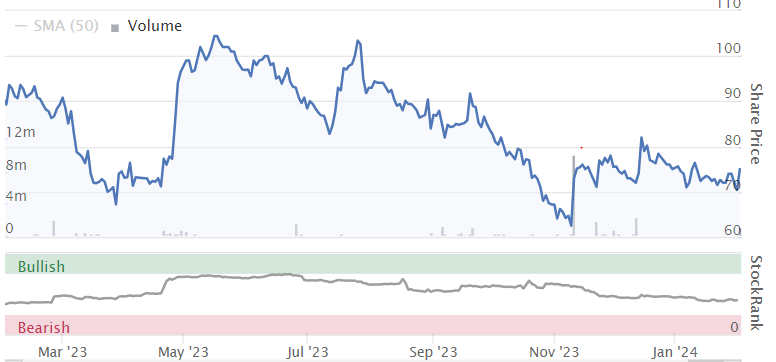
I’ve been positive on this one since last August; the share price hasn’t co-operated yet, but I’m enjoying the news flow. Revenues are rising well, and costs are no longer soaring as they were previously.
Valuation based on current forecast numbers still leaves plenty of upside in my view:
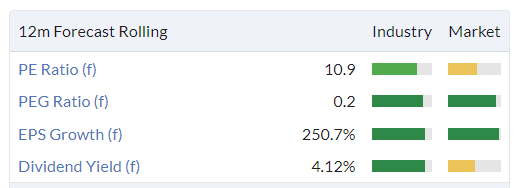
I can’t argue that this is a high-quality stock, as its performance is so sensitive to factors that are beyond its control - energy costs, high-net-worth visitor numbers, and consumer sentiment. But it does strike me as a value stock with good potential from this level, so I’ll stay positive on it.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

86 comments
Gresham House Energy Storage Fund (LON:GRID) and Harmony Energy Income Trust (LON:HEIT) I don't hold and know little about either but noticed the piece from Adam Bell on X yesterday with regards to OFGEM possibly invalidating the above's business model somewhat.
https://x.com/Adam_Grant_Bell/...
Re Gresham House Energy Storage Fund (LON:GRID) - Good debate. It is clearly a huge sell off especially in the last 6 months and crystallising in the latest trading update. However, just as the upside was driven in part by wishful pro-green thinking (turned into invested capital by shark like financial types like £GRID!), is the current sell off not the reverse? The responses above include a lot of anti-Net Zero rhetoric, only some of it related to investment vs a political view.
A basic insight is that UK renewables are now big and forecast to keep growing fast. The brilliant website National Grid: Live (iamkate.com) shows that renewables delivered 36% of national grid power in the last year vs 35% for fossil fuels. That will only grow in the next few years - especially under a Labour govt. Renewables face issues of intermittency and meet demand side intra-day peaks and troughs. Gresham House Energy Storage Fund (LON:GRID) batteries can deliver volumes for 1-2hours at peak times and respond very fast to keep the grid balanced. There is (nearly) always cheap excess power at night to arbitrage. Seems likely tech solutions can be found to the grid control room system issues that have undermined the business case recently
All market prices reflect different views of risk: reward and a willing buyer and seller. At under 50p and a price to tangible book for nearly new CAPEX of 0.4, Gresham House Energy Storage Fund (LON:GRID) looks pretty good to me. I will be a buyer from those disappointed sellers who - not unreasonably at the time - bought at 120p a year ago
We'll only know who made the right decision in 5 years (or <12months if it goes belly up!)
.
Battery storage is supplier of last resort to the grid. Therefore they make huge amounts of money, intermittently.
Debt to fund these batteries. They require regular interest payments. And loan repayments. And probably have covenants around quarterly/half yearly income.Historically (although there isn't much of that), the battery storage guys made their money from super rapid energy release to stabilise the grid - frequency response - plus some 'last resort' buying. The former business has largely gone and capacity growth means its spread out over many more batteries. The latter is always there but as you say, feast or famine.
The battery business in the future will have a much higher % of traded energy (effectively buy cheap, sell back in the peak). It will still be volatile but a portion of their capacity can be sold to secure a regular (lower but more certain) income to match the interest required.
From my research, there are some quite big technical tailwinds coming for batteries most likely - depends on continued growth in renewables, govt regulations and some IT problem solving - especially under a Labour Govt. So, its an industry that will grow.
Gresham House Energy Storage Fund (LON:GRID) have gone early and secured lots of the best sites / connections and got given cash from investors to buy their initial kit at high share price vs today's - but then run into a short term, classic new business revenue and cash flow problem. Hence the divi cut (I dont think this will be the last missed divi this year and the dropping of international expansion)
You might be right on there being better financing structures in theory but my belief is that Gresham House Energy Storage Fund (LON:GRID) will be able to recover and manage its finances (new short term debt to manage the long term debt? - good I know!) and then be in a strong position within the industry.
You can only bet on the horses in the race at the odds on offer. At 120p and unbuilt, I was glad it was other investors money going in, at 50p with most stuff built and potentially able to generate revenue soon if opportunity arises, I like the odds much better....but I could very easily still be wrong, especially if financing costs don;t drop. As ever we will see.
NWF (LON:NWF) H124 results – analyst presentation with Q&A from yesterday. Video & podcast.
New management the ex CFO, Chris Belsham, becomes CEO and a new CFO, Katie Shortland, her experience includes: M6 Toll, Meggitt and Rolls Royce. A good team
Results in line, reflect normalising market conditions. Lower oil demand and prices, due to warmer weather; feeds: again lower volume and prices due to lower demand because of wetter, warmer weather. Food (grocery food logistics) was the real star with EBIT +38% and an EBIT margin 7.3% (historic average 3.7%).
73% of earnings are in H2 and they are forecasting in line for the FY24.
In FY24 they’ll invest in a new Foods warehouse, the site will have £8.5m capex with a further £2.5m in FY25. This will impact FY24 PTP by 12%, £1.7m. It will be operational by Autumn 2024. It is expected to generate an IRR of c20%. FY25 forecasts remain unchanged.
FY24 may see more M&A in fuels, as the revenues for potential acquirees stabalises so a far valuation can be arrived at on both sides.
PE 10.5 Divi 3.8% ROCE 20%. I sense ambitious management.
The Bank of England has forecast that inflation could ease to its 2% target within a few months - as it opted to hold borrowing costs at 5.25% for the fourth time in a row.
In a further sign that it is beginning to consider lowering the rate, the nine-member committee was split three ways, with one member, Swati Dhingra, voting for a cut, two members voting for higher rates and the remaining six members favouring a hold.
The Bank upgraded its forecasts for gross domestic product (GDP) growth in the coming years, projecting annual growth rates of 0.5% by early next year (compared with a previous forecast of zero growth), 0.8% by early 2026 (compared with 0.6%) and 1.5% by early 2027.
"two members voting for higher rates"
What exactly are these people smoking. Any hikes now won't have an impact for maybe 18 months? you have to question their sanity.
Highly unlikely theyll cut until the US cuts. I think they probably should have already cut but what do I know.
Almost everyone's turning bullish so I'm keeping half an eye on rate lag effects potentially causing serious problems this year. After the last 3 crazy years it's worth keeping an open mind on all possibilities, taking nothing for granted.
"two members voting for higher rates"
"What exactly are these people smoking. Any hikes now won't have an impact for maybe 18 months? you have to question their sanity."
Yes, that surprised me.
Forecasting anything is notoriously difficult but these people seem to be right every time.....apart from one tiny detail!
Was it Philip Davies MP that described B of E Governor Andrew Bailey as a 'clown who has been wrong about virtually everything'?
As you say Wolf, keep an open mind but surely even a novice can read the general direction of travel....?
It’s an election year economy; they will cut at some point close to when the yield curve is not so inverted and usually that’s when the bear market accelerates (after the elections).
Isn't that the big worry?
One could easily dismiss those two members who voted up as muppets.
But they are definitely no fools... And they do have access to more macro data than you or I or most investors would have.
This is a useful video for potential inflation numbers in a couple of weeks. If we do see a short term spike in inflation it may provide a good entry into housebuilders/suppliers etc. Can never be certain whatll happen but will be interesting to see if the market starts to price this in, or has a panic short term selloff. Of course Jamie Constable could be wrong, but I watched a lot of these videos in 2022/23 and he called things far better than most imo, and is always worth listening to
Made Tech (LON:MTEC) How on earth was this rubbish given a valuation of £180 million at IPO. Maybe it'll start winning lots of contracts this year but even Singers sound depressed and they've been bulls since 2021. Float price was 122p I think so it joins the 90% club.
When you pocket so much money during IPO would your heart really be in it now?
Thanks WolfoSS,
That's such a good point - checking the Admission Document for the selling shareholders, can be incredibly revealing, as in this case with Made Tech (LON:MTEC) , thanks for posting that very useful info.
This reminds me a bit of why BOTB management were relaxed about selling up for a lousy price. It's because they had already financially cashed out big time, previously stuffing the institutions at £24 per share. So their remaining shareholdings were literally chicken feed in comparison.
Regards, Paul.
Although in fairness Rory MacDonald and Chris Blackburn appear to have increased their holdings in the Autumn to 43% of the company.... we could certainly criticise their cashing out originally, but they clearly see value at these levels and are definitely incentivised.
Bushveld Minerals (LON:BMN)
Huge spike up in volume today at this South African Vanadium miner. Over 58M shares traded today against usual 5m with lots of small trades going through. Not sure if this has been tipped anywhere recently?
I notice an RNS saying
'Completion of Convertible Loan Note Refinancing'
which could of course be the catalyst as without this situation would be dire....
No sign of Director's buying but they were huge sellers in 2021 at 17-19p. Current sp down to 1.48p although business is heavily loss making and has a LOT of debt.
Anyone else following this one? I used to hold back in 2021 but got out when the Directors abandoned ship
Sold Bushveld Minerals (LON:BMN) last week at near 90% loss. For me the last straw was the non appearance of money from investor. Another significant factor which sent the share price down further after I had sold my pathetically small value holding was abrupt departure of the CFO. Looks to me that this share could go to zero but it might stumble on. Another example of a contributor to the energy transition (Vanadium & Vanadium Storage Batteries) that appears to be failing
Just seen Bushveld Minerals (LON:BMN) up 48% today though still only 0.07p above my sale price ! Just do the opposite of whatever I do and you will make money. Though to be honest I think the rise is only a temporary halt to its demise - even with the refinancing arrangements there is still a lot of debt.
For any holders or potential holders of Zotefoams (LON:ZTF) this is worth a few minutes of your time.
According to the investigation, a packaging solution made of HDPE beats cardboard (theincmagazine.com)
Apparently the Rezorce packaging has performed well in tests. There is no mention of cost comparison though which will obviously be important.
Zotefoams (LON:ZTF) (I hold, so the following comment will do me no good at all!)
Helvellyn - Your link refers to a report which was published in 2021. It is not news. The alternative view is this (link)
So, the overall picture is encouraging, but the decline in MuCell sales is particularly worrying. This is meant to be their next big product, but it has been permanently loss-making, increasingly so as their broker, Singer, says:
But the ReZorce product has not commenced sales yet. So surely the MuCell division's revenue and losses are irrelevant at this stage?
Agreed Paul - in essence if the ReZorce product does not commercialise the overall group profitability will go up when it is decommissioned. If it does take off then a potentially big new revenue stream.
I don’t hold because I haven’t quite got my head around the risk/reward yet but looks interesting though has re-rated somewhat recently
Zotefoams (LON:ZTF)
Probably somewhat irrelevant if info is out of date - but just to also highlight it looks like Zoefoams paid for this "independent research" - i would always preume if company is paying with presumably strict list of stuff they want to be looked at its very easy for results to come out positive !!! - note if they pay and results arent positive i would strongly suggest then there woulm have been no update. In summary the good news in this article is probably highly biased in favour of the narrative thats suits zotefoams. I doubt anyone spends the sums zotefoam have spent without being able to produce some positive independent comments - imho that article perhaps says very little about its actual usefulness unless there is more meat on then bones. even the article itself says says its "potentially more environmentally friendly" - not that it actually is !
Zotefoams commissioned the LCA Center to conduct a test with its independent expert
Zotefoams (LON:ZTF) Your comment above "There is no mention of cost comparison" will be crucial, if ReZorce can't be supplied to carton manufacturers at the same cost or less than the current Tetra Pak product, then it's unlikely to dent Tetra Pak's dominance. The cardboard/polyethylene film/aluminium foil composite that is Tetra Pak's product claims to be fully recyclable, which it can be but only with specialist recycling machinery. I am sure in the uk, most cartons are not recycled (I am sure they are not in N.Yorks anyway). The ReZorce carton and its cap would easily be recycled being only one material high density Polyethylene (HDPE), this is its green advantage over Tetra Pak, but Tetra Pack do a good job putting this product can be recycled on each of their cartons, even though few countries will have the machinery to do it. Whilst consumers believe the current cartons are being recycled, I cannot see brands wanting to pay extra for packaging, so costs of ReZorce will need to compete or be a niche product. I do own a holding in ZTF, gambling that ReZorce can compete on cost or future packaging legislation makes the cost irrelevant or Tetra Pak buys the sole rights to it.
Thank you Paul for your write up on Microlise (LON:SAAS) today.
I bought soon after the IPO in 2021 but sold on 9 Sept 21 at 220p for a 28% gain.
I bought because as you say I thought this was mission critical for Fleet Operators but I sold for once at the right time as I anticipated profit taking.
On my watch list now.
I mentioned a few days ago how publishers like Reach (LON:RCH) and Future (LON:FUTR) might benefit from removal of cookies by Google as the year progresses.
Group digital director at Reach gave his views recently:
Reach reveals ‘three pillars’ that prepare it for end of third-party cookies
Publishing giant targets digital revenue growth using first-party data and contextual ads.
https://pressgazette.co.uk/mar...
Paul Hill also chats to James Thorne, Fund Manager at Columbia Threadneedle about Reach (approx 75 mins):
Reach (LON:RCH) is on a p/e of 2.8 yielding 11.98%. The pension deficit issue is well known but the digital side should benefit post cookie removal.
Interesting that Harwood are now stake building in Argentex (LON:AGFX)
Probably bodes well medium term
Argentex (LON:AGFX) (I sold) and Richard Staveley of Rockwood Strategic (LON:RKW)
Paul says that Mr. Staveley is the man of the moment.
For an alternative view see this substack post and search for Titon Holdings (LON:TON) (I hold).
Just to show there is ALWAYS an alternative viewpoint about everything!
I am really struggling to see how Argentex is worth 59p. Last year Operating Profit 10.4m and Net Profit 7.4m. If the gap between OP and NP stays at £3m then the NP now will be £8m - £3m = £5m . Divide by 113m shares = 4.4p/share, down from 6.5p and no growth in prospect. Say 10 P/E? Seems generous to me in the circumstances. I reckon the shares are not worth more than 44p. I'm looking forward to seeing who is right. Criticism of my figures welcomed if it helps me get my head round this situation.
Perhaps there is a sale in the offing and that's why they have appointed an interim CFO and the CEO (ex. NED) is also interim? That might explain why the founders haven't sold their shares yet. Perhaps that's it.
EDIT: According to the RNS Rockwood bought 4m shares = 3.5%, and crossed the 3% threshold on 30 January. Looking at the LSE trades the price may have been around 50p so not a great deal more than my "valuation".
I do not hold Argentex (LON:AGFX) but perhaps Richard Staveley looks ahead and not just a picture frame of current results.
Argentex (LON:AGFX)
Enterprise value is £40m
Net profit will be £6m this year so trades on 7*
versus peers that’s very cheap
CEO has a very successful track record in payments businesses having built and sold two. He will do the same here at the right juncture imo.
In reality you can see that some of the investment they made was wasted and that’s what is driving the change in profitability. Strip that out and profitability should exceed £8m with no growth and that’s a PE of 5 (cash adjusted). So new mgmt have got plenty of low hanging fruit available with lots of net cash in a restructure.
So imo the share can happily double or more by core business just treading water and some proper self help mgmt actions. In the event the new CEO does what he has historically on the payments side then plenty of upside to that.
Risk/reward looks good to me - as it seems it does to Staveley and Harwood. I will be buying some
Argentex (LON:AGFX)
David - £8m Operating Profit or Net Profit?
Net profit Michael.
Todays numbers = £8m op profit which will translate to around £6m net profit (see 2019 accounts - you can see that net profit to op profit is not a fixed £3m as you asserted.
However, the drop from Op profit of £11m to £8m was due to some extra costs not anticipated (ie one off’s - extra investment/restructuring costs etc). So next year with no growth I would expect Op profit to be back around £11m and the net profit around £8m and that’s before any “self help”.
Beeks Financial Cloud (LON:BKS) - big volumes since yesterday afternoon.
On a light hearted note, as I read Gresham House Energy Storage Fund (LON:GRID, (Don't hold) I mistakenly thought it was Gore Street Energy Storage Fund (LON:GSF) (I hold) and really couldn't reconcile this to the statement in January.... so my day is not quite as bad as I thought.
I listened to the Navient (NSQ:NAVI) (I hold) webcast last night and can't see much downside in the story now. Sherborne have their feet under the table and over the next year I believe what they have outlined will be accretive. The sale proceeds plus availability of unrestricted cash make the outsourcing deal very accretive .... at least 50% on my maths.... so fingers crossed all works out. This should therefore boost the NAV of Sherborne Investors (Guernsey) C (LON:SIGC) (I hold) to 100 and beyond and 100 seems a reasonable target for now for the share price.
Good luck all with the usual Thursday barrage of newsflow.
Everyman Media (LON:EMAN) (I hold)
Blue Coast Private Equity have taken their holding up to 28.3% today.
The max price I can see that they have paid for their shares in the last 12 months is 60p vs 62.75p today, with 60p bring the minimum price they would have to offer if they crossed the 30% ownership threshold.
I wonder if they might attempt a cheeky low ball offer soon?
A
Bloomsbury Publishing (LON:BMY) (I hold)
For anyone following the story here:
https://www.amazon.com/charts/...
If anyone knows a data source that shows Total Fiction Books Sales By Week please do share. It would be interesting to see whether the market has shrunk, or if SJM sales have indeed gone through the roof.
Thanks
Bloomsbury Publishing (LON:BMY) Yes SJM sales seem to be booming - it also features heavily in the NY Times bestseller lists. I seem to recall there are plans to do a big TV production which should help drive further momentum.
Bloomsbury Publishing (LON:BMY)
Morning Abtan
I hold Bloomsbury. It is a top 5 holding in a relatively concentrated portfolio of 27 UK small caps.
My view is that the company is likely to issue a further ahead update prior to the release of its prelims in May due the strength of its fantasy and science fiction book list . I posted my reasons for this on 10th January, see below.
Just my view and somewhat speculative. The company also has £39m of cash looking for a home.
"Morning Paul
What a gargantuan effort. Very well done.
I hold a number of the shares mentioned; Volex (LON:VLX) ME International (LON:MEGP) Bloomsbury Publishing (LON:BMY) Porvair (LON:PRV) and will explore the others in your selection for possible investment.
Volex (LON:VLX) and Bloomsbury Publishing (LON:BMY) are in my top three and I would not be surprised to see a further ahead statement from the latter before the finals in May. Reasons:
Further down the line the Harry Potter books are being made into a television series by Warner Bros Discovery.
Just my thoughts and I am often wrong.
All the best"
Good spot abtan now confirmed by co.
https://www.stockopedia.com/sh...
Eurocell (LON:ECEL)
Not earth shattering, but a nice touch I think. NEDS committed to regular purchases of their company's shares.
"Eurocell, the market leading, vertically integrated UK manufacturer, distributor and recycler of innovative window, door and roofline PVC building products, announces that all of the current Non-executive Directors have entered/re-entered into a share purchase plan ('NED Purchase Plan') for 12 months from 1 February 2024, on the same terms as the plan previously announced on 3 February 2023.
In accordance with the NED Purchase Plan, each Director has irrevocably instructed the Company to direct one quarter of their net monthly fees to an appointed broker to automatically make market purchases of ordinary shares in Eurocell for the account of the Director. The appointed broker will purchase ordinary shares from the market on, or around, the fifth trading day of the month following each 3-month period.
As a result of entering into the NED Purchase Plan, each Director will be committed to make the purchase of ordinary shares under the NED Purchase Plan in what otherwise may be a closed period. Entering into the NED Purchase Plan will not preclude the Director from buying additional ordinary shares in the Company during open periods.
The market will be notified of the share purchases under the NED Purchase Plan in accordance with regulatory requirements."
All NEDS should be remunerated on this basis in my view
The counter to this is that a NED is supposed to be independent. Ie they are not supposed to be incentivised to allow management to take undue risk purely to chase share price.
So imagine a situation where a CEO is incentivised with a bunch of options that require the share price to be 50% higher. Then the NED buys a bunch of shares. Is the NED now independent or is he incentivised in line with the CEO who is perhaps too focused on short term share price gains for long term stability?
Thus the situation around comp and shares / options for NEDs is quite complicated.
Pendragon (LON:PDG) 8:00am RNS confirming the sale to Lithia completed yesterday and "the beginning of the transformation of Pendragon into Pinewood Technologies, a pure-play SaaS business, which operates the Company's dealer management software business. The Board strongly believes that the growth prospects for the Company will be enhanced materially as a result of becoming a standalone business, as well as through the Strategic Partnership with Lithia."
I hold (in SIPP fortunately) and am interested to see how Pinewood perform going forward
Yes, very exciting times. A lot of volume recently so hopefully they're getting through the Hedin stake.
Yes Peter, I bot after the interview with Christopher Mills and effectively the “stub” has risen by 50% since so I’m wondering whether to off load the share. But I think I’ll hold on as when it’s standing alone and free to win business from other dealers now it may push on quite strongly. It’s also an interesting experiment and I’ll have 24p div to deploy, the question for us all is do we reinvest that in more Pinewood?
Is pinewood traded ? I’m not quite following it
Hi planetx
No - once the 24p divi is paid the shares will be worth 12p as it stands. At that point I believe the name will change as the physical business will have been sold and the SaaS business remains.
Rank (LON:RNK)
Ang coverage of Tekcapital's SALT IPO?
I don' t understand why anyone would be buying SALT at current asking price of 55p when you can buy Tekcapital (LON:TEK) (I hold and was topping up at 7p last month) for 10.5p?
Based on IPO price 43p Tek's holding in SALT was worth £14mil plus they own about £3m shares in Lucyd and £3.3m in Belascura.
Current Market Cap of Tek is £19.5m, and you get 100% of unquoted Guident for free.
Not for widows and orphans obviously.
In a nutshell - discount for liquidity risk.
Tekcapital (LON:TEK) will always trade at a 20-30% discount to the value of micro salt due to investor perceived liquidity risk. Ie offloading shares to realise the investment would need to be done at a large discount to prevailing price.
Gresham House Energy Storage Fund (LON:GRID) So, we finally get a trading update I dont think I have ever seen such a sharper retrace of a share in a month without any news, since I have been investing., from £1,10 to £0,60 in a month, I think the authoities should seriously look into this.
I'm in GSF and the retrace has been equally brutal. GSF has the advantage of profitable geographical diversity. The UK market looks a mess.
Harmony Energy Income Trust (LON:HEIT) as well has shown a similar pattern to Gresham House Energy Storage Fund (LON:GRID) . If anything Gore Street Energy Storage Fund (LON:GSF) has shown a bit more resilience (presumably because of its lower exposure to the UK market. The UK electricity market is showing a lot less intraday volatility, which is a sign of the lack of opportunity for BESS operators compared with a year or so ago, when the national grid seemed under great strain.
My concern will all these companies is their structure. To me they are all high risk operating companies, trying to develop a potentially profitable opportunity. Even given the recent stretch into alternative investment trusts, these companies are really not suitable to be considered investment trusts. Like all investment trusts they use NAV accounting (IFRS10) and therefore it is impossible to see good disclosure on the real underlying performance of the assets (how much are the batteries being depreciated, how hard are they being used etc). This we would see, if they were structured as an ordinary operating company. I once tried to get to see the operating performance of each of the subsidiaries (of Gresham House Energy Storage Fund) which are published by Companies House - but this was hugely time consuming and even then the disclosure is still not as full as I would like and the time lag is so long, so that the figures are not really relevant by the time they have been disclosed.
Interesting to note that someone else uses Companies House documentation as a source for research.
I might also add that documents submitted to Companies House tend to be more brief and to the point as they lack the PR bloat aimed at shareholders.
I dont think I have ever seen such a sharper retrace of a share in a month without any news. I think the authoities should seriously look into this.
It happened to a good portion of my portfolio as 2021 stumbled into ‘22. Count yourself lucky it’s just one share!
Should the authorities investigate? The TU today gives a good explanation for the ever growing investor anxiety of the past month, the reasons for which were understood by the market and discussed on chat boards and websites before the month started. So what is there to uncover? National Grid’s glacial progress towards net zero? The continued competitiveness of gas as an energy balancing resource?
There we have it Gresham House Energy Storage Fund (LON:GRID) have declared no div for Q4. So what are holders in it for if it is not the yield...?
A pretty dire trading update to from Gresham House Energy Storage Fund (LON:GRID). As another subscriber commented the UK electricity market is a mess. It seems a lot of the problem stems from the continued use of gas powered power stations to balance the grid . If the fossil fuel vigilantes get their way then eventually Battery Energy Storage Systems (BESS amongst many other acronyms) will be able to play a greater role after all we don’t need gas do we…? . I hold Gore Street Energy Storage Fund (LON:GSF) which whilst affected by the UK mess does have some international exposure to soften the blow - though you wouldn’t know it from the share price performance. I just hope that Gore Street Energy Storage Fund (LON:GSF) doesn’t have to scrap its dividend and implement a serious capital reallocation policy a la Gresham House Energy Storage Fund (LON:GRID) . As I mentioned in a SCVR comment yesterday there is a useful detailed review of the Gore Street Energy Storage Fund (LON:GSF) business and the BESS market on the Money Makers investment trust website this week. Overall, given the complexities of the EOS (Energy Operating System!!) it might have been wise if I had steered clear of these vehicles on the basis of ‘if you don’t understand the business don’t invest’!
What authority do you suggest and what are they to investigate? The simple fact is that the investment case has gone wrong and the share is dropping to meet the markets' perceived value. You are not the only one to have been caught out; as recently as 16th November 2023 Schroder bought an additional 9.6m shares in HEIT (according to Stocko figures) to bring their total holding to 39.1m shares. Unfortunately it looks like energy storage is still a pipe dream here in the UK and anything in that sector is having a wobble.
TBF this share has been falling for many months - but its worth delving back to the last TU end Sept 23 when they outlined the problems but seemed to imply the dividend was secure...There is always substantial risk with shares that pay (or promise today) mega dividends
I bought GRID after Christmas 23 and have lost 60%. I am new to Stockopedia! I Believed the September update website video on the GRID site! The Fund manager and Board clearly knew the situation had gone pear shaped by mid December. I was offered a one hour slot by the fund manager last week as I had asked why the share price kept falling. I assume he had been briefing others earlier. When I first started investing, Investment trusts were a low risk 'entry level' product. Now they seem very risky. London markets seem manipulated by insiders. I think the institutional drift away from the UK will continue. Other posts about the appointment of Mr Sutherland announced today seems to confirm this view. it's very sad.
I'm following Megan Boxall to the compounding USA.
I'm following Megan Boxall to the compounding USA.
Sorry to hear you’ve had a tough time with your investment in GRID. The best thing is to learn what lessons you can and make better choices. And it looks like you’re doing just that. I seriously recommend keeping it simple with a S&P500 tracker ETF. Beating the market consistently is only possible with a Nasdaq ETF but that carries higher risk.
Neal58 - the key is to stick to the established, vanilla investment trusts of which there are many very good ones. The problem is that a lot of terrible (and far too complex) 'alternative' trusts were set up over past few years and many of these have since imploded - Hipgnosis Songs Fund (LON:SONG) Digital 9 Infrastructure (LON:DGI9) to name just a couple. I would stick to the equity trusts where you can't really go wrong - if you want some alternative exposure as well (property, infrastructure , private equity, bonds) stick to those with a really established long term track record - 3i Infrastructure (LON:3IN) and Pantheon International (LON:PIN) being good examples of those, in my view.
Neal58.
I’m also very sorry to see you’ve lost heavily on Gresham House Energy Storage Fund (LON:GRID and agree with Bouden54 that it’s far better to start with mainstream Investment Trusts. For starters they are much easier to follow and understand and unlike with these Renewables Trusts it’s easy to see the shares they hold.
There are excellent Investment Trust threads here on Stockopedia including a new one started yesterday by Charles Mitchell.
For those new to Investment Trusts I wrote the post below on an Investment Trust thread yesterday. It covers 5 mainstream sectors.
Here it is.(Sorry about the big K but can’t get rid of it)
ken mitchellJoined 2016 670 postsYesterday 8:41pm
For you or anyone else unfamiliar with Investment Trusts here’s a bit of info and suggestions which might help get you started.
1. The AIC website (it’s the trade body for Investment Trusts) is excellent. This link takes you to a very useful page there:-
https://www.theaic.co.uk/aic/f...
Click on the arrow on the “AIC sectors” heading to bring up every sector in alphabetical order.
New investors could perhaps start with a small portfolio of, say, 5 Investment Trusts from these 5 easy to get to grips with sectors:-
1. COUNTRY SPECIALIST.
https://www.theaic.co.uk/aic/f...This link takes you to the Country Specialist Trusts.
Either VinaCapital Vietnam Opportunity Fund (LON:VOF) on 19% discount to NAV at 455p compared with NAV of 562p or VietNam Holding (LON:VNH) 337p on a smaller 7% discount. I prefer VinaCapital Vietnam Opportunity Fund (LON:VOF) despite recent underperformance compared with VietNam Holding (LON:VNH) but hold both.
Look no further than the monthly reports from the Managers like this one from VinaCapital Vietnam Opportunity Fund (LON:VOF) on 17th Jan for why and others are so keen on Vietnam. Here it is:-
https://www.theaic.co.uk/compa...this link brings up this latest monthly report.
2. GLOBAL.
https://www.theaic.co.uk/aic/f...for all the GLOBAL Trusts.
Perhaps Monks Investment Trust (LON:MNKS) £10.58 and 12% discount or Scottish Mortgage Investment Trust (LON:SMT) £7.84 and 10% discount. It used to trade at a big premium to NAV.
When selecting choices check out performance figures and Results statements ,any research comment etc and also top 10 holdings.. I prefer Trusts with more concentrated portfolios.
3. GLOBAL EMERGING MARKETS.
https://www.theaic.co.uk/aic/f...for all the Global Emerging Trusts.
Emerging Markets have had a long spell of underperformance. That could change soon.
e.g BlackRock Frontiers Investment Trust (LON:BRFI) £1.46 and 6% discount or JPmorgan Emerging Markets Investment Trust (LON:JMG)£1.07 and 10% discount or Utilico Emerging Markets Trust (LON:UEM)£2.29 and 14% discount. UEM invest mainly in utilities and infrastructure.
4. UK ALL COMPANIES.
https://www.theaic.co.uk/aic/f...plenty in this sector too!
e.g JPMorgan Mid Cap Investment Trust (LON:JMF) £9.40 and 13% discount. Plenty of alternatives!
5. UK EQUITY INCOME.
https://www.theaic.co.uk/aic/f...Plenty in this sector too. Ditto UK SMALLER COMPANIES SECTOR if that tempts or as an alternative to EQUITY INCOME.
e.g BlackRock Frontiers Investment Trust (LON:BRFI) £1.86 and 12% discount ….and again plenty of alternatives too.
6Reply
Apparently Jefferies have issued a note this am for HEIT - there is almost certainly a read across to GRID and other BESS co.s relying on our disjointed / erratic UK renewable energy goals.
Out of Charge - Downgrading to Underperform
The current extremely weak trading environment for GB batteries presents risks to HEIT's debt service cover. Moreover, with debt amortisation due to begin in 18 months' time, the fund may also potentially struggle to deleverage using excess cash flow. Consequently, we downgrade to Underperform.
Risks to debt service: While HEIT's 51% discount to estimated NAV suggests that the risks around the uncovered dividend (see here) are well understood, the next logical question is whether the current revenue is sufficient to service the debt interest. HEIT's operational cash flow was completely offset by debt costs for the quarter to 31/10/23, when debt outstanding was £95m, or 36% of NAV. Bumpers and Little Raith have both become operational in mid-October, so will support cash generation going forward. However, GB battery revenues have also fallen significantly since then, so we see the risk to debt service coverage continuing into FY24.
Exhibit 1 - Modo Energy 2-hour battery index LTM performance (£/MW, annualised)
Source: Modo Energy/Jefferies
Interest coverage: Assuming HEIT's operational batteries performed in-line with Modo Energy's 2-hour benchmark, we estimate the fund's interest cover for the quarter ending in 31/01/24 to only be 1.1x. As of 28/01/24, January revenue for 2-hour batteries has averaged £27,900. If the quarter to 30/04/24 continues to be as weak, interest costs would once again be uncovered. Furthermore, this could be exacerbated if debt drawings increase to fund construction projects.
Exhibit 2 - HEIT debt interest cover for quarter ending in April depending on unit revenue and debt drawn*
Source: Jefferies *Includes £1.1m in capacity revenue and assumes Rusholme, Wormald Green and Hawthorn Pit become operational on 1 April **Assuming 50% of 2024 OpEx assumption is fixed, so putting through £12.5k/MW of OpEx across all trading revenue levels
Deleveraging: HEIT will need to start amortising the term loan that makes up the vast majority of its debt from June 2025, increasing debt service costs by c.£10m per quarter, based on the current debt outstanding. Even at full operational capacity, HEIT would require annualised trading and ancillary services revenue of c.£150,000/MW to have sufficient excess cash flow to cover this level of debt service (i.e., interest plus amortisation). This compares to the c.£60,000/MW achieved by Modo Energy's 2-hour BESS index over the last twelve months. In turn, this presents an unclear path to deleveraging using excess cash flow, with asset sales the more realistic option at this stage.
High gearing: HEIT is likely need to draw additional debt to fund the Wormald Green (33MW) and Hawthorn Pit (49.9MW) projects, both of which are still under construction and are expected to become operational during calendar Q2 2024. As HEIT's outstanding debt was already 36% of NAV as at 31/10/23, further drawings on the £110m term loan and £20m RCF would entail higher gearing levels, against an investment policy limit of 49%, and especially if subject to a lower NAV driven by changes to the longer-term revenue assumptions. Moreover, it is unclear where any covenants are potentially struck on the debt.
Exhibit 3 - HEIT gearing (% of NAV)
Source: Jefferies
Despite also being wholly exposed to GB battery revenue, GRID has lower gearing at £110m, or c.13% of NAV. With larger operational capacity than HEIT, this results in debt service costs currently being covered - so not quite as bad as HEIT's predicament.
I avoid Green Energy shares the economics are brittle and over hyped. Climate lobby are doing untold damage to our energy security . The graph that is never shown , shows a huge decline in CO2 emmissions over the last 50 years for the UK. CO2 is not the problem we need more not less for the world to thrive
ITM Power (LON:ITM) H1 yesterday, a stock that has been a. Big disappointment to many (I’ve never held), but much evidence of a significant turnaround in the results with very positive forward looking statements re demand and market opportunity rationalised product set with strong market fit, sharply reduced cash burn, revenue now accelerating and a cash pile equivalent to 70% of market cap. Very strong trading volume yesterday. Could this be the start of a genuine turnaround? I’ve bought a few this morning.
ITM Power (LON:ITM) did a presentation on Investor Meet Company yesterday and a lot of detail on what the new management have achieved in the last 12 months and ongoing plans. I bought some in the new year re-shaping of my portfolio along with Corero Network Security (LON:CNS) so I'm glad to see my faith rewarded. Both a bit too speculative it would appear to get coverage from SCVR so definitely do your own research and you might find they suit your risk/reward criteria.
I brought some CNS, just looking at their customer base and links to Juniper. I was very impressed
Inline update from Venture Life (LON:VLG) this morning. The best feature is the reduction in debt which had increased due to aquisitions. A note from Cavendish https://www.cavendish.com/rese... points out that that revenue growth was delivered completely organically, a first since 2019. Free cash yield is estimated at 15.8%
Graham gave this an amber last July saying "I am cautious when it comes to my interpretation of the company’s EBITDA and cash flow claims" but perhaps the balance sheet is in better shape now.
The sp is up 8.8% at open.
Venture Life (LON:VLG)
Paul Hill talked with the CEO of VLG today. The last time he published one of these here he came under attack and so has not posted one since.
So..... I have not been paid to post this but I do hold VLG shares. Paul was probably paid by Vox for this and Vox may or may not have been paid by VLG.
Euan Sutherland walks into a new job.
Truly astonishing.
Euan Sutherland always reminded me of Uncle Colm from Derry Girls. Only much less charisma.
LOL. If you don't know:
Sails in, surely?
Euan Sutherland walks into a new job.
(At AG Barr , which Graham is writing up as we speak) - Yes Graham and I have been having a good laugh about this on our WhatsApp this morning! We reckon he must have particularly good soft skills, a nice suit, a gravelly voice, and a piercing stare. How else does he land these big jobs?! It's certainly not on a successful track record! Maybe he hypnotises the interviewers without their knowledge?
Saga (LON:SAGA)
Euan Sutherland
I always wander with large organisations whether it is more the group culture that is the issue rather than an individual staff member. So although i was spectacularly unimpressed with everything the saga board has done to update small shareholders i wander if these large companies are too ingrained in their culture for one individual to sort. Being frank - communication with investors trying to predict the future was probably bottom of his priority list with all the issues he will have had trying to do the basics right at saga. Looking at superdry after he left and Dinkerton came back to save the day i dont thinks ghot any better - although thats comparing p poor v p poor imho - i got the feeling processes at superdry wehere shambolic during his tenure and also after. Can't believe i am trying to semi defend the guy here there ya go.
I do notice huge difference between quality of info from companies with hands on the pulse and let us know how it is straight talkign no waffle quality info - compared to the waffle brigade.
What we really need is the no waffle screen on stocky - that solely judges companies by ticklist of clear talking accurate data. perhaps marks out of 10 on 5 or 6 most important bits of investor communciation.
Some companies that spring to mind are Next , Redde , H Boot and SThree Norcros. Must admit i am trying to morph my investment choices into companies that are close to s hot in this regard (thats a low bar withn listed comopanies) and away from the waffle brigade compamies like saga portmerion blah. My logic here is if you are doing well and on the ball its easy to communicate. If you are not doing so well or not on thenball and need to semi bluff that fact you probably try to go into waffle mode - thats over simplistic really as decent well run companies still tell it straight when time are tough / poor - so not all well run companies will be delivering well at all times.
Add Ramsdens Holdings (LON:RFX) and Ultimate Products (LON:ULTP) to the list of plain speakers. Both nooorthern of course
Where has he shown up? I need to sell immediately! ;)
A G Barr (LON:BAG) - I think Grahams reference to the CRI stepping down was a tongue in cheek reference.
It is staggering really. This one is off my potential investing list for sure
My morning smallcap tweet: Fool steam ahead
Live (LON:LVCG) Advanced Oncotherapy (LON:AVO) Thruvision (LON:THRU) Wilmington (LON:WIL) SEEEN (LON:SEEN) Gresham House Energy Storage Fund (LON:GRID) Made Tech (LON:MTEC) Vanquis Banking (LON:VANQ) Arecor Therapeutics (LON:AREC) Warpaint London (LON:W7L) Fusion Antibodies (LON:FAB) Anexo (LON:ANX), Tandem (LON:TND), B90 Holdings (LON:B90), LSL Property Services (LON:LSL), Venture Life (LON:VLG), Ricardo (LON:RCDO), Various Eateries (LON:VARE)
◄Live Company (LVCG)► not dead yet. It "remains hopeful of completing all matters by the end of the week to enable re-trading of its shares on AIM." and avoid cancellation. [SP=2.08 Cap=5m]
◄Advanced Oncotherapy (AVO)► not dead yet. However the hoped for investor fails to cough up initial tranche of funding. Expects this (c.$15) in Feb, Also talks on a short-term loan. [SP=1.75 Cap=9m]
◄Thruvision (THRU)► has launched the LPC71 Series "focused on meeting the specific needs of the Retail Distribution market" ie checking staff aren't nicking stuff. Has new "future-proofed image processing software". Ooh. [SP=20 Cap=32m]
◄Wilmington (WIL)► sells MiExact for £6.6m cash and £3m loan notes with a 7% coupon, deferred for up to three years. [SP=326 Cap=292m]
◄SEEEN (SEEN)► FY-Dec update. Scroll a long way past the positives to find the dismal rev fig of $2.1m ($3.3m). Blames shift from lower value CSP business towards higher value media technology business. Gross margin over 20% (15.2%). Claims it can achieve cash flow breakeven with its current cash resources. [SP=5 Cap=5m]
◄Gresham House Energy Storage Fund (GRID)► goes bang. FY trading - "continues to be impacted by the weak revenue environment". Skips Q4 div. Intends share buyback. Will defer its investment in Project Iliad. Already down 64% in a year. [SP=58 Cap=333m]
◄Made Tech (MTEC)► guides H1-Nov rev down 7% but adj EBITDA in line at c.£1.4m due to increase in billable utilisation, a reduction of contractor numbers and targeted restructuring initiatives. [SP=13 Cap=19m]
◄Vanquis Banking (VANQ)► guides FY23 broadly in line with adj pretax now expected to be £25m. [SP=118.2 Cap=293m]
◄Arecor Therapeutics (AREC)► guides FY-Dec total income £5.6m (£3.5m) inc grants. Rev £4.6m (£2.4m). Cash and cash equivalents £6.8m, ahead of market expectations [SP=166.72 Cap=51m]
◄Warpaint London (W7L)► renews Ward & Hagon Management Consulting contract. [SP=380 Cap=294m]
◄Fusion Antibodies (FAB)► recieves £280k tax credit. [SP=4.5 Cap=3m]
◄Anexo (ANX)► guides FY-Dec trading in line with management forecasts but pretax only broadly in line with market expectations. Huh? Update on diesel emissions cases. [SP=69.66 Cap=82m]
In line: TND, B90, LSL, VLG, RCDO, VARE
New AIM #IPO today Microsalt #SALT, part of TekCapital's portfolio #TEK. Nice to see a new company listed at last.
Let's hope the performance is sweeter than other recent IPOs.
Another good update from 3i, effectively a quoted private equity group, a way in to sharing in the success of Action, now with about 3,000 outlets in Continental Europe. The only exposure I have to retail. For me, as a kind of byproduct,also exposure in the hands of good management to the growth of quite a few smaller businesses.
I shop in Action a lot here in Amsterdam. It’s always packed. The Dutch love it.