Small Cap Value Report (Thu 1 July 2021) - RBG, HEAD, SPR, AGFX, COG, ALT, LOOK

Good morning, it's Paul & Jack here with the SCVR for Thursday. Good job I checked the date, as this originally said Friday!
Timing - today's report is now finished (14:45)
Disclaimer -
A friendly reminder that we don’t recommend any stocks. We aim to cover notable trading updates & results of the day and offer our opinions on them as possible candidates for further research if they pique your interest. We tend to stick to companies that have news out on the day, and market caps up to about £700m. We avoid the smallest, blue sky type companies, and a few specialist sectors (e.g. resources, pharma/biotech).
A central assumption is that readers then DYOR (do your own research) and discuss in the comments below. The comments, incidentally, sometimes add just as much value as the articles. We welcome all rational views, whether bull or bear!
It's helpful if you include the company name or ticker within reader comments, otherwise some readers may not be aware of what company you are commenting on.
Agenda -
Paul's Section:
Revolution Bars (LON:RBG) (I hold) - a strong trading update. Since re-opening indoors, 86% of 2019 revenues achieved, on only 28% capacity. Guidance raised, and net debt largely eliminated by recent 20p placing. Good upside here in my view, providing covid restrictions don't return.
Headlam (LON:HEAD) (I hold) - is holding a CMD today at its Ipswich HQ. Slides are available online here. I think broker forecasts look far too low, and I see long-term upside of c.70% on the current share price. Obviously don't rely on my view, as it could turn out to be right or wrong, nobody knows for certain what the future holds. A resumption of divis in future could lock in a yield of over 5%, if historic payouts return.
Cambridge Cognition Holdings (LON:COG) (I hold) - interesting news of the spin-out of startup (Monument Therapeutics) which COG has incubated since 2018. Creates about £1.5m value for COG shareholders, who now have a free carry in Monument, with further upside potential from licensing. A cherry on top of the cake!
Lookers (LON:LOOK) - accounts for 2020 are finally published. Positive trading, but we already knew that from the strong trading update on Monday this week. The whole sector is cheap, so why chose one that doesn't seem to have proper control over its financial reporting?
Altitude (LON:ALT) - an in line with expectations trading update for FY 03/2021, and Q1 of the new year. Some encouraging signs here, but I'm not convinced it has a good business model, time will tell.
Jack's Section:
Springfield Properties (LON:SPR) - strong end to the year with record revenues for this Scottish housebuilder with a diverse skillset and good local connections. Net debt has fallen considerably and the outlook appears positive, so it looks well placed to continue growing.
Argentex (LON:AGFX) - looks like the post-pandemic recovery is shaping up at this FX services provider. The group is investing for growth and forecasts suggest a company with ambition, albeit one whose business is tied to market confidence and sentiment.
Paul’s Section
Revolution Bars (LON:RBG)
(I hold)
21p (yesterday’s close) - mkt cap £49m
Revolution Bars Group plc ("the Group" or "the Company"), a leading operator of 66 premium bars, trading under the Revolution and Revolucion de Cuba brands is pleased to announce an update to trading ahead of our year end date of 3 July 2021.
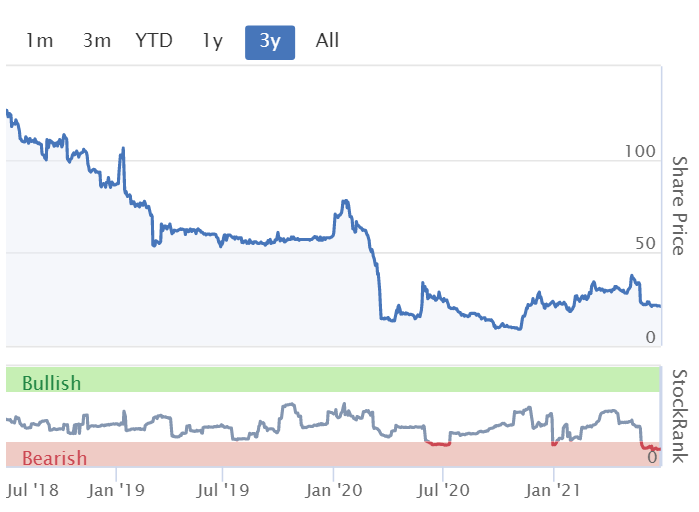
Preamble - The last update was on 11 May, and described re-opening trading as “extremely strong”. That pushed up the share price to nearly 40p, drawing in buyers, who just 2 weeks later were slammed with news of a deeply discounted (20p) placing & small open offer. Hence some disgruntled shareholders exist. Still, everyone who wants to has been able to buy in the market at 21-22p, so there’s not really any reason to remain angry.
Discounted placings are only a problem if you don’t stand your corner, by averaging down. I’ve loaded up at 20p in both fundraisings, and was/am happy to part-sell above 30p, thus locking in gains which more than offset the dilution on the previously held (smaller) position. Hence despite the share price having declined 90%, and the share count increasing from 50m to 230m, it’s still been possible to make money on this share, or at least limit the losses, by buying lots more at the lows.
This point is covered well in the book I’m currently reading, The Art of Execution, by Lee Freeman-Shor. He emphasises that when a share price goes down heavily, we need to take action either way - sell out, or buy more, depending on the situation. Sitting like a “rabbit” and doing nothing, is the worst option. I take on board the excellent point made by Mojomogoz here that a lot of the data in this book is suspect, unreliable even, because it covers too short a period of time, that includes the 2008 crash! Hence I’m largely ignoring the data given, but the narrative is still good.
Today’s update - since re-opening on 17 May, RBG has still been subject to severe restrictions - only 28% of total capacity has been available. That’s because RBG makes its money mainly from customers being packed in like sardines on Friday & Saturday late nights, mostly standing. That’s still not possible, with seated, table service only available currently.
Despite that, since 17 May, trading has been down 14% on the 2019 pre-pandemic comparator. Not bad at all. Consequently -
...revenue for the year therefore expected to be ahead of management's previous expectations.
Outlook -
Following the customer reaction we have seen over the last six weeks, the Board is confident that significant further pent up demand exists and therefore further strong trading is anticipated in the coming months as restrictions fall away and we fully open up the estate…
Words of caution are expressed about the coming year, due to covid uncertainty. As we’ve seen, RBG’s business model is particularly vulnerable to covid restrictions, because it’s almost an all-or-nothing type of business, which makes money on busy Fri & Sat nights (and student nights mid-week). If those can’t happen, then it has little revenue to cover fixed costs.
Guidance raised - an awful year has ended not quite as badly as feared -
Taking the above into account, together with ongoing excellent cost control and continued support from third parties, we now expect that our full year performance for the year ending 3 July 2021 will be ahead of previous management expectations with an EBITDA loss pre IFRS16 adjustments of c£12.5m
Net debt - drastically reduced, almost eliminated, thanks to the recent placing -
...net bank debt significantly improved to c£5m following this period of trading and after our recent equity raise.
That’s a lot lower than I was expecting. This means, with bank facilities available, RBG now has plenty of firepower to continue its refurbs, and pounce on good sites which become available. Expect a flurry of site acquisitions, I know management are ambitious & want to take advantage of current market conditions to secure decent new sites on attractive rents.
My opinion - it’s been a bumpy ride to say the least, but that doesn’t matter. Shares are valued on the outlook, not the past, an outlook which currently looks very good for RBG. I reckon it’s likely to see a bonanza of trading in the coming months, tempered by the risk of covid restrictions coming back in, in the autumn.
Hence if things go smoothly, there could be a 50% gain to be had here, in my view.
EDIT: A Finncap update note has just come through (available direct, or via Research Tree), many thanks for this. Although personally I’m not setting much store on broker forecasts at the moment, as generally they’re being far too cautious. Hence I find it more useful to refer back to pre-pandemic trading, and make my own adjustments to that, depending on the circumstances, which often wildly differs (positively) from current broker forecasts.
Finncap says the update today is a £2.2m profit upgrade on its forecast.
Finncap’s forecast for FY 06/2022 doesn’t look credible to me, with only c. breakeven forecast, so I’m ignoring that.
End of edit.
.
Headlam (LON:HEAD)
(I hold)
442p (up 1%, at 09:05) - mkt cap £378m
This is a floor coverings distributor, market leader with c.20% of the UK market, and smaller operations in Europe.
Capital Market Day - is being held today at its Ipswich headquarters - an actual physically present meeting! Remember them?! It’s also being recorded, for a webcast, details to follow. Here are the presentation slides, which I’ll have a look through now. Good grief, there are 80 pages! To summarise them, it looks as if there are many projects underway to make HEAD more efficient & to drive growth. I can’t help thinking that, with all these opportunities, maybe the company wasn’t very well-run in the past?!
Trading Update today -
YTD revenues for FY 12/2021 are now in line with the 2019 comparator. That’s an improvement from “slightly below” previously reported for Jan-Apr, therefore HEAD has had a positive performance in May & June.
Residential sector strong, commercial sector improving.
Supply issues, but inventories have been maintained at £117m
Diary date - 29 July 2021 for next trading update
My opinion - this is another share where the current analysts forecasts don’t make sense to me - they look far too low.
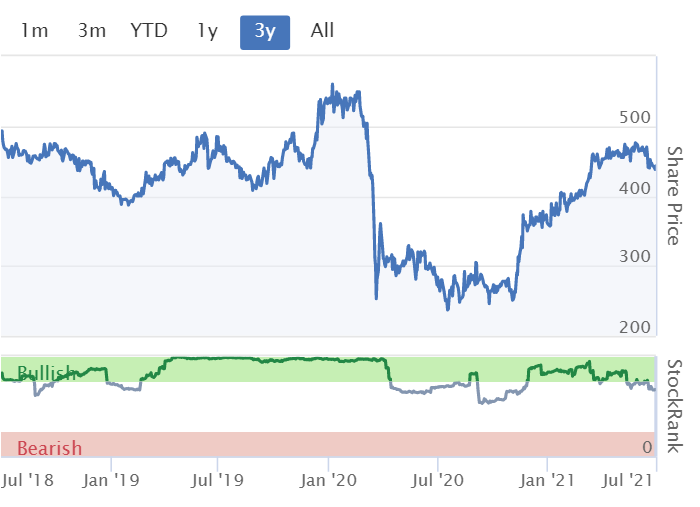
I can’t get hold of any broker notes, but Stockopedia shows consensus forecast of 26.0p FY 12/2021, and 30.4p FY 12/2022. Those numbers don’t make sense to me. Pre-pandemic, HEAD achieved c.40p EPS, and there has been no dilution since (very strong balance sheet, including tons of freeholds). Costs have been stripped out, and a push for greater sales is underway, plus numerous efficiency gains in the pipeline.
Therefore, I think c.50p EPS is a logical forecast to value the company on. Given its strong balance sheet, I think a PER of 15 is justified. That gives me a price target of 750p, which is +70% upside potential on the current share price.
Hence I am happy to hold for the foreseeable future, and should probably increase my position size actually. With so many shares looking toppy, it’s pleasing to find something that is still modestly priced. Once again, the opportunity is provided by working out that analysts forecasts are too low, and not even logical in some cases. You have to do this work manually, so I think this is a good example of where putting in the donkey work creates the opportunities to make money. That’s assuming my figures are right of course, which they might not be! It’s all educated guesswork, as none of us know for sure what the future holds.
Note that the Stockopedia quality rankings are skewed by losses in 2020. So operating profit, ROCE and ROE are actually much better than they look, now the company is profitable again in 2021.
.
.
Cambridge Cognition Holdings (LON:COG)
(I hold)
177p (up 6%, at 12:40) - mkt cap £55m
Spin-out of Monument Therapeutics
Cambridge Cognition Holdings Plc (AIM: COG), which develops and markets digital solutions to assess brain health, is pleased to announce the completion of the spin-out of Monument Therapeutics Limited ("Monument Therapeutics"), a drug development company applying digital phenotyping to central nervous system ("CNS") disorders.
What an interesting announcement. I’ve never heard of Monument Therapeutics, but it seems to have been a startup in 2018, buried within COG, which is now being spun-out - i.e. becoming a standalone company. Often spin-outs involve floating the separating company with its own stock market listing, but that doesn’t seem to be the case here. Maybe eventually it could be floated, who knows?
Medical details of what Monument does are included in the RNS, but I don’t really understand it.
The financial details I do understand, as follows -
- Monument has raised £2.6m funding from a consortium of investors for 63.1% of Monument
- COG retains a 36.9% shareholding (valued at £1.52m using the same price as the outside investment)
- Licence payments from Monument to COG for use of its software
- Unspecified royalties will be payable to COG on successful commercialisation of new products
- COG’s Chief Scientific Officer will step down to working part-time for COG, and become part-time CEO of Monument
- Royalties could become “considerable … in the future”
My opinion - £1.5m value for COG shareholders has appeared from nowhere, which is 4.8p per share. Plus potential upside on the investment, which is being funded by third parties, with COG having a free carry. What’s not to like?!
The newsflow from COG has been wonderful, and it’s now 9-bagged from the pandemic lows in March 2020. I’m happy to run with it, so am personally not looking to bank any profits. The big money is made from longer term multibaggers, so why cut the winners?
That obviously means being relaxed about pullbacks along the way - things can’t rise in a straight line forever.
The other consideration, is that this share is illiquid, so it can be annoyingly difficult to acquire shares. It took me 15 buy transactions over 7 months to accumulate the position size I wanted. For that reason, I don’t think it’s wise to trade in & out, trying to time the market - i.e. if I top slice, then I might not be able to buy them back.
Here’s the all-time chart since COG floated in April 2013. As you can see below, it’s hitting previous highs. I think that’s justified, since the fundamentals are now better than at any point in the past - in particular with a much stronger order book, 2021 forecasts are already in the bag. Hence I’m hoping it might be able to win more contracts and see further upgrades in future. Nothing is guaranteed of course, so there is risk.
.

.
Lookers (LON:LOOK)
71p (unchanged at 13:57) - mkt cap £276m
The saga of its delayed 2020 accounts is finally resolved, they’ve been published. I think it’s correct to say that the shares would have been suspended today if these hadn’t been filed. As we reported here at the time, on Monday 28 June, Lookers announced a further delay, but that it was still hoping to get the accounts filed by the 30 June deadline. First thing this morning is near enough.
Current trading is confirmed as strong, but we knew that already from the positive trading update 4 days ago, hence why the share price hasn’t moved today.
There’s no change from my view here on 28 June - car dealers are all cheap, and trading well, so why buy one that’s had accounting problems? I prefer Vertu Motors (LON:VTU) (I hold) personally. Although LOOK also has a big freehold property portfolio, as do some others. This is a nice sector for value investors, especially as divis should be resuming.
.
Altitude (LON:ALT)
41p (up 9%, at 12:30) - mkt cap £29m
Altitude Group Plc (AIM: ALT), the operator of a leading marketplace for the global promotional products industry, is pleased to provide the following trading update for the first quarter of the current financial year (April, May and June 2021) ("Q1 2021").
Q1 is trading in line with expectations. “June order value exceeding both 2019 and 2020 levels” - not clear if that means order intake, or total order book?
FY 3/2021 - “trading remained robust”, with revenues not less than £7.4m, gross profit of £5.2m. Actual profit (i.e. profit before tax) is not stated (so it's probably a loss)! At the end of the update it says -
The Group expects to report a profitable adjusted EBITDA for the financial year ended 31 March 2021 in line with Board expectations.
Cash - “robust” at £1.4m on 30 June 2021. That seems to be down from £2.1m reported at end March 2021. I wouldn’t describe it as robust at all, I’d say it’s looking a bit precarious, and an equity fundraising could be needed. Not that this would necessarily be a problem - a small top up placing of say £2-3m would only be about 10% dilution, nothing much to worry about.
My opinion - neutral. This company does look potentially interesting, but it’s not delivered on the hype so far. Although to be fair, the pandemic must have had a big, albeit temporary impact. I did have a little gamble on it earlier this year, and did well, but it would take more concrete good news for me to want to buy back in. After all, £29m is a fair whack for an as yet unproven business model.
At this stage then, I think it’s more a punt than an investment, but the story is quite interesting, so I could be tempted, if it is able to demonstrate real profitability emerging & strong growth. It’s not quite there yet, and I’m not convinced it’s necessarily going to get there. Time will tell.
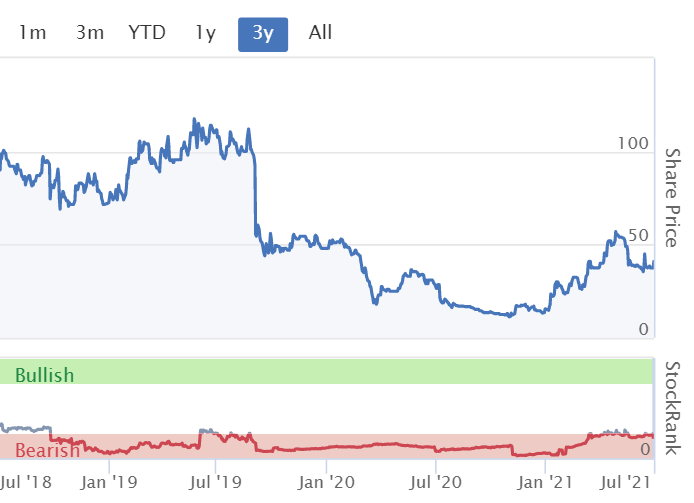
Looking at the 3-year chart below, it was in a nosedive well before covid struck - important to remember that. So this heavily hyped share failed to deliver before, which begs the question why would it succeed now? I'm only asking the question, don't shoot the messenger!
.
.
Jack’s section
Springfield Properties (LON:SPR)
Share price: 163.5p (pre-open)
Shares in issue: 102,105,821
Market cap: £166.9m
This is a housebuilder with developments across Scotland, where it operates under its Springfield, Dawn Homes, and Walker Group brands. It focuses on sourcing land for private housing in areas with high growth potential and progressing those developments through the planning process.
It also has a collaboration agreement with Sigma PRS Management Ltd to acquire and develop sites in Scotland with housing for the private rented sector.
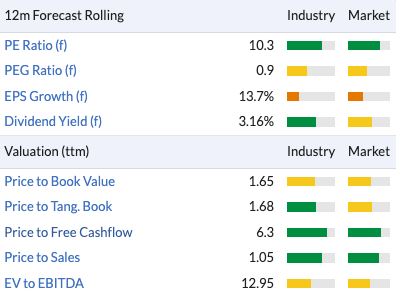
Housebuilders have been well ranked in recent years, and Springfield is no different with its Super Stock classification and SR of 92. The shares have recovered strongly from their Covid lows (of 65p or so), and yet the group trades at just 10.3x forecast earnings with a forecast PEG of 0.9.

Price to tangible book value of 1.65 sits in the middle of the pack against its peers, above Bellway’s 1.28 but comfortably less than Persimmon’s 2.85.
Highlights:
- FY revenue +49% to £215m (the group’s highest ever turnover)
- ‘Substantial increase [in] expected in profit before tax, in line with recently upgraded market expectations’
- Net debt reduced to approximately £21m, down by £50m.
The group says build and sales activity throughout the year was strong due to high demand across the business.
Private housing continues to be its largest contributor to revenues but ‘material’ strategic land sales to two national housebuilders have also helped.
As a result, the Group expects to report revenue for full year 2020/21 of approximately £215m and profit in line with recently upgraded market expectations, reflecting significant year-on-year growth. The Group also substantially reduced net debt to approximately £21m at 31 May 2021 compared with £71m at the same point of the prior year.
Springfield provides homes that are larger, with space for home offices and with gardens, which are in semi-rural locations. Demand has increased for this type of property over the past year.
In affordable housing, the group delivered a substantial increase in revenue and completions in H2 compared to H1, ‘representing significant growth for the full year over 2019/20’.
The Group also signed contracts for, and commenced work on, multiple new affordable developments that are due to be delivered in the current year. The Scottish Government is committed to the delivery of affordable housing, with over £3.4bn earmarked for funding through to March 2026.
Innes Smith, CEO of Springfield Properties, said:
A key driver of our growth has been the greater popularity of the spacious homes that we provide, with private gardens and easy access to surrounding greenspace, particularly at our Village developments. At the same time, there continues to be a chronic undersupply of housing of all tenures across Scotland. Thanks to the strength of our offer and of our partnerships, which will now include the delivery of homes for the Private Rented Sector, we are exceptionally well-positioned to help meet this housing demand and provide great places for people to live, building quality homes and creating sustainable communities.
Conclusion
This is Scotland’s only listed housebuilder as far as I can see, and it looks to be closing out an excellent year with significant growth in both its Private and Affordable Housing divisions. The landbank sales are a useful boost that take revenues to record levels. Meanwhile net debt has fallen by some £50m to £21m.
It looks like brokers have been too conservative in their adjustments to forecasts. These could get tweaked higher still by the sounds of it. Revenue of £215m is comfortably ahead of consensus expectations of £194m.

The company notes a ‘chronic undersupply’ of housing and appears to be well placed to meet this demand going forward with its focus on family and affordable housing. Springfield skillset also tends to buy land more cheaply off market and then focus on more complex, long-term projects that require multiple skills and a lot of expertise to see through to completion.
Its sweet spot is mid-sized ‘Village’ communities in rural settings but close to fast growing Scottish cities. Securing these sites requires close co-operation with local councils and other stakeholders.
These skills and relationships are signs that it might be hard for larger competitors to simply set up shop and start competing for share. That plus the undeniably strong trading at present suggest it’s likely worth a closer look, particularly if the group can selectively acquire in Scotland, which also looks to have been the case so far.
Argentex (LON:AGFX)
Share price: 123.5p (-1.59%)
Shares in issue: 113,207,547
Market cap: £139.8m
This is a ‘bespoke service-led FX solutions provider’, which helps clients sort out currency headaches by providing advice, hedging strategies, and related products. Clients include institutions, corporates and private clients across a range of industries.
Once a client has been assigned a dealer, it is their job to work with that client, on their terms, to identify and quantify any FX risks inherent in their business and present a range of strategies that will entail at least one of either spot, forward or options trade, that can mitigate those risks to enable informed decisions.
The growth rates here look promising, with a 39.6% 5y compound annual growth rate (CAGR) in revenue, double digit profit and cash flow CAGRs, and strong profitability metrics over time.

But the shares have had a rough ride since listing. There’s a fair amount of volatility in the share price chart, including some steep drops. Listing just before Covid was unfortunate.

Highlights:
- FX turnover +5% to £12.75bn; revenue down slightly from £28.9m to £28.1m,
- Underlying operating profit -30.4% to £8.7m,
- Basic earnings per share -26.8% to 5.2p; underlying EPS -33% to 5.9p,
- Final dividend held at 2p.
Argentex notes a pick up in client acquisition in H2 and ‘record H2 client activity’, with 499 new corporate clients traded during the year and volumes recovering to record levels in the second half.
The group has made 21 new hires including 12 new sales team members. Employees have been ‘safely transitioned’ back (should that be ‘dragged back’?) to the new headquarters in London following a period of remote working.
Growth initiatives include:
- The Amsterdam office, which is now in its first year of operation and generating revenue,
- Australian licence application - underway, with the intention of opening in Sydney in FY22,
- Investment in sales team and new CFO in February 2021 - a senior hire that the chairman hopes will ‘assist in unlocking the significant potential value available to Argentex shareholders’,
- New London headquarters provides substantial capacity for further growth
Harry Adams, Chief Executive Officer, states:
I am pleased that our first quarter of the current financial year has continued this trend and our revenues are approximately 34% per cent ahead of the same quarter last year. It's this momentum, combined with the exceptional talent within the business, that provides renewed confidence in our long-term strategy.
The group says that ‘a key differentiator from our peers continues to be our prudent and conservative approach to risk management’ - I’m curious to learn how those peers fared. Sometimes market disruption can prove to be a market share opportunity for more prudent operators.
Conclusion
It’s worth noting a wide gap between profits and net cash from operations in these results (£7.4m of PBT versus a £4.1m net cash outflow from operations). In previous years, cash generation has been good.
Like any trading business, Argentex wasn't immune to the dip in market confidence during H1, but it is bouncing and reports a 5% improvement in year on year turnover, driven by growing client demand and record levels of activity in the second half.
The nature of the group’s business means that some degree of cyclicality or volatility can be expected in future. The dip in market confidence around Covid did have a noticeable impact on client volumes through H1 and something similar can happen in future.
The underlying growth trend looks quite strong though. Per the chairman:
Confidence is everything in an economy and there is much to be optimistic about as we all approach "a new normal". The key markets in which Argentex operates are on the right path for a sustainable recovery and trading volumes are encouraging.
Nobody knows the future but in my view it’s likely that as businesses and societies reopen, there will be a catch-up period of growth and recovery. It could be a good environment for operators like Argentex.
With this kind of business, I often wonder how much of those profits in good years accrue to employees and how much to shareholders. Another miscellaneous point: co-founder Carl Jani resigned on the 11th June 2021. He looks to have been an instrumental figure. Perhaps that’s totally innocent.
All in all though, these results strike me as better than they might have been given the exceptional conditions, and the company seems to have its sights set on long term growth. Given that sentiment is lukewarm at the moment and the shares remain close to the IPO price from a couple of years ago despite strong growth forecasts, it could be a good time to do some digging.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

30 comments
I was rather surprised that the prelims of Finncap (LON:FCAP) were not picked up this
Quite a busy day I guess but I was surprised that neither the chiefs nor even Mr Contrarian picked up the prelims of Finncap (LON:FCAP) this morning. I guess that the results were largely predicted, but I thought that the reduction in SP was surprising. If you can find time tomorrow, I would be grateful for a comment from the team. After all, Finncap (LON:FCAP) is often quoted for its free and prompt research on this platform. I live in hope for tomorrow. Thank you.
After the close, Bidstack (LON:BIDS) has announced a £10m placing at 2p (c33% discount) - leading to a more than doubling of shares in issue, with no rights for existing private shareholders to participate. (no Primary Bid raise, no Open Offer etc).
Re. Bidstack (LON:BIDS), it’s ”another kick in the b***s” for the PI as Pink Floyd once nearly sang.
On the principle that even if it doesn’t repeat it at least usually rhymes, history suggests the shares will open down 30% or so tomorrow, slightly above the 2p offer price giving those not in the placing the chance to buy in the market and avoid the heavy dilution. If you still buy into the story top up as the placees sell down to their preferred holding position. If not cut your losses and sell. This seems to be the modern/cheap way of achieving an underwritten rights issue nowadays. No position.
Gus.
Scs (LON:SCS) (I Hold)
Has anyone else seen the 'surprise but welcome trading update' issued by Shore Capital on Research Tree today?
Some excellent figures.....
From 4th April '21 to 12th June '21 order intake up 371% and (more impressively) up 79% on same period FY 2019.
Declaration of delayed interim dividend of 3p per share
Forecast Net Y/E cash of £74.5m against a market cap of c £110m
FY21 & FY22 forecasts substantially upgraded
Despite this sp has fallen today....?
Hi Norfolk'n'Good, re Scs (LON:SCS) trading update...
I've misplaced my Research Tree login on my phone (how??!) but from the numbers it looks like the updates that are on the Scs (LON:SCS) website dated 16/18 June. The share price had gone up sharply before then, and I bought more on the news, but it has been edging down ever since. There's no predicting anything.
Hi Indie re Scs (LON:SCS) You are right - I hadn't thought to look there, we live and learn so thank you for replying!
Re Headlam (LON:HEAD) - just been through Capital Day presentation - refreshingly simple business model and strategy. I held already, loved what I saw and bought more today on the back of it. My notes
* Already market leader from loads of small acquistions, goodwill always fully written off (20% mkt hare, x6 vs nearest competitor, UK focus)
* Grow sales (esp from Multiples currently <10% share, added value trade counters)
* Cut costs (stop transport duplication, digitising procurement, better links for customer - really liked the news had used customer focus groups to update website)
* Grow margin via mix (O/L products, trade counter items, NPD, direct to final customer and indie trade social media done in house for cost and control)
* People (v important - new tier 2 leadership team with specific skills highhlighted, new sales leader has cut 60+ positions but given sales more latitude to hit bigger targets)
Personally I think they can do £725Mn Sales by 2023 and they (credibly IMHO) state a target a 7.5% Op Margin - so £54Mn Op Profit (vs +/- £40Mn 2016-19).
So 35% ahead of when they traded at a range of 440-640p - my target is 600-860p with an extremely good chance of a 5% dividend by next year (strategy to pay out 50% profit)
With WFH an ongoing trend, consumer savings from missed overseas holidays and re-opening of F&B/commercial sites, I can't see carpets/flooring having a bad go in next 24months unless the whole economy is tanks again. So also relatively low risk I feel.
I hold - and now my 2nd largest position
With Headlam (LON:HEAD) I think the big imponderable is to what extent they have already benefitted from the housing market mania that is now inevitably going to slow as the stamp duty holiday is phased out?
I suspect that the residential market is at its peak right now and that it will start to decline in about two months time as the number of housing transactions diminishes. The boost from the WFH trend has already peaked too I would think.
Can commercial pick up the slack? I don’t see a reason for that. So, I think profit acceleration has to come from operational efficiency rather than revenue growth. I’m sure that they have opportunities to become more efficient but their input costs are likely to be increasing like they are for everyone else eroding potential efficiency gains.
(No current position having sold out some time ago as market sentiment did not seem very favourable for this stock).
Fair pushback on Headlam (LON:HEAD) but my view is revenue should at least return to 2019 levels by 2022 (esp now they confirm this is already being achieved in mid 2021)and should probably go ahead from i) more sales to big multiples and ii) taking share from smaller regional players weakened by COVID closures or impacted more than Headlam by cost/availabity squeeze.
To me this is like how DFS steadily grew mkt share and value through recessions - except without the PE induced goodwill/debt overhang.). I think the WFH thing on carpets is much slower burn than say 'office chairs'. You can make do for 12months with a dodgy carpet but eventually if you are going tospend more time at home long term , you want to do the 'office' up or at least you will wear the carpet out faster. Only if carpets go out of fashion will their absolute sales decline and to an extent they have mitigated this by diversifying (a bit) into other floor coverings
I thought the other big risk was a disruptor finding a way to go big online at scale as their systems and 'local company' approach would have made this approach possible so I was very re-assured when I saw them recognise this in the Capital Day presentation to the extent of taking it in house.
They have grown historically through loads of small, cheap acquisitions to fill in geographic gaps (until recently when they felt they had become national). With their balance sheet strength, I would not be surprised to see them now make a substantial regional acquisition to buy market share and better access adjacent markets. Domus was a mis-timed (London, big project focus) but strategically sound attempt to do this.
The efficiency gains look straightforward and credible and come from a scale based 'moat' that other direct competitors dont have, given their claim to be x6 bigger. That has got to help short term with stock availability and priority in containers.
Finally, there must be a chance that PE look to make a bid directly as per DFS although I think the moment for that has probably passed.
Net, especially with dividends resuming at a decent level this is sleep easy share for me with good upside possible over next 18-24 months.
Thanks Zipmanpeter, for taking the time & trouble to post that - very useful.
I've been a somewhat lone voice on Headlam (LON:HEAD) for some time now, so it's great to have another investor crunch the numbers and come to a similar conclusion & price target as me.
I see it's up 7% now, so maybe the brokers visiting Ipswich today have been texting buy orders in to their offices!
As you say, it does sound like they're starting to properly integrate all those separate businesses they acquired. Some of the existing practices do look surprisingly primitive, even sloppy. Hence there should be low hanging fruit in terms of improving profitability here.
All in all, the shares still look cheap to me. And I love the c.£100m freehold property assets too.
Regards, Paul.
For the very patient and those interested in a potential special situation, there appears to be fresh management change over at Dolphin Capital Investors (LON:DCI) . DCI is not to be confused with the Dolphin Trust - a well known fraud.
The discount to NAV exceeds 70% (getting your attention?) but is slowly degrading (oh...). There are some new shareholders on the register in the last 15 months, one of whom (Peter Gyllenhammar) features in the excellent Free Capital book by Guy Thomas (hmm..).
A real DYOR if ever there was one, and patience required. SP seemed to troughed in April 2020 at 2.1p, after which it has been steadily ticking up. There's still a significant margin of safety here at 4.5p.
Here are my SCVR heat maps for today (prices as at ~9:15am).
I share these heatmaps with the intention of giving a visual indication of what is going on in the SCVR world: who’s reporting (and it's impact on the share price); and what’s moving more than 'normal'. There are no associated recommendations, implied or otherwise, just information. How, or indeed if, you choose to use that information is up to you. Please feel free to ignore them if you don't find them useful.
Please read my heat map thread for a great deal of explanation of how the heat maps are formed and how I use them to guide me with my research, and for a full key to the contents.
I very much welcome feedback so if you do have any feedback, not already covered in the heat map thread, it would be very helpful if you could post your comment in the heat map thread rather than the SCVR thread. The more specific and constructive the feed back is, the more that likely it is that I will be able to act upon it. Thank you all for the feedback so far.
Small / Micro Caps reporting today:
Big movers today in the SCVR world (moving more than a 20d EMA of the ATR against either yesterdays close, or today's open):
Warm regards, stay safe, and best of luck!
greensiax
The Art of Execution is a great book.
The sample size could be bigger, but I think it offers plenty of takeaways for private investors.
I've summarised the book here:
https://twitter.com/shiftingsh...
An intriguing situation at private equity investor Cip Merchant Capital (LON:CIP) - this morning. Corporation Financière Européenne S.A has increased their holding from 18.2% to 25.4%. CFE had their bid at 50p in September 2020 rejected and then made another offer in January 2021 wanting 50p still. They have evidently decided not to give up. The company trades at 60p this morning which is well below its NAV per share of 89.6p - Cip Merchant Capital (LON:CIP) invests in mostly publicly listed companies.
I am not experienced enough to know what might happen here. Looking back at the previous announcement CFE were restricted from making another bid for six months which I assume is from the date of the bid, so maybe they can have a go again at the end of July?
CFE previously indicated they planned to take Cip Merchant Capital (LON:CIP) private. In the situation the company gets taken private on the cheap would I automatically get bought out or would I find myself somehow owning private shares. Anyone know?
The upside here is whether CFE decide to try and buy out the rest of the shares at a more expensive price. My buy price was 56p.
Good results from Polar Capital Holdings (LON:POLR) this morning which looks like a beat against Stocko's market expectations to me. Given average assets under management were £16.7bn during FY21 which achieved 62.2p adjusted diluted EPS, and we're currently at £22.7bn then maybe we could be looking at 70p (conservative) to 80p (optimistic) EPS for FY22??
So potentially this is trading on a current year p/e of 11, with c.5% dividend yield, and about 15% of the market cap in cash. Plus this is quite an acquisitive group so potential for further upside from spending that cash wisely. That looks good value to me?
The main downside risk here is it is heavily focused on the US, and also the technology sector (about 50% of assets under management) so if sentiment turns sour on US tech then this could be heavily affected. So it'll probably never be on a high rating but current value looks very reasonable to me?
Just worth highlighting that they received a lot of performance fees in an exceptional year for tech (around half their AUM). I would imagine this would be something of a one-off. Not sure how much this contributed to the 62p eps, but does need to be factored in.
£POLR "Adjusted diluted core EPS" was 40.6p. This excludes performance fees.
I think that's a fair point to draw attention to. Also there's c.£7m of additional 'other income' compared to last year which seems to be from the realisation of some of their seed interests. This looks like it represents about half of the extra non-core profit (I don't know if this caused other costs though). However, their seed investments are worth about 33% more than they were in 2020 which bodes well for future years' profits maybe?
Performance fees are clearly difficult to predict so that probably does need to be factored into the valuation. Thanks for underlining that point.
With markets having traded well so far this year I would have thought we'll see a decent increase in core profits coupled with some level of performance related and other profit.
Maybe when I have more time I'll go back and work out what their average performance related profit tends to be perhaps as a percentage of core profit.
Angle (LON:AGL) Listened in to the AGM and Q&A session yesterday. Some salient points IMO were :
1. Funding is currently sufficient to last until Q1 2023 but additional streams will be generated by the new labs
2. Contacts have been made with ctDNA users with a view to offering Parsortix to enhance their services.
3. FDA approval is required to sell the Parsortix system but not for its use in clinical accredited labs.
4. Asked about branching into prostate cancer AN mentioned they had been approached by a group of urology clinics in the US with a view to a collaboration. Some points made were
- the current PSA test can give significant false results ; many men test positive but do not have prostate cancer
- many men die with prostate cancer and not because of it. If it’s not aggressive it may not need treatment and access to CTCs could determine what action is required
- re the last point he suggested up to 60% of prostate removals (with associated serious side effects) could be avoided.
- the value of the prostate cancer market in the US is over $5bn pa
The session was being recorded so should be available shortly on the Angle (LON:AGL) or Meet the Investors sites.
Hello Jim. Re Angle (LON:AGL) comments, thank you for that. I look forward to picking them up.
Argos Resources (LON:ARG) are one of a number of payments firms, all of which seem to have a good return of business in the second half. Its clear that there is a significant growth opportunity in this market and Argentex seem to fly a little under the radar but have excellent management, a good strategy and provided a solid update today. Thoughts appreciated.
Sorry wrong ticker! :( It should be £AGFX. As I said, are one of a number of payments firms, all of which seem to have a good return of business in the second half. Its clear that there is a significant growth opportunity in this market and Argentex seem to fly a little under the radar but have excellent management, a good strategy and provided a solid update today. Thoughts appreciated.
Presumably these are the auditor signed off year end figures for Lookers (LON:LOOK) that were announced as being delayed.
https://www.investegate.co.uk/...
Not sure it’s explicitly stated anywhere that they are (there’s a lot to read!) but it looks like they just about made the deadline. Figures/commentary is pretty up beat as per rest of the sector.
Gus.
results a bit off what I was hoping for but the narrative and outlook seems okay from Argentex (LON:AGFX) I'm on the fence.
Good results from Polar Capital Holdings (LON:POLR) Only problem is its obviously closely correlated to market performance
I'm a big fan of Polar, although they are correlated to market performance of course, they are also winning plenty of new clients as well.
My morning smallcap tweet: Biome bio-degrades expectations
Headlam (LON:HEAD) Biome Technologies (LON:BIOM) Atlas Mara (LON:ATMA) Xeros Technology (LON:XSG) Petards (LON:PEG) Sareum Holdings (LON:SAR) Genedrive (LON:GDR) Revolution Bars (LON:RBG) Zoetic International (LON:ZOE) AO World (LON:AO.) Cambridge Cognition Holdings (LON:COG) Gresham House Energy Storage Fund (LON:GRID), Altitude (LON:ALT)
Headlam (HEAD) YTD rev in line with 2019 having been slightly below for the four months to 30 April. [SP=438 Cap=373m]
Biome Technologies (BIOM) warns FY21 & 22 rev materially below market expectations. The customer for compostable coffee-pod filtration material has a problem in its factory which will cause months delay entering production. Will have a significant impact on growth in the nearer term. Also shipping delays "are now proving a significant constraint on the division's ability to quickly undertake the multiple development iterations that are required to support growth with new customers." RF div trading OK. [SP=473.1 Cap=18m]
ATLAS Mara (ATMA) trading halted due to failure to publish FY accounts. Blames ongoing strategic review and engagement with the creditors. [SP=0.43 Cap=64m]
Xeros Technology (XSG) co-operation agreement with Hanning Elektro-Werke to test and market XFiltra to domestic washing machine manufacturers. Hanning is a leading manufacturer of component parts for major industries. [SP=231.2 Cap=55m]
Petards (PEG) £0.5m contract to supply ProVida systems to a new overseas customer. Delivery H2 2021. [SP=12.11 Cap=7m]
Sareum (SAR) top-line results from SDC-1801 covid treatment project confirm initial encouraging results reported. [SP=5.75 Cap=192m]
Genedrive (GDR) good progress with rapid covid test. "In contrast to many competitor products, the test targets two genes of the SARS-CoV-2 genome, and is shown to be inclusive of all current Variants of Concern." [SP=56.75 Cap=36m]
Revolution Bars (RBG) guides FY(July) ahead of mgmt expectations with EBITDA loss (pre IFRS16 adjustments) c.£12.5m. Rev since indoor re-opening down 14% from 2019. Co "confident that significant further pent up demand exists and therefore further strong trading is anticipated" [SP=21.25 Cap=49m]. I hold.
Zoetic (ZOE) $0.72m order from US distributor. Chill website UK launch. [SP=52 Cap=110m]. I'm short.
AO World (AO.) FY(Mar) rev up 62% in line. EPS 3.73p (0.21p). Outlook - "We have started the new financial year well and remain prudently optimistic that we will be able to deliver double digit growth as we lap the strong Covid performance comparatives." [SP=253 Cap=1213m]
Cambridge Cognition (COG) Spin-out of 63% of Monument Therapeutics which gets £2.6m in funding from a consortium of investors. Monument is a drug development company applying digital phenotyping to central nervous system disorders. [SP=165 Cap=51m]
Gresham House Energy Storage Fund (GRID) £100m placing at 112p, a 7% discount, to finance projects. [SP=120.91 Cap=421m]
In line: Altitude (LON:ALT)
Morning Paul/Jack. Would appreciate your thoughts on the announcement this morning from Logistics Development (LON:LDG)
Morning Simmo1a,
I've had a quick look. Logistics Development (LON:LDG) seems to have been an investment company, with one big holding, which is has just sold for net cash proceeds of £127m.
That compares favourably with the mkt cap of about £83m. I can't see any other liabilities on LDG's balance sheet.
I think it would now be a cash shell, with c.£127m in the bank, looking for a home. Hence if the mkt cap stays significantly below that, then it could be a bargain - but we don't know what management will do with the cash pile. If they mess it up, with a bad acquisition, then that could destroy value.
My other question is what are the tax consequences of the disposal, would any tax be payable? That's key to the valuation.
Overall though, this certainly looks an interesting special situation for further research by readers. My initial glance at it suggests there could be an opportunity here for the share price to rise closer to the cash figure. It's almost like a SPAC now, but at a discount to cash.
Thanks for flagging it.
Regards, Paul.
Interesting spin-out development at Cambridge Cognition Holdings (LON:COG) :
"Cambridge Cognition has been incubating Monument Therapeutics since 2018, with early-stage research supported by two Innovate UK grants. Monument Therapeutics applies a novel drug development strategy, leveraging digital assessments of cognition to match patients with new pharmaceutical treatments. Monument Therapeutics has a pipeline of promising drug development programmes, with the most advanced two being for cognitive impairment in schizophrenia and for post-operative cognitive dysfunction ("POCD").
To develop these programmes as an independent company, Monument Therapeutics has secured £2.6 million in funding from a consortium of investors led by Catapult Ventures and Neo Kuma Ventures. Cambridge Cognition has retained a 36.9% shareholding in Monument Therapeutics and has agreed a license for the use of a number of its gold-standard cognitive assessments, including CANTABTM, for patient stratification. Furthermore, upon successful commercialisation of its drug development programmes, Monument Therapeutics will pay royalties to Cambridge Cognition."
https://www.investegate.co.uk/...