Small Cap Value Report (Thu 1 Oct 2020) - BOO, PMP, RWI,HFD, TFW, CNCT, CTO

Good morning, it's Paul here with the SCVR for Thursday.
Please see yesterday's full report, which I carried on updating until nearly 6pm, with new sections.
Timings - I should be done by 1pm today.
Change of plan, I've popped into the De Beauvoir Arms (N1), my new local when I'm in London, so will type up some more notes over lunch here. Revised finish time c.3pm.
Agenda -
Renewi (LON:RWI) - trading update
Halfords (LON:HFD) - trading update
Fw Thorpe (LON:TFW) - final results
Connect (LON:CNCT) - trading update
Tclarke (LON:CTO) - trading update & interim dividend confirmation
All looks fairly dull, so I'm also going to do a bit more on Boohoo (LON:BOO) first.
.
Boohoo (LON:BOO)
372p - mkt cap £4.55bn
(I hold)
In case you missed it, the recording of yesterday's webinar is here.
I find that it's useful to take photos on my phone, of the most interesting slides, and to make paper notes of the key points in webinars, because sometimes the links to webinars don't last very long - they can be taken down for various reasons, including commercial sensitivity.
For me, the key points are that the supply chain issue is being taken very seriously indeed, and the action being taken is so comprehensive, that it's clearly not just a PR exercise. Mistakes were made, and they're dealing with it. That's fine, end of story. I see some journalists are desperately trying to string out the story today, but they're wasting their time (and ours).
There were numerous other insights into sourcing, margins, and how BOO is managing & expanding the newly acquired brands. All in all, essential viewing for all investors who want to profit from a unique growth business.
Are the shares expensive now? Clearly the share has recouped nearly all the losses from the shorting attacks & supply chain issues. However, it's earnings that matter, and the adjusted diluted EPS of 4.53p at the interim stage indicates to me that this full year FY 02/2021 could be heading for 9-10p EPS.
The house broker issued an update note yesterday, forecasting only 8.22p for FY 02/2021, which strikes me as far too low, since it implies a drop in EPS from 4.53p in H1, to 3.69p in H2. H2 earnings down 19% on H1. Really?! Why would that happen?
This is what actually happened in recent years (numbers are all adjusted diluted EPS);
FY 02/2020: H1: 2.91p, H2: 2.97p (2% rise from H1 to H2)
FY 02/2019: H1: 1.99p, H2: 2.16p (8.5% rise from H1 to H2)
As you can see, H2 earnings have tended to be up on H1, not down. Therefore it looks to me as if the 8.22p EPS forecast from Zeus is probably too low. It says as much in yesterday's note;
Management guidance for the full year reflects highly prudent assumptions on consumer spending, normalising return rates, ongoing distribution cost inflation and increased marketing spend.
H1 FY20A has already delivered 50.7% of our full year revenue forecast and 55.9% of our full year EBITDA assumption with H2 growth targets appearing undemanding.
We see clear upside risk to our numbers should the trading momentum seen YTD continue.
This backs up my view that 9p+ adj EPS for this year is probably more realistic.
Should we value the share on this year's earnings? Probably not, given that the stock market is supposed to look at least 6 months ahead, then we should be valuing BOO on FY 02/2022 figures. The house broker has pencilled in 11.37p there, which again is likely to be too low, because BOO normally exceeds forecasts. The Directors have a track record of under-promising, perhaps because they got caught out soon after listing, missing over-ambitious (short term) growth targets. Since then, they've been more prudent.
My view is that we can probably bump up the forecast for FY 02/2022 to at least 12p (I wouldn't be surprised if actual is nearer 15p, but lets leave some upside for another day). What sort of multiple should BOO trade on? Given the unique nature of the business model, and ongoing growth from bolting on more & more brands, then I think anything under 40 is missing the point. Here are some options;
PER 40: 480p per share
PER 50: 600p per share
PER 60: 720p per share
PER 70: 840p per share
In that context, I reckon the current share price of c.370p looks unrealistically cheap - a PER of 31
For that reason, I'm increasing my position size. Did I make a mistake in selling some between 306-320p recently (as discussed here)? Well obviously, yes, because the price is now higher. However, at the time, my decision was logical - I was worried that the supply chain review would be negative (which it was, but not catastrophically so), and I didn't know how the company was trading.
Now however, I am happy that the supply chain issue is dealt with, and we've just had bang up-to-date trading news, showing that the company is trading tremendously well. With this fresh information, combined with my assessment above that the share is looking undervalued, then I'm very happy to buy back my previous shares at c.370p.
As a reader commented, a legal action against the company in the USA is a potential thorn in the side, but it wasn't mentioned by anybody in the Q&A in yesterday's webinar, so clearly it's not bothered any of the analysts.
EDIT: I've made some enquiries about the US legal action, and can't print the actual reply, but translating it am told that it's not a problem at all. Would be good to get some independent confirmation of that though, which I don't have. End of edit.
Overall then, my current view on BOO is more bullish than before, and I reckon the shares look great value, for a unique growth business. Maybe investors are starting to realise how incredibly ambitious the team at BOO is. They see this being a huge, global business in the future. A few years ago they told me it could be a £5bn revenues business in the long term. Now they're talking £10bn, £20bn as possibilities. Hence why I'm inclined to keep buying, and to sit tight on them, almost irrespective of valuation. I've never looked at any share like that before, but this one justifies it, I reckon.
Also I'm hearing that the newish CEO (ex Primark) is very highly regarded, and seen as a very successful hire.
All in all, this is looking very exciting in my (long term) view. Obviously as always, please DYOR, as you should know by now that I do sometimes get a bit over-excited. I think the facts justify it with BOO though.
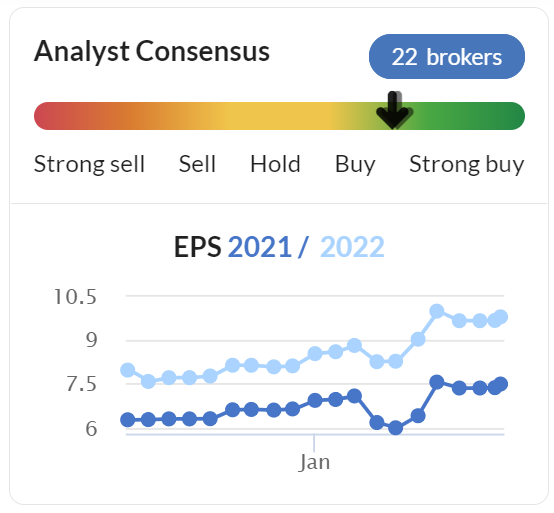
As mentioned above, the broker forecasts are clearly looking too low again. So more upgrades likely, which is the trend, as you can see below. Hence why the PER is actually a good bit lower than people think it is, because they're using overly pessimistic forecasts.
As an aside, wouldn't it be nice just occasionally, if short sellers would come forward and say, "Sorry, I got it wrong". They never do that, do they? Which undermines their credibility next time.
.
.
The consensus figures above are well below Zeus's upgraded forecasts yesterday, which are now 8.22p and 11.37p for the two years above. Hence expect this graph to show further progress upwards, as increased broker estimates start to feed through in the coming days/weeks.
.
Portmeirion (LON:PMP)
427p - mkt cap £59m
(I hold)
Your questions please!
I'm doing an audio interview with the new CEO of this pottery, candles & homewares group, tomorrow afternoon. It'll probably be shorter than my usual, in depth interviews, because a lot of it was covered here a few days ago, in a very informative interim results webinar on IMC. Therefore I'm not going to duplicate the same areas.
If you have any specific questions for the CEO, please leave them in the comments below. Please keep them brief, and to the point, and I'll do my best to include them in my interview. Thanks!
.
Connect (LON:CNCT)
22.1p (up 19%) - mkt cap £55m
This is a newspaper/magazine/other stuff distributor, called Smiths News. It disposed of the heavily lossmaking Tuffnells subsidiary a while back, which improved the future outlook, with that millstone gone.
The financial year is 31 Aug 2020.
Today it says -
Trading ahead of expectations
Trading in Smiths News over the last quarter of FY2020 has been stronger than management's revised expectations following the further easing of UK wide lockdown measures
Some specific figures are given;
In the fourth quarter ending 29 August 2020, trading EBITDA was £10m with strong cash generation. As a result, the Group expects to deliver Adjusted EBITDA (pre-IFRS16 lease adjustment) for FY2020 of £38.5m to £39.0m, above the top-end of the guidance previously announced in July 2020. The run rate performance in Adjusted EBITDA in the fourth quarter has continued in September trading, in line with the Board's expectations for the year.
That sounds great, so I checked my previous notes to compare. This is worth reading, my notes from 14 July 2020 trading update. The company said then, that adj EBITDA would be £35-37.5m. So today that range is increased by £1.5-3.5m. Useful, but not earth-shattering.
As my notes from July pointed out, the over-sized bank facility, due to be renewed before expiry on 31 Jan 2021, is the big issue here.
There was a "material uncertainty" in the interim results, emphasising how important this issue is.
Improved trading today should certainly help the company refinance.
Net debt - sounds at a reasonable level, but we're not told if this includes any Govt support enabling them to stretch creditors & hence temporarily reduce net debt?
Net debt at FY2020 year end is expected to be circa 2X EBITDA prior to the repayment of the Tuffnells working capital loan (see below).
The Tuffnells loan has been repaid in full, which sounds like £6.5m in the coffers - helpful.
Balance sheet - is very weak. When last reported, NTAV was negative c.£(90)m. At some point, I think the group will need to do an equity fundraising to plug at least some of that gap.
My opinion - positive Q4 trading, and an improvement in the full year estimates, is clearly good news, and this should improve the odds of the company being able to successfully refinance - which it needs to do soon. No doubt it will be currently in negotiations with the bank, to renew the existing facilities, on which the group is heavily reliant, before expiry in 4 months (31 Jan 2021).
The big question is whether the bank is going to insist on an equity fundraising to accompany renewal of the borrowing facilities? With a market cap of only £55m, an equity fundraising could dilute existing holders quite a lot, especially if it has to be done at a discount. Would there be much market appetite to refinance a newspaper/magazine distributor?
Nothing was said today about how the negotiations are going, for a refinancing of the bank facility, which strikes me as odd, given that it's such a material issue. Maybe a fundraising is being worked on behind the scenes?
For me, it's too risky, until a proper refinancing is done & dusted. I think there's a more than 50% chance of it needing to do an equity fundraise imminently. With more equity raised, the balance sheet (at least partially) repaired, and new bank facilities agreed, then this share could be potentially interesting, for value investors. But what long-term future is there for this type of business? It looks inevitably to be a gradually declining business, with constant cost-cutting necessary to offset falling revenues.
Note that there is also a pension deficit, so ultra-low interest rates forever is tending to make these problems worse. That would need checking out too, before buying this share.
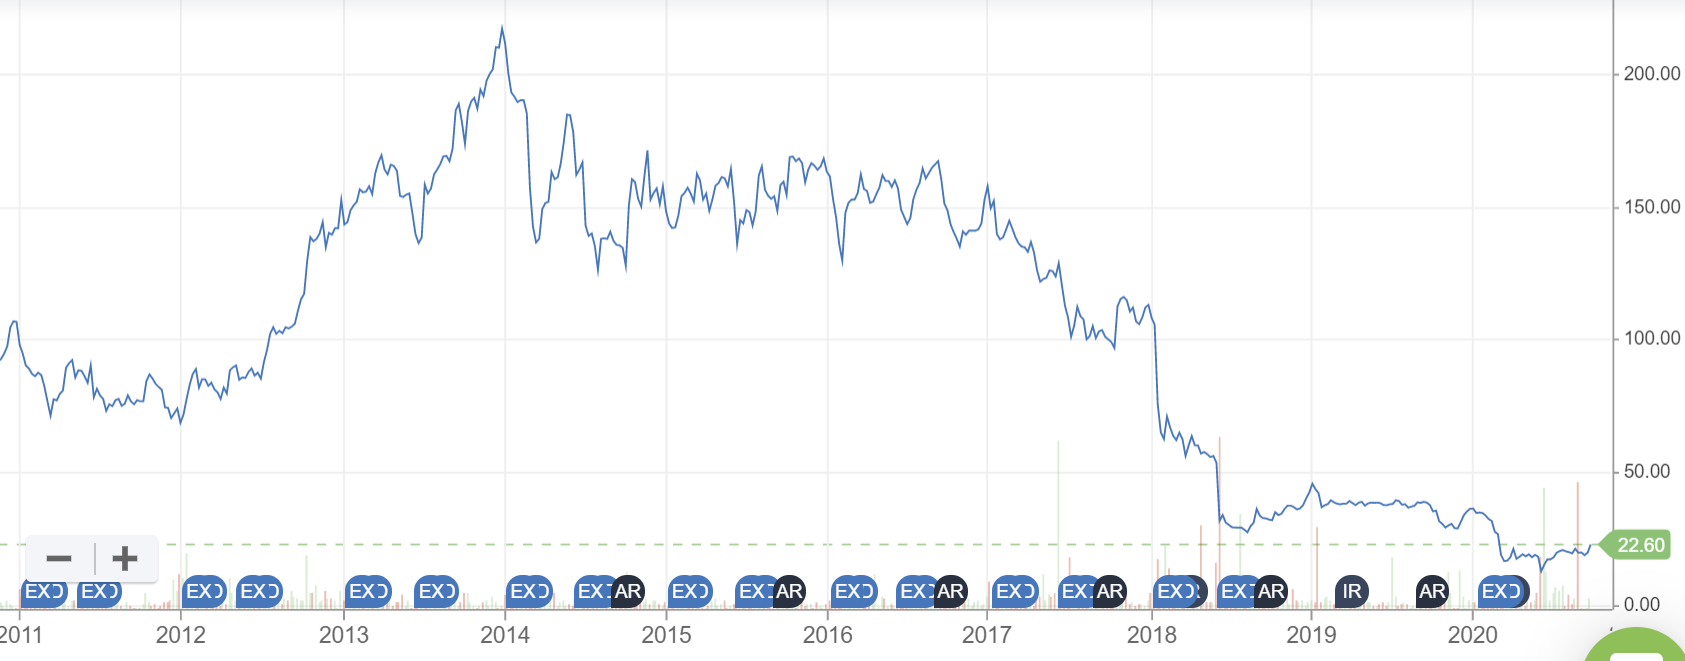
The long-term chart tells a story of a business in structural decline. It could be a nice trade, if the refinancing is pulled off without dilution, but it's not the sort of thing I would want to hold long term.
.
.
Halfords (LON:HFD)
216 (up 19%) - mkt cap £430m
Another strong update from Halfords today - well done to holders.
See the RNS for the detail, but to summarise, cycling-related sales are strong, and motoring is improving.
Given stronger than expected trading since week 20, we now expect profit before tax1 for H1 FY21 to be in excess of £55m.
We do, however, remain cautious in our outlook for H2. The potential impact of second waves of COVID-19 now seems more pronounced than just a few weeks ago, and the economic impact of an end to the furlough scheme and the outcome of Brexit
negotiations remains very uncertain. We are well placed to address any headwinds we may face and capitalise on the tailwinds as they arise. Our balance sheet and liquidity position remain strong.
Checking my notes, its last update was covered here on 11 Sept 2020, indicating £35-40m H1 profit. So a move up today to £55m is quite a step up, in just 3 weeks! There must have been a mad rush for bikes, once people gave up on the idea of an overseas holiday.
Remember that H2 is quieter seasonally.
My opinion - it's great to see Halfords doing so well. The shares don't interest me though. How sustainable is all of this? Roll things forward a year or two, and the current cycling trend might have dissipated, and earnings falling? Also, I don't like Halfords weak balance sheet, with negative NTAV.
Well done to holders, but personally I'd want a more convincing long-term earnings outlook to get me interested.
.
Renewi (LON:RWI)
23p (up 19%) - mkt cap £184m
Another strong riser today, but not a company I've looked at before, so please excuse anything I miss, on this first review of the company.
A couple of years ago the market cap was £600m, so it's become a small cap the wrong way around. From a quick skim of the StockReport, it seems to have had a poor profits track record, and I can see the balance sheet also looks a problem, with a lot of debt. It's quite a big company, with operations in several European countries, focused on recycling of waste.
Renewi plc (LSE: RWI), the leading international waste-to-product business, announces its trading update for the period from 1 April 2020 to
30 September 2020, in advance of the Group's interim results which will be issued on 10 November 2020.
The main bullet points below read well (I've cropped the list, as it was too long);
- Overall trading in the first half has been materially ahead of the Board's Covid-19 adjusted expectations
- Good recovery in Commercial volumes during Q2 with Netherlands now operating at 96% and Belgium at 90% of prior year
- Cost savings of €10m delivered during the first half, on track to be ahead of the €15m expectation for the full year
- Strong cash performance, with a cash inflow of €63m to the end of August and leverage is expected to remain below 2.9x as at 30 September, broadly in line with pre-Covid-19 levels and well below the adjusted covenant of 5.5x
- Liquidity remains strong in excess of €300m
I have no idea how to put that in context, so am going to have to look up the last full year results statement & digest that next.
Results for FY 03/2020 - this is quite a large, and complex set of numbers. A few points;
- Revenue of E1.7bn
- Underlying profit before tax (PBT) of E44.5m (down 23% on LY) - not a very good profit margin
- Core net debt of E457m - plus more indirect debt in other structures like PPI
- Debt:EBITDA at 2.98 (covenant of 3.5) - NB covenant has since been relaxed
- Problems with onerous contracts, especially UK municipal waste - quite material
- Interesting debt structure - although debt is huge, some of it is via "green bonds" in Belgium, which are cheap, at c.3.5% pa interest - could be a plentiful source of secure funding, which I quite like.
- Pension deficit recovery payments of E3.5m pa
- Awful, overly indebted balance sheet. NAV: E235.3m, less intangibles of E610.1m, gives NTAV of negative E(374.8)m
.
My opinion - I've seen enough now to realise that researching this company properly would be an all-day job.
The balance sheet is so bad, that I wouldn't be interested in buying any shares in this. Although you could see the equity as almost a call option on the business recovering, which it seems to be doing, getting over the worst of the covid period anyway.
I'm not keen on the onerous, loss-making contracts which reminds me of the many infrastructure companies which have collapsed over the years because large complex projects went wrong.
On the upside, European countries are really keen on recycling, and reading through the commentary, it sounds as if Renewi could be profiting from this favourable attitude of policymakers towards its sector.
A key thing to research would be all the terms of the borrowings, maturity dates, what do the bonds trade at? In a very low interest rate world, I can see why some investors might like an ethical, green bond, that pays more than a bank account. That could mean Renewi is able to keep rolling over its debt, at cheap levels?
Overall, I'd say this is a special situation which would need a lot more work. It's probably not for me, so I'll leave it there. If the company continues recovering from covid though, I could see the shares maybe starting to recover, who knows? So it might be one to spend some time on, for readers who understand the sector.
.
Fw Thorpe (LON:TFW)
290p (down 5%) - mkt cap £338m
Let's have a look at another company, instead of wasting more time reading the fractious junk in the reader comments below.
FW Thorpe Plc - a group of companies that design, manufacture and supply professional lighting systems - is pleased to announce its preliminary results for the year ended 30 June 2020.
As with everything at the moment, it's difficult to know how much emphasis to put on results which cover the covid/lockdown period, as this announcement does.
A few key points;
- Revenues up 2.4% to £113.3m
- Profit before tax down 9.7% to £15.9m - seems pretty robust, considering Q4 was impacted by covid
- Fire at Lightronics facility in Holland very recently, on 23 Sept 2020
- Dividends increased a little, to 5.66p for the full year - a small, but dependable yield
- Pension scheme, but I've not looked into it in detail
- Amazing balance sheet, this is a real stand-out feature here - net current assets (i.e. surplus working capital) of £72.9m. NAV: £128.3m, less £21.0m intangibles, gives NTAV: £107.3m - this is so big that it deserves paying more, in terms of PER, for such a bulletproof financial position
Outlook comments seem a bit mixed. Current orders sound fine, but it goes on to say;
it is difficult to predict anything other than a downturn in orders at the end of the 2020 calendar year.
My opinion - it's a wonderfully well-funded business, with one of the best balance sheets out there in the small caps space.
With uncertainty over the outlook, I'm not interested in paying the current rather toppy valuation. So it's not for me, whilst recognising that it's a very well-run, decently profitable business. I just don't find the valuation attractive.
.
That's it for today. I'll see you tomorrow, and will write about whatever I like. I won't be reading or responding to any reader comments, as they're ruining everything, and life's too short.
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

127 comments
I'm not a holder of Boohoo (LON:BOO) but I still enjoy reading Paul's analyses of it.
Working on the obvious assumption that we all subscribe here to make money, I read many Stocko articles about shares I have no intention of owning, simply to learn from others analysis.
Whilst I hold Boohoo (LON:BOO) it still seems an obvious stock to discuss in the SCVR as it has been such a phenomenal growth stock.
For the same reason I enjoy reading about £GAW in the SCVR, which Graham covered only earlier this year, even though I have never owned it. (If only.....!)
Whilst 99% of the SCVR stocks are small caps, not looking sideways and discussing boohoo, Next, Games Workshop and other non-small-caps would be a great loss in my opinion.
Well said Jon...
Paul, thank you for your opinions and insight. As an amateur investor, I believe you and others here have given me insights that I have never been able to get before. Keep up the great work and believe that your input is very widely well received. Keep keeping it real.
Paul, you are doing a brilliant job. Keep up the good work.
The dichotomy of the enigmatic Boo. So basically its a big girls blouse shop. Has caused a lot of fuss. I think its important to focus on hot spots as they ignite. Sure it will pass as and when. Pretty good deal to be able to get daily in depth financial scrutiny from a company accountant on a variety of small caps that many brokers have probably never heard of. I like Paul's forthrightness about stock that interests him and honesty about companies that he doesn't understand or know too much about. On top of that Paul takes requests occasionally.
Some of Stockopedia readers are not necessarily familiar with the history of Paul and BooHoo. His initial discussions on BooHoo were when the share price had fallen from around 40p to 20p. Yet it was his analysis that certainly encouraged someone like me, who does not have the forensic accounting skills, to invest in it. My initial price was 26p, so not the absolute bottom, but a good deal nonetheless. I think a lot of subscribers at that time would also have invested on the basis of Paul's analysis (never a tip). BooHoo was definitely a small cap then. And isn't the idea here to unearth, the kind of company that will demonstrate a strong record of growth. A lot of subscribers therefore have an investment in the stock - starting from that low base - and will still be interested in what Paul chooses to say about it. I'm disappointed that some folks are griping about this report, when it is a free part of the subscription, and uniquely insightful and honest. As Paul says if you don't wish to read about a stock don't. Stockopedia has avoided some of the polemics and ramping of some chat sites, and tbh that's another tick in it's favour.
Thanks for feedback Archaic. Who knows maybe Revolution Bars will be another Boohoo ——-smiley Have taken a small position just in case.
Paul you can cover Boohoo (LON:BOO) Revolution Bars (LON:RBG) and BigDish (LON:DISH) as much as you like, more than you currently do if you like.
Just giving an alternative opinion of course...
Paul I think the SCVR and the amount of work you put into it is brilliant. All your comments/write ups on Boohoo (LON:BOO) are so helpful and I always look forward to reading your thoughts every time I see you have provided further analysis. The BOO share price has been such a roller coaster lately that having you share your extensive knowledge of the company and sector has been very reassuring during these times. Please do keep these updates coming.
Many Thanks
Hi everybody, Thanks Paul for your terrific write ups. I tried to buy some Boohoo shares yesterday through selftrade but they did not execute the trade. I have spoken to selftrade but got no sense and they have not replied to my emails. Has anyone got any ideas? 70 million shares were traded yesterday!
micke
Hi micke , poor service would have me moving to another broker sharpish, imagine trying to get your money out. I highly recommend X-O as a no-frills execution only broker for trading or ISA investing. A limit buy might have more success with a volatile share like Boohoo (LON:BOO) ,good luck.
Here's the Sumo (LON:SUMO) H1 20 results presentation given to analysts yesterday (30.9.20) by Carl Cavers, CEO & David Wilton, CFO. Great detail on the Pipeworks acquisition, and they sound very confident about the future. Share price is up over 10% since the announcement. Video and podcast.
David & Carl will be presenting again, to any investors who wants to attend, on Thursday 8th October, 1pm, a webinar followed by the opportunity to ask your questions. Register here (if you haven't already).
Moving on from Boohoo (LON:BOO) related stuff...
Take this opinion/warning with a huge pinch of salt as what do I know!
I've tuned out of PI discussions at the moment. I think things are particularly febrile. I think groupthink and herd behaviour are particularly dangerous right now. We are clearly at the end of a very long macroeconomic phase (since late 70s IMO). Most of us learn and have wisdom based on heuristics. We are all over fitted to the heuristics of the last 40 years and particularly the last decade. I believe you should question everything. I'm not saying that things change tomorrow or even within the next year...but the 2020s are going to be very different from the 2010s.
There's some that have lost money and so a bit sore/humbled/unsure/etc and there's some that have made money. I feel the latter group are in a dangerous place. Note, I'm up 15% ytd...giving back from 20%+...so I'm not grumbling as I'm down. I do own what many would consider a bag of crap...ain't much fashionable except for Getbusy (LON:GETB) and a few gold miners...all bought when disliked....and GETB is a little fruity right now but I like it longer term and don't have much risk in it (so happy to buy if falls) whereas the gold stuff has lost some sheen...I'm not a gold bug and its a capital cycle related play by me with some macro optionality built in...negative real rates, currency uncertainty and a whole heap of fiscal stimulus to come.
High multiple, low earnings, perpetually refinancing for bluesky growth or for acqusitions...these kind of stocks have done very well...everyone knows they are the future...plus the market always re-liquifies and bids these 'winners' up....right? Everyone knows that the platform companies are going to kill old dull companies...and these new wave companies are good at nearly any price....after all, what's a mere 50x for a killer platform?
There's quite a decent chance that the US has a melt up short term IMO as 1) fear Biden trade ain't coming through (already short term priced/overblown?) , 2) covid second act isn't really frightening anyone (except media and prominent health experts) and 3) the stimulus bill in US will go through to add fire to a rapidly expanding economy. Boom boom boom (see this from August if your glutton for punishment... https://medium.com/@mojomogoz/... )
BUT do you buy "crappy" restaurant or High St retailer rather than Amazon, Zoom and Boo?
Thanks Mojomogoz, and thank you for the note added later on yesterday on S&u (LON:SUS) this has been added to my weekend work, seems to me like it falls into my City Of London Investment (LON:CLIG) and Creightons (LON:CRL) investment category, nothing exciting but Cuprinol if we are still allowed to say that?
Tommy
No worries Tommy. I like S&u (LON:SUS) and think it’s almost the most obvious quality, value and growth combo in the mkt (might not quant score like that but need to understand the dynamics of their biz). DYOR obvs
They are hosting a meeting on this platform tomorrow at 9.30
https://presentations.investor...
It’s recorded so you can go to it at weekend.
It’s very unlikely that S&U will zoom up but once people warm up to it there’s a 2-3x return over 3-5 yrs with a dividend that should grow meaningfully too. I don’t invest in anything for dividend but for this company the payout makes sense.
buying into a beautiful business is all that counts. The market value is volatile but a good business is always a good business. We just have to buy it at the right price.
BS not supported well by history I’m afraid... but hey, this time is different (Generally rather than specifically Boo)
Hi Paul! Just want to say a massive thank you for these SCVR. After discovering them, they have become a great tool for me when i'm researching a share. i still put plenty of my own time in to understanding what a company does, however i have no financial background so the way you break down the balance sheet and raise red flags is extremely useful.
Regarding the discussion about Boohoo, i think you are well within your rights to mention it here. It would be a complete disservice to everyone for you to drop coverage of a clear winner. the write ups also provide insight as to what Boo has done right over time, and personally i've highlighted these points and refer to them when looking at small cap companies in the fashion industry. Anyone who doesn't want to read about it can simply scroll down to the next one.
Could not agree more. I regard this as one of the great buying opportunities and Boohoo (LON:BOO) now represents 25% of my total portfolio. Frankly,I am not bothered about negative press,and short sellers,as it gives an opportunity to buy more.
To those "interested" in the Boohoo (LON:BOO) US legal case(s), there is plenty of information out there. I have tried to answer in post 34 but maybe many people don't bother reading contributions from others. Bit frustrating really - personally I find many contributions more than worth the time and effort involved in reading all of them.
Just finished watching the results presentation. If anything I'm a bit worried that all that emphasis and focus throughout on the measures that they're taking is going to make a rod for their own back. Yes, it's good that they have taken the report seriously but no room for manoeuvre if there are any problems, particularly on the UK manufacturing side, in the future. And where does it end? Are they going to be as diligent with every manufacturer, material manufacturer/supplier, cotton grower, logistics company etc. etc. throughout the chain? You can bet some of the national media will expect that and be only too happy to flag up any shortcomings and place the blame squarely at boohoo's door.
Another moan - could people please try to remember to put £ followed by ticket somewhere in their post as it saves a lot of time having to click back through posts to see what comment or share you're talking about.
PS - Boohoo (LON:BOO) a big holding for me.
Yes, it's good that they have taken the report seriously but no room for manoeuvre if there are any problems, particularly on the UK manufacturing side, in the future. And where does it end? Are they going to be as diligent with every manufacturer, material manufacturer/supplier, cotton grower, logistics company etc. etc. throughout the chain.
Remember that they have been heavy users of influencers as a sales technique, and the influencers tend to be ultra-woke to guard their online reputation. They need to be doing something to keep them onside.
£BOO
Question for PMP - I will let you decide how you want to frame it. Management own very few shares in the company and in terms of executive management i mean practically none. In the recent placing their participation was derisory particularly if you take into account how far the share price has fallen.
Hello Paul, if you see this. I would just like to second Jeremy's question about paltry management shareholdings. It actually stopped me pressing the button on buying a few days ago. I may come to regret that; it may not get back to 385p ever again! However, there seems a good international marketing job to be done and yet they aren't really backing the story.
Second, I'd love to know what % of sales are down to Portmeirion Botanic Gardens. Altogether there's a huge range, but I am concerned that 80% are makeweights.
I have to say I agree with you on this point. BOO, Revolution Bars, Next and Big Dish seem to feature almost constanly in this report and I given this is the only daily review of companies on the site I would definitely like to see more variety. Those companies that are endlessly discussed should have their own thread.
I cover about 500 companies here, almost single-handedly. That should be enough variety for everyone.
If a company doesn't interest you, then skip to the next section.
I couldn’t agree more, Bigclaw! Although you did miss £TEG off your list... :-) And quite why you have been reported for moderation for a factual ‘inoffensive’ comment, is beyond me tbh...hey-ho, I guess it’s the society we live in now!
Though understanding why some are fed up with coverage of BOO here, bear in mind the fantastic job Paul does here on so many shares day after day after day. It takes him most of the day and I’ve never understood how on earth he manages to do so much detailed research AND then write in detail too. It’s a labour of love, but it might not take much to make him think it’s not worth it.
It’s a great service and alone worth the subscription to Stockopedia. So surely he should be allowed to enthuse and write about a non small cap share that he is particularly interested in? OK it is over the top for non BOO followers or holders, but so what as nobody is forced to read any of it. And some of us have already enjoyed the BOO share price gain from 35p and have always appreciated Paul’s updates and some of the excellent reader comment too.
I am a bit concerned about the US BOO news and have no idea what it’s about. But aside from so many UK Companies coming unstuck in the US (it’s not just Trump who goes for US first) what happened to BP after the Gulf of Mexico disaster which cost them $billions in offer spurious compensation claims, shows what can happen when a UK Company faces legal issues in the US. So I hope it is a storm in a teacup.
Thanks Ken, but ultimately, I write about what I find interesting, and completely ignore anyone who snipes about the companies I cover! :-)
"I see some journalists are desperately trying to string out the story today, but they're wasting their time (and ours)."
Paul, I don't understand your comment. You are still writing about it. What is wrong with others still doing so? It is an interesting story which the public legitimately may wish to be informed about until it is finished. I share your confidence that the company takes the issue seriously and intends to improve things. But the issue remains alive until the improvements have been made.
Stockopedia should rename this Blog to the ‘BooHoo Report’ - surely there must be other shares we can discuss on the ‘Small Cap Value’ Blog...??
I quite agree, Chris. For the last two days, everything has been buried by the deluge of Boohoo-related stuff. With hindsight, it would have been better dealt with through a separate discussion. Perhaps this approach may be taken in future?
Now my own, perfectly polite post suggesting that Boohoo would be better addressed under a separate discussion has 12 thumbs down and is "under review".
Surely people can see that this sort of behaviour detracts from sensible discussion?
Effortless
Thumbs up from me. There was absolutely nothing wrong with your comment. You are a valuable contributor here so please keep it up.
Personally, I think we just go through phases here where something is dominating the news and it all gets a bit heated. Brexit, COVID-19, etc.
So now it is BOOHISS and it is not even panto season.
Thanks, Graham.
Many readers here miss the point with these reports. You dont have to be interested in every company that reported on, however the real value is added through how the research is pulled together and analysed, and each company is analysed on its own merits.
Simply put if you not interested then just scroll down, but if an CFO from the retail sector starts writing about another retail stock then I tend to sit up and listen.
Many readers here miss the point of these comments. Mentioning that the discussion is being buried under comments on Boohoo and suggesting that it meant be better dealt with elsewhere, as it is definitely not a small cap, is not the same as criticising Paul as the author or those that are commenting on it.
Simply put, read the posts properly and think about what they are saying. Don't indulge in mob mentality and simply thumbs down anything that may seem remotely critical.
it might not be a small cap, but do we just abandon everything once it reaches mid/large cap status? I thought that was the point of investment?
Yes Chris1011!
The thin skins and hubris around Boohoo (LON:BOO) and the mutual back slapping when it’s okay are tedious...compounded by some fairly dodgy narrative and analogy based analysis (eg comparing to Amazon is very heavy mental over stimulation).
But I’m sure everyone disagrees with me ;)
Anyway...round of applause from me to all. Does anyone want to hear how I made 25x my stake in....(brag brag brag)
For the record I’ve never been (oh so evil) short seller of boo. I like a lot about the business but I do think there are some quality of earnings issues, strange behaviour around cash levels and raises, self dealing in the family and a senior mgt that clearly doesn’t respect shareholders. Role the dice dudes...it’s cheap at least 40x current earnings ...current earnings that may have covid related hangover (or may have stepped permanently to a new level)
It is, in my opinion, absolutely pathetic that your post is "under review". It certainly demonstrates that your "thin skins" comment is 100% correct.
EDIT: Review now cleared; one small victory against Stockopedia mob mentality!
Quite agree! My point is that if the folk and author on this SCVR Blog what to debate Boohoo (LON:BOO) to the extent we see on a daily basis, why not set up a separate forum and discuss the ins-and-outs of itv there?? There are 1000’s of other small caps we could be discussing instead - this is just my point of view...
*it not itv...!!
Well, ITV (LON:ITV) is both smaller and has a higher value rank than Boohoo (LON:BOO), so maybe it should be ITV (LON:ITV) in the SCVR ;-)
I'll get my coat...
I think its just my fans trying to encourage me and obvs they want more of it....they know I love the opprobrium
Mojomogoz will be sad if he only has 11 votes down
Mojo .Go on in a few short words tell us how you made 25 x your stake...was it on the winner of the Gold Cup when Norton’s Coin won @100/1 and you backed for a place on the Tote...go on Mojo prove to us you really are a human with an ability to write short simple sentences...Yes? No? .Tony
Tony, perhaps improve your comprehension skills?....do that and I might tell...but I'm a bit shy and don't like to brag along with all bling trader boys
What utter rubbish! I'm writing about loads of small caps, AS WELL AS BOO, not instead of.
Bottom line, I spend many hours on these reports, and I'll write about what I find most interesting. If you don't like it, don't read it.
I hold BooHoo and have no intention of selling.
This by Shore Capital today might help explain today's drop:
BooHoo: Shore Capital Markets reiterates sell with a target price of 390.0p.
"BooHoo: Shore Capital Markets reiterates sell with a target price of 390.0p."
Does not make sense to me, the share price is around 350p, so is it a sell above 390p or what?
SP action on Boohoo (LON:BOO) - mad!!!
The share price fall could be because of shorting campaign. If that’s the reason it’s not concerning for reasons so well explained by Paul.
But what is this possible US legal challenge and why did nobody think of raising that question yesterday? Could that be behind the sudden share price fall today?
EDIT. I’ve just checked and Paul has added a section on that now. I’m keen to know more. E.g what is it that BOO might have done wrong. Until knowing more this worries me far more than those newspaper so called revelations.
Too many UK Companies have found US a graveyard for their business, including Tesco and before that Dixon’s and Marks and Spencer. So until knowing more even a hint of trouble there merits explaining further if anyone here knows more.
Does anyone know the reason for the drop in £boo (hold) over the last 2 days despite a good trading update?
profit taking I should think.
Paul - £BOOHOO PER is reading as 42.4 today. Where do you get 31 today from???!
You could try reading Paul’s well argued analysis above. I have never held Boohoo (LON:BOO) but do find Paul’s analysis realistic rather than over-excited.
Sunny have you actually read Pauls write up?
He believes that an EPS forecast of 12p for 02/2022 is much more likely than the current EPS forecast. So based on his assumption of 12p the current Boo share price of 370p means it is trading on a PER of 31.
Hope this helps.
Question for your interview with CEO of PMP. (I hold)
The sixth point in his newly adopted strategy (see IMC webinar materials) is enhancing operating margins through targeted capital investment in the factories. What is his minimum acceptable ROI (or maximum payback period or whatever metric he uses) for such investments? Also, same question re acquisitions.
Thanks Paul
PS the other five points are all about sales growth, couldn't believe his background is accountant, not sales or marketing guy!
Hi Paul - Pleased you are having a look at FW Thorpe. Been a holder for over 10 years and there are few businesses with more solid balance sheets, although I also hold James Halstead, again reporting today, which runs them close). Cannot think of another which owns investment property in the shape of land with fishing rights on the river Wye, but guess that comes with the territory of a strong family interest. Handling covid well in my view and treated their employees brilliantly. Unlikely in my view to shoot the lights out (sorry!) but a good business with acceptable yield.
Burford Capital (LON:BUR) (I hold)
I've always liked this company and today's results did nothing to quell my enthusiasm for its (hopefully) long term success.
I also appreciate the very detailed updates now being published, even if the Financial Reports now resemble something regurgitated up by a team of highly skilled and over-the-top lawyers.
They're certainly keen to make things as complicated as possible, but they are thorough, which is better than not being thorough - the Annual Report alone took me 3 days to go through, with every figure that initially confused me being explained somewhere.
TODAY
Cash generation was excellent, as we knew it would be from previous updates. There is also a big chunk to come from receivables and, based on past experience, I'm sure there will be minimal issues collecting this.
If there is one thing I wasn't pleased about, it was:
This could have a material affect on future cash generation.
My fear is that they reduced commitments/deployments simply to show the doubters that they could generate cash and show it sitting as a large Scrooge McDuck pile on their Balance Sheet.
I also noticed that they settled some cases at average returns to "de-risk" their portfolio during Covid lockdown, though again, I wonder if it was simply to show a large period end cash balance.
If my assumption is correct, then personally I would have preferred them to ignore the noise, carry on doing what they've been doing and keep cash balances to a minimum.
But then I've never have been good at politics, so perhaps this might end up being a good move in the long run in case they ever want to issue equity at a higher share price or have a more solid foundation to re-issue debt (though note debt repayments are years away, c$111m is due in 2022 and the next chunk is due in 2024).
Happy holder for now.
A
Burford Capital (LON:BUR)
Abtan would be interested on your thoughts ref this line in todays news
In particular, Burford's most concentrated position was successful, generating $172 million of income and a 182% return on invested capital, with the result that our cumulative returns rose to a 97% ROIC and a 32% IRR.
Does this mean that if the outcome with regard to this one case was different (adverse) they would have potentially reported profit $172 mill lower ? or do they have a materially matching expense going out when cases are successful booked as income. I would presume that cases with that level of profit/income booked would be hard to come by - although they seem to keep churing out these decent whoppers for now .
Unfortuantely for me looks like i may be too late to this party with regard to my plans to bottom fish before US listing.
Burford Capital (LON:BUR)
https://www.rns-pdf.londonstoc...
Slide 6 has the detail you're looking for:
"Burford’s most concentrated position was successful, adding yet another example of outperformance to Burford’s long track record and generating $172 million of balance sheet income, a 182% ROIC.
We deployed $144 million Group-wide ($94 million on the balance sheet) into a related group of 18 cases in the 2016, 2017 and 2019 vintages.
Those cases were all resolved in our clients’ favour in the first half of 2020 and their judgments have begun to be paid; when all cases are paid, we expect to receive cash proceeds of $423 million Groupwide (balance sheet: $266 million), for a Group-wide ROIC of almost 200% and an IRR of 56%.
At the end of 2019, those cases were all held at cost, as no objective event had occurred under our valuation policy to cause us to recognise gains prior to this period. As a result, the balance sheet generated $172 million in realised gains from these matters in 1H 2020, not including the asset management fees they will ultimately produce."
Also, it's worth checking out slide 23 for ROIC by case. I'll paste the image, but it's probably clearer at the source:
A
I would welcome any thoughts on Buffettology Smaller Companies Investment Trust. IPO launched today via PrimaryBid at 100p.
Buffettology Smaller Companies Investment Trust.
Ashworth-Lord has a good reputation and his Business Perspective Investing strategy will resonate with many investors here. It certainly does with me and I am actively considering an investment in this trust. The key issue is whether you think the shares will sell at a sufficient premium to the issue price to justify buying in the initial placing or whether it might be better to wait and see whether greater value will be available in the market. Allowing for costs initial NAVps will be about 98p, for which you will have paid £1.
Thank you DWit199 for your reply. The strategy resonates with me also. Mark Slater on a Piworld podcast echoed your sentiments on buying at initial placing. I will wait and buy at market price.
You can go to the AIC site where you will find the average discount for smaller company ITs is over 10%. Can’t see what this offers over other long established ITs.
I agree. The only reason to buy in the initial offering is if you think Ashworth-Lord has sufficient star qualities to attract a premium. His other Buffetology open ended fund seems to have done quite well but I have never understood why he bought Revolution Bars, so there are some question marks over his judgement. I do, however, like his general style which is why I am looking at this fund more seriously than most.
I saw the companies he mentioned and they were more or less the same as Jpmorgan Smaller Companies Investment Trust (LON:JMI), Blackrock Smaller Companies Trust (LON:BRSC) and £ASCI. The whole point about ITs is the discount. IMHO its bonkers to buy a bog standard IT at a premium.
Could you see Warren Buffet buying RBG? I think the Buffetology bit is fluff. Terry Smith or Nick Train more like it.
I see Mark Ward has topped up another 1% of the company, now the third highest owner, he's got faith.
Anyone know who this mystery man is?
wow! Would love to know what Mark Ward is thinking or knows. I'm holding although now down 60%, but not feeling brave enough to average down further by topping up
But of course without knowing who Mark Ward actually is, his holding is pretty irrelevant.
Fanboys (& girls) of Filtronic (LON:FTC) like to make a lot of the shareholding of : Mr. M.H. and Mrs. D.M. Dixon who now own more than 20% of the company - I read suggestions that Mark Dixon might be a current or former senior executive with Nokia, which would potentially be very significant.
However, a bit of sleuthing suggests that Mark & Diana are something to do with the Horse Racing crowd and own a few horses as well as dabbling with various shares with limited success.
Their 20% holding in Filtronic (LON:FTC) is worth about £3.5m , but they cost a lot more to acquire - maybe this punt will ultimately come off for them, but their holding has hardly been a success so far.
I would wait until it has launched. there are some really good smaller company ITs out there like Jpmorgan Smaller Companies Investment Trust (LON:JMI) which I own and sits on a 15% discount. When I read an interview with him he mentioned more or less the same shares as many other ITs have in their portfolios.
Paul, Just wanted to drop a line of appreciation for the continued commentary on Boohoo (LON:BOO) I for one, find it very useful.
Thank you for your ongoing write up on £BOO.
I have said to my wife that there is the possibility for Boohoo to be the Amazon of apparel, especially if they continue to consolidate popular brands that cover a broad spectrum of buyers.
I have nothing like the knowledge of fashion retail as Paul (mine extends to 5 years in men’s knitwear in Harrods!) but in strikes me that it is a fragmented industry which is ripe for consolidation.
Amazon has 5% of all retail sales in the US. World apparel sales are north of $1 trillion. 5% of $1 trillion is $50 billion. Even if we divide that by 5 we get to $10 billion of sales. 5 or 6 times where we are now. I would have to assume there will be slips along the way but I don’t thing it unreasonable to believe that they will get there within the next seven to ten years.
They have grown turnover 18 fold in seven years so a six fold increase in say ten years should be a walk in the park. :-).
Regards
Michael.
Michael we often have words about Boo. I’m interested in how people go about valuing shares, particularly growth ones. But there is no such thing as an Amazon of apparel. Amazon’s model is to sell everything. If Boo has the technology it could try to emulate Amazon as WalMart are trying to do.
On revenue projections it’s much easier to grow say from £50m to £1bn than from £1bn to £6bn. Percentages don’t always help. If they are to do so they will likely have to move into other product areas - like Next did with home - or further geographic expansion. Where will this £5bn come from?
It’s PER is 62. Would you rather own 1 £Boo share or 5 Next (LON:NXT) - on a PER of 12?
As I point out in the article, if you use a realistic forecast for next year's earnings (12p) then the PER of BOO is 31. It's not expensively rated at all, if you dig into the numbers. That's my whole point!
Next (LON:NXT) is great too, but much slower growth, and a retail estate in gradual wind-down, is why it has a lower PER.
Both are really good companies, but you pay more for spectacular growth.
from what I can glean from stocko's data Next (LON:NXT) also has a significant amount of debt being carried, vs Boohoo (LON:BOO) which holds net cash.
in the current climate I'd argue this gives Boohoo (LON:BOO) more flexibility should the need arise and that IMO carries some premium in the current climate.
Hi Antehelion,
Remember with Next (LON:NXT) that it runs its own consumer credit operation. Hence there is a very large receivables book (asset) which I think more than offsets the net debt owed to banks, bondholders, etc.
Also, data providers are (annoyingly) including IFRS 16 future lease payments in net debt figures, which is misleading.
Overall, Next's finances are absolutely fine, with effectively no net debt.
Regards, Paul.
thanks Paul, I appreciate the clarification there, cheers.
Sorry kgb1953 if we have had “words” before on Boohoo (LON:BOO) not intentional.
Perhaps Amazon was a bad analogy but what I was trying to imply was that they could be the web site that you go to if you want clothes. Amazon started off selling books and I for one never saw them ending up where they are today. Boo started selling fast fashion to young women in the UK. They have now expanded internationally and up the age, quality and price range. I am not expecting them to start selling books, just that they could become all things fashion to a large segment of the market.
My slightly tongue in cheek comment about growing the company was to point out the size of the apparel market and in my opinion £50m, £1bn and £6bn are all small numbers in the context of the addressable markets which is in excess of $1 trillion.
To carry on with the Amazon analogy. Amazon’s revenue in 1999 was about what £BOO’s is now. Six years later they had grown that ~7 fold to $10.7bn.
As to the Next (LON:NXT) question, this is not a business I know much about, beyond that it is a well respected company where as Boohoo I have owned since 2015 with a short hiatus from March to June this year. Historically Next looks as though it comes under the category of being a good (great?) company but not a good investment?
To answer your question directly. Yes I would rather own Boo at a 31 PE than Next at a 12 PE (though Stocko has it on a fc PE of 18 and Sharepad on 28). (Certainly over the past 5 years, I bought my initial Boohoo holdings in 11/2015, 2/2016, 4/2016 and 6/2016 and held until this year). But of course this is a forward looking business and yes I believe that Boo will make me more money than Next over my preferred holding period which five to ten years.
Kind regards
Michael.
Paul, Thanks for all the details on Boohoo
What is the possible legal action in the US, I seem to have missed that
alexdonnelly - Re Boohoo (LON:BOO) and the American legal action. It centres around class action(s) based on claims that BooHoo marketed products at big discounts, which in some cases are time limited, to previous or original prices which the claimants say never existed. So, they claim, pressurising potential customers to press the BUY button to avoid missing out on a bargain.
But, as far as I know, these are fairly old claims and BooHoo has already applied to have at least one of the actions ruled out.
In many of the cases no purchases were actually made so claimants have not actually suffered any losses (that may be the reason BooHoo has applied for those cases to be ruled out, but my memory fails me).
I've spoken to the company (someone senior) and been told not to worry about it, not a problem apparently.
thanks
"I've spoken to the company (someone senior) and been told not to worry about it, not a problem apparently."
That maybe so, but they were never going to say: it's a big problem. Start worrying.
thanks
Apologies Laughton.
Your moan is justified! I read most of the comments here but somehow missed your very helpful comment on the US legal action in your post 34.
Paul,
Well done with your opinion of Boo.
You don't need to worry about the shorters. They have not only lost the argument but also their money.
That is more than ample recompense.
Life is too short
(no position but wish I had!)
Michael
Michael,
Paul's analysis suggests it's still a strong buy, so I'd be interested to know why you'd like to have a position but do not. Reading the neutral or negative case would help me understand BOO better.
I am not giving an opinion on Boo, only a comment on the recent past. It is not a sector or company I know well, but I was considering buying during the media attack and the SP got battered. Also I don't have the cash for a new position atm.
FREng, for me Boohoo (LON:BOO) is one of the most interesting special situations in the markets right now. Thanks to info in this column, I bought in on the drop and sold out last Friday, making it my single largest winner this year.
I sold out because I’m trying to increase my cash position and I was afraid of the situation we are seeing now, where Boohoo (LON:BOO) deals with the Leicester issue, puts a good set of numbers out but doesn’t get rewarded with a share price bump. This is a situation that might persist for a while, as BOO has now surprised the market (the market does not like surprises) several times, short sellers are obviously circling and institutional money is wary of committing. Now if you are a true believer and willing to hold for a few years anyway like Paul, this is all just noise that can rightly be ignored. At some point, the market will have to accept that Boohoo (LON:BOO) is delivering above average returns and will have to reward it appropriately. However, who knows when that will happen?
The ESG situation is fascinating. Over the past few years, Boohoo (LON:BOO) has been attacked on E (well, it is a fast fashion company), S (Leicester) and G (I have a memory from a few years with issues from the family buying companies from other family members or something). I’m willing to accept they are dealt with (and honestly I don’t really care that much about them) but you have to accept if you hold this share that it increases the risk as a proposition - at some point something might stick and a fashion brand has to be fashionable. To some extent, with diversification into different brands Boohoo (LON:BOO) has mitigated the risk but there is always the other way of looking at this - that any damage to one travels back across all the brands.
For myself, I’ve been debating all morning about whether I should buy back in. The key positive fact I took from those figures they put out is that their customers really don’t care about the ESG stuff - they just want cheap fast fashion. The majority have never even heard of Leicester and don’t even live in the UK. That’s as we expected but I had wanted to see it confirmed. If sales had slipped even slightly, it could have been a very different situation.
I think I’ve decided if the price dips below 330, I’m interested. I have a personal rule that the price has to slip by at least 10% on my sale price before I buy back into any company so I’ll run with that.
Bigdish (LON:DISH):
Update:
The Company will provide a further update this week to the market with regards to BigDish-to-GO.
I like Tclarke (LON:CTO) as a company, though I know Paul's not a lover of its rather thin margins. It's been falling over the last few weeks, presumably because the rise of WFH means that there's less demand for office fitouts. In this trading update they flag their strength in healthcare, education and data centre sectors, presumably in an attempt to address this concern.
Paul
I see James Halstead (JHD) is not on your list. An excellent family-run company which is in many IHT portfolios.
I am puzzled by your focus on Boohoo which is far too large a company to be classified as a "small company". Personally, I would regard it as uninvestible for corporate governance and other reasons.
Next time you come to Edinburgh, I will buy you lunch and invite King McKong along too.
Kuronagi
Hi Kuronagi,
Fashion retail is my sector specialism, and I think Boohoo (LON:BOO) is by far the best share in my specialist area. I've been raving about it here since it was 23p, and readers have made millions from it. Hence I'll continue raving about it, because as explained today, I reckon we could make many more millions from it, and ultimately this is all about making money! You think it's uninvestable, fine that's your opinion. I think you're behind the curve though. The company is on a journey from being a private company, to being a proper plc now, it's coming of age in a way. Watch the webinar, and you'll see what I mean. This is why the volatile founder is being side-lined a bit, as his style isn't really suitable for a business of this size any more. But operationally, his knowledge & experience are still invaluable. Over time, founders have to loosen the reins as time goes on, and businesses develop. I think the discipline of being a plc is good for BOO.
James Halstead (LON:JHD) - I had a quick look at its results this morning, but at £1bn mkt cap, I wouldn't cover it, as I have no particular knowledge or insights into floorcovering manufacturing. It looks a good company, and resilient through covid, but the valuation looks crackers to me. A PER of 26 for a business that's largely ex-growth now, in both profit & revenues. Why on earth would anyone think that's an attractive price to pay?
My sector pick in floorcoverings is distributor Headlam (LON:HEAD) (I hold) - pre-covid it made about the same profits as JHD, yet it's now only about a quarter of the valuation! Despite having £100m of freeholds on its balance sheet. Recent trading update showed it returning to pre-covid levels of trading in July & August. That's a vastly better investment proposition at the moment, in my view.
Send my regards to KingMcKong & everyone else in Edinburgh!!! I enjoyed my visits there years ago.
Regards, Paul.
1 housepoint awarded for amusing use of the word "volatile"
HI PAUL (and anyone else!)
I'm considering £BOOHOO. But what do you make of the Shadowfall research specifically regarding tax payments due not being recognised i.e "discretionary payment view of mgt", misleading FCF, and misleading numbers vis a vis Pretty Little Thing ownership by the founder's son?
Also I checked the FCA shorts and currently around 1.1% of the share capital of the company is shorted - not a disaster but worth noting.
Also we all love metrics.....a PE of 40 ish looks stretched! Also we know unemployment will rise when furlough ends.....esp in low paid sectors where a lot of £BOOHOO's customers will be at the moment. At the end of the day, isn't it likely sales will drop???? The market will really cut the froth on this share price if sentiment changes....
Again just bouncing ideas and interested on your take....
We've covered all that stuff before, have a look through the archive.
Hi Paul
I watched the £boo webinar last night (I hold).
(If nothing else, Covid has provided us with more of these results presentations and they will hopefully become the norm).
With boohoo’s commitment to much greater transparency over the next six months about their supply chains in the UK, and independent scrutiny of their foreign suppliers, then it feels like they are raising the bar for other UK based clothing manufacturers to follow. Interesting to see how they respond, or not.
You have mentioned many times about problems across this sector. Any suggestions elsewhere that just boohoo need to address this issue conveniently ignores all the other players.
Thanks as always for your analysis.
Jon
Hi sunny1978,
I agree with you that £boo price is stretched on a PER of around 40 but as Paul has pointed out (and I agree with him) that you pay a bit more for growth in a quality company. £boo has a lot going for it and in an ideal world it would be nice to be able to buy a share with a PEG of below 1 but when the EPS is being rerated, how do you then value the share price? Sadly its price is currently a bit on the high side for me. My opinion is that a good time to buy a company is when the price drops to around its 50 day MA or around 10% below the 50 day MA. Looking at the Stockopedia charts that would currently imply that a reasonable price for me to pay would be between 270p - 306p. Let's hope the price drops down to that region because I believe that would be good time for me to buy a few £boo shares.
Hi Paul, Kuronagi - I agree with Paul's view here re James Halstead (LON:JHD) (Momentum Rank is mid-40's) and rather look at Headlam (LON:HEAD) (over long time periods it has impressive growth). I'm stuck on Howden Joinery (LON:HWDN) so not sure it's worth switching. There is Turnaround activity happening though so Momentum Ranks for all 3 could well edge upward.
Market likes the results at Burford Capital (LON:BUR), and with a US listing later this month it looks an interesting stage in the company's evolution. Chart looks out of the doldrums, could be good from here imo but I'd love any views
£Bur
1.always challenging to analyse these numbers but income from realised cases is higher and income from mark to market now less relied on. Investor call will be interesting
2. secular uptrend. Comments in the figures...“…much as we deplore the suffering we have seen this year across the world, no one disputes that the tumult of both the pandemic and the ensuing economic consequences will inevitably lead to a vast landscape of disputes for years to come.”
3.US listing v positive
4. corporate governance and account issues hopefully proven and behind them
5. reasonably uncorrelated investment
Hi Donald,
If you want a co-related play try Litigation Capital Management (LON:LIT) - more conservative on their accounting projections, but growing pipeline, high IRR, and supported by Simon Thompson(Investor Chronicle)...we'd just need to check how COVID impacts their early global expansion (London, Singapore). Interesting play on corporate portfolios not just singular litigation deals. Lastly one might need to keep expectation in check - peoples/services Co's typically don't hit the same 5x, 10x that product based Co's sometimes hit (opinion).
I agree, there is a good presentation from Litigation Capital Management (LON:LIT) on the PI site if you haven't seen it
Litigation Capital Management (LON:LIT)
yes I concur...the difficulty is trying to understand and believe the business model. The pluses are collective contracts (corporate portfolios create sticky clients), early in cycle advantage, focus on main verticals (eg aviation and mining) is broadening, and demand for specialised off-balance sheet funded litigation services is increasing. Hopefully brand and service quality proves itself and some share option schemes prevent loss of staff. That's maybe it's risk and its qualification method that could be copied. So I'm unsure of how good a moat exists outside (so I hold).
Halfords (LON:HFD)
Stunningly strong update from Halfords (I don’t hold) - I did hold long time ago but sold as the long term profits trend seemed to going in the wrong direction.Based on these numbers I can see there being a strong bounce in shareprice this morning. Is trading so exceptional strong it’s unlikely to be repeated next year? - I know not.
Looks like management here are doing a good job here.
How many people like the Pcf (LON:PCF) trading update today? I know quite a few PIs like and CEO Scott Maybury is always out pressing the flesh persuading people to get on board. Call me cynical but...
I believe PCF are too keen to take on risk and tightening lending standards but growing business are mutually exclusive things. Their discussion implies growth is from motor and property bridging finance. Supposedly taking advantage of weaker hands pulling out (and improving quality of loans they make)...but other strong hands tended to step back from lending during the period
For sure income and CF will be positive if more lending is done even as others are in forbearance...but water, bathing suits, etc...
Its possible they are making a killing taking business that others have foregone....but this makes them very very very good. I wonder if another capital raise is the pipeline to support "growth"?
I'd be interested in someone making the case for why they have it right.
I'd put it to you that businesses that overlap with them in some areas such as 1pm (LON:OPM) and S&u (LON:SUS) have done the prudent thing in terms of lending and provisioning....ie putting money aside for potential but as yet unseen loss and pulling back on level of lending so as they can ensure on increased quality.
None of the names are loved in this area but PCF has enjoyed a sheen compared to others for their relentless growth rhetoric....growth in providing credit is always easy...
PCF (LON:PCF)
Not much to like here mojomogoz (I still hold) I guess the main positive was the lack of any real bad news - still in profit and the fact that business is ticking over.
Negatives - not sure suspending guidance cuts it with me - come on well paid finance bods you have one business here to add the numbers for and should know everything inside out - saying how’re ain’t good enough particularly as you are able to say business is profitable.
The main concern here is the low bad debt provisions they have previously had - that provisioning simply doesnt seem enough based on level of current arrears. They have kicked this problem down the road today - but this is the elephant in the room.
I would sort of disagree with you if you think their taking on motor home and bridging loan business seems a desperate ploy to keep the lending numbers up? Ref motor homes there is a real shortage of these at present so motor home sales are genuinely booming so this would suggest that increases in lending here is natural rather then a desperate measure. I suspect the same is true ref bridging finances property in certain areas very desirable at present so the Standard sell before you buy route a present isn’t always the best option - bods I know in this position at present are all very sound financially speaking. Not convinced the sales in these 2 sub sectors are material though anyway though to over worry about?
Perhaps cbils will come to their rescue ref bad debts if some of their risk can be passed onto the government.
Hi rmillaree
I'll be straight up and say I've got a real negative vibe on Pcf (LON:PCF) ...had it before covid. I think its a stock that could go bang....but if its survives the lumps along the way then it'll look like a great growth stock...but I feel in pursuing growth it has left its future to chance.
Three things
1) the CEO is always promoting and IMO has been a bit vague and then inconsistent in answers I have received from him around credit quality and provisioning
2) growing loan book at end of cycle with some signals that others had taken as signifying increasing risk (eg Brexit). IMO they seem to have viewed getting a banking license and so being able to take deposits as a pure growth ticket
3) To be a bank and fit with capital requirements and also support loan book growth at the same time they have had to move their lending up the quality scale from their old non prime (quite like 1pm (LON:OPM)) to more prime-y stuff. This means they have re-appraised their credit assessment processes and moved to more automated and volume based assessment rather than bespoke human approach. This part of the necessity of being a bank really and playing by big boy rules. Return comes more from leveraging your book than spread. Some risks detailed below.
IMO they are being reckless and claiming the impossible -> they can grow fast, move into new areas, change their risk assessment dynamics AND be better at that than other lenders....so they can actually be taking new business off of these schmuck old lenders in the middle of the bad times....surprise that they can be so good and foresightful yet they can't provide guidance (TBC I don't think not providing guidance at the moment is wrong, I'm just pointing out the preceding logic that PCF are saying they can see through the problems such that they can lend more where others have stepped back)
This could all work out really well for PCF but I think its a crapshoot rather than judicious management. A bunch of cowboys taking the gift that is a banking license and running hard with it....
Here a cynical perspective...I'm wealthy Caribbean family office that owns c.70% of an old school non bank asset finance business....I shake it up and get it a banking license and instruct it to grow assets as rapid as possible (don't worry about the risk too much)...then the bank hits stress through a bit of its lending...it goes to market saying it needs to bolster its balance sheet....the hordes of PIs that had bought growth with stories of risk management don't like that at all....institutional investors are not on the scene at all....so daddy family office steps in takes control, injects capital onto the balance sheet and now owns a much larger company that is now a bank than it started with several years ago and its cost it a minimal amount.
Too cynical? Maybe...but I'm not sure how PFC can be more magic than all the other credit providers before them....after all, people are always very keen to receive credit at low prices
Note, moving from non prime to prime sounds safer....but its not that simple as in non prime you are outside of the territory where credit rating agencies are assumed to be useful and you must make your own risk assessment process (the system is anomalous and a low risk conservative small building company will be non prime whereas a bigger affair is prime simply as it is larger...there are many more examples). So in non prime risk work pays and you can charge a decently high spread for low-ish risk lending if you get it right. In prime you run with the credit agencies and leverage that result....this is what leads to systemic credit issues
I have started a non prime consumer lending business from scratch in the past...did all the FCA and credit risk work...nightmare....I also managed money during credit crisis and made money to the short side in financials and financial instruments. This doesn't make my view correct here...but it is part of why I feel PCF are wronguns.
PCF (LON:PCF)
Too cynical? Maybe...but I'm not sure how PFC can be more magic than all the other credit providers before them....after all, people are always very keen to receive credit at low prices
In some respects i don't disagree with your caution and scepticism - one just has to look back to companies like cattles to see how easy it can all go wrong quickly without really that much changing. I have pcf in my punt category - their lending seems kinda lower risk and the growth seemed to suggest that this could have be multi bagger based on how quickly the loan book was expanding. The last thing i was expecting when i bought PCF was for us to be in the pandemic situation that will force many businsses to close "overnight" without a chance to trade on in zombie format and kepe paying down debts.
Mojo, are you in SUS?
Yes. Over last couple of months built up a position .
No forecast it will take off immediately but think with 3+ year view this is excellent value and growth
I wrote a comment in yesterday’s SCVR partly to point out the insanity IM(not)HO (I hate imho! Hee hee) of PIs completely shunning quality value + growth just due to area....but will take any old zoomie moonshot in some other sectors....but then I’m a curmudgeon...I still like 1pm (LON:OPM) loads too who imo have played the whole covid thing with good quality (it’s riskier tho)
Re Pcf (LON:PCF) - Solid sounding trading update today. (Large) Retail deposits, the key to its financing, remain strong and forbearance has dropped and is (now )"12% of our portfolio down from 32% in early June." Overall it says it remains growing in terms of loans portfolio and both profitable and cashflow positive across the COVID period. Warns on need to re-assess provisions for impairment but tone seems less worried than other lenders.
Established divisions have moved sharply towards prime lending on tightened terms with car loans doing well, business loans losing out a bit to cheaper govt schemes but interestingly it also says "In many cases companies asked for assistance as a precaution rather than a necessity and the SME sector has benefited from considerable government support."
With competitors pulling back and surely a reckoning coming for many non-prime companies, PCF looks in a good position being a well funded, technology invested and agile new bank without legacy issues in a very big market.
Only possible concern is appointment of new broker: is it thinking about fund raising to exploit its opportunities faster? I hold and would normally support a rights issue but with all these fund raises and trading opportunities, it is difficult to know when to support and when to hold powder dry.
Paul what are your thoughts on Rolls Royce today?
Not quite a small cap yet but give it six months and it might be
I don't think Rolls Royce will be allowed to go bust. One day it should be worth more but in the meantime I would need to see reasons to buy. Last time I looked the chart was in free fall. I think it is outside the scope of a quick review by Paul and there should be plenty of other research available in any event.
Great chirp!! But a while still before 3D printing makes high bypass turbofan engines..
I second a £Rolls-Royce review
It's a large cap, and outside my sector expertise, so I've got nothing to add on Rolls-royce Holdings (LON:RR.) I'm afraid. There's tons of stuff on it from brokers, journalists, etc, no point in me rehashing it all here.
My morning smallcap tweet:
Digitalbox (LON:DBOX) Petrofac (LON:PFC) Renewi (LON:RWI) Inland Homes (LON:INL) ATTRAQT (LON:ATQT) Urban Exposure (LON:UEX) Sportech (LON:SPO) Hydrodec (LON:HYR) Corero Network Security (LON:CNS) Stobart (LON:STOB) Connect (LON:CNCT) Tclarke (LON:CTO) M&C Saatchi (LON:SAA) Actual Experience (LON:ACT) Drumz (LON:DRUM) Clear Leisure (LON:CLP)
Digitalbox (DBOX) buys student mag publisher Tab Media for £750k. £1.2m subscription at 4.9p, a 2% discount, to fund this and more acquisitions. Will be significantly accretive to EPS in the second FY. [SP=5.2 Cap=5m]
PFC (PFC) guides FY loan portfolio up 30% (55%) with H2 up c. 9%. New business volumes c. £260m (£276m). Forborne loans, by value, currently 12% of portfolio down from 32% in early June. [SP=111.45 Cap=386m]
Renewi (RWI) Guides H1(Sept) materially ahead of mgmt Covid adjusted expectations. Good recovery in commercial volumes during Q2 with Netherlands now 96% and Belgium at 90% of prior year. Also guides FY materially ahead. [SP=19.42 Cap=155m]
Inland Homes (INL) two sales worth £52.8m to two separate 'Build to Rent' Funds. Immediate payments c. £18m. [SP=49.23 Cap=112m]
ATTRAQT (ATQT) buys AI co Aleph Search for an initial consideration of £0.35m and 3.6 shares. £4m placing at 32p, a 3% premium, to fund the acquisition, increase investment in sales, marketing and product development activities and to accelerate growth. [SP=30.25 Cap=54m]
Urban Exposure (UEX) which is in wind down. Cash bal now £65.5m (prev RNS £51m) and expects to distribute c, £43m within 2 months. [SP=65.96 Cap=105m]
Sportech (SPO) multi-year ontract extension with UK Tote. How many years? Place your bets. [SP=17.75 Cap=33m]
HydroDec (HYR) trading remains challenging. Temporary suspension of trading. Outline terms agreed on refinancing with one party, expects completion in the near future. Extends FY by 6 months as unable to produce FY19 accounts. [SP=3.35 Cap=1m]
Corero Network Security (CNS) record order intake in Q3 of over $6m. [SP=7.51 Cap=37m]
Stobart (STOB) core operations at London Southend Airport and Stobart Energy operating within scenarios set out in June. £119m of cash and undrawn bank facilities available at 31 Aug. No FY guidance. [SP=19.66 Cap=123m]
Connect (CNCT) Smiths News stronger than management's revised expectations so guides FY adj EBITDA £38.5m to £39m, above the top-end of the guidance. [SP=18.45 Cap=46m]
TClarke (CTO) trading encouraging. Guides FY rev £240m and underlying EBIT c. £6m. Forward order book remains at a near record of £410m.. Will pay interim div 0.75p. [SP=79.98 Cap=34m]
M&C Saatchi (SAA) suspended pending results, as announced. [SP=57.4 Cap=66m]
Actual Experience (ACT) wins small initial order from Oracle for its new Human Experience Management service. Hopes for more. [SP=105 Cap=50m]
Drumz (DRUM) £500k placing at 0.55, a 4% discount, "to provide additional cash resources to enable the Board to respond quickly to investment opportunities". Comes with warrants at 1.2p. [SP=0.59 Cap=2m]
Clear Leisure (CLP) suspended pending results, as announced. [SP=0.24 Cap=2m]
PFC there should be PCF...
Here's a piworld interview with Mark Adams, the new CEO at Attraqt (LON:ATQT) who discusses the interim results for period ending 30th June 2020 (released last night), together with the acquisition of Aleph, announced today. Mark also gives his initial observations as CEO, and what's happening in the market. Video & Podcast.
(ATQT's main activity is development and provision of e-commerce site search, merchandising and product recommendation technology, for the likes of Screwfix, ASOS, etc).
piworld should have a recording of ATQT's analyst presentation over the next few days, along with Sumo (LON:SUMO), 1spatial (LON:SPA) & an interview with Air Partner (LON:AIR). All of which we'll publish here.
Good Morning Paul...I got up early today to watch the boohoo..Boohoo (LON:BOO) video , the link which you posted yesterday...in my view the content and delivery was brilliant, informative and a must watch for any long term shareholder...Your articles on Boo got me invested and it’s clear to anyone, this amazing company has not even started getting going yet..Big thank you Paul...Tony
Good morning! Below covers todays regulatory and potentially price-sensitive announcements.
GENIUS IS YOU...HollandSmith...your work is incredible