Small Cap Value Report (Thu 10 Aug 2023) - MRK, SUS, JIM

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £1bn. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
Summaries of main sections
Marks Electrical (LON:MRK) - Up 5% to 99p (£105m) - Trading Statement - Paul - AMBER
Strong revenue growth of +31% in the first 4 months of FY 3/2024, but nothing is said about profits or cash. I think this business is quite attractive, but seems fully priced, so will need to beat forecasts to justify the valuation. Low margin, competitive sector.
S&U (LON:SUS) - up 4.5% to £23.82p (£290m) - Trading Update - Graham - GREEN
The Chairman strikes a cautious and irritated tone but the good news is that S&U continues to carefully manage risk. Loan advances to motor finance customers are down and gearing reduces. Property lending is less than originally planned. I like the value and quality here.
Jarvis Securities (LON:JIM) - down 15% to 124.9p (£56m) - Trading Update (profit warning) - Graham - GREEN
I remain stubbornly positive on this despite brokers writing down the PBT forecast for the current year by nearly £1m, to £6.1m. This includes exceptional costs relating to a regulatory review. UK share dealing is very quiet right now but I still think this can do well long-term.
Paul's Section:
Marks Electrical (LON:MRK)
Up 5% to 99p (£105m) - Trading Statement - Paul - AMBER
Marks Electrical Group plc ("Marks Electrical" or "The Group"), a fast-growing online electrical retailer, provides a trading update for the four months ended 31 July 2023 ("the period"), ahead of the Company's Annual General Meeting to be held today at 11:00 a.m. BST ("AGM").
Strong trading momentum driven by excellent customer service
Impressive revenue growth of +30.7% in the first 4 months (April to July 2023)
Net cash (but no figures provided)
Gaining market share.
“Challenging market backdrop”, with wage inflation and competitor discounting mentioned.
“Started August well”
Nothing is said about trading vs expectations! That’s the whole point of a trading update, so why miss it out? I want to know about profit, not just revenue growth.
Equity Development is forecasting 17% revenue growth to £114.5m for FY 3/2024, so it looks as if the company is tracking ahead of this so far.
EPS is forecast to grow 11% to 5.37p - I would hope there’s upside on this number, as 31% revenue growth should be flowing through better to the bottom line.
As I’ve pointed out before, profitability has been flat at 4.8p to 5.0p in the last 3 years, so there is a danger the company could be buying growth by cutting prices too much maybe?
The valuation is 18.4x FY 3/2024 forecast EPS - punchy for a low margin, highly competitive sector. If it beats forecasts though, that valuation could be justified.
Paul’s opinion - this seems a good company, and owner/management impress me on webinars -seemingly running a tight ship.
Shares look fully priced to me, but I do like the company. It’s a much better investment proposition than larger competitor AO World (LON:AO.) in my opinion. AO has a difficult balance sheet (including large warranty debits & credits), and a patchy history, and delusional management in my view. Although AO has now belatedly started focusing on trying to make a profit, and its broker forecasts are on a rising trend, so maybe I’m being too harsh?
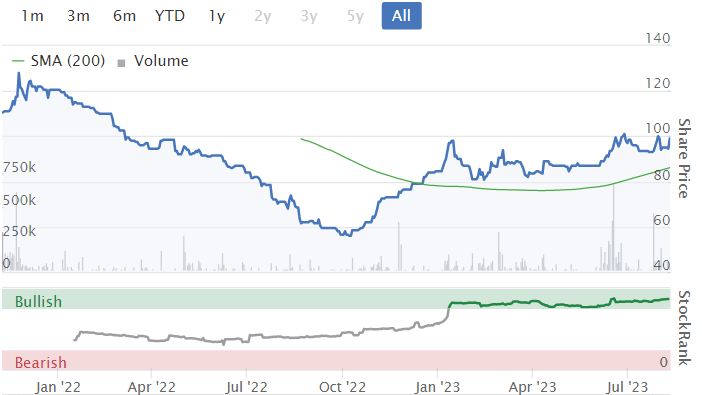
MRK shares have been recovering nicely since last autumn, bucking the grim small caps market trend -
Graham’s Section:
S&U (LON:SUS)
Share price: £23.82 (+4.5%)
Market cap: £290m
S&U PLC, the specialist motor and property financier, today issues its trading update for the period from its AGM statement on 21 May 2023 to 31 July 2023. S&U will announce its half-year results on 3rd October 2023.
This is an H1 update (the financial year ends in January).
It spends more time than usual berating the UK for its economic policies: “record levels of taxation, steeply rising interest rates, massive government borrowing, and a failure to stem the tide of incessant regulation, especially in the financial services industry”.
In another unusual statement, the Chairman expresses frustration with the S&U share price:
…protecting the quality of the Group's assets and producing responsible growth requires constant innovation and attention to detail. These produce consistently good results, although frustratingly given global investor perceptions of the UK, this is not reflected in S&U's or general stock values. Too often it feels like a tuned and trained athlete is required to continue to perform, wearing army boots on a cinder track.
Readers may have noticed engagement by S&U with investor conferences in recent years: they have been trying to get the word out, but their share price is still lower than it was five years ago.
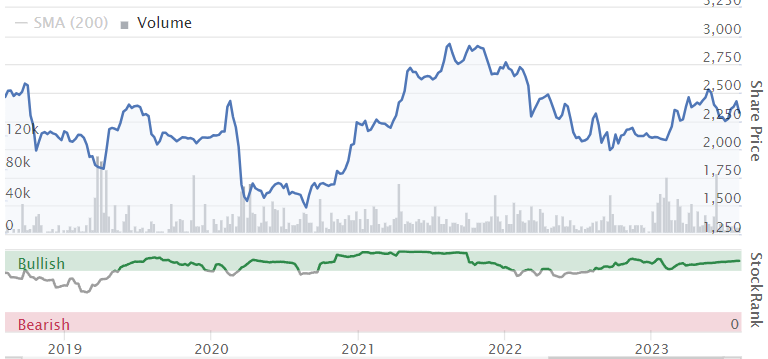
The shares trade at a moderate premium to book value, but the 8x earnings multiple might be considered tempting:

Note, however, that the “Industry” percentile for S&U’s PE Ratio in the above graphic is red: this is telling us that most Banks are cheaper! The entire UK banking industry is trading cheaply right now.
Let’s get back to today’s H1 trading update.
Advantage Finance: this is S&U’s core motor finance business.
Key points are:
In a slower and more price-competitive market year to date, advance levels for H1 23 finished 11% below H1 22.
Average customer risk score improved
Receivables are £313m, up 12% compared to a year ago.
It might seem strange that new loans (“advances”) are down, but the lending book (“receivables”) is up - this is because it takes several years for customers to repay the loans, and last year’s loans haven’t been repaid yet.
In bad news, “net interest margins have unsurprisingly not kept pace with the egregious interest rate rises of the past year”, but “strong repayments performance has also continued in the period with levels of up-to-date customers exceeding our expectations”.
Aspen Bridging: the property bridging division now has receivables of £104m (a year ago: £90m). New transactions have been fewer and smaller than originally planned, given the conditions in residential property, but “solid progress” is expected in H2.
Impairment is “below budget” - that’s good news. It was previously reported that 10 out of Aspen’s 140 loans were in default, but there was an expectation that they would be recovered.
Balance sheet: gearing has reduced and borrowings have reduced to £184m.
At the time of the AGM statement, I noted that S&U was taking a more aggressive approach with respect to their own gearing than they had before. I can’t blame them for taking their foot off the gas, even if momentarily, to help manage the risks they face in this environment.
Outlook statement doesn’t give anything away. Estimates previously published by Edison suggested PBT of £42.9m and EPS of 268.4p in the current year.
Graham’s view
The Chairman seems irritated, but I think investors should take some comfort from the reduced gearing and the cautious stance.
You might be tempted to think of the stock as being ex-growth, but it still has plenty of momentum:
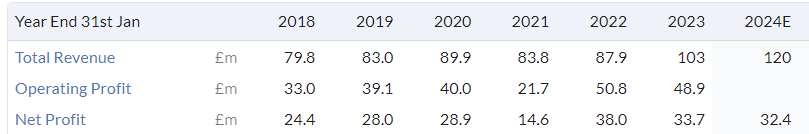
However, with the property market currently challenged, and in a cost-of-living crisis for consumers, I think it’s reasonable to have a focus on higher-quality lending for a period.
As I noted last time I covered this one, S&U is pumping out a solid ROE of 14% - 15% (depending on who you ask). Given its track record, committed management from the Coombs family who founded the company, and only a moderate premium to book value baked into the share price, I’m going to remain positive on this one. NAV per share should hit £20 early next year.
As far as the risks are concerned, I think their underwriting processes are well proven. However, they do face an exposure to rising interest rates through their revolving credit facilities. I think they are acutely aware of this, and would be quick to de-gear if necessary. But of course no investment is risk-free. As far as financial stocks go, this remains a personal favourite.
Jarvis Securities (LON:JIM)
Share price: 124.9p (-15%)
Market cap: £56m
Today’s trading update from Jarvis is a profit warning:
The Q3 quarterly dividend 2.25p is smaller than previous quarterly dividends (the most recent quarterly dividends were 3.5p, 3p, 2.5p).
The regulatory “Skilled Person Review” is starting to hurt the company’s financial performance. Things must have deteriorated since the recent H1 results:
The associated restrictions on Model B clients, has led to the loss of certain Model B clients and the corresponding revenue. In addition the costs associated with the Skilled Person review are higher than anticipated. These factors, combined with reduced trading volumes caused by market conditions, mean that the Company is now trading below current market expectations.
Net cash is £5.2m, slightly down from where it was at the end of June, but “well in excess of current regulatory requirements”.
Estimates from WH Ireland for the current year are reduced as follows. Revenue is forecast at £12.7m (previously £13.6m). Adjusted PBT is forecast at £6.6m (previously £7m). There will also be £0.5m of exceptional costs relating to the review, so actual PBT may be in the region of £6.1m.
Revenue and adjusted PBT are both forecast to increase slightly in 2024.
Graham’s view
The PBT forecast is down by 13%, so that’s the context in which we have a 15% share price fall today.
However, about half of the reduction in the forecast is due to one-off costs.
I have been positive on this stock, so perhaps I have underestimated the bear points? I provided five bull points and five bear points in July.
The way I see it, however, the difficulties faced by the company are very much transitory in nature. The Skilled Person Review will end, sooner or later, with some sort of resolution - hopefully not one which hurts the company too much.
The very quiet trading conditions are also temporary in nature. Although, you could be forgiven for throwing in the towel at this point and thinking that UK equity trading was never going to get out of this trough!
Jarvis’ X-O platform only deals in UK-listed securities and so it is unable to benefit much from shifts to US shares and to funds. It does offer ETFs and investment trusts, but funds are probably not its strong point.
The product is therefore somewhat limited and from an investment point of view, it’s a concentrated bet on a particular asset class - an asset class that is currently out of favour.
The 3-year chart illustrates the declining sentiment around JIM stock:
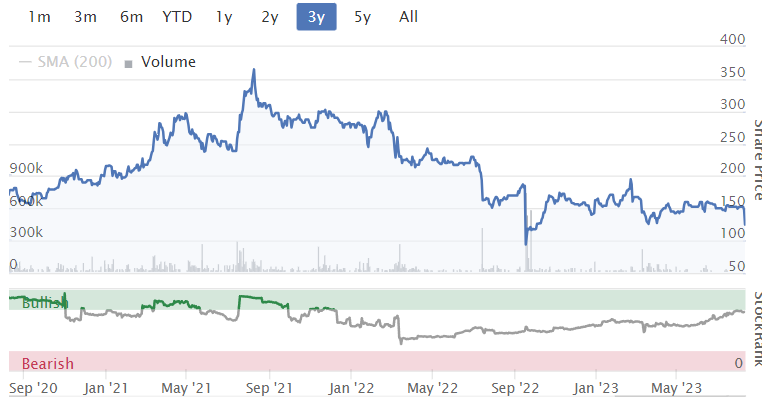
But it’s not all doom and gloom: go back to the July interim report and you’ll see that revenue was up and PBT was up, thanks to rising interest rates.
If the company does generate £6.1m of PBT this year, even after incurring some exceptional costs, that will still be significantly better than its performance every year prior to 2020.
Therefore, I’m going to remain positive on this one, as I take a long-term view. There are some problems in the short-term, yes. But for long-term investors, I continue to believe this is a quality company and worthy of further research. The latest market cap (£56m) looks overly pessimistic to me.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

34 comments
No comments here on Checkit (LON:CKT) yet so let me start. (I hold a small number resulting as a residue from the tender for Electron following the sale of Bulgin).
Today's preclose statement indicated results inline but the more interesting bit was the renewal of the contract with John Lewis (including Waitrose) "with improved pricing" and 3 new contracts with Compass under their "master service agreement".
There is a note out from Edison here.
I was struck by the comparison with US ratings:
"On an EV/sales multiple of 1.0x for FY24e and 0.9x FY25e, Checkit trades at a material discount to the UK software sector (2.4x current year sales, 2.2x next year sales) and US SaaS peers (6.7x current year, 5.6x next year). If Checkit were to trade on the UK average for FY24e, it would be worth 39p per share and moving to trade in line with US SaaS peers would imply a valuation of 89p".
I think that the key with this one is the move to breakeven. At the last IMC presentation they said that they agree with the analysts who said at that time that there was enough cash to see through to breakeven which they expect will happen in the year to Jan. 26.
CKT is also one of those microcaps with large but ficticious spreads. At around 3 p.m. it was 22/24 but I was quoted 22.25/22.5 !
Thank you for your comments on Jarvis Securities Graham, we continue to hold and when the dust dies down might add a few more.
You're welcome JASVFS - fingers crossed for you! G
I see this kind of thing quite a bit, and I find it a little disconcerting. Caledonia Mining (LON:CMCL) has a momentum score that is up by 16 points over the last 30 days (currently sitting at 62). However the stock has dropped 15% in that time and has had no positive news - so how does the algorithm have it up so much. I know the algo has its own quirks but this does seem ridiculous to me. Btw I am sure this score will change tomorrow off the back of the results today - but it still doesn't make a lot of sense to me. We all like to have good stock-ranks for our holdings - but this type of thing makes me cautious to the point of finding them often irrelevant - it may even give me a false added sense of security. I tend not to put to much attention on the stock ranks anyway - but these types of anomalous scores feel as though the algo is not working correctly all the time. Just something to think about for all my holdings - to not get complacent because a share has a high stock rank - and to regularly sanity check its accuracy.
cheers
Matt
I'll stick in my 6pennyworth, I think that if the stockrank is rising its generally a good sign but if its falling gradually its worth looking into to re-assess
NWOR National World
Yet more nonsense from David Montgomery and his huge ego and ridiculous self serving view of the world
Following the debacle of the “we might bid for Reach” group that was preposterous rubbish from the off .
Now the ludicrous RNS “we are considering thinking about maybe might be interested in Telegraaph group “
This is just a guy with a big ego trying to make himself a player whilst riding the life out if his shareholders rewarding himself and his directors with their ludicrous and grotesque hand in the pot greed.
What a muppet.
Might do an RNS myself saying “I’m maybe might think about a bid but maybe not “
Hello All,
I see consensus forecasts for Oxford Metrics (LON:OMG) have been trimmed?!
3.5p earnings now forecast for this year, 2.5p was achieved in H1, and H2 is usually stronger. This seems at odds with the interims, which were very strong.
Am i missing something?
Oxford Metrics (LON:OMG)
I dont hold but have been looking at it recently, from memory they had about half a million £ in net interest income in H1 23 , as that should increase in H2 they have not got to do much more to make that extra 1p.
Exactly. H2 Weighted so 6p could be achievable? Stocko forecasts has this on a PE of 25, which is misleading as net of cash would be more like 10/11. Why you need to DYOR! Or am I being too optimistic?
Could it be the travails of the film and TV sector impacting spend on OMG products?
Following on from yesterday's discussions regarding RM (LON:RM.)
Interesting to note that directors have been buying. Non-exec Helen Stevenson just picked up £26k worth, and the CEO £5k worth.
Not huge, and I've seen management throw good money after bad many a time, but interesting nonetheless.
With regards to Harwood/Rockwood taking the company private or forcing through a placing - yes they do have form. However you also have Aberforth, Schroders and Artemis owning the funds in trusts or collective retail vehicles that have to mark to the price to market daily, and they really won't want it going private.
Surprising that no-one has mentioned the results from Goodwin (LON:GDWN). This company is going from strength to strength under the management of the next generation of the Goodwin family.
Goodwin (LON:GDWN)
Hi Kanddas
Just a short comment from me on this one.
I took a brief look at the latest results and I am still struggling to see the upside potential here.
Yes, revenues were up significantly (+29% YOY), but any bottom-line benefit seems to have been lost through the lower Gross Margin %. Here are some recent GM %:
As a result Operating Profit was up £2m over the last year even though revenues increased by £42m.
---
I'm aware that the order book has been growing in recent years, but I recall reading that some of this revenue was due to recognised over many years (actually I think it was decades, but probably best not to quote me on that.)
I appreciate this this might not be reflective of the rest of the order book, but in any case I would prefer more profitable orders in the short term to get me more interested.
----
I know this is a favourite with PIs, but I don't quite fully understand the reasoning, at least quantitatively.
If higher profitability levels become more evident - and the order book continues to grow - then I would be much more tempted to take an opening position.
Cheers
A
Goodwin (LON:GDWN) doesn’t screen well *yet*…arguably when it does it’ll be far more expensive & is complicated to model because they’re doing multiple new investments simultaneously to move the business into a significantly bigger & better business…they don’t window dress this in the numbers but do try to explain v clearly in the text what is going on…so the text is vital to the investment case.
as an illustration here is the operating companies P& L over the last few years…key to understanding what is occurring is the significant physical expansion in the foundry (complete next month) that gives it capacity to handle multiple times the current revenue primarily for US & U.K. naval & nuclear contracts at attractive margins. This ramp up is fully underway in the current year & will allow for revenue in the foundry to move dramatically upwards…& the bulk of that output will be machined by sister company Goodwin International.
the order book is primarily for delivery over the next 2 years but the underlying programmes it increasingly represents rolls over decades eg AUKUS…so it’s the tip of the iceberg of the business they see in front of them.
looking at *last* years results in numeric terms alone will miss this, equally margin evolution is yet to be apparent as start up of new casting types is time/cost intensive …& that is ignoring the rest (c50% of profit) of the business…I’d note they’ve set up 2 new Ltd companies, one for AVD Lithex which is ramping up fast now (see the comments in the RNS)..& one for Soluform another new product .
it’s my largest position & a company I know well…it’s a special business imho… an unusual vertically integrated globally active family controlled….it reminds me of JCB
It's not me!
Are you going to get round to doing Robert Walters (LON:RWA)?
Why do Robert Walters (LON:RWA) Step Peters
FY results this morning from Zoo Digital (LON:ZOO) look excellent, though current trading negatively affected by the actors and writers strikes.
Profitable, growing, net cash and after significant SP decline, looking quite cheap?
Recent profit warning seems to have reset expectations?
AI a threat or an opportunity?
The Progressive Research analyst's report out today (available on their website and I think Research Tree) says that Zoo Digital (LON:ZOO) see AI as an opportunity rather than a threat. And maybe for now companies will prefer voice actors and translators instead of AI generated dubbing and subtitles. That might be right for now but how long before the stingy film companies decide that AI generated dubbing or subtitles are good enough for overseas viewers who have no other choice in the matter - accept the localisation provided or don't watch the film?
My guess is that at least some of the recent sell-off is due to fears about AI making ZOO's premium service obsolete.
I have held in the past but now see this as too risky. Any other views?
In effect a Profit Warning? from Jarvis Securities (LON:JIM) But it is not quantified which is unsatisfactory . Jarvis has been subject to a Skilled Person Review & states “The associated restrictions on Model B clients, has led to the loss of certain Model B clients and the corresponding revenue. In addition the costs associated with the Skilled Person review are higher than anticipated. These factors, combined with reduced trading volumes caused by market conditions, mean that the Company is now trading below current market expectations.” They still declare a quarterly dividend slightly lower but still in normal ballpark
A "Skilled Person Review" sounds innocuous, but it isn't.
The FCA will direct firms to conduct a Skilled Person Review when they have found something they don't like, or have concerns over how the business is operating.
It is not one "person" - it means you have to employ an independent FCA approved 3rd party (usually one of the regulatory consultancies or the usual consultancy/accountancy names, in this case Ocreus Ltd) to send in a team to conduct a review for the FCA. It often takes 3-6months, and you pay for it.
It often means the FCA is concerned all is not well and that your own internal compliance procedures haven't stopped it first....
Given Jarvis also agreed to further restrictions on new-client take-on and a limit on dividends you have to wonder what was going on, and whether their Model B service remains viable?
I know Graham is a fan. Maybe he will give us his perspective.
Jarvis Securities (LON:JIM) Research Tree have a new note with revised forecasts from WH Ireland. I am wtching, but may buy if goes below £1.00
I was using (LON:JIM) as a client of a broker using their model B service. I found their charges to be very high. They charged to pay out proceeds of sales and gave no interest on cash balances. I have moved away from them and so glad I did. I suspect they will lose many more clients as they are uncompetitive.
Horses for courses mbarnard, I moved to JIM's cheap and cheerful on-line service after Charles Stanley's expensive personal service costing five times as much. This was over 20 years ago when I was just starting out and choice was thin on the ground after a bad experience with a bucket shop called Grahame H Wills. I have only withdrawn cash once since then when moving house at a cost of £20, I rarely have uninvested cash in my account but If I decided to take a break I don't consider £20 for someones time unreasonable, I'm pretty sure this is a fixed fee. I use their automated on-line X-O service at 5.95 a trade where I do all the work and I think it's fair that, like Ryanair, if you want extras involving the back office, you pay for it. Cash left uninvested helps to keep costs down and no hidden charges for my ISA compared to other providers is part of this. I've held shares in JIM before I became a customer and I'm happy to remain as both. Their model B service has always seemed aimed at very occasional naive investors via building societies etc like my first ever sale via a high street bank of de-mutualised Norwich Union and has possibly been the blind leading the blind with lack of oversight from JIM leading to a complaint to FCA, strangely no one complained when prices were going up.
Marks Electrical (LON:MRK) - Marks Electrical Group (MRK) released a trading update ahead of its AGM. The company enjoyed strong trading in the first four months of its FY2024 financial year as enhanced delivery options, sustained high service quality levels and more widespread brand awareness helped the company to over 30% sales revenue growth in the period, compared with nearly 14% a year earlier. With further benefits of strong cash conversion – consistent with a proposed 0.66p final FY2023 dividend – we reiterate our fair value of 150p for the shares. Our note published this morning is here: https://www.equitydevelopment....
S&U (LON:SUS) seemed to have issued a party political broadcast which I struggle to understand. I took it as a business environment is super tough but we’re doing better than most. I continue to hold long term this we’ll run company
I laughed my socks off too but find it hard to disagree with their conclusions. From S&U (LON:SUS) RNS this morning:
Whilst the Chancellor of the Exchequer may make heroic pleas that "declinism about Britain is just wrong", the past decade has seen persistent government policies which act against a climate of entrepreneurial activity, enterprise, and growth. More recently record levels of taxation, steeply rising interest rates, massive government borrowing, and a failure to stem the tide of incessant regulation, especially in the financial services industry, have all contributed to this. The result has been 10 years of sluggish growth in the UK averaging just half a percent per annum- and a lack of faith in the free enterprise culture.
Although S&U has historically outperformed despite these challenges and will continue to do so, it does not operate in a vacuum. In such an environment protecting the quality of the Group's assets and producing responsible growth requires constant innovation and attention to detail. These produce consistently good results, although frustratingly given global investor perceptions of the UK, this is not reflected in S&U's or general stock values. Too often it feels like a tuned and trained athlete is required to continue to perform, wearing army boots on a cinder track.
Sounds like something Terry Smith would write. S&U (LON:SUS)
The environment is the environment, everyone gets dealt the same hand. Companies should concentrate on telling us how they play their hand...this sort of thing is a red flag to me. I neither agree nor disagree with it, I just don't believe it belongs in a results statement.
The S&P is up 17% so far this year so I am afraid everyone is not dealt the same hand. It is only when the pressure from UK companies becomes so powerful that it becomes a political force may things change and overcome this "declinism". It is with regret that I think such statements are necessary.
The UK is becoming more sociopolitical by the day, it's creeping in everywhere one looks.
Hmm...I think politics, sociology and economics have alway been entwined. Social media has made it more obvious. Without the above comment from Sutters I would not have looked at S&U (LON:SUS) statement.
B Corp - 1400 UK companies have signed up to this. Nothing to do with their business and providing a service to customers, it looks very socio political to me. Refusing people a bank account seems to be part of this as well.