Small Cap Value Report (Thu 10 June 2021) - DFS, BEG, IGP, CARD, ERGO, HRN

Good morning, it's Paul & Jack here, with the SCVR for Thursday.
Timing - we've covered 6 companies, and don't want to overload you, so that's it for today. We were going to look at SPE and NXR but they don't seem to have moved much in price, so there's less of a rush to report on them.
Agenda -
Paul's Section:
Dfs Furniture (LON:DFS) - very impressive Q4 order intake, and crystal clear guidance for what's turned out to be a year of bumper profits for FY 06/2021 - who would have thought that outcome would happen, this time last year?!
Notes from my briefings yesterday with Begbies Traynor (LON:BEG) (I hold) and Intercede (LON:IGP) (I hold). I'm pleased with progress at both companies, and see them as good long-term holds, probably priced about right for now.
Card Factory (LON:CARD) - I have a proper rummage through the FY 01/2021 results - which to be fair are not as bad as I feared - thanks to massive taxpayer support. Stretched balance sheet badly needs the £70m equity fundraise that the company has agreed with its banks to do on a best efforts basis. Overall, I think risk:reward looks unfavourable. I'll look at it again once trading (not very impressive since re-opening) has stabilised, and the £70m placing has been done. Until then, for me it's an avoid. Why take the risk? £225m mkt cap looks full, for a highly indebted retailer with limited online progress.
Jack's Section:
Ergomed (LON:ERGO) - strong trading momentum continues, with FY adjusted EBITDA to be 'materially ahead', although existing forecasts appear to be conservative based on historic growth rates.
Hornby (LON:HRN) - revenue growth of 28.3% in a Covid-disrupted year is creditable and the company is investing for growth, but a fair amount of further recovery is already priced in.
Paul's Section
Dfs Furniture (LON:DFS)
272p (pre market open) - mkt cap £703m
Ahead of its financial year end on 27 June 2021, DFS Furniture plc ("DFS" or "the Group"), the UK's leading retailer of living room furniture, provides the following update on recent trading through to 6 June 2021.
Strong trading performance and outlook, with fourth quarter order intake to date up 92.1% on FY19, demonstrating the strength of our 'Integrated Retail' operating model
That’s a staggeringly good Q4 order intake, sensibly compared with FY19, ie. 2 years ago, not the meaningless comparison against FY20 when lockdown 1 was at its height. I’m pleased to see this comparison with 2019 becoming the norm for most companies reporting, as it helps us understand the underlying picture. Providing of course that the business hasn’t materially changed (e.g. acquisitions/disposals), which would need to be stripped out to give a like-for-like comparison. A footnote to this statement indicates that Sofa Workshop has been excluded from the 2019 comparison period. Sofa Workshop was disposed of by DFS, hence removing it from performance figures is correct, to give us the true underlying trading figures. All good so far.
Q4 +92.1% order intake - driven by pent-up demand from lockdown in Q3, and increased consumer spending on home improvements.
Online sales in Q3 (when showrooms closed) was up 222.5%. Since re-opening of the showrooms more recently, online sales have settled at c.19% of the total, which I find impressive, considering many people want to see, touch, and sit on (where appropriate) furniture before buying.
H2 to date (23 weeks) - total order intake up 14% on FY 06/2019 - this is really impressive - DFS has achieved this strong result despite its showrooms being closed for a lot of that period! Although there is a time lag between orders being taken, and product being built & shipped, as things are made to order. So there could be an element of revenues being shifted from FY 06/2021 into FY 06/2022, which doesn’t really matter in the long run of course, but might skew the figures a bit.
Profitability - all important, and it looks good -
(Almost) full year (49 weeks) revenues are up 10.4% on 2019, which I find remarkable, given this period includes 2 extensive lockdowns.
Bumper profits are indicated - well ahead of pre-pandemic levels -
On course to achieve FY21 underlying profit before tax**** of at least £105m
****Underlying profit before tax and brand amortisation
Unfortunately it doesn’t tell us what broker forecasts are, and I can’t find any broker notes. However, the StockReport gives analyst consensus of £45.8m profit after tax for FY 06/2021. Add back tax at c.20%, and I get to £57m pre-tax profit. So at least £105m looks a large beat, assuming those figures are in the right ballpark.
Actually, that seems to conflict with what the company says today, namely -
We are on track to report at least £105m of FY21 underlying profit before tax****, slightly above the 'medium' scenario discussed in our interim results
Therefore it looks like the forecasts used on the StockReport could be out-of-date unfortunately - I've raised a green blob to request this is looked into.
Guidance for next year - as I suspected, the company says some of the recent bumper order intake will be delivered, hence recognised as revenue in FY 06/2022.
So I’m a little confused as to why the latest guidance is for profits to reduce in FY 06/2022? This could be because business rates are set to resume. It also mentions margin pressure -
Retail margins are expected to be lower in FY22, given manufacturing cost inflation under constrained output capacities and rising raw material prices
FY22: Underlying profit before tax**** range of £66m-£96m, with a medium-case scenario of £85m PBT**** (+70% relative to FY19)
Even better, DFS gives us 3 scenario outcomes for profit in FY 06/2022. This is absolutely brilliant, and I wish all companies would do this. It’s nonsense to just give a single figure for forecast profit. A range of scenarios like this below, makes much more sense. Companies have these forecasts internally, so why not share them with investors? Well done to DFS for publishing this, it's fantastic, and makes me more likely to want to buy some shares, as there's less guesswork involved when proper guidance is given by the company -
.

.
New sites - the above guidance includes 16 new showrooms expected to be added by end FY 06/2022, compared with FY 06/2019, hence why total order intake is higher than the LFL order intake above.
Supply constraints - seems to only be causing delays, rather than anything more serious -
Our revenue growth in FY21 has however been constrained by sector-wide pressures on supply chains from raw materials availability, container shipping delays (including the effects of disruption in the Suez Canal), and Covid-19 disruption of factory production. Therefore the majority of the revenues and profits from our strong final quarter of trading will be recognised in our FY22 financial year.
Dividends - a 7.5p final divi is expected to be declared in Sept 2021.
Dilution - due to its awful, painfully weak balance sheet, DFS was forced to raise more equity during the pandemic. Therefore, note that the share count is now 258.4m, well up from the pre-pandemic level of c.215m. That curtails the upside per share.
Whereas smaller rival Scs (LON:SCS) (I hold) which has a bulletproof balance sheet, didn’t need to raise fresh capital, and should therefore have better upside per share. Plus SCS shareholders could sleep soundly at night during the pandemic, whereas DFS at times looked to be in a dicey position. I like to make money on shares without having any worries about insolvency.
My opinion - DFS is a really good business, no doubt about that. It’s performed remarkably well in such a heavily disrupted year, showing that lockdowns have not impacted demand for furniture, just caused delays which are quickly recouped when showrooms re-open. Plus people spending more time at home, seems to drive up consumers desire to revamp our homes.
My balance sheet concerns remain, and the weak finances resulted in material dilution during the crisis, showing the folly of running any business on a negative NTAV balance sheet (substantially so in this case). Management clearly have not learned any lessons from this, as they're re-starting dividends.
I think Scs (LON:SCS) is a much better, lower risk proposition as an investment, since it’s sitting on pots of cash, and trading well, at a bargain rating. There should be read-across from upbeat figures today issued by DFS. Hence DFS being up 12% at the time of writing, looks justified from this strong update today. Read across to SCS (I hold) hasn't happened, and it's down 1%. There's an obvious mismatch there, so I'll be topping up SCS when funds permit.
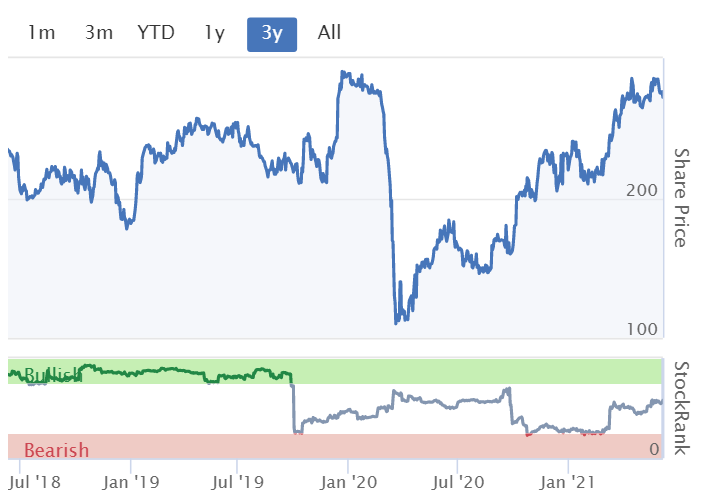
A remarkable share price recovery at DFS, which I think is justified by strong performance.
.
.
Card Factory (LON:CARD)
65.2p (down 2.5% at 10:49) - mkt cap £222m
Card Factory, the UK's leading specialist retailer of greeting cards, dressings and gifts, announces its preliminary results for the year ended 31 January 2021 ('FY21').
As regulars here might remember, my main concern with CARD is its weak balance sheet, with too much bank debt. It has limped along from month to month, getting bank covenant waivers on the last day of each month - a very precarious situation, that in normal markets would have smashed the share price down. However, we’re not in normal markets, and the market has seemed happy to ignore the insolvency/dilution risk, and excessive bank debt.
More recently, a refinancing was announced. I thought it would be good to get a different perspective, as I might have become biased, so Roland covered the May 2021 bank refinancing here on 21 May 2021.
The banks agreed to provide £225m facilities, until Sept 2023. Net debt was £110m on 16 May, although Roland reckoned that is likely to rise as business resumes, and when creditors are normalised (he's right).
An equity fundraise of £70m is on the cards, but not compulsory. There seem to be penalties if it’s not done - understandable, as the bank debt would be more risky without an equity placing.
Trading was reported as above expectations, but personally I wasn’t impressed. I like to see pent-up demand causing a big rise in revenues after re-opening (as we’ve seen above with DFS). That was not the case at CARD, with revenues reported on 21 May as having been marginally down on 2019.
That’s the background, so let’s move on to today’s results/outlook.
Key figures FY 01/2021 -
Revenue down 37% to £285m
Underlying profit before tax £(15.2)m loss (LY: £67.2m profit)
Underlying EBITDA £47.0m (LY: £125.9m)
Ended the year with a £35m reduction in net debt to £107.7m, 2.3x leverage (EBITDA), achieved by stretching other creditors
Poor numbers obviously, but no surprises given the major disruption caused by the pandemic.
I wonder how aggressive they’ve been with the “underlying” adjustments? Actually, there are hardly any adjustments between underlying, and statutory PBT, so this is fine. Always worth checking though, especially at financially distressed companies.
Remember that the company has benefited considerably from Govt support schemes like business rates relief of £18.1m, and JRS of £31.4m - huge amounts. Future years will see that removed, so revenues need to recover a lot, just to get back to breakeven. Offsetting that a little, I imagine lease renewals would be coming in at reduced rents, but that takes years to play out. Plus we have wage inflation to think about.
The hospitality sector is having widely publicised trouble getting staff back from furlough, and I imagine retailers may well face similar problems. After all, what would you rather do? Stand around all day behind a till, having to deal with the revolting British public, trying to stop them nicking things? Or whizzing around in a van or moped, delivering parcels for Amazon, or the local takeaways? Some people might prefer the latter, especially in the summer, I would, if unemployment loomed!
Current trading/outlook - seems somewhat underwhelming to me - when last reported in May, they said trading was ahead of expectations - not any more -
The strong initial pent up demand has steadied and our performance since reopening has been in line with expectations…
… The business is likely to continue to face increasing National Living Wage costs amongst other cost pressures. In addition, the full impact of Covid-19 on the short to medium term performance of the business is unclear. However, the business is operating close controls over its cost base and liquidity in order that it emerges from this crisis on a strong footing.
Equity raise - doesn’t sound particularly pressing, but also perhaps indicates that shareholders may not be in a rush to commit fresh money on generous terms?
The big risk with this share is that an equity raise might have to be discounted heavily to get it away. As we’ve recently seen with Revolution Bars (LON:RBG) (I hold), the institutions don’t like being asked to get the bank off the hook, and can demand a big discount, thus diluting the small shareholders -
As previously announced, Card Factory intends to use its best efforts to raise net equity proceeds of £70m in due course, subject to independent advice and prevailing market conditions, to facilitate an early reduction of overall debt prepayments….
Following the impact of Covid-19, the Board intends to prioritise de-levering the business, which will impact the distribution of cash to shareholders in the short-term, as reflected above. Given the inherent uncertainty around the recovery of the business following the extended lockdowns experienced to date, and the risk of any subsequent lockdowns that may be imposed in the future, the Board will consider various options to ensure the key stakeholders of the business are protected as much as possible in these uncertain times and will look to provide a further update on capital policy as trading conditions become clearer.
Importantly then, although no dilution has happened as yet in the pandemic, it’s very likely to happen, and needs to be factored into valuation measures. We have no idea what the terms might be. It could be heavily dilutive if the Instis demand a deep discount, or it could sail through at or near the current share price. It’s that uncertainty which puts me off this share completely. I don’t want to have to guess, making assumptions that could turn out to be completely wrong. The heavy dilution at Revolution Bars (LON:RBG) (I hold) has made me super-cautious now, and am really keen not to take on any other shares where there’s dilution risk.
See further down, where I sketch out some example numbers & the dilution resulting at various prices.
Net debt - £144.9m of this relates to lease liabilities, which as usual I’m happy to ignore, because it’s not debt, it’s future years’ operating costs. The balance of £107.7m doesn’t seem too bad, but how much have other creditors been stretched, and what sort of level would it rise to once business has normalised? This note is helpful too, on seasonality -
It should be noted that net debt at the half and full year period ends is lower than intra-year peaks, reflecting usual trading patterns and working capital movements.
Balance sheet - NAV is £206.5m.
However, intangible assets are huge, at £320.3m, which I always write off.
That arrives at NTAV of negative £(113.8)m - pretty awful.
Even the £70m placing would not fully sort that out - deduct say £3m fees, and £67m net raised, would reduce the NTAV to a still negative £(46.8)m - still fairly bad.
That said, CARD does have a capital-light business model, and its inventories are low cost (greetings cards are notoriously very high margin), plus there’s little in receivables because it sells for cash to customers, before having to pay creditors usually.
Therefore it doesn’t actually need a strong balance sheet, but even so the excessive dividend payments of the past, whilst overly-relying on bank debt, was clearly a folly. In this case, management does seem to have learned from that, and are now prioritising debt reduction, probably having their wits scared out of them by dangling on the edge of the solvency precipice for a while now.
Normalised working capital - note that inventories are £18.0m down on a year earlier (pre-pandemic), so we can safely assume this would return to a similar level in future.
Creditor stretch is evident in “Trade and other payables” line, which should have gone down (to reflect lower inventories), but is actually up, Y-on-Y by £12.4m.
Put those 2 together, and it looks like working capital has been stretched by c.£30m, so I would add that on to reported net debt, taking us up to normalised net debt of £107.7m+£30.4m = £138.1m. The company indicated above that seasonal peaks would take this figure higher, I don’t know by how much.
My conclusion is that the £70m placing is very necessary, and needs to happen, but that’s probably enough to get the ship back on an even keel.
Although that depends on future trading. Will it return to previous levels of profitability? Personally I think that’s unlikely - costs are rising, and a certain amount of High Street footfall has probably gone forever, we just don’t know how much.
Future dilution from a £70m fundraise - here are my workings:
Current position: 341.6m shares in issue, at 66p share price = £225m mkt cap.
Fundraise of £70m is needed. We don’t know the price, that’s decided by Instis. Here are a range of possible outcomes, and resultant dilution:
66p per share: 106.1m new shares issued, 31% dilution
60p per share: 116.7m (34% dilution)
50p per share: 140.0m (41% dilution)
40p per share: 175.0m (51% dilution)
33p (50% discount): 212.0m (62% dilution)
EDIT: I've expressed dilution as the % increase in the share count. End of edit.
So current small shareholders are facing likely dilution anywhere from 31% to 62%, and you’ve got no idea what the price will be, assuming it’s within that example range of the current price, down to a 50% discount. Will a sensible sized open offer be included, if the placing is deeply discounted? Again, we don't know.
Remember dilution is important, because that’s taking away some of your future upside on the share price, in return for securing the business’s finances - lower risk, but lower returns for shareholders.
My opinion - I’ve tried to look at this with fresh eyes, and be impartial.
To be fair, the figures are not as bad as I’d feared.
It’s historically been a good, cash generative business. With lower footfall likely, and higher costs, I don’t see it returning to previous levels of profits/cash generation.
There’s not much in today’s update about online, and CARD has been largely left behind by newer competitors such as Moonpig (LON:MOON) - they’ve eaten CARD’s lunch, under their noses.
I’m happy to look at CARD again, once it has properly refinanced with the £70m placing. Until then, I can’t see enough upside to justify taking the risk of heavy dilution.
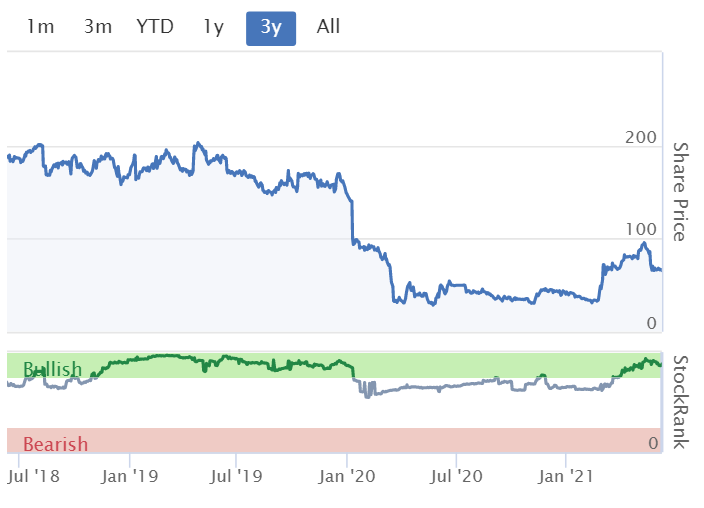
Note that CARD was struggling before the pandemic struck - it had already halved from c.200p to under 100p before covid. More recently, the re-opening frenzy amongst investors clearly chased the price too high, and personally I cannot see any reason why this share is over 50p, I think that would be generous. The future returns depend heavily on how the refinancing happens.
.
.
Begbies Traynor (LON:BEG)
(I hold)
143p - mkt cap £214m
Results presentation - Equity Development organised a results webinar yesterday, which I attended.
Here is the recording, it's interesting, so worth a watch -
I mainly listened & soaked it in, but did jot down a few key points as follows -
- Cumulative earnings growth of +20% p.a. - acquisitions, plus some organic growth despite insolvency market being suppressed due to Govt support schemes - necessary at the time, but likely to be withdrawn & tip a lot of companies over the edge - so insolvency market (counter-cyclical) is expected to improve
- 70% of BEG’s business is counter-cyclical, 20% cyclical, and 10% uncorrelated to the economy
- Aiming for 50:50 counter-cyclical:not in future
- Wide range of services in insolvency, accounting, and property
- Growing dividends, and improving divi cover
- Property auctions have all moved online
- Recent acquisition has a big profit-based earn-out - self-funding earn-outs
- Routine cases are £10-100k fees, so a nice spread of smaller jobs, reduces risk, a few larger insolvency jobs. Cases typically 2-3 years in duration, or 5 years for larger cases.
- EPS (actual, then forecast) table shown progressing: 5.7p, 6.8p, 9.2p - strong forecast growth from big acquisitions made recently (hence PER is about 15, which seems about right to me, not expensive).
- Lots of IT projects done, to become paperless, instead of old paper files. Hence working remotely has been possible. More IT projects in the pipeline
My opinion - Begbies is making encouraging progress. I think the recent rise in share price is fully justified by the strong earnings growth & positive outlook. Very strong owner/manager in Ric Traynor, who has demonstrated ability to make multiple acquisitions at good prices, and enhancing earnings per share.
I think the current share price looks about right, but for me it’s a longer term coffee can type share, that I reckon should deliver respectable shareholder returns in the years to come.
Intercede (LON:IGP)
(I hold)
110p (up 5%, at 09:55) - mkt cap £63m
This cyber-security credentials management software company is doing results presentations, with an InvestorMeetCompany presentation today at 16:30 - well worth attending.
I got a slot yesterday to go through the results presentation that will be the same slides as in today’s IMC. There wasn’t a lot new, and remember that results presentations are just re-hashing the results RNS, but in a more readily digestible fashion. I like hearing management talk about the company in their own words, and having the chance to ask questions to clarify things I don't fully understand.
A few key points -
- Good revenue growth in core USA market, was +14%, +15% at constant currency
- I queried the nature of licence revenues - are they subscription, or perpetual? They’re mainly perpetual, i.e. one-offs. So company has to keep winning new business to generate licence revenues, but at £2.3m this was only 21% of revenues
- Recurring/repeating revenues make up the other 79%, being support & maintenance, plus bespoke professional services which is regular income
- Recurring/repeating revenues now cover pretty much the whole cost base - a good position to be in, and greatly improved from the past - these are “incredibly sticky” revenues
- “Client list to die for” - and big clients use IGP extensively internally, not just in niche areas - some clients have >100k user licences
- Covid has delayed pipeline, not reduced it - could be some catching up
- IGGP traditionally at top end of market, now growing into much larger middle market, but not interested in low margin SME bottom end
- Convertible loan notes - 12 of 13 holders have converted into shares, and are long-term supportive holders, not flippers
- Code - very few bugs, outages of MyID platform almost unheard of - very stable
- Growth of 6% in FY 03/2021 would have been >10% without covid
- Q - I queried how much growth the team can cope with? A. Very little of the work is related to volume of clients. Can switch on a new client in an hour after they sign up, as MyID is now an off the shelf product. So growth potential is not limited by staffing
- Weaker dollar will have more of an impact this year FY 03/2022, hence why Finncap forecasting modest growth this year
- Strong end to the year, as stated in results RNS
- Partners - trained in how to use, setup, integrate, and sell IGP products. Encouraging, e.g. hoping large Guidehouse deal is first of many larger deals
- M&A - probably the biggest change in emphasis - it seems IGP is now actively looking for acquisitions, because the sector is consolidating, “no reason we can’t be a consolidator”. That does introduce risk of course, if they mess it up, but I rate mgt highly so am pretty confident they won't.
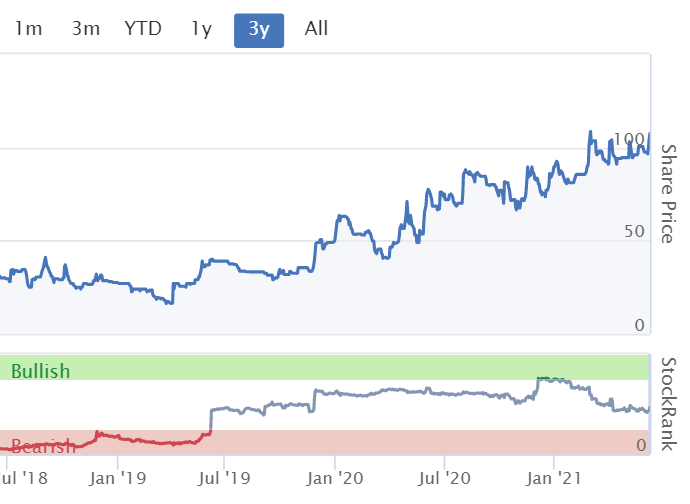
My opinion - I’m happy with progress here. I really rate management at IGP, because they set out a clear turnaround strategy 3 years ago, and have delivered what they set out to do. That’s the crux of small cap investing - backing the best management, at companies with good potential.
I think the share price looks about right, neither expensive, nor cheap. So for me it remains a long-term hold (I’ve been in since mid-2018, and see no reason to sell, because things are working out well).
.
.
Jack’s section
Ergomed (LON:ERGO)
Share price: 1,200p (pre-open)
Shares in issue: 48,790,681
Market cap: £585.5m
(I have an interest in this share)
Ergomed (LON:ERGO) is a services provider to the pharmaceutical industry that has, over the past couple of years, refocused its efforts away from the co-development of new drugs and towards running drug trials and monitoring newly developed treatments for adverse effects.
It has been a highly successful change so far, as the company is now growing into a large market with lots of organic demand. The services side also benefits from lower R&D costs and less predictability.
The share price reaction has been impressive.

It has paused for breath recently. Earnings grew by 45% in FY21, but earnings growth for the year after is expected to be a more modest 13.3%. This would be quite some slowdown, so it’s possible that these forecasts are conservative.
Indeed those forecasts have been steadily increasing, so there’s always a chance that Ergomed’s growth prospects are not being adequately reflected.

The group says it has made a ‘strong start’ to 2021, building on its momentum from the preceding year.
Its strategic transition to a services-based business model is now complete but the company remains busy. The Ashfield Pharmacovigilance business is now fully integrated and Ergomed's pharmacovigilance division continues to experience strong growth in revenues ‘in line with prior trends’.
In the CRO business, integration of MedSource, which was acquired in December 2020, is progressing well. The rest of this business is seeing ‘further acceleration in the growth that resumed in the second half of 2020’.
The two acquisitions noted above are helping Ergomed to expand its operational presence in the important US market. There’s expansion in other markets as well, including Japan, where ERGO has recently announced a new operation. This is the fourth largest pharmaceutical market in the world.
Impressively, at this early stage, the group comments:
With continuing strong sales and order book growth, solid trading in the first months of the year, effective cost management and acquisition synergies, the Board currently expects adjusted EBITDA for the full year to be materially ahead of market expectations. Reported revenues for the full year are expected to be in line with market expectations, notwithstanding a higher proportion of US dollar denominated revenues leading to some FX headwinds.
Conclusion
It’s impossible to fault Ergomed for its strategic pivot, ongoing execution, or the size of the opportunity it has identified. It seems as though pharmaceutical companies the world over have an appetite for the company’s high-quality, outsourced expertise.
The only real quibble is valuation.

When high growth companies become ex-growth companies, there can be a nasty de-rating. That certainly doesn’t seem to be the case here though, with Ergomed having continued to grow through the pandemic and already beating expectations for the current financial year.
I wouldn’t bet against this trading momentum. The US acquisitions and its expansion into Japan should yield further strong growth opportunities.
Perhaps you might argue that the easy rerate has happened now, with the company’s strategic transition complete. Some might find it’s better to journey than to arrive. But if you just read through the recent updates, there’s no real reason to sell beyond that.
2020 saw Ergomed grow its order book substantially while other companies fought for their lives. This order book stood at an all-time high of £193m by the end of 2020, up 55.5% year-on-year, providing solid revenue visibility for FY21.
There is also scope for ongoing M&A as Ergomed continues to grow into the pharmacovigilance and CRO markets. Reputational risk is key here, and there is a chance competition could intensify, but these pharmaceutical companies must trust their outsourced partners. Ergomed is building an enviable track record in this regard.
Some stocks deserve to be bought and held for the long run and today’s update shows that, if you can handle the high rating, the Ergomed story could have some distance to run yet.
Hornby (LON:HRN)
Share price: 61.32p (+3.93%)
Shares in issue: 166,927,838
Market cap: £102.4m
Hornby (LON:HRN) develops, produces, and supplies toy and hobby products through a network of hobby specialists, retailers, and its own websites. Some of its brands are verging on iconic status, such as Scalextric, Airfix, and Hornby’s own train sets.
The group has been battling declining revenues for some time now and is firmly in ‘turnaround’ mode.

But it has a very experienced turnaround/value specialist as its major shareholder in the form of Phoenix Asset Management. The shares are tightly held, with the top ten shareholders accounting for c93% of shares in issue. Phoenix holds just under 75%.
The central sticking point for me here is the current valuation. With 167m shares in issue, today’s market cap is about £102.4m on £48.5m FY21 revenue and FY21 net profit of £1.36m (helped by an income tax credit of £1.02m).
Back in March 2011, it looks like the market cap was around £53.5m with revenue of £63.4m and net income of £2.86m. Half the price for 31% more sales and more than double the profits.
Today’s valuation is already pricing in quite a lot of profit recovery and a degree of revenue growth. But then again, with the advent of internet retail, perhaps Hornby faces a fundamentally more attractive opportunity?
Highlights:
- Revenue +28.3% to £48.5m,
- Operating profit up from £2.8m loss to £0.6m profit,
- Underlying profit before tax up from £3.4m loss to £1.5m profit, reported PBT up from -£3.4m to £0.3m
- Underlying basic earnings per share up from 2.57p loss to 1.36p of earnings,
- Net cash of £4.7m, down from £5.9m.
Hornby maintained market prices in the year and managed to improve the gross margin. Trading terms have been ‘aligned to the collaborative support provided’. It’s a creditable result given the disruption to the retail industry.
Revenue growth of 28.3% is also encouraging. The company says:
Despite the many challenges to the Company caused by Covid-19 the old adage that people turn to hobbies in times of recession proved correct and sales increased across almost all channels and brands except concessions that were closed due to lockdowns for the majority of the year.
It also adds that it gained a lot of new customers over lockdowns. Just how many of these stick remains to be seen but so far Hornby says that the demand continues despite lockdowns easing.
The new product development cycle is established and Hornby is working on its 2023 product ranges. New product investment is increasing and ‘significantly more new releases and ranges’ are planned.
Regarding Covid, the group comments:
Fortunately, a proportion of our product sales were already via e-commerce and we have been able to strengthen the channel as our logistic facility has remained operational under strict distancing protocols and we continue to dispatch goods. Similarly, our retail customers have implemented e-commerce systems and were better prepared to trade in later lockdowns.
Brexit has had an impact, leading to ‘countless importation difficulties’ and fourth quarter sales were affected. As the UK figures out how to trade profitably with neighbouring markets, this could transform from a headwind into a tailwind. For now though, it appears to remain the former.
And we have the (by now obligatory) comment on shipping prices:
There are still shipping delays from our supply chain with container shortages. Shipping costs from our factories are three times what they were previously. It would appear that the shipping companies favour these higher prices; they are in no rush for a return to past pricing levels. We anticipate that some normality will return in 2022.
Segments
Third party sales by the UK business of £37.4m grew by 31% in the year due to improved choice of products on offer and a significant increase in direct sales via the website.
The European businesses generated sales of £5.9m, down a percent as a result of Brexit complications. The European operations continue to be loss-making.
Sales in the US business of £5.2m increased by 60%. The trading loss of £0.3m compares to a £1.0m loss in last year. Hornby says this is a key market for future growth.
Capex
Property, plant and equipment (PPE) increased year-on-year by £2.5m to £6.7m as a result of increased expenditure in tooling for new products and technologies. Overall investment in new tooling, new intangible computer software and other capital expenditure was £5.0m (2020: £2.7m).
Finances
The facility with PNC is a floating facility capped at £12m with a margin of 2.5‐3% over LIBOR.
The Phoenix Facility is a £9m facility with a rolling three-year term and attracts interest at a margin of 5% over LIBOR on funds drawn. Undrawn funds attract a non‐utilisation fee of the higher of 1% or LIBOR.
The balance sheet looks fine, with net assets of £38.3m and net tangible assets of around £31m.
Net cash from operations has swung from a £3.9m outflow to a £4.2m inflow and capex has increased from £2.5m to £4.2m.
Conclusion
Hornby looks to be doing a lot of things right. It is investing in new product development and will release more product ranges. It is investing in technology and tooling. Revenue and capex are growing. Management anticipates increasing demand and more online direct sales.
Sales since the end of March 2021 are ‘in line with expectations’.
As for the FY21 results, 1.36p of earnings translates into a PE ratio of 45x. The underlying earnings per share does not appear to strip out the £1.02m tax credit, which is responsible for around 40% of the underlying profit figure used in the calculation.
There is a decent amount of further recovery priced in at these levels. A lot depends on what a fully recovered Hornby looks like, and how much upside there is from here in terms of revenue and margin expansion.
The global toy market is vast so perhaps there is scope to significantly improve upon its historic levels of trading. That is what the company will have to do in order to continue creating value for shareholders at these levels, in my opinion.
So what is the size of the market for these kinds of hobby products?
On the one hand, Hornby looks to be priced quite aggressively considering where it is in its turnaround and the trading figures it is generating.
On the other hand are some valuable brands with a market opportunity that could be larger than it was a decade ago due to the widespread adoption of online purchasing.
But to what degree are these brands a UK-centric phenomenon? Overseas sales currently represent 23% of group revenue, down from 24% in the prior year owing to stronger UK growth. Perhaps this proportion can be increased, or perhaps other markets have their own nostalgic hobby products.
There is plenty of detail in the accounts and talk of a long term culture. This is a company that is passionate about its products and customers, and boasts brands with a long heritage. So there is value, and perhaps the mindset and financial backing to unlock that value.
Ultimately though, I would hope for a more modest market cap before buying into the turnaround story as risks remain and I wonder if the upside might be limited from here.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

53 comments
Oh how right you are Card Factory. Management have a lovely philosophy of paper to customer card production but they have squandered their capital on rolling out shops and ignoring online presence and advertising. Shame.
What is the fixation with Card Factory (LON:CARD) and Dfs Furniture (LON:DFS) - we want GLOBAL Britain and sofas and paper posted items are not on my SIPP portfolio - neither is watching the Chase.
Avon Rubber (LON:AVON) - surely there is some demand for their offering.
GLOBAL Britian
I too want Global Britian but I think we shall have to make do with Card Factory (LON:CARD) and Dfs Furniture (LON:DFS)and our children riding bikes for Deliveroo: LON: ROO or Dominos Pizza (LON: DOM) .
Go West young man for the likes of Square (NYQ:SQ) or KLA: (NSQ:KLAC): you won't find it in Global Britian!
Bonitabeach
Disclosure: Long Square (NYQ:SQ) and KLA: (NSQ:KLAC) .
Wondered if there were any thoughts on the formal offer made by management for Cambria Automobiles (LON:CAMB) that came out late yesterday afternoon? (and in particular the alternative being offered to the 80p cash offer). Here’s a post I logged on yesterday’s SCVR that might have slipped through the net.
——————————————-
“Details of the Cambria Automobiles (LON:CAMB) MBI emerged late this afternoon.
https://www.investegate.co.uk/...
In addition to the previously flagged recommended cash offer of 80p a share there is also an alternative (with strings attached) that will allow investors to convert into shareholders in the bidco. The strings are, at least, that the conversion shares are non-voting and limited to not more than 20% of the new share capital of bidco. Also the new shares will not be listed/readily tradeable (at least initially). At face value it’s not an especially attractive alternative but there may be more to it when full details emerge.
Gus.”
LON: BEG good summary as always, Paul
For those who missed it live , here is link to recording (including investor Q&A) :
https://www.equitydevelopment....
Thanks for the link to the BEG presentation, Andy.
I've embedded the Begbies Traynor (LON:BEG) video into the main article above now.
Regards, Paul.
The good trading at Dfs Furniture (LON:DFS) implies good licensing revenues for French Connection (LON:FCCN) which is in desperate need for high margin licensing income to offset what must still be a heavily lossmaking retail business in the first few months of this calendar year.
(I hold FCCN)
re card factory i often see dilution stated as %age new shares represent vs current issued but surely it should be based on the resultant %age held by the current shareholders post the raise?
so using the 66p example current shareholders hold 76.3% of the issued cap post raise so the dilution is actually 23.7% not 31%
Sure, you can look at dilution either way, there's no standard format.
I like to see how much the share count is being increased by, so that's the figure I used in the report above.
In my view, brokers like to show the % of total enlarged shares in issue from a placing, because it makes the dilution appear less severe!
P.
EDIT: you got me thinking, Jonathan, so I've just worked out how much EPS would fall by, for a 31% enlargement of the share capital. That would result in a 24% drop in EPS, so I'm now leaning towards your way of looking at dilution, because it shows how much EPS would drop by in % terms. Thanks for flagging this point!
Scs (LON:SCS) Dfs Furniture (LON:DFS) (I don't) & Dunelm (LON:DNLM) (I hold)
No-one seems to be talking about the elephant in the room - Inflation.
My company supply raw materials to UK based suppliers of both these companies. Our prices have increase circa 30-40% from lows last year, partly as a result of higher shipping costs (which are not going away) but also as the oil based raw materials have recovered with the oil price. Simple supply at the required quantities continues to be a challenge.
As a result of forward purchase contracts by our clients, these increases have been masked so far and aren't reflected in the figures presented by £DFS. Although, make no mistake, tough buying stances by these companies won't cut it and these increases in many components that go into a sofa or bed or scatter cushion, etc will need to be passed on.
These companies will then have a choice - either suck it up or pass it on to the consumer. Probably a mix of both will happen but will this impact on volumes and therefore profits? Make your own opinion...
To be fair, Dfs Furniture (LON:DFS) did mention cost pressures today, which I flagged up in the main report above. They said they're facing margin pressure, as you suggest.
Very fair, apologies... but RPI is running at 2.5% currently and inflation of their components perhaps 10 times that, without being sensational.
However to be balanced, with imported sofas facing the same inflationary pressures and ocean freight issues, maybe clients will pay the increases to get what they want in time. After all, they won't be having their 2 weeks in Benidorm in the near future, so will have cash to splash!
"Scs (LON:SCS) Dfs Furniture (LON:DFS) (I don't) & Dunelm (LON:DNLM) (I hold)
No-one seems to be talking about the elephant in the room - Inflation."
Well the room will need a pretty large sofa then, won't it?
Sorry...
is £CPX too small to cover here? I've seen it mentioned numerous times on the 100 bagger thread
Hi Josh,
Cap Xx (LON:CPX) looks similar to that other micro cap you mentioned yesterday - tiny company, loss-making every year.
I've read through today's short trading update from it, but there's nothing I can say about it - more losses, on revenues of only £2.3m. It seems to be Australian.
What do you want me to say? There's nothing for me to analyse!
Order book looks good at 127% up on 6 months ago.
It's taking legal action against Tesla in Delaware. How much is that going to cost?
It's way too speculative for me. We're mainly focusing here on proper companies that make profits, or are not far off. Not trying to find jam tomorrow punts that might come off. You can make money in a bull market on this kind of speculative micro cap, but it's just not what we do here.
Good luck with it!
Regards, Paul.
Cap Xx (LON:CPX) - my 30 second look says;
- Continually issuing new shares
- Never made a profit
- Z score zero
- Bankruptcy risk - huge
- plenty of debt
- virtually no cash
- a stock rank of 4 and a Quality score of zero!
etc etc
Good luck with this one.................I'll keep hold of my money thanks.
Encouraging update from DKL! (I hold)
https://twitter.com/DekelAgriV...
Unloading more cashew nuts purchased for processing. A sort of cash & carry for cashew nuts.
They speak 78 different languages in the COTE D'Ivoire. Not quite sure if this is in French or a mixture. They have been working on Cashew processing plant for a while and hope to have it operational in Q2 (electricity connection permitting, hope its not EDF) and compliments their Palm oil asset which is continuing to do well with stronger pricing which should produce a material uplift in earnings this year.
Been put off by the management pay which is excessive
As usual, thanks for the write-ups Paul & Jack.
Re DFS - I'm not sure how large their liabilities have been but they did have a significant problem with PPI mis-selling. Now that the timebar should be in full effect maybe this will help boost their balance sheet since they're not bleeding anymore (most people given until August 2019 to complain, but I was still seeing a backlog of exceptional circumstances complaints until as late as March 2021)
On a non-small cap note, LON:CMCX has just reported stellar results. EPS up 104% and a lovely final dividend of 21.4p. what i particulalry like is they have given guidance for 2022 expecting revenue to be ~330m (2021 409.8m, 2020 was 252m, so an expected increase of 30% from 2020). it was clear the amount of trading this year was a bit of a boom - so its great to have some clarity as to expectations.
Cmc Markets (LON:CMCX) results did indeed look very good and well ahead of consensus expectations shown in the Stockopedia Stock Report. The reaction of the market in terms of share price was muted with little change. Perhaps the market wasn’t convinced by the bullish outlook believing instead that once the pandemic is over CFD trading and the like will revert to a more normal level. I guess we will have to wait and see.
RE: Cmc Markets (LON:CMCX)
The reaction of the market in terms of share price was muted with little change. Perhaps the market wasn’t convinced by the bullish outlook believing instead that once the pandemic is over CFD trading and the like will revert to a more normal level. I guess we will have to wait and see.
The outlook section in the results states that income next year will be "in excess of £330 million" which is potentally a lot less than the £409 million reported today.
timarr
I don't have three hours in the morning to sit watching a spread bet screen. And if I did it whilst 'working from home' then both the paid capital inputting into the account and the working capital which will be reducing by 20% will eventually make me lose my job and destroy my capital.
That said if I had the time the day trading with a nice pot would be great fun. But need great focus and experience.
So all the spread/cfd/fx cos may struggle when people may have to go out to er 'work' for a living. Lifes tough.
Sorry Cmc Markets (LON:CMCX) Plus500 (LON:PLUS) Ig Group (LON:IGG) Aj Bell (LON:AJB)
I don't have three hours in the morning to sit watching a spread bet screen. And if I did it whilst 'working from home' then both the paid capital inputting into the account and the working capital which will be reducing by 20% will eventually make me lose my job and destroy my capital.
Which, unsurprisingly, is why people 'working from home' don't do that. Anyway, we're all far too busy.
The main driver of spreadbetting revenue is market volatility, boosted by the general issue of zero interest on savings which has pushed people into more risky investing - the stockbrokers are also seeing record revenues. Unsurprisingly the pandemic has driven volatility and that's seen spreadbetting revenues soar.
As and when volatility subsides and interest rates rise so will earnings, but as Cmc Markets (LON:CMCX) suggested this morning they'll probably normalise at levels significantly higher than pre-pandemic times albeit lower than where they are today.
In general the spreadbetters are an easy trade - buy on volatility, sell when markets go flat. But they'll always be cheap due to the constant drumbeat of regulation in the background.
timarr
From my limited experience, CMCX Share price always lags behind (more so than its competitors). it'll tick up in price slowly but surely over the next 10 years and pays chunky dividends. the threat of regulation means this isn't an exciting share, but im happy to tuck it away with my other long term, dividend paying beauties.
From my limited experience, CMCX Share price always lags behind
Not recently it hasn't.
If we look at the performance of the spreadbetters since the March 18th 2020 pandemic inspired bottom:
The best of the brokers is Jarvis Securities (LON:JIM) which is up 189%.
Cmc Markets (LON:CMCX) has massively outperformed its peers - which I certainly didn't see coming. On the other hand it was clearly undervalued pre-pandemic, so the outperformance is partly a reaction to this, although its figures have been extraordinary:
2019 was where ESMA really hit, showing the potential impact of regulation. On the other hand they were already recovering pre-pandemic. Now they expect net operating income of at least £330 million this year, presumably assuming market volatility normalises.
Frankly, with figures like these trying to forecast is a triumph of hope over expectation. In the absence of punative regulation or unforeseen unhedged losses they'll probably carry on doing OK. But neither of those risks is completely negligible.
On the other hand, if volatility rises then they'll probably beat this year's numbers ...
timarr
Norcros (LON:NXR)
On the face of it very pleasing year end figure here ignoring one quibble.
Main good news is that the pension deficit reduced from 48.9 mill to 18.3 mill despite the liabilities number increasing this year (the trend in liabilities total has been and should long term be downwards due to this being a mature scheme)
Profits and net cash previously flagged - company has confirmed year end cash balance pimped up by deferred vat - pimped up or not the cashflow this year was off the scale good even there will be the necessary part reversal of that next year.
Main important update today is from the outlook scetion ref trading in the new year and these comments seems pleasing. Note ye 31/3/2020 sales at 342 mill were higher than 2021 £324 mill - so 23% seems ahead of what i would have expected perhaps with expected sales growth probably only 5-10% this year ??
We have ended the year strongly, outperforming our expectations and the markets in which we operate in recording revenue*, profit and cash generation growth on prior year whilst operating within the constraints and disruption of the unprecedented COVID-19 pandemic. Pleasingly, this strong trading momentum has continued into April and May with Group revenue ahead of the comparable period in 2019 by approximately 23%.
Ok - back to the quiblle and its the dreaded adjustment amounts - there really is a stark difference between underlying operating profit of £33 mill and pre tax profit of only £18 mill. Post tax profit is only £15 mill so that will be my starting point to see what adjusts downover we can perhaps ignore.
IAS 19R administrative expenses
(1.4)
ok this one looks likes its extra costs ref managing the old pension scheme - on the basis the pension scheme will probably be about for the next 10 years i am minded to say this is a nenessaary cost that should not be added back. Note long term they may be able to ditch the pension thing entirely i would like to hope so adding the whole whack back probably is slightly unfair perhaps?
Acquisition related costs
3
(3.7)
Personally i am minded to fully remove this "intangible asset amortisation item" generally - i possibly should not do so but from memory other than the large acquisitoon a few years back most smaller items have been self funded and as most units are sort of perfoming to me all the craploa ref accounting for the past is not relaly relevant to the future buisness prospects - just be aware minor acquisitions do eat up excess cashflow generated !
Tricky one this - i probably should give the company the benefit of the doubt here perhaps ? it is real cash out the door though.
COVID-19 related restructuring
(3.8)
Net finance costs
(6.4)
Ok its ridiculous to have any finance costs "below the line" so i will say these are real and present costs - note company ended year with £10 mill cash in the bank so some room here for this figure being materially lower going forward (acquisitions ignored) . Note there is £2. mill of derrivate movements here that may be completely one off.
So ultra conservative calcs start with £15 mill post tax bottom line profit and add back £3.7 mill acquisition costs and 80% of covid restructuring costs £3 mill - gives us profit of £21.7 mill post tax - to me this figure is very conservative i am generally happy with the transparency on show here albeit its annoying to see half the underlying operating profit vanish out the door. with £81 mill shares in issue i make that conservative eps of 26.8p - this is well up on 18.6p per profits and well below the 31.2p basic underlying. Note stockopedia (presumably semi similarly adjusted) expectations were 27.9p much closed to my calcs that either the high or low numbers stated by the company.
Looking forward there is reason to hope that the company can get the adjustment numbers tredning downwards.
Moving onto where we are now with expected eps of 31p for new year (preumably conservative number) and shareprice of 322 - pe of 10 still seems cheap for company that has spare facilities to make acquisitions and seems to be trading reasonably solidly - obviously the south african arm the pension deficit and historical anemic organic growth will probably be quoted by many when they say "the company deserves a poor rating" - at least the largest negative elephant has left the room for now (no debt wooop)
I will continue to hold here and NXR remains one of my top ten holdings - note probably only top ten due to doubling of shareprice from the old days when it always seemed to return to 160p price whatever happened.
Cracking set of results from Norcros (LON:NXR) with strong momentum into the current year. Sales running around one-quarter higher in recent months as compared to a year ago. I have held these for a long time on the basis that they're good value despite debt and pension liabilities, with a decent dividend to compensate me for waiting. The debt is now paid off and the divi is reinstated after a pause last year (which was the right decision in my view). With strong construction and home refurbishment activity likely to continue I'm happy to keep holding.
The FD retires at the end of July ("he is thanked" as MrContrarian would say) and is replaced by an internal candidate with reassuring levels of experience in other plc roles. All handled in a controlled way. Good succession planning is an often-overlooked aspect of management quality, in my view.
Paul is reporting on a briefing by Intercede (LON:IGP) . They are also doing one on IMC at 4:30pm today.
Interesting IGP hitting a new recent high, but still being a falling star.
Intercede (LON:IGP) is still a "fallen star" because Stocko have yet to feed in the results from Tuesday. It will be interesting to see how the stock ranks move when this has been done.
Out of interest, how long does that typically take? (updating the ranks after an announcement)?
the trading update had these figures out on April 7th. From where the sp started to decline a little. So I don't understand what is so significant today to make them deliriously pleased, although I am very happy too. Will now be on new high screen, momentum screen and falling star if we hold £1.12
Which stock are you talking about?
It’s in the Intercede thread Intercede (LON:IGP)
What thread? All I can see is a reply to someone who also did not mention which stock, then dead end. Please can posters put the £ + ticker, it makes it so much easier to know what company is being discussed. Not everyone is using the same settings, devices or sites.
There are 7 different ways of reading these comments of which 4 are not threaded. If you choose to read a threaded version please say which company you are referring to so that all readers will know.
There are 7 different ways of reading these comments of which 4 are not threaded. If you choose to read a threaded version please say which company you are referring to so that all readers will know.
While agreeing it's irritating, if you're going to make this request you'll end up doing it every single day and often several times a day.
My view is that if people can't be bothered to add the company they're referencing then I can't be bothered to click through to find out what they're talking about. As said company is of no interest to me 99% of the time I've found this a highly satisfactory solution.
:-)
timarr
Re: adding a subject line to posts
Last September I used the green blob to suggest an optional subject field in the input box for discussion post replies. It was not taken up, I suspect this is due to mine being a lone voice and so not given any priority. Shame because I end up skipping so many comments on this board because life is too short and it is too much hassle to find out what it being discussed.
I thought these graphs of the current COVID situation from someone on Twitter were quite helpful - although I'd also be interested to know what the current situation looks like versus an equivalent stage in previous peaks:
https://twitter.com/Dr_D_Rober...
I'm increasingly worried that at some point in next couple of months it will be necessary for the government to either introduce a) significant restrictions (maybe going back to the pre-May step as cases were continuing to decline then?) or b) another lockdown. I am not sure that's being priced in by the market at the moment and I certainly wouldn't want to be holding pure-play travel, bar or restaurant stocks right now.
I think a lot of people are hoping being double-vaccinated breaks the link between cases and significant hospitalisations - it might do but I am not sure if it's going to do it quickly enough and there are concerns the AZ vaccine efficacy against the Delta (Indian) variant isn't strong enough. And what about further new variants like the one cited in Vietnam recently? From a market perspective people might even start worrying that vaccines aren't going to prevent lockdowns or significant restrictions, only slow down their frequency.
I've decided to avoid buying anything or topping up at the moment in sectors that would likely be affected in a negative way including retail shares with a significant highstreet presence. Now might be a good time to trim portfolios? What do people think? I'm not really interested in a debate on the pros/cons of Government policy - more in how we respond. Of course for those who have lost loved ones during the pandemic there are much bigger worries than investment decisions so this post is not meant to sound insensitive.
Suggest Patrick your question should be asked in a separate thread . It’s certainly worthy of specific detailed consideration by everyone who invests and is certainly something that I am wary of .
Nobody knows! Interestingly, according to the Zoe covid action tracker which usually has bang up to date & accurate data, partly the reason why the Indian variant appears super transmissible are due to a new set of covid symptoms, these are already mild in the young anyway but are appearing more and more like that of a common cold without the traditional nasty cough or the loss of smell. Because of this people are going about their normal business unaware and spreading the virus. There is already lots of evidence that double vaccinated people are only slightly less protected so any new wave will be significantly safer.
Hi Patrick .
Insightful comment, as a holder of Restaurant Bars, I am nervous about the ongoing situation. However, I am a firm believer in ‘what goes around comes around’.
My Taylor Wimpey shares have tanked recently, but house building is buoyant. They have a habit of doing this and at least I have the comfort that they are unlikely to go bust any time soon.
Best wishes and good luck.
Re COVID & investing - I think sometimes what is over-looked is that the UK has now built a big vaccine delivery capacity with more on the way; the 'new' vaccines are designed to be more easily tweaked for variants; and importantly (excluding the minority of anti-vaxxers), in the UK we are mostly willing to take them - especially if vaccine passports come in by the back door eg "Recommended" vaccinations in Freshers Week required if you want to enter a mass Uni event (remember 50% of young people go through college now; that is a big part of the unvaccinated group).
So whilst we ALL may require bi-annual booster shots (vs just the elderly with flu in 2019); international travel & trade will be impacted; and the govt will incur huge bills administering the system - my unskilled and inexperienced 18 yr old son earns £19/hr testing truck drivers! - I am optimistic that we are unlikely to lock down hard again. Humans are very adaptable given time and need to socialise.
So in 3, 6 or 12 months "normality" will emerge. This will be different than before and who knows how exactly - but more similar to 2019 than to some strange & distant future. High traffic hot spots will re-emerge - just maybe fewer and re-located. With overseas travel restricted and the govt doing everything to keep incomes mostly intact (at the expense of debt), that means a lot of extra money for UK domestic consumption.
For SOME retailers whose purpose has not been usurped (impulse card purchase, meals out with friends as opposed to planned fashion shop?), I think we remain in a 'blood on the streets' retail buying opportunity on a 5 year horizon : higher risk yes and some outright failures /dilutions to come but potentially big rewards still. I accept my risk tolerance and timescale is higher/longer than most but I feel the logic based on history is strong - I only wish I had acted on it more strongly last year!
I am 76 with a wife who is 72 this year who has been shielding. We have been desperate to get out and have now been going out for several meals a week and the good restaurants are very busy. Last week we tried to book lunch for this Tuesday but they were fully booked. We managed to get in for today. We have also booked flights. With this in mind I have bought heavily into Loungers (LON:LGRS) and already held Marston's (LON:MARS) and £JDW. Also hold International Consolidated Airlines Sa (LON:IAG) and will probably add other travel companies. I guess you are naturally optimistic or pessimistic. My son recently went to the US and he says life is like it always was, crowded airports with long queues at Starbucks! I believe with the number of vaccinations we should get back to normal. Of course there will be more cases but they will be younger people who won't die. Now that we have a vaccine any variants can be dealt with very easily. We just have to live our life as we will be dead sooner or later in any event from something else if not simply old age! Anyway, I must get ready to eat out!
Previous facilities management basket case Mitie (LON:MTO) was flagged as a possible recovery play on SCVR after its acquisition of Interserve and substantial rights issue last year. Full year results to March 31st out this morning.
https://www.investegate.co.uk/....
Bit of a mixed bag with profitability and eps subdued but various debt indicators and future workflow strong. Commentary is upbeat and “materially ahead of expectations” outlook for FY 2022. CEO Phil Bentley is not usually one to over promise. Shares have rerated since commented on in early November 2020 (up from 28p to 70p) so the market cap is now above the SCVR ceiling, but might be worth looking at. I hold.
Gus.
My morning smallcap tweet:
Ergomed (LON:ERGO) Norcros (LON:NXR) DFS Furniture (LON:DFS) Netscientific (LON:NSCI) Amigo Holdings (LON:AMGO) Sopheon (LON:SPE) TruFin (LON:TRU) Wilmington (LON:WIL) M P Evans (LON:MPE), CAP XX (LON:CPX), musicMagpie (LON:MMAG)
Ergomed (ERGO) guides FY rev in line and adj EBITDA materially ahead of market expectations. [SP=1199.28 Cap=585m]
Norcros (NXR) FY(Mar) rev in line. U/L EPS up 10%, FY div 8.2p (3.1p). Recent 2 months rev up 23% on 2019. [SP=319 Cap=258m]. I hold.
DFS (DFS) guides last 10 weeks order intake up 92% on 2019; first 49 weeks of FY up 10%. Guides FY U/L pretax at least £105m. Guides FY22 pretax £66m-£96m, materially ahead of analyst consensus of £61.4m. [SP=275 Cap=711m]. I'm short.
NetScientific (NSCI) £7m placing at 130p, a 10% disc, for working cap and growth. [SP=149 Cap=22m]
Amigo (AMGO) still begging the FCA on its knees to give it some leniency in compensating borrowers. This could result in a revised scheme of arrangement or insolvency. [SP=8.15 Cap=39m]
Sopheon (SPE) AGM stmt - "Visibility for the full year 2021 now stands at $28m, compared to $23.2m at the time of our AGM announcement last year, which is very encouraging". [SP=888 Cap=93m]
TruFin (TRU) its partner (I think) Satago extends commercial pilot with Lloyds Bank to enable pilot testing to be concluded. If successful it will lead to a five-year commercial agreement. [SP=84.69 Cap=68m]
Wilmington (WIL) strategic review result - co "will focus on governance, risk and compliance ("GRC") and Regulatory Compliance and will structure and report its business as two strategic divisions". New vision is "Helping our customers to do the right business in the right way". Crikey, that's lame. [SP=197.45 Cap=174m]
M. P. Evans (MPE) AGM stmt - fresh fruit bunches in last 5 months up 24%. Crude palm oil equivalent production up 25%. Some ESG guff. [SP=740 Cap=404m]
In line: CAP XX (LON:CPX) musicMagpie (LON:MMAG)
Does anyone here have any thoughts on Cap Xx (LON:CPX) ? I have seen it mentioned on the 100 bagger thread board
Oxford Cannabinoid Technologies Holdings (LON:OCTP) - Oxford Cannabinoid Technologies floated on the LSE a few weeks ago. The company develops cannabinoid based prescription drugs for the global pain market. If you are interested to hear more about their portfolio of drugs in development and how the company plans to develop over the coming year then please come along to a webinar at 1pm today hosted by founder and CEO Dr John Lucas and executive Chair, Neil Mahapatra. Register https://us02web.zoom.us/webinar/register/1316221058814/WN_RIzq0rv9SQuVHlhGwRcuhQ
Hornby (LON:HRN) (I hold) finally back in profit after multi year turnaround. Would be great if this could be covered today please
Yes please I hold too
Jack's looking at £HRN now, should be a section up fairly soon.