Small Cap Value Report (Thu 10 Mar 2022) - MEAL, FCAP, TUNE, FORT, BOO, FSJ

Good morning, it's Paul & Jack here with the SCVR for Thursday.
Agenda -
Paul's Section:
Parsley Box (LON:MEAL) - placing & open offer, at 20p per share. Directors & associates are stumping up £4.1m of £5.9m placing, an impressive commitment. Trouble is, so far the business model has been a cash burning failure. Is that likely to change? Revised strategy looks more about survival than growth, so I see lots of risk and little upside. Hence best avoided I reckon.
Focusrite (LON:TUNE) - an in line trading update for H1. Share price overshot last year, and like many small caps, has corrected sharply this year. Is it a bargain now? Not really, but the valuation of PER 20 seems justified for a good quality business.
Boohoo (LON:BOO) (I hold) - back by popular demand, as it's almost a small cap again after a disastrous sector-wide de-rating in the last year. Today's FY 2/2022 update is (surprisingly) in line with (lowered) expectations. This looks a turning point to me.
Jack's section:
Finncap (LON:FCAP) - full year revenue to exceed the top end of its £45m-£50m guidance. No word on distribution of profits. The shares are very illiquid, but they also look cheap given how well the group is performing. Market conditions could turn of course, in which case you’d have to expect some volatility.
Forterra (LON:FORT) - FY results slightly ahead of expectations, despite previous upgrades. The shares have fallen along with the rest of the market but the results are good and the valuation undemanding, so it could be worth taking a closer look at these levels. The company notes rising costs but is pushing through price increases.
James Fisher And Sons (LON:FSJ) - not a company I’ve followed before, but one with a long operating history. Things have gone badly over the past couple of years and the share price has collapsed, so being cautious. There could be value given the lack of equity dilution and it might be worth monitoring on that basis, but debt is quite high, the results are poor, and the long term strategy has yet to be properly defined. I'm curious to see how the situation develops but the risks are considerable.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Parsley Box (LON:MEAL)
18p per share (yesterday’s close)
No. shares: 42.3m (before placing) + 29.5m (placing) = 71.8m (plus open offer)
Market cap (after placing): £12.9m
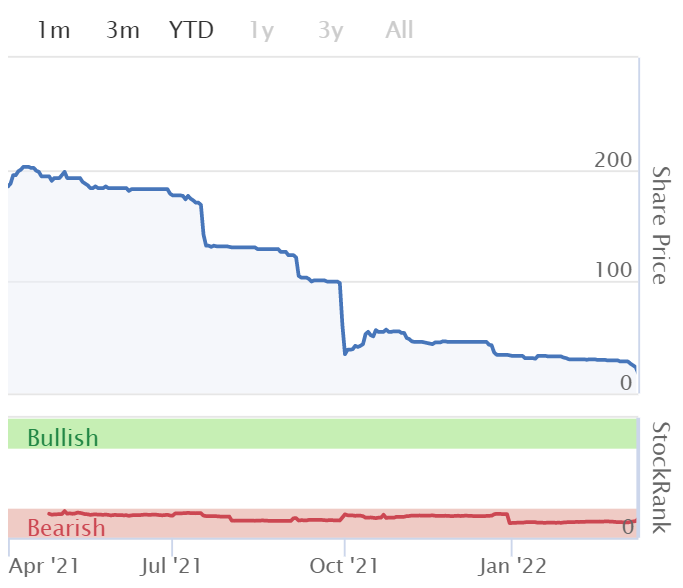
No surprises at this equity fundraising being needed, as it was flagged a while back, following disastrous performance & cash burn in 2021. What is surprising today, is that the fundraising is being done at 20p, and not much lower. The other surprise, is that of the £5.9m being raised, £4.2m is coming from Directors and associates. There’s nothing like burning your own cash, to focus your mind on getting value for money from that expenditure. This could have been much worse - without Director participation, I reckon any fundraising, if possible at all, would have been in single digits of pence, because the company’s position is now so weak - a failing business model, and a bearish stock market backdrop.
What went wrong?
Outsourced supply chain fell over last autumn/winter, causing shortages of inventories
Marketing spending reduced, causing new customers to stall
Current trading - little meaningful detail provided.
2021 performance - modest revenue growth of 5%, and huge loss of £(7.1)m adj EBITDA, the main culprit being excessive (and clearly ineffective) marketing spending of £8.0m, which was greater than gross profit!
Balance sheet - now weak, with only £1.1m NAV, hence without further funding the business would have probably gone bust in 2022.
New strategy -
- Driving growth from existing customers.
- Fewer, but higher quality new customers (so presumably much reduced marketing spend)
- Moving to a new lead supplier.
My opinion - MEAL lives to fight another day. I’m impressed Directors (and associates) are putting up the bulk of the new money, and at a very fair price I’d say.
Trouble is, so far the business model has been a failure. The new strategy means it’s likely to remain a small business, struggling to replace customer churn.
The elephant in the room, is that the product is such poor quality, hence of limited appeal. I’ve mystery shopped it several times, trying lots of different products, and they’re mostly very disappointing, although a few items were quite good. It makes far more sense to order cheaper, more generous, & better quality frozen ready meals from a supermarket. There might be a small niche for people who have to have ambient temperature product though.
.
.
Focusrite (LON:TUNE)
1010p (up 1% at 08:55) - market cap £590m
We like TUNE here at the SCVR, it seems a good quality company, run by an owner/manager, and has made a series of seemingly good acquisitions. The trouble is, it got so expensive last year, that put it out of range for me personally, in valuation terms.
As you can see below, the chart has followed a familiar pattern of so many small caps - an excessive bull run in 2021, then more recently a sharp correction. I wonder is this now a more attractively-priced entry point? Let’s find out.

.
Focusrite plc (AIM: TUNE), the global music and audio products company supplying hardware and software used by professional and amateur musicians and the entertainment industry, is pleased to give the following update on current trading for the financial year ending 31 August 2022 ('FY22').
H1 is in line with Board expectations for revenues, profit, and cash.
Demand has remained strong
H1 revenues £91m (down on £95.3m, last year’s exceptional performance)
Last year comparatives will ease in H2
Supply chains (component shortages, freight cost) causing gross margins to reduce in short term, actions taken to address this
Sales to Russia/Belarus/Ukraine suspended - “very small”
Net cash of £17.8m at 28 Feb 2022
Planned increase in inventories
Full year guidance -
The Board is confident that the Group is on course to meet its full year expectations and will give more detailed guidance at the time of the announcement of the H1 2022 results on 26 April 2022.
Forecasts - as you can see below, there have been a series of profit upgrades, so it’s all the more impressive that the company is trading in line with more demanding targets.
If we value the company on c.50p EPS, then it all depends what PER you think it justifies, especially now that we’re in a market which has scrubbed off a lot of very high PERs for companies perceived as being exciting and growth-orientated.
The current share price of c.1000p is a PER of about 20, which feels about right to me, maybe slightly on the warm side, in this more bearish market?

.
My opinion - there are so many bargains around at the moment, that paying a PER of 20 for TUNE doesn’t seem sufficiently attractive to me, to persuade me to buy.
However, it does seem a more rational, and reasonable valuation than the excessive peak hit last year, where even bulls on the company must admit that they chased it too high.
As usual the StockRanks explain things with great clarity - a very high quality business, but still not cheap. Although overall, a StockRank of 58 is leaning towards the positive side.

.
Boohoo (LON:BOO) (I hold)
91.7p (up 16% at 10:18) - market cap £1,162m
I wasn’t going to comment here on BOO, but reader comments & thumbs ups suggest that as it’s come down so much that it’s not far above our usual £700m limit, that we could bend the rules and comment here on BOO.
Boohoo provides an update for the three and twelve months ended 28 February 2022.
Boohoo is an expanding stable of fashion eCommerce brands, about 15 of them in total now -

[Source: Boohoo website]
Key points from today’s year end FY 2/2022 trading update -
Q4 net sales +7%
Full year net sales +14% - in line with (lowered) expectations
Higher returns rate, due to product mix changing back to going out clothes
UK continues to trade strongly
International - under-performing, blamed on supply chain, particularly outbound freight, which is expensive & slow (esp. transatlantic flights) - broker notes say a US distribution centre will sort this out in 2023 - so possible resumption of overseas growth in the pipeline?
EBITDA of £125m achieved, in line with guidance - this is a very positive surprise to me, as the share price collapse seemed to suggest more bad news was inevitable.
My opinion - delighted with this update, as I was convinced more bad news was imminent.
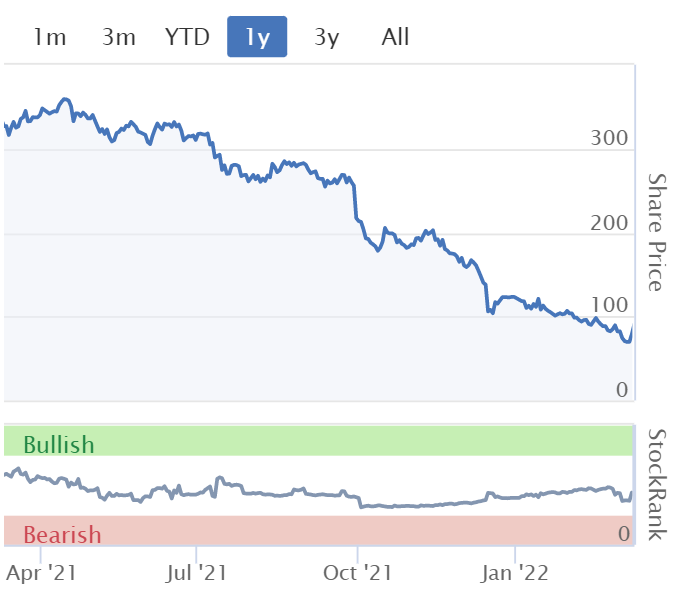
2 revised broker notes out today suggest c.5p EPS for FY 2/2022 - make no mistake, that’s a poor outcome, well down on last year, and breaking the trend of years of uninterrupted strong earnings growth. But that’s why the share price has tanked. At c.90p, and 5p EPS, the (no historic) PER is only 18 - you could argue that’s justified, as EPS has dropped. Or you could argue that one-off external, fixable problems with supply chains have affected everyone, and should ease later in 2022. It depends entirely how you see things.
Brokers are pencilling in 6-7p EPS for the new year. Given that there’s a lot of growth from new brands, and new product launches (e.g. the lucrative beauty market), and good reasons to expect expensive & slow outbound air freight to become cheaper as flights normalise, then I’m prepared to hang my hat on 6-7p EPS, and for me a PER of 20 is justified because I think this will be a much bigger business in 5 years’ time, which has always been my investment rationale. That comes to my own current valuation of 120-140p as things stand now. Hence at 90p, I’m happy to buy more. I think this looks like a turning point in the downward share price trend, as it looks to have considerably overshot on the downside. You may agree or disagree, happy to hear all rational views.
I think the balance sheet is fine, with £86m forecast net cash, and the new substantial freehold Soho office providing protection if extra cash were ever needed (e.g. sale & leaseback).
The historic share price movement has been a disaster for me, but that doesn’t matter, because we can’t change it, but can learn lessons from it. All that matters to me now, is what the future holds, and these numbers suggest to me BOO is currently undervalued, hence I’m comfortable buying more.
There’s also the issue that this has been an enthusiastically shorted share, so with positive news out, there could be a rush to close those shorts, helping the rebound in share price.
Rumours from a usually good source (Betaville) suggest that the founders might take it private. I think that has some credibility. After all, why go through the rigours of being a listed company, if nobody is interested, and the rating is low?
Finally, competitive pressures are intense, especially from Chinese direct to consumer operators. For that reason, I think it makes sense to forget about BOO mgt’s 10% target EBITDA, and instead assume a lower 6-8% margin might be more applicable in future, giving them scope to remain competitive in product pricing, special offers, and marketing spend. That’s what the broker forecasts are now based on, so they look achievable.
.
.
Jack's section
Finncap (LON:FCAP)
Share price: 29.84p (+12.6%)
Shares in issue: 179,802,609
Market cap: £53.7m
Trading update for the year to 31 December 2021
FinnCap’s stock is very illiquid - the StockReport suggests around just £2k can be reliably bought or sold at market prices, and this comes across in the share price chart.

While that means the shares can shoot up, it also means that, given the past few months, the stock has actually fallen considerably - by about 41% from the high back in April 2021. The result is a valuation that seems modest if the group can continue to grow.

Today, the company reports that full year revenues should exceed the top end of its £45-£50m guidance range. The group’s CEO says that the group is well placed to deliver ‘record’ revenue in FY22.
Conclusion
It’s an exceedingly brief update, three sentences long, so there’s not much to interpret. FinnCap has obviously traded well though and appears to be confident of a good performance in 2022. At the current valuation, it is worth looking into for those that don’t mind the lack of liquidity, but that illiquidity does of course present its own risks.
That valuation also reflects concern over the durability of these results. It’s rare these days to see a company whose forecast PER is less than the forecast dividend yield. It does suggest to me that the stock is potentially cheap, but I suspect that in order for the share price to really kick on, it will need to convince people that it is growing not just due to favourable conditions, but also because it is gaining meaningful market share.
FinnCap has a healthy net cash position, so it’s got optionality and funding as it looks to grow.

It’s also worth noting that the company only guides on revenue, so no indication yet of how much of profits will flow to shareholders rather than employees.
The stock looks cheap and the company is trading well, so it might appeal to some, but the lack of liquidity will remain a concern for others. The shares have probably fallen too far over the past couple of weeks though.
I think FinnCap plays a useful role for private investors and it seems to have a growing presence in the area, so perhaps there is something in the strategy that can ensure underlying growth beyond more transient market conditions. It’s probably a market that could do with some disruption.
Forterra (LON:FORT)
Share price: 225p (+0.67%)
Shares in issue: 226,488,861
Market cap: £509.6m
Final results for the year to 31 December 2021
A familiar share price chart regarding the past couple of months:

Forterra is a UK manufacturer of essential clay and concrete building products. It says its position in its market is unique, it’s been around for decades, and ‘wherever you are in Britain, you won't be far from a building with a Forterra product within its fabric’.
FY results are ‘slightly ahead’ of expectations.
- Revenue is up 26.9% to £370.4m,
- EBITDA is up 85.8% thanks to revenue performance and EBITDA margin up from 13% to 19%,
- Operating profit +160% to £54m,
- Earnings per share +165% to 17.5p,
- Cash flow from operations +48.8% to £81.2m
- Net cash (ex leases) is up from £16m to £40m, and the total dividend has jumped from 2.8p to 9.9p.
That values the stock at around 13.1x FY21 earnings with a yield of 4.3%. Forterra targets a dividend payout ratio of 55%.
Full year brick sales volumes were 33% ahead year-on-year and 1% ahead on 2019. H2 cost inflation was not fully recovered, meaning margins are lower than 2019 although significant double digit price increases are planned in the coming months.
Construction of the new Desford brick factory remains on track with commissioning due end 2022. This will deliver a 22% increase in brick production output from 2025 and an anticipated incremental £25m of EBITDA (guidance was previously for £15m). That upgrade results from higher selling prices and reduced performance at the old factory.
There’s plenty more organic investment. A total of £27m is being spent on the Wilnecote brick factory refurbishment, and the group announces a ‘highly cost-effective’ £12m investment to manufacture clay brick slips at the Accrington factory.
It sounds as though Forterra has a number of additional capital allocation options, with an ‘attractive pipeline of organic investment projects in place each offering compelling returns’. The group is also targeting bolt-on acquisitions and has initiated a £40m share buyback programme, with £5.5m returned to date.
Outlook
Market conditions remain highly supportive with continued demand for new housing and constrained UK manufacturing capacity driving brick imports to record levels, despite increasing macro-economic uncertainty and supply chain pressures which have created a higher interest rate environment
The order books are strong, supported by robust customer sentiment and an ongoing housing shortage. Meanwhile, price increases should recover margin in the year ahead.
All in all, this looks very positive.
Conclusion
The valuation is modest and the update is good, so the market could be presenting an opportunity here.

Forterra could be a ‘baby with the bathwater’ situation, there’s enough of them around at the moment. Operationally, the company is doing well and is investing in further growth initiatives. The dividend is increased, net cash is healthy, and the company is buying back shares. It also looks as though the group is confident of its pricing power going forwards.
Clearly there are macro concerns, and fortunes are tied to house construction, but there is good long term demand here and the government is committed to increasing volumes. The shares are only slightly above lockdown levels but I would argue that the outlook has improved since then.
This looks like a solid, cash generative company, reflected in the Quality Rank of 87.

James Fisher And Sons (LON:FSJ)
Share price: 382.5p (-23.35%)
Shares in issue: 50,340,948
Market cap: £192.6m
Full year results to 31 December 2021
Shares are down c23% this morning, having lost around three quarters of their value since 2019.

Revenue is down 4.7% to £494.1m, but reduced margins mean adjusted operating profit is down 30.9% to £28m and adjusted earnings per share are down 58.2% to 20p. Statutory results are far worse: an operating loss of £20.7m and diluted earnings per share of -55.2p.
The adjusted results exclude £48.7m at the operating profit level and £86.5m at the earnings per share level. Material figures.
Management references pandemic disruption, but also ‘markets not recovering at expected rates, and an underestimation of the headwinds faced by some of the businesses’, which doesn’t inspire confidence. UK lockdown affected the first half, but project delays and provisions further affected H2. Further provisions are required against asset carrying values due to the prolonged impact of reduced profitability.
Group CEO Eoghan O'Lionaird comments:
In June 2021, we outlined a roadmap to achieve our objective of greater than 10% operating profit margin and greater than 15% return on capital employed. This roadmap is based on three phases: "Reset, Reinforce and Realise". Throughout the year we continued to execute the Reset and Reinforce phases to create the foundations for sustainable profitable growth.
Having sold Paladin and two of our businesses, during 2022 we will continue to optimise our portfolio to focus on businesses where we have a competitive advantage, strong growth prospects and attractive returns. The internal change agenda will continue at pace. We are executing several self-help initiatives, focusing on operational and commercial excellence, including a LEAN programme, to improve the underlying performance of the Group.
Future direction
With a backdrop of ever-increasing focus on climate change, and the acceleration of an energy transition to a low carbon economy, the oil and gas services industry is likely to decline over the long-term. However, it will take time for the required global low carbon energy infrastructure to be developed.
… As the pace of the energy transition towards sustainable energy sources accelerates, we are equally focused on accelerating our own transition, as new opportunities emerge for our well-established and fast-developing services supporting the growth of renewable energy.
Management sees opportunities primarily in offshore wind and the responsible decommissioning of redundant oil and gas assets. The group adds:
We are well-positioned in these fast-emerging sectors, where the Group can combine its traditional oil and gas-oriented subsea capabilities with newer, renewable-energy specific solutions, such as the installation, monitoring and management of high voltage cabling in offshore wind, and the provision of bubble curtains that protect sea life from the noise impact of pile driving during the construction of the wind farms.
Conclusion
It sounds like it’s still relatively early in this reset strategy, too early for me as I don’t know the company or its markets, and so I’m not well placed to form a firm view on its prospects. There’s a lot yet to be thrashed out by management.
The key strategic challenge for the Company over the next decade is in defining the optimal approach to address the energy transition, capitalising on the many opportunities that are available in renewables whilst enabling our customers to make their own transitions in a financially and environmentally responsible manner. It is a challenge on which our management team is keenly focused and will continue to define with more precision as the shape of the energy transition becomes clearer.
So a turnaround is required and being enacted, but the actual long term strategy has yet to be properly articulated, as far as I can see.
James Fisher has been around for a long time though, and I hope it can find a new footing.
The last two years have been among the most challenging that the Company has experienced in its 175-year history. The Board is committed to delivering a successful turnaround of the James Fisher Group and believes that the steps it is taking strategically, operationally, and financially are in the best long-term interests of all stakeholders.
There is value in a company with a long heritage (and the expertise and relationships developed over that time), but markets change, companies do go bust, and new management teams are capable of quickly wrecking decades of good work. So the long operating history is comforting to a degree, but what’s far more important is where James Fisher is heading.
The line from management about ‘underestimating headwinds’ is concerning, but I do also credit them for communicating that to shareholders rather than spinning it positively or burying it further down the update.
I want to know more about what management’s plan is for sustainable profitable growth though. Turnarounds take time and it seems like there is work left to do before management can provide investors with a firmer handle on the group’s prospects.
But the markets identified are potentially attractive, so I’m curious enough to monitor the group’s progress from here. There’s not been any equity dilution for a long time, and the company previously had a solid history of profitability.

The dividend track record was also very good.

It’s had a torrid run - three profit warnings in FY21 and down again today. I’m sure the pandemic has had a big impact, but it also feels as though something more fundamental has gone wrong. These results are bad, but I also note that net debt has come down slightly, from £198.1m to £185.6m - although reduced EBITDA means that the net debt : EBITDA ratio is an uncomfortably high 2.9x (up from 2.8x, with covenants requiring less than 3.5x).
It’s probably worth investigating a little further as a high risk, high reward turnaround play given the lack of dilution, but I wouldn’t go any further than that yet as I think the risks are considerable and it’s perfectly possible that things get worse before anything gets better.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

48 comments
Isn't the bigger medium term risk for Boohoo (LON:BOO) that rapidly increasing inflation (which we can expect a lot more of with Russia's invasion of Ukraine and the subsequent sanctions) will severely squeeze UK household's disposable incomes? I suspect this will affect the revenues of all companies that sell "unnecessary/optional" goods and services over the next couple of years.
Or, as we’ve seen in past recessions, is it the mid-market that really gets squeezed?
Those who shopped mid-market move to the more budget end and those who shopped top end aren’t impacted.
Re Boohoo (LON:BOO) and "inflation squeezing UK disposable incomes" and the additional issue is the age focus of BooHoo's main brands (young adults).
They are under huge age-specific pressures from govt measures like NI, changes to student loans and general essential inflation plus a continual failure to address issues on housing. I am hoping that the (relative) move upmarket and into slightly older person brands like Karen Miller and especially Debenhams will help but it will take time to grow these.
The other offsetting factor in their main UK market is scale - they may be able negotiate better prices and marketing budget cuts than the many small competitors and squezze out some margin gains by tightening returns policies etc. In their other markets, esp the US until they get better distribution costs, they will suffer.
I hold, have taken a bath having bought back in a twice today's price but think the price will recover somewhat in time but it may be a 12-18month wait.
Boohoo (LON:BOO)
I don't hold, but I do keep an eye on the results.
I certainly would have preferred more detail today and found it hard to infer how the company is performing going into FY23.
A Full Year Gross Sales figure, for example, would certainly have been useful, as the Q4 +7% Year-on-Year Net Sales figure in isolation doesn't tell me the whole story.
I think it's worth adding that this +7% figure is the lowest YOY revenue number I've seen by the company going back to 2017.
The above aside, I can't help thinking that the company is going to do a large raise in the near future to pay for their future US warehouse. I'm therefore not keen on buying in right now with the possible threat of dilution on the horizon. Or perhaps I'm being too cautious?
A
Capital (LON:CAPD) results this morning seem very strong on many fronts.
disc i hold as i see it as picks & shovels not directly exposed to mining. it , like bigger operators Geodrill + Major Drilling all talk of the multi year investment cycle that has started in Gold as evidenced by the global increase in financing for projects.
Capital (LON:CAPD) could be argued to be cyclical but it very low rating reflects this and it has a good long term track record. when the price was 103p back in 2011 ebitda was 34m and eps were 11c. 10 years later the price is 93p and fcst ebitda is more than double at 80m+ and eps likely to be more than double 22c. there is good see through to these figures.
there is an excellent 8 year chart break out pattern that supports a decent upside with limited downside. IMHO
I hold £CAPD. I think the most important factor is still the mining services contract with £CEY. This is Capital Drilling expanding out from drilling (hence the name change) in a big way. The contract is so big that it is really make or break for CAPD. So far, all the signs are that it is 'make' but the risk is still there and needs to be carefully monitored. On the drilling side they are just starting to move outside the core African market (plus some work in Saudi) by setting up rigs in Canada. So there is certainly growth potential. Note they were on 'Sell it to the City' on PI World a month or so back where they got a thumbs down. They've done OK for me so far though.
Capital (LON:CAPD) the thumbs down was based on a rather lazy assessment that it was based in Africa and therefore too much political risk. It wasn't really based on any in-depth insight, so wasn't too concerned about that (but probably explains the low rating)
Hello JCPr. I am a member of Mello and am a fan of Mark Simpson who often takes part in the Mello Bash at the end of the programme. He has a recurring theme of seeking out shares with Added Value and some months ago picked Capital (LON:CAPD), a very unusual gem in the picks and shovels category. His view was that the company had additional elements which added value and were not fully reflected in the SP. The two added value ones were the labs and the investments. Both are very interesting from my point of view, and will come to pass. All IMHO of course!
I hold Capital (LON:CAPD) - broker note following todays positive results from Tamesis states target price of 140p following upward revision of 2022 revenue estimates from $248.6m to today's company guided $270-280m, which they believe to be on the conservative side. I am happy to continue holding.
Where is the Capital (LON:CAPD) broker note please, rk71? Gratefully received if you can.
ridavies
The Capital (LON:CAPD) note is available on Research Tree, although it doesn't even stretch to 2 pages
James Fisher And Sons (LON:FSJ) (I hold) FY21 results.
SP this morning 393p (prev close 499p)
Mcap 198m
After writing this – I see Jack’s excellent writeup. As my note contains a little detail upon the what’s gone wrong and what they are doing to put it right note – I’ve still posted, apologies for any recovering of ground.
Short note on James Fisher a 175year old marine services company based in Barrow-on-Furness and serving the marine services, oil and gas, renewables, sub-sea, decommissioning, defence, submarine rescue, nuclear and coastal tanker fleet.
FY Headlines
Headline results contain a lot of negative numbers. Turnover 494m (down 5%), Operating Loss 20.7m (up 52%), Loss before Tax 29m (up 44%) and Loss per Share -55p (up 51%).
There are some positive operating figures – but all down on the year. Operating profit 28m (down 30%), and underlying eps 20p (down 58%).
On the face of it poor results and a second year of losses and write-downs. Disappointing. Not surprisingly those who had recently bought the rumour – have been baling out on the news this morning with the share-price falling from the previous close of 499p to 385p at 10am. Not a market for disappointments.
To their credit the company has been upfront with the figures. Perversely I am encouraged by the results but to understand its necessary to look beyond the headline figures into whats gone wrong at Fisher and what is being done to put it right.
This is supposed to be a short note – but its a complicated story.
What went wrong?
Short version – too much debt at start of pandemic 230m (207m discounting lease obligations) at end 2019 and mis-timed and ill-judged acquisitions during 2019 combined with lockdowns, travel restrictions and restricted customer site access across nuclear, defence and off-shore installations (which still continues), an insurgency in Mozambique and delayed restart to North Sea/European Capex and Opex budgets combined to raise debt to an eye-watering level and reduce fisher to a 2021 focused upon survival rather than recovery.
To Place or not to Place?
Institutions that had bought in anticipation of a swift recovery sold. Share price was 290p in December in justified expectation of an emergency funds placing. Personally given the company history – and the 25% ownership by the Sir John Fisher Charitable Trust (worth a look if you so minded) I thought the company would strive to avoid a placing. And they have.
Below the headlines
Results today show that fresh capital is not needed – although it would certainly help - which in itself is a success for the company – with net debt/EBITDA at 2.9 below the 3.0 covenant despite the impact of delays and deferrments.
Encouragingly long term debts have all been renegotiated with corresponding dates – finance costs are down this year on 2020 – and I expect recovery and unwinding of working capital, together with some potential disposals at the right price to significantly reduce debt and allow for increased investment in leading growth segments of the company (they actually managed to invest over 20m in their businesses this year which is creditable under the circumstances).
Revenue, underlying operating profit and underlying operating margin are all as I expected following – surprisingly so – given the last of a string of profit warnings in December.
The cash generated from operations at 58m is higher than I anticipated. But so also is the level of writedowns.
The silver lining here is that operating cashflow shows the business is running better than expected, and has allowed more investment, whilst higher write-downs help to avoid future write-downs, reduce the level of intangibles and clear the decks for profitable disposals in the near future. The wonders of accounting.
Turning Point
In my view this is the turning point for Fisher. I expect 2022 to be a year of recovery. With Mozambique payments resolved and short term costs funded, deferred projects now being delivered and both capex and opex rising in the North Sea/Europe across Oil/Gas, renewables and marine services and the tankships division reporting high Q4 utilisation and rising spot charter prices – I see opportunity for Fy2022 to significantly exceed the current expectations which are understandably starting from a low base.
This is not the first time in its history James Fisher has had to respond to market dislocation and change direction. They have a creditable history, though too long for this note, of doing this – and within the group are market niche leading companies that will prosper greatly in coming years with the coming energy transition and growth in defence and nuclear spending.
New Team
The board and executive team have been refreshed. The chairman, FD and two non-execs arrived in mid 2021 and the CEO in late 2019. As the CEO memorably said the work being carried out now is ‘self help 101’. It shouldn’t really need to be stated – but had not been carried out at Fisher for too long. Together with the long overdue reorganisation of the company, not least to face directly into the growth markets, the divisional heads have all been recently appointed (though have been with the group for a long time) and I don’t expect the same mistakes of capital misallocation to be made. Quite the reverse from what I have seen I highly rate team, their capability, knowledge of the businees and markets. I think they will succeed very well with a difficult job under challenging circumstances. But low risk it is not.
Forecasts
Consensus figures for FY2022 are for 40p eps – today that puts the share price below 10x earnings. I think that’s reasonable given the work still to be done and the still very high level of debt.
With recovery likely this year across all of its markets, and given the write-downs in these results, I see 40p as a base and 45-50p eps as more likely.
There is a lot of work to be done to reduce debt, reorganise and invest for growth. I am happy that the company is more conservative with its forecasts now - especially given the volatility in markets today. But it’s likely 2023 before we start to see the trajectory of future revenue and profit growth with margins back towards the 10% plus of old.
I’m still ploughing through today’s results – I’ll try to post some more detail on their prospects and my forecasts across their divisions in a separate thread sometime soon,
cheers
Mark
many thanks indeed Mark / illiswilgig for this helpful background and commentary on James Fisher And Sons (LON:FSJ) . This remains firmly on the list for me, although I'm not sure there is a rush to buy just yet.
James Fisher And Sons (LON:FSJ) Hello Mark - thank you for your kind comments. I agree. I think the share price got ahead of itself this week and it will most likely lie around 380 - 400p for a few months now - unless there is some very positive news flow which seems unlikely this early in the year,
cheers
Mark
Jack: re Forterra (LON:FORT) , you wrote "The valuation is modest and the update is good, so the market could be presenting an opportunity here. ... ... The shares are only slightly above lockdown levels but I would argue that the outlook has improved since then."
The SP is much the same as it was five years ago, and the share count is about 10% higher, at 226m. The case for investment seems to depend a lot on one's belief that the capex will significantly improve profits. Even though there's a decent dividend while we wait, I don't see this as a GARP share, do you?
£FORT. Also, unless I misread, fuel cost was some £8m up in 2021, with some hedging . Forterra (LON:FORT) report a long term solution from 2025, but it doesn't look as though they've been able to do much new hedging for this year
On Forterra (LON:FORT) (I hold) the argument is that they expect costs to be passed on. there are only 3 brick makers and so the power is with the suppliers rather than the buyers. there may be a time lag as I suspect price increases are passed on quarterly. the bull case is that the Capex on new projects will increase production and efficiencies. To be a holder you probably need to believe in the mgmt team .
Re Forterra (LON:FORT) - I own Ibstock (LON:IBST) who reported yesterday and listened to their presentation of the results. They now described their pricing as dynamic and at least quarterly but also seemed very confident of pushing prices through (and that at current levels some some of energy support would be forthcoming from the Govt).
They have been focused on energy reduction/carbon reduction for some time via capital investments.
I came away confident for the brick industry ie that the triopoly felt secure ands that returns would be good . Having scanned Forterra (LON:FORT) I see a very similar strategy (energy reduction, brick slips etc) and thus outcomes
Brick slips are a great point. Imagine standard 100mm thick bricks constructed by hand in all weathers and difficult work - to modern methods of construction - having the 'look' of robustness and numerous design (stone, slate, colours, textures) but stuck onto a board or rendered surface. Time, skills, cost efficiencies. But manufacturing wise slips can be 7mm, 9mm or 15mm so a 6:1 ratio minimum.
Fred Dibnah would not approve of these 'new fangled methods' but makes sense (until we start ripping them down lol - but thats not Forterra (LON:FORT) or Ibstock (LON:IBST) problem dem fire proof.
There are issues over backing board and insulation, but then thats another story.
And Bison is a precast concrete plank which is used on housing and lower rise I think to save pouring wet concrete, and probably the strongest thing in the whole edifice. Fingers pies.
Had my finger on the buy button then thought of my heating bill. Can
Forterra (LON:FORT) pass on full energy cost hike I wonder? It would be good to check what fuel efficiencies will come with the new plant coming on line later this year
Good morning Paul, Jack and all.
Any thoughts on James Fisher And Sons (LON:FSJ)? It rallied over the week but results out today seem to have disappointed..
I too would be interested in hearing Paul, Jack's or indeed other subscribers views on James Fisher And Sons (LON:FSJ) . Put it on the to do list recently but there's no doubt these results seem poor and if this is a turnaround, it is proceeding with difficulty, and slowly. That said, the recent (pre results) Cannacord note (available on Research Tree), entitled "Chasened", seemed to offer hope, based on the markets James Fisher And Sons (LON:FSJ) is addressing, combined with a renewed management self help, again re-instated in the commentary to these results.
Do readers here see potential, and rate the current management to succeed in returning James Fisher And Sons (LON:FSJ) to prior levels of glory?
Thanks Mark for adding perspective and Thanks Jack for your view above.
Morning Paul. Do you still have your BOO blog going? Would be interested to know your current views.
Paul: re Boohoo (LON:BOO) Thanks for the helpful analysis.
You wrote "Rumours from a usually good source (Betaville) suggest that the founders might take it private. I think that has some credibility. After all, why go through the rigours of being a listed company, if nobody is interested, and the rating is low?" ... and ... "these numbers suggest to me BOO is currently undervalued, hence I’m comfortable buying more."
That must mean that you think that, for BOO to be taken private, there would have to be a fair premium to the current SP. What sort of premium would be required, in your experience?
That must mean that you think that, for BOO to be taken private, there would have to be a fair premium to the current SP. What sort of premium would be required, in your experience?
Absolutely no idea!
The turnaround at Just (LON:JUST) seems to be gathering momentum, finally. The recapitalisation and reorganisation of the business is complete, and new business growth is solid. Reinstated dividend.
https://www.investegate.co.uk/...
Also, the Treasury review of Solvency II is a tailwind that would release significant capital for productive investment - although that's true of many UK based insurers.
timarr
Agree entirely on Just (LON:JUST) and think it is ridiculously undervalued at less than half TNAV. Dividend reinstatement will help particularly if they can move this up to the 3%+ mark which should be easily achievable. Now generating £50m+ p/a of own capital so that's good too.
£238m operating profit and targeting 15% growth p/a over medium term suggests at a market cap of £850m it's trading on 3* earnings and at 40p in the £. TNAV should be above 200p this year based on capital generation.
Usefully sensitivity to UK house prices has now significantly improved. A 10% immediate drop in house prices equates to an 11% drop in surplus capital. Given current capital position that should be more than manageable.
Hopefully if the market gets back to some sort of normality in the near future this will be recognised. I'd expect it to trade at maybe 80% of TNAV so nearer 160p feels like fair value to me.
I still hold some Just (LON:JUST) but sold a big chunk when they indicated previously that rising interest rates would have a significant negative impact. I see with these results that although adjusted profits were fine, IFRS profits were -£21m due to £251m of "investment and economic losses". The explanation for these is:
"Investment and economic losses for 2021 were £251m (2020: £9m profit). The main driver for the large difference compared to the prior year is the increase in risk-free rates during the year, which contributed losses of £226m compared to a gain of £360m when interest rates fell during 2020."
I can't say I feel comfortable with these being adjusted out of profits. Surely exposure to interest rate changes is part of their normal business? Neither do I feel comfortable with the throw away comment that "The Group actively hedges its interest rate exposure to protect the Solvency II capital position, but in doing so we accept the accounting volatility that ensues." What does that mean?
All a bit too opaque for me.
Basically as I understand from the report it means that they are liability and duration matching future liabilities and cashflows, which is sensible, but the instruments they use to hedge out interest rate exposure are seen as investments from an Accounting perspective and therefore marked to market. Thus whilst the end result (say 10 years down the line) will be more or less the same there can be significant gains/losses from these hedging instruments year on year.
So you do need to take them out of IFRS profit to show the adjusted profitability as this is the value the company is actually generating for shareholders. The ups and downs of the hedging instruments is effectively noise.
David, I didn't want to put this detail in my previous comment ... I originally assumed (in essence) the position that you describe, but what was not clear to me is how the corresponding gain is treated. They back out the losses on the hedge, so to arrive at the correct profit figure, they must either back out the corresponding gain on the position that they hedged, or that gain must not appear in the IFRS profit in the first place. I can't see any corresponding gain backed out, so the implication is that it's not in the original profit figure. But ...
The reason for the hedge is there to protect against increases in insurance liabilities. Higher rates help them by reducing future liabilities so the hedge works in the opposite direction. They confirm this by saying:
"Change in insurance liabilities was £1,039m for the current year (2020: £2,983m). The decrease is principally due to an increase in the valuation interest rate due to the rise in risk-free rates noted above."
So, the change in liabilities is less bad than last year because rates went up. If rates had fallen further, the change would have been worse. This is the movement that the hedge is there to protect them against, so this line and the hedge should be treated in the same way. But this "Change in insurance liabilities" is one of the key lines in the P&L (e.g. see page 14) while the hedge is excluded. So, at least on my reading, it appears that this is not a fair statement of underlying profit because profit and loss are not matched.
Note that although you talk about the "ups and downs" of the hedge, there is no guarantee that there are any ups at all, it might be losses every year until the hedge is closed. In which case what does that say about the accuracy of the adjusted profit? The loss never appears but the gain always does!
I'm not familiar with the relevant accounting treatments so I'm very willing to believe I'm wrong about this if you have the time to enlighten me, but I think it needs explaining, which is why I said ... opaque.
Just re-reading this I should have said that it is not the whole value of change in insurance liabilities that needs to be treated the same as the hedge, but rather that component that relates to changes in the risk free rate.
Acquisition announced by Wynnstay (LON:WYN) which is “immediately earnings enhancing” and extends their South of England footprint.
As Boohoo (LON:BOO) is now only £250m off the SCVR cut off, would you consider commenting here! :-).
Regards
Michael
£BOO I should have added that I hold and this was in relation to the TU this morning, which didn’t seem to say much.
It was my second largest holding and is now my second smallest!
Michael
Also Polymetal International (LON:POLY) is now down in SCVR territory. Is anyone feeling brave?
I can't bring myself to take a penny from Russia, sanctioned or not.
From the RNS yesterday it seems POLY expect the Russians to take the same view, so they really have to be valued on the assets in Kazhakstan alone.
yes but just a small position;)
I've lost quite a lot on £POLY but after much agonizing decided to ditch it today primarily on since the war started its been sitting very uncomfortably with me holding something thats helping fund the war. It would take a regime change and a significant change in their direction for me to buy back into anything relating to Russia.
I am currently working on cutting off all the Russian customers we have in the SAAS company I work for as we don't plan to work with any of them again for the foreseeable future and where possible we are returning them the money. Hard to know where the Russian economy is going to land but it's likely to be much smaller than it already is. Incredible to think before the crises the economy was smaller than Italy's and that beyond anything is Putins legacy to the Russian people.
Brookeda, a noble stand..hats off to you!
Paul
Thanks for the comments on £BOO. Much appreciated.
Regards
Michael.
There was a good set of results from Jarvis Securities (LON:JIM) offset by concerns about costs. Your comments would be welcomed.
John2: The market appears to disagree that the results from Jarvis Securities (LON:JIM) are good. The earnings per share (13.91p) are lower than the latest broker view (15.6p) that was increased at the time of the Interims in July. As this forecast comes from the house broker and is therefore the company's own expectations, it seems reasonable to regard this as a profit miss, despite the upbeat statement from the chairman.
I feel that the likely increases in interest rates should benefit JIM in the current year.
I would welcome Paul's view, if he has time to review the figures. He was very impressed by the Interim results in the July 15 DCVR.
I hold.
I agree, Jarvis Securities (LON:JIM) is a good company, decent results but a miss. Future looks okay.
Strong results from Capital (LON:CAPD):
· FY2021 revenue of $226.8 million, up 68% on FY 2020 ($135.0 million);
· 2021 EBITDA of $73.3 million, up 116.9% on FY 2020 ($33.8 million);
· Basic earnings per share (including investment gains) of 37.0 cents, up 108.2% on FY 2020 (17.8 cents); and adjusted earnings per share of 19.2 cents, up 141.7% on FY 2020 (7.9 cents)
Presentation at 9am: https://webcasting.buchanan.uk.com/broadcast/6221ec7cd196af24e1e91a0c
We're proud to announce that they will be presenting live and in person at the SCL Meet on the 23rd March: https://sites.google.com/view/...
There will also be short presentations from fellow private investors and Marks Electrical (LON:MRK), with the focus on the Q&A and plenty of time to meet other investors.