Small Cap Value Report (Thu 10 Oct 2024) - GMS, LIO, TET, ATG, RFX

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
** New SCVR summary spreadsheet for calendar 2024 ** This is the live one! (updated 6/9/2024)
Archive - SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia. More stock screening strategies here (possible bargains?) - 21/9/2024.
Companies Reporting
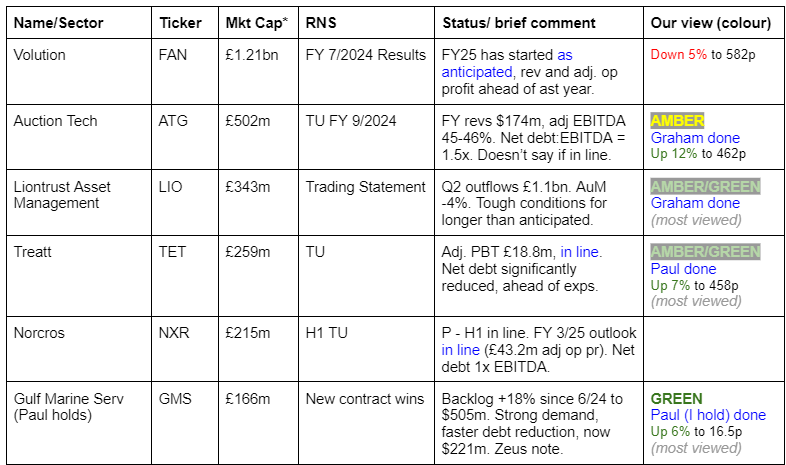
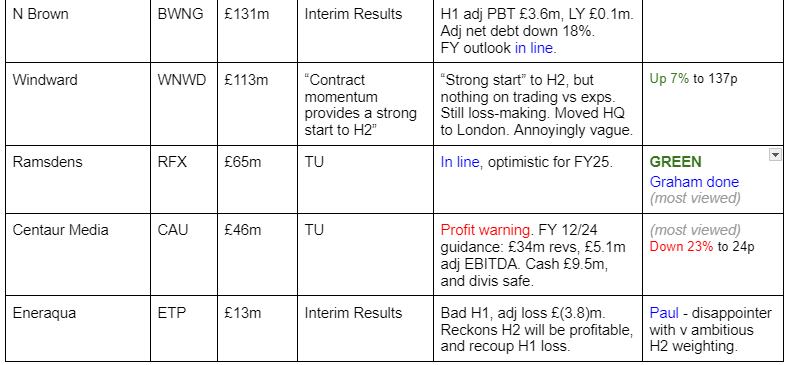
Summaries
Gulf Marine Services (LON:GMS) (Paul holds) - up 7% to 16.6p (£178m) - Contract - Paul (I hold) - GREEN
The already large order book grows another 18% in just 3 months after winning new & renewed contracts. Deleveraging is happening faster than expected, and is no longer a problem anyway. Shares seem irrationally lowly valued, with a deep discount to NTAV not making any sense to me, given the prodigious cash generation. Persistent selling related to Seafox may be distorting the market for GMS shares. OR maybe they know something that we don't?!
Liontrust Asset Management (LON:LIO) - down 4% to 508.5p (£330m) - Trading Statement - Graham - AMBER/GREEN
It’s no surprise to see more quarterly outflows at Liontrust. Budget anxiety gets the blame this time but over the last few years there have always been good reasons for outflows. 3-year and 5-year fund performance may not be helping. I’m staying lukewarm on this due to obvious cheapness.
Treatt (LON:TET) - up 9% to 467p (£283m) - Trading Update - Paul - AMBER/GREEN
In line trading update for FY 9/2024. Lacks a proper outlook comment for the new year. Net debt all cleared, and I confirm the previous balance sheet for Mar 2024 is strong, but had excessive inventories - hopefully since reduced. This share was over-priced in 2021-2, but now looks sensible value. I quite like it.
Paul’s Section:
Treatt (LON:TET)
Up 9% to 467p (£283m) - Trading Update - Paul - AMBER/GREEN
Treatt, the manufacturer and supplier of a diverse and sustainable portfolio of natural extracts and ingredients for the beverage, flavour and fragrance industries, today publishes a trading update for the year ended 30 September 2024 ("FY24").
“Strong H2 momentum with full year sales and profits in line with expectations”
Today sees a nice 9% bounce in share price, after a soft patch for the shares in recent weeks, despite this only being an in line update.
It’s still down YTD - with shares being on the main market, so not disrupted by possible AIM IHT sellers.
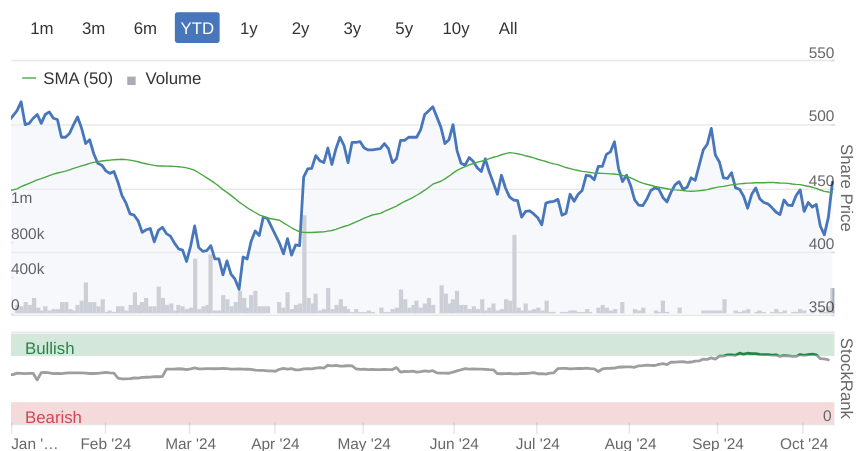
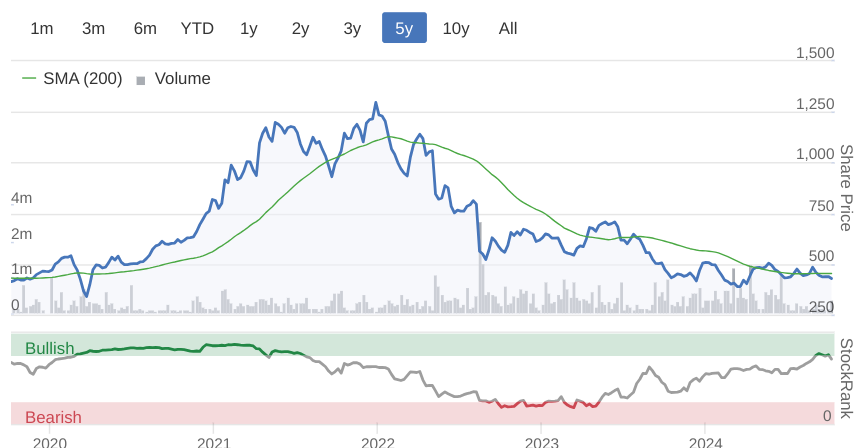
Longer term, TET shares became significantly overvalued in 2021-22, but are now down to a much more palatable valuation.
Revenues up an impressive 16% in H2, as demand normalises - it previously had customer de-stocking problems in Q1.
FY 9/2024 revenue growth of +5% (or +7% at constant currency) to £155.2m
Adj PBT up 9% to £18.8m, and in line with expectations - a healthy 12.1% PBT margin.
Net debt is particularly good, having reduced from £10.4m a year earlier, to a negligible £0.7m end Sept 2024.
Outlook - I would have preferred a more specific comment on the outlook, all we get is this vagueness. It raises questions when companies are vague about the outlook, and only comment on medium or long-term, so I think this could have been better worded -
“With our value-add products, and available manufacturing capacity following the investments in recent years we will start to target greater customer reach in adjacent markets and new territories. We are confident in Treatt's long-term prospects.”
Broker updates - nothing available to us, so I don’t know if brokers have adjusted the new year’s forecasts or not, I imagine not, since there were no surprises in the FY 9/2024 trading update.
Valuation - the StockReport shows middling valuation metrics as of last night. Remember that today’s 9% pop in the share price will move these figures adversely, so the forward PER will be c.17x now.
Also note the modest divis, but quite good asset backing (it built a sparkly new factory in recent years, to provide more capacity and remove production logjams from a previous hotch potch of facilities in the UK) -
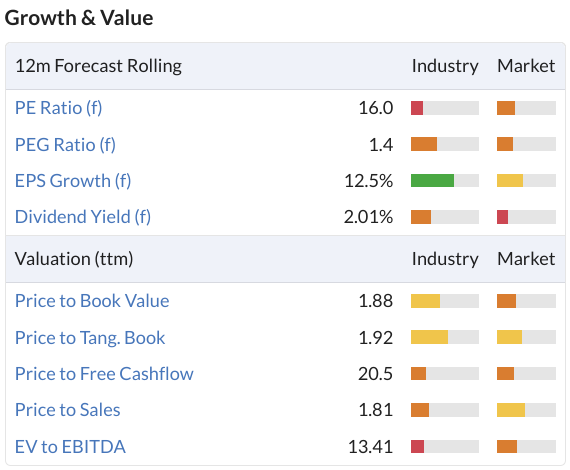
Paul’s opinion - in the past TET reached very high PERs, for reasons that didn’t strike me as terribly convincing - mainly that it would greatly increase production, and improve margins when its new factory came on line. Also that there are only a few players in this sector, and its European counterparts were also on very high PERs.
As it turns out, the financial benefits from the heavy capex look rather limited so far, but maybe there’s more growth to come now it has greater capacity?
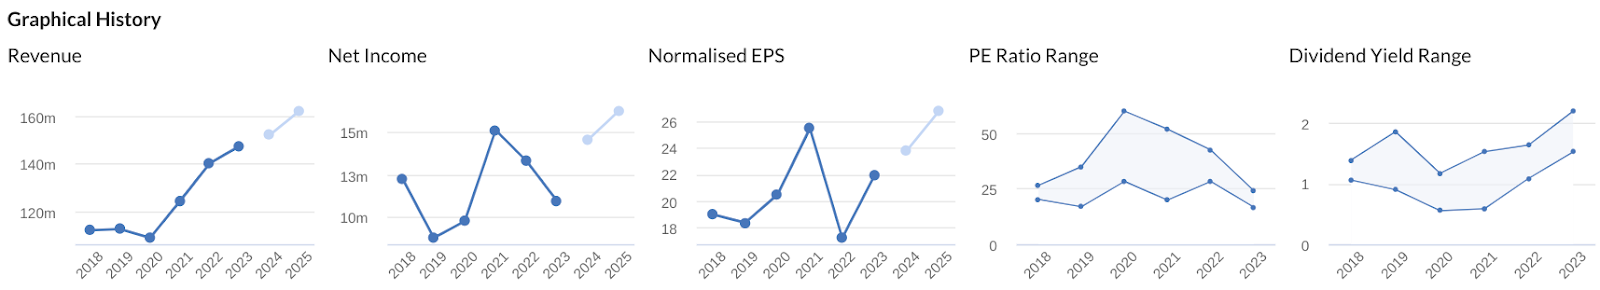
Still, it’s a decent business, making quite good margins, and now with a debt-free balance sheet. The last balance sheet was strong, albeit with excessive inventories, so I’d like to see some pruning of inventories in future. Maybe it stocked up to prevent supply chain issues disrupting production, who knows? That would be a good question to ask management - why inventories are so high, and if they’re tackling it to release tied-up capital? Inventories were £61m at Mar 2024, well over the entire cost of sales in H1 - indicating a risk of there possibly being a need to take a hit with a write-off?
Overall though, I see we were AMBER/GREEN twice earlier this year, and I’m happy to stay there. I think it’s a fairly good business, and now at a reasonable valuation too, so moderately attractive.
Gulf Marine Services (LON:GMS) (Paul holds)
Up 7% to 16.6p (£178m) - Contract - Paul (I hold) - GREEN
“Gulf Marine Services (GMS), a leading provider of self-propelled and self-elevating support vessels for the offshore energy sector…”
Contract wins take the already large order book up to a remarkable >$500m -
“award of a new long-term contract in Europe and the extension of two existing contracts in the Middle East, adding a total of twenty five months to the backlog, inclusive of optional extensions.
The current backlog totals USD 505 million, representing 3.3x 2023 revenue and a c.18% increase over that announced at the half year end on 30th June 2024. “
Great visibility, although as I’ve mentioned before, I’d like to ask the company what the contract terms are for any possible client cancellations? Ie how secure is this order book, if eg demand drops off a cliff for any unexpected reason?
GMS mainly operates in the M.East, out of UAE, hence some investors might have geopolitical concerns about that area, although UAE doesn’t seem to get involved in regional conflicts.
Today’s news doesn’t seem to affect forecast profits, as nothing is said about performance vs market expectations. However it does say the key issue of deleveraging is going better than planned -
“The strength of market demand is allowing the Company to meet its deleveraging goal quicker than anticipated…”
Although I would point out that the gearing at GMS is now normal, and no longer the crisis that it was previously. Bank facilities were renewed on normal terms, see our archive for more details, as I regularly update on this interesting value share.
This deleveraging means we should see dividends commence soon, and the dividend paying capacity of GMS should be prodigious if current market conditions of strong demand & large cash generation continue. Shareholders have been very patient, in waiting for the company to dig itself out of a deep debt hole, so I think they deserve some reward. The nightmare scenario is if the company makes the same mistake as before, and orders loads more expensive ships, financed with debt, right at the top of the cycle. Then a shortage of ships turns into a glut, daily rates fall, and we end up back at square one, fighting for survival.
I suspect that management might want to start ordering new ships to service the offshore wind market, a good growth area. Although no doubt competitors are thinking along the same lines, as I think we read something about the sector seeing more capacity in the pipeline. Hence the feast/famine risk with this sector.
Debt reduction is mightily impressive this year FY 12/2024 so far -
“Market fundamentals are steadily improving, allowing us to meet our deleveraging goals faster than expected. As of the end of September, our net debt has decreased to USD 221 million, down from USD 267 million at the start of the year and USD 238.5 million at the end of June.”
Remember that GMS has a fairly modern fleet of ships, and maintenance capex is only about one tenth of cash generation, roughly. As debt reduces, on improved terms, the finance costs decrease, which combined with more attractive terms on contract renewals has delivered remarkable cash generation, which looks locked in for the next 3 years.
The StockReport shows GMS shares trading at a big discount to NTAV, with a price to net tangible asset value of only 0.62x. Some people have questioned the value of the assets (mainly its ships), but given they’re generating huge cashflows, why on earth would they be worth less than book value? That doesn’t make sense to me, if anything maybe they would have a premium value?
The Stockopedia growth & value statistics show a high quality business on a bargain basement valuation -
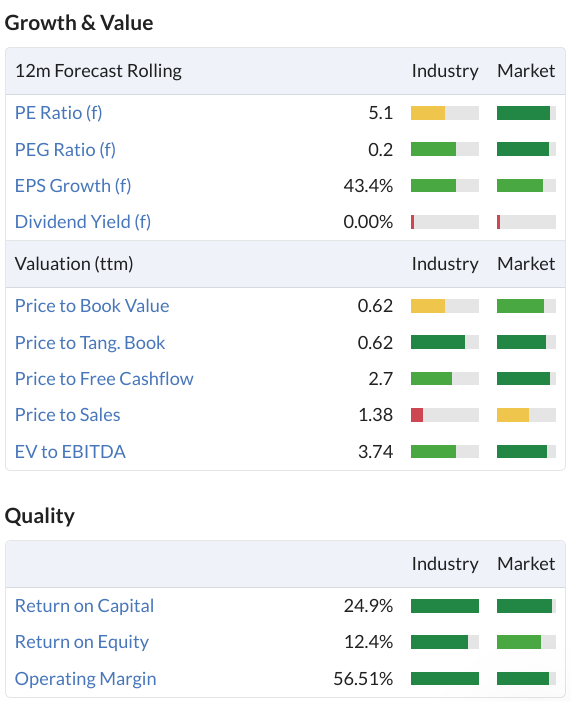
Overhang - the main issue here is that there’s been a selling overhang from the major shareholder Seafox, which dumped a chunk of shares at 17p when the price was 20p. Then it distributed some more of its GMS shares in specie (ie broke up its holding), to its own shareholders. Some of them might be sellers, as it definitely feels as if there’s still an overhang in the market.
Critics might say that given Seafox operates in the same space, and they seem desperate to sell out of GMS, then is this a warning that something might not be as good as it seems? Possibly, but people sell because they want liquidity, so it might have some other pressing use for the cash perhaps (maybe to finance building more of its own ships, given the attractive returns available)? Also it was originally a turnaround investor, so might just feel its job is done, who knows?
I tend not to worry too much about selling overhangs, as I feel that patient investors are being given a buying opportunity. Although sometimes it does transpire that the seller foresaw trouble ahead, so each situation is unique.
We’ve seen before in the recent past how surges in GMS share price seem to be sold into by sellers. Maybe the same thing will happen again?
For these reasons, I’ve decided to buy the dips, with a small opening position recently taken at c.15p. I’ll add to that if it drops back down to 15p again in the coming weeks.
GMS shares are main market, so we don’t have to worry about possibly disruption from any changes to the IHT treatment of AIM shares, it’s not relevant here.
Warrants - remember there’s dilution from warrants and share options which is quite significant, something like 13-15% dilution from memory, so that needs to be remembered when valuing this share, details are in our archive.
Paul’s opinion - today’s encouraging news just makes the already strong bull case even stronger.
I always listen to bearish arguments too, and none of them stack up for me. Even the cyclical nature of this sector shouldn’t be an issue given that GMS has 3-years bumper trading locked in with its existing order book, by which time it’s likely to have very little debt remaining.
The main risk is that management over-extend and order lots of new ships at the wrong point in the cycle, hence why I hope they prioritise divis, not buying new ships. Risk:reward overall looks very good to me. Any disruption caused by sellers won’t last forever, then it could re-rate. So personally I like to buy before the turning point, to lock in a low price, but some people prefer to wait for a favourable chart, and pay more.
A useful note from Zeus today confirms it's leaving forecasts unchanged. It has a higher EV/EBITDA multiple than Stockopedia, and points out that GMS isn't much cheaper than the oil services sector as a whole. Although the attraction is the GMS is generating so much cashflow and using it to deleverage, that the upside all flows to equity. That's the bit I like the most. So for me it remains firmly GREEN.
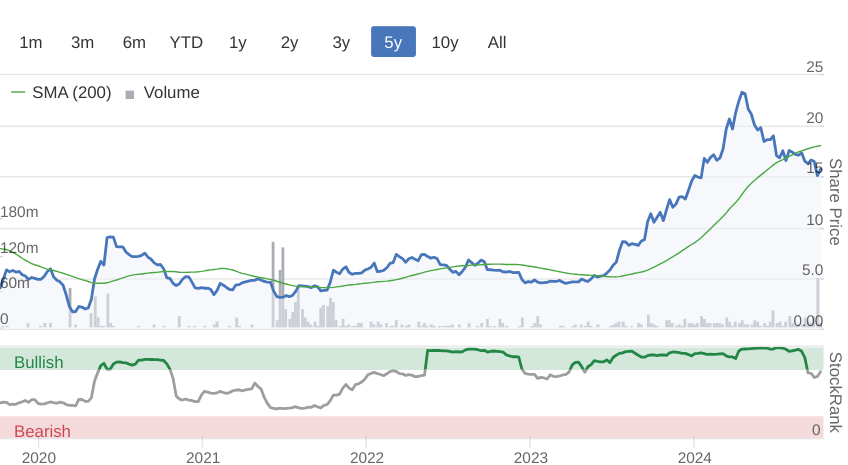
Still a very good recovery in the equity, despite the more recent pullback -
Graham’s Section:
Liontrust Asset Management (LON:LIO)
Down 4% to 508.5p (£330m) - Trading Statement - Graham - AMBER/GREEN
It’s a Q2 update (to September) from this fund manager, and the sequence of outflows continues: another £1.1 billion, up from £0.9 billion in Q1 (to June).
Assets under management and advice (AuMA) are down 4% over the period to £26 billion. The year-on-year decline in AuMA is 6% (from £27.7 billion in Sep 2023).
The CEO comment blames “speculation and uncertainty” around the upcoming Budget statement for hurting investor confidence - but of course the sequence of outflows has been around for far longer than Budget 2024 has been relevant! The CEO notes that “the challenging environment for active managers has continued for longer than anticipated”.
Other points mentioned:
New enterprise portfolio management system implemented.
The Global Equities team led by Mark Hawtin (recruited from GAM, which Liontrust tried to acquire last year) is now settled in.
Among UK financial advisors, GAM is ranked 4th best asset manager and 2nd for brand familiarity.
AuM/Flows
As usual, the net outflows during the quarter were concentrated in the UK Retail Funds category (£0.9bn), as that is where most of Liontrust’s AuM can be found.
The “Institutional Accounts & Funds” category saw nearly 10% of its starting AuM leave (£123m out of starting AuM £1.6 billion), as did the “International Funds and Accounts” category (£82m out of £900m).
Performance isn’t mentioned much in the commentary and so I’ve counted the figures in the performance tables today.
Results:
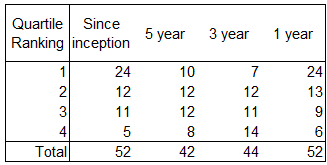
How to read this: this counts the number of funds in each quartile over each time frame.
So for example, over a 1-year timeframe, there are 52 funds. 24 are in the top quartile (top 25%) of performance, 13 are second quartile, 9 are third quartile and 6 are bottom quartile.
The 3-year and 5-year timeframes are worrying to me.
Over 3 years, the majority of Liontrust’s funds are in the bottom half of funds (3rd and 4th quartiles).
Over 5 years, nearly half (48%) of Liontrust’s funds are in the bottom half of funds..
Remember that this is not comparing Liontrust against benchmark indexes. This is only comparing Liontrust against other funds, which is usually much easier than comparing against benchmark indexes.
Also remember that these statistics are always subject to survivorship bias, as fund managers have a tendency to shut down or merge some of their funds over time, and new funds are created. Only 42 of Liontrust’s existing 52 funds are eligible for 5-year return statistics.
Graham’s view
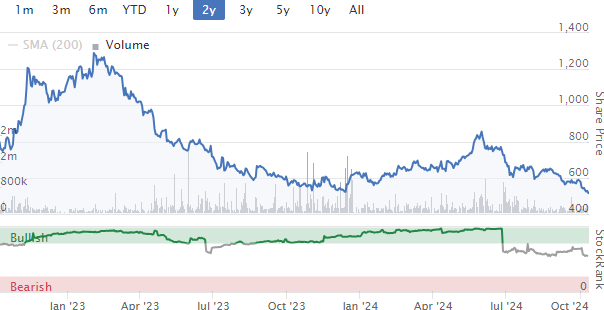
These shares are down by nearly 20% since I reviewed them in July. I am inclined to keep my mildly positive stance due to their extraordinary level of cheapness:
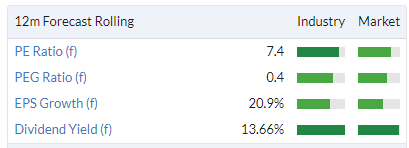
It’s true that I find other fund managers to be much more appealing investment opportunities than this one. I like fund managers with niche expertise, with lean operations and with simple fund ranges. Liontrust is not ticking any of these boxes for me as it seems to want more complexity rather than less. It wants to be the acquirer, while I would like to see it being acquired.
Therefore, Liontrust is one of the last fund managers I would add to my portfolio at this time. However, I still think that, like its peers, it does offer value to investors. The company somehow managed to post a loss in FY 2024, but that should not be a regular occurrence. Under different management or with a different strategy, I could probably be GREEN on this again. For now, I’m lukewarm.
Short Sections
Auction Technology (LON:ATG)
Up 12% to 463p (£563m) - Trading Statement - Graham - AMBER
Auction Technology Group plc… operator of world-leading marketplaces for curated online auctions, provides an update on its trading performance for the financial year ended 30 September 2024.
ATG owns a range of websites that host the sale of art, antiques, collectibles, industrial machinery, etc.
Cavendish have made no changes to their ATG forecasts but the market must have been expecting worse as it seems to like this update.
Key points:
Gross Merchant Value (value of goods sold) slightly negative year-on-year but trends are improving.
Revenues up 2% organically, up 5% in total to $174m.
Costs in line with expectations.
Debt: the year-end leverage multiple is expected to be 1.5x at year-end, in line with forecasts.
At the interim results, net debt was $142m and was declining year-on-year.
Graham’s view
I may have jumped the gun when I went positive on this one in January (at 542p).
Paul was AMBER/RED in July, though he acknowledged that such a stance “will be too harsh if it achieves current forecasts”.
Forecasts have only shifted down marginally since then:
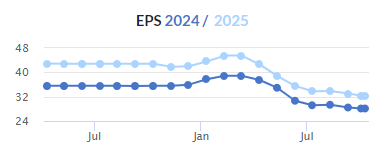
I think an AMBER stance is fair enough in these circumstances, considering the debt load and the continued presence of the private equity seller, TA Associates.
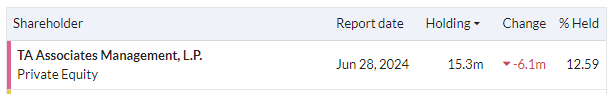
In a separate announcement today, we learn that ATG's CFO is stepping down and moving to a job with another private equity-backed company. He has been with ATG for eight years already, and will stay with ATG until next year to allow for a smooth transition, so I wouldn’t be inclined to read too much into this.
Ramsdens Holdings (LON:RFX)
Down 5% to 195.55p (£62m) - Pre-Close Trading Update - Graham - GREEN
A brief update that’s in line with previous guidance that PBT in FY September 2024 would be at least £11m.
CEO comment:
"We're pleased with the record profit performance in FY24. All key income streams are growing and we have optimism for further progress in FY25."
"This performance once again demonstrates the strength of our diversified business model which underpins our long-term growth strategy."
Graham’s view
No change in my view since the August trading update, which raised the PBT forecast from £10.5m to the current “at least £11m”.
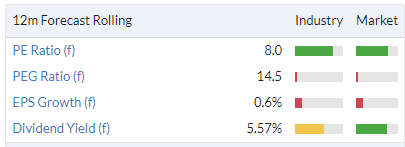
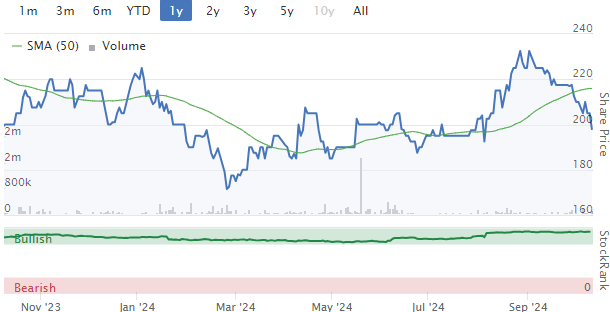
At a single-digit earnings multiple, I continue to have a high opinion of this company and its industry peer H & T (LON:HAT). RFX’s StockRank is an impressive 94.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

103 comments
Mr Scott - this is in the SCVR land.
British e-commerce firm THG (LON:THG) will proceed with plans to demerge its technology services arm Ingenuity into a standalone independent private entity at an equity valuation of up to 100 million pounds ($130.51 million).
The company, which owns online brands Lookfantastic and Myprotein, announced last month that it was looking into options for a demerger of Ingenuity - and can the focus on said brands.
THG plans to raise about 75 million pounds (lol - from who exactly :)) in equity via placing and subscription and a retail offer of ordinary shares, to ensure adequate levels of funding.
Founder and CEO Matthew Moulding is expected to invest £10 million in the proposed equity raise (brains, tax, needs to? to support likely).
Of interest as I got suckered in early day and its in the 'coffee can'. But there was a good story and I do protein suppliment things (rather than the bacon sandwich) but do not know who else in this space. But health and cheaper eating is not a fad.
Yes indeed, pricing of the THG placing will be announced in the morning. We're RED, absolute load of loss-making junk.
In theory, THG (LON:THG) should be worth c£1.5bn EV, by my calculations. This is doing a valuation of Beauty as a standalone, and valuing Nutrition based on Applied Nutrition potential price (£900-1bn EV), IF THG Nutrition manage to turn around its margins post-rebranding and get back to growth.
THG currently £800m market cap, £1bn EV (with the £200m+ net debt).
This somewhat chimes with the logic of this demerger. I guess they are hoping that the THG shares will re-rate 20-30% more, once Ingenuity is gone, and the next 6m results show Nutrition back to growth + improving profitability trend.
Gulf Marine Services (LON:GMS) I calculate :
1,069,946,316 shares in issue,
53.4m warrants outstanding at 5.75p,
Equivalent to 83m shares (x1.55 per warrant)
= 7% dilution
No biggy
Late announcement confirming bid for Cab Payments Holdings (LON:CABP) lowball offer IMO and I hold
CAB Payments Hldgs - Statement re Possible Offer #CABP @CABPayments https://www.voxmarkets.co.uk/r... #voxmarkets undefined
Jet2 (LON:JET2)
For the largest company listed on AIM, the share price has been remarkably resilient given the mauling received by other good quality AIM shares such as, in my opinion, Volex (LON:VLX) and Property Franchise (LON:TPFG)
Perhaps business is better than anticipated, but who knows given the current parlous state of the UK AIM and small cap market.
Probably the greatest FOMO megacap of all time.
Almost exactly 2 years ago - just before #ChatGPT was launched & became a 'verb' - NVIDIA (NSQ:NVDA) stock was trading at $11.25.
Since then NDVA has more than 11 bagged to $133 - and is currently the world's 2nd most valuable stock, worth some $3.2 trillion (or >20x EV/sales).
What's more few investors today feel the business is benefitting from an enormous & probably unsustainable growth spurt (re training GenAI/LL models) - effectively bringing forward GPU demand.
Meaning there is likely be a lot less FOMO around in 3-5 years' time.
Just had a phone call about this so I will take their word for it as I trust these people 100%.
You used to value Rosslyn Data Technologies (LON:RDT) on 7X and you thought it was so undervalued! so valuing NVIDIA (NSQ:NVDA) on 20X (although this falls to less than 10X) in 2027 I personally think that this is a bargain!
All the best
The party must deflate back to mean from tea leaf analysis
Weekly Stocko chart of SPX - very nice - beautiful rise.
Mean reversion kicks in at some point so 5400 will reconsider the narrative.
Can put into a folio on stocko and alert and forget about it - but when the email comes in then don't ignore. These are good signals (Chinese rice traders) and then DYOR.
Following on from the GBP 200k purchase by the CEO, Vistry (LON:VTY) major shareholder and board member Usman Nabi has just bought GBP 7.5m in shares. Not massive relative to his huge holding, but not insignificant either.
Vistry (LON:VTY) . Thats a huge share buy. Yesterday’s purchase by the CEO hasn't stopped the shares sliding further today. I think I read somewhere ( maybe even here) that the black hole in the numbers only came to light last friday. Maybe the market is sceptical that the matter had been fully investigated and resolved in such a short time by the following tuesday ?
Maybe the market is sceptical that the matter had been fully investigated and resolved in such a short time by the following tuesday ?
I think you can count on that being the case.
Vistry (LON:VTY) So until they fully explain in detail what has happened and why they are so confident the issue has been bottomed out, the shares will probably not recover. However much the wealthy directors throw at it !
Any chance, if time , on Volution (LON:FAN) . It seems a typical company for this thread. And , by my standards, I’m a large and enthusiastic holder.
Anyone have any thoughts of Intercede (LON:IGP) taking a 11% dip today? A product of them not mentioning profits in their recent update perchance?
I think it is the whole panic over AIM IHT storyline. If you look at Intercede (LON:IGP) trading update last year, it followed the same format (only commenting on revenue and cash), upgrades then followed when I guess they have more certainty over how the year will then turn out.
Re Intercede (LON:IGP) , my guess would be some profit taking as the valuation had got a bit lofty, allied to the lack of clarity on the outlook and of course, concerns around the possible removal of IHT relief in the budget. Intercede (LON:IGP) is AIM listed and rightly or wrongly, I have trimmed many AIM holdings in advance of the budget. If others are doing the same then pressure will be downwards across AIM until we have clarity. I realise timing the market is a dangerous game, but with such a clearly signposted risk ahead, it seems sensible to use our single greatest advantage as PI’s - that being our agility.
On that note and for better or worse I just added to my pension which by definition has a much longer term horizon than my trading account!
Paul, Re. Treatt (LON:TET) inventories, you can gain a lot of insight from the annual report.
The inventories figure is helpfully split into 3 sections; Raw Materials, Work in Progress & Finished Goods.
Raw materials as a % of COGS have averaged 22.1% over the 20180-23, with a spike to 30.4% in 2022 caused primarily by citrus price inflation. Last year saw a return to 23.5%. Nothing to see here.
WIP as a % of COGS has averaged 21.7% over the 2018-23 period with 2023 reaching 24.5%. This equated to an absolute number around £2.5m higher than the long term average. Nothing to see here.
The only area of real volatility is in finished goods, which averaged 4% of COGS from 2018-2021 before jumping to 15% in 2022 & then reducing slightly to 12.8% in 2023. Financially this equates to TET carrying ~£10m more finished goods than previously, however I believe this can be explained by industry destocking reducing expected sales (£13m of finished goods = just over 1 months sales, which seems to tally with customers saying they don't need quite as much as usual?)
They also state inventories net of an impairment provision of £2.8m, which notably was reduced from £3.6m the year before.
Overall, it looks like Treatt are at the bottom of their cycle & I think they should have been rated GREEN. Their cash generation has been superb & they are trading at 2x tangible book, which is half their 2017-2023 average. A high quality GARP stock in my opinion.
Hi Paul
Like many other industries, I believe customers of Gulf Marine Services (LON:GMS) can cancel their O&G/renewable energy orders (see below), but would also incur financial penalties for doing so - ie depending on the specific contract T&Cs.
Interesting comment from Chemring (LON:CHG) this morning who have announced funding from the Norwegian government for a feasibility study:
....... to assess establishment of a new explosives production facility with Chemring Nobel
Together with Chemring Nobel, the Government plans to look into the possibility of setting up a new production capacity for military explosives. To this end, the Government has decided to launch a feasibility study to examine all relevant factors and determine whether establishment of such a facility is viable. The Government will require such a facility to adhere to the environmental standards of the future. In addition to environmental aspects, the ability to recruit enough qualified staff and the facilitation of critical infrastructure locally, including sufficient power, are important factors.
Still in Norway, Alex Sweet of sweet stocks kindly looked at another Norwegian holding of mine ... BORREGAARD ASA (STO:BRGo. He liked it so much he bought a position. The write up is on his substack here: (6) Borregaard – an economic castle protected by an unbreachable moat (substack.com)
Bytes Technology (LON:BYIT) - has anyone caught wind why this is almost down 6% today? It's recent TU was fairly positive and its accounts are out on the 15th Oct. Additionally, it's NOT listed on AIM.
Bytes Technology (LON:BYIT) - has anyone caught wind why this is almost down 6% today?
No. I hold and assumed it was just the usual market gyrations. There’s a lot of it about today. Or perhaps it’s Paul creating dry powder for AIM budget day!!
Bytes Technology (LON:BYIT) Probably nervousness ahead of the interim figures due in 5 days time. At the 4 month stage, the company said that growth had slowed down and with a prospective p/e of around 20, the shares are not cheap. Having said that, the track record is good and they are still growing fast and the company has £71.5million net cash. I hold and happy to retain
Bytes Technology (LON:BYIT) Probably nervousness ahead of the interim figures due in 5 days time.
But they gave some well-received hints in a trading update two weeks ago, so I still think it’s just volatility, perhaps a clumsy seller.
Re Gulf Marine Services (LON:GMS) is UAE domiciled…that makes the enforcement of shareholders rights in the event of anything going awry somewhat unpredictable…that coupled with an informed insider unloading large quantities of stock at seemingly bargain prices whilst the business is shooting the lights out would suggest caution might be appropriate. Obviously this could just be sour grapes from an ex holder who was flat out lied to by a previous director before it all went awry the last time.
BnB may well be right about the direction of the market, especially small caps heading south and AIM is absolutely friendless and will remain so until the budget and clarity as to where the tax axe will fall.
But much of the uncertainty appears already to the in the price of several companies .
Companies auch as Ramsdens Holdings (LON:RFX) provide a confident update and the shares, already cheap drop over 2%. Ben Graham was right in the short term the market is a voting machine, in the long term it is a weighting machine.
Big gap down down in FW Thorpe (LON:TFW) on no volume today. Perhaps more AIM BPR panic. This was my mystery share from last week”s reports that I mentioned I was going to add to the BnB Fund during my brief interchange with Paul on Monday regarding the absence of his mystery share! I”ve jumped on the drop to complete my position.
The curse of BnB suggests you can expect further falls!
Norcros (LON:NXR) - the H1'25 pre-close statement infers that headline trading in Q2 was similar to Q1, leaving group revenue flat overall y-o-y for continuing businesses. On the same basis, while profitability looks to be slightly lower - which may reflect mix effects - company expectations for the full year are unchanged.
While easing inflation and interest rates have been welcomed in Norcros’ primary markets, any significant pick-up in economic activity is still pending as new governments bed in in both cases. H125 LFL revenues nudged ahead in the UK (continuing operations +1%) and declined modestly in South Africa (-2% at constant currency) giving a flat y-o-y performance at group level, excluding the exited Johnson Tiles UK and Norcros Adhesive businesses.
Our expectation is that management will report more fully on strategic actions taken to date with the H124 results. The completion of Vado’s warehouse consolidation moves and streamlining Grant Westfield’s distribution are two examples of positioning these businesses for growth with more efficient service platforms and greater alignment in these areas across operating companies.
We make no changes to our estimates or fair value ahead of the H1 results due out in November. As before, we believe that translating strategy into enhanced earnings growth can be the catalyst for generating share price upside that could be well in excess of our current fair value of 253.5p / share.
Link to note: https://www.equitydevelopment....
Norcros (LON:NXR)
cheers equity development - Norcros (LON:NXR) is one of my larger holdings. Note although its still cheap based on current p/e or 7.6 per stocky - it has probably been cheaper in the past as its always commanded a stingy rating most of the time. So for me up to now uplift from 160p-180p ish buying price to current price with divis paid makes it solid tickover hold. I suspect the risk is on the downside this year ref hitting profit expectations - and also they have flagged 10% expected uplift next year so perhaps the economy needs to get moving in that regard for that taregt to be doable (plenty of time as next year doesnt start till april)
So its back to the the anemic growth of old temporarily - thats not necessarilya terrible thing here - with low pe doing nothing they chuck out buckets of cash and another year means the pension scheme assets should trend down further again de-risking pension.
So nowhere near my list of top up shares at present but i am happy to hold and if they hit forecasts for this year and next it would nice to think that shares could trend towards the 300p mark - perhaps wishful thinking on my part.
In the meantime steady pair of hands making business as efficient as possible - simple stuff done without much fanfare - eg update below all in transparent fashion.
During the period we successfully completed the consolidation of the warehousing and distribution functions at both Grant Westfield and Vado. One off cash cost, associated with this investment of circa £2 million will be reported separately as an exceptional item.
Avation (LON:AVAP) for anyone interested there is a good interview with Jeff Chatfield on Zeus - an alternative perspective. In it he talks about the market dynamics, the fact that aircraft supply will be very restricted for many years to come and that residual aircraft prices therefore continue to rise thus supporting and growing NAV even by doing nothing.
They reduced debt by 10% last year which transfers to equity because the planes are not depreciating, they are increasing in value. There is an opportunity for refinancing on the bonds which increases profits and reduces interest - he thinks about 2% diff on the bonds which is material - prob adds $7-8m in profits.
He also talks about the fact that any merger activity occurs at NAV (which in Avation (LON:AVAP) case is 275p and going up). He also points out that they currently hold more cash than the market cap.
Finally with the planes on order he is asked about where he thinks the overall business gets to in 5 years time and he thinks it doubles. Assuming NAV follows in line then 600p would be realistic. Risk/reward looking favourable to me. Probably requires patience - ie long term hold but now feels like 20%+ p/a total return is more than achievable.
Foresight group (LON:FSG) - six monthly update looks good to me....the share price graph has a nice upward trend generally. Stocko gives it an 87 score overall. Any thoughts Paul or Graham? or anyone else? I can see it's a busy day though so Foresight group (LON:FSG) might not make the cut...
This company has caught my eye over time - they sold their Forestry subsid not long ago - which may well have been a distraction but I would want to learn more of the rump of their activities - not just figures.
I have a nice profitable holding here ,as it has growth sieved several time over the last 18 months. Please note today it is in the Slater zulu holdings this morning. Decent divi too, Tony
Gulf Marine Services (LON:GMS)
Looks like its debt is reducing at a rate of $6m a month which should clear it all in about 2.5 years (probably quicker if interest rates come down).
After that is done, that is a lot of free cash flow that could come back to shareholders in the way of dividends or buy backs. The $500m back log of orders further underpins this story, as in the business is already won, it has the orders, doesn't get more reassuring than that.
Yes 2.5 years is a long time and a lot can happen but the reward is pretty decent in my opinion for those prepared to wait.
The award of a contract for a second vessel, as announced today, for offshore wind in Europe, is also quite significant imo. They have one E class vessel, their largest size, in Europe already. I assume the contract today is for another E class vessel. E class vessels are the most expensive to hire as they're the largest vessels and historically, the utilisation rate on these vessels has been lower than their other classes because their large size has meant demand is less for them. Their current E class vessel in Europe was also hired on a 3 yr long term contract, longer than their average contracts, so if this new contract is for the same length then that's more good news. The fact they're willing to go to time and expense of moving an additional vessel from Middle East to Europe shows that new contract is probably for more & longer than average contract. It diversifies revenues and taps into booming European offshore wind market, where there's huge demand for specialist offshore vessels.
Hi Burnt Onions - looks to me like it’s more like $3-4m p/m debt reduction. The $3m from mid Sep is almost a months worth.
Over time the debt value will transfer to equity agreed, the main issue and risk is the escalating tensions in the Middle East. The share price is held back by an overhang.
I’m not long yet but I do like the story and will probably buy at some point.
Hi David, Gulf Marine Services (LON:GMS) , sorry to nit pick but i think it is $6m a month not $3m, have a look below at the Zeus balance sheet forecasts plus a debt reduction of 238.5m to 221m (June to Sept as per their statement) is approximately $6m a month, no?
Always highly respect your opinion on this forum but I think I am right on this one....
Hi Burnt,
Zeus though say in their note that debt has reduced from $224m to $221m since mid September which is c. $3m in a month.
They also show debt reducing from 275m to 220m this year which is 55m which is 4.5 p/m
Next year they reckon close to 6m p/m at a 70m reduction but not entirely clear to me why that ramps up.
Anyway, I don’t disagree with the overarching theme that debt is reducing rapidly. I just like to be cautious when it comes to debt and prefer to assume reduction at existing rates rather than forward looking expectations.
I do wonder what is going on at Seafox but looks a good business. I like the fact that the equipment can be used for multiple purposes and not just O&G as that reduces the risk of a slump in rig rates causing a terminal decline.
reGulf Marine Services (LON:GMS) - Paul mentions Seafox - They made an offer back in 2020 so I guess not surprising they now want to sell, but I would not discount the competition going forward. The list of major shareholders includes Feira Capital fund manager but also institutions Ive never heard of - Who are they
Avingtrans (LON:AVG)
Adaptix has been named the most exciting emerging technology at the Aerospace Innovation and Technology Awards 2024.
Not financially relevant at present, but is a further endorsement of Avingtrans investment in medical imaging. Adaptix 3D X-Ray imaging device has FDA 510 approval and has commenced sales for use in veterinary work to be followed shortly by use in orthopaedics.
My morning smallcap tweet: Bish bash loss
Eneraqua Technologies (LON:ETP) Centaur Media (LON:CAU) Auction Technology (LON:ATG) Norcros (LON:NXR) Windward (LON:WNWD) OptiBiotix Health (LON:OPTI) Gulf Marine Services (LON:GMS) N Brown (LON:BWNG), Treatt (LON:TET) Ramsdens Holdings (LON:RFX)
◄Eneraqua Technologies (ETP)► H1-July rev up 15%, adj pretax -£3.8m (-£0.4m). Blames increased loss on "reduced Gross Margins and an increase in operating expenses [needed to achieve] operational capability required to deliver forecast contract volume in H2". Expects FY adj profit in line. [SP=39 Cap=13m]
◄Centaur Media (CAU)► warns FY24 rev only £34m+ at an adj EBITDA margin c.15%, significantly below the 'analyst consensus range' [sic]. Blames weak market. FY25 also hit. [SP=30.75 Cap=47m]
◄Auction Technology (ATG)► guides FY-Sep rev $174m up 5%. In line? Says that's good progress but 'headwinds in the underlying end markets have yet to reverse'. [SP=412 Cap=501m]
◄Norcros (NXR)► guides H1 rev down 7% (largely due to the sale of Johnson Tiles UK) but flat on a constant currency LFL basis. Guides FY U/L op profit in line. [SP=237 Cap=213m]. I hold.
◄Windward (WNWD)► claims strong start to H2. In line? Yet another co which is "laser focused on achieving profitability". [SP=128 Cap=113m]
◄OptiBiotix Health (OPTI)► Brunel University of London reported study results "showing significant impact on multiple parameters important to appetite and hunger regulation" from SlimBiome. [SP=14 Cap=14m]
◄Gulf Marine Services (GMS)► wins new long-term contract in Europe and the extension of two contracts in the Middle East. Backlog total $505m or 3.3x 2023 rev. CO will meet its deleveraging goal quicker than anticipated. [SP=15.55 Cap=166m]. I hold.
◄N Brown (BWNG)► H1-Aug rev down 7% and adj pretax £3.6m (£0.1m). Guides FY adj EBITDA in line. Not rev then, I infer. [SP=28 Cap=131m]
In line: TET, RFX
Woodford views a little ray of positivity going into the budget...due to positive nominal GDP revisions tax receipts should be high enough to cover the black hole. I find it most interesting that I tend to agree with most of what he writes even though I don't want to. I can't help being drawn to people willing to be positive at the moment.
An interesting turnaround in the relative fate of HK and China overnight .. with HK +4% Vs CSI +3% ... back to positive for the month etc etc....
Its CPI day... since we looked at the US Treas spreads yields have risen..20-30bps but the curve has flattened slightly. This would suggest the market is discounting a bit more inflation but less growth. So I say inline or slightly lower will be good for more rate cuts argument and a higher number may cause more flattening. Bond vol is high with MOVE at 122....suggesting the market expects fireworks. We see.....fingers crossed for a dull inline with a month on month sitting at the 0.2%.
Morning RDHOWARTH,
Woodford's blogs on economics are interesting, and always worth a read.
One thing I learned from his recent blog was that the UK Govt is heavily exposed to index-linked Gilts, so the interest payments soared during high inflation, but are now a favourable tailwind as the interest payments normalise.
I also note that the press are now speculating Reeves could increase employers' NICs in the Budget. That sounds credible to me, as most people are not even aware employers NICs exist, and it doesn't affect their net pay. So looks a likely target I'm guessing, as it would raise a decent amount of extra tax revenue if say raised 1%, and would be consistent with promises not to take more tax from working people. Who would suffer? Obviously employers where wages are a high % of their costs - off top of my head hospitality, retailers, professional services, etc.
Also I should remind people that political stuff which directly affects markets & investments is fine to discuss here, but we prefer it if people don't post blatantly political comments that don't even mention markets or finance. They're boring & irrelevant, cluttering up the comments section. Thanks.
Regards, Paul.
1% is perhaps neither here no there but uk based business have already had corp tax increased 6% recently and dividend tax raised - why not tax the overseas based entities sucking cash out of the uk instead ?forget lack of investment- if cash departs the uk with little taxes paid it won’t be recycled and that’s what is needed to keep things ticking over every pound spent bsvk in uk will earn some extra tax revenue normally. Not against uk based business paying fair share but seems they are number one whipping boy at present
I think the other trade off Paul will be employers won't be offering as generous pension matching perks, as an example when I worked for Aviva many moons ago from memory if I paid in an extra 8% of my salary to the company money purchase pension they would match with another 8% their end on top of the standard 8% of salary they paid in regardless of matching.
The main incentive for employers to do this is the employer national insurance saving so my guess is moving forward if it happens employers will be far less generous with pension matching post end Oct 2024.
So ultimately people will be poorer in retirement two interesting stats the state pension alone now accounts for 12% of the entire UK tax take and from memory (again) debt interest payments of close to 100 bil per annum account for 10% of total tax take.
The other point to remember is for years UK Government could borrow sub 1% lots of that debt will be rolling off ultra low rates and will need refinancing at nearer 4-4.5% moving forward.
An interesting counterpoint on the state pension costs is that with the rate bands remaining unchanged an increasing number of pensioners will be paying income tax for the first time or paying larger amounts than before. Initially the effect will be small, but I suspect it will be a “hidden” tax benefit to the government before very long especially as the triple lock promise will accelerate as inflation reappears, which it surely must as employment costs rise.
Hi RDHOWARTH,
I do enjoy reading your macro posts, thanks for doing these. Interesting comments from Rachel Reeves at an FCA event on Tuesday, if I interpret the tone correctly, it would seem a complete contradiction to the message if AIM IHT rules then get changed.
https://www.cityam.com/rachel-...
RD you are mustard on the macro how about a daily RD macro ramble to complement Mr Contrarians daily small caps results round up.
Minor beat by Treatt (LON:TET) on revenue and PBT, although EBITDA - and presumably EPS (not quoted) - misses slightly, without any detail on outlook. But expectations-beating cash generation leads to a higher level of debt reduction, almost to the point of extinction - the debt, not the company. Coffee is the stagnant stream, while tea and citrus flow nicely.
I think the market will focus on the debt reduction at Treatt (LON:TET) and the rating discount to its peers and send the shares higher today. Numbers look solid overall and this well invested business with a great runway for growth with its new expanded facilities is a core long-term holding for me.
Polar Capital Holdings (LON:POLR) - link to new research note: https://www.equitydevelopment....
AUM increased 4% over H1-25 (1 Apr 24 – 30 Sep 24) to £22.7bn from £21.9bn on 31 Mar 24. It was a half-year of two quarters with Q1 AUM up by 7.4% (net inflows: +£644m, investment performance: +£978m), while a more challenging and volatile market environment saw Q2 AUM down 3.5% (net outflows: -£172m, investment performance: -£655m).
The marginally negative net flows of Q2 (0.7% of AUM) were not a surprise for a period of investor nervousness, with UK investors withdrawing from equity funds in the latter part of the quarter (see page 2). And the negative investment performance of Q2 occurred in a period which saw an equity sell-off and a significant currency headwind on those assets held in US$. Polar’s reporting currency, GBP, strengthened by 6% over the US$ in Q2 from 1.26 to 1.34.
Other than adjusting performance fees, forecasts are unchanged. We note our end-FY25 (31 Mar 25) AUM forecast is £23.5bn, only 3.5% above that of 30 Sep 24. Our fundamental valuation remains 650p, 22% above the share price. With its strong profit margins, balance sheet, and a dividend yield of 8.6%, we think Polar Capital should trade at a substantial premium to its PER of 12.6.
Liontrust Asset Management (LON:LIO) trading update: reduction in AUM and making their point.
Labour's pro-growth strategy looking more like anti-growth so far. This (Labour, not Liontrust Asset Management (LON:LIO) feels a bit like a company reducing expectations so at a later date they can say they are ahead. Seems like the best outcome we can hope for.
Very pleasantly surprised today as a Jupiter Fund Management (LON:JUP) holder that the shares didn't sell off majorly as they're heavily uk focused similarly to the most underperforming parts of Liontrust Asset Management (LON:LIO) /
Oh sh*t! Firms urged to brace for AIM turmoil
https://edition.pagesuite.com/...
Depressing, loose talk causes chaos, so much for a government for growth
Article seems sensationalist to me. Says one unnamed investment bank has told its clients to prepare proactive plans in the event of a change to BPR on AIM companies. We don't know what or if it will happen but the removal of BPR from AIM shares is of concern. Any well run company should prepare for all eventualities.
Plenty of AIM stocks have dropped 20 - 30% on no news recently; Volex (LON:VLX) System1 (LON:SYS1) Journeo (LON:JNEO) to name three that I own, so hopefully (!) we may be nearing the point that the IHT removal is priced in. Probably not quite reached capitulation point yet though. I'm hoping for a rally in the days before the budget but who knows!
well even though I hold a few AIM shares, I hope they do remove IHT relief, and that they drop 30%. There are a few good companies there, and I'd love to scoop up more shares at a big discount
Hi dodge1664,
"well even though I hold a few AIM shares, I hope they do remove IHT relief, and that they drop 30%. There are a few good companies there, and I'd love to scoop up more shares at a big discount"
Excellent post, I agree that this is a time to be planning for scooping up some potentially wonderful bargains, if the IHT relief on AIM shares is removed. That could give us some stunning buying opps.
Hence I'm trimming back on some main market shares, to build up a cash pile for pouncing on bargains. If it doesn't happen, then I'll just buy back my main market positions.
I don't believe the AIM IHT relief is justified. The evidence for what shares are held in IHT portfolios is that it's a fairly narrow set of mature companies that don't need to raise any fresh capital. So it's not attracting in money for entrepreneurs to expand. That area is better served by EIS, SEIS, and VCTs, where the tax break is much better deserved for taking high risks to fund small, growing companies.
Regards, Paul.
I think at least some of the reasoning behind the AIM IHT relief is to enable small businesses to change hands intact when their owners die.
Hi Paul,
Have you got a list of potential AIM stocks that might be worth looking at? tia
Mark wrote a good article yesterday.
That may be true but the timing and uncertainty around this couldn’t be much worse after 3 years of pain. https://news.sky.com/story/sco...
AIM--BPR and IHT
James Halstead (LON:JHD) , Cerillion (LON:CER) , Aquis Exchange (LON:AQX) , Cavendish Financial (LON:CAV) , Jet2 (LON:JET2) , etc.
One concern with the potential withdrawal of BPR on AIM shares isn’t being mentioned here. It is based on the concept of ‘what would I do’ (a principle which I haven’t found universally reliable over the years).
If I were a major shareholder in an AIM company and my heirs’ inheritance or my business (i.e. the business of the AIM IHT portfolio managers--Octopus, Canaccord, etc., although almost all of the big investment houses have AIM IHT services) depended on holding assets that qualified for IHT relief, I wouldn’t necessarily sell shares. I would ask the major shareholders if they supported delisting. A delisted company is entitled to BPR relief (currently, and unlikely[?] to change). With some of the companies I hold, this would be the obvious thing for major shareholders to do. I would, furthermore, be surprised if this discussion had not already taken place.
Here are two examples chosen because they are discussed on the SCVR rather than because they are at all unusual in their exposure to changes:
James Halstead (LON:JHD)- {waiting for clarity to buy}
Major shareholders (holding over 4%): Rulegale Nominees 17.5% (This is the nominee company for James Sharp’s clients. James Sharp runs an IHT advisory. James Sharp would likely vote for delisting.); John Halstead Settlement 17% (This sounds like a Trust. To avoid a capital tax [styled as inheritance tax] on UK Trusts, shares must be entitled to BPR. If this is a UK Trust, it would be foolish for the Trustees not to vote for delisting.); Octopus 6.6% (One of the most visible companies running AIM IHT services); Mark Halstead 6.4% (An individual and therefore mortal). Total visible % that would probably vote for delisting: 47.5%
Cerillion (LON:CER)- {I hold.}
Major shareholders (holding over 4%): LTH (an individual & the CEO, presumably mortal) 30.5%; Livingbridge (VC firm, probably agnostic as to BPR) 17.8%; Gresham House (likely to be part of IHT portfolios) 9.6%; Rathbones (have an IHT service) 9%; Premier Miton (no idea, but probably prefers continued listing) 4.4%; Canaccord (probably part of the IHT service) 4.4%. = 53.5%
There is a requirement for a 75% vote (of those voting) for a company to delist from AIM (although not paying your NOMAD is another route for removing a listing). There will be non-visible AIM IHT advisors holding shares for clients, and many individuals who would be happier to hold unlisted shares if the AIM exemption is removed. Announcing that there will be a vote to determine if shareholders want to delist usually causes a panicked exit.
I wouldn’t consider it safe to continue to hold every company I now own if decisions were taken to delist.
Some companies, judging by shareholder lists, look like they are destined to remain public (e.g. Fevertree Drinks (LON:FEVR) , Impax Asset Management (LON:IPX) , Polar Capital Holdings (LON:POLR) , Jet2 (LON:JET2) …{I hold the last three}), so they would receive some selling pressure from IHT portfolios. I anticipate that this could begin quickly but continue for many years; it isn’t easy to unwind positions of 15 to 30% in a smaller company.
I’m finding risk management quite challenging. The potential outcomes could be extreme.
My strategy: Selling the majority of AIM shares is not feasible for me (CGT, upcoming Principal Charge, etc. {the Actuaries are complacent, but you never know…}). I have sizable holdings in several AIM-listed companies that would be hit by the loss of BPR. Some companies’s shares are very good value today; if I waited to buy more until budget day, those low prices would be gone because I would be competing with everyone else who has been waiting for clarity. I have been on a partial buyer’s strike due to uncertainty, and I’ve unloaded some companies’s shares where my conviction does not outweigh the risk. There is some cash waiting to catch any bargains.
Speculation: I’m hoping that the Aquis market will retain its unlisted status and there are prepared RNSs ready to be issued from every affected AIM company concerning an immediate switch to Aquis. {I own Aquis Exchange (LON:AQX) & Cavendish Financial (LON:CAV) which would benefit from this.}
I’m not in a position to second-guess the UK government. I presume that they don’t want to cause another Liz Truss moment (in the AIM, this time), but ideology (etc.) can get in the way. It isn’t an instant way to raise cash, either, so won’t fulfil immediate objectives. Changes may cause great losses to be set against CGT, giving a fiscally negative result for many years. –And it is complicated; AIM isn’t the only market officially considered ‘unlisted’ ( https://www.gov.uk/government/publications/designated-recognised-stock-exchanges-section-1005-income-tax-act-2007/designated-recognised-stock-exchanges-section-1005-income-tax-act-2007-v3 ).
Cavendish RNS 7.x.24: We have been working with our clients to plan for any adjustments which could be needed.
Investment trusts don't qualify for IHT relief as far as I am aware?
Investment trusts don't qualify for IHT relief as far as I am aware?
As you imply, Investment Trusts don’t qualify for IHT relief.
I’m assuming that I wasn’t making a clear enough difference between a Trust (a legal person set up to protect or direct money that is given away by a settlor—often as part of a will or to support vulnerable family members) and an Investment Trust (a listed, closed-ended vehicle for pooled investments)...? Trusts are charged IHT every ten years on the capital value of the Trust.
You refer to IPX and POLR both of which are I believe investment trusts and therefore considerations as to delisting would not apply?
You refer to IPX and POLR both of which are I believe investment trusts and therefore considerations as to delisting would not apply?
Ah, I see what you mean.
Polar Capital Holdings (LON:POLR) and Impax Asset Management (LON:IPX) are asset managers. Some of the funds they run are Investment Trusts (e.g. Polar Capital Technology Trust (LON:PCT) is a fund in the Polar Capital stable and Impax Environmental Markets (LON:IEM) is an Investment Trust managed by Impax). It is my understanding that Asset Managers are eligible for IHT relief as they are trading businesses.
Some highlights from the article: scrapping IHT on AIM could raise about £1.6b pa. £6b of IHT vehicles could be affected. Scrapping the tax break could cause and immediate 20-30% loss across AIM.
AIM reached a high of ~800 in May 2024, now 735, down 8%. An immediate 20% further loss sounds hyperbolic to me, but I guess we'll see.
I agree that the 20 to 30% drop in AIM shares sounds overdone.
It is far from certain that Reeves will scrap Business Property Relief.
Less that 5% of estates pay inheritance tax. I would be surprised to learn that a large proportion of those estates own large quantities of AIM shares.
I only own two AIM shares, Renold (LON:RNO) and Warpaint London (LON:W7L) . Both shares have performed badly recently, despite Warpaint London (LON:W7L) reporting record first-half results. I reckon a number of their investors have got their panic in early, accounting for the poor performance.
I hope I don't live to regret my decision, but both my AIM holdings are strong companies that are trading well. I will hold onto them and if a price drop does eventuate I will probably top up my holdings.
Reeves might decide to cap BPR at £0.5m per estate. Or she might only allow IHT relief on shares bought before 30 Oct. I'd expect that a former BofE employee would prefer to avoid creating a market crash. Rachel Reeves isn't another John mcdonald
Assuming there is a political decision to remove AIM BPR I think this will be tempered by knowledge of the real damage cliff-edge cessation of relief would cause the market.
With this in mind, the most likely outcome would be either a limited per estate (as you suggest) or have BPR being phased out in say 5 years. Not ideal but would provide certainty and reduce immediate impacts on the market.
I also hold Warpaint London (LON:W7L) and Renold (LON:RNO) plus another AIM stock trading well but with poor stock performance. I am holding my positions and top up if an opportunity presents itself. I wont be selling until there is clarity. We all need to get past this Budget at the end of month!
Eneraqua Technologies (LON:ETP) interim results CEO overview of today's results video & podcast.
There is a results webinar with Q&A today at 9am. Register here.
Liontrust Asset Management (LON:LIO) And conversley dissapointing to see a decline in AUM yet again, the small investor is plainly rattled. We need to get the budget behind us, the power of financial fear.
Yes, dreadful start by new government. This sums it up from Liontrust Asset Management:
The new government's large electoral mandate raised expectations of political and economic stability and a strong pro-growth agenda. The speculation and uncertainty around changes to taxation and reliefs in the lead up to the Budget on 30 October, however, have impacted investor confidence and fund flows for the whole industry including Liontrust. This has contributed to another quarter of net outflows as the challenging environment for active managers has continued for longer than anticipated.
And yet Polar Capital (POLR) report an increase in AuM. Maybe Liontrust need to be more self critical....
However compared to the previous quarter period the POLR AuM has also come down a bit by 3% I think.
Different periods - Liontrust Asset Management (LON:LIO) were reporting over the quarter, while Polar Capital Holdings (LON:POLR) is over the financial year. But I agree POLR looks to be holding up much better, thanks to its better mix of specialist funds (tech, healthcare, etc), while LIO is much more exposed to UK equities.
Agree with this, their recent deals aren't generating any meaningful returns, the last deal of any real note was their purchase of Alliance Trust . Seems like a company that has lost its way, and is trying to blame others for a mess of their own making. If they produce a marketable product then people will buy, if they can control costs and run funds with reasonable returns then people will buy.
This is the same company that spent a fair amount of time and money trying to buy GAM, that didn't exactly turn out well, when they could have concentrated on streamlining their existing business.
I still hold some shares, mostly now on the hope that some other company will come along and take them out.
The Business Secretary was doing the rounds today announcing a roster of new employment rights. The spin against a tidal wave of business critical comments was that the changes are designed to help growth.
Its a nonsense line, but it is just another kick from non-business friendly politicians in Govt.
Th e growth will be in spurious Industrial Tribunal claims, and businesses holding back on hiring, I suspect.
We do
Brokers were expecting around a £1bn decline in AuM for Liontrust Asset Management (LON:LIO) so a tad behind that.
At just 8*PER the stock is clearly priced to lose more AuM but with a 14% dividend yield that is only £3m light against eps and against a large unrestricted cash pile this shouldn’t prove a burden in my view so I’d expect that to hold.
Assuming we are close to the nadir then market performance and inflows should reverse. Asset managers generally trade 11-15* so it’s at quite a discount. But that’s what happens when stocks are unloved I guess.
Polar Capital Holdings (LON:POLR) today report a 4% rise in their AUM over the last 6 months, however they also report
"The more challenging market environment over the last quarter resulted in AuM declining from £23.5bn at the end of June 2024 primarily due to negative market movement and performance of £655m after the summer equity sell-off alongside net outflows of £172m driven by mandate redemptions"
So the uncertainty caused by the Government is certainly having a negative impact.
There seems to be an outflows across the vast majority of asset managers. I'm a little puzzled as to where all that money is going. Trackers?
I heard a long time ago someone say that asset managers are fragile beasts that really shouldn't be public companies. Make of that what you will.
Moneyweek reported in July 2024 that £1.8b were withdrawn from UK equity funds in May. “May was the worst month on record for UK equity fund flows, quite the
accomplishment for a sector that has been in outflow for eight years.
Even more troubling for UK asset managers is the fact the trend seems to
be accelerating.”
Money is coming out of UK equities and going into Europe and US equities. People are pouring their money into global passive trackers, of which the UK is just 4% of global markets.
It's interesting to get a perspective from Terry Smith. He argued that there's no such thing as a passive strategy, they're all active in some way. Sure, you might not be picking individual stocks, but you are picking regions and the underlying composition. He argues that trackers are, in effect, momentum funds.
This is borne out by what we see, Buoyed by the Mag 7, the US market has been racing ahead, whilst the UK is heading in the opposite direction. Even some Stocko authors seem to have abandoned hope in the UK markets and are attracted to the US ones.
The problem with momentum is that it fails to take into account valuations. US markets are at extended levels, whilst the UK are undervalued.
Hi Mark,
I have invested in both markets before this century and the equivalent returns are striking indeed!
All experienced investors know that the US normally trades on 16X-20X earnings but now is on 25X so a correction of 20-25% at some point should not be discounted.
The growth over in the US will never be achieved here and what seems to be overvalued now in 2-3 years will be undervalued.
The cash flow generation of the US companies is unreal. Apple (NSQ:AAPL) have bought back about half of their shares in the last 10 years!
Apple (NSQ:AAPL)
Microsoft (NSQ:MSFT)
Amazon.com (NSQ:AMZN)
Alphabet (NSQ:GOOGL)
NVIDIA (NSQ:NVDA)
I could go on for ever naming another 100 US listed companies and I struggle to find one UK one that can ever match these.
This is the tragic reality.
All the best
Agree with every word Mark but the issue is if US corrects 20% , cheap UK mid and small caps would probably go down a similar amount or more so everyone needs the US to keep going up so that the other markets that follow do the same.
I would say a lot more, 40-50%.
I'm a little puzzled as to where all that money is going
vanguard and the like?
I was at an investment Roundtable last night, the investment manager hosts mentioned in passing that they had reduced uk equity weightings in favour of global equities where they see better prospects.
A lot of natural cash or bond investors had to go to equities during the extended period of negligible, even negative, interest rates (remember TINA) and will have been shifting back to their comfort zone (low coupon short dated gilts particularly attractive to higher and additional rate tax payers with effectively zero risk).
Momentum investing works until suddenly it doesn't, the successful momentum investor knows to change horses quickly when the tide starts to turn. The quality and/or value investor just has to be patient and wait for the tide to turn.
i dont deny that funds will be going somewhere completely differently at times - but i am seing massive uptick in people with cash to "invest" using low cost trackers like vanguard compared to old school routes . dont know how managed funds compare to these low cost alternatives ref returns but i suspect the low cost trackers deliver better returns for your less savy investors?
fundamentally can we expect these fund manager companies to command the margins they have done previously with clearly more low cost competion that presumbaly provides superior returns on average compared to "most" fund managers - i would perhaps exclude fund managers that have clearly delivered great results long term - some clearly deserve their premium place.
so without working out where the cash is going generally should we expect that fund managers still have a marketplace that isnt expected to "dwindle". perhaps orderley decline can be managed but i wander if companies like this might be poor investments if this area is in semi terminal decline.
all pure speculation on my part
My cash is going in the USA markets. Fed up with UK plc and future not exactly promising
I think one finds it hard to argue against then long term returns for us stocks - and i am sure their larger marketplace makes it better for continual long term growth. I would worry slightly that the returns provided by the big 7 may not be repepeatable and might even go into reverse - but with a tracker then i think you possibly dont have to over worry. I certainly have moved more of my sipp funds into use stocks when exchange rate has been 1.3 plus - so the exchange rate is somawhat back in our favour again after a couple of years of absence. My annoyance is that i have had some incredibly poor picks ref us stocks i picked up last time exchange rates were in out favour - basically i was a bit of sucker during covid preuming that some decent companies wouldnt have had the post covid blues i should have seen cominga mile - hey ho never to old to live and learn.
I would say looking at the most excellent SIF portfolio review and perfomance it does seem clear to me that disciplines investors can eak out close to 10% pa compounded returns without having to be over clever - so thats not to say that uk shares cant deliver everything we need - they certainly can
8 Trillion in money market funds most of that flowed in last two years.
$6.5T sit in money market funds.
Nothing spectacular as the market cap in the US now is over $60T.
All the best
USA
Probably S&P 500 trackers Mark and also I think there is currently round 8 trillion sitting in money market funds.
Pre Close update today from Ramsdens Holdings (LON:RFX) today, showing decent progression. The recent director sell doesn't seem to indicate anything serious.
Contract wins and accelerated deleveraging at Gulf Marine Services (LON:GMS) - good time to buy or continue to wait until seller has cleared?
Gulf Marine Services (LON:GMS) Why wait on a single decision that could go either way. Buy some now and some later??
FWIW I have been nibbling for a while, whilst recognising the risk of the recent selling potential following the distribution of shares from a major shareholder, I felt that there was a chance that this was already baked into the price and you could therefore miss an opportunity.
As it was, the SP did come off some, but this meant I simply bought some more at a cheaper price. If you believe in the long-term story then short-term price fluctuations aren't going to make that much of a difference - you simply run the risk of the price suddenly breaking out without being on board - Ive learnt this too many times with numerous shares of Paul & Grahams liking, that I have waited too long and missed the boat...............although to be fair, they have often continued to gain and often its never too late. Plenty of one baggers have become two and three-baggers over the last couple of years.
Great to see continued good news here and I am a firm believer in the long-term story and will certainly be adding at some point.
Anything around 16 pence is worth nibbling at, in my view.
I'm more than happy to be patient with this one.
Been nibbling on Gulf Marine Services (LON:GMS) in the sale for a while now so great to see this good news. Also recommended by Capitalist Exploits. Great update guys, thank you.