Small Cap Value Report (Thu 11 April 2024) - SDY, ULTP, RBG, CAU, LOK, CNS, MER

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
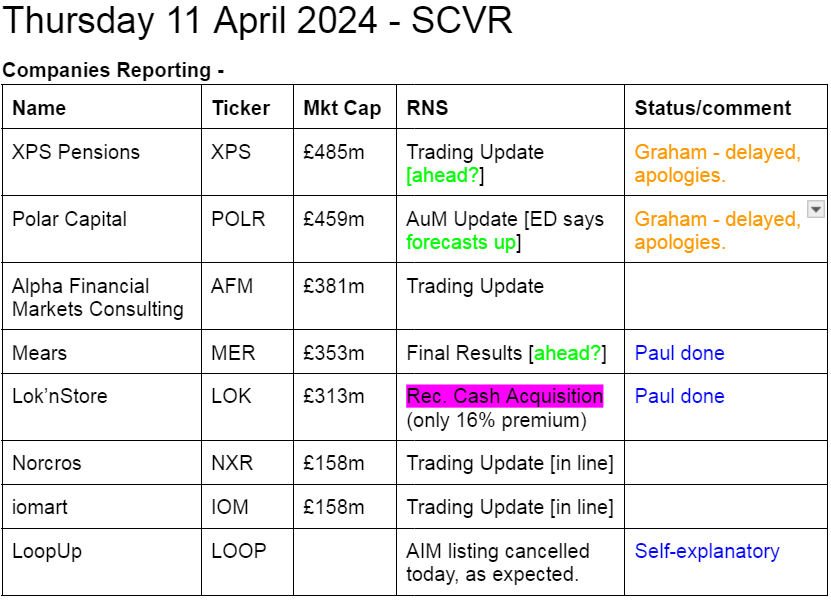
Other mid-morning movers (with news)
Corero Network Security (LON:CNS) - up 14% to 12.0p (£61m) - $1.8m Contract Win - Paul - AMBER
We’ve not looked at CNS for two years, it does cyber-security software to stop denial of service attacks. I'm not sure if it's selling proprietary software, or reselling other companies' software? There has been a flurry of positive newsflow this year. Fundamentals aren’t great - it’s traded around breakeven for several years, including unimpressive results for FY 12/2023. Outlook on 27/3/2024 indicated a "strong start" to 2024, and a good pipeline. But the company also described 2023 results as “strong”, which they weren’t (a small loss before tax). Last balance sheet at Dec 2023 looks OK, with adequate net cash of £5.2m, and NTAV of c.£3m. So I don’t think it will need to raise any more cash. Paul’s view - could be worth a look, although £61m mkt cap for a company with no track record of consistent profitability, is looking a tall order. If it genuinely has a leading DDoS product, then obviously the demand and market globally would be enormous. Hence it’s worth sector experts taking a look, I’d say.
Summaries of main sections
Speedy Hire (LON:SDY) - 25.75p (£132m) - Year End Trading Update - Paul - BLACK (profit warning) - AMBER/GREEN on fundamentals.
Another profit warning from this accident-prone equipment hire company. Blames many external factors, but I'm concerned a lot of the problems are probably more internal. New contract wins might help FY 3/2025 numbers, but broker cuts forecasts for both years. Sound balance sheet (shares trade at a discount to NTAV)and cyclical recovery hopes mean I'll edge up my opinion from amber, to AMBER/GREEN, despite the problems.
Ultimate Products (LON:ULTP) - 149p (£133m) - Interim Results [in line] & Share Buyback - Paul - GREEN
Flat profits, despite some customer destocking. Outlook for FY 7/2024 is in line with expectations, with nice clear reporting. Modest valuation of PER 9.6x. Strong quality metrics. Owner-managed business, which we like usually. Generous divis & share buybacks starting. Looks a good business, modestly priced still.
Revolution Bars (LON:RBG) - up 38% to 1.65p at 12:55- Interim Results & Fundraise/Restructuring - Paul - RED
Complicated restructuring required, and a £12.5m fundraise conditional on court approval of CVA (or similar). High risk until conditions have been met. It's ditching the loss-making sites, but also looking around for better offers with a FSP having started. Bank is writing off £3m of debt, in return for warrants that kick in if share price gets to 4.0p, which would be a terrific outcome for anyone putting in fresh money at 1.0p. Luke Johnson to become Chairman, and is investing £3m. Still high risk, as the fundraise could yet fall through, as it doesn't complete until Sept 2024.
Centaur Media (LON:CAU) - Up 29% y’day to 51.5p (£76m) - Possible Offer - Paul - PINK (bid approach)
No details provided on price, but CAU says it's received a "highly preliminary expression of interest" from a secretive Dutch private equity firm, which specialises in buy & build deals. Seems to be another example of dominant major shareholders seeking liquidity and an exit by encouraging private equity to buy out listed companies.
Lok'n Store (LON:LOK) - up 17% to 1,120p (£369m) - Recommended Takeover Bid - Paul - PINK (bid approach)
LOK receives & agrees a takeover approach from larger European rival Shurgard. Directors holding 19% have agreed it, so we can be sure it's a fair deal. LOK shares have done very well over the years, but the shares didn't look attractive on valuation or quality measures. There we go.
Mears (LON:MER) - up 1% to 366p (£356m) - FY 12/2023 Results - Paul - AMBER/GREEN
Strong results for FY 12/2023, which look ahead of broker consensus for EPS. No profit growth expected in 2024 though. Strong cashflows allow it to pay divis and do large share buybacks. Good company, but shares have risen a lot in the last 6 months, and seem fairly priced now I think, hence I've eased off from green to AMBER/GREEN.
Paul's Section:
Speedy Hire (LON:SDY)
25.75p (£132m) - Year End Trading Update - Paul - BLACK (profit warning) - AMBER/GREEN on fundamentals.
Speedy Hire, the UK's leading tools and equipment hire services company, operating across the construction, infrastructure and industrial markets, today provides an update on the Group's trading performance for the year ended 31 March 2024 ("FY2024").
We last looked at SDY on its profit warning here on 30/1/2024. A variety of problems caused a 35% drop in broker forecast earnings for FY 3/2024. I wondered at the time if there might be a buying opportunity on the way, since I didn’t have any worries about solvency, and the divis had been attractive. Cyclical upturn on the way, maybe?
What’s the latest for this FY 3/2024 trading update?
Revenue down 5% on LY, at £420m.
Blames -
- Challenging market backdrop,
- wider macroeconomic uncertainty,
- underperformance from regional base,
- reduction in wholesale fuel prices,
- warmer winter affecting seasonal products,
- cost inflation and softer demand faced by construction sector.
Any positives? >£40m annualised revenues from new business in multi-year contracts, which should benefit FY 3/2025 onwards. Secured “with continued pricing discipline”.
Outlook - light on details, as is the whole update -
The momentum from securing major opportunities and progressing operational efficiencies, positions the Group well to benefit from the anticipated recovery of the wider macroeconomic environment during the second half of FY2025.
As a result, while the Group expects to report results for the year towards the lower end of the Board's expectations, it is encouraged by the commercial progress in the business and the outlook for FY2025 given the recent contract wins.
What is the range of the Board’s expectations? It would have been helpful to tell us.
Cashflow/debt -
The Group has remained highly focused on working capital management and expects to deliver free cash flow2 in excess of £20m, with net debt3 reducing by year-end to c.£102m, within our target leverage range.
Again, what is the target leverage range? Why not tell us? I see this bank debt has risen from £89.6m reported on 30/9/2023.
Transformation strategy - they’ve given it a name, “Velocity” - sounds like that’s been inspired by watching The Apprentice! Says the costs of this are “significant” and will be adjusted out in the year end accounts.
I already had the impression that SDY is badly run, and has poor internal controls. I got that impression from when it lost all that scaffolding (£20m-worth) in early 2023. An equipment hire company that loses that much kit is not something I would invest in, transformation plan or not.
Broker update - many thanks to Liberum for updating us with revised numbers. This follows the previous pattern, where SDY seems to sound reasonably relaxed about performance, but the broker quietly slashes forecast. Liberum lowers FY 3/2024 again, from 3.2p to 2.7p. the macro position hasn't significantly worsened in the last 3-4 months, so I see these problems as home-grown by SDY.
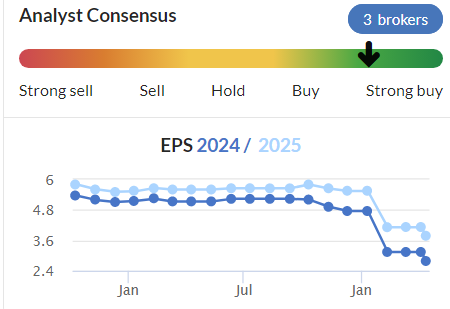
Next year forecast EPS is also slashed from 4.7p to 4.0p. What's the betting they won't hit that number either?
Balance sheet - last reported at 30/9/2024 had NAV of £182m, less intangibles of £24m, gives us NTAV of £158m. That’s assuming they haven’t lost any more scaffolding. The interim results did say no further equipment was missing in the latest stock counts, and processes had been improved.
I like to look at loan to value (LTV) wit hire companies. SDY has a hire fleet of £200m within fixed assets, and £91m borrowings in long-term creditors. That looks OK to me.
So it’s a reasonably decent balance sheet, and the market cap is lower than NTAV. That should provide strong downside protection for investors.
Paul’s opinion - there’s no avoiding the reality that SDY seems poorly managed, and a low quality business that doesn’t earn much of a return on its assets.
However, with the shares having now fallen to a discount to NTAV, and the prospect of a cyclical upturn in demand for its equipment hire as the economy begins a cyclical recovery, I’m tempted to take a bit of a risk here and up our stance from amber to AMBER/GREEN.
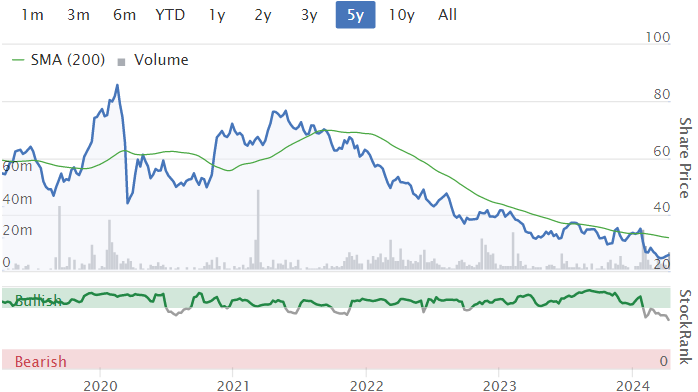
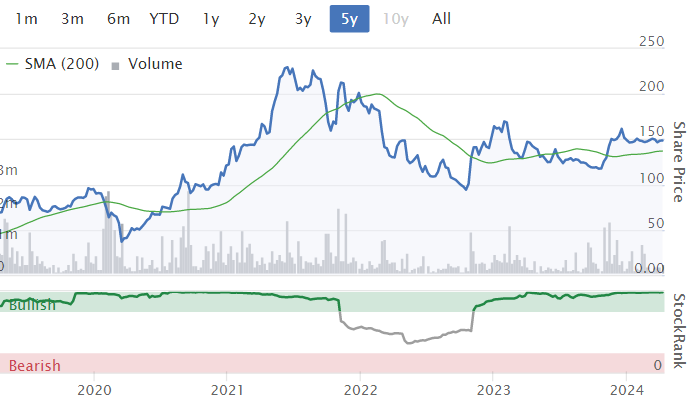
Note that the share price collapse came when we were well into the pandemic, in mid-2021, similar to many other small caps, but a fall of this extent has also been due to poor company performance -
Ultimate Products (LON:ULTP)
149p (£133m) - Interim Results & Share Buyback - Paul - GREEN
Ultimate Products, the owner of a number of leading homeware brands including Salter (the UK's oldest houseware brand, est.1760) and Beldray (est.1872), announces its interim results for the six months ended 31 January 2024.
Company’s headline -
Trading in line with market expectations*
* Consensus market expectations for the financial year ending 31 July 2024 are revenues of £166.7m, adjusted EBITDA of £21.5m and adjusted EPS of 15.6p
Great clarity there, so we can immediately see the valuation: share price of 149p, divided by expected adj EPS (FY 7/2024) of 15.6p = PER 9.6x - looks good value.
Adj H1 profit is up c.2% to £9.6m, despite revenues being down 4%, blamed on some supermarket customers de-stocking.
There’s a very good progression of key numbers here -
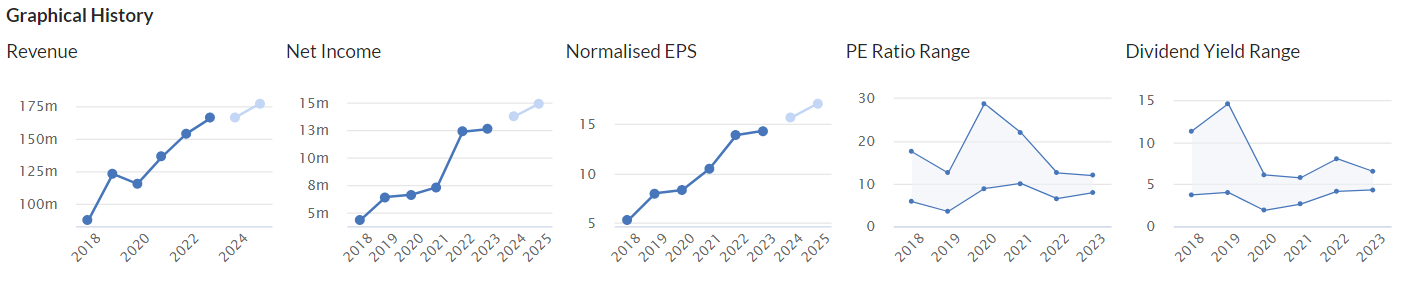
Readers seem to think we should emphasise quality metrics (esp ROCE) here more often, which is a fair point. These are excellent for ULTP -
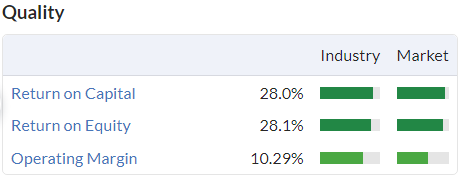
Although I’m not sure how many investors would see this as a quality business, since it’s just importing small consumer products from China. I’m very wary of all companies that have stuff made cheaply in China, then sell it for good margins in the UK (and other Western countries). That’s because the Chinese seem to have realised they can cut out the middlemen and sell direct to Western consumers. Anyway, you can decide for yourself if, and how much of a threat that might be.
Dividends are generous, with a yield of c.5.7%
Balance sheet - there’s a striking reduction in net bank debt, from £19.4m (Jan 2023) to £8.0m (Jan 2024). Although a lot of that has come from a big c.£10m fall in receivables in the last year.
NAV is £50m, less intangibles of £37m, gives an OK NTAV of £13m. We could eliminate the deferred tax of £7m (usually related to goodwill) which would make adj NTAV c.£20m. It’s OK rather than particularly strong overall.
Cashflow statement - looks very good, it’s generating plenty of cash, and using it to pay down bank debt, and fund generous divis.
Share buyback of around £1m per quarter is planned, up to c.10% of the total issued shares.
Paul’s opinion - I like it. Last time on 13/2/204 I was GREEN, and these latest figures confirm my favourable opinion. It also talks about considerably increasing revenues in Europe, from a new showroom in Paris. The focus is now more on branded products, which seems to be working. It’s an owner-managed business too, which is usually a good thing.
Revolution Bars (LON:RBG)
Up 37% to 1.65p at 12:56 - Interim Results & Fundraise/Restructuring - Paul - RED
Fundraise - to issue up to 1,251m new shares at 1.0p each (existing shares: 230m), to raise up to £12.5m (before costs), and £11.6m after costs.
Of this fundraise, most of it has already been committed: £3.0m Luke Johnson, £3.0m Robus, and £3.5m from 3 existing shareholders.
Restructuring - plan is to exit leases on 18 sites, rent reductions on a further 14 sites, and other cost savings, saving £3.8m in year 1. Sounds like a CVA type of arrangement, and the detail says the restructuring plan needs a 75% creditor vote, which sounds a lot like a CVA, although that term is not specifically mentioned. The fundraise is conditional on the court sanctioning its CVA.
Luke Johnson to join board as a NED, and then Chairman later.
Nat West has (unusually) agreed to write off £4m of existing debt, and defer interest payments est. at £2.2m. It is also suspending the key covenant until April 2025. In return Nat West will get c.150m warrants for new shares, exercisable at just 0.1p per share, but only if the share price exceeds 4.0p.
Shares were suspended on 2/4/2024, and the H1 results statement says -
“the Company has requested that trading in its ordinary shares on AIM be restored with effect from 7.30 a.m. on 11 April 2024.”
Launch of formal sale process - running in parallel with the fundraise & restructuring proposals, to see if a better offer can be found - but remember that a better offer may be for the bank & creditors interests, which may not necessarily be in the interests of shareholders. Note that companies in financial distress start using the term “stakeholders” instead of shareholders for this reason.
Interim results - to 12/2023 show an IAS17 (the most relevant measure) loss before tax of £(2.1)m. Net bank debt was £20m. Outlook statement says trading is challenging, but in line with expectations. Going concern material uncertainty again. Revolution is the problem brand, with de Cuba and Peach Pubs performing better.
Paul’s opinion - wow this is complicated. Hopefully I’ve captured the main points above. Overall then, court approval of the CVA looks the first essential step. Placing monies are only received by the company if this is approved. Then the company restructures, closing the loss-making sites. It should then have a viable business, having ditched the problem (mainly Revolution branded) sites. Although it also talks about refurbishing remaining sites in future, which of course will be expensive.
Existing small shareholders have to decide whether or not to take up the Open Offer entitlements.
The new share count will be almost 1.5bn, so the share price is unlikely to have more than a penny or two upside, even if everything goes well.
Having created this mess by maxing out the bank borrowings to buy Peach Pubs, I wonder why new equity backers haven’t had a complete clear-out of the Board?
I imagine there’s likely to be very brisk two-way trading in RBG shares once they come back from suspension today (caused by late interim accounts which have now been published). I think it’s still very high risk, and this is now the third fundraise, which will mean the share count up by about 30x from pre-pandemic. That said, history doesn’t matter to new buyers of the shares now. If it goes from 1.0p to 2.0p, new buyers will have made a 100% gain.
Personally I’m not tempted to dabble here, as it’s been a stressful share for me historically, with big losses (and big gains from trading the dips heavily before). You could argue that with smart investors piling in a decent slug of new money at 1.0p, then they must have concluded risk:reward is favourable at that level. Clearing out all the loss-making sites, just before a potential consumer recovery, might be a good move that brings a competitive advantage maybe? Tricky one.
UPDATE at 12:56 - the market clearly likes this announcement, with a big % increase this morning to 1.65p - already a hefty 65% premium to the proposed fundraise at 1.0p. If that sticks, it should mean full take-up of the open offer. Although there's also a temptation for people to lock in profits for unissued shares through eg opening a short CFD, if it's possible to get a borrow. Given that, if this deal happens, then the share count would be c.1.5bn, then the new market cap would be about £25m at the current 1.65p, and you've also still got insolvency risk, or equity wipe-out risk if someone else comes along and offers to buy out the bank, and take control that way, or subverts the CVA in some other way? Hence it's for risk-takers only at this stage, but it looks like so far anyway, the bet has paid off! Good luck to holders.
Centaur Media (LON:CAU)
Up 29% y’day to 51.5p (£76m) - Possible Offer - Paul - PINK (bid approach)
Centaur is an international provider of business information, training and specialist consultancy within the marketing and legal professions…
Issued during market hours yesterday at 12:53, CAU stated -
“Recent media speculation” re a bid approach.
Has received “a highly preliminary expression of interest from Waterland Private Equity Instruments B.V.” re a proposed acquisition.
No price is mentioned.
Board remains confident in its growth strategy.
Doing a bit of googling, Waterland is described as a secretive private equity firm based in Holland, which has raised billions for various funds specialising in buy & build acquisitions. CAU seems quite a small acquisition relative to the multi-billion funds it seems to raise.
FY 12/2023 results were published on 13/3/2024, and look pretty good, with a 62% rise in adj diluted EPS to 4.2p = PER 12.3x at 51.5p/share.
Balance sheet at 31/12/2023 only had NTAV of about zero, but it had £9.5m in net cash because customers pay up-front (reflected by £8.4m deferred income creditor).
Paul’s opinion - I’ve not looked at CAU since a quick review in Mar 2023, when I thought it looked priced about right at 53p (very similar to the current price, post 29% bid premium). Although a quick look at FY 12/2023 results have improved my view of the company, since profit increased strongly.
Harwood Capital is the largest shareholder at 29.9%, plus Aberforth with 23.9%, makes this look like another situation where big shareholders might have pressed management to sell up to private equity in order to give them an exit at a premium maybe?
CAU is up for sale now, publicly, so let’s see what happens next.
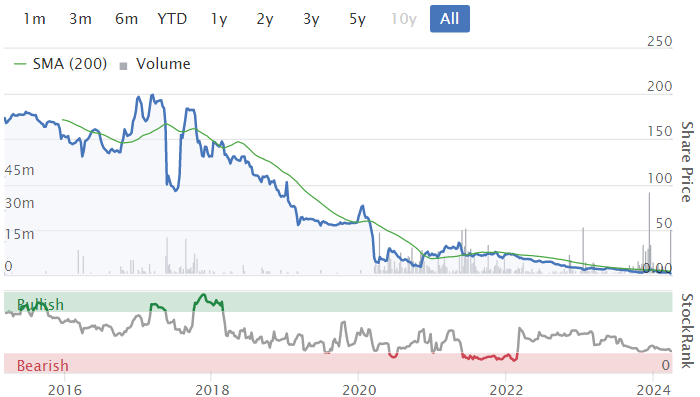
The share price hasn’t gone anywhere in 20 years, although it’s been a good dividend payer in its time as a listed company.
Lok'n Store (LON:LOK)
Up 17% to 1,120p (£369m) - Recommended Takeover Bid - Paul - PINK
Bidder - Shurgard Self Storage Ltd (large European self-storage property company)
Type - recommended cash offer
Price - 1,110p cash
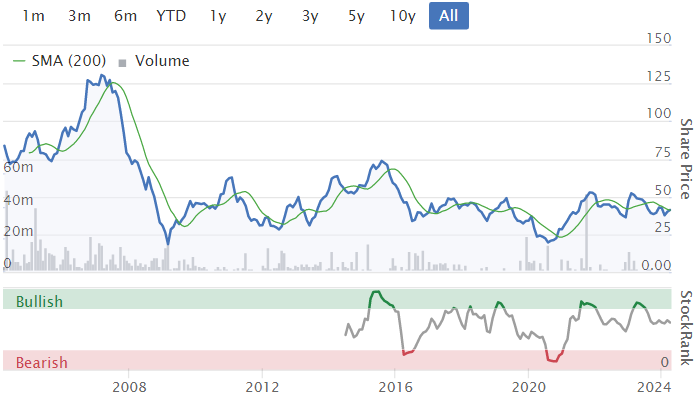
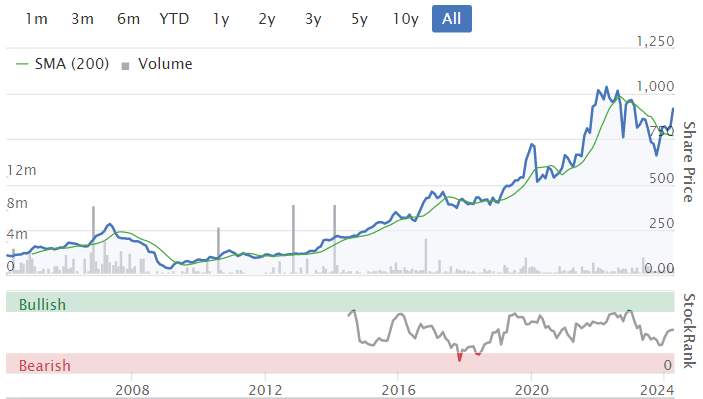
Premium - 15.9% to last night’s close. Although the share price chart makes it look as if the news might have leaked and some insider dealing might have happened, as a 10% rise in share price occurred in the week before this announcement. So that’s more like a 30% premium to the share price on 5/4/2024 (before the sharp upward move began).
It’s a 2% premium to the previous all-time high in Jan 2022.
Shurgard (nothing to do with the famous horse) is a larger listed competitor in Europe - here’s a snapshot of its StockReport below (I’m lucky enough to have use of the international version of Stockopedia) - as you can see, its market cap is almost 10x that of LOK, and it’s a trade buyer, operating self-storage facilities in Europe. It also has 41 sites in London, according to its website. So acquiring LOK seems a quick route to expanding further in the UK, since LOK has a wider spread of sites in the UK, and only 3 (just) inside the M25, according to LOK’s website..
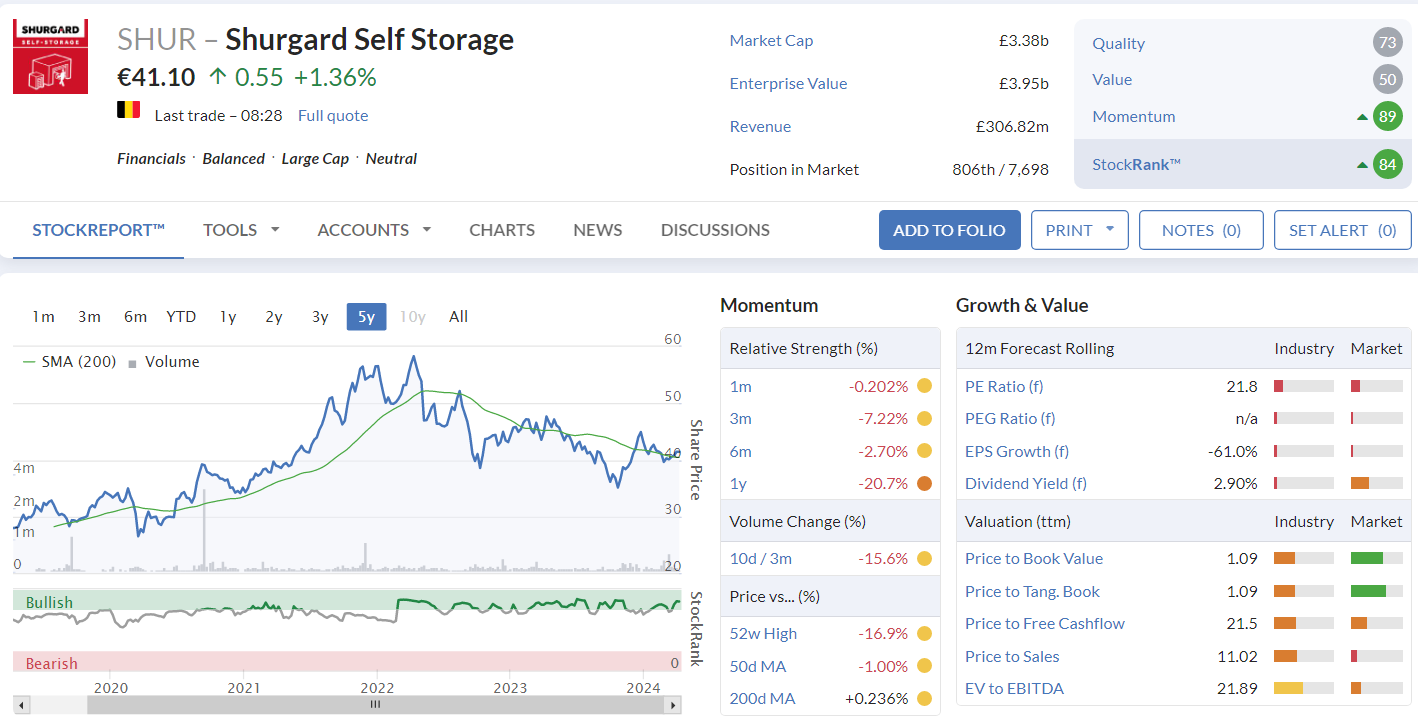
Is it a fair price? Directors at LOK support the deal, holding 19% of the company, which tells me it’s a good deal for LOL shareholders. Owner-managers don’t agree a deal unless it’s good. The blurb says that the valuation is 27.1x adj EBITDA for FY 7/2023, and a 12.5% premium to adj NAV. That looks quite a punchy valuation in current circumstances.
Paul’s opinion - this looks a decent deal, and I imagine it’s likely to be agreed by shareholders, since owner/management have backed it with their 19%.
I’ve never really focused on LOK shares, which is a pity as it’s been a superb long-term success, roughly 30-bagging from the 2009 low, when the world seemed to be coming to an end in the financial crisis.
When we have looked at LOK, we’ve tended to think it looked too expensive, both on a high PER, a premium to book value, and with low ROCE, so no particularly obvious appeal to the share.
I had lunch with some very successful self-made investors yesterday, and they’ve switched most of their money into property companies this year, where they tell me there’s (selectively, as always) terrific value. So if you know what you’re doing, then I think focusing on REITs and other property companies could be a lucrative theme. Although there are obvious risks, the main one being to ensure that borrowings are under control, and that balance sheet values are realistic (many commercial property values have plunged since interest rates rose). We might well see more property companies implode under excessive debt, as I’m told is happening in China.
Another worry is environmental costs of upgrading old buildings, which I’m told could be ruinous for some UK property companies, so that needs careful checking.
Going out at an all-time high, what a great result!
Mears (LON:MER)
Up 1% to 366p (£356m) - FY 12/2023 Results - Paul - AMBER/GREEN
Mears Group PLC, the leading provider of services to the Housing sector in the UK, announces its preliminary financial results for the year ended 31 December 2023 ("FY23").
Headline numbers look good - and it’s fantastic to see MER reporting average daily net cash - this needs to become the standard, as cash on one day (year end) can be meaningless as it’s so easily manipulated -
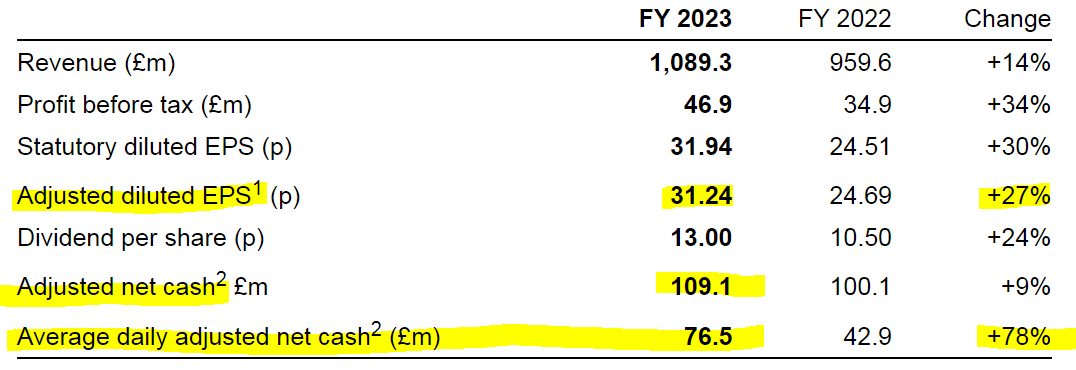
At 366p/share that gives a 2023 PER of 11.7x, which looks a sensible valuation for this type of business.
Stockopedia shows a broker consensus of 28.8p adj EPS, so assuming the numbers are calculated on a comparable basis, this looks like a beat against forecast. There are no broker notes available on Research Tree, which is something MER needs to address.
Outlook - doesn’t inspire, with profits in 2024 expected to be flat -
Mears has made a strong start to 2024. The Board continues to anticipate a reduction in management-led revenues as the elevated activity level seen across FY23 normalises, although the timing remains uncertain. Adjusted profit before tax in FY24 is expected to be of a similar quantum to FY23…
The Board believe that the Group is well-positioned for the future and is pleased that the strong trading momentum built in 2023 has continued into 2024."
Average daily net cash of £76.5m is 21% of the market cap. So there is an argument for adjusting out the cash in our valuation measures. Although remember that you would then need to also adjust out the £4.4m (see note 5) of “interest income from short-term deposits”, which is almost 10% of total profit before tax.
Further down it mentions a lower average daily net cash figure, it sounds as if the share buybacks might be responsible for the difference? -
The Group reported a net cash position of £109.1m on 31 December 2023, but the Directors believe that the average daily net cash, after adjusting for the full year impact of the share buybacks, averaged £50m during 2023, provides a better indication of the underlying position and is a better indicator of the Group's liquidity.
Balance sheet overall is strong, with £69m NTAV. Note there are particularly large entries relating to leases. There’s a £20m pension surplus - is it a real surplus? It seems to be, according to note 26. I can’t see any reference to deficit recovery payments.
Cashflow statement looks impressive. £136m after tax cash inflow looks amazing, but note that a lot of this disappears further down with £48m “discharge of lease liabilities”. Overall though, Mears managed to self-fund £25m capex, pay £11.8m in divis (total 10.95p), and do a huge buyback of £38m of its own shares - so the share count has fallen from c.113m in 2022 to just 97.6m shares in issue now. After all those cash outflows, it still ended the year with £15m more can than at the start. So this looks a very nicely cash generative business.
Note 21 is a bit worrying, with a £14.5m charge to the P&L in 2023 for onerous contract, legal, and other provisions. This needs further investigation, and would be good to ask management how these problems have arisen, and how they can be prevented in future.
Paul’s opinion - this looks good, with some very positive aspects, mainly how cash generative it’s been, and with meaningful share buybacks that should be beneficial for both EPS and DPS. The trouble is, the outlook statement doesn’t envisage any further growth in profit in 2024, which means that the PER of about 12 is probably about right, unless something changes for the better.
We’ve noted before that MER is doing particularly well thanks to “Asylum Seeker” housing contracts, thus it’s not clear how long, or at what level, those profits will continue?
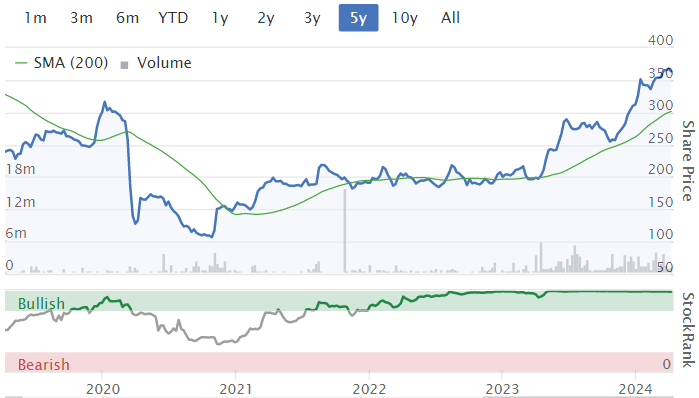
Given that MER shares have risen from 250p to 350p in the last 6 months, then I’ll take my foot off the gas a bit, and ease back my view from green to AMBER/GREEN - so still positive, but less of an obvious bargain than it was last autumn is my conclusion today.
Shares hitting a 5-year high, and note the very high StockRank -
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

101 comments
Ultimate Products (LON:ULTP) management conducted a live Investor Presentation following Interim Results (for the period to 31 Jan 2024).
Andrew Gossage (CEO) & Chris Dent (CFO) ran viewers through the financial and operational highlights of the period, which included stable profits (EBITDA) and a marked reduction in bank debt. The company also discussed trading in line with market expectations, its intention to buy back up to 10% of its shares, and the ongoing productivity drive through focus on continuous improvement, including the automation of hundreds of tasks across the business. The team also answered investor questions in a wide-ranging Q&A session.
The full video is now available here (divided into chapters for ease of viewing):
?si=DXVWaei5ZjFx4hLfDoes anyone know why Shoe Zone (LON:SHOE) suddenly fell 10%?
Shoe Zone (LON:SHOE) Hi Rusty2, this is going to sound glib and it's not meant to be, but ever since the profit warning a few weeks ago we've had a lot more sellers than buyers (including myself).
The price has dipped below moving averages on the charts so it looks weak, the outlook statement was guiding lower so all in all steady/bearish.
Plus i read today there was a Poundland profit warning so I'm guessing things are tough at the budget end of the High Street? maybe a read across?
As a previous long term holder I totally trust the Smith brothers and think everything they are doing long term is right so this is probably more of a road bump than anything else but i'm in no hurry personally to buy back in at these levels and maybe other potential buyers are thinking the same...
I got a Stockopedia alert at 4.19pm, on Shoe Zone (LON:SHOE) which was set at below 200p, when l looked it was way below that. Seems to be a sudden 10% fall, I thought something had happened. The Poundland profit warning was out this morning? Unless the alert was hours late?
I was lucky I sold out about 270p, after the share tip, pushed the price up. Share tips have some uses.
Shoe Zone (LON:SHOE) I hold, seems to have fallen to 195p. As Paul Hill has hinted Cockney Rebel's tiered adherents can move prices now? Re customers: Once loyal customers convert to going 'online' they will buy on price unless there is a loyalty scheme? It may be that CR and coterie have lost faith in the Smith's.
Shoe Zone (LON:SHOE) was around 192p when I looked. The market is so thin, everytime I sell around £1,000, in small cap shares the price falls, noticed that on the last 3 trades, on Yu (LON:YU.) it fell more than the spread which was quite wide. Cohort (LON:CHRT) also. Often I can't even get a quote. Not heard CR mention Shoe Zone (LON:SHOE) recently or several others he was in.
Shoe Zone (LON:SHOE) Oh nice sale price! I was out at £2.30, dithering over to hang in for the dividend or not.......Sorry couldn't add more colour to the reason for the fall but just looks like a multitude of small sales, maybe stop losses triggered at £2.
Yes l was lucky with Shoe Zone (LON:SHOE) and on JD Sports Fashion (LON:JD.) but many others have continued to rise and defy gravity.
Usually when I sell the shares go up and the ones I buy fall.
Yes l was lucky with Shoe Zone (LON:SHOE) and on JD Sports Fashion (LON:JD.) but many others have continued to rise and defy gravity.
Usually when I sell the shares, they go up and the ones I buy, fall.
Can anyone remember the name of the poster (or link to the post) who reviewed the Mello conference in November as I would like to give them a free ticket to this coming Mello2024 conference in May?
I believe that was ShoeShineBoy.
https://www.stockopedia.com/co...
Great write up it was too. Thanks SSB
this is a nice gesture, well earned too.
Norcros (LON:NXR)
https://www.equitydevelopment....
updated equity dedelopment note available via link above with some useful commentary - it looks like the actual future numbers in this report are unchanged from the november update which i linked earlier today.
Some good stuff on this thread but after a few days will be very difficult to sift through - makes me wish we had a thread for each company.
I posted this on a new dividend thread earlier today, in response to a poster (like so many smaller investors) not interested in dividends. I thought it might be worth posting here too. It took me 20 years to wake up to the reality of having a lot of income shares (they too can multi bag) as well as growth shares in our portfolios.
Here’s that post:-
“ I used to have little interest in or enthusiasm for dividends, but at last saw the light a few years ago when discovering that Lord John Lee gets 100% and more back every year on a lot of the shares he holds, just in dividends.
Already after only a few years of belatedly focusing on dividend income I’m now getting so much in dividends every year that they now pay for a lot of our new share and Investment Trust buys.
I.e before much longer the portfolios become self financing. I hold Investment Trusts paying up to 20% a year in dividends. (There’s a very good Investment Trust thread on Stockopedia btw).
Another BIG plus is that there is big income during bear markets to compensate for capital losses. So less worry than with the non dividend payers we hold.
And although there has been a useful recovery recently, thanks to the UK Market being SO unloved, there are quality shares and Investment Trusts paying extraordinarily high dividends. That high yield should, if the UK Market ever comes back in to favour, lead to significant share price gains, as yields return to the levels in the past.
Just a couple of examples from my portfolio are Legal & General (LON:LGEN) and TP Icap (LON:TCAP) both bought on market dips. Legal & General (LON:LGEN) dividend yield at my 155p buy price is around 13% AND there’s a 50% capital gsin on top.
TP Icap (LON:TCAP) (like LGEN it is not a growth share) I luckily bought at the £1.02 bottom only a couple of years ago. They recently announced a big dividend increase and the yield is 15% a year already. AND the capital gain is already around 115%.
The 100% a year from dividends that John Lee and similar investors get is GROWTH BIG TIME! And that’s before including the share having multi (and sometimes multi multi) bagged.
It’s surprising how few small investors cotton on to this. I read it and ignored it for over 20 years!”
great comments ken - i would say the key here is picking companies with a sustainable dividend - over the years there have been many debt (or liabilities) laden companies paying out chomping dividends when that probably wasnt sensible - or wqas at least "risky" . IMHO there isnt exactly a shortage of choice here so the key if probably simply to stay away from the debt laden ones or the ones where the business model might not look great for 5 years time.
I think i learned my lesson a few years ago with centrica - the p/e looked cheap , price was well off highs and it looked a reasonable divi play at the time. They had large debt though , it was totally stupid of me to presume that as they had managed the debt previously they should be fine - i should have picked a similar company that simply didnt have that risk profile. Result was that i managed to lose 75%+ of my investment (at low point) - albeit the company has bounced back strongly recently - thats more by luck than my good judgement holding on. So the key here as with any other company investments is to get the right company - or perhaps so not invest in the wrong uns of get shot of wrong uns.It doesnt take many 75% losses to wipe out all the benefits of the divis coming in for a year or two !! Perhaps most people arent as stupid as me and sell their losers at first sight of deterioration - thats tricky though as we can possibly all over tinker at times ?!
Thanks for such an interesting reply rmillaree.
Re selling decisions. I nearly always sell on a profit warning or disappointing trading update. I also sell if there are hints in updates of a dividend cut or cancellation ahead. That tactic works well. If, as with Legal & General (LON:LGEN) and Aviva (LON:AV.) they are confident about their progressive dividend policies to the extent of forecasting middle single digit annual dividend increases. Then I use any big dips as a chance to average down or up. That tactic too works well. I always keep an eye on dividend cover. Ideally at least 1.5times for a share and at least covered for investments like Investment Trust REITS.
For years just as I ignored all the excellent articles etc on the merits of dividends so too I wasn’t ruthless enough with selling, and did what so many small investors do, which is to continue to hold a share in the teeth of evidence it’s going wrong.
The key is to cut losers quickly and run our winners (and top slice when profits look too good to miss).That way the losses on our losers stay small, while our gains can end up with plenty doubling and more.
Finally I NEVER hold a share that lets me down and wait for it to get back to my buy price. Get out and put that money to much better use.
It took me a couple of decades to cotton on to this….yet really isn’t it obvious?
Ken
Thanks for the note about dividends. It really should be common sense but for so many investors its just icing on the cake and not one of the fundamentals
For myself I will always look at the capital gain and the accumumulated dividends to determing whether the stock was a restrospectively a good buy and to that end my portfolio spreadsheet (you can tell I'm an accountant) has three columns one of which is linked to a nearby dividend control sheet which I update whenevera new divi is announced. I have a running yield of over 5% from 48 holding of which only 3 pay nothing
This is not rocket science but when you have Legal & General (LON:LGEN) Shell (LON:SHEL) bought at bombed out prices it makes sense
Keep smiling
TP Icap (LON:TCAP) (like LGEN it is not a growth share) I luckily bought at the £1.02 bottom only a couple of years ago. They recently announced a big dividend increase and the yield is 15% a year already. AND the capital gain is already around 115%.
I’m enjoying your enthusiasm, Ken. But you’re letting it get the better of you in making hyperbolic financial claims. The yield on your original purchase is 15%, but the yield on your increased capital is more like 7%. Neither of those numbers are to be sniffed at, nor should one ignore the excellent capital growth. But your rewards are coming from superb timing rather than from owning a high-quality business.
Appreciated you replying BnB.
I agree that my 155p buy prices for Legal & General (LON:LGEN) and £1.02p for TP Icap (LON:TCAP) were lucky timing, especially so TCAP bought right at the low.
Obviously I’ve bought other dividend payers (and growth type shares) that went on to fall further before recovering, with some only getting above my buy prices recently. Polar Capital Holdings (LON:POLR) is an example of a too early buy and until their excellent AUM update today it was below my buy price.
I’m totally bemused about your comment about my yield on the increased capital only being 7% and my supposed hyperbolic financial claims. So can you explain please. And isn’t TP Icap (LON:TCAP) quite a high quality business? It gets 97 on Stockopedia stock page.
I calculate my dividend yield the standard way. If I buy TP Icap (LON:TCAP) at £1 and the dividend is now 14.8p then I’m getting 14.8% of my stake back every year in dividends. So that’s an 14.8% annual yield.
And if say, Lord John Lee paid £3 for a share and he now gets an annual £3 dividend, he is getting an annual dividend yield of 100%. And John Lee does hold shares paying him 100% and more a year just in dividends. I would be in that position now too if I had taken more notice of articles making the same points as I’m making now.
I calculate my dividend yield the standard way. If I buy TP Icap (LON:TCAP) at £1 and the dividend is now 14.8p then I’m getting 14.8% of my stake back every year in dividends. So that’s an 14.8% annual yield.
It is 14.8% on your original stake, but if the price of your shares is now £2, then your capital is twice as large and still tied up in the asset, so the yield on your revalued capital is 7.4%. That is how you should be looking at it, because if you sold the asset and reinvested in another dividend stock, you'd be calculating the new yield based on your larger £2 pot, not the original £1.
That said, still a great piece of business.
Meanwhile I don't consider TP/ICAP to be a quality share, no matter what Stocko's algo thinks, because it has sluggish revenues and falling eps over a long period, not to mention its all a bit old tech. By my definition, a quality name is one that you can confidently buy at any point in the cycle, often with little regard for the usually off-putting multiple, and come back 10 years later to find you've at least doubled your money, probably more.
I think you're both right, just different ways of looking at it, running yields and effective yields. You also have to take any tax payable on sale into consideration as diminishing the reinvestment capital available.
But hey, these are all first world problems if ever I saw one ;-)
Hi Ken
Hope all is going well with your recovery. Glad to see it is not blunting your investment exchanges and hope it is helping pass the time, and profitably.
From your discussion with BnB it looks to me like what you are calculating is the Return on Original Investment, which is a reasonable measure of performance, whilst BnB is focusing on the Return on Current Capital deployed. Is that fair?
Arguably we should always be focused on where we can get the best return now/for the next 12 months. For this weekend I'm going with Mr Incredible! I'll put that down as an homage to some of your excellent past picks. Do please keep sharing your thought.
Thanks for the very kind comments sevenccc.
You’re right …and I see where BnB was coming from now.
Very brief on my health as it’s off topic here……at last blood has been taken while I was having a rigor and from that at last they’ve found 3 separate positive blood cultures and it’s pus leaking from an abscess or something somewhere. My case is SO unusual that I’m lucky in now having a team trying to get to the bottom of it.
Posting and checking out shares and Trusts is just for fun now as luckily I’ve got a portfolio that will look after itself thanks to so much dividend NCOME. And it takes my mind off things.
Again I hope this doesn’t result in a lot of (justified!) posts about it being off topic, but for the National I’m backing these 5 with a very small each way stake. All outsiders with a chance …..but it needs to be an outsider year!
NAS Salam 33-1
Late Night Pass 22-1
Glen Gouly 50-1
Galia des Liteaux 22-1
Chambard 66-1.
My past National outsider winners where I can remember them include Noble Yeats at 50-1, Auroras Encore 66-1 and a good while ago Silver Birch …which started at 33-1 but I got 50-1.
Hope your pick wins!
Clever old Lord Lee manages to bag his fair share of takeovers too, Lok’n Store Lok'n Store (LON:LOK) today one more into his coffers!
Thank you Ken
I manage my mum's ISA (aka Pension) for income now as she is 84 years young, so many lessons learnt of what not to do. So appreciate the income posts!
Slowly I am moving part of my own SIPP to income generation, whilst I am not yet drawing it with the initial plan to just reinvest dividends, it is about learning with real money and not just a model portfolio. So using the next couple of years to understand actual income achieved, capital allocation - number and sizing of positions, sectors, rises and falls and all that, basically working out what my own strategy for retirement is, and I will also apply this to my sister's ISA too over the coming year(s) as she moves into retirement, and make tweaks to mum's ISA where appropriate.
I would add that in the past I have made decisions on capital gain with my mum's ISA and whether to book and move on, so if I bought Company A for £1 with a 7p dividend (so 7% yield), if that company rose to £2 and the dividend remained at 7p (so 7% yield against purchase, or 3.5% yield against capital value), if I did not feel there was likely to be further growth I booked the capital gain and reinvested elsewhere, so using the annual capital gain allowance, and allowing the move into ISA. So buying 2 shares in company B £1 with a 6p dividend, so actually getting 12p income instead of the original 7p. Obviously dividends are being drawn not reinvested in this case.
I do not know which is the right answer, I suspect both are right, hold and take the income and sell and increase the income.
@rmillaree, I have (since large losses in Covid total argh moments) run a manual stop loss approach, selling when 20-25% down from purchase. So I have some simple sell rules, such as a company cancelling or stopping the dividend. Obviously some things continue to go further down and I am a genius, and some bounce back and go above sale and purchase and my Fear of Missing Out, and ability to kick myself comes to the fore.
This also had a part that her old broker, before I took over, had made her portfolio a total mess and had not made use of ISA allowances, capital gains allowances and it took Covid for mum to finally let me take over, and it took a couple of years to get her money where it should have been 15 years ago, making money for her not for the Broker. Different rant.
Cheers
Tommy
Excellent post Ken Mitchell, couldn't agree more.
I have this year put together an income portfolio of 40 stocks & investment trusts, blended initial yield of 6% (but progressive hopefully). Plan is to run, automatically reinvest and compound over the next 15 years. One of the quirks of UK company law is these dividends are not taxed because my business (the holding company) is a UK registered company and therefore as long as my investments are also UK registered (and not REITS) then the dividends are tax free....
Have you ever posted your portfolio in full? I totally understand if you wish not to share but I'm happy to trade ideas if you're interested?
Thanks
Thanks Burnt Onions. I’ve got a very similar mix of Investment Trusts and it would be interesting to see your portfolio too. Question is ….where to post them? I’ve already done a complete off topic post on this thread and this isn’t the thread for it.
Hi Ken, probably me but I cannot see the dividend thread under the discussions...Cheers Tommy
Hi Tommy, it’s in the comments section here.
Corero Network Security (LON:CNS)
I've just seen Paul's comments on this morning's movers and a couple of things I would add :- Yes it's their own software they are selling. It's a huge addressable market with strong sales to leading network infrastructure companies and their customers. New CEO last year who comes across as very capable. It is definitely worth doing your own research and a good place to start would be the presentation video of last years results which although a strong year showed a small loss because of paying off debt. The ED video is HERE
Re Corero Network Security (LON:CNS)
Thanks Samsgrandad, very interesting. Can I query one point though, you say -
...last years results which although a strong year showed a small loss because of paying off debt.
Paying off debt wouldn't impact profitability, surely? If anything it should help profitability, due to a lower finance costs charge on the P&L.
2023 results show a loss before tax of $(0.2)m, down vs PBT of $0.4m in 2022. So I don't see how 2023 can possibly be called a "strong" year. It's not, it made a small loss. Although adj EBITDA rose from $1.7m to $2.2m, so maybe that's what they're using as their definition of a strong performance?
I see the gross margin is very high, so if they can really get revenues rising fast, then the operational gearing here could be very exciting.
Cashflows are not impressive as yet. Note that the borrowings it repaid in 2023 total only $1.2m, so not a big deal there.
Thanks for the link to the ED video, I'll check that out. I like potentially exponential growth companies, providing I can get in at a reasonable price, so CNS might be an interesting one to research over the weekend!
The existing numbers don't support a market cap anywhere near £60m, so the valuation almost entirely rests on hopes for future growth.
Regards, Paul.
Thanks Paul, as you'll see from my profile accountancy isn't my forte, I was in IT technical support, so between the two of us maybe we'll cope. There is certainly a lot of good news in the price but the take up by the market says a lot. I don't claim to be an expert in the field of security but what i've heard from the company makes a lot of sense and the hybrid war that putin is unleashing on the west makes getting the best very urgent.
Sorry, ran out of time today! But you can find all our research here https://www.equitydevelopment.... for Corero Network Security (LON:CNS) . Of course, it is expensive if they don’t keep delivering the growth, but as well as those contract wins take a look at their partnerships with Akamai (covering US signed on 11th Oct) and TechEnabler (covering SAmerica signed in Feb) which should help drive growth.
I don't see why anyone would buy DDOS protection from a tiny company like this personally.
I've worked in software development for almost 20 years and I've never heard of this company. There are huge US companies that do this as a standard (AWS, Cloudflare etc). I can't say I looked into whether there is a key differentiator here compared to the US tech giants but let's face it, if there is one then no one is buying it.
Avingtrans £4 for 2 years .
Can’t help feeling this is going to pop its 2 year trading range where it’s been trying to break the 4 quid barrier .
Pretty solid performance really compared to the market and whilst many share prices of vastly inferior companies are now making decent upwards moves Avingtrans remains pinned on the ropes .
Reminds me of Bloomsbury which did a similar thing around the same 4 quid barrier .
Market and investors clearly are not liking the new imaging division which is burning a bit of the cash they generate .
Could stay in this 4 quid range for 0-6 months but I think with a bit of market strength going to see a pop upwards ,
Sorry no reason for writing this other than pumping my own book .
I hope you are right, l have held Avingtrans (LON:AVG) for a few years, my patience was beginning to wear thin. Got quite a few of these type of shares in my folio. I have held Bloomsbury Publishing (LON:BMY) as well, one of better holdings.
I hold Lok'n Store (LON:LOK) and even though I'm sitting on a decent 77% return in 6 months feel a bit disappointed by the offer from Shurgard (greed anyone?). Broker Cavendish said on 20 Feb (worth a download):
"In the following table, we have compared the space-based valuation metrics from the Pickens deal to our target price calculation. Using the Pickens metrics derives a 1356p per share valuation for Lok’nStore (including the existing stores and pipeline stores). This is almost identical to our 1352p target price, which is based on applying the current valuation of Lok’nStore’s existing stores to the pipeline stores.
The SSG bid included a premium to NAV to reflect the fact that it is a platform (including brand and systems) from which the acquirer can then add or build assets. Our 1352p target price and the Pickens deal simply reflect the potential and existing value of the underlying assets/stores and pipeline.
Any bid for Lok’nStore plc would be a platform deal that should attract a premium."
I wonder why Cavendish, being an adviser to the deal, didn’t hold out for their target price?
POLR…..polar has shot up this morning …I have held for a while having read a write up here…Thanks Stockopedia…..Those are the shares I like….The ones that go up and pay a decent divi….and the sun is shining for once …Good day so far
POLR
Graham, coming from the fund managerial background picked up Polar as his first choice among the asset management sector. Well done to him.
Cockney Rebel first alerted me to this stock about 3 years ago and it has been my best performing share over that period . Another good one he recommended in the same podcast was Redde Northgate (LON:REDD) which is another long term hold for me. Been a nice couple of days with the Centaur Media (LON:CAU) possible offer.
Speedy Hire (LON:SDY) "Building a robust platform for growth" (FY24 pre-close statement)
Against a tough trading background in FY24, Speedy Hire has taken steps to build a platform for long term sustainable growth through the launch of its Velocity strategy. While progress has been more strategic than financial in the year – although we note positive underlying cash flow was achieved - new business wins, the acquisition of Green Power Hire and a transitioned B&Q model all suggest that profitability is likely to move ahead again from FY25 onwards.
Speedy’s FY24 pre close statement echoed January’s trading update, pointing to successful new business wins with National customers but also some mobilisation and adverse seasonal effects. Stated group revenue of c.£420m infers that H2 was slightly ahead of H124’s reported £208.5m. While closing year earnings expectations are likely to nudge down further, the prospect of year-on-year progress from FY25 onwards appears to be intact.
The launch of Speedy’s Velocity strategy in FY24 laid out clear group financial (FY28 revenue of £650m, EBITDA margin 28% with conservative gearing metrics) and operational ambitions (to deliver sustainable growth from an efficient digital and data-driven platform). The primary enabling actions are expected to be in place by the end of FY26, though there is clear capacity to accommodate an earnings recovery and growth beginning in FY25.
Notwithstanding market conditions, the company has taken clear strides in FY24 towards achieving its five-year targets, investing accordingly.
Link to research note: https://www.equitydevelopment....
UK brick deliveries recovering since December low:
https://twitter.com/NobleFranc...
Hi eParo
I suspect I see life from a different perspective to you. According to ONS stats published 10 April UK Brick deliveries in Jan and Feb were down just over 9% year on year for each month . I'd agree that the rate of decline has slowed, from the 30% or so we were seeing for much of last year, but I don't see this as a recovery. Hopefully that isn't too far away!
Noble Francis is imo disingenuous in looking at the Feb v Jan stats in isolation. Talking a book or a paid spokesperson?
"Noble Francis is imo disingenuous in looking at the Feb v Jan stats in isolation"
Agreed.
My understanding was that January/February Brick Deliveries were usually an improvement from December, so that tweet/x from Noble Francis didn't really provide much insight.
Coincidentally I looked at the latest ONS data that he is referring to a few weeks ago and subsequently sold my holding in Michelmersh Brick Holdings (LON:MBH) - I didn't see a recovery yet, and the company (I inferred) revealed as much a couple of weeks ago.
Following on from the Revolution Bars (LON:RBG) restructuring, City AM is reporting today that Stonegate (owned by PE firm TDR Capital), Britain’s biggestpub operator with 4,000 pubs, has £2.2bn of debt and included a “material uncertainty” statement in its recent annual report about its ability refinance debt due in July 2025.
On Revolution Bars (LON:RBG) - this does seem like a substantial restructuring, if they have 46 current sites and they are going to do "something" with 32 of them (18 closures, 14 rent restructuring).
However, the rent restructuring seems to be more temporary than permanent; it goes on to say that it will only be for the next 3 years. So somewhat of a rent "holiday" type thing than permanent restructure.
I remain intrigued by Revolution Bars. I also share Paul's sentiment that there might be more money sloshing around pockets now, given the April minimum wage increases. However, that is balanced against the structural decline in demand for nightclubs...
Geiger Counter (LON:GCL) - As a relatively novice investor I was wondering if anyone can offer informed thoughts/clarification regarding the potential up/downsides of the open offer to purchase one new ordinary share for 37.74p for every share currently held.
https://www.stockopedia.com/co... Plenty of information regarding the offer here.
Thanks for pointing me to this. Very helpful.
As a correction, it's 1 share for every 5 held.
The question to ask yourself is do you think it's worth buying something at 37.74p that's currently trading around 54p, and has a NAV of around 75p (70p fully diluted after the rights issue)? To me the answer is yes.
Downsides? How big is your position currently? How much exposure do you want to Uranium? Do you have the spare cash? Maybe there will be some short term selling as people bank some profit which will cause the price to drift?
Great answer af and just to add I am a holder and have subscribed.
Aysgarth
It’s well worth taking up the offer. You can buy more at 37.74p compared with a 53p share price now. When you receive the funds you are then free either to continue to hold the extra shares you’ve now got OR sell them and (barring an unlikely big share price fall) collect a useful profit.
NAV (Net Asset Value…I.e what the share is worth) is way higher than the current share price, so it could well be that the low share price now, compared with 70p NAV, means the market has already priced in the extra shares in issue.
And if that’s right the current 25% share price discount to NAV could well narrow again and lead to a significant share price gain ahead.
By the way this is a very good site for information on Geiger Counter (LON:GCL) and all the other Investment Trusts. You can check their top 10 holdings and keep an eye on how their share prices are doing too.
Here are their top 10. Note the concentrated portfoilo,including 27.4% of the entire Geiger Counter (LON:GCL) portfolio in NexGen Energy
https://www.theaic.co.uk/aic/f...
I hold and will of course take up... if you don't have spare cash ...say you have 10,000 Geiger Counter (LON:GCL) ... you have 2000 rights entitlement, so you would have to sell c.1400 shares to raise the £760 to buy 2000 ...which is free money. Good luck with the holding.
Geiger Counter (LON:GCL) not a company I follow , but I would imagine the rest (8000) are adjusted the date it goes ex rights.
The fully diluted NAV of 72 reflects the subscription offer.
There will be an Ex rights price as more shares will be issued.
You’re right of course RDHOWARTH that the fully diluted NAV of 72p compared with 54p share price reflects the subscription share offer.
This is an Investment Trust subscription share offer and NOT a single share rights issue (though subscription shares are like disguised rights issues) and there is no ex rights price to come, unless this subscription share is different to all the other subscription shares I used to hold and follow in the good old days when there were lots of them to be exercised, .
The share price has almost certainly already priced in the subscription share offer.
Already diluted then and not something you can take up now?
Yes yiannos1. The Record date was March 21st.
Thanks Ken
Ultimate Products (LON:ULTP)
I expect that automation of tasks refers to the digitalisation of workflows - anything from building spreadsheets to creating “citizen programmers” using AI-based tools* to help line users create IT applications without the need for IT specialists - which is a good thing because an unglamorous little company like this won’t have any “IT whizz kids”, just some trainee programmers, some tired old contractors, and a balding middle manager called Graham. I hold.
*see ServiceNow or Netcall, GitHub or Gitlab
Re Ultimate Products (LON:ULTP) - some of their process/IT/coding people are significantly above competent (particularly for the biz they work in)...there will be some graduate trainees too (as they have big grad recruitment)...ULTP develop and build all the time so the capability is cultural and likely to be durable...
Overall, there are similarities in approach between Space-X and Ultimate Products...strip down and simplify so that complexity is necessary rather than just for the shitzngiggles. Obvs they are merely sending product to Tesco etc rather than Mars so there are degrees of difference. I suspect the mgt at ULTP will not like the comparison to Musk.
And while I'm on here, just flagging Corero Network Security (LON:CNS) who are quietly getting on with winning more contracts, today's for $1.8m over 3 years with Tierpoint.
They have replaced an incumbent, if further proof were needed that their SmartWall ONE product was superior. And the scale of Tierpoint (40 data centres across 20 US markets) should also speak to their robust procurement process. CNS debt free, cash generating...
This from results the other week https://www.equitydevelopment....
Corero Network Security (LON:CNS)
and another contract for $2m less than 2 weeks ago, and ARR enough to sustain the company so profits starting to roll in.
Corero Network Security (LON:CNS) I've just noticed that my last post was my 255'th so this one will be 2^8. So something appropriate " There are 10 sorts of people in the world, those that understand the binary number system and those that don't"
01 :) !
Juniper have 10% and their customer base is huge. CNS client base is impressive going by their website
Thanks for the good write-up on Ultimate Products (LON:ULTP) Paul. I've been a holder for a while and think its a great little founder led business. It has a strong record of rejuvenating historical UK brands. Historically, mostly these are purchased for next to nothing from the administrator, Salter being the exception as its a #1 brand. The brand is then re-designed in-house and relaunched about a year later like Petra, Beldray, Progress and Kleeneze. They are sold at a price point just above cheap appliances and well below premium. Good point on competitive threats, but they are probably better placed than most being at the value end.
I think the quality of the business comes from the management team, the excellent relationships with retailers, brand recognition and their design base in Oldham which is not easy to replicate. It's also a capital light model which means there is a high return on capital and high dividend. The business is quite mature in the UK, so Europe is next through the likes of Action which is a major European customer. European growth is critical to doubling the size of the business in my view, and the Paris showroom is all part of that. The only brand that they don't own is Russell Hobbs wich is on a rolling 3 year licence from Spectrum Brands in the US. I suspect they might acquire the brand if it came available. Always the chance that they could be a bid target for Spectrum Brands, but hopefully they will stay independent for another decade or so.
Really its all about following the founder led management team.
Nice synopsis, thanks topvest! Just to query one point though, I vaguely recall from a podcast with management I did a few years ago, that the product design was mainly handled by the Chinese factories. Maybe I got that wrong? Another query which would be useful to raise with mgt is for more colour on their automation of simple tasks which is mentioned in the commentary. What type of things would that be, and what tech are they using? I think they mentioned AI (doesn't everyone though LOL!)
We tooks a few investors (who might comment on here) on a site visit to Oldham last November and products are definitely not designed in China. This is a brand business, with product design, innovation and brand management all done from their HQ in Oldham.
Automation - the easy response is listen in tomorrow to their presentation! They have an initiative within the business to for everyone to submit ideas on how to save time/automate tasks, and their internal IT whizz kids programme solutions. It's all iterative and small but it's building up to a better run, error free (so important for their customers) business which competitors struggle to match.
And small correction topinvest - Russell Hobbs is on a four year rolling licence, but otherwise an impeccable analysis.
Tomorrow's presentation for ease: https://www.equitydevelopment....
Impressive response from the Equity Development team - Investor relations 10 out of 10!
Thanks Paul on Ultimate Products (LON:ULTP) - they do have a design team in Oldham, but I suspect you are correct and most of the detailed work is completed in China.
To be fair to them that have been talking about automation of tasks for a couple of years now. They have given a couple of examples on recent presentations, but mostly back-office tasks etc. They are definitely not a technology play...more like a Sports Direct of the kitchen!
With Ultimate Products (LON:ULTP) , its a shame they are so dependent on a country that will happily steal all their IP and use it to become direct competitor. I would very much like to see them actively moving manufacturing elsewhere
With Ultimate Products (LON:ULTP) , its a shame they are so dependent on a country that will happily steal all their IP and use it to become direct competitor. I would very much like to see them actively moving manufacturing elsewhere
They don’t have IP in the sense of innovation or secret formulae. It’s all about the brand, which is built and nurtured in Europe. I’m completely relaxed about the manufacturing base in China, especially with all the spare capacity there that is going to keep costs very low for a while.
Morning shanklin!
With Ultimate Products (LON:ULTP) , its a shame they are so dependent on a country that will happily steal all their IP and use it to become direct competitor. I would very much like to see them actively moving manufacturing elsewhere
That's a good point that I was also wondering about. Why is it that China is the world's manufacturing hub for a vast number of products and components, yet we're told it's no longer a low wage economy? It just doesn't make sense to me.
I've asked several companies (including I think ULTP) why they get everything made in China, and the response is usually that the Chinese infrastructure is so geared up for mass manufacturing, that they make it look easy, there aren't any problems with product quality, moving things around is so easy, etc.
I also remember hearing some time ago that the Chinese Govt subsidises production in some sectors, in order to create full employment, so they sell some products at below cost - remember how China destroyed the solar panel manufacturers in Europe by dumping below cost, I believe? There was that special situation called PV Crystalox that we followed for years where a customer had forward contracted for a large number of solar panels at a price that became totally uneconomic due to Chinese competition undercutting, as apparently the Chinese Govt had decided it was a strategically important industry that they wanted to dominate. So PVCS in the end had to shut down their European factories as it was not possible to compete with the prices from China. I think the client paid up multiple millions in the end, just showing the potential dangers of forward ordering any product at a fixed price.
I also heard suggestions that a lot of Chinese products are actually made using very cheap labour in North Korea, then shipped over the border. Which also helps explain why China tolerates the maverick regime in N.Korea.
I'd be interested to hear from anyone with expertise in this area.
Regards, Paul.
Guys
The way it generally works is that a large (and they are huge) Chinese factory / manufacturer will work with their brands and develop / adapt the same technology everyone is using .
Tooling costs are high on many products so adapting an open mold and adding a few tweejs is how it works .
As for stealing IP I think you don’t really understand the general technical excellence of some Chinese factories .
Here’s an example I sat down last month with a roof tent manufacturer Wildland and the owner .
Their brand in Wildland and the owner has built it from nothing , brilliant engineer .
We were looking at each country and I had a list of all their main competitors and the so called market leaders in USA / Germany etc .
It’s funny - every single brand I named he simply said “yes we are making those, we design for them “
Even at the end he has some new models that were pretty cutting edge he was complaining “I want to keep for Wildland brand but all my customer push me to buy “
So in house design teams very rarely design from ground up unless you have a superstar like Dyson , nornally and always its in conjunction and in most cases (and I strongly suspect Ultimate) it’s as simple as put a logo on .
Ask yourself this - how big a design team would Ultimate need to design all their products in their range, ? Takes a lot of time and cost to design from scratch and be a market leader .
Ultimate Products (LON:ULTP) and design
1) they design all their products...this is done in conjunction with factories to align capability, pricing and styling/functionality. So you can call the design iterative or surface level...but its their design
2) they fully outsource the tooling and the engineering capability (tho I believe retain ownership of the former).
They will never be the first to make a product but will be among the first to replicate (with their own branding) ie, they are not in the original innovation game to a significant degree (there be some of their own tweaks)
So they have a design team that copies other people’s products ?
That’s a strange design team .
Let’s get real here as you say “they will never be the first but they will be amongst the first to replicate (that does actually mean copy ) “
So they don’t actually design anything .
So to sum up
- They use either standard products and put on their branding
-They copy other products and make their own version
nothing at all with this but its not exactly James Dyson who has a design team educated in his own university and truly designs ground up .
I think it’s ok to call a kettle black In this case and buying cheap Chinese electrical goods , or making cheap Chinese electrical goods and rebranding them or copying other successful products and making cheap versions in China is the business model .
It works
Good business
China is the major electrical producer in the workd
They are a major UK importer
End of story
The best business model ever “buy it for one sell it for two - rinse and repeat “ On a 4 times stock turn with a lean o er head will spit out a lot of profit .
Haha…I explained reasonably…but no need to agree. We are free to split our hairs as we choose
Ultimate products.
Paul, I think you're quite correct.
But in addition, how about that the cost of doing business is a fraction of the costs that we pay in the West. Health and Safety, regulation, cost of energy and ESG insanity , for example.
Until we slap on tariffs to level the playing field, especially to penalise for the emissions they produce which we have exported so we can claim to be green, China will continue to crush the West.
Yes, this would have costs for the consumer, but this might encourage less consumption of stuff we could do without.
Vietnam or Mexico but cheaper?
That is interesting. I know Action having been a supplier back in their early days and I now hold equity (though 3i (LON:III) as they remain a private company). Action operates 2,500 stores across Europe from a start 30 years ago in the Netherlands. They serve 15 million customers and another 9.6 million customers online. They operate one brand across Europe and continue to grow rapidly. They plan to enter the UK market ... watch out Aldi and Lidl. The offer is firmly value and if Ultimate Products (LON:ULTP) can secure a listing in the homewares category, then this could prove to be a major inflection point.
Polar Capital Holdings (LON:POLR) - "AUM and forecasts up, stellar returns, positive flows"
AUM jumped £2.3bn (+12%) over Q4 of FY24 to £21.9bn on 31 Mar 24, which is 12% above our previous forecast of £19.5bn, and +14% y-o-y growth (AUM 31 Mar 23: £19.2bn). In turn, our FY24 revenue forecast increases from £188.4m to £191.6m (+5% y-o-y, FY23: £182.9m).
PBT rose from £50.1m to £52.1m (+15% y-o-y, FY23: £45.2m) and basic EPS from 38.3p to 39.8p (+8% y-o-y, FY23: 36.8p). The EPS revision translates to a forward PER of just 11.5x
Investment performance was the booster for AUM in Q4, adding +£2.3bn or +12%, but for us probably most pleasing update was a return to positive, albeit modest, net flows in the quarter of +£56m. Moreover, Polar reported strong net flows in March (+£228m).
For the sector, there are signs of an improving outlook for UK and European equity and active management fund flows. For Polar Capital we think that its PER has clear potential for a re-rating and our fundamental valuation increases to 650p/share (42% above the current share price).
New research report: https://www.equitydevelopment.co.uk/research/aum-and-forecasts-up-stellar-returns-positive-flows
You forgot to mention to readers that you have also significantly increased FY25 adjusted estimates from 36.5p to 44.4p!
Thanks for your notes generally, it's so nice to be included in broker notes for a change.
Re Polar Capital Holdings (LON:POLR) in the note it looks like the benchmark for the Tech fund and Tech IT is the same - Dow Jones Global Tech net return index so why are the benchmark return figures different for them, both over 3M and 12M?
Thanks
Hi Doug, reason is the trust is data to end-Feb not end-March so 1 month timing difference, the trust factsheet to end-March wasn't out when written. See footnotes of chart.
Just to mention that Polar Capital will be exhibiting and presenting on three of their trusts and funds at the Mello2024 conference in May. There will be 40 plus listed companies there and so many investors from Stockopedia Stockopedia | Mello2024 conference...22nd and 23rd May | By carmensfella
Very strong results from Mears (LON:MER) this morning. Increased dividend too.
Yes, huge cash pile too. Hopefully management guidance on FY 24 is one of under promising to over deliver! Often wondered if there is a takeover possibility here?
This share has been on my watchlist for 12 months don’t know why I haven’t invested :/
A busy day for results so I shall get my request in early in the hope it’s successful
I would appreciate you casting your eyes over XPS Pensions (LON:XPS) which today updated us that they would be ahead of previously upgraded expectations. Rather like profit warnings coming in three’s, ahead of expectations seem to follow each other
Several key drivers are given for the growth which they say underpin FY25
I see that they’ve had a broker upgrade today to 298p & 14.9p EPS
I hold
Polar Capital Holdings (LON:POLR) AuM update.
Slightly positive inflow of £56m with an increase in AuM of £19.2b to £21.8b due to fund performance.
Paul, Thanks for the update on Ultimate Products (LON:ULTP) much appreciated from yesterday. Will probably hold until next update to see if Europe is working out for them, but concerned about the comment, the Chinese can just cut out the middle man.
Maybe one for Graham, but Polar Capital Holdings (LON:POLR) AuM update just out, up 14% over the previous 12 months.
Polar Capital Holdings (LON:POLR) most of that increase came in the last quarter which suggests things really picking up now. The most positive sign for me is their key global tech fund has gone from heavy outflows back into inflows - not surprised as performance looks very good.
Polar Capital Holdings (LON:POLR) - If my calculations are correct there were inflows of around £56m in the last quarter. This only the second net inflows in the last 8 quarters.
My morning smallcap tweet: Humpty Dumpty outlook 'never stronger'
Distil (LON:DIS) Novacyt SA (LON:NCYT) Lok'n Store (LON:LOK) iomart (LON:IOM) Norcros (LON:NXR)
◄Distil (DIS)► Q4 volume down 47%, rev down 23% to £344k despite advertising and promotional spend up 78% to £130k. Outlook "Despite a slower Q4 than expected, and the medium-term outlook for the spirits market remaining challenging, we are encouraged by the double-digit full-year growth following the restructuring of the business over the past year". [SP=0.6 Cap=5m]
◄Novacyt (NCYT)► FY-Dec results delayed from 30 Apr to May. Blames time required to integrate the accounts of Yourgene Health. New CEO appointed. [SP=50.86 Cap=42m]
◄Lok'nStore (LOK)► rec offer of 1110p, a 16% premium. [SP=952.72 Cap=313m]
◄iomart (IOM)► calls FY-Mar 'solid' despite sales miss with rev c.£127m but adj pretax c.£15m. F/C £128-131m and £14.3-16m resp. [SP=140.5 Cap=158m]
◄Norcros (NXR)► guides FY-Mar rev down 11% (6% at const FX). South Africa rev down 12.3% at const FX which it glosses as 'resilient' citing power interruptions in H1. U/L op profit in line with exp of £42.7m. [SP=176.5 Cap=158m]. I hold.
Norcros (LON:NXR)
Mr C
◄Norcros (NXR)► guides FY-Mar rev down 11% (6% at const FX). South Africa rev down 12.3% at const FX which it glosses as 'resilient' citing power interruptions in H1. U/L op profit in line with exp of £42.7m. [SP=176.5 Cap=158m]. I hold.
Ref SA
I think its a matter of fact there have been issues in Sa that are beyond their control these issues are not new news and have been widely publised in the press.
https://www.fairplanet.org/sto...
Note in H1 SA revenue was down 25% actual (11% cc) in H1 so its not really a susprise to me based on exactly the same happening in H1
What they have kind of glossed over is the ye revenues only coming in at £390 mill compared to £406 mill expected - for many companies sucha sales shortfall would perhaps lead to profit warning - thankfully norcros seemed to have managed to hit their profit targets despite these lower sales (hmm lets look at the adjusts in the final accounts to see the nasties !!!)
What i like about norcros is that they dont really hide anything and the numbers do the talking for themselves - they give us detailed broker notes so that where they do miss (such as on revenue) its all out in the open - here is the november full update with forward loking numbers (really useful guide to look back and see how company has doen compared to hopes earlier on)
https://www.equitydevelopment....
Note ref turnover they did close Johnston adhesives at the start of this year - presumably that wasnt adding to group profit so reduction in turnover compared to last year is not 100% lfl. Note that closue was well before interims stage so wont be reason for sales shortfall.
Hopefully stuff like the prior acquisition of Grant Westfield is helping - i think thats lower turnover higher margin work so overall despite a return to "tepid" lfl numbers then overall results are very acceptable for me. Many companies in the building and house refurb sector are really struggling at the low point of the cycle - so imho overall decent profits and tepid numbers is not the end of the world.