Small Cap Value Report (Thu 11 Jan 2024) - NGHT, TSTL, SPA, LORD, POLR, TRST, MER, XPP

Good morning from Paul & Graham!
Let's leave it there for today, before my elderly PC (or me!) blows a gasket!
Mid to large cap news so far this year strikes me as pretty good, which is encouraging for the overall economy, and hopefully smaller caps too - eg.
Larger housebuilders - are much higher share prices up with events now? -
Persimmon (LON:PSN) - y'day seemed surprisingly upbeat - reported FY 12/2023 completions (sales) ahead of expectations, albeit 33% down on 2022. Its outlook sees "highly uncertain" market conditions in 2024, but mortgage rates easing is already helping demand. Build costs moderating. Shares have risen 54% since late Oct 2023!
Taylor Wimpey (LON:TW.) - Today says FY 12/2023 operating profit at top end of guidance (£440-470m), which it says is in line with expectations. Uncertain market conditions, but improving mortgages outlook & enquiries. Order book is reduced. Planning system "extremely challenging" - slow. Build cost inflation almost gone, at 0-1% on new tenders, but 4% in H1 2024 due to time lag. Also trades in Spain, which I didn't know! Net cash £678m. Optimistic medium & long term, PSN said the same thing. Shares up 42% since late Oct 2023 low.
Big retailers - as you know, last week we had -
Next (LON:NXT) reporting a good Xmas & raised guidance, but
JD Sports Fashion (LON:JD.) warned on profits & plunged.
This week so far we have -
J Sainsbury (LON:SBRY) - yesterday it reiterated full year profit guidance at £670-700m. Groceries did well, general (mainly Argos) struggled. They offset. Shares dropped about 6% y'day on this news.
Tesco (LON:TSCO) - today says it traded well over Xmas, and raises retail op profit guidance to £2.75bn (previously £2.6-2.7bn). "Cautiously optimistic" about consumer spending in 2024.
Marks and Spencer (LON:MKS) - strong sales growth, esp groceries. Increased costs. FY 3/2024 looks in line with market expectations. Uncertain outlook for FY 3/2025, and increased costs, esp labour & business rates. Shares down 4% in early trades, after an excellent bull run since Oct 2022, up >150%!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Summaries
Nightcap (LON:NGHT) - Up 10% y’day to 5.65p (£12m) - Trading Update - Paul - AMBER/RED
Strong Dec 2023 trading, but still heavily negative for H1 (Jul-Dec). I don't like this company's fundamentals - too much debt, loss-making, overpaid mgt. However if we have a consumer resurgence in 2024, then there's operationally geared upside for this sector.
Tristel (LON:TSTL) - down 10% to 405p (£192m) - Director sales - Paul - AMBER
CEO & CFO sales announced yesterday afternoon hit the share price by 10%. The CEO is retiring, but why did the CFO also sell? Not vast amounts each, but it has clearly hurt short-term market sentiment.
1Spatial (LON:SPA) - 52.5p (£58m) - Enterprise contract wins - Paul - AMBER/GREEN
Contract wins announced yesterday sound pleasing. I just wanted to flag this share, as we’ve not looked at it for 4 years, but over that time it’s been transformed into a much more credible, and now profitable, growth company. Worth taking a closer look, I think it looks quite good, on a quick review only.
Lords Trading (LON:LORD) - down 8% to 42p y’day (£70m) - CFO leaving - Paul - AMBER/RED
I’m raising an amber/red flag here, due to abrupt departure of the CFO, only days after the year end, which concerns me.
Polar Capital Holdings (LON:POLR) - down 0.1% to 453p (£458m) - Aum Update - Graham - GREEN
Rising markets and strong returns have masked a large outflow of client money in Q3. One fund has generated a large performance fee, and this is also boosting short-term results. I remain positive but want to see client demand recover as quickly as possible.
Trustpilot (LON:TRST) - up 19% to 173.5p (£731m) - Trading Update - Graham - GREEN
Excellent news from Trustpilot as revenues for 2023 are ahead of estimates, with strong margins and the result is that adj. EBITDA is above the range of market expectations. With positive cash flow and a large cash balance, the company announces a £20m buyback.
Mears (LON:MER) - Up 8% to 337p (£343m) - Trading Update [ahead exps] - Paul - GREEN
This housing services group issues a slightly ahead update for FY 12/2023, but materially increases the FY 12/2024 outlook, although only to flat vs 2023, whereas previously it was for a fall in profits. Note the share buybacks are on a large scale, and strongly enhancing EPS, enough to more than absorb the increase in Corp Tax that kicked in from April 2023. Despite a big rise in share price, I remain of the view this share seems good value. Long-winded section below, as I had to calculate my own forecasts due to lack of broker coverage available.
XP Power (LON:XPP) - up 1% to £13.05 (£309m) - Trading Update - Graham - AMBER
Q4 revenues and net debt are both better than expected, due to the delayed relocation of a facility. So Q1 will see the negative impact (lower revenues and higher capex). Net debt has returned to a more manageable level, but I’d continue to treat this one cautiously.
Paul’s Section:
Nightcap (LON:NGHT)
Up 10% y’day to 5.65p (£12m) - Trading Update - Paul - AMBER/RED
I’m just looking back at the Admission Document for this small bars group from Jan 2021, and it floated at only 10p. Then look below at what happened to the share price - which can only be described as an initial frenzy, more than tripling in early 2021 to a daft price approaching 40p!
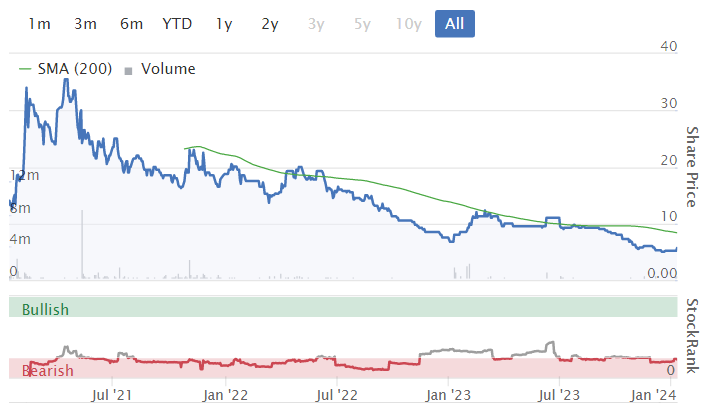
Maybe it was Dragon's Den viewers getting over-excited, as founder Sarah Willingham appeared on that TV show in 2015-16. She’s appeared on The Chase too. Her Wikipedia page shows other business activities previously, mainly involved in bars and restaurants, so lots of sector experience.
Personally, I’m wary of any kind of “star” management, as they so often seem to go wrong - look at Woodford, Sir Martin Sorrell’s S4 Capital (LON:SFOR) , and in hospitality Hugh Osmond’s Various Eateries (LON:VARE) which have all flopped. Hence over-paying for star management in IPOs is I think often a really terrible idea. If it’s just a startup, they have to prove themselves from scratch, just like anyone else.
On to yesterday’s news.
Trading update
Nightcap (AIM: NGHT), the owner and operator of 46 premium bars, is pleased to announce a positive trading update for the four week 2024 Christmas period as well as the 13 weeks and 26 weeks ended 31 December 2023, with record trading weeks across several of the Group's sites. This positive trading is despite the ongoing challenges of train strikes, inflation and the cost of living crisis.
This is H1, as the year end is FY 6/2024. It’s a good idea having a mid-year financial end, as Dec year ends leave peak trading right to the end of the year, making forecasting more difficult. Revolution Bars (LON:RBG) also has a June year end, but is high risk at the moment due to excessive bank debt used to acquire Peach Pubs.
Peak period (4 weeks to 31 Dec 2023) LFL sales an impressive +11.9% (for comparison, RBG achieved +9.0%, and the shares plunged about 20%). Remember that hospitality needs to achieve these levels of revenue growth, just to absorb the large hike in costs (especially labour, but also energy, and food/drink inflation).
Labour costs in particular rose c.10% in 2023, and is set to do the same in 2024, due to living wage increases. This is the largest cost in hospitality, being typically 30-35% of revenues, so it remains a major sector headwind.
However, customers benefit greatly from higher wages, and should have a lot more disposable income in 2024 (wages up c.5-10%, and inflation maybe 2-3%?), which is why the hospitality sector is coming alive again.
H1 (July-Dec 2023) LFL revenues were down 10.0% - which is awful, given that costs will be much higher than last year. This is despite the strong Xmas trading. So Q1 must have been absolutely dire.
Cash/debt - isn’t good, I don’t like the reliance on bank debt here -
The Group's cash position as at 31 December 2023 was £3.9 million (including cash in transit of £0.9 million). At the same date, the Group had total bank debt of £8.9 million resulting in a net debt position of £5.0 million (excluding convertible loan notes). £1.0 million of the Group's total bank debt is scheduled for repayment during FY2024.
Convertible loan notes are £2.65m (10% coupon, and minimum conversion price of 12p), so total net debt is really £7.65m, not £5.0m above. I don’t like the misleading reporting here.
Balance sheet is weak, NAV £14.5m, included £19m intangible assets, so it’s negative £(4.5)m at 2 July 2023. Fine if the business is profitable, but it’s not, there was a £(4.9)m statutory PBT loss in FY 6/2023.
Note that Director remuneration is excessive for the size (and lack of profits), with Mr & Mrs Willingham-Toxvaerd paid a combined £707k in FY 6/2023! That’s much too high, given the wobbly financial position and losses. Management should get paid handsomely once they've created a successful, profitable business, not before. What happened to sweat equity?!
Forecast - thanks to Allenby, which forecasts a reduced loss before tax of £(336)k for FY 6/2024, but this assumes a large fall in staff costs from 36% to 29.5% of revenues, which strikes me as unrealistic. Hence I’m expecting a profit warning at some stage.
Paul’s opinion - the closer I look, the less I like NGHT shares.
It’s a collection of I think rather tired brands, eg Dirty Martini, The Cocktail Club, and others - some bought out of administration (there’s a reason for that).
NGHT doesn’t make any genuine profit. There’s too much debt too. So overall it has to be a mild thumbs down from me, with AMBER/RED.
The sector opportunity is that consumers may come roaring back in 2024, with large increases in real terms earnings in the pipeline. With typical gross margins around 70-80%, bars and restaurants could see operationally geared upside if demand surges up.
So if you fancy a punt on that upside scenario playing out, NGHT could be of interest. Although it strikes me as a poor quality business, I’d be looking for more interesting, lower risk punts in this sector. I’ve gone with Tortilla Mexican Grill (LON:MEX) (I hold) in the casual dining space as my hospitality sector choice at the moment, where I think risk:reward seems better.
Tristel (LON:TSTL)
Down 10% to 405p - Director sales - Paul - AMBER
CEO sold £211k-worth (50k shares) at 422.5p (£1.1m remaining)
CFO sold £169k-worth (40k shares) at 422.5p (£968k remaining)
This announcement was issued at 14:27 yesterday, and triggered a 10% drop in share price.
Nobody likes to see Directors selling £6-figure (or more) shares, as it raises questions about how much upside they see for the shares.
Although in this case, TSTL’s very long-serving CEO had previously announced his intention to retire, so I think reducing his shareholding is understandable. The CFO following suit isn’t a great signal though. Obviously this has hurt short-term confidence, although we don’t know whether that will linger, or be quickly forgotten?
Paul’s opinion - It’s a pity Directors have sold some shares, as I really liked the last update from TSTL on 19/12/2023, and since it was brimming with positivity, I went up from amber to amber/green.
We always complain about the high valuation of TSTL shares, and even after yesterday’s 10% price fall, the forecast PER remains high at 27.4x
I think Director selling is more important when combined with a high valuation, as it raises the question as to whether the upside is really as exciting as the market thinks?
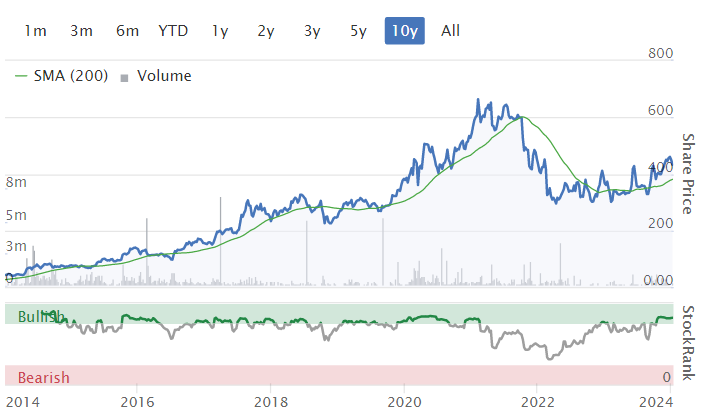
This does raise a question mark, so I’m dropping from amber/green back to AMBER. Looking at valuation, I’d be happier if the share price started with a 2 or a 3, not a 4. It’s still a nice company though, with a terrific long-term track record, having 20-bagged in the last 11 years. So as usual, my only quibble is valuation, not the fundamental quality of the company, which is very good.
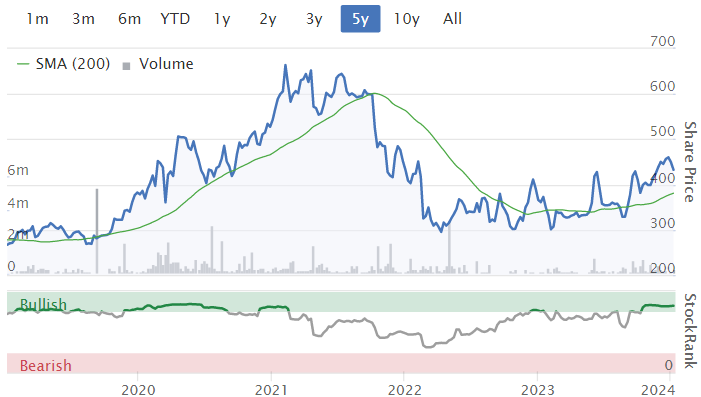
Zooming out to 10 years, the really big % gains happened in years 2014-18
1Spatial (LON:SPA)
52.5p (£58m) - Enterprise contract wins - Paul - AMBER/GREEN
1Spatial, (AIM: SPA), a global leader in Location Master Data Management (LMDM) software and solutions, secured several multi-year Enterprise contracts in December, strengthening the Group's position across its key geographies and closing the year with good momentum.
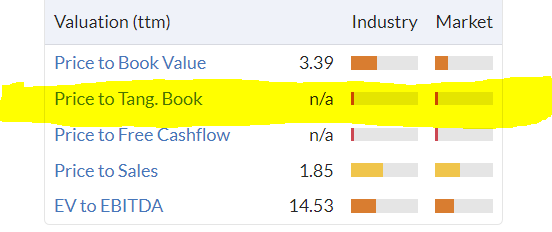
I wanted to get something into the system here about 1Spatial, as we’ve not reviewed it for 4 years, and things have improved considerably - a good growth track record, and it’s moved into profit - although no divis yet, and the balance sheet needs a look (whenever you see “n/a” here on the StockReport, that means the balance sheet is negative, so weak, and requiring more investigation) -
Good growth track record now -
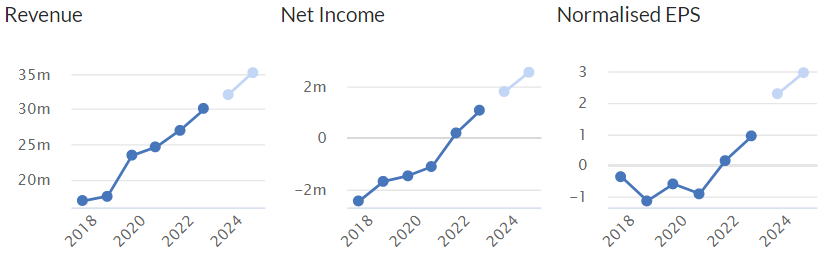
Is it worth the market cap of £58m though? Possibly, if it achieves forecasts, and if profit growth continues.
News yesterday was about 2 contract extensions, which as SPA says, demonstrates that customers like its software, in Europe and USA.
Director comments - sound intriguing -
Commenting on the contract awards, 1Spatial CEO, Claire Milverton, said: "We are delighted to have been awarded these significant contracts from these major organisations, expanding our presence in Europe and the US. These wins demonstrate that the Land and Expand strategy in our Enterprise business is continuing to deliver organic growth, and alongside our 1Streetworks and NG911 offerings, we believe the opportunity for 1Spatial has never been greater. These wins prove that our customers understand the value of our world-leading and innovative technology as we are increasingly selected as the chosen provider on a repeat basis, and we expect many further opportunities from our patented 1Integrate offering across key geographies."
Paul’s opinion - I don’t know much about the 1Spatial, but I vaguely recall it cropped up recently on my radar as sounding interesting - possibly a webinar, or fund manager interview, I can’t remember.
Anyway, giving it a quick review today, yes SPA does look interesting, it strikes me as a credible software company that seems to be on an interesting growth trajectory. I’d like to learn more about this company, so please do let us know in the comments if you’ve looked at it closely, and what your view is.
This latest RNS doesn’t say anything about trading vs market expectations for FY 1/2024, but this headline implies things are OK - “closing the year with good momentum”.
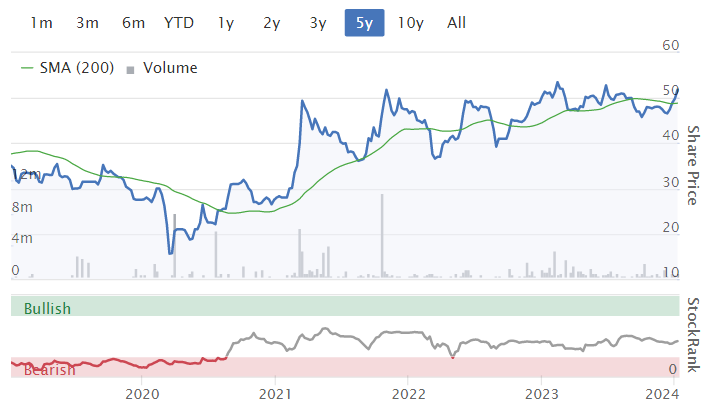
Interesting how SPA shares have shrugged off the last 2 years bear market in UK small caps - so the relative performance is much better than this chart suggests -
Lords Trading (LON:LORD)
Down 8% to 42p y’day (£70m) - CFO leaving - Paul - AMBER/RED
Lords, a leading distributor of building materials in the UK, announces that Chris Day, Chief Financial Officer and Chief Operating Officer, has informed the Board of his decision to leave the Company to take up another professional opportunity.
One of many disappointing 2021 floats, Lords is a distributor of building products.
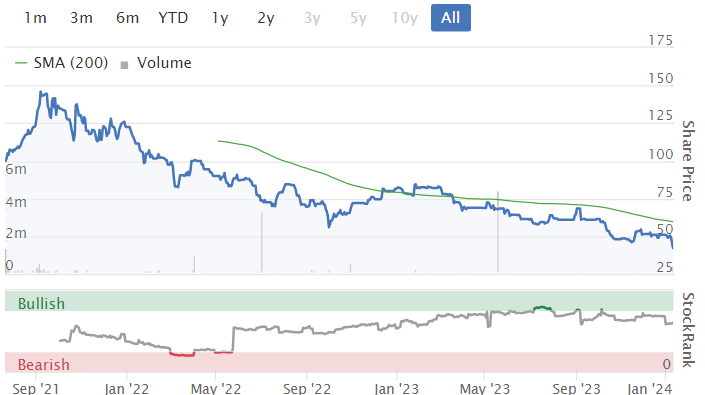
Shares hit a new all-time low yesterday, as confidence seems to have taken a knock (understandably) from Tuesday’s news of the abrupt departure of its CFO/COO (same person).
It’s the timing that worries me - it’s not good when a CFO resigns just after the year end - there’s an unwritten rule that CFOs should stick around and get the audited numbers out, and then move on to another job. However in this case it says he will be leaving Lords in H1 2024, and is thanked. But a new CFO is actively being sought asap to “ensure a smooth transition”.
Paul’s opinion - I find this unsettling, so even though Lords looks attractive on value metrics (PER 7.3x, and 4.9% divi yield on the StockReport), I’ll be keeping my distance for the time being. Looking back at my previous notes, it lowered FY 12/2023 guidance by 15% on 7/9/2023, mentioning tough market conditions. Also I’ve flagged before that the founding family has too large a controlling stake for my taste, so the free float is only tiny, hence difficult to trade and possible delisting risk?
It could all turn out to be fine though, so I’ll update you again when the next trading update is issued.
Mears (LON:MER)
Up 8% to 337p (£343m) - Trading Update - Paul - GREEN
Mears (LSE: MER), the UK Housing solutions provider, announces the following update on trading for the financial year ended 31 December 2023 ('FY23') and its expectations for the current financial year ('FY24').
This sounds good -
Strong trading performance and cash generation
Significantly upgraded earnings expectations for FY24
We previously flagged Mears positively (GREEN) 4 times - 8/12/2022, 28/4/2023, then twice more in the last 6 months -
SCVR 16/6/2023 - GREEN - up 8% to 263p - Materially ahead TU.
SCVR 3/8/2023 - GREEN - up 2% to 277p - Good interims. Still reasonable value. Benefiting from asylum seeker accommodation contracts.
What we liked was its low PER, good divis, and sound balance sheet. I hope some members here have gained from the recent surge in share price - up 33% since the Oct 2023 lows. Although lots of shares have surged in the last 3 months, and it remains to be seen if these sometimes rather frenzied rises will hold, or if profit-taking might be the order of the day? As always, it depends on our individual investing/trading timescales and risk tolerance.
What does it say today?
FY 12/2023 trading is “modestly ahead” -
The strong financial performance reported in the interim results on 4 August 2023 continued through the second half of FY23. The Board anticipates reporting results for the full year that are modestly ahead of market expectations1 with revenues and adjusted profit before tax in excess of £1,050m and £43m respectively.
1 The Board consider the current consensus analyst forecasts for FY23, prior to this announcement, to be revenues of £1031m and adjusted profit before tax of £40.9m. Adjusted profit before tax is reported before the amortisation of acquisition intangibles. On the same basis, the Board considers market expectations for FY24, prior to this announcement, to be revenues of £888m and adjusted profit before tax of £ £33.9m respectively.
This is great - Mears discloses adj PBT (good) and not adj EBITDA (bad), well done Mears! Everyone needs to do this, I’m sick and tired of EBITDA nonsense in trading updates, and so are almost all the investors I talk to. So come on other companies, give us the figures we actually want please, not fantasy numbers! Or give both, then everyone’s happy.
Plus a detailed footnote above, top notch reporting Mears!
Note that before today the market was expecting a sharp fall in 2024 PBT vs 2023, it's now guiding profits to be flat from 2023 to 2024.
Net cash - I’m in danger of exploding with excitement here, as it also provides another key item on my wish list for company reporting - average daily cash! -
The Group delivered a strong conversion of EBITDA to operating cash flow, with net cash at 31 December 2023 of c.£105m and an average daily net cash over the 12-month period of c.£75m, both of which are ahead of previous guidance.
The Group delivered a strong conversion of EBITDA to operating cash flow, with net cash at 31 December 2023 of c.£105m and an average daily net cash over the 12-month period of c.£75m, both of which are ahead of previous guidance.
Outlook for 2024 - again, crystal clear guidance here -
The momentum seen in 2023 is expected to continue into 2024 and, as a result, the Board's expectations for FY24 now sit materially ahead of market expectations1.
The Board continues to anticipate a reduction in management-led revenues as the elevated activity level seen across FY23 normalises.
However, adjusted profit before tax in FY24 is now expected to be of a similar quantum to FY23, reflecting continued margin progression.
Share buybacks - authority now used up. Will seek a fresh authority.
Broker updates - nothing available to pond life like us.
Working out the figures manually myself, using the interims (and today’s update), plus the broker consensus figures on the StockReport as guides, here are my numbers.
£43m adj PBT. Note that adj and statutory profit are practically the same. Note that corporation tax was 21% in H1, but is likely to be higher at 25% in H2 (it went up from 19% in April 2023). So I’ll use 23% tax for FY 12/2023. That gives PAT of £33.1m. Divide by 113.5m fully diluted share count (taken from note 8 in interims), ah no hang on, there’s been a big share buyback, so scrap that. The share count seems to have come down from 110.86m at the health year, to just 101.55m in the most recent RNS on 2/1/2024, that’s a huge fall in just 6 months.
For EPS we should use a weighted average share count I think, but I’m going to use the current share count of 101.55 + 2.67 share options dilution (unchanged from interims, I assume), giving 104.22m shares in issue.
This results in 31.8p EPS (diluted) by my calculations for FY 12/2023.
At 337p per share today, that results in a PER of 10.6x - still looks good value to me, considering it also has a nice cash pile on top.
Moving on to FY 12/2024, it says a similar result is likely, so £43m PBT, but higher tax at 25%, so PAT falls to £32.3m, and with more buybacks likely, I’ll estimate a further reduced share count of say 5m, so let’s call it 99m shares by end 2024, and hence a slight rise to 32.6p EPS. Giving a FY 12/2024 PER of 10.3x - good value.
Paul’s opinion - I think the big rise in MER share price recently is fully justified, and shares remain good value. So I’m happy to stick with GREEN.
Sorry this was a bit long-winded, but I wanted to show my workings, and once you start these things, you can’t stop!
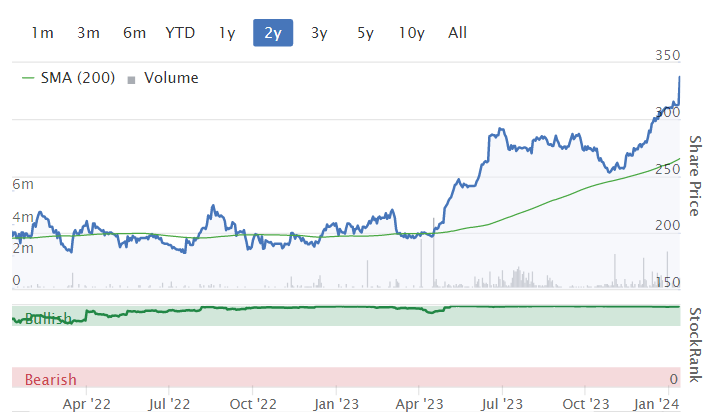
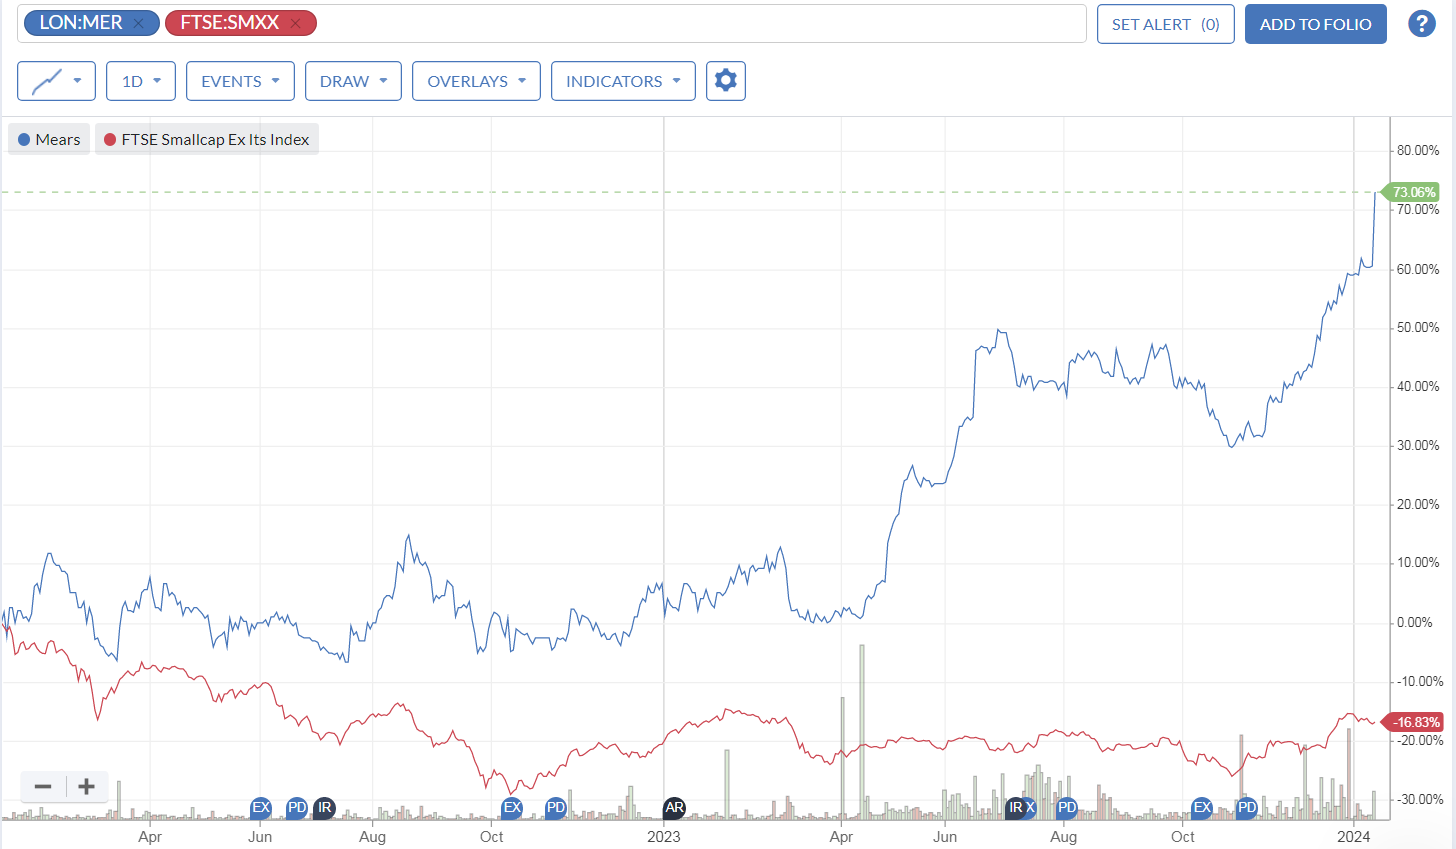
Mears shares laugh in the face of a 2 year bear market -
Here it is compared with its benchmark index (SMXX since MER is fully listed) - up 73% in two years, compared with SMXX down -17% - with divis on top of that too - a cracking investment I'd say -
Graham’s Section:
Polar Capital Holdings (LON:POLR)
Share price: 453p (-0.1%)
Market cap: £458m
This is a Q3 update to December, as Polar’s year-end is in March.
Assets under management have risen to £19.6 billion (Dec 2023), versus £19.1 billion at the end of Q2 (September 2023).
Net flows were negative in the quarter to the tune of £1.1 billion - more than the first two quarters combined.
However, AuM still rose as investment returns more than fully reversed the impact of net flows.
CEO comment:
Despite global equity markets rallying in the final quarter, the 'risk-off' stance by investors resulted in net outflows in the quarter of £1.1bn as clients reduced their weighting to active equities, taking profits in many cases following a strong period of performance.
Possibly providing some consolation, the CEO says that “redemptions were concentrated in terms of number of clients, as opposed to representative of a wider trend”.
One fund (not named) has generated a large performance fee, and this has provided a big boost to Polar’s total performance fee income:
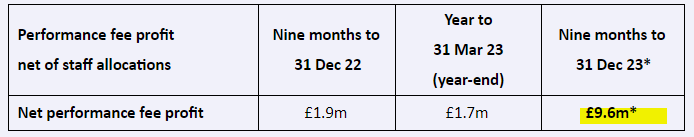
Estimates: Many thanks to Paul Bryant at Equity Development who has published new forecasts this morning; with the benefit of these performance fees, his PBT estimate increases from £41.6m to £50.1m.
The EPS estimate increases from 31.8p to 38.2p.
Graham’s view
One difficulty with valuing Polar (or any fund manager) is the uncertainty around performance fees; if we are attaching an earning multiple to profits, it almost feels like we should have one multiple for performance fees - lower due to their uncertainty - and another, higher multiple for profits from management fees.
Personally, I have been positive on Polar and I picked it for my 2024 best ideas list. Today, we have positive news on performance fees, but the news on flows remains poor.
If I had a choice, I think I’d prefer to see positive news on flows, as this speaks to the health of the underlying business and client demand for Polar’s products.
With the Biotech and UK Value funds posting “impressive absolute fund performance and strong performance relative to benchmark” (in the words of Polar’s CEO), I’m hopeful that we might see a stabilisation in flows before too long.
Investors only get £43 of AuM for every £1 invested in Polar shares at the current price, so this fund manager is on a much richer valuation than others in the space we have reviewed (especially the likes of Jupiter Fund Management (LON:JUP) etc.).
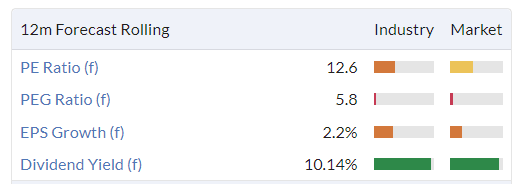
I also note that its enormous dividend yield is not fully covered by current earnings
Overall, I continue to like the stock and retain my positive stance, but must admit that I would be alarmed if flows continued at their current rate for much longer.
Trustpilot (LON:TRST)
Share price: 173.5p (+19%)
Market cap: £731m
We have three announcements from Trustpilot this morning - trading update, share buyback, and directorate change.
Let’s start with the trading update for 2023:
Revenue +17% to $176m, annualised recurring revenue +18% (at constant currency) to $197m.
Adjusted EBITDA above the top end of the range of market expectations.
The company helpfully discloses that it believes market expectations to be revenue growth of 15% and adj. EBITDA of $11.1m - 14.1m.
Continuing:
Net dollar retention rate (i.e. revenue from existing customers) dips from 100% to 99% (still v. good).
Net cash rises from $83m (June) to $91m.
Since the company’s cash balance is rising and it plainly doesn’t need all of this cash, it separately announces a buyback of £20m (c. $25m). The company’s intention is to cancel the shares purchased, i.e. permanently reducing the share capital of the company.
The company says:
As previously announced on 19 September 2023, the Company is committed to running an efficient balance sheet and returning excess capital, not required for other priorities, to shareholders.
Indeed, we commented on this in a September SCVR, when the company said that it was cash flow positive and was committed to returning excess capital to shareholders. So there was a clue that this could happen.
Returning to the trading update, here are the CEO’s comments on recent performance:
"Building on a solid performance in the first half of the year, we achieved further growth and margin improvement in the second half, with profitability and positive free cash flow ahead of expectations for the year...
The strong performance in FY23 shows the strength of the Group. We remain confident in our ability to sustain growth and improve margins over the long term as we deepen the network effects in our model to capitalise on large and growing market opportunities."
In the final RNS of the day from Trustpilot, the company announces that a long-standing NED is retiring.
(As an aside, this strikes me as the right way to publish multiple news items - in separate RNS announcements. Jupiter Fund Management (LON:JUP) caused a bit of a stir this week by publishing a trading update at the bottom of an RNS whose main subject was personnel change).
Graham’s view
I’m delighted that the investment thesis is playing out here. Note the very strong earnings momentum, prior to today’s beat:
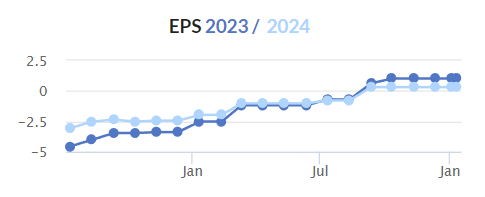
It’s a powerful situation when a company is making the transition from losses into profitability; small increases in revenues/margins translate to huge percentage increases in expected profits.
Trustpilot is doing that but with the added tailwinds of a) an enormous cash balance, giving it the flexibility to invest as required but also to return money to shareholders, b) a strong - and in my view - increasingly strong - competitive position, where the bigger it grows, the more compelling its product becomes. I believe these are the “network effects in our model” mentioned by the CEO.
Naturally, I must perform the analyst’s equivalent of “letting my winners run”, and keep my positive stance on these shares.
XP Power (LON:XPP)
Share price: £13.05 (+1%)
Market cap: £309m
XP Power, one of the world's leading developers and manufacturers of critical power control components to the electronics industry, is today issuing a trading update for the fourth quarter and full year ended 31 December 2023.
Paul has provided excellent coverage of this one in recent months, most recently the £45m fundraising in November.
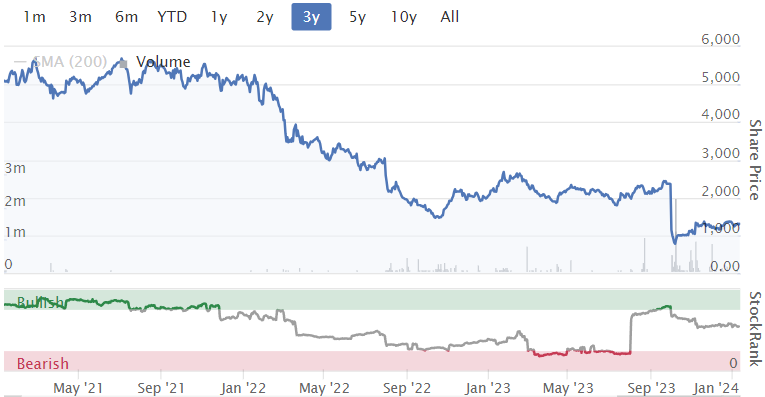
The wheels have sadly come off here in recent years, as profitability has evaporated:
Let’s catch up with today’s trading update:
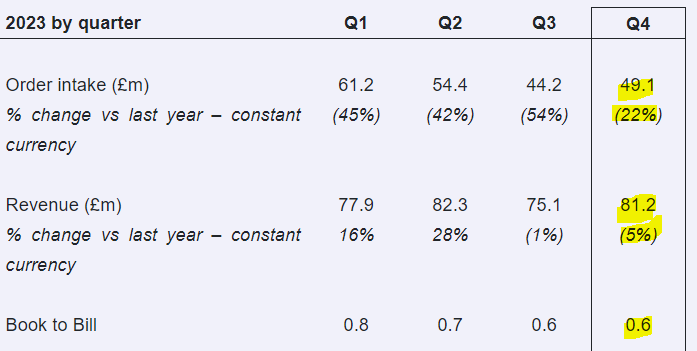
The right-hand column shows a sequential improvement in Q4 orders and revenue vs. Q3, though the numbers are still down compared to last year.
One possible bright spot is that the revenue decline in Q4 compared to last year is “only” 5%, and is ahead of expectations.
However, this is “largely” due to “the decision to reschedule the relocation of our facility in California, from December 2023 to January 2024. This had the effect of bringing forward £5.0m of revenues from orders shipped earlier than expected in Q4 2023 rather than Q1 2024.”
So these £5m of revenues will be missing from the Q1 result.
On a full-year basis, revenues are up 8% (at constant currencies).
Orders
Book-to-bill of 0.6 confirms that the order book continues to decline.
The book finished 2023 at £192m.
XPP doesn’t mention what it was a year ago, which is never a good sign! So I’ve looked it up: a year ago, the order book was £300m.
In the company’s defence, it did say a year ago that the £300m book gave the company “a greater visibility than normal” and that they expected visibility “to return to more normal levels” in 2023 - this has certainly happened!
Net debt
At the end of the year, net debt was £112.6m, better than expected, but again this is due to the delayed relocation of the US facility. £12m of capex payments will hit in early 2023.
Paul’s September report noted that XPP’s net debt position had reached £163m by early October, prior to the refinancing.
Net debt/EBITDA at the end of the year is expected to be c. 2.0x, vs. 2.6x at the end of Q3.
This is consistent with the idea that the fundraising eliminated about a quarter of the net debt.
In very general terms, lenders start to get nervous when net debt/EBITDA crosses above 3x. At 2.0x, XPP should have some breathing room.
Cost and debt reduction plans announced with the fund plan are “on track”.
Outlook
Whilst it is too soon to be definitive about prospects for 2024, we continue to expect that market conditions will improve as the year progresses, with our results being weighted towards the second half. Our performance will be supported by the actions taken to reduce our cost base and we will continue to respond decisively to market conditions as they evolve.
Graham’s view
I’m going to stay neutral on this one, as it appears that the company’s balance sheet can survive in the short-term, given the latest net debt/EBITDA multiple. After that, it’s difficult to say - visibility has “normalised” in the form of a far smaller order book, with revenues now also seemingly under pressure.
I can’t help thinking about the recent trade secrets lawsuit against XP Power. Apart from the immediate financial damages ($40m, including $20m of punitive damages which XP Power are appealing), I wonder if the lawsuit has had any other repercussions for the company, such as reputational issues?
For anyone who previously had XP Power on their “buy” watchlist, maybe now could be a good time to get involved? But personally I wouldn’t be in any rush here.
Paul - Ignore this - just trying something out!
Name | Ticker | RNS type | Mkt Cap | |
Nightcap | NGHT | Trading Update | £12m | Paul done |
Tristel | TSTL | Director selling | £192 | Paul done |
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

71 comments
Tristel (LON:TSTL) The CEO and CFO are married so that would explain why they are both selling shares on the former's retirement.
Thanks for the review on Polar Capital Holdings (LON:POLR) Graham. I did instinctively feel surprised this morning, at the large outflows in Q3. I bought it last July for the (i) big upside once markets get back into full swing, and (ii) the whopping dividend. I've posted before about this, so some of this is repetition.
I think (i) is a given, we just have to wait long enough. In relation to (ii), the dividend clearly is at risk but how much risk is still not clear. It's not covered by full year earnings, but the company stated in the annual results:
"The Group's dividend policy is to pay an annual dividend within a range of 55% and 85% of adjusted total earnings, dependent on the scale of performance fees in the relevant year and the anticipated trading conditions for the following year. Where appropriate, the Group will consider using its balance sheet strength to support the dividend."
They seem to be ignoring the 55%-85% rule. Last years dividend was 100+% of adjusted earnings. I had previously focused on the adjusted total earnings bit, because last year this gave significantly increased EPS when compared to basic EPS (last year, basic was 36.8p, adjusted was 44.3p). It's not clear whether the upgraded EPS forecast of 38.2p for this year is intended to be adjusted earnings, or unadjusted, so it's hard to make an estimate on this.
But today's performance fees are much larger than last year, so they may be feeling rich. That depends how much the outflows have surprised / scared management, but that's impossible to know right now.
I think if they decide to cut (rebaseline is the current way of pretending you're not cutting) the dividend, the share price would fall significantly, which I assume they won't want. Given they've said they would look at supporting the dividend from cash on the balance sheet, which they have quite a bit of (£70m at the half year), I'm hopeful (no more than that) that the dividend will be safe.
Cheers
Chris
Anyone looking at investing in Fund Management groups might want to look at this annual survey by the Investment Association. I found it will doing some research into the listed UK fund management sector. https://www.theia.org/sites/de...
Monster report today.
I am not sure I will have time to read it all, I sure don’t know how you find the time and energy to write it.
Mega applause.
Regards
Michael.
Thanks Michael!
Yes we've pulled out all the stops, and have the accelerator flat down!
Thank you for the encouragement, much appreciated!
Regards, Paul.
anyone know why Kenmare Resources (LON:KMR) keeps falling?
re Kenmare Resources (LON:KMR) , their selling prices tend to follow the level of Chinese construction activity. I am no expert, but I would expect them to be receiving lower prices this year. Plenty of other possibilities. I hold.
Cavendish Financial (LON:CAV)
I have noticed recently that half of my emails are from them.
Are they the brokers of so many listed companies?
I have opened a small position until further research.
Any opinions on this one?
Thanks
Cavendish is a merger between finnCap and Cenkos both of which covered a large number of companies.
Full list here: https://www.cavendish.com/rese...
Hi Yiannos1, Cavendish Financial (LON:CAV) I have a small position at 10.5p so it's on my radar but I can't find any research on it and I have no access to forecasts and thus no idea what it's worth!
From the last results they mooted £7m savings post merger and they had £17m in cash against a £40m mkt cap, numerous small director buys but they have been losing money.
However the investment thesis is very interesting, they have gone from being 2 small cap brokers competing on price to becoming the largest AIM broker. This must give them better pricing power. Furthermore if after two years of no IPO's and minimal placings you think this is going to change and this year we will see a lot more corporate action in the AIM sector then these guys will be the obvious beneficiaries, operationally geared etc etc
I will probably add on positive news flow or if I see a lot more activity in the small cap sector, until then it's wait and watch.
Has anyone read Savills (LON:SVS) TU today? It seems to say virtually nothing useful for shareholders, just generalised backdrop to the property market.
On the other hand hat-tip to whoever drafted the TU and avoided saying property prices are heading down, instead using 'recalibrated'.
Made Tech (LON:MTEC)
A very interesting appointment in the new CFO; with a well proven track record.
I will appreciate if anyone familiar with the company to tell us more.
hi yiannos1
Made Tech (LON:MTEC)
Agree the new CFO has a strong pedigree and appears a good appointment.
The departing CFO doesn't get any glowing praise, being merely 'thanked for her contribution to the group since IPO'. Also her departure is unplanned and sudden.
Graham last reviewed MTEC in May when he commented;
'a nasty profit warning from this 2021 IPO (the words “2021 IPO” should strike fear into the hearts of investors)'
and
'looks like just another opportunistic IPO from that annus horribilis'
Not sure much has changed.
Snazzy
Look at her LinkedIn profile. She moves on every 2 or so years, so I'm not losing sleep over her departure.
Chief Financial Officer
Made Tech · Full-time
Sep 2021 - Present · 2 yrs 5 mos
London Area, United Kingdom
"Joined Made Tech to support the company and help lost on London Stock Exchange’s AIM and become a publicly traded business."
(Nice typo above in her profile!)
Probably recruited to help with the IPO and now time for a more heavyweight to take over.
3 microcaps for 2024
https://blackswanshares.substa...
MADE TECH GROUP (MTEC) MC £16 mil
This is a mini KNOS, software co which specializes in digitisation projects for central and local UK government. The sp has been an absolute disaster since ipo. Again, this is another human capital intensive business which hired too many expensive employees at the top of the market and coupled with normalizing demand after covid, meant a tough, loss making period in which the ceo decided to shift focus on profitable growth by cutting costs, etc. The main positive with MTEC is the net cash position. It has c £8 mil net cash and this should be more than enough to support the transition to profitability without dilution. The main weakness is that these gov contracts are on a “call off basis” ie there are no defined time schedules so the timing of contract delivery it’s entirely at the client’s discretion. A few delays in timing caused poor staff utilisation rates which in turn impacted profitability but MTEC never lost a client and has a contracted backlog of c £67mil so it’s a matter of when, not if. Once these contracts start, the operational gearing will have the opposite effect: super profits.
Trustpilot (LON:TRST)
Excellent analysis from Graham.
My biggest holding having added this 3 weeks ago . It is my opinion that this one will be growing for many years and will be returning millions back to shareholders. An excellent growth opportunity here.
All the best
TRST
Most likely will be bought by google!
EKF Diagnostics Holdings (LON:EKF) (I hold) - +8% today
RNS this morning -
EKF Diagnostics Holdings plc (AIM: EKF), the AIM-listed global diagnostics business, announces that the Board of EKF has been informed that on Tuesday 9 January 2024, certain funds connected to Christopher Mills, Non-Executive Director, purchased a total of 100,000 ordinary shares of 1 pence each in the Company ("Ordinary Shares") at a price of 30 pence per Ordinary Share. Following this transaction, Christopher Mills' total direct and indirect interest in the Company is 132,250,000 Ordinary Shares, representing approximately 29.147% of the total voting rights over the Company's issued share capital.
The market makers seem to think this has a positive effect, but am I right that 30% is usually the limit for the Mills cohort, and does this remove a buyer from the market?
Either way, I have a target of at least a double from here if (and only if) the South Bend enzyme reactors work properly and they find customers for the huge new output.
EKF
I’d see it as positive
Mills and his team are pretty savvy at engineering exits / sales
They will not sit back on hold but will Engage with management and get this into play
Interesting history of Mills' involvement. I remember him pushing this business ages ago in one of his interviews with Paul Hill when he was saying how knowledgeable about enzymes the CEO was, then the wheels fell off with the core business underperforming and the new South Bend facility going way behind schedule. The CEO is now changed, the previous one now focusses on South Bend IIRC, and I'm guessing this is one Mills will want to put behind him before too long (but not at 30p).
Polar Capital Holdings (LON:POLR) continued outflows are a concern and I suspect could be the result of ever increasing competition from passives (plenty of sector themed ETFs that can compete with Polar's tech and healthcare funds) - the big market rally over last couple of months offset the outflows this time but can't rely on this every quarter.
Taylor Wimpey (LON:TW.)
Interesting : build cost inflation is now running at 0-1%! Real wages up, interest rates down, build inflation zero……… feels like 6 months forward looking they could have a good few years from here.
But more importantly it seems to validate that inflation could well be below 2% this year.
MPAC (LON:MPAC) I am surprised by the muted reaction to results. I know they are in-line but consider what they tell us. 2024 Revenues are more than 60% covered by the growing order book (higher revenue visibility to normal). They are net cash and forecast to do 38.5p EPS in 2024. If we look at H1 and H2 split for this year which was weighted largely due to normalising margins (rather than any seasonal split) then I think 38.5p can be beaten relatively easily.
Even if that’s 40p EPS then surely 285p (or a PE of 7) is just too cheap. And all of that completely ignores any FREYR potential upside.
Brokers seem to think it’s worth closer to a fiver - that’s almost double potential.
MPAC (LON:MPAC) David I just tried to buy some more but can't even get a quote for 3000 shares, have you had any luck buying today?
Hi - no I haven’t tried. I topped up a few weeks back to a full position. I have to say I am tempted to increase but trying to keep discipline on sizing!!
Interesting that you can’t buy even £10k worth in current market. I guess that suggests price is maybe being held back for some reason - block trade maybe?
Also got a buy order in at 300p, but getting quoted over 310p on £10k worth to buy now, which is way outside of the spread, crazy for a smallish trade.
I'm having a look at MPAC (LON:MPAC) this morning and it looks interesting now that margin has improved a lot. But that also happened during FY22 when H1 gross margin was 21.1% vs H2 of 30.2% so perhaps the H2 improvement for this year reflects a new problematic pattern in the first half rather than having turned the corner?? (although at least there is an upwards trend now)
Also , looking at the Equity Development broker note there is a *huge* difference in reported and adjusted EPS estimates. For FY23 it is expecting an adjusted EPS of 26p versus a basic EPS of 6.4p. Why is that? Is it because of the way they treat amortisation of intangibles?
And when you factor in the £3m pension costs all post tax statutory profit of £1.3m is wiped out for the year. Even next year the pension consumes 30% of estimated adjusted profit.
Hmm... I think I have talked myself out of this one but interested to hear views!
MPAC (LON:MPAC) no it was a normalisation of margins - so expect similar margins from H2 persisting across year in FY24
Pension is almost done. Next couple of years this will be off the balance sheet imo.
Thanks. On what basis will the pension be almost done? Is there anything you can point me towards? I can't see that in the broker notes I flicked through but admittedly I have only looked at most recent ones
Shore Cap do a full deep dive into the business and they estimate any payments will fall to £1m p/a in 2025 and beyond. Stated objective is to move the pension deficit to an alternative provider. Whilst the scheme is now heavily in surplus from an Accounting perspective it was in 2021 under an Actuarial deficit circa £25m I think. This should be materially lower at the next triennial (this year) given bond yields and LDI.
But nonetheless expectations are for another year at £2m and then max £1m p/a.
That's v helpful thank you!
would welcome thoughts on 1spatial as a few fund managers have recommended them in the shares magazine today
1Spatial (LON:SPA)
this company does look interesting - i quite like the consistent trend of improving numbers here. Looking at stocky it looks like its been a long hard slog but 2023 2024 and 2025 look transformational compared to what has gone beforea and its a nicely improving trend.
Lets have avery quick butchers at the balance sheet.
date 31/7/2023
For these type of companies i always start by looking at capiatlised intangibles - its easy to get away with capitalisng costs that are necessary to earn ones current crust. So imho if intangibles are growing period on period then that suggests current reality is not as good as profit and loss suggests.
at 31/1/2022 intangibles 17.7 mill
at 31/1/2023 intangibles 19.0 mill - up 1.3 mill
at 31/7/2023 intangibles 20.15 mill - up 1.1 mill 6 months
Ok houston we have a problem. Its clear that factoring in capitalised spend pretty much most of the profits that are being reported are going out the door on spend that is capitalised - so if we exepnsed all of this stuff company would probably be at breakeven.
Note intangibles at 31/1/2019 were only 10 million - this suggests that that the increase in capitliation may have peaked (sketchy logic) - so it could be the good trend is equally valid its just each year is possibly simialrly worse of if you were to expense capital spend.
Note the trend here can be your friend - if capitalisation trends to be less than amortisation it could be future profits might understate how profitible they are then.
so main questioon here is do teh coompany think they are trending to position where net capitalisation each year is nil - generally speaking , if they have acquisition or buy in intangibles then one should expect the trend may not be consistent.
average shares in issue - nice tick here not much chage since 2020 (i have used stocky which may not be right up to date)
receivables - i dont trust software company as far as i can throw them if receivables are increasing faster than sales. receivables strik me as being very high - 12.3 mill on 32 mill pa sales. But no increase compared to same tikme previous year (what about previous years?)
balance sheet overall test
receivables and cash £15.6 mill
liabilities exluding lease and pension = £16 mill
they can subsist just ! as long as customer pay what they owe.
The ultimate question here is is this company bout to turn into cash making machine if they can continue to grow profits organically and keep lid on capiatlising intangibles.
It certainly loks pretty promising - anyone have any thoughts on what the companies prospects are ref increasing sales and profits ?
Whilst not being quite where i would want them to be now everything seems to be trending in right direction here.
More good news on Boohoo (LON:BOO) (forgive the irony) but then the share price is so bombed out does it really matter anymore. That paragon of virtue, BBC Panorama, runs yet another negative storyline on this retailer. I wouldn’t be surprised if the owners take the business private to escape the public markets scrutiny. As to the truth of Panorama’s ‘investigation ‘ who knows!
BBC Panorama appears to have a vendetta against UK built businesses.
No mention of Shein or Temu who are considerably worse.
I know - I’ve got a good idea…..let’s hold UK companies to a standard far higher than the rest of the world, let’s beat the crap out of them if they are slightly off that standard (or if we just feel like it) and then let’s wonder why we aren’t competitive and get left behind. Our media penchant for “bashing” really gets my goat!!!!!!!
100% agree! BBC Panorama should have been scrapped a while back - it is little more than a BBC version of the worst tabloids. To be honest I think the BBC has a vendetta against anything business related. Perhaps they should stick to the 'spaghetti on trees' storylines! https://en.wikipedia.org/wiki/...
BBC news were laying into FTSE100 execs' pay being such a large multiple of their average workers' pay - but obviously no mention of them paying Lineker £1.5-£2m pa for commenting on football - oh the irony!
TBH I'm sick of the BBC - constant stream of rubbish which they present to us as newsworthy, yet they haven’t updated the 'War in Ukraine' coverage on their website for 5 days....
Same old stuff from the BBC. Yes, they should get their own house in order.
Linekar, he is only part time, does not even do all the Saturday Match of the Days now.
Lots of excessive pay and expenses in the BBC.
Morning all
Unremarkable update from Gresham Technologies (LON:GHT) with no mention made of their new software Floe system which is supposed to transform their fortunes. This could be a slow burn until they get another major bank on board. I was quite impressed with a recent management investor briefing which included a section from a senior anz member who was extolling floe’s virtues.
Golden Crosses - I know many people are wary of technical analysis and I hope this doesn't make me a pariah here on this forum but I ran an exercise last night on my 'buyable' stocks watchlist of circa 75 small caps to see what it would reveal and the results were compelling.
Golden crosses, for the uninitiated, where the 50 day moving average shoots through the 200 day moving average, is for me a useful chartist tool to confirm a change in the long term trend of the stock. It's a lagging indicator so you rarely catch the bottom with this tool but the momentum/follow through afterwards makes this a worthwhile exercise. I'm not wedded to technical analysis by any means but I think a few aspects of it can be very useful.
To cut to the chase, golden crosses signalled in the last few weeks/recent months on my watchlist:
Windward (LON:WNWD) McBride (LON:MCB) Spectra Systems (LON:SPSY) On Beach group (LON:OTB) Filtronic (LON:FTC) Gear4music (HOLDINGS) (LON:G4M) Trainline (LON:TRN) Renold (LON:RNO) Kinovo (LON:KINO)
All of the above stocks have gone on recently to make phenomenal gains and I'm kicking myself for not having undertaken this exercise 3 months ago, for example the signal to buy Mcbride at 25p, boy am i annoyed (kudos to yiannos1 who did tell us all)...
So that's the past what about now, well there are a couple of stocks approaching a golden cross but yet to be confirmed and may not yet make it, namely Oxford Metrics (LON:OMG) Luceco (LON:LUCE) Somero Enterprises (LON:SOM) Cavendish Financial (LON:CAV) ....ones to watch for sure.
But the ones who have just made golden crosses (and i've included the share price at the point of signal) are:
Eurocell (LON:ECEL) £1.30
MPAC (LON:MPAC) £2.90
GB (LON:GBG) £2.70
Sanderson Design (LON:SDG) £1.18
Fonix Mobile (LON:FNX) £2.24
Now I just want to stress, I would never use technical analysis in isolation (and I am by no means an expert), the fundamentals and narrative has to come first but the charts are a great way of seeking entry/exit points and confirmation you are onto something.
Please DYOR, it's not foolproof by any means, but the back testing really made me sit up and take notice so I just wanted to share this with you as I thought it was very interesting.
I thought Fonix Mobile (LON:FNX) was around 202p? It went up to 260p and then dropped back to around 220p. Cavendish Financial (LON:CAV) has doubled in price, in the last month or so. So it can be a bit late.
Good post, thanks for sharing. I think as investors it's important we use as many tools as possible from within our armoury to inform our buys and sells, especially those that give us an advantage over bigger funds - being able to nip into and out of a position quickly. This kind of technical analysis is an additional data point we can use to support our research and inform when to buy/sell. Charts are used by a good number of investors and fact alone implies they can impact market sentiment and buy/sell patterns.
Burnt Onions
Great post, I screen for Golden Crosses every week, one of the more reliable Technical Indicators, and as you say if they play out can be very profitable. Technical Analysis is seen by many as mumbo jumbo but it can be costly to ignore it.
This is Weinstein's famous Stage 2 indicator except (a) he used the 20DMA rising above the 150DMA and (b) he also looked for examples where the share had bumped along a bottom for a while (stage 1) and (c) he needed to see increased volume to accompany the move. In my experience it works best if a company shows signs of increased profitability and the movement in the share price is really a re-rating - in the best cases profits and the P/E both double and you get a four-bagger. Somero Enterprises (LON:SOM) (I hold) sadly isn't going to be one of those.
When Weinstein was trading he depended on almost indecipherable charts sent to him once a week on paper in the post so we have it easy really. Except it's never easy, is it?
Thanks for the post, Burnt Onions - very informative. I’m a dividend investor mainly so don’t use TA that often, but I think Golden Crosses are one of the more reliable indicators. Do you use Stocko for your screens? If so, can I ask what parameters you use? I’m not too hot on the screening side of things, but I’d be interested to set up something similar for future use.
Yes I just use Stockopedia, 200/50 day moving averages, ideally with volume confirmation. I input manually which is a bit cumbersome but it helps if the football is on in the background and last night it was.
This used to be on the old Stocko site, seems to have been lost in the move.
There were various chart indicators, that were quite useful.
"This used to be on the old Stocko site, seems to have been lost in the move.
"There were various chart indicators, that were quite useful."
- Ed Croft said they were very little used, but I tried to remember to review those charts displaying Technical Indicators such as Golden Crosses regularly, and I hoped to use them more to improve my lousy buy/sell market timing.
I certainly miss their absence in the updated version of Stockopedia, but they suffered from a lack of a prominent link on the homepage - out of sight, out of mind.
I should think many subscribers were even unaware that functionality had been available to them.
Quite some time ago there was an article written about Golden Crosses here on Stocko. I don't remember when exactly or who the author was, but the gist of the screen is 50dMA / 200dMA > 100%. It's easy to set up using the screen functions and add any other parameters you may wish (market cap, etc.)
Regards, Jon
But that picks up every stock with 50dMA above 200dMA, over 500. What we want are ones just crossing or just below. Limiting it to less than 101% helps but still 50.
I did find this: https://www.stockopedia.com/le...
Indeed Rusty2. Spglet posted a better version, which had I read before posting, would have saved us both some trouble!
Certainly limiting the results as you suggest is a good idea!
A cursory glance at the article you found, but it's not the one as I recall, which included some screens
Regards, Jon
I did try that but it selects 757 stocks, unless I'm doing it wrong.
Hi again Rusty2,
I think you're doing it right, I get the same results (can also be wrong of course!)
The OP was more related to stocks that were already on a watch list, that now indicated a golden cross. I've tried playing with rules, but cannot come up with something that provides what you are looking for, other than applying limits (98% to 101%), results in 162 stocks. Adding a rule for 10d/3m average volume can bring the results down, my idea being volume increases are also generally a favourable indicator.
Regards, Jon
Thanks. Yes I think volume is something to consider as well. One I've just seen that is close to golden cross and has a lot of recent volume is Greggs (LON:GRG), I don't hold at the moment.
One to watch Zotefoams (LON:ZTF) I hold.
Great post Burnt Onions - out of interest do you have an automatic screening tool for golden crosses that is reliable?
Hi David, You can create a Stockopedia screen that does that. (Not sure if you knew that already of course.)
Use the 50dMA/200dMA rule to list stocks greater than 90% and less than 110% (for example) and it'll list all the stocks within a range 10% below and 10% about the Golden Cross point. I've run it, and it shows ECE 104.14, FNX 104.19, GBG 100.25, SDG 100.56, and MPAC 100.90 as Burnt Onions says.
100 = the Golden Cross point on the chart. Much quicker than a manual approach of course, it shows up quite a lot of other opportunities.
Thanks Burn Onions - your post got me looking into ways of doing Golden Cross analysis using Stockopedia.
Super - thanks spglet. I did not know that but now I do I will have a look and run it. I like the 50 day MA to time trades particularly if it is close or crossing the 200 and looks a bit like a bowl with volume picking up.
Thanks Burnt Onions. Here's a list of golden crosses triggered in the last 3 days. (20m minimum m/c & excl. Loss Making companies)
That's very interesting, Wolf. Is that Sharepad? I have been wondering for a while whether to combine Sharepad with Stocko but am wary of information overload.
Burnt O. Excellent post! the previous version of Stocko. used to provide golden cross indicators and I miss them! I have no idea why they ceased ?
I note that in Knights group (LON:KGH) half year results until 31st October, today, they state that staff turnover has dropped from 11% a year ago to 6%. The company has worked hard to improve staff retention after a crazy post COVID period, but this level suggests, to me at least, that a lot of froth has gone from the jobs market, and so, hopefully, that interest rate cuts are not that far away.
Morning. Windward (LON:WNWD) this morning. FY numbers expected to be comfortably ahead of market forecasts. Rev increased 31% and LBITDA reduced to $5.1m from $12.1m and has $17.4m cash. Shipping systems with 98% recurring revenue with US government and just about to turn very cash generative. Dodgy start to life as a listed company but back on track now. I hold.
Windward
Had a really good look a few weeks ago after Lawrence Hulse talked very positively about them .
Looks good technology
But the northern pig garner in me wasn’t so keen of the brackets round the profit numbers .
Looks like there will indeed be lots of jam tomorrow and it is going to get there .
But my fear of jam tomorrow was just enough to override what looks a good prospect , certainly in a good sector and if my memory serves me correctly they will get a tail wind from the 2024 shipping issues as all companies will want to know where their goods are .
My morning smallcap tweet: SInk your teeth into the smallcap sandwich
Cellular Goods (LON:CBX) Dianomi (LON:DNM) Gresham Technologies (LON:GHT) SIMEC Atlantis Energy (LON:SAE) Myhealthchecked (LON:MHC) Cyanconnode Holdings (LON:CYAN) Ethernity Networks (LON:ENET) Windward (LON:WNWD) Robert Walters (LON:RWA) Mears (LON:MER) Abingdon Health (LON:ABDX) XP Power (LON:XPP), MPAC (LON:MPAC)
◄Cellular Goods (CBX)► pivot to becoming an AI recommendation agent for personalized skincare and beauty routines. Name will become Cel AI (CLAI). "The high end beauty buying experience is ripe for disruption and it is very clear that our prospects and customers want us to provide them with a full suite of product recommendations and beauty ideas." Is it? [SP=0.49 Cap=3m]
◄Dianomi (DNM)► guides FY-Dec rev c.£30.1m, broadly in line with market expectations. Adj EBITDA -£0.3-0.4m. Is that in line? [SP=43.11 Cap=14m]
◄Gresham Technologies (GHT)► guides FY-Dec rev £49m vs F/C £50.2m. Adj EBITDA at least in line with current market expectations of £11m. [SP=115.8 Cap=97m]
◄SIMEC Atlantis Energy (SAE)► Battery Energy Storage System at Uskmouth has been granted planning consent with conditions. [SP=1.42 Cap=10m]
◄MyHealthChecked (MHC)► guides FY-Dec rev £11m down 51%. Adj EBITDA breakeven (£2.3m). In line? [SP=13 Cap=7m]
◄CyanConnode (CYAN)► wins order for 1m Omnimesh Modules plus infrastructure, software, maintenance etc. No £££. The installation will be completed within 27 months and followed by a 93 month Support and Maintenance contract. [SP=10.22 Cap=31m]
◄Ethernity Networks (ENET)► reaches agreement to keep the wolf from the door. Creditors will be paid over 12 months. Needs court approval. [SP=1 Cap=4m]
◄Windward (WNWD)► guides FY-Dec comfortably ahead of market forecasts with rev c.$28.3m and adj EBITDA c. -$5.1m. F/C $26.6m and -$7m resp. Has begun 2024 with continued good momentum. [SP=90 Cap=77m]
◄Robert Walters (RWA)► guides FY-De net fee income down 10%. Pretax in line with market expectations of £20.5m. [SP=410 Cap=297m]
◄Mears (MER)► guides FY-Dec modestly ahead of market expectations with rev over £1,050m and adj pretax over £43m. F/C £1031m and £40.9m. Sees FY24 materially ahead of market expectations of £888m and adj pretax £33.9m. [SP=313.5 Cap=318m]
◄Abingdon Health (ABDX)► guides H1-Dec rev up 118% to £2.4m. Cash £1.9m. Outlook confident. [SP=12 Cap=15m]
◄XP Power (XPP)► Q4 rev of £81.2m was slightly ahead of expectations but only because it delayed relocation of facility in California bringing forward £5m of revenues. Cost cutting going to plan. [SP=1290 Cap=305m]
In line: MPAC
Polar Capital Holdings (LON:POLR) - "Forecasts up on jump in performance fees" - new research report here: https://www.equitydevelopment....
AUM grew £0.43bn or 2.2% over Q3 of FY24 (01 Oct 23 - 31 Dec 23) to £19.56bn and is now slightly above our previous £19.40bn forecast for the 31 Mar 24 FY-end. Investment performance was exceptionally strong in the quarter, contributing +£1.51bn or +7.9% of opening AUM. This was despite a currency headwind which would have depressed GBP AUM levels of USD holdings (GBP/USD +4% over Q3 from 1.22 to 1.27).
Performance fee profits (net of staff allocations) jumped from the previous marked-to-market £1.3m, to £9.6m. As most PF’s crystallise at the end of December, this increase is now secured and not merely a mark-to-market estimate. FY24 forecasts have been upgraded accordingly.
Our fundamental valuation rises to 600p per share (32% above the current share price) as a result of the increased FY24 forecasts, and a fall in 10Y-gilt-yields (the risk-free rate used in our DCF valuation). This gap between fundamental value and share price is supported by our view that both Polar’s PER (12.3) and that of the sector (13.1) have the potential for a re-rating.
It's certainly doing a hellalot better than Jupiter!
MPAC (LON:MPAC) - "Strong performance in line with expectations" - new research report here: https://www.equitydevelopment....
In a Trading Update for the year to 31 December 2023, Mpac Group reports that revenue and (adj.) profit before tax in H2 were substantially above the first half, whilst margins for the year returned towards normal levels. As a result the Group expects FY23 (adj.) PBT to be in line with market expectations and sees FY23 performance as providing a sound platform for continued growth in FY24.
Whilst Mpac’s shares have recovered somewhat over recent weeks, they still trade on a 32% discount to the market cap-weighted average of their peers and we maintain our Fair Value of 485p/ share, indicative of a FY24 EV/EBITDA multiple of 7.5x.
Marks and Spencer (LON:MKS) Large cap, but a sector specific important Christmas statement. Grows market share in food, highest sales growth of any grocer (according to Kantar). All important Womenswear category performed especially well within Clothing & Home which also grew market share (Kantar) with a higher % of sales at full price. New and refurbished stores driving operational growth. International lagged (bad planning?). Headwinds on staff costs and taxation. Opportunities in everything, (product, stores, online, efficiency). [I hold]
Boards of some AIM companies must be welcoming the advent of BTC ETFs - it makes their shares look investment grade by comparison!
Only in USA to start with I think. The predicted inflows into bitcoin holding ETF's if proven right are staggering. https://www.theguardian.com/te...
Paul, As to your comments on the RNS issued yesterday announcing the sale of @Tristel (LON:TSTL) shares by the CEO (Paul Swinney) and the CFO (Liz Dixon), are you aware of the fact that the two are married and so the sales are linked? There were two late trades yesterday, each for 90,000 shares, so it looks as if the shares were placed and that there may be another disposal to be announced.