Small Cap Value Report (Thu 11 May 2017) - LOOK, FLOW, SAL, PTCM, RBN, ASY, OTB

Good morning, it's Paul here.
Today I am reporting on the following;
Lookers (LON:LOOK) - another car dealership reporting a positive Q1 performance (boosted by changed in excise duty)
Spaceandpeople (LON:SAL) - shares have soared 45% on a positive trading update
Flowgroup (LON:FLOW) - yet another blue sky company that has dismally failed. Major fundraising announced at just 1.5p.
On The Beach (LON:OTB) - Interim results
Robinson (LON:RBN) - trading update
Andrews Sykes (LON:ASY) - final results
Porta Communications (LON:PTCM) - final results
OnTheBeach (LON:OTB) - interim results
So that's quite a lot of work for me to plough through. I'll be taking my time, so will be updating this article throughout the afternoon. So (as usual) please refresh this page later for more sections added.
Lookers (LON:LOOK)
Share price: 122.5p (up 0.4% today)
No. shares: 396.6m
Market cap: £485.8m
Q1 trading update - covering Jan-Mar 2017.
This is a chain of car dealerships.
These figures look stunningly good. However, as was pointed out yesterday in an RNS from another car dealer, Vertu Motors (LON:VTU) , changes in vehicle tax rates were implemented from 1 April 2017. This triggered advanced purchasing to beat the 1 April deadline.
For this reason, I think the Q1 figures from Lookers are largely meaningless.
On new cars the LFL growth in gross profit was +9%
What I'm scratching my head over though, is that used car gross profit was +17% in the quarter, also on an LFL basis. I don't see that there would be any benefit from accelerating purchases of used cars, so this is a bit of mystery as to why used sales were so strong, and on good margins by the looks of it.
Outlook - overall the company says it is trading in line with expectations for the whole of 2017.
My opinion - another car dealership which appears to be in rude health. We had a good discussion yesterday about the factors affecting this sector.
Lookers seems to be quite a bit more expensive than Vertu, on both a price to tangible book value basis, and a forward PER basis. Therefore I would say Vertu looks better value, out of these 2.
Flowgroup (LON:FLOW) - just a quick note here. I see the share is down nearly 40% today to just 1.89p.
This is due to an announcement stating that a major fundraising (over £20m) is to be done at 1.5p, with some convertible loans at 1.8p.
I've never rated this company - its main product seemed to be creating an uneconomic solution to a problem that doesn't exist. Then when that didn't work, they branched out into another area in the energy sector.
Why on earth would people pour more money into something that has dismally failed? Crazy.
Blue sky shares practically always fail. I cannot fathom why investors are drawn to blue sky "investing" (i.e. punting), when the failure rate is so extraordinarily high? Maybe it's just laziness - that people can't be bothered to analyse the numbers for proper companies, so instead just punt on a blue sky story?
Anyway, blue sky shares tend to seriously damage your wealth. My performance has dramatically improved since I developed the discipline to (most of the time) steer clear of blue sky stuff. Although the odd one does occasionally slip through into my portfolio unfortunately.
The other risk with blue sky stocks, is that you keep averaging down. This can turn a small initial loss into a huge eventual loss. I'm sure most of us have done that. Averaging down on good quality companies which happen to be in a bad patch can be very lucrative. However, averaging down on failing blue sky story stocks is usually disastrous.
That's another good reason to avoid blue sky stuff altogether. Even if your initial position size is small, the temptation is to get sucked into buying more as the price falls. Blue sky investing is a complete mug's game, in my view. Risk:reward is usually terrible, and these things are often priced to perfection too - even though they've often delivered nothing in commercial results.
Spaceandpeople (LON:SAL)
Share price: 37p (up 45% today)
No. shares: 19.5m
Market cap: £7.2m
Trading update - covering Jan-Apr 2017.
It's good to see this accident-prone minnow apparently turning the corner, after a whole series of problems in recent years.
These are the key points from today's announcement;
Revenue & profit ahead of management expectations.
Main drivers of this are a strong performance from its UK promotions business, and cost reductions.
Confidence that the strong start to 2017 will be maintained.
The company reiterates that its business is seasonally weighted to H2 every year.
The key retail contract in Germany has been successfully renegotiated, which will further improve profits. This is key, as without a renegotiation the German business would have been finished.
Very helpfully, the company provides guidance for this year (all companies should do this), of profit before tax of £1.1m, and EPS of 4.5p.
This translates into a PER of 8.2
Cash generation has been good - they expect to end the year with net cash of £1.25m - also good news, as this should remove investor fears about the balance sheet, which was starting to look a tad weak.
Divis - no mention is made of this, but I imagine the company might reintroduce a small divi (maybe 1p?) at the end of this year. It has proven keen to pay divis in the past, when trading well.
My opinion - I'm delighted that management seem to be getting the business back on track. I'd be even more delighted if I still held shares in it, but Sod's Law kicked in, and I ditched them pretty much at the all time low. Never mind, these things happen.
I'm not planning on revisiting this share, because it doesn't meet my tougher investing criteria these days. I'm looking for growth businesses that can really scale up. Whereas this one has pretty limited market opportunities. It's not likely to grow to say 5 times its current size, probably ever.
Furthermore, as we've seen in the past few years, its businesses are heavily reliant on a few key customers, and results are generally unpredictable. Therefore investors really can't sleep soundly, as you never know when the next profit warning might crop up.
Therefore, I feel the current valuation of about 8 times forecast earnings is probably about right, providing the company meets those revised numbers.
On a personal level, I got to know management here quite well in the last few years, and I know how hard they've tried to get the business back on track. So it's really pleasing to see their efforts come together with a better performance.
i doubt there is much sustainable upside on this share for now, after today's 45% rise. The reason being that there must be so many stale bulls in the stock. The problem with that, is that share price rises tend to be snuffed out by relieved holders who've been waiting for a more favourable exit price.
Porta Communications (LON:PTCM)
Just a brief comment, as I consider this share uninvestable.
The main reason is its car crash balance sheet. The capital structure is all wrong, with Bob Morton's expensive loans propping up what would otherwise be an insolvent group.
The P&L looks awful too. The adjusted EBITDA numbers are meaningless here, as we've seen before how aggressive the accounting is. Every year there are loads of restructuring costs, and other items which are massaged out of the way. The reality is that this company doesn't really make any money. Anything it does make would be needed to repay the expensive loans.
Overall then, I think the existing shares are worth nothing as things stand now. At some point the group has to do a financial restructuring. It's a safe bet to assume that Bob Morton will come out on top. So why put your money lower down the financial hierarchy than this known sharp operator?
I think the Board departures here were positive. Maybe new management will be better? Their main priority is to sort out the horrendous balance sheet, and the whole capital structure.
On the upside, current trading sounds good. If management is able to convince a different lender to finance the repayment of Mr Morton's loans, then there could be light at the end of the tunnel. Do I want to punt on that happening? No.
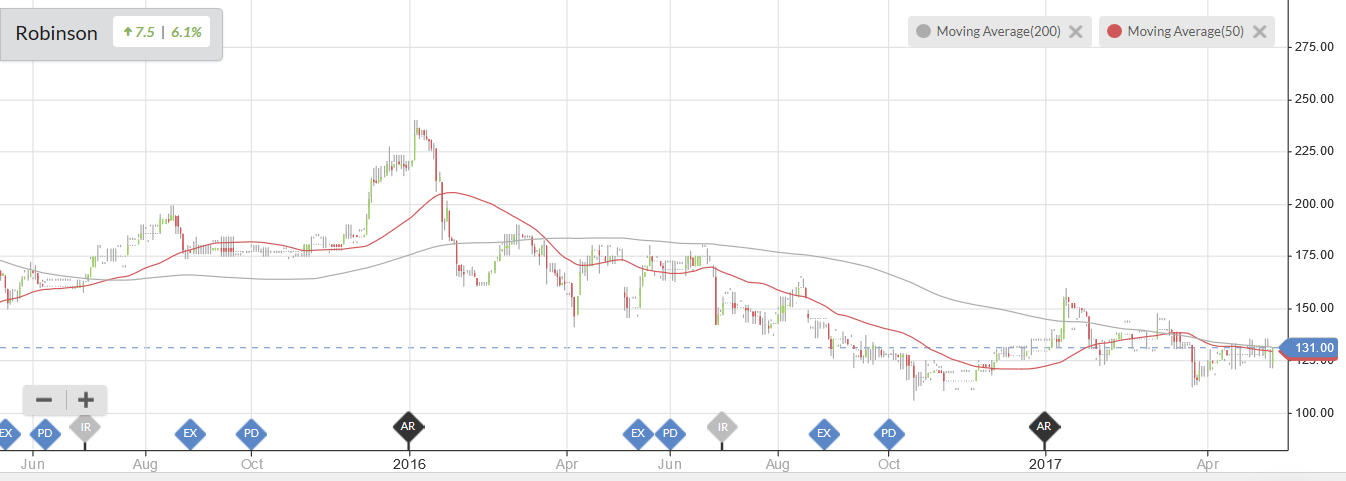
Robinson (LON:RBN)
Share price: 131p
No. shares: 16.6m
Market cap: £21.7m
AGM trading statement - this company describes itself as "the custom manufacturer of plastic and paperboard packaging based in Chesterfield".
It has a 31 Dec year end, so this update is for Jan-Mar 2017, as follows;
"In the first quarter of 2017, revenues were at the
same level as the previous year.
New business gains continue to come on
stream slower than expected but the projects remain in the pipeline and
will benefit the second half."
I'm quite quite suprised that the shares didn't sell off on this news, which is hardly inspiring.
Stockopedia shows the broker consensus forecast being a 10.9% increase in revenues for 2017 as a whole. Therefore if no increase has been achieved in Q1, that leaves a steeper hill to climb in Q2-4.
Slower than expected new business gains hardly gives confidence either. Although the comment about H2 benefiting from new business wins is the only positive comment in the above paragraph.
Property - there is value in this share from the development potential of surplus land owned by the company. On this matter, the latest update is as follows;
"Following the outline residential and retail planning
permission granted in January 2017, work continues in preparation for
development of the sites, and we look forward to updating shareholders
in due course."
My opinion - this share doesn't interest me. The sector it operates in, is so competitive, that I think customers will be putting constant pressure on suppliers like Robinson to cut prices & margins. So I see Robinson as having little pricing power, hence margins are not likely to grow.
Also there has been little, if any organic revenue growth in recent years. The growth has come from an acquisition of a Polish packaging company.
So the only real point of potential upside seems to be on the property side of things. Potential investors would need to do detailed homework on this, to find out the value of the land, and what (after tax) the company intends doing with the proceeds.
Dividends look quite good though - the forecast yield being about 4.6%. So for people who don't want to take too much risk, then the upside from property disposals, and decent divis in the meantime, might have some attraction.
Note also that this share is extremely illiquid, so it could be difficult to exit a position, once you've bought. There's also the dreaded bid/offer spread to contend with, as with most illiquid shares.
Overall, I feel the market is looking for growth companies at the moment, and things like Robinson are on the sidelines, with little investor interest in them. So there's only really any upside if the value of the property turns out to be more than expected. It doesn't interest me, because there's an opportunity cost to parking money in shares that flatline, when so many other things are roaring upwards.
Andrews Sykes (LON:ASY)
Share price: 505p
No. shares: 42.3m
Market cap: £213.6m
Final results - for the 12 months to 31 Dec 2016 - so another company with extremely slow reporting - it's really not good enough, leaving shareholders in the dark for such a long period after the year end. There hasn't even been a trading update. So the majority shareholder knows how the company is performing, but outside shareholders are left completely in the dark for 4 and a half months from the year end date.
The company's activities are hiring, and selling temporary air conditioning/heating & water pumps. So its business is highly weather-dependent - i.e. the business does better in extreme weather conditions.
The figures for 2016 look excellent.
Basic EPS rose from 25.55p to 34.25p, although that includes some forex-related gains.
PER is 14.7, which looks good value to me, for a high quality niche business.
Net cash was £17.7m
Balance sheet overall is excellent. You don't often come across an equipment hire company with net cash.
Dividends are generous, albeit flat on last year at 23.8p. That's a yield of 4.7%. Note also that the company has surprised & delighted shareholders with special divis in the past. With the cash piling up again, I'd say there's a fair chance the same might happen again in the not-too-distant future.
Cashflow is (as always) excellent. This business is a terrific cash generator - it seems to occupy a lucrative niche.
My opinion - regulars here will know that this is one of my favourite shares. I really regret selling out, and am pondering whether to buy back in? It's horribly illiquid though, as the vast majority of shares are held by one shareholder. So some people may not like the capital structure, and the uncertainty this brings about what might happen to the company in future.
It's a fantastic business though, as evidenced by another set of excellent numbers. Well worth a look, if you can live with the unconventional capital structure, and the uncertainty that its weather-related activities bring. It might be a share to keep on my watch list, and buy on any plunge from disappointing results in a year where the weather misbehaves?
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

26 comments
Thanks for the additional coverage Paul.
On Andrews Sykes (LON:ASY), I've been a happy holder since September. It's incredible how economical they are with their updates - just 3 RNSs released in the whole of 2016 and 18 in total since the beginning of 2013. Some companies release that many in a quarter!
My reading of the finals was that their dependence on extreme weather is reducing:
In every year's finals going back to 2010 they've mentioned they were developing or expanding their non-weather dependent markets, but whereas previous reports have mentioned performance being adversely affected by 'temperate weather', the fact that they are now reporting improved performance despite the lack of extreme weather maybe indicates their efforts at diversifying are finally bearing fruit.
The free float is less than 10% so it is a ridiculously illiquid share. I wouldn't necessarily see that as a bad thing though as I have no intention of selling.
1. Titon: I too wish that I'd taken a position in Titon Holdings (LON:TON) when it came up on a screen of mine. Hindsight and all that... FREng how did you know/find out that this is a Lord Lee favourite?
2. ProPhotonix (LON:PPIX): I was put off by the balance sheet - specifically the huge accumulated deficit. I assume that this is similar to the situation at Porta Communications (LON:PTCM) which Paul explains above, although I couldn't find any details in the accounts/report.
I wish I'd trained as an accountant - it would make reading these reports and accounts so much easier!
He has done several interviews in the last few years, also his holdings are declared on his House of Lords profile. I did have them all set up on a folio but have not kept up to date recently, his largest holding is in Treatt (LON:TET), around 40%. Actually I can't see him holding Titon Holdings (LON:TON).
I'm looking forward to your views on the Andrew Sykes Andrews Sykes (LON:ASY) results. Many thanks for all that you do Paul.
My average down nightmare was Polo resources. Every time there was a positive comment in IC I bought some more of the losers. Finally gave them the boot last year. I saw Flow today and threw them out too, luckily I only had a small holding.
Hi Paul,
I suppose the logic behind "blue sky" investing is they nearly always fail, but if 80% fail and 20% are 20 baggers, then, the investor is ahead. Without needing a 50% success rate.
However, in practice, as you imply, the odds are much much worse than 80:20. Maybe some people over estimate their ability to pick the winning blue sky stocks.
I also stay clear of them.
JJ - the biggest challenge is not picking the 20 baggers. Sooner or later you'll invest in one.
The much bigger challenge is still being in when it's gone up 20 fold.
only 6 months into trading, but sirus -sxx could be my story to look back on and learn from.. haha
I assume you mean Sirius. Would be interested to know what you expect to learn.
Pity that Andrews Sykes (LON:ASY) hasn't been covered yet. IMO the results look really good and the company looks solid. Buying the shares is another story. Around 86% of the equity is held by the Sykes trust and the sp spread is on the high side. Generally a little illiquid, so may not be to everyone's taste.
Paul - any chance of comment re On the Beach Interims please?
Impax Asset Management (LON:IPX) my best performing current holding reported for the half year today.
I confess to not being a fan of asset managers although the only other one I have ever owned Ameriprise Financial NYSE:AMP (funds include Columbia and Threadneedle) has performed okay. When I came upon Impax in November, valued at the time at £60M, I was dubious but when I spotted that they appear to be the only (as far as I know) manager who operates 100% on the theme of sustainability I got interested.
Subject to the usual caveat with this industry that when the market drops they bomb out because of the double whammy of their assets dropping in value and clients going to cash, then I consider Impax a no brainer-
A current and future big theme- Sustainability
Executives/employees own circa 34% and get paid nearly all their bonuses in shares but without dilution as they go into the market to buy the requisite number of shares to fund the bonus. This in fact underwrites the share price.
The second biggest shareholder, with about 25%, Banc BNP Parisbas, is their largest client. I don't think this is a financial investment by BNP but a strategic one, to stop any competitor buying the company.
Most managers are struggling to grow AUM due to the huge growth in ETFs but in 2016 Impax's AUM went from £2.5bn to £4.7bn and in the first two quarters of 17 to £5.7bn and as of today ( week 6 of Q3) £6bn. This is gobsmacking growth for this sector and of course as full income on new AUM only shows in the figures after 12 months, further growth in profits are nailed on.
All this growth required taking on four new staff last year and one so far this year.
Half year headlines from todays RNS-
· Revenue in first half of 2017 was £13.9 million (H1, 2016: £9.4 million)
Operating earnings2 were £3.2 million (H1, 2016: £1.6 million)
Profit before tax was £2.4 million (H1, 2016: £2.1 million)
Diluted earnings per share were 2.11 pence (H1, 2016: 1.35 pence)
Interim dividend increased by 40% to 0.7 pence per share
The share price has moved up 80% during the last 6 months but I believe the runway for this company is very long. Their fixed cost base moves up very little relative to the AUM growth, sure the Execs/Employees get a big share out of the profits but I am not complaining.
Dave
You make a convincing case Dave, Impax Asset Management (LON:IPX) certainly seem like a company that warrant further research. Given Asset Management is one of Graham's specialisms, I'd be very interested to hear his views......
There was a useful results presentation today
https://www.impaxam.com/sites/default/files/H1%202017%20investor%20presentation%20FINAL_0.pdf
I hold a lot of these as I think they're in a virtuous circle sweetspot at the moment
Ben,
I exchanged mail with Graham last night and hopefully he will be commenting on Impax today.
Dave
Excellent, thanks Dave
Yes Titon looks interesting. Any thoughts Paul?
Sorry to put my two pence worth in but Titon Holdings (LON:TON) put out a great update imo. Net Revenue up 29%, Profit before Tax up 61%, EPS up 34%. Chart is a breakout on high volume. Looks like a winner to me.
Hi Paul, re your query about Lookers seconhand sales doing so well. I would think all the new second hand stock has been traded in by customers who are more focused on the purchase of a brand new car. They are easy meat for a salesman who will do them a favour and take the old car as part of the deal but at a price which gives a good margin when polished up on the forecourt to attract the secondhand buyer. Often a car with a known history needing next to no preparation. Private sales are getting more difficult, with owners not having the time, the space or the expertise and the risk of being done over whether selling or buying.
On a different note Jarvis Securities (LON:JIM) have a very good trading update. Graham likes them, maybe he can give them a look soon.
Titon Holdings (LON:TON) (a Lord Lee favourite in which I hold a tiny scrap but forgot to buy more) has put out a popular update today.
Hi Paul,
Very keen to see your take on Porta Communications (LON:PTCM), as I know you used to be keen on that company a long time ago. Things have changed since then, and Porta Communications (LON:PTCM) is now clearly an example of what to avoid on AIM. I am really angry at the way Bob Morton and David Wright behaved, always hiding the truth in semi-lies, taking lots for themselves and leaving the company in such a poor state without an apology (and actually "with great pride" of having disappeared millionsm says David Wright!!!).
Actually I have not dug in the detail but I fear that Bob Morton keeps suckign money from the company through the high-interest loan to Hawk...
Thanks for the great work anyway!
Thomas
Hi Thomas,
I've just published a section on Porta Communications (LON:PTCM) .
I very much agree with you. David Wright was hopeless, and it's positive that he's gone.
Bob Morton has also cast a cloud over things, both with his shattered reputation, and the exorbitant loans he has lent to PTCM.
It's a pity, because there are some good people within the individual companies, and with a better capital structure the business could perhaps make progress. Although I tend to avoid people businesses, as the staff demand the upside in the good times, with higher salaries & bonuses. Plus the best people often just leave to set up their own firms, taking clients with them. So not a good sector for investors, usually. Also very cyclical of course, so sooner or later earnings collapse.
Regards, Paul.
thanks! Great insights from you, as always! Agree it is completely uninivestable at this stage!
Hi Paul,
Out of interest what was your worst average down mine was Northern Petroleum in the days before I knew better. Avoid all small oil/mining companies these days and most blue sky allow myself a small gamble with 5% of the pot.
I'm also having far more joy buying stuff with high stock ranks rather than another rookie habit which normally goes wrong of bottom fishing (although to fair generally in the horror stories of my earlier days),
Think my 8k in Nop over 4 average downs is now worth £300 ish.
Lets here some stories folks there's (expensive) lessons to be learned here.
Regards
Andy
re Flowgroup (LON:FLOW) an excellent Mea Culpa and lessons learned from staverly here:
http://www.stockopedia.com/content/flowgroup-painful-after-thoughts-86609/
i fully agree with your comments about blue sky companies. I have had several similar experiences. Do not go there! If the story comes good buy later.
Lennart