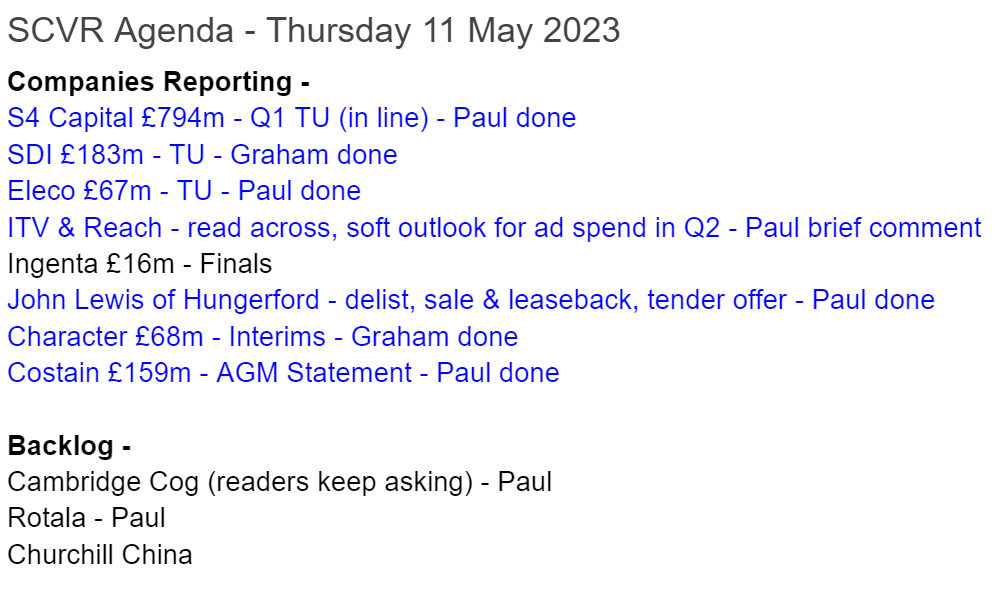
Small Cap Value Report (Thu 11 May 2023) - ELCO, SDI, SFOR, CCT, JLH, RCH, ITV, COST

Good morning from Paul & Graham!
Today's report is now finished at 13:16.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Summaries of main sections
(more detail below)
Eleco (LON:ELCO) - 80.5p (£67m) - Q1 Trading Update - Paul - AMBER
An in line with expectations Q1 update. SaaS model means good visibility. Although I question why it's on a high PER above 20, given no profit growth in the last 5 years?
SDI (LON:SDI) - down 21% to 138p (£144m) - TU (profit warning) - Graham - AMBER
Difficult news for SDI shareholders as it turns out that the company must eliminate all PCR revenues from FY 2024 forecasts. FY 2024 now estimated at 7.3p. Valuation may be fair.
S4 Capital (LON:SFOR) - down 1% to 138p (£790m) - Q1 Trading Update - Paul - RED
Sir Martin Sorrell's acquisitive digital marketing group. There's nothing wrong in this update per se, it's trading in line, and is "cautiously optimistic" for the rest of 2023. However, on rummaging through the 2022 accounts, I see a horrible geared balance sheet, and gigantic adjustments necessary to move statutory losses into profit. Not for me, but only the brave would bet against Sir Martin, given his track record!
Character (LON:CCT) - down 4% to 338p (£65m) - Interims - Graham - GREEN
Terrible H1 figures but the company and its broker insist that full-year PBT can still be achieved. Another major profit warning can’t be ruled out but the value on offer is tempting.
Quick comments -
Reach (LON:RCH)
Down 8% to 78p today. There’s no company-specific news I can see today, but wonder if this is sentiment read-across from a Q1 update from ITV. EDIT - many thanks to TheFly who has pointed out in the comments below that RCH went ex-divi today for a chunky 4.46p dividend. Sorry, I should have checked divis too, not just the newswire!
ITV (LON:ITV)
Down 4% to 74p (£3bn). ITV said ad revenues were down 10% in Q1, but expected to worsen a little to -12% in Q2. So no signs of any recovery in ad spending as yet, on traditional media anyway. At some point ITV shares could look interesting for a recovery maybe? It's also investing heavily in digital revenue growth. The StockReport shows attractive value metrics - possibly a share to investigate further? I’ve just quickly looked at ITV’s 2022 results, and it reminds me why I prefer focusing on the simplicity of small caps - it’s a large & complicated business! Note its pension scheme will suck out £62m, £67m, and £47m cash in 2023, 2024 & 2025, despite being in an accounting surplus.
Costain (LON:COST)
Up 1% to 58p (£160m) - AGM Update - Paul - AMBER
A brief trading update today says it’s in line with expectations. This share has done well in the last year. My notes here from 20 July 2022 are still very relevant, running through the bull & bear points. My conclusion then at 38p was that the share was cheap for various reasons (pension cash outflows absorbed half profit, very low margins), but that it was worth researching further, because it had arguably got too cheap. Is it still cheap now at 58p, after a good recent run? Not as much, but note broker forecasts have been rising in recent months. So if you do invest in low margin contracting businesses, this one is probably one of the better ones in my view.
John Lewis of Hungerford (LON:JLH)
Down 9% to 1.35p
Market cap £3m
Delisting, sale & leaseback of property
A very sensible announcement, explaining why this £3m mkt cap tiddler thinks the costs (£250k) of keeping its listing are not worth it. I completely agree, and never understood why this small upmarket kitchen seller was listed in the first place!
Also, it's doing a sale & leaseback on a £3m property, and paying down an expensive £1m loan, an interest saving which will largely offset the new rent payable. That also makes complete sense to me.
A tender offer for up to 10% of the company's shares will be made available, and an intention to do more in future, once it's a private company. In my opinion this all makes total sense, and looks a fair way to exit the market. Note that shares have recovered from recent lows, so the exit price c.1.5p is OK I think. Also there will be a matched bargain facility set up for shares in the private company to be bought or sold. We need to see more tiny companies leave the public market, there is no sense in keeping shares like this on a public market. Shareholders here should be thanking the Directors for handling this in an orderly way, confirmed with only a 9% drop in share price today, whereas a delisting announcement usually causes a 50% instant negative market reaction, as people rush for the exit.
Paul's Section:
Eleco (LON:ELCO)
80.5p
Market cap £67m
Eleco Plc (AIM: ELCO), the AIM-listed construction software specialist…
At its AGM, ELCO updates us on Q1 (Jan-Mar 2023) performance -
"I am pleased with Eleco's trading performance for the first three months of the financial year.
"Eleco continues to deliver on its organic growth strategy, with solid progress in its transition to SaaS, a robust balance sheet, and increasing recurring revenues. Eleco remains well-positioned for the future and the Board is confident that the Group will deliver in line with market expectations for the full year".
ELCO is one of many software companies that have been transitioning to a SaaS model (i.e. regular monthly fees, instead of big, unpredictable, up-front licence fees). This brings the benefit of much more reliable cashflows, hence lower risk of profit warnings for investors. However, it suppresses short term profitability, and often makes companies superficially look ex-growth, whereas the story is that they’re building a longer-term, more reliable income stream, and hence foregoing up-front licence fees & profit.
We can see that in the historical graphs below - not much growth in the last 4 years, but if it meets forecast profitability (the lighter blobs for 2023 & 2024), then an improving trend would be established.
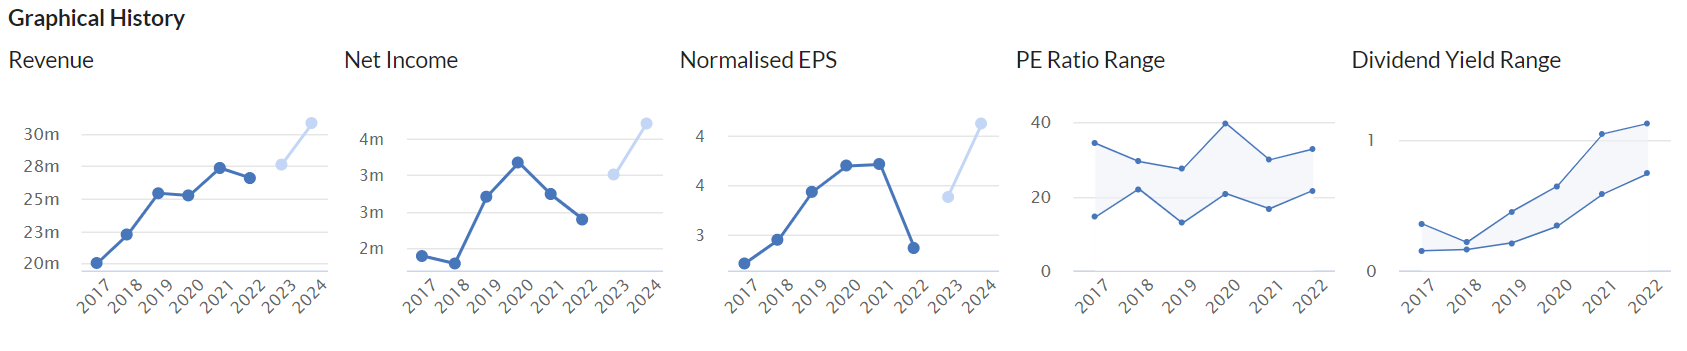
Reporting in line with expectations today is a help, although that would only result in 3.6p adj EPS for FY 12/2023, well below 2020 and 2021. Hence at this stage, Eleco doesn’t really look like a growth company. Which makes me question why it’s priced like a growth company, on a PER of 80.5p share / 3.6p EPS = PER 22.4x ?
Dividends are negligible, with the yield only 1.0%, so there’s an opportunity cost here - you can get 1% pa from ELCO shares, or 4-5% pa just by holding cash on deposit. Equities have a lot more competition now interest rates are more historically normal. So you’re effectively losing money if you hold low (or nil) yielding shares, if there’s no share price appreciation - which might be a tall order when the share price valuation is already at the top end.
Paul’s opinion - ELCO seems a nice company, operating profitably in a software niche. It has a cash pile, although this is from up-front customer payments, as is usual with software companies. The balance sheet overall looks OK, and should benefit from the reduction in liabilities of a German subsidiary which has been recently disposed of.
If you think that ELCO’s prospects are excellent, then it might be worth paying up. Remember we're only reviewing the numbers, and current forecasts here, we don't have a crystal ball to reliably predict the future! Forecast for FY 12/2024 looks more interesting, with growth accelerating, but even then profits would still be below 2020 & 2021 actuals.
Hence on valuation grounds (it’s too expensive), I can’t push myself beyond AMBER.
It needs to start beating, not just meeting, broker forecasts to drive the share price sustainably higher on fundamentals, in my view.
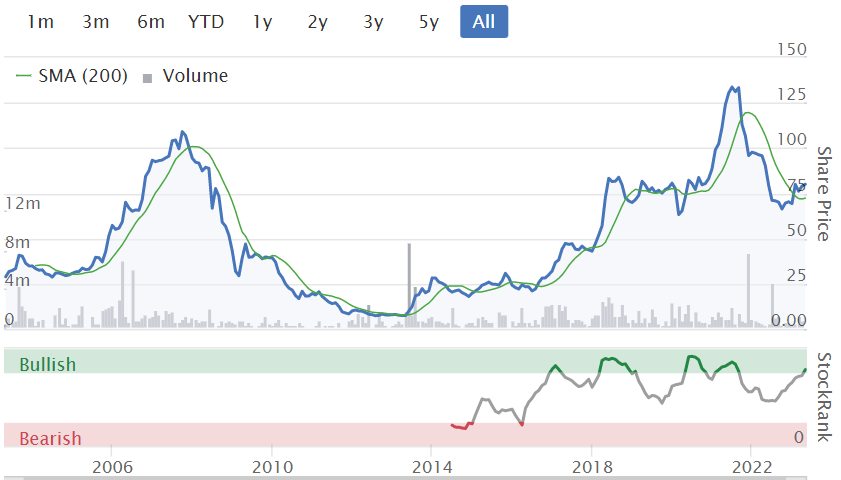
Long-term, it's been a rollercoaster for shareholders - with the share price currently where it was 5 years ago -
S4 Capital (LON:SFOR)
Down 1% to 138p
Market cap £790m
This is the rapidly growing (by acquisition) digital marketing group, set up by Sir Martin Sorrell, who of course achieved notoriety from building up WPP from nothing, into a major business. I see from previous RNSs that he has been unwell, so I hope he’s now on the mend.
No great shakes in today’s Q1 (Jan-Mar 2023) update, key points I noted down -
Net revenue Q1 £219m up 28% (but organic is +6.8%, the rest from acquisitions)
“Solid start; guidance reiterated”
Note that this is mainly a US business, with 79% of revenues coming from N.America.
“Cautious optimism” for the rest of 2023, there’s more detail in the announcement.
Share buybacks are stated as being to offset dilution from share options, so this is clearly just management remuneration, hence should not be adjusted out (which it is) in my view.
Seasonality - expecting “significant” H2 weighting.
FY 12/2022 accounts - we didn’t cover these here at the time, so I’ve just had a quick look, and have to say I don’t like the numbers at all. Specifically -
Adj operating profit of £114m turns into a loss before tax of £(160)m! Absolutely massive adjustments, mainly relating to acquisitions/restructuring, amortisation of goodwill, and share options, in that size order (largest first). Adjustments on this scale render the numbers practically useless, in my view. Is it profitable or heavily loss-making? Both, depending on which number you focus on!
Balance sheet - the company says it’s strong, which it’s very definitely not! There’s a gigantic, and rapidly growing £1,165m in intangibles (mostly goodwill), and NAV is only £850m. Therefore NTAV is heavily negative, at £(315)m. That makes it uninvestable for me.
There’s too much debt, and also the contingent consideration creditor is very large too, which could either mean a big cash outflow, or dilution if paid in shares.
Paul’s opinion - negative, I wouldn’t touch this. The figures look horrible, with a very weak, geared balance sheet, and profits that only appear after making huge adjustments.
However, there are always 2 sides to any investment story, so for balance, the bull points might be -
Reputation & track record of Sir Martin - so anyone betting against him would have historically failed!
Stockopedia shows the forward PER as 10.1, which could turn out to be cheap, if/when a cyclical upturn in advertising takes hold, and assuming the market is happy with the large adjustments to arrive at profits.
As always, your money, your choice, but SFOR is definitely not for me.
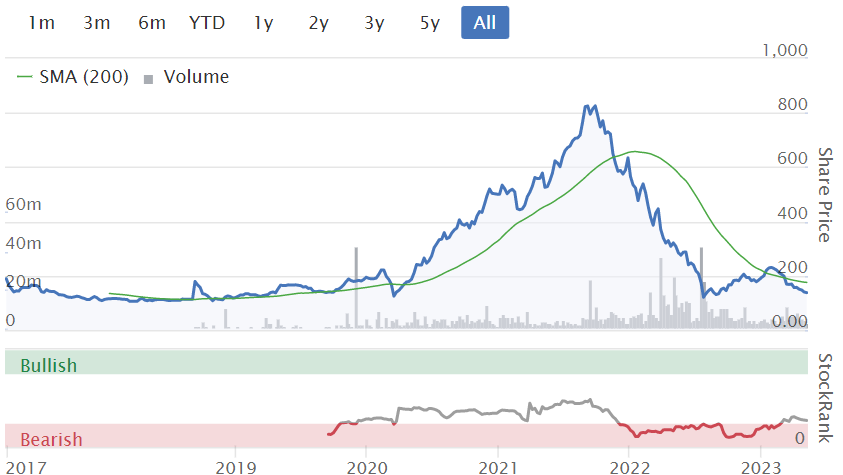
Look at how the hype got wildly out of hand during the pandemic. Could such a rollercoaster ride happen again I wonder?
Stockopedia remains unimpressed too, note that the StockRank has never achieved a high level, even when the shares had crazy momentum during the boom years.
Graham’s Section:
SDI (LON:SDI)
Share price: 138p (-21%)
Market cap: £144m
Some difficult news for SDI shareholders this morning as forecasts for FY April 2024 suffer a 21% broker downgrade.
Let’s review the RNS first.
FY April 2023: these results are in line, with revenues of £69m (up from £49.7m thanks to acquisitions) and adjusted PBT “in the region of £11.8m” (last year: £11.8m).
FY April 2024 outlook
Macro conditions remain difficult, according to the company, with “some” easing of supply chain issues in H2.
And now for the bad news. SDI does not expect any more PCR-related sales to a large customer who bought £8.5m of cameras from Atik in FY 2023.
This PCR risk was something I flagged in December but it wasn’t difficult to do as the company was very transparent about it. The company was clear that they had “no visibility” around future orders from this customer, and that Covid-related orders had caused “revenue and profit fluctuations which have not fully settled yet”.
Unfortunately, despite having no visibility around future PCR orders, SDI did assume that they would generate more PCR sales in FY 2024. As of this morning, all revenues in this category have been removed from forecasts.
Despite the loss of £8.5m of revenues compared to FY 2023, they remain optimistic for the new year:
The Group's federated structure and our hard-working staff continue to allow us to respond to these various challenges and we forecast a good year of organic growth when excluding this previous one-off business. FY24 revenues are expected to be ahead of FY23. We continue to invest in our existing businesses and in acquiring complementary businesses and we expect to continue our buy and build strategy in FY24.
I guess we will see “adjusted organic growth” in the full-year results, which will be something much higher than actual organic growth.
New estimates: for FY 2024, the company’s broker has left their revenue forecast almost unchanged at £71m. Atik’s high-margin revenues are reduced, but low-margin revenues at SDI’s newly-acquired businesses (e.g. LTE Scientific) are thought to be stronger than expected. This isn’t mentioned in the RNS but I guess that the company must have communicated it.
With lower profit margins due to the new business mix, the FY 2024 PBT forecast is reduced by 17% to £9.8m. The EPS forecast is reduced by 21% to 7.3p. In addition to lower gross profits and higher operating expenses, the company is also suffering from a higher interest charge.
Graham’s view
I can’t fault SDI for pretending that its PCR sales at Atik were a sustainable or long-term revenue stream. They did not do that; in fact they were very clear that this was not the case. So I have no issues whatsoever with management for this morning’s news from the point of view of their integrity.
If we were being really harsh, we could fault them for including PCR sales in FY 2024 forecasts, when there was no visibility around future orders. But then I don’t think that companies are obliged to choose the worst possible outcome when drawing up their estimates, only the outcome that they genuinely think is most likely.
No, the main issue here for me remains the one I’ve mentioned before: the lacklustre organic growth.
The H1 results disclosed organic growth of just 3.8%, which is below the level that I think good companies should be able to achieve in these inflationary conditions. Judges has been doing significantly better than that.
With the disappearance of PCR sales, the company is now going to have to report organic growth “excluding PCR”, in addition to what we might call “statutory organic growth”!
The buy-and-build model pursued by SDI (LON:SDI) , Judges Scientific (LON:JDG) and Halma (LON:HLMA) is great when it works but I don’t think that growth by acquisition is enough. I think that it’s vital to see real, quality underlying growth at subsidiaries.
With this morning’s 20% fall, the shares are now trading at 19x FY 2024 EPS. I suppose that’s a fair response to a 21% EPS downgrade.
I’m happy to take a neutral view on the stock here, because I still view SDI as a better business than the average one that we cover in this report, and at a sub-20x P/E multiple I think it is worth keeping an eye on.
Character (LON:CCT)
Share price: 338p (-4%)
Market cap: £65m
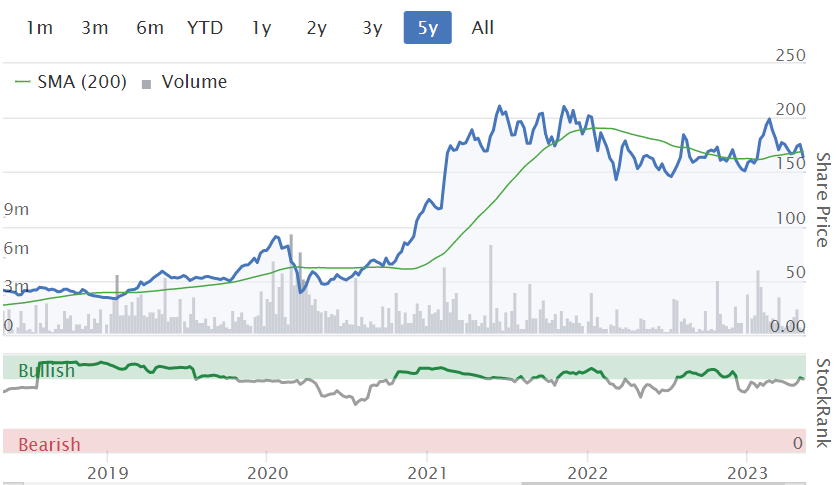
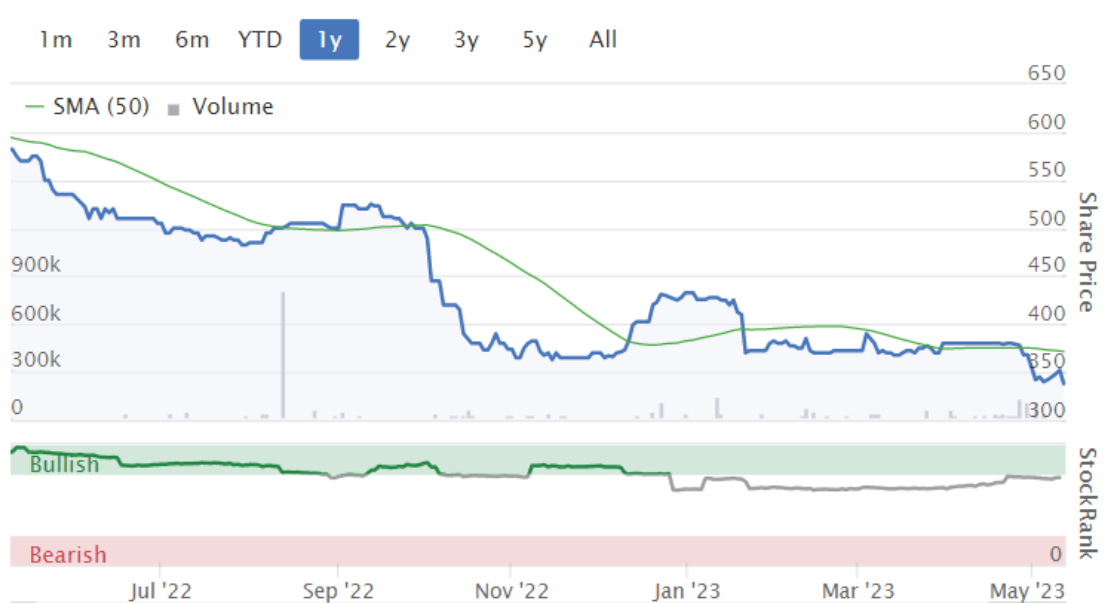
The last time we looked at this one was in October 2022, when it issued a profit warning. The shares have remained weak since then:
The fragility of Sterling (in contrast to the US dollar) has been a problem, as Character buys its goods from Chinese sub-contractors who only want to get paid in dollars.
Character is also highly exposed to the cost-of-living crisis as the toy budgets of families have been squeezed.
Today we have interim results for the period to February 2023. They are terrible, as anticipated:
Revenues down 36% to £57.9m (H1 last year: £90.9m)
PBT £0.2m (H1 last year: £6.5m)
Cash £10.7m (H1 last year: £21.5m)
Despite this weakness, the full-year PBT estimate is unchanged.
Dividend: Character declares an 8p dividend (H1 last year: 7p), even though it doesn’t have the current earnings to pay for it!
That will cost £1.5m, according to my sums. It “reflects the Board's confidence in the Group's prospects for a second half recovery and performance beyond the current financial year.”
Buybacks: Character’s share count has reduced over the years, but it’s not currently doing any buybacks. The company “will consider further buyback initiatives in the future, including by way of a tender offer”. We should definitely watch out for this, as we might then have the perfect situation with an undervalued company buying back its own shares!
Outlook
The company still expects to make an “underlying” PBT of around £5m in the current financial year (FY August 2032). More on this in a moment.
Whilst the conditions remain challenging, the Board has a strong belief in the current product line up. The success of Heroes of Goo Jit Zu continues and is supported by other lines, including the influencer inspired Lanky Box and Aphmau products which are also featuring well in our sales numbers. In addition, the scheduled release of the new "Turtles" movie in August 2023 bodes well for the launch this summer of the Teenage Mutant Ninja Turtles line of products that we are distributing in the UK and Ireland.
Estimates: the broker says that H1 should be the “nadir” for Character financially, and that H2 should see revenue bounce by 33% (vs. H1) with £4.5m of PBT in the second half. However, they also acknowledge that macro/geopolitical issues make forecasting difficult!
They cut the full-year revenue estimate from £135m to £128m but they also see operating costs reducing, and leave the full-year PBT estimate unchanged at £5m.
My view
I’ve felt priced out of this share ever since it rocketed up to £5 in 2015. Here’s the long-term chart as a reminder:
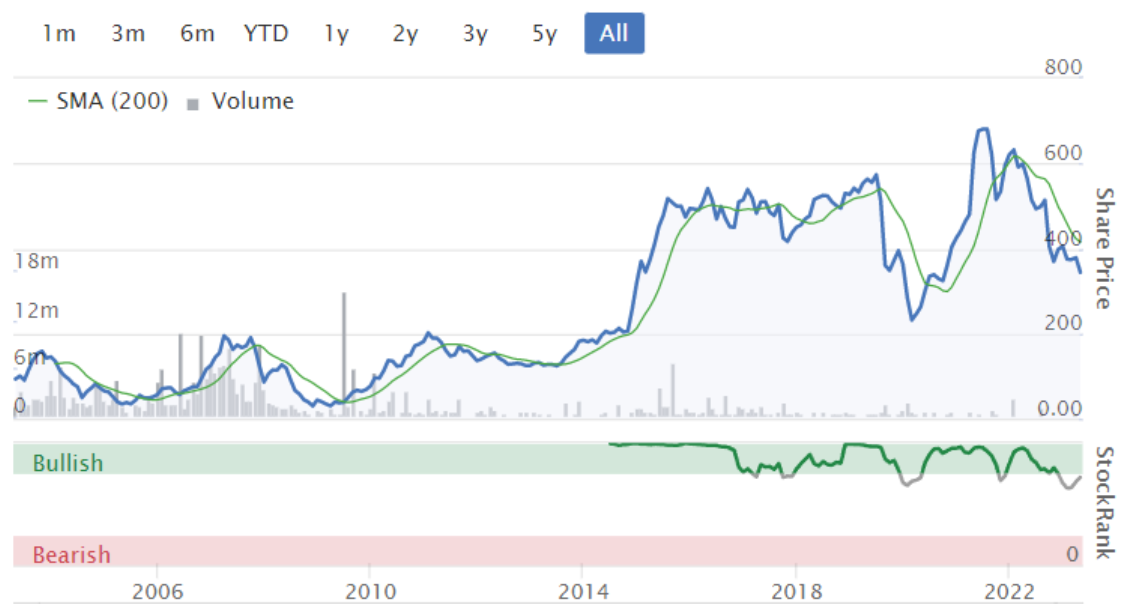
At the current level, I’m getting interested. Could it have dropped back into value territory now, with a market cap of £65m, £10m of cash, and the promise that it will earn £4.5m in the current six-month period?
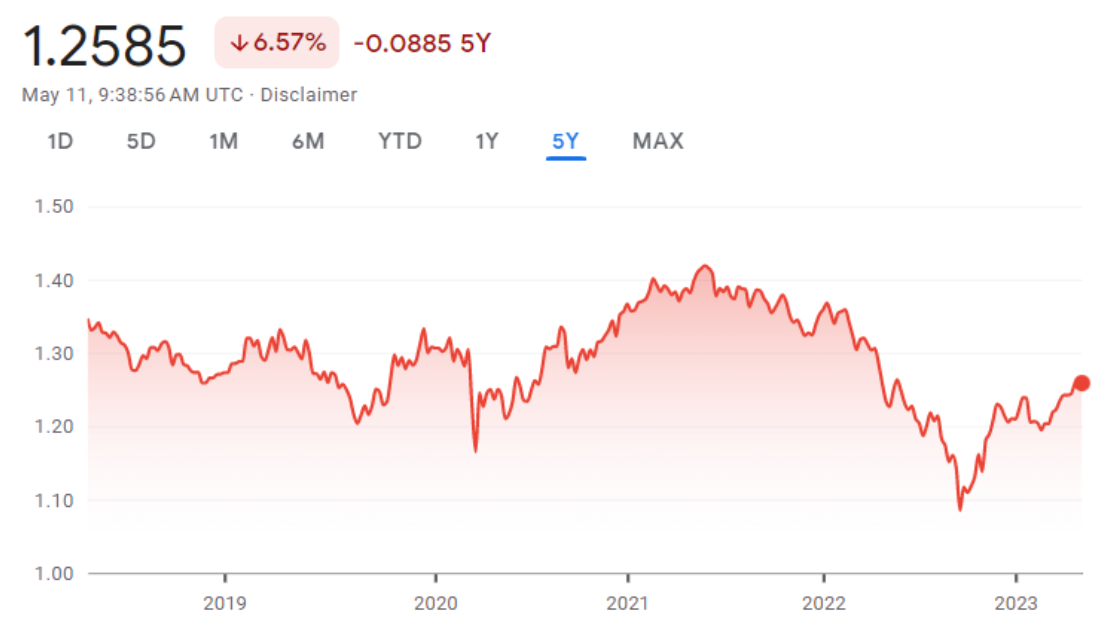
On the currency risk, they do make some attempt to hedge this by buying dollars forward (one year ahead), but it can only protect them so much. Long-term dollar strength is still going to hurt them, and it has. At least the pound has recovered from the low it reached in 2022, and might be getting back into its prior range:
Courage would be needed to buy in, given what has gone wrong over the past few years, and the ongoing macro uncertainty. However, I am going to give this stock the green light because it has enough interesting features for me to think that it is definitely worth researching in greater detail. A tender offer to buy back some shares would be an excellent catalyst to watch out for.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

29 comments
SDI (LON:SDI) Once again remarkable luck by Mike Creedon to sell almost £1million quid at £1.65, 6 months ago.
I had a feeling something like this would be coming after that sale. Whether it makes any difference longer term is up for debate but it's not the type of earnings momentum that would attract me.
I see there was a tiny 6.5k share purchase today by the same director. If anything that puts me off even more than the warning.
SDI (LON:SDI) Once again remarkable luck by Mike Creedon to sell almost £1million quid at £1.65, 6 months ago.
I sold on this director disposal back then. Not because of the value - it was his whole holding I think, but because of his bullshit answer when asked about his sale: "Oh I don't watch the share price - I just needed some cash". Yeah, right.
Yes they seem remarkably keen to sell between 165-195p considering they don't watch the share price.
Agreed…I’d appreciate a less tokenistic buy today to give any weight whatsoever to it given the history
Anyone following ZOO? Wanted to buy in but seems to keep dropping..
I'd imagine a couple of reasons for ZOO fall.
Revenue growth was well down H on H and missed firecasts, main customer "reorganisation" after a management change hitting revenue in last quarter. The placing looked to me to be opportunistic, using high share price to get cash in the bank as an insurance policy. Don't think the directors took part in it? They didn't say what the cost of the acquisition was. No idea but I suspect it's a lot less than they raised. CEO said they were targeting potentially 5 acquisitions. These are red flags for me.
Disney growth doesn't look great. ZOO heavily reliant on one customer, so any slowdown or cancellations will hit forecasts.
If the "reorganisation" was only a temporary blip and normal activity resumes then the shares look good value. If revenue growth stalls or goes backwards then they look expensive to me.
Thank you so much. Other than the placing, I did not find any of this info. So helpful thank you!
Re SDI (LON:SDI) …I think it demonstrates how difficult it is for mgt/brokers to guide/model a business akin to a snake that’s swallowed a beach ball (the Atik China OEM PCR Covid orders) in a wider group context…& especially so when there’s a possibility of further beach balls at some indeterminate point in the future…today any second beach ball was taken off the table for this FY.
I hold & expect this to be a bump in the road rather than a permanent change of direction …apologies for the metaphor abuse btw
To me the market reaction to SDI (LON:SDI) seems harsh given they had always advised the ATIK camera orders from the OEM were one offs.
Paul - Re Costain (LON:COST) - agree it may well recover lost ground. Looking at the full stockreport - It shows a Dividend Yield of 3.8% - although the mini report window to the right shows zero. Any way this can be fixed please - it's frustrating. Last divi was paid in 2019 when SP was around 400p
Unfortunately Stockopedia’s dividend figures are wrong far too often. Costain (LON:COST) is not a one off.
e.g Stockopedia show Ferrexpo (LON:FXPO) dividend yield as a juicy 12%. That’s nonsense. Ferrexpo (major Ukraine iron ore pellet Miner) stopped paying dividends last summer.
Ferrexpo is well worth keeping an eye on btw. They were paying 50p a year in dividends ahead of the War. The share price has inevitably tumbled to just £1.10. Large potential upside if this awful Ukraine War can end.
For reliable dividend information that is updated as soon as dividends are announced this is the one:-
https://www.dividenddata.co.uk...
It’s a superb site for dividends. Just key in the share code to bring up the next dividend amount and date if a dividend has been declared and the dividend history for that share too. All the headings there including obviously the dividend pay dates are worth checking too.
And here’s the link for Ferrexpo (LON:FXPO) dividends and dividend history.
https://www.dividenddata.co.uk...
That's really helpful Ken thankyou.
Regarding the Costain (LON:COST) dividend both figures are correct. The figure to the right in this report is the TTM figure which is zero. The 3.8% figure in the SR that you refer to is the 12m Forecast Rolling figure based on consensus forecast of a 1.63p dividend this financial year. In the results presentation they said they were committed to a return to dividends. One analyst asked if the board had considered one for the year being reported on and the CFO said yes they had but considered investment in the business a priority for cash at that time. Pressed on a date for a return to a dividend she refused to say when but from a later remark it is in any case tied in with current talks with the pension board to review the latest actuarial figures. Those comments probably helped revise down the foecast for this year from 3.3p showing in February before the 22 results were announced
On Reach there was a detailed note on the Pension Black Hole by an Investment Blogger who has been named in RNS annoucements in the past when they have caused big share price moves. Plus maybe the publicity around the latest in a long line of court cases about Phone hacking etc. kicked of again recently.
Paul you queried the fall in SP of Reach (LON:RCH). It went ex-div (4.46p / 5%) today. Plus an extra 1-2% knee-jerk bonus as over-reaction to fall?
While I'm on, many thanks Paul for the 2 weekend podcasts, which I really enjoy. Not to mention the CEO/CFO interviews which are always informative. Please keep them coming!
Could Reach (LON:RCH) have reacted to the Prince Harry news on phone tapping against the Mirror?
Regards
Michael
Reach (LON:RCH) is ex a 4.46p dividend today.
Thanks TheFly - I've given you a hat tip in the main report in an edit, for pointing out this ex-divi on RCH, which I missed!
How do people cope with sometimes disproportionate movements on Thursdays, exdiv day. Take for example
Clarkson (LON:CKN) which is today exdiv of 64p yet price down 105p I have not yet developed a 'sell before' regime' but I do diary a buy alert for the day or two after when considering a purchase. Of course its not always a consideration - but often is!
Director selling over the last year would put me off this . In percentage terms the drop today is not that large considering ex div .
Clarkson (LON:CKN) but they sell every year, they are share options. Common to sell half of share options to cover the tax.
Some stocks drop more than the dividend such as Legal & General (LON:LGEN), did 2 weeks ago.
Thanks Rusty - Agree you always need to look behind the news - as you mention here the share sells may well be regular to pay tax - and Yes, Legal & General (LON:LGEN) another good example of price dropping so much more than the dividend - and still not recovered!
legal and general is my bargain buy today.
never cut dividend even during the covid.
Morning,
AIM looking very weak again, difficult to see what a catalyst might be short term?! Go away in May...
been like walking through treacle for 2 years... fingers crossed buyers will come back at some point, the market tends to work ahead, it seems to see the catalyst before we do, I just continue to hold and hope
Splendid results today from Petrotal (LON:PTAL) . I hold.
Yep - 11% dividend starting June paid quarterly plus a buyback program.
Net cash now $70m and production rates 21,000 bopd which means they have fully recovered the Jan/Feb low river shortfall and are ahead of guidance for the year. This will obviously be offset a bit by the decline in Brent, though personally I expect that to be temporary.
Should be highly cash generative with a good growth profile. Good quality in my view.
I'm sure it will re-rate over time but at present I am getting compound growth of 11% p/a (tax free as in my ISA) before any capital growth so can be patient.
My morning smallcap tweet: NEW FORMULA. Now 30% more penetrating.
MobilityOne (LON:MBO) SDI (LON:SDI) OKYO Pharma (LON:OKYO) John Lewis of Hungerford (LON:JLH) Ilika (LON:IKA) Galliford Try Holdings (LON:GFRD), S4 Capital (LON:SFOR), FBD Holdings (LON:FBH), Costain (LON:COST), Gresham House (LON:GHE), Eleco (LON:ELCO)
◄MobilityOne (MBO)► withdraws UK electronic money institution application after FCA asks for further information on biz plan. Co "reviewing its proposed business plan in the UK and its options in relation to submitting a further revised FCA application". [SP=7.5 Cap=8m]
◄SDI (SDI)► guides FY-Apr rev £69m and adj pretax £11.8m vs F/C £66.3m and £11.8m. [SP=175 Cap=182m]
◄OKYO Pharma (OKYO)► delays delisting to 22 May "facilitate late transfers of certificated positions into CREST". [SP=2.22 Cap=37m]
◄John Lewis Of Hungerford (JLH)► tiny kitchen shop chain proposes delisting, tender offer after a sale and leaseback for £3m. Blames listing costs. Will tender for only 10% of cap at 1.5p, roughly par. [SP=1.42 Cap=3m]
◄Ilika (IKA)► ships stacked Stereax M300 batteries to a customer at last. Faraday was still alive when IKA first announced this tech. [SP=47 Cap=74m]
◄Galliford Try (GFRD)► is 'sole appointee' for £387m UK defence contracts. Does that just mean it won the contracts outright? [SP=177.58 Cap=192m]. I hold.
In line: SFOR, FBH, COST, GHE, ELCO
Fast post and funny as usual MrContrarian - Re Ilika (LON:IKA) "Ships.. M300 batteries to a customer at last. I think Faraday was still alive when IKA first announced this tech". Perfect start to the day Sir