Small Cap Value Report (Thu 11 Nov 2021) - PMP, VLX, TED, BOTB, GMS

Good morning! It's Paul & Jack here with the SCVR for Thursday.
Agenda -
Paul's Section:
Best Of The Best (LON:BOTB) (I hold) - after a chaotic year, with earnings estimates down by two thirds, this online supercar competition company seems to be stabilising. An in line update today, so it looks like we're over the worst. I conclude that the shares seem attractively priced now, but not everyone will agree, given the unpredictability of earnings, and new, well-funded competition.
Gulf Marine Services (LON:GMS) (I hold) - 2 contract extensions, at increased charge out rates (no figures provided, probably commercially sensitive). The problem is massive bank debt, but everything seems lined up now for debt to reduce quite fast, with its 13 vessels in high demand.
Jack's Section:
Portmeirion (LON:PMP) - good update, with full year revenue now expected to be 5% ahead of current expectations. More guidance on margins would be appreciated given the pressures. However, the shares continue to look reasonably valued, the turnaround is going in the right direction, and the group scores a consistently high Quality Rank.
Volex (LON:VLX) - strong revenue growth of around 44% as the company pushes through price increases to negate rising costs. In the long term, there is scope to continue growing both organically and acquisitively, but the current conditions are tricky and the group is moving fast with acquisitions, so the shorter term risks are worth bearing in mind.
Ted Baker (LON:TED) - some positives in this update but I'm still not convinced that the recovery is as entrenched as the share price suggests. There's a key trading period coming up, and I'd rather see how the company performs there before making a judgement on its ability to recapture its former glory.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section
Best Of The Best (LON:BOTB) (I hold)
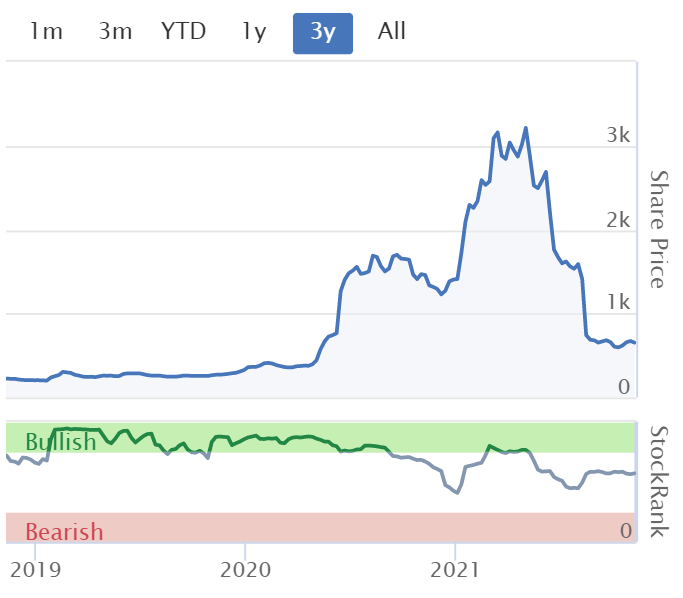
655p (up 5% at 11:25) - mkt cap £62m
Trading Update (for H1)
Best of the Best PLC (LSE: BOTB), the provider of online competitions to win cars and other prizes provides an update on trading for the six months ended 31 October 2021.
Here’s the text in full (with my bolding of key points) -
The Company reports that financial performance for the period is in line with the market guidance issued on 13 August 2021. Customer acquisition costs have stabilised, albeit at the higher levels previously reported.
Engagement from the enlarged player base has also normalised, with average order values and frequency similar to pre-pandemic levels.
Trading for the period has, therefore, been consistent with management's revised expectations. The Board remains confident about the prospects for the business, both in the second half of the financial year and beyond.
We remain focused on our growth strategy and will update shareholders with further details upon release of the Company's Interim Results in January 2022.
Valuation - the share price collapse at BOTB occurred because earnings expectations have crashed by about two thirds, as you can see from the broker consensus chart below -

.
It’s now clear that BOTB experienced a one-off boost from lockdowns, with profit and EPS forecasts looking to be back on a long-term upward trend. So I think we could still see BOTB as a growth business, once the one-off pandemic boost is stripped out.
Although looking at the revenue line below, that looks more of a step-change, and has only fallen slightly from the peak. So the problem seems to be mainly due to higher customer acquisition costs -

.
How to value it? That’s the difficult bit. I would have thought a PER of say 15-20 is realistic. That arrives at the following valuations -
FY 04/2022 forecast 53.3p, at PER of 15-20 = 800-1066p
FY 04/2023 forecast 64.1p, at PER of 15-20 = 962-1282p
In that context, the current price of 655p looks too low.
However, an alternative view is that earnings have been so volatile, that some investors might only be willing to use a lower PER to value the company. Given the earnings volatility in the last year, and the extreme operational gearing, then this is a reasonable view too.
There’s increased competition, in particular from Omaze, and many me-too smaller car competitions. Some of them use a more transparent model than BOTB, e.g. publishing the total number of tickets to be sold, thus making the odds clearer.
My opinion - the big lesson I’ve learned from BOTB is the importance of operational gearing. Extra revenues drop through almost fully to the bottom line at BOTB - great when sales are rising, but awful when sales drop. Although as mentioned above, the revenues line hasn’t actually dropped very much from peak levels.
Another lesson is that online businesses can be hit with increased cost of customer acquisition, which seems to be the main problem BOTB has experienced. Although as we saw recently from Sosandar (LON:SOS) (I hold), marketing strategies can be tweaked to focus on the most cost-effective way to acquire customers - SOS has greatly reduced its customer acquisition cost, and is trading very well. Maybe BOTB might be able to improve the cost-effectiveness of its marketing strategy, rather than being a price-taker of higher cost online ads? It’s also a reminder of the pricing power that Facebook (now called Meta) and Google have, in online advertising. Hence there’s potential risk for all online businesses, if unexpected and large increases in online marketing costs occur.
A third risk is that, like many other sectors, BOTB is facing new competition that is apparently backed by private equity or venture capital funds. These operate by different rules. Instead of being self-funding like BOTB has been, some new entrants may have pots of cash that they can throw at marketing, incurring heavy short term losses. The idea being that many such businesses will fail, but the odd one could become a massive success. It does feel like unfair competition though.
We’re seeing well-funded new entrants in other areas too, like online selling of secondhand cars. New entrants which all seem to operate at heavy losses, and are burning through cash piles on big marketing budgets. After this boom has ended, people may look back and say, “What on earth were we thinking?”, chasing loss-making companies like Cazoo up to a valuation currently of over £5bn. That's exactly what happened when the original dotcom boom & bust happened in 1998-2000. Or larger US rival Carvana, currently worth £37bn, despite never having made a profit. Things are pretty crazy right now in some areas, but the trouble is that existing businesses are facing very well-funded new competitors, and I think that is a risk for BOTB.
Many investors were drawn to BOTB by the incredibly high quality measures, like ROCE, ROE, etc. However, we didn't think enough about whether the business model was sustainable at those levels. High returns attracts competition, a risk we maybe need to think about more in future?
On balance, I think BOTB does look attractively priced now. With hindsight it clearly overshot on the upside, but has now probably overshot on the downside too.
Also remember BOTB pays out surplus cashflows in special divis, so we get paid to wait. Hence overall, looking at it with fresh eyes, BOTB seems reasonably attractive at 655p per share. Although given the wild volatility in earnings and share price, I can understand why investors may be reluctant to get involved here, which could limit the upside for the time being perhaps?
.
.
Gulf Marine Services (LON:GMS) (I hold)
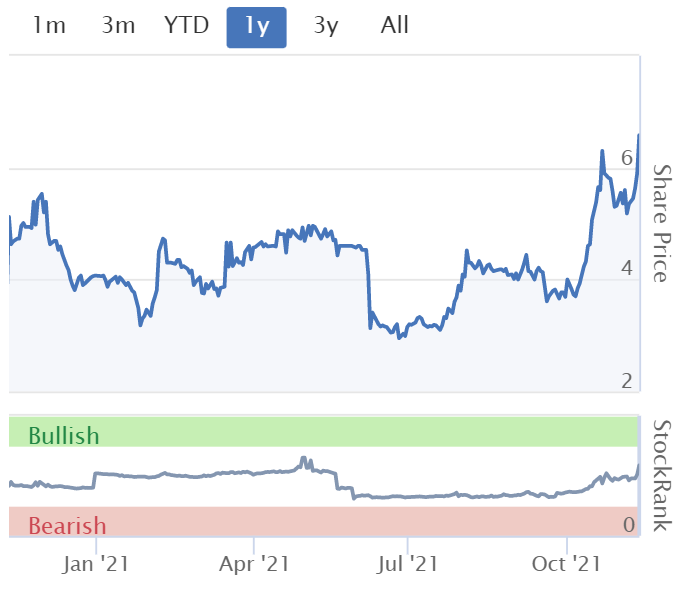
6.4p (up 8%, at 12:41) - mkt cap £65m
I mention this because it’s close to being a trading update.
See the archive here for my fairly recent discovery of this interesting, albeit quite high risk special situation.
Here’s the short version: GMS owns a fleet of 13 specialist support vessels for oil/offshore wind sector. It’s got an awful track record, and a balance sheet groaning with way too much bank debt. Rise in oil price now means these vessels are back in demand, with daily hire rates rising, and utilisation high. The company should now be highly cash generative, which is forecast to bring down debt to manageable levels in 2022. The benefit of this should flow through to the bombed out shares, giving considerable (albeit still risky - something could go wrong) upside.
What I particularly like about this special situation, is that everything is already in place for the turnaround to happen. Hence we are set up for positive newsflow on contracts, cash generation, and debt reduction. You can work out the figures easily, as EBITDA is massive, maintenance capex is low, etc. Vessels are rented out on contracts of several years, some of which are now renewing, but at higher daily charge out rates - flowing straight through to higher profitability.
Today’s news is 2 contract extensions, at higher daily hire rates. Hence a continuation of existing contracts (no downtime to move the ships), one contract is to end 2022, the other to end 2023. Hence good visibility of cashflows.
Market is tightening, which should be very good indeed for GMS’s profits/cashflows -
"The two contract extensions, on improved rates, signal that the market for our vessels, particularly in MENA continues to tighten and that clients are taking action to ensure they have vessel availability to support their ongoing operations.
Today’s update is light on specifics (no figures given), but I imagine contract details are probably confidential (and commercially sensitive).
Confident outlook -
These awards further increase our confidence that the financial performance of the Company will continue to improve in 2022 and beyond."
My opinion - it’s early days, but so far the newsflow is panning out as I hoped. The sector tailwinds made this easy to anticipate.
Management explained the situation well in a recent webinar, and seem to have a grip on things. They’ve already done one successful renegotiation of the bank facilities, and it should be possible to normalise the banking arrangements by end 2022. We hope, but that’s not certain.
GMS is one for special situation investors, as there’s quite high risk, if something were to go wrong with the banking relationship. Although with the company now spewing out cash like nobody’s business, enabling it to pay down debt quite fast, why would the bank get difficult at this stage?
I like this share - rising cashflows, on a fixed cost base, should transform its financial position. GMS could be a very good performer, if things keep moving in the right direction.
This share has been an absolute dog in the past, but has now transformed into a highly cash generative business. Hence why it's of interest to me.
.
Jack’s section
Portmeirion (LON:PMP)
Share price: 685p (+0.74%)
Shares in issue: 13,985,442
Market cap: £95.8m
Portmeirion designs, manufactures and distributes homewares under the Portmeirion, Spode, Royal Worcester, Pimpernel, Wax Lyrical and Nambé brands. They’re well regarded brands, but margins took a hit recently so the company is in turnaround mode.

Since our interim results announcement in September 2021, we have continued to see strong sales of our brands across all key markets and have healthy order books for the remainder of the year, including the important Christmas trading period. We therefore now expect sales to be at least £95 million, approximately 5% above current FY21 consensus market expectations.
The group is still experiencing cost inflation and supply chain disruption. Together, these ‘will limit, in the immediate short term, the upside on profit from our higher sales in FY21.’ Portmeirion does add though that it thinks this disruption should be short-term in nature.
Mike Raybould, Chief Executive commented:
We are delighted to see the strong levels of demand for our brands around the world. Our focused strategy is transforming our business and our growth is being driven by our ongoing development of online channels, new product launches and expanding international markets. Whilst there are undoubtedly short-term cost and margin pressures within global supply chains, we are managing any current impact on the business and we are confident in our expectation that we can grow our operating margins over the next three years.
Conclusion
A short update but it looks like the strategy here is working well, with online proving to be a valuable new revenue stream. Portmeirion has said before that it’s only in the early stages here, so there should be more progress to come.
Shares have recovered well from Covid but remain well below their previous levels. There has been a degree of equity dilution, around 15% or so over Covid, which is manageable. Others have suffered worse.

What’s more, the valuation remains fairly modest at 12.5x forecast earnings (helped by a significant forecast increase in FY22 earnings), so there’s runway for a further rerating despite the High Flyer status. Sales are now expected to be c5% ahead for the current year, but it would have been good to get some more guidance on margins given the pressures faced by the group.
FY21 EPS estimates look a little low, with a big rise expected in FY22. I wonder if, given the trading momentum, the company might beat the current year estimates.

It’s already got a good H1 in the bag. H2 is more important, so it's positive to hear the sales beat. That plus the habitually strong Quality Rank means the shares are still well worth a look in my view, with scope for further steady progress. It’s not hard to envisage another 25%-30% added onto the share price over the next year or so should wider market conditions remain stable, although I wonder how much upside remains beyond that.
The company still has to navigate cost inflation, labour shortages, and supply chain issues of course (which it so far appears to be doing).

Volex (LON:VLX)
Share price: 411p (-8.05%)
Shares in issue: 158,718,709
Market cap: £652.3m
Volex is a global supplier of integrated manufacturing services and power products, serving blue-chip customers from an increasingly flexible and global operating base. The group is very acquisitive, which means there is scope for continued inorganic growth, but such a strategy obviously brings acquisition risk.
And it’s a difficult time in the market. Some customers are experiencing extended component lead times and Volex continues to pass through rising costs. There’s a lot for management to deal with right now.
The group’s key markets include:
Electric vehicles - The automotive industry is experiencing a period of rapid change. The company anticipates increasing competition here and is investing in its manufacturing capabilities to ensure it remains one of the lowest cost producers.
Consumer electricals - Power cords and related products are sold to the manufacturers of a broad range of electrical and electronic devices and appliances (PCs, power tools, etc.)
Medical - Here, the group’s products are used in smaller medical devices for patient monitoring and treatment.
Complex industrial technology - This segment includes a wide range of equipment and customer solutions, including building control, smart metering, laser technology, vehicle telematics, telecommunications, industrial automation and robotics.
Highlights:
- Revenue +44.5% to $292.7m,
- Underlying operating profit +31.3% to $27.3m,
- Underlying profit before tax +21.5% to $25.4m,
- Basic earnings per share +7.8% to 11 cents,
- Interim dividend per share +9.1% to 1.2p,
- Net debt before lease liabilities of $21.8m (H1 2020: $32m of net cash).
Not for the first time, there is a notable difference between adjusted and statutory profit. The main culprit here is just over $5m of amortisation of acquired intangibles, related to acquired customer relationships and order backlogs. You can see the additional items here, in note 3.

You might argue that Volex is a little too easy with its adjustments. It’s unclear from this update, for example, how much of the share-based payments charges are ongoing incentives for senior management versus one-off awards granted to the management teams of acquired companies.
What’s clearer is the strong revenue growth of 44.5%, ‘reflecting high levels of customer demand in all sectors’. Operating profit has gone up by less (but still +31.3%) as the group manages cost pressures and extended lead times.
It’s been busy acquiring, with three North American businesses entering the fold. Two of these came after the period-end.
Electric vehicles sales have grown some 210% year-on-year to $45.3m due to Volex’s strong position in grid-cords and expansion into other products. The prior year was impacted by Covid. Demand in Q1 of the current financial year was very strong but tapered slightly in Q2 as customer production suffered from component shortages.
Consumer Electricals sales were up 74% year-on-year to $127.4m, including positive impact from the acquisition of DE-KA. Medical revenue grew by 15% to $62m, with signs of improvement in the sector following Covid disruption. Complex Industrial Technology saw a slight reduction in year-on-year revenue to $58.1m following high levels of demand for data centre products in the first half of FY2021.
In terms of geography, North America contributed 41.4% of revenue and grew by 30.5% to $121.2m, with Europe contributing 34.5% and growing by 124.7% to $100.7m, while Asia made up 24.1% and grew by 9.4% to $70.7m.
Regarding cost increases:
We look to pass on higher component and commodity costs to our customers through contractual mechanisms and regular repricing. We have experienced increased freight and copper costs during the period. These have been passed on to customers, increasing revenue but not the absolute margins on individual products. This results in slightly lower gross margins as a percentage of revenue. There is also a small time lag in passing through such cost increases, which has an adverse impact on margins when prices are rising. This becomes a positive impact when prices are falling. There was an adverse impact on gross margin from these effects of 1.5%.
During the first half of the year, inventory has increased significantly to support the growth of the business and as a direct result of increases in lead times in the global supply chain, as well as longer shipping times between production facilities and customers.
Operating cash flow before working capital was $30m. The increase in inventories cost $20.4m, and an increase in receivables was $13.4m. That’s set against a $15m increase in payables, so you can see the cash impact as the company manages its position amid global pressures. The result after accounting for tax and some other lines is a net CFO figure of $7.3m.
The net debt position has increased and will rise by a further $35m after the acquisitions of Irvine, Prodamex, and TC. This will total $56.8m compared to $27.3m of underlying six month operating profit, which is manageable but still something to keep an eye on given the conditions.
Conclusion
The revenue growth is good here, but there’s an impact on its balance sheet and cash flows as it balances a highly acquisitive strategy with a tricky global environment.
The strong forward order book sees Volex on course to deliver on its full-year consensus market expectations, however global component shortages and shipping issues are a risk. The growing pipeline of acquisition opportunities must be carefully balanced against the group’s capacity to make such acquisitions, particularly at a time of heightened global costs and disruption.
Still, inorganic growth is a key part of the strategy and the group aims to grow revenue by 10% p.a. through the purchase of accretive and cash generative businesses. Six businesses have been acquired over the last 3 years for $140m with an additional three announced since August 2021. I think some shareholders would understand if the group reduced this rate given the current volatile conditions, but it doesn’t look like that is in the company’s plans.
Nevertheless, Volex describes its longer-term prospects as ‘excellent’. Managing such an acquisitive strategy must be difficult and time consuming, so I think the next six months or so is a period of heightened risk, although the longer term investment case remains intact.
As long as Volex can ride out the current pressures and continue to pass on costs, there’s scope for continued growth in the long term. But for now, at around 22x forecast earnings and some challenges to navigate, the shares look up with events in my view. There's a presentation today at 11:30 on investormeetco, which should be a good opportunity to hear more from the team.
Ted Baker (LON:TED)
Share price: 139.2p (+1.83%)
Shares in issue: 184,608,786
Market cap: £257m
- Revenue +17.6% to £199.3m,
- Reported loss before tax has improved from -£86.4m to -£25.3m,
- Basic EPS has gone from -64.1p to -10.1p,
- Net cash has declined from £60.7m to £12.7m.
While there are some year-on-year improvements here, the two-year performance is negative and the steep decline in net cash is alarming. Net cash flow for the period was an outflow of £38.3m (2020: inflow of £7.7m).
Ted does say this reflects the normal operating cycle of the business, as it brings stock in for sale during H2 ahead of Black Friday and Christmas. Still, that’s a hefty cash burn within the context of an extensive turnaround.
Ted Baker has significantly diluted its shareholders in order to raise cash over the past few years so the big risk is continued dilution. I remember in response to the most recent placing, a broker said the group’s balance sheet had been ‘fixed’, which I think downplays the financial risk.
That’s not to say the company and refreshed management team isn’t working hard. The transformation plan is on track, sales are improving sequentially, and the group is recovering its premium positioning. There’s little negative impact from supply chain disruption and inflation and the group has a ‘basket of mitigation strategies’.
Ted Baker has upgraded its target to achieve a net cash position, with this target to be achieved by the end of the current financial year. No guidance is given but Ted Baker is ‘comfortable with market consensus’.
Current trading and outlook
Q3 trading has been impacted by ongoing Covid restrictions and subdued footfall into physical retail. However, the group has seen further sequential improvement in trends during the period, with further progress in trading margin as a result of reduced promotions.
Balance sheet
Net tangible asset value of £102m looks better than it has done in the past, but it’s the rate of reduction in net cash that is the concern. This is a retailer though, and the group reassures that this is in keeping with normal trading patterns ahead of key periods.
Conclusion
Ted Baker can turn around. It’s more the risk:reward as I see it that has not seemed all that attractive. Often, it feels as though the risk has been understated while the return potential has been diluted.
But some have a different perception of the risk profile and there are plenty of investors banking on a successful recovery. It’s still too early for me but Ted Baker was until recently a valuable brand, and if it can recapture that prestige then of course there is upside potential.
The losses are still substantial, however, and the year-on-year reduction in net loss is flattered by a non-cash £45.8m impairment charge in FY20. On an underlying basis, net losses have improved from -£38.4m to -£27.1m.
There’s a sequential improvement in trading and it’s possible that that risk:reward trade off is improving now but I do worry that a sustained recovery is being taken for granted. The reduction in net cash is a concern, but the group does say this is partially due to investment in stock ahead of an important trading period.
Given the depth of the turnaround that is required here, I’d rather wait until after this key trading period is over and there is more concrete evidence of success.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

81 comments
Volex (LON:VLX) gets the main headline tip in Small Company Share Watch, 2 page spread.
Good read and normally helps the companies involved the following monday.
Prophotonix Prophotonix (LON:PPIX) ( I hold) received a takeover / merger offer at 8.7p this morning however the stock opened and closed at 7.75p, up 37%. Does anyone know why there is such a discrepancy between the takeover and the market prices given that it appears a done deal and expected to complete next month?
The takeover price is being paid in dollars so I’m expecting to receive less than 8.7p due to the commission charge to convert dollars into sterling and that, together with the risk that the deal is only done when it’s done, makes up the difference. Just my opinion
ok thanks
Have exactly the same question this morning - still trading at 7.75. Did you find out?
For those who left the Volex (LON:VLX) presentation before the end you missed the best bit - in summing up (59:50 in) Nat said the technical problems showed the need to move from 100Gb/s to 400Gb/s cables which was very bullish for their Complex Assemblies trade!
I appreciate Nat was in a hotel in New York, and his CFO was somewhere else with terrible internet, but it was bloody annoying to waste 30 minutes on a webinar with Volex (LON:VLX) (I hold) that was so awful in terms of sound quality today.
Paul.
Thanks for the write up on Gulf Marine Services (LON:GMS) , an interesting special situation. One further wrinkle investors need to get their heads around is the role of the two principal shareholders, Mazrui Investments and Seafox International who between them hold about 43% of the company.
The announcement made at the time of the June placement sets out a bit of background (as well as a lot of information on the business that is well worth a read) https://www.stockopedia.com/sh... but the sense is that there was something of a coup going on in the background leading up to the refinancing and other options (such as a complete take private) were considered.
Risk, as ever, with this sort of situation is that just when the upside begins to come into view it’s whipped away in a corporate action pushed through by a rump of executive shareholders and a few compliant institutions (think Cambria Automobiles (LON:CAMB) , Bacanora Lithium (LON:BCN) and others) to the detriment of the small PI. At the moment everyone’s interests seem to be aligned but that may not always be the case.
Gus.
Made.com (LON:MADE) (no position)
For any Made.com holders out there, here is Westwing's Q3 report published this morning (which I hold.)
https://ir.westwing.com/downlo...
Of particular note was:
Supply chain issues of course persist.
The above I can live with. But operating cash generation (pre-working capital movements) looks pants, much lower than I would have expected given the company's size these days.
I have Made.com (LON:MADE) high on my watchlist but after that last point, I'm more inclined to wait - I have a feeling they will have similar issues.
Cheers
A
I noticed a similar build up of inventories and poor cash generation in the Norcros (LON:NXR) (I hold) figures out today. I guess both companies are responding to supply chain issues, and perhap inflation prospects, by building up inventories.
Norcros (LON:NXR)
JCPr
"I noticed a similar build up of inventories and poor cash generation in the Norcros (LON:NXR) (I hold) figures out today. I guess both companies are responding to supply chain issues, and perhap inflation prospects, by building up inventories."
Thats a harsh assessment that is pretty unfair to Norcros (hmmm i always sound like a fanboy whne i mention Norcros numbers so take my comments with a pinch of salt !!)
The inventories build up is more a return to the norm than anything else - their inventories have always ebbed and flowed anyway and they have not really ever had any w/off issues so i am 100% happy with working capital movements.
If we go back to last pre covid period inventories at 30/9/2019 were £84 mill
This figure dropped to £70 mill last year during covid
the figure is now back up to £94 mill at 30/9/2021 - however sales are 10% higher last 6 months than same 6 months in 2019 - so add 10% to the £84 mil 2019 total and i would say inventories are within a rounding of historical norms. The poor cashflow this 6 months was always going to hapen after the ridiculously good cashflow the pripr 12 months. Going from £53 mill net debt sep 2018 to net cash 30/9/2021 is an insanely good 3 year outcome - so we should have nil worries ref the cashflow here. In some respects as you have mentioned with prices going upwards and uncertain supply issues the more the merrier ref inventories i would say at present (not often i would say that) - so i would not say its poor cashflow as such as to me it was expected that the prior unwinding would take place in the natural order of things.
Bonus cherry here today was further progress ref pension deficit - timing could not have been any better in that regard with the 3 yearly review taking place as we speak.
Re Norcros (LON:NXR) - I see it differently. Inventory is £10.9Mn higher (£94.8 vs 83.9Mn) than Sept 2019 to support a bigger, growing business. Product in hand seems to be a good place to be right now with supply chain problems and rising prices. Underlying EBITDA in H1 was 23.8 (+15% vs 2019), not stellar but no bad for a company with a market cap of 266Mn
Since Sept net debt has come down from £(41)Mn to +ve £1Mn.
I am hoping they can find a decent sized business to buy to do more of the consolidation and cross selling they call out (& further diluting the relative size of pension scheme). They've kept the £600mn by 2025 and 50% non-UK ambitions (plus already in place 15% ROCE.
The key risk now I think is their dependence on a mostly China supply source and ( as ever) political risk in South Africa.
I have been holding for years and they finally (famous last words) seem to be coming good with which Stockranks, with score of 98, concurs.
£Made
Hello abtan
Cheers for i am an interested watcher on the sidelines like you at present - as the company looks like it has the potential and ambition to go places (is the plan cunning or not is the question?)
As you have aluded to i think Made are also morphing over to holding more inventories with the associated extra costs too - which does appear to be a change in tack away from the just in time methods they were employing (i like a bit ot taguchi methadology mee buts thats another thing entirely) .
I see the bigger picture here in that as long as they are roughly on track ref sales i will let the other sins not put me off investing be that a dip in margins or cashflow - i am firmly on the sidelines here though with no spare money allocated at present and in no hurry to jump on board at levels above 150p - so if the shareprice ticks up much anytime soon i may miss the boat here. They do have lots of work to do though to keep scaling sales so quickly that this is a very risky play at present i would say.
Just logged out of the Volex (LON:VLX) presentation on investor meet - an absolute shambles, must be their first attempt at a webinar !
I must have left just before you - couldn't bear to watch it either!
Hi bohenie i missed the webinar with Volex (LON:VLX) so can i ask was the "shambles" a technical issue (ie with webinar) or the performance of Volex Management...and if the latter was that down to poor presentation skills or a lack of knowledge/confidence? many thanks (disc. I hold)
Volex (LON:VLX)
I too logged out of the session. The ‘shambles’ was down to the hosting platform as far as I could tell – comms gremlins - and the actual presentation by the Volex management seemed fine. FWIW I shall continue to hold.
It got better later on and came across very reassuringly to me as a holder. Investor Meet Company need sort the technicals out -very painful. Of most interest was the Q&A at the end as this morning’s RNS had everything else.
Well thank goodness someone had some patience.... . As to whether it was the fault of VLX or IMtheC not sure but these guys have been presenting these webinars for some time - Hopefully, whoever was at fault will own up ! I have just emailed IMC and asked if there will be a re-recording available. Will post again when they respond!
Don’t panic. Investor Meet Company had announced way before the session that a recording would be made available. During the gremlin attack they said they would edit the soundtrack appropriately.
not sure the technical problems were their's or the investor meet company
re: Volex (LON:VLX) i webinar the breakdown in sound was frustrating but down to the hosting co. not the presenters. I also found it reassuring; Nat, as usual was impressive, especially considering he was speaking from New York so must have been early hours there. I think all my concerns were answered during the presentation or Q&A session, including why the margin has dropped a little, price of copper etc. Future looks really promising to me so 2/3 year (at least) hold for me.
Beximco Pharmaceuticals (LON:BXP)
Good Q1 figures issued @ 20 mins ago. Revenue up 22% and Profit after tax 36%. Forecasts on Stocko look materially understated.
Still think its a bit weird, but sometimes weird is good.
Phil (I hold)
Just about on point with market cap size but Bank Of Georgia (LON:BGEO) looks very unloved. This is a business with an ROE of 25%, very strong tier 1 capital at 12.8%, low leverage ratio, pays a dividend of around 6.5% and trades on a PE of 4.8 ! Cost to income ratio of 36.8% is super good in banking terms too.
Todays trading update Q3 profit up 24%
SP just never seems to go anywhere, strange.
Agreed £BGEO; has a Stockopedia score of 90 and a dividend of 6.9%. However if you look at banks generally they have not recovered significantly compared to, say, 8 - 10 years ago.
I am invested in Bank Of Georgia (LON:BGEO) and it is producing good returns.
The Georgian economy is growing massively, BUT there is a lot of inflation. The bank itself seems to be a trusted partner of World Bank etc etc and able to get funds from these international institutions to lend out to Georgian companies.
The negative aspects will always be Russian activities, corruption etc
I am a long term holder and think they will rise steadily whilst paying a strong dividend (world events permitting).
There are a few banks based in Eastern Europe that regularly come high up on the Stock Ranks screens that I’ve been tempted by but not yet nibbled at. Nova Ljubljanska Banka Dd Ljubljana (LON:NLB) is another that would appear to be unloved and undervalued yet provides strong quality stats. As with Bank Of Georgia (LON:BGEO) the share price is up 50% or so since the end of April so somebody is starting to pay attention to the decent metrics. Ideally, I’d like to find an IT or ETF that holds a basket of these to spread the risk of apparently attractive FI’s in non-mainstream markets.
Gus.
I hold Georgia Capital (LON:CGEO) as well as Bank Of Georgia (LON:BGEO) - not sure if that counts as diversification. I was alerted to them by Bruce Packard's write-ups for Sharescope. I think he worked on the floats.
Georgia Capital (LON:CGEO) Bank Of Georgia (LON:BGEO)
Banks in fringe emerging countries are always very cheap at some point. Can get super returns at points in cycle (usually a synchronised global economic growth and bull market...so that's minority of time) and good returns through local earnings growth due to local economic activity (...but that rarely gets priced highly and the valuation continues to look cheap) -> this can run a long time and decent returns accumulate.
The down escalator can be brutal at times and often can have an unexpected (to foreigners at least) political element.
I wonder why these Georgian entities are UK listed (I know quite a few Russian orbit things are)? Very small and banking is always local (more so for Georgia) and not 'global' like commodities. This is a question not an insinuation.
This is my experience investing in emerging market banks (for me particularly LatAm). Had big bags....and big swoons down if holding the bag at the wrong point.
Hi Paul, would you be prepared to look at IBPO (IEnergizer). I have been following this for a while and it has kept delivering good results. Again today. It has benefitted from home working as a software developer and offers home learning, as well as back office support. It pays a good dividend. The balance sheet isn't great given the presence of Goodwill 102m BUT that seems part and parcel of these software businesses. In the past this is what scared me. Still don't like it but overall becoming increasingly impressed. I am sure your other readers may see something worth having a look at, if they haven't already.
Why is Volex down 7,8 percent on good news?
Because it's not as good as it appears
Njoydev12
For Volex (LON:VLX) it would depend on your entry point, if it were nearer £5 my commiserations, if it were back at £1.50 it is an ouch but just a bump in the road on the long term investment process.
We all look regularly in our rearview mirror (sorry for using a driving analogy but I cannot think of anything better right now). So we feel that we should have bought at x, sold at x+2 and bought back at x+1) or in my case buy at x+1, sell at x, buy back at x+2 and sell again at x-1...
If your profit is diminished, then you have to decide does what was said today and in the IM presentation change your investment case, and if it does not continue to hold, if it does sell and take the profit you have. The same is true if you sit on a loss, it is just a lot harder to do that as we all like to hold on the hope of recovery...maybe Bp (LON:BP.) will reach £5+ one day?
As an anecdotal this feels like it is happening a lot this last month or two, prices get a big drop if there is not a significant beat or upgrade. Hard when you hold, but potential top up or entry for those who do not.
As I tell myself every day, you are in the game, keep playing and keep learning and hopefully you will spot the next 10% jump and miss the next 10% drop.
Tommy
I don't hold currently.
Interesting news this morning from Saietta (LON:SED) who are buying a Dutch commercial electric vehicle company - looks like a lot of synergies and opportunities arising from this purchase. They also seem to have bought very well as it is a distressed asset from Evergrande (or perhaps better to say a good asset from distressed Evergrande).......
I love the Saietta (LON:SED) potential. It really appeals to my ESG sense of how good commerce and innovation can combine to derive very strong positive social benefit in the form of Co2 emission and air pollution reduction.
Purchase looks good - cheap but will accelerate its own tech.
Of course it is most definitely a jam tomorrow stock and not exactly roaringly cheap at this stage of its development either. Nonetheless potential is enormous but a bet on managements ability to execute. A bit of a blue sky investment for most people but I suspect that will change if revenues start gaining traction. Wondering why it's listed in London though when the US seem to give completely outlandish valuations to this type of EV maker............
Here is Paul Hill's view from Vox markets this morning:
https://www.voxmarkets.co.uk/a...
Thanks. Does look like a cracking piece of business from a distressed seller.
Anyone following Deepverge (LON:DVRG) , they put out a really positive note regarding their app based skinclub which is launching at scale in the US.
Yes the Skin Club seems to be growing massively - the addition of B2B is very interesting as well (so selling via beauty companies / skin care companies). It is very exciting and it will be interesting to see whether they break out the Skin Club revenues/profits separately next time they report.
They already have a massive data set but the Skin Club will rapidly grow this further....and of course they then sell on this data to Pharma and Beauty /skin care companies.
Re PMP 's trading update - More evidence in my view (I hold) that that this share is undervalued medium term. It has still not yet returned to pre Covid levels (itself a low after some issues) but is now a much better business under a newish ex CFO MD
Demand is good - Sales Forecast is upped to min 95Mn ( & still under-cooked I think) and product innovation has been strong
Online says it is doing well - this is key long term >10 %ppts better margin than via shops . (again I think this may be rising as seem to be reducing the level of discount offered in promos)
I had supply side concerns over high gas costs in its UK pottery factory but today it says "it buys energy under long term contracts. In the first half of 2021 we extended those contracts until early 2024" and specifically confirms container costs/delays wont derail the profit consensus.
I think if H2 plays out well (and mid Nov, it looks good) then these shares are likely to re-rate strongly in 22 as the good news comes through.
Portmeirion (LON:PMP)
I think will will have to start calling you mystic zipman Zipmanpeter as i think you have previously predicted they would beat on revenues but those extra revenues would be eaten up additional inflationary / supply issues - looks like that prediction was bang on the money.
I remain sort of content holder here - i am not as convinced as others that their future growth potential is as good as something like Sandersons. SO IMHO they still have work to do to deliver with regard to the next year targets. PMP havent exactly been reliable in the past so i am more along the lines of i want to see the proof of the pudding before believing - at least the targets for next year and down in black and white.
Note i think some here have got over exuberant with regard to prospects for this company - as i had seen some bods predicting ye sales would be over £105 million this year due to the seasonal weighting - so i think the optimistic bods have so far not been proven right if we will come in between £95 and £100 mill - who knows perhaps they have something in the tank.
Note i would say its probable that the sales beat is mostly down to increased pass through pricing only - not exactly much of a beat if the volume of sales is roughly what they previously expected.
Hopefully they will continue to at least match expectations this year and next (they certainly have sound base that seems reasonably conservative) and perhaps the market may start to believe that this company is not the "dead duck" it has been since the start of 2019 with regard to increasing bottom line profits each year - fact is with next years good growth (if they hit) they will be l £300k above the profit they made in 2018 with 20% more shares in issue - thats still a move backwards overall.
Re £PMP - I agree most of your points but I am more than content because I think even a recovery to previous sales levels will leave it with sales of a higher quality/margin and with a better platform for further growth than in 2018 (as much more DTC and digital) ie it will have made the jump to the new age of internet selling and is a better business. This more than offsets the dilution.
I also think the cost pass through pricing increases will be retained even as (some) supply chain costs drop back because it was over discounting before and the product range is better.
The 2 together will make a big difference to final profit in the medium term.
My mystical view is thus a further small rev beat even vs today's update, that will deliver a small profit beat this year but show they are on the way to a much bigger one next with a return to strong dividends promised. On a narrowly traded share, a few buyers based on this will drive the price up - but as ever, we will see! No one knows the future for sure.
Most mystics are portrayed as living in rags for a reason
£PMP
Rmillaree - 'optimistic bods' - Oooh! That stings. But guilty as charged I expect.
However.
Last 12 months revenue actually comes in at £99m.
They used the wording 'strong sales' in the update - which I don't take to mean less than last year?
They may have lifted the guidance to £95m but unless they are expecting H2 to be worse than last year - thats still conservative.
I think I can understand where they are coming from. At this stage all of the wholesale export orders have been shipped. Which leaves the direct orders (UK, US and Canada) which are an increasingly important part of their mix being higher margin.
After the last 2 years I can see that just about anything might happen in the next 6 weeks - but PMP have a remarkably consistent seasonality over the years. Based upon the H1 sales and the seasonal weighting a figure of £104m was calculated on a thread in another place - which I shared here.
Looking at the trailing 12m I'd be disappointed with anything less than £100m. Not so far from the £104m and closer than the brokers £90m was until today.
But call me 'optimistic bod' by all means. Thats not unfair. Like you I recognise that PMP has serially disappointed in the past and it will take time to build trust in the new management and new operations. Which might also be why the management is being ultra-cautious, I would be if I was making the statement.
cheers
Portmeirion (LON:PMP) (I hold)
brief comment on today's positive trading update.
Good to know that energy costs were fixed in H1 this year through to 2024. Management do seem on the ball here and a quick google reveals stories on reducing energy costs and switching to renewables (wax lyrical) across the group.
Revenue upgrade to 95m is fine as far as it goes. The wording 'strong sales' implies at least in line to me but ttm revenue is 98.99m so it still seems cautious to me. I expect that this uplift is based upon the global export orders all now shipped - and not on the UK and North America (Nambe and Canada) direct sales channel. Direct sales have been trending upwards strongly - assuming this continues - then I anticipate further revenue growth and also some margin improvement as direct sales are higher margin - and a further trading update shortly after christmas.
cheers
The Volex (LON:VLX) RNS reads well but as IGPJ points out there are a few cracks in the report that suggest the integration of the new acquisitions is taking time. To be expected but it’s a bit of a wake up call for a company based on a “buy and build strategy”. Still, share price seems to be clawing back some of the early mark down and despite the fall shares are only back to where they were on about October 7th. As mentioned on another post a couple of days ago noteworthy that the shares were already being marked down recently ahead of today’s official news release.
Gus.
Paul. Your thoughts on today's Trading Statement by Volex (VLX) would be very welcome.
Price action this morning has been pretty awful to say the least! :(
I had a quick look at Volex (LON:VLX) and expected a good reaction. Having thought about it though the update was only in line with previous guidance. So it would seem the share price had gotten ahead. No change in the story though so am holding.
Perhaps there were a couple of hints re the Volex (LON:VLX) share price fall in their update today, including this comment:-
“Mindful of potential for disruptions caused by global component shortages and shipping issues however, at present, continuing to successfully manage these risks.”
Also note the references to excellent long term prospects. Perhaps a strong hint there that they are less confident short term?
Ref Volex (LON:VLX) having had a quick look at the numbers I think they all looked good - in line, with a positive statement from the Chairman regards the longer term potentials.
Imagine my surprise when I logged onto my HL account to see them down 12%. I cannot make head nor tail of these markets.
I previously chose not to invest in Halfords (LON:HFD) after a recent visit to a store and getting some feedback from staff regards product availability. Only to see them go up by 20% yesterday.
I give up, time to hibernate and not look at anything for a few months......................
£VLX - There's loads of problems in the numbers in my opinion that elevate risk:
Declining margins
Gone from cash positive to negative
Increase in receivables and payables
Company gives lots of excuses but they wouldn't be the first to have plausible sounding explanations that turn into structural issues - market it saying there's heightened risk here.
Company doesn't seem to have done anything with the acquisitions other than just buy them, they don't appear to have done anything to integrate or consolidate them and with another three acquisitions on the way I think some people are nervous about this.
On a FY23 forward P/E of 22 I think the price has got ahead of itself for what is, essentially, a low margin manufacturing business.
Edit: I sold 1/3 of my holding Tuesday for £4.52 and just sold the rest at £4.11 - overall a 50% gain in 12 months. Would look to buy back around £3.75
£vlx i think the market wasn’t too pleased with margin dropping from 10% to 9%. With hindsight this could have been predicted, as they previously announced they would pass through the increase in copper price to customers. It’s a mathematical thing innit…
Same with flip from net cash to net debt. 3 acquisitions. This should begin to reverse at YE unless the make further buys.
The trader in me should have been awake to this earlier in the week!
Well, the other thing I would say, and I hasten to add there's two points that need addressing before I do so; 1. I'm an idiot 2. this is anecdote not data so treat accordingly:
The market in my experience doesn't like buy and builds after the first couple of purchases. As the acquisitions rack up the numbers get harder and harder to interpret and it becomes more challenging to work out what's going on. The previous buy and build company I owned, RPC, ended up having a management buy out, the price stagnated over a couple of years and the reason was put out that was because the analysts couldn't see the "clean" accounts.
I'm not a very good predictor of the future but I can see a world where the VLX share price doesn't move much as the big investors have difficulty valuing the business as it gets bigger.
I share your surprise on the share price movement on Volex. But have only scanned the headlines so far. I will now have a detailed read through and try to spot what I have missed. Perhaps Paul will give us his views on it. There is a presentation later this morning in Investor Meet too.
Regarding Halfords, my son is in the bike industry and there are currently great shortages of bikes and parts. It predates present supply chain issues, and goes back to the initial Covid lockdowns in China, and a heavy demand for bikes at the start of Covid over here when everyone became nervous of using buses, trains and tubes. I don't know anything about Halfords, but suspect their issues are those common to the every bike shop at the moment.
Winter beckons. Spring awaits - next year of course.
Par for the course I'm afraid.
The best listed company managers will try to manage market expectations such that they have some wriggle room.
This means there are always some investors hoping for an upgrade to guidance come the next opportunity for the company to comment on the outlook. If the company reports "in-line" then there are some shorter-term holders who may be disappointed. You get into "better to travel than arrive" territory.
This share was 250p a year ago, so a matter of perspective?
What are your thoughts?
Gulf Marine Services (LON:GMS) another contract renewal looks interesting for 2022 numbers
Agree. Only thing I'd add is that contracts were for the S & K class vessels, which are their small & medium size vessels, which usually have pretty high utilisation rates anyway (usually about 80 or 90% from memory). It's their large E class vessels that I'm hoping they get some nice juicy, improved rates contracts for as that would really move the dial. I think their E class vessels usually have a utilisation rate in the 70% range so would make a big difference to bottom line if they hired those vessels out more at a higher rate. Having said all that, the encouraging news today for me was the higher rates bit. That's a good sign.
BOTB have fallen from grace somewhat but in our feckless society where huge sums can be given away without any effort made they seem to have found a healthy hole. As such I am topping up as their fall from grace has allowed another chance to get into this cash cow.
Best Of The Best (LON:BOTB) Unfortunately Camtab you make a very valid point ' in our feckless society where huge sums can be given away without any effort made'. It's a sad reflection on the position we are in from the very top to the bottom of the ladder.
Best Of The Best (LON:BOTB) - see expanding a bit from cars into a flight in a spitfire wow - but just don't like spot-the-ball - it's too random - a bit like my stock picking system.
Re: Best Of The Best (LON:BOTB) what I've never understood is why the results are decided by a judge rather than where the ball actually was!
Best Of The Best (LON:BOTB)
"I've never understood is why the results are decided by a judge rather than where the ball actually was!"
It's so that no-one can find the still image from the game and cheat.
Also, then it isn't a game of "skill" so it might not escape gambling/lottery rules...there's plenty on this topic online (and on this website) already if you wanted to know more here.
A
Ted Baker (LON:TED) interims and Q3 update interview with Rachel Osborne, CEO and David Wolffe, CFO. Margin improvement through improved product mix. Revenue +17.6% , still loss making but turnaround on course, and cash position better than anticipated at 12.7m. Video & podcast.
Separately, join us for webinars:
Tracsis (LON:TRCS) FY21 results webinar Friday 12th November, 1.30pm. Register here.
Ig Design (LON:IGR) H1 22 results webinar, Tuesday 23rd November, 1pm. Register here.
Tpximpact Holdings (LON:TPX) (formerly The Panoply) H1 22 results webinar, Thursday 2nd December, 11am. Register here.
Morning Paul and Jack. Would be great to get your views on Ienergizer (LON:IBPO) please (I hold). On first view results look good, with improved revenue and profit plus new contract wins, having handled COVID / working from home well.
Good morning,
Yes, excellent interim results from £IBPO. Revenue, profits and margins up. Nice 40% increase in interim divi.
13p EPS for H1, say 26p for FY would mean current PE of 10 for this year. Cheap!
Thanks for highlighting this one.
Slightly alarmed (given their area of expertise) at the "About" bit of their website which appears to have been hacked...(don't click on the embedded link...I've not checked it)
"Our BPO capabilities help companies increase operating website that writes essays for you efficiency through cost-effective, value-generating customer contact and back-office processing centers."
Apparently they do the moderation for Roblox....I think my kids will be banned from the chat function for a little while longer.
The AIM/Guernsey nexus is one that demands extra due diligence, and I'm not sure I know enough about the Indian labour market....but interesting.
[Edit] Portmeirion (LON:PMP) guides FY rev at least £95m, 5% above FY21 consensus. No material profit hit from energy cost rises.
Jack, Any chance of your views on the trading statement from M Winkworth (LON:WINK) issued today? You covered their interim results on 8th September quite favourably and I wonder if your opinion remains the same now.
A relief to see Tremor International (LON:TRMR) report good progress today (I hold). Adtech has had a volatile run down from ATHs on both sides of the Atlantic - most recently with AcuityAds taking a beating following recent results. For those companies that continue to innovate and consolidate the industry, there is a seemingly massive addressable market with very high levels of profitability. I have been betting on TREMOR, with a large cash holding, being one of the global winners. It will be interesting to see how the market reacts given sector sentiment presently.
Tremor International (LON:TRMR) results were extremely good, beating expectations by 15% at a profitability level that they set just 3 months ago.
looks like EBITDA will be around £110m+ now for the full year. Given the £225m cash pile it is still only on 9* EV/EBITDA, miles off its competitors valuations.
I see broker has upgraded expectations again and revised price target to 1700p from 1400p
Another point made by finncap on Tremor International (LON:TRMR) is about consolidation in the industry. As they point out, Tremor International (LON:TRMR) is cash-generative and relatively cheap. That means it has opportunities as a consolidator itself and potentially as a target. I think they mean because the EV is lower than market cap, it's even cheaper than it looks.
The track record on acquisitions is good - buying Unruly completely transformed the business. I'd back the management to use our cash wisely, if they do find other opportunities. I don't personally believe the new 1700p target is likely within 12 months but would be delighted with 1400p as suggested previously.
The reason Tremor International (LON:TRMR) is cheaper than it appears is for 2 reasons
1) The net cash position of £225m+
2) There is a lot of depreciation currently coming through the reported numbers that relates to the historical mergers and acquisitions. This masks the true profitability of the operating business in the reported EPS number and therefore the PE.
I imagine at some point this is going to get a bid. It is earnings enhancing for competitors at anything below around 20 * EV/EBITDA which is circa 1700p, so I guess that's where the brokers target is broadly pitched. That may well be elevated but it does appear particularly cheap to me at 9* though.
Tremor International (LON:TRMR) selling off a little today. It is a volatile share though. I was planning on a top-up but the persistent director selling is very off-putting. They seem to be slowly disposing of their stakes. (Incidentally the Stocko data is incorrect, it claims CEO Ofer Druker's stake is zero - but he retains 1.84% after today's sale. It looks cheap on the financials, but I find it difficult to invest with conviction when key directors continue to off-load.
I also fear a NASDAQ correction would hit Tremor International (LON:TRMR) quite hard. Any thoughts from fellow holders?
These don't look like large disposals to me. The sums look like typical lifestyle and tax bill quantities taking advantage of the post-earnings boost and end of pre-earnings lock-up, although I agree their regularity raises questions.
Tremor International (LON:TRMR) Had a quick look at directors sales, these seem to shares they got in September for nothing. That's not the same as buying the shares and then selling them. They may need to sell some for tax reasons and usually free shares are treated as bonuses.
Quite a fall today down 14%. I don't hold.
What a hopeless update from Best Of The Best (LON:BOTB) . From the below paragraph, we're sent in four directions to try and uncover the referenced info. Why not just share the figures instead of sending us on a wild goose chase?
"The Company reports that financial performance for the period is in line with
the market guidance issued on 13 August 2021. Customer acquisition costs have
stabilised, albeit at the higher levels previously reported. Engagement from
the enlarged player base has also normalised, with average order values and
frequency similar to pre-pandemic levels. Trading for the period has,
therefore, been consistent with management's revised expectations."
Their trading updates are never the clearest and I think a lot of us were wanting a trading above guidance update today. However, this is still essentially an 'in line with expectations' update. The company has lost some credibility with shareholders because of the fall in revenue in this financial year (FY22) so far which the company hadn't managed expectations on following FY21 stellar results. But putting emotions and last year's one off resultd to one side this is still a rapidly growing business - the company said in August that 'The Company's revenue is c.2.5 times higher than the corresponding period in FY 2020, the pre-Covid comparative year.'
Where can you buy that kind of growth for a p/e of 12?!
In the same way operational gearing means EPS expectations this year are much below last year, even modest future growth could mean rapidly growing profits.
£BOTB
“Their trading updates are never the clearest and I think a lot of us were wanting a trading above guidance update today.”
They never are and that is why they are uninvestible for me. That said I am an ex unhappy holder who got badly by the profit warning.
Games Workshop (LON:GAW) are similar. Dreadful almost arrogant updates, which is why I offloaded a quarter of my holding at around £12. It should have been more.
Regards
Michael
Best Of The Best (LON:BOTB) (I hold)
"What a hopeless update from Best Of The Best (LON:BOTB) ."
I couldn't agree more. It was almost a pointless update.
---
Revenues: I have no idea. I had assumed £18.5m from previous commentary, but again, I was hoping for some numbers today,
COS - this should be c£8.1m for any interested
Marketing - It's good to hear that CAC has stabilised. It would certainly have been useful to know how much the company actually spent on marketing though.
PAT - for reference, I think this will be c£3m for H1, and there's often a H2 weighting too. FY22 forecast's are currently for a PAT of £5m.
----
On a related note, I'm starting to see signs of recovery from other companies (eg Zynga) that were hit by the Apple iOS changes earlier this year (which I am assuming was the main unpredictable issue for the company, beyond the more predictable post-lockdown spending-less-time-online issue.)
So hopefully that CAC will come down soon and growth can return to pre-2020 levels (if they haven't already - who knows?)
A
Interim results out for Volex (LON:VLX) and Frp Advisory (LON:FRP)