Small Cap Value Report (Thu 12 Oct 2023) - YOU, RTN, MCG, SPSY, SHI, HOTC

Good morning from Paul & Graham!
Today's report is now finished.
Graham's 11:30 video (also recorded) - featuring Mobico, Restaurant Group, and SIG starts at 11:30 - these are great I think, so I'm tuning in every day! It's like a video/podcast version of the SCVR, and is free, so if you have the time you might like it!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Summaries
YouGov (LON:YOU) - 880p (£1.01bn) - FY 7/2023 Results - Paul - AMBER
Superb figures for FY 7/2023, and lots of positives in the outlook comments too. I rummage through the numbers, and flag up some aspects I'm less happy with, so you can make up your own mind about whether these matter to you or not. A huge acquisition pending will take the balance sheet from net cash to heavy net debt, so they have to get that right. YOU has made tremendous progress over the years, building a much bigger, global business, with lots more to go for, so I definitely wouldn't bet against it.
Restaurant (LON:RTN) - up 37% to 66.4p (£507m) - Recommended cash acquisition of RTN - Paul
Bunting out for shareholders here, with a 65p cash bid from US private equity giant Apollo. It's a very good offer I think, for a struggling, over-indebted hospitality group with a terrible long-term track record of shareholder value destruction. Although its life-raft acquisition of Wagamama is now very much the jewel in its crown. Is this a one-off, or do we need to re-think our attitudes towards the hospitality sector? Discussed in more detail below.
Mobico (LON:MCG) - down 20% to 67.7 (£416m) - Q3 trading update (profit warning) - Graham - AMBER
This has been an awful long-term investment and shareholders have woken to another profit warning this morning. Passenger growth is weaker than expected and costs are higher. I review various factors and conclude that Mobico bonds are a more interesting investment.
Spectra Systems (LON:SPSY) - up 6% to 190p (£81m) - Largest Central Bank Consumables Order - Paul - GREEN
A nice update here, with more detail in a helpful note from WHI. Forecasts now seem very well underpinned, with the chance of beating expectations dangling in front of us I think. I remain bullish on this GARP share with a generous yield, strong balance sheet, and quirky high margin niches. At last the market seems to be noticing that it's doing well, with a modest share price rise of late.
SIG (LON:SHI) - down 14% to 29.3 (£350m) - Q3 trading update (profit warning) - Graham - RED
It was a marginal decision but I’ve decided to go red on this. Profits are trending towards the lower end of market expectations: the company has seen soft demand from Europe and is shrinking in real terms. It now needs cost savings to help it produce a reasonable result.
Hotel Chocolat (LON:HOTC) - up 9% to 142p (£195m) - FY 6/2023 Results - Paul - AMBER/RED
I've moved up a notch, from RED to AMBER/RED. Why? Because the Q1 (Jul-Sep) current trading section contains some nice positives - strong LFL up 13%, better margin, and cost-cutting. That should improve FY 6/2024 profits considerably from the collapse in profit to only breakeven in FY 6/2023. Balance sheet looks robust. But why is the market cap nearly £200m, for a business with such a poor track record? Definitely not for me.
Paul’s Section:
YouGov (LON:YOU)
880p (£1.01bn) - FY 7/2023 Results - Paul - AMBER
YouGov, the international research and data analytics group, announces its results for the year ended 31 July 2023.
- Strong performance amidst a difficult trading environment
- Confident in the Group's prospects for FY24 and meeting current market expectations
It’s been a few years since I looked at YOU. The shares have been very successful, so it’s one that slipped through our net when it was a small cap. I remember (this is c.2016-17) always complaining that its accounts were too aggressive, with heavy capitalisation of intangibles, resulting in little genuine profit pr cashflow. The shares also always looked very expensive. On reflection, clearly there was something good about the business that outweighed those factors, so my caution turned out to be wrong.
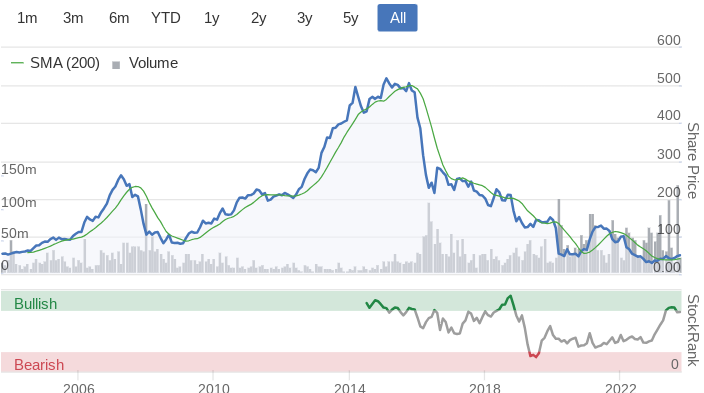
As you can see below, it roughly 30-bagged from 2010 to the highs in 2021, albeit with a big downward correction since - opportunity or a new downtrend, who knows, only time will tell!
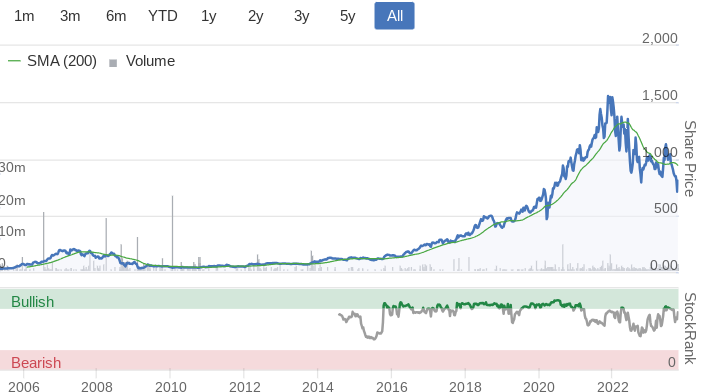
In the shorter term, there was an explosive upward reaction to recent FY 7/2023 results, although this was largely recovering a recent spike down - here’s the year-to-date (YTD) chart for 2023 -

Quite a few companies have charts looking like this - with even “in line” results triggering a big rebound in some cases - cause for optimism maybe, or just a short term rally in a downtrend? We’ll find out over the next year or so.
What does it do? A nice clear self-description here -
YouGov, the international research and data analytics group, announces its results for the year ended 31 July 2023.
The FY 7/2023 figures are really impressive, here are a few key numbers -
Revenue £258m (up 17%, of which 9% is organic, and 8% from acquisitions)
Adj PBT £56.4% (up 63%, nearly all from organic growth)
Statutory PBT £44.7m - this is the figure I’m using, as I think the adjustments are disallowable, being almost all share-based payments, which I regard as an operating cost (staff & management remuneration). You don’t have to agree with me, that’s just my personal interpretation.
Adj EPS 40.5p (up a very impressive +71%)
Statutory EPS 31.5p (up 100%)
PERs are: adjusted PER 21.7X, and statutory PER 27.9x - not necessarily expensive, given that it’s reporting huge earnings growth, the big question is whether growth continues? If it does, then the relatively high PER could be worth every penny. The high PER in the past turned out to be fully justified, after all.
Net cash is very healthy, at £107m, boosted by £49.8m placing recently (July 2023), as part of the financing to fund a pending, very large acquisition - part of GfK. This is a key point that investors need to research carefully, as it’s so material to YOU, and will result in substantial net debt, so this acquisition has to work.
Outlook comments - positive. Confident in meeting FY 7/2024 market expectations.
Current trading in line. Improving trend from tech customers (who had cut back previously). New CEO from Aug 2023 - another key area to research - eg background, track record, strategy, etc.
Plenty of other positives mentioned - eg demand strong, sticky client relationships, new business momentum, high customer renewal rates.
Operates globally, with US biggest market, second is UK, third is Europe, fourth Asia. So it looks like plenty of market share to go for, as individually quite small in large markets I’d say.
High margins.
Total number of people on its opinion panels: 25.7m! I’m actually on its daily political views channel as a panellist, and I have to say the questions are usually ludicrous - asking ordinary people for opinions on complex geopolitical issues that the vast majority won’t have a clue about. The only intelligent reply is "Not sure", which I usually select, buut few others do. But that’s the social media world of today - everyone has a strong opinion, and speaks like an expert, despite being totally clueless. The result? Actual experts are drowned out by the background noise. Sorry, that’s one of my pet hates, let's move on.
Back to YOU, and I’m certainly impressed by the long list of positive aspects of this business summarised above.
Capitalised spending - an issue in the past, and it’s still aggressively accounted for. The cashflow statement shows capex was only £1.1m of physical items (office furniture and computers, I imagine), whilst development spend capitalised was hefty at £9.0m. Also panel recruitment costs of £7.3m were capitalised, which personally I would prefer to see fully expensed as incurred. At the very least, EBITDA is meaningless.
I’m only flagging this as something for you to consider, and make up your own mind, as there are different ways of viewing this, and of course YOU are within accounting standards (which in practice give a wide range of possible interpretations of profit!), so there’s nothing untoward in capitalising these costs, it’s allowed. Personally I would manually adjust things out, to be more prudent.
Employee shares - note that £10m pa cash is spent buying shares to be given to employees on share option exercises. Is this reasonable? I would say no, since the context is that it paid only £7.7m to shareholders in divis. So it’s a fair question to ask - whose benefit is this company actually being run for? Looks like it’s mainly staff and management to me. I'd want to see the ratio change in favour of shareholders, whilst also recognising that share options can be good for attracting & retaining key staff - providing management don't hog them for themselves! Although if the share price keeps going up, does any of this really matter?
Balance sheet - NAV of £196m, is mostly £114m intangible assets - although you could argue some of these do actually have some real world value.
The pending acquisition of part of GfK will radically change the balance sheet though, with net cash about to turn into hefty net debt, and NTAV will turn negative I think, due to the goodwill. So investors need to carefully check the big acquisition, as it’s making a dramatic change to the balance sheet.
An RNS from 2/10/2023 details the new 280m Euro bank facility to fund the bulk of the 315m Euro GfK consumer panel acquisition (awaiting competition clearance currently, I believe).
An RNS from 6/7/2023 details the rationale for the GfK acquisition, saying it’s an EU required disposal due to a larger deal, an argument being that YOU has achieved a good price for the purchase as it’s been forced. Revenue of 134m Euros, and adjPBT of 24m Euros don’t strike me as a bargain, given YOU has agreed to buy it for 315m Euros. Is this really a good deal? It might be, but I’m just raising a question mark for further digging. It does mention 4m Euro synergies, which helps.
Cashflow statement - the £69m (same in both most recent years) cash generation figure is fantasy, as it ignores capitalised internal costs, and tax. After those real world cash costs, it’s £42m cash generation. Then £3.2m leases rent, and £9.8m purchase of treasury shares for employees needs to come off that figure. So we’re looking at £29m cashflow remaining - not that much for a £1bn market cap company I suggest.
Paul’s opinion - I’ve only reviewed the numbers remember, not done a massive research job on the business itself.
There are lots of positives here, definitely. I can see why some investors like this share, and are prepared to pay top drawer for it. And that’s certainly worked in the past!
I’ve flagged up some negatives above too, so people can make your own mind up about whether or not those matter to you.
Based on just an initial review, I’m happy to go with AMBER, with a slight leaning more towards the positive side on fundamentals, but less keen on the high valuation, but you have to pay up for quality and growth (and then keep our fingers crossed that nothing goes wrong!)
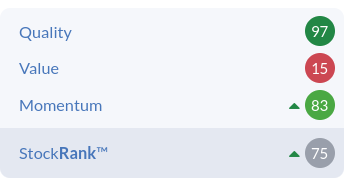
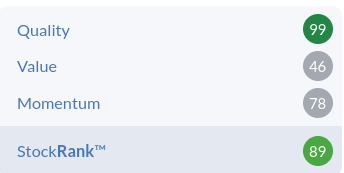
Stockopedia neatly sums it up - great quality, but expensive -
Categorised as a "High Flyer" here -
Restaurant (LON:RTN)
Up 37% to 66.4p (£507m) - Recommended cash acquisition of RTN - Paul
A huge surprise here, I thought the struggling hospitality sector would be one of the last places to see a takeover bid! Lots of bids are happening, but mostly for tech, and healthcare, and structural growth companies. So a struggling, low margin highly indebted restaurant operator seems a strange bid target. Maybe we need to re-think things? Could this be a sector to focus on for recovery, and more deals maybe? Or will this turn out to be a brave but foolish mis-step for the bidder?! Who knows.
Key points -
Bidder is Apollo, a huge American private equity firm (>$500bn assets under management, according to Google) - so this is a tiny deal for the bidder.
Management have agreed this deal, having negotiated improvements on 3 previous offers - well done management, this looks a more than fair price to me.
Price is a 34% premium to yesterday’s price, and shares have been in an improving trend of late.
Valuation (enterprise value = market cap + net bank borrowings), which is customarily done on an EBITDA multiple, is 9x - seems quite a full price, given macro conditions.
Only 19.9% support so far.
The market price has gone to a slight premium today (66.4p at 09:41 on high volume >26m share trades printed, with probably plenty more working in the background and not yet printed). So it looks, at this early stage, as if the market considers there’s a small chance of a higher bid emerging - could get exciting!
Paul’s opinion - I definitely didn’t see this coming! What a surprise. Reading the RNS, it seems Apollo is attracted to RTN’s scale, potential for further expansion, quality of brand (Wagamama is the main one), and good management - not everyone agrees with that, including activist shareholder(s).
They don’t seem to be put off by RTN’s terrible long-term track record of shareholder value destruction, low margins (although planned to increase in the medium term) and excessive debt!
It will be interesting to see if investors see read-across to the small (and tiny) listed restaurant groups at our end of the market? Hostmore (LON:MORE) shares are up 6% as I type this. I’ll take a fresh look at MORE once it’s refinanced, which is in progress, currently making it uninvestable for me personally, with that uncertainty (over dilution/solvency) hanging over it.
The nano-cap restaurants like Tasty (LON:TAST) (far too small to be listed, struggling) and Comptoir (LON:COM) (doing a bit better of late) don’t interest me as a bombshell delisting announcement could come any day and wipe out half the little remaining value. So they’re option money only. TAST’s format is very dated (although the fit-outs are nice), and it’s still struggling with uneconomic leases. I visited a COM in the summer, and it’s actually a nice & distinctive format, so that’s the only one I would even vaguely consider investing in. But as with all shares, anything can happen!
I wonder if this RTN deal might trigger wider interest in pub groups too? I’ve been meaning to look at Marston's (LON:MARS) actually. The highly indebted ones could be restructured by deep-pocketed private equity owners, perhaps making them attractive bid targets?
Another idea that occurs to me, is that with food inflation falling now, and energy prices becoming more reasonable, then possibly 2022/3 could be the low water mark for margins in hospitality? Apollo’s bid interest in RTN is perhaps flagging this as a possibility - something for us to think about!
Anyway, well done to any RTN shareholders here, swimming against the tide and ignoring the risks has paid off! ;-)
Spectra Systems (LON:SPSY)
Up 6% to 190p (£81m) - Largest Central Bank Consumables Order - Paul - GREEN
This is light on specifics, but sounds encouraging - this is the announcement in full, as it’s fairly concise -
Spectra Systems Corporation, a leader in machine-readable high speed banknote authentication, brand protection technologies and gaming security software, is pleased to announce that one of its long-time central bank customers for banknote security materials has placed a new order for the year ending 30 September 2024 as part of the five-year contract, which was entered into in 2019.
This consumables order is the largest in the Company's history and approximately 60 per cent. larger by value than the order for the year ended 30 September 2023.
Dr. Nabil Lawandy, Chief Executive Officer, stated: "I am very pleased that we have received such a large order incorporating the 22 per cent. price increase which was agreed last year when we solved our customer's supply chain concerns. This order makes a meaningful contribution to achieving our expected profitability this and next year."
There’s not much specific detail there. Has there been a broker update to help us?
Yes, a hat tip to W H Ireland, whose update note is very helpful, saying that today’s update “all but guarantees” FY 12/2023 forecast revenues & profit, and “injects significant visibility” into FY 12/2024 forecasts.
WHI emphasises that its forecasts are based only on “highly predictable revenue only”, giving a “high level of confidence” in its forecasts. I like that a lot, as it suggests the likelihood of a profit warning should be low, and maybe we might even see a beat against forecast? SPSY seems to operate on a shoestring, with low overheads, so more contracts seems to drop through nicely to profit.
Paul’s opinion - I’ve repeatedly flagged this share here, as a reasonably priced, well financed, generous dividend-paying GARP share. Today’s update adds to my confidence, so I remain an enthusiastic GREEN. The share price seems to be edging up a bit, whereas usually the good news is ignored in this small caps bear market. I think patience could pay off eventually with this share, providing nothing goes wrong of course, as with everything, which we can’t predict. Hence why we have a portfolio of shares, and accept the risk that the odd one disappoints from time to time.
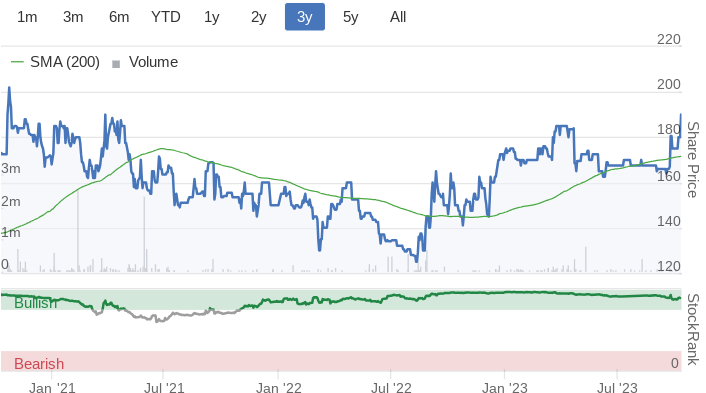
The StockRank system loves it too! I always like to see my analysis confirmed by the computers, and it makes me think again if the StockRank is low -
Hotel Chocolat (LON:HOTC)
Up 9% to 142p (£195m) - FY 6/2023 Results - Paul - AMBER/RED
A neat little summary here at the top of the announcement today -
Hotel Chocolat Group plc, a direct-to-consumer premium chocolate company, today announces its audited full year results for the 53 weeks ended 2 July 2023 ("FY23") which are broadly in line with market consensus and in addition provides a trading update for the 13 weeks ended 2 October 2023 ("FY24 Q1") highlighting the significant progress made against its strategic priorities.
Very poor results for FY 6/2023, but this was flagged earlier this year, in 2 profit warnings. They call it a “transitional year”, which I can translate as, the year we totally screwed up almost everything. That was after a giant mess up in FY 6/2022 over its Japanese operations, which required a £30m exceptional charge.
It’s an underlying loss before tax of £(0.8)m for FY 6/2023, which after exceptionals becomes a statutory loss before tax of £(6.9)m.
Balance sheet - the good news is that solvency & dilution risk are slight - the one good thing management did was to raise loads of equity, and it’s still in a nicely comfortable position, with cash of £11.2m, and no interest-bearing debt. Leases are not debt, so shouldn’t be on the balance sheet at all. Rents are just future operating costs, much like business rates, and shop staff wages, which of course are not on the balance sheet, so IFRS 16 is total nonsense.
Although interestingly, IFRS 16 can point us to whether a company has loss-making sites (in which case the lease liabilities exceed the right of use asset - have a look at Superdry (LON:SDRY) to see a really, really bad case of this - indicating many of its sites must be bleeding cash like no tomorrow, which there probably won’t be once its latest cash injections have worn off).
HOTC seems to have almost balanced lease entries, which suggests to me it’s probably the central costs that are too high, not the store leases being a problem - a good thing.
Inventories still look far too high, but have come down somewhat. This might be since HOTC is vertically integrated, making the chocolate itself, which would tie up cash.
Cashflow - looks fine, until you come across the whacking great £11m lease cash outflows figure, which absorbs about three-quarters of the whole group’s cashflow. Capex of £9.8m is eating into cash reserves, which fell from £17.6m a year earlier, to £11.2m now. So I think if it cannot improve cash generation, then HOTC won’t be able to safely open more new sites.
Outlook - this is where we get some good news!
I’m encouraged by the Q1 update, with some much better figures, indicating that turnaround actions do seem to be making some headway -
Q1 (Jul-Sep 2023) - LFL stores revenues up an impressive +13%
Gross margin also up, thanks to less discounting, up 6ppt (which I think means going from say 50% to 56% - made up numbers, but that’s my understanding of their terminology, leave a comment if you think that’s wrong!)
Cost reductions made.
Too early to give guidance for FY 6/2024 - oh dear, they could have given a basic, conservative, wide range of guidance, instead of saying nothing.
Liberum does have a stab at forecasting, and pencils in £4.2m adj PBT for FY 6/2024. That looks sensible to me, given the upbeat Q1 comments, from a broadly breakeven year for FY 6/2023.
I’m going to ignore its following years forecasts, as these have tended to be wildly optimistic in the past, but for the record are £11.8m and £15.2m PBT.
Paul’s opinion - I’ve previously turned RED, on the 2 profit warnings earlier this year. But given today provides some evidence that things are starting to improve, then I think it’s only fair to move up a bit to AMBER/RED.
If HOTC was valued at say £40-50m, then I think it would be worth a punt for a recovery.
The trouble is, the valuation is sky high, at £195m, and for a share that historically the market has wildly overvalued, and been repeatedly proven wrong when it disappointed.
I can’t get anywhere near that valuation, as it has to execute well (as opposed to really badly in the past), just to come close to justifying today’s valuation.
Above all, every time I’ve tried the product, it’s seriously disappointed me - it tastes horrible, and is wildly over-priced, in my opinion. Fancy packaging, and store fit-outs don’t result in me wanting to buy the product. Some people like it though, but not enough for the company to actually make any profit at the moment.
So definitely not for me, and I think risk:reward currently looks very poor. But that could change in future, so we’ll keep an eye on it.
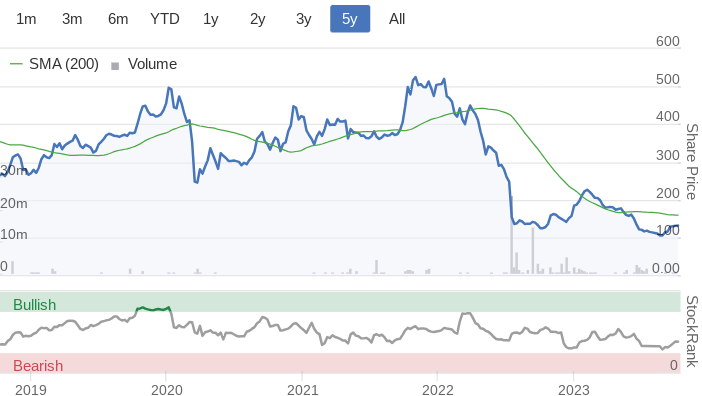
There's been about 21% dilution from new equity over this period, so not too bad at all. Hence a return to previous profitability could see this share sparkle again maybe? We've got to consider all possible outcomes!
Graham’s Section:
Mobico (LON:MCG)
Share price: 67.7p (-20%)
Market cap: £416m
National Express changed its name in June; it’s now “Mobico”.
But this probably won’t help long-term shareholders forget what they’ve suffered here. This was formerly a mid-cap, but it’s now in small-cap territory:
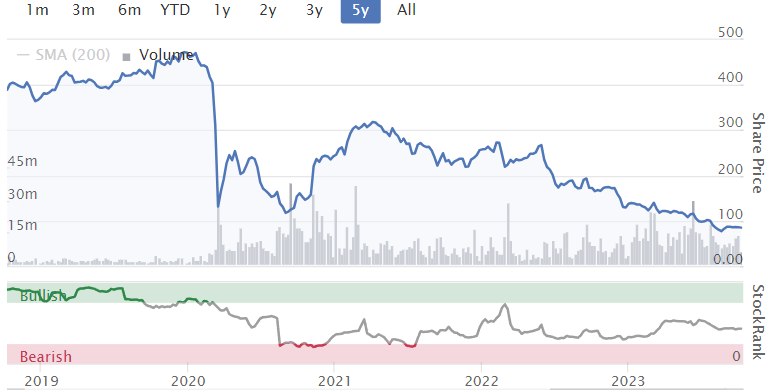
Perhaps it makes sense that National Express would fail to recover to its pre-Covid valuation, with former commuters now spending more days working from home?
Unfortunately, today brings a fresh profit warning.
The headline is:
Full recovery in profitability taking longer to deliver; decisive action being taken on our cost base and to accelerate deleveraging
Here are the key points:
Revenue up 10%; but costs are up, too.
2023 EBIT expected at £175m - £185m (previous guidance: operating profit of £200m - £215m). So the profit forecast has been cut by about 12%.
Cost reduction programme has delivered £15m of savings for 2023; will deliver £30m annually from next year. A further £20m of savings are targeted.
Looking to sell the North America School Bus business (paradoxically, selling this business will enhance growth for Mobico).
Dividend suspended.
The yield had become rather large with this share. A reminder that it can be risky to count on large dividends:

CEO comment:
"We recognise that the recovery of our profitability will take longer than we had previously expected. That is why we are announcing decisive actions to ensure we deliver sustainable profitability from our growing revenue base. Whilst our belief in the potential of the Group remains strong, we will move at greater pace with new leadership teams in the UK and North America.”
There are new CEOs at Mobico’s UK/Germany and North America businesses.
Some other key points:
UK Coach: revenues boosted by rail strikes. 12% of passengers who used them on a strike day for the first time decided to continue using them on a non-strike day. Q3 revenues up 26% year-on-year.
UK Coach Hire: two of the five depots will be closed due to their low returns. The remainder are under review.
UK Bus: passenger volumes at 97% of 2019. So almost a full recovery. But the growth in passengers is “slightly lower than previously anticipated”.
North American School Bus: driver recruitment, training and exam costs are above forecast.
Graham’s view
Paul reviewed the company’s final results back in March. Net debt then was £986m, or 2.8x EBITDA (an improvement from 3.6x). The company was anticipating “free cashflow of £1.25bn” by 2027.
Where are we now, in terms of the balance sheet? Well, the company recently (26 September) announced a €500m bond issue. These bonds were rated investment-grade by Moody’s and Fitch, carry a fixed coupon of 4.875%, and are being used to refinance existing debt. So all of that sounds very orderly.
I do note that the existing debt that is being refinanced is GBP bonds which only charged 2.5%. So while 4.875% might not sound too high, it’s a more than doubling of the prior interest rate.
Scrolling back further to the interim results, net debt was £908m (June 2023). Gross debt was £1.5 billion. The leverage multiple was still 2.8x, i.e. on the higher end of the spectrum.
With profits having been downgraded since then, it’s possible that the leverage multiple is now over 3x.
The company warned that interest charges would rise, both through higher bond coupons and higher rates on their bank facility:
2022: £51m interest
2023: £75m interest expected
2024: £82m interest expected
So that’s a hefty chunk of anticipated EBIT that will be eaten up by interest, e.g. there could be £75m of interest charged on £175m of EBIT.
I always think that it’s finely balanced when interest charges are eating up half of EBIT. It’s rare that a company will face that situation for long. Surplus cash flow should hopefully be used to pay down the debt, producing a positive snowball effect as the interest charges reduce. But if profits and cash flow take a hit, then things can quickly go in the opposite direction.
In this case, I think Mobico investors can take some comfort from the following factors:
Investment-grade credit ratings (of course the agencies are not to be trusted blindly)
Leverage multiple is probably around 3x, which is still respectable.
Bond investors were willing to refinance them at a reasonable price, although ECB rates are lower than BoE rates and I guess that will have helped. The company will need to manage its euro exposure carefully.
Forecasts suggest that the company is profitable, although after interest and taxes the bottom line is probably going to be quite small. Numbers below are before today’s £30m profit warning.
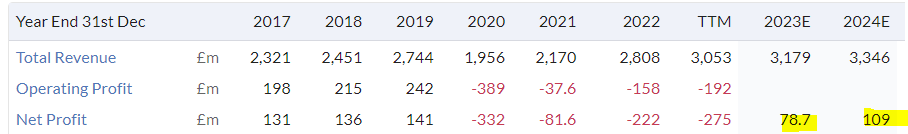
I’m going to have to take a neutral stance on this one, as I think it’s too soon to say whether or not it’s going to prevail in its battle against inflationary cost increases, weaker passenger growth than anticipated, and a large debt pile. If it does succeed, then the equity is priced to do well from the current level. But I think I’d rather own the bonds.
SIG (LON:SHI)
Share price: 29.3p (-14%)
Market cap: £350m
SIG plc… a leading supplier of specialist insulation and building products across Europe, today issues a trading update for the six months to 30 June 2023… in advance of the release of its H1 results on 8 August 2023.
Unfortunately this is another profit warning.
SIG is another large and complicated business that is active across Europe.
We last looked at it in Jan 2023, with Paul commenting on the company’s turnaround plan.
Today we learn the following about H1 performance:
Revenue is flat on a like-for-like basis at £1.4 billion. Volume declines offset by price inflation.
GN note: this means the company is shrinking in real terms. However, after taking into account acquisitions etc, SIG’s total revenues are up by 5%.
Other points:
“Challenging and variable” market conditions. Softer demand in May and June, particularly in Germany and France.
Underlying operating profit c. £33m
H2 to benefit from “ongoing productivity initiatives”.
Many thanks to the company for publishing the range of market expectations: underlying EBIT of £65.3m to £84m.
Full-year operating profit should be within but towards the lower end of that range.
Net debt at £176m (pre-IFRS 16, i.e. excluding leases) or £470m including leases.
The company reports that price increases from inflation added 9% to revenues. I’ve been using 8% as my inflation benchmark although hopefully I can start to bring it down soon, maybe to 6%. But as far as SIG is concerned, inflation is still running at 9%.
Outlook
We expect weak and uncertain demand conditions throughout the rest of the year, along with a continued, but further moderating, revenue tailwind from input price inflation. Whilst trading in recent weeks leads us to be more cautious as to the timing of any broad-based improvement in demand conditions, the second half will benefit from ongoing productivity initiatives as well as an expected profit on one specific property move.
Graham’s view
The outstanding feature of this one is its extremely low margins. I understand that it’s supplying the construction sector, where margins are unlikely to be very exciting, but the gross margin tends to run at only around 25%.
You then have all of the corporate and retailing apparatus on top of that, and it leaves the company with a wafer-thin profit opportunity. It makes sense that the company should focus so heavily on “productivity initiatives” - when you’re dealing with a profit margin like this, every pound and penny saved makes a huge difference to shareholders.
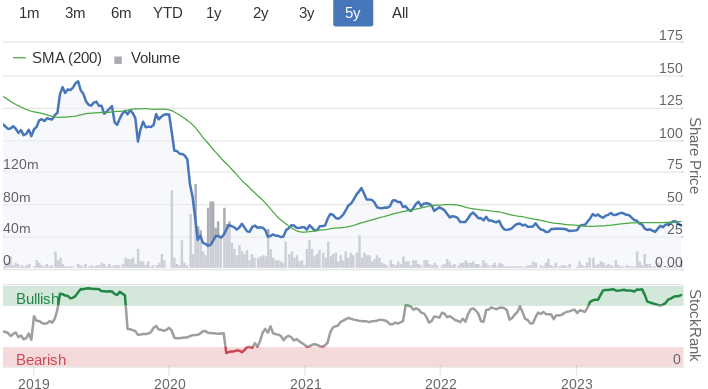
Is this stock offering value right now? If it is, I’m not seeing it. The market is pricing in improvements through cost savings:
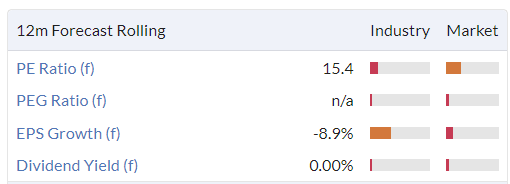
There are so many high-quality companies trading at reasonable prices, I just don’t see why investors would want to get involved with this one. There is considerable financial risk here, too, with substantial leases and borrowings.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

98 comments
Hi davis,
Thanks for the thought-provoking question! "Why bother with smallcaps"
I can answer you question in two ways.
Firstly, sector considerations - I have a particular interest, and have gained a lot of experience over the years, in analysing financial stocks, including small-cap and mid-cap financials. Typically with these stocks I am not hoping that they will generate extraordinarily high returns. But I do think that quality financial stocks can generate attractive and lowish-risk returns. So in summary, I like to fish in pools where I understand the fish and where even if they aren't the biggest and most amazing fish, I think I am reasonably good at catching them!
Secondly, on the question of exceptional companies - while I agree with you that the companies with the most impressive technologies and network effects (etc.) are larger, I also think that small-caps (and mid-caps) can enjoy these, too. When they are successful, these companies often graduate to bigger leagues (e.g. Games Workshop (LON:GAW) ) but that's only by enriching the small-cap investors who found them first. I do think mid-caps are more likely to have the traits I'm looking for in exceptional companies than small-caps, but we are covering companies with market caps of up to £1 billion here. The bear market has helped to drag many former mid-caps into this range.
Hope this helps to explain - thanks again for the comment! G
Halfords (LON:HFD) Talk of a takeover
"Betaville reported that there has been
takeover interest in the company."
Anyone know why Halfords (LON:HFD) spiking up?
Up 18% on IG, but cannot see a reason
Betaville.
Thanks, not familiar with this but looked on the website and couldn't see anything. Trade Volumes in last hour or so, dont seem to have ticked up lots?
Hi Andy - try this one then https://www.sharecast.com/news...
Thanks, I have just seen the RNS also.
Cheers
Hi Graham. Following Paul's positive comments on your daily videos I too have taken to watching and find them great. As you work through a stock I can almost see your the cogs in your brain turning! I've also re-watched your video "Most Shares Are Terrible Investments" which has prompted me to ask why you are drawn to the smallcap space in the first place. To summarise (badly) your argument in the video - a tiny proportion of stocks accounts for most positive returns and, held long-term, most stocks will show a small or negative return. Therefore, you advocate searching for stocks that display the traits of exceptional companies viz: proprietary technology, network effects, economies of scale, strong brand. But aren't smallcaps inherently unlikely to display these characteristics? I appreciate that Microsft and Amazon etc started small but to spot them as smallcaps would have involved taking risks that you advocate avoiding. So why bother with smallcaps, or am I missing something?
Graham is way smarter than Ill ever be when it comes to investigating companies, but I'll tell you why I do it. In 2009 I made over 200%, in 2020 165%, with several other 30-50% years. This is almost impossible with anything other than small /mid caps, at least for me.
There are periods when it's extremely difficult to make any money but as long as you can protect most of your cash pile during drawdowns, when the sun shines you can really make hay.
Hi Wolf
Thanks for the comment. Are you implying that your's is a trader's (momentum) strategy, which would make sense? Graham's video seemed to be using the context of a 'buy and hold' strategy which is what prompted me to ask the question.
I'm more a trader yes. But if you'd held any of these in last 10-15 years you'd have done alright.
Hi Wolf
Thanks for that - really interesting. My main takeaway from what you've said is to protect capital during drawdown which i haven't done too well this time having had one or two horror stories. What I find most difficult to judge is whether/wnen to sell a stock that has been a good performer but has hit a bad patch eg XP Power (LON:XPP.
I'm the wrong person to ask Davis on long term investing. I'm pretty hopeless at it as I always want to fiddle and bank profits, and I know next to nothing about accounting. I just don't have the personality for it unfortunately. Lots of good long term investors here on stockopedia.
I hate drawdowns so try to avoid them where possible, no problem going 50%+ cash at times. In 1999/2000 it was an amazing market so like everyone else I made lots of money, unfortunately I lost about 75% of it on the way back down. All the usual stuff, no stop losses, averaging down, over trading not moving to cash, extrapolating todays frothy sentiment and valuations into next year. Was gut wrenching, really made me feel physically sick to have been so dumb to give it all back.
Just decided I'd never get into that position again so started to look at things from the perspective of what could go wrong rather than how much money I'll make if it goes right. Basically posh gambling as Paul called it but always using a stop, never averaging down, only buy when the percentages/probability is in my favour and learn to take lots of small losses. It's a pain at times having to sell when youre convinced it'll probably recover again but just have to stick with it. Can always buy again later.
Someone said, Minervini maybe? Theres only 4 outcomes when you buy. Small profit, Large profit, Small loss, Big loss. The first 3 are fine, eliminate as much as possible the last.
Theres a book I saw on Amazon, I haven't read it, called "Best loser Wins" . That is it in 3 words,
Sorry, went off on a tangent there :)
The standout performer from that list for consistency seems to be Games Workshop (LON:GAW) (I HOLD)
Wolf,
An interesting table when considering a 10Y hold. Of these 7 of the companies show a constant return ( 3x Green) over the last 1, 5 and 10 years, highlighting an ongoing Moat. I already own Games Workshop (LON:GAW) and 4imprint (LON:FOUR) and I have been considering buying Spectra Systems (LON:SPSY) on their quality and valuation metrics. The table has highlighted the niche that Spectra Systems (LON:SPSY) have and has prompted me to buy starter position this afternoon.
Many thanks for this info.
Iwright, if it goes well you can thank me in 10 years. If it goes badly, we never met :)
As ever with investing its a case of DYOR, so your 10Y small cap returns table provides additional info, for me to make a call. So I am content with my decision whatever the outcome :)
Hi Wolf if you have time any chance of a Wolf's whistle stop post going through what you view as positive factors/figures to make you consider dipping toe in and also Wolf's red flags, long term downtrends i'm guessing would be top of your red flag list.
No drama if its a ball ache and you don't fancy doing it but look forward to your posts on here as you seem to be on the money more often than not.
Regards Andy
Have you found that you develop a feel/sixth sense over the years Wolf ?
This morning when I read the Mobico (LON:MCG) RNS, I had that horrible "here comes a big loss, what a naff start to my day" feeling. At the open I set a market sell order to get rid of my shares asap. I was gobsmacked (and overjoyed) to see they sold for only a 3% drop on last nights closing price. It wasn't a huge holding, but still 3% of my portfolio. Over the next few minutes it fell to 10%, after half an hour it was 20% before settling at around 30% down.
My question to readers is - Why in this case was I able to get out and the SP allowed to make a graduated (albeit swift) fall, yet in other cases, the SP simply opens 30% down, such as with Cambridge Cognition Holdings (LON:COG) a few weeks back. What or who defines this and are there variances based on sector, broker or company size.
Thanks in advance,
Ben
Ben, Mobico (LON:MCG) is a full market listing on SETS platform, with a large order book. We could place our own buy/sell orders onto the order book.
Cambridge Cognition Holdings (LON:COG) is AIM and only has only 4 market makers, SETSqx platform. Difference is the markets makers could open the price at any level they want if there's a profit warning so it's much more risky and illiquid.
Here's the order book of both
Hi Wolf,
Thanks so much for your explanation, very clear. Apologies if this is a naïve follow up question but is it the case that all stocks on AIM are SETSqx and all LSE listings are SETS, or does it depend on other factors?
On a side note, I notice you have used Level 2 data to show this with your screen grabs, is this something that you would recommend upskilling myself to use? I have only been investing for a couple of years and I was always under the impression that Level 2 is it something that adds value predominantly for individuals making regular trades at higher volumes.
Cheers,
Ben
No problem. The larger AIM companies trade on SETS also so just depends. Some of the real dodgy AIM companies can have only 2 or 3 market makers so at times you're trapped if you want to sell.
It depends on your investment timescale whether level 2 would be of use. I hardly ever day trade anymore but probably looking at 3-6 month holds usually so id feel blind buying/selling without it. If youre a long term holder then it wouldn't make any difference really and probably cause you to overtrade.
Hi Ben - Level 2 is a waste of money for most people unless you understand what it does and the limitations.
You're correct re it being used by people who make regular trades. If you're intraday trading then you need it. If you're not, then you probably don't.
I've written about SETS and SETSqx and Level 2 here:
https://www.shiftingshares.com...
Hi Michael, Thanks for the link to the article. Looks detailed so I will need to take a proper look after dinner once I've had some brain food. I notice you are a published author as well, it always amazes me how many experts we have here on the SCVR who take the time to support relatively novice investors like myself. Thankyou.
Great write-up on YOU Paul. As you mention it all hinges on the GfK acquisition - yes, it's not cheap (but cheaper than YOU). Essentially, YOU are getting the equivalent of 50% more revenue for a third of YOU's own valuation. Arguably, they would have had to pay considerably more if a voluntary sale - and unlikely ever to have come up for sale. GfK consumer panel business is highly attractive - high quality revenue - strengthens YOU's geographic coverage and market position catering to FMCG client base. So, strategically it looks like an excellent fit. See the FY23 presentation here link
As YOU are strong in the political polling space - 2024 should be good - as we have elections coming up in both UK and US.
Thanks for your views on YouGov (LON:YOU) Paul. Very helpful.
Ive been looking for a buy point on this for ages, just wanted to see the outlook statement on Tuesday first before pulling the trigger.
They've added debt risk, but in my simplistic mind if the acquisition goes well and they hit forecasts then I think the shares should do very well, if they miss they won't. Risk/reward looks decent. There was talk of a US listing a couple of months ago also.
For a UK company they have some nice metrics. Price has diverged from eps growth forecasts for the first time in years as the PE ratio has dropped back to much nicer looking levels.
Hey where do you get these graphs??
Hotel Chocolat (LON:HOTC) mcap should be closer to 100 than 200M!!
Restaurant (LON:RTN)
Just listened to your podcast Graham - thumbs up but one minor point is that you divided EV at offer price by number of Wagamama sites to give a price per site but don't forget the bid is for the whole group that also includes pubs and concessions.
Pubs is a poor description. These are high end gastropubs like this one catering for the Cheshire set.
Of them RTN says:
Concessions are mainly in airports so have suffered longer from the return to travel but, as many are posting about Jet2 (LON:JET2) this morning, numbers are now back to greater levels.
That said, the offer remains generous and I would accept if I were still a shareholder (I got out at a good profit when things started to go wrong in 15/16).
re: Restaurant (LON:RTN)
Thanks sharw - excellent point! That does reduce the price paid per Wagamama site. Cheers.
Norcros (LON:NXR)
Nice tickover update today "on track to meet market expectations" - specifically the lack of any bad news is good news as others in this sector are struggling so even though times are tough they are still on target to make underlying operating profit of £43.4 million this year - not bad going for £131 mill market capitalisation company !!! - pe here makes Just Eat Takeaway.com NV (LON:JET) look like its on a somewhat racy rating! - note Norcros (LON:NXR) does often have adjustments to underlying operating profit than can reduce the final bottom line figures so anyone potentially investing here should always look under the bonnet to see if they are happy with any adjustments that are made. also there is always the pension/south africa blah blah. Net debt down over £10 mill compared to last year - at under £50 mill debt is modest enough that they have room to make further acquisitions if they wanted to - i for one are happy with them ticking over paying down debt as fast as they can for now unless a no brainer comes along. Probably just me a and the chickens left here in this one cluck.
Another Jet vs Jet2 again :)
Hope you haven't been buying the wrong shares, rmillaree!
Norcros (LON:NXR) Reassuring update but yet again no impact on share price and PER less than 5 per Stocko, thoroughly depressing state of stock market right now, if there had been even a mild profit warning it would have got hammered, any positive news just goes into the ether, when will it turn and still amazed that this company has not been subject of a takeover despite pension deficit which seems to be the regular negative factor.
Norcros (LON:NXR)
Sometimes one needs to play the really long game - lets hope it doesnt go belly up in the meantime. hey ho reminds me of my first share purchase over 20 years ago bought after price had declined 2/3 -from peak in quick fashion thought it wont take that long to get back to prior highs - got there eventually but it did take 23 years and that was only this year!!
At least with this one there is some decent dividends while we wait (28p last 3 years) -
jonno re your post today on Jet2 (LON:JET2) I bought a small position on 12 Sept at 1139p and sold on 4 October at 1029p for a 10% loss.
I am looking to re enter as i think the market has got it wrong. Jet2 consistently gets rave reviews from its customers which is a real tribute to them in an Industry that often deservedly gets lambasted for poor service.
Vague bid talk in the Times about Essentra (LON:ESNT) looking at its share price it’s rallied 20% since mid Sept with no apparent reason apart from a small acquisition from them. Maybe there’s something brewing. It’s the old Filtrona.
Jet2 (LON:JET2)
All the current evidence, anecdotal and otherwise indicates that the travel industry is going like a train (pardon the pun). One only has to look at announcements by easyJet (LON:EZJ) Ryanair Holdings (ISE:RYA) , On Beach group (LON:OTB) and Ramsdens Holdings (LON:RFX) (foreign currency).
Jet2 (LON:JET2) continues to trade well and has been subject to recent upgrades. From the September AGM statement:
"Although there is still some way to go in the Leisure Travel winter booking cycle, based on current visibility and having absorbed approximately £13m of cost and lost margin from the Rhodes wildfires and the recent NATS air traffic control failure, we are on track to exceed current market expectations for Group profit before foreign exchange revaluations and taxation for the year ending 31 March 2024(1), with the outcome presently expected to be in the range of £480m to £520m. This guidance remains dependent on avoiding any material extraneous events in the balance of the year."
Also from the prelims announced in July:
"Total cash balances at the year-end of £2,624.7m (2022: £2,228.5m) increased 18%. 'Own Cash'† which excludes advance customer deposits, increased by 4% to £1,127.1m (2022: £1,083.8m)."
In addition it has been ahead of its contemporaries in ordering new aircraft and recently taken delivery of the first part of its order of new A321/320 Airbus. I would also mention that it is rated number one for customer service by 'Which' and scores well for employee satisfaction on Glassdoor
So here we have a company that is trading well, has run rings around the likes of TUI AG (LON:TUI) that had an 1.8 billion euro rights issue earlier this year, has in my view excellent management and cash of more than 50% of its market cap, yet is available at a PE of 6.5 or thereabouts.
Either the market has got it wrong or I have. I am not given to hubris and remain convinced that I am right. Needless to say I hold.
I hold Jet2 (LON:JET2) too and am frustrated and slightly mystified that its skills and charms are not more widely appreciated. I can only think that the bears are worried about the overhang of Meeson's holding, but any fund with half a brain should be bidding him for it!
I agree. I don't understand it either. Jet2 (LON:JET2) is best in class, has over £1 billion in cash, and a forward PE of 6.3. What's not to like? (I HOLD)
easyJet (LON:EZJ) seems cheap at these levels also at 415p? Reinstated divi. Any views from those better researched?
easyJet (LON:EZJ)
looking at stocky pe's this suggests easyjet pe is higher than £JET2 7.7 compared to 6.3 - and Jet2 seems to have better sales growth - one should look at balance sheet surplus or deficit ref "liquid assets" for each company though before investing - note sure which one has the stonger balance sheet here ?. I have previously held easyjet in the good old days but they seemed to have slightly lost their mojo somewhat pre covid anyway - deffo would say that easyjet doesnt look expensive either though.
Jet 2 and otters
Looks very good we always try to fly jet 2 over and above easy jet / Ryanair etc .
Cheap, with cash, good sector .
I did buy few weeks ago right at the top of the range but you can’t always time the market entry point.
Vertu seems to be spiking up and heading to the 80p barrier fortunately this is the one I did time right and I was buying heavily in the sun 50p period so that was well timed .
Georgia capital has come off its recent highs looks a good entry point now .
Planetx I sold Georgia Capital (LON:CGEO) a month or so ago. Got nervous reading reports of some anti Russian graffiti appearing in Tibliski -large numbers have left Russia for Georgia. Looks great value, but waiting for a friends adult son to return from a working holiday picking grapes to see what his view is.
There can.be quite a big spread o. Georgia capital so I am a sit and hold investor here
The share is at such a big discount to NAV yet underpinned with its % ownership of bank of Georgia that I just think it’s almost n rye special situation category .
As I have said previously the geopolitical risk in the UK is not exactjy low and certainly I prefer to have a % of my funds invested in a fast growing economy not one quite literally on its arse .
The Russians have moved most of their fleet from Sevastopol in the Crimea to the "Russian" port of Novorossiysk following successful Ukrainian strikes against the Russian fleet .... a quite remarkable achievement for a country with no navy. The leader of the Georgian breakaway republic of Abkhazia, Aslan Bzhania, claims he had signed an agreement with Putin for a new permanent base in the south of Abkhazia. Abkhazis is part of Georgia not Russia. I believe there is a fair chance Georgia gets dragged into the Ukrainian-Russian war and the geopolitical optics are less than attractive. In addition, although Georgia has averaged 5.4% growth since 2004, this has recently accelerated to between 7.5 and 8%. This is entirely due to the influx of Russians escaping the draft. I can tell you the locals are less than happy and there are bars that refuse to serve Russians and other bars that charge Russians a Ukrainian tax which is sent to Ukraine. There are other political challenges in Georgia .... Georgian PM Garibashvili sparked international headlines by blaming NATO for the Russian invasion of Ukraine and in July 2023 Georgia signed a strategic partnership with China signalling a further move away from the West. Georgia is politically on the cusp and is, in my view, uninvestable. I hope those that do decide to invest have a full understanding of the geopolitical challenges and threats. As you can imagine, I have no position.
jamesalastair Thanks- you echoed my concerns. I will watch and listen for the time being. I have real concerns re Putin/Russia- and may feel now with the Israel situation he can exploit further. We must remember he wants ideally the old Soviet Union back.
Can someone breakdown the actual cash position for Jet2 (LON:JET2). I am not the best with balance sheets so I am struggling to resolve it. Stocko shows approx. £1.25b in net cash (under the net debt number) - it also shows in the balance sheet, capital lease obligations at £544m. From what I understand, you would usually add this back to the net debt figure - so this would then equate to something like £1.8b in net cash - but obviously I must be missing important numbers within the balance sheet, otherwise we have a £2.2b market cap with £1.8b cash. If anyone can resolve / clear this up I would be very much appreciative.
cheers
Matt
Jet2 (LON:JET2)
you always need to go to the actual accounts
at 31/3/2023 they had
280 mill receivables
deposits £1.7 bill
cash £955 mill
say 2.935 bill liquid assets (i have ignored £1 bill of poperty plant and equip on basis they need it to earn profit)
what they owe out
payables 339 mill
defered revenue £1.54 bill (this line pretty much cancels out deposits)
current borrowings 126 mill
long term borrowings 603 mill
say £150 mill of other stuff
that totals 2.758 bill (dont presume my maths is correct this is quick calcs)
so surplus of say £170 mill - thats all fine and dandy - note the reality is though that most of the cash they have is not technically theirs. Bonus would be if plant is easily turned into cash without them losing ability to keep turnover at current levels (noten if you sell planes and turn them to cash but then have to lease planes p[rofits would be lower but there would be less assets)
practicably speaking they may be able to mange without decent surplus - but the danger here is that if the card providers are equally liable for refunding customers if bookings are cancelled then all the cash would be gone - so card providers may force company to hold decent suurpluses to cover worst case scenario. Cant remember what the other cheap arline was that got solkd for 1p or summit i think that was due to card providers removing support.
Many thanks Rmillaree, I really appreciate your efforts in breaking this down. I have not looked at Jet2 before, and as it was mentioned a bit today I thought I would take a look. On the face of it, it looks very cheap and drowning in cash. But having seen your analysis, I think it gives a different and more accurate reflection on the cash position - and perhaps is not as financially strong as it may appear when taking a superficial glance. Thanks again, much appreciated.
cheers
Matt
Just Eat Takeaway.com NV (LON:JET)
Airline earnings have always been subject to high variability - the danger here is extrapolating a purple patch earnings for year or two as being sustainable over the long term . In some respects its a bit like the housebuilders - bad years can be really bad compared to some sectors that can chug along making reasonable profits in a recession. Note thats not to say companies wont churn out ever increasing earnings on average over the mdeium to long term - Easyjet had a decent run of years where they had increasing average profits in line with turnover increases.
Having a quick look at the numbers it seems like they have been catching easyjet up somewhat over the last 5 years as 5 years ago turnover was not much over half that of easyjet and now its approx 2/3. So it does seem like easyjet has been outperforming at a quick glance ref getting bums on seats.
Ref cash at bank over £1 bill - they need that due to the fact that its only really customer deposits. Ref dilution i calculate both easyjet and Jet2 have increased share count by 60% over the last 5 years. So although they may have diluted les than Tui thats still decent share count increase and similar to easyjet.
Thanks for pointing this one out it does actually look quite tempting - with airlines though you pay your money and take your chance !
Clearly out to lunch...
Wrong ticker posted, rmillaree :)
I agree that Jet2 is undervalued due to the sum of the parts. Yes, there is a holiday arm that should command a much higher rating. But because its an airline too, there's that high fixed cost, fixed debt basis that will get the whole company in trouble in an economic downturn. The holiday arm will do just fine; all the costs are people variable costs, just do huge rounds of redundancies and cashflow is conserved. But planes... and don't forget hanging on to all those aircrew (hard to train, hard to keep certified, hard to find) during bad times will be a big drain as well.
That's why, on a fundamental level, I don't have any airline shares on my watchlist, and my main exposure to the continued travel boom is in On Beach group (LON:OTB) . Albeit a little unsuccessfully so far!
(I hold OTB in the Boon Fund)
Jet2 (LON:JET2)
Interesting discussion with some good points made, for and against. Increased share account as a consequence of covid acknowledged.
I shall revisit the accounts but it is difficult to see how one can misunderstand the statement in the July prelims
"Total cash balances at the year-end of £2,624.7m (2022: £2,228.5m) increased 18%. 'Own Cash'† which excludes advance customer deposits, increased by 4% to £1,127.1m (2022: £1,083.8m)."
As is said cash is cash . Jet2 (LON:JET2) clearly states that its own cash, excluding customer advances is £1.2billion. So I am unsure how you come to the conclusion:
"Ref cash at bank over £1 bill - they need that due to the fact that its only really customer deposits. Ref dilution".
It may be that there is some financial "sleight of hand" that I have missed, but I can't see it. Happy to be corrected by those who have greater experience of company accounts if I am wrong.
Jet2 (LON:JET2)
Its a difference of difference of opinion as to what is their cash to keep !! - for the record i am not saying they dont have the cash - all i am saying is they have some chunky liabilitioes that are owed out.
They are saying its their cash if they have £1 billion sale which they bank with matching cost of £1 billion that they have not paid yet that is not ringfenced customer money. They are not wrong to say they have £1 billion cash - its there and in the bank - i am looking at the matching liabilities of £1 billion that are owed out and i am am saying that practicably speaking as they owe the £1billion back out its not really their cash to keep - they just have a good working capital profile so they get to keep the cash temporarily and may be able to hold onto it for longer if they keep the wheels spinning. The reality is suppliers/banks may not be over keen on giving this credit forever.
The reality here is that they will likely have used bank debt and trade suppliers.
The difference here does matter
You can have company A with £70 mill in the bank and no liabilities owed out - thats a real £70 mill of useful cash.
You can have company B with £70 mill cash in the bank and and £70 mill of liabilities - that cash imho isnt as useful as the cash that cokmpany A has very very obvious reasons.
Big difference in these 2 companies from risk profile
so when anyone says on here company B has £70 mill cash - its not wrong to say that but more useful to aslo flag up the other side of the equation if there is one. Plenty of type B companies go pop without ever having run out of actual cash at the bank - if creditors call in their credit and they cant pay.
the reality here is would they have been doing rights issue previously to issue more shares if they didnt need to and could have dipped into their own cash coffers - probably not. The peeps that handed them credit would have demanded they dont deplet those cofffers as tehir satefy net would not be there.
Note i am talking generally here - this specific company coudl be lucky enough that peeps who hand over the credit dont care and that cash could simply be paid over to shareholders - i woudl be surprised if that was the case though.
Airlines such as Jet2 (LON:JET2) are, rightly, disturbed by almost every international problem. So we now have not only a war in Ukraine, complicating or blocking travel to various destinations. With a Middle East war a further round of destinations get stopped or are threatened around a Israel (Jordan? Egypt?). And maybe some further shocks to fuel prices, heightened security concerns, rerouting etc.
So I am entirely unsurprised that airline investments are (as usual) “exciting” rather than consistently forecasts Le.
wait until we all get personal CO2 allowance in order to save the world from climate change! Net zero -> zero wealth.
Was wondering why James Latham (LON:LTHM) has taken such a battering this week - then saw the update from Travis Perkins (LON:TPK) and understood the reaction - Shame I ha not swapped for Restaurant (LON:RTN)
Eneraqua Technologies (LON:ETP) yesterday, Mobico (LON:MCG) today, two profit warnings, one of those weeks!
One step forward, two steps back.
Tough markets Newinvestor. I think I mentioned this a couple of months ago when Mobico (LON:MCG) price was around 100p, and I'm honestly not trying to be a patronising know it all, but anything in a long term downtrend requires extreme caution. It's like trying to stop a large boulder rolling downhill before it's slowed down.
Personally I'd wait for the update showing things on track or improving. You'll pay maybe 10% more but that information is well worth paying for. In markets like this it's as much about avoiding unnecessary risk as stock picking.
Very true mate and good advice, the rest of my PF is ok, I take too many risks, will learn eventually to avoid falling knives.
Restaurant (LON:RTN) I suspect Apollo just want to get their hands on the Wagamama brand - they're not going to be bothered about the stretched balance sheet as it will cost them very little just to pay this off. I think this highlights the value of good brands, even if the company looks poor on traditional metrics. For that reason would certainly not expect any bids for Host ore as can't believe anyone would want the TGI brand.
Especially as Hostmore (LON:MORE) don't own the TFI brand........
I see Goldman Sachs has cut Boohoo (LON:BOO) and ASOS (LON:ASC) to Sell.
Don't blame them but would probably have been more helpful to anyone interested if they'd done it before shares were 95% down.
Probably a buy signal
No the buy signal is me cutting my ASOS (LON:ASC) this am!
I think a good general rule is that when a shares has a Stockopedia Momentum rank that's red, one should view that company with extreme danger. The momentum might not be without its faults, but I take it as an emphatic warning the market thinks there is something very wrong with the company.
ASC has a Momentum score of 5, whilst BOO is 3.
BOO has projected losses for the next two years and £162m in debt. Scary,
As for ASC, I see that it has an EV of £1.24b and a mkt cap of £455m. I sometimes use that as a quick-and-dirty guide to eyeballing if a company is likely to have too much debt. Basically yeah, way too much debt.
So I think the vampire squid is calling it right.
Be careful with stated EV as net debt now often includes leases.
Take Ten Entertainment (LON:TEG) for example. Stocko shows as having a large net debt but it actually has net cash.
Unfortunately the accounting rules mean that you have to go into detail, strip out leases before comparing EV to market cap to see if debt looks genuinely onerous.
Polar Capital Holdings (LON:POLR) - Solid H1 amidst sharp sector share-price falls (new note with audio summary here: https://www.equitydevelopment....)
AUM was slightly down (-0.4%) to £19.14bn over H1-24 (to 30 Sep 23), with a -2.9% fall in Q2 (Jul-Sep) following the +2.6% gain of Q1 (Apr-Jun). Investment performance was positive at +£546m (-£154m in Q2, and +£700m in Q1), net flows negative at -£581m (Q2: -£380m; Q1: -£201m), while fund closures reduced AUM by £50m.
We reduce our FY24 & FY25 forecasts due to AUM and marked-to-market performance fees being lower than prior forecast: end-FY24 AUM forecast is now £19.4bn (prev. £20.7bn), FY24 revenue £169.2m (£178.4m), and core operating profit £40.7m (£44.1m). We reduce our fundamental valuation from 625p per share to 575p, although this is still 31% above the current share price.
Additionally, on page 2 of our report we elaborate on why the recent sharp falls in asset management valuations look over-done to us, especially in light of recent M&A activity in the sector.
Brooks Macdonald (LON:BRK) - "Well-flagged sluggish quarter but price fall looks over-done" (new note with audio summary here: https://www.equitydevelopment....
FUM increased marginally over Q1 of FY24 from £16.85bn on 30 Jun 23 to £16.86bn on 30 Sep 23. As flagged in the FY23 results release of 14th Sep 23, net flows were slightly negative for the quarter at -£70m, although BM has indicated it expects positive flows for the whole of FY24.
It’s important to keep this small negative quarterly net flow number in context: it follows nine consecutive quarters of positive flows (achieved despite difficult market conditions) and a period where BM recorded a higher organic growth rate than peers for 6 out of 8 quarters.
We leave our forecasts and our fundamental valuation unchanged at 3,000p per share which, following the recent share price fall of BM (as well as the sector more generally), is now 89% above the current share price.
It is also worth zooming out to look at sector valuations in light of recent falls. Since the end of the bull market at the end of 2021, investment/wealth managers and platforms have ‘de-rated’ significantly with the median PER of a tracked peer group declining 54% from 27.6 to 12.6.
While valuations may well have ‘over-run’ to a degree at the end of the bull market, we certainly see the current median PER of 12.6 as very low (noting that this has dropped 25% in just one month from 17.0 when we published our most recent note on 14th September 2023).
Marks Electrical (LON:MRK) - Service uplift sparks 25% sales growth (new note & audio summary here: https://www.equitydevelopment....)
Marks Electrical Group’s sales revenue advanced by 24.8% in the first half of its 2024 financial year, according to a trading update released today, as the company made further market share gains in its core categories. Notably strong advances by category included +71% for televisions, +74% for washer-dryers and +36% for American fridge-freezers. These gains were achieved against relatively flat domestic markets for both Major Domestic Appliances (MDAs) and Consumer Electronics (CEs). An improved service offering, which now includes integrated installation services, made a notable impact: not only in a strong sales growth rate, but also a best-in-class 4.8 Trustpilot score.
Due to first half sales growth strength, we have revised upwards our sales forecast for FY2024 from £114.5m to £116.0m. However, we reduce our EBITDA forecast from £8.9m to £8.0m as well as making downward adjustments to FY2025. Margins are expected to contract as a result of order growth being faster than revenue, higher driver wages and the integrated installation service addition. Importantly, the company is not willing to make reductions in marketing spend to offset these items. Rather, it continues to invest in brand recognition with a view to sustainable growth.
Given MRK’s strong cash position and clearly articulated strategy for sustainable business expansion, we maintain our 150p fair value for the shares.
As a previous customer and since customer elsewhere - they have the lukewarm items costing £x00 more, not the hot ones at lowest. Which is fine if they have brand value for enough people - but ...
Next day isn't that special these days (but I don't care about installations - so haven't experienced that side and could see that being very useful for a lot of people).
For me AO world delivery was just as good (dishwasher, oven, hob a couple of years ago), they even swapped out the dishwasher because I didn't like the technical design (it would leak steam into the under counter space at the end of the cycle) but their prices and stock seem off the boil as well now.
There is a lot of drop shipping direct from the manufacturer these days so the retailler just does the billing and doesn't impact on delivery or installation.
We buy enough items in the £500-£1500 range across several properties that it is worth price hunting for latest bargain. Almost for every 7 get one free!
Do they just risk failing between lowest cost or best service? or is that the optimum point? Time will tell, but they aren't what they grew on the back of (IMHO).
Marks Electrical (LON:MRK)
I get the impressions marks live in the real world - profits are not amazing but facts are they manage to eak out a profit and seem to be proper buisness . Compared to ao online who were happy to sell at loss to them for many years on the basis that would pay dividends later (now?) . Things have probably changed slightly now ao are expected to be making a profit (hmmm so were made.com) - in some respects if ao are now also living in the real world and making a profit that suggests that perhaps they are not as cheap as they were - albeit i would guess marks cant drive suppliers down in price to the same extent as ao?. My main worry here would be founder leaving and getting replaced by corporate versions of max headroom . I always remember clinging onto tesco shares for too long on the basis that big was best - that turned out to be poor logic on my part. To be fair to marks i presume they are probably sensible with cash and deal they do not like lying shysters who used to run then roost at tesco (would love to see em try and argue they werent)
Gore Street Energy Storage Fund (LON:GSF) this was discussed a bit yesterday - they put out an encouraging update this morning. Looks like the share price fall a bit overdone and probably a bit of panic selling going on.
Agree. Looks like international revenues are higher that expected, so Div should hopefully be safe.
I do own a little bit of Gore Street Energy Storage Fund (LON:GSF) on the basis that it is oversold but I would be very careful.
1). Still no mention of Stony starting commercialisation (only a repeat that it is energised). Stony has been much delayed and still the last update I have seen says commercialisation should happen by end-September. We are already past this.
2). The dividend is not covered even on GSF’s preferred measure “operational EBITDA to dividend”. But this measure is meaningless in my opinion. It does not include costs of running the fund. The Fund EBITDA is therefore a better measure but even this includes 100%. of partially owned battery sites. I think the div has paid out of cash raised from the shareholders not really a sign of a board valuing shareholders’ cash.
3). The NAV needs quite a lot of faith to believe. Future revenue curves are very hard to predict (as shown by collapse in UK) and as far as I can see many of the projects (under construction and even pre-construction) are valued on a DCF. The 10-11% discount rate on pre-construction assets seems aggressive to me, particularly given the history of repeated construction delays.
4). Like all battery operators there is a risk of technological improvement reducing the value of current assets.
There are definitely positives: the geographical diversity, no debt at present, the strong US pricing in Q3, the recent £1m manager purchase of shares. These factors got me to buy some.
Paul, thanks for a detailed and informative analysis of YouGov (LON:YOU.
Thanks BnB, glad you found my review of YouGov (LON:YOU) helpful! Certainly a very interesting company.
Travel sector is on fire. easyJet (LON:EZJ) reports strong numbers and a resumption of divi early next year. Conditional arrangements for 157 new Airbus planes for delivery between FY29 and FY34
Saga (LON:SAGA) has popped recently too although On Beach group (LON:OTB) has given up gains post its update.
Sorry, but not only easyJet (LON:EZJ), but Luton Airport was on fire...
Bizarrely, easyJet (LON:EZJ) is down this morning
I was mulling what Paul said about how he and Graham were happy with the valuation of their shares. I was also discussing this with an American mate.
I found this interesting chart of growth vs value:
It's the Wilshire growth index divided by the Wilshire value index. It's for the US. If anyone could point out an approximate equivalent for the UK market, I'd be grateful.
You can find the chart at this link: https://www.longtermtrends.net...
What this chart is telling you is that as the line rises, growth does better than value. As it falls, value does better.
Fundsmith was launched in 2010/1. As you can see from the chart, this would have been a great time to buy growth companies, as the line slopes upwards. Nick Train also put on a fantastic show.
But look at where we are now. Growth is in an extended region. If there's a reversion to normal levels, value should do better. It's not possible to say when this will happen, but we're pretty high right now.
So, everyone's intuition that value is due for a pop is likely right.
I can give you a couple of examples from my portfolio where things are bonkers. Take IG group (LON:IGG) for example. The fear is that it is has gone ex-growth. But look at the valuation. It's on a PE of 6. It pays a yield of 7.5% and earns returns on capital of 26%. Analysts project 15% growth in EPS for 2024 and 10% for the year after.
Another one: British American Tobacco (LON:BATS) . It's on a PE of 6.5, with a yield of 9.7%. That dividend is covered. Its interest cover is over 10. Analysts are projecting positive earning growth.
There must be tonnes more, and they aren't even obscure micro-caps where you really have to scratch your head over.
This brings me on to Scottish Mortgage Investment Trust (LON:SMT) This is a trust that has gained legendary status, although its performance has faltered lately. I predict that it will continue to perform badly over the next couple of years. It is in growth shares. Here's some of its top shares and their PEs: ASML 30, Moderna 35, Nvidia 113, Amazon 103, Ferrari 49. It runs a concentrated portfolio. If growth and value start to normalise, the pain for SMT will continue.
Excellent well explained post. Thank you
I am honoured :)
IG group (LON:IGG) screens like the perfect stock, a low PE , incredible returns on equity , a huge net cash balance and forecast to grow strongly. But you have to price in the very real threat of regulation . An incoming Labour government is more inclined to look at an industry where 80% of punters lose money and regulate or tax it more heavily. The last time the Conservatives tightened the rules the IG stock price lost nearly 50% in a day .
Spread betters are also low beta and usually do well during periods of market volatility, so can act as a nice hedge, although doesn't alway work out in practice!
I think a fair chunk of their business is now international so that should lessen the threat of yet further regulation.
Agree on most of those, but I personally don't think British American Tobacco (LON:BATS) looks that cheap once you factor in the high debt, regulatory headwinds (which I suspect will get ever more stringent) and the long-term decline of smoking.
Thanks very much for the comment Mark. I particularly appreciate as I own long-term stakes in both British American Tobacco (LON:BATS) and IG group (LON:IGG) - hopefully it is time for value to have a few winning years! Cheers. G
Spectra Systems (LON:SPSY) nice start to the day . This order will make a “meaningful contribution “ to this and next years profits.
https://www.stockopedia.com/sh...
Two ways to look at the Spectra Systems (LON:SPSY) RNS:
1. Bullish - An important client has made a large order at higher prices. The order was in their forecast but still good
2. Worrying - The client’s five year contract expires in 2024.They are stocking up in the expectation that they won’t renew the contract when it expires.
We will know better when / if this client signs another (hopefully five year) contract
From what I know about this industry - switching suppliers is a huge endeavour. As the covert materials are proprietary, and intrinsically linked to the manufacturing process (so to therefore make it harder to counterfeit), it will take a long time to onboard a new supplier, run through all the testing, etc before being confident to roll out new notes.
However, of course, the central bank could be doing all this covert material testing very covertly as well, and have a competitor lined up to take over the Spectra Systems (LON:SPSY) contract in 2024 already :)
On today's announcement, I am a little surprised about the increase in the order. If this isn't some sinister contract switching plot, then it suggests that banknote demand has increased? But I find that hard to believe. Unless, of course, inflation is causing more people to go back to cash to budget, and also the falling value of money means more banknotes needed? Maybe the drug epidemic is exploding and therefore the trade has seen a huge demand for notes?
Either way, at least there's a bit of a break-out in terms of valuation, hopefully it goes to the next SP band, 200-230p and settles there.
(I hold in the Boon Fund)
https://www.uscurrency.gov/lif....
Shows that the no of banknotes in the USA are increasing every year. 54.1bn in 2022.
Thanks for this! I'm going to take this a step further and convert it to volume of banknotes, from value. Just to see if the volume has increased.... especially of the higher denominated ones (which I am guessing are the ones needing covert materials to make counterfeiting harder).
Restaurant (LON:RTN) turn today for takeover at a juicy premium by Apollo. Have a couple kicking around but didn't even consider that one materially undervalued like a lot of our small cap watches. Hope this takeover trend continues
Quite an impressive outcome this, fairly decent cashflow plus a credible growth strategy wins the day.... despite reasonable headline debt and a chunky exposure to leases. Never the less 9xEBITDA is good for the sector no doubt.
Miserable ending and offer for long term holders.
Yup. I don't own Restaurant (LON:RTN) and don't have a view on whether its a good strategic investment...but assuming it has any half decent future then PE has made a steal from AIM once again. I continue to pray that my investments don't attract their rapacious eyes ;)