Small Cap Value Report (Thu 12 Sept 2024) - KIE, FEVR, KEYS, TRN, MRL, NCC

Good morning from Paul, and from about 08:30 Roland will be joining me. Graham & his family have come down with a bug, so sending them our best wishes to get well soon.
All done for today!
Considerable volatility in the US market again this week, with the Dow last night doing a c.900 point (2%) fall, then recovering all of the drop intra-day. What's going on? It seems to be uncertainty over inflation and interest rate expectations. I do think it's important not to let day-to-day volatility shake me out of good shares that I'm invested in, so I ignore it.
In our small-mid caps space, we're seeing some bargains appear again, as readers were discussing in yesterday's report. If we can get good companies, that are trading well, 10-20% cheaper than a week or two ago, then that's a good thing! BLASH (buy low and sell high) is the golden rule.
I suspect the UK small caps space is being disrupted by the anticipation of higher CGT in the late October budget. Hence people feel incentivised to bank profits now, to lock in a potentially lower rate of CGT. Although maybe some of the sellers will be wanting to buy back in, so this could just be a short-term dip. Again, personally I won't be letting unusual price falls disconcert me, that's more of a buying opportunity than a threat in my view, because the likelihood is that sellers are motivated by tax factors, rather than inside knowledge of poor trading. As always though, it's all educated guesswork, that's what makes investing so fascinating!
UK futures are showing a strong rebound today, as the UK plays catch up with the US strong bounce in later trading. So I'll be hovering over the buy button at the open, with any available scraps of cash I can locate for some possible bargain trades!
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
** New SCVR summary spreadsheet for calendar 2024 ** This is the live one! (updated 6/9/2024)
Archive - SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia.
Companies Reporting
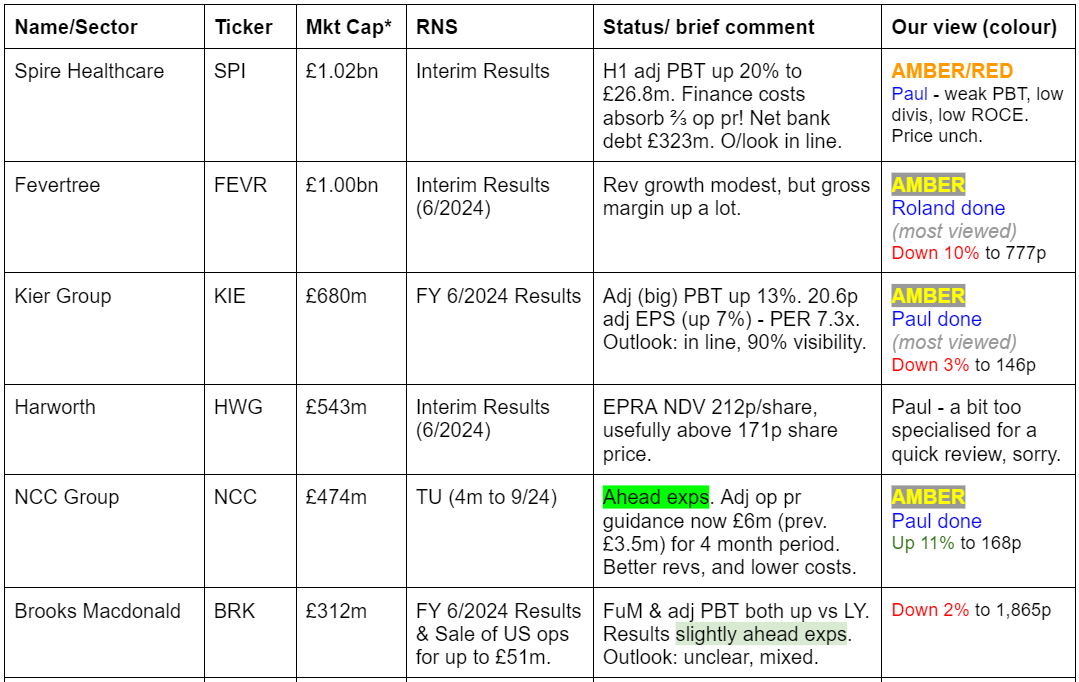
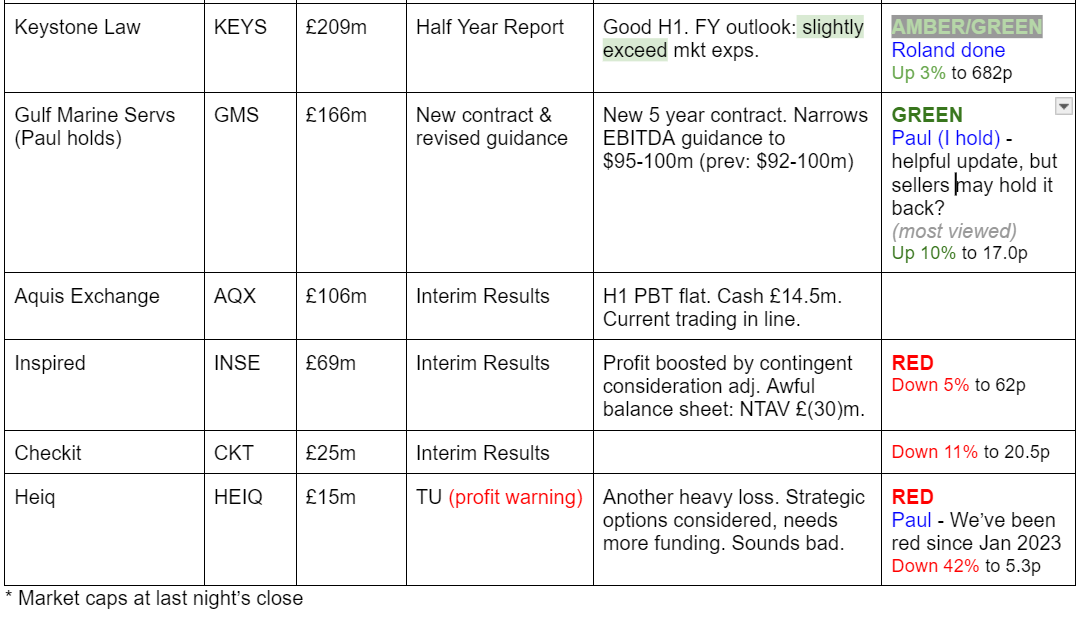
Other mid-morning movers (with news)
Trainline (LON:TRN)
Up 10% to 330p (£1.51bn) - H1 Trading Update - Paul - AMBER/GREEN
“ the leading independent rail and coach travel platform selling tickets to millions of customers worldwide”
Good revenue growth in all regions, up 16-17% overall (ahead of 7-11% guidance). Fastest growth in Spain & Italy. UK (largest market) also good rev growth +17% - more people switching to digital tickets, now c.half of total, and reduced impact from strikes.
Outlook improved -
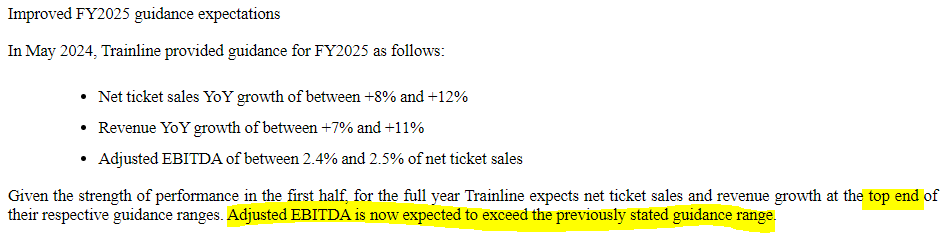
Paul’s view - battered by the pandemic, Trainline is now producing good figures, and beating expectations. I think it looks worth a closer look, and there could be a better moat here than I previously realised (a fund manager interview recently highlighted that point).
My last notes from 3/5/2024 show a weak balance sheet, and excessive management share options (being mopped up with buybacks). Overall, I think we should go up from amber to AMBER/GREEN, as this does look an interesting IT business.
Marlowe (LON:MRL)
Up 7% to 460p (£405m) - Demerger of Occupational Health division - Paul - AMBER
Marlowe has had an interesting recent past. It did tons of acquisitions, got into too much debt, but then pulled a large rabbit out on 22/2/2024 which we covered here, clearing all its debt in one fell swoop with a big disposal. A big special divi of 155p was paid in July 2024. Shares have done quite well since then. Share buybacks have also been done.
Today it has decided to spin out Optima Health, which will become an AIM listed company. Each Marlowe shareholder will be given (in specie) 1 share in Optima, for every existing 1 existing share held in Marlowe. So obviously when the deal completes, Marlowe shares will drop in price accordingly, and the free Optima shares will become priced by the AIM market at whatever price the free market decides they’re worth.
I suppose the hope is that this might create shareholder value by shining a light on Optima, which could result in a higher valuation than it remaining a part of Marlowe. The initial Optima valuation is £225m, but that’s really just a guess. The stock market may decide to value it differently once dealings in Optima start.
Paul’s view - it amuses me when management are building these groups, and making multiple acquisitions, they always talk about the acquisitions being accretive, creating synergies from becoming part of a group. When that doesn’t work, they decide to divest parts of the group, which is also supposed to create shareholder value through unbundling! That said, Marlowe's strategy of divesting assets has clearly worked very well, so with hindsight it turns out there was a lot of hidden value in the group before these deals were done.
There’s some introductory information here on Optima’s website. It says the AIM Admission Document will be published on 23/9/2024.
Presumably there will need to be some buyers lined up, to hoover up Optima shares that some Marlowe shareholders may not want?
Quite an interesting development, hence me mentioning it. Last time I looked at Marlowe, I left it AMBER, as no strong opinion either way from me. Optima would be a NO COLOUR for now, as I await further details.
NCC (LON:NCC)
Up 11% to 168p (£525m) - Trading Update - Paul - AMBER
NCC Group plc (LSE: NCC, "NCC Group" or "the Group"), a people-powered, tech-enabled global cyber security and software escrow business, provides the following unaudited trading update for the four months ending 30 September 2024 (the "Period").
Good news - better than expected summer trading means it’s upping guidance for the 16-month period to 30/9/2024 (new year end).
Previous guidance was £100m revenues, and adj operating profit £3.5m - just for the 4 month period.
New guidance is £104m revenues, and adj operating profit of £6m for the 4 months extension to the year end.
Sounds good, but bear in mind that the 12-month interim results to 31/5/2024 were so heavily adjusted, that it’s difficult to work out what the real picture is at this company.
Eg FY 31/5/2024 showed revenue of £324m, adj EBITDA £42m, and a statutory operating loss of £(21.5)m! Goodwill impairments caused that loss, but demonstrate that previous acquisitions must have included some bad deals.
The last reported balance sheet was weak with £310m intangible assets, taking NAV of £235m down to NTAV negative £(75)m.
Paul’s view - not as good as today’s update suggests, when you look back at the last set of full numbers.
I can’t get above AMBER - unchanged from my review here on 21/6/2024.
Summaries
Kier (LON:KIE) - down 1% to 148p (£673m) - FY 6/2024 Results - Paul - AMBER
H1 results as expected, and outlook comments say it's trading in line with expectations. No surprises today, with everything as previously disclosed in the 19/7/2024 trading update. I'm shifting back down to neutral today, as the weak balance sheet with some strange elements to it reminds me that this is not a particularly well financed business. Maybe the reintroduced divis were premature? Bull & bear points covered below in more detail.
Fevertree Drinks (LON:FEVR) - down 9% to 784p (£910m) - Interim Results - Roland - AMBER
The premium drinks company has cut revenue guidance for the year, resulting in a fall in my estimate of likely profits. I think underlying operating trends are positive, but the valuation already prices in significant growth. Overall, I’m neutral.
Keystone Law (LON:KEYS) - up 3% to 682p (£215m) - Interim results - Roland - AMBER/GREEN
This founder-led legal firm appears to be generating strong growth and high returns on capital from its capital-light model. A strong H1 performance has prompted a modest upgrade to full-year guidance. I’m positive, albeit with a measure of caution on the valuation.
Paul's Section:
Kier (LON:KIE)
Down 1% to 148p (£673m) - FY 6/2024 Results - Paul - AMBER
Kier Group plc ("Kier", the "Company" or the "Group"), a leading UK infrastructure services, construction and property group, announces its results for the year ended 30 June 2024 ("FY24" or the "year").
Company’s headline -
“Year of significant growth; material debt reduction; new long-term growth plan”
For background, our previous notes on Kier were -
7/3/2024 - AMBER at 139p - Interim Results - Paul - H1 results as expected, and FY 6/2024 outlook remains in line (note that forecasts have been slightly reduced in the last 9 months). Balance sheet is large, complicated, and weak. Shares have had a great run, but look up with events to me now. (I later changed my mind on this, and should have stayed at amber/green with hindsight).
19/7/2024 - AMBER/GREEN at 161p - FY 6/2024 TU - interesting situation - traded in line, good visibility thanks to giant order book of public infrastructure projects. Shares have already re-rated significantly from a PER of 3.1x to 7.3x, and could possibly have further to go? I've shifted up a notch from amber to AMBER/GREEN.
On to today’s actual FY 6/2024 results.
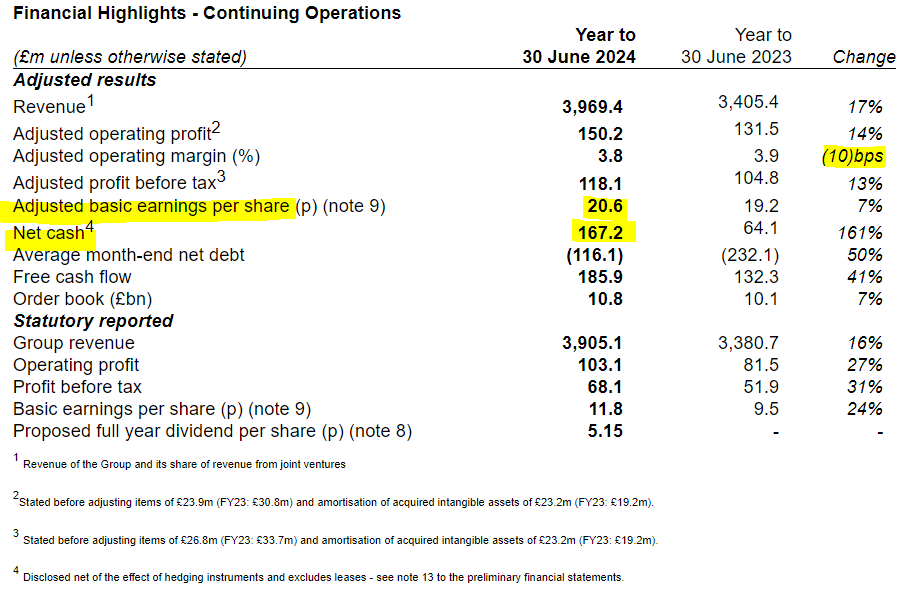
Adj EPS of 20.6p is slightly ahead of the broker consensus data we have here of 20.0p. A note from Panmure dated 16/7/2024 on Research Tree suggests 20.6p adj EPS, so it looks in line (as the co told us in its 197/2024 y/e update). So that’s all good.
Net cash - of £167m is a red herring, as the 19/7/2024 TU previously mentioned, saying that it was boosted temporarily by seasonal cash inflows from the construction division. Average net debt of £115m was the more relevant number to reflect reality. So do be careful if you’re valuing this share using the unreliable EV/EBITDA method!
Today we’re given the updated figures for average net debt, which are very similar to the previous figure of £115m -
“Average month-end net debt halved to £(116.1)m (FY23: £(232.1)m)”
That’s a very good reduction in average net debt though, good to see. Given the huge revenues of c.£4bn pa, I reckon intra-month cash/debt swings could be very large, so personally I would prefer an average daily net debt disclosure, plus high and low points during the year (for all companies) to give us the accurate reality.
Adjustments - note that the adjusted to statutory profit is a big amount in both years above, so you need to be comfortable that these adjustments are reasonable. Statutory profit margin is wafer thin at only 1.7%.
Divis reintroduced, again as expected. 1.67p interim paid, 3.48p final proposed. Total 5.15p (yield 3.5% - not bad at all for the first year of divis resuming, as there’s usually upside on future payouts). Policy is to target 3x divi cover “through the cycle” - difficult to do, as a lot of the time companies don’t really know where they are in the cycle, until afterwards!
Bank refinancing also previously announced, so nothing new there.
Massive order book up 7% to £10.8bn, so "good multi-year” visibility - but as always in this sector, investors just have to hope nothing goes wrong with any projects, since they’re low margin. It’s a bold investor who assumes that all of the large & complex projects go according to plan, with no cost overruns or remedial work that cannot be reclaimed from the customer. These big contractors have to be very well managed, otherwise it’s only a matter of time until something hideous goes wrong.
Margin upside is an interesting possibility though. Kier is one of only 39 “strategic suppliers” to the UK Govt, which have close working relationships with the Cabinet Office. Hence I can see the point that this might give those companies greater pricing power, hence there could be potential margin upside since this sounds like a moat.
“The contracts within our order book reflect the bidding discipline and risk management now embedded in the business.”
Let’s hope it doesn’t go wrong again, as it has in the past.
Outlook - it says “Current trading in-line with Board expectations”. A bit more detail - this sounds fairly upbeat -
“The Group has started the financial year well and is trading in-line with the Board's expectations. The Group is well positioned to continue benefiting from UK Government infrastructure spending commitments and we are confident in sustaining the strong cash generation evidenced especially over the last two years allowing us to significantly deleverage, increase dividends to shareholders and deliver the evolved long-term sustainable growth plan which will benefit all stakeholders. “
Balance sheet - NAV of £520m, less intangible assets of £638m, gives NTAV negative at £(118)m.
Note the NTAV includes £133m deferred tax asset, and £105m pension surplus, which the prudent might remove, taking adj NTAV down further to £(356)m.
Pension deficit contributions appear to be dwindling issue which is positive -
“deficit payments will decrease from £9m in FY24 to £7m in FY25, £5m in FY26, £4m in FY27 and £1m in FY28.”
The cash/debt position below seems bizarre - this doesn’t tie in at all with the commentary on bank facilities, which it says are much smaller than the amount drawn down below -
“The facilities comprise £250.0m Senior Notes, £260.9m Revolving Credit Facility ('RCF'), £37.3m US Private Placement ("USPP") Notes as well as £18.0m of overdrafts.”
I imagine there’s a reasonable explanation for the huge cash and overdrafts disclosed below, so if anyone has figured out this peculiar situation, please let us know in a reader comment.
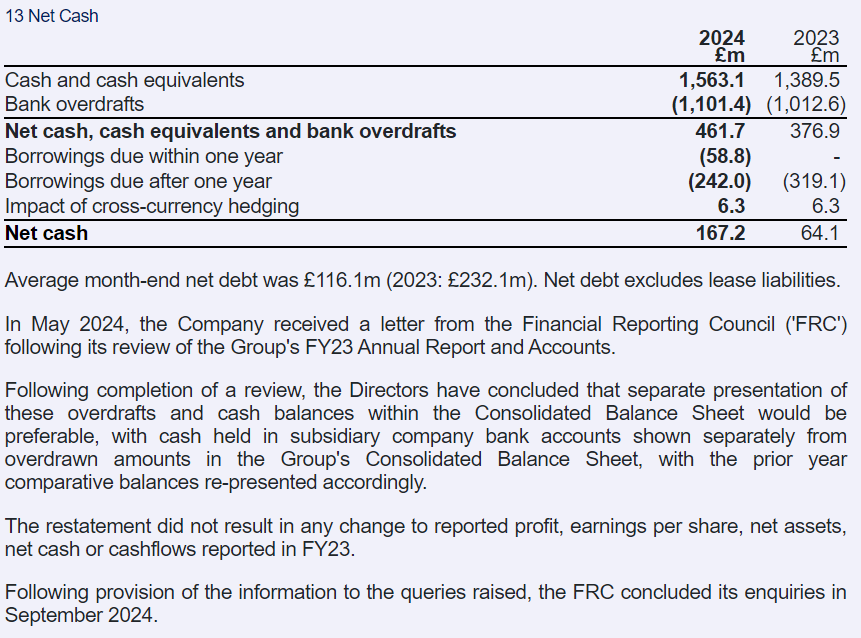
Paul’s opinion - it’s a bit more complicated than I imagined, due to all the various moving parts in particular on the balance sheet.
The bull case seems to be about potentially increasing margins, because the big infrastructure groups like Kier are important to Govt, to improve infrastructure & hence public services. Kier seems to have recovered from its past problems.
The bear case is that margins remain thin, especially if we ignore the large adjustments, and how long will it be before something else goes wrong?
Shares have nicely re-rated, which I think is justified given the progress made.
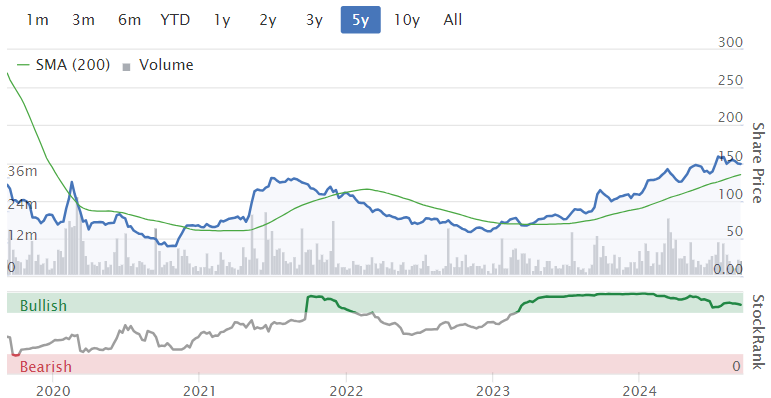
How much further upside is there? I think that depends more on investor confidence, and nothing going wrong on its big contracts. As mentioned last time, the shares could re-rate further (fwd PER 7.1x now) to maybe something like 10x, if we’re being generous? If earnings surprise on the upside, then the effect on EPS could be large, which combined with a higher PER could see shares at 200p+ if the upside case pans out.
Downside is obviously that something goes wrong, and profits are slammed with big exceptional costs. Shares crash, then the cycle begins again, as one-offs are adjusted out, and everyone focuses on recovery potential.
On balance, I think it makes sense to shift to a neutral view again, as I’ve been reminded that the balance sheet still isn’t good, although not in an alarming way.
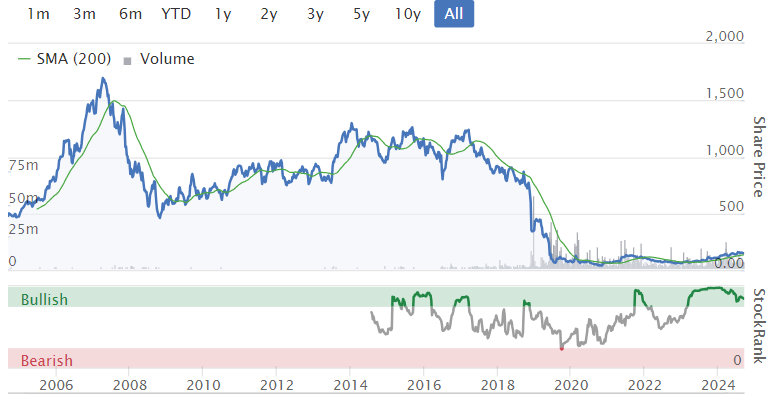
A reminder below that over the long-term, Kier shares have been a disaster, with it all going terribly wrong in 2019, pre-pandemic. The share count then quadrupled, so 150p/share price today is over 600p equivalent pre dilution that began in 2019. It seems very optimistic to me, to assume nothing will ever go wrong again, given the type of activities Kier deals in.
Roland’s Section:
Fevertree Drinks (LON:FEVR)
Down 9% to 784p (£910m) - Interim Results - Roland - AMBER
Shares in this premium mixer business are down by around 9% at the time of writing, despite some seemingly upbeat headlines at the top of today’s half-year results, such as this:
“Significant operational progress driving 520 bps of gross margin improvement and c.80% increase in Adjusted EBITDA”
When there’s a disconnect between market reaction and the tone of management commentary, I usually head for the outlook section to see if guidance has been cut. It looks like that may be the case here.
Fevertree has cut its revenue guidance for the full year, on the back of a damp summer (my bold):
“We expect to deliver brand growth for the second half of c.7% to c.10%, resulting in revenue growth of c.4% to c.5% across the full year for the Fever-Tree brand.”
Back in March, Fevertree said it was “comfortable with consensus expectations of c.10% [revenue] growth” in 2024. So the company’s original sales growth guidance for 2024 has been cut in half.
This is helpfully confirmed by a Reuters flash news update available in Stockopedia’s news feed for the shares – see here.
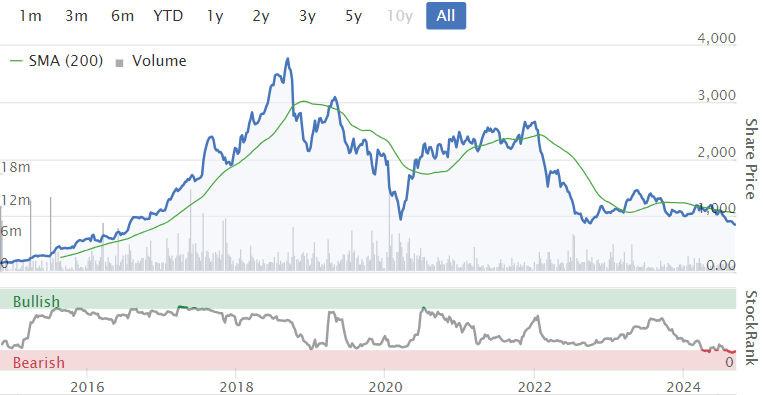
Fevertree’s share price has dropped nearly 40% in 12 months and is nearly 80% below its 2018 all-time high of c.£39. Is value finally emerging? Let’s take a look at today’s half-year results.
Half-year results summary: these figures cover the six months to 30 June 2024. The headline figures are mixed:
Group revenue down 1.5% to £172.9m
Adjusted EBITDA +79% at £18.2m (H1 23: £10.2m)
Reported pre-tax profit: £13.2m (H1 23: £1.4m)
Earnings per share: 6.49p (H1 23: 0.94p)
Interim dividend +2% to 5.85p per share
There are two elements here that interest me – the weak revenue performance and the improvement in profitability.
Revenue: today’s cut to revenue guidance is explained by a poor performance in the UK and Europe so far this year.
The “total Fever-Tree revenue” figure below is actually an adjusted figure relating to “brand revenue”, not total group revenue, which fell (see above):
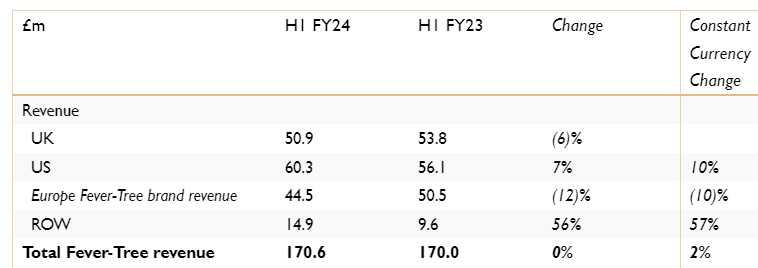
UK (-6%): poor early summer weather and “a soft Gin category” held back sales, with the company noting that rum, tequila and vodka have been the growth categories in recent years. While tonics remain the biggest seller, UK sales growth is now driven by non-tonic mixers.
Europe (-12%): sales were held back by “phasing of distributor orders” (destocking?) and poor weather.
US (+7%): on a more positive note, US growth has continued, extending its position as the company’s largest sales region. Management say tonic water and ginger beer have gained share and grown “ahead of every competitor”. New distribution agreements also helped, including Hilton and Marriott hotels.
RoW (+56%): sales growth in the Rest of the World segment appears to have been driven by a strong performance in Australia and Canada. However, I’m not sure if some of this 56% gain is a one-off, following an inventory buy-back last year. The company doesn’t split out an underlying sales growth figure for RoW, unfortunately.
Improved profit margins: Fevertree’s gross profit rose by 15% to £62m during the first half of the year, compared to the same period of 2024. That’s equivalent to a 5.2% improvement in gross margin, from 30.7% to 35.9%.
This improvement has been driven by lower costs and some price increases:
the re-tender of UK and European glass supply, contracting of improved trans-Atlantic freight rates and pricing actions taken with customers across regions.
For comparison, gross margin in the peak profit years of 2018 and 2019 was about 51%. It seems the company’s continued international growth has come at a cost to profitability.
Operating costs (staff and marketing) were broadly flat during the first half, supporting an improved operating margin of 7.1% (H1 23: 2.2%). I’d hope to see some further recovery in this towards the 10%+ levels seen in the past. Rival soft drink manufacturers such as A G Barr (LON:BAG) and Britvic (LON:BVIC) routinely achieve double-digit operating margins.
Cash & dividend: net cash was £65.9m at the end of June, representing an increase of 10% over the first six months of the year (Dec 23: £59.9m).
A quick look at the cash flow statement suggests the company has returned to more normal patterns of strong cash generation, helped by some positive working capital movements.
A further reduction in working capital is expected over the remainder of the year and management expects the company to be able to return surplus cash to shareholders in 2025. The company has prior form on this, having previously returned £50m to shareholders in 2022.
I’m reassured to see FeverTree generating cash again and do not see anything to worry about on the balance sheet.
Outlook: I don’t have access to any updated broker notes today.
The company’s revised guidance for 4%-5% revenue growth suggests we could see revenue of c.£381m in 2024.
Assuming a slight improvement in operating margins to 7.5% and applying the company’s underlying effective tax rate of 25% suggests to me we could see a post-tax profit of perhaps £23-£24m, including some interest income.
I estimate that could drop through to earnings per share of around 21p, 27% below the 29p consensus figure shown in Stockopedia prior to today’s results.
That prices Fevertree shares on a pricey 37x forecast earnings with a c.2% dividend yield, assuming my sums are correct.
Roland’s view
Today’s results appear to amount to a profit warning, but I think the underlying trend is more positive than it might seem at first sight.
I’m also reassured by the return to positive cash generation and evidence that inventories and working capital are returning to more normal levels.
Having said that, justifying the current valuation still depends on significant further growth, in my view.
After all, Britvic has just been taken over at a valuation amounting to around 20x forward earnings.
I’m going to maintain our previous amber view on this stock, as I think it’s a good company, but do not have a strong view on the potential for further growth.
Keystone Law (LON:KEYS)
Up 3% to 682p (£215m) - interim results - Roland - AMBER/GREEN
Keystone now expects revenue and adjusted PBT slightly ahead of current expectations for FY 2025
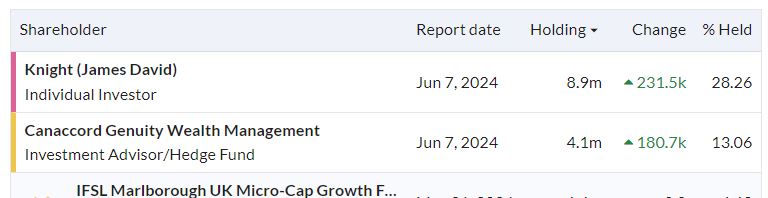
This is a listed law group that floated on AIM in 2017. It remains under the leadership of founder James Knight, who also controls 28% of the stock. So there’s nice management-shareholder alignment.
The company’s business model is also somewhat differentiated, in my view. It operates a networked business model that allows self-employed lawyers to work from their own offices, but using Keystone’s admin/IT infrastructure. So this isn’t simply a conventional partnership law business that’s listed (a model I am not keen on).
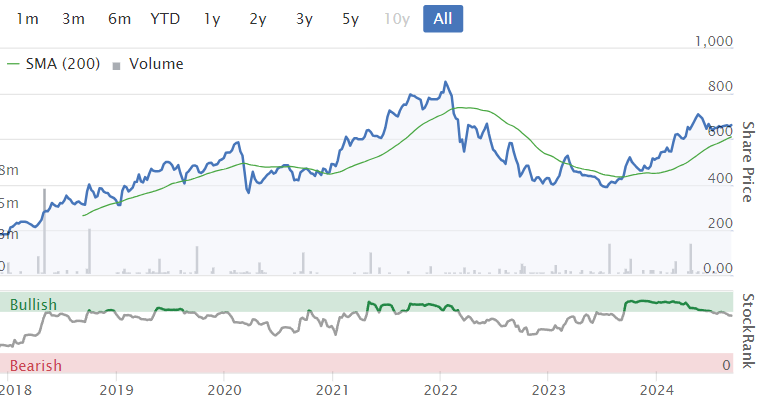
Keystone shares have multibagged since IPO, despite some weakness over the last couple of years:
Today’s half-year results are described as “strong” and have prompted management to upgrade full-year guidance.
Half-year results summary: today’s results cover the six months to 31 July 2024.
Keystone says it added 30 new principals to its network during the first half of the year, taking the total to 442. However, this is only a net increase of 10 from 432 at the end of January, so clearly there’s some attrition.
The total number of fee earners rose to 557, from 549 at the end of January.
The legal recruitment market is described as positive and Keystone has enjoyed a steady increase in demand from qualified applicants for its services:
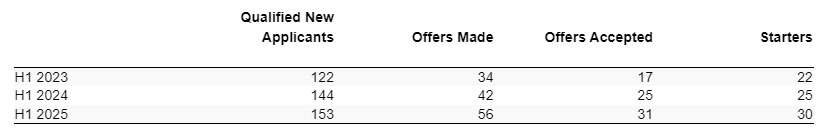
These numbers suggest to me Keystone is reasonably selective about who it accepts onto its network, an important point.
Financial results from this continued growth appear strong:
Revenue up 8.3% to £46.5m
Adjusted pre-tax profit up 7.1% to £6.1m
Reported pre-tax profit up 5.3% to £5.5m
Operating margin 10.8%
Adjusted earnings up 7.4% to 14.6p per share
Interim dividend up 6.9% to 6.2p per share
Net cash: £8.3m (Jan 24: £8.4m)
Profitability: Keystone’s operating margin seems unexciting at first glance, but this business is capital light, with only a suite of offices and some central IT services.
As a result, Keystone generates exceptional returns on capital employed. Last year’s ROCE figure was 47.3%, a new record for the business:
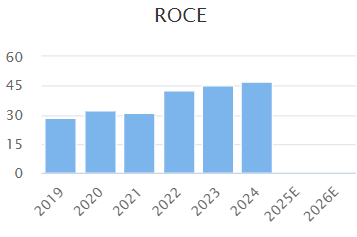
I’d expect the business to continue to benefit from economies of scale, although I’m not sure how much further this figure is likely to rise.
Even so, it’s a very attractive result for me. Keystone’s high ROCE supports strong cash generation and shareholder returns – dividends have risen rapidly since 2018 while the group has maintained a consistent net cash position:
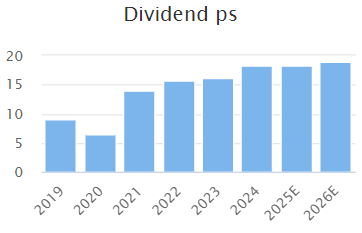
Current trading & outlook: Keystone says that a strong start to the year has given the board confidence to upgrade full-year forecasts:
the Board is confident that Keystone will deliver both revenue and adjusted PBT slightly ahead of current market expectations.
Helpfully, an updated broker note from Panmure Liberum is available today – many thanks. Panmure’s analysts have upgraded their FY25 earnings forecasts by 4% to 27.9p per share.
That prices the shares on a FY25 P/E of 24, unchanged after today’s modest share price reaction.
There’s a 2.7% dividend yield as well – modest, but the payout has risen by an average of 15% per year since 2019.
Roland’s view
I’ve become interested in this company as I’ve learned about its network model. I’m also impressed that it remains founder led, with a strong balance sheet and excellent profitability.
I don’t have any insight into legal market recruitment conditions or the ultimate growth potential of this business. Clearly, there’s also the potential its success could attract additional competition.
My view on the business is favourable, but given that earnings growth is running at single-digit levels, I can’t argue a strong case on valuation, despite the quality metrics. On balance, I’m happy to go with AMBER/GREEN here, to reflect the positive momentum and upgraded expectations.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

71 comments
Cheers Paul. I also find the talks with the fund managers the most interesting.
hVIVO (LON:HVO)
Quite surprised to see them down today after Tuesdays results which I thought were excellent.
Expected to do an EPS of 1.6p next year and will be at £50m net cash (more than 25% of market cap)
So that’s a forward rating of 13* PER cash adjusted which is just too cheap given both the moat they have in HCS as global leader and compared to other CROs.
Much is made of the £6m drop in order book but not sure why as the answer is very simple - revenue contracted for H2 was accelerated due to a customer request (which also invoked an extra acceleration fee) and this moved money from the order book to revenues. That is why H2 is expected to be lower revenues than H1. It was a just a re-balancing.
Then there is £40m worth of orders they are expecting to land to top that order book up to record highs.
Revenue diversification has begun - offering in-field patients from the database and expanding offerings in the lab. Mo put up a bridge of which revenues are expected to contribute to the £100m+ revenue target in 2028 which looks more than achievable to me. I reckon they get there well before 2028.
At £100m with 25% margins you are at £25m EBITDA (need to add £2m to that in interest alone)
So all on track and assuming they achieve that we should be looking for double or more on the share price. Even at current profitability I’d expect them to be trading 35-40p. Not sure why they are just languishing price wise - perhaps just a period of consolidation.
Any ideas on why SLP continues to fall? I thought that the bad news had already been filtered into the share price - apparently not
Simon Thompson 'sell' recommendation in the Investors Chronicle will not have helped.
The title of his article is "hVIVO has foundations for strong growth", so I highly doubt it's a sell recommendation! Plus I've never seen him issue a sell on anything, that's not his bag at all.
There are several reasons for resistance at 30p, the major one being the 2x secondary placings from Cathal Friel that resulted in his complete exit from the share register. Secondly, they haven't won many new deals this year all - the last major one being way back on 2nd January! Finally, the pace of growth has slowed dramatically meaning the PE of 21x doesn't appear cheap. I'm not a fan of cash adjusted PE's, just as much as I think 'debt adjusted' PE's would also be a waste of time.
I suspect they'll use the cash to buy something else which will boost the growth profile again, if / when that happens then shares could well break the 30p barrier.
Mortgage Advice Bureau (Holdings) (LON:MAB1) : Can buy now at 582p. Nearly 25% drop in last couple weeks. Half year results on 24th September. I hold (since 15 mins ago).
Good luck all.
Alpha International (LON:ALPH) apologies if this is boring but it's not my fault: yet again another director dealing, another by Clive Kahn. My last post on this as it now seems to be a daily occurrence!
Director/PDMR Dealing
Alpha Group International plc (LON: ALPH) announces that it has been notified today that Clive Kahn, Non-Executive Chairman, has purchased 25,000 ordinary shares in the company. https://newsfile.refinitiv.com...
Paul, Trainline (LON:TRN) l don't understand their moat. You can book direct with the train companies, no need pay any fees as booking with Trainline. Fares are same price. Why book with an intermediary if you have to pay more money? I never use them, because of the fees, I just book with my train operator, get e-tickets, easy. If you book 1 month in advance the fares are quite cheap, under £12 for over 2 hour journey into London.
It's a platform business so the 'moat' is typically 2-sided network effects. Sellers benefit from exposure to a wider range of buyers, buyers benefit from the aggregation of sellers providing a better selection in a single location. I'd assume that as the dominant player in the UK they benefit from brand recognition and scale economies, too (both weaker 'moats' IMO).
I never use it for the reasons you outlined but most people I know buy almost exclusively via Trainline- they seem to trust it. Worth noting that they have a B2B business white-labelling their solutions, no idea how much of the business that is but you may have booked tickets directly via Trainline's technology without even realising it...
Rusty2, what you have written is correct.
However, it is a pain to navigate to each train company and book tickets (especially if you split tickets across train companies), whereas Trainline provides a single portal to do the same across the UK and Europe. A similar argument can be made for using Booking.com/Expedia to book hotel rooms vs going to the Hotel company website and getting cheaper rates directly. In summary, consumer are paying a top notch booking portal, visibility on all options and convenience.
National Rail are a single platform for all train companies and route you to the correct one to book the ticket for the journey you have chosen. What does Trainline offer that justifies their fee?
You can pay for your ticket without having to leave their site, saves you having to login/register/input payment details in some cases. I think that's about it, whether it justifies the fee or not is open to debate.
Ok, please don't shoot me .. but some blurb on their competitive strengths ... investors can make up their own mind
Competitive strengths
Europe’s leading independent rail platform
We enable millions of travellers to seamlessly search, book and manage their journeys through our highly rated Trainline website, mobile app and B2B partner channels.
Market-leading customer experience
Our innovation focuses on creating a simple, consistent, friction-free experience for booking and managing travel. We bring together all carriers into one app while providing smart, real-time travel information and self-serve capabilities like journey changes and refunds.
Digital marketing leadership
We have developed a highly scalable, marketing playbook in the UK, which we are deploying across our core markets in Europe. This helps drive customer acquisition at scale while maintaining a low cost per new customer acquired (“CPA”)
Platform One – single global tech platform
As a platform business, we offer our innovative retailing experience directly to customers through our Trainline-branded businesses, while also giving carrier partners and other travel businesses access to our retail solutions to offer to their customers.
Tailwinds for growth
European domestic rail markets liberalising at pace, creating need for an aggregator
I’ve just used their service to travel across Europe, it’s amazing, collates your tickets prompts them on your phone, gives you live info, headache free when dealing with so many companies. I’m really impressed. Cost me no more really for the ease.
Uber offer a good booking service too.
I dont see much of a moat either. I book tickets at my local station for franchises and destinations not connected with that station.
The man in seat 61 seems also seems to suggest that there are no barriers to cross booking between franchises.
https://www.seat61.com/train-t...
Trainline (LON:TRN) - I think they may be entrenched with some employers whereby you have to use them under corporate travel policy, to the extent you risk not getting your expenses paid if you buy your train tickets elsewhere. I’d assume there must be some advantages to the employers using them for this service, maybe a promise to find lowest fares, less risk of false/inflated expense claims, etc. but could be sure what these advantages are and how easy to replicate for a competitor
Live at 9.30am on tomorrow's Vox Markets Exchange (Friday 13th Sept), I will be interviewing UK smallcap fund manager Brendan Gulston of Gresham House.
It's sure to be another insightful conversation - including lots of compelling stock ideas such as #AOM, #RCDO, #FNTL, #FRAN, #NET, #SYS #XPS, #MPAC & #TCAP. Alongside a smattering of riskier special situations like #AGFX and #IOM.
If you'd like to ask any questions, then please feel free join us here on Youtube. Everyone is welcome.
I find your Fund Manager interviews really helpful Paul - thanks very much!
Abrupt departure of CEO at Cambridge Cognition Holdings (LON:COG) just announced.
Great spot Paul. Do you sense a profit warning coming at Cambridge Cognition Holdings (LON:COG) ? Nothing published by their joint brokers yet either.
That said #COG are still trying to recruit a new CFO, so may not know the full scale of any possible damage?
It’s never a good sign IMO when CEO and CFO change within 12 months.
Capital (LON:CAPD) SP has been on the slide recently, meanwhile, their investment in Wia Gold seems to be doing very well for them. WIA Gold Limited's (ASX:WIA) market cap surged AU$29m last week, individual investors who have a lot riding on the company were rewarded - Simply Wall St News
Contributing materially to the current market cap,
I noted this morning that one of my holdings IG group (LON:IGG) say turnover is up15% over the previous half year. Might be a knock on to other well covered spread bet companies.
IG Index seems to be the big daddy in this sector with global reach and no market exposure (unlike some competitors). They pay good divis and also have a share buy-back in play.
The whole sector seems to be making hay at the moment.
I wondered if these companies would make a good portfolio hedge? Market meltdowns might boost profits - but apparently not if you look back over the long term share price charts. In bad time the stock falls along with everything else.
As others have said, there certainly seems to be some kind of general sell-off occurring in the last week or two broadly across a number of areas of the smallcap market and affecting shares in entirely different sectors that ought to be totally uncorrelated. This makes me less worried that the steep drops are a harbinger of some lurking terrible news on any of these individual stocks.
There are a few examples at the moment where very positive recent announcements / upgrades have been released, shares rose very strongly accordingly, but then all these gains have subsequently gradually been given up in the recent sell offs such that you can now buy the shares for the same price as before the upgrade (and with no further news or negativity anywhere to be seen). This exact situation has been the source of some of my most successful winners - it feels like having time-travelling ability as you get to buy the shares for the price before the news announcement but already having the benefit of the fruits it contained! ("Great Scott!!" springs to mind for any of the same generation as me).
There is of course always a chance that current market behaviour is all part of the general global nervousness about a looming global recession (as the US yield curve activity would have us believe) which, if a global 'hard landing' slowdown does materialise, probably means there is worse to come. So it's not a one-way bet, but it feels pretty close to one for stocks unlikely to be much affected in reality even in the event of a recession.
I am looking at two in particular which look like nailed on opportunities, but I'm not going to name them just yet as I'm still trying to buy myself! Suffice to say they are discussed in these parts and should be on the radar for us SCVR regulars.
Happy hunting folks ...
BIACS
FEVR I've been missing out on all the excitement on this one. Analysts have been downgrading their forecasts (I love that little chart that Stocko analyst consensus), which isn't what you want to see on company with a PE of 24.
This may come good again, I have absolutely no idea.
There does seem to be a bit of a popularity curse with it, though. When a share becomes too popular here, one that can't miss ™, there's an element of risk. BOO and ASC come to mind immediately , but there are many many others whose names I don't recall. The higher the profile of the investor bullish on it, the higher the profile the company becomes (I'm not taking a pop at anyone in particular, you understand).
W7L seems like another one of those Can't Miss companies, although there's no evidence of it hitting any roadblocks at the moment. Analyst estimates and performance has been robust so far.
Thought I'd share an interesting tweet by Alex Sweet.
"Fevertree depends on tonic water for close to 60% of revenue. What percentage of tonic serves are paired with gin? Roughly half, at a guess? Diageo is the world's #1 gin producer by far: Gordon's and Tanqueray the top two brands"
You can find him on his substack or X profile.
Looking at Fevertree Drinks (LON:FEVR) this morning, I thought I'd write a note about the immense power of the Stock ranks and how I believe they can really help people to avoid losing money (Buffet's rule #1).
There is so much incredible analysis here and so many podcasts, videos and financial data and insights around that it's sometimes easy to lose sight of the simplicity and power of the Stock Ranks. For those of us mere mortals who aren't trained accountants or analysts, the Stock ranks are such a great asset to keep us in the game. Obviously they aren't foolproof and I'm sure somebody can find examples of shares on high rankings that have collapsed in price but taking a portfolio approach whilst avoiding low ranked or losing style shares is such a powerful aid to avoiding bear traps.
I write this because I watched Fevertree Drinks (LON:FEVR) rocket to nearly £40 back in 2018 with real FOMO and I've watched it ever since, wondering if I should get involved. It always seems so compelling with its US expansion and capital light model but in the last 6 years, it has only once, very briefly held a Stock Rank above 80 and Stockopedia has consistently warned me off. As it tumbles again today to £7.83 I might have been tempted to bottom fish but the "Falling Star" style tells me there is almost certainly further to go or at least that it could be a long time at these lows (opportunity cost is so important especially with such a small dividend yield).
Similarly, I'm watching Diageo (LON:DGED) for all the reasons Nick Train loves it - such a great portfolio of global brands etc. but in January 2023, the Stock Ranks fell out of bed and the share price has retreated month on month ever since. I'd love to own it but that "Falling Star" rating keeps me away and helps to enforce that most important investing trait, "patience". So I shall sit and watch patiently until the Stock Ranks indicate that it might be safe to get back on board. Sure, I may miss the bottom but the ride up is rarely vertical so there will always be time to get back on the moving escalator.
Some interesting thoughts, which have mirrored some of my thinking.
Originally I avoided Fevertree Drinks (LON:FEVR) mainly as I didn't like the product - especially as the 'light' tonic contains quite a few calories and shouldn't be sold as such IMO. However, I remember sitting up and thinking that when they went to the US, that actually the market there (not in the tonic space), but for mixers for other spirits, i.e. rum would be massive.
As a rum and whisky collector, I could see the rum market was huge and had legs to move (lots of people love a rum cocktail etc), I was going to watch with baited breath. I note today that this is happening, so I can see a point where this starts to become the driver for growth - and to be fair they carry cash, but their margins are being hit. If they can start gaining more traction with other drinks partners as they do with Asahi and Makers Mark, then the market is undoubtably massive.
Looking at the share price, I'd argue the company is in a better position to secure long term growth than it ever has been, if it pulls off the above. I'd like to see a better dividend (or perhaps just wait for the price to drop further) before commiting.
With regard to Diageo (LON:DGE) I've not liked the way they've overpaid to buy growth and this is hurting them now and I would like to see a portfolio overhaul to target key growth markets and reconsider their pricing (premiumisiation) in mature markets as producers such as Mortlach have lost hoards of traditional buyers with their move to higher RRPs together with a move from 70 to 50cl bottles.
Again the share price is looking tempting, but I want to see some stronger moves by the board to unlock value.
Yes, totally agree, so it makes you wonder why Stocko can't grow it's subscribers and give Paul some help? Perhaps an Oxford education isn't enough? (ouch)
Fevertree Drinks (LON:FEVR) still seems pricey at 30x+.
There comes a time when a growing company becomes one of these two states:
In this case, maybe Fevertree is succumbing to both?
They blame "soft market demand" driven by weather, and on the surface looks like they were dependent on external forces for half their growth ambitions.
But maybe also that creating bottles of fizzy liquids, with premium branding, is rapidly becoming commoditised.
Ashtead Tech. Been a strange week since results, which I thought pretty reasonable, and liked the investment in extra specialist equiptment,: my thinking - that was for new contracts being discussed ? .Upgrades in the future ?? Mister market crashed the price nearly 25% ??strange reaction was my view ,even though at 822p [160% profit for my buying ] ,I did reduce my holding,as I felt we were ahead of ourselves. On friday noticed it now Slater zulu sieves ,so added a few @600p. Further dropped this week to 550p ,and then this morning flies up 10% . What on earth is going on ?? A fund buyiung in at a more sensible rating ?? Any views ? Tony
Morning fellas a request if you have time for a view on Brooks Macdonald (LON:BRK) looks like they have sold off part of the company, muted market response, fund management sector is unloved at the moment but trade off against that is loads of mergers and buy outs over the last few years.
Anyone else misses Mr Contrarian?
A very much liked , early morning feature in this space.
i think he takes a few weeks off a year to update his other site......https://WWW.mrContrarianswonderfulpuns.co.uk .
Another way of saying, I agree! For me he adds a breath of fresh air to morning RNS's
not sure i would enjoy investing as much, without the likes of SCVR, mr C, the teams notes and training articles (invaluable alongside all the data points/ratios) and all the invaluable contributions from posters.
keep up the wonderful work all and good luck with your investments (research?)
PS that isn't Mr C's website disclaimer
Hopefully he’s just taking a holiday and shall be back
Re the sharp fall in Warpaint London (LON:W7L) yesterday, I sincerely hope this reflects the comments made by Paul this morning about tax issues and concerns rather than insider information.
There has been some rise this morning, but not enough to dent the fall yesterday.
Finals are due on the 17th. I tried to get access to the analyst meeting on the day but was politely told no. However, it was confirmed to me by the spokesperson that there would be a presentation the following Monday 23rd on Mello,
As usual, the small investor having to wait far too long for the background behind the RNS, and the bigger people getting the advantage of asking the questions and acting on the replies.
“ I tried to get access to the analyst meeting on the day but was politely told no.”
This really pisses me off and make sure you give the management a really hard time at Mello .
Any company that treats PI with contempt gets a red flag .
I had similar push back from Crestchic when I politely asked to go to their analysts open day .
I then pointed out I held more sharres than all the analysts and maybe their clients and was duly “allowed” to go .
Ended up having a good walkround with chairman and FD, saw what was happening operationally and logistically that would transform the business as it mirrored one of the situations I had .
Meanwhile the analysts walked round with glazed eyes waiting for the prawn cocktail sandwiches and trains back to london .
My suggestion
Ask warpaint if you can come look round the operation and meet some of the team . Emphasize its “light touch” and as a point of principle you like to visit all the companies you own .
Its amazing how many times particularly on AIM they quite enjoy some shareholder genuine support and interest.
Id just prod the doors, possibly your rebuttal came from one of the crap PR companies that they are obligated to use who care even less about the actual company than the prawn cocktail analysts .
I agree with your concern about Warpaint London (LON:W7L) . For what it's worth, I apply a trailing stop loss to all of my holdings which I keep track of in a spreadsheet. I follow Ed's suggestion of varying the stop loss percentage according to the risk rating, which for Warpaint is speculative and therefore a 25% stop loss. Last night they closed at 21.9% below their high point, so I don't yet have to decide whether to sell or not.
I really hope that they don't go any lower, I suspect that as others have said a lot of small investors are worried about changes to inheritance tax and capital gains tax. I am sure that a lot of us have made substantial gains in this share since it was first flagged in the SCVR.
I have sold this morning all my Warpaint London (LON:W7L) shares. This is in large part due to the dropping prices of late but also because I have watched what has happened to US makeup-related shares, namely Ulta Beauty (NSQ:ULTA) (bought recently by Warren Buffet) and ELF (which I also own and have sustained significant losses in recently, although there might be a turnaround happening now). Estee Lauder Companies (NYQ:EL) is also a disaster. I may very well regret this come September 17th, but I am increasingly skittish in this market and especially in the makeup category.
Paul
“I suspect the UK small caps space is being disrupted by the anticipation of higher CGT in the late October budget. Hence people feel incentivised to bank profits now, to lock in a potentially lower rate of CGT.”
Given Labour’s ongoing threats to increase taxes in the budget, IMHO they are making matters even worse by not announcing their major tax measures much sooner. At the moment people are having to consider protecting themselves against all varieties of insane tax changes; whilst Labour may only enact some of them this year,
The downside corollary of this that they will probably need to introduce even more tax rises in future years as the tax take falls as a direct result of their ongoing assault on wealth generation
All IMHO. Where is the light switch?
If you're right Shanklin100 (& I think you are), then maybe the 'light at the end of the tunnel', is that there should soon be even more attractive buying opportunities for investors.
Meaning powder drying time?
I agree with that Shanklin, and what I have noticed is particular small caps that have been big winners for retail investors have really taken a bath in the last few sessions, things like Warpaint, IG Design, Journeo and so on....
None of these mooted CGT changes will improve flows in an already decimated small cap sector but maybe therein lies the opportunity?
Anyway, sun is shining, stocks are bouncing, a better day today.
I think this is a failed attempt at expectations management. The eventual tax increases probably won't be as bad as all the hype and everyone then breathes a sigh of relief.
The unfortunate this is that meantime real damage is being done to business and the economy.
My sentiments exactly!
Not sure if this was posted yesterday but IHT concerns have to adding to the this as well. Over sized moves in MAB1, AT/, decent falls in BOKU, ABDP, IPX. There is a fairly decent correlation to Octopus holdings there.
The upside surely comes as these move to the main market and get bid up by index buying - see ALPH last year, GAMA will get it soon. Just got to be mercurial in your timing!
Nice steady as you go FY24 Kier (LON:KIE) Increases dividend, keep on looking at that FCF and reducing that debt as they said they would. Give it time this could gather some pace a bit like Capita (LON:CPI) ?
Kier (LON:KIE) and look at todays market reaction - down 1.75% not the first stock to suffer when posting excellent results
Hi Bohenie, I'm not an expert on why the shares might be down, but if you look at the 2024 estimated target for net profit shown on Stockopedia, it appears to have missed it by 23%. Maybe that's why there has been a negative reaction, as the market was expecting a better result? Kier (LON:KIE)
Kier (LON:KIE) where did you get that table from Martinus67? I see stat profit before tax of 68.1 this year versus 51.9m last, up 31%...
Hi Newtarrow.
I made the table myself and populated the figures. Hopefully I am correct and did not misunderstand the figures.
Hi, No sorry I read it that you were comparing to FY23.
For fy23 stocko has the unadjusted profit figure from the accounts but the adjusted eps. For fy24 the eps forecast is adjusted at 20p. Was the 88.5 adjusted or statutory, I dont know but always get confused with what stocko is picking up. Maybe they were expecting a lot less adjustments to get to the 20p but doubling of the stat profit seems a bit unrealistic?
Hi Newtarrow, thanks for getting back to me.
I may have gotten this wrong, so thanks for the sense check. I took this figure, highlighted in red by me, and worked back to today’s announcement.
I was just trying to understand why the market took a negative stance, even with a solid +31% increase in yearly net profit, as you mentioned.
The thing that confuses me (a lot) is that if you look at the 2023 net figure, it shows net £41.1 million, but in today’s company report, it stated net £51.9 million, for last year?
Hi,
I think the 41.1 for last year is the net profit (after tax) figure. The 51.9 is the pre tax profit
Interesting new stock - Optima Health - coming to AIM on 26th Sept, after its been spun out (in specie) by Marlowe (LON:MRL) .
No fresh capital is being raised for this UK provider of occupational health services who reported March FY24 revenue & adjusted EBITDA of £110.9mn (-4% vs FY23 £115.3m) and £18.0m (-16% FY23 £21.0m) respectively.
Currently Optima supports around 170 large clients (contract size of >£100k pa) and 2,000 in total across both the public and private sectors. The UK occupational health market is forecast to grow to £1.4bn in 2028 from £1.3bn in 2023, representing a 3% CAGR - with the Board's aim to ultimately capture a 25% share vs 9% today.
However in H2'23, a major longstanding customer unfortunately gave notice - alongside another contract which was significantly reduced in size by a 2nd large public sector client who decided to take some of its occupational health services in-house.
Hence March FY25 revenue is expected to be lower than in FY24. No FY25 estimates are provided today - albeit I would guess we're talking of circa £105m & £15m in sales and EBITDA. Which if put on a 7x-8x EV/EBITDA multiple - on top of circa £20m of net debt - would hypothetically generate a marketcap of between £85m-£100m.
In comparison, Marlowe originally acquired Optima Health in Jan22 for £135m.
That said according today's demerger RNS from Marlowe - the exec team "will be subscribing for new shares at an equity valuation of £225m". Which to me would suggest Optima Health's gross margins are high (say >75%).
Implying too, if the company was ever taken-over by a trade buyer, then instead it might go for as much as 2.3x EV/sales or 16x EB/EBITDA, even for a currently declining business.
Let's see what house broker Panmure Liberum come up with later this month.
https://www.londonstockexchang...
Hi Paul H. The demerger statement talks about the Optima management subscribing for new shares at a valuation of £225m. I don't know how much this suggests that the anticipated market cap of Optima will be £225m, but it looks a more likely figure than your £85-100m if the demerger is going to unlock immediate value for Marlowe (LON:MRL) shareholders?
Reeves urged to launch tax raid on lump sum pensions
Capping tax-free allowance at £100,000 would affect around one in five retirees, says IFS.
https://archive.ph/Ob2Lv
There may be a big sell off before the budget as retirees cash in.
But only something like 4% of UK pensions is in UK assets, would that move the dial?
So I cashed in my tax free lump sum and I believe so did Simoan. I know of others in my company also doing this and the warning articles are now hitting the newspapers.
This all entails selling shares and as we know, most individuals deal in UK shares, so I suspect some volatility is indeed due to people being cautious.
As soon as you crystalise your pension by taking a lump sum, you lose the IHT protection under current rules. Reeves might ofcourse do away with the free IHT advantage. Is there a way to protect the tax free amount?
You could feed £20,000 each year into your ISA. That wouldn't protect the entire tax free amount in one go, but it would over time.
"As soon as you crystallise your pension by taking a lump sum, you lose the IHT protection under current rules."
Are you refiring the tax-free part, no longer having IHT protection, as I thought pensions in general are not subject to IHT. From Standard Life web site:
"Inheritance Tax usually doesn't apply when you pass on your pension pot. This is because, unlike other investments, your pension plan isn't normally part of your taxable estate.
That's why it can be tax-efficient to keep your pension savings invested within your pension plan and pass them on to family members or down to future generations. In addition to the potential savings on IHT, you may also get tax benefits on any future investment returns. Beneficiaries (those you want to pass your money onto) may be able to receive tax-free withdrawals if you die before the age of 75.
It's important to bear in mind that money you take out of your pension pot could form part of your estate if, for example, you don't spend it and it's still in your bank account.
Money left in your pension savings can be passed on to your dependants or family tax-efficiently, depending on:
Only by reinvesting it into a trust, an eis or seid eis last two very high levels of risk, trust also has 20% entry charge tax on any amount placed into it above £325k
As soon as you crystalise your pension by taking a lump sum, you lose the IHT protection under current rules. Reeves might ofcourse do away with the free IHT advantage. Is there a way to protect the tax free amount?
It depends on your circumstances. If you can arrange to be a non tax payer in the year you take the TFLS you can earn up to £6k of savings interest tax free. That’s £5k due to the starting rate of tax, plus your standard £1k savings allowance. I wouldn’t expect this to survive the coming budget though!
Good points Si but as you say both probably up for the chop or scaled back big time.
I think I must be a bit thick but what do you do with the more than £100k? My net worth is under £3M but my biggest problem is the amount already outside 'tax wrappers', having failed to max ISA and SIPP in the good times. The last thing I would want to do is take money out of tax protection.
Looks like a nice contract win for Gulf Marine Services (LON:GMS) with the nice line in the RNS, "revise its adjusted EBITDA guidance for 2024 to be in the range of USD 95 million to USD 100 million, versus the adjusted EBITDA guidance communicated earlier of USD 92 million to USD 100 million."
I'm in two minds about Gulf Marine Services (LON:GMS. I bought at about 5p and held for a short while but got bored and stupidly sold out. I might get back in if it drops below 15p if Seafox shareholders sell after Sept 15th. My main worry is the state of the oil market. The oil price has cratered recently and consensus is that market will be oversupplied with crude next year. OPEC have been witholding supply from market in attempt to support price but they're planning to bring back withheld supply next year. OPEC need to keep members happy and they can't do that by witholding supply for very long. The Saudis might even crater oil price by flooding market and start a market share war, as they've done twice in last decade. Saudi have got over 3m barrels a day in spare capacity they could bring back. Spare capacity is never bullish oil. China, the biggest importer of oil, is weak and their switch to EV's continues apace. There are recession fears in US and fracking goes from strength to strength. Consensus oil price for 2025 is about $70-75, not bullish. The IEA released their latest oil market report today with headline 'When the music stops'. The oil market is clearly cyclical and the good run after covid, and the boost from the Ukraine war, looks like it's coming to an end but the oil market is always vulnerable to shocks. When oil price falls then the first thing the producers cut is growth capex. This is my main worry about GMS. Can the producers cancel or delay contracts ? They'll still need GMS for maintenance capex but this will be alot less than growth capex. Gas supply out of Qatar is in big demand so GMS can still hopefully do plenty of business with Qatar Energy and their renewables business might also increase. It would be interesting to see a revenue split between Oil/Gas/Renewables. If you look at the Offshore drillers and Offshore support vessel co's share prices this year then they're similar to GMS. Valaris (NYQ:VAL) Transocean (NYQ:RIG) Borr Drilling (NYQ:BORR) Tidewater (NYQ:TDW) . Nice run but weak recently. An investment in GMS based on numbers alone looks a no brainer but as with all cyclicals question remains - are profits sustainable ? Good luck to holders.
Hi Joe,
I usually find with the Oil price that once the headlines come out the price has topped or bottomed. The people who move the market and have the real insight into demand/supply dynamics have usually done their positioning by then. So it wouldn’t surprise me if oil actually starts moving back up from here.
Note- switch to EVs actually is having very little impact on oil - the thing to look at is gasoline consumption : this was accompanied in 2019 with “peak demand” hyperbole…… in 2023 they had to admit gasoline consumption was going up again.
Never quite tell what the Saudis will do but on both occasions they over supplied the market in the last decade they recognised it was a big mistake retrospectively. I think on both occasions the minister responsible was fired. The problem for them is that in the short term the price drop is more significant than the extra barrels produced and in the medium term it makes almost no difference to their market share. So crashing the price from over supply is net negative to the Saudis and I don’t have them down as fools! I’d be surprised if they made such a mistake 3 times in a decade.
With regards Gulf Marine Services (LON:GMS) this has been on my watchlist - around 15p feels like a good entry price if it gets there. From memory and I think Paul had more insight here their equipment is used much wider than O&G but not sure quite how that translates.
Gulf Marine Services (LON:GMS)
Good questions Joe and well articulated. I don't know if the producers can cancel or delay contracts, but please do let me know if you find out!
I've been watching oil prices and various commodities retreat and am excited by this because it's deflationary and hopefully validates my expectations that interest rates will be lowered further than current market consensus.
So for that reason I have been buying shares in companies with lots of debt but the cash flow and the stated policy to pay it down, Gulf Marine Services (LON:GMS) is definitely one of those, so is McBride (LON:MCB).
But Gulf Marine Services (LON:GMS) you're right does look a no brainer, should double over the next couple of years just from predictable cash flows paying down debt which comes back to us as equity holders, however who knows what could go wrong over the next 2 years, maybe everything maybe nothing, sorry this post is rubbish, yours was much better, i'm just rambling now.........
Inspired (LON:INSE) H1 overview video & podcast.
Results are in line. Increased gross margin 10% due to product mix although increased interest on debt reduced PBT. Good cash generation to reduce debt going forward. Each division is covered in more detail. Outlook, in line with a good sales pipeline.