Small Cap Value Report (Thu 13 July 2023) - TRST, APTD, AVG, JIM

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £1bn. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
Summaries of main sections
Trustpilot (LON:TRST) - up 15% to 78p (£325m) - Trading Statement - Graham - GREEN
Pleasant news as adj. EBITDA should be above the top end of market expectations ($4m) this year. “Mid-teens” revenue growth is currently running at 18% and I remain optimistic for this company’s long-term prospects. Valuation relative to ARR remains modest, to my eyes.
Aptitude Software (LON:APTD) - down 14% to 292p (£168m) - - Trading Update & Directorate Changes - Paul - AMBER
Shares drop after an in line with expectations update, but cautious-sounding comments. So it looks as if it's in line due to cost-cutting, rather than lacklustre revenue growth. I'm struggling to see why this share commands a PER of 21x.
Avingtrans (LON:AVG) - Up 4% to 425p (£137m) - Trading Update & Possible Acquisition - Paul - GREEN
A solid, in line with expectations update. Strong order book, upbeat management commentary, and a very resilient share price further encourage me, to move from AMBER to GREEN. Valuation is probably high enough for now though. It's looking to absorb the rest of the shares in a small medical imaging company that it currently owns 18% of. Not material though at £3m deal size.
Jarvis Securities (LON:JIM) - up 1% to 147p (£65m) - Half-year Report - Graham - GREEN
Excellent H1 numbers here as Jarvis continues to benefit from rising interest rates. As I outline below, there are some significant risks involved but the stock continues to offer many attractive features for investors, including enormous profit margins and returns on capital.
Paul’s Section:
Aptitude Software (LON:APTD)
Down 14% to 292p (£168m) - Trading Update & Directorate Changes - Paul - AMBER
Aptitude Software Group plc (LSE: APTD), the specialist provider of Finance Digitalization and Subscription Management software, today provides an update on trading for the six month period ended 30 June 2023 as well as notification of changes to the Board.
The first paragraph sounds fine, so it’s a surprise to see the share price down 14% -
The Group will show modest revenue and profit progression to H1 2023 despite the macro economic headwinds faced by the sector and the economy generally. The Board are confident that the Group will meet profit expectations for FY2023.
However, the update then mentions some more cautious/downbeat things -
Higher customer churn seen in 2022 has continued in 2023.
ARR rose 3% Y-on-Y, but fell 1.4% in the last 6 months suggesting a mature, or even slightly declining business.
This sentence is strangely worded. Is it trying to say that customers are cutting back on their spending? -
...certain clients monitor spend as a result of wider economic uncertainty and high inflation.
Use of the phrase “heritage products” is unnerving, with lengthened sales cycles.
Cost cutting done in H1.
Net funds of £12.2m.
CEO stepping down immediately after a 3-4 year stint, and is being replaced by a regional CEO on an interim basis. This suggests investors are not happy with performance or strategy maybe?
Paul’s opinion - it sounds as if growth has stalled, which makes me question the premium valuation. Stockopedia shows a PER of 21.1x, which doesn’t look justified when hopes for growth seems to hinge on a new product.
Overall then, I don’t see anything of interest, so will be neutral, AMBER.
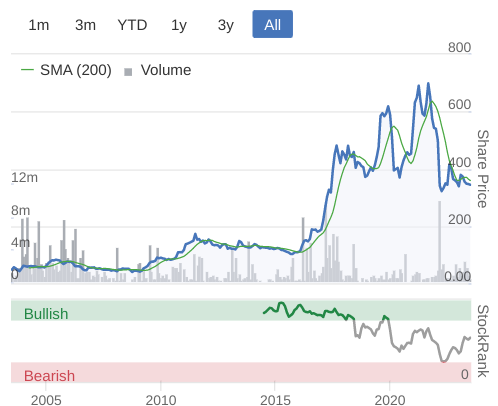
I suspect the downtrend may continue -
Avingtrans (LON:AVG)
Up 4% to 425p (£137m) - Trading Update & Possible Acquisition - Paul - GREEN
I last looked at this group here in Feb 2023, with an amber view - noting its in line with expectations trading, and a strong balance sheet (albeit with unusually large receivables, which I queried).
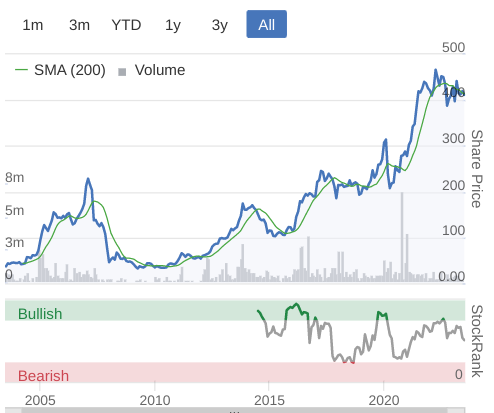
As you can see below, the long-term share price performance at Avigtrans has been excellent, and particularly resilient in the last year or so, when almost everything else in the small caps space has been relentlessly falling this has been solid -
What’s the latest today?
Avingtrans plc (AIM: AVG), the engineering technology group, announces a trading update in respect of the financial year ended 31 May 2023.
Given the wobbly macro outlook, this seems pretty good to me -
The Board is pleased to report that the results for the year ended 31 May 2023 are expected to be in line with market expectations*.
*Consensus FY23 Revenue, Adjusted EBITDA & Net Cash of £108.9m, £13.5m & £13.6m respectively
The momentum from FY23 has continued into FY24 and the current order book has continued to strengthen leaving us with a record order book for this time of year.
The Group is also pleased to announce that it has secured a number of positive contract wins throughout the period, notably in the nuclear sector, several of which have been set out below…
Outlook comments from the CEO sound positive -
"We are delighted by the performance of the Group in what have been difficult market conditions, including on-going supply chain disruptions, albeit that these have eased somewhat from their nadir. Despite the headwinds, order intake has been robust, notably growth in Engineered Pumps and Motors (EPM) has been particularly strong. As a result, we are pleased that the Group is entering FY24 with the best order cover since prior to the pandemic which leads the Board to view the outlook for this year with confidence."
Forecasts - no broker research has filtered down to me unfortunately, so I’ll have to go with the broker consensus figure on the StockReport, which is 22.4p for FY 5/2023, and 24.0p for FY 5/2024. Those give PERs of 19.0x and 17.7x - not bargain basement by any means. Although if you think the company will beat the FY 5/2024 estimate, then valuation could be acceptable.
Paul’s opinion - the long-term track record at Avingtrans speaks for itself, and this group has been good at creating shareholder value.
I also like the upbeat tone & content of today’s update, the group seems to be doing well despite tough macro.
Although valuation looks fairly full, I think it has to be GREEN here.
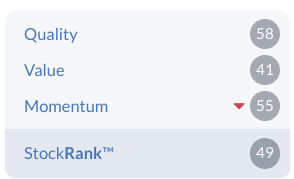
Stockopedia's computers are a bit more hesitant -
Graham’s Section:
Trustpilot (LON:TRST)
Share price: 78p (+15%)
Market cap £325m ($423m)
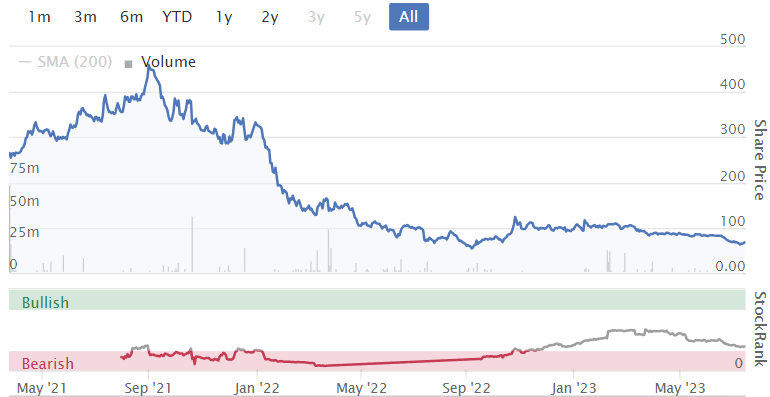
I’ve noted previously that this is “much riskier than the type of companies I usually like”, but continued to view it positively ever since reviewing it last September (share price at the time: 71p). Perhaps I should try to exclude this fact from my thoughts, but I couldn’t help noticing that it IPO’d at 265p as recently as March 2021!
Today brings an H1 update, with the following table:
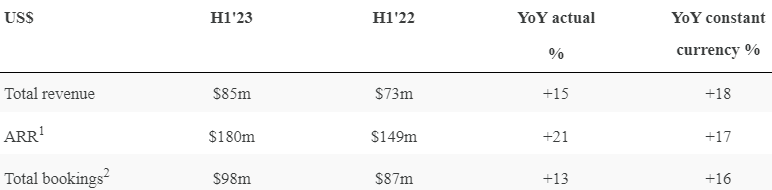
In March, the company issued a revenue warning, stating that constant-current revenue growth in the current financial year would only be in the “mid-teens”.
However, 18% revenue growth in H1 is really at the top end of “mid-teens”, and we get the following outlook statement:
We reiterate our expectation for FY'23 of mid-teens cc revenue growth. Due to resilient trading combined with improved operational efficiency, we now expect like-for-like full-year adj. EBITDA above the top end of the range of market expectations (excluding the effects of IFRS 15 - see note 6 below).
In a footnote, the company says that it considers market expectations to be for adj. EBITDA of $2.4m - $4m.
However, the company expects to report adj. EBITDA of $3m in H1 alone, so it’s reasonable to look for a full-year result that’s over $4m!
These might not seem like very big numbers, but they are a considerable improvement on last year, when the company generated adjusted EBITDA losses for both H1 and for the full financial year.
Other key points:
Strongest bookings growth was seen in Europe and Rest of World (21%).
North America was slower at 11%; the company says that the situation improved there in Q2 with a new marketing strategy.
New CEO - as we already knew, Trustpilot’s founder wants to take a backseat. The company says it is “pleased” with the progress made in the search for a new CEO.
Graham’s view
I continue to view this as a unique company doing things that very few other companies are doing and that few other companies can do, as Trustpilot has already built a powerful brand.
The major competitive threat, that is true for many ambitious online businesses, is posed by the tech giants. Could Alphabet (in which I have a long position) create a rival product? Alphabet already has a rival product in the sense that businesses are rated on Google Maps, and these ratings can sometimes be very useful. But this product, to my eyes, still falls very short of the Trustpilot system.
So I like the business in principle, but I don't give something the thumbs up if the valuation scares me away. Annual Recurring Revenue here has reached $180m, so the company is trading at c. 2.3x ARR. This is before making an allowance for the company’s large cash balance (over $70m as of December 2022).
This is about the same as the valuation it was at before, and is much lower than I have seen many other companies trading at (especially in the US), so I have no reason to change my view on this one. It’s one of the few 2021 IPOs which I could potentially back for a recovery:
Jarvis Securities (LON:JIM)
Share price: 147p (+1%)
Market cap: £65m
Let’s catch up on the news at this small stockbroker. We have interim results:
Revenue +17% to £7.3m
PBT +23% to £3.8m
Earnings per share +16% to 6.52p
There can be few complaints about these numbers.
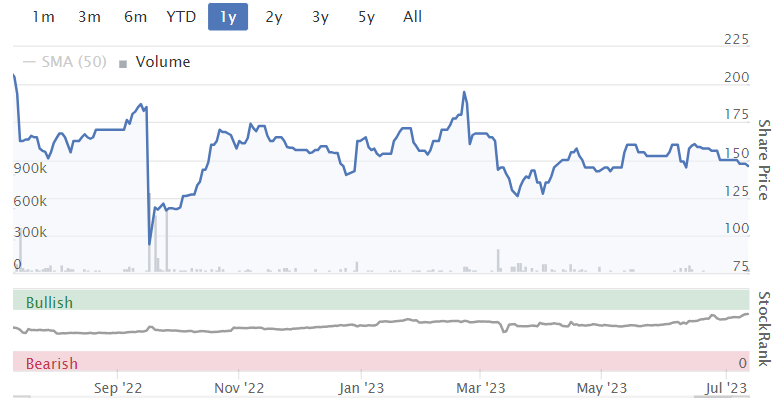
As noted in this report last September and again in March, Jarvis is working on some regulatory matters and this has put a cloud over the stock.
This chart shows where the market learned about the problem; the stock fell almost 50% that day, but has recovered most of those losses:
The Chairman updates on the “skilled person review”:
We have increased the resources in our compliance department to undertake this work, and we anticipate that even when the review is satisfied, we will continue with increased compliance resource within the firm. As part of the review, we have over the last six months been exiting some model B relationships which posed a higher than tolerable risk level for Financial Crime and Money Laundering compliance. This has resulted in a reduction in assets and cash under administration and has been a difficult transition for all parties involved.
Under what is known as “Model B”, firms such IFAs and smaller brokers can outsource a range of services to Jarvis, but there are clearly some regulatory factors that need to be revised.
As for the simple share dealing business, Jarvis reports that volumes remain subdued (no surprise there) but it continues to benefit from rising interest rates, as it gets to keep the interest earned on client cash. It could be argued that this is unfair, but on the other hand the share dealing charges are very low (£5.95 fixed dealing commission). In their own words:
Interest income has always been a significant contributor to the business model enabling Jarvis to maintain its fixed low-cost commission which has not been increased for over 12 years despite rising costs and the recent high levels of inflation.
Graham’s view
Jarvis keeps its reports short and sweet, and I like that. There’s not much more to analyse, so let me sum up why I remain positive on this one:
I expect interest rates to remain at “normal” (higher) levels for the foreseeable future, which will make interest income a regular and significant contributor to profitability.
I continue to suspect that Jarvis will emerge unscathed from the skilled person review.
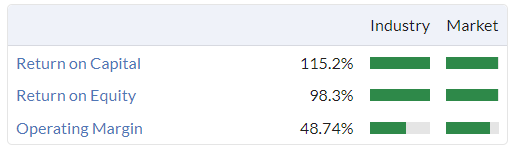
Profit margins and return on capital remain amazing. The PBT margin was over 50% in H1. Look at these quality metrics:
Valuation. According to Stockopedia we have a PER of 11x and a dividend yield of 8.5%.
The company remains under the leadership of founder Andrew Grant who has been running it since 1984 and who remains by far the largest shareholder.
To keep things balanced, here are some negative possibilities:
Interest rates could fall again soon, depending on economic conditions and the thought processes at the BoE. That could reverse the gains in profitability we have been seeing here.
X-O only deals in UK-listed stocks. With UK markets underperforming for several years, X-O can’t offer any foreign opportunities, and foreign shares may be more popular in future.
The regulatory review could result in fines or other very negative consequences. It’s not possible to predict these things with any certainty.
Competition is intense among stockbrokers and as I’ve noted previously, X-O does need to work hard to maintain a competitive offering in this market. They may need to invest more in the future in order to do this.
We don’t have transparency on where client money is deposited, so it’s not possible to judge the credit risk that the company accepts in order to generate interest.
Overall, I remain positive on this one, and it’s still one of my favourite financial stocks.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

60 comments
Thank you Graham for your comments on Jarvis Securities (we hold), the loss on AUM is explainable but large so I'm minded to remember the adage, Turnover is Vanity and Profit is Sanity on this one. Not quite the same at T Clarke.
Jet2 (LON:JET2) With all the talk of Philip Meeson possibly selling his large holding after stepping down, looks like hes giving a signal to the market today, buying £168k worth.
obviously 168k means nothing if you already hold 39,32m shares @ 1166,5p.
For anyone who cares US stocks, there will be a 'Special Rebalance' of the Nasdaq 100 Invesco QQQ Trust Series 1 (NMQ:QQQ) announced tomorrow 14th July and taking effect before the market opens on July 24th. Only happened twice before, 1998 & 2011.
A special rebalancing, which is part of Nasdaq 100's methodology to maintain compliance with a U.S. SEC rule on fund diversification.
The special rebalancing may be conducted at any time if the aggregate weight of companies, each having more than 4.5% weight in the index, tops 48%, according to Nasdaq. During the rebalancing, it is capped at 40%.
Microsoft has the largest weight at 12.91%, followed by Apple at 12.47%, Nvidia 7.04%, Amazon 6.89% and Tesla 4.50%, according to Refinitiv data.
More info in the link
Reuters story link
I have had this stock called Pagseguro (PAGS) on my watchlist for a while (I think I read about them in the IC or perhaps another publication a couple of years ago when they were flying high) and imo the chart is starting to look very interesting. Also the stocko metrics look very impressive (you will need the US subscription); but there is very little information I can find when trying to research the company. Is anyone familiar with them?
They are a Brazilian digital payments and banking company (listed in the US), mainly targeting SMEs.
The stock price has been as much as 6 times higher than current levels. In August 2021 there market cap was about £14b on a lofty pe rating in the 40s. They are now trading at a pe of 8, with a peg of 0.6.
Their projected growth is still very strong and I know from the limited research information available that they are looking to expand across the South American market.
There last results in May were a small beat and if I remember correctly the stock bounced about 15% but has been struggling to make ground since. I am hearing that the Brazilian economy is actually quite strong atm (having raised interest rates high and early) and they have a reasonable hold on inflation. So I am hoping for another beat in I assume an August update. So I think this could represent the bottom of the cycle for them and could be a good entry. The stock price has been volatile over the years - and it has shown the ability to bounce back significantly.
I have taken a small position (less than 3%) as a bit of a punt - it will have to be small as I just can't find enough information about them. So my punt is based on them having a very good track record historically for growth. I think they have been through a really tough economic period - and have actually come through in tact and looking quite strong. A resumption to better times seems a realistic bet. I think the sector is still offering a good growth runway and I am happy to have some exposure to the Brazilian market which I think could be a very good performer over the next few years.
The main bear arguments are that its a very competitive sector and earnings visibility is not easy. Also Brazil has had a lot of political instability recently. And also that there is so little information about the company it becomes a bit of a black box situation.
So I am interested if anyone knows anything about PAGS? I am also interested on peoples views of investing in a company where you have such little available information - does a small punt seem sensible - or am I utterly mad?
(ps. Apologies for it being slightly off general discussion topics - not a UK smallcap but hopefully one or two people may have interest)
cheers
Matt
go for it - it's a Super Stock. Punts are confined to illiquid Sucker Stocks.
Here is a recent article on PAGS:
https://turtles.substack.com/p...
I bought it much further up. Operationally, it is delivering less than I expected when I invested, but still in the right direction. I have found their website fairly informative with regular investor presentations etc.
HTH
Many thanks jinjah. That was a very interesting article. I had forgotten to mention the currency risk, which is always a big concern when investing within certain regions. Anyway many thanks again for sharing the link - I have been really struggling to find any independent analysis - this was great!
cheers
Matt
Paul, thank you for covering Avingtrans (LON:AVG) but I think that you have failed to recognise the potential of the Adaptix acquisition if it completes, which could indeed be material to future earnings. In short Adaptix has developed a portable X-ray unit for 3D imaging (CT imaging). The device has FDA approval and will enter the American market shortly. Its application is in small scale orthopaedics (knees, wrists) and also the small animals (pets) market.
Magnetica the medical division of Avingtrans (LON:AVG) is working on a portable MRI unit in tandem with the Adaptix X-ray device. It is using the information gained by Adaptix, both regulatory and technical in the development and path to market for its MRI unit. X-rays and MRI (Magnetic Resonance Imaging) are complimentary technologies not competing.
My one question is that Avingtrans (LON:AVG) appears to be paying less for the 89% of Adaptix that it doesn't own that it paid for the 11% that it currently owns. Having said that money was very cheap at the time of its initial purchase and is now much more expensive, 0% v 5%ish interest rates. I don't know the financial details of Adaptix and there will no doubt be marketing/distributing/regulatory costs associated with its portable X-ray unit.
The proposed £3m acquisition, which has been accepted by the owners of Adaptix is being paid in shares, so they must be confident in Avingtrans (LON:AVG) ability to successfully commercialise the portable X-ray unit, otherwise they wouldn't be accepting shares.
For a better explanation you may want to watch the VOX market interview that Paul Hill did with savvy management team at Avingtrans (LON:AVG) , Steve MaQuillan (CEO) and Steven King (CFO) in February. Link below.
I hold and fully admit to bias!
Q&A with Avingtrans CEO, Steve McQuillan & CFO Stephen King - Vox Markets
Sosandar (LON:SOS) FY2023 results presentation, given earlier this week video & podcast.
Strategy
Outlook: strong start to the year, primed for growth with the intiatives above, with the teams, systems and infrastructure to deliver growth to be one of the world's biggest fashion brands.
Well done, dumping losers, especially big ones, is the hardest thing you can ever do.
I bet you'll find a huge weight has been lifted off your shoulders. Now every new trade you make, have a plan and an exit strategy.
If you're looking for new ideas to replace the losers I am doing an all day live zoom event tomorrow, be using sreens to find new ideas and make trading plans from those, also be doing some order book and level 2 analysis - lob me an email if you might like to attend at robbiethetrader@aol.com.
If anyone is thinking of dumping losing shares and building a new portfolio put on "Rip it up and start again" by Orange Juice while you're doing it, might help.
Interesting discussion with Megan yesterday thanks and will re-listen when less tired after a days work. Very interested in spread betting and had mindset of a day or two not a month. I stopped using stop losses the market seems to know where you put them and if can stomach the loss they do recover particularly if a good share to start with which as you say stock provides the fundamentals net. And using Level II to confirm and time the entry. Will look you up when have time to devote properly.
Wynnstay (LON:WYN) H1 results presentation from last week video & podcast. I'm sure Paul wrote about them but I can't find that - certainly he mentioned in his excellent weekly podcast.
2022 benefited from the high fertiliser costs which were obviously not repeated in H123. The H2 outlook is encouraging
As Paul flagged, they are interesting to listen to, not only because they are trustworthy management with a reliable business but also because they give an insight into the macro environment for farmers and agriculture, especially with inflation where we learn:
Hi Paul,
I am thinking of transferring my SIPP to a new provider. From Smart investor to ii.
I noticed you did this a few months ago (not necessarily the same providers!)
Would it be appropriate to ask how was your experience ?, how long were you locked out? Is it worth it?
Many thanks.
SIPP Transfer to II.
This is slightly off topic - but relates to transfers generally & II.
Seems to depend a lot on what you hold - I only hold UK stocks & Investment Trusts and have found transfers generally reasonably easy & not too slow. For some reason, transferring open ended funds seems much more of an issue and can incur significant delays (albeit this experience is 10 years old from when I was dealing with my late father's assets). I'm not sure, but there could also be the requirement to confirm that you've read the KIID for some collective investments.
If you hold & want to transfer anything remotely out of the ordinary, it's worth checking first with II that they will let you hold the asset as that could be a significant stumbling block. Eg Tritax Eurobox - II would let me buy the less liquid Euro denominated BOXE online without hassle, but to buy the £ denominated shares EBOX which they don't list, I had to do a telephone trade (at online commission) and had to be read a script & confirm I'd read the KIID........
II seem pretty good at admin generally but, when I was trying to transfer shares within II as executor for my mum a couple of years ago, they were much more painful than Iweb. I was told that I couldn't speak to them - but that turned out to be wrong.
Taking money out of the SIPP has generally been OK - but be aware that it's typically nowhere near as simple as a withdrawal from an ISA / trading account. And, in my experience, SIPP providers tend to work to rigid timescales which means it can take several weeks before you see the cash! Urgent withdrawals seem to be impossible
Good luck!
I've had accounts with ii for some years now, and during that time they have twice launched a "new and improved" website that on both occasions has, imho, proved to be a dog's dinner. I much prefer Degiro whose website is clear and simple, as well as being considerably cheaper.
I have my SIPP with A J Bell, who started out as a bit of a SIPP specialist. I think that they are excellent.
To all the Pauls, take a bow:
National Paul Day is annually observed on July 13. The purpose of the day is to express our appreciation for everyone named Paul, so if you or someone you know is named Paul, please take this opportunity to recognise them (or yourself!).
Had to Google this as a Paul and its real !?! Will have to tell da missus - I might get a special treat Oy Oy !!
I really enjoyed the Naked Trader interview organsised by Stockopedia last night. Really insighful interview with Robbie Burns - I will buy the book being released tomorrow.
It's a good read, pre ordered a copy.
Link for those interested -
Is there a link to that interview?
I had an email from Lawrence with a link to last night session.
Very enjoyable one hour with Robbie Burns last night. Pity it got closed off after one hour but hope Megan's house didn't burn down. A repeat webinar sometime would be welcome! Some simple but excellent advice eg. never average down...I have certainly been guilty of that in the past. Interesting that he has made more money over the last 3 years by shorting than going long. I am sure like many it is something I have long been meaning to do but never got round to, mainly because of the perceived complexity.
Interesting session with Robbie Burns last night, he seemed to want to continue, in an effort to change my mindset, I have dumped a bunch of loss making shares this morning
Hope your loss making shares didn’t include Watches of Switzerland (LON:WOSG) which is a significant loss maker for me but is up over 13% today! In his interview Robbie mentioned couldn’t understand why people would still hold at huges losses the likes of Boohoo (LON:BOO) &Saga (LON:SAGA) which they had followed various commentators into. He carefully didn’t mention the SCVR!! I know he is keen on stop losses but in my experience when I used them the sold shares nearly always recovered. Having said that when I decided to hang on to shares they kept on going down.!! Stocko metrics can help with decisions but even then it is easy to get it wrong!
You should sell if the fundamentals of a business have deteriorated, but not just because the share price has fallen. Small cap for share prices in particular are not always rational. Would never use stop losses as you could end up locking in losses and not benefit from any future recovery. If you've done the research and still believe in the company's prospects then why sell?
The main lesson from Robbie seminar was: DO NOT AVERAGE DOWN!!
And yet Warren Buffet says "I buy when it's cheap, and if gets cheaper, I buy more". I think this is a traders mentality - don't catch a falling knife. Never heard Warren or Charlie or any of the great long term investors ever say this - they're all pretty much like Warren. Many ways to heaven though and I like traders selling when the market looks rough - if the business is sound then those create bargain moments.
TOTALLY agree Lucky Dip.
'Double downing' on losers is extremely dangerous, especially in small/microcap land. If you're wrong (which I am 37% of the time) - then recognise the truth and don't throw good money after bad.
It's one of the fastest routes to poverty
As predicted, the housebuilders had a shake out led by Barratts. The news is hardly a surprise as transaction volume is down due to higher mortgage rates. Barratts is managing the risk well by building fewer homes.
The interest rate is near its peak. The government has instructed the lender not to repossess , owners want to keep their homes at the expense of cutting other costs.
Housebuilders as a sector are not laden with debt, in fact they have plenty of cash. Generous dividend of 10% can be cut if the circumstances get tougher.
The imbalance of demand and supply remains, if landlords are selling , the big institutions are entering the rental market.
Looking beyond the next two years, I think the sector offers outstanding value for me.
Ten percent only because the current share price is so depressed. As the price rises so does the dividend drop back. Nothing to see here except for the blind. Other than this it pays well to hold on and wait for better times in house-building, or as Lucky dip says, buy the dip.
M Winkworth (LON:WINK) Forgot to mention profits warning yesterday from due to slow down in sales market due to mortgage approval hold ups. Rentals still holding up. Prices more or less unchanged.
Shall we all club together and buy Unbound (LON:UBG) for £651.56k?
Need to find a CEO that is more interested in bunnions and corns than curated omnichannel customer experience
Across several touch points, obvs.
Eliminate the k and that was my fortunately small initial investment (part of £2,5k invested in the Electra Investment Trust positively reviewed in the SCVR at the time) in Unbound (LON:UBG). Now worth about a fiver so won’t be averaging down
Happy to come in as CEO on a reasonable package with upside based on performance!
Positive trading update from Avingtrans (LON:AVG) that reports a record order book and confidence in meeting market expectations.
Also an interesting development regarding Adaptix in which Avingtrans (LON:AVG) currently holds a little more than 11% of the equity. Adaptix has devloped a portable X-ray unit incorporating 3D imaging technology that received FDA approval at the start of the year. The Adaptix unit is focussed on the examination of knees, wrists etc with further application to small animals. Avingtrans (LON:AVG) has tabled a proposal to aquire the whole of Adaptix for a further investment of £3m payable in Avingtrans (LON:AVG) shares, The proposal has been accepted subject to no higher competing bid being received by 21 July.
The Adaptix X-ray unit is being paralleled by Magnetica, the medical division of Avingtrans (LON:AVG) that is developing a portable MRI scanner for similar applications.
Exciting times I would suggest. I expect the market to react positively to the update but given its depressed state especially for UK small caps I take nothing for granted.
Market consensus is for Avingtrans (LON:AVG) to close the year with net cash of £13.6m.
As you may have guessed I hold.
Views and observations invited.
Good spot - looks an under the radar stock with no debt and a quiet bulletin board and although a fairly high PE has potential to grow strongly if Adaptix delivers . Paul reviewed it on 22nd Feb and although overall looked fine had concerns over receivables - '£25.7m “contract assets” was included within receivables - as I understand it, this is where work has been carried out on contracts, booked as revenues, but not yet been invoiced. This seems an unusually large number, so I’m raising an amber flag here. '
Do you know if these have been received yet?
Avingtrans (LON:AVG) subsidiary Maloney Metalcraft has a major contract underway with Sellafield for the supply of 3m cube low level radioactive waste storage boxes…I’d expect that alone would lead to a build up of contract assets, Hayward Tyler will also have sizeable contract assets in the normal course of business….given their counterparties id not be concerned about bad debts. I don’t hold but follow
Avingtrans (LON:AVG) has been covered in various interviews with Christopher Mills by Paul Hill, you may want to seek those out.
Here is the latest one, last month: https://www.stockopedia.com/co...
£JIM
"Cash under administration has decreased 31.2% versus 30 June 2022"
Pretty sure we could have usefully been told this much sooner. If this isn't worth disclosing, no company should ever have to disclose anything between results statements.
Been rescued for now by increased interest margin.
Jarvis Securities (LON:JIM) 's cash fall is due to exiting some model B relationships, which we knew was happening.
MrC, Agree we knew some Jarvis Securities (LON:JIM) clients were being managed out there no clue that would lead to such a large (31.2%) decrease in CaU.
Jarvis Securities (LON:JIM)
Their last annual report stated: "Their [Model B customers] loss will have an impact on trading volumes, but the impact on cash under administration will not be significant as their clients do not hold large cash balances at Jarvis."
But today they're saying that the large drop in cash under admin is due to the loss of Model B customers. So I'm confused, this makes it hard to work out how the underlying business is doing (pretty average, I'd assume, but we're in a bear market, so no surprise if that's the case).
The rise in interest received was more or less as expected. One of the benefits of the trading platform businesses is as transaction volumes drop, interest payments increase.
timarr
My broker used them, now changed ,no reason given but as quite a complicated manoeuvre I presume there was one.
Surely cash under administration doesn't just mean a cash balance belonging to a customer earning interest but the value of customers investments and any surplus cash. A customer moving his investments to another broker would affect CUA but not have an immediate effect on cash flow or profit. Maybe Graham will comment on this point, he's done an excellent "warts and all" review today.
My broker was using LON:JIM for its model B relationship. They are moving away from them. I had a few different accounts with them and cash of £500,000. Jarvis pay no interest. When you sell any investments, they hold onto the cash and only send it if requested to do so. I have not been happy with their service and have moved my accounts away from them. So loss of model B clients can lead to a loss of cash under management.
Jarvis Securities (LON:JIM) In which month did you/your broker remove assets from Jarvis? I'm attempting to determine how much of HY23 may have been affected by the changes.
If you ate asking me, I think process started about 6 months ago and has recentltly been completed.
Good Morning Paul and Graham,
If you get time, I would welcome your analysis and comments on Dr Martens (LON:DOCS) Q1 trading statement.
My read on it is that everything has been pretty crappy, but they are being very careful to say that ‘it’s all as we expect, don’t worry everyone’!
Thanks.
My morning smallcap tweet: A volley of news
Arix Bioscience (LON:ARIX) Trustpilot (LON:TRST) Avingtrans (LON:AVG) Novacyt SA (LON:NCYT) Seraphim Space Investment Trust (LON:SSIT) IQ-AI (LON:IQAI) Proton Motor Power Systems (LON:PPS) Helical (LON:HLCL), Hays (LON:HAS), Corero Network Security (LON:CNS), GYM (LON:GYM), Aptitude Software (LON:APTD)
◄Arix Bioscience (ARIX)► strategic review to include investment and realisation strategies, capital allocation and shareholder returns policies, and a tax-efficient wind-down. [SP=97.56 Cap=126m]
◄Trustpilot (TRST)► guides H1 rev up 15%. Expects FY adj EBITDA above the top end of the range of market expectations of $2.4-4m with rev in line. [SP=66.97 Cap=280m]
◄Avingtrans (AVG)► guides FY-May in line with market expectations. New orders. Offers £3m in paper for the remaining shares in Adaptix, the emerging MedTech business. Accepted by the majority of Adaptix shareholders. [SP=412 Cap=133m]
◄Novacyt (NCYT)► AGM due on 10 Aug cancelled and will be held by the end of October. Cites delayed FY accounts and offer for Yourgene Health. [SP=43 Cap=37m]
◄Seraphim Space Investment Trust (SSIT)► share buyback programme. Investment activity has been robust. [SP=26.1 Cap=62m]
◄IQ-AI (IQAI)► subsidiary gets FDA Orphan Drug Designation (for gallium maltolate for the treatment of pediatric glioblastoma multiforme) extended to non-adults. [SP=2.55 Cap=5m]
◄Proton Motor Power Systems (PPS)► follow-on order from DB Bahnbau Gruppe. Delivery Q1 2024. No £££. [SP=8 Cap=124m]
◄Helical (HLCL)► AGM trading stmt - 'good progress'. In line? [SP=268 Cap=331m]
In line: HAS, CNS, GYM, APTD
Polar Capital Holdings (LON:POLR) - "Investment returns mean that FY24 starts well" (note: https://www.equitydevelopment....)
AUM was up 3% over Q1 of FY24, from £19.2bn on 31 Mar 23 to £19.7bn on 30 Jun 23. Investment returns were strong over the quarter, contributing +£700m (+4%) to AUM growth. Net flows were negative at -£201m, but the trend continues to improve from the technology sector driven outflows of calendar year 2022 (we remind readers that over FY23 to 31 Mar 23, technology strategies accounted for £1.2bn of the £1.6bn total net outflows). The closure of the Melchior European Absolute Return fund also decreased AUM by £7m.
Polar reported continued demand and inflows into its Sustainable Emerging Market Stars, European ex-UK Income, Healthcare Blue Chip, Biotechnology, and Smart Energy Funds with combined net inflows of £313m. Importantly, with 38% of AUM in technology strategies, the rate of net outflows from open-ended technology funds continued to decline, with just £103m of net outflows in Q1.
The Q1 AUM level is ahead of the trajectory required to meet our FY24 AUM forecast, but being so early in the financial year, we believe it would be premature to revise forecasts at this stage. Our fundamental valuation remains at 625p per share, 32% above the share price, and we maintain our position that there is strong potential for both a company and sector re-rating.
Brooks Macdonald (LON:BRK) - FUM closed FY23 (30 Jun 23) on £16.9bn, 7.5% up y-o-y (30 Jun 22: £15.7bn) and 0.3% up over Q4 (31 Mar 23: £16.8bn). Q4’s net FUM flow of +£97m continues BM’s impressive run of positive net flows (now spanning nine consecutive quarters) during a period of difficult market conditions and investor nervousness. FY23 net flows totalled +£817m (FY22: +£785m). BM has flagged a healthy pipeline for FY24, although investor sentiment is still subdued.
Andrea Montague has been appointed CFO and Executive Director, effective 1 Aug 23, to replace Ben Thorpe, subject to regulatory approval. Andrea has an impressive executive and board track record in the long-term savings and asset management sector. She leaves Aviva where she was Group Chief Risk Officer, and prior to that, Group Chief Financial Controller.
BM has indicated it expects FY23 results to be in line with forecasts, although we see a slight change in how revenue is made up (FUM ending the year a little below our previous estimate and average revenue yield expected to be a little higher with the continued rise in interest rates). The slightly lower closing FY23 FUM level reduces our FY24 forecasts: revenue from £131.5m to £128.2m and underlying PBT from £34.1m to £31.2m. Our fundamental valuation reduces to 3,100p per share but is still 38% above the current share price. An additional noteworthy point for investors is the marked uptick in the volume of shares being traded since late 2022, which suggests growing investor interest in BM (see page 2 of the note). Note: https://www.equitydevelopment....
Would love your views Paul/Graham on finnCap (LON:FCAP) this morning. I am down a bit here as I got in too early but hopefully today's results will put a bottom on the cash balance and enable a floor for the share price to settle. Would appreciate views as I think this could multibag from these levels following the merger with Cenkos and when the economy lifts.
I would be really interested in views on why Cenkos Securities (LON:CNKS) (I hold) share price seems to have drifted lower and lower since the merger was announced ? Is there a serious doubt about it going ahead?
Hi Patrick L,
I had a quick look at the finnCap (LON:FCAP) figures last night, and was pleasantly surprised by the current trading & outlook comments - not as dire as I expected, given market conditions.
Disappointing that they didn't give any indication of what duplicated costs can be stripped out with the Cenkos merger.
Balance sheet looks adequate, although more redundancies, and assigning leases of expensive office buildings could drain a lot of the cash away maybe?
As a cyclical thing, the shares could possibly multibag in the next bull market though, so I am tempted to have a dabble. We know how cyclical brokers are, so it makes sense to buy when they're dirt cheap & confidence is on the floor. Then remember to sell once they're raking it in from the next M&A & IPOs boom.
Regards, Paul.
Apologies I am writing this on my phone, needless to say, the US CPI nos came is as predicted simply by looking at the roll off of the back book. For the next few months this is done … looking back at 2022 … the month on month numbers were virtually zero for July and August and 0.2% for September. So CPI will have to make another big drop from 0.2-0.3% month on month. This may happen. Or it may just bumble along now in a range 0 -0.3%. Barring a sudden change I would be very surprised if it really strengthens to say 0.5%. 0.2% is about where the Fed wants it - so that is Goldilocks - but it would mean the headline number rises from 3%. Maybe not enough to worry the Fed … so they remain on pause ? Only time will tell how the mkt takes it.
One swallow doesn’t make a summer but the initial reaction was $ down and that plays to value incl emerging markets. Over the next day or so we will see if it holds but it is a favourable trend for UK equities if it does. I have my fingers crossed because I’m guessing we will all make a little money. June wasn’t kind so let’s hope July treats us better.
Happy hunting everyone.