Small Cap Value Report (Thu 13 Oct 2022) - ZTF, NXR, RNK, TET, XPF

Good morning from Paul & Graham! Today's report is now finished. I'm shortly speaking to Beeks Financial Cloud (LON:BKS) (I hold) so will publish the written summary of that interview in tomorrow's report.
It's going to be a crazy day today, as I (Paul) am recording two CEO interviews! Plus the usual report, so my head will probably be spinning on its axis by the end of the day! Still, it's all very interesting.
Brief macro/markets thoughts from Paul
Plummeting markets create opportunities for our bulging watch lists. Although as mentioned in my most recent couple of podcasts, I'm becoming increasingly worried at signs of stress in the global financial system (these problems are certainly not confined to the UK, as the parochial/clueless UK media would have us believe) - e.g. look at double digit inflation in some European countries (17% in Holland, 16% in Poland), plus the Euro is now below parity against the dollar, and showing little signs of recovering.
Another sovereign debt crisis looks to be brewing, with Italian 10-year Govt bond yields now up to 4.8% (higher than the UK), against 2.4% for Germany. So I think the next big crisis could be strain on the single currency, which was never going to work in my opinion, as the countries in it are far too diverse, and there are now massive imbalances, e.g. the ECB propping things up by buying Italian debt on a gigantic scale (something like 500bn Euros, I believe). What happens when that stops?
It seems obvious to me that central banks (esp the Fed, and the BoE) have made major policy errors, in ending QE too abruptly, and allowing bond yields to rise far too quickly. That's triggered plunges in bond, equity, and property values, so that's bound to cause major problems. Unless they change course, I think we're possibly heading into a major financial crisis, I'm sorry to say.
The early signs are already there - this pensions derivatives fiasco, clumsy handling of it by the Bank of England which I think urgently needs a more switched-on Governor, open-ended funds beginning to "gate", i.e. suspend redemptions (e.g. Columbia Threadneedle open-ended UK property funds). Close your eyes, and it almost feels like 2007 again, when the credit crunch was beginning to build up, and forced liquidations of assets began.
I don't like the macro picture one bit, and am very worried actually. It could all be fine, but if a major player in the financial system fails, and needs a bailout (Credit Suisse maybe?) then everyone starts to worry about counter-party risk again (just like in 2008), and we could go into another credit crunch as lenders withdraw credit to shrink their balance sheet risk. Buyers can then name their price.
Central banks could nip all this in the bud, but they seem determined to demonstrate machismo against inflation that is largely a result of supply chain shocks which are already beginning to ease. So they really don't need to crash the economy (and probably the whole financial system) with overly rapid rises in bond yields. I don't like this situation at all, and sorry to be alarmist, but that's how I see it.
Summaries
Paul's Section:
Zotefoams (LON:ZTF) - I reported positively here on this specialist foam manufacturer's interims in Aug 2022, expecting it to out-perform soft forecasts. The good news today, is confirmation of a strong Q3, and raising full year expectations. Demand is strong, and impressive price rises have been passed on to customers. The balance sheet is strong, with plenty of freeholds. It's benefiting from weak sterling vs dollar. Plus there's blue sky potential from the Re-Zorce new product. It got a thumbs up from me last time, and I'm now awarding it "Mystery share" status for this weekend's podcast - one of the top companies reporting. It's up 25% today, which I worry could be a spike up, despite the good news, things often tend to drift back down again after good news in this horrible market, but it's high on my watchlist for a future purchase.
XP Factory (LON:XPF) (I hold) - CEO Interview - I asked to speak to the CEO of this very rapidly expanding leisure business, because I think it looks really interesting. I've typed up the key points in a section below, and the recorded audio version is here. It's also gone out on my podcast channel too.
Graham's Section:
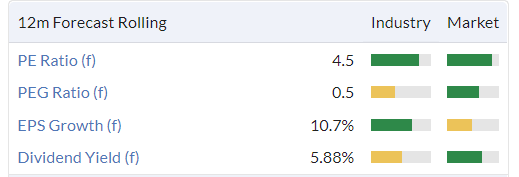
Norcros (LON:NXR) (£159m) - a reassuring in-line trading update from this provider of bathroom products such as showers, taps and tiles. The shares are once again extraordinarily cheap; they have often looked cheap in the past, but the PE multiple is now less than 5x, according to Stockopedia. I suspect we are again at the point where the shares are worthy of a gamble, for those willing to research it in more detail. The pension scheme contributions look manageable and can’t rise by more than 5% p.a. Additionally, I suspect that rising interest rates have caused another very favourable movement in the surplus. The company is carrying some financial debt now, but the company it acquired with borrowed money is performing in line with expectations. An intriguing valuation at today’s share price, in my view.
Rank (LON:RNK) (£276m) - this Q1 trading update has further diminished the price of Rank shares as the market cap now sinks below £300m. Q1 net gaming revenues increased by just 2% (to £166m), with weakness in Grosvenor Casinos outside London. The average spend by casino visitors is down as people reassess their spending habits in light of the cost-of-living crisis. The inflation is hitting Rank too, as its own energy bills and other input costs have risen enormously. The consensus earnings forecasts here aren’t worth relying on - the business is clearly going to have a tough year, and will be lucky to get through with any meaningful profit. As a recovery play, I think this could be a wonderful share to own, but there is no evidence of stabilisation or recovery in trading yet. Much, much safer to stay on the sidelines for now.
Treatt (LON:TET) (£342m) (+10%) [no section below] - this ingredients business says that FY September 2022 profits will be in line with expectations of £15m - £15.3m, on revenue growth of around 13% (9% at constant currencies) to £140m. FY 2022 sounds like it was a good year: growth in all categories except Tea, a small new Coffee category has been created, and price increases were passed on to reflect higher commodity prices. Hopefully this will turn out to be an inflation-proof company for its shareholders - food producers ought to have little difficulty negotiating price increases.
Looking forward, UK production capacity is set to double during FY 2023 thanks to a new facility. FX hedging techniques have been revised and improved, and the company has a modest net debt figure of £23m. There are “positive market dynamics” and costs are under control. The CEO is “confident the business can revert to its trajectory of growth”.
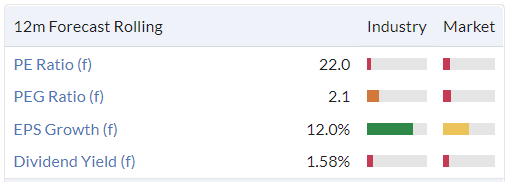
There’s very little to dislike here but the shares do perhaps already reflect the strength of trading with an expensive PER of 22x (as of last night’s close) and a modest dividend yield of 1.6%, according to Stocko. With the promise of good inflation protection, this might be one of the more relaxing stocks to hold over the next few years. [no section below].
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Agenda
Paul's Section:
Zotefoams (LON:ZTF)
267p (up 15% at 08:20)
Market cap £130m
13 October 2022 - Zotefoams, a world leader in cellular materials technology, today provides a trading update for the nine months ended 30 September 2022 ("year to date") and in respect of its financial year ending 31 December 2022.
Continued positive momentum through Q3 and full year expectations increased
Summarising today’s update -
Revenues - record performance in Q3, up 27%, despite strong 2021 comparatives.
Year to date (YTD) revenues +24% vs LY - impressive!
Demand continues to be resilient in most markets.
Revenues & margins benefiting from price rises earlier in 2022 (e.g. Polyolefin revenues up 27%, but volume only up 4%, implying big price rises have been achieved).
Some benefit from dollar strength vs sterling, although limited by hedging.
Input cost inflation - “some recent abatement”, e.g. polymer prices easing from record levels in H1.
Energy costs - this is very interesting, and could have positive read-across for other UK producers maybe? -
Wholesale energy prices remain volatile but, in the UK, which accounts for the majority of Group energy consumption, the short-term risk associated with energy pricing has been reduced due to Government pricing actions.
Re-Zorce - potentially exciting blue sky project, making “good progress”.
Outlook - sounds good -
Demand entering the final quarter remains encouraging and we have good visibility of confirmed orders for the remainder of 2022.
Based on its current sales forecasts and foreign exchange rates, and subject to there being no material disruption to the business, the Board now expects adjusted profit before income tax to be significantly ahead of market expectations*.
* Current Company-compiled consensus expectations for adjusted profit before income tax and separately disclosed items, for the year ending 31 December 2022, is £9.3m.
Cash generation also continues to be strong and so the better than anticipated earnings performance should contribute to an appreciable reduction in both net debt and leverage.
Updated forecasts - many thanks to Arden for providing guidance with an update note this morning. It’s raised forecast adj PBT to £11.6m, which is 19.7p EPS (up from 15.2p actuals in both 2020 and 2021).
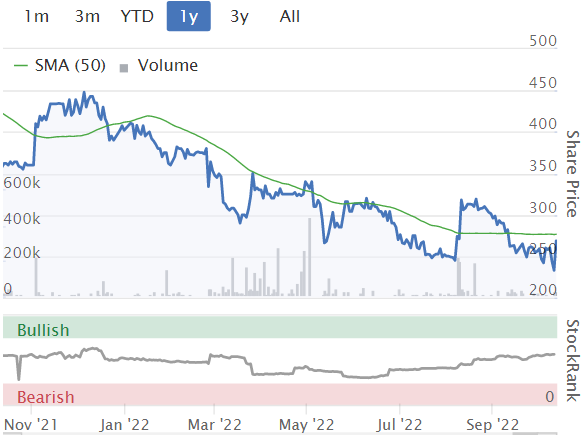
Working out the PER on this morning’s increased share price of 267p (at 08:21), gives a 12/2022 PER of 13.6, which strikes me as a reasonable price (remember that PERs should now be lower than in recent years, given higher interest rates, and macro uncertainty).
My opinion - I remember having a very positive call with management in Aug 2022, and writing up a positive review of its interim results here on 9 Aug 2022. That’s well worth revisiting, if you’re interested in this share. It passed my balance sheet review with flying colours (some debt, but not onerous, and freehold factories), so no issues there. My crystal ball was working well (for a change!) back then, as I correctly predicted that forecasts were set too low, and likely to be beaten, pretty easy to work out from the interim results & positive outlook comments back then. I concluded with a thumbs up in August, and today’s positive update reinforces me positive view of ZTF. So it gets another, more emphatic thumbs up today!
I’ll approach management, and see if they’ll do an interview with me, and ZTF is going on my “Mystery shares” list for the podcast later this week (i.e. best share ideas of the week, exclusively for Stockopedia subscribers).
I particularly like that ZTF has demonstrated it has strong pricing power, and able to push through price rises, even expanding its profit margin. That's telling us this is a quality, resilient business.
At some stage I want to buy some ZTF myself, but am not ready to push the button, due to horrible macro outlook for markets generally. So I think there’s probably no need to chase the price higher today, as the share price could easily drift back down again, we’re seeing that happen in lots of cases. I could be wrong, but it seems to me we’ve probably not reached a market bottom yet, as the macro picture seems to be worsening by the day.
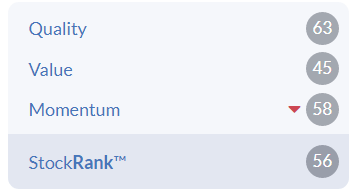
Note that the middling StockRank of 56 is likely to increase, once upwardly revised forecasts come through - that should increase both the value, and momentum scores. It will be interesting to check that theory in a few days' time.
.
.
XP Factory (LON:XPF) (I hold)
15.5p
Market cap £23m + dilution from deferred consideration (25m new shares, fixed amount)
Interview with the CEO, Richard Harpham - click here for the audio recording
Disclaimers - I’m not charging a fee, I do hold shares personally (intended as long-term investment), not investment advice, please do your own research.
- Description of the business - original business is Escape Hunt (escape rooms), plus recent (Nov. 2021) acquisition of Boom Battle Bars (competitive socialising bars format).
- TripAdvisor reviews are excellent, for both formats. “We obsess” over customer experience.
- Very rapid site roll-out now of new sites underway. 8 sites pre-pandemic, c.50 by 2022 year end, mix of company-owned, and franchised. Plus 25 international franchised Escape Hunt sites.
- Franchise business model - 10% of sales royalty is charged to franchisees. Explained why this stacks up, is it sustainable? Seems to be, because sites are achieving 20-39% EBITDA margin. Explains services provided to franchisees, e.g. setup, counter-signing leases that franchisees would not be able to secure independently, marketing, group purchasing of food & drink, support - accessing expertise that wouldn’t be available to an independent operator. Centralised EPoS system, so sites can be monitored.
- Extremely high gross profit, around 85%+, because games revenue is almost all gross profit. Drinks are high margin of 80%. Food is small proportion of sales.
- Site acquisition - landlord cash contribution to capex is typically £0.5m per Boom site, with c.£0.8m capex. Landlords cash is passed on to franchisees. So net cash capex per new site only £0.3m, one year cash payback - very impressive. Plus rent-free periods over & above that. Less competition to take large empty units. “Once in a generation” opportunity to acquire great sites, hence fast expansion.
- Risk of rapid rollout? Manageable. High calibre team put in place, to serve a larger business. Has put pressure on team, but it’s been exciting. Rate of growth slowing from this point, 8 new Boom sites planned for 2023. Sound strategic reason - putting cash raised to good use, crack on with it, not let cash sit idle in the bank.
- Shore Capital note - revenues of £40m in 2023.
- Any loss-making sites? No, for Escape Hunt. Yes for Boom new openings, but deliberate (e.g. over-staffed when first opened). Strong LFL sales (8% vs strong LY comps). Sites mature rapidly after opening, and continue improving for 2+ years. Significant leverage benefit from sales increases, due to v high gross margin. Only 8-12 weeks of losses for new site openings. But this is shortening now, with only 2-3 weeks losses in latest new sites due to e.g. training staff at existing sites, so they hit the ground running. Gives examples. Each new site should get a little easier.
- Franchise model protects XPF in a downturn, as 10% royalty would reduce, cushioning the central co. Worst case scenario, if a franchisee fails, the site would return to XPF. We discuss the worst case scenarios in a bad downturn.
- Young customer base (25-35) is fully employed, and not that susceptible to energy or mortgage costs. No discernible downturn in demand has been experienced to date. Sales growing almost every week currently. “Still feels pretty good”.
- Experiential leisure should be more resilient in a downturn than standard pubs. Lots of games options, not focused on one specific activity.
- Escape Hunt (EH) - question from Stockopedia reader, about the concept of escape rooms can go stale, once you’ve done a couple of them. Fair point, but EH is a low density model, only needs 80 customers per day. Plenty of people in catchment areas. Never refreshed a room yet, but sales still building. If customer numbers do decline, EH rooms are modular, can come in & out quite easily. Same with Boom, games can be switched easily. Competitors have tended to focus on one type of game, e.g. crazy golf. We’re avoiding that, so modular build is really important & makes it flexible. In house team constantly inventing & trying out new creative ideas.
- Cash - £15m fundraise at 30p in Nov 2021. Deferred consideration on Boom is contingent liability c.£9.5m on balance sheet. But this will be paid in a fixed number of shares, 25m. So lower share price has not changed the dilution. No cash settlement or price adjustment. Crossing out the £9.5m provision, and increase share count by 25m, to understand post dilution position. The earn out being triggered is a good thing, as it means the business has hit targets. Paul thinks the balance sheet looks OK, but cash position of c.£5m maybe not overly comfortable? Remember that c.£10m of the £15m fundraise was spent on acquiring Boom. We feel pretty good about cash position - very much in the trough now, because we have to build new sites before getting in landlord cash contribution, which follows. Most company owned new sites have now been paid for. “So we feel we’re in a good place” re cash. If the economy really turns down, we don’t have to keep opening new sites, it’s optional. So quite well positioned.
- Debt financing could be more available once we’re showing profits. A supplier has offered debt funding if required. So have flexibility.
- Could you run the c.50 sites by end 2022 for cashflow, if the economy crashes? Assuming no massive deterioration in trading, then yes they would be cashflow positive.
My opinion - I wasn't madly impressed with the original Escape Hunt business, but I think the acquisition of Boom Battle Bars is transformational. The current rapid roll out of new sites should deliver profitability in 2023, but obviously we're taking that on trust at this stage, because the historic numbers show losses as expected from a small number of sites, and heavy central costs needed to scale up.
I think there's a good chance this new style of bar could weather a consumer downturn better than standard pubs, because it's a distinct, novel, destination for leisure.
The CEO is experienced & knowledgeable, and has obvious energy and drive, and it looks to me as if he's delivering on the ambitious expansion plan. Not without risk of course, but on balance I think risk:reward at 16p per share looks pretty good.
Graham’s Section:
Norcros (LON:NXR)
Share price: 180p (unch.)
Market cap: £159m
This is the “market leading supplier of high quality and innovative bathroom and kitchen products”, which we have covered many times before in this report.
As a reminder it owns the followings brands, among others:
- Triton
- Merlyn (shower enclosures and trays)
- Vado (brassware)
- Johnson Tiles
- Croydex (bathroom furnishings and accessories)
Let’s see how the company performed in H1 (the period from the end of March to the end of September).
- “Robust H1 performance reflecting the strength of our customer proposition and the breadth of our distribution channels.”
- Revenue +1% on a constant currency like-for-like basis (this is the best way of measuring revenue growth, in my view).
- Reported revenue +10% to £220m, which I believe is due to the acquisition it made this year.
Geographic split: UK like-for-like revenue minus 3% vs. last year, South Africa like-for-like revenue +10% vs. last year.
The company is eager to point out that its UK revenues were higher than 2019, which I guess is the last time we had a “normal” year (I have to put that in scare quotes because normal years don’t seem to happen very often these days!).
So what is going on with the UK business? “Softer demand in the retail channels and destocking in some of the larger retail customers”. The destocking issue has been mentioned before - it has been going on for a while, making 2022 yet another abnormal year.
Meanwhile, the South African business continues to “outperform the market”, with “growth across all divisions reflecting market share gains”.
Balance sheet: net debt of £60m, after the company made an £80m acquisition that was only partially financed by raising new equity.
Committed banking facilities of £130m suggest lots of remaining headroom.
Pension scheme: expected to be in an accounting surplus (as Paul has noted recently, the accounting view of pensions doesn’t necessarily mean much).
Outlook: in line with expectations for FY March 2023. Underlying operating profit in H1 to be “no less than £21m”.
My view
This strikes me as a business that should be on a modest rating, since (for example) I don’t think that Triton showers command high prices just because they have the Triton brand attached to them. These are normal, mainstream products - nothing too fancy.
But wow, these shares are cheap:
Let’s remind ourselves of the current arrangement with the pension scheme. At the company’s final results this year, it said:
The Group has reached agreement with the Trustee on the 2021 triennial actuarial valuation for the UK defined benefit scheme and on a new deficit recovery plan. Deficit repair contributions have been agreed at £3.8m per annum from 1 April 2022 to March 2027 (increasing with CPI, capped at 5%, each year).
Compared to underlying operating profit of £21m in six months, these pension contributions look very easily affordable (assuming that cash conversion is ok).
So I don’t think that the pension scheme is a very good argument these days, when it comes to explaining why these shares are so cheap.
I’d also point out the following snippet, again from the final results statement in July:
The net position relating to our UK defined benefit pension scheme (as calculated under IAS 19R) has improved to a surplus position of £19.6m at 31 March 2022 from a deficit of £18.3m at 31 March 2021, primarily as a result of an increase in the discount rate driven by market factors.
I acknowledge that this is the accounting calculation, which is less meaningful than the actuarial calculation, but I have to point out that there was a £38m swing in one year, caused by rising interest rates. Rates have only gone in one direction since then - much higher.
I think it might be time to get excited that pension deficits are not going to be the problem that they were before, for many company balance sheets.
The Norcros contributions are indexed to CPI, but capped at 5%. This hints at the point I made earlier this week - that defined benefit pension payments are often capped at a 5% annual increase, so that schemes don’t have to match runaway inflation.
Following the acquisition it made, Norcros does now have a large RCF balance (I think of this as a company credit card), so there is again some financial risk with this share that is separate to any views on the pension scheme.
And there is also the exposure to South Africa.
But maybe this share is simply too cheap now?
The ValueRank is 84 and it even passes the Benjamin Graham Deep Value Checklist.
I prefer higher-quality companies than this one but if I had to buy a deep value share, this would go on the shortlist.
With UK value shares being perhaps more unpopular now than they’ve ever been before, it looks like this one has been rather carelessly de-rated. With an in-line trading update, the company has demonstrated an ability to manage these economic conditions so far:
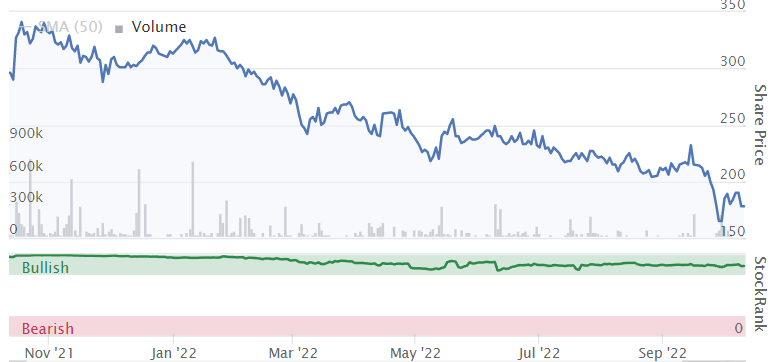
This is worthy of further research as a possible value investment, in my view.
.
Rank (LON:RNK)
Share price: 59p (-8%)
Market cap: £276m
I’m limiting this to a short section as whenever I mention it, I get the sense that private investors have limited interest in this one!
But this is a huge business - it’s the largest casino operator and the largest bingo operator in Britain. It also has bingo operations in Spain and a collection of digital brands.
I’d like to own shares in it some day, which is why I’ve been carefully following its share price collapse. I also simply find it interesting to see such a big and established business trading so cheaply.
The market valued it at £1.2 billion as recently as February 2020, and now it’s worth less than £300m, only a fraction of the revenues it generates:
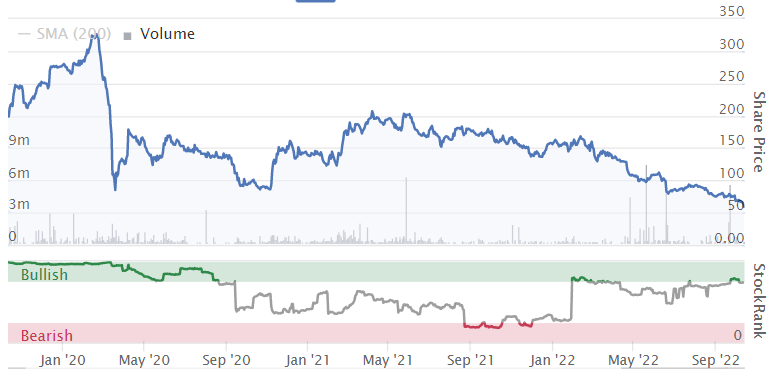
As you can see, its post-Covid recovery was muted and over the last 18 months, it has sunk lower and lower.
Key points from today’s Q1 trading update:
- Net gaming revenue +2% to £166m
- Grosvenor casinos down 5% to £75m
- Digital revenues +13% to £49m.
Visits to Grosvenor were up but with a lower spend per visit. Strong growth in London but significant decline outside London.
Outlook
Consumer discretionary expenditure is expected to remain under significant pressure this year with inflation likely to remain high for some time, despite the positive impact of the energy price cap, and the impact of rising interest rates. We expect to see some continued impact of these external pressures on the business, particularly in the Grosvenor venues outside of London.
Energy costs in the current financial year will be £34m (£23m last year).
Other inflationary problems include: wage inflation, food prices, and supply chain pressures.
Next year will be worse again with the loss of rates relief and furlough payments.
My view
The market has evidently decided (and perhaps it’s right) that a business like this is going to be a victim of this economy. You have rising cost pressures on the one hand, which greatly impact real-life venues such as casinos and bingo halls.
At the same time, you have a cost-of-living crisis which makes people reassess how much they are willing to spend playing blackjack or bingo.
As of August 2022, Rank had a net cash position of £19m, before lease liabilities. These lease liabilities are significant, having a present value of £182m. But it looks like the balance sheet could survive some stress, before the company needed to raise fresh equity.
I’m going to stubbornly keep an eye on this one, looking for an improving trend and any sign that trading might have stabilised. But it does look like things will be tough for at least the next year or two.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

71 comments
Thanks for the reminder about Rank (LON:RNK) , it's one I had been watching before too. Your piece prompted me to review my chart. Looking very interesting from the technical picture, it appears to have been in a trading range since 2004, and has just made contact with the lower boundary, the recent gap down on the daily TF could be interpreted as an exhaustion gap, and on the monthly TF it looks very much like a selling climax imo. So.... very much one to keep an eye on for potential to turn up ! Of course it could yet retest the all time low made after the GFC so still a wait and see ;-)
Glad to find out I'm not the only one intrigued by Rank! The technicals are interesting, and hopefully they won't be overridden by disastrous funny-mentals. G
Paul-I agree with both you and dartagnan2019 regarding your thoughts on the macro/financial front. The sooner that clown leaves the BOE and is given his P45 the better. A lot of the recent problems could have been averted if interest rates had been raised earlier when inflation was starting to take off which was before the invasion of Ukraine. A lot of wealth has been lost due to the incompetency of both the Government and the BOE.
100% agree- it was obvious 14 months ago. Makes you wonder how independent the bank were after the last PM- I mean Boris not Liz !
£xpf really enjoyed the interview @paul and it looks like your subscribers liked it a lot!
Thanks NewInvestor1972. Unfortunately there was an interview with XP Factory (LON:XPF) (I hold) on Vox Markets yesterday, which has a much bigger audience than I do. So I had to make some last minute changes to my questions today, so that it wasn't just repetition.
I urge anyone interested in XPF to listen to both mine, and Vox Markets podcasts this week, as we cover some different aspects of the company, so both are worthwhile I think. Am looking fwd to mystery shopping it when the new Bournemouth site opens shortly! We should have a Stockopedia subscribers social there actually, and vent our anger about the markets by doing some competitive axe-throwing! :-D
100%, well worth listening to both. It's nice to listen to a good news story tbf, in amongst the doom and gloom. I really like the focus on customer and the team, and of course the fact they are comfortably funded for the current roll out plan, and have a contingency plan if things get tighter.
happy holder here.
Paul - I like your 'brief macro/market thoughts' section but should point out what I think may be an error in the figure you quote of 17% as being the level of inflation in The Netherlands. I don't know from where you got your figures but the official organisation (CBS - statistics bureau) quotes the average inflation for 2022 as 9.5%, be it that each month this year except June is up, till the end of September and this is a significant upward trend, reaching 14.5% for the month of September.
regards, dartagnan2019
I copy and past the official statistics - 'gemiddelde' translates as 'average '
When the Bears are in ascendancy it is normally time to start buying back in . I would like to see some corporate activity first though, as many UK companies look cheap, especially to US$ investors.
I would like to see some corporate activity first though, as many UK companies look cheap, especially to US$ investors.
There's already quite a lot of corporate activity - EMIS (LON:EMIS), AVEVA (LON:AVV), Micro Focus International (LON:MCRO), Biffa (LON:BIFF), Contourglobal (LON:GLO), Euromoney Institutional Investor (LON:ERM), Homeserve (LON:HSV), Mediclinic International (LON:MDC), RPS (LON:RPS) for starters.
It's more or less open season on UK stocks.
timarr
Must be near the bottom then.
Adding to today's comments relating to macroeconomic impacts, it's worth pointing out that quite a few experts believe that the most critical period for energy shortages (and prices) will be this winter so spring 2023 may well mark the start of a transition to lower and more stable energy prices. Over subsequent years the increased development of fossil fuel (particularly gas) and renewables production occurring now should gradually kick in so I believe that in the medium and long term we are heading for an era of cheap energy, with fossil fuels helping keep prices down. Windfall taxes may impede this a little, although these don't seem to be significant in the US, where LNG producers (with vast reserves) will make up for the gas supply lost from Russia. There are clearly other factors involved, but at least I think the outlook for energy prices and their impact on inflation should get better.
To watch the power of what just happened with indices with the build up prior to the Inflation figures came out hotter than expected in the USA, and then the sudden fall, makes me realise us private investors are just riding on the back of much greater powers at play.
I tend to agree with Simoan, I don't watch the News and try and keep a clear head and in many ways trade the day with todays facts, not the hype, and twitter Sh#te.
I know the companies I hold are good well run companies on low P/E's, I have trimmed out all the maybes. I also know that having more cash than equities at the moment is probably the right call.
Buying is the difficult thing now, and when, and in that sense is the number one question for those sat in cash, and FOMO is the beast that needs to be tamed.
Todays trading is telling me indices have a way to go down, and thus I cant get too excited about target prices being triggered, but I still do....and the beast again needs to be tamed.
I would agree, I had a big clear out yesterday which is often the sign for the major bounce as my sells are typically when everything rebounds, for example Natwest (LON:NWG)
But right now I want a sleep at night strategy in place
I agree the buy timing is always hard were a number of small (typically 0.5-1%) purchases were also cut within a few days to weeks or purchase as they hit and/or crossed the capital protection line so had to be sold. We all then have a mental should have waited longer! Then when we wait longer that seems to trigger the bounce, is that Tigger or Trigger's New Broom I have no idea which one.
There is no right or wrong answer, there is being honest and saying what is the right thing to do today, and being prepared to go back and say I was right, or I could have done this better, or urgh just hit the sell button again...
Good luck!
Tommy
HI
FTSE250 doing odd things
Hot CPI. US Markets tanking hard.
US CPI YoY Actual 8.2% (Forecast 8.1%, Previous 8.3%)
US CPI MoM Actual 0.4% (Forecast 0.2%, Previous 0.1%)
US Core CPI MoM Actual 0.6% (Forecast 0.4%, Previous 0.6%)
US Core CPI YoY Actual 6.6% (Forecast 6.5%, Previous 6.3%)
It is the core reading that is frightening markets - this suggests it is feeding into wages and could become ingrained. Not good, but not a surprise given the tightness of US labour market. Fed will have to carry on tightening by the looks of it.
Hot CPI. US Markets tanking hard.
And then, like magic, they are now up. Watching this stuff hour by hour is really just the first sign of madness. Take some deep breaths, go out into the garden and hack something to pieces. Works for me :)
Are you available to come help with the new fence? That is the next redundancy project, everything has now arrived, just have to tell the neighbours to cut everything back, but if you are available?
Are you available to come help with the new fence? That is the next redundancy project, everything has now arrived, just have to tell the neighbours to cut everything back, but if you are available?
Sorry, but the reason I started investing for myself is so I could retire in my 50’s and never do a bloody days work again…ever. I’m no gardener or fencer but you want to see the mess I can make of a shrub with my hedge cutter and mattock when the portfolio is all red :)
Good luck with the job interview btw.
I don't normally comment on macro stuff because it is pointless IMHO. I know I don't know what will happen, and more importantly, I know no-one else knows what will happen tomorrow, next week, or in a year's time. So what's the point? I realise it makes some people feel better having their own biases confirmed by others but in my experience it only leads to poor investment decision making.
Six months ago I completely stopped listening to the Today program and only watching TV news very occasionally because the constant stream of negativity is so distracting and you become focussed solely on the short term. As an investor, that is no good whatsoever. And you know what, I feel so much better for it and more generally less stressed.
From experience, my best long term performers have always been through hitting the buy button and simultaneously wincing. It feels uncomfortable, almost painful, but that is when you start make real money in the longer term.
Likewise simoan though I stopped listening to Today a while before you and unsubscribed from the FT about a year ago. I still read ohn Authers daily news letter but do wonder whether this is musings by somebody who knows no more about the future than anybody else and therefore is not worth my time. I also regularily come off Twitter for two or three weeks and each time I return my addiction is less.
There is a book (which I believe is worth reading, though I havent read it yet)
Stop Reading the News: A Manifesto for a Happier, Calmer and Wiser Life
https://www.amazon.co.uk/Stop-...
Regards
Michael
I still read John Authers daily news letter but do wonder whether this is musings by somebody who knows no more about the future than anybody else and therefore is not worth my time
I think JA is incredibly well informed on markets and has a great breadth of knowledge. But he cannot resist the journalistic urge to frighten and that undermines his credibility in my eyes. He does however share with me a deep love of Mahler’s 2nd Symphony whose finale * is the very apotheosis of the classical tradition, so I continue to read his newsletter. However, I prefer Robert Armstrong in the FT who is decidedly more even-handed in his exposition and drily witty to boot.
* Survival Tips!
I think one of the big things to remember is JA is paid a 7 figure $ salary plus package to produce his articles every day, having been paid to relocate to NYC.
I am amazed at what he does each day and it is really good when I have the time to read, currently I have unscribed.
I need to go back and ask my friend (works for a competitor, but used to work for the same company), is it just JA or does he have an army providing the data and he just conducts?
Thinking to the Daisy Meadows series of books to those who have daughters or granddaughters, they are a collective under one name...
Tommy
I still read John Authers daily news letter but do wonder whether this is musings by somebody who knows no more about the future than anybody else and therefore is not worth my time. I also regularily come off Twitter for two or three weeks and each time I return my addiction is less.
I used to get his newsletters (I think it was him?) 10/15 years ago but after a while I just felt the guy was "a stopped clock". He just seemed to be negative all the time and there was not much in the way of balance. IIRC He was relentlessly wrong following the GFC and if you'd listened to him you missed the start of one of the greatest bull markets ever. Of course, eventually he will be right and everyone will have long forgotten the rubbish he turned out day after day in the past and label him the "new messiah". IMHO only a charlatan would continue to pump out such stuff having been so horribly wrong for so long.
why has the FTSE 250 just risen 500 points ??
People / institutions making risk on bets across the board, taking positions in advance of US inflation data print, they are betting it comes in lower, data due at 1330….
I think the Pound has jumped on the rumours of a mini-budget U-turn, according to the news. From $1.11 to $1.13.
Yes i think that's it...
didnt last long !
Is that blue I see across the indices?!
I guess your screens are in a different colour to mine!
It looks like I'll see a blue close ... albeit very marginally. I don't hold a lot of small caps and am overweight in resources/energy.
But it's a two-way street. I get burned at times when it seems everybody else wants to party.
Hi
As various people are commenting on macro issues, I thought I would add a small contribution.
With regard to today's US CPI print due to be published today, which is a key driver of the FEDs plan to raise its rate a further 75bps at its next meeting.
A bit of new information which I came across today and had not understood before, is this.
The CPI print is based on looking back across the previous twelve months inflation data. When a new CPI print is done, the earliest months figures drop out of the equation. Why is this interesting?
The levels of the inflation numbers falling out of today's were very low. It seems to have been 3.3% annualised, or 0.27% month over month, according to this professor from Duke University. So, the effects of them dropping off the assessment will be very small.
(see YouTube, this channel, https://www.youtube.com/c/TDAm...then this vid .... sorry for this convoluted linking but Stocko not able to support vid links posted in the SCVR yet (I've reported it but no solution yet))
Other estimates I have seen suggest today's CPI print will be high still, and so it seems the FED will raise rates a further 75bps.
This Professors comments seem to reinforce this.
So, although we are all seeing real world costs of several input measures falling ... lumber, freight, commodities etc ... It does not look like US CPI is likely to report lower figures today. Nor perhaps in the next CPI print.
I do not know, but I suspect the UK and others also apply this rolling 12 month method, thus until that 12 month hits a high inflation number month, it seems the CPI numbers might not fall noticeably enough for the FED to take a more dovish action, for a little while longer.
Obviously this is but one persons view and many other factors are at play, but it was a new insight to me and might interest others commenting on macro challenges.
IMO I do think the US markets have quite a bit further to fall. I also believe other markets will follow suit.
Regards
Howard
Well hello Howard! Of course it's a rolling 12 month scheme for working out annual inflation. How else would one calculate a 12 month index?
And it does mean the powers that be are likely to be punitive with the medicine if they follow orthodox economic thinking. I think we'd do better to slightly undercook the interest rate rises as they add to the problem rather than cure it. But equally, there is no point in trying to restore demand in economies like the UK that have little spare capacity and cash being sucked out by the energy producers and war makers.
I believe we need to see inflation slowing in the US before balance and harmony in markets can be restored, so selling anything Emerging Markets and trying to resist buying almost anything whilst the trend is lower highs and lower lows. Each to their own of course and GLA.
Just to mention that Mello London, our popular two day Autumn conference, has just launched with full details in my posting here... https://www.stockopedia.com/co...
This is a very interesting time to be out there networking again with fellow Stockopedia fans and we have 50 companies lined up to meet with investors and do nearly 100 presentations over the two days. At least half the delegates are likely to be readers of the SCVR joining you and looking for bargains in these crazy markets.
So why not have a beer with Paul and Graham and no doubt many more of the Stockopedia team. We have special offers and you will absolutely love the two day investorfest as no doubt others on here will confirm.
If you have companies you would like to physically meet and engage with just invite them to contact Georgina@melloevents.com as we currently have seven places left so you may increase your personal benefit of coming to Chiswick.
There are lots of really good quality speakers and panel sessions so lots to watch and we do not record anything so what is said in the room is for your benefit and stays in the room. Do engage and ask questions as we learn from each other. Mello is a community.
There is at one extremely bullish scenario that could play out for markets. There were a number of supply side contributors to inflation that are beginning to ease . Global Lockdowns led to massive price increases in everything from shipping containers to semiconductors to used cars, all of which have begun to fall dramatically in price . This was exacerbated by a sharp spike in commodities caused by the Russia Ukraine War, whose comparatives we will begin to lap next year .
On the demand side economies clearly ran ahead of trend, as pent up demand and consumer savings were complemented by very loose monetary and fiscal policy and a booming housing and stock market. All of these are in reverse with a recession already underway and consumers, businesses and central banks tightening their belts.
If these deflationary forces cause inflation to fall rapidly back towards 2%, and central banks to turn dovish this would be incredibly bullish. The economy will have been redenominated 20% higher than 2019 but with stocks again priced for a world with low interest rates. in my opinion investors' faith would be greatly strengthened that the disinflationary forces of the last 40 years are still present and strong enough to overcome the extreme scenario precipitated by COVID. There may well be a nasty recession in the next 12 months but the stock market is quite capable of looking ahead once central bank policy changes direction.
Hi All,
Is anyone with knowledge of the space able to share their thoughts on the Cambridge Cognition Holdings (LON:COG) acquisition yesterday?
Hi Joshwood976
Cambridge Cognition (LON:COG).
The acquisition of eCLINICAL looked very good to me. It is an excellent fit and expands product range. Cross-selling opportunities as mentioned in the RNS will add 5%-15% to revs next year. V good for growth medium term. COG have £8m or £9m cash so an acq. of £1.7m is v manageable. I like bolt-ons rather than large acquisitions. COG will know this company well as it is a competitor. It may well be that one or several of their clients suggested buying it to improve their product range. COG have been looking to make acquisitions for a little while as mentioned in their last webinar. From their body language it was clear something was coming. Maybe there is more in the pipeline.
I have been an investor in COG since April 2020 and have a sizeable position. It is now well managed, growing nicely, profitable, generating cash and has the luxury of strong sector tailwinds. It generates its revenue globally with more than half from USA and gross margins are about 80%.
I am happy. There is a webinar at 5pm giving more info. Details are on yesterday's RNS.
The macro picture makes a lot more sense when you realise this is a controlled demolition of the economy by design.The middle classes are being systematically eliminated to leave a wealthy elite and a serf class.
Fiat currencies have reached the end of the road and will be replaced with CBDCs giving governments complete control of the populace.
This has profound implications for our investment decisions. For more details on this see the work of Ernst Wolff, Catherine Austin-Fitts, Francis Hunt (The Market Sniper), Gregory Mannarino, John Titus, Melissa Ciummei, Lynette Zang etc.
Henry, I think that's well outside the scope of our remit here.
Maybe best for Twitter, or other social media?
Is this how the USSR managed itself and its dominions, and indeed Russia still does? sorry, still outside the Stocko remit.
Have to say I'm impressed by the depth of commitment to be found on the SCVR today.
Silver
Hi Henry Walpole
You are definitely in the wrong forum.
Adding Zotefoams (LON:ZTF) to the listed I added yesterday covering thumbs up stocks on the SCVR. This is just from memory in no order: Victorian Plumbing (LON:VIC), Crestchic (LON:LOAD), K3 Capital (LON:K3C), Ricardo (LON:RCDO), Wincanton (LON:WIN), Wilmington (LON:WIL), Redde Northgate (LON:REDD), £SPSY. Note this is not a definitive list!
When Paul, one of the worlds great optimists, starts to waver I wonder if it isn't time to start investing. But seriously where would you go at this time. Correlations are nearing 0.7 or 0.8. You're not alone Paul. Fear and Greed Index - Investor Sentiment | CNN
Thanks Camtab!
I very much see bear markets as times to be bold, and pick up the terrific bargains they throw up, which has worked very well for me in the past (e.g. 2001-2003), and in 2020, when I was buying heavily at the bottom, and did extremely well over the next year or two in both cases.
Whereas 2008 was a disaster for me, as I didn't sell, but held on hoping for the market to turn, and had run out of capital by the time it did! Although I did make excellent returns in 2009 I remember, but not enough to repair the damage from 2008, and it really took me about another 7-8 years to fully rebuild.
So as things stand now, it seems to me that, yes there are excellent bargains out there, but we only seem to be starting to see macro conditions worsen. So it feels much too soon to be factoring in a recovery. In particular, as I focused on in the main article, it's the plunge in asset values across the board, and the resulting strain that inevitably puts on the whole system, which seems to be only starting now.
That's why, yes I like all the old adages about buying when there's blood on the street, being contrarian, yes of course. But it's way too soon in my view to be taking that approach at the moment, given that serious problems could only just be starting.
There's usually a trigger event that tells you to buy. I recall in 2008, it was when Govts finally took decisive action to fix things. For example Gordon Brown (for all his faults) did forced recapitalisation of UK banks (c. £50bn from memory), and provided Govt guarantees that drew a line under the contagion. Other countries did similar things. Also, the US acted with Lehmans, and AIG, and people finally realised that the system had to be backstopped by the Govt, and that worrying that inaction due to "moral hazard" was actually suicidal, and the people urging Govts to just let banks fail were dangerous fools, who had to be ignored. That was the point when it was obvious to start buying shares, in late 2008, and people cleaned up when markets strongly recovered from that point.
I don't see any such catalyst for a recovery right now. Quite the opposite actually. Policymakers seem intent on making things much worse, and are only likely to act when we're staring at Armageddon.
This could all be wrong, nobody knows. It's just my instinct, having been through a few crises & bear markets before. There are obvious parallels with 2008 building up right now, and more evidence of that comes through on my newsfeeds every day, so it would be crazy to ignore that, and be optimistic, in the face of so much trouble building.
Thanks for your input, I always find your comments interesting & thought-provoking! :-)
Best wishes, Paul.
Forgive me replying on Camtab's link Paul. I'm not an optimist, I've been bearish on the UK economy since Brexit but that's not for this Forum, but I have been investing selectively after Stockopedia analysis and members' comments for several months, too soon clearly and almost all falling knives which supports your comments today. I like to think I'm a realist though and I'm chastened but not deterred, as Camtab asks "Where would you go at this time?" I can't call the bottom but a catalyst for recovery imo is a resolution of some sort to Putin's war. With the ever increasing amounts of explosive being used my hope is that resolution, for everyones' sake especially Ukraine's is not too far away.
Sorry very late reply
I have been going back in, some of these have been cut as they continue to fall, I have a manual -20% capital protection sell, though obviously does not always happen. And today going argh at Natwest (LON:NWG) and Legal & General (LON:LGEN)
We are in this for the long term, I think a solid set of rules are the way to go forward, to invest on principles of good companies, sound research, and sometimes we will go ouch and be forced to press "sell" and other time we will go, why did I not by a LOT more?
Good Luck
Tommy
Armageddon.
Interesting take as when the majority think it's about the worst time to get in, it's historically the best time to get in. For someone without any leverage and a long time view, my problem is what to buy, not trying to time the best time to buy. I have no problem with falling asset prices as it gives me more opportunity to buy. That's the period I think we're in and good companies selling below my calculation of intrinsic value is great while I'm buying. Most people I see here, focus on the market value of the assets they hold to determine their wealth which gives rise to fear and greed. For me, I work best by focusing on the accumulation of larger portions of the businesses I think I understand that I think have long term futures because of good management and durable competitive advantages in the services and products they sell. The market will rise and fall with time. The time will come again when I need to think about selling as market prices get too far ahead of my calculation of intrinsic value and when that is - I don't know. The catalyst for that happens when the majority least expect it. I also see no catalyst for change, but I am blind to knowing. We might be in a buyers market for longer or shorter than the consensus expects and will mean I accumulate more or less than I expect. Logic does not predict markets, so hears my take - and I am happy to be right or wrong - I think things will get worse, even a lot worse than they currently are but as I'm a buyer, I can remove myself from the emotional side of the market movements and keep buying knowing full well that I will never get the bottom, but I will have a nice average. Pessimism right now sounds intelligent, optimism sounds delusional :-)
There are many quotes from my favorite business manager and investor and arguably the best of all time, which I actively am a life long student of. WB.
“Forecasts may tell you a great deal about the forecaster; they tell you nothing about the future.”
Time is the friend of the wonderful company, the enemy of the mediocre.”
I never attempt to make money on the stock market. I buy on the assumption that they could close the market the next day and not reopen it for five years.”
Calling someone who trades actively in the market an investor is like calling someone who repeatedly engages in one-night stands a romantic.”
There seems to be some perverse human characteristic that likes to make easy things difficult.”
“There is nothing wrong with a ‘know nothing’ investor who realizes it. The problem is when you are a ‘know nothing’ investor but you think you know something.”
Interesting take as when the majority think it's about the worst time to get in, it's historically the best time to get in. For someone without any leverage and a long time view, my problem is what to buy, not trying to time the best time to buy.
Impossible for me to agree more! A couple of months ago my barrel had a few fish in it that I could pick off one at a time, but now there are so many fish you don't really know what to do and you end up overwhelmed and driven to a state of inaction if you're not careful. Having said that, there's no need to rush and I am just constantly dripping money into my favourite ideas.
”There’s usually a trigger point that tells you to buy”
So in your opinion Paul, what would be the likely trigger point this time around?
One point not widely mentioned is that the market indices and share prices are nominal numbers. With inflation of 10%, share prices should be up 10% other things equal to reflect higher selling prices and higher nominal profits. Therefore share price falls have been larger than has been appreciated. Evidence that we are closer to the bottom and a turning point than many suggest.
I share the concern Paul.
However in my experience these crisis tend to start and finish rather quickly. The crisis is the catalyst for the change. So although I would not rule out your worst fears...I think much more likely is the brewing crisis emerges and we get the response.
We can sort of see what that might be since the UK seems to be at the front. Sovereign bonds are getting smoked so QT will have to stop. Im not sure about rates....but the problem is that somehow they need to weaken the Dollar and so ...I think that means that US rates need to pause and everyone else needs to catch up. Which is why the UK 50bp rise was a mis-step equal to the budget failure. The UK govt will have to play ball and therefore the easiest way is to delay all a year and buy some time. If successful the Dollar weakens and this allows markets to get off defcom 1...but.....
As I have already hinted I don't think this paves the way for 2020 style recovery, although it might. The economy is going to be tricky because the current situation suggests the problems won't be solved through a monetary injection. A replay therefore of the 2018 pivot or 2020 will not achieve the low inflationary growth being sort. So it will take time. If this is how it plays out we could lurch down...work out how to solve the crisis .... shoot back up ( could be huge given positioning) .... and then end up locked in an awful trading range with little liquidity waiting for data that allows the Fed to ease.
Of course its easy to write all this and less easy to live through it. All I would say is the market behaviour so far is not that different from either big correction of 00 or 08. This is a crisis made in the bond market and being felt now in currencies. Never the less equities have already fallen significantly... if we focus on the US.. the S&P 500 is probably 10-15% away from making a bottom...which would then be a 30% fall from the top. Id have normally said it could be worse but nominal growth is helpful to equities which will limit the impact.
The UK stock market is in a better starting position since it is arithmetically cheaper. It is holding up well which may in part be due to Sterling. Ive mentioned Index linked gilts and the moves we have seen do illustrate how overvalued they were in the first place. Inflation of 2% was already in their price. Now its effectively zero. So now investors capture all the excess over zero which would be a decent return. Not Stella but good. I have bought some #INXG...
I know it sounds counterintuitive but crisis are good....they are the end of the bear not the beginning... equities lead....and the economy follows. Equities are cheap and for investors this is positive. But it takes a crisis to get there. As you said in your podcast ... these prices lead to the positive returns of the future. I feel more positive not less. To be clear im not beating the drum saying rush and out and buy but I would be ready and selectively willing to buy. I see this as a great market because prices are already attractive.
To add my little input, to me it does feel different to 2008. The risk back then was banks, Money printing has been volcanic since then and so we now find ourselves in a situation where money has to be taken out of the system (to stem inflation), which was not true in 2008. People's expectations are not there and until they feel real pain it won't get there. We are not and won't be for a while in money making mode. Just survive for now and as Paul says the time will come in stocks its just they may not be the stocks you think offer promise today. In the end everything returns to the mean and we have been well above the line for quite a few years now. Bit glum for a Thursday morning.
Sadly the problems always finish up with banks even if they don't start it Camtab, look at Barclay's fundamentals, how cheap do they have to get?
Thanks RDHOWARTH,
Just to say I really enjoy your thoughtful, well-informed macro posts. They're great, so keep them coming! :-)
I'm thinking of introducing a "Mystery subscriber" of the week to my podcast, for the best reader comments, and think you're probably going to be the inaugural winner!
Best wishes, Paul.
Cheers Paul.... I find it very useful to think aloud. Your comments are always thought provoking and the Stocko community have created the best discussion board I have come across.
Its sounds like the biggest U turn ever coming here.... this doesn't shut the door on anything they were proposing though IMO - they just need to get the narrative right. If it gets the currency markets to move on then they can all concentrate on the real job.
Always love your macro commentary Paul. But can i query this?
"Central banks could nip all this in the bud, but they seem determined to
demonstrate machismo against inflation that is largely a result of
supply chain shocks which are already beginning to ease"
I think supply chain shocks were the initial cause, made worse by the Russian invasion of Ukraine which raised energy prices, but is not the issue now that inflation is continuing to feed through to the wider economy? Surely businesses, who didn't have long-term hedging in place, are only now starting to feel the effect of higher energy costs for example, which might have a knock-on effect on prices they then set? Or do you think we are past the worst of that?
Speaking to some fund managers I know the big worry they say is wage inflation with something like 1.7 job openings per unemployed person in the US and similar over here so central banks need/want to engineer a recession so they can expand the labour market and drive down wage inflation.
I know it is a sample of one but...
Having been made redundant 2 weeks ago
I applied for a job that I did 10 years ago with a previous employer on Monday
I was rejected today as "not having suitable experience"
My friend was at a conference today talking to a number of their staff saying they have a desperate shortage and are really struggling to recruit
The question of what is jobs available, versus jobs people want, versus salary people are prepared to work for, versus who is the hiring manager applying all their personal bias?
On the plus side I have an interview Wednesday, 50% of my previous salary but seems very interesting so tomorrow is preparation!
The future is different and I hope that I will be part of it.
Tommy
I hope it all works out well for you Tommy!!
Be greedy when others are fearful Paul? Warren Buffet.
Yes, wouldn't a bulging wallet ever go with "our bulging watch lists"? ;-)
Norcros (LON:NXR)
Solid update today from norcros everything ticking along fine . Note they have made a material acquisition this year so huge jump in debt not unexpected - norcros generally converts profits into real cash with no issues - even after factoring in divi payments + pension payments debt should come down rapidly all other things being equal. Note with new acquisition we should be expecting higher sales and higher profits and that is showing up in broker expectations so all sweet.
Commentary that despite gilt issues
pension is well managed. That’s probably not really saying much though so I guess only time will tell whether this could be a ticking time bomb for the company - with large pension scheme they are much more at risk if there are hidden nasties yet to be laid out on the table.
Morning Paul,
Thanks for the interesting macro view.
For those of us that weren't investing in 2007/2008, what lessons did you learn from that period, and how do you think you'll weather the storm this time around?
Thanks,
Agree with your macro outlook entirely Paul. But even more concerning is the potential for bail ins rather than bail outs this time around…. Possibly not a good time to be holding large amounts of cash on deposit or any shares in financial institutions?
Never say never but the starting point is very different. Banks are much much better capitalised 5-6-7x.....and much lower leveraged...ie much smaller asset books. Sure there will be losses - I imagine problems in venture and private equity ... and someone always does something stupid ...but I wouldn't be alarmist... Banks are in much better positions. This is a sovereign crisis.
Not a small cap but I thought interesting that easyJet easyJet (LON:EZJ) this morning says it only expects to fly at 83% of 2019 levels during the next quarter. I hadn't appreciated just how far off airlines/holidays abroad still are from their pre pandemic peak. (Also keep in mind they focus on short haul which I thought would have recovered more quickly by now).
One of the companies I do contract work for used to (pre covid) fly me and about 100 others around Europe 6/7 times a year for work. That has all gone online and will never (in their words) go back to face to face. While easyjet isn't the business person's flight of choice, it is often used to/from regional airports where BA etc. might not fly. I'm sure my company is not alone in reducing these flights.
Bang on carvalio, my largest client, a private American based multi-national produced $10m savings in the first year of the pandemic purely from (no) flight, hotels and restaurants. They said then they would maintain this way of working and they have. Travel now is purely on an absolute need to basis and the owners enforce that. Its a on-line world now and all the more boring for it.