Small Cap Value Report (Thu 14 Mar 2024) - NXQ, IPF, ABDX, PRES, VTY, IGG, GDWN, MOON, OSB, BKS, TRN

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Paul's 2023 share ideas, with live prices.
New SCVR summary spreadsheet from July 2023 to date, updated at weekends (very useful quick reference tool, search for ticker using CTRL+F). Hover over cell for pop-up notes.
Frozen SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
(We can't cover everything remember!) ... EDIT: oh yes we can! It's a clean sweep today :-)
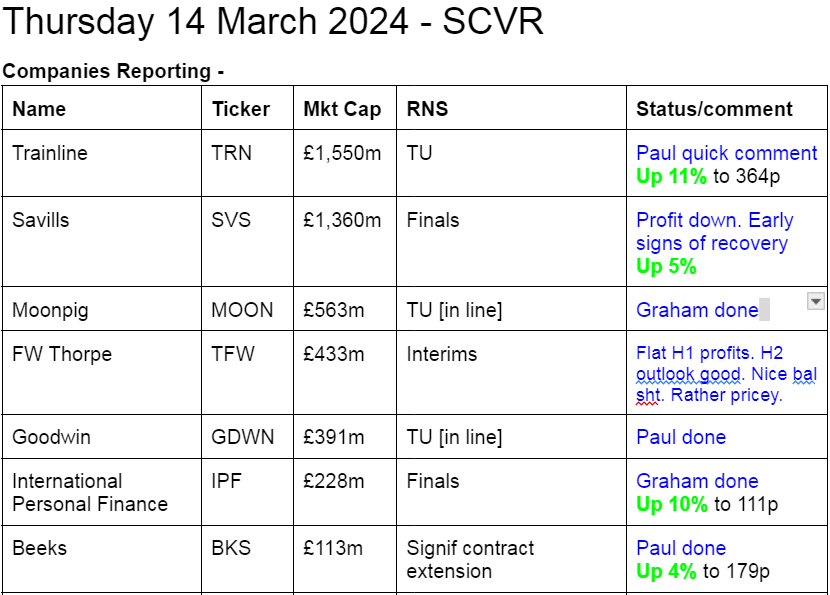
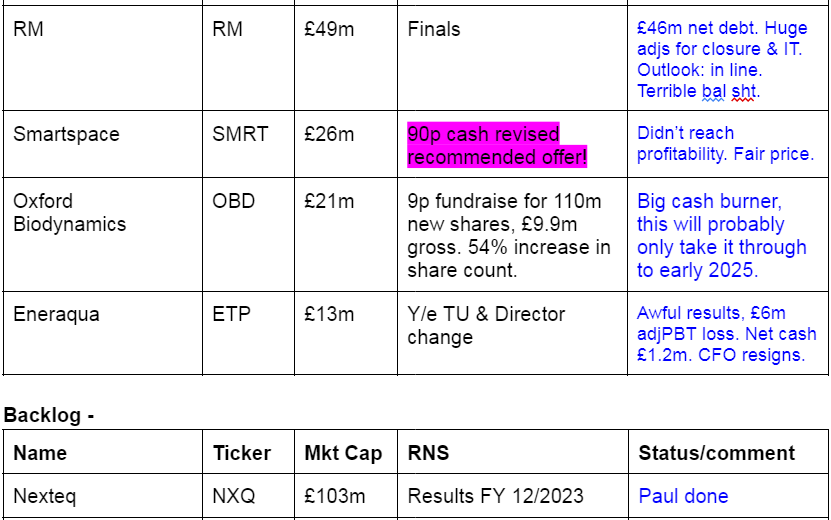
Other mid-morning movers (with news) -
Abingdon Health (LON:ABDX) - up 26% to 8.5p (£10m) - H1 Results (Dec 2023) - Paul - AMBER/RED
Well received results. H1 revs doubled to £2.4m. Loss halved to £(1.2)m in H1. Says H2 revs will be significantly higher than H1 (as they were LY). FY 6/2024 revs to be materially higher than £4.0m LY. Says it will reach breakeven in 2024 (calender, presumably? Not FY 6/2024). Says it won’t need another fundraise - they always say that! It’s still burning through the cash, with only £2.0m left at Dec 2023 (£20m cash was raised in the IPO), so I think it will need another fundraise. Still loss-making, and a disastrous 2020 AIM float at 96p, never turned a profit, so it has a lot to prove. Not of interest to me at this stage, even as a punt.
Pressure Technologies (LON:PRES) - up 7% to 36p (£14m) - Contracts & Disposal - Paul - AMBER/GREEN
“two major contracts, as expected” won by Chesterfield Cylinders, the core business. No financial info is provided. One is defence (Australian), the other in green energy - a pilot, using 48 large cylinders to store surplus energy via compressed air. If this takes off, could be exciting maybe? “Maintains outlook” for 2024.
Pending disposal of PMC division - has received “a number” of indicative offers (I dislike this ambiguity - 1 is a number! Surely “several” would be clearer, if it’s more than 1?). Looking to complete the process in Apr-Jun 2024 (Q3 of FY 9/2024).
Paul’s view - I quite like PRES, things seem to be moving in the right direction, but it’s still requiring heavy guesswork/inside info to know what the financial specifics are for contracts, and the possible disposal proceeds, hence what the shares are worth. But I’ll go up from amber to AMBER/GREEN. I’ve always liked the potential for Chesterfield Cylinders, but it’s had false dawns before, where surging profits later dried up. Nice to see activist institutions nurturing it back to health, after Lloyds Bank let it down, removing a tiny facility.
Vistry (LON:VTY) - up 5% to 1168p (£4.0bn) - FY 12/2023 Results well received. The newswire says it’s a profit beat, and higher production expected in 2024. Also a further £100m share buyback announced. Paul’s view - I really like Vistry’s differentiated, partnership model for building houses. It’s proven much more resilient than traditional house builders in this current downturn. Outlook comments are positive. Now trading at almost double NTAV, so maybe the shares are up with events now after a great run (up c.78% since last summer’s lows)? Political risk from a new Govt possibly worrying?
IG group (LON:IGG) - up 4% to 735p (£2.8bn) - Q3 Update - confirms trading is in line with expectations for FY 5/2024 (revenue and adj PBT). Big shake up of the Board, with the CFO and COO being presumably pushed out by the newish CEO Breon Corcoran, who friends tell me has an impressive track record, and kicks ass.
Osb (LON:OSB) - down 16% to 386p (£1.52bn) - specialist lender plunges 16% on FY 12/2023 Results - adj PBT down 28% to £426m (still an awful lot for a £1.5bn mkt cap though). Net loan book up 9% to £25.7bn. Net interest margin down from 303bps to 251bps. Adj EPS down 25% to 75p (PER 5.1x). New share buyback of £50m announced. 32p total divis, yield of 8.3%. Bal sht NTAV exceeds market cap.
Paul’s view - first time I’ve looked at this, and I’m intrigued. It’s a simple savings & loans bank. The cash mainly comes from retail deposits, of c.£22bn. So my main worry would be a risk of depositor flight, as we’ve seen in recent banking crises. I never invest in banks personally. But the 8.3% yield, and straightforward, seemingly sound finances at OSB do seem quite appealing. Also a mortgage broker told me recently that many lenders are deserting the buy to let lending space (OSB's niche), or offering lousy deals and requiring high LTVs. Hence maybe more business might come OSB’s way? Not many BTL borrowers default. Looks potentially interesting, I won’t give it a colour though, as I don’t know enough about the company or this space. I wonder if there’s regulatory risk that I’m not aware of? For sophisticated investors, bonds in banks are an interesting alternative to the equity.
Beeks Financial Cloud (LON:BKS) [Paul holds] - up 4% to 178p (£117m) - Contract Extension - Paul - GREEN
More reassuring news from this specialist cloud computing company, probably my favourite GARP share. “Significant extension” to its big contract with Johannesburg Stock Exchange - reinforcing the company’s “land and expand” strategy which generates ongoing organic growth, as customers start small, then do more business with BKS as they gain confidence in the service. Demand is higher than expected, and significant pipeline, are mentioned today. Forecasts for BKS were recently upped, so this deal seems part of that, not in addition to it, I think, as it “further supports” recent upgrades for FY25. Hence a modest share price rise today seems sensible. Also a possible second (backup) site for Johannesburg is mentioned.
Paul’s view - I see the bull case playing out very nicely here. The bear case seems to be backward-looking, pulling apart historic figures, but I’m not buying the past, I’m buying the future, which is looking very good. It doesn't pay to stubbornly stick to a wrong opinion, as we learn over time, often the hard way! The bears are wrong here, in my view, but I do like to hear what they have to say, so I can think about it.
Trainline (LON:TRN) - up 11% to 362p (£1.7bn) - Trading Statement - relating to FY 2/2024. Positive market reaction (up 11%). Revenue £397m, up 21% is slightly ahead of 15-20% guidance. It’s obvious from reading this TU that TRN is way too complicated for me to get into now. Also I am not given access to any broker notes or updates. An 11% share price update suggests that privileged info has probably been issued to professional & institutional investors, in this market that is rigged against PIs - no wonder some people are giving up and switching to US shares.
I don’t see anything attractive at all in the StockReport numbers & forecasts, so am not motivated to investigate TRN further. Maybe readers can explain the bull case here? It seems to talk about European expansion, but is still a mainly UK travel intermediary. I see reader comments are discussing the bull:bear views. Sorry I can’t add anything more, due to lack of information.
Summaries of main sections
Nexteq (LON:NXQ) - 155p (£103m) - Audited Final Results -(y'day) Paul - AMBER/GREEN
Decent results, that beat expectations. Forecasts raised by the house broker for 2024. Amazing balance sheet, with ample surplus capital & cash, giving plenty of firepower for acquisitions. The wobbly, over-PR'd outlook statement spoils it for me though, with a soft H1 in 2024 now seeming likely, and it dodged the question of meeting 2024 profit expectations, instead only confirming revenues - which strikes me as deceptive, and introducing doubt. Very odd to be raising broker forecast at the same time as giving a wobbly-sounding outlook - this wasn't thought-through properly.
International Personal Finance (LON:IPF) - up 10% to 110.95p (£249m) - Final Results - Graham - GREEN
Uncertainty around Polish regulation has been partially lifted as IPF has been able to quantify the cost of recent news at £10m of annual PBT. For a stock trading at a low single digit multiple and for whom £10m is only a fraction of annual profits, it’s excellent news.
Goodwin (LON:GDWN) - up 1% to 5240p (£394m) - Trading Update - Paul - AMBER/GREEN
It's good to see this engineering group introducing more regular updates than before. It's in line with expectations, and
Moonpig (LON:MOON) - down 0.3% to 178.9p (£616m) - Trading Update - Graham - AMBER
Performance has been in line with expectations at Moonpig following Christmas, Valentine’s Day and Mother’s Day, and expectations are unchanged. Additionally, balance sheet concerns may be eased by confirmation that the leverage multiple is on track to reach 1.5x.
Paul’s Section:
Nexteq (LON:NXQ)
155p (£103m) - Audited Final Results -(y'day) Paul - AMBER/GREEN
Nexteq (AIM: NXQ), a leading technology solutions provider to customers in selected industrial markets, is pleased to announce its audited full year results for the 12 months ended 31 December 2023.
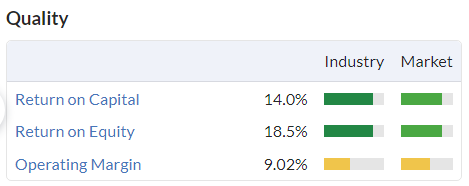
Revenues down 5% to $114.3m, but the gross margin has increased markedly (32.2% in 2022 to 36.3% in 2023), saving the day, with adj PBT up an impressive 45% to $14.7m - a healthy 13% PBT margin - which tells me this is a decent quality business, with some pricing power. Sure enough, the StockReport shows decent quality measures (these are historic, so the operating margin will go up once the 2023 actuals update) -
Adj EPS is only up 2% to 18.09c (ahead of consensus 16.4c shown on the StockReport), converting to sterling = 14.1p = PER of 11.0x - which seems decent value at first sight for a decent quality business. That’s despite this share being up more than 50% since the lows in Dec 2023.
EDIT: note that, as kindly pointed out by Snazzytime in the comments below, EPS growth was suppressed by a tax credit of $2.2m boosting the FY 12/2022 comparative earnings, compared with a reversal into a more normal $2.0m tax charge in FY 12/2023. This turned 47% growth in PBT into a 1% fall in PAT. End of edit.
Broker update - Cavendish helpfully confirms that the 2023 results are ahead of its forecast - actual 18.09c, forecast 15.9c.
It also ups 2024 forecast adj EPS from 16.8c to 18.1c (flat with 2023 actual, so hopefully they’ve left room for out-performance as 2024 progresses).
Outlook - this is perhaps why NXQ shares slipped slightly yesterday (after a very strong run in the last 3 months) - a more hesitant outlook.
“Slower order intake” so far in 2024, due to customer destocking.
Improvement expected in H2.
Visibility is good, due to “healthy order backlog”
"confident in meeting market expectations for 2024 revenues, with a second half weighting." - I’m more interested in profit than revenue, so dodging this point does not go unnoticed, and introduces doubt.
Organic growth opportunities “in the medium term” - again the wording introduces doubt about the short term.
More efficiency actions being taken to prioritise profitability.
Net cash expected to further improve as supply chains normalise, further building cash surplus - says acquisitions may be done.
Balance sheet - wow, this is superb! It’s got c.$60m in net current assets, including $28.4m cash. Negligible bank borrowings of c.$0.5m.
This is a lot of surplus capital for a business with a market cap of £103m. I’d say it has ample firepower to make quite big acquisitions, if it was prepared to take on a bit of debt too - up to say $15m net debt position wouldn’t concern me. So that gives it over $40m in potential acquisition firepower.
Dividends are modest, which is strange for a nicely cash generative company that’s sitting on a large & growing cash pile. Why are they so hesitant about shareholder returns?
Paul’s opinion - the outlook statement blew it for me, they’ve tried to be clever by twisting market expectations to cover revenues, not profit. I hate it when companies do that - do they think we’re stupid and won’t notice? All they’ve done is to introduce doubt, and that is worsened with the H2 weighting. So we’ve now been warmed up for probably disappointing H1 results.
If the outlook statement had been stronger, then this share would have had a clear road up to about 200p I think, but the wobbly outlook has put me off for now. Am happy to keep monitoring it though. The excellent balance sheet gives nice hidden upside though, if they spend it wisely on a decent acquisition or two.
Let’s go with AMBER/GREEN, due to very good fundamentals and modest valuation, whilst being aware that a soft H1 for 2024 sounds like it’s on the cards, so there could be a pullback in share price at some point, possibly.
Long-term it's been disappointing, and de-rated from a growth company to a value share - could there be an opportunity for perception to improve in the next bull market, I wonder?
Goodwin (LON:GDWN)
Up 1% to 5240p (£394m) - Trading Update - Paul - AMBER/GREEN
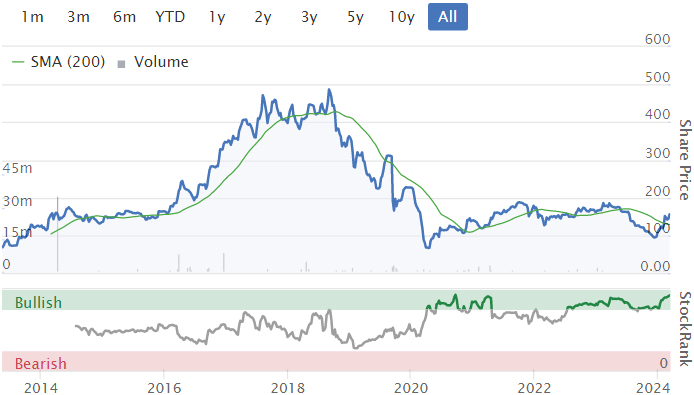
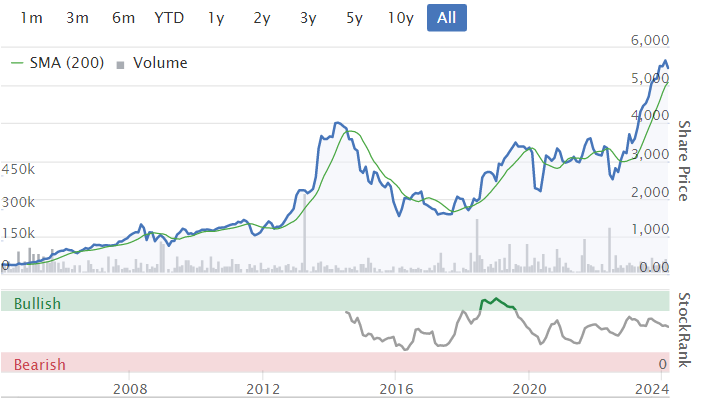
This is a family-controlled engineering group. I like the company, and included it on my top 20 shares ideas for 2023 at 3335p. It’s up 57% since then, and both Graham (SCVR 20/12/2023) and I (SCVR 11/8/2023) thought the price looked up with events, but were impressed with its large order book disclosures each time.
Reporting is sparse, and I note it doesn’t usually issue an update this time of year, so my initial worry in those situations is that it might be a profit warning.
A helpful note from Shore Capital today says that management has introduced quarterly updates to shareholders to keep investors better informed - bravo for that!
The first sentence of today’s update reassures us -
The Group's trading activity has remained in line with expectations and the profitability of the Group in the second half of the year will be similar to the first six months
That makes it easy to work out - H1 was PBT of £12.1m on £97.6m revenues, so a nice healthy margin. This profit benefited from a £0.9m profit on a SWAP derivative, so “trading profit” was £11.2m. It’s not clear which profit figure GDWN is referencing in today’s update.
In EPS terms, it was 115.7p in H1, so double that to 231p roughly in FY 4/2024.
The PER on that is 22.7x - not cheap, but I see this as a quality growth business -
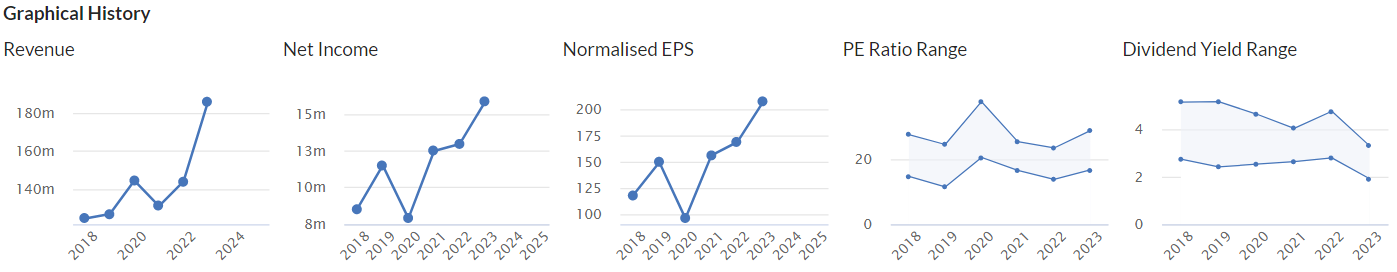
Order book - which it called “current workload”, I assume that’s the same thing? Is large, at £252m. Yes it seems to use these terms interchangeably, as in the 20/12/2023 published H1 results, it disclosed a “current forward order book of £266m”. Today’s £252m is c.5% down, not enough to cause me any alarm, it’s still a big number, and well over a full year’s revenue.
Energy - it’s using more solar, and planting 500k trees to offset use of gas in its manufacturing.
Growth - I like this bit -
Following a record order input last year at Goodwin Steel Castings of £77.2 million, higher than the cumulative input over the last five years, the level of throughput at the foundry is increasing. Consequently, the foundry will be contributing a greater level of profits moving forward as a higher proportion of the work will relate to highly technical and specialist mission critical castings that are priced accordingly. Over the past five years nearly all of these components have been through a development process and have successfully been delivered to our customers. With activity levels continuing to increase throughout the year, the Board sees this as an exciting time for Goodwin Steel Castings going forward.
Turnaround at Easat is still pending -
We commented in the 2023/24 Outlook section of the Interim Report that we believed Easat Radar Systems, over the next six months, will be announced as the successful bidder of a number of contracts, though we have nothing further to report at this time as the tendering processes are still ongoing…
Balance sheet - looking back at H1 figures, the Oct 2023 balance sheet isn’t that great actually. It contained a fair bit of net debt at £54.6m, although the H1 commentary said this was expected to “reduce over time” as capex falls and working capital unwinds somewhat.
It would have been helpful to give an update on the net debt position today too, but that is not mentioned.
Forecasts - there don’t seem to be any, with Shore saying it intends to introduce figures in due course. But we have good guidance from the company today, which I’ve worked out as c.231p EPS this year, as above.
Paul’s opinion - a very interesting company I think. It seems to have successfully carved out profitable niches, and there’s been plenty of investor talk in the past of large contracts having potential to become very large and long-term - nuclear waste storage containers was I think (from memory) one of the mooted growth areas. This was a strategy to move away from its previous over-reliance on the oil industry. However, with oil & gas now seemingly firing up again over energy security issues, maybe we might see growth return in that area too?
My view is unchanged, I really like this business, but feel the share price is up with events again. So I usually colour-code those as AMBER/GREEN.
I know we have several readers who have studied this in much more detail than me, so I’m looking forward to hearing your views in the comments.
Twenty-bagger in 20 years, wow! Who said boring was bad?!
Graham’s Section:
International Personal Finance (LON:IPF)
Share price: 110.95p (+10%)
Market cap: £249m
I’m a long-time fan of this company, but I still find their self-description rather odd:
International Personal Finance is helping to build a better world through financial inclusion by providing affordable credit products and insurance services to underserved consumers across nine markets.
Markets served include various Eastern European countries, Australia and Mexico.
The good news is that these are solid results, with rising PBT despite some weakness in key metrics:
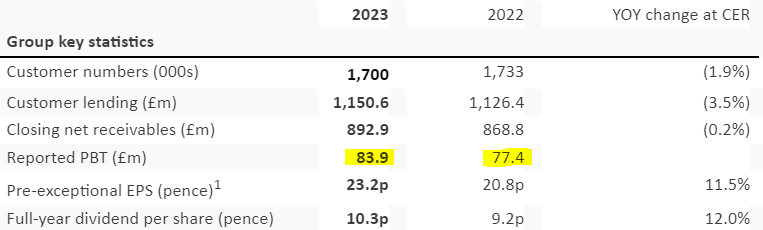
The PBT result (£83.9m) was “ahead of our internal plans”.
Remember that Poland has been the most difficult territory for IPF in recent times, as Polish regulators have clamped down on non-interest fees charged by lenders.
Last October, in the Q3 trading update, we learned that IPF’s lending in Poland was down 23% year-to-date.
Today we learn that the full-year result is even worse: lending in Poland fell by 29% for the year.
But the stats excluding Poland are perfectly fine:
Customer lending up 8% excluding Poland (it’s down 3.5% overall)
Net receivables up 12% excluding Poland (it’s down 0.2% overall at CER)
And the lending portfolio is performing well: the impairment rate did increase from 8.6% to 12.2%, but IPF’s long-term target is 14% to 16%.
CEO comment excerpt:
All of our businesses delivered good growth, with the exception of Poland where we anticipated a shrinkage as we adapt to new regulation and the rollout of our credit card product. We are now serving more than 130,000 customers with this exciting new offering and we continue to adapt and change our Polish business to customer needs and ongoing changes in regulation.
Regulatory update
Unfortunately this section does contain some bad news, from an IPF shareholder perspective.
The Polish regulator has written to all lenders to express its views on how the country’s new lending regulations should be interpreted. I won’t go into all the details but this is the result:
The Group estimates that if the expectations set out in the KNF letter are implemented in full in their current form, the non-interest fees generated by the Group's Polish credit card business could be reduced by approximately 30% - 40%. On an ongoing basis, after taking account of the Group's strong trading performance in 2023, this could reduce the Group's profit before tax by up to £10m per annum.
Outlook
The positive momentum from IPF’s strong overall performance in 2023 (presumably excluding Poland) “has continued in early 2024”:
Our actions over the last two years to maintain tight credit standards, improve revenue yields and drive cost efficiency have been very successful in improving the Group's returns towards our target levels. Credit quality is excellent, we have a robust balance sheet and strong funding position, and we are progressing with plans to refinance the Eurobond maturing in November 2025.
The refinancing of the large Eurobond (c. €300m outstanding) will be a key event for IPF. Note that this single bond is worth more than IPF’s market cap!
Graham’s view
The news from Poland is certainly a blow but in some ways it shouldn’t come as a shock that the regulator would want to shut down non-interest charges on credit cards, after they have already done this for home credit loans.
It does mean that IPF’s strategy - of seamlessly switching from home credit to a credit card model - has been hugely undermined.
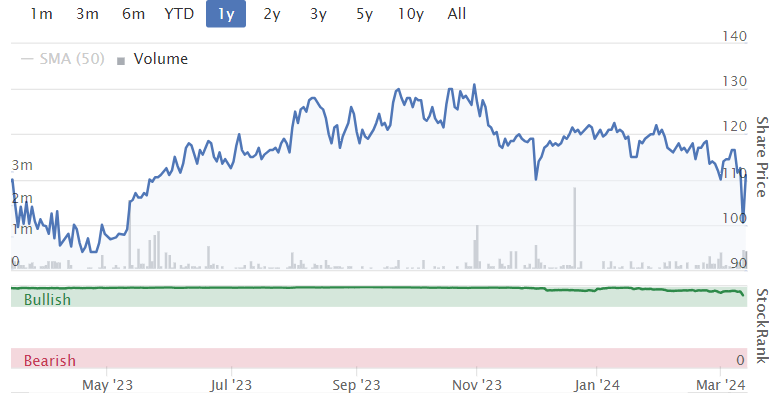
The good news is that the IPF share price has been pricing in plenty of bad news:
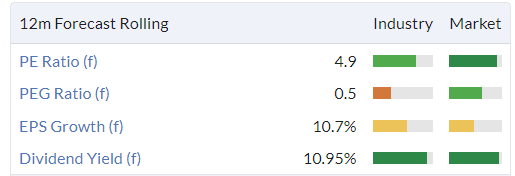
Indeed, if a £10m hit to annual PBT is the last bit of bad news that is left to hit this stock, then shareholders should do extremely well from here.
The company reports an adjusted return on equity of 11.1% for 2023, slightly lower than the 11.5% achieved in 2022. And the adjustments seem reasonable to me (without the adjustments, it would have reported an even higher ROE in 2022).
This is a reasonable rate of return in my book, but the company still trades at a very steep discount to its balance sheet net assets of over £500m (tangible net assets £446m)..
For me, the bad news and the risk should be priced into the equity at this level. Although as I’ve said before, I think IPF’s debt instruments are also potentially very attractive investments and maybe even offer better risk/reward than the equity. For example, there is the 2027 retail bond (trading under the ticker IPF3 on the LSE’s retail bond platform) that pays a 12% coupon. If that could be bought around par, I might even prefer that to the equity.
Moonpig (LON:MOON)
Share price: 178.9p (-0.3%)
Market cap: £616m
Moonpig Group plc (the "Group"), the leading online greeting card and gifting platform in the UK and the Netherlands, today provides an update on its trading performance in the current financial year ending 30 April 2024.
Performance has stayed in line with expectations and expectations for the financial year are unchanged.
We’ve now had Christmas, Valentine’s Day and even Mother’s Day, so I guess that most people won’t need to buy cards again for a few months!
Balance sheet - Paul has been highly critical of Moonpig’s balance sheet (see comments last September) and the company is keen to reassure investors on this front:
The Group is highly cash generative and we remain focused on deleveraging. We continue to expect that we will reduce the ratio of net debt to Adjusted EBITDA to below 1.5x by 30 April 2024.
Checking the interim results (for the period ending October 2023), I see that the leverage multiple (“net debt to pro forma adjusted EBITDA”) had reduced from 2.45x to 1.83x year-on-year.
This was thanks to a £40m+ reduction in net debt year-on-year, down to £167m, combined with an increase in EBITDA.
Given the substantial reduction in the leverage multiple already achieved, maybe it’s reasonable to think that they can keep going and get it down to 1.5x in the near future, as planned?
I also note that Moonpig’s £167m net debt figure includes leases, which many investors would be happy to exclude from the calculation. Excluding leases, net debt was £149m.
Leverage of 1.5x is something which most companies should be able to manage comfortably, assuming that trading does not suddenly collapse.
New RCF: this also sounds like positive balance sheet-related news.
Moonpig previously had a £175 term loan, along with an £80m RCF. So total bank facilities were £255m.
These have been cancelled and replaced by a single £180m RCF.
For me, this new RCF is effectively proof that Moonpig do not intend to increase their bank borrowings any time soon. They had bank borrowings of c. £171m at the interim results, not far off their new upper limit.
Graham’s view
I think there is lots of positive balance sheet-related news for investors to chew on here.
We do still need to account for the debt when valuing Moonpig; adding on c. £150m of financial net debt to the market cap gives an enterprise value of £765m.
This isn’t a cheap stock:

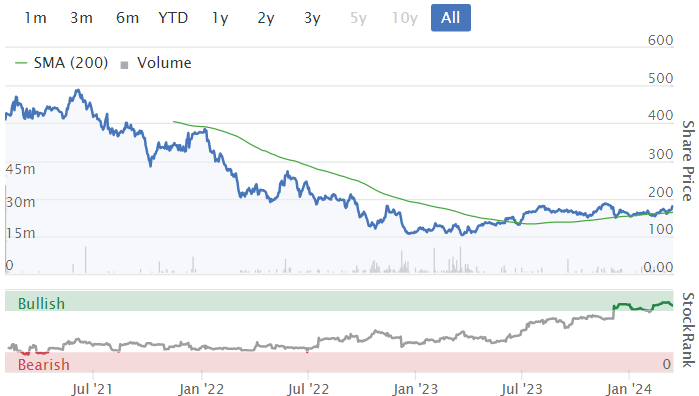
Forecast net income is £35.5m for FY April 2024, rising to £41.2m for FY April 2025 (source: StockReport).
I do like this company a lot - the brand is very widely recognised and the customer experience seems good for most people (4.2 on Trustpilot). But perhaps the stock is fairly priced at this level? I’m neutral.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

101 comments
CAPD
Hi, did you manage to have a look at CAPD's results please?
Thanks
Run For the Hills Day
Cut and run from the last of my non core positions today
Trifast - didn’t like the CFO leaving abruptly end feb, think this will be a long slow turnaround that doesn’t really interest me in any way shape or form. Plus I kept getting it muddled up with titon .(Thought I’d done well buying 17k of Titon at 76p last week only to realise today I’d bought Trifast )
Centaur - cleared the last of the holding today was a bounce trade really and it bounced a bit .
Restore - had been building up but again it’s a 3 year turnaround and likeky to be up and down and doesn’t excite me at all .
LDG - chopped out a residual small position
Funds generated go towards
MSI - getting to a bigger position as good qty available at present , liquidity seems much improved
Transense - illiquid microcap but I like management and one of their top guys has 2 of my bikes so at least I’ll have something to talk to him About .
Titon - always regretted selling my chunk to Rockwood so have been building back up . Likely to go nowhere for a while but find this one more interesting not sure why .
Also bought a 6m high by 10m lomg carved elephant frieze and some 4m high Zulu warriors so can put them outside our building to wind up Sheffield city council who are a nightmare but that’s a different story .
Vistry (LON:VTY) ( I hold)
There is some reasonable differentiation in the business models of the various house builders. Vistry currently stands alone as deciding to focus purely on the Partnerships model. In terms of valuation, its "comp" in the US is NVR which trades at circa 5.5x NAV! Its also why 3 of the top 10 shareholders are US funds. Lennar the biggest US homebuilder trades at 2x NAV.
NVR has been rewarded for being asset light with much higher returns as a result. NVR and VTY are not identical but effectively VTY will not own land this will be provided by say a council . VTY develops it, accepting a lower margin but having far higher volumes and visibility. As a result it can negotiate better with suppliers and workforce as it has better line of sight through its whole business.
https://www.yetanothervalueblo...
This link is to a podcast for those interested in knowing more. This is the 10th largest shareholder. This blog is excellent btw!
Goodwin (LON:GDWN) is my largest position so my bias is considerable….my belief is one of the few free lunches we get on the stock market is when a business is complex & fast changing but ignored by analysts and
off the radar of institutions….that enables private investors who have the stomach/patience/time available to understand the business evolution & the significance of the pieces of information that are out there.…to bag a free lunch ..obviously that only applies if the business is any good…in this case it is one of best long term compounders on the LSE so there’s a chance they might know a thing or two about business building ..
we’ve also not *yet* seen the fruits of all the enormous step up in activity/capex/innovation/physical footprint over the last 10 yrs or so, but in addition you’ve also got 3 bought & paid for potentially transformative projects just starting to ramp up…first is AVD..https://www.avdfire.com/what-i...
new factory opens next month 2.5 acre site 50000 sq ft factory …sales doubling every year for the foreseeable future (AGM discussion ) …then the ramp up in EASAT …https://www.easat.com/ which is imminent ..albeit later than initially appeared likely…and then from June you get Ducoya products beginning their journey into “the largest market we’ve ever entered”
..& the rest of the business is looking well set too….(understatement alert) …the foundry was running at half capacity..they’ve just finished extending it & re-equipping it to double capacity…& they expect to be flat out for the next decade or more…predominantly with high margin U.K. & USA defence work…I could go on but I’d probably outstay my welcome…
Good post rhomboid1, I'm going to out it on the Goodwin thread for future reference.
Paul,
Spot on re Beeks Financial Cloud (LON:BKS) - this is exactly why these types of businesses trade on high PERs versus market. Firstly the customers are sticky and secondly if the offering works the expansion is usually large. So long term revenue visibility that grows and then starts to throw off vast amounts of net positive cash flow. We are very close to that point with Beeks Financial Cloud (LON:BKS) I think and it is also in my top 3 GARP shares. Slightly surprised it didn’t go up more on this news as it is quite material both in size but more importantly overall context and business momentum.
hi David
Beeks Financial Cloud (LON:BKS)
it is also in my top 3 GARP shares
I'm guessing GlobalData (LON:DATA) is also one of your 3?
Would be interested to hear who else in in your top 3.
Snazzy
Hi Snazzy,
Actually it isn’t. I like GlobalData (LON:DATA) and I hold and see good upside but it’s well outside my top 3. Mainly because I think investors find it complicated, so suspect that will hold back the share price. Inflexion deal probably underpins it on downside risk but doesn’t really appear to be on anyone’s radar. Doesn’t help that founder is gradually bringing his holding down to a more reasonable level for a PLC as this means institutional demand is met without putting upward pressure on price. That said I also have a relatively small position weight so happy to hold and let play out. If it continued to drift I’d probably top up.
For what its worth my top 3 (well 4 - 3rd equal) GARP preferences are
hVIVO (LON:HVO)
Beeks Financial Cloud (LON:BKS)
MS International (LON:MSI)
MPAC (LON:MPAC)
Different sectors, all have done well this year. None of these are trades for me - medium to long term holds so I have no idea when the story plays out. Held all of them for a long time and topped up MPAC (LON:MPAC) when it was very unloved around 225p
I would have said Bank of Georgia (LON:BGEO) and Georgia Capital (LON:CGEO) but they are not really GARP shares and whilst I still think both are cheap (haven’t sold any) there’s prob less upside.
Beeks Financial Cloud (LON:BKS) I agree with your thoughts. What I’d add is that my experience of financial services clients is that once one has a technological advantage, then they all feel they must follow suit.
Yes - that and credibility BnB. Once credible with some of the largest world exchanges that becomes a valuable Moat.
Goodwin (LON:GDWN) are perhaps the only UK listed company that, when issuing a TS, only mentions items of interest relative to the prior results. No repeat mention of several areas of the business where sales are doubling annually or just about to ramp up explosively, as we have already been told this.
IG group (LON:IGG)
I am looking for arguments against buying more of this stock as it seems to offer both UK &US exposure for a fair price with strong dividend policies and a buy back plan for this year. Lack of UK liquidity in shares is holding back performance of the UK arm but I guess this will improve meanwhile the US acquisition seems to be growing well.
hi Paul
Nexteq (LON:NXQ)
Adj EPS is only up 2% to 18.09c
FY'22 EPS was inflated due to a net $2.2m tax credit (tax credit $2.7m less actual tax charge $0.5m) so on a like for like basis adj PBT for FY'22 was inflated by $2.7m and similarly that means EPS was overstated by around 25% on a LFL basis.
So FY'23 EPS of 18.09 cents, rather than being the headline +2%, was more like a 30%+ increase on a LFL basis.
Snazzy
Hi Snazzy,
Ah yes someone mentioned the tax credit/charge at NXQ yesterday, probably you! I'd forgotten about that by this morning when I wrote the above. Thanks for reiterating.
You're quite right, the P&L shows $2.2m tax credit in 2022, and $2.0m tax charge in 2023. That's a material impact, so I've edited the main article to include this point, with a little hat-tip to you for pointing it out :-)
Many thanks,
Regards, Paul.
I posted this summary on the Goodwin (LON:GDWN) thread today, thought it might be useful to post here for the wider audience (I hold):
Goodwin March 2024 Trading Update
Something to watch at lunchtime....
Join us for our Tax Efficient Investing Webinar tomorrow, Thursday 14th March 2024, at 1pm. https://melloevents.com/melloeis/
The webinar will discuss the Enterprise Investment Scheme (EIS) for investors seeking tax-efficient ways to support early-stage businesses. With EIS, investors can benefit from significant tax incentives, including income tax relief, capital gains tax deferral, and exemption from inheritance tax.For more information, please visit https://melloevents.com/melloeis/
The programme is as follows:
1.00pm Keith Hiscock of Hardman and Co introduces EIS investing
1.20pm Company presentation from Learning with Experts
2.00pm Company presentation from Clipper Automotive
2.40pm EIS review session
Register for FREE here: https://us06web.zoom.us/webinar/register/WN_7sSaWLFJTBqvR84kpL0wxw#/registration
Badly timed for the hordes who will be watching the Cheltenham Festival.
Nexteq (LON:NXQ)
Excellent comments Paul - all unecessarily odd that they go out of their way to cross reference revenues only - whilst the brokers have actually upped the earnings expectations. Would be interesting to see if this is some corporate muppet saying they shouldnt cross reference future earnings in results outlook ? strange how some companies shoot straight and some always seem to give reasonable clarity while others actively swerve straight shooting , even if those numbers are being formally presented by broker same day - ridiculously annoying that official release doest pretty much say exactly what broker is saying (presuming they are in agreement over the numbers)
I tend to ignore the speak and go with the brokers - normally though if it aint said its bad news rather than good. I would agree though the fact they have avoided mentioning profits does make me wander if they may have reasons for that - the dreaded investment for future growth bullshot which just means later in the year they spend like mad to hit revenue targets set now !!!
Pressure Technologies (LON:PRES)
I hold.
As mentioned in earlier posts, the company does at last seem to gaining some traction. Whether anticipated or not the two contract wins are good news. Also there appears to be a number of potential acquirers for the PMC division, which suggests that the company should be able to obtain a reasonable price. Hopefully sufficient to repay the loan from Rockwood and Peter Gyllenhammer and leave some for reinvesting in Chesterfield Special Cylinders.
Grrrr - I see today that L&G are joining a group of investors that are intending to make Nestle hold a vote on ceasing production of its most 'unhealthy'products. This woke ESG meddling in co.s' affairs is making my blood boil - it is no wonder co.s are not listing in the UK or are delisting and moving elsewhere. Surely the only unhealthy product is the one that is consumed in excess? If that's what the British masses want then that is what they want (and will get) - whether it is made on home shores or abroad. You can't stop personal choice by social engineering at company level. A large holder of Glencore is attempting to get it to stop the sale of its coal division and move its listing out of London to Sydney! Coal is still used - that isn't going to be stopped by woke western idealism, if UK registered co.s don't profit from it then somebody else will. What good does that serve? Absolutely nothing! The world is going to carry on smoking but lots of UK funds won't touch tobacco co's for fear of some ESG / woke backlash. So what does that achieve? Tobacco manufacturering and the co.s move abroad - they don't stop. They just move and take their profits and employment with them. Leaving the UK with a vastly depleted list of co.s - still as long as we're top of the ESG list eh?
Not only do UK registered co's have to put up with our nations fascination to be so very ESG perfect but they have the beaurocratic interferring of the likes of useless OFGEM and other official bodies constantly interferring in their business. OFGEM lets co.s start up with obvious poor business models (why so very many went bust) and then charges the rest of us an increased standing charge on our electricity bills to make good the discrepancy caused by their poor performance. As soon as a co. gets large and highly profitable it future growth is hampered by meddling of such civil servant bodies as Monopolies and Mergies - what happened to market forces? Of course, the civil servants themselves couldn't run a p**s up in a brewery themselves. Don't get me started on the useless FCA and how a certain Mr Bailey (despite the FCA being useless on his watch) was promoted to the BofE as reward for being usless. The no. of co.s that are permitted to register / remain on AIM even though their prospectus and / or business model is highly questionable is alarming. Its like the wild west - little or no regulation and certainly not a market to aspire to. Contrast that with the SEC - they do have teeth and use them.
No wonder the market in the UK is on its knees.
Rant over!
I see today that L&G are joining a group of investors that are intending to make Nestle hold a vote on ceasing production of its most 'unhealthy'products
Unbelievable
Slight bit of good news the use of ESG (i prefer deeds not talk) by companies in their earnings calls is dwindling - thats in the us though - so i suspect it may not be the same here.
https://insight.factset.com/lo....
Morning Lincs,
I'm getting some mixed messages from this, I don't mind admitting. On the one hand the free market (in the UK at least) is deciding that ESG is a good thing, but you don't like that.
The regulator OFGEM is bad at it's job and interferes too much, and should leave it to the free market forces (see above).
Aim doesn't have enough regulation, and should have more of it, like the incredibly interventionist regulator the SEC (see above and above).
Hmmm, I'll need to have a cup of tea and re-read it, see if it makes any sense then. Hope your day gets better from here ;)
Cheers
Chris
Its clear to me some external bod with their own "biased agenda" telling a chocolate company they shouldnt be selling kit kats as a treat is over intefering. Hey ho thats my opinion - i am sure they will argue they are simply tring to make the world a safer place and protect the vulnerable.
Hmmmm - i do like a kit kat - chunkier and bigger the better if i am having one.
Whats stupid is they could have probably complained that they are using not enough chocolate and too much sugar and are clearly not acting in manner you would expect of global company that should respect the history of their products locally and dont and try and morph everyone into eating snacks as they are made in america - in that regard they would have had my support !
Exactly! And that’s because the core problem with the woke (ahem ESG agenda) is that it seems to be entirely subjective. And the line is ever moving. Today Nestle. Tomorrow Diageo. I mean isn’t alcohol bad for you too. And mining, and defence (ask Ukraine where they would be without it), etc, etc. In the traditional capitalist model there were two natural correctives. Consumers could stop buying and shareholders could sell putting pressure on the share price. Now activist shareholders buy in deliberately seeking to undermine the companies they are investing in. They could of course be building up rivals if they really see a gap in the market. Not how we do things today. Because consumers need saving from themselves. Nanny knows best. And then we wonder why productivity in the West is collapsing. Simple - it’s Marxism or at least ever heavier cost, regulation, redistribution by stealth. Business working with one hand tied behind its back. Which would be fine, except the rest of the world has not fully subscribed to our self-destruction. Have you noticed that through green washing all we have done so far is export our heavy industry to China. It’s just funny to me the legion of useful idiots we have in the West - many on six figure salaries in the finance industry amongst others who are pushing all this but being so ignorant that they don’t understand that it’s a thriving economy that ultimately pays their salaries. Undermine it and there will eventually be less of them too. But how nice it is be virtuous and rich…
In the meantime China is building two coal plants per week.
To be fair to China they are are adding more renewables than any other country by a large margin. Replacing an old inefficient coal power station past its best with a more modern efficient lfl is a needs must sitaution for them with their resources. I have been tracking their Coal output for a while (lost a bet on that i must admit) - and while they have failed to reduce output as i (and they) would like - they are pretty much close to peak clao useage right now , so we can expect coal use to drop off over the next 10 years despite the new coal power stations coming on stream. The reality is as their lifesyles improve they will use more energy per head of population - so to expect coal to decrease to quickly while overall energy use is still increasing is a step too far imho ref expectations. Again we tend to throw stones at them just because we now have our house in order NOW - if we accept they are 20 years behind us with regard to first world living standars i think its a bit cheeky us expecting them to kow tow to our standards NOW when we didnt do that when we were in similar position to them.
Not to mention the entire West has dumped their manufacturing into China to take advantage of the very low cost manufacturing. It's then a bit rich to complain that they are using lots of cheap coal.
China's population has now started to fall so that will also have a positive impact on their energy consumption reduction over time.
But in the interim the Indian power ramp up story is just getting started. And even The Economist reluctantly admits that it’s going to be very heavily coal based at least in the medium term. And no one is even assuming that Africa eventually increases its derisory power usage per head. I am not a climate change denier. But the idea that our self-denial is going to somehow tip the balance is ludicrous. It will only lead to our own self-improvishment and increasing irrelevance - also in our ability to influence the wider global agenda. I appreciate that we are straying a bit off topic so just to bring it back to Nestle. So crudely. We are happy right now to pay millions of productive adults in the UK to be economically inactive owing to ‘mental health’. We seem to have no problem with this ethically (the lives wasted, the rising cost to working tax payers, and the investment in education / infrastructure foregone by carrying this burden, not to mention the higher tax rates necessary, which in turn deter investment and marginal effort - why is the UK stock market flat lining anyone…). But we do have a problem ethically when they put Nestle in their mouths instead of Lindt!? I’m sorry. This shows we are not a serious society anymore. We deserve our flat lining growth, growing tax burden and economic irrelevance. Just please don’t complain when the UK market continues to tread water…
By all counts the population decline is partly brought about by the young making a silent protest against the rulers by not having children.
From memory you need 35 tonnes of coal to make one chinese solar panel
Should we consider the correlation between diet and population health ? Japan versus USA for example... the burden on the NHS could be improved?
But then people would live a lot longer, which would be further burden. The burden on the NHS would just be deferred? Just look at all the problems in Japan with an aging population.
More productive, healthier workforce generating higher economic growth and more tax revenue ? Japanese healthcare spend much lower than US, Europe etc... the aging population problem is their extremely low fertility rate...
ESG costly regulation that adds no value, another lever of the globalists to censor freedom of choice.
This has prompted me to make a transfer of my L&G pension from a previous employer to my SIPP. I did the same with Aviva when its CEO announced any non-diversity hires would need her sign off.
Go woke....
Whether you believe in woke or not, in this day and age I think it is very important to give your assertions some context it could easily be misconstrued.
Amanda Blanc (CEO of Aviva) was attending a treasury committee on "Sexism in the City".
A question was asked by one of the committee members to which she answered.
"There is no non-diverse hire at Aviva without it being signed off by me and the chief people officer, not because I do not trust my team, but because I want to make sure that the process followed for that recruitment has been diverse, has been properly done and is not just a phone call to a mate to say, “Would you like a job? Pop up and we will fix it up for you”. A lot of work has been done to make sure you get those numbers right."
You can read the full transcript here
https://committees.parliament....
Now it sounds to like to me she is trying address nepotism which is (was?) rife in financial arena.
DYOR - very important nowadays.
Lets be honest, its pretty clear that she doesn't trust her team, if she thinks that the approach they might take to recruitment is to call a mate.
Re " it is no wonder co.s are not listing in the UK or are delisting and moving elsewhere" I take your point re Glencore but re Nestle SA (SWX:NESN) they are registered in Switzerland and I believe only have ADR's listed in the US with nothing listed in the UK.
Therefore the Nestle thing should not really affect investors on the UK markets although many of us will wonder why L&G is sticking its oar where it doesnt belong !
Also could this backfire on L&G - had been looking at adding them to my portfolio ?
My own view is that companies should state that they comply with all legal requirements regarding the environmental, working and other regulations, and leave it at that. The environmental regulations for the UK are quite good, there's no need for companies to posture over them.
The notion that companies can be "net zero" is an impossibility anyway. All companies consume energy, it's unavoidable. Unless they're going to put turbines and/or solar panels on top of the factories sufficient to generate all the energy requirements of the factory - a highly dubious proposition - they can't claim to be "net zero."
Oil companies in particular extract hydrocarbons from the ground. They definitely can't be neutral.
But you agree there should be regulations? I ask because a lot of people here seem to think that everything should come down to personal choice and market forces and that any kind of government interference is bad/woke (whatever that means)/wrong. Food (e.g. Nestle) is an interesting example. There is an obesity epidemic in the West - poor diet/life style/lack of exercise. Government could choose to ignore this - after all, we don't want to meddle with company profits/share holder returns/international competitiveness/freedom of individuals to eat rubbish food and take no exercise.
But obesity is the primary cause of the increase in Type 2 diabetes. And diabetes, and complications from diabetes (gangrene, blindness, kidney failure) account for a third of the entire NHS budget. This does not factor in the costs of other health issues arising from obesity nor the lost productivity from workers on sick leave nor, sorry to sound woke, their mental health. I would argue there is an ethical element to this, but purely from the perspective of economic self-interest, there is so much government could do to promote healthier eating/more active life styles., which, in turn, leads to better economic outcomes (productivity, health spend etc).
Alas, this kind of joined-up, long-term thinking seems to be beyond most governments.
Osb (LON:OSB) very sharp drop this morning - as execpted a big fall in adjusted profits due to a one-off adjustment announced last year. However, what's causing today's drop seems to be the outlook/guidance section which suggests a significant fall in net interest margins this year, as a result of higher funding costs and various other factors.
Oversold in my view so have topped up
Bonkers reaction to Osb (LON:OSB) if you ask me but I would say this seems to be a share that is tightly held by institutions and loosely held by retail. So what you see as a result is exaggerated moves on news so a trait to watch.
In essence the one off adjustment was well flagged. Borrower behaviour changed and that meant the reversionary input needed to be amended. This non cash p&l charge is taken up front but the cash charge (ie the real charge) is spread over the duration of the book. So in reality it looks a large number but isn’t really.
The outlook should also have been well known - NIM was always going to come back around the levels we are seeing as the cost of funding lag effect takes place. Nothing new for me - Loan book growth at 5% plus share buy backs of 3% means EPS should rise from adjusted 66p to maybe mid 70’s. I need to do the sums, haven’t had chance to do that yet.
Anyway this book will chuck off loads of cash for a long time even if they never write another mortgage. With closer to a 10% yield and over that with buy backs the reaction just looked bizarre. Probably a case of people not actually knowing what they were looking at and trading anyway.
Osb (LON:OSB)
Hi David
Thanks for sharing your thoughts.
I usually never invest in Financials, however this was a FOMO purchase for me as the cash generation and yield was too tempting after the profit warning last year.
I'm not an expert here at all so I hope it's okay to continue the discussion.
When you say the current lending book will chuck off loads of cash, I presume you primarily mean for the next 2-5 years?
I appreciate that repayments will continue after this timeframe (and more loans will be originated in the meantime), but I was under the impression that most mortgages/loans are fixed for a duration <5 years, after which it's easier for borrowers to jump ship?
---
Even after today's fall, I don't have plans to sell as the loan book is continuing to grow, which will help offset the unsurprising drop in NIM - I must admit that the Group seems to generate so much cash, and will continue to do so for at least the next few years, that I don't quite understand why the share price drop was so large this morning, or indeed why the market cap is so low.
Thoughts from yourself or anyone else reading this would be appreciated.
A
No further bad news from Eneraqua Technologies (LON:ETP) this morning. Trading in line with (albeit battered down) expectations but two key points for me are that they continue to win (big, lumpy) business and the CFO has gone.
In my opinion, the business model is wrong but not completely broken. The key strategic error is not having a business model that provides critical financing for customers. The renewables equipment they sell is expensive and few customers can or will pay upfront for it.
This is how the large US solar providers (e.g. Enphase Energy (NMQ:ENPH) and First Solar (NSQ:FSLR)) operate and is core to the Eenergy (LON:EAAS) business model.
Interestingly Eenergy (LON:EAAS) also focusses on funding public sector customers (although seems focussed on lighting in education). It recently entered into a £40 bilateral facility with a UK bank but it's not clear how much scale that will provide.
Perhaps a combination of the two would bring scale to attract funding from the multitude of green energy funds. Alternatively, a CFO with a banking, corporate/project finance background could help move things along.
I do not hold.
Trainline (LON:TRN) trading update gives some strong numbers which are ahead. I wrote about it here:
https://x.com/MGinvestor/statu...
but then realised some people have abandoned X so here it is pasted:
Trainline's trading update is better than expectations when they upgraded the range in the HY results. Smashes current forecasts:
• Revenue +21% to £397m
• Adj EBITDA +36% to ~£121m
• EPS is FC to be +39% but IMO this will be closer to +50%
#TRN comes across as an antifragile business:
• Been around for 25 years
• Survived & then thrived from the pandemic & state app consultation & despite the usual strikes too!
• 2/3 of UK rail tickets sold by Trainline
• Very successful in Spain & Italy & now to replicate in France & Germany
• Many startups have tried to hack this space without success over the years
• Thiel's 'dont mention competitive advantage' at play
- Yes I hold
I'm hoping for some bear case now which you lot seem to be good at. Gapped up on open.
They do face competition. I use UBER to buy train tickets now.
Why buy from Trainline (LON:TRN) when you can buy direct from the train company? With no fees?
Time and convenience. Saves having multiple accounts with train companies, a single app for your tickets etc
Good point but I only ever use one train company. Also I can buy tickets for anywhere in the UK with them, no fees.
I do have the Trainline (LON:TRN) app but like Rusty2 I only usually travel with one company (GWR) so there is no advantage, I just use the GWR app. Does it matter what I think, though? The numbers speak for themselves. European expansion is exciting, France is a huge potential market for them.
Maybe the Trainline app is better for the users than the train company's app? Perhaps the Trainline app has features that make it better, or easier to use, or enables savings to be made against the train company's prices? The train companies probably don't want to make it easy for users to find the cheapest ticket.
I never found the prices any cheaper on Trainline. Just looking now, some prices are misleading, said cheapest is £12 for March, 28 but when l go into that date, cheapest is over £20. Don't think the App is any better than my train co. one. Trainline fees are "This fee will vary between a minimum of 59p and a maximum of £2.49"
Trainline offer an automatic option called "split fare". Same journey, split in two. Same train, don't have to change seats and is cheaper than buying a single ticket to your destination. The company own apps (LNER or LUMO) don't offer this. Not seen this feature on UBER ether (yet). Worth using Trainline for that. Where there's no difference, I've sometimes used the company own due to getting some cashback/perks going direct.
I have tried that split fare but it was always more expensive.
They also have the nasty cancellation fees if you need to cancel your ticket before use naturally.I've been hit by those so just brave the touchscreens at the stations nowadays unless going a bit further down country perhaps.I'm guessing the users are 'sticky' and the branding is decent and now the government has decided to not do their own software/app.. perhaps it has increased their value in the market's mind.The extra fees are extortionate though but some folk will always go for the 'easier' option - ordering your ticket upfront from the comfort of your own couch.
But I can do that on my train company App. No fees at all. Save the tickets on your device but I print them off as well, much easier going through the barriers.
Trainline (LON:TRN)
2/3 of UK rail tickets sold by Trainline
I'm surprised by this. Why do people book by trainline when you can book direct or purchase at a station for the same ticket price without having to pay Trainline a booking fee?
You asked for a bear case so this is mine!
Market cap £1.7B.
Revenues £400m.
Operating margin about 10%.
Forward FCF about £80m.
Limited upside as the market cap in relation to the numbers I have provided does not offer much upside.
This company has offered no upside since its listing.
All the best
Trainline (LON:TRN) is a middle man. Now I have never worked in the rail industry, but I worked my way up the ladder in commercial department in airline business, not dissimilar to rail business. Believe me, I tried to get rid of middle men selling our product, and made sure we made it very easy for customers to book directly by having the best website and a great call centre. I would imagine most rail bosses want to cut costs and sell direct, but given the UK TOCs don't have a commercial incentive now, perhaps they don't care?
One of the reasons I am invested in Whitbread (LON:WTB) is they sell Premier Inn hotels direct to cut out huge commissions paid (they do however sell their German hotels via booking.com), and thus gain a competitive advantage to those selling through Expedia, hrs etc. Rail companies must be trying to save this cost and cut out the middle men.
From a personal perspective, I have never used Trainline despite being a regular rail user in UK, Europe, and the World. In UK I can book through one of the TOC websites, and often get cashback via Quidco or Top Cash Back as well. Interrails are always booked through National Rail, currently 3.2pc cash back.
I have in the past shorted Trainline (LON:TRN) .
Why do railway companies pay a commission to Trainline ? I am sure Trainline do not create new business or save the railway cos money. It appears to be a parasitic business which would disappear if it hat to charge commission on top of the fares as it should. I t does have a good app which I use , but have never bought a ticket from them and never will as I want my all money to go to the business who is providing the service that I want.
Moreover, I want the very helpful sales offices in stations to continue .
International Personal Finance (LON:IPF) I am hoping that ‘our Graham’ might look at IPF as it has been a rather painful hold of late. This is primarily due to the proposed regulatory changes in Poland. In todays results I see that they’ve put a potential cost to profits of up to £10m
Profit pre tax ahead of internal estimates at £83.9m (it would be nice if they also referenced market expectations) and a final dividend of 7.2p
Mexico continues to show good growth but is this adequate compensation for the regulatory risk elsewhere (esp Poland)?
Paul or Graham, if you get a chance to look at Oakley Capital Investments (LON:OCI) it would be appreciated. I have only skim read and it seems positive. There is a large discount to NAV which makes me comfortable, although I would like to see some value come out via that gap closing! One thing that did catch my eye was saying that the portfolio was on an average EBITDA/EV multiple of 16+. This seems a little rich for private businesses unless they can show they have consistently sold investments of a similar nature at this multiple in recent times, or have good external comparators.
Greyster
Morning Greyster,
I've had a quick look, and Oakley Capital Investments (LON:OCI) seems to be a closed end investment fund. We don't cover those here I'm afraid, as it's a specialised area, where you have to dig into too much detail about the individual investments within the fund. So it would take too long for me & Graham to do each one. Hence why we stick to fairly straightforward trading businesses, that can be reviewed quickly.
However, don't let me stop you discussing any shares like this here, as I know it's an interesting sector where there are some nice discounts to NAV, which subscribers have shown interest in before.
Regards, Paul.
Paul.
There’s an Investment Trust thread here set up by Charles Mitchell and with a new thread at the beginning of each month. So for discussion on Trusts like Oakley Capital Investments (LON:OCI) that’s a good place to look and ask.
Here’s the link for it:-
https://www.stockopedia.com/co...
And the header article provides some very used links too.
There are bargains galore in the Investment Trust sector at present, and with discounts to NAV until recently the widest those discounts have been for years. Also dividend yields are also unusually high as a result of the falls in the share prices.
Also for any looking to invest in foreign markets not confident about making wise choices then Investment Trusts are a solution. There are Trusts covering all the major World Markets as well
I’m particularly keen on frontier market Vietnam where two of the 3 Trusts there are trading on big discounts despite impressive multi year performance. I.e VinaCapital Vietnam Opportunity Fund (LON:VOF) and Vietnam Enterprise Investments (LON:VEIL. VietNam Holding (LON:VNH) has an excellent performance record but the discount at 6% is smaller than usual.
For Commercial Property, Investment Trusts are way superior to open ended Funds and with no risk of being locked in. They’ve taken a big hit partly because higher inflation has reduced the attraction of their dividends. Result is some are paying 9% yield.
Here’s the aic link (aic is the trade body for Investment Trusts) for UK Commercial Property Trusts:-
https://www.theaic.co.uk/aic/f...
And for Global Trusts:-
https://www.theaic.co.uk/aic/f...
It’s east to find every sector there.
Oakley Capital Investments (LON:OCI) Re the EBITDA/EV multiple - any idea how we are getting 14% organic growth in EBITDA and a 3% increase in valuation multiple but only 4% NAV growth (plus 1% divi)? Are we losing nearly all of it on interest payments? I hold.
Update: costs are 2.8% of NAV (so losing some there too). No mention that I can see of realisation prices v book value - don't like that....
Re valuation, my back of a fag packet calculations give a PE of circa 25 - agree this looks pretty high.
Is Metro Bank too big for coverage in the Small Cap report? I thought their results yesterday were interesting.
Hi CamRaid,
I doubt we'll be looking at Metro Bank Holdings (LON:MTRO) results from yesterday, as it's a bit of a special situation, and I recall came perilously close to going bust towards the end of 2023. So it would need a lot of work to go through the detail, which we haven't really got scope for here, unless something looks to have stunning potential upside, when I can occasionally be coaxed to look!
Regards, Paul.
Capital (LON:CAPD) . Good set of results with profit a decent amount ahead of broker consensus forecasts. With gold price strong they have some good tailwinds behind them
Capital (LON:CAPD) ( I hold). They are investing heavily in MSALABS. The potential revenue and growth is the main reason I hold.
Yes agreed the MSALABS could be the real engine of future growth. But good to see they seem to be doing well on other fronts too - sign of good management. Of course, being CAPD, the SP falls on good news but fortunately the divi is reasonable to see us through the fallow years,,,,
Oxford Biodynamics (LON:OBD) raised gross proceeds of £9.9 million pursuant to a placing, conducted via an
accelerated bookbuild process, through direct subscriptions and a retail offer.
Exciting news from Beeks Financial Cloud (LON:BKS) this morning on the significant extension of JSE exchange cloud contract - further validation.
My morning smallcap tweet: Mind over chatter
Smartspace Software (LON:SMRT) Versarien (LON:VRS) Amati AIM VCT (LON:AMAT) Pressure Technologies (LON:PRES) Beeks Financial Cloud (LON:BKS) Abingdon Health (LON:ABDX), Eneraqua Technologies (LON:ETP), Moonpig (LON:MOON), Restore (LON:RST), RM (LON:RM.)
◄Smartspace Software (SMRT)► 90p rec offer, 3 months after approach announced. 20% premium. [SP=72.33 Cap=21m]
◄Versarien (VRS)► manufacturing licence agreement and a know-how licence and technical assistance agreement with Brazil's Montana Química. £50k up front. 5% royalty (£25k PA min) if Montana commences manufacturing. [SP=0.14 Cap=1m]
◄Amati AIM VCT (AMAT)► struggling fund to consider investing beyond AIM while continuing to comply with VCT rules. Cites challenges in the AIM market and the resultant performance issues. [SP=86.01 Cap=130m]
◄Pressure Technologies (PRES)► awarded two major contracts, as expected, in the defence and green energy sectors and maintains its outlook for FY24. One of the customers is Cheesecake Energy. Cheese cake?
[SP=34 Cap=13m]
◄Beeks Financial Cloud (BKS)► significant contract extension with the Johannesburg Stock Exchange. No £££. Supports FY25 exp. [SP=171.5 Cap=113m]
◄Abingdon Health (ABDX)► H1-Dec rev £2.4m. Guides H2 rev significantly higher than H1. Expects "breakeven and cash flow positive position which it forecasts will be achieved in 2024 without the need for additional funding". [SP=6.93 Cap=8m]
In line: ETP, MOON, RST, RM.
LOL That's brilliant Mr Contrarian, what a skit that was from Peter Kay.
Pressure Technologies (LON:PRES) (I Hold) With a potential sale of PMC in the next 3 months and further new contract awards it would appear Pressure Tech might finally be approaching an inflection point.
This is one of Harwood's (20% holding I believe) turnaround projects and I have heard the new CFO Richard Staveley had appointed is making a real difference to the business.
AGM next week, hope to see fellow Stockopedia investors there...
Pressure Technologies (LON:PRES) I hold Burnt Onions. Richard's appointment tipping the balance for me (shades of Crestchic)
Where’s the AGM ? London of Sunny Sheff ?
The Company's AGM will take place on Thursday 21 March 2024 at 09:30 am at the
offices of Singer Capital Markets, 1 Bartholomew Lane, London, EC2N 2AX.
I'll be at the Pressure Technologies (LON:PRES) AGM.
See you there Burnt Onions.
I hold
What typically separates the ‘wheat from the chaff’ in the equity world?
Well to me, it comes down to understanding why you invest? Simply to make money, or instead because you love doing it?
Sure having a large bank account is great for paying the bills, eating out and going on holiday. Yet equally, its not fulfilling on its own, & certainly doesn't make you a marvellous stock picker. If anything the opposite might be true, if one becomes a little complacent after a 'lucky run'.
Instead, the most successful investors tend to LOVE the PROCESS, far more than the actual outcome. Continuously learning about new ideas, secular growth trends & potential risks. Whilst equally remaining hungry for knowledge, whatever their financial circumstances.
If you’re doing something you enjoy & basically addicted to - as opposed to simply trying to make a ‘fast buck’ - then this becomes second nature. Augmented of course, by thinking independently and staying positive when things inevitably go wrong.
The good news is - this is all free. And assuming one remains sane, can be repeated for the rest of one's life.
Happy days indeed.
Terrific post Paul that tallies perfectly with my philosophy. Which is a good thing because I’m far from “making a fast buck”. And it’s keeping my brain well exercised and my knowledge at the cutting edge of an ever changing world.
Agreed. A truly great post Paul, which , like BnB is also my philosophy. I really love the process and , now retired, can happily spend many hours everyday analyzing stocks in a number of markets . It’s obviously great to make money whilst doing this but it does not bother me too much when I lose.
it’s made my retirement a hell of a lot more enjoyable and fulfilling
“wood from the chaff”!!!
Yes, nice post but its actually 'wheat from the chaff' with chaff being dry, scale-like plant material such as the protective seed casings of cereal grains, the scale-like parts of flowers, or finely chopped straw - we keep learning :-)
Thanks & great spot - now changed. I dictated the article into Google & missed the 'wood' typo on review.
Good grief Paul, it's not rocket surgery! (other mixed metaphors are available)
Pity, I thought it was amusing!! I love it when people muddle up sayings, and I often do it deliberately myself for fun, and to see if people notice/react :-)
EDIT: probably the funniest one I remember was when a friend's son was enthusiastically telling us about their holiday at the Luxor Hotel (Egyptian themed, including a huge reproduction of a Sphinx) in Vegas. And he excitedly disclosed that their balcony was "Right in the eye of the sphincter!" Of course everyone collapsed with laughter, with him innocently asking, "What? What?!" Looking back, I think he knew what he was doing.
I've always loved Arthur Daley's 'The world is your lobster'!
My wife came out with ‘wouldn’t touch it with a maypole’ once which I guess could be reserved for shares which are worse that ‘bargepole jobs’ assuming a maypole is significantly longer than a bargepole.
Beware Maypoles. They come with strings attached.
Arthur my all time fave another great quote when he was revising for a pub quiz "Dave need your help Kublla Khan, now did he bat or did he bowl ?" Cole and Waterman were brilliant together.
I have found that the biggest factors of success from those I've worked with are the ability to learn from mistakes quickly, as well as self-discipline and self-motivation. If you have all three then the learning curve is steep.
I find investing very interesting. I made a lot of errors along the way, which have helped me improve. But now i estimate i can make more than 10% on my SIPP compared to the 3% an annuity would offer me. Win win.
Good to hear sir what were your biggest learns if you don't mind me asking ?
I think it seriously helps concentrate the mind to focus on getting a good outcome if you actually need the money (eg: being able to retire and 'lend' one's offspring a deposit for a flat). I reckon it's also good to have something else that you really enjoy as well so on dull/disastrous market days you can take your mind off it - in my case it's gardening to get flowers and veg which I may be able to sell if it all goes pear shaped :)
Agreed.I love gardening too.Started with my own allotment finally 10 years back, but got much more into all sort of gardening since.Great hobby and relaxation as the day to day minutiae of markets, however fun at times, can get wearisome at times (and i can sure start overanalysing and wondering if you're doing it all wrong at times!).Need to keep up some regular income to afford all the new dahlias this year though!