Small Cap Value Report (Thu 15 Aug 2024) - RNK, ACSO

Good morning from Paul & Graham!
Reminder - 17:30 today Stockopedia's latest live webinar - these are always excellent & thought-provoking, so I'm looking forward to this. You should have received an email invite, I can't find a link unfortunately, sorry.
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia.
Companies Reporting
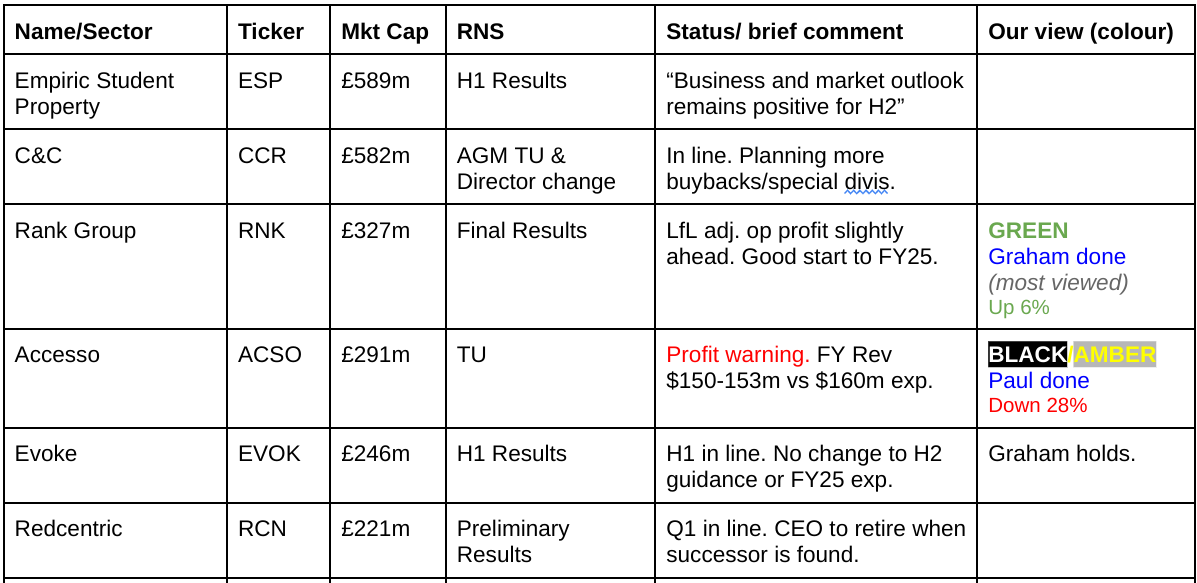
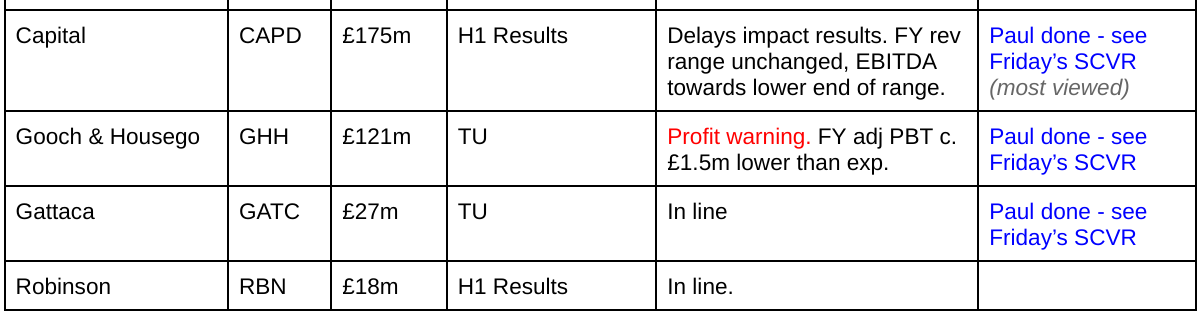
Summaries
Rank (LON:RNK) - up 6% to 74.1p (£347m) - Final Results - Graham - GREEN
Rank has declared its first dividend since pre-Covid in a strong signal of management’s confidence in the group’s continued recovery. I’ve been looking forward to seeing this casino/bingo hall operator (with increasingly profitable online operations) return to strength after the Covid/inflationary era. Hopefully it can stay on this positive trajectory for the foreseeable future. I continue to like it at this valuation.
accesso Technology (LON:ACSO) - down 27% to 514p (£213m) - Trading Update [profit warning] - Paul - BLACK (AMBER on fundamentals)
Warns on profit, due to customer project delays, and reduced demand. Still has net cash, but it's declining after lots of acquisitions. Has it gone ex-growth? Overall I'm unenthusiastically AMBER.
Paul’s Section:
accesso Technology (LON:ACSO)
Down 27% to 514p (£213m) - Trading Update [profit warning] - Paul - BLACK (AMBER on fundamentals)
accesso Technology Group plc (AIM: ACSO), the premier technology solutions provider for leisure, entertainment, and cultural markets, today provides the following trading update ahead of its interim results which it expects to release on 26 September 2024.
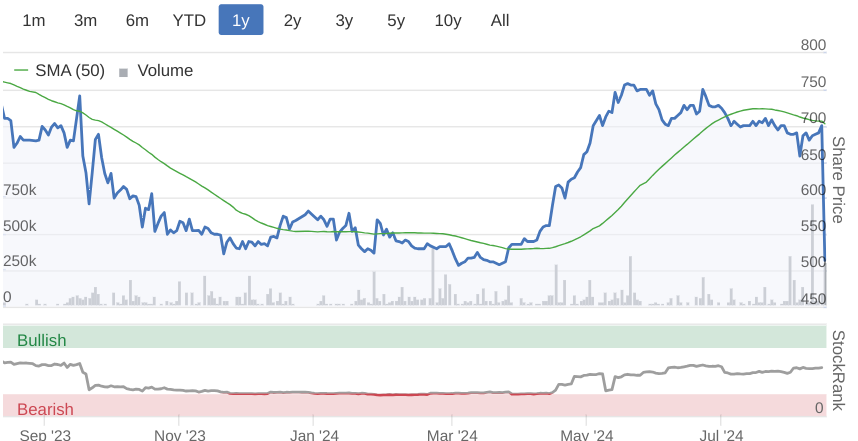
Bad luck to holders here, as ACSO shares plummet 27% to 514p, and give up all of this year’s bull run - it seems strange that the shares rose so much, when the company fundamentals were deteriorating - which just shows that following the chart isn’t necessarily a good thing -
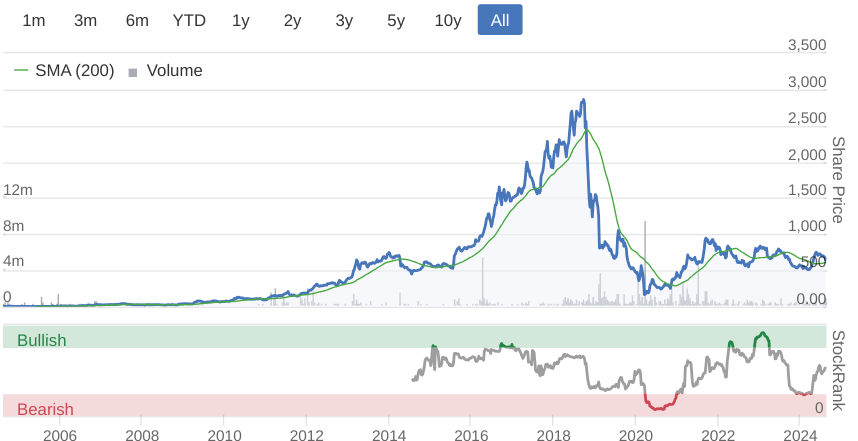
Longer-term, ACSO shares were an astonishing rollercoaster, back in the days when it was called Lo-Q - with this share amazingly 1000-bagging until it hit the rocks in 2018, going on to lose more than 90% of its peak value in two years. The last 4 years have been relatively stable, with a range from 500-1,000p, now at the bottom of that range today -
This is today’s profit warning -
“Based on recent trading volumes in the early part of the northern hemisphere summer months, and slippage in timelines for specific new park openings, the Group now expects a full year revenue outturn of approximately $150-$153m, rather than the not less than $160m communicated at the time of the Group's final results in April 2024.
The Group is taking measures to manage its cost base in line with this lower revenue expectation, so as to mitigate the impact on Cash EBITDA as far as possible. As a result, the Group expects to deliver a full year 2024 Cash EBITDA margin of 13-14%.”
It’s a calendar year, so FY 12/2024.
What’s gone wrong?
Project delays (new theme parks) mean client milestones have been missed, but only delayed into FY 12/2025, not cancelled - this isn’t too bad.
More serious is a decline in demand -
“Recent consumer trading volume across our key end markets has been below our expectations, notably during the peak trading month of July. Our revised full year revenue guidance assumes these lower volumes persist through the remaining peak months of the year.”
Outlook & cash position -
“Overall, the Group's sales pipeline continues to exhibit positive momentum which will benefit the Group in subsequent years. Furthermore, its focus on operational excellence is expected to ensure continued strong profitability and cash generation as the Group continues its development. The Group balance sheet remains robust, with a net cash position at 31 July 2024 of approximately $23.3m.”
Broker updates - nothing available. I often find that profit warnings are worse than they at first appear, so I have a policy of not buying after profit warnings without access to the latest broker notes, and to be sure that the full downside has been reflected in cautious revised numbers. As we all know, bad news can often be drip-fed into the market, creating a series of profit warnings.
At least shareholders here don’t have to worry about the balance sheet. I’ve checked the 2023 results, and the balance sheet looks solid. Although note they spent a lot of the previously much larger cash pile in 2023 on acquisitions. So it now has $165m of goodwill at the top, which is the bulk of the $194m NAV. They need to stop doing acquisitions now.
Note the progression downwards of net cash: $65m end 2022, $31.5m end 2023 (after $50m acquisitions), and $23.3m end July 2024. Starting to be concerning maybe? This contradicts the company’s comment above about it being cash generative, yet net cash has fallen this year to date.
ACSO has done a lot of acquisitions over the years, and it’s difficult to see how they’ve added value. Maybe more a case of acquisitions obscuring a decline in the core businesses?
Cash EBITDA by the company’s definition was 15.8% in 2023. So the guidance for 2024 at 13-14% is a step backwards.
Is this a useful measure? It excludes quite a lot of costs, but does take into account capitalised development spending, so it’s not complete nonsense, and finance costs are not large due to the net cash position -
(1) Cash EBITDA: operating profit before the deduction of amortisation, depreciation, acquisition and integration costs, and costs related to share-based payments less capitalised development costs (see reconciliation in Financial review).
Cashflow last year was quite good, but dominated by $50m cash outflows for 3 acquisitions.
It only capitalised $2.8m in development spending in 2023, which is reasonable (it used to capitalise anything that moved under old management, so the figures are much more credible now).
I see there’s a dreaded employee benefit trust, which hives off cash to buy free shares for management. This cost $3.7m in 2023, and $5.8m in 2022. Given that ACSO has never paid any dividends to shareholders in its 22 years as a listed company, it’s pretty obvious for whose benefit this company is run! Management. You often find that with US-based companies.
Cashflow statements are far more useful than the P&L to find out what’s really happening under the surface to the cash.
Paul’s opinion - previously I’ve been a bit sceptical on ACSO, but gave it the benefit of the doubt with AMBER on 29/1/2024, although I did raise some questions about growth, and the acquisitions.
Today’s profit warning is disappointing but not disastrous I think. I can forgive contracts slipping due to customer delays on new sites, that’s outside ACSO’s control. The lower demand is a concern though, can we corroborate that with information from theme parks more generally, I wonder?
Cash looks OK, but it has dropped significantly so far in 2024.
It talks about a good sales pipeline, which is helpful, but there are never any guarantees that pipeline turns into firm orders. My nagging doubt remains about whether ACSO is ex-growth, and has done acquisitions to prop up the growth numbers maybe?
Overall then it has to be an unenthusiastic AMBER this time. I think there are much better opportunities in the UK market with faster-growing, and still reasonably priced companies. Remember also ACSO put itself up for sale a while back, with no takers, which raises the awkward question that the business might not actually be very good.
Graham's Section
Rank (LON:RNK)
Up 6% to 74.1p (£347m) - Final Results - Graham - GREEN
This company has a year-end in June. We covered its Q3 update here, and today we have full-year results.
I’m pleased to see this casino/bingo hall operator returning to the black:
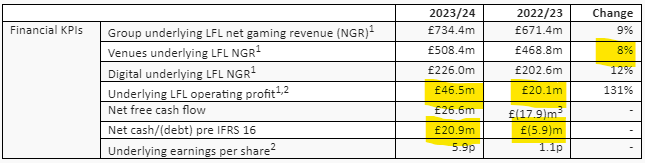
As you’ll see above, there is a more than doubling of underlying like-for-like operating profit.
Actual operating profit is materially lower at £29.4m - I’ll take a look at the discrepancy a little later.
The move from net debt to net cash is noteworthy too, and management are confident enough to recommend a final dividend of 0.85p, given “the continuing recovery in profitability combined with the Group’s balance sheet strength”.
Business review
In recent years, Rank has suffered from weak consumer demand during the cost-of-living crisis, combined with higher labour and energy costs. This combination of negative factors meant that profits collapsed. There was also the small matter of Covid-19 in 2020/2021:
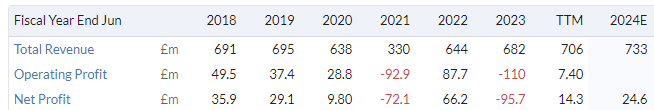
I’ve been hopeful of a recovery on the basis that inflation might come under control, costs might stabilise and the consumer might feel a little stronger. While not all of these things are happening at once, the recovery seems to be underway.
Here are some of the key bullet points from today’s business review:
Grosvenor (casinos): net gaming revenue +9%
Mecca (bingo halls): NGR +8%
Enracha (Spanish bingo halls): NGR +7%
Digital: NGR +12%
Grosvenor is the most important contributor to Rank’s net gaming revenue, responsible for 45% of the total (£330m out of £730m total).
As for profitability, Grosvenor and the Digital operations are the main contributors. They have each generated over £23m of underlying operating profits in FY 2024 (before central PLC costs are deducted)..
Grosvenor
The 9% growth in NGR is explained thus:
This is an acceleration on the 3% growth delivered in 2022/23 as the business continues to recover from the impact of lockdowns, the slow return of international customers, particularly to London's casinos, and the tightening of affordability restrictions in recent years.
Average weekly NGR, which was £7.5m in the eight months prior to lockdown in 2019/20, grew from £5.9m in 2022/23 to £6.3m, highlighting the further opportunity to grow revenues, even before the much needed and anticipated legislative reforms.
Digital
This division saw a remarkable 79% increase in underlying profits despite revenues only increasing by 11%. Rank acknowledges the “strong operating leverage within the digital business as revenues grow”.
Digital’s revenue growth in the UK is due to “the delivery of some key technology developments” which are laid out in more detail in the announcement.
Outlook:
We have made a good start to the new financial year. We exited 2023/24 with good momentum which has continued into 2024/25, with Group NGR up 10% for the first 6 weeks against a strong comparative.
CEO comment excerpts:
"This has been a year of strong financial, operational and strategic progress for Rank. We are continuing to rebuild profitability following the impact of lockdowns and the material inflationary pressures experienced in recent years. Trading continues to improve..
We have started the new financial year as we finished the previous one, with good momentum across all businesses. With inflation receding, disposable incomes improving, investment continuing to be made in the customer proposition and a strong pipeline of growth initiatives underway, we are confident in the future prospects of the Group.
Graham’s view
I’m very pleased to see that this one is playing out as hoped, although the share price remains near the bottom of its long-term range:
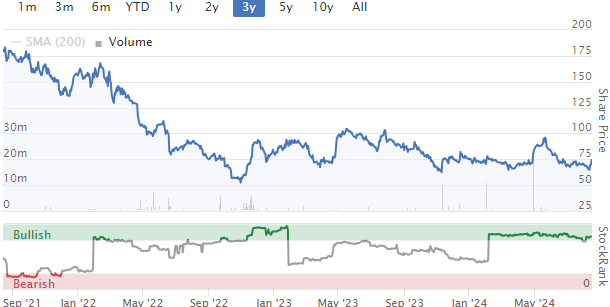
To my eyes, it looks like a potential opportunity: why is the market not giving Rank more credit already for the improvement in trading? With NGR up by another 10% at the beginning of the new financial year, I think investors can reasonably hope for another year of positive operational leverage leading to further acceleration in profits.
Valuation is as follows:
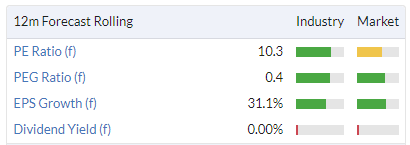
I promised to look into the adjustments that Rank made to its profit figures (to explain the difference between “underlying” profit of £46.5m, and actual operating profit of £29.4).
These adjustments are numerous, but the ones that really matter are impairment (a net charge of about £8m) and amortisation (£6.6m).
The impairments were driven by some Grosvenor/Mecca venues that failed to meet expectations. Some of these venues were shut down.
Amortisation relates to some websites and is a regular charge, not related to performance.
As always, it’s a matter of opinion how you wish to treat these charges. Personally, I would be inclined to look past the amortisation charge in this case, but I might not look past the impairment charge as it reflects poor trading at some of Rank’s sites.
Unadjusted after-tax net income, the strictest measure of profitability, comes in at just £12m. Of course the market cap of c. £350m implies that things are only going to get better from here, and I agree with that stance. I’m happy to maintain my positivity at the current valuation.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

76 comments
Zotefoams (LON:ZTF) - Posted on the Zotefoams LinkedIn page today. More positive momentum for Rezorce.
Link - https://zote.info/4dJ5mJ9
For those wondering why OSB was hit so hard by the market, here is Cityam's take on today's numbers. I can see it going even lower - perhaps. I will be waiting to pick bottom.
https://www.cityam.com/onesavi...
Yes - a lot of nonsense written on Osb (LON:OSB) unfortunately Lord Gnome.
Feel free to pick the bottom - they are spending £60m+ on buy backs and very high free cash generation so now that retail investors are out in a panic the lack of liquidity on the downside likely to switch back.
does anyone have a link to the webinar? I registered this afternoon but perhaps too late. If not will it be put on the site somewhere?
I try to watch all the webinars created, find something new and useful from them every time.
Edit. got the link thanks
link doesn't work any way
I normally get the invites but I've heard nothing about this one...
ACSO As I recall, that was a share that "everyone" was raving about many years back. There have been a number in the past, including ASC, companies with "famous" directors starting new enterprises, and much more stuff that I can't recall. They are often backed by positive commentary from extremely successful investors.
You end up thinking that something can't lose, only to find out that it most certainly can. ASC has been an abysmal investment of 5 and 10 years. ACSO has been mediocre at best. Please note that I am not having a dig at anyone. The gurus have certainly performed much better than me. I am just trying to give a gentle reminder that compelling stories do not necessarily make for good long-term investments no matter how savvy an investor is.
Stay safe out there.Magnificient 7
No not the likes of google / facebook / alphanet
Thanks for comments past day or so on deployment of fresh funds
Going to be deployed as follows
New shortlist down to -
Real Estate investors , Capital , Tribal
Increase (if weak)
Centaur, Titon,
Maybe
National world , Pennant
Capital looking very good at 85p level
#RNK Graham, with reference to your suggestion of a possible re-rating here, I personally am wary of investing in a company, whose major shareholder holds 60% of the shares and seems to have connections to South East Asia
Please elaborate.... What about a shareholder from South East Asia is worth being wary about?
Good luck with Tribal. Not a great track record and somewhat disaster prone
Sold a couple of years ago after finally losing confidence in management team
Hopefully most/all have been replaced but haven't followed since then
Picks and Shovels!
Continuing with my picks and shovels approach, I have added a few more VP (LON:VP.) In my view and like several companies that serve the construction and housing building industries, the shares continue to be underappreciated. Jeremy Pilkington (73), the founder retains just over 50% of the equity and will in my opinion, once construction and housebuilding gain traction look to sell the company. In the meantime VP (LON:VP.) continues to trade in line and the shares still look too cheap in my view. So failing any mishaps I shall continue to take the 6% dividend and wait for the house building etc to improve.
I don't own any housebuilders, but do hold several other picks and shovels type companies, all bought, with some good fortune towards the bottom of their trading range, e.g. Van Elle Holdings (LON:VANL) Michelmersh Brick Holdings (LON:MBH) Brickability (LON:BRCK) and Sigmaroc (LON:SRC) . Although all will benefit from an improved construction/housing market, they are, as most Stockopedia members will be aware some significant differences.
While Brickability (LON:BRCK) supplies (imports) bricks, the business is capex light and in my opinion the outlook for its enlarged cladding (provision and remediation) capacity following two acquisition is positive. Van Elle Holdings (LON:VANL) and Michelmersh Brick Holdings (LON:MBH) are cash positive. The former will be among the first on site insofar as house building is concerned and is building a presence in energy and water. I fail to understand why Michelmersh trades at a significant discount to the likes of Forterra and Ibstock, notwithstanding its smaller size.
Sigmaroc (LON:SRC) is the second largest producer of lime and aggregates in Europe and appears to be bedding down the recent substantial acquisitions from CRH. I remain a fan of its entrepreneurial management team that I have met on several occasions.
Just my thoughts. All views welcome, positive and negative.
All the best
MBH is at the top of shares portfolio Jonno, along with MacFarlane by number of shares held, third and fifth by value. We got in early on Cairn the Irish builder and are happy to hold, it's been well covered here by the SCVR. Sold out with a modest profit on Crest Nicholson before the now withdrawn bid offer, still monitoring that one. Also monitoring VP.
Kromek (LON:KMK) A few people taking a punt on this serial disappointer ahead of tomorrow's results - up 5% today. I hold....for now....
Interim results from Capital (LON:CAPD) today. Share price drops yet further, to 85 or so. This is a company which has knocked up annual earnings growth of over 25% over the past five years, and is valued on a PER of 5.6. That might make sense for a miner, but surely not for mining services? (I hold.)
We hold Capital too SundayTrader, looking to add when the price settles.
Capital (LON:CAPD) I hold for the growth story which I am still confident about although there is a cost. May add depending on how prices responds. The SP has lost the long term channel which is a red flag.
Bizarre reaction to Osb (LON:OSB) interims this morning imo. I don’t think investors actually understand this business - it is a cash machine and even if they made no more loans (let alone growth) would throw off tons of cash every year for a long time.
And yet it trades down 20% sitting on a PER of 4 paying a dividend yield closing in on 9% and with another £60m of buy backs to do whilst generating lots of cash
Unlike other banks it has a cost to income ratio in the 30%s, CET is strong at 16% and has no offshore, difficult to understand/value illiquid type assets sitting off balance sheet. Loan book is still growing.
I can only think that some investors are focussing on borrower behaviour switching quickly to fixed term but any change to that model (a) has no cash profitability impact - it’s just an earnings recognition and (b) is likely to revert in a year or two creating bumper earnings (but again non cash impact).
Anyway hey ho.
Osb (LON:OSB) there was a modest reduction in NIM guidance (of around 10bps) due to the subdued mortgage market, but can't see how this can possibly justify a 20% fall in the share price. I loaded up this morning as it's a very well run specialist lender with ROE approaching 20%, yet now trading well below book value. Also would expect the mortgage market to recover as rates come down, so wouldn't surprise me if they end up beating their NIM guidance.
Yes - modest reduction in NIM - very marginal and reasonably likely to be beaten I think.
As I say I don’t think people understand Osb (LON:OSB) business and the cash generative nature of it. I suspect the mere mention of the reversionary model (ie customer behaviour - spending less time on variable rates post end of fixed terms) has caused some retail investors to bail - probably because they don’t actually understand the difference between cash generation and spreading the profit over the life of the expected mortgage.
That behaviour is quite likely to switch the other way in the next year or so in my view as rates drop because borrowers will be waiting for rate reductions before coming off variable back to fixed.
Osb (LON:OSB) (I hold). I have been trying to justify the 20% for a couple of hours and I cannot find any good reason behind it, if somebody knows please help me out. I have added to my position today.
As I noted above the sell-off appears to be driven by a (modest) reduction in their NIM guidance amid increased competition in a subdued mortgage market. However, the sell-off appears very excessive in my view, and I would actually expect the mortgage market to recover as rates fall. The fact is, management don't really know what the NIM will be going forward, so I suspect they are just putting out a conservative best guess based on current market conditions. Remember, OSB operate in the specialist market serving professional BTL investors (effectively small businesses with a portfolio of properties), so they face less competition from the mainstream mortgage lenders.
Hi Bouden54,
Thank you for your input. I understand that NIM has gone down but a PER of 4, yield of 9% and 100% increase in pretax profit (H1 Y/Y) seems too good for me. Also, as Paul mentioned once, OSBs customers are BTL and not many of them go bust. I am still positive on this one.
All true, except the 100% increase in profit was due to the big EIR adjustment last year not being repeated.
Last year's hit was due to borrowers moving quicker than forecast from standard variable rates to fixes, was the result of the Truss effect on interest rates.
With interest rates still elevated, it is little wonder that lenders are
taking a more timely approach to locking in rates, rather than pay the
higher margin SVR.
Underlying net interest margin is expected to be in a range of 230 - 240bps for the full year as increased competition in the subdued mortgage market leads to maturing fixed term mortgages redeeming or switching onto lower prevailing spreads more quickly, and as we continue to monitor customer behaviour in reversion on the Precise book for any potential impact on the measurement of EIR.
The Group is undertaking a cautious re-entry into more cyclical, higher margin sub-segments, including commercial and asset finance, supported by improvement in the macroeconomic outlook. Whilst it will take time to impact the net interest margin this approach will provide a positive contribution to returns in the medium term.
I read this as - we are more interested in margins than market share as we return to higher risk lending.
I hold and have added today.
For anyone tracking Empiric Student Property (LON:ESP) , looks like management are of the deceptive type and like to cherry pick what they say
On the surface, their outlook for the 24/25 academic year looks good. 92% occupancy already sold, predicting 97%.Rent growth will keep them positive YoY, but occupancy is important. This drop YoY I think is because of the international applications dropping like a stone...
Even the 97% prediction, IMO, they are going to miss.
RE Empiric
This key paragraph looks somewhat concerning....
In July we saw a change in Government in the UK, with the Labour Party's
manifesto indicating a desire to make higher education more accessible
to UK students. There are no immediate intentions to revise the UK
tuition fee cap nor is there expected to be any significant change in
migration rules following the recent report by the Migration Advisory
Committee. There is a desire to support high performing research
institutions and a recognition that current university funding
structures are unsustainable and are, therefore, likely to be reviewed.
Further, no rent controls are anticipated and we expect to see positive
changes in the planning process, not just with respect to capacity, but
helpfully also in the speed of processing.
If Empiric is sensitive to a couple of percent softening of demand, then there is enough in this paragraph to warrant concern.
Slightly surprised that some of the negative issues are presented in such a neutral tone. I would like to know why they do not consider rent controls for students are anticipated. No real explanation here.
Most of the paragraph reads quite negative with issues outside Empirics control. Some of the issues would not be solved overnight if at all. One for me to avoid.
Do not hold.
We hold Watkins Jones Boon, it looks as though it's beginning to recover after a hard few years triggered by the Pandemic. It looks a better bet than Empiric Student Property imo. An FT article recently on student housing touched on the shortage and the inflated building costs per room now. Watkins Jones pre-sells new build blocks, institutions reneged on deals in the pandemic. I stand to be corrected by better investors on this.
Empiric has very different style of accommodation vs Unite (LON:UTG); often they are smaller blocks or even apartments above high streets (https://www.empiric.co.uk/our-...) vs a large block of relatively homogenous flats (https://www.unitegroup.com/our...). Empiric accommodation tends to be spec'd out more and accordingly is more expensive - as a result they have a higher mix of international and post grad (which tend to go hand-in-hand) vs Unite which does better with undergrads (especially first year). There's been a big drop off in international applications to the UK (https://www.theguardian.com/ed...) after the Tory rhetoric and that won't rebound and improve the nearer term numbers due to the lead times in this business. It's not surprising that Empiric operational results have dropped off relative to Unite's which have been more robust.
Windward (LON:WNWD) results next week. I hold.
I noticed one of Paul's recent podcasts mentioned Windward in passing and that he didn't have a view on valuing it given it's not yet profitable. Hopefully the below is of some use for this.
I think Windward is at an inflection point and it isn't going to take much for it to multi-bag over the next few years. Credit to Dowgate's Laurence Hulse for the idea and Vox's Paul Hill for interviewing him.
First a bit of context: Windward provides software and analytics for the maritime industry, covering sanctions compliance, supply chain, security. They were founded in Israel in 2010, listed in London in 2021.
Main attractions
Main risks
Now to valuation: this will be far from precise. They said they are on track to hit cash breakeven on a run-rate basis this year. As a largely fixed cost base software business, any further growth beyond this will be dropping straight to the bottom line. If for argument's sake we assume 2 years of 25% sales growth (they've been over-achieving vs this, particularly recent years, eg 37% in the interim trading update), constant R&D and a bit of increase in S&M, G&A. they'll already be on roughly 8x EV / operating profits just by 2026. If you want to extrapolate that a bit further, the shares look exorbitantly cheap by 2028. And it is a finger in the air extrapolation, but not a bad one for a proven software solution that has clear traction and is extending its reach at a fast pace with new and existing clients. At that point putting a very unassuming 5x sales multiple (equivalent to just 15x operating profit) gets you to almost 5-bagging from today.
Figures below are all in USD
Reality won't really play out like this. In his recent interview with Edison, CEO Ami Daniel implies as soon as breakeven is reached, surplus cash is going to be reinvested to grow the business faster.https://www.edisongroup.com/edison-tv/deep-dive-into-artificial-intelligence-windward/33842/
If that's the case, sales and marketing, even R&D, won't stay as static as I've suggested and you might not see the operating margins jump as early as I've modelled. But Ami describes this as a scenario where he's aiming for 50-60% type growth, rather than the more cost-controlled growth that has been achieved thus far, and the shares will still start looking very cheap on earnings by 2026 (though the shares will run well ahead of this I'd hope).
Overall I think you're getting a very high quality, fast-growing business that is at a sweet spot in client traction, in operating gearing, and with no more funding risk with macro tailwinds seemingly a perfect storm. And we're at a point where without strong assumptions they'll start looking cheap on clean cash earnings in little time.
Hope this is of use. Appreciate any and all counterpoints.
ITM Power (LON:ITM)
If you believe in reducing CO2 emissions is a necessity but battery powered transport isn't the answer, an interesting but still loss making green hydrogen producer reports a year's progress from a new start for the company after a radical change in management and massive re-capitalising with investment from Linde (European industrial gas company and owner of British Oxygen), Lord Bamford of JCB, Peter Hargreaves of HL.
Preliminary year end results beat guidance figures :
Financial results summary
· Revenue £16.5m (FY23: £5.2m) in line with the £10m to £18m guidance, a more than threefold increase year-on-year
· Adjusted EBITDA* loss £30.4m (FY23: £94.2m) well ahead of the £45m to £50m guidance, reduced to less than one third of the previous year
· Net cash at the year-end of £230m (FY23: £283m) ahead of guidance of £200m to £220m, allowing us to conclude the year with a strong balance sheet"
Part of a very detailed commentary from the CEO, CFO and Chairman, a long read.
I found their presentation of much interest this morning. Clearly they are not a company this particular website will follow carefully as they don't make a profit but they have plenty of cash and an interesting product for which Govts are starting to fund. They have a leading product and some very clear paths to market. Management have now tidied up what was a sh88sh98!! Cash is now central to their focus. I think he said sales opportunities have risen by 25 times which is something he never seen before. So yes jam tomorrow but I opened a small position simply because I can see momentum returning to this sector and if it is successful a £112m enterprise value will look very cheap.
I see train drivers are being offered to 15% pay rise without any increased productivity. The doctors are going to do pretty well as well along with other civil servants. After a lot of pain inflation is around 2%. This is the start of a new stagflation?
Id give the doctors a 50% oay rise and tell them to have a “nornal” pemsion like the rest of the mortals and sign an exclusivity agreement only to work for the NHS .
The country cannot afford those pensions .
"Id give the doctors a 50% oay rise and tell them to have a “nornal” pemsion like the rest of the mortals and sign an exclusivity agreement only to work for the NHS .
The country cannot afford those pensions ."
The current GP pension scheme is estimated to be fully funded by contributions on an ongoing basis (historically may not have been the case, but employee contributions have significantly increased).
Not sure about the rest of the doctors, but would expect the situation to be largely the same.
Having said that, I'd abolish all final salary schemes to new contributions, there's too much uncertainty in the world to be making promises that far in the future IMO, and the risk-aversion of trustees leads to non-optimal investment decisions. Defined contribution, and you get what you get should be the way to go for everyone IMO.
Disclaimer: I hold (my wife is a GP!)
All government jobs in excess of £100K should be given be just the basic state pension and personally self fund thereafter they can afford and its tax relievable.. Given the exponential rise in highly paid civil service positions the pension cost is unsustainable for taxpayers
They think they have bought peace but as with the London Tube strikes, it just becomes an annual event.
They have to earn as much as they can before trains, like other vehicles, become self-driving.
Not a small cap, but Admiral (LON:ADM) demonstrating today what a class act it is.
A 45% return on equity. Earnings up 35%, Dividend up 39%.
Yes. The insurance industry generally seems to be doing quite well. Ripping the ar*e out of us poor consumers. To get my own back and spread some concentration risk I bought the Polar Capital Global Insurance fund which has done well over the last few years. Apologies to the die-hards to mention a fund but what works works.
I’m not surprised insurers are doing well they are exploiting us all with crazy increases and in my view the competitive nature of the industry seems to be weakening ie they are all doing the same. At least three of my policy renewals were x2 on last year with no change in what i was insuring or any claims. Good strategy to invest in these to offset the extra fees but I think they are exploiting customer base.
Almost fell out my chair reading the loss ratio improvements in Motor and Home for Admiral (LON:ADM) . Stunning moves in a positive direction.
And then coupled with being able to increase prices too, and no wonder they're printing money...
Coupled with Aviva (LON:AV.) good numbers too, I'm looking to load up on more general insurers, as it looks like it'll be a sector wide tailwind.
I already own Direct Line Insurance (LON:DLG) as one of my largest positions. Albeit their results won't be as good, as I suspect they have lost customers to Aviva and Admiral... but the improved cost/loss situation and rising prices will still mean dramatic increase in profitability.
Sabre Insurance (LON:SBRE) looks interesting too recent results good one for Graham to look at at full year?
Living wage / minimum wage and employers now thinking twice ?
Whilst its all well and good to increase min wage have to say as an employer (very small currently thankfully) ) as im woefully ill equipped to deal with a moderm generation .
Anyway we have an alprentice type situation with a friends son taking a gap year from a business degree to learn about business with a proven entrepeneur .
As hes just turned 21 hes jumped to the main band .
Anyway after a very unproductive morning where he ricked up hung over, half asleep and totally off pace I had a discussion with him about what a 12 pound an hour employee needed to “earn for the company”
12 quid an hour , add NI say 15 quid
Most companies are lucky to make 10% margin at end if year
So he needs to be “worth” 150 quid an hout of turnover .
He was a bit surprised
Given we have 3 staff and turnover around 1k a day either - increase sales or cut staff is the metric .
Yet not so many of this generation are bothered about sales and look at you with like you are an alien when you say you buy annd sell stuff for a business .
Not exactky sure why im sharing this other than I think unemployment will rise pretty significantly in the next years as from an employers perspectuve the numbers dont really add up .
Haha @planetx enjoyed that "look at you with like you are an alien...."
I'm still struggling to manage and motivate Gen Z. What scares me is that I end up celebrating anyone I find with commercial or problem solving nous!
Just to say at the other end of the spectrum, I knew of a friend who complained about the trap of employing older sales guys, who were still boosting their cv's from one year they did of good sales, but were floating around the market expecting good salaries for usually poor results. Two years later after lackluster results they were floating around again.
It was all a bit Arthur Miller'ish.
The fecklessness of youth. Even Shakespeare wrote about a schoolboy: 'Then the whining boy with his shining morning face, creeping like snail unwilling to school'
Interesting real world economic reality planetx. It seems wrong to me that an individual cannot afford to raise a (small) family, own a decent property and have a reasonable standard of living without taxpayer subsidy on the average national income. It feels to me that this is largely the legacy of the Have Yachts looking after themselves too well in the GFC and claiming they were saving the world. The amount of money pumped in to economies then, globally, has ended up with the asset price inflation which make it difficult for under 30s to be properly independent. And saddling them with student debt too starts them out with a very different perspective on life and the prospects of succeeding. If you can't see much chance of getting out from under how hard do you try?
Consequently I think the National Living Wage will have to go much higher. And we need to find a way to make sure residential property stops increasing in value until it is truly affordable for those on average income. Councils will surely have to build houses again and with no right to buy.
And I'm of the optimistic perspective! I expect to see another rate cut in the UK this year and 0.5% or more off US rates too. August markets seem to blow with the wind. Not to be taken too seriously or worried about too much though they may provide some openings for those with cash when odd drops happen. I haven't got any cash so it's time for a bike ride. GLA
Its all broken
Property prices should be 30-50% lower but if they were everyone would be up in arms so the current property owners (parents) have the paradox of liking the increase in value of their property whilst bemoaning their children cant afford
Universities from what i have seen in some visits with my teenage son this year are a total joke and nothing more than snowflake appeasing colossal money grabs .
I went to manchester university for open day to see if my (pain in the ass) son wanted to go.
Now i studied mech eng there where we had 4.5 days solid lectures 9-5 and wednesday afyernoon off for sport . It was pretty hard .
I was also last year to get a grant with no fees.
Anyway on entering the “simon” building where i did my 3 years of study (aka torture) there was now in reception a barrista privately owned coffee shop , presumably paying commercial rent to uni, charging 4 quid for a cappuccino !
It gets worse
I walk 20 metres ground floor to my old engineering lab to find a “students massage and wellness centre”
It gets worse
I head across to the students union to find a big sign inviting me to sign up for weekly “goat yoga classe”
Now admittedly all i did in my lectures for 3 years was sit next to adam duckworyh at the back of the class, i would read cycling weekly and all rhe cycling mags, he woukd read MCN (motorcycle nees) and when wed finished we woukd swap magazines .
Somehow i passed , and so did he .
He becane editor of MCN and I started a bike company .
Here is my thesis,
Many university degrees are now worthless junk run by establishments that have lost sight of what they are there for .
If you are 17 years old and I only had 80,000 pounds would you soend it all on a univrtsity education of little benefit .
If 50% of these invested 80,000 into starting a business then we would have the fastest growing economy in the world for sure .
Entreieneirship and marco polo style trading is dead and buried and we are a snowflake generation of mental health issues demamding an education and goat yoga classes.
Anyway another totally pointless post / rant
Like your thinking to a point Planetx….We lived through the 16% morgage fun times with 3 daughters under 3 (twins were to blame for that)…My husband was a professional with a reasonable wage but I dragged the kids around while I tried to sell Tupperware to helps out (it bought kids beds and a carpet)..then went back part time to the NHS where I stayed until 64 yrs old ….I reckon there should be fewer university nefarious courses and far more ‘apprentice type jobs’ that involve paid work and ‘technical college’ type studying…I did ONC and HNC and at the end of it had a job plus a worldwide recognised qualification…plus loads of work experience ….
Councils should be totally BANNED from building new houses on green sites until they have solved the problems of dead City/Towns by using empty shops and the masses of empty potential living space over town centre shops as new living accommodation ..This should revitalise town and city centres to a beating heart ….It may even stop the crazy need for second you could live in the city work time wise and retreat to your single home at weekends ..then areas like some where I live wouldn’t have properties that are empty for 80% of the year while youngsters can’t find anywhere to live….
Plus I would let all politicians pay their mortgages monthly but then only let them have the state pension as income for 2 years and let them see how the hell they would manage to live on it….That would be interesting…
Finally (just for Paul) SEE is going up very nicely Thanks for covering it the other day
Not sure I completely agree Planetx
Both of mine recently finished degrees at a Russell group - red brick.
Daughter decided not to go into Psychology but being creative has started her own fashion brand business. That’s going pretty well now - she designs, makes and sells. I’m fairly certain that what she learnt in her degree and the resilience built in living on her own, being part of social committee and organising events etc etc has not only helped in creating the business but i’m fairly certain she would not have taken that entrepreneurial step if she hadn’t been to Uni and built some of those skills and confidence.
On the flip side having those business skills on top of a good degree should be pretty valuable to employers if she ever decides running in the world of fashion is not her bag.
So, yes a lot of degrees at certain unis are worth very little. Yes, resilience is a general problem in the young and saddling youngsters with such a large compounding debt at a young age doesn’t feel right…….but is entrepreneurship dead through demand for a Uni education…….I dont think so.
David
Id counter that by saying your daughrer has lost 3 years and is now effectiveky 80k behind the curve .
Great to see her start a fashion brand business and the “space” of university possibly helped her make that step .
Its actually exactky what I did - 3 years engineering then straight into starting my business
Could i have gone straight into business absolutely not as i discovered my passion for triathlon there .
Sometimes its simply about luck and timing and spotting the openings .
A good entreoeneur will find them when they appear, might be at 17 out of 6th form, 22 out of uni .
But this blindness and pressure to “get an education” and one that costs a small fortune is a myth started by tony blair and perpetuated by universities .
And incidentally when taylor swift cancrls a concert you get a refund
When lecturers go on strike you dont get a recund .
Im helping a couple of young fashion businesses in sheffield , theres a nice upswing going on especislly in recycled and repurposed .
Tell your daughter to check out “Atelier” hes a good guy doing some unusual stuff .
I enjoyed your rant on universities, planetx. For balance, however, I’d offer that I went to Oxford in the Brideshead Revisited 80s and did nothing but drink and chase women. In those days it was hard to get laid - but then perhaps that’s just me . And I eventually left with a scraped degree, a hangover, an overdraft, no clue of what I wanted to do, but also (some years later) a wife. A generation later, our daughter made it to Cambridge for a wishy-washy Eng Lit degree and was worked to the bone as well as securing a prized Blue and shedding her teenage mental health problems. Meanwhile, our son slaved for 4 years as a researcher (plus 4 as undergrad) in Durhams’s Chemistry department in order to earn the right to submit a 300 page PhD thesis, working on a failed project to burgeon the reputation of the Head of Department. It was unbelievably tough for him and the failure of the experiment threatens the award of his doctorate still. But he was very active in his favourite sport and built a network of friendly nerds around the world representing the university in debating.
For both, university was far tougher and yet more rewarding than my undergrad years and I am in no doubt that the demands on students at this, admittedly, rarified level have significantly increased, along with the opportunities for self-realisation.
“Drink and chase women “
Love that
Im guessing no studebt loan etc
Could have gone on a 3 year round the world trip budiness class and 5 star hotels for the price of a university education .
Probably youd have drunk more and chased more women and mer as many friends .
Consequently I think the National Living Wage will have to go much higher
Really sevenccc ?
Do you work in the public sector by any chance?
I recommend reading about the fall of the Roman empire, where the populus, having enjoyed a good standard of living from employing immigrant workers (slaves) and the fruits of the empire, voted for government that would give them more public holidays and more entertainment at the Colisseum until the empire objected to the levels of taxation necessary to sustain their entitled lifestyle.
In my experience Business "Group" or Central Costs, often called Sales, General & Admin (SG&A) tend to get allocated to Product Lines (PL's) based on their Revenue as a % of Total
PL Directors hate being charged SG&A
Not being political but its the same principle as Roman Senators, Elected Government, Local Government - PL Directors have no control on what they are charged, or whether it is cost effective.
Even worse if a PL is divested the SG&A allocation now becomes more onerous on the PL's remaining if the Senators don't reduce their running costs. Take note you Roman Senators
Samsgrandad
I'd say that's exactly my point. The 1% (Roman populous) need to share the wealth with the rest (peoples of the Empire) or expect it all to end in tears. Employees need to be treated fairly and equitably. Not like the Oighurs or as modern day slaves. Ok exaggerating to make the point.
The recent riots were all for the wrong reasons imo but reflect the combustible nature of many groups bubbling just below the surface of our society. I'd suggest we need to take heed.
And fyi I had only a very brief stint in the public sector. It wasn't for me for what it's worth but I won't knock those that provide the services we need to make our society work. I believe we need to provide them with affordable housing for starters. Hopefully before things get too divisive.
Well I'm not one of the 1%. I'm living on a state pension and a company pension for which increases are at the companies discretion. So an increase to minimum and living wages paid out of my taxation would hurt me. I'm all for increasing the taxation of companies, based in foreign countries with lower tax regimes, that forward all their earnings after deductions for IP or whatever accounting tricks. Philip Green ensured that Arcadia's profits matched what he charged for management consultancy to Arcadia owned by his wife (who lives in Monaco). Ireland is doing well out of this system.
To continue the theme of the hoi polloi setting their own rules - Unusual US Politicians trades site (share transactions to be immediately reported to stop criticism, now used to "track" their purchases). They seem to be very good at investing! - https://unusualwhales.com/poli...
Sounds about right ! ..... Interestingly recently watched a YouTube video where the American economist Thomas Sowell talks about minimum wage laws in the US and why , in his opinion, they don't work.
Recruitment mistake ? Your choice to take him/her on in the first place ?
My morning smallcap tweet: Unexpected item in bragging area
Quantum Blockchain Technologies (LON:QBT) accesso Technology (LON:ACSO) Gooch & Housego (LON:GHH) Kingswood Holdings (LON:KWG) Gelion (LON:GELN) Rank (LON:RNK), Gattaca (LON:GATC), Aoti (LON:AOTI), Evoke (LON:EVOK)
◄Quantum Blockchain Technologies (QBT)► abandons attempt to port its Methods A, B & C to existing commercial ASIC-based mining hardware and software system, via CGMiner. Blames speed and power consumption inefficiencies created by the designers. Now targets the more recent AxeOS (ESP-miner). [SP=0.8 Cap=10m]
◄accesso Technology (ACSO)► warns FY-Sep rev c.$150-153m (previously $160m+) due to weak trading and delays in new park openings. Cost cuts - targets FY cash EBITDA margin of 13-14%. [SP=700 Cap=292m]
◄Gooch & Housego (GHH)► warns FY adj pretax may be c.£1.5m lower than expected due to supplier and customer delivery delays. FY25 exp unchanged. [SP=470 Cap=121m]
◄Kingswood (KWG)► additional £6m debt facility at 12% PA deferred "to provide the Company with the capital required in the short term to satisfy upcoming deferred payment obligations". [SP=12.46 Cap=85m]
◄Gelion (GELN)► has developed 1Ah semi-solid-state Lithium-Sulfur pouch cells using its GEN 3 tech. [SP=23 Cap=31m]
◄Rank (RNK)► FY-June LFL underlying operating profit £46.5m, slightly ahead of analysts' consensus. Resumes div with final of 0.85p. FY25 started well. [SP=70.11 Cap=328m]
In line: GATC, AOTI, EVOK
Positive GDP numbers this morning. 0.6% (or 0.3% GDP per head).
Jupiter Fund Management (LON:JUP) Apologies for this tedious genre of question but JUP steadily rose 6.5% yesterday and I couldn't see any reason for it apart from low level US interest in undervalued UK stocks. Was there simply a tip somewhere?
yes UBS upgraded Jupiter Fund Management (LON:JUP) this from The Times:
Investors were delighted with UBS for doing away with its "sell" rating on Jupiter Fund Management. The asset manager has done a good job of right-sizing its cost base over the past couple of years, analysts argued, and as a result they view "the downside risk" to earnings to have subsided significantly.
Clearly this was just what the market wanted to hear as Jupiter's shares jumped 5p, or 6.5 per cent, to 83¼p.
Jupiter Fund Management (LON:JUP) Aha thanks!! Broker note got it....
Nice, tuck-in acquisition from Judges Scientific (LON:JDG) this morning, adding just under 2m to its 34m of EBIT, paying only 6 x EBIT, hence accretive. Shares are up nearly 10% from the recent PW, which I said was a dip worth buying, while Graham disagreed - chiefly on valuation - and he might prove right in the long run. Nevertheless that rebound comes despite recent market volatility. Today's news might give further comfort that there are still M&A prospects that can move the profit needle by a few ppts.
edit: broker note says add 1% to FY1 and 4% to FY2
US CPI data came out yesterday... and it's apparently a damp squib ... move on says J Authers, clears the way for rate cuts says R Armstrong.
It came in at 0.2% which is the magic on target (ish) number. So what's to worry about? Its below 3% and US is slowing they say... apologies, But there is a BUT.... I am a little confused exactly what we want, some sort of mild slow down I think. Anyway for now we can relax because the August number last year was a little punchy at 0.4% and even September was 0.26% so yes, for now we have room to cut. However, in "A" level Marco economics corner, the keen will have spotted that Oct Nov and Dec were all negative last year...and so, it isn't too far off that "IF" we hover around the magic 0.2% number the overall impact will be rising inflation not falling come the end of the year. This is a little tricky and errr dare I say we probably need the monthly CPI numbers to be somewhat weak come Q4. May June and July played ball, below 0.2%, so maybe we get the result we want. I obviously have no idea ..... but none of this sounds very "out of the woods" to me. Inflation and CPI set to remain pesky afraid. For now we can enjoy the rally and positive short term outlook but this aint done.
“so maybe we get the result we want”
What is the result we want ?
CPI Nos weak enough to be viewed stable in terms of overall inflation paving the way for some cuts but not so weak as to indicate a more rapid slow down. and conversely the result we don't want..... sticky high CPI ( >2.5%) with falling employment into hard landing. This is purely a mkt view of course....
Mmmm
Not entirely convinced by the focus on this level of analysis and how it would actually affect a budiness owner / shateholder .
Sharon coming in late after a row with her boyfriend and the bike mechanics running out of black bar tape .
I genuinely think 80% of comoanies dont ever care or are affected by all this , and certainly the improvements they make by “controlling the controllables” to quite brailsford outweighs .
Bit blase to say and proper northern pig farmer mentality but “i wouldnt worry about it”
Let's get you back on how to spend your wonga planetx. Have you looked at the Benjamin Graham Bargain Screen on here. Sadly we have three all at various depths underwater sinking with our wonga but you might find a good recovery play in there. Ok here's the three I wish we'd never bought - Novacyt - Synairgen - XLMedia. We have more but not on the screen.
Yeah but I wasn’t addressing moanies - business owners - entrepreneurs etc I was thinking only about mkt rats, share traders, investors and speculators … i apologise, I thought we were just trying to guess what’s gonna happen next in markets.
I disagree that inflation remains the big issue today. It’s definitely the jobs numbers that matter now. There's still scope for a harder landing than hoped even if that is not the base case for most observers today. The market showed its sensitivity less than two weeks ago!
I think productivity is the big challenge for many businesses and with Labour empowering their union friends, will drive more mechanisation and AI reducing employment