Small Cap Value Report (Thu 15 Dec 2022) - ZTF, CAR, SAG, HTG, CURY, DX., STVG

Good morning from Paul & Graham!
Agenda
Paul's Section:
Zotefoams (LON:ZTF) - a positive, ahead of expectations, update for FY 12/2022. I explain why this is one of my favourite GARP shares (no holding personally, unfortunately). More detail below. Thumbs up from me.
Carclo (LON:CAR) [quick comment] - down 20% to 12p this morning (at 08:12), so market cap now tiny at £9m. It says H2 (of FY 3/2023 I assume, the RNS looks like a typo, saying FY 3/2022) will be “materially lower” than previously expected. Bank remains supportive, and in discussions about amending bank covenants. I went through the FY 3/2022 accounts here in some detail, explaining why the expensive debt, and pension scheme cash outflows use up all the profit. There does seem to be significant freehold property though, which could be why the company hasn’t already gone under. Very high risk of a dilutive equity fundraise (which could be on ruinous terms, as we saw yesterday with Trackwise), hence I would say this share looks too risky for now. (no section below)
Currys (LON:CURY) - Interim results from this £10bn pa revenues electrical retailer, making a surprising appearance within our small caps universe. The seasonally slower H1 has been soft, and full year guidance is trimmed, but still guiding a decent FY profit. The balance sheet concerns me - it's weak, and completely reliant on massive trade credit for buying the stock - if trade credit insurers get cold feet, that could kill the business. Divis look unsustainable. Thumbs down from me, as it's too risky if we see an extended consumer downturn.
DX (Group) (LON:DX.) [quick comment] - nothing particularly noteworthy in this AGM update. Trading continues to be in line with expectations for FY 6/2023 so far. Pipeline of new business opportunities is “very healthy”. Liquidity good, with “significant net cash”. The valuation metrics on the StockReport here look good - fwd PER of 7.6, and divi yield of 5.2%. There’s been a big improvement in profitability here, so it looks a successful turnaround. My view - might be worth a fresh look, after a troubled past.
STV (LON:STVG) [quick comment] - this is called a trading update, but it seems more like a PR release, talking up the good bits, but without giving figures for overall performance or outlook. Other than saying that it “performed strongly in 2022”. Thanks to Shore Capital for a note today which reduces FY 12/2022 EPS by 5% to 39.9p, and a thumping reduction of 18% in forecasts for 2023 & 2024. So this is a 2023 profit warning that’s been slipped out via the broker, and not explained at all in the RNS. That’s really bad. Remember that STVG has a huge pension scheme issue, so that’s why the shares are on a low PER. Although the accounting deficit did reduce a lot in the recent interims. Deficit recovery payments were £7.1m just in H1. So make sure you fully understand the pension schemes before investing here.
Graham's Section:
Science (LON:SAG) (£183m) - FY December 2022 is trending slightly ahead of expectations thanks to dollar strength that was subsequently locked in by the clever use of financial derivatives. The company is successfully navigating both cost inflation and a slowdown in demand from the consumer-oriented sectors it serves. If it acquires the consulting and engineering business TPG, as planned, then it will enjoy further diversification with exposure to the aerospace and defence indutries. Based on its financial track record, Science looks like a better-than-average company in its sector, so I can get behind the market’s valuation at a PER in the mid-teens.
Hunting (LON:HTG) (£444m) - the order book at Hunting has grown to nearly $500m, most of it to be delivered next year, and the company accordingly increases its guidance for FY 2023 EBITDA to $85-90m (previously: $80m). I don’t believe that EBITDA is a useful measure of profits at this company but I still prefer to see upgrades rather than downgrades! The business appears to be doing very well. I note the very volatile historic results - this company has a tendency to perform very well or very badly. Hopefully the oil and gas industries can continue to boom, and Hunting’s shareholders can experience the former instead of the latter!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul's Section:
Zotefoams (LON:ZTF)
298p (pre market open)
Market cap £145m
15 December 2022 - Zotefoams, a world leader in cellular materials technology, today provides an update in respect of its financial year ending 31 December 2022.
Continued positive momentum through Q4 and full year profit ahead of market expectations
Positive trading - this looks good -
As communicated in the Group's trading update of 13 October, performance over the nine months to 30 September 2022 had been strong, with revenues approximately 24% ahead of the comparable prior year period.
Encouragingly, trading during October and November has remained strong, with both the Polyolefin Foams and High-Performance Products businesses continuing to deliver year-on-year growth as well as a continued focus on cost and efficiency.
As a result, based on current FX rates, the Board now expects Group FY22 adjusted profit before income tax to be ahead of current market expectations*, with the extent of the outperformance primarily dependent on the timing of customer shipments in the final weeks of the year.
* Current Company-compiled consensus expectations for adjusted profit before income tax and separately disclosed items, for the year ending 31 December 2022, is £10.7m.
Outlook - this sounds fine to me, given that ZTF has successfully mitigated challenges (such as raw materials cost inflation, and energy costs) in 2022 -
"Whilst we expect a number of the challenges experienced this year to continue into 2023, we are confident in our ability to respond and we continue to see significant opportunity for the Group."
Broker updates - nothing unfortunately. I’ve nagged the company’s adviser on this, saying that they need to get some broker research out there to PIs, via Research Tree or commissioned research, otherwise we’re in the dark without any guidance.
This is what Stockopedia has for broker consensus, from 3 brokers that feeds into this data -
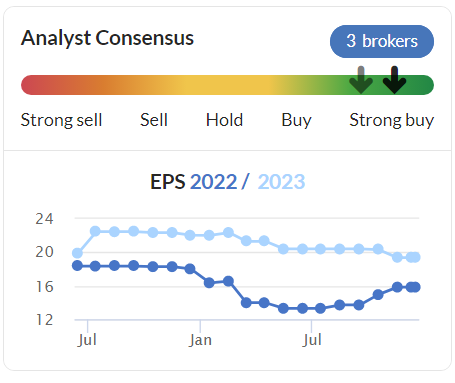
This is where we have to use some educated guesswork. We have 15.8p broker consensus now, so “ahead of expectations” probably means anything between 17-20p EPS for FY 12/2022. The fairly upbeat outlook comments also make me comfortable with the existing forecast of 19.3p for FY 12/2023.
At 298p per share, that means a PER probably between 14.9 and 17.5, which looks reasonable - neither cheap, nor expensive really.
Dividend yield (forecast) is modest, but worth having, at 2.5%.
Balance sheet - is strong, with freehold factories in at cost. There’s a fair bit of debt, but it’s expected to fall rapidly, due to a large capex programme now being complete, with well invested factories, so the company is now in cash generation, de-gearing mode. This point is confirmed today here -
Cash generation also continues to be positive. The better than anticipated earnings performance should contribute to an appreciable reduction in leverage compared with that reported in the interims at 30 June 2022.
My opinion - this is one of my favourite GARP (growth at reasonable price) shares. So I interviewed the CEO in late Oct 2022 - audio here, written summary here.
It’s been particularly impressive how the company has been able to raise selling prices considerably this year, demonstrating that its products are in demand, and have pricing power. It’s a specialised niche, with little competition, that’s why.
There’s also the blue sky project Re-Zorce, which is thrown in for free. If this takes off (and early signs sound encouraging) then it could trigger a re-rating, and higher profits - this is innovative fully recyclable food/drink containers, a huge potential market.
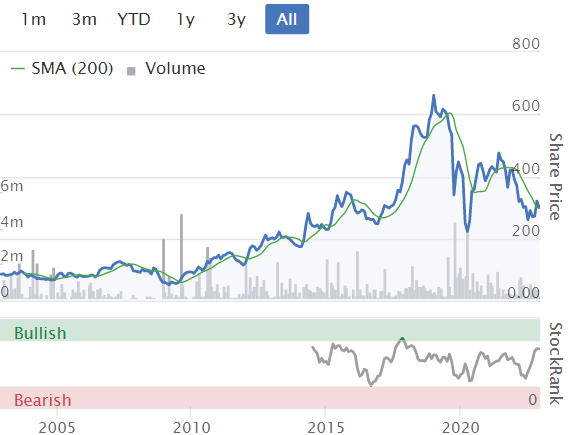
I think the shares are a long-term buying opportunity right now, at less than half the peak share price in 2019. It’s proven very resilient this year, and today’s positive update confirms that, so I think the downside risk on this share looks pretty low, with good longer term upside. So a thumbs up from me.
Currys (LON:CURY)
60.4p (down 8% at 09:15)
Market cap £681m
It’s not often I review companies with £10bn revenues in these small cap reports! Currys has popped its head around the small caps door, and requested permission to enter.
These are quite large & complex accounts, so it would take me too long to report in detail here, so I’ll just draw out what seem to me the key points -
H1 figures for the 26 weeks ended 29 October 2022 -
H1 revenues £4,473m (down 6.5% vs H1 LY)
Weak LFL (like-for-like) revenues, at -8%
H1 looks the seasonally weaker half
Impairment of goodwill of £511m (I’m happy to ignore that)
Statutory loss before tax £(548)m - mainly caused by the goodwill write-off
Adjusted H1 loss before tax £(17)m
Guidance: FY 4/2023 a profit of £100-125m (PBT) - this is lower than previous guidance of £125-145m
UK - profits up, from increased gross margins, and cost cutting (offsetting sales decline)
International - more problematic, with sector excessive inventories & heavy discounting. CURY says these are temporary negatives.
Medium-term - targeting a 3% adj EBIT margin, realistically it’s always going to be a very low margin business.
Going concern note says it can operate within bank facilities & covenants, even in a downside scenario (but that’s only a -5% sales fall, which doesn’t look harsh enough to me)
Balance sheet - looks horrible. NAV of £1,847m contains an absolutely bonkers £2,670m of worthless intangible assets. Deleting that, results in NTAV of £(823)m. Note that the lease entries combined show a deficit of £(251)m, which indicates there must be quite a few loss-making sites that need to be closed, if and when leases expire. So I would expect the business to continue shrinking from store closures.
Net bank debt is modest at £105m, but the business is mainly financed by the trade creditors of £2,856m. Therefore the main risk here is not so much the bank getting the jitters, but trade credit insurers withdrawing cover.
An excellent disclosure here, we need all companies to provide this information -
The average net debt for the half-year period was £(114)m, compared to an average net cash position of £290m in H1 2021/22.
I’m not sure why the previous average net cash position has worsened so much in the last year?
Pension schemes - big numbers, see note 5, with assets of £987m, and liabilities of £(1,237)m, so a deficit of £(250)m. It's astonishing to see how asset values have crashed in the last year. Trouble is, liabilities have not reduced, it's just that the way they're calculated (referencing bond yields) has technically reduced liabilities. So I'm uneasy about big pension schemes generally.
Cashflow statement - pension scheme deficit recovery payments are running at £78m pa, so highly material.
The operating cashflow last year was all consumed by capex, and finance costs (including big lease liabilities). Dividends and share buybacks were funded through increased borrowings.
Therefore I would say the dividend yield looks unsafe, and should probably be pulled, as the company really cannot afford to be paying divis at all, in my opinion. So I wouldn’t buy this share for the generous divi yield, as it could disappear quite easily.
Outlook - I've focused mainly on the downside risks above, but for balance, the company also gives the upside potential in the guidance section -
We are confident that the improvements to UK&I gross margin and ongoing cost control will continue to deliver robust profitability despite our expectation that market conditions will not improve in the second half.
In International, the high market shares and our long track record of growth in sales and profit, together with self-help action on margin and costs, give us confidence that profitability will recover robustly when market conditions normalise. The timing and extent of this will depend on when demand normalises, but especially on how long competitors need to clear excess stock, and how long they sustain unprofitable pricing.
My opinion - I’m not at all keen on this. The balance sheet is too weak, and the whole business relies on trade creditors extending almost £3bn of financing. There’s no reason to expect those credit lines to be pulled, but it’s a huge exposure. Investors often forget that trade credit (i.e. suppliers delivering goods before they get paid) is the main way that many businesses are financed.
Due to this financial weakness, dividends look unsustainable to me.
It doesn’t look in any immediate risk of going bust, but if trading gets a lot worse, say in the event of a deeper consumer downturn in 2023, then things might get difficult. Although management says it has levers to pull, which I’m guessing would be curtailing capex, cutting the marketing budget, staff cuts, etc. So there is some flexibility in the cost structure.
Meanwhile there are online-only competitors, where nobody has any pricing power, as many consumers compare prices and go with the cheapest.
For me, this one’s an avoid.
Stockopedia gives it a fairly decent StockRank of 69, so maybe I'm being too cautious?
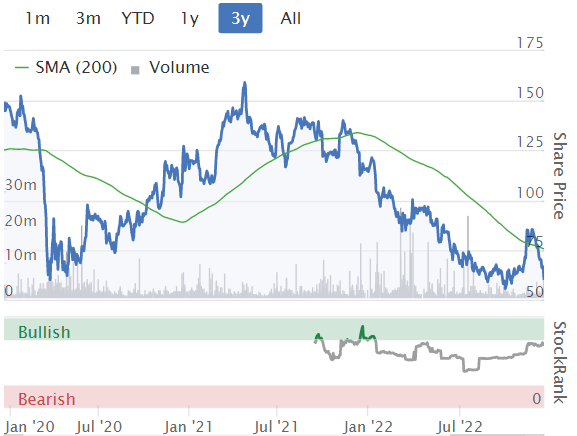
The share price is right back down to pandemic lows of early 2020. Opportunity, or a worry? That's your call!
Graham’s Section:
Science (LON:SAG)
Share price: 404p (+6%)
Market cap: £183m
This calls itself “an international science, technology and consulting organisation”.
Paul has covered it on numerous occasions this year - see the archives - and in general has looked favourably on it.
This morning brings a pre-close trading update that is slightly ahead of expectations.
As anticipated, while some market sectors, particularly medical, are continuing to invest, consumer-oriented sectors in both services and products have been impacted by the global economic slowdown. With a significant proportion of income generated in US Dollars, the Group has benefitted from the relative strength of the Dollar, offsetting the significant increase in energy prices and other cost inflation. In aggregate, the Board anticipates that revenue and adjusted operating profit for 2022 will be slightly ahead of current Board expectations.
I’m impressed that Dollar strength has been enough to offset cost inflation. I wonder if Science Group has been successful at pushing through its own price increases to customers?
Balance sheet - gross cash of £44.5m, net funds of £30.1m. The company’s £25m RCF is undrawn and its term loan has been fixed using an interest rate swap. So the company has “limited exposure to future interest rate increases”.
Currency cap - the company has used another derivative to protect itself from US dollar weakness until the end of 2023. It looks to me like this trade has already been incredibly successful as they’ve capped $1.25m of monthly revenue at a GBPUSD rate of 1.20. But GBPUSD has already risen to 1.24!
If, for example, GBPUSD trades at an average rate of 1.30 for the duration of next year, then my quick calculations suggest that this derivative will pay out in the region of £1m to Science over the course of the year. There will have been some costs to set it up, of course. It’s a lovely bit of business to have done.
During the mini-Budget panic, Cable fell as low as 1.07, so this explains why it was possible to get a cap at 1.20.

Monthly revenues in excess of $1.25m aren’t hedged, so Science will still have some exposure to dollar strength or weakness.
And by early 2024, the hedge will have expired - it’s easy to forget that hedges don’t last forever. For example, many companies who have benefited from energy fixes in 2022 will be unprotected at some point over the next 12-18 months. Something to watch out for!
TP Group acquisition - the company continues to anticipate that it will take over TP (LON:TPG) “early in 2023”. TPG’s financial track record looks quite bad, so hopefully the influence of Science on it will be a positive one!
How to pay for it:
The Board does not anticipate that the cash outflow (including repayment of TPG bank debt, fees and integration costs) will exceed £25 million and therefore the acquisition will be funded through Science Group's existing cash resources and finance facilities.
With net funds of £30m, perhaps Science will barely need to use its RCF to pay for this?
Outlook - TPG will give Science “ entry into the defence market, together with synergistic opportunities for growth in the medium term”.
My view - Science is a diversified consultancy business that includes a digital audio company. With TPG, it is seeking to add another branch of consulting, plus some engineering services.
To me, the market is pricing this one about right. Having been burned by professional services companies in the past, I would never want to overpay for them again. But Science has a financial track record that says it’s a better-than-average consultancy company, and in any case it is more than just a consultancy. So perhaps a PER in the mid-teens is fair?

Before I wrap this up, I’d like to reiterate that I’m genuinely and deeply impressed that they bought a GBPUSD cap at a rate of 1.2. What a clever bit of business!
At market extremes, banks don’t price long-term derivatives correctly - remember that Warren Buffett sold many billions of dollars worth of put options on stocks during the great recession (a bullish bet that paid off handsomely). It takes highly opportunistic traders and investors to exploit this.
Hunting (LON:HTG)
Share price: 269p (+2%)
Market cap: £444m
This is an “international energy services group”, with a year-end trading update. They provide “innovative products enabling oil and gas extraction worldwide”. Oil and gas producers have had a good year, so I would assume that Hunting has done well, too!
2022 is trending in line with expectations for EBITDA of c. $50m. The company reports in US dollars.
Key points:
- Order book is still improving and approaching $500m.
- 2023 expectations raised for EBITDA of $85-90m (previously $80m).
- New sales group focused on “Energy Transition” (“carbon capture, geothermal and other low carbon technologies”).
The order book is short-dated and will be delivered mostly next year, although some products won’t be delivered until 2024/2025.
North America - “steady sales” and “strong momentum” reported across Hunting’s various business units.
South America - “New opportunities continue to be pursued… with drilling and completion activity accelerating as unconventional resources are developed…”
EMEA - “improving results”.
Asia Pacific - “steadily improving performance since the middle of the year…”
Balance sheet - net assets of $847m (November), although this will include a large amount of goodwill and illiquid equipment. Cash of $24m, reducing to $20m by year-end.
2023 outlook - the raised EBITDA guidance is a result of the strong order book performance which, as I’ve said, mostly consists of sales that will be delivered during 2023.
My view
I’m not a sector expert when it comes to oil and gas, but I can make a couple of observations.
Firstly, I know that many investors like to take the “picks-and-shovels” approach to energy, i.e. investing in the associated tools, equipment and technology rather than in the energy producers and the energy assets themselves.This way, you can still get positive exposure to the industry but perhaps without some of the more extreme cyclicality and the other risks that come from owning energy assets. Hunting appears to be a good example of a “picks-and-shovels” stock.
Secondly, and more negatively, I note that Hunting reported nearly $40m of depreciation last year. It has a range of capital-intensive manufacturing facilities and therefore in my view the EBITDA number must be thrown out as irrelevant. Upgrades to EBITDA estimates are still better than downgrades, but the EBITDA number itself is too far removed from profitability to be of interest to me. Depreciation is a real cost and is a significant one at Hunting.
Overall, I’m not sure how to justify Hunting’s current market cap of nearly £450m. The estimates for 2023 are good, and it appears that investors are willing to give the company the benefit of the doubt that it will hit these forecasts.

Perhaps the Hunting share price also reflects a belief that commodity prices will continue rising over the next few years, as inflation remains a key issue. Oil and gas are booming industries these days and it should not be difficult for Hunting to make money in this environment.
If we look back to 2018/2019, Hunting was amazingly profitable. Perhaps the company can get back to that kind of performance in the next few years, if the oil price stays high?
Given the volatility of historic results, this one is offering lots of opportunity, with lots of risk.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

31 comments
Not small cap, but it just struck me that on inflation, we have a market that has a very optimistic view that inflation will fall back down easily, against the Feds and BoE who are keen to stress that the picture is not so rosy, or at least not enough data yet to make that call.
Surely the smart bet is on the Fed and BoE view? They have data points we don't, as well as being the experts in poring through the price data in both countries.
Whereas most market participants, have never been in their profession during the last big inflationary period.
Granted, there are the two super doves on the BoE; but it looks like their dovish position is not because they think inflation is no longer a threat, but more about whether we're hurtling in a deep recession, and they'd rather prefer inflationary risks than recession risks.
Any thoughts from others more knowledgeable on this than I am?
I agree the stubborn outlook on inflation announced yesterday and today by the central banks and the sustained height of future interest rate predictions, I think is driving this sell down, which could very well continue. Europe's inflation looks set to be more stubborn, and the fear must be that a deep recession in Europe and perhaps the UK is more of a possibility.
I am however reassured by the low values of UK companies generally and the lack of any sort of meaningful rally in the small and midcap space to date. This makes me think that although we could see some pressure on share prices, I can't imagine it breaking previous lows. That said the potential for a big Covid outbreak in China, with substantial loss of life, and emergency lock downs while the Government scrambles to vaccinate the population, could add additional pressure...
It's going to be challenging 6 months ahead, but don't feel compelled to join the sell off unless stop losses are breached.
Surely we've all come to accept there will be a significant recession in EU and UK through at least part of 2023? Inflation caused by COVID supply chain issues has just about worked through and now we need to get past the response to Putin's invasion. My guess is that will be April or maybe a little later so expect high inflation print for a few more months yet, though hopefully dropping below double figures as we've massaged the energy impact out already with all the Govt subsidies.
USA may have a shallow recession but that will be it. They will yet again make money out of war and emerge with a stronger global position enhanced by China suffering quite badly from their botched COVID release and general unrest.
Too soon to look through it just yet? Won't be long though IMO.
Your question is covered today both by John Authers on Bloomberg and Robert Armstrong in the FT. Both worth reading and not just today
On Beach group (LON:OTB) - Another director buy yesterday:
14 December 2022
On the Beach Group plc
("On the Beach", "OTB" or the "Group")
Director / PDMR / PCA / Shareholding
On the Beach Group plc (LSE: OTB.L), a leading UK online retailer for beach holidays, announces that Hawksford Trustees Jersey Limited (as trustees of the SC 2014 Settlement) , a PCA of Simon Cooper (Founder and Chief Executive Officer of On the Beach Group plc), notified the Company on 13 December that he had purchased 288,587 ordinary shares of 1 pence each in the Company ("Ordinary Shares") at price of 117.91 pence per Ordinary Share (GBP340,272.93 in aggregate).
EPS forecast of 12p 2023, followed by 15.7p for 2024. EPS growth +496% followed by 31%. PE/PEG 11.2/0.364 followed by 8.58/0.311.
Cash at bank should start earning a decent income now. Dropped to near 100p on results day; a serious rebound since.
Of interest to no-one I assume...but I looked at new IPO Smarttech247 today (I torture myself with cybersecurity cos trying to grasp something meaningful about them other than "fck we're cybersecurity screwed") as was interesting in that has revenue, clients and profits. Any view welcome.
I mentioned a few days ago about if we write up on shares we are interested in and seemed to get a number of thumbs up, so here goes mine.....
Came across 1Spatial (LON:SPA) today via an RNS taking about replacing it's CFO and I must say I really like what I see here and have taken an opening stake in the business. CFO has been replaced and the old CFO is thanked and hanging around so should be a smooth transition (share price unmoved).
Seems to be gaining traction with a string of high profile orders, particularly state side with its location software. Also some high profile projects such as HS2.
I like how it has steadily grown revenue and gone from loss to profits over a number of years, and it appears that it is now starting to push into a decent profitable business. Constant director buys, small but no sells which looks good.
It has a number of broker notes on research tree so worth a look, with Stocko showing broker upgrades.
Downsides are no dividends at present and it is using a little of its cash, but still has a decent cash pile, and has no debt. It has had share dilution, but none in the last few years. Margins are tight, but growing and I assume scale is starting to kick in.
I would like to have paid 45p for it and would consider that my second tranche, but it does look like it could rerate.....and very unusually for a £50m market cap business the spread is good, shares seem available, with buy orders @ 48p from brokers.
Had a quick look back and it would appear Paul has not looked at it for a few years (unless the TAGS are not working?). Be interesting to hear if you recall this one Paul?
StockRank is not amazing but my gut feeling is, its on the up.
All the best
Paul
Sosandar (LON:SOS) here is the H1 23 presentation, including Q&A Q&A. Video & podcast. They are firing on all cylinders.
A really comprehensive presentation embellished by some tremendous investor questions and answers. Probably 30 minutes of Q&A.
Secure Trust Bank: We met David McCreadie, CEO at STB last week. He gives a good overview of the business here, video & podcast. I liked him. He first joined as NED, saw the opportunities and became CEO 2 years ago. It trades on a PE 3.4 & divi yield of 7.4%. They are a retail bank, they use savings from retail customers to make loans to business clients in Retail (furniture, jewellery & used cars), Property (to developers) and Factor Invoicing to SMEs who supply large organisations with longer payment terms. They have a prudent approach to risk. Here are the medium term targets they set for themselves at their Capital Markets Day, November 2021:
More broadly, it provides good insight to macro for finance sector generally.
SThree (LON:STEM) FY22 Trading Update analyst call from yesterday. Video and podcast.
They are starting to see evidence of the macro uncertainty but the contract order book is +19%, so they have good visibility.
Finally, Begbies Traynor (LON:BEG) interim results analyst presentation. Video and podcast. They had a strong first half and are confident in the full year.
Worth a listen for the macro picture too. Small company insolvencies are up 23% on pre-pandemic, interestingly larger company administrations are still 35% below pre-pandemic but they expect this to change. In the GFC, insolvency peaked at 26,000 cases, BEG think this time it will be higher.
excellent work on £SOS
Thanks Tamzin, very interesting, with some good questions and even better answers IMHO.
Richard
hi Paul
All tags except for DX (Group) (LON:DX.) have disappeared.
Snazzy
You're a star, thank you Snazzy :-)
I've just put the disappearing tags back in. There must be loads more missing, so I must go through the old reports to check them all.
Best wishes, Paul.
Hi Graham,
Thank you for your review of Science (LON:SAG) (I hold)
I agree that it appears priced about right by the market given current conditions and for what appears on the face of it to be a consultancy business
But is the market right? I think its undervalued for multiple reasons.
[1] The business is more diversified than it appears. The R&D services division provides environmental, safety and science consultancy where independent services are sticky with customers. There is also a food science division which provides regulatory testing and research services from its labs. Lower margin but even stickier as customers have to have independent testing. The two main properties Harston Mill (Cambridge) and the Leatherhead Food Sciences Laboratories have been moved to a property subsidiary which leases to both science group companies and third parties. Frontier Smart technologies, a previous basket-case acquisition, is a high margin chip designer with a leading position in the sale of digital radio chips and modules.
[2] According to the forecasts on Stocko FY23 revenue and profits are forecast to be flat on FY22. But the existing businesses grew profits by 10% in H1. Zero growth through FY23 looks to be an undemanding steer from management at this point. Understandable under current circumstances but given past and current performance growth of between 5-10% would be more reasonable?
[3] The acquisition of TPG agreed by shareholders yesterday is said to be earnings enhancing. Yet there is nothing in the FY23 forecasts for this acquisition.
Based upon FY22 H1 TPG figures I’d anticipate FY23 revenue of £40m and adj op profit of £3m and that assumes just the contribution from TPG service division (which grew adj op profits at 12% in H1 FY22), shorn of corporate costs, and nothing for Maritime. Assuming close to a full year contibution for the acquisition.
Thats about +45% revenue and +17% adj op profit growth from the acquisition.
The acquisition is very unusual as SAG directors have controlled the TPG board for some months already, disposed of and written down under-performing businesses and assets and parchuted SAG senior management into the maritime subsidiary to renegotiate legacy contracts with customers and turnaround the business. As a result the acquisition is both almost entirely de-risked and already working alongside SAG. Very astute management.
[4] Longterm growth record of the company – including record profits through the pandemic years – and the medium term prospects from the TPG acquisition through synergies, organic growth, turnaround of the maritime subsidiary and access for SAG businesses to the UK MOD and TPG businesses to the US market are substantial. Which significantly understates it.
[5] I rate the management very highly. The Frontier acquisition, TPG acquistion and recent USD cap are good examples. Longterm ‘founder’ and largest shareholder Martyn Ratcliffe interests appear to be well aligned with shareholders.
I don’t see this as an instant multi-bagger more a long-term compounder combined with a buy-and-build ability. Future astute acquisitions are to be expected.
Something like 10-12x FY23 earnings, assuming some organic growth and including the acquisition appears to be very under-rated to me on the long-term view.
Just my opinion - others are welcomed - and written in something of a hurry today so apologies for any typos in advance.
If the price stays around the same level whilst I am looking for more cash down the back of the sofa – I’ll be buying some more,
cheers
Mark
Dear Paul,
According to your colleague Zotefoams is the diametric opposite of a quality company while disagreement is good the divergence between the two of you is extreme could you ask him for a comment as it would no doubt add balance.
Hi Tombholliday,
"According to your colleague Zotefoams is the diametric opposite of a quality company while disagreement is good the divergence between the two of you is extreme could you ask him for a comment as it would no doubt add balance."
Who are you referring to please? A link would help too, then I'll take a look at whoever it is who has apparently written something bearish about ZTF.
I see the StockRank is pretty good, so the computers are leaning towards my view!
Thanks, Paul.
appears to be related to this post, where Mark is almost being trolled https://www.stockopedia.com/co...
Thanks tic_tac_toe,
I see there's a vigorous debate in the comments section in this post form Mark Simpson about Luceco (LON:LUCE) where he then went on to express negative views on Zotefoams (LON:ZTF) focusing mainly on low ROE.
That's one way of looking at it, and he's entitled to his point of view. The writers here are all freelance, so we don't consult each other when writing or talking about shares - e.g. Graham did a very negative review of Boohoo (LON:BOO) whilst sitting next to me at Mello. It's fine, we just debated the various bull & bear points.
I agree with Mark that ZTF is capital-intensive, and it's spent a lot of money updating its factories. But now the benefits (higher profits & cashflows) are starting to flow through.
So personally I'm only interested in where the company is now, and where it's possibly going in the future. Analysing historic numbers looks to me a fairly pointless exercise.
I'm unusual in that I don't necessarily follow the current fashion for chasing high ROE and high ROCE. I like balance sheets stuffed with freeholds & cash, because that greatly reduces risk, and increases the likelihood of sustainable divis & buybacks.
So as with everything, there's no right or wrong in investing, just different perspectives. It's always good to hear different views, so I welcome the debate.
Regards, Paul.
P.S. but I'm pretty sure that I'm more correct on ZTF! ;-)
You were very sure about Boohoo (LON:BOO)
Yes Rusty2, I was very sure on Boohoo (LON:BOO) when the facts & figures supported that bullish view. The facts & figures then gradually worsened, very considerably. So the investment case now has completely changed for the worse. That's what happens sometimes. Nobody can predict the future with any certainty, and these days business models seem to change much more rapidly than before, so it's not as easy as people think to pick the winners. In practice, we all have some winners and some losers every year.
So if the facts & figures at ZTF deteriorate, I'll amend my view accordingly.
On Currys Currys (LON:CURY)
My partner and her 95yo mum (MIL) had fun with them over the last 2 weeks or so.
MIL (not great eyesight or hearing) wanted a TV that was clearer and has audio description. Went to the shop. saw one that looked good. tried to buy it. assistant spent 30mins trying to get connected to the payment system, eventually gave up. partner bought one online from currys later that day. arrived on time ~2d later.
I unpacked it and plugged it in and ... in real life the picture was hardly any different and the remote control was _really_ hard to use if you cannot see well.
The advisor had an opportunity to Sell them a _really_ expensive one that fitted MIL's needs, but pointed them at a mid range one that did not.
After a week she decide to return it.
Partner tried calling currys - no luck. Used web chat - arranged collection, except they didnt collect. we were told they tried to by couldnt (MIL lives in flats with a secure entrance). we were told to leave it in an unsecure place, but that would be at our own risk... we would get emails and messages saying they were collecting and then nothing...
After 6 attempts over 10 days to arrange collection it turns out that the call centre (in india) was arranging collection with DPD online and getting confirmation a collection was booked but DPD was overstretched and so not actually collecting. Partner drove the package to a currys and dropped it off (it seems this is not a standard option)
My takeaway from that is
(I have no position in currys)
From my experience Richer Sounds is the best place for TV and HiFi.
The guys are very technical and will help but not pushy. Will home install and show how to use stuff. 5 year guarantee on tvs.
actually 6 year guar just bought the worst quality samsung from them !!
Something appears to be going on at apparent basket case cyber technology firm Osirium Technologies (LON:OSI)
Two significant share purchases by private investors yesterday, both of which have triggered a flurry of (mostly buying) trading activity.
Nicholas Slater purchased 12.5m shares (10.2% of the company), a wholly new holding announced yesterday.
Also Mark Horrocks & family interests increased their holding from an undeclared level (i.e. below 3%) to a holding of 6.95m shares (5.7% of the company). This was only announced this morning.
Yesterday's announcement triggered a 30% uplift in SP and today's announcement has so far triggered a further 10% uplift in SP to 3.1p.
Watching with interest from the sidelines.
Snazzy
Paul, since my post of a couple of days ago, a debate has rumbled on with several members piling in on me and with me standing my ground, while others have echoed my comments. I think it’s time to draw a line and your recent coverage and championing of Zotefoams (LON:ZTF) is an example I’d like to highlight as a piece of first-rate stock research that we can all benefit from, and not just financially. Thanks for your hard work and good humour.
Thanks BnB, I appreciate you reaching out on this.
Graham & I discussed it, and agreed there was no point in getting involved in any more discussions about what we cover, or why, as it gets us collectively nowhere, and expends mental energy that can be put to better use.
But we have taken on board feedback from many people with different views, including yourself, and hope that by covering a lot more companies now (e.g. 14 yesterday, 12 on Friday), we can keep everybody happy-ish :-)
Regards, Paul.
Hi Paul - I just wanted to say that I have found the move to you and Graham writing short comments as well as your usual in depth pieces useful.
Thank you
Martin
Brokers boost Travel expectations but Moonpig (LON:MOON) gets the thumbs down , a bit belatedly since Moonpig (LON:MOON) now stands at 112p!
* EasyJet EZJ.L : JP Morgan raises target price to 320p from 260p
* Ryanair RYA.I : JP Morgan raises target price to EUR 21 from EUR 18.2
* SSP Group Plc SSPG.L : JP Morgan raises target price to 350p from 320p
* Wizz Air WIZZ.L : JP Morgan raises target price to 3400p from 2800p
* Moonpig Group MOONM.L : HSBC cuts target price to 210p from 345p
We should be able to get through all of this lot, with longer sections for the more interesting companies, and short sections for the rest. So we don't need any discussion on what we're covering and why,. we're just getting on with it! :-)
EDIT: The next step is that we also look at the top % risers/fallers at about 9am, to pick up on anything we've missed that has moved prices a lot. So the above list might grow, depending on what happens.
Update - It's a clean sweep, yay!!! Well done Graham & I, wish this happened more often, but there are usually too many updates to cover everything.