Small Cap Value Report (Thu 15 Feb 2024) - CTG, WATR, JIM, JET2, CBG

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
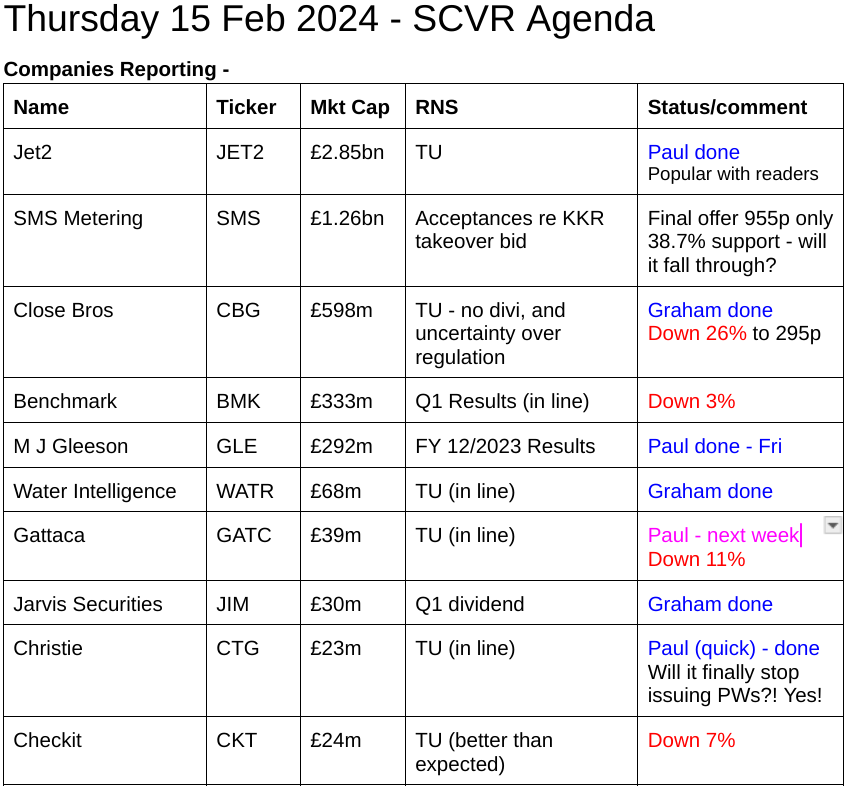
Other mid-morning movers (with news) -
Renalytix (LON:RENX) - down 33% to 30.5p (£30m) - Interims issued. Multi-year cash burner, but only has $5.6m cash at Dec 2023. So it’s bust if it can’t raise fresh cash, says: “Raising funds… is essential”. Also looking at non-dilutive funding. Christopher Mills is Chairman & 10% holder. Will he be kind to small shareholders in the next fundraise?! RED for me - bargepole job until it refinances.
DSW Capital (LON:DSW) - down 32% to 41p ( £9m). Profit warning following bad performance in Jan & Feb 2024. Says M&A market has stalled, but it remains profitable.
Genus (LON:GNS) - down 18% to 1,750p (£1.15bn) - animal genetics co. H1 to Dec 2023 in line exps. Tough market conditions, esp in China. FY 6/2024 guidance revised to £58m adj PBT, Liberum says that’s 20% below its forecasts. Highish PER share, so can’t afford to disappoint.
MicroSalt (LON:SALT) - up 24% to 105p (£46m) - very recent (1/2/2024) IPO - patented low sodium salt. Announces partnership with ATI, “a leading US food and beverage export company”.
Jarvis Securities (LON:JIM) - up 18% to 60p (£27m) - announces 1.75p quarterly divi. Does this imply the situation here might be under control after recent problems? The market seems pleasantly surprised. EDIT: Graham has now written an additional full section on this.
Summaries
Christie (LON:CTG) - 85p (pre-market) £23m - Trading Update FY 12/2023 [in line] - Paul - AMBER
The profit warnings have finally stopped! No further reductions in guidance for FY 12/2023. More encouragingly, it says 2024 has got off to a good start. Overall, I can't see that much upside on the current share price, but it might have a bounce, who knows?
Water Intelligence (LON:WATR) - down 0.7% to 387.4p (£68m/$85m) - Trading Update - Graham - GREEN
Upgrading my stance to positive after an in-line trading update. WATR has a solid track over many years and yet shares trade at an enormous discount to prior levels (both in absolute terms and in terms of PER). Net debt of $7m is modest and the Chairman is well-aligned.
Jarvis Securities (LON:JIM) - up 33% to 68p (£30m) - Dividend Declaration - Graham - GREEN
The market breathes a sigh of relief as Jarvis declares a 1.75p Q1 dividend, after it failed to make a Q4 payment last year. A “skilled person” review will be delivered to the FCA by the end of the month, so we should hopefully get clarity on the company’s position soon.
Jet2 (LON:JET2) up 4% to 1,377p (£2.94bn) - Trading Update [ahead] - Paul - GREEN
A positive update today, with Canaccord raising its estimates for both FY 3/2024 and FY 3/2025. Shares have risen a lot in the last 3 months, but still seem good value to me. So a continuing thumbs up from me, if you're happy with the sector risk.
Close Brothers (LON:CBG) - down 26% to 295p (£444m) - Trading Statement and Dividend Announcement - Graham - GREEN
An enormous fall in the equity value here as Close Brothers admits it is vulnerable to an unknown, unquantifiable impact from the FCA’s review of historical commission arrangements for motor loans. The dividend is suspended. Amazingly cheap but high-risk.
Paul’s Section:
Christie (LON:CTG)
85p (pre-market) £23m - Trading Update FY 12/2023 [in line] - Paul - AMBER
Christie Group plc, quoted on AIM, is a leading professional business services group with 37 offices across the UK and Europe, catering to its specialist markets in the hospitality, leisure, healthcare, medical, childcare & education and retail sectors.
Christie Group operates in two complementary business divisions: Professional & Financial Services (PFS) and Stock & Inventory Systems & Services (SISS). These divisions trade under the brand names: PFS - Christie & Co, Pinders, Christie Finance and Christie Insurance: SISS - Orridge, Venners and Vennersys.
We covered this a fair bit in 2023, with a series of profit warnings, blamed mostly on project delays in its core property advisory business. As you can see below the EPS forecast collapsed into an expected loss of -4.2p for FY 12/2023, which is consistent with a note I have here from Shore Capital (many thanks) issued on 8 Dec 2023.
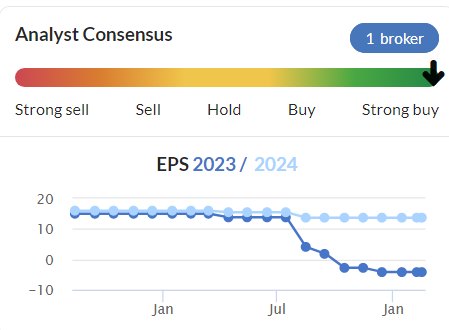
The static EPS forecast for FY 12/2024 looks suspect, as it’s unusual for companies to fully bounce back after a really bad year. I suppose it’s possible though, if delayed deals in 2023 do complete in 2024.
Today’s update confirms no further deterioration, which is something -
The Board of Christie Group plc (CTG.L) advises that, as anticipated, it will report an improved second half trading performance in 2023 compared to the first-half. The full year result, before exceptional costs, is expected to be in line with market expectations which were revised in early December.
2024 outlook - sounds more encouraging -
The Group is seeing positive and encouraging activity levels across its sectors at the start of 2024, with its UK transactional and advisory pipelines having now recovered to a significantly improved position from a year ago.
2024 for the Group has started positively, with particularly strong January invoicing in its UK agency and advisory business, Christie & Co.
Paul’s opinion - my view of the company was badly dented by the lousy performance in 2023, especially given that several competitors reported conditions being normal.
Is this business actually any good, especially given that performance seems quite erratic, and they’ve proven inept at forecasting?
Actually the historic track record isn’t bad. It’s usually profitable, and dividend-paying. I’m not clear why this company is listed, as it’s ex-growth and doesn’t seem to have a clear strategy to use the listing for anything.
There hasn’t been any dilution during the pandemic, so if it can get EPS back to historic levels of about 10p/share, then at 85p the share price would make sense at this level, possibly slightly higher.
I don’t see any great appeal overall therefore. There’s the chance of a trading bounce, on the more upbeat tone today, but the wide spread & illiquidity could make it difficult to make much money on this.
I’m lukewarm, so will go with AMBER.
Jet2 (LON:JET2)
Up 4% to 1,377p (£2.94bn) - Trading Update - Paul - GREEN
Jet2 plc, the Leisure Travel group, announces the following update on trading.
Trading for year ending 31 March 2024 (FY24)
Things are going well, with the conclusion -
… we tighten and slightly raise our guidance for Group profit before FX revaluation and taxation for the financial year to between £510m and £525m (previously £480m to £520m), which remains dependent on no material extraneous events in the balance of the financial year.
Trading for year ending 31 March 2025 (FY25)
This is much more vague, with no specific profit guidance, saying -
The Group will provide a further update in April 2024 and will announce its Preliminary Results for the year ending 31 March 2024 on 11 July 2024, which will include a fuller outlook for the all-important Summer 2024 trading period.
The rest of the commentary seems to be saying overall that forward bookings are “encouraging”, tempered by some cost increases.
Broker update - many thanks to Canaccord, with an unusually bullish note today, explicitly stating this share is significantly undervalued. I agree.
In EPS terms, Canaccord raises FY 3/2024 from 160.3p to 167.2p.
It also raises FY 3/2025 from 157.4p to 164.9p.
In both years that gives a PER of about 8.3x
I imagine there might be further upside potential on the FY 3/2025 forecasts, which seem modestly set considering demand is up. Holidays seem to be a high priority for households, something we’re hearing from other companies too, as people get back to normal post-pandemic, and want to do things we enjoy again.
Paul’s opinion - this is a good update today, with broker forecasts raised a bit.
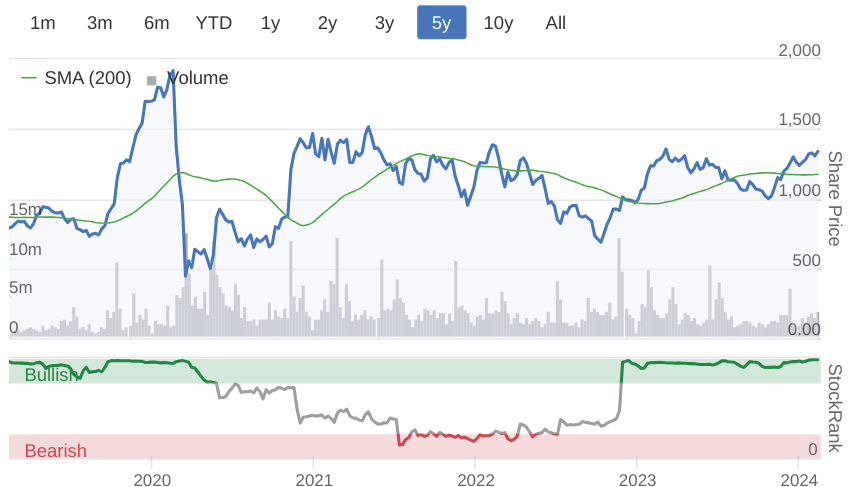
I looked at JET2’s interim results here on 23 Nov 2023, in response to a lot of interest from subscribers here. I concluded very positively, when the share price was 1084p.
It’s risen a lot since, but the way I see it, JET2 has gone from ridiculously cheap, to just cheap now. So I’m happy to remain at GREEN, like last time.
Sector risk is something to bear in mind though - maybe some investors may want to eschew travel shares, as the whole industry can so readily be shut down if another pandemic were to happen.
Graham’s Section:
Water Intelligence (LON:WATR)
Share price: 387.4p (-0.7%)
Market cap: $85m
Water Intelligence plc (AIM: WATR.L) ("Water Intelligence" or the "Group"), a leading multinational provider of precision, minimally-invasive leak detection and remediation solutions for both potable and non-potable water, is pleased to provide a trading update for the year ended 31 December 2023…
This is an in line with expectations trading update.
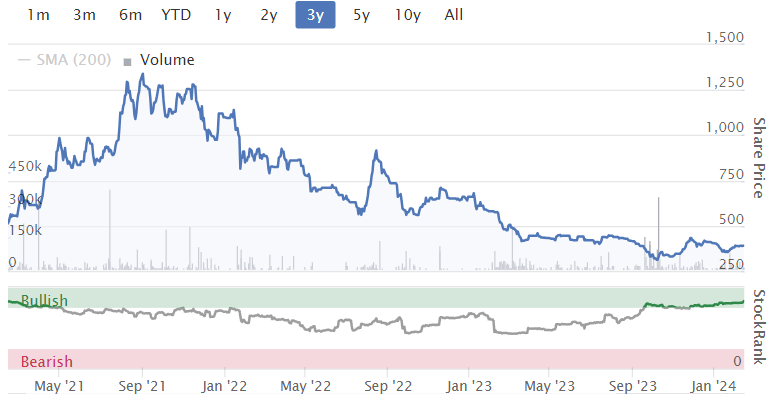
Checking our previous notes on this one, I’ve been neutral but leaning towards taking a positive view on it, as it trades at much cheaper levels than it did before:
It’s a franchise type of business, making its own direct sales to customers but also having franchisees under its various brands. And it has a heavy weighting to the United States through its core business American Leak Detection.
Today’s news:
Trading in line “despite the sharp rise in interest rates and persistent inflation adversely shaping consumer spending decisions”.
Pittsburgh franchise is being bought back for $0.5m and will be operated directly by American Leak Detection rather than by franchisees.
Whenever a franchise company buys back a franchise, I tend to view it with mixed feelings.
On the one hand, it implies that the franchise business model isn’t working, which is unfortunate (as it’s such a profitable business model when it works).
On the other hand, it can also be a demonstration that the owner of the brand is determined to fix any problems that have arisen, which is a good thing for customers and for the long-term health of the brand.
What you definitely don’t want to see, as a shareholder, is a company buying back its franchises in order to pad its revenue figures.
With respect to Pittsburgh, this is what WATR says:
The Group believes that the Pittsburgh location was underperforming as a franchise and sees an opportunity to increase its growth trajectory.
I’m happy to take that at face value.
Financial highlights for 2023:
Network sales (all sales to customers, including by franchisees) up 3% to $170m (2022: $165m)
Revenue up 7% to $76m (2022: $71.3m)
PBT up 13% to $6.2m (2022: $5.5m)
US inflation was 3.4% in 2023, so you can see that WATR’s total network sales - including international sales - did not quite match inflation during the year.
But there are signs of operational leverage, with PBT still growing at a healthy rate.
Profit margins all increased, another positive sign.
Net debt is $7m after subtracting bank debt and deferred acquisition payments ($22.8m) from cash ($15.8m). I agree with WATR that this is a “conservative” positioning. They say they have “dry powder” for further investments!
Compensation in shares
We are told that:
Consistent with prior years, members of the Board have elected that they would prefer to receive their compensation in equity, in lieu of cash compensation for the year ended 31 December 2023, in order to benefit from capital gains as the Company executes on its growth strategy.
I’ve gone back to the 2022 annual report to see what happened then. Chairman DeSouza was paid $591k, but also received stock options worth $80k in lieu of cash.
So while this has been presented in an unusual way, I think it’s actually quite normal. Most compensation is still in the form of cash.
Chairman comment: it seems as if more franchise reacquisitions are on the cards.
Given our strong balance sheet and continued performance in generating profits, we are able to invest in capital projects that sustain our long-term growth: (i) strategic franchise reacquisitions to provide regional corporate support to grow neighboring franchisees; (ii) customization and implementation of web applications to promote operating efficiencies and upselling opportunities; (iii) new products and solutions for water and wastewater infrastructure problems.
Graham’s view
I remain impressed by the long-term trajectory here. I’m also interested in it by default, given the capital-light business model which in theory should lead to high returns. Although that hasn’t quite happened yet:
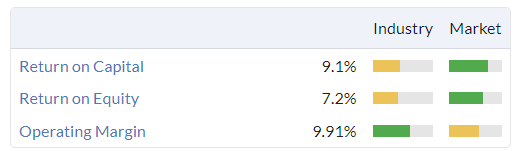
However, the latest results do show margins improving and I’m hopeful that this can feed through to higher returns over time.
The Chairman owns 28% of the company and I think he remains well-aligned with other shareholders.
Top-line growth has been a little slow but perhaps we can write off 2023 as a particularly difficult year.
The enterprise value (market cap plus net debt) is $92m, vs. PBT of $6.2m. Again, I feel that my stance here is finely balanced: should I upgrade my stance, or leave it neutral?
Checking the broker notes, I see that WH Ireland is putting it on a PER of 12x, versus a historical average of 20x.
Stockopedia also puts it currently at the bottom end of the range of its historical PER:
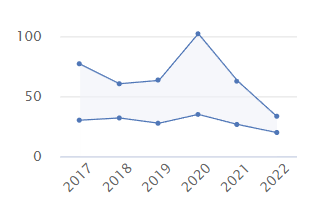
Given the consistent track record, I will upgrade my stance here.
Jarvis Securities (LON:JIM)
Share price: 68p (+33%)
Market cap: £30m
I’m not sure if I can remember such a positive response to a dividend declaration before.
The Board of Jarvis announces that it is declaring a first quarterly interim dividend of 1.75 pence per share, to be paid on 19 March 2024 to shareholders on the register on 23 February 2024 and the shares will become ex-dividend on 22 February 2024.
News flow from Jarvis has been quiet since 13th November, causing some shareholders to fear the worst:
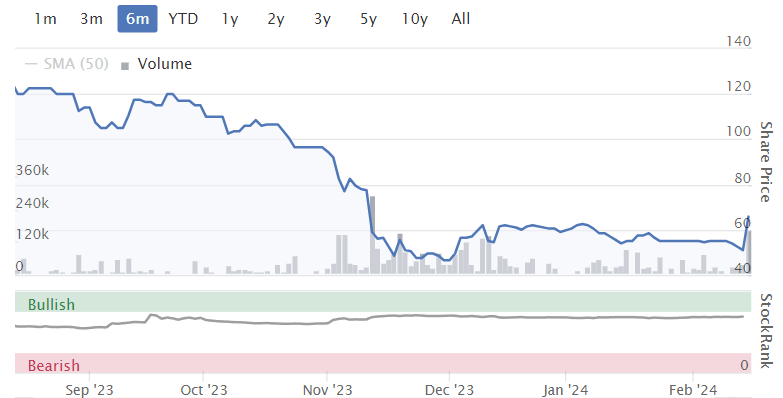
We covered that 13th November update in some detail.
In particular, the company said at the time that there would be no Q4 dividend for 2023.
Given the ongoing regulatory reviews, it was reasonable for shareholders to be concerned that bad news was coming with respect to 2024 dividends. Perhaps trading could have deteriorated to such an extent that a dividend would be considered unaffordable, or perhaps the FCA might have objected to a dividend payment.
Those concerns are now shown to be unfounded, at least for the time being, as the company declares a 1.75p payout.
Last year, the company paid out 3p for Q1, but then it failed to pay anything in Q4 and the entire annual payment was 8.75p.
Therefore, I would say that 1.75p is a decent Q1 payment, giving the company scope to pay 7p-9p this year, if it can manage four quarterly payments. (WH Ireland have today reduced their estimate for JIM’s annual dividends in 2024, from 9.1p to 8p.)
We do badly need an update on the regulatory situation and on trading. There is a deadline for the current review to be delivered to the FCA by the end of this month. The dividend payment doesn’t tell us anything about the contents of this review, but it does seem to hint that the contents might not be damning.
For now, little has changed since my comments in November, when I cautiously gave this stock the thumbs up (at 56p). We now know the company is able and willing to continue making dividend payments.
On that basis, I have to leave my positive stance here unchanged. It may be high-risk given regulatory involvement but at the same time, the market is expecting PBT of £6.6m for 2023 (before regulatory costs of £1.3m). Given the £30m market cap, I remain optimistic for shareholders.
Close Brothers (LON:CBG)
Share price: 295p (-26%)
Market cap: £444m
This relates to last month’s FCA announcement regarding discretionary commissions for motor loans, whereby brokers could be incentivised to arrange loans at higher rates. These types of commissions are now banned, but the FCA is studying historical arrangements to determine whether some customers may be entitled to compensation.
Close Motor Finance may be affected; here is the latest from Close Brothers Group:
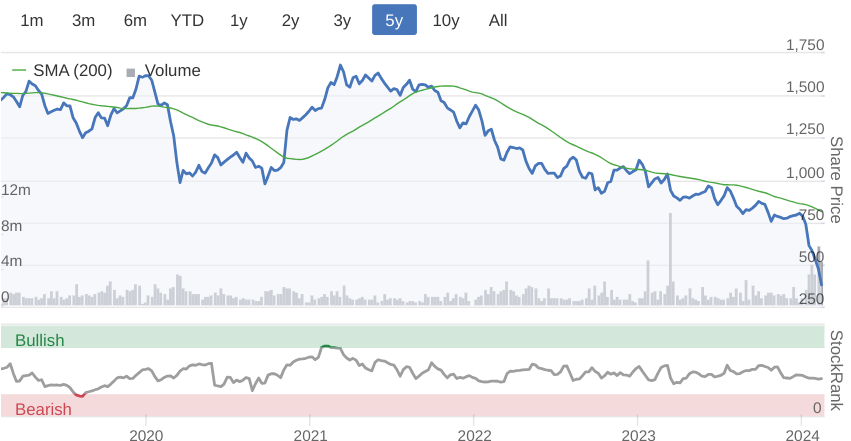
There is significant uncertainty about the outcome of the FCA's review, and the timing, scope and quantum of any potential financial impact on the group cannot be reliably estimated at present.
The market hates uncertainty, and the value of CBG shares is lower by £155m today.
The company was already trading at an astonishing valuation, even before this:
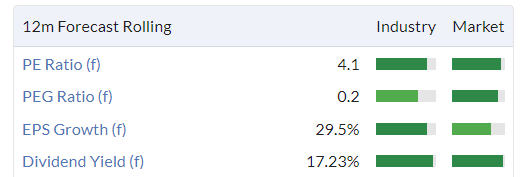
They provide reassurances around their financial strength: they expect to report £94m of adjusted operating profit in H1 (period ending Jan 2024) and have a common equity tier 1 ratio of 12.5%. Their liquidity is “comfortably ahead of both internal risk appetite and regulatory requirements”.
However, unlike Jarvis, they won’t be making any dividend payments. So the 17% yield in the above table is a mirage:
While there is no certainty regarding any potential financial impact as a result of the FCA's review, the Board recognises the need to plan for a range of possible outcomes. It is a long-standing priority of the group to maintain a strong balance sheet and prudent approach to managing its financial resources…
Therefore, the group will not pay any dividends on its ordinary shares for the current financial year, and the reinstatement of dividends in the 2025 financial year and beyond will be reviewed once the FCA has concluded its process and any financial consequences for the group have been assessed.
Graham’s view
I can understand why shareholders might be rushing for the exits. The danger of financial loss relating to this issue will have been known, but now the company is a) acknowledging that it faces an unknown, unquantifiable impact, and b) suspending its enormous dividend in advance of any loss.
Personally, I would be open to betting on Close Brothers here.
Let’s put it this way: today’s movement in the share price implies an additional £150m of expected costs/loss of economic value.
Before today’s fall, the market cap already made little sense if any reasonably stable performance could be achieved.
So if the potential penalties/costs relating to motor commissions amount to less than £150m, and if a reasonably stable performance is achieved in the coming years, then I think investors should do very well.
However, there is no getting away from the risky nature of it: nobody can tell how large (and damaging) any potential costs and penalties might be.
And for income-seeking investors, there is no telling how long we might have to wait before Close Brothers pays another dividend.
The July 2023 balance sheet showed £1.4 billion of tangible equity, several multiples of the current market cap.
I’m giving this the thumbs up, with a disclaimer that I view it as being even higher-risk than most shares I take a positive stance on!
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

123 comments
"In summary, a larger working age population does indeed increase total GDP but that figure is divided by more people. The GDP per capita has been falling due to net migration and therefore we are worse off.
....
Nothing political in this - it's just basic maths"
It's not just plain maths. It's a fundamental failure by you to understand what the data means. GDP in the UK has fallen, or failed to grow, for a host of reasons. Lack of infrastructure, Brexit, years of austerity. If those immigrants hadn't arrived GDP might well have fallen, or not risen as far, resulting in even lower GDP/head. That may or may not be right, but you certainly can't tell from your figures
Thanks for your post very well explained.
They have contributed £43B net to the British economy. It is basic maths.
Unfortunately no maths or figures were given from MarkL.
It actually helps when we do provide an extensive research to support our arguments and not just what we believe.
Its a shame the Bloomsbury Publishing (LON:BMY) IR head needed a 6 minutes interview to provide the information that should have been in the TS. Hopefully the six minutes will next time be spent on writing a far clearer TS rather than having to do fire-fighting afterwards.
Incidentally, surely the company has far better uses of cash than share buybacks
Class A drugs are widely available. I don't regard that as progress!
I don’t see loved-up ravers starting fights at kebab vans or taxi ranks. Stoners don’t tend to beat up on their partners. And the statistics for injury and death paint alcohol in an even worse light. Let the kids choose their favourite form of oblivion. Despite the sensational headlines, they’re safer with almost anything but alcohol.
Unfortunately in my travels I do see coked up nutters thinking they’re superman, unpleasant smell of weed permeating the air and don’t get me started on the spice zombies in some town centres…
I honestly think it depends on the area as to how degenerate the drug users can be.
SALT Low sodium salt, surely that's already been done hasn't it?
For those with an interest in the background to the UK's current economic performance and a potential plan to improve it - I found the recent report
'Ending Stagnation - A New Economic Strategy for Britain'
by the LSE, the Resolution Foundation and funded by the Nuffield Foundation to be a good read - whether you agree with it or not - there is plenty of food for thought?
It's a book in itself and it based upon the interim report 'Stagnation Nation' and 70 reports carried out in the course of the 'Economy 2030 Inquiry'.
And before you dismiss it with - Isn't the Resolution Foundation a loony lefty outfit? And that Torsten Bell isn't he a raving loony socialist? Well yes, if you think being a Treasury civil servant and then a special advisor to Alistair Darling is raving loony socialist?
I checked up on the Resolution Foundation and - contrary to rumour - it was founded by Clive Cowdery (founder of Resolution Life) and the President is David Willets, a conservative peer, ex-paymaster general and ex-minister for universities and science (currently the chair of the UK Space Agency and apparently chair of Darktrace PLC). The report is co-chaired by Clive Cowdery and Minouche Shafik, Economist, Ex deputy governor of the BoE, and currently President of Colombia University. Not a loony left line-up? No doubt it will get brick bats from both Left and Right as the report says things that neither extreme will want to hear? But worth a read all the same?
cheers
Mark
Paul, your comment about CTG’s “historic” EPS of 10p made me chuckle, as I’m almost certain you meant historical, but in the context of CTG’s recent performance, perhaps levels of 10p could be described as historic!
One of the most common grammatical errors, “historic” refers to something momentous or important in history, whereas “historical” is just something that happened in the past.
A big tick in the box for Graham for getting it right in his part :-)
Enough of immigration and the GDP.
Avon Protection (LON:AVON)
I do not hold , but looking at how the price moves for the last three days it is evident to me that there is some serious buying from professionals here.
Been sat on the fence for a year with Avon Protection (LON:AVON) given the damage to brand from the body armour issue.
The CMA presentation is really worth a watch, if a little long at almost 3 hours.
Details on how they are focussing on what they are best known for to increase revenues and a small example of their CI approach through which they plan to improve margins, all struck me as a business that knows itself and is knuckling down on executing the basics exceptionally well.
The CEO and CFO both gave off a lot of confidence around the restructure they’ve completed and team they’ve built,
It convinced me to finally take the plunge and open a position.
Home Reit (LON:HOME) - I've never held this, but it deserves to be investigated. FCA review - better late than never. Today's RNS implies they have been selling 117 properties at a c£48k average price. The state of these properties must be awful. The board don't look very clever after signing off on the previous valuations do they? The investment manager must have been either stupid, negligent or fraudulent. Not a great example of a UK investment company - tarnishes the reputation of other much better companies.
HOME has two big things that I don't like about it. First, it's only been listed for a few years. Second, it's a "bottom-feeder". From their profile, it invests in "a diversified portfolio of accommodation for people facing homelessness." No, just no!
With so many professionally-run REITs out there, why invest in this completely sketchy outfit.
This Is Money called it "a genuinely worthwhile investment." Shocking. The trust is run by an outfit called Alvarium, which is based in New Zealand, of all places. It has a wealth management service. Personally, if I were a client of theirs I'd take my money out straight away. Utterly terrible.
Another thing: in Sep 2021 Alvarium announced a merger deal though a SPAC (special-purpose acquisition company). https://www.fnlondon.com/artic... When I first heard of SPACs I thought they were sketchy. In Jan of this year Paul Kiernan of the Wall Street Journal wrote "Spac mania is dead. The SEC wants to keep it that way." That would be my thinking on the matter, too.
Bloomsbury Publishing (LON:BMY)
A new interview has just been released for any interested:
It looks as though consensus revenues for FY24 have just been increased by £40m (!) with just 2 weeks of the Financial Year left - remarkable.
Here's another interview from a couple of weeks ago, though it's perhaps slightly out of date now:
Quite a nice interview. Explained well, and simply.
Personally, if they have a lot of investment opportunities I would like to see them pursue those than do buybacks. I do like a nice dividend, though.
Interesting that she mentions the potential for buybacks in the future, something that was discussed yesterday by a few individuals. I think the dividend will need adjusting upwards as well, they certainly have the cash for it!
One thing that nobody has mentioned yet is the time it takes Maas to write her books. Typically she had a new release every year earlier in her career and every two years more recently. Hopefully, with the current success she can whip out the next 6 books in the next 6 years!
If anyone would like to ask Graham Neary or myself any investment related questions.
Then please feel free to login here tomorrow morning at 9.30am.
Everyone is welcome.
Thanks for notification re MicroSalt (LON:SALT) news, which ii failed to tell me about! Wondering if that is the main reason for rise in Tekcapital (LON:TEK) or whether that's due to 2 major shareholders increasing holding or news today about Guident (which ii did divulge).
"Guident Ltd, a Tekcapital portfolio company, and a leading Autonomous Vehicle (AV) teleoperation monitoring company announced today that it will integrate its industry-leading AV remote monitoring, control, assistance, and passenger support services with the world's most compact and flexible level 4 autonomous shuttle, MiCa from Auve Tech. Auve Tech is an Estonia-based company that specializes in the development and manufacturing of autonomous transportation systems.Auve Tech's MiCa vehicle provides turnkey, autonomous transportation with integration for diverse environments coupled with fleet management software. By working together, the groundbreaking MiCa shuttle will now incorporate Guident's teleoperation solution, further enhancing its safety and Auve Tech's leading, self-driving technology. For each vehicle outfitted with Guident's technology there will be a hardware fee and a recurring license fee."
Meanwhile price of Belluscura seems to be creeping up since your comment on Tuesday.
I hold Tek. Not for the faint hearted.
As I understand it the Microsalt holding is worth more than the entire market cap of TEK so the rest of the holdings are in for nothing. As you say not for the faint hearted but clearly does have a multiple upside if it works out. I hold.
I sold Tek 5 or 6 months ago. The constant fund raising even though they had quoted investments they could have sold, poor communication other than how everything was great. Would not touch it again.
I would have been very disappointed if they had sold their investments early Charles! I've taken the drop in share price as an unbelievable opportunity to more than treble my holding - in this for the long term but might take something off the table soon.
Roger- I hope it goes well-I mean it. But no longer for me.
Pure speculation as usual from me perhaps!!I do play a few US listed smallcap pharma companies, for fun still as i can't give up a bit of volatility addiction still and due to much better liquidity than AIM listed ones and i don't hold Renalytix (LON:RENX).There's been a real run in Spdr S&P Biotech Etf (PCQ:XBI) and small cap pharma m&a recently.Investor's Chronicle mentioned the big pharma patent cliff about a year ago i think.And they are competing and buying like mad currently.
Not 100% sure.But i think the Renalytix (LON:RENX) US ADRs had a lot of the unusual volume the previous few days underlying the volatility.The shares in the US were under a dollar (which involves a delisting risk for US shares i believe).Perhaps they were heavily shorted, like many US microcap pre revenue pharma companies, and some US longs smelt an opportunity for a while there.
As you are interested in US small cap pharmas, PureTech Health (listed in UK as well as US) might be worth your due diligence if you have not already done so, as it has a strategy which seems to have worked OK up to now. I have a small investment in the company and am waiting for the 2% royalties to start from KarXT if the drug proves to be as successful as some people think. Perhaps this company might almost appeal to some value investors, which is quite unusual for a smallcap pharma. There is an up to date (and long!) slide presentation on the company's web site.
Bank of Georgia (LON:BGEO) news I missed as was mid morning
Looks like they have regional aspirations with what appears to be an imminent transaction of a leading bank in Armenia. Interested to see what details emerge here.
Water Intelligence (LON:WATR)
does the chairman licence the ip to the company still -ie they or their company owns the ip ? cant remember exactly what the deal was in that regard ?
what % of profits exits the door to buy back franchises? is this small beer? - one would like to think flow of money was into then company from franchisees not out the company to franchisees - hey it is what it is though - if they splash the cash and get all the future profits i am not saying that wont work.
although all the trends look good ref profits it does strike me that profits seem to get eaten up somewhere as costs - i guess growth dont come for freemor paying of franchisees doenst come for free.
Finally i am trying to understand how this could have ever spiked up to 1250p
one would hope if they are "investing for growth" that pot of gold at the end of the rainbow would kinda be within grasp by now ? - keep an eye of broker forecasts for evidence in real ramping up ref profits perhaps?
does anyone else wander if this might be lifestyle business for directors ?
i might have bought but when i looked previously but i wasnt convinced that investors were obviously the main beneficiaries here - that was cleary poor thinking ojn my part when price rose to 1250p - so perhaps its cheaper again as peeps like me dont quite get it or wont get it till we can touch thatn pot of gold.
rmillaree I had an interest in Water Intelligence (LON:WATR) some years ago as liked the franchise model and layering of national insurer contracts over the top. The profit growth rate was also in the 70-80% growth region. Strategy changed to buying in the 'underperforming' franchises and the profit growth was only 13% this year and according to Stocko forecasts is due to be c15% this year. Perhaps that helps explain the decline from the stratospheric 1250p to current 378p share price?
The boss also likes to blow his own trumpet in the longest and, IMO, least helpful statements. I still keep an eye on it as the idea of Leak Detection seems a great area to be in.
I've taken a small stake in Ondo InsurTech (LON:ONDO) instead as all their contract news seems really positive. Early stage and still burning cash at the moment though. Spin out from Homeserve before they got bought by Brookfield. They still have a 16% stake by the looks of it.
Not disagreeing there, but the simple calculation, dividing GDP by population, ignores the question of what would have happened to GDP without immigration? It doesn't allow you to say that immigration has reduced per capita GDP because of immigration. Given skill and labour shortages it's quite possible it would have dropped futher without the impact of immigration. There have been plenty of studies that suggested that, while were in the EU, EU immigrants/temporary workers contributed more on average to GDP than the indigenous workforce. That may still be true now they've been replaced with non EU immigration, or it may not!
I had a poorly timed purchase on Close Brothers (LON:CBG), but thankfully sold out within a day or so of the FCA announcement (down about 10%) as I could see that Close Brothers had paid a lot of commission payments over the years and had a red flag contingent liabilities note in the prior year accounts. When I looked, I think I came to the conclusion that the banks primarily impacted are those with a material commissions paid line (a few years back) on their income statement. So unless they are hiding it Secure Trust Bank (LON:STB) and S&U (LON:SUS) are less materially impacted than Close Brothers (LON:CBG). Anyway, this just underlines to me how risky it is lending to anyone - banks are always on the end of regulatory action for wrong doing even if they comply with existing legislation at the time. I've never been a big fan, but will steer clear of banks in the future and only have a couple of very small positions now. Close Brothers (LON:CBG) did have an excellent long-term record, so acute pain can be experienced by even the best in the banking sector. This is their second error in a few years though with a big hit on a litigation finance loan book. They call themselves a merchant bank, but that is not really a good description of their current activities.
Today’s ‘wisdom’ - Poolbeg Pharma (LON:POLB)
https://x.com/mojomogoz/status...
Harsh ;)
Love him or hate him he has made money for early investors and the businesses have not ended up as just hot air and hype, they have been good solid profitable companies. Both Amryt Pharma and hVIVO (LON:HVO) are very good businesses, highly cash generative with good moats and business momentum.
However, I can understand why his hyperbole and promotion style irritates some investors. If you were a buyer of hVIVO (LON:HVO) around 40p whilst that promo was still going on I get why you might not be too amused. But in reality with the de-merger of Poolbeg Pharma (LON:POLB) today the share price is still some 31p equivalent, and it is a 5 bagger from the 6p acquisition price.
I’m not particularly keen on the style myself either (I know you hate it) but I am capable of recognising patterns and probable outcomes and that can make you decent money. I said a month or so back at 8p that I could see a story developing at Poolbeg Pharma (LON:POLB) as the ex Amryt pharma execs all returned to create 2.0 and that pattern has already started to play out. Again he’s been clever enough to make sure the business is well funded with lots of net cash - c. £15m so no need for dilution and plenty of deals to be done - that seems to be where he excels operationally. Personally I back him - but always early and never after any big spike and always with realistic fundamentals in mind. I do tune out the rhetoric though.
Jarvis Securities
I just noticed the share price has gone up by 40% today. This company was the flavour of the month in 2022 on this site but all has gone quiet now.
It would be appreciated if anyone has some insight here to share it with the long suffering shareholders!
Hi yadi,
"all has gone quiet now" on JIM?!
I flagged this morning in the mid morning movers section that JIM had moved up. Graham has since written a full section on it above.
We have also covered JIM (see our archive here) on:
14/7/2022
20/9/2022
9/3/2023
13/7/2023
10/8/2023
14/11/2023, and
today.
Paul.
Hi yadi, Jarvis have a good website HERE that gives among other things dates of announcements so you can do what Orval and I did and put your alarm clock on. We were discussing JIM from 0715 and included WH Ireland revised divi forecast and you would have had time to put a limit buy on.
Recession was highly likely given the inverted yield curve. This is a global phenomenon (Japan also in recession now) and the sooner the world goes into a recession, in my view, the better. Not because I am a doomster, but the sooner we have a, hopefully mild, recession then the sooner we can have a bit of a reset and look forward to better times on the other side. Recessions are normal...we just haven't had one for a long-time other than the Covid-19 short sharp shock. The real question is whether its going to be mild or deep? I don't think we will know the answer on that until the US bubble pops or deflates slowly. At the moment its looking mild.
In the UK there has been some very poor commentary on this months inflation number which was encouraging, but largely irrelevant. The important months are Feb, Mar, April and May as the 1m numbers last year were 1.1, 0.8, 1.2 and 0.7 respectively......that is a very lot of inflation dropping out of the number at the same time as gas prices falling-off the end of a cliff (down 52% yoy). Inflation could be well below 2% in May. So, we will have a recession and very low inflation. That will likely lead to interest rate cuts being an almost certainty, barring the US going the opposite way and messing the rest of the world-up.
Had to smile at this response from AJ Bell as to why UNBOUND (Hotter shoes) which has delisted but was still appearing in my portfolio at a price of 0.5p per share:
This stock will not be removed from your portfolio as it is not offically deemed worthless. This could potentially hold future value if it relists on a HMRC recognised stock exchange therefore we can not remove this from your account.
Strikes me this is definitely the triumph of hope over experience!
BMY.L RE the discussion yesterday eps forecasts for y/e 28/2/24 have been raised to 46.4p by Investec and 45.2p by Numis but both have left 2025 EPS forecasts unchanged at 32.2p. FYI
Bloomsbury Publishing (LON:BMY)
Find it difficult to believe that next years EPS will fall by close to 30%. I have no idea what it will come in at and a lot of water passes under the bridge in 12 months, including I suspect an acquisition. I can't imagine the £39m on the balance sheet, which is going to increase will remain idle for a year. Time will tell!
Bloomsbury Publishing (LON:BMY) Projected revenues from different reports are for 2025 £283m and for 2026 £293m. That’s the reason EPS will fall. I am not claiming that this will be the case. I don’t know.
Bloomsbury Publishing (LON:BMY)
Find it difficult to believe that next years EPS will fall by close to 30%.
any confusion here is odd.
Does anyone know if there are any brokers updates from yesterday onwards confirming current expectations for 2025?
I would like to think something has been published ref 2025 "based on yesterdays info" and we really need to use that as yardstick. If that confirms 30% fall is expected then you had better believe it unfortunately in absence of company saying anythig to the contrary albeit that might be ultra conservative.
Ideally you need to know if that 30% fall is real and "up to date news" if it is and you doint have explanation as to why perfect fodder to throw email to company and see waht they say.
Note i could easily see scenario where there has been huge surge in popularity of one of their stars - if that person is selling all their books right now to all and sundry you shouldnt necessarily expect that spike in sales would last - it might very well do but i could easily imagine there woudl be peaks and troughs here that follow fortunes of their stars.
Companys hould not really be leaving a void though ref 2025 - albeit as its still "next year" as we speak they are still in current year mode mostly. so perhaps teh timing of tehn update has lefta mini void? Would be odd that if eps was expected to reverse that price is shooting up - so no idea what the reality is here. If 30% eps decrease is real and confirmed to the market i suspect spike up may not last too long.
Hey ho that may be oportunity for us on the sidelines who have missed this boat if that is the case - to me even if there is drop in earnings that wouldnt necessarily mean management are doing anything wrong.
Bloomsbury Publishing ( LON:BMY)
Numis yesterday upgraded their FY24 to £46.8m and EPS 45.2p (from £37.6m and 36.2p)
Their forecast for FY25 remains unchanged at £35.8m and 32.2p
FY25 forecasts remain unchanged largely due to lack of visibility on next Sara J Mass book release
Bloomsbury Publishing (LON:BMY)
Ok that does make complete sense - in that context its slightly surprising to see shareprice shootup (unless peeps havent twigged about the expected reduction in profits) , having said that holders should kinda expect lumpy stuff so with unknown future concentrating on good current stuff aint totally illogical - possibly pretty logical , albeit i tend to exclusively look ahead myself.
I always remember when i first bought IG group (LON:IGG) (1 out of 1 so far) i didnt realise they tended to be pretty conservative ref future years numbers or numbers at start of the year - so i sold out on expected drop in earnings (think it was 30% frokm memory coincidentally) - at the end of year earnings might have been down but they did much better than forecasts the they had at the start of the year. Having watched them since i see repeat pattern of conservatism with them.
Tricky bit with each company is working out whether they start each year glass empty , glass half full or glass rammed full - note sure if long time holders have an opinion in that regard (are you reading this abtan?).
In the absence of indications they are conservative i would tend to expect what they promise so that takes a minor shine of the numbers from my viewpoint - albeit it clearly looks like they may be omitting potential income - so it sounds like their glass is more empty than full (i like that normally)
It does possibly though indicate how much of an earner their mega bucks stars are - if we know Sara is delivering in buckloads i would be pretty sure she knows it too! - hopefully she is cut from the same cloth as Ms Rowling ref loyalty rather than Miss Swift (being honest i like how TS dealt with scooter braun - i suspect he may not have been loyal to her in which case dont expect loyalty back)
Bloomsbury Publishing (LON:BMY)
"Find it difficult to believe that next years EPS will fall by close to 30%".
I remember a similar situation with another company - i.e. current year just ending above market expectations announced at preclose. The house broker (I think finnCap now Cavendish) was one of those that made reports available to PIs and so I could read something along the lines of "we are upgrading our forecasts for the year now ending but will not review next year until the company's preliminary announcement".
I suspect BMY's house broker Investec may have said something along those lines but it is one of those brokers for whom, as Paul put it, PIs are pond life.
No doubt Investec are proud of this headline:
With 86% ownership, Bloomsbury Publishing Plc (LON:BMY) boasts of strong institutional backing
BBC News - Pryzm nightclub boss blames lack of students for closures
https://www.bbc.co.uk/news/bus...
Interesting read across to a few companies such as Revolution Bars (LON:RBG) and XP Factory (LON:XPF) .
Personally I'm glad to not be involved with the sector.
On today's Today programme discussing the problems of the nightclub/hospitality sector, a girl one year out of uni was saying that pre-loading was now the norm for students, and that they would frequently only pay an entrance fee to a club, and buy no drinks at all. More shift from on trade to off trade. Bit different from back in the day...
In my university days (a long time ago now) we would both pre load, and drink at the venue where the drink prices were very cheap. I wonder how cheap drinks are on a student night out currently? If they are normal prices then students won't touch them.
perhaps you are getting old grumpy? - i suspect pre loading has been the norm for 10-15 years plus !now ! im too old too have been doing that research 10-15 years ago.
Exactly, pre-loading has always been the norm, even back in my days 15-20 years ago.
The big difference is three shifts I think:
Cost of living just accelerated the decline in the past 12 months, otherwise it could have been a slow, managed decline. Instead, the industry definitely needs to right-size, quickly, so that the remaining players can have critical mass and be profitable.
Also internet dating. In my youth, if one was single you usually had to go out clubbing to meet people, nowadays you really don’t.
On balance I am happy I was young and single then and not now, but all older people think that.
Ah you are reminding me of halycon days Matt when I was clubbing on hot summer nights late nineties early noughties awesome memories
I often say to my to son's who have started getting interested in online dating, back in my day if you approached a girl you had to be ready to take ---- off to your face.
Boon you were obviously thrifty even then! We never went near the clubs apart from when they ran Student Nights with the beer at special prices. Most socialising was in Uni bars/concerts - with great bands that were breaking or already in the charts. Has that scene disappeared?
Would hope most students have more sense than to do the expensive weekend club scene. If they can afford it they are not proper students! If clubs are relying on this demographic they deserve their demise. Target those who can afford it.
I confess I have a bus pass! I guess the other difference from my uni days is that if you want to get off your face, class A drugs are widely available. I don't regard that as progress!
Apologies for age misappropriation here I kinda presumed you were 10-15 years younger than me rather than older.!! Anyone over 35 is out of the loop nowadays ref the youth
.
Morning Paul. Thanks as always for all of your output. I have just listened to last weekend’s podcast and wanted to follow up on one item. You rather dismissed Futura Medical (LON:FUM) on the basis that their product doesn’t work. You encourage us to put forward different points of view so here goes.
Futura Medical (LON:FUM) main product Eroxon got clearance last year from the FDA for sale as an OTC product for erectile dysfunction. The FDA asked for an additional trial, after previous clinical trials had satisfied European regulators. Whilst the product does not work for everyone , trials and feedback are suggesting it works for about 60 per cent of users.
Recently Futura Medical (LON:FUM) appointed Roy Davi’s to their board. His track record at different companies includes: Optus : bought by Nikon for a 30 pc premium to shareholders;Gyrus: bought by Olympus for a 58pc premium; and recently Medica: bought by private equity last year for a 33 pc premium. Because of this there must be a reasonable chance that Futura Medical (LON:FUM) will be set up for a takeover at some point.
trading update last week showed 3 million revenues from initial sales in 2023 following soft launches in Uk. They have taken 20 per cent market share which has exceeded expectations and are now rolling out in ten countries before April 24.
Haleon have been appointed for US distribution and will be paying 4 million dollars to Futura Medical (LON:FUM) in 2024 . Haleon are a big global outfit with brands such as Sensodyne Panadol and Advil. We are waiting to hear of US launch date but no doubt Haleon are setting up the necessary infrastructure for distribution and marketing before launch. The erectile dysfunction market is huge and if Futura Medical (LON:FUM) can get a fraction of 20 pc in global markets prospects look good. They reported a 58 pc margin in the trading update last week.
Then yesterday it was announced that Eroxon will soon be available on prescription on the NHS ( in addition to current over the counter availability in Boots and elsewhere). The bar is high to getting prescription status and regulators like NICE want good evidence of safety and efficacy before approving things. This announcement gives extra credibility as well as extra sales and my view is that there is little downside this year for this share ( company now has 7.7 million in the bank) and a lot of potential upside.
I will add that I consider myself a novice in terms of investing but do know something about health research, clinical trials and placebos.
Thanks.
I am 100% with Paul on this one Futura Medical (LON:FUM) and I believe that when we mention different companies and different acquisitions we have to be transparent and know all their price history(not just the premium paid on that certain day the acquisition was announced) and especially the aftermaths of all these acquisitions.
Some of the names you mentioned here were involved in one of the greatest Japanese frauds in recent history and I will not comment further in this subject.
For those choking over their corn flakes on reading the news brief about the sale of 117 properties:
* Home Reit (LON:HOME) GROSS PROCEEDS FROM SALE PROPERTIES ARE
£1.02M
The full quote should read PROCEEDS FROM SALE PROPERTIES ARE
£1.02M below the draft August 2023 value.
The actual sale proceeds from yesterday’s auction of 117 properties from this severely damaged REIT were £5.6m with further properties being auctioned today.
(I stupidly still hold and can’t sell as shares suspended)
HOME REIT
This is Money quoted as saying.......
"Home REIT suffered another blow in December when property group Jones Lang LaSalle (JLL) – which it hired to assess the value of its portfolio – concluded that its properties were worth less than half what they cost to buy."
This should be fairly easy to reverse engineer and to find out exactly why this happened.
Dont hold.
Home Reit (LON:HOME) We already know why this happened. It was revealed in the report by Viceroy Research. And of course we also know what, when, how, and where. Who is perhaps still an open question (but not in my mind). The board said 'Not us guv' and blamed the investment adviser, Alvarium.
If I was a regulator I'd try and get a few handcuffs on, but I'm not, and there won't be any handcuffs which is a pity because it's severely damaged the involvement of the private sector in social housing. On the other hand, I always thought that anyone trying to make money out of letting residential accommodation, whether purpose-built or re-purposed, to so-called "charities" and "non-profits" who then sub-let to tenants whose inadequate rent is paid by local authorities is misguided, ignorant, or in the case of someone raising outside capital something worse.
Yes - Viceroy have done some very good research here. No doubt about this. Quite incredible that the HOME board should have dismissed this report out of hand at the time.
From the Viceroy report it is suggested that one property in some portfolio acquisitions was grossly overvalued. Also suggested that the portfolio was valued on income yield basis.
I think my point was that someone will have had to authorise these valuations. Who??
Yesterday's RNS confirmed the FCA are finally investigating:
Home REIT plc (the "Company") has been notified by the Financial Conduct Authority ("FCA") of its commencement of an investigation into the Company, covering the period from 22 September 2020 to 3 January 2023. Naturally, the Company will cooperate fully with the FCA in its work.
RE: HOME
Sorry to hear from holders here who are stuck in Limbo. I have no skin in this particular game but have followed this for a number of reasons.
I would guess that rent collection will be an ongoing problem for a while as a number of the intermediaries who are contracted to HOME have gone into liquidation/administration.
As I see it, these contracts will have to be legally terminated and the properties contracted to new partners or sold.
From various reports, I would guess that substantial refurbishment will be required on some of the portfolio. Annoying, but this could also extend the timescale
Now as the dynamic and ever vigilant FCA have taken control we can await developments.
Over a year in and monthly reports are still reading:
Rent collection including arrears representing 10% of rent invoiced during the month.
One year in and that's the best they can manage!
Like xerxes, I remain an involuntary holder - should have sold the bad news.
Many thanks to Whitbourne for his very interesting response about my post yesterday on Bloomsbury Publishing (LON:BMY) .
I find the whole story on how the Harry Potter stories so nearly never saw the light of day quite fascinating.
I see Bloomsbury Publishing (LON:BMY) is up again this morning. I do not hold.
That reminds me, several readers yesterday claimed some StockReport data on Bloomsbury Publishing (LON:BMY) was incorrect. I don't think that's right. The reason it shows EPS forecast dropping, is because the forecast for FY 2/2025 was lower than FY 2/2024. So people need to check the definitions, if it has "(f)", it means forecasted. Or just click on the link for each term, to see how it's calculated.
I see that the FY 2/2024 broker consensus forecast has updated overnight, and is now a barn-storming 45.8p! (my guess was c.40p), so this adds further fuel to the bull case I think. As I complained yesterday, it's appalling that this price sensitive information was slipped out to institutions & HNW investors by premium brokers (who get inside information from companies), and we were kept in the dark until 24 hours later when the consensus numbers are forecast. This whole area needs a regulatory investigation, as it's clearly unfair, and could be illegal in my view - as the rules are that price sensitive information has to be disseminated to everyone at the same time, but we all know that doesn't always happen.
The FY 2/2025 forecasts for BMY don't seem to have moved overnight, so at 32.2p this now assumes a 30% drop in EPS in the new year that starts in a few days. That seems unrealistic, but this is why the StockReport now shows forecast EPS dropping close to 30%.
Therefore, to clarify, it's not a data error, as some subscribers wrongly stated yesterday.
Regards, Paul.
This whole area needs a regulatory investigation
can you (or we all) complain to FCA on the basis there is less transparency here than we get with regard to the kickbacks car dealers and insurers get from "preferred"finance partners when selling car or insurance policy - they see fit to take action in that area so action here would be appreciated as there if often nil transparency on then "official updates"
Chuck in that you would like to think they wouldnt wait five years twiddling their thumbs before they decide that for the last 5 years investors have not had transparency the they should have had - specifically with regard to managment and brokers both agreeing new changed "expectations" and that financially sensitive info is only made available to the select few "insiders" and their "frieeeeeeends" whilst not being made clear to the market in timely fashion , and that info is drop fed by the "frieeeeeeends" at a time when it suits them.
The fact that a decent % of companies are mostly transparent highlights that at a minimum there are a hard core of companies clearly not being transparent on their rns releases. Copy 3 or 4 of Saga's trading updates (and last update from Bango) and compare to change in broker expectations soon after / at the time and it will be clear some companies are simply not telling us how it is and are relying on sneaking broker updates at random times later to get the reality.
I think I remember Graham sugggesting that Close Brothers (LON:CBG) was one of his preferred bank/ financial choices. Given it is down another 15% this morning, then any view he can give would be great. Obv. There is a lot of uncertainty given the known issues around vehicle and car finance.
Close Brothers (LON:CBG) And I don't think the article in the business section of todays TIMES has helped!
CBG
This share is now a binary option! I believe the market prices it for bankruptcy and it will either be worthless or taken over or bail out by the shareholders when they need a massive equity raising.
It may however, survive and in that case it is a bet which may pay off. For now, I am neutral and not adding to my big losses.
Other banks and insurance companies are also involved and they may take it hit. That is why Terry Smith does not invest in Banks of any sort.
Definitely 'punt' territory for the time being i would say without the company knowing the full quantum of the situationSurely it would be much lower mcap if the market was even smelling the start of bankruptcy risk?However, i would assume a few funds including divvy funds are forced sellers now..?Could be a Jarvis Securities (LON:JIM) a few months or later down the line..Might not!
The management have done a poor job. Hopefully CBG will be taken over by a company with a better understanding of banking and broking!
Poolbeg Pharma (LON:POLB)
It looks like Cathal Friel will be using some of the money he has made from his sale of hVIVO (LON:HVO) shares to invest in Poolbeg Pharma (LON:POLB) . He is also moving from non executive to executive chairman all of which has had a positive effect on the share price first thing this morning. (I hold both).
Jet2 (LON:JET2)
I hold.
Pleasing update. Straightforward and comprehensive; management tells it as it is. No dancing around the edges. My preferred share in the travel sector and in my view remains underappreciated.
Hadn't expected to be right quite so quickly after debate on hVIVO (LON:HVO) but all now becomes clear and as I suspected.
Cathal moves to be Exec Chairman of Poolbeg Pharma (LON:POLB) and intends to invest there - It is basically the old Army pharma execs aiming to achieve Amryt 2.0 so that has become his focus and explains the partial exit.
This is consistent with his M.O so that leaves me not concerned at all for my investment rationale in hVIVO (LON:HVO) which remains in tact. Mo Khan is excellent in my view, very non promotional and with good business momentum.
Spot on yesterday davidjhill. Very happy to continue to hold both Poolbeg Pharma (LON:POLB) & hVIVO (LON:HVO)
Gattaca (LON:GATC) - "Profit expectations maintained" (new research report here: https://www.equitydevelopment....)
We are encouraged by several aspects of the pre-close trading update covering H1, not least the outcome and movement in net cash. A renewed focus on the cost base should result in improving conversion rates, offsetting any further shortfall in fee income during H2. We also remain confident that a recovery in Gattaca’s markets should emerge during Q4 ‘24/early FY25 supporting a further re-rating of its shares.
The yoy shortfall in NFI of 16% during H1 includes a large RPO contract which ended in September. The H2 ‘23/H1 ’24 comparison is as a result more favourable, with the larger contract included for just two months of the former period, with fee income down 8.6%. Overall, contract NFI was more stable, declining 6% yoy, compared to 38% in perm.
H2 ’24 onwards will witness a greater focus on productivity, resulting in outgoing sales heads in the business not being replaced and further room for cost cutting within perm focused employees. Over the medium term, we expect administration headcount as a proportion of total heads to move towards best industry practice of c.25%, down from the current 32%.
Should we be proved correct on expecting a recovery in the Group’s markets then the current valuation appears too low. Based on a DCF model we retain our fair value / share at 175p.
Hi gents - will you be looking at Gattaca (LON:GATC) today? It’s market cap looks to be at just above cash and on on about 1 months revenue!
Gattaca (LON:GATC)
A very low operating margin business (about 1%) and market cap is £40m and cash £22m with estimates to fall in 2024/2025/2026. I wouldn’t say the market cap is just above cash.
However , Gattaca (LON:GATC) pays a dividend and buybacks its shares.
All the best
Gattaca (LON:GATC)
A very low operating margin business (about 1%) - Yiannos1
Over the medium term, we expect administration headcount as a proportion of total heads to move towards best industry practice of c.25%, down from the current 32% - Equity Development
These two observations are not unrelated! They demonstrate that GATC is less a value added recruitment firm and more a very low margin seat and form filling operation. There is no moat built on consultant skill or sector specialisation. They can be discarded for the first firm to come along with another 10bps cut in margin. And I’m afraid that the second comment tells you how little Equity Development knows about the industry it is commenting on. Best practice is to have admin below 10%.
Might be a good trade in a sector rebound but why take the risk when the top names are at half peak values and much better embedded in their markets.
Morning Trendz,
I'll see how we get on with the other stuff on our list, and if there's time we might have a quick look at Gattaca (LON:GATC) , I see it's in line. Chart seems to be in a gentle up-trend, and I like the balance sheet support.
Regards, Paul.
Thanks, Paul!
Jet2 (LON:JET2) raises profit guidance slightly and sounds positive for summer '24 with more higher margin package holiday customers. I hold. Cheap p/e with a load of cash and a star of Stocko's multibagger research.
Another good thing about the Jet2 (LON:JET2)’s RNS is that they give their own clear guidance. So many companies hide behind their paid analysts’ forecasts and many don’t even say what those third party forecasts are. We all know that the analysts’ forecasts are given to them by the companies so why not save the analysts fees and just tell the world yourselves. Many good companies (such as Jet2) do exactly that. The pretence that analysts’ forecasts are independent doesn’t work anyway. Share price are still hit when companies issue profits warnings
And the guidance is good. A quality business. I hold
Jet2 (LON:JET2)
Must admit i like what i see here ref quality of management and i can be a picky old sod , more the fool me for sitting on the sidelines hoping there might be a mini pull back after price climbed to 1200p - the reality is it looks cheap to me at today price. My only real issue here is more with sector rather than company in that most purple patches in travel dont last forever so discount is kinda needed off pe when times are very good - however its not as if pe of under 8 is expensive even if you add 30% travel premium risk - particularly when you factor in their record of goods consistent growth - reminds easjet in the earlier days when they had simple plan of replicating work works on bigger scale each year withot any fuss.
Apparently we are in a recession, I suppose the Governor of the Bank of England will be pleased now.
Recession ?
I’m always surprised by the nationwide obsession and focus on whether we are or aren’t technically in a recession as defined by a defined parameter
Eg we may have 0.1% growth , or -0,1% growth
One is headline news that “we are officially in a recession” the other isn’t
It doesn’t change anything really except sone economist and journalist can write some big words and make headlines .
Everyone else goes about running their businesses , dealing with problems , sorting customers out , Buying shopping , arguing with the wife , getting the heating fixed , getting ready for a 10 o clock meeting only to be told they changed it to 9 and didn’t bother to tell you
for me it us just totally utterly meaningless headline grabbing waste of energy .
I don’t particularly think businesses ever focus whether we are or aren’t in a recession and as Dave B says
“We can only control the controllables”
Morning planetx,
On a daily basis routine it doesn’t really.
But since we deal with stocks here , a persistent negative GDP ( i don’t think it is the case here) will affect negatively corporate profits and share prices.
Although most of the times this is already counted in share prices. I have experienced many stock market rallies as soon as a mild recession was official!
Yiannos
I’m not so sure the effect on small caps is much
My point is the actual tipping into “recession” is just not relevant it’s. Headline grabbing that’s all
And if we go to plus 0.1% is the next headline “we’re out of recession”
Markets are tough everyone knows that but equally defence sector is red hot and bicycle market is in a huge recession .
Anyway never bothered me in 30 years and good companies see opportunity in adversity .
You are right that there is little difference between +0.1% or -0.1%. The problem the country faces is that the economy is not growing. If you look at the statistics on a per capita basis then there is a decline because of the high level of net immigration.
Can you elaborate further please on your argument with exact figures and the damage net immigration does to the UK’s GDP. Please include figures of net legal immigration and the negative contribution to the GDP (for example a foreign student that studies here and stays and works here or a foreign doctor that works for the NHS and makes his life and future here). I personally know at least 100 of these people-they are lawyers-doctors-bankers-accountants-businessmen-they bought houses etc etc etc-they even own one of the biggest hotels in Manchester etc etc etc.
Do not include illegal immigration (that’s illegal it’s wrong and something should be done about it).
Thanks
the reality is many tradespeople who used to earn decent living say in the 90's were crucified when we opened up our doors to "the entry in eu" without any restrictions whatsoever - from memory other countries had temporary limits.
Note this was aligned with super generous tax credits and ability to even keep those kids back in the eu and claim for each kid and send that money back to the home country.
This might have been great for consumers able to pick up a nice quality refurb for cheap as chips cash prices.
However for these skilled grafters the almost unlimited amount of extra peeps turning up charging rates often at half the price and often milking the system (not all or even then majority) - destroyed the average manual workers salary over 2 decades. Anyone whom cant see thats what brexit was about is pretty much blind as a bat.
So i am all for free movement and i am all fro immigration provided we have enough houses.
But we did zilch for 20 years to protect the living standard of your average multio gereration manual worker. The best probably still thrived but not all manual workers are super buisness peps or super talented - thats not to say they dodnt deserve a decent crust when they are trying the best.
There is a reality that times change and its just tough you need to be better or you need different skillset - but it was too big an ask for one gerenation.
Thankfully some pricing power has returned to wages since covid - long may that continue but its clear fact millions had their hard graft that previously was rewarded by "average pay" them turned into something that was deffo "low pay2 or they could perhaps match working 16 hours max and claiming benefits as their.
Obviously there was always an element that labour rates would be depressed and peeps needed to understand that and if necessary retrain - however the free for was bad for a decent % of manual workers who resented other peeps turning up from abroad and their taxes from lower income being handed directly to these individuals.
Immigration can be good overall but boy did we royally screw it up for many hardworking brits by destroying their standard of living year aftre year after year.
Note whats bad for these peeps may have been good for the economy perhaps? - but i am far from convinced that taking peeps making decent income paying decent taxes claiming very little in benfits and changing that to system where wages were low less tax was collected more was paid out in benefits and wads of cash left the country to go to the eu to be spent there was good overall for the economy - all imho. Its hard to know how the alternate reality of no imediate mass free for all immigration would have worked out so i think its impossible to say if system we have used was good or bad without having multiple spiderverses.
Apologies for straying off topic peeps i wont post any follow ups here till market has closed.
An article about growing population flattering GDP figures. It doesn't specify the exact cause of the growing population, or who is funding the Resolution Foundation.
https://www.resolutionfoundati...
Can you elaborate further please (with exact figures) on the "at least 100" people you know? Please include figures such as wages, home ownership and shoe size. Please also show your working out. Thanks ;-)
I think Stevenlondon3 was simply making a mathematical point. I didn't see anything in there that could be construed as a criticism of immigration. If the population grows - be that through immigration or fecundation - yet GDP does not, then GDP per capita falls.
Mohammed El-Erian explained he problem in detail and the lack of infrastructure in the UK.
Worth to listen.
This.
The reason London is rich is _because_ it has a good mass rapid transport system.
The rest of the country does not and this govt have made sure the north is stuck with its victorian (and earlier) era infrastructure for another generation.
There was a study in the early 00's comparing Birmingham and Lyon (similar size, pop etc) - the GDP per capita in Lyon was ~20% higher. They worked out that the biggest reason was that the transport system in Birmingham was not good enough to reliably commute from one side to the other, unlike Lyon. It means that if there is a good job on one side of Brimingham and a good employee on the other, that job is not filled or not done by the best person. So business do not grow as they could and GDP per capita is lower than it could be.
I live a 1h bus ride from bristol. It is just about commutable (there is ~1 every 40m) that skilled person who lives another few miles out will not go to that good job he/she could do in bristol because they cannot reliably get there (even if they drove).
We are all poorer for a good number of really boring things like high house prices, poor travel infrastructure, lack of adult education and all that has v. little to do with any of the big political issues over the last 10+ years. but basic service provision / delivery is difficult and boring.
I do not see this changing (sad face)
Great post thanks.
I was watching the other day a live interview of two of the most successful investors of recent time.
Where do they invest these days?
In Infrastructure stocks!
The reason London is rich is _because_ it has a good mass rapid transport system.
I could not agree with this more. As a general point, but especially as someone who lives in Birmingham.
The reason why London has a mass rapid transit system is because it has 10m people https://worldpopulationreview....
Except as andrew said, other European cities of a similar size to Leeds or Birmingham, such as Lyon do have mass transit.
https://www.newstatesman.com/s...
Radio 4 World at One today (15/02/24) had an economist explaining the damage net migration does to the UK economy.
In summary, a larger working age population does indeed increase total GDP but that figure is divided by more people. The GDP per capita has been falling due to net migration and therefore we are worse off.
To have rising living standard from migration you need migrants on average to produce more output than the existing GDP per capita.
Nothing political in this - it's just basic maths.
hmmmmmm
if we take the viewpoints migrants are more likely to be 18-50 and going straight into work - they MAY be taking less out the syste,m than they are putting in compared to other peeps - imho if thats the case is that bad for the economy?
Ie on average much lower % of migrants are probably sucking it out of the system ref costs of bringing up youngsters if they are mostly not kids
much lower % of migrants are old and therefore less are sucking it out of the system ref pension payments and healthcare and social care for the elderley.
Surely for balanced picture you need to see what they draw from the state too - if they draw less from the state but earn slightly less imho that must be good overall as less taxes need to be paid by the entire population all other things being equal
Seems pretty basic that new peeps can turn up and earn below average but still add to the economy by paying more in taxes than they take out ie much smaller drain on the public purse - how is that a damage to the econmy if thats were the case
Obviously the wrong kind of migration where they are put up in hotels and not allowed to work and have few job skills will be a burden at least short term could flip it back.
Not sure what % of peeps suck more out than they pay in taxes but i suspect figure is potentially crazy high - so imho if we are importing people working full time claiming little benefits and not unduly upsetting then applecart for everyone else (ie taking their jobs !) -m i can see win win win situation being posible despite what this "economist" says.
Perhaps the economist is so blinkered that they perceive lower GDP per person on average as automatically being bad for the economy - perhaps thats where they need a lesson in reality ?
NET contribution of £43B last year to the British economy from legal migration!
It’s sad to read all this about migration without fully understanding it
It’s simple maths someone wrote and there are no numbers in their post-another one wanted to tell him their shoe size!
Average disposable income in the UK is £30,000. I personally do not know any migrant that earns less than this amount.
The UK needs infrastructure in the following:
1. Ports 2. Airports 3.Railways 4.Steel industry 5. Energy 6.Nuclear Power7.NHS 8.Transport 9.UNIVERSITIES (how can you expect a British born citizen to pay for the fees-government should provide this-it’s education and it should be free as in the long term the benefits for the government are more.
The private sector needs support from the government to advance AI and medicine.
Lack of infrastructure for the last 20 years that needs to be addressed as soon as possible.
It is basic numbers but I cannot see any numbers in your post.
Net legal migration contributed NET £43B in the GDP last year.
That’s net migration and net contributions.
I’m always surprised by the nationwide obsession and focus on whether we are or aren’t technically in a recession as defined by a defined parameter
Yep so true - probably the same with focus on house prices if they are down 5% its the end of the world and if they are up 5% its the end of the world.
I saw an interesting stat that left me slightly gobsmacked - the tat comes from Savills (so they might be talking their own book here) - in real terms house prices are (allegedly) now back at the level they were in late 2015 in real terms. I dont doubt that on multiple of salary many posh houses in nice areas are eyewateringly expensive still (thats bad) but if that stat is true its good to hear. Note if we have seen material house price correction downwards in real terms without most people noticing thats a real good job done - cant beat a bit of stability , we dont mind it being tough up in the north :). what happened back in 2008 where first peeps to lose ability to get finance were the builders and they shut up shop overnight putting hundreds of thousands of grafter out of work - that imho was probably the single factorn that made that recession worse than it needed to be - support given to fat bankers not the real companies employing workers that kepe the economy thriving (or ticking over)
in real terms house prices are (allegedly) now back at the level they were in late 2015 in real terms.
yup
Nationwide UK House Prices Index Adjusted for Inflation ['Real' Prices] (housepricecrash.co.uk)
about 30% down from the peak in 2006 and 10% down from 2015 (by eye)
about 30% down from the peak in 2006 and 10% down from 2015 (by eye)
wowsers that seems out of kilter with the perception that house prices now are ridiculusly high - perhaps the average of expectations ref first house purchase nowadays is not the same as the expectations back in our day (any 1 bedroom flat in sketchy location was a start back in the day) - i still want more homes built and for prioces to remain reasonable - best qualify of life improver having decent roof over ones head.
And our chancellor!
Phew, after Jarvis Securities (LON:JIM) (I hold) didn't pay a quarterly dividend in Q4 2023, the first time since 2009, we have a 1.75p dividend for Q1 2024. If that's static for the next 3 quarters, that's 7p. Analyst expectation for 2024 is a dividend of 9.1p (Stockopedia report). Even so, a 7p annual dividend would be 13.7pc yield. Not sure Jarvis Securities (LON:JIM) is out of the woods yet, but after a disastrous 2022 and 2023, at least we start on a positive in 2024.
Announcement below:
The Board of Jarvis announces that it is declaring a first quarterly interim
dividend of 1.75 pence per share, to be paid on 19 March 2024 to shareholders
on the register on 23 February 2024 and the shares will become ex-dividend on
22 February 2024.
Jarvis Securities (LON:JIM) up 18pc from 51p to 60p in first hour of trading.
Jarvis Securities (LON:JIM)
Yes, infinitely better than last quarter and should at last put a floor under the SP. Finals announcement on March7 when we might get more news of trading and FCA review. Skilled Person review deadline to FCA is end of Feb but that doesn't mean feedback to JIM imho, lets hope no more delay. Broker recommends a reduced dividend forecast for year of 8p this morning in spite of increased level of cash at interim. Seems a wise move until fog clears.
Well if the brokers are right about 8p, at current buy price of 65.6p, thats a 12.2pc dividend.
If the 2013-2023 typical earnings/dividend cover of 1.3 for Jarvis Securities (LON:JIM) is applied for 2024, that would be eps of 10.4p, so currently a forward PE of 6.3. Obviously that's just me putting 2 + 2 together, best waiting for final announcement on 7 March to see what the company says.
Bit of a shocker out of Close Brothers (LON:CBG) today; no dividend. I've steered clear of this one, it seems a bit accident prone. But there is a read across to other companies involved in motor finance....
If you look at the chart perhaps bad news is not so unsurprising!
The directors were selling at £6 too.
Close Brothers (LON:CBG)
i have sympathy for holders here - hopefully the strong warnings posted here in recent weeks have made some investors stop and think ref investments in similar companies. From rates paid by peeps i know to close , they have alywas been bafflingly eyewateringly high rates - that might even been for a plain annual insurance policy renewal being funded monthly.
I think its particularly poor form that the company may have had an inkling this was coming and has waited till now to drop the bombshell. I dont have any viewpoint as to whether this company is a good investment or not or whether they may come out of this with a clean bill of health. High rates themselves might simply be an indication they are able to charge premium as they take the risk others will not.
Hopefully this clean by the FCA will do a good job of putting the shyster operators out of business or getting them to change practices so that the honest providers can provide a clear and transparent service. Nothing intrinsically wrong with high rates as long as its all done with the highest level of integrity. Hopefully if lenders havent realised before now integrity probably matters they probably need to realise that fact now.
There is significant uncertainty about the outcome of the FCA's review, and
the timing, scope and quantum of any potential financial impact on the group
cannot be reliably estimated at present. In accordance with the relevant
accounting standards, the Board has concluded that it is currently not
required or appropriate to recognise a provision in the group's Half-Year 2024
results in relation to this matter.
Perhaps the fact they have not needed to make any provision now might perhaps mean its not as bad as it seems - but i dont really have an opinion as to whether this is really bad news or a blip on the radar.
Practicably speaking the danger here is probably almost identical to the "insurance cover" rip offs that used to be in place when peeps bought goods from pc world etc . the reality is it was a cash making machine for both parties with the actual cost of the cover bneinhg provided probably being peanuts.
If close have a customer who has just bought an insurance policy and that insurance company only recommends close and its not clear what kickback insurance company gets from passing on that captive customer base i supect that ultimately more transparency may be needed even if they are not breaching FCA rues as things stand. Practicably speaking a very minor tweek in FCA rules could really hit their biggest margin earners if the customers would take exeption to insurance company earning hunderds on top of insurance price they are already paying - hear no evil see no evil situation.
Note my above thoughts are somewhat pure speculation and may be wide of the mark- this could perhaps all be a storm in a teacup.?
One of the many strengths of Stockopedia is the healthy debate & refreshingly candid comments.
So in the spirit of ‘throwing more fresh steak’ into the flying pan - it’s maybe worth active stock pickers once again stepping back and considering the value presently offered by UK smallcaps (see PEG chart below).
Indeed as bond yields have climbed over the past month in line with sticky services & wage inflation. One could (perhaps controversially) argue that this unloved sector is even cheaper now than it was at the start of the year (ie in relative terms).
Problem is if you drill into individual AIM companies, at least one person on here will probably be able to articulate clearly and fairly why the price is what it is. And should we not find a person who can, I’d wager we’d find an overvalued share for every undervalued one. Size/liquidity factors alone may cause the valuation of smaller companies to persistently fall short of the comparators you’ve chosen in the bar chart. So not personally convinced the sector as a whole is that much cheaper than it should be.
Excellent post and something that appears cheap on yesterday’s balance sheet if it doesn’t grow (most don’t) then tomorrow’s balance sheet will probably make it overvalued.
In my mind we need to be watching for structural changes Paul. The move to cancel LTA for Pension Funds was positive. I hope a new Labour Govt will see the light despite saying they will reverse it. I think a significant increase in SIPP allowances will also assist. We have to get capital working again. Thanks for the post very revealing.
My pleasure Camtab - thanks
Complicated.
if the legislation is enacted, I have the feeling that even if lab win (betfair indicates a 150+ lab majority) they won't repeal. Mostly because there are a tonne of highly experienced NHS consultants over 55 who will be really angry and some will just leave and retire (yes they will have protection as will all high earners).
What you really want is the undoing of the last 30 odd years of pensions legislation and accounting standards that have pushed collective pension funds to sell equities and buy gilts. I don't see that happening either. Not least as while you are running a deficit it is handy to have forced buyers.
Also I don't see any political gain in raising the annual allowance and a lot of anger if they try to reduce it.
TL:DR; I expect and hope that nothing much happens in pensions for as long as possible. Things are bad enough already.
OI kind of agree except a reintroduction of a lifetime limit set at a sensible level might appeal to most politicians other than certain members of the blue party.
Everyone loudly shouts that the Nasdaq and S&P500 are grotesquely overvalued but by your chart above the PEG is basically the same as the FTSE100. I know I'd rather have the S&P over the FTSE100.
Stocko on the homepage reports that the average EPS growth forward is 16%, from the aggregate of all the broker forecasts, for AIM100.
However, that does seem quite unrealistic? Say if we take 10% instead of 16% as more reasonable, what would the PEG of AIM100 be then?