Small Cap Value Report (Thu 15 July 2021) - ALU, GFRD, JIM

Good morning, it's Paul here today with the SCVR for Thursday. Jack's busy with other things today, so you'll have to put up with just me.
Disclaimer -
A quick reminder that we don’t recommend any stocks. We aim to cover trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research) - don't blame us if you buy something that doesn't work out. Reader comments are welcomed - please be civil, rational, and include the company name/ticker. If you're angry about anything, don't leave a comment here, nobody is interested, put it on Twitter instead if that makes you feel better.
Timing - TBC
Agenda - everything by Paul today
Alumasc (LON:ALU) (I hold) - another strong trading update for FY 06/2021. Outlook comments mention possible supply chain problems, as many companies are reporting at the moment. Note there's a pension deficit here which sucks out a fair bit of cashflow each year.
Galliford Try Holdings (LON:GFRD) - a mildly positive trading update (towards upper end of analysts forecasts, with a footnote provided!). Cash is above market cap (although outweighed by creditors). Order book strong. Tiny profit margins though, on large complex projects.
Jarvis Securities (LON:JIM) Interim results - readers asked me to look at this, and I love it! Strong results, broker forecast goes up 15% today, divi yield over 5%, and on a PER of only 16.6, which seems good value for such a high quality, growth company. A big thumbs up from me.
Alumasc (LON:ALU)
(I hold)
274p (last night’s close) - mkt cap £99m
Alumasc, the premium building products, systems and solutions group, provides a trading update for the year ended 30 June 2021, ahead of publishing FY 2021 results on 7 September 2021.
How about this for a nice chart? Is it getting toppy though?

.
Here are my notes from the last (positive, ahead of expectations) trading update on 13 May 2021.
- Strong Q4 (Apr-Jun 2021)
- “...demand & margins holding up well in the final quarter”
- Revenues for FY 06/2021: £90m, up 18% on LY (last year)
- Underlying PBT (profit before tax) “ahead of the Board’s previous expectations” (I wish companies wouldn’t use the word “previous”, as it can be ambiguous)
- Growth achieved in all 3 divisions
- Resilient construction market
- Gained market share
- Cost price inflation has been successfully passed on to customers (a key point at the moment)
- Cost control & restructuring last year have boosted profits
- Levolux turnaround has worked
- Net debt almost eliminated, was £1.0m at 30 June 2021
- Bank facilities of £24m extended, to April 2023, and hints at acquisitions possibly?
VAT arrears - I don’t understand this, as it seems contradictory - but not a material figure, so doesn’t really matter -
VAT deferred under the Covid-19 support scheme was repaid during the year, with £0.7m outstanding at 30 June 2021, which is due for repayment in the first half of FY 2022.
Outlook - supply disruption, but demand sounds fine -
Demand remains strong entering the new financial year, which has started in line with management's expectations. The Board is however cognisant of the potential for short-term disruption to our customers' operations from shortages of building materials, labour and road haulage; and delays in the global container shipping industry.
Notwithstanding these risks, a strong platform is now in place which should provide the Board with confidence for another strong year.
Forecasts - Finncap has issued an update today, raising EPS forecast by 8% to 23.5p for FY 06/2021. That's a PER of 11.7
A modest rise to 24.1p is pencilled in for the new financial year ending 06/2022. Let’s hope that gives scope for subsequent upgrades as the year progresses.
My opinion - bear in mind there’s a big pension deficit here, which sucks out cashflow, so the PER is low for a reason.
That said, the company seems to be trading well, and I’m minded to run my position, I seem to have bought some at 172p a while back. So far, so good.
Obviously supply chain problems could cause a profit warning if they worsen, but that should be a solvable, transitory problem, so is a risk I can live with. It’s more important that demand is strong, and selling prices have been raised to pass on cost increases - pricing power is key at the moment, and is a sign of a good company with good products.
.
Galliford Try Holdings (LON:GFRD)
151p (up 3% at 10:12) - mkt cap £168m
Galliford Try Holdings plc, the UK construction group, today provides an update on trading for the year ended 30 June 2021. The Group expects to announce its results for the full year on 16 September 2021.
A mildly positive update -
...full year profit before tax expected to be towards the upper end of the analysts' current range1.
1 The range of analysts' estimates for profit before tax for the year ending 30 June 2021 is £9.0m to £11.2m based on forecasts at 1 July 2021.
- High quality and large order book of £3.3bn (up from £3.2bn a year earlier)
- Pots of cash - £215m cash at 30 June 2021
- Also provides the useful average month-end cash figure, of £164m
- Sites progressing in line with medium term margin targets (not stated)
- Previously announced resumption of divis in March 2021
- Supply chain problems (inflation, and shortages) have been navigated “without any material impact on trading”
- Strong balance sheet helps with winning high quality contracts
- Mentions a portfolio of PPP assets, no pension liabilities, and no debt
- Positive outlook, with Govt infrastructure spending on the rise
My opinion - this sounds interesting, could be worth readers taking a closer look.
Looking at the last balance sheet dated 31 Dec 2020, the cash pile seems to be due to favourable working capital - i.e. it receives cash from customers before creditors have to be paid. Of course nobody can guarantee that will always remain the case. The current ratio isn't great, at 0.95 - i.e. creditors actually exceed cash + receivables. Strangely, I cannot see any inventories on the balance sheet, which seems odd for a construction company. Maybe everything is outsourced to subcontractors?
Overall, I can't get excited about this, as it ekes out such a tiny profit margin. If margins were to meaningfully improve, then it would look more interesting. I tend to avoid big contractors, as sooner or later something bad seems to go wrong, and they frequently go bust, if over-indebted (which GFRD isn't providing it can keep the plates spinning with its creditors).
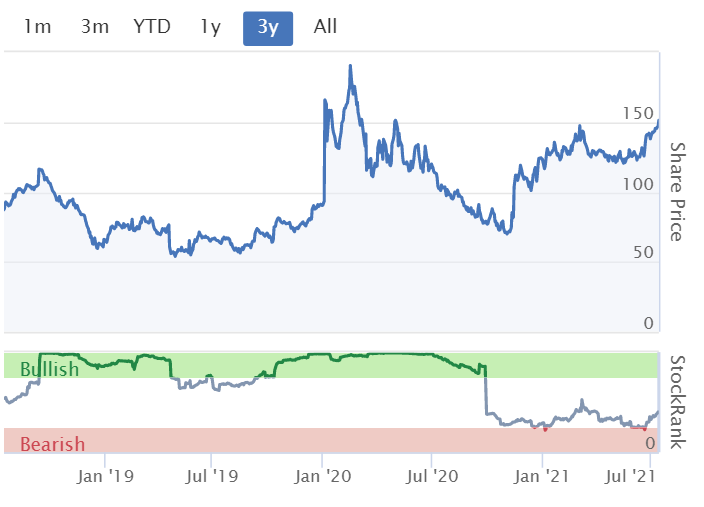
Note below that the StockRank suddenly went from highish to lowish in Sept 2020.
.
.
Jarvis Securities (LON:JIM)
260p (up 6% at 10:35) - mkt cap £116m
Jarvis Securities plc is the AIM traded parent of Jarvis Investment Management Ltd. Jarvis has been providing retail and outsourced financial services since 1984.
Jarvis Securities plc is incorporated in England & Wales. Its shares are admitted to trading on AIM under ticker JIM. The company's operations are principally carried out in the United Kingdom.
Jarvis operates a number of retail stockbroking brands that provide nominee, certificated, SIPP and ISA accounts to individuals and organisations. Jarvis also provides outsourced financial administration services to many investment firms, including some of the World's best known financial names. Services include settlement, broking, ISA plans, SIPPS, regular savings plans and investment trust schemes.
[Source: company website]
Bear with me, as I’m not familiar with this company. Several readers have mentioned it in the comments, so thought I’d take a look.
I can see why you like it, these numbers are superb - with an amazingly high profit margin -

.
Interim Results for the Six Months Ended 30 June 2021
- H1 revenues up 19% to £8.1m
- H1 Profit before tax (PBT) up 28% to £4.6m
- Staggeringly high profit margin of 57% (that’s bottom line profit before tax remember, not gross profit!)
- Mentions favourable trading conditions on the stock market
- Sale of treasury shares for cash
- Distributable reserves being increased to allow higher divis (it already seems to pay out most of its earnings in divis)
- Balance sheet looks strong to me
- Broker upgrade - WH Ireland has raised its forecast for FY 12/2021 by 15% to 15.6p, a PER of 16.7 - not expensive for such a high quality, strongly growing business.
- Forecast divi for this year is 13.3p, giving a lovely yield of 5.1%
- Shareholdings - 52% owned by Andrew & Florence Grant
My opinion - this looks terrific! Thank you to readers who flagged it up in the comments. A very high quality business, growing strongly, at a reasonable price. What’s not to like?!
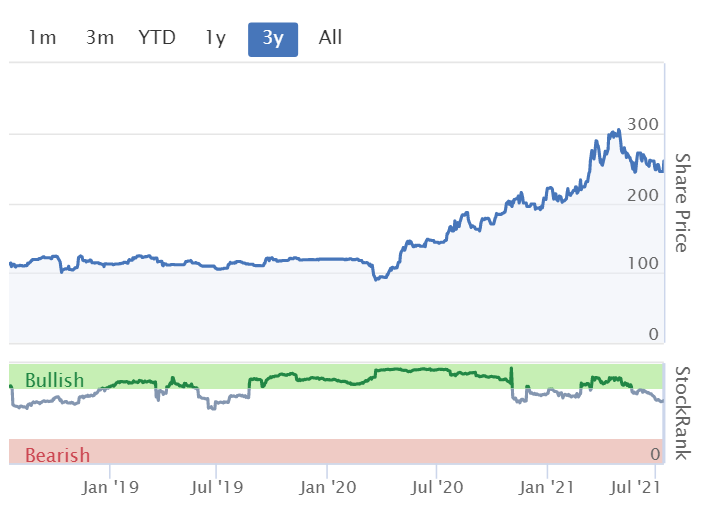
Providing profits are sustainable, then the big rise in share price looks fully justified, and could continue maybe? Although as with many other shares, profit-taking seems to have set in in the last couple of months. I see that as a healthy market correction, and it provides a buying opportunity in quality companies like this, in my view.
.
 .
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

56 comments
Anyone following the Jarvis Securities (LON:JIM) discussion here yesterday might be interested to know they have today declared a special interim dividend of 8.5p. I’m a happy holder as I’m sure are others.
Big after hours acquisition/ reverse takeover with accompanying debt and equity finance package announced by Sigmaroc (LON:SRC) . Buying Nordkalk Oy AB for €470m.
https://www.stockopedia.com/sh...
Includes a retail offer via PrimaryBid at 85p (about a 5% discount to this evening’s close). For once „game changing“ seems an appropriate adjective given the relative scale of the target. Also, unusually, seems the news didn’t leak into the markets as the share price has barely moved in last few days. Good article by Jack Brumby last year looking at the company‘s approach.
https://www.stockopedia.com/co...
Gus.
gosh, thanks for this - I'd missed it! As you say, that sounds pretty transformational.
Boohoo (LON:BOO) and ASOS (LON:ASC)
I have always though that ASOS are a much more flakey outfit than boohoo - they seem to continually run into bad patches - if we go back to 2016 ASOS sales were 5 * what boohoo managed and if we look at 2022 forecasts it looks like boo will make significantly more profit than asos depsite having their year end 6 months earlier.
I think 2019 was an example year where they performed poorly.
This gives me some hope that what is terrible for ASOS may simply be a minor inconvenience for Boohoo - i guess we wont have that long to wait for an update of some sorts. Must admit i have stupidly caught this falling knife at 290p despite seing domeone posting that there was no support till the 270p. When will i ever learn that patience is generally rewardeed when the trend is downwards - sigh.
I think this is one of the best websites.The information published is sooo informative that you can only learn but you have to look at the global picture.The companies are part of the economy where Pandemic, interest rate ,the direction of the flow of money i.e Dollar /Pound and govt policy all play a very important part in fluctuating the stock prices of individual companies.Please don't get angry as this is a very good platform.Congratulations to all the writers on Stockopedia, keep up the good work.Well done for all the hard work.
I have held some JIM for the past 14 months showing a profit of 88.9% to date, so very happy with it
Hi Paul, be interested in your views on Asos trading update and how Boohoo may be doing
A lot of the small caps have had and are having big pullbacks while the indices for the big caps paint a picture that everything is ok.
Any reasons for this from more experienced investors?
Is it just a summer lull and should pick up by September? Alternatively, if there is an economic slowdown coming and small companies are affected more by such things? Still a lot of good value in small caps.
Is the advice just to stay put and wait it out?
Hi Diversification 99,
Whilst I may not qualify as a great investor I may well fit your narrative of "experienced investor" since I've been investing since the late 90s.
Your assertion of a "summer lull" may well be correct. During the summer months, particularly July and August trading tends to be on thinner volumes and markets can drift a bit. This can at least partly be explained by a lot of staff at investment houses being more focused on annual leave with school holidays and such like.
So to your comment "Is the advice just to stay put and wait it out?" that is generally the approach I take. I will try and monitor my holdings and like any other time of year consider if the investment case has changed on a holding which could lead me to consider selling or topping up. Otherwise, if nothing significantly has changed just relax over the summer months since the market always tends to recover (eventually), although some specific stocks may not!
There are currently macro noises about inflation fears going on. However at any one point in time the market headlines are worried about something whether it be inflation, interest rates, exchange rates, legal rulings, war, foreign policy,...... There is always something to worry about if you go looking for it. However the more I read about successful investors the more they ignore the macro noises and succeed throughout because they have good stocks.
I don't know your investment style so can't say what is best for you. For me at least I'm an investor rather than a trader and over the long term see triple digit % gains in most of my holdings, but then again I tend to hold for years, not months.
Thanks for the advice wildshot
That helps a lot. I'm also an investor and look at fundamentals and long term prospects and nothing really has changed with the prospects or story for each of my stocks. As you say there is always something to worry about and Peter Lynch mentioned this also in one of his talks.
I have been in and out of the markets but don't think I have stayed longer than a year in the past, lol, until now my second year. So this pullback in a lot of small stocks in different sectors as well was worrying. So it's good to get your perspective based on your many years of investing. Thanks again.
I have been investing since the 70's but i could not have put this better - well done wildshot !
Solid State (LON:SOLI) there was some discussion on this and about valuation on results day. Interesting presentation by management yesterday on Investormeet platform. Pretty impressive bunch, so worth a look if interested in the company. Addressed the tricky electronics market conditions head on. They saw it coming ahead of time and positioned accordingly so have fared ok during this period and managed to service their customer base without interruption. That will serve them well going forward and I think demonstrates the benefits of being in business for 50 years led by family founder members, so a big tick here from me.
They affirmed the 60p EPS target for 2022 and whilst they wouldn't comment on my question about forward growth rates in the meeting did say that they were shortly finalising the next 5 year targets. Asked about where they aspire to be CEO talked of £250m+ type market cap (3* current levels) so interesting ambitions, particularly as he is quite cautious on over stretching given the family connection to the business.
I can see good growth on offer in end markets too. Space tech as an example is one of their target markets and this is growing substantially over the next decade. Seems they are also investing in R&D, which I'm not sure is particularly well appreciated by the market so that should come through as an investment return in future periods.
I have held from around 400p so share has been good for me so far. Had been toying with where to let them go and had a 1200p target price as around fair value but have now changed my mind and happy to hold over next few years. They aren't going to be a sexy rocket ship but I can see them giving me 15-20% annual average share price growth with dividends on top, which is more than satisfactory for me.
Does anyone have any views on Boohoo (LON:BOO) and why it continues to head south, even with good news announcements?
ASOS (LON:ASC) growth warning today probably had some effect, ASOS (LON:ASC) shares are currently down 15%.
I have noticed a lot of momentum shares dropping back in the last few weeks, profit taking in a nervous market?
Maybe a buying opportunity?
Agree with herbie that ASOS news/update today is key reason (rather than that negative US news) why BOO share price has been falling recently. Agree it will be a buying opportunity but maybe lower to go before the bounce. Same applies to ASOS where despite various negatives their outlook comment was very positive long term.
I’ve also posted, and so have others on a BOO thread, and hope Paul will post his thoughts both on the ASOS update and the follow through probable same current negatives, for BOO over there too.
The thing to laugh at though is the "read across"to ASOS is completely irrelevant since the reason for the fall is the increase in freight costs hitting margins whilst revenue continues to grow 40%. For Boohoo (LON:BOO) of course freight is much less relevant as, ironically for the ESG brigade, they manufacture in Leicester rather than overseas. The more relevant number for Boohoo (LON:BOO) would be that revenue growth appears to continue to be super strong in online fashion.
Feels like the summer lull has started and liquidity has dropped out of the market so lots of moves looking exaggerated to me but mainly on the downside and driven by retail investors.
The reason for the ASOS (LON:ASC) fall is more to do with the slow down of growth, now forecast to be similar to last year's, due to Covid and weather in UK. So it is relevant to Boohoo (LON:BOO).
the drop is mainly related to margins from what I can gather rather than top line growth, and the margins are hit primarily because of freight costs. Top line growth is not expected to accelerate from here. 60% growth p/a in UK markets is clearly unsustainable over the medium term given the size of sales £ASOS already has. I don't believe any institutional investor is pencilling this in, they are all expecting it to moderate and given the market is forward looking that expected moderation is in the price. If not the share price would be in the stratosphere! Margin hits however, are less expected and hit the entire revenue stream not just the growth so have a more profound impact. I think you will find analysts putting the red pen on the margin and profit levels.
Boohoo (LON:BOO) are expecting significantly less than 60% type growth - more like 20-25% and won't get hit from freight cost increases, so less effect and hence much less of a read through.
re £ASOS, Boohoo (LON:BOO), etc, my own view is that the online retailers got a one-off boost from Covid which must now unwind - so with unchanged underlying growth trends the numbers over the next year will not be as good as you might have expected if you simply extrapolated last year's growth. A bit of retrenchment across the board doesn't seem unreasonable.
davidjhill
Are you really saying that none of these reasons given by ASOS today don’t apply to Boo?
1. Increased global supply pressures.
2. Delivery delays partly because of worker shortages.
3. Elevated freight costs.
4. Trading conditions have worsened during the last 3 weeks because of covid.
5. Rest of the World trade impacted by covid.
6. Returns are returning to normal levels...I.e higher.
Is it really likely that uniquely none of these apply to BOO?
Note that other online retailers are also down today. Even Next is down 3% and QUIZ 7%. Isn’t that in reaction to the downbeat ASOS update?
I would also welcome Paul’s thoughts on this.
In my view
(1), (2) & (3) Boohoo (LON:BOO) operates a local business model and therefore should suffer much less
on (4), (5), (6) nothing new : all well flagged : really what £ASOS said about revenues is don't expect 60% p/a type growth - things are normalising. Tell us something we don't know!!
In Boohoo (LON:BOO) case they have steered us to a much more reasonable 20-25% p/a base case. So the actual read across should be that Boohoo (LON:BOO) should be well outperforming over the course of the last 4 months, which gives them plenty of headroom for the rest of the year to meet/exceed expectations.
My point being that if the first set applied to Boohoo (LON:BOO) in any great sense I'd be concerned but the business model differs so much there isn't a big read across.
The rest I'm actually encouraged by. It tells me that Boohoo (LON:BOO) guidance looks pretty robust.
There are several issues which effect ASOS (LON:ASC) and will also effect Boohoo (LON:BOO).
"British online fashion retailer
ASOS ASOS.L reported a 21% rise in sales in the four months to
June 30 but said trading in the latter three weeks was more
muted as uncertainty over COVID-19 and inclement weather
impacted market demand.
ASOS, which sells fashion aimed at 20-somethings, said it
anticipated trading volatility to continue in the near term,
given the rapidly evolving COVID situation worldwide.
As a result, it expected its underlying growth rate for the
balance of its 2020-21 year to be broadly in line with the prior
year period."
So there is no growth at the moment it is same as last year and forecast to continue plus there are higher costs. Boohoo (LON:BOO) also imports many clothes and I believe this proportion has grown thanks to the media coverage in the UK. ASOS (LON:ASC) are not talking about 60% growth, it was around 20% and now 0%.
"UK retail sales 526.4m 329.2m 60%"
ASOS (LON:ASC) that is just for the UK. The adjusted underlying figure for the UK is 36%.
davidjhill
I hope you’re right!
Until the ASOS update I also thought that BOO “should be well outperforming over the last 4 months,” helped by their bargain buy UK acquisitions. That could well be the case, but though hoping I’m wrong I can’t see how BOO cannot have been affected, even if to a lesser extent, to the short term problems covered in the ASOS update today.
If my posts gave the impression I’m negative on BOO, that’s not the case! Influenced by Paul’s comments and analysis I see the current weakness as a great long term buy opportunity and a chance to add, except that it’s possible the share and the sector could get weaker still short term.
hi Ken
I have a smallish position in Boohoo (LON:BOO) for me so I'm not a diehard fan of the stock by any means but I do see the long term potential in it. At a macro level if they continue to innovate and execute well then I see them performing strongly over the next 5-10 years. However, you are right to constantly test your assumptions as to the investment case around any stock, and in particular any potential negatives.
I just think that Boohoo (LON:BOO) business model relies much less on cheap overseas manufacture and therefore freight costs shouldn't hurt margins in the same way so we shouldn't try to read that across as it's an apples to oranges comparison. Where we can read across is on UK sales in particular I think. £ASOS were up 60% on an absolute basis and 36% on an adjusted basis. Both of these numbers exceed Boohoo (LON:BOO) target growth rates so my expectations of 20%+ haven't changed. On that basis I'm happy the investment case remains intact for now, though of course that doesn't mean I will be right! And of course as you say, investors are fickle so the sector could continue to get weaker and that will drag the share price down.
I'm a bit apprehensive about this US action. $100m is neither here nor there really from a valuation perspective but it isn't helpful, particularly if management have to spend lots of time on the matter.
ASOS (LON:ASC) those figures you quote are just for the UK part which is only 41% of revenue, overall the adjusted figure is 21% for the last 4 months and forecast to be 0% for the rest of the year. Why are posters just quoting the UK figures?
Boohoo (LON:BOO) seems to have a lot more issues to deal with, suppliers and the USA.
For the very simple reason that the UK part of the business for Boohoo (LON:BOO) and £ASOS is reasonably comparative and in Boohoo (LON:BOO) case 50% of their business. Rest of World is much less comparative - different geographic splits, warehousing models, sourcing models etc.
So I focus on what I can compare as opposed to trying to read tea leaves across the stuff I can't, where I'm likely to be comparing an apple with an orange, or worse...a banana!
That doesn't mean that Boohoo (LON:BOO) don't have a set of specific problems elsewhere that £ASOS don't have, or vice versa, but at least it gives you better indicators over a good chunk of the business and some room for error.
Probably a read-across drop from the Asos trading update?
https://www.ft.com/content/9cc...
Boohoo founder fights to avoid giving evidence in US lawsuit
Market sentiment seems to be drifting, which is odd when you think of the number of bidders there seem to be out there stalking good businesses.
Morning all,
Fonix Mobile (LON:FNX) share price dropping like a stone, no news that i can find?
I hold.
Regards.
Anything to do with the £BT.A latest plan, phasing out 3G?
I hold Fonix Mobile (LON:FNX) as well as Bt (LON:BT.A)
Silver
Re Fonix (fnx)
I cannot find a reason for drops in share price which seems to be contrary to general info on this share. Very poor liquidity I have not been able to trade in this share for last 3 days despite many attempts trying to buy and sell in 1000 share lots. Suddenly able to trade today and have taken advantage by clearing my holding since I do not like being locked into illiquid positions.
I was able to buy a further 10K at 282p online at A J Bell without diffculty
No news - looks like it is just dropping as no new updates. The problem with these types of shares are that retail investors tend to get bored and switch around, so relatively small numbers of sells moves the price. Then investors like zaracrest below become concerned and get out. It's a MM stock rather than SETs too so more prone to this type of movement in my view.
As there is no news and we are now past y/e I can only surmise that profits for the year will be around 7 to 7.5p EPS and growing in the 20%+ pa range with cash on the balance sheet.
compared to peers it looks well undervalued and assuming it can do 8.5p+ eps next year then on 15* earnings price looks very undemanding. Presume we will see a full year trading update fairly shortly so I guess that will give more information.
I will be the third of your readers to mention the sparkling interims from Jarvis securities £JIM ( I hold) this morning with the following numbers highlighted
-£1,297,166 (19.0%) increase in revenue versus six months to 30 June 2020
· £1,001,861 (27.9%) increase in profit before tax versus six months to 30 June 2020
· Cash under administration has increased 17.3% versus 30 June 2020
· EPS increased to 8.45p (2020: 6.67p) which on my reckoning is an increase of 26.7%.
It currently has a PE of 17.3 but its quality figures are outstanding with a CAGR EPS : 15.7% , ROC : 102.9% , ROE 90.8% and an operating margin increasing to 57% from 51.5%
Graham Neary was the last one to look at this share in April 2020 and his view then was "There's no change to my view on Jarvis. It's a well-run, high-quality little company"
Todays numbers confirm that view and it would be good if you could pass your eyes over the numbers .
The broker forecasts prior to today for Jarvis Securities (LON:JIM), as per Stockopedia, look ludicrously low given the H1 results released this morning. Even with the company's inate conservativeness, significant upgrades should be forthcoming.
Worth noting that these platforms usually trade on very high multiples because of the recurring revenues streams (huge hassle to change brokers! ) - AJ Bell and Hargreaves have both traded well over 30x earnings in the past although not checked current rating - but Jarvis does look very cheap compared to them. It's also nice to have something that does well in more volatile market conditions - if we have a market correction I would expect Jarvis to benefit as people put through more trades.
re Jarvis Securities (LON:JIM). WH Ireland now see fair value at 350p - a 43% upside to current share price. Expect a bullish ST update in the IC before the end of the week, along with a raised dividend. 1st bought at 48p and has been a splendid coffee can share for me...
Not small cap, but noticed this in the ASOS trading update “We expect overall full year adjusted PBT to be in line with our expectations”.
we expect to reach what we expect to reach. We won’t bother to tell you what we expect to reach though, but rest assured, when you find out, it’ll have been what we expected.
ASOS (LON:ASC) forecasts slowing growth due to Covid and the weather, shares are down 7%.
“it expected its underlying growth rate for the balance of its 2020-21 year to be broadly in line with the prior year period”For holders of Vertu Motors (LON:VTU) this may be milding interesting - CEO Robert Forrester to appear on ITV's "Undercover Big Boss". Article here.
My morning smallcap tweet:
Glanbia (LON:GLB) Immedia (LON:IME) Maestrano (LON:MNO) 600 (LON:SIXH) Bango (LON:BGO) Malvern International (LON:MLVN) Alumasc (LON:ALU) Galliford Try Holdings (LON:GFRD) Darktrace (LON:DARK) Cyanconnode Holdings (LON:CYAN) STV (LON:STVG) Capital (LON:CAPD), Brooks Macdonald (LON:BRK), Costain (LON:COST), Gresham House (LON:GHE), Iofina (LON:IOF)
Glanbia (GLB) hikes FY(Jan) adj EPS growth to 17-22% at const FX (from 6-12%). Cites "very strong demand, in the second quarter in particular, across both Performance Nutrition and Nutritional Solutions." [SP=14.05 Cap=4105m]
Immedia (IME) termination of RTO talks with Sprift Technologies Ltd and lifting of suspension. Board continues to consider divestment options for its main trading subsidiary, Immedia Broadcast. Secured loan of £900k to Spirity repayable within 12 months. "The Directors currently believe that Sprift will be able to repay the Loan in accordance with its terms, but this may be dependent on its future trading performance and its ability to secure additional working capital funding as and when required." Oh dear. [SP=25 Cap=9m]
Maestrano (MNO) guides FY(June) rev up 92% but pretax loss £1.3m up 31%. "The board is delighted to see these excellent results and the underlying growth trajectory. We will continue to invest in R&D to maintain our lead in end-to-end LiDAR+AI solutions." [SP=11.5 Cap=19m]
600 (SIXH) 2022 loan notes extended to Aug 2023. [SP=14.5 Cap=17m]
Bango (BGO) guides H1(June) rev up 49% and adj EBITDA over £2m(£1.1m). I line? "Bango enters the second half of 2021 with tremendous momentum across the business, enabling continued investment for future growth." [SP=223 Cap=169m]
Malvern (MLVN) AGM stmt: University Pathways deposits for the September intake of the 2021/22 academic year are currently up but restrictions in international travel will probably delays some student starts. Has "sufficient liquidity and flexibility to allow the Company to manage through the period of any further disruption caused by Covid, and to contribute to planned growth initiatives." [SP=0.25 Cap=5m]
Alumasc (ALU) guides FY(June) rev up 18% abnd U/L pretax ahead of mgmt expectations. Current trading in line. [SP=276 Cap=100m]
Gallifrod Try (GFRD) guides FY(June) pretax towards the upper end of forecasts. [SP=146.24 Cap=162m]. I hold.
Darktrace (DARK) guides FY(June) rev up 40% and constant currency Annualised Recurring Revenue up at least 44%. Hikes FY22 rev guidance growth to 29-32% (previously 27-30%), Expects adj EBITDA margin 1-4%. [SP=577.5 Cap=4050m]
CyanConnode (CYAN) follow-on order from Thailand for 31,000 Omnimesh Modules and associated gateways. [SP=10.05 Cap=22m]
STV (STVG) H1(June) ad rev up 32%, ahead of expectations. Total TV viewing up 5%. Guideds July ad rev up 35-45%. [SP=356 Cap=166m]
Capital (CAPD) guides H1(June) rev up 52% and hikes FY rev guidance to $200-210m from $185-195m. [SP=77.6 Cap=148m]
In line: Brooks Macdonald (LON:BRK) Costain (LON:COST) Gresham House (LON:GHE) Iofina (LON:IOF)
Thanks Mr Contrarian, i had missed the RNS for Malvern International (LON:MLVN). For some reason it is not appearing in Stocko. I shall follow up with the tech team.
Morning Paul andJack. Be great to get your thoughts on Alumasc (LON:ALU) Strong trading update, ahead of expectations and management look to be doing a nice job here. I hold a small position.
Keep up the great work!
Very strong updates this morning from Jarvis Securities (LON:JIM) and Capital (LON:CAPD) . Perhaps of interest to Jack... ...and yes I hold both so am definitely biased.
The update from Capital (LON:CAPD) confirms to me that the commodity super cycle is well underway. I hold.
morning Paul... could you dig into CAPD update please... your opinion often as good as gold.
Paul doesn't do miners etc. My thoughts are that it looks excellent, but for the fact there's no mention of profit, all figures relate to revenue. One hopes that there's some correlation between the two!
Strictly speaking, Capital (LON:CAPD) is not a miner, though arguably its fortunes are so tied to the gold price it might as well be. Just guessing myself, but in the nature of the business they may be reluctant to issue a figure for eps at the interim stage, because there may be decisions to be taken on the value of old equipment which they would prefer to take at the year end. I thought the operational update they give was more informative than the "adjusted ebitda" figure which you see so often. I hold, and like you I like the numbers.
£capd do own stakes on various goldminers though. They were written up in the last full year results
A shame you don't do financials Paul. JIM are the typical picks and shovels company and should be a part of every portfolio. Maybe Jack will give it a mention later.
'Poke The Troll'. I think you may be on to something there Paul.
I thought better of that, so it didn't survive the first edit ;-)