Small Cap Value Report (Thu 16 April 2020) - RBG, WGB, DNLM, VLX

Good morning, it's Paul here with the SCVR for Thursday.
It's busy for updates today. I'll start with 3 companies in which I have long positions, as obviously I read the updates that affect me personally first thing. Newer subscribers may not be aware that I'm primarily a professional investor (since 2002), doing writing as a sideline.
Today's report is now finished.
Revolution Bars (LON:RBG)
Share price: 20.4p
No. shares: 50.0m
Market cap: £10.2m
(I hold a long position in this share)
Completion of banking documentation
You might recall that this operator of 74 town centre late night bars, surprised on the upside 2 days ago, with an update that its bank (Nat West) is being supportive, thus eliminating (for now anyway) the need for an equity raise. Being long of the shares myself, (this is now my biggest position in my trading account), I'm delighted that it seems the company won't need to dilute me at this stage, thanks to bank support.
Today RBG confirms that the bank paperwork has all been finalised;
Revolution Bars Group plc (the "Group"), a leading UK operator of 74 premium bars, trading under the Revolution and Revolución de Cuba brands, confirms that it has now executed final documentation with its lending bank, Natwest to increase its revolving credit facility to £30.0m until 31 August 2020, as further detailed in the Group's announcement of 14 April 2020.
Here at Stockopedia we've provided a range of opinions on this share this week;
- Graham - sounded very negative here
- Paul (me) - positive, whilst acknowledging it's risky, in the same article, in the reader comments section
- Jack - seemed middling, leaning to slightly positive, in his excellent article here
It's good to have confirmation that the increased overdraft documentation has been executed, which should make the necessary larger facility available. This buys RBG time to tread water until the lockdown is lifted, hopefully soon.
As mentioned in yesterday's article, after reading the OBR report on the likely cost of lockdown, I am increasingly convinced that the Govt has little option but to phase in a lifting of the lockdown relatively soon. That's starting to happen in other countries too. Hence there are really 2 unknowns with RBG at the moment;
1. When will lockdown be lifted for bars? Currently RBG is generating nil revenues, but has costs of £0.4m per week (I assume that's on a cash basis)
2. How strong/weak will trading be, once its bars are allowed to re-open? Opinions differ on this. Some people think customers are likely to be cautious, and stay at home. Others (including me) think that the 18-25 customers that RBG mainly serves, may want to go crazy and party hard, after being cooped up at home in lockdown. Don't underestimate the impact this is having on many people's mental health. Hence why I see it as a pressure cooker, waiting to be released.
If the positive scenario plays out, then I think it's perfectly possible this share could be a 5-bagger. Hence why I've bought up nearly 3% of the company. If lockdown is not lifted for bars, or is re-imposed if a further virus outbreak follows in the summer/autumn, then the shares could be diluted heavily in an equity fundraise, or worse still, even go bust. Although to be fair, you could say the same thing about many other hospitality/retail sector shares. RBG's finances are not particularly bad when you look at other, often much larger, businesses in the same sector. Therefore everyone looking at this share, needs to have their eyes open about the considerable risks facing the whole sector.
Walker Greenbank (LON:WGB)
Share price: 44.5p
No. shares: 71.0m
Market cap: £31.6m
(I have a long position in this share)
Results date & Covid-19 update
A very unsatisfactory update today, from this soft furnishings & wallpaper group. It doesn't give us enough information, hence is fairly useless in assessing how to value the share. The limited amount it does say can be summarised;
- Results delayed from 23 April, to 30 June - blames the FCA's (rather bizarre to my mind) instructions to delay results due to Covid-19.
- "Vast majority" of employees furloughed under Govt schemes
- 20% pay cuts to preserve cash, including Directors (good)
- Some (reduced) licensing income being received
- Company "has headroom" under its existing £12.5m bank facility, and has agreed a £2.5m overdraft. There is also a £5m accordion facility. No figures given on cash, nor amount drawn down on bank facilities. Hence we're in the dark about headroom - very poor, this is key information that shareholders need
- Positioned to resume operations swiftly when circumstances permit
- Obvious, and sensible measures taken to preserve cash;
Measures have been taken to preserve cash including suspension of the final dividend and of capital expenditure plus very tight controls over operating costs. Wherever possible, the Company is accessing government support mechanisms both in the UK and overseas.
My view - this announcement is general, but doesn't give any specific figures. That makes it largely useless. Compare this with the very much better information given below, by retailer Dunelm (LON:DNLM)
As with most shares, it's impossible to value WGB until we get some clear information on trading, and updated broker coverage. I'm assuming heavy losses are likely in the short term. Then a recovery in earnings once lockdown is lifted. It's a very strange situation, which I've not seen before, where we simply have no idea what 2020 earnings are likely to be, nor how much of a recovery is likely in 2021. That applies to almost everything, not just WGB. That's why I'm looking for bargains, and am not paying top whack for anything. Remember the starting point when Covid-19 started, was that shares looked very expensive generally. Hence if something is only down say by a third, is that enough of a discount to make it a bargain? Maybe not.
Dunelm (LON:DNLM)
Share price: 859p (up 4% today, at 08:20)
No. shares: 202.3m
Market cap: £1,737.8m
(I have a long position in this share)
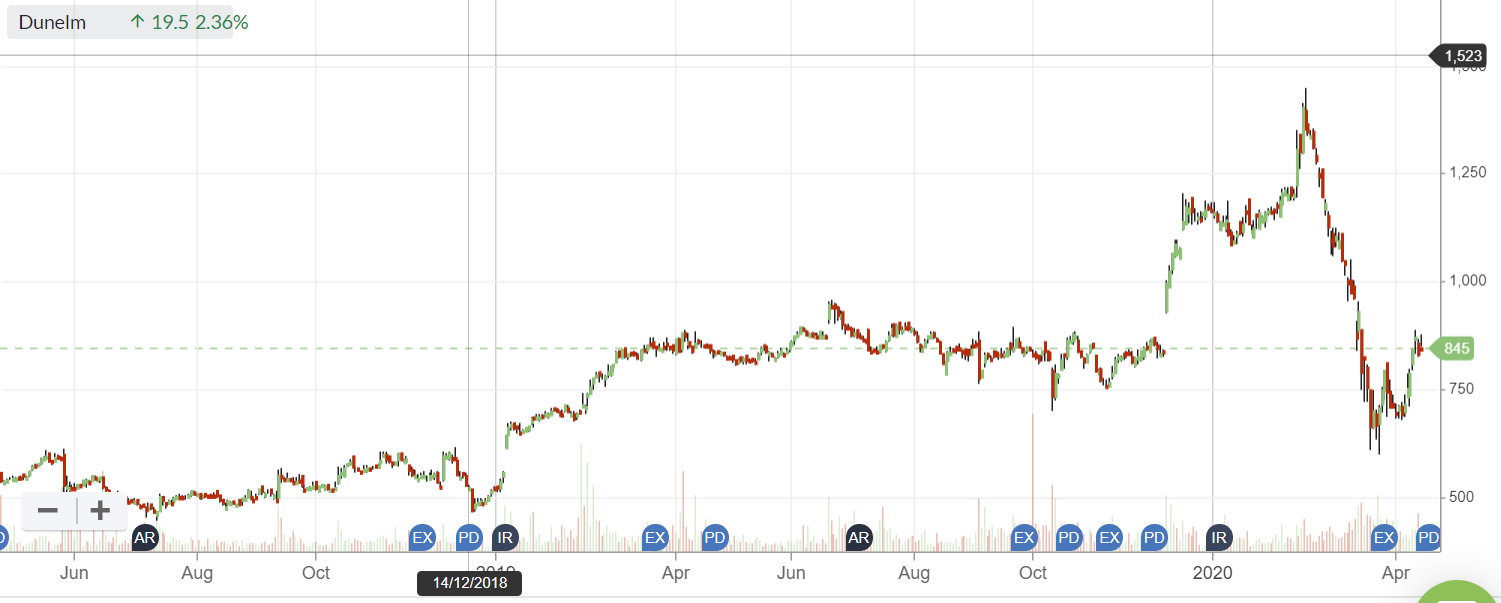
This is a homewares retailer. Checking my previous notes, I was very impressed with its last results, and wrote about it here on 12 Feb 2020, saying that it's a good company but too expensive at 1326p per share, but I would buy on a pullback. The current crisis enabled me to do just that, buying at 702p average, in late Mar & early Apr. So far so good.
I'm very happy with this update, because it provides the information investors need. Let me summarise it;
Online business Dunelm.com has re-started, after extensive health & safety work, and approval from Trading Standards
Since reopening, we have been able to satisfy a high level of online customer demand, with recent online order levels significantly higher than those seen prior to the onset of Coronavirus.
Stores remain closed, but preparing for re-opening. Store staff furloughed, others working from home.
Liquidity - £165m RCF drawn down in full [very sensible]. Net debt £40m as at 11 April. Hence it has plenty of cash available.
More borrowings potentially available from Govt;
In addition, we have now received confirmation from the Bank of England that we are eligible to access funding under the Covid Corporate Financing Facility ("CCFF").
Crucially - this is a very strong statement, highly reassuring;
The Board is confident that the Group has access to sufficient liquidity, even in the event of a prolonged store closure period.
Currently, we would only anticipate the need to issue paper under the CCFF scheme in the event that our stores remain closed for a period greater than six months.
Belt and braces then, very good indeed. I think it's very important that all companies spell out how long they can tread water for, during lockdown.
Pay cuts - CEO, Chairman & NEDs showing real commitment to the business here, even if it is only for 3 months (which is normal). We're all in this together, so I see it as a litmus test that Directors take some pain personally, at all companies;
We continue to focus on reducing operating expenses and tightly managing our cash flows.
The executive management team have taken a voluntary 20% pay reduction. Nick Wilkinson, our CEO, has taken a voluntary 90% pay reduction, and our Chairman and Non-Executive Directors have waived 100% of their fees. These reductions will be in effect for the three months from April to June.
My view - this is how a well managed business handles a crisis. Very impressive all round.
This crisis has allowed small cap investors like me the opportunity to move up the food chain, and buy some mid caps at knock-down prices.
I'm very pleased with today's update. It demonstrates clearly, and with figures to back it up, that the business has plenty of liquidity for 6 months and beyond. Being large shed type of shops, I think these could be allowed to re-open sooner than places like bars, where people are in close proximity to each other. We've seen in other countries how large retail sheds are trading, with customers spaced apart well, and wearing masks. Perhaps something similar might be adopted in the UK?
Hence I see this share as lower risk than my position in Revolution Bars. The compensation for that is Dunelm won't be a 5-bagger! But equally it won't be going bust either. I could see this share being maybe 50% higher, once trading has (hopefully) returned to normal - no idea on timescales for that though.
.
Volex (LON:VLX)
Share price: 138p (up 11% today, at 09:47)
No. shares: 151.8m
Market cap: £209.5m
Volex plc (AIM: VLX), the global provider of complex assemblies for performance critical applications and power products, issues the following trading update ahead of the announcement on 18 June 2020 of its full-year results for the year ended 5 April 2020.
This update reads positively, hence the 11% rise in share price. There's been a very impressive turnaround at Volex in recent years.
Reiterates guidance for FY ending 5 April 2020. Impressive, since Feb-Mar could have had an impact from Covid-19, but doesn't seem to have done so.
Forecasts - there's an update today, available on Research Tree. This gives 16.6p adj EPS for FY 03/2020 - a PER of 8.3. Obviously the PER is low, because the share price is factoring in potential future damage from Covid-19. For long term shareholders though, looking through the current crisis, this valuation looks attractive.
A modest increase to 17.2p adj EPS is pencilled in for FY 03/2021, but it's clearly finger in the air stuff, given the unknown extent of the global recession that appears to be starting.
Liquidity & divis - this looks really strong, I'm impressed. Paying a divi when many other companies are running for cover and scrapping divis, is a powerful statement right now;
Net cash as at 5 April 2020 of $31.7 million compares with $7.9 million reported at the half year. We intend to declare a final dividend of 2 pence per share based on our full-year results
Therefore, it seems investors should be able to sleep well, without fearing insolvency.
Outlook - the most important part of all trading updates, especially right now.
Looking ahead, it appears likely that economic activity and consequently trading will be impacted by restrictive governmental measures put in place to contain the spread of Covid-19. However, the quantum and precise impact will depend on the length of time such measures are in place and their severity, offset against our defensive exposure to medical devices and data-centre products, which make up approximately two-thirds of our complex assemblies division...
However, despite this 'perfect storm', Volex's business has proved remarkably resilient, continuing to produce a solid performance in both sales and operating margins. Our strategy to diversify our products, customers and geographic footprint, together with our exposure to medical devices (and high-speed data centre products, which are in even greater demand as much of the world's population works from home), has resulted in continued growth and strong cash generation, despite significant headwinds.
It's possibly a little early to declare remarkable resilience, given that the crisis has only recently started.
In the first paragraph above, it does acknowledge there's likely to be some adverse impact, so we shouldn't get too carried away with the positive commentary.
My opinion - this is an impressive announcement - one of the best I've read in recent weeks, and I think the share looks quite interesting.
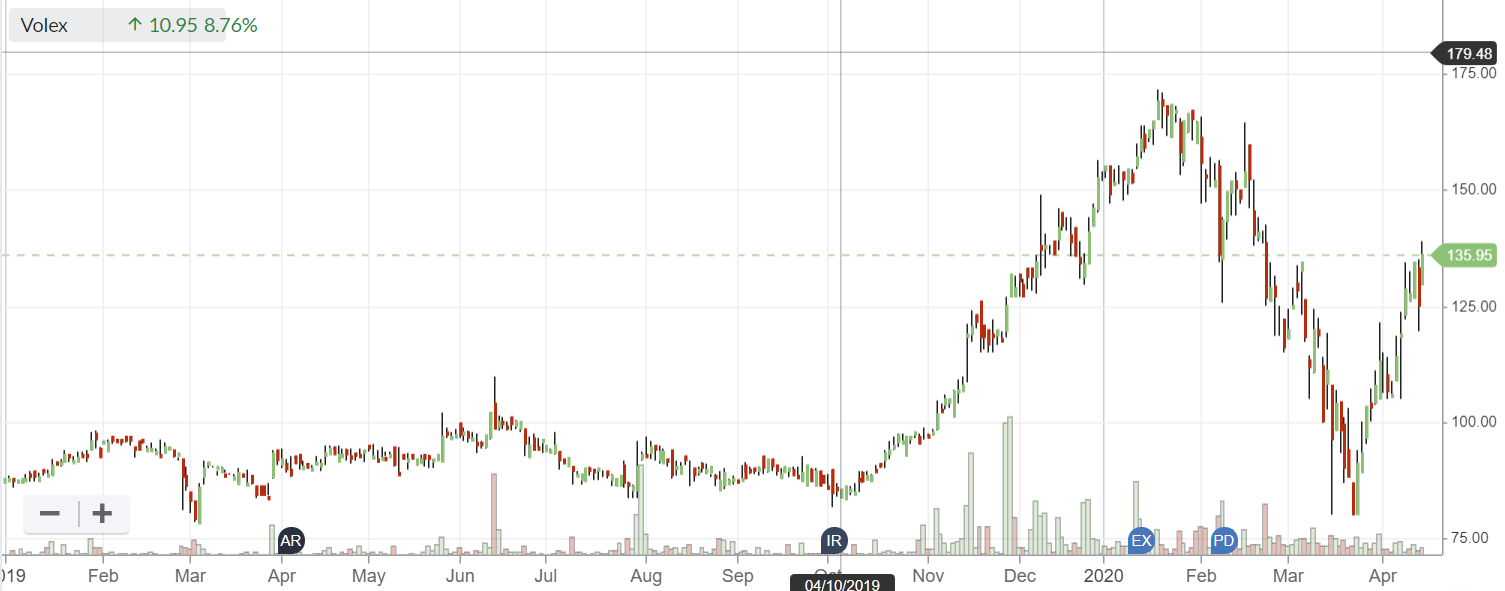
Whilst acknowledging the positives, one look at the chart below shows that the rebound in price from panic selling lows recently, has already been extensive. Given the uncertainty, I'm struggling to imagine why anyone would want to chase the price any higher in the current environment? I'll certainly add it to my watchlist though, and monitor newsflow. I'd like to see a few more months trading information before deciding to buy any, if at all.
Well done to shareholders who held their nerve, and didn't panic sell at recent gut-wrenching lows.
.
That's it for today. I hope you're all surviving these very difficult times.
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

77 comments
If you like that sort of thing:
BOE Speech - Monetary policy during pandemics: inflation before, during and after Covid-19 16 April
Key bit for me
"The key conceptual challenge is that there have been large shifts in spending patterns, which will change the
representative household consumption basket. Spending on social consumption has stopped almost
completely, for example, while spending on essentials from supermarkets has increased markedly. These
changes will be largely temporary, but while they persist, interpretation of the data will be particularly difficult."
Paul excellent update thank you. I had the IPO of RBG fortunately sold early on albeit for a small loss at around 200p. A friend who owns a few Independent bars in London who is extremely worried about his livelihood spoke with me. Above all else was saving lives and he added that he also expects a similar thing as you with youngsters and especially the pink pound customers young and older will return hard and fast. Regulars too he felt will return quickly to help his business start up again.
Lots of debate on Revolution Bars (LON:RBG) here, let me throw in a few additional thoughts.
At end-June 2020, net debt is going to be c£22m (versus historic EBITDA of c £10m that was trending up due to operational turnaround plan seeming to work). In a remotely normal world (clearly not now) that would not be viewed as a particularly high level of debt.
The cash burn rate for company is c£0.4m per week while we are in lockdown. If lockdown is released very slowly then the key thing for the company will not be to “party like its 1999” but instead to achieve cashflow break-even on a weekly basis, assuming strong social distance measures remain in place for the long-term. Moving from -£400k per week cash loss to break even across c75 bars does not seem like too much of a stretch given that management will be able to pull levers (e.g. only bringing back some of staff to serve and leaving rest on furlough). If they can achieve this position of being cash flow break even (i.e. debt stops increasing) while still being in a strong social distancing phase then the shares could offer good value based on current price as in that situation it is unlikely that the bank (who appear very supportive and are government owned) will force a recap. £RBG could then maintain that cash flow break even operating model until the world returns to something resembling normal (and it will eventually). At that point you have a company valued on c 3xEBITDA of which 2x is Net Debt. If that scenario plays out then Paul gets his multi-bagger and I will be the first to buy him a drink to celebrate.
So, if company can achieve operating cash flow break even (as opposed to £400k per week loss) at time of partial lockdown release that will be a HUGE step forward for the investment case here.
You were going well except June 30 2020 happens to be a period end. So historic EBITDA will no longer be £10m... and forecast EBITDA.... will not be £10m either.... so the debt x will be .... easily 3, could 4, maybe 5, 10? We shall see I guess... but they lose £4m in lockdown and £7m before.... cash flow is zero. And in December, could net debt be higher still with another covenant test?
June 30 2020 covenant has been waived. And yes EBITDA for bank covenant is trailing which will obvs be low but no government owned bank is going to impose a recap at those debt levels otherwise they will have to force entire sector (public and private) to recap which means wiping out thousands of small businesses. Yes, there is risk, but if they can get to cashflow breakeven then I think that will be enough. Cashflow breakeven is about £12-15k per bar per week versus their normal run-rate of c£40k per week. Do-able in my view. But buyer beware etc.
Ok, £12-15k per bar per week looks low to me, id have said between £24k and £30k ... staff/bar and how you manage that is awkward, more staff less queue etc at the bar... is it that easy to run RBG on 50% staff.... if you can run at cash breakeven with revenue down 60% then I agree, its doable.
Revolution Bars (LON:RBG) ... alternative analysis.
"The leases are not a problem at all, providing the bars can actually trade! That's because in aggregate, RBG's sites normally generate strong cashflows."
In principal I agree. However, Mar 18 2020 net debt £10.5m.... 4 weeks later, £17.8m. Cash burn has been reduced to £1.6m / month - Im going to say add £4m - so in July you are at £22m net debt.
Now you reopen, and in a good year, you trade at £10m ... lets say that's £1m / meh over the summer. So what do we think trading will be in corona recovery - more to the point what LFL Vs 2019 is cash flow breakeven - my guess is between -5--10%. -20% is loss leader. So even if they reopen they could still be consuming cash. How much cash... well in month to April 14 they consumed £7.3m and this has now been reduced to ( not going bust) level of £1.6m. Seems to me being closed might be a better option than reopening.
As Paul says, it could be a 5x... but it could be a zero. It was about to go bust before this bank facility was in place. If they owned their sites their cashflow would be £10m better - borrowing costs on £80m with real estate backing... probably cost £2-3m.
I very geared play on a V shape recovery in July.
Paul (and others),
what do people use to track company news and announcements? Is there some kind of aggregator site or app outside of stockopedia's news tickers?
Cheers.
Investegate - occasionally it lets you down and I go to London Stock Exchange if I have to.
Paul, don't get me wrong I appreciate your expertise and look forward to the daily report but is it wrong of me to suggest you are providing a bias to shares you own personally ? You today report on 3 of the companies you own, fair enough I didn't make requests of my own this morning but surely to be fair to paying subscribers you could assess your own preferred shares as notes to yourself only more often (I appreciate your need to expedite this), but after all Revolution Bars (LON:RBG) has been reported to excess on here I believe. There was other noteworthy news on Dx (group) (LON:DX.) Rbg Holdings (LON:RBGP) & Tp (LON:TPG) all of which I own that didn't get a look in, I thought the news on Tp (LON:TPG) was especially interesting and worthy of assessment.
Typing for myself: I think that a known and declared bias, that motivates a writer to demonstrate analysis or articulate a view, is of more value than a lesser motivated piece. Personally I'm hours/days/sometimes weeks behind when catching up, so my context may be different to yours.
What a boring comment. I'm happy to stand down if you think someone else can do a better job. But am I going to waste my time writing about rubbish/boring companies? No. find someone else to do that.
I'm particularly offended and shocked by that response, and expected better from you Paul, isn't it Robbie Burns who is always telling us that the boring companies are well worth buying ? I would have thought a company Tp (LON:TPG) developing a product that will assist hospitals was very interesting and topical personally, and not a "rubbish" company either (although Revolution Bars (LON:RBG) at £12m mcap and a terrible chart could fit that tag) I am going to reflect on my subscription if that is the sort of blanket response I get to what I believed was a fair question/comment, I just lost a load of respect for you right there
For some idea on what the world might look like once the lockdown is relaxed - this is quite sobering
https://www.cam.ac.uk/research/news/study-identifies-275-ways-to-reduce-spread-of-coronavirus-following-lockdown
For a better understanding of the statistics around coronavirus, the interview with Professor David Spiegelhalter, the Winton Professor of the Public Understanding of Risk here is very interesting
https://riskytalk.libsyn.com/coronavirus-understanding-the-numbers
I wonder whether people are starting to over-trade out of sheer boredom?
I’m winning at the moment!!!
Me too Doggy100. One small holding company I bought (NSCI) just three weeks ago was up 18 fold today on the price I paid then .....after a huge dump by a forced seller. A lucky spot. I am finding that the markets are very exciting at the moment. Just as well with three very good but very bored teenagers in the house! We will look back in a year and think such moves were crazy!
52 Week High 18.50 16-Apr-2020 Low 0.75 Date 26-Mar-2020
I bought novacyt @105p
According to Mr Google, nearly 500,000 people work in the UK pub and bar sector, and I suspect the government will not want to keep picking up that tab for too long.
I also believe that the Government position is all about protecting the NHS and they expect/want the majority of us to get the virus eventually, even before a vaccine is ready.
Therefore I can see them opening up bar and pubs before summer is fully here.
I own 3 pubs in the west West Country and I suspect we will open before June the 1st
If you need to wear gloves/mask in pubs sobeit
Breweries already looking at late May for some action
Doggy100,
You did make me chuckle! You won't be selling much beer if they all have to sit there in masks!
The craic will be a bit muffled as well.
I'm off now to drill a hole for a straw in the mask.
Bonitabeach
masks off for a slurp
Pubs will be booming if they can hang on for 6/8 weeks
Hi Doggy100,
‘Breweries already looking at late May for some action’’
Why do you say that, as a owner of three pubs you probably have more insight here. Is that anecdotal, or multiple breweries acting the same way?
We've noticed quite a few pubs in London that are obviously doing lock-ins - lights on, curtains closed, laughter inside.
I'm sure it's the same across the UK.
We cannot hide from this virus forever. Appreciate all the health aspects, but anyone who is financially literate, and has read the OBR report, must surely realise that lockdown is a disastrous & unsustainable strategy.
Life is full of risk. 1,000+ people die in car accidents each year. We don't eradicate road travel until we can stop these deaths. They are part of the risk involved in normal life.
The OBR report gives no evidence to suggest its assertion that inaction would cost more than action.
The reality is that we all face risk, all the time. This cannot be eliminated. Covid-19 is NOT the worst risk in living memory. Nazi bombers overhead, pebble-dashing our cities, was a far greater risk, numerically in terms of deaths.
The lockdown is likely to cause thousands of hidden, deferred deaths - from suicide, alcohol/drug abuse, people losing their homes, businesses, depression, etc. We'll be feeling the effects of the lockdown for years. So to pretend that saving a relatively few, end of life, lives, is a good price to pay, for wrecking the lives of millions of working age people - I think that is an honest discussion we should be having. I don't know the answer, but it should be discussed, not suppressed.
History may judge that an almost total risk aversion approach that we now have, could be wrong. But who knows? I just think it's interesting to discuss.
Covid-19 is NOT the worst risk in living memory.
I have been making this point on another thread, there is evidence now available that the real mortality rate is likely to be somewhere between 0.1-0.5%. 50-66% of those deaths are estimated to happen anyway during 2020.
Nazi bombers overhead, pebble-dashing our cities, was a far greater risk, numerically in terms of deaths.
For publicity purposes this situation was referred to as this generations world war 2. There is no way you can logically compare the loss of 450,000 (majority in their 20's) U.K lives to Covid 19.
I have been making this point on another thread, there is evidence now available that the real mortality rate is likely to be somewhere between 0.1-0.5%. 50-66% of those deaths are estimated to happen anyway during 2020.
There is evidence for all sorts of rates, people can find any estimate they want to back up their prior beliefs, but that's not the point - it's the total number of hospitalisations that determines the overall death rate.
If the NHS was overwhelmed then it wouldn't be a small number of old people dying - you'd also have significant increases in death rates among younger people because they couldn't get treatment for otherwise survivable illnesses or accidents. You'd have women dying in childbirth, young men dying because of drunken accidents, middle aged people dying because of heart attacks, not to mention an increase in younger people dying from cancer and strokes.
We can get a flavour of this now by the jump in non-Covid-19 deaths caused by people with life threatening conditions staying away from hospital.
It'll be a long time before we have the data to show whether this is an overreaction or not, but realistically the government isn't about to change course now. It has a big majority, opposition backing and is nearly five years away from an election. As investors it doesn't matter whether they're right or wrong, it's what they're doing that matters and which should govern our investing decisions. Anything else is just wishful thinking.
timarr
This will be my last post on this thread re: Covid, any further comment will be on the Lockdown thread.
If the NHS was overwhelmed then it wouldn't be a small number of old people dying - you'd also have significant increases in death rates among younger people because they couldn't get treatment for otherwise survivable illnesses or accidents. You'd have women dying in childbirth, young men dying because of drunken accidents, middle aged people dying because of heart attacks, not to mention an increase in younger people dying from cancer and strokes.
If this is true there should be a large jump in deaths in Sweden, assuming they don't buckle under political pressure. We should know in a few weeks. An article in the Economist suggests otherwise:
"An uptick in the number of pneumonia admissions has been more than balanced out by an enormous fall in the number of people coming in with other problems."
https://www.economist.com/britain/2020/04/08/a-sharp-drop-in-accident-and-emergency-admissions-worries-medics
We can get a flavour of this now by the jump in non-Covid-19 deaths caused by people with life threatening conditions staying away from hospital.
That's because the government are trying to scare everyone into house arrest and the media are publishing fatality rates of 13% for the U.K which is complete rubbish. Only testing people that are ill enough to be hospitalised is massively underestimating the real number of infections and overestimating the mortality rate.
https://news.sky.com/story/coronavirus-the-infection-numbers-in-real-time-11942138
"If the NHS was overwhelmed then it wouldn't be a small number of old people dying - you'd also have significant increases in death rates among younger people because they couldn't get treatment for otherwise survivable illnesses or accidents."
Actually the NHS is worried about the opposite - significant numbers of deaths because of the disproportionate allocation of resources to covid.
“NHS England analysts have been tasked with the challenging task of identifying patients who may not have the virus but may be at risk of significant harm or death because they are missing vital appointments or not attending emergency departments, with both the service and public so focused on covid-19.
“A senior NHS source familiar with the programme told HSJ: “There could be some very serious unintended consequences [to all the resources going into fighting coronavirus]. While there will be a lot of covid-19 fatalities, we could end up losing more ‘years of life’ because of fatalities relating to non-covid-19 health complications.”
https://www.hsj.co.uk/policy-a...
"If the NHS was overwhelmed then it wouldn't be a small number of old people dying - you'd also have significant increases in death rates among younger people because they couldn't get treatment for otherwise survivable illnesses or accidents."
Actually the NHS is worried about the opposite - significant numbers of deaths because of the disproportionate allocation of resources to covid.
It's concerned about both. It's barely coping now but remains open for other business - some of the concern is that patients aren't being referred in or prefer not to risk going to hospital. If it's overwhelmed then everything else would be squeezed out and other admissions would become very risky because of a much higher cross infection risk. The ideal for the NHS is keeping the peak as low as possible.
The lockdown isn't about hiding from the virus nor saving everyone from the virus. It's about preventing healthcare capacity from getting overwhelmed. Granted there is risk everywhere and we can't lockdown forever, but the usual risks from daily life like driving cars doesn't have the possibility of overwelming the healthcare service.
[Angela Merkel put it nicely recently: In Germany, they have a R number of around 1, so 1 person infects 1 other. If that was to increase to 1.1, healthcare capacity will be reached in October. An increase to 1.2 would lead to healthcare capacity being reached in July. R of 1.3, June. The margin is thin, so it is time for caution rather than overconfidence.]
Yes, I agree we have to get businesses going again and not to do so will have dire economic consequences, but we'll have to do so in a way that maintains some kind of social distancing. Perhaps of the kind that is now seen in supermarkets. This would allow businesses to open but with measures in place to limit contact.
I'm not sure what the consensus is, but social distancing of some form will probably need to remain until either a vaccine is available for the masses or until we have herd immunity, neither of which will be possible until next year.
Re discussion about risk to life.
There are about 26,000 premature deaths in the UK per year from type 2 diabeties (source .www.diabetes.org.uk). The majority of these are avoidable given certain lifestyles 'choices'. As a society we haven't done much about this and yet it 'overwhelms' the NHS in treatments. The response to Covid19 deaths is not in line with our response to type 2 diabeties deaths ( i.e. the Govt is putting more value on someone likely to die from the covid pandemic than type 2 diabeties).
The only explanation is timing, deaths from pandemics come very rarely but all at the same time so it looks shocking v. other premature deaths which happen year after year 'below the radar'. Humans eh!!
Not the only explanation at all.
Paul,
Exciting to read about your position on Revolution Bars. Hope it works out and is a 5 bagger or better!
Did you consider JDW as an alternative? Spoons owns quite a bit of freehold property if I recall correctly and is more broadly based. As you mentioned, freeholds come with company debt, so not a one way bet.
Also pubs in the UK are closing down at a substantial rate (I forget the official figure). Long term social trend. I'm sure that after the crisis lifts, the attrition of more traditional boozers will turn out to have been much accelerated.
So I thought JDW could emerge with reduced competition, and being larger with longer opening hours, it is more suited to whatever gradual release of the lock-down is allowed.
We don't know what that might be, but only allowing limited punters at any one time,perhaps served at tables is possible. I get the impression RBG is much more reliant on a few hours on Friday and Saturday nights with crowded bars and downing shots. Can't see that being allowed until COVID19 is pretty well eliminated by a vaccine or new antiviral treatment.
Mark
Yes, I had a close look at J D Wetherspoon (LON:JDW)
The Govt has to let pubs re-open, or we'll be looking at unimaginable disaster.
JDW didn't look cheap enough for me. I'm a higher risk investor, so I want a 5x return, for taking a bit more risk. JDW doesn't seem to offer that. It's got plenty of freeholds, and I like the robust Chairman. Hence a bit like Greggs - lovely business, but the shares are not cheap enough at the moment to reflect the risk. For me.
Today's board is lively, especially around Revolution Bars (LON:RBG) and analysing Paul's approach as to whether he is playing a gamble . But aren't we all essentially gambling in the financial markets ?
Personally I find the term "investment" only applicable to a financial transaction I make that I have direct actionable control over, be that shared with others or on me alone.
So I don't consider any purchase of shares that I make to be investing but "speculating". Unless shares bought are at a level that has influence in the company decisions (or you are a respected journalist!) we all have to sit and take the what the market delivers as a reaction to company events, hence why we await company announcements just one hour before the market opens and we see our stakes rise / fall / stay flat. But we cannot influence that movement, nor pre-empt it (well not legally anyway)
Gambling for me is more binary, in that you place a stake and get it back if you win, but not if you lose. With speculating you can cut losses and recover a partial stake - but isn't that really just "informed gambling" ?
Personally the rush of being lumped on to a winner takes some beating, which is why I still do it. But I try not to kid myself that this is an investment I can control - I keep those outside of this arena, and keep my capital lumps separated.
Well played to anyone lumping on at scale in the current markets, it's still a better option than a bag of cash under the mattress or a punt on "red or black" in the casino in my view.
Hi LumpedOn
An interesting perspective though one which I think Ben Graham would disagree:
“An investment operation is one which, on thorough analysis, promises safety of principal and a satisfactory return. Operations not meeting these requirements are speculative.”
I agree with Ben I am afraid.
I would add that you are right that putting money to work in most stocks in the current market is completely speculative as there is, IMO, zero visibility as to earnings etc and therefore “thorough analysis” cannot be carried out.
KR
Michael
Re Revolution Bars (LON:RBG) - the way I look at it, is that it's my money, and I'll do WTF I want with my own money! It's very kind of others to proffer their views, which I will take into account possibly. Actually I won't, I'll ignore them & do what I want with my own money.
It's an entirely different matter for fund managers, who handle other peoples' cash. That's not my bag. Tried it briefly, it's horrible.
love it Paul. It’s refreshing to read your response to various comments on here . Am also a shareholder in RBG,and will continue to acquire on weakness. Thanks for your candour and professional expertise.
Hi Paul
Thank you for your fascinating report today.
Whilst I am considerably more risk averse than you, it is incredibly helpful of you to not only analyse individual shares but also let us into the mental process which allows you to feel comfortable to hold such a large quantity of a relatively illiquid stock, where future trading is so up in the air currently.
As I hold GAW in size, your analysis of DNLM is also very interesting... ...I would really like GAW to also re-open online!.
And I wish I had bought back into VLX a few weeks back when it was becoming obvious that it was trading well.
I hope the various positions you mention work out for you, particularly the one in RBG. I would certainly be unable to sleep if I held that much RBG but hopefully that will be my loss not yours.
Kind Regards, Martin
Paul, I am puzzled by the disconnect between your view of the economic situation (yesterday's SCVR) and your own trading activity. You appear to be focusing nearly all buying on the sectors that are worst affected by the lockdown (e.g. retail, leisure, property) whilst simultaneously expecting a more severe economic shock than the market is currently predicting. Surely your trading strategy will require a v-shaped recovery to succeed (especially those hanging on by a thread like Revolution Bars (LON:RBG)). Am I missing something?
Re: Dunelm (LON:DNLM)
The prospect or reopening stores soon sounds good. But.... Dunelm (LON:DNLM) sells discretionary items. People who are worried about their jobs and their businesses tend to buy the essentials (food+++) and put off purchasing beds and sofas. I don’t imagine that the post lockdown recession is going to be a good time for companies like Dunelm.
JulianH That for me is the issue with the hopes of a V shaped recovery. Governments, corporates and individuals will, hopefully, be in balance sheet rebuilding mode. They will be, again hopefully, paying down debt and restructuring balance sheets to be more “Antifragile”. We don’t know what the next shock will be (Euro collapse, Trump second term, another virus, a weather event, a true black swan as opposed the white swan that was the current pandemic) but we do know there will be one in the lifetime of most of those reading the SCVR and our lives and in our investing strategy (I had partly followed my own advice but not sufficiently to take a real pasting in March).
I think that this will mean we all have to recalibrate our expectations for returns on capital employed and therefore stock price trajectories.
I have bought heavily into RBG (nothing like Paul Scott though.....just a lot for me). I also just see it as an option on the drinking sector! I certainly would not blame anyone else if this goes down. My view is that almost everything is a punt at the moment; there are no "investments" and if the markets turn nasty, nothing will be safe. I am also interested in other very risky stocks such Intu, the owner of many shopping centres and ESL, the holding company of Eddie Stobart , the truck company. I believe that fortunes will be made at this time and the "winners" will only be known in hindsight. Look at the testing company NYCT; from 6p to over £5 in six months. I agree with a comment made elsewhere; for the moment the stock market has become a casino. But then....how many front line staff are gambling with their lives daily?
Re. Revolution Bars (LON:RBG)
I have carefully read Paul's and Graham's analyses and frankly, it all comes down to risk appetite.
The following is based on my assumptions.
Let's assume a 50:50 probability of the lockdown being lifted no later than June and the millennials flocking back to the restaurants and bars. Under this scenario, let's assume RBG shares multi-bag by a factor of 5.
So for a £100 investment, the expected gain is (50% x 0 (loss outcome) + 50%x500 (gain outcome) } = £250.
In other words, a 2.5:1 punt with a 50% chance of being wiped out.
Conclusions? You can take this bet and size your stake according to your risk appetite, and what will make you sleep at night.
Personally, I am seeing a number of better opportunities in the market with better capital protection prospects.
The rational approach to a 50% risk of wipeout, but with outsize gain on the upside, would be small and many bets.
Yes the snag is always trying to find enough similar situations that you can have confidence that the overall outcome across a portfolio will be representative of the risk:reward probabilities.
Germany latest:
Large public gatherings including religious services will remain banned until 31 August. Bars, cafes, restaurants, cinemas and music venues will all remain closed.https://www.bbc.co.uk/news/world-europe-52299358
Thanks Tom.
You helpfully provided the following:
"Germany latest:
Large public gatherings including religious services will remain banned until 31 August. Bars, cafes, restaurants, cinemas and music venues will all remain closed.
https://www.bbc.co.uk/news/world-europe-52299358"
What I couldn't work out from the BBC article and from trying to read various German publications with my very limited AS Level German was whether "remain closed" meant until August 31st or until further notice. Thoughts?
Hello abtan,
This link to the German government website (in English) might help:
https://www.bundesregierung.de/breg-en/news/fahrplan-corona-pandemie-1744276
:)
I would call this setting the stage for great news at Whitsuntide when restrictions will be lifted.
Through my job I've found out today that the current lockdown will be in place until the second half of May/early June at the earliest. After that things will gradually be opening up again.
Cinemas, concerts, festivals and similar activities will likely be closed for a much longer period. Restaurants/pubs/bars might start opening up, but they will have to follow certain social distancing measures, which I believe will be similar to what we have been seeing in Sweden for the last couple of weeks. The transport system is likely to continue running a reduced service, and workers who can work from home, will still be encouraged to still do so.
This will probably change as and when we know more about the new number of cases and deaths, but hopefully it gives you a bit of a guideline of what to expect.
Regarding bars e.g. Revolution Bars (LON:RBG) comments seem to be focused on a black and white trading/not trading distinction. I think a more likely scenario when they are initially allowed to open will be trading at reduced capacity i.e. trading with limits on the number of customers allowed inside. It seems likley to me that the kind of regime that we are becoming used to at supermarkets will apply across other sectors such as non-essential retail and hospitality.
Bars and night clubs will be at the back of the queue to reopen. But if they are to reopen at all while there is any onging social distancing, then the last thing the govt will want is pictures in the papers of crowds of drunk people hugging each other. One thing they might do would be to say you can have so many people per sq ft. The rozzers would wander around and shut down anywhere that looked crowded. They may also enforce closing at say 9pm.
However it's done, I would be surprised if the govt didn't try to restrict trading. How long will this last? Well it sounds as if the govt is very lukewarm about a testing and tracing regime, so it would last until a vaccine has been delivered at scale, which would probably be summer 2022.
This is all good news if you want a job as a doorman, or if your bar was never crowded anyway, but not so good for previously very profitable venues.
I am in France (under lockdown) and here bars, restaurants etc are staying closed at least until July (so read September IMO). The UK is behind the curve compared to France so one has to consider the very real possibility of UK bars, restaurants etc being shut until say November(?).
Besides, even if lockdown is “cancelled” before a vaccine or treatments is readily available, are people really going to rush out and risk infection (even ignoring the likelihood of them being strapped for cash)?
Hi Michael
You helpfully provided the following:
"I am in France (under lockdown) and here bars, restaurants etc are staying closed at least until July"
Is this 100% happening/the law? Or hearsay? Partially closed or fully closed?
I appreciate you may not know the answer to the above, but thought I would send it back your way in case you did.
Thanks!
A
Revolution Bars (LON:RBG) is not a company that I follow. But its future seems to be largely outside its control. Resting largely on when and how the Government lifts the lockdown. And, very importantly, how its customer base reacts. If the lockdown stretches to say seven weeks, that could be enough time for habits to be changed or replaced. The re-opening of its bars might also coincide with bad weather. Which I would assume will be bad for business. While in the background, is a banking facility which will come up for review in September 2020.
It could, as you mention, tap into huge pent-up demand. In which case the stock price will probably rise substantially. But it does strike me as a gamble rather than an investment.
As I understand it, from a relative who has been in the nightclub business, good summer weather is the worst thing for the bars without gardens, which I presume is RBG's situation.
Revolution Bars (LON:RBG)
As I understand it, from a relative who has been in the nightclub business, good summer weather is the worst thing for the bars without gardens, which I presume is RBG's situation.
That won't be the case for all of RBG's outlets - for example the Durham branch was rammed last time i was in on sunny saturday afternoon. I think the chester branch was similarly busy when i tried that despite it not having the best location.
Interesting question as to what percentage of their bars have good summer daytime trade ?
I am on this board because I am prepared to take the risks that come with small cap stocks; the reduced liquidity, wide spreads, more limited access to capital, greater exposure to unexpected shocks and so on. But I am not seeking out extra operational risk.
Much of the value in this site is the to and fro of different views backed up by analysis - and yet, RBG?
With Revolution Bars (LON:RBG) we have a company that has not made any money since 2017, is on banking life support with a four month deadline on a debt pile that probably exceeds its gross annual sales and has all its businesses indefinitely closed. It’s equity has declined every year for the five years, but still has never exceeded a far from stellar ROE of 12.6. The sales have never managed other than a leisurely growth ( the turmoil of opening and closing new premises is not an “exceptional cost” in this type of business), there is certainly not demonstrated “fizz” - unlike their drinks.
This is not a cheap stock, it simply has a low price.
So there we are, I am now fully exposed and Paul can come crowing when it roars back!
Paul,
Can I confirm that it's not a typo, you have 3% of Revolution Bars (LON:RBG), not 3% of your portfolio?
Cheers.
Adding up the figures, actually it's about 2.6% of Revolution Bars (LON:RBG) that I now hold (1.3m shares). Yes, that's % of the company, not my portfolio. I never imagined holding that much, but I bought heavily at the recent lows, at about 18p per share average.
It's essentially a fairly high risk punt on bars being allowed to trade again from c.July onwards, hopefully. It could go disastrously wrong, which I've budgeted for.
Anyone who decides to follow me into this, absolutely must do their own proper research & take ownership of the decision.
I've never asked anyone to follow my trades, as it's got zero upside for me - they take the credit if it goes well, and blame me if it goes wrong LOL :-)
I mentioned it in the SCVR because it's such a bold move, that clearly readers need to know that my commentary is bound to have some unconscious bias, even though I also try to balance it with downside risk comments.
The positive update from Volex (LON:VLX) is well worth a read. An inexpensive, well financed company with good growth potential in electric vehicles, data centres and complex medical devices. Strix (LON:KETL) also shares many of the same characteristics, again inexpensive, excellent cash flow and cash conversion and using its technology to expand into growth markets of water filtration/purification. The latter point was one of Philip Fishers criteria discussed in his book 'Common Stocks, Uncommon Profits'. Also both have committed to dividend payments.
I hold both, having sold early due to the their exposure to China, but being lucky to be able to buy them back in the market chaos.
This is just my view and others may think differently.
Keep well.
Great update from Volex (VLX) Here is a company that is finally doing everything right. Check it out.
Paul thanks for your report on RBG plc, in my view the company is significantly undervalued. Most bar and nightclub companies make a disproportionate part of their annual turnover between September through to New Years Eve, the summer is the trough of their trading year, so as long as the country is back to some sense of normality by September companies like RBG should trade very well in that period. Plus their customers 18 – 24 year olds, are either students, or just starting in jobs market which will in the main be protected by government furlough scheme. They won’t have been away for a summer holiday and will have reduced their outgoings significantly, so hopefully have some money to spend when things pick up again.
I have to say I don't see the situation for Revolution Bars (LON:RBG) playing out so positively for the following reasons:
a) I suspect that bars, restaurants, cinemas, and sporting events will be the last industry sectors to have their lockdowns lifted. Not only that, but after months of relentless 'avoid each other at all costs' messaging, there is a minor (pretty minor) social stigma about gathering in place. A further concern for me if I was invested in bars and/or resturant groups would be that I suspect we will be into the second wave of infections and therefore second lockdown before a drink is poured.
b) I don't get a sense that there is a pressure cooker building amongst the young who are ready to party all night. Now, granted I am in my late-30s, but my junior associates at work have been complaining about how much they are drinking at home just to get through the lockdown and won't it be nice just to be able to go for a walk etc. I get the sense that when lockdown is lifted people will stagger out of their caves in dribs and drabs
c) the young are the the least experienced and therefore most expendable in any workplace. I suspect (but don't have the figures) that they will form a disproportionate amount of the newly unemployed, and for many, their entry-level positions will simply evaporate.
The above is total speculation, passing from an amateur to a pro, based largely on anecdote, so take it for what it is worth. However, I would be very concerned that the second lockdown will be here before the first one has lifted for bars and restaurants.
In terms of your point b - they can go for a walk now and whilst the millennial's are less inclined to get smashed beyond belief they love to socialise and will definitely be out for a good time.
In terms of c) In the 2008 crisis I knew of very few youngsters unemployed (my friends) as they were cheap resources and "green". Those that were, managed to be re-employed quickly I assume its easy to find jobs paying less than £40k however for the more experienced looking for £60k plus its not a quick turnaround. I was working as a consultant at the time of the GFC crash and the amount of "deadwood" I saw in our major banks was frightening, I assume most were cleaned out during and after the crisis and replaced with the younger and more eager.
Agreed re the second wave, its an unknown but the economy and leisure type shares will struggle if it appears
Part of the reason for lockdown was to "protect the NHS"; by the time of a 2nd wave (say Sept/Oct), they will have built capacity and learned lessons. The "stay at home" message will be addressed only to more vulnerable groups (old and unwell).
I do agree apart from maybe one big "Escape Party", demand will not be at/above previous levels but equally the desire by the 18-30 crowd to party will equally not be less. I think habits may change and they will go back to "saving" during the week with 1 big blow out at the weekend. We may also see a move to underground/house parties where drugs/supermarket drinks replace expensive cocktails in a bar.
The key for Revolution Bars (LON:RBG) is thus :
i) how much disposable income does this group have ie how badly has unemployment hit it
ii) how many city centre competitors go under & how quickly new bars/clubs replace them. Here I am a bit more positive, as a lot of independents will probably fail
Net, I am now more confident Revolution Bars (LON:RBG) will survive (good news as a holder) but not very optimistic. I wont see dividends for 2 years at least. I find myself (once again !!) hoping for a good return from them on a 2+ year basis.
At least if Paul is up to a near 3% share I can be sure of extensive commentary :)
I am not a holder but can see the dichotomy in views. I take the view there will be a selective release from lockdown but I am unconvinced that bars will be in the first wave. I think it will be let’s see the impact before moving to those environments where social distancing is harder to manage. This does not seem to suggest that bars etc are an area to invest in as yet. I am not sure anyone got rich by trying to second guess Government policy but I may be wrong. Were I to invest in this sector Fullers seems better placed but just my thoughts .....
Yes there is certainly signficant economic pressure to start releasing lockdown as soon as possible. Though it's generally acknowledged that the UK is 2-3 weeks behind places like Italy and Spain, so the start of any relaxation is not imminent. Any initial steps will be, as elsewhere than bars, in allowing a wider range of non essential work and shopping to take place, probably with clear guidlines and adjustments to promote distancing. Activities that potentially bring large numbers of people into close contact will be last. Possibily phased opening of restaurants, and perhaps bars with food, where table sizes and density can be reduced. But partying at bars and anything like that is going to be a no-no for some time to come. That would be surest way of starting to spread the virus amongst the population again rapidly, and might well have to lead to reintroduction of total lockdown, which would be the thing everyone would wish to avoid.
The main problem with RBG I would argue is it doesn't own the bars, and has £10m of annual lease charge. Therefore the gearing is substantially higher than one would imagine - clearly if they generate £10m plus EBITDA ( after lease) they survive and generate some equity. Its a brave call because sitting on the asset and waiting for the good ( better) times to return is costing hard cash in lease commitments.
The leases are not a problem at all, providing the bars can actually trade! That's because in aggregate, RBG's sites normally generate strong cashflows. Why would anyone see their lease as a problem, if a site is profitable? Answer - they don't. Although obviously right now, with the sites closed, then leases are definitely a problem - landlords want rents, whether sites are trading or not, although many are being flexible generally.
Another important point, is that about 9 sites were put on uncompetitive rents (onerous leases) to raise cash, in around 2008 I think, well before IPO. This has been a drag on the company of about £1m p.a. cash outflows. This has now been sorted, with a recent deal with the landlord on all those sites. RBG has kept the profitable ones, and extended those leases, and the landlord has taken back the loss-making ones. This deal was also amended recently, to reduce the payment, and defer a lot of it - a cracking deal.
Companies that own freeholds are not necessarily better off, because freeholds come with a ton of bank debt - which could be a bigger headache than leases, if covenants are breached.
My point is just its very geared - if you had £20m to £30m of debt against £80m of property - this would be conservative. What you actually have is £30m of debt against a brand. You borrow your £80m of property.
A good bar/pub can have good management, be a good site or a good concept. You pay your staff and management. This leaves the profit to share between the site and the concept. If you don't own the site you lose a decent chunk of return. If the brand loses its appeal the site still has value. RBG is a virtual business, that doesn't make it a bad one, and yes I can see a path to the 5x....although one turn has been gobbled up in additional borrowing. However its binary and you have no protection ( asset value). I don't disagree with you that all the kids will party like its 1989 ... if its 2021 and not 2020 though RBG have a problem.
Personally I like a bit more protection in my largest holding that's all.
I don't disagree with you that all the kids will party like its 1989 ... if its 2021 and not 2020 though RBG have a problem.
Well, yes, but having lots of young people in a confined space drinking copious quantities and failing to observe social distancing is a Covid-19 infection multiplier nightmare, especially given Britain's youth drinking culture. Clearly it's possible bars may re-open fully in a month or so but I'd have thought it more likely that there'll be a partial re-opening with restricted licencing hours and limited numbers allowed inside which will obviously have an impact on cashflow.
If Neil Ferguson is to be believed we'll have those kind of measures in place for at least a year, possibly more. Relaxing suppression measures would see a resurgence in cases - and the problem, lest we forget, is not about saving the lives of a few economically useless old people (*) but in ensuring that the NHS isn't overwhelmed so that lots of younger people don't die because they can't be treated for otherwise non-fatal conditions.
A gradual re-opening is likely to be accompanied by the government phasing out a lot of the business support measures although I'd imagine bars and restaurants may get some special treatment. But - as we can see - there's lots of speculation in even a simple analysis. Happy to sit this one out in my back garden with a bottle of beer.
timarr
(*) That's irony, in case it's not immediately obvious.
£RBG I think Paul said "nearly 3%".
Good spot, thanks.
Paul, if you own 3% of Revolution Bars (LON:RBG) don’t you need to tell the company so they can put out an RNS showing you as a major shareholder? Just a thought.
Over 3% ==> RNS
Nearly 3% = =>no RNS
My morning smallcap tweet:
Haydale Graphene Industries (LON:HAYD) Brooks Macdonald (LON:BRK) Hornby (LON:HRN) £Group Induction Healthcare (LON:INHC) Woodbois (LON:WBI) Charles Stanley (LON:CAY) Capital Drilling (LON:CAPD) Management Consulting (LON:MMC) Walker Greenbank (LON:WGB) Dillistone (LON:DSG) Escape Hunt (LON:ESC) Proton Motor Power Systems (LON:PPS) Volex (LON:VLX) £N4P Biome Technologies (LON:BIOM) Collagen Solutions (LON:COS)
Haydale Graphene Industries (HAYD) general slowdown in a number of its markets, especially for Silicon Carbide blanks due to aerospace slowdown. CO fall markedly short of its trading expectations. Facilities are operational. Co has sufficient reserves to adequately manage the anticipated impact of COVID.
Brooks Macdonald Group (BRK) Q3 revenues 'held up well' with higher transaction revenue partly offsetting the lower fees. If markets at YE(June) are broadly in line with current levels co expects a 'satisfactory' result, with underlying profit marginally ahead YoY.
Hornby (HRN) FY(March) in line. "Whilst the Group will not be immune to the effect of the virus, it has started the new financial year in a strong position following the completion of the fund raising."
DX (Group) (DX.) reduction in delivery activity since lockdown of ~33%. Co "has the operational and financial capacity to navigate this challenging period."
Induction Healthcare (INHC) covid has had minimal impact on our operations. INduction App user base has increased by 10% since end Jan., MicroGuide app up 6%. "Our strong balance sheet and net cash position give us enough leeway to deliver new features to support the healthcare community and fund our active acquisition pipeline when market conditions stabilise."
Woodbois (WBI) Q1 rev up 10% with no discernible slowdown in demand evident until the end of Q when new enquiries tailed off sharply. Gabon activities temporarily halted by a lockdown. Dependent on loans from largest shareholder.
Charles Stanley Group (CAY) FuM down 20% since Dec. FY(March) rev up 11.4%. Comparatives for FY21 are expected to be far less favourable. Commission income is currently holding up well since greater market volatility is leading to more trading. Co confident about the strength of the Group's balance sheet and liquidity position. May pass div.
Capital Drilling (CAPD) Q1 rev up 6%. Covid: mining and production activity have continued uninterrupted . Gold price remains highly supportive.
Management Consulting Group (MMC) majority of its projects suspended or put on hold. Een on a worst-case basis, the Group has adequate resources to be able to operate for the foreseeable future but a material uncertainty in the Group's ability to generate revenue.
Walker Greenbank (WGB) continuing to serve its customers in all key territories from warehouses in the UK and the US. Almost all other trading activities have been reduced significantly. Co "has headroom in its existing £12.5 million revolving credit facility. Significant progress has since been made with the Company's lenders in obtaining a temporary overdraft facility of £2.5 million, the terms of which have been agreed, for use if the Company needs further funding."
Dillistone Group (DSG) pre covid co had a strong start to the year, with orders comfortably ahead of internal targets but now a significant reduction in demand. FY will be significantly below expectations. Won't tap shareholders if it get a Gov't backed loan.
Escape Hunt (ESC) cuts monthly cash costs by ~70%. Has launched its first downloadable, 'play at home' escape game, 'Stolen'. No reassurance on liquidity.
Proton Motor Power (PPS) no negative COVID-19 impact and remains on track to fulfill all deliveries to customers.
Volex (VLX) reiterates current FY guidance of rev over $392m. Expect 2p div.
N4 Pharma (N4P) initial proof of concept work on usng Nuvec to develop covid vaccines will commence during the first week of May.
Biome Technologies (BIOM) FY(Dec) rev down 16%, pretax -£1m (+£84k). You have a scroll a long way to see these figs. Poor. Co has enough cash for 12 months from the date of approval of the accounts. Covid will further delay any upturn in orders for Stanelco RF's furnaces.
Collagen Sol (COS) following an approach co starts a strategic review.