Small Cap Value Report (Thu 16 Dec 2021) - RWA, MCB, SMK, BMY

Good morning, it's Paul & Jack here with the SCVR for Thursday.
Agenda -
Paul's Section:
Boohoo (LON:BOO) - trading update - too large for the SCVR now, so I've posted my comments on the BOO thread, which is here. Please would you post your comments using that link there, rather than cluttering up this article, which some subscribers get uppity about! Many thanks.
Mcbride (LON:MCB) - oh dear, another profit warning - with continued input price inflation being the problem. It's trying to raise selling prices again, but that takes time, impacting profitability. Now trading at a significant loss, and in talks with the bank over covenants, makes this too risky for me to want to consider investing.
Jack's Section:
Earlier in the week I had the pleasure of talking through some small (and large) caps with Paul Hill and David Thornton. Great guys, both full of enthusiasm for the markets and their own investment ideas. Here's a link to the YouTube upload - have a watch and let me know if you have any thoughts on the stocks covered.
Robert Walters (LON:RWA) - another upgrade for this recruiter. The stock has rerated and is close to all-time highs but, with wage inflation across a number of countries, the near-term outlook continues to look positive. The StockRank of 96 and Quality Rank of 98 are positives, so it looks like a good candidate for those looking for exposure to labour shortage and wage inflation themes. Broker estimates are behind the curve.
Samarkand (OFEX:SMK) - I hold - H1 business disrupted by supply chain challenges for its customers, although an improving trend has been reported from October onwards. The stock itself has a lot of growth priced in and there’s not much trading activity, so there’s downside risk. Of more interest is the read across comments on supply chain.
Bloomsbury Publishing (LON:BMY) - acquisition of US-based academic publisher. Bloomsbury says it should be able to use its Digital Resources division to scale ABC’s digital offering. There have been a few acquisitions here recently, and BMY still has cash, so it’s worth taking a closer look at the growth strategy IMO.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul's Section:
Mcbride (LON:MCB)
53p (down 10% at 09:22) - mkt cap £93m
Financial Year 2022 trading update
McBride plc (the "Group"), the leading European manufacturer and supplier of private label and contract manufactured products for the domestic household and professional cleaning and hygiene markets, today provides the following trading update ahead of the close of the first half of the financial year on 31 December 2021.
The current financial year is FY 06/2022.
Supply chain & inflation -
… raw material and packaging costs have continued to experience very significant inflationary pressures with availability continuing to impact our supply chain efficiency. In addition, the shortage of haulage capacity and even higher fuel costs has not abated and have continued to substantially inflate distribution costs.
As we know, inflation is all around at the moment, and companies have to be able to raise their selling prices, to protect profit margins.
Price rises -
McBride has been actively engaged with all its customers to secure substantial price increases to mitigate the impact of these exceptional cost rises affecting the whole industry. Our early increases in late summer have now been outpaced by further rises in input costs and hence further pricing action has been underway more recently.
It is pleasing to see the support of most customers to these price increase requests with the effect of these further increases starting to benefit December trading and delivering more fully from January onwards.
Revised guidance (profit warning) -
The Group now expects to report an adjusted loss before interest, tax and amortisation (EBITA) of between £14m and £17m for the six months ended 31 December 2021. The increase in this loss compared to our previous update in October is a consequence of the ongoing rapidly rising input costs and the timing of pricing agreements. At this stage, our wide range of outcomes is a result of pricing delays with a small number of customers and the resultant implications, which could impact short term volumes.
Checking back my review of its last profit warning here on 19 Oct 2021, previous guidance was a £(10)m loss on the same basis (EBITA).
The £(14)-(17)m revised loss for H1 is a big number, considering it’s for only half the year, for a company with a market cap of £93m. This is starting to look worrying to me.
Liquidity & bank covenants - also worrying is the mention of bank covenants, so it sounds as if the company could be heading for a breach of them. It’s rare for banks to pull the plug in this low interest rate environment. However negotiating revised covenants could mean possibly higher fees & lending margin from the bank, and the risk that the bank might insist on an equity raise to reduce its risk. So be aware that the risk of dilution has just increased a lot. What I don’t like in these situations, is that we have no way of knowing how supportive the bank will be. Some banks seem to be remarkably relaxed when problems emerge, whilst others lean heavily on management to raise equity at the first sign of trouble. It’s the uncertainty I don’t like.
McBride continues to enjoy a strong liquidity position with c.£80 million in available cash at hand, and we are currently in supportive and constructive discussions with our bankers regarding our December covenants.
My opinion - as mentioned before, in inflationary times the last things I want to be invested in, are very low margin suppliers of anything. A low net margin tells us that the company’s products are not sufficiently differentiated, and that there’s lots of competition.
Being in that position when costs start rising considerably, is a bad place to be, because -
- There’s no buffer to absorb cost increases, given that profit margins were already so low, and
- It takes time to persuade customers to accept price rises, hurting profits at least in the short term
- There’s a risk that some customers might have fixed price contracts, which of course the customer could refuse any price rises for the contractual term
Overall - this looks a very unappealing investment right now, and wasn’t particularly appealing to start with. Why get (or remain) involved, when the risks are increasing? Upside could eventually come from a turnaround, but when is that likely, and is the company going to return to profitability, if so how much? Will the bank remain supportive? How much dilution might occur if it's forced to raise fresh equity? There’s too much uncertainty here for me. With a battered portfolio, I want to pick my spots carefully, where the situation is an absolute no-brainer. I don’t see that here.
.
.
Jack’s section
Robert Walters (LON:RWA)
Share price: 766.47p (+1.12%)
Shares in issue: 76,612,035
Market cap: £587.2m
We saw Sthree (LON:STEM) down earlier in the week on what looked like decent results. After such a rerating, I suppose the market was looking for a little more in terms of fireworks. The shares there are still comfortably up on the year (from c300p in January to 459p at yesterday’s close).
Still, it’s a reminder that staffing company shares go down as well as up and are historically quite volatile, even though they are currently benefiting from positive conditions with wage inflation increasingly taking hold.
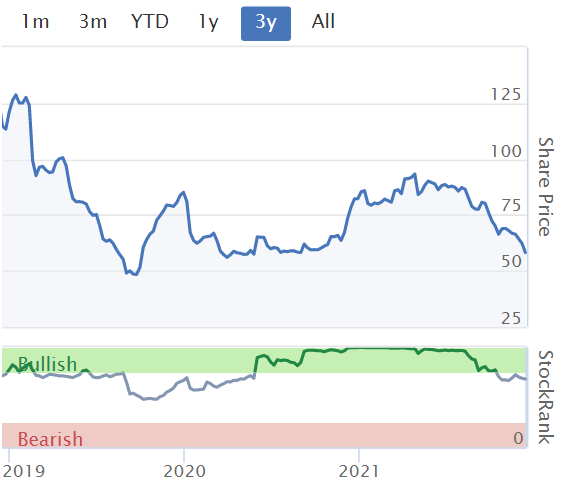
Robert Walters stock has underperformed the market by c7% over the past month but has outperformed by 50% on a one-year view. The long term chart shows how close it remains to all-time highs.

The StockRanks remain strong here at 96, with a notable 98 for Quality, although operating margins are quite low.

Another short update:
The Board of Robert Walters plc announces that as a result of strong trading across all regions in the first two months of the fourth quarter and improved visibility in respect of December trading, profit before tax for the full year ending 31 December 2021 is expected to be comfortably ahead of current market expectations.
The group will publish a trading update for the fourth quarter ending 31 December 2021 on 11 January 2022.
Conclusion
Current expectations are for 37.3p of earnings per share for 2021. How much will ‘comfortably ahead’ equate to? This is not the first time RWA has announced that it is trading ahead of expectations this year. Last time I looked, the group had just reported c21p of EPS at the halfway stage of the year while FY forecasts were for just 33p. I think the estimates are stale here, and brokers are suffering from incrementalism.
So I’m assuming the forecasts are just anchored at too low a number.

EPS in the 42-45p range would give an FY21 PER of 17.0x - 18.2x. Not overly expensive, but not obviously cheap for a company whose outlook is tied to economic conditions. At some point, perhaps market participants will seek to look through current trading towards some sort of downturn or moderation.
That said, Robert Walters is a fundamentally well run business and conditions are presently favourable. This shows no sign of slowing down. Recruiters are often some of the first stocks to recover from a downturn, so the question is whether the share prices here have further to run. That depends not just on trading performance but also market sentiment.
For now it’s hard to argue against that backdrop of labour shortages and wage inflation. It’s a global business, too, which separates it from some of its listed peers. My impression is that the current recruiter cycle has further to go, with salary inflation evident in many developed countries.
Samarkand (OFEX:SMK)
Share price: 160p (unchanged)
Shares in issue: 51,618,966
Market cap: £82.6m
(I hold)
I’ve just had a call with management here.
Samarkand is listed on the Aquis Exchange and does a few things. At its core, the group’s Nomad tech is designed to integrate with China’s consumer market. This is trickier than it sounds and is a barrier to entry for many overseas businesses looking to win share in the world’s largest ecommerce market.
Samarkand also has three of its own brands selling consumer healthcare and fertility products. Sales here are more focused on domestic markets, but the plan is to leverage the core Nomad tech platform to sell them in China.
There’s a lack of liquidity here though and the stock is listed on the Aquis Exchange. While the potential is huge, Samarkand is still early on in its journey in terms of revenue and profits, so there’s a lot of future growth priced into the £83m market cap.
Reading the room, it’s the kind of growth story that the market doesn’t really have time for at the moment, but the company’s comments about supply chains are of interest.
- Revenue of £7.2m, flat year-on-year against strong comparable period,
- Nomad technology revenue is up 15% and brand ownership revenue is up 13%,
- Wholesale distribution part of the business has been deprioritised as planned and revenue has decreased 31% from these activities,
- October and November trading was 15% and 25% ahead YoY respectively ‘with this trend continuing to accelerate significantly into the first two weeks of December’.
- Adjusted EBITDA loss was £2.6m (H1 2021 profit: £0.3m) which reflects the ongoing investments,
- Continues to enjoy a strong balance sheet with cash and cash equivalents at 30 September of £10.4m.
FY22 (March end) forecast is for revenue of £22.6m, which implies there’s a bit of catching up to do. Supply chains are currently the biggest challenge facing the group and that’s the area I was hoping to get a bit of insight and wider read across on.
For Samarkand itself, getting product from customers into China is not the problem. It’s getting product from the customers, who are facing supply chain issues and component shortages that’s the issue. Samarkand’s customers are consumer businesses looking to increase their cross-border trade.
To summarise the key points from the conversation:
- October, November, and December performance at SMK has improved due to adapting to global supply chain issues.
- The group has invested in more stock (inventory of £3.5m compared to the £1.9m at the same point in the prior year).
- Disruption has been from existing brands being out of stock or struggling to give guidance on stock, which SMK needs in order to plan a couple of months ahead for key trading periods.
- ‘People have realised that just-in-time (JIT) is not going to cut it for the foreseeable future so there is more stock-building’.
- There was a lag period while people tried to make JIT work.
- The situation is ‘starting to stabilise a bit’ but there was definitely a period when nobody seemed to know when they would get products or components.
- Managing supply chains continues to be the key challenge in the short term.
Conclusion
A challenging time for an ecommerce tech company to IPO and find its feet.
Re. Samarkand itself - there’s some catching up to do to hit forecasts but longer term it’s a question of whether or not you think the company’s strategy of building out a tech platform that facilitates cross-border ecommerce is likely to be a source of enduring value.
There has been promising operational progress, including good traction from customers and SF Express coming on board as a very big partner. The group says it is in talks with some other large enterprises that could accelerate growth in ecommerce tech, payments, and logistics.
But there is a lot of growth already priced into the shares and the conditions right now are difficult, so there’s a derating risk here. I wouldn’t be surprised if shares fell in the short term. It’s really a lack of trading activity keeping them up at the moment.
I’m not flagging it as an immediately enticing investment prospect - of wider interest are the comments on supply chains. It seems like JIT just isn’t cutting it at the moment, which means many operators are having to build up inventories. Low margins and stretched balance sheets are at risk over the next few months at least.
Samarkand says the situation is showing signs of stabilising, but I still view this dynamic as a key risk to the global economy. Working capital management is important now. In the coming years, I wouldn’t be surprised to see companies shorten and ‘reshore’ their supply chains.
Prices are rising, pushing up inflation. The CBI reported in October that stocks in relation to expected sales were at a record low for the seventh consecutive month. The Bank of England’s view is that the worst of the disruption will have eased by early next year, but for now, it’s a dynamic that continues to drive market sentiment.
Bloomsbury Publishing (LON:BMY)
Share price: 351p (+5.72%)
Shares in issue: 81,608,672
Market cap: £286.4m
Bloomsbury has spent much of the past five years with an SR of above 90. Its shares have more than doubled in that time, with dividend payments to boot.

At this point, a growth catalyst is needed in order to keep the shares interesting as there has been an expansion in multiples here. Earnings per share forecasts have been increasing and the group has been making a couple of acquisitions, although I’m not familiar enough with the situation to say more than that.
It does seem to have led to a slight shift in perception re. how to value this share though.

Bloomsbury has acquired ABC-CLIO for $22.9m (£17.3m). This is an ‘established academic publisher of reference, nonfiction, online curriculum and professional development materials in both print and digital formats for schools, academic libraries and public libraries, primarily in the USA’.
Purchase price | Revenue (CY2020) | PBT (CY2020) | Gross assets |
$22.9m | $14.7m | $1.2m | $12.5m |
Strange that Bloomsbury does not give a net assets figure here, just gross.
The company was founded in 1955 and is based in Santa Barbara, California, providing ‘curriculum-aligned content and lesson plans, professional development support and student activities to US schools and academic institutions’.
In the remaining two months of Bloomsbury's financial year ending 28 February 2022, ABC-CLIO is expected to contribute approximately £2.1 million of revenue and £0.3 million of profit before tax, prior to integration and acquisition costs. It should be earnings enhancing in the current year.
Conclusion
It’s this move into digital and academic publishing that is of interest, so good to see an acquisition here. More of a focus on academic publishing presumably means income is more dependable.
ABC-CLIO strengthens Bloomsbury Digital Resources and accelerates Bloomsbury's academic publishing in North America. The business will operate within Bloomsbury's Academic and Professional division and ABC-CLIO's 32 databases will be included within Bloomsbury Digital Resources, enabling Bloomsbury to scale ABC-CLIO's digital offering globally.
The deal itself doesn’t look particularly cheap, but some of that depends on just how well the business fits in strategically with Bloomsbury. The group’s ability to scale ABC’s digital offering could explain the price.
ABC looks like it has a strong reputation as a ‘long-standing and respected American publisher of academic reference, nonfiction, online curriculum, and professional development materials in print and digital formats for academic institutions and schools, faculty and students, and public libraries.’
I remember thinking a few months ago that full year forecasts for Bloomsbury were leaving room for an ‘ahead of expectations’ announcement at some point. The group has a net cash position and is putting that to work with a few acquisitions, so it’s worth tracking back to properly go over the group’s growth strategy.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

53 comments
I know there's a Boohoo (LON:BOO) thread but this is not Boohoo related directly...
Saw that Quiz (LON:QUIZ) dropped -13% today, probably a read-across from Boohoo as they sell lots of partywear, and likely hit by the same huge increase in returns?
But the difference is that Quiz (LON:QUIZ) still does lots of retail store sales, which are less impacted by returns. I haven't looked at Quiz in a while since they rocketed above 20p, but it looks like it might be now getting closer to a good value to buy.
(I don't hold either)
Yes, I think you're probably right. I wouldn't put them in the same demographic as Boohoo (LON:BOO) either
1) They have more sales from stores - returns will be less : plus they have introduced more loungewear so little less reliant on party scene.
2) It's a more expensive product so I suspect purchasers will just keep a purchase and wear it next time rather than return it. Whereas a 20 year old smack bang in the Boohoo (LON:BOO) demographic may well want the money even if it is a much lesser amount. I know mine would!
3) Rents are now revenue based so lower revenues will result in lower costs helping with margins.
I do hold Quiz (LON:QUIZ) for the longer term. I'd imagine there will be some level of impact on sales given this week, but hopefully not major.
REACT (LON: REAT)
I promoted this stock here in the past. I am writing now to say I have sold out entirely. It has taken a long time to sell.
I had a chat with management which did not impress me. It seems to me that they promoted the stock a lot so their options would kick in and haven't bothered much since. I am concerned that future updates aren't going to be particularly good and I prefer to invest where I have confidence.
Hi Michael,
I see that React (LON:REAT) has gone all the way back down again. It looked very much like a stock promotion, jumping on the bandwagon of covid, and making exaggerated claims about what it did (just a contract cleaning company), and the supposed potential.
This type of business should only command a very low PER, as there's so much competition, margins are not likely to be sustainably good. And why is something so small listed on the stock market? What a waste of money, with listing costs and management time, cost of NEDs, etc. So de-listing risk would be high.
I think the tiniest shares on the stock market are generally best avoided. De-listing risk is too high, there's little market liquidity, and they're generally rubbish businesses, with poor management. Occasionally a little gem appears and you get a 10-bagger, but it's so rare - even the ones that do ten bag, usually come back down again after a while because they were speculative spikes, not genuine value being created.
Regards, Paul.
Paul,
We don't seem to hear much from the expounders of 'The New Monetry Theory', these days. I wonder why that is?
JASPERTHEDOG,
We don't seem to hear much from the expounders of 'The New Monetry Theory', these days. I wonder why that is?
Sorry I don't understand your point. What is this supposed to mean?
P.
base rate raised to 0.25%
Yes, good. And also cease the QE programme at the end of this month. Although they have accumulated 895 Billion in mainly govt bonds, which looks sticky.
This is a heck of a percentage increase from 0.1%.
I would appreciate a look at SigmaRoc £SRC by you guys, if the Mkt cap is not too large for you
Good Morning Jack,
I watched your Vox Markets vid yesterday afternoon and consequently am doing some work on Centralnic (LON:CNIC) this morning. You and Paul discuss a very important point about the importance of the skill and hunger of Management of Small Caps, not something that is always easy to identify at an early stage.
Richard
Hi Dick,
Many thanks, I've definitely found management to be an important differentiator at the small cap level and it can be quite a hard thing to determine. Some have ambition but a lack of regard for shareholders, some think like shareholders but are too cautious, and others can simply not be up to the task.
Centralnic (LON:CNIC) is an interesting one, I first started looking at it when there was a more obvious valuation gap with Tremor International (LON:TRMR) . But there's plenty to dig into even after the recent rise. Mgmt continues to acquire and integrate, revenues & cash flows are quite resilient, and the new CTO is a promising new hire.
Hi Jack
Thanks for the pointer to the Vox video. Lots of companies that interested me and I actually hold seven of them. A mix of long term holds (inc Somero) and a few more recent acquisitions (Vertu, Central Nic and Supreme). All above water except RBG. I entirely agree that honest, quality, entrepreneurial management is gold standard.
I will now take a look at Royal Mail and Airtel Africa. Not small cap but interesting comments from you and David Thornton. Thx again.
Mark
For those who believe in perfect markets the clear message - certainly in small caps is that the end of the world is nigh. Personally I think that unlikely and even if it is you can’t take your money with you anyway!!
So much stuff now dirt cheap regardless of fundamentals. I know some are up today but many have strong business momentum based on recent TUs. Is anyone selling at the moment - I guess some people must be! My only concern is that predators see this as a great opportunity to steal great businesses on the cheap
Must admit i have completely sold out of my largest holding today (fevertree) simply due to the fact the shareprice is "up with events" - i quite like having some spare cash right now to allocate amougst the carnage that has been created recently or may be created soon. I have already bought my first depressed price stake in saga (not for widows or orphans !). That leaves me with a couple of other potential purchases. I don't normally like to sell out of my core long term holding generally speaking when i feel there is still long term upside for what i perceive as slighty better value "now" elsewhere but i am making an exception now for right or wrong. Just need to find 2 more shares to buy into now.
How about a little bit of 'abroad'? Some don't like mining, but I think the UK consumer is as least as tricky to predict. I don't understand the uninterest in some of my mining shares, and Wentworth Resources (LON:WEN) (I do hold) put out an operational update this morning to guide expectations up further on their gas output in Tanzania.
It won't double overnight, but goodness, dividends as good as guaranteed at nearly 8% over the next year from a company with half its market cap in cash now, doing what is demanded from a growing economy that needs more power. And it will offset more and more of its emissions. OK, it's not solar, but it's needed for the next decade. Wish I had more spare cash myself...
I agree ... Stocko is neglectful to the point of abuse when it comes to resource stocks.
It's just crazy ... more especially because it seems to be deliberate and considered. I just don't understand Stocko's obsession with tiny UK businesses. I don't believe following that obsession will get me very rich (or even at the least a little bit rich, to which, hey ... I can aspire!).
Feels like a hobbyist approach, to be frank.
DaviStoVest - I think you are confusing Stocko with the SCVR. Stocko provides data on all shares be they resources or anything else. The authors of the SCVR (Paul/Jack/Roland and previously Graham) have all said that they personally do not have any expertise in the resource sector.
There is nothing to stop you doing a daily "Resources report/discussion" should you so wish.
Jack has covered resource stocks on this report many times.
You see what we have to put up with...
Here you are: https://www.stockopedia.com/co...
Wentworth Resources (LON:WEN) has announced a share buyback of up to £2m.
Or it's still overpriced and getting to fair value?
We'll see in a few months!
£stx Strix: Paul / Jack any views on this pharma company . News today has given the price a nice hike ..albeit from a horrible falling graph . I (unfortunately) hold.
Sorry Shield Theraputics not Strix!
So much was promised by Shield Therapeutics when they got approval for the iron supplement in the USA. However, they have continued their downward spiral ever since.
Luckily, I got out with a small loss and am happy that I managed to do this before they went into free fall.
National World (LON:NWOR) good trading update today. Similar company to £RCH.
Would appreciate Paul or Jacks views.
Super trading update from Immotion (LON:IMMO) good to see the HBE division doing £2m of revenue but importantly they appear to be now rolling out the new "Vodiac" product which is a compatible premium content for the existing headsets people have bought. That may add ancillary revenues.
Uvisan seems to be gaining traction £400k for H2 and Q1 has visibility of a further $350k so it appears this line is decent incremental.
Cash going up (though as Mojo will point out it is still not that high at £1.2m) and strongly profitable in H2 with £9m of revenues so all looks pretty good I'd say.
I think the GorillaTRek product being launched in the Zoo market next year should be another big step up. All caveated on no more lockdowns of course, though they do point out that 2/3rds of their revenue is from the US in the LBE product.
Trackwise Designs (LON:TWD) fund raise a kick in the teeth for existing holders (like me). 45% discount! You just get the sense of naive management being taken for a ride.
Yes, disappointing and shocking placing for Trackwise Designs (LON:TWD) (I hold) at 80p when share price was at 145p. The inepttude of their CFO has been commented on elsewhere. However it was only for a small amount, £6m, and by my calculation fair value subsequent to the placing would be about 127p per share and so the 40% reduction in price this morning seems way overdone.
Happy to be corrected on my calculation but this might be a buying opportunity - I picked up a few more near he low - for those not already invested. They are essentially setting up a printing works for the electronic cabling of the future and the margins once established are very good and there doesn't seem to be anyone else out there who could easily do the same.
It is 'double or quits' time with Trackwise Designs (LON:TWD) for me. They should have foreseen the potential for delays when they could have raised more money on better terms, now they're having to go cap in hand and take a bad hit, leaving us with a sour taste. Strategically ill thought out. Their technology seems good and it does seem that revenue will start to flow from the Arrival deal in the next 6 months, so if slightly reluctantly, I'm probably going to give them the benefit of the doubt. Wasn't a huge position to start with, but has got a lot smaller.
Trackwise Designs (LON:TWD) Bit of a shocker. Plus side is they have managed to raise the money before going bust and my holding doesn't look quite so overweight any more!
Volex (LON:VLX) - trading good/inline. Chart could not form a base but maybe today. But with Boohoo (LON:BOO) and Avon Protection (LON:AVON) in mind perhaps wait for another days candle.
Volex (LON:VLX) - trading good/inline. Do you have something to back that claim up. They haven't reported that I can see so assume this was an inept ramp attempt
Sorry it was dated 11 Nov. Just saw the price rising and put two and two together to make nothing. Volex (LON:VLX) one of those want to buy in when can see a base.
Interesting acquisition by Bloomsbury Publishing (LON:BMY) announced this morning. Adds significantly to its USA presence and its digital ambitions. Companies that are able to self fund acquisitions are relatively rare and usually good long term investments provided they choose their targets carefully, Very few come to mind, Halma (LON:HLMA) being an exceptional example. I hold.
Any thoughts Jack?
Gamma Communications (LON:GAMA) would be another that makes acquisitions from FCF jonno but I agree, quite rare. I am regretting letting Bloomsbury Publishing (LON:BMY) get away but might revisit in the new year.
Hi Jonno,
Bloomsbury Publishing (LON:BMY) has been on my watchlist for a while so am interested in the RNS, even if it's not strictly a trading update. I'll take a look later in the morning (have a management call at 09:20 to prep for right now!)
All the best,
Jack
One of the big benefits of the "Non-Consumer" division. with its "Academic & Professional" slant is that Bloomsbury Publishing (LON:BMY) is creating considerable and growing annuity type income. On the last IMC presentation, it was stated that some courses are essentially impossible to teach unless one subscribes to Bloomsbury Publishing (LON:BMY) resources.
This is a useful complement to the potentially more volatile "Consumer" division, and helps justify a higher rating.
Funny you should mention annuity type income. Harry Potter would appear to be the archetypal form of annuity income. The books have become a children's classic and will be enjoyed by children for many years to come, just like Thomas the Tank Engine for example. Not my original thoughts, but borrowed from one of PI World's interviews with Richard Leonard.
Bloomsbury Publishing (LON:BMY) (I hold)
Hi Jonno
3 very high level thoughts:
It's a shame that there was no mention of ABC-Clio's Net Assets in today's release.
https://www.ebsco.com/products...
I imagine that Bloomsbury will probably look to integrate the non-US-centric databases into their Digital Resource platform (BDR).
Hopefully that will increase the international revenue potential of the acquisition.
I'm pleased to see the company deploying some of their cash and remain a happy holder
A
Bloomsbury Publishing (LON:BMY)
Hello abtan quick question if i may
I have some spare cash to deploy Bloomsbury certainly seems a fairly solid company - i don't know the ins and outs of it though at present in detail. Would you expect cashflow conversion to be better than profit numbers (eps) being generated short/medium term abtan? ignoring acquisitions. Just having a quick lok at the stocky numbers it seems that cash conversion has been most excellent the last 3 years - always a bonus when cash conversion is over 100% of earnings - albeit that cant last forever.
Bloomsbury Publishing (LON:BMY)
Hi rmillaree
I'm afraid that I generally don't look at profit or EPS (too many funnies for me with accruals, deferrals, depreciation, etc...), and when it comes to cash generation I prefer calculating it myself and then looking at it relative to the EV.
With this particular company, I think cash generation is excellent, even after capex, and supported by legacy Harry Potter revenues and their growing BDR platform.
Good luck whatever you decide.
Cheers
A
Another 'ahead of expectations 'trading statement from RWA. FRP,looked steady set of results . Tony
After a torrid few months, it is good to see National World (LON:NWOR) come through with a substantially ahead trading update today. It appears that Montgomery is quietly transforming the portfolio of assets, under the radar, and the commentary suggests strong progress on all strategic fronts including digital. Interesting to see a smaller decline in print, which may read across to REACH, which has also been hammered recently. I hold both.
Yes National World (LON:NWOR) looks seriously undervalued to me. It now has 1/3rd of its market cap in net cash. Even if revenues remain flat they will increase the p&l by £5m p/a based on the expense reduction programme. That alone adds 1.5p to EPS which itself appears to me to be generating FCF of circa £8m p/a or 3p judging by increases in cash.
So we should see a business in 12 months time with an eps of circa 4.5-5p and cash north of 10p so that puts the business on cash adjusted PE of around 3 ?
Reach (LON:RCH) did report last month that print only declined 3.5% so similar to National World (LON:NWOR)
Yes looks good value and does not have the pension issues either.
Another shocker from Boohoo (LON:BOO) today. I am seriously lucky on this one. I have been watching it all the way down and looking for an entry when a new base was established. I had finger over the buy button under 140p but pulled away because I thought there could be more Supply Chain/ service/ gross margin bad news in the pipeline. This was a fortunate near miss. As per discussion earlier this week, a sharp fall today may present a nice opportunity IF you believe the 'transient' messaging from the Board. At some point there is residual value here for a business that is still growing double digit in a shocker of a year.
Just seen Paul's link to the other BOO thread. Apologies. Thanks to Paul for his viewpoint on this.
I just wonder how much Paul is down on Boohoo to be honest and that's not meant to rub lemons. But it was one of his strongest conviction trades and one which he kept adding and adding even after it went against him.
Darren that's a bit like asking the missus hw much she weighs!
You cannot judge this short term - unless you are a day trader/trader Paul has always made it clear that he is taking a 5 year view.. There are not many good businesses that never have any blips in their upward March, even companies like Amazon, apple etc. it depends whether you are an investor or trader and an obscenely high % of traders lose money overall!!
especially those that are long Boohoo