Small Cap Value Report (Thu 16 July 2020) - EYE, LOOP, XAR, LGRS, PURP, BOO

Good morning, it's Paul here with the placeholder for Thursday's SCVR - designed to provide a place for your early morning 7am RNS comments. In particular for MrContrarian's brilliant early morning summaries - I think we should do a whip round for him at Christmas actually, for the sterling service he selflessly provides to the investing community.
Estimated timings - TBC (let me look at the RNS and then I'll publish a totally unrealistic deadline, fall asleep after lunch, and miss it by miles!)
Today's report is now finished.
To get you started today - I added a few more sections to yesterday's SCVR throughout the afternoon, so it now covers 6 companies, including 3 reader requests. Several of which look potentially interesting actually, so thanks for flagging, and do please take a look & let me know your views.
.
Pubs
It's been a while since I've talked about pubs, but have been doing a bit more research this week about pub re-openings in London. My local, the Lord Clyde, has been open for a little while, so I went there on Tuesday night, and was surprised to find that it only had cider and Guinness on tap - it's quite understandable that breweries are having trouble scaling up production, and in any case I love Guinness, so had a few pints of that. This is an easy, quick fix, so doesn't matter.
It was table service, which is fantastic, this must become the new norm. I normally sit outside anyway, in the fenced-off pavement area, so I can watch all the traffic near-misses, and expletive-laden arguments between motorists. But social distancing makes it all the more sensible to sit outside, if you want to avoid covid. I'm in two minds. If antibodies only last 3 months, then surely I should be exposing myself to covid again, in order to refresh my immunity? I have felt a bit peaky this week actually, so have been wondering if the disgusting old man in a local cafe on Monday, with the runny nose, might have temporarily re-infected me?
Also, it's quite fun to see the local care in the community lady, called May, who shuffles down the road, getting free food and drink from all the local shopkeepers (either very smart, or genuine, I can't decide). She's a cheerful soul, typically booming out at all the men,, "Hello! How's your wife?!" She usually asks us to adjust her collar, or hold her hand and walk her across the road. She's pretty harmless, in the main. I assured May that my (imaginary) wife is very well, which pleased her, then sat down to enjoy some lager this evening, as rumour had it that fresh barrels were arriving today at the Lord Clyde. A freshly poured pint of Amstel, dancing beautifully with swirling clouds of tiny bubbles, was pure heaven. So I had 4 of them.
Also, a little tip is to ask for a wedge of lime, and smear it all over your hands. Not to disinfect them, but just to enjoy the lovely scent of lime for the next few hours.
Why was I mentioning this? Oh only to say that the London pub was very quiet, I would say well under half normal occupancy. As I tottered up for my 4th or 5th pint, the barman asked, "Same again?". Yesh please, I replied, "I'm trying to make up for all the missing customers!". A local quipped, "They'll be back soon - just like chlamydia!" How common, I thought to myself, but you often have to hold your tongue in this part of London, and make a quick decision that it's probably best not to engage. Hence I feigned deafness.
As I enjoyed my final pint of gorgeous bubbly liquid, 4 young, middle class bearded millennials sat down at the table behind me. I try not to eavesdrop, but if they're very close, and talking loudly, you can't avoid it. To set the picture, one was called Oli, and another Will. That tells you everything you need to know. I could barely stifle my laughter when Will said;
"Oli, I'm like not really OK with this whole table service thing. Isn't that like, slavery?" (with upward inflection of course)
"Will, you don't like actually like own the waitress. Or waiter. So, no not really"
Glad they've got that pertinent issue resolved! It wasn't said ironically either.
Then they went on to discuss 5-aside football. What happened to the 5th person, I wondered. Then they talked about fights, and headbutting someone, so I rapidly decided they weren't the nice middle class chaps I thought they were, and tuned out.
There was something else leading on from this, ah yes;
Face Coverings
A shares blog is definitely not the place to discuss policy on face masks or coverings. However, I just wanted to make a couple of subsidiary points;
1. Will the new requirement to wear face masks stop people going shopping? My view is that it might, for some people. But for others, it might reassure them. My feeling is that once you get used to wearing a face covering of some kind, it becomes quite reassuring. I spent a 2 hour train ride to London recently, with the carriages maybe just a quarter full, if that, and everyone complied, wearing face coverings as required. It seemed to work fine.
2. Find a face covering that you find comfortable. Even if it's just a formality, it's not worth fighting against it, just wear the damn things. I started with the paper, concertina ones, and they're uncomfortable, and made my glasses steam up. 10 minutes was enough. However, I since paid £25 on Amazon for 50 cloth face coverings, and they're absolutely fine to wear for a few hours. You forget it's there after a while.
3. Many people have disgusting hygiene habits - I'm sure you've seen many people cough into the air, or even directly into our faces. I just give them a filthy look, and maybe even tut, or mutter "honestly!" under my breath. But these pig ignorant people have no idea that they are pig ignorant. Hence making them wear a mask can only be a good thing, and me wearing one keeps these disgusting creatures one layer of fabric further away from my bloodstream. Yes I hate the public. Or "lumpen proles" as my mother accurately describes them. I've just googled that, and discovered it's a Marxist term! Typical, I always suspected her of left-wing leanings. My Dad learned to speak Russian, and took Mum to the USSR and most of the Eastern bloc countries in the mid 1970s, so I've always suspected my parents of being Soviet spies. We did have a long wave radio, with a large antenna rigged up in the attic. But he's so right-wing, maybe he was an American double agent? Or not sure either way? Maybe it was a bluff? We will never know. The toys they brought home for me after that Communist trip were so shoddily built and unappealing, that I knew, even at the age of 8, that the USSR was going to lose the Cold War.
I was brought up having it drummed into me that "coughs and sneezes spread diseases". Why? because in the 1970s, there were enough people around who survived the 1918 Spanish Flu pandemic, to drum those lessons into younger people. Once the old people had all died, the importance of hygiene also died. Now we're having to re-learn from scratch. It's the same pathetic reason that vaccines have gone out of fashion - because the threat from the awful diseases was eliminated, hence the next generation were too stupid to realise the threat could re-surface any time.
That's probably enough ranting for one evening. See you in the morning!
Right, I'd better do some work now, instead of rattling on after the pub.
Eagle Eye Solutions (LON:EYE)
Share price: 188.5p (up 11.2%)
No. shares: 25.7m
Market cap: £48.4m
Eagle Eye, a leading SaaS technology company that creates digital connections enabling personalised, real-time marketing through coupons, loyalty, apps, subscriptions and gift services, today provides an update on trading for the year ended 30 June 2020 (the "year").
It's got one of those headings which tells us what to think;
Strong trading performance, successful international expansion and continued innovation combined with business resilience
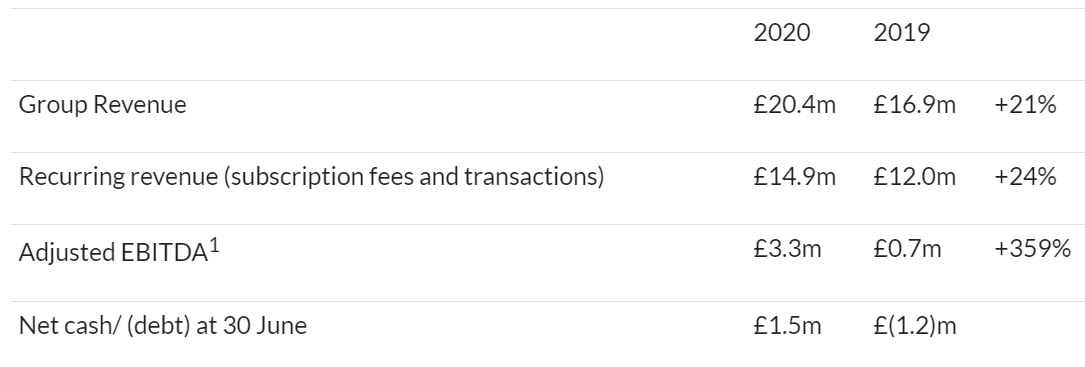
The highlights table shows decent growth (all organic I believe), what it calls recurring revenue (which would probably be better described as repeating revenues), meaningless EBITDA number, and a tight cash position;
.
EBITDA - this figure is meaningless because the company capitalises a lot of its costs onto the balance sheet. This was £2.6m last year, and increased to an annualilsed run rate of about £3.0m in the last interim results. That swallows up nearly all of EBITDA, so in reality the company is trading just slightly above cashflow breakeven. They're not keen to tell us that though, I had to figure it out.
Contract wins & extensions - the list of clients is very impressive (big supermarkets). and it's not just UK, there are international customers too. Volumes of vouchers have risen strongly;
Redemption and interaction volumes increased by 135% to 2.1bn (2019: 847m).
I don't know how they are defining "interaction" volumes? Probably loosely, as it's very apparent that this announcement is a bit rampy - i.e. over-PR'd.
Cash - position has improved to net cash of £1.5m, but some of this (not quantified) are one-off benefits that are expected to unwind in the new financial year. Bank facilities of £5m are due to expire in May 2021 - the company is in "advanced discussions" with Barclays about extending this facility. I think it should raise some equity, to strengthen the balance sheet. Companies that are not really profitable yet, shouldn't have debt on the balance sheet, in my opinion.
Outlook - confident, sales pipeline growing. However, there are hints below that growth might be a little sluggish in the short term perhaps? Also "invest" below means more costs!
While new business decision making is likely to continue to be delayed during this period of uncertainty, our sales pipeline continues to grow, and we are engaged in positive discussions across multiple geographies.
In the year ahead, we will invest in product development, sales and marketing, and in new geographies to capitalise on the momentum being achieved in the US and Australasia, while continuing to manage the business carefully during the COVID-19 period. The Board, therefore, continues to be confident in the long-term growth opportunity for Eagle Eye.
My opinion - this seems a long-winded update, with quite a lot of waffle in it, and too much spin. I think this should have been edited down to just the key points.
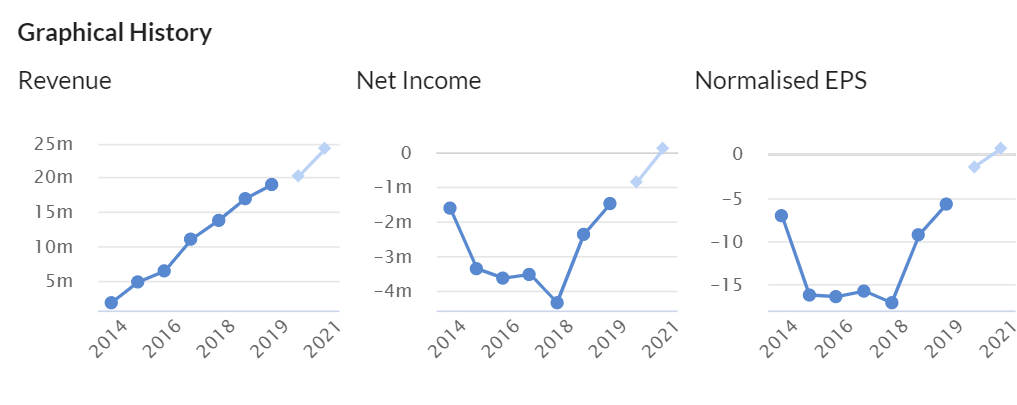
The Stockopedia graphs below nicely cut through all the PR, and tell the real picture - that this company has spent a long time struggling to get to breakeven. But it's achieved it, and the business model starts to get interesting once we layer on more clients - although I suspect costs are likely to keep increasing as revenues build. That's normally what happens with growth companies.
I like this company, and think its client list is very impressive - which should make it easier to win new clients. I'm not 100% convinced that the growth is fast enough to justify taking the market cap higher than £48m currently. But we're in a bull market for tech shares, so this is the right space to be in at the moment.
.
Loopup (LON:LOOP)
Share price: 180.5p (up 10%)
No. shares: 55.4m
Market cap: £100.0m
LoopUp Group plc (AIM: LOOP), the premium remote meetings company, is pleased to provide the following trading update for the six months ended 30 June 2020.
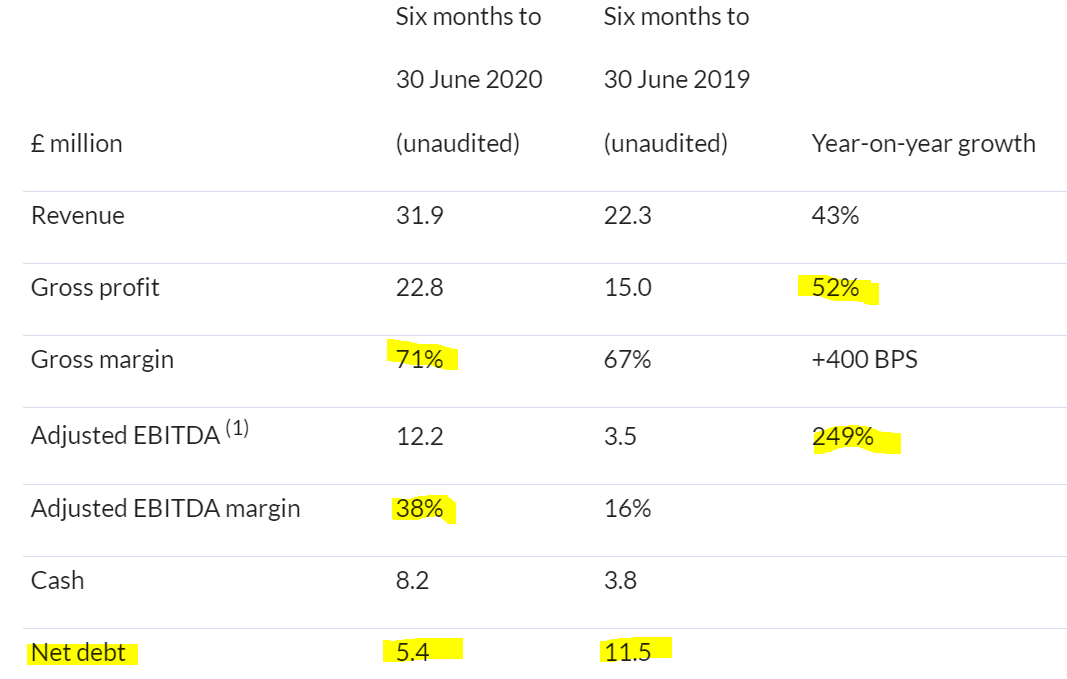
Some very impressive figures below for H1;
.
Key points;
Very strong rise in revenues
High gross margin, so nice operational gearing
Adjusted EBITDA again - this is NOT a valid measure of profits! Checking back to 2019, the depreciation & amortisation charge in the P&L was substantial, at £7.5m. Or looked at another way, it capitalised £5.0m of expenses into intangible assets on the balance sheet EBITDA ignores both types of costs, hence is an artificially inflated number. I prefer to work on a cashflow basis, so if we take the H1 2020 adj EBITDA of £12.2m, and assume that development spend is running flat, at £2.5m per half year, then we get £9.7m positive cashflow in H1 this year - that's highly impressive - although the commentary points out that H1 is seasonally stronger.
Net debt - this has come down a lot, to £5.4m, and no longer seems a problem. Net debt was £11.4m 6 months earlier, at 31 Dec 2019, so it's dropped by £6.0m in the last 6 months. Again, highly impressive.
Outlook - sounds good;
Although it is difficult to predict near term developments in working practices and business climate, and also noting that seasonal usage is naturally H1-weighted, we expect to exceed market expectations for the current financial year to 31 December 2020 in terms of revenue, EBITDA and cash generation.
My opinion - I've been critical of management in the past, because they've made lots of mistakes. But when the facts change, then I change my mind. This update today is really excellent. The big question mark is obviously whether this is a flash in the pan from covid-related home working? Most people seem to think that things have (at least partially) changed permanently, with more people likely to want to work from home at least some of the time in future. As my sector expert pointed out in a phone call earlier, if just one key person is working from home, then the only option is a remote meeting.
LOOP is a niche specialist, so it's offering more secure conference calls (with a video option) than say Zoom, which is coded in China apparently, and has widely-known security issues. LOOP seems particularly popular with firms of lawyers and accountants, which are sticky customers. Hence I see LOOP as more a niche product, than mass market.
We can see how the product works on 29 July, with a results webinar.
Overall, I think this looks very interesting, and I've turned positive on this share again, due to the impressive figures published today.
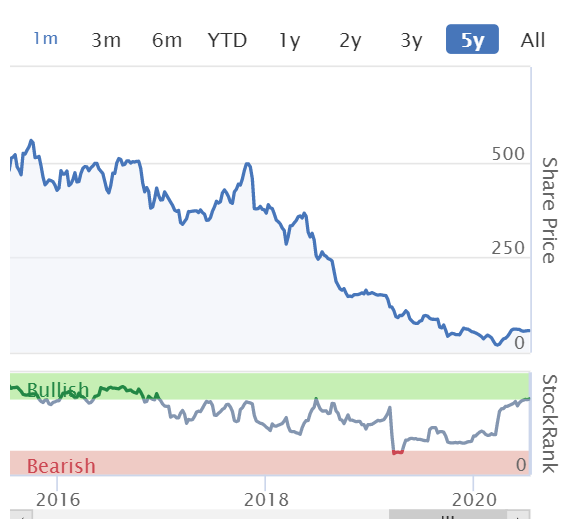
Note below how the StockRank plunged into red territory when the problems began in 2018;
.
Xaar (LON:XAR)
Share price: 62.4p (up 13%)
No. shares: 78.2m
Market cap: £48.8m
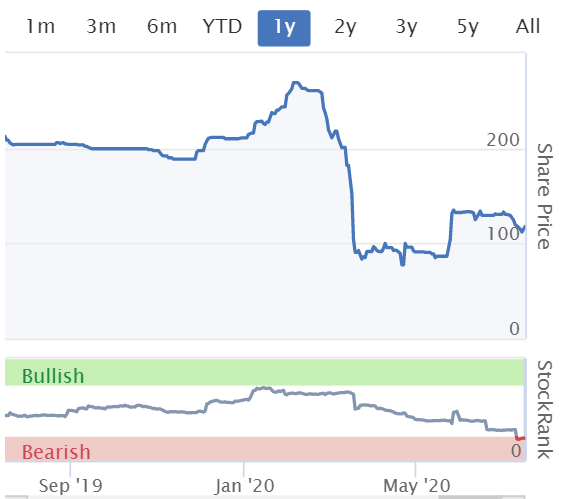
This formerly highly profitable specialist maker of inkjet print heads, has gone horribly wrong, as you can see from this history 5-year chart. It was heavily reliant on one product, for Chinese tile printing machines. New products which sounded promising, failed to take off in the same way.
.
I've always wondered if XAR might be able to resurrect itself with new products, hence why I keep an eye on it. The share rising 13% today has piqued my interest.
Xaar plc ("Xaar", "the Group" or "the Company"), the leading inkjet printing technology, today announces a trading update for the six months ended 30 June 2020.
Update today - this sounds reasonable, given that covid is bound to have had some impact;
The Board is pleased to announce that trading for the six months ending 30 June 2020 has been in line with expectations and good progress has been made implementing our strategy. Revenue for the period is expected to be £23.7m, representing a decline of 7% relative to H1 2019 and in line with H2 2019....
Outlook - a bit mixed, as is the additional detail in the RNS, which I won't repeat here;
As a result of the continued uncertainty surrounding economic conditions globally, the Board will not be providing guidance at this time.
The short-term order book is healthy, and the business is well placed to withstand the difficult trading environment.
The Board remains focused on the medium-term strategy to return the business to profitability and growth and will provide more details on our future plans at the half year results in September.
That sounds as if it must still be loss-making currently?
Balance sheet - as at 31 Dec 2019. I've had a quick skim through the Annual Report, and Xaar's balance sheet is very strong, with plenty of cash. 2019 looks like a kitchen sink year, with big write-offs, and disposal of a heavily loss-making part of the business. Continuing operations still made a £15m loss, so hopefully costs have been cut more since then, otherwise the cash pile could deplete rapidly.
Cash - I'm reassured by this;
The Group retains a strong balance sheet and cash position. Cash and cash equivalents at 30 June 2020 were £23.9m with both the Printhead and Product Print Systems business improving their cash balance relative to 31 December 2019. The 3D business continues to be well positioned to fund its development and go to market needs. The Group maintains a strong cash focus and disciplined cost controls.
My opinion - there's a glimmer of hope here. It sounds like the company is focused on protecting its cash pile, which buys it time to execute the turnaround strategy. I don't see enough in today's update to make me want to rush out and fill my boots, but there do seem to be signs of life - i.e. it's not a basket case.
I'll put this on my watch list, and see if anything interesting happens in future. I'd want to see more evidence that financial performance is improving meaningfully before taking the plunge here.
.
Loungers (LON:LGRS)
Share price: 118p (up 2.5%)
No. shares: 102.4m
Market cap: £120.8m
This is very clearly explained;
Loungers has successfully re-opened 75 Lounges and 19 Cosy Clubs (from a total estate of 138 Lounges and 29 Cosy Clubs), following the relaxation of the Government imposed closure period due to Covid-19. We have been very encouraged by the reception from both our teams and our customers. The steps we have taken to ensure everyone's safety have been well-received and have not prevented us delivering our usual exceptionally high standards of hospitality and atmosphere.
As a result of the confidence we have gained from the trading at our re-opened sites to date, we have decided to accelerate our re-opening programme and will have the full estate re-opened by 5 August.
Two sites are not being re-opened at all.
Loungers will be participating in the Eat out to help out scheme.
VAT reduction recently announced will be a big help, as it applies to 65% of Loungers sales.
My opinion - it all sounds upbeat, but there are no figures given. I would have liked to see some figures on profitability of re-opened sites, LFL sales versus last year, etc. There's no guidance given at all in this announcement. So I guess we have to read between the lines. As the re-opening is being accelerated, then this must mean re-opened sites are trading at a satisfactory level.
The downside risk is obviously that covid resurges, and sites have to be re-closed. We're seeing that in a few states in America right now, so it's a very real risk. Many Loungers sites are quite small, so I'm surprised they are keen to re-open now. Cosy Clubs are larger, so should be able to better handle social distancing.
The upside is that if covid is defeated (maybe next year), and things can return to normal hopefully, then Loungers shares would probably more than double from the current level.
It did an equity fundraising a little while ago, so it's financially stable I think.
This is a straightforward punt on covid. Much like many other pubcos. Loungers is a very well run business, so should certainly be on the shortlist if you want to take a punt on this sector. This share is extremely illiquid, as it's tightly held. The quoted bid/offer prices are so wide you could get a bus through them, which is very off-putting. Until they can improve liquidity, this share lacks appeal for me.
.
.
Purplebricks (LON:PURP)
Share price: 58.2p (up 6%)
No. shares: 306.8m
Market cap: £178.6m
This is an announcement from yesterday. PURP is on the long list of UK companies which tried to conquer the world, and then was forced to retreat with its tail between its legs. The sale of its Canadian business has completed, and interestingly this now leaves it with a substantial net cash pile of £66m. This is to be "invested" in the UK business. So brace yourself for more of those incredibly annoying & misleading TV ads.
I bought a property through PURP, and it's nothing like a conventional estate agent. The business model is badly flawed in my view, and needs a re-think before they squander the cash pile on more ads.
That said, the valuation is looking quite interesting now, for the market-leading brand that everyone has heard of. I'm not sure how many competitors still exist.
My opinion - there could be speculative upside from this level, maybe? The huge cash pile provides a solid buffer too.
.
Boohoo (LON:BOO)
(I'm long) Breaking News - Directors have just bought over 7m shares in the market, at around 214.3p, splashing out £15m. That's not pocket change, and it sends a strong signal to the market.
I remain super-bullish on this share, and see it as a cracking buying opinion in my view. The trick is holding your nerve. I see negative opinions on this as background noise, best completely ignored.
.
That's it for today, see you tomorrow!
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

105 comments
cmpeckham
There is nothing wrong with a bit of idle speculation, but actually we know what the testing approach was in the US because the CDC publicised it. There was no preventitive or precautionary testing.
I am not convinced that link proves anything cmpecksm - Infact priority one group included hospitalised patients - it specifically does not mention that they need to be symptomatic in that link.
Being honest as I don’t know I don’t really want to Labour the point - all I would say is that it’s generally
Up to someone who is trying to prove an argument is true to produce the evidence - statistical Figures need proper data to relied upon if you don’t fully know your sample group any assumptions made could be wrong if you are comparing two different sample groups which we clearly were here.
My final comments on the subject will go directly back to the original numbers posted - the earlier testing was coming back 95% negative so I still stick with my original assumption that that group of people being tested will probably have included a subset that did not have symptoms due to that low positive % rate being returned.
Omega Diagnostics (LON:ODX) is up 21% today (no position). I know it is a volatile stock, which recently did a placing but there is no new news out today and as far as I am aware. The only reason for the move, as far as I can tell (please correct me if I am wrong) is that the company gave a well attended online presentation yesterday evening on InvestormeetCompany, which I did listen to and only gave background information on the story. There is a similar interview out with Proactive Investors this afternoon. This either shows the importance of investor communication or the frenzied state of current "Covid stocks" (or both).
My thoughts are that I was very surprised at the previous LOOP comment here which I thought a bit dismissive. I refrained from commenting as I wanted to see more concrete figures and improve my understanding of the company and the market which I accept is competitive. Citrix is a big competior, for instance.
I see no immediate concern with the intangibles/capitalised development cost argument. From the last report and accounts
......increased its product development spend from £4.3 million in FY2018 to £5.0 million in FY2019. The resulting amortisation charge is lower at £3.8 million (FY2018: £2.6 million) due to the timing of completion of individual development projects.'
I also am quite happy with EBITDA as a result, despite what Charlie Munger has to say about it.
In fact the aggregate of intangibles and goodwill, which shot up with the £61mn MeetingZone acquisition of June 2018, seems to have changed very little since then. I am expecting further good earnings in the coming years, albeit that Spring 2020 was (in a way, sadly) fortuitous for LOOP.
If a company is capitalising £4.3m (i.e. removing this cost from the income statement) of development cost -- and also amortising around the same amount (i.e., putting the cost back on the income statement) the world is in balance.
EBIT in that scenario makes sense: amortisation = capitalisation, profit = cash profit, everything is gravy.
Why would you then jump to EBITDA? What using EBITDA in this scenario does is say:
"Yes, of course you can exclude the capitalisation from your income statement - those aren't real costs (despite the cash outlay). And yes, the costs you incurred in the past on your development, which you're now amortising - you don't have to put those through the income statement either"
You're letting them exclude the cost twice. They are spending cash, and neither the upfront spend nor the future amortisation is put through the income statement. Your cash earnings will never match your supposed profitability.
Re LoopUp (LON:LOOP) this marketplace looks pretty crowded with some heavyweight competition such as Slack and Microsoft Teams. My instinct would be that companies might select LOOP when they realise they have a need (everyone will have realised this by now) and they can pay for LOOP on a per use basis. But when they get serious they will switch over to the more heavyweight offerings(?)
Many here will know more about this than me, can anyone put me right and tell me why LOOP has a long term future?
Edit: just seen the comment above from Nick Hewett who seems to be thinking along similar lines and posted while I was still scratching my head.
Agreed LOOP is in a market with some absolutely huge competitors - but the market isn't uniform. As I posted at 8:13 "Great as ZOOM and others' self-service broadband offerings are they leave niches for differentiated players with superior service and technology to also prosper."
LOOP's offering is high quality online conferencing specifically catering to the professional services market. This is attractive to firms that are hosting online meetings and conferences involving external clients where the sound quality, in particular, is all important. This niche is valued at about $7bn revenue per annum - so not small. It's this differentiated offering that explains why LOOP has delivered great results against such awesome competitors such as ZOOM, Microsoft, CISCO, Amazon and others.
I sold my Loopup position this morning for a reasonable gain mainly because of the competition arising from all of the other platforms available for voice and video meetings. Some at the low end are free. Others (like Microsoft Teams) are fully integrated with large company ERP / data management platforms........I am not sure I see growth for Loopup despite the changes to office working being driven by CV19
Same here Nick sold when it peaked at something like +10% for the day. Tidy profit made.
Covid stuff...excuse me for being so boring but its what people are talking about. Clearly we are just waiting for the post covid-fear onto covid-coping boom to start...its coming, probably this year and its going to be really surprising. Its a new thing to have such a deep depression in such a condensed period but not have massive capital destruction (people and cos), some positive capital cleansing and positive consequence of corrective depression still going to come (ie productivity gains and new businesses).
This chart is interesting:
Taken from here https://www.cdc.gov/nchs/nvss/...
318 deaths at week to 11 July. Note that they throw the next wide including pneumonia and flu. Its not good that they have this excess death. Covid is real and a problem for sure. Never denied. But some perspective needed...and this hard number is a good counterpoint to some of the hypermedia hyperbole and unleashed angst express by some.
Then I think this article in Bloomberg by the always excellent Cathy O'Neill aka mathsbabe (I recommend her book weapons of mathsdestruction) captures the angsty juxtaposition to the (complacent to many) view that the decline in deaths is the real news.
https://www.bloomberg.com/opinion/articles/2020-07-14/florida-s-covid-19-deaths-might-rival-new-york-s?sref=uZT4AnwP
IMO Bloomberg have become a little obsessed about being anti-Trump so have loosened editorial standards to fit that goal...this article fits the bill as the very credible and usually objective Cathy is really projecting her fear and angst with a bit of bogus number extrapolation. She may prove right but she doesn't have anything other than a number hunch to prove it.
ANYWAY....what's happening in the US is functionally great for global economy. This is whether deaths don't move up much, move up some of the way or move up all the way. It doesn't matter. What matters is that the US (through accident and disorganisation) is pushing us into resolution rather than constantly twiddling our thumbs and our politicians caught in a game of media and expectation tactical moves with no strategy.
Resolution is crudely one of the following:
1) The virus potency has decreased. Vigilance for some vulnerable people but rest of us get on with life (Italy happens to hint at this if you look at medical stuff coming out of there and look at how Italians are behaving and socialising after their acute trauma. There is much discussion locally but it doesn't make international news as there's nothing mawkish enough (eg https://www.huffingtonpost.it/entry/coronavirus-per-10-scienziati-ce-unimpennata-dei-casi-debolmente-positivi_it_5ef1f012c5b6ae596a3e0da9?utm_hp_ref=it-coronavirus&ncid=other_homepage_tiwdkz83gze&utm_campaign=mw_entry_recirc)
2) The virus is potent and highly deadly with devastating subsequent waves. This will see mass mobilisation of resources and finance in the US akin to WW2. The economy will become managed. Debt load will be seen as an irrelevance to be forgiven or inflated away. These things are going to happen in version 1 above too but if the virus remains "apocalyptic" then the action will be on steroids
[ There's a middle ground 3 that I've run out of patience to try and explain here...its a dilution of 2]
It is easy to slag the US and the orange man fool off. Its fun but it misses the point...
Note, there was an economic boom in the US after the Spanish Flu subsided. Different times and conditions but it is also highly erroneous to use Spanish Flu second waves as a model for covid.
I think the global evidence all weighs towards 1. Perversely, as we come through this it is states that have most restricted freedom of movement and suppressed virus spread that will likely struggle the most. But thankfully the giant key global engine that is the US will function and so everything else is manageable.
Hurrah for US disorganisation and madness!
Ciao
The US is not disorganised. It does 3 million tests per week. Yes there are more cases but likely only because of the incredible - and increasing - amount of testing.
The testing is bottom up driven...organised chaos of the market.
At a national and regional level the US is chaos.
Its medical treatment is also bottom up....chaos and inspiration
The 7 day average for deaths in the US was 835 three weeks ago and is now a whole 516 in a country of 330 million. Some states have issues like Florida but most do not. As in this country the MSM only emphasises the downsides.
I agree K.G.B. ...the past is not prologue either to the positive or negative inflection...we wait to see how things turn and we should seek to filter the hysteria out
Whilst the amount of US testing was increasing on a linear basis the increase in cases discovered was increasing on geometric basis - i.e. it wasn't just the volume of testing causing the Covid figures to rise - it was revealing an accelerating infection rate.
Earlier in the week (can't remember which day) someone (can't remember who) hypothesised that maybe the extra people being tested were more likely to be infected.
In the UK it was actually the opposite and I presume it would be for the States too, but as the policy on who could get a test was set State by State, there is no easy way to demonstrate this.
We know that testing was initially focused on highly symptomatic cases and that large numbers of people who only had a sub-set of symptoms were turned away from testing e.g. see here:
https://www.technologyreview.com/2020/03/25/950320/what-the-hell-is-going-on-with-coronavirus-testing-in-the-us/
and the CDC prioritised testing for hospitalised patients. As capacity has increased, they have gradually included a wider cross section of society.
So, all else being equal, we should expect the infection rate of those tested to decrease as more people are tested. Did anyone attempt to give a reasonable explanation for their claim that "the extra people being tested were more likely to be infected"? I would start on the basis that extraordinary claims require extraordinary proof.
Dear Pecks...may I say pomposity of response does not equate to veracity...
Pot, kettle, etc obvs...but hey...
No one has a flaming clue on covid inc the experts. Data is a smorgasbord. Anomalous outcomes abound globally....and yet we are certain of our perspective.
I take comfort in the anomalies....they tell us our hysteria is, well, hysterical. I'm waiting for stoicism and coping to arise. It may be truly formative in a sociopolitical sense when it does. Exciting.
Goodnight
LOL (literally). Why jump in like that on a conversation that didn't involve you? I guess that means the unnamed person making the extraordinary claim was you then mojomogoz! Now there's a surprise!
If there is any reasonable justification for your claim then I seriously would like to hear it. It might tell me something I don't know, or it might give me another laugh!
cmpeckham
I guess that means the unnamed person making the extraordinary claim was you then mojomogoz!
To set the record straight the comments were not mojomogoz but by me.
The comments have been taken slightly out of context as i was just providing a possible alternative explanation to highlight the fact the figures being quoted at that time really didn't prove anything and may have been misleading to a greater or lesser degree.
My idle speculation was that it is entirely possible the original population of people being tested may include a high % of key workers or at risk people who are being tested as part of prevantitive or precautionary measures. It was known at the time many who were reasonably known to be positive weren't being flagged up and were also being missed from the sample.
If those same original sample still exist and the new additional tests relate to individuals that are more likley to be positive (previously excluded from the test) - it seems posisble that the % positives would go up.
Nothing more than a idle speculation - but without decent robust methodology anything really is idel speculation in that regard either side of the fence - note it is a known fact that the reported cases in the uk were rising quickly when the actual numbers were on the decline - so to me a spike in numbers being tested positive doesnt necessarily mean the actual numbers are going up. using stats that may be statistically flawed to back it up desont really cut the mustard with me.
Note i did kind of get the reponse i wanted to my speculation as timarr linked to the reported hospital admissions in florida. Thats probabbly a more reliable measure - not without its problems also. These numbers do show an increase - material but not as high as the other stats possibly. My one slight worry with american hospitals is that if they have a spare bed and the bill is picked up by the taxpayer will they be more than happy to sit someone in that bed to be on the safe side when if normal rules apply that may not be the case - that deffo is idel speculation on my part.
https://covidtracking.com/data/state/florida#historical
Ref the coming of the winter of discontent and whether its reasonably certain there will be a material big spike over the winter here . I am completely on the fence here - being frank no one knows and the probability range is probably in the middle area that we will just have to wait and see. I think robust measures to mitigate should be able to help to a greater or lesser degree - we had zlich measures in place ref the first spike and that will not be the case second time round - although the fisrt spike wasnt fully in the winter months - I am cautiously hopeful that it will not be so bad that hospitals cant cope with the burden but its dangerous to underestimate covid to any degree.
Thanks for the post rmillaree. There is nothing wrong with a bit of idle speculation, but actually we know what the testing approach was in the US because the CDC publicised it. There was no preventitive or precautionary testing.
The CDC document has been updated since that time, but there are still news reports summarising it available online, for example here:
https://www.aappublications.org/news/2020/03/26/coronavirus032620
In summary, what that says is that there are 4 groups: priority 1 down to priority 4. Non symptomatic healthcare workers were in priority 3.
At the time, they didn't even have the ability to test everyone in priority 1. Now, in places, they have the ability to test down to priority 4 (non symptomatic members of the general public).
It should be said that it's possible that individual testers ignored the CDC and did their own thing. But unless this was true on a systematic basis, and there is no reason to believe it was, then there is no reason to believe that the test results did not reflect the national strategy.
So, all else being equal we should expect to see a lower infection rate in the current testing cohort than in the early testing cohorts due to the way that these populations were sampled.
On the future, I agree we don't know if there will be another spike, but I can't see any convincing evidence to say that a spike can be avoided without as you say robust mitigation. Let's hope decision makers everywhere can get somewhere close to the right balance between risk and reward and lets hope double for quick effective treatments and vaccines.
Not sure where you get your figures from but I make it 760 average per day, there has been 5318 deaths in the last 7 days, this does not include today as the figures are not all in yet. Many states are only counting hospital deaths.
The US is not disorganised. It does 3 million tests per week. Yes there are more cases but likely only because of the incredible - and increasing - amount of testing.
Increased testing doesn't explain more people in hospital - and rates are at record levels in a number of states. The US is really a bunch of different countries under a federal umbrella and given that the Trump administration has essentially delegated management of the crisis to state level it makes more sense to look at it at that level.
So New York largely has it under control but California, Texas, Florida and a bunch of smaller states have an underlying surge in cases mainly driven by young people who are ignoring basic hygene and social distancing. As young people don't tend to get serious symptoms that demographic shift probably explains the lower death rate but means that the increase in cases bad enough to end up in hospital is even more concerning.
timarr
Like I said....its good we are in the resolution phase in US...
Proposing a Waiting for Godot approach - long batten down the hatches waiting for miraculous dispersal of the storm or miraculous cure - is an unreality. It isn't coping.
More people in hospital will turn into more death. A peak like the first one and above may come. I do not know. It isn't yet and based on every wide reading my personal belief is that there is not going to be a second wave more devastating than the first.
We have nothing to fear but fear itself etc (well...we have something...I'm a bit worried but nevertheless braved a pub crawl yesterday)
The only way they will avoid a second wave is through various interventions such as the re-intoroduction of lockdown like restrictions that have taken place over the last couple of weeks. You don't have to look hard for the evidence. For example, the increased % of tests that come back positive:
https://www.cdc.gov/coronavirus/2019-ncov/covid-data/covidview/07102020/clinical-labs.html
This should be seen in the context that, all else being equal, more tests would mean a lower % coming back positive, and that evidence suggests this is the time of year at which infections are least likely to happen.
It maybe that some interventions will be entirely positive (e.g. a good vaccine) but the evidence says that some kind of intervention or set of interventions is needed. You are free to have your personal beliefs, but perhaps you agree that the more evidence based these beliefs are, the better.
cmpeckham, my beliefs are evidence based so I can't agree with what you imply in your response...but of course I agree with the tautological truism of "evidence based" responses. My earlier post is anything but a flight of personal fantasy.
TBC your response to me was just a vibe that I'm a wrongun on this. As we know, this is how stocko-village discussion go on controversial topics
Anyway. I've reached my covid saturation point for the day and probably everyone else has unless harbouring some obsessive desire to see all as negatively as possible.
Let's see how stuff plays out.(I can tell you that as usual I will probably be ballpark right)
mojo out
I'm more worried about Biden than Covid when it comes to the US. Read look at Germany before the US money floods over there. Will miss our poor little no tech stockmarket.
I mentioned the other day that the $ is very much in focus, interestingly there have been two periods of distinct strength in USD over my investment lifetime....
1995 - 2001 DXY 81.8 to 118.43
2011 - 2020 DXY 73.9 - 101
These two periods coincide with a growth/momentum/US cycle clearly benefitting technology. I think you can see why this is viewed as important and why the current level is receiving attention. I don't think a weak Dollar does anything particularly negative or positive for technology, but it can make other things look a lot more attractive.
Hi Paul
I love your chats about the pub scene, and I am shocked to hear your parents were KGB spies. WOW.
So to get back to reality, have you any thoughts on #DISH Bigdish Plc I bought them at 2.50 and I have been stopped out at 1.14 over 50% loss. I know highly speculative and all that. But do you know why the drop? I also see the Stocko's stock rank is 0 and a sucker stock
Because Bigdish (LON:DISH) is a gaming chip. It is an idea not a viable business at the present time. Accounts for 15 months to 31.03.19 show income of £31,955 and a loss of £3,634,940 while the accounts for the 6 months to 30.09.19 show income of £11,766 and a loss of £1,050,255. Either you will lose all your money or if you forget about it you may find in a few years you have made a lot. To me it was an idea that needed substantial private equity. How it can be a quoted company is beyond me!
I just don't worry about the short term share price of DISH. It goes all over the place.
"I just don't worry about the short term share price of DISH. It goes all over the place."
So with that statement, you presumably don't use stops
Is that not very dangerous, on a low-value shares like DISH., surly you could easily lose all your money or am I missing something here?
Sorry to worry you, but I would love to hear your logic on this subject
Regarding using stops on a stock like BigDish (LON:DISH)
BigDish (LON:DISH) has a volatility of 169 according to Stocko. With volatility that high you really can't meaningfully use stops. Personally, I find anything with a volatility over about 40% difficult to work with.
A volatility of 169 means that the stock will likely swing by +169% or its reciprocal -62% in a year. In a week it will likely swing by +/- 25% ( = 169/sqrt(50)). This is not a stock that moves sedately along!
Sorry, tried to find the 169 volatility figure on the Bigdish page - where is it? TQVM
Don't think it is on the Stock report page anywhere. You need to add it to a portfolio (or have it as a result of a screen) and then customise the table by adding the "Volatility" column.
Thanks guys
I also wonder how the Government's £10 pound off in August will impact on Dish especially if it is extended for the rest of the year. I have punted on this stock a few times this year. Very volatile and punting money only; not an investment in my view. Buy at about 1p, sell above 2p has worked really well. A great idea and someone will make this into a huge business in time in my view but whether that will be Dish or a competitor is another matter.
Excellent pre-amble again Paul, it put me in mind of my student days in York - when the Saturday morning walk back from a night on the town lead through an alley with two pieces of bizarre graffiti.
The first was : Lumpen Proletariat Posse - I always assumed this one was an SWP politics student trying to be witty.
And the second : >We don't want to see the stars - As far as I recall York didn't do either Astronomy or Media studies at the time I had no clue about that one.
Any else in York in the late 80s with any insight?
Anyway, just I thought about BigDish (LON:DISH) and barnetpete's thought :
" I also wonder how the Government's £10 pound off in August will impact on Dish"
On the one hand you could say why will restaurant's need a DISH discount to fill the quieter days (Mon-Weds) when the Government is doing on for you.
On the other hand if the restaurant's could apply the DISH discount second (by making it effectively a cashback or eg 'we pay 25% of your bill") they could come out with some very compelling discounts for the quietest times during Monday to Wednesday.
And in fact if anyone has a sufficiently quiet time that they could stomach a 50% discount that could offer free meals up to £20 / head.
That might seem like unethically gaming the Government offer - but in reality it would achieve all of the objectives of the scheme :
THE DESIRED RESULT!
However, I have to reflect on the fact that I spent to much of my career working with Sales People on a "Payplan" because the very first thought I had when Rishi first mentioned he scheme was to spot the very obvious scam that is available (and which I am sure will happen)
Gromley - as you say, the scheme is very definitely going to be gamed but assuming the restaurant operates correctly then your figures need to adjust slightly as:-
"To calculate the value of the transaction and make a claim to HMRC, you must first apply any special offers, vouchers or discount schemes you might be promoting or accepting"
So, in your example of a £20 meal, first deduct the 25% DISH discount, leaving £15, then deduct the HMG 50% discount, leaving £7.50. So the customer will pay £7.50 and the restaurant will still end up with £15 (the customer is £2.50 better off having received the DISH discount and the restaurant is £5 worse off having accepted the DISH discount).
The obvious scams are, well, obvious.
Thank you Laughton, I confess I hadn't read the small print!
There might be other clauses, but that one doesn't explicitly running a different promotion including a bonus gift rather than a discount - could be a desert up to the value of £5, could be a £5 off voucher for return visit, more questionably could be a five pound note.
Whilst it is gaming it still delivers all of the benefits the scheme is designed to (in fact the voucher for a return visit probably doubly so).
There is definitely an opportunity for some creative pricing and promotions here; but on reflection taking your clarification in mind then for most, this probably IS a reason no to bother with DISH during August.
Sorry to be pedantic Gromley but how are any of your suggestions not covered by "special offers" or "vouchers"? For them not to be "special" presumably they would have to be offered on every day of the week.
There are much simpler ways (but none of them involve DISH)
Valid question, and indeed maybe I really have spent too much time with payplaned sales people, so therefore I would say that they do not impact the price actually charged to the customer. Whether that would fly or not I don't know.
That's a much more interesting point having now thought of it. I hadn't really researched the DISH offer in detail, but following your logic - any eatery owner can offer 20% off between 2pm & 4pm Monday to Wednesday for example.
I guess the edge that DISH offers is that if Tuesday becomes busy you automatically withdraw the discount - a bit like the Easyjet pricing model. Clever no doubt, but actually I think you've convinced me (not that I think was necessarily what you were arguing) that this might be to much hassle for too little gain for most eatery operators. ISDN
Gromley - I too worked with a lot of Sales people prone to creative accounting to maximise personal benefit (in fact I always remember being advised to only recruit/retain Salespeople with enough creativity and ruthlessness to do it to a certain extent!). However, the COVID response measures are going to result in millions (billions?) of pounds of fraud.
I understand why the 'helicopter approach' of just letting fraud occur for the greater good has an appeal but feel the govt needs to at least show concern and bluff (hire more accountants to track fraud - should be many cheap and available ones!). Otherwise, risk is that the fraudsters & spivs do well at the expense of the broader society and 'we are all this together' social cohesion and trust in authority drops even further.
More (I think this is new anyway) developments on the Boohoo (LON:BOO) story . BBC News , reporting that Carol Kane was before the House of Commons Environmental Audit Committee back in 2018, facing allegations of illegally low pay.
Doesn't appear to impacted the share-price today however.
It was about this HoC report "Fixing fashion: clothing consumption and sustainability":
https://publications.parliamen...
Boohoo (LON:BOO) are mentioned a few times and Carol Kane's responses quoted at length. There were a bunch of recommendations but, as we might expect, nothing was done.
timarr
Paul, another excellent preamble. I had a drink with a friend who is a hotelier last night. He has business in popular City and over on coast. I felt dreadful for him. He has built his City hotel from a shabby Best Western to a rather lovely set up. That said the investment has been large and this year was the first year he was starting to make real headway then Coronovirus hit. Currently 4 people staying. On the other hand the business he has on the coast is full and whilst spacing has cut restaurant capacity seems much more robust. My point being location remains the key it has just refocussed itself. So the London major City hotels will be really hurting whereas there might be some light for locally owned hostelrys in popular holiday places.
We live in Southend where people just seem to get on with it. We travelled to London for an appointment last Friday and the contrast could not have been greater. Seems that masks are a fashion accessory there. It was like wandering onto the set of Contagion. Its going to kill the city and good businesses like that of your friend.
Can't be a rebel and live in London anymore (well, unless you are the minority of rich rebels)...its where people come to sell their soul to the corporate devil with very little space to take a risk. Even the start up scene is hackneyed.
London needs shaken out of a complacent monoculture. It needs to do the 70s again....perhaps fill up all the empty finance towers post covid with record labels, gig space, illegal bars and clubs and whack-job artists and fashion people...throw in some coder/hackers, green space cadets and some olds willing to mentor and waste money whilst getting high on the madness of youth.
That's my manifesto anyway. #votemojo
Trading update from Morses Club (LON:MCL) today (up 9% to 57p vs +/- 130p pre-Covid).
Doubt Paul will comment (ethical concerns which I understand but disagree with) so would welcome some community comments .
Core Home Credit business (aka Doorstep Lending) was obviously initially hard hit by Covid since its Agents had to stop calling on its customers - probably for the first time in >100years! However, the moves in recent years to bring this business into the 21st century have really paid off. Some 60% (109/184K) customers now on portal; 80% have their money collected remotely (which will give a big long-term efficiency saving); and (client:agent) satisfaction is at 99%! Remote agent -endorsed lending has been established, a great blend of F2F and Digital for the long term in this lending area. Fresh lending so far has only been to existing (thus low risk) customers until this month when new lending resumed (no word if rates changed). Credit lending in M1-4 was 47% down but Mar-June is a relatively quiet period for new lending normally and June "up" to -30%. Critically, cash collection still running at 91% vs LY so whilst impairment will clearly be up it does not look as if the ultimate hit will be huge. Net customer numbers have dropped by 16% but I would expect this to reverse now agents can move more freely and demand will start to grow as the recession bites. What’s left are therefore high quality customers served very efficiently.
Net I think the COVID crisis has accelerated the modernisation of the business and in ways that all the small doorstep lenders (50% market) will have struggled to match. I think the slow process of small lenders selling/shutting up shop will be much accelerated in next 12-18M and only Morses will have the money and appetite to do it – and they were doing it well until 18months ago when selling prices got too high. Prices/set of book is typically only £1Mn so easy to do in low risk, bite sizes pieces. Of the 2 big national competitors, Provident Financial (LON:PFG) (+/-50% mkt share) is focused elsewhere whilst Non-standard Finance (LON:NSF) (sadly I own a big chunk!) are financially strapped and need a big rights issue or (and!) to sell Loans@Home. I think MCL could easily raise money to take this if they wanted.
Some may think that doorstep lending will fade and die but I think it has a role and meets a need for some so whilst it may shrink, it will take a long time to go.
On the downside, Morses also say they have been busy on their digital banking/lending arm but are noticeably more reticent on this (which is already a bit behind especially in terms of losses incurred) so I expect more losses. Balances are only 7% up on Feb 20% - so at least any losses from impairment must be small! However, I am happy with a cautious strategy as I am confident growth will come as demand will rise and less cautious competitors are going bust/scaling back.
Regulation is a cost (eg govt led automatic right to defer payments will have helped both the genuinely affected and the chancers) but long term, along with a negative corporate image, is a big barrier to entry. I can’t see it being banned as ‘red wall’ MPs who understand the real world will know it meets a need and high satisfaction levels mean it is not like pay day loans.
Overall, 20020 will be bad but I think Morses Club (LON:MCL) are the only class act listed in the non-standard finance space and will do very well over the next 2-5 years. (Disc. I clearly hold!)
I'm a long term holder of Morses Club (LON:MCL) and, although it took a huge dive during COVID lock down, it is a solid business and the reason I hold and have added to my position is the dividend, at 10%. I've no intention of selling this one in the medium term at least, even though it does look quite ugly in the portfolio at the moment! It's a shame Paul has an aversion here on principle as it would be good to get some professional comment on the financials, without emotion or sentiment. After all, there has been a lot of coverage of many companies on here that have turned out to be huge frauds or have ethically questionable practices!
Paul
Within my lifetime, at the beginning, knew of a distant cousin who had suffered polio, and had a withered limb as a consequence, and also heard of children who were severely mentally and physically damaged by their mothers not having any vaccine for the Rubella virus, and caught measles when pregnant.
Now all these are vaccinated against as a commonplace.
So the anti vaxxer movement really is one of the more disgraceful modern innovations in my view, and represents a triumph of ignorance over knowledge.
How easily we forget and take for granted what we have
Anti Vax is a difficult to assess and can be quite nuanced. It’s not just the hard-line no vax at all but also a solid group that should vax – but don’t for whatever reason.
Figures from Public Health England show that for the 2018 to 2019 season only 70% of front-line healthcare workers actually get a flu jab. Extract from PHE figures below.
National vaccine uptake rates
Overall,70.3%(739,187/1,051,851) of frontline HCWs received the seasonal influenza vaccine during the 2018to 2019season
I think that the position in Scotland for that year was even worse being nearer to 50%. GPs only 62%
These sorts of figures not only undermine the whole vaccine message but help explain why some people resist going into hospital for fear of catching a Hospital Acquired infection.
#EYE.
I've been watching Eagle Eye for some time.
Bought a starter position during the carnage earlier this year around 140p.
Previous to today, they had made clear that their grocery clients (C19 winners) made up 90% of revenue while the other 10% suffered from C19. They say their customers are sticky and usually add services after initial order. Client wins in US and NZ.
There is a very good explanatory video on their web-site.
I like the recurring revs which have increased to 73% and the update reads well and bears out their previous expectations and strategy.
They have said they have sufficient funds for their present growth plans and this is substantiated today by their cash position.
#EYE seem to be executing their plan - smells good to me.
Hi
For an insight into the UK business health, by each sector, this UK Gov report gives a comprehensive view with 10 insightful graphs across a wide range of metrics.
Coronavirus and the economic impacts on the UK: 16 July 2020
Link is here
https://www.ons.gov.uk/businessindustryandtrade/business/businessservices/bulletins/coronavirusandtheeconomicimpactsontheuk/16july2020
Far too much to summerise, but several positive statistics IMO. Not 'breath a sigh of relief levels', but soundly positive in contrast to common news feeds.
Regards
Howard
Hi
Adding to my previous post. This ONS/Gov report has 7 graphs covering more social aspects of life (people, population and community) such as retail footfalls, price indices and shipping trends to list but a few.
https://www.ons.gov.uk/peoplepopulationandcommunity/healthandsocialcare/conditionsanddiseases/bulletins/coronavirustheukeconomyandsocietyfasterindicators/16july2020
Regards
Howard
Paul
any thoughts on the positive trading update from Loungers (LON:LGRS)?
May I add my thanks to Mr C - really don't know how you do it - it's my must read early on in the morning.
I read TP (LON:TPG) 's H1 trading update first thing this morning as it's an ex-holding, read it again, had another cup of coffee and then had it confirmed by Mr C. They've issued a TU without any reference to revenue - no figures or meally words.
What's next, blank trading updates?
Some time ago I set up an arbitrary value portfolio on stocko as way of monitoring a potential shift in market strength - I apologise its large cap in bias - had 16 stocks and was 60% Oil and Resources 18% Banks 6% Tobacco and 12% House Builders with the stocks equally weighted. Its arbitrary with no scientific basis other than I wanted to pick up something I may miss....which was most likely strength in resource stocks, which have never been my strong point. For a long time this portfolio lagged the market miserably - over 12 months it has lagged - in the March sell off it underperformed 10% - BUT to my surprise it has turned positive and over the last three months is 4% ahead of the market return of 10%.
Clearly these stocks haven't even captured lost ground in the March sell off. However as a bit of fun, and rather than try and debate what Tesla may or may not achieve, I thought I would just compare Tesla to 5 UK stocks. I have chosen BT, BP, Rio, Barc and IMB as a representative value list. I will also monitor the All share index for comparison so we can have a window on value generally.
As an aside, should the marvellous Tesla hit $2000, this is only a 30% return, which over 10 years is less than 3%. I think my small list of stocks may well offer 100%.... I'll post the numbers every few weeks or when they are interesting...unless of course its of no interest, in which case I'll just watch it myself.
Why not compare with say Fundsmith? Thats a better comparison than Tesla which many people think is already massively overvalued? Its also quoted in sterling.
No view really but obviously the strategy of Fundsmith may be adjusted through time whereas the All share Index composition can only change through performance.
Fundsmith rarely change the portfolio and I guess would be a reasonable proxy for a growth investor. if not then the FAANGs?
"BUT to my surprise it has turned positive and over the last three months is 4% ahead of the market"
Apart from 6% in tobacco, that portfolio is entirely cyclical stocks. So it is very much consistent with market history that it should outperform as the market pulls out of a slump.
From a market theory point of view this is also to be expected as buying cyclicals in the middle of a slump means that you are taking on additional risk that should be priced in and compensated for, but so much for theory. Perhaps we could say that the reason it happens every time is that, like you, no one else expects it either.
There is an article by Alister Heath in today's DT about the 'extinction of London' as an unintended consequence of the government's response to Covid. People are now too used to working from home and unwilling to return to commuting. Talking to my son who works in one of the banks about this he says its the bosses who like it best! The government should get its civil servants back to the office if they want to set an example.
Could I also ask the community their views of Mj Gleeson (LON:GLE)? I bought this in the dip at around £6.20 with Berkeley Group (LON:BKG) because I thought that the housebuilding sector was cheap - most shares in the sector had crashed by 50%. I liked Gleeson's business model targeting first time buyers in the North of England but the shares aren't really moving. Their directors bought a load of shares at 600p. Looking at the accounts the only thing that puts me off is the historically high executive remuneration.
Its PE of 10 is higher than Vistry and Redrow but below Berkeley. I wonder if the market is anticipating an end to help to buy?
Paul just want to say that your writing just gets better and better. Just cracks me up. All the preamble was great but loved the story about your parents. Thank you. Something to make one smile in the morning is what we need in the current times!
Paul - I hope it is Stockopedia who provides MrContrarian with the Christmas present in the form of a regular, small stipend! I really appreciates his (witty) summary each day to get a sense on the day's RNS fast without trawling through each one.
Yes, indeed Paul a great contribution by Mr Contrarian each day!
Just to mention, piworld have an interview/webinar with Andy Brough today 16th July, at 1pm. Andy is Head of the UK & European Small&Mid Cap team, Schroders. He will give insights & tips on managing money from his 35+yrs at Schroders. Plus a rare opportunity to ask your questions. Register here.
Next Friday 24th July, 1pm, piworld have an interview/webianr with Mark Slater, Slater Investments. Mark will comment on how he's handled the markets, what he thinks is next, and general views on investing. Register here.
Both should be superb, they are top investors and top speakers.
Morning Paul, any thoughts on Xaar (LON:XAR) and Loopup (LON:LOOP) trading updates would be welcome today.
Just looking at leader board for the “Stock Picking Challenge 2020” the top 7 have Metal Tiger (LON:MTR) showing at an incorrect % gain so no insight can be really gained from what’s really happening here.
Skip boring paragraph
*** I thought it from the start, which would get around this technical problem, but the winner should be picked from the median position stock out of the 5 picks. (Position 3) It would then change the winner from the current +400% to around a 40%… Anyways, no need to start a debate about this as its been set it stone and month away from the finish line; just little heads up to whoever is in charge of maintenance of this that some % are incorrect.***
But, if any insight can be taken from this, all the leading picks seem to have a gold/metals bias. I wonder if this will change when all the correct % are taken at the end of the year :)
I agree it’s ridiculous some of these stocks chosen - they don’t even have any resemblance to conventional spreads!
Hi Paul,
A belated request for Luceco which reported a couple of days ago with some very strong looking numbers. Totally understand if its time barred:) !
Many thanks, Mike
Morning Paul, Early request for you to cover Morses Club (LON:MCL) if possible?
It's an industry I am trying to become more familiar with, particularly it's long term prospects.
Reassuring to see it's online division is growing to mitigate the COVID impact, but is essentially rapidly advancing the strategy for the business.
I was wondering why Purplebricks (LON:PURP) had jumped this morning, but they announced last night that they've sold their Canadian subsidiary for £35m leaving them with net cash of £66m. They're now entirely UK focused:
https://www.investegate.co.uk/...
Hat tip to @abtan who pointed out the opportunity here, although defo not for widows, widowers, orphans or those otherwise of a delicate disposition.
timarr
Purplebricks (LON:PURP)
Hi Timarr
You're welcome.
I must admit that I was actually quite disappointed with the sale of the Canada business for only a little more than they paid for it just 2 years ago. Top level they made c £5m on the purchase price, less whatever they have put into the business over these 2 years.
Still, at least it leaves the company able to better focus on one territory, with a huge cash pile to boost.
A couple of other points:
a) If cash today is £66m then this implies that the company had a net cash outflow of c £4m in April/May/June/half of July. (cash at end of March was £35m + £35m proceeds received from Canada business).
b) Purplebricks (LON:PURP) actually has what looks like a reasonable stake in a German equivalent, HomeDay - 10% I think. From memory I think this is valued at c£30m-40m. It's fast growing and is also being propped up by Alex Springer. Accounting for this implies the already very profitable UK business is only worth £60m. I'm cautiously anticipating a material re-rating at some point. Fingers crossed.
A
I have a small holding of Jarvis Securities (LON:JIM) but couldn't get a quote for 20 minutes this morning (from 3 brokers) by which time it was 660
I'll be interested to see what prices were achieved between 8 and 8:20 although I still wouldn't know how to get better access, unless that's where a proper broker comes in?
I'm also aware that if the opposite happened and I wanted to sell I may have had the same problem.
Beware liquidity!
634.4 from HL
I have repeatedly found that A J Bell fill limit orders inside the spread (for sizes several times the EMS and often within a minute or two) when they can't offer any online quote for larger than the EMS. I give them the price at the limit of what I'm prepared to pay and they usually do quite a bit better than that, so I'm happy to trust them.
Exactly my experience with AJ Bell too.
Votes for LOOP & JIM from me as both beneficiaries of the current climate.
Covid is clearly the driver behind LOOP's growth. One point I'll highlight is that that LOOP's higher margin offerings - basically professionally hosted on-line conferences have contributed disproportionately. Great as ZOOM and others' self-service broadband offerings are they leave niches for differentiated players with superior service and technology to also prosper.
Hosted service 'Event by LoopUp' was acquired with MeetingZone Group that they took over in June 2018.
A vote for Loopup (LON:LOOP) if you get a chance Paul? Some positively looking numbers regarding their six mth update.
Thanks
Paul I would be interested in your thoughts on Eagle Eye Solutions (LON:EYE) which had a reassuring trading update today. (I hold).
The company seems to be turning into a cash generative business. The company has ended June 2020 with net cash of £1.5m - implying free cash flow of £3.7m in H2. Some of this has been due to tight working capital management and will revert in FY2021. But still if the £5m RCF with Barclays can be renewed (and I see no reason why it should not) then it looks like the company can stick to the promise it made in the November 2018 Capital Markets Day that it could fund its business plan without the need to raise new equity.
I second this request for Eagle Eye Solutions (LON:EYE) to get a look from you, Paul - the combination of good and consistent revenue growth and increasing profitability seems to confirm that this business has some real value. Although "adjusted EBIDTA" is a questionable measure, £3.3m is quite a BIG number for a small company! (After having watched for months I just bought a starter stake).
I would second a request for (LON:EYE) I hold and think this has a lot of potential. Stockranks dont like it as it isnt making a profit yet but there is strong growth and recurring revenues which are building nicely. I suspect they could be profitable if they wish but are instead reinvesting into further growth which I think is the right call given the opportunity. There are quite a few results presentations on the PI world site which give a good overview of the business for anyone interested.
Paul - thanks for your interestingcomments.
Great idea. I would definitely contribute something for MrContrarian's Xmas present!
My morning smallcap tweet: LOOP cock a hoop
Aseana Properties (LON:ASPL) Tiziana Life Sciences (LON:TILS) LoopUp (LON:LOOP) Eagle Eye Solutions (LON:EYE) Morses Club (LON:MCL) Symphony Environmental Technologies (LON:SYM) Sumo (LON:SUMO) Gresham House (LON:GHE) PV Crystalox Solar (LON:PVCS) TP (LON:TPG) Hardide (LON:HDD) OptiBiotix Health (LON:OPTI) Loungers (LON:LGRS) SIMEC Atlantis Energy (LON:SAE) Mirada (LON:MIRA) Nanoco (LON:NANO), Brooks Macdonald (LON:BRK), Xaar (LON:XAR)
Aseana Properties (ASPL) revised timetable for demerger - vote in Aug. Four Points Sheraton Hotel in Sandakan permanently closed after Marriott terminates mgmt of it, along with a number of other hotels that they manage in Asia.
Tiziana Life Sciences (TILS) has submitted a patent application on potential use of Foralumab, a fully human anti-CD3 monoclonal antibody, to improve success of CAR-T therapy for cancer and other human diseases.
LoopUp (LOOP) guides H2 rev up 43% and adj EBITDA £12.2m (£3.5m). Expects to exceed FY market expectations.
Eagle Eye Solutions (EYE) guides FY(June) rev up 21% and adj EBITDA £3.3m (£0.7m). "While new business decision making is likely to continue to be delayed during this period of uncertainty, our sales pipeline continues to grow, and we are engaged in positive discussions across multiple geographies."
Morses Club (MCL) Home Collected Credit issued during first four months of FY is 34% ahead of the covid plan, albeit down 47% on year. Cash collections 21% ahead of covid plan. Borrowing cut to reduced to £12m cf plan of £18.5m - puts co in a strong position to take advantage of any increase in market demand
Symphony Environmental Technologies (SYM) guides H1(June) rev up 21%. Some distributors have experienced severe lockdowns which have delayed growth. Group does not expect to need any additional cash in the next 12 months. "Group is pleased to see growing orders, and indications of a much stronger order book going forward." But no guidance.
Sumo Group (SUMO) £13.7m placing at 180, a 7% disc. Cash is for potential M&A opportunities.
Gresham House (GHE) Trading at least in line with market expectations for FY. AuM up 17% in H1, 10% organic.
PV Crystalox Solar (PVCS) 55p (9% premium) tender offer but only for up to 3.6m shares. 7.3m in issue. Will delist end Sept.
TP Group (TPG) H1(June) trading: no rev figure! Co "well equipped to continue its robust performance in the second half of the year."
Hardide (HDD) guides FY(Sept) rec at least £4.7m, down 8%. Delay of large order from a major oil well operator which has rescheduled the development of a major project to 2021. Co has sufficient cash reserves for the medium to long term based on the current sales projections.
OptiBiotix Health (OPTI) has extended the terms, territories and products from its distribution agreement with CTC Holding for the sale of CholBiome.
Loungers (LGRS) has re-opened 75 Lounges and 19 Cosy Clubs (from total 138 and 29 resp.). "As a result of the confidence we have gained from the trading at our re-opened sites to date, we have decided to accelerate our re-opening programme and will have the full estate re-opened by 5 August." Will close 2 outlets though.
SIMEC Atlantis Energy (SAE) flagship Uskmouth power station conversion project will now be developed in two halves due to lockdown delay. Financial close expected to occur in late Q1 2021 or early Q2 2021.
Mirada (MIRA) FY(Mar) rev up 7%. Pretax $275k (-$3.3m). "Despite the uncertain impact of COVID-19, Mirada's financial position is continuously improving,...these factors have led to an improved commercial performance, with participation in multiple deals, which, combined with the growing pipeline, provides confidence in the Company's ability to secure more contract wins in the coming years."
Nanoco (NANO) increased fundraise last night to £3.4m, at 17.5p, a 3% discount.
In line: Brooks Macdonald (LON:BRK) Xaar (LON:XAR)
Paul, any immune response will see a drop off in antibody levels once the virus has been controlled by the immune system, because the cells that make antibody, plasma cells, are short lived. This makes sense because making antibodies uses loads of energy and resources, so you only want to make them when you need them. What’s important for longer term immunity are the presence of B and T memory cells, the former can very quickly turn into plasma cells on a second infection and resume antibody production, the latter can very quickly turn into the Killer T cells that you need to take down cells infected with virus. So I don’t really understand the concern over antibody count. And I don’t think you should be trying to catch Covid again!
The Altman Z-score, in my opinion, is a valuable element of the StockReport. So this article from Bloomberg may be worth a look. In essence, Altman predicts a surge in the number of large US companies about to go bankrupt. Moreover, he asks what could be considered a really simple and relevant question for investors on both sides of the Atlantic. Why provide companies that have solvency problems with more debt? Surely they should be de-leveraging?
https://www.bloomberg.com/news/articles/2020-07-15/father-of-the-z-score-predicts-a-surge-in-mega-bankruptcies
Why provide companies that have solvency problems with more debt? Surely they should be de-leveraging?
Often unplanned forced deleverging (presuming its via right issue) is akin to sitting by the beach with your chips and actively encouraging the local mutant seagulls to share your feast - you won't be left with much as the gulls feast out and grow bigger again. Those big gulls know when to pick a fight and when not too.
I guess the other factor is the government will do anything to kick the problem down the road - they probably fear many such businesses will simply go pop as they won't be able to secure finacing if they don't feed the frenzy.
I don't think one needs to be an expert on the Altman score to realise the precarious situation we are in at present - but useful tool it is. For my sins i own marstons / easyjet and carnival - and Altman sensibly puts 2 in the red and one in the caution zone - i think i should be more than cautiously worried about my carnival position though if i am being honest. As i have said before its a complete crapshoot at present for companies in debt with no clear quick route back to enough profit to service that debt.
Its hard to deleverage unless you make a profit or sell assets. A lot of the debt run up in the US is from airlines and cruise ships who have cash burns of $hundreds of millions, The Fed is also buying corporate bonds and is seen as the backstop to this issuance. Perhaps buy Goldman Sachs for the fees they earn from all the debt raising. Their results were very good.
I’m feeling everyone’s difficulty deciding on where we are going, will there be a depression, no, will we be back to normal in a few months, no. Recovery in a v shape, u shape, w, v etc.
Bearish, bullish, my mood changes like a manic depressant.
I get the argument that we're investing for the future and that a lot of companies will get back to normal, many with increased market share.
However, whats christmas going to be like this year, realistically theyll be no vaccine and covid outbreaks increasing. That means no winter-wonderland, no midnight mass, no office party, no christmas market, no pantomime, no big family christmas gatherings, delivery companies trying to cope with increased christmas workload on top of the extra covid workload, and traditional retail having to restrict customers in their already half empty stores.
So many companies relying on the christmas trade which will never come.
I brought marks & spencer at 89 in a moment of optimism targeting 189 by end of next year! right now I wish i'd taken the 110 on offer last week.
I beginning to think traditional retail is toast along with quite a few other businesses.
Team 17 just posted an interesting report. Any thoughts? Paul?
Tencent is massive. I’d have thought any affiliation with them to be a good thing.
Hi Paul
Extremely decent results this morning from Jarvis Securities (LON:JIM), so perhaps worthy of your review this morning.
All the best, Martin
I should have added that as well as being excellent results in themselves, Jarvis Securities (LON:JIM) have issued them 16 days after the end of the period. What a contrast to other companies where the delay is many months.
Loved today's preamble, positively Shakespearean. As for face masks: they make it far less likely the wearer will infect other people and slightly less likely they'll catch it themselves. People who refuse to wear them are simply selfish, I'm certainly not visiting anywhere crowded unless people are wearing them.
On to today's news, couple of my holdings reporting. Jarvis Securities (LON:JIM) have announced half year PBT up 50% and are currently trading above expectations. That's in line with most companies geared to trading volumes.
Loopup (LON:LOOP) have a trading update that, unsurprisingly, shows good growth - gross profit up 52% and net debt halving. They expect to exceed market expectations for the full year "in terms of in terms of revenue, EBITDA and cash generation". Whether that'll be exciting enough for the market remains to be seen.
timarr
re Jarvis Securities £Jim
No explanation as to why huge increases in Trade Receivables & Payables, receivables are more than the revenues. This also makes the cash flow statement negative.
No explanation as to why huge increases in Trade Receivables & Payables, receivables are more than the revenues. This also makes the cash flow statement negative.
It's a fair point, and without explanation is a red flag. Usually with Jarvis Securities (LON:JIM) this is related to settlement receivables and, roughly, is a good sign as these increase as trading volumes go up. However, given the big jump it certainly should have been explained.
timarr
stegga1000000
AIUI, the "trade and other receivables" is highly volatile from day to day. It comprises trades where clients deal through a stockbroker that has a Model B account with JIM, and settlement is delayed for one or more days. For regulatory and cash purposes, JIM has to fund this delayed settlement from its own cash.
Obviously, with the increased trade volumes, this figure will tend to be larger than used to be the case.
For each such trade, JIM has minimal if any credit risk as they hold whatever stock the ultimate client has bought, as well as having a suitable security arrangement with each individual stockbroker on Model B. So if the client doesn't pay, the amount owed can still be obtained from the stockbroker and/or selling the stock.
Thus AIUI there was zero bad debt in the reported period.
The annual results do provide a breakdown of the "trade and other receivables" figure albeit, as it varies so greatly day to day, it does not add much clarity IMHO.
Hopefully the next set of results will provide a bit more detail as per the above.
HTH. Cheers, Martin
Tim. Agreed. I have been in France since lockdown (confinement) which was lift in early June. Without mandatory messages people, I think, choose to interpret information to suit them (a bit like the weather, I go to multiple weather sites until get the weather that suits my plans for that day).
Here in France from my own anecdotal experience people get complacent and many people do not wear masks (inside public spaces) or social distance because “cases have dropped, deaths are non-existent so I don’t need to bother”). Bizarrely when I popped into the supermarket yesterday the people not wearing them wear old, morbidly obese or the young fit dudes. Then you get the oddy of a couple walking a long with one wearing a mask and one not.
Regards
Michael
Magnificent stuff, up there with that great recent one from Bournemouth, with that lyrical description of the sunset walk, ending with the payoff line from the graffiti on the bench. That still makes me laugh.
More "research" in the pub I see Paul ;-)
Excellent intro Paul-you really should think about writing a novel..
I would welcome any thoughts you might have on the S4C (SFOR) RNS announcement yesterday evening (5.20pm)-seems like more dilution on the way?
I used to frequent a Lord Clyde in South London many moons ago (90s) whilst working for the London branch of an American corporate. Great local; wish my area still had pubs like that (they're now almost all converted to blocks of flats). My boss would take great delight in walking or cabbing our American overlords, who were used to swanky NY bars and fine dining, over to the Clyde when they came over. Would be great to see their nervous confused polite grins as they really didn't know what to make of the local South London boozer, with it's array of characters and landlord who seemed to know everyone by name. A few ales, Guinness's, pie and mash meals and games of darts later, they'd all be asking to come back next time they were in town.
Sorry for the diversionary story. Have joined the Stocko community this year and was rather hoping to make my first post something of real investing value! Ho-hum. Anyway really enjoying Stocko; great community of knowledgeable, polite, respectful, helpful posters. Am looking to get back into investing / trading, and so am devouring as much reading matter as I can. Not enough hours in the day sadly, so Stocko helpful for focussing on many of the key events and issues. Well done Paul, Graham, Jack for this great blog.
Hi CBC19,
Welcome, and what a super inaugural speech! Well done. Very much in tune with our (usually) polite and supportive tone here.
My Lord Clyde is in N1, so sounds like there's another (even better?!) one in South London. Or saaarf London! ;-)
I look forward to discussing shares with you in future.
Best wishes, Paul.
Hi Paul any thoughts on the Nanoco (LON:NANO) situation seems the cash raise has extended the run way until the end of 2022 buying time in the case against Samsung. It could be developing into a special situation akin to the solar wafer company a few years back that won a dispute with the Chinese and got a large cash pay out.
Sense that Paul has not visited the real Lord Clyde in Borough. One of the best local pubs around which can be busy even on a Monday evening in winter. However, am a mite worried that its name might not last for much longer given the current PC climate. Lord Clyde, according to the pub's website, put down a slave rebellion in Demerera in 1823 and went on to play a big part in putting down the Indian mutiny of 1857.