Small Cap Value Report (Thu 16 June 2022) - BOTB, HRN, BWNG, ANX

Good morning! It's Paul & Graham on duty again today.
Agenda -
Paul's Section:
Best Of The Best (LON:BOTB) (I hold) - Results for FY 4/2022 are ahead of expectations. The company also announces that shareholders can tender shares (total up to 11% of the company) at a c.50% premium price of 600p, which has put a rocket under the share price today. It's probably worth taking up the tender offer, given that management is doing so, but they remain very substantial shareholders. Valuation does look cheap, with a PER under 10.
Graham's Section:
Hornby (LON:HRN) - a successful turnaround story continues at the model railway company, after many years of pain for shareholders. Potential operating leverage could generate very significant profit growth in the years ahead, if the Chairman’s analysis holds true. The shares already price this in to an extent, but depending on your view of the medium-term sales trend, could offer some very nice upside.
N Brown (LON:BWNG) - this trading update doesn’t mention any progress with the Allianz litigation. Trading has softened compared to last year, due to the lack of any online retail tailwind from lockdown. Earnings expectations are unchanged. Looks extremely risky due to multiple factors, difficult or impossible to value.
£ANX (no section below) – this credit hire (car hire) and legal services group provides an AGM trading update. Trading is in line with expectations. Credit hire is growing rapidly with vehicles on the road up 52% compared to last year. The legal services division is seeing increased cash collections but it’s unclear if the other information given in this section of today’s update is useful or material. Negotiations continue with VW over the emissions scandal, where Anexo’s subsidiary is representing clients against VW.
ANX shares are superficially cheap versus earnings but investors need to have a strong view on the quality of the company’s £215 million in total assets, including £188 million in receivables (as of December 2021), as any writedowns could be very damaging to future earnings!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Best Of The Best (LON:BOTB) (I hold)
467p (up 24% at 08:15)
Market cap £46m
Best of the Best plc (LSE: BOTB), the provider of online competitions to win cars and other prizes, is pleased to report its preliminary results for the year ended 30 April 2022 (the "Period")
I last reported on this online competitions business here, when it issued a “slightly ahead of expectations” (for profit) update on 11 May 2022, re FY 4/2022. This seemed encouraging, and the valuation looked modest, hence why I decided to continue holding, despite a very disappointing previous collapse in share price.
EPS has come out ahead of what I was expecting previously (around 40p), and broker consensus of 41.7p. Actual is 45.3p - not bad. Note the exceptional prior year, pandemic boosted comparative -
Earnings per share was 45.30p (2020: 37.51p, 2021: 122.52p)
Current trading - in line with expectations.
Tender offer - I need to get my head around this separate announcement as a priority, to see if I need to do anything (buying or selling).
BOTB is returning surplus cash of £6.275m to shareholders via a tender offer for 11% of the shares, at a big premium of 52%, priced at 600p.
This will boost EPS.
It’s voluntary, so shareholders can opt to tender any amount of shares, I think. As it’s a large premium, then I’m guessing many shareholders are likely to over-apply, so it could be over-subscribed, which would result in applications being scaled back.
Cash of >£2.0m will remain in the company, which it says is “sufficient”.
Shares purchased by BOTB (via Finncap) will be cancelled, thus reducing the share count from 9.4m to c.8.37m.
Directors holding 48.6% of the company are taking up their basic entitlement (i.e. to sell 11% of their holdings) at 600p.
There’s also a trading update in the tender announcement -
As stated in the aforementioned announcement, the Company has delivered consistently strong results over recent years and management have been adjusting the various business levers at their disposal, to ensure that where revenues and customer acquisition are settling and normalising post pandemic, the business continues to produce strong profits and cash generation. Whilst this has not been without its challenges, with so many unknowns in this financial year, the Company is pleased to have produced financial results a little better than market expectations.
The Board remains confident that the Company is underpinned by very solid financials, a large and loyal database, and a proven business model. There will understandably be continued focus in the short term on both profit and cash generation to support and strengthen our platform as we then to look to further business development opportunities and growth.
My opinion - given the large premium in share price, then it seems logical to tender as many shares as I can, then buy them back cheaper in the market. The market price is currently about 470p bid price.
It’s a bit disappointing that management are taking up the tender offer, but they will still own c.43% of the company after tendering 11% of their holdings. Previous large disposals were made at £24 per share.
Finncap has upped current year forecast EPS to 53.9p (a 23% rise, about half of which looks due to the tender offer). Hence the PER would be under 10, at the current price of 478p - that looks too cheap to me. Although management selling some more at 600p does make the upside look limited for now, maybe?
As demonstrated in the pandemic year, BOTB has stunning operational gearing, in both directions! Plus, revenues are still running at about double the pre-pandemic level, so it’s held on to a lot of the growth. The main problem is that online marketing costs shot up.
Overall, I think it still looks interesting, and am glad I held on. It's understandably likely to take time for confidence in the company to return, but these numbers certainly help, as does the tender offer - reinforcing that it's still a very good cash generator.
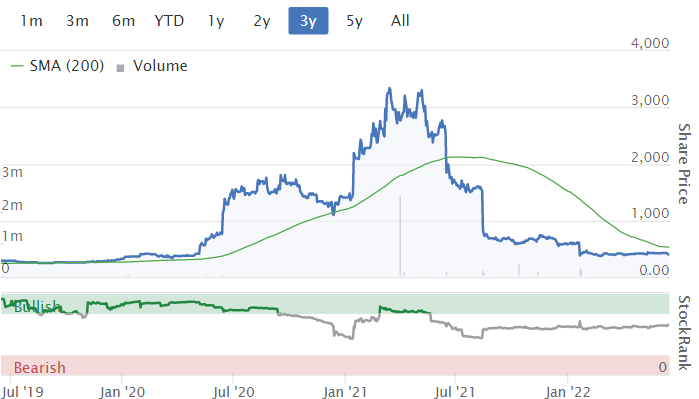
What a rollercoaster this has been -
.
Graham's Section:
Hornby (LON:HRN)
31p (up 3% at 08:35)
Market cap £52m
This model railway manufacturer has been in turnaround mode for years, and did finally succeed in turning a profit last year.
Today’s results (FY March 2022) show further improvement in revenues and profits:
- Revenue £53.7m (2021: £48.5m)
- Operating profit £1m (2021: £0.6m)
- Earnings per share 0.89p (2021: 0.82p)
The results of the last two years will come as a great relief for shareholders, who previously endured nine consecutive years of losses!
Even so, very few investors will be sitting on capital gains:
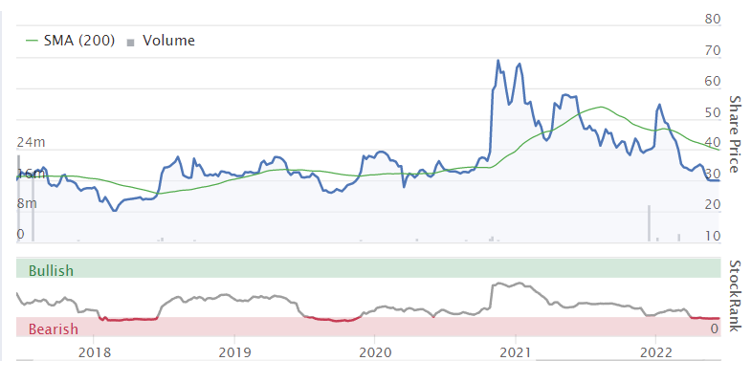
One obvious factor in the lacklustre share price performance is the quadrupling of the share count since 2015:
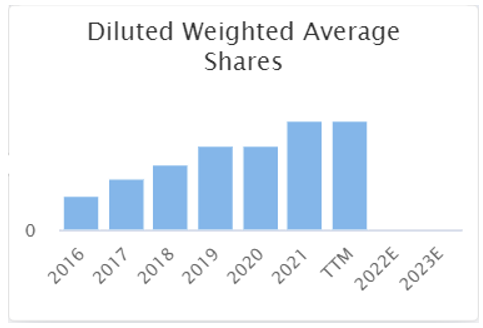
Those of you who are familiar with my work know that I hate dilution (and I love share buybacks, which are the opposite!).
Of course there are times when dilution is necessary, but it still makes life hard for existing shareholders. Hornby shareholders have seen the overall value of their company increase, but due to the rising share count, have not yet seen a sustained increase in the value of their shares.
Let’s dig into these results in a some more detail.
Supply chain – Hornby was affected by various delays, which both increased costs and held back sales. In particular, the company tells us that many Hornby and Scalextric sets did not arrive until after the Christmas season.
The Chairman provides excellent detail here, e.g. 70 days of transit time for shipments (previous 30 to 35 days), and container shipping costs rising in price from £3,000 to £17,000. These issues will have affected all companies. Some very useful information here.
I hope these issues aren’t also affecting Father’s Day! Hornby has a clear target audience in “gifts for Dads”, meaning that Christmas and (to a lesser extent) Father’s Day are key dates for the company.
Looking forward, Hornby wants to diversify production outside of China, but little detail is provided on this yet.
Financial performance – the Chairman provides a very helpful, plain English description of the company’s performance, with the help of the following table:
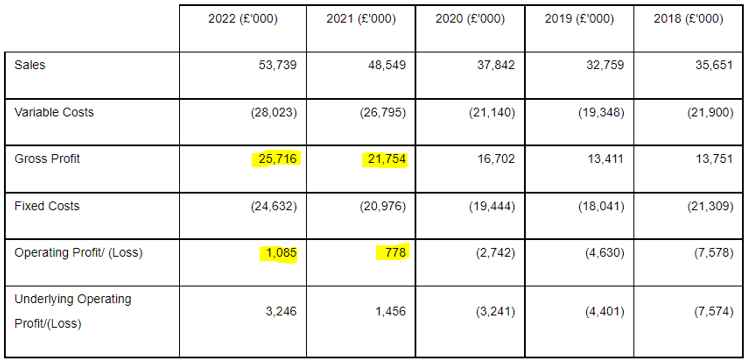
Hornby’s gross profit margin (gross profit divided by sales) is now 48%, up from 39% in 2018. In the long-term, the Chairman is looking for this to reach 60%. A very worthy goal!
Separately, the company is predicting a reduction in fixed costs as a percentage of sales, from the current 45.4% down to 40%.
Operating leverage - the funny thing about fixed costs is that everyone knows they aren’t really fixed. They naturally increase, as sales increase. The trick is for them to grow at a slower pace than sales do.
If you see the table above, you’ll see that I’ve highlighted some numbers. In 2022, the company has made an operating profit of £1.1 million, despite making a gross profit of £25.7 million (against £24.6 million of fixed costs).
If fixed costs were really fixed, then there would be scope for operating profitability to very quickly double or treble! Gross profit would only need to increase by 4% or 5%, in order to grow by more than £1 million.
Then, if fixed costs were fixed, that extra £1 million would drop straight through to operating profit, and the company would be twice as profitable!
But look at what happened between 2021 and 2022. Fixed costs grew by £3.6 million, wiping out most of the increase in gross profits.
The Chairman comments on this as follows:
In the last annual report, I reported that our current fixed cost base could service a business bringing in £50 million to £55 million of sales. Our fixed costs have now risen, as they must, if they are to support sales of £60 million to £70 million. These increases in fixed costs are in several parts of the business, but mainly in our Digital Team and the support that they require. This started to bring rewards in the second half of the 2021/22 financial year.
Online sales – these are limited, the Chairman appears frustrated with the lack of progress here but wants to improve.
Outlook – current trading is line with expectations, but this is the quiet season.
My view
I have a positive view on this one! I’m excited by the prospect that current fixed costs, according to the Chairman, might be sufficient to support sales of £60 million to £70 million. If that’s the case, then very significant additional gross profits might feed through to operating profits.
The market cap is around £50 million, which does already price in an increase in profitability. But if you can see operating profits grow by £4 - £5 million from the current level, then I think the value on offer is quite good.
If I was to put my pessimistic hat on, I could argue that the model railway market is a small, well-defined niche without significant growth prospects.
I could also say that while Hornby is the undisputed market leader in the UK, there is difficult competition outside the UK, particularly in the US. All of these companies are doing the same thing in the sense that they all import their wares from China/Korea/etc. International growth is likely to be very difficult.
So while I don’t see this company offering much long-term growth, I do think that it could offer investors quite lot of value in the medium-term, as the turnaround concludes.
91% of shares are owned by Phoenix (the majority shareholder) and Artemis. I know a little bit about Phoenix and have no concerns about their ethics, so I would not mind being a shareholder in a company where they are the majority owner.
N Brown (LON:BWNG)
27.6p (down 3% at 09:34)
Market cap £127m
Paul has ceased coverage of this online clothing retailer and lender, for understandable reasons.
I’m still curious to see what it has to say for itself today, so let’s just have a brief look.
Q1 revenue is down 2.1%, with financial services (i.e. lending) revenues down 4.8%, and product revenue down 0.6%.
Last year’s lockdown “provided a tailwind to online retail demand” (agreed!), so an equally strong performance could not be achieved this year.
And it’s another inflation story:
The trading environment has been challenging since the start of FY23, with inflation impacting consumer confidence, resulting in softer volumes and revenue than anticipated at the start of the year.
Strong balance sheet?
I’m not sure about this:
As at 28 May 2022 the Group had unsecured net cash of £30.8m. The securitisation facility was voluntarily underdrawn by £66.6m and can be redrawn if required. In addition, the RCF of £100.0m and overdraft of £12.5m are both fully undrawn.
As flagged by Paul, there’s a legal problem which hasn’t been resolved, which may affect the cash situation here.
It’s all explained in the twenty-second footnote of the most recent annual report. It appears that JD Williams (the N Brown subsidiary) and Allianz are blaming each other for what happened during the PPI mess.
From the most recent annual report (I’ve added the bold):
Should the matter proceed to trial, the eventual outcome is highly uncertain. The range of potential outcomes is very significant given the disputes between JDW and the Insurer as to which sums should be brought into account and what proportions of the liabilities they should each have to bear.
The likelihood of a Court finding wholly in favour of the Insurer, without taking into account the costs already borne by JDW, is considered remote. Accordingly, the maximum potential outflow is considered to be significantly less than the £66 million claimed by the Insurer.
N Brown has only made a provision of £28 million so far.
Outlook - unchanged.
The Board remains confident that over the medium term our strategy will support the delivery of 7% product revenue growth with a 13% EBITDA margin.
My view
Looking through the archives, I previously wrote that it might be worth “digging around for value” with this share.
I acknowledged that the company’s website brands – Jacamo, Simply Be, and JD Williams – weren’t top tier, but I still thought they could make some money for investors.
Unfortunately, this share has headed ever deeper into “value” territory over time, and now it has this dark cloud of litigation hanging over it, which looks set to linger.
There’s also a very complicated balance sheet to contend with, due to the large credit operations.
The most recent annual report shows £577 million under “amounts receivable for the sale of goods and services”, offset by £68.7 million under “allowance for expected credit losses”.
To finance these lending operations, there were £302 million in bank loans.
Since you have websites of questionable quality on the one hand, and large bank-backed consumer lending into a tough economy, with significant credit losses, on the other, there is now little doubt in my mind that BWNG shares should be very cheap. That’s without even mentioning the Allianz litigation.
At low enough levels, BWNG shares could make for an interesting “punt” or a trade, but I don’t see them as an investment.
.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

83 comments
this is a buyers market for me. I have no influence on the market, I am a buyer and I believe it will get better for me, but I don't know. I know this is great. It could become greater. I hope.
lower lower price equals greater return
please sell and make me richer
what you do is up to you. If the market is a casino, then you will be lucky or not
I am seeing the gambling from the investor and until this is finished, we will get back to the real investors. When we own the companies profits and losses.
Understand your business and buy it when it is cheap. It could become cheaper, buy more. This is the best time to buy. Hope that you can buy more at a lower price.
traders will not do well
not not true, very good traders do well. It's a very hard game that I admit I do not have an advantage
please sell and give me a better entry price
Paul, Should I plough into LON:BOO
My short answer would be - No.
Why, because you're asking for an order - not for advice. Also, perhaps personally, this question horrifies me.
Not everyone will agree with me, but I'm ok with that and power to them. This is a quick snippet of my process.
I would read the last five years of annual statements, do research on the creative director, the chairman, the CEO and the chief financial officer. Then I would also listen to all the presentations, especially the shareholder questions at the end. Once you've done that and you understand the balance sheet, the income statements and the cashflow statements for as far back as you can. Once you've done that, you will know what you are going to do and it'll be your decision.
If you don't understand how to find and value a business, find books (at least five different books is a good start) and read them from people who have at least 20 years experience. Don't short cut as that short cuts yourself.
That's how conviction works.
Hi Mark - totally agree. What is the 5+ book out of interest?
I meant, read at least five books on the subject of finding and valuation of businesses. Sorry for the ambiguity.
Yellow Cake (LON:YCA) (I hold) has me puzzled. Its dollar denominated so it should strengthen with the rising dollar and has a NTAV of around 430p. Apparently (according to Russ Mould in The Telegraph) the US govt has initiated strategic buying of enriched uranium to secure energy supplies. Thus I am puzzled why the SP is sitting at the bottom of its recent range?
I expect there are many such examples at the moment.....
I was just browsing the popular screens and noticed that Photo-Me International (LON:PHTM) (I hold) is now in the Jim Slater Zulu Principal screen. This makes sense as they appear to be rolling out the laundrette business such that the EPS growth looks excellent with the resultant PEG well below 1.
There has been significant profit taking of Photo-Me International (LON:PHTM) in the recent sell off which might offer a good entry point for those who think this share could defy the recession gloom. SP now sits at a strong support level.
Personally I am waiting to see if this support level holds before adding to my holding. The RSI is warning that the SP could drop to a lower support level. This wouldn't surprise me as the market seems to be selling off everything (even those with good news flow and earnings upgrades!)
Photo-Me International (LON:PHTM) is most definitely on my radar, in this market anything can happen. Not surprised at all if 75p breaks.
Nice to see you back Graham.
Sorry to revert to £Boo but looking over the TU for Boohoo (LON:BOO) (and I might be clutching at straws here) I would highlight:
Over the three-year pre-pandemic period revenue is up 75%, (CAGR of 20.5%)
UK: Revenue of £272.1m is 0.9% lower YOY versus a very strong prior year comparative (Q1 FY22: revenue of £274.6m was +50.0% YOY). January and February are typically slower months in retail, a trend that has been exacerbated by a strong prior period comparative when UK non-essential retail was closed. UK sales have improved month-on-month over Q1 and returned to net sales growth in May.
USA: Revenue of £95.0m is 28.0% lower YOY (Q1 FY22: £131.9m was +43.4% YOY). As in the UK, growth in Q1 is impacted by strong prior year comps
A facility in Pennsylvania has been secured and once operational will potentially enable the Group to offer next day delivery to c.50% of customers, with 2-3 day delivery available to c.90% of customers.
At last nights close price Boohoo trades on FY23E EV/Sales of 0.4x falling to 0.3x, an EV/EBITDA of 7.2x falling to 5.3x and a PE of 26.2x falling to 16.4x
Maybe they should be on a PE(f) of 14 but personally that seems to low. Buy? If I only knew. But the sell of certainly looks overdone to me but then I would say that!
Regards
Michael
With regards to Boohoo (LON:BOO) Michael I feel your pain - not nice watching a SP continually declining.
Luckily I bailed out much earlier, but have traded in and out a bit, but never felt truly bought into the longer-term story/plan - feeling that it needed some evidence of recovery before I felt comfortable.
With todays update I see the light at the end of the tunnel and some better results/promise in the short/medium turn, but the risk is that these trends are stopped dead in their tracks by a downturn in spending patterns if/as recession strikes.
However, today might be a buying opportunity as I am sure the SP is oversold on the back of both the ASOS and broader market down-trend.
To this end I bought a small holding in my SB account, but won't go near them in my SIPP/ISA without a more general market up-move and/or hard evidence of recovery. I tend to trade my SB account so this isn't likely to be a LT holding.
If I was sitting on the big losses as you seem to have its a hard call, but probably I would take my losses and find something else - it could be a very long road to recovery, and probably more a personal view, I don't like seeing -50% shares sat in my PF, so I generally get out and look to make money elsewhere - easier said than done and I don't always eat my own cooking!
Good luck and lets hope Boohoo (LON:BOO) makes a move upwards in the short-term.
Just as an aside, my teenage daughters don't buy anything form Boohoo (LON:BOO) they both use Shien all of the time. Hardly a representative sample, but the competition is definitely out there.
Welcome back Graham
Best Of The Best (LON:BOTB)
I do not hold but a tender offer really makes sense only as a mechanism for management to take even more money out of the business. They own 48% of the equity so they will effectively receive 3m back. Why are they not doing a buyback instead at market? I'd expect it to be heavily oversubscribed, no idea what the price will be post the tender!
Paul
As Boohoo (LON:BOO) (I hold smallest holding was largest - no sales) market cap has dropped this morning from £823m to £703m and is back (in one short and painful year with a worst performance than Bitcoin!) in SCVR territory, would you be prepared to comment on their’s (and £ASOS) trading update.
Do you think Boohoo is a zero? I don’t
Could they be taken private? I do and I would if I was Kamani et al. I hope not.
Has the baby been thrown out with the bath water?
Are you buying at these levels? I am thinking about doing so. My position has shrunk to such a small level that I really should make a decision. Either get shot (I don’t have to, as Buffett so wisely said, and probably shouldn’t make it back the way I lost it and not have to look at a six figure paper loss every time I look at the portfolio) or buy a lot more to bring the holding up to a level where a recovery in the price can have impact in the portfolio.
Thank you.
Regards
Michael.
Hi Michael, share your pain though maybe not quite to the same degree.
I think the key here is to clamp down on returns. A wife of a mate purchased 5 shirts for a party so he could select one and return the rest. Apparently "all their friends do it all the time". The industry needs to address this IMO - ESG it is not!
I, by the way, went to the same party - shopping in Reading was interesting - very little selection. M&S and Zara were about the only places with any range. Online the selection was vast.
I cant see LON:BOO going under but boy has the steam gone out of it! Like you I've thought about doubling down on it - but each time I haven't - I've been rewarded.
Apologies for not being able to add much more. Hopefully Scotty will give his pennyworth later.
Very interesting.
On returns I think that to some extent their hands are tied by the law but also market forces.
They could try:
Offering only credit notes which they are allowed to do
Not offering free returns (ie customer pays for returns)
Maybe a membership (a la Prime/Costco) to get free returns
Maybe there is (or could be developed) technology that could assess whether the goods have been used
The first two could well back fire. The third one I would have thought would be worth investigating especially if they can find a way of throwing in other benefits.
Who knows on the last one.
Regards
Michael
"Could they be taken private?"
If there is any life left in Boohoo I would guess that this is the most likely option - but a price which would probably disappoint any remaining shareholders.
I think you just have to be patient with Boohoo, you might be looking at several years for a recovery. In the near term they are going to keep suffering with pandemic related problems and now inflation. ASOS are also having a tough time at the moment.
Longer term the US distribution centre will be running from mid 2023, if pandemic issues have gone and they get back to the sort of growth that they used to have in the US there is a good chance that it will be a multibagger from these levels. On the other hand if you believe that online fashion has run out of growth or that Boohoo is no longer able to compete effectively then perhaps it is time to get out of Boohoo.
I'd like to see some comment on Boohoo here too. Or perhaps in a separate post if people object to it being in the SCVR.
Boohoo (LON:BOO)
“I'd like to see some comment on Boohoo here too. Or perhaps in a separate post if people object to it being in the SCVR.”
Agreed though there is a very good thread at:
https://www.stockopedia.com/co...
With some excellent bear case posts
Regards
Michael
MichaelFBS just to offer some additional thoughts regarding the above if useful at all and specifically related to ASOS (I hold), given the overlap in terms of business models and target demographic some will also apply to Boohoo.
In terms of the update from ASOS today, by and large I found it positive, not because of the impact from higher return rates or near term impacts to free cash flow generation, but because the key underlying numbers which I think are important to the long term destination of the business are all moving in the right direction.
Given the tough comparatives the company is facing from the covid driven boom of 2020/2021 for the business to have held on to those market gains from that period and to be accelerating in the key growth market of North America is really promising. Add to that 20%+ increase in premier subscribers in the period as well as increases in basket size and order frequency and the customer base appears to be becoming increasingly loyal and sticky.
The likelihood of those trends/flywheel continuing looks high given the companies relentless focus on sharing its scale advantages with its customers by lowering prices and improving the customer offer and experience (the business also benefits from other competitive advantages such as strong network effects given the brands it aggregates and the marketplace it runs). I see online fashion as a business with low barriers to entry but high barriers to success, given its 20+ year history I think ASOS has shown its ability to succeed and continue to succeed where others have failed (think misguided recently). I personally think a competitive advantage built on doing lots of little things better than others learnt over many years is a lot more durable and defensible than other moats.
over the past 10 years ASOS has achieved roughly a 16% return on incremental capital invested in the business, on retained earnings of over £700m+. The company has a large runway ahead of it (particularly in the US) with the ability deploy large amounts of additional capital at similar rates, so has the ability to compound investors capital at a very attractive rate IMO.
Regarding boohoo (I don't hold) what worried me most about their update was the decline in North America, my concern would be that given the time it would take them to get the US distribution centre set up, they would likely lose additional ground to players like SHEIN, ROMWE, ASOS etc.. and may find that their reputation for their customer proposition will be too dented by that point to take meaningful share from other major players.
ASOS (LON:ASC)
Hi Bully15
I completely agree with your positive sentiment.
I was speaking with a friend this morning and saying pretty much everything you have mentioned, especially on that excellent US growth.
If there was one unexpected negative, it was the change from net cash to net debt by the end of the year. That took me by surprise and I'm not sure I understand why the change is so drastic. Stock write-offs from Russia perhaps?
Nonetheless that's a huge fall today (-32% right now) and with a market cap of £800m, I must admit to being very tempted to buy back in.
A
Started buying in on lows, tranches of ETF's for Emerging Markets, FTSE All share, and S and P as long term holds (10 years plus.). Thinking of 6 tranches or so over 6 to 12 months, maybe longer depending where the market goes.
Am thinking that with 50-60% of my portfolio spread across the above ETF's and the rest I can use on UK small and mid caps.
Anyone else been thinking along the same lines?
I decided to sell up on the last peak (or as near as I could judge it) in the beginning of April. This included losses as well as gains, and left me pretty much breakeven after my first year investing (since June 2021). I held on to a few stocks that I thought would recover even though they are down at the moment. I forget who posted the thought the other day, but I agree with the sentiment that I would prefer my cash to be eroded by 10% per year than watch a 30% loss on any equities that I might buy.
I decided to buy when the FTSE falls below an RSI of 35 and sellout with a 5% trailing stop (even at a loss). Within the next year I can only see the market getting worse, but I certainly wont be able to spot the bottom (I think there are many wiser and experienced heads than mine on these forums), so can only follow the bumpy ride down !
After alot of reading / research on investing over the past year, I do not know if the 'buy and hold' paradigm is as inviolate as has been espoused. I think it is based on the belief that the main indices will slowly and surely average a gain. I dont know (inflation corrected) whether the FTSE falls into this category any more. Sure there are some companies that will do well because they are excellent, I am not sure that I am any better at spotting them than anyone else...
Without sounding hopefully like a total numpty anyone know why the FTSE 100 is down so much today US closed up last night off the back of the 0.75% hike.
I realize Thursdays are normally ex divi days and bank of England have put base rates up 0.25% but can't fathom why the FTSE is off nearly 2.5% was the market thinking B of E should have gone for 0.50% or higher or is it something else ?
I get we are in dire times but this seems a drop normally associated with something really bad being priced in on the day in question and I'm not seeing a dire bit of news for the UK today.
Any thoughts welcome.
I think we are in a market down turn with an occasional up.
I think the FTSE 100 has managed to outperform the global market because of its big oil and mining and defence stocks, but that seems to now be unwinding as the sell off and lack of confidence is effecting all stocks.
To many headwinds for now I would say and losses will continue...but know one knows.
(Deleted)
I’ve noticed that a broker downgrade can have an overly dramatic effect on FTSE 350 stock at the moment, almost panic.
But if you look at the S&P and Nasdaq futures for today, they're both down quite a bit.
So looks like there was a surge of BTFD activity yesterday in the USA, but the downward pressure is set to continue today.
The basic reason is that the UK is in a worse position than the US. In the US, there is hope for a soft landing. In the UK, the view is that the outcomes are bad either way. Not many are convinced by the current BoE stance and tiny rate rise. It doesn't solve the inflation problem. On the other hand, the BoE are talking about current negative growth, and should they raise rates aggressively, as in the US, the economy would probably tip in to recession. They're caught between a rock and a hard place.
The major fallers in the FTSE were retail banks. They accounted for a lot of the fall. A recession is very bad news for banks. But equally, if there is no recession, then it now looks as though the BoE will increase rates significantly. If they do, then this will still be dangerous for banks. That's because a lot of their customers will be paying a lot more on their mortgages and debts, which will increase defaults, particularly given the other pressures consumers are under. This damages the quality of the banks' assets. It's another rock and another hard place.
I think we are in a position of bad news and recession, a lot of which is now baked into some good stocks that have been hammered yet there is no support at all .
But right now it is pretty simple on AIM especially that there are literally no buyers so prices are just going lower and lower but ultimately with a positive head on that wreaks of opportunity.
Some great companies that arguably are recession proof starting to look very cheap, they says fortunes are made in bear markets so it is a question of finding the great companies and buying at great prices.
Look for those backed up by rock solid hard assets like good real estate and old fashioned cash and there looks to be some great deep value opportunities starting to unfold.
So unless you are fully invested now is the time to start doing some good research, rule out the dross , rule out the self serving management teams, rule out the high growth stories and find the bargains now on sale.
Nothing to turn the sentiment round right now but definitely the time to be doing the research for the shares that are going to overshoot on the downside that are heavily asset backed in good sectors with good long track records and in rising tide recession proof areas .
The B of E was very downbeat. Also interest rates of 1.25% are far too low , they have to be much higher to combat inflation. But of course interest rates of say 5% would hammer the economy and company earnings.
Don't know how many will have seen this: Hargreaves Lansdown and AJ Bell boost small investors’ access to floats but it looks like a step in the right direction for PIs
The turnaround continues to be move in the right direction having steadily moved into profit:
As has been much quoted about recently: “amateurs talk about tactics, but professionals study logistics” on which basis the current team (even whilst a CEO is still to be recruited) seem to be professional.
I personally think this could be a multi-bagger over a 3-5 year period if they continue to develop the various brands they have.
....just saw you already posted on this Graham which was helpful analysis. The one comment I would make is that they have more than toy railways when it comes to their brands (e.g. scalextric). Also I expect them to expand the range of toys they develop as they get the fly wheel moving. Phoenix own just under 75% and agree on the ethics (as well as rigour of analysis). To model properly I'd like to understand the tax credit better and factor in the employee profit.
Which share are you talking about - if you are quick you can update your post to show the ticker
It's Hornby (LON:HRN)
Thank you for the excellent comment and additional insights, Dogon!
Anybody got any ideas on the continued slide in Angle (LON:AGL) ? Today, another supportive RNS, yet it has lost all the gains after its FDA approval, and more. It is as though there has been institutional sized dumping, but no changes in disclosable holdings have been made.
My guess would be that initially people saw FDA as a momentous event and bought in. There were also people who knew that the really important issue is if you have coverage by Medicare and insurance companies. Setting these up and then getting physicians to start using the product will take years, which means more funding may be needed and/or you need to partner with a huge pharma as they have the salesforce required. My understanding is that £AGL haven't done this yet. Bottom line is you can have a great drug/device but you can be years away from reaping the cashflow which will stave off further dilutions via rights issues.
Funneymoney You are obviously fishing for a response 8-)
I’ve read numerous theories as to why the price has fallen – see post in latest Angle (LON:AGL) discussion thread. There will no doubt have been profit taking by short term holders after the FDA spike but my view is that the continuing fall is due to the overall market carnage. If, as expected, the Polaris trial is a success a new major income stream will start around Q2 next year.
Jim, Have they set up the relationships with payers and physicians already for this? No coverage, no cash (I don't know the answer to that BTW, just bitter experience of an FDA approval with no revenue). Fishing expedition corrected!
Funnymoney Angle (LON:AGL)
Afraid I don’t know either but we might find out more in the Q&A session following the AGM on 29 June. You could submit a question for the session in advance or even e-mail Andrew Holder at Angle (LON:AGL) investor relations for a more informed reply. With regard to Solaris, I (naively) assumed it would be a staged company to company payment at $1000 - $3000 per test as Angle (LON:AGL) will be running them in their own US lab even after a successful outcome - but I may be wrong. AN has referred to clinical reimbursement codes being a requirement for widespread deployment.
Hello JimMcLad, Funnymoney and Grumpy 5. Haha Angling Direct (LON:ANG), and although you rarely make a mistake Jim it is Solaris not Polaris. Shooting for the stars we are but via a different mechanism!!!
PS In the next day or so, I will be putting a substantial addition to the Discussion Board for Angle (LON:AGL) which adds to the strength of the £AGL proposition IMHO. However, I admit I was caught out by the market sustained selling response, and I guess if I had been canny, I would have sold at 150p when the FDA announcement was made and bought back in at today's price. Money in the bank to cover some of my more recent losses - or to add even more Angle (LON:AGL) shares of course!
i agree with these comments. Getting the regulatory approval is only half the story. Then comes the commercial risk which many companies fail to execute properly. Also, often the expectations of market opportunity size are overdone and the build up to profits can take many years and further capital expenditure. I think there was a comment to this effect by the Chief Executive which led to the share price slump.
So after the initial excitement reality sets in that the process to achieving the expectations on sales and market penetration will take longer than hoped for. Takeovers are often touted by holders of these breakthrough story stocks but they rarely happen.
Lots of examples on the stockmarket of companies failing to execute successfully or taking a long time to do so - STX (seems like a complete commercial flop), Renx, Polx and others.
The smart investors take their profits and/or original stakes out to leave the rest in for free because these biotech type stocks remain overvalued and high risk and there are no guarantees that they will succeed.
Halfords (LON:HFD) down heavily on reduced guidance for next year. Given the strong likelihood of a recession they obviously have to be prudent, but in reality they simply don't know at this stage what will happen to earnings (or the economy) so I really wouldn't read too much into this. Also, the shares are already down heavily this year so surely this should have already been priced in?
As of now, the business seems to be performing well, with a larger part of its income coming from services (higher margin, stickier and less cyclical). Tempted to take a position, although would be interested to hear the views of Paul or Graham.
Hi Bouden
I think that there are a number of moving parts here to work through.
Halfords (LON:HFD) have a good footprint and presence for what they do, cheap crinkly tin sheds selling various stuff.
I guess the key questions are, like the 2012 Olympics, Lockdown gave a massive bicycle boost, assumption has been for a while that this would not continue, and with the fall in available cash who is going to prioritise buying a new bike? Maybe for the kids? Yes service, maintain, replace the stuff that has worn out, but again can of oil, inner tube, just stop using the bike and let it rust in the garage. For those within the higher income bracket (assumed less impacted maybe?) they would typically go elsewhere for the large purchase, specialist shop, customised stuff, after sales and servicing (do I really want an 18 year old with general training taking my £20,000 bike to bits?). Yes I have three bikes, but together they were less than a 1/10th of that purchase, and one is >10 years old and one >25 years old. I use the local shop to service, knew the owners parents who ran it, and obviously his son who is going to probably take over. All three bikes bought local, two same brand and know the local shop trained to service that brand, so happy to pay for them to do every couple of years. Girls bikes I buy local, but it has depended on which of the two shops could get what I wanted, so researched online then bought local. They are great for adjusting the saddle, checking the breaks and all that and because we buy there, don't charge. I would not get the girls to cycle to the local Halfords as busy road, numpties and all that, we go in the car if we are going at all.
The car parts and servicing. This will continue, obviously your break light has gone you have to get a new one type thing, they are often local, convenient and quick. When I have used them in the past, drive up, get the part, it is fitted whilst you do a call or a couple of emails on the phone, drive out. Servicing again the local garage is used, know him, never does stuff unless needed, but good.
But again with the cost of living squeeze, are thinks like the bigger services going to be squeezed as people try to stretch the gap between them, yes meant to be 12,000 miles but the car is fine lets push to 15,000 miles, hence they will make money, but as much as previous?
Then add in can they pass on the price increases for labour, parts and all the rest to customers, as assume a large part of their base is price sensitive, so will call to ask a quote for a full service for me Ford CMax, and if they are £10 more than the Kwik Fit, you are going to the Kwik Fit.
So yes there is stuff to like, they will survive, they will continue, but is now the time to buy? With the hold I guess you are figuring what the future might be, can you sell and buy back cheaper in the next month, or do you sell and miss a big bounce (I am good at this part).
I guess the other one is are they in a position to consolidate, so increase footprint and dominance if others drop out the market?
Cheers
Tommy (ps. I do not currently hold Halfords (LON:HFD) )
Thanks Tommy, some things to think about there. I just think the drop today is a bit ridiculous - earnings are obviously going to be lower this year if we are going into a recession - I can't see why this would be a surprise to anyone. Furthermore, the SP is already down 50% so this should have been fully priced in. I think you perhaps give too much emphasis to cycling - motoring now makes up 70% of earnings and growing. No idea what will happen to SP in near term, but on around 5x earnings this has to be good value on a long term view.
Trading update from NWF (LON:NWF) (I hold):
The Group is pleased to report it has delivered a record year, in line with
its trading update issued on 10 May 2022, and a materially stronger
performance than had been expected at the beginning of the financial year.
These results demonstrate both the resilience of the Group and its ability to
deliver a good financial performance in volatile market conditions. Cash
generation has remained strong and the Group was cash positive at the
year-end, compared to reporting net debt last year.
What exactly is being said there? My, albeit limited, understanding, is that being cash(flow) positive is very different from the company being free of net debt. NWF’s debt has always put me off investing in the past.
ASOS (LON:ASC) and Boohoo (LON:BOO) both set to be pummelled again after missing analysts sales consensus - ASOS (LON:ASC) FY revenue growth now expected to be 4-7% vs 10-15% previous estimates, Boohoo (LON:BOO) Q1 sales of £446m vs £472m consensus. Most disappointing with Boohoo (LON:BOO) is that UK sales actually fell by 1% in Q1, with a big drop also see in the US. I continue to hold but it’s certainly a testing time to be a shareholder!
Also Halfords getting hammered. Marks & Spencer and Next also caught up, both down @ 5% . (Sorry the £ thing doesn't appear to be working).
Would be interesting to hear Paul's general view on the retail sector if he has time.
Phil
having lost £90,000 of my £200,000 that I invested in stocks since starting in nov 20 I bit the bullet and stopped holding everything which had included boohoo, saga and many other favourites here on this long and strong ethos. For the past six weeks I have been effectively day trading american stocks like Vertex energy, rivian and enphase where there are big swings but I am still ok if I get stuck in them long term. So far I have recovered £70,000 of that £90,000 loss. I know it is totally counter to the investing philosophy of most here but these seem unique times and I just could not take it any more.
i would strongly advice to steer clear from American stocks as many of them as still very overvalued. Rivian could fall a lot - it is heavily loss making. Enphase Energy offers very poor value in my opinion at the current valuation. Playing with USA stocks is like playing with fire - I experienced that firsthand. The concepts of greed and boom and bust are taken to a whole different level and it often ends in tears (except for executives of the companies who cash out!)
I agree with you Resource Man. My biggest losses have resulted in not selling when the charts were indicating I should sell.
I've added a few short term wins which have helped offset the general decline (buying the dips and then getting out with a profit). I also dodged a couple of bullets by selling when i was happy with the gain. It feels like trying to run up an escalator but at least I'm not just watching my portfolio shrink rapidly. I haven't made the gains like you but I am better off for trading.
Occasionally, I sell out, missing a further rise in share price but in the current climate that is rare. Most investors seem to be using SP rises to reduce losses resulting in a general downward trend.
It could be 3+ years before the US markets regain their highs. I also don't believe that discretionary retail will show growth for some time (as a sector). So anyone with a buy and hold philosophy needs to be happy with these time frames. It takes nerves of steel or a coffee can approach to resist adjusting a portfolio on yearly timescales. I have realised that I don't have this mindset.
Having said the above, there will be anomalies and some companies will defy the general trend.
I do have a few conviction holds such as Somero Enterprises (LON:SOM) and Indivior (LON:INDV) although the size on the holding does depend on the charts. I've recently increased my Somero Enterprises (LON:SOM) holding as I believe they are oversold. Indivior (LON:INDV) I sold on the last high and I am currently buying back on the recent dip.
Hi Revs8
”I agree with you Resource Man. My biggest losses have resulted in not selling when the charts were indicating I should sell.”
What do you use to determine that (and the opposite “I've recently increased my Somero Enterprises (LON:SOM) holding as I believe they are oversold.”)?
What resources (books/sites/courses) did you use to learn about this?
Thx,
Regards
Michael
If you try TradingView basic (free) very customisable charts and loads of chart tools to explore for the rest of your life - fibonnaci, MACD, Donchian, Ichimoko etc etc and subscriber developed ones.
Other than that Stock charts are very good if the SP is above the 50 dma then ok if drops below - warning Will Robinson. Look for where the SP historically bumped either the 200 dma or with markets as volatile as now the 100 dma.
Charts are followed by everyone around the world so your following the 'herd' - the trick is to be a contrarian.
Candlesticks are also great fun - Investopedia a good learning resource.
Influenced by Micheal Taylor unfortunately - let the Share Price tell the story, and let Stocko provide the risk management.
I think the US market is headed down. So shorting is the best policy if you must day trade. Overall i strongly suggest you don't do this!
I totally agree the US market is heading down but the thing is it will take the UK stocks down with it regardless of valuations. Shorting should be illegal in my opinion so definitely do not do that but that does not mean I do not use the knowledge of short deadline days on companies like Vertex energy to plan my day trades and so far that has been working well for me in conjunction with fed meeting days and all the other things American’s can be pretty much relied upon to panic about or swarm onto. I totally get the warnings do not misunderstand me but equally I know I would have lost half my invested money having continued as I was rather than be coming back to my original stake. Everyone must make their own decisions and do their own research I am not recommending that what has worked for me the past 6 weeks will continue to do so. I also recognise that following the US crash of another 20-30% if that happens and the impact that will have on UK stocks there will be every incentive to get back into these UK shares. I have just taken the decision to step away from them for the past six weeks and for a few more yet. I continue to follow the thoughts on them avidly.
I'm exploring spread betting on a very small losable basis. Learning going long but for some reason cannot read shorts. Things go down quicker than they go up, so should be easier. Maybe upending charts is the issue - is there a programme for that or just turn the screen upside down :)
Thank you Resource Man.
Interesting and very honest story. I did something similar in 2020 when I crystallised my losses and was 48% ish down YTD. I made it back to flat on the year by investing in and getting out of (luck) a lot of hyped stuff eg £NYCT. I would have been up 30% in 2020 if I had done absolutely nothing but you live and learn.
Today my portfolio is off 50% from its ATH sometime during the back end of last year. (The damage Boohoo (LON:BOO) Best Of The Best (LON:BOTB) mainly but also just general carnage in AIM. Games Workshop (LON:GAW) of 50% for example)
I can not make any comment on trading US Stocks but if I was in your position I would be happy where I have recovered to and read the BRK Buffett letters, the Buffett Partnership letters and listen to the recordings of the Annual Meetings on Spotify/Apple etc and go from there.
I have been “investing” (the quotes because I am not entirely sure that is what I have been doing) since 2012 and have, give or take the odd £1000, a big fat zero to show for it. If I had gone the safe root and given it all to someone who knows what he is doing (Warren Buffett) I would be up 238% or in the S&P500 255%.
I am absolutely not giving any advice here but just wanted to relate what I consider to be my errors. I think it takes incredible skill, hard work, time, focus and insight to make excess returns (over and above say Mr Buffett or the S&P) in UK small caps over any time period. There are currently five shares on the LSE with a 15% CAGR over 15 years.
I am currently pivoting over the next 24 months so that half my portfolio is in BRK, £VUAG and six large tech stocks.
Regards
Michael
Surprised here Michael, I consider you one of the wiser people on here and always look out for your wisdom so surprised you are down so much.
I am down around 20% this year after being up 25% last year so pretty much getting back to where I was. I have added some money this year but have quite a bit waiting to be deployed (excess income as I still work and some bonds due to be mature this year.)
I have found has you have that the overall markets have maybe done better than I over some of the years and so any additional money I put in are now going into tracker funds. I enjoy investing and will continue too, but I don't want to have any additional money sitting in individual stocks.
What's comforting is that this isn't us , the whole market is down but it'll recover.
Brookeda Well that is underserved compliment but thank you.
I have read a lot and sort of know what I should have done but it has been a tough 2 1/2 years which has made me question my suitability for investing. I am envious of people just starting out as this bear will mean they learn a lesson early. From 2012 to 2020 I thought I was a genius.
Just to clarify my figures. I was flat 2020 (but it hurt mentally that if I had nothing I would have been up 30% [I think it was closer to 35%]). Last year I was down 15.3% and this year 26.5% YTD but from ATH somewhere around -50%.
I have been hit by Boo which I have held since Oct 2015 (apart from sell in March 2020, which I started re-purchasing in July 2020). It was at one point something like 13/15% of the portfolio. (Hubris) Best Of The Best (LON:BOTB) and others.
My holdings are below, which as you can see is very AIM centric the US stuff are recent purchases.
I could probably write a small book on the past three years, maybe I should, but hope that gives you a flavour of where I have been.
I certainly agree when you say “have found has you have that the overall markets have maybe done better than I over some of the years and so any additional money I put in are now going into tracker funds. I enjoy investing and will continue too, but I don't want to have any additional money sitting in individual stocks”
I down but not out but yes I have a long back to make. Fortunately I am not 100% invested in the stock market as I have a couple of income generating properties but these are trying times.
Regards
Michael
PS The TSLA holding is just for a bit of a laugh and to be along for the ride. I won’t be buying any more!
Boohoo (LON:BOO)
danjamesbaker
"ASOS (LON:ASC) and Boohoo (LON:BOO) both set to be pummelled again after missing analysts sales consensus" - Q1 sales of £446m vs £472m consensus.
Per boohoo today they said
-- As expected, gross demand growth remained positive against tough comparatives, +9% year-on-year, with net sales impacted by the ongoing normalisation of returns due to product mix change
The Group's outlook for the year ending 28 February 2023 remains unchanged.
To me its mildly positive that the full year outlook has not worsened today , ref the 446 v 472 consensus you quote Dan where did you get these numbers from ? - if sales had missed expectations today by that much i would not expect them to say that outlook remains unchanged and that demand was as expected (in a sketchy sort of way must admit).
P.S. Boohoo (LON:BOO) getting very close to that £700m threshold for this report ;-)
BOO is actually in line, but the market isn't interested! Q1 (Mar-May '22) is the last period where the prior year benefited from the pandemic (physical stores of competition were closed). It was flagged in the last trading update that Q1 would be soft, due to those tough comps, then the figures would improve from Q2. So all as expected, but the market treats it as a bombshell. It's crazy at the moment.
The Fed seems to be on a mission to plunge us all into a recession. How long before they have to backtrack, like they did last time?
It's just a nightmare at the moment, isn't it?
Regards, Paul.
Or an opportunity - depends on your outlook. Mine is at least 10 years. I like the quote, don't think about buying anything for 10 minutes unless you're willing to hold it for 10 years. The focus on what is happening, the short term over rides almost all thinking of what the long term picture will be. The short term picture is all doom and gloom but as with everything, it will pass and history has told us time and again, we will be better off in the long term. When is that? God knows, we guess. Good valuation work is met eventually by the market, but no-one can tell you when, although plenty are willing to give their opinion. My opinion is that we could be in for 2 to 10 years of very poor returns in the market, but as I don't know, I keep buying when my valuation of the companies I like is less than what the market is pricing them currently. This means I buy every pay day, when I can and could be doing so for the next 2 to 10 years. I hope it's not 10 btw, but I will have accumulated a lot of shares in very good companies over time and while I earn excess income, this will always be my focus. I know I cannot time the market, and I believe there are others who think they can - but repeating that feat is historically impossible except for the very few or the very lucky. I am not one of those.
Mark B
I do agree and I try to look very long term but I also remember that it took 25+ years for markets to get back to their highs from their 1932 low.
On a positive note, I'll be 78 then - if I am still in the land of the living. Investing is definitely not for the pessimists, that's just too hard by it's very nature. One day the world will definitely end. I just hope, not too optimistically, that it's not on my watch. If you have a clear business plan, follow it and take the bumps in the road with the suspension you made as you prepared for both good and bad. I have no idea what the near term future will bring, but the past is a very positive indicator that some time in the future, near or far, things will be better.
It didn't .... it took 4.5 years. Everyone forgets about the epic dividends.
The Fed seems to be on a mission to plunge us all into a recession. How long before they have to backtrack, like they did last time?
Unfortunately I believe the FED (and other central banks) are in the process of doing the monetary equivalent of a pilot induced oscillation (where pilots over-react to changes in pitch, resulting in larger and larger oscillations). There is a danger that they now over tighten too late and take us all into recession. At which point they might panic and reverse the monetary tightening resulting in a stock market surge (but not necessarily a sustainable one). After which who knows????
Thanks for your views on Boohoo (LON:BOO) , I do enjoy reading your comments Paul.
As I type Boohoo (LON:BOO) is valued at £710m so still just out of scope for the SCVR! Let's hope this is the low point and it never reaches that level. (No position but like to keep an eye on it)
“It's just a nightmare at the moment, isn't it?”
YES.
On the Fed, way above my pay grade but there was talk on Twitter before the hike that a .75% increase would be good for the market because it meant the Fed was 1. Intent on controlling inflation, 2. Getting ahead of the curve.
As for recession, pretty certain already in it with or without the Fed/BOE action though London didn’t look like it yesterday.
The job figures are confounding because UK unemployment is 3.8% AND vacancies stand at 1.8 million.
And at some point I believe we have to get back to “normal” interest rates. The mistake, again I am no expert but I believe, was the Fed not holding its nerve and backing off from raising rates every time the market swooned. But that, to quote Jeremy Irons, “Is spilt milk under the bridge”.
The fact that the central banks didn’t see that having endless QE, trillions of Covid support thrown into a semi shut down world economy, supply chain issues due to Covid and a chip shortage would lead to inflation means that they were derelict in their duty.
Sorry if I am being controversial, but they have really f… a lot of peoples lives up here.
Regards
Michael
I think a schoolboy could have told them that if you print that amount of money you will get high inflation, but the governor of the Bank of England recently refused to acknowledge that connection.
macro economics are extremely hard. Everyone has a rear view mirror. Are you able to do a better job. It's very hard.