Small Cap Value Report (Thu 16 Mar 2017) - TFW, SAA, SEE, SOM

Good morning!
Many thanks to Graham for really excellent & insightful reports this week.
Today I'll be covering results from;
FW Thorpe (LON:TFW)
M&C Saatchi (LON:SAA)
Seeing Machines (LON:SEE)
Also, I'm hoping to catch up on a few other things from earlier this week.
FW Thorpe (LON:TFW)
Share price: 323p (pre market open)
No. shares: 115.7m
Market cap: £373.7m
Interim results - for the 6 months to 31 Dec 2016.
This is a group of lighting companies. It's essentially a family controlled company, with a stock market listing. There's nothing wrong with that, indeed some investors (such as Lord Lee, and David Stredder) seek out such companies - appreciating their long-term thinking, and prudence.
The headline figures for H1 certainly look good;
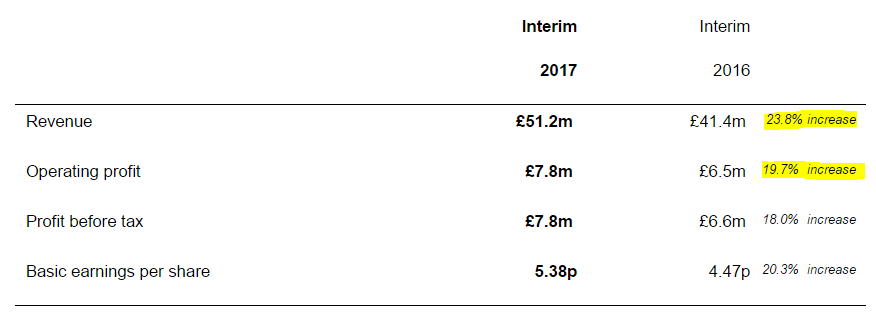
Note that when profit rises by a smaller percentage than revenue, that's a quick way of noting that the profit margin has reduced. Dividing operating profit into revenue confirms this - the operating margin was 15.7% last year in H1, and has dropped a little to 15.2% this year in H1.
The narrative explains that this is due to overtime payments;
Whilst normally expecting a higher level of profit attainment on raised revenues the exceptionally buoyant first half at our largest entity, Thorlux Lighting, had to be met by the imposition of high levels of overtime, shift working etc. which inevitably has led to a higher cost of production than we would have liked.
These actions were necessary to satisfy spikes in customer demand but it is unlikely that the need for such levels of activity will persist.
Any problems caused by buoyant customer demand, are quite nice problems to have, in my view. Although the last sentence seems to be suggesting lower customer demand in future, which is a concern.
Thorlux is by the most profitable part of the group, as you can see from the segmental analysis in note 2 of today's interim results. It made £5.9m of the £7.8m total operating profit.
Seasonality - looking back as last year's numbers, H2 seems to be a good bit stronger than H1. If the same sort of pattern plays out this year, then it looks as if the company might deliver perhaps 12-14p EPS.
I can't find any broker research on the company at the moment, but have put in a request to my broker, so will update this later if anything comes through.
Outlook - "satisfactory overall result for the year" is the same wording that was used at the AGM update in Nov 2016, and is used again today;
We remain optimistic of a satisfactory overall result for the year.
This company seems to be open & honest in its trading updates & results narrative - giving both positive and negative points, making them a pleasure to read. It's good to know that management can relied on, and are not trying to hide areas of under-performance, unlike many other companies.
Balance sheet - wonderful, as always.
This includes net cash of £35.8m. The overall working capital position is a surplus of £56.7m (i.e. current assets, minus current liabilities). That's a current ratio of 4.25 (where anything over about 1.5 is strong!)
Why does this matter? Well, it means the company won't be going bust. Also, it means there is cash ready & waiting to buy up any suitable acquisitions - which would boost earnings of course. Therefore this balance sheet strength should be factored into how we value the company.
Valuation - tricky, as whilst I like this company very much, it's become very expensive on a PER basis (which is the sensible way to value a fairly mature company like this).
Even if we're optimistic, and assume it might deliver 14p for the full year to 6/2017, then at 323p share price, the PER is just over 23 times.
If we take off say 10% of the market cap to allow for the surplus cash, then that would bring the PER down to 20.8 times - which looks a full valuation.
My opinion - I very much like the company, and acknowledge that it is trading well, and delivering decent growth. However, that very much looks already baked into the valuation - so where is the upside going to come from? Also, what happens if growth slows in H2? I think you'd need to be very confident about the future, to be willing to pay the current price, or to continue holding. That said, the company's done well in the past, so it may well continue to do so.
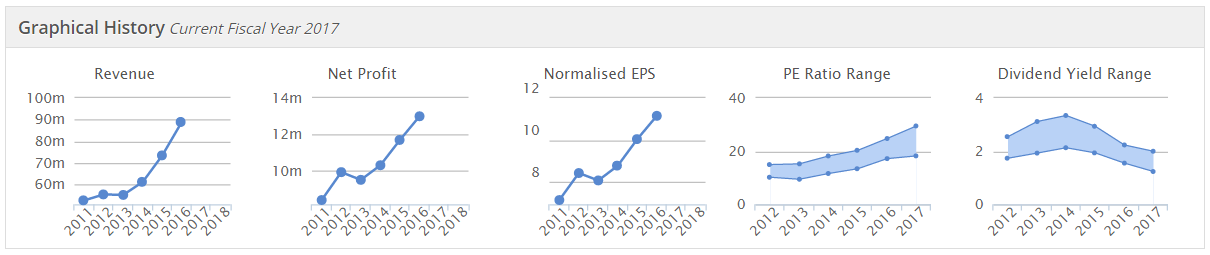
The Stockopedia historical graphs neatly encapsulate the situation (see below). So excellent growth in revenue & profit has driven an increasingly high PER.
M&C Saatchi (LON:SAA)
Share price: 353p (unchanged today)
No. shares: 75.7m
Market cap: £267.2m
Final results - for the year ended 31 Dec 2016.
You always have to be so careful when looking at the accounts of PR companies. After all, embellishing the truth (to put it politely) is their business, and I find that usually carries through into their accounting too!
The headline figures here look excellent, e.g. operating profit up 24% to £23.0m.
However, the statutory figures don't look anything like the highlighted figures, e.g. profit before tax is shown on the face of the P&L as being down 46% to £6.8m.
Note 3 is the key place to look. This gives a reconciliation between statutory, and adjusted profit. The table is too big to copy here, but it contains 6 categories of adjustments. The one I have the biggest problem with, is a column called "Put option accounting". This is by far the biggest adjustment, adding £8.6m profit. It has an asterisk next to it, which says;
These values represent share based payment charges (£7,997k) and fair value adjustments to minority put option liabilities (£597k), the non-controlling interest charge is the additional charge had the put option not been accounted for under IFRS2 conditional share awards.
To my mind, if £8.0m is share based payment charges, and £0.6m is put option costs, then surely the column heading should be called "Share based payment charges", and not "Put option accounting"?
My view is that, in a people business like this, share based payments are just part of employee/Director remuneration. So to adjust out those costs, and pretend they don't exist, seems to me to overstate the real level of profits. I suppose these payments might be earn-outs for acquisitions? It's all far too convoluted for my liking anyway.
My general feeling is that the more adjustments there are to accounts, then the higher the risk that we're having the wool pulled over our eyes.
Balance sheet - this looks very odd to me. There are some hefty liabilities called "minority shareholder put option liabilities", which add up to £33.2m. Plus another item called "other financial liabilities" which adds up to about £32m (2 figures need to be added together).
Overall, the balance sheet is negative, when you get rid of intangibles. The working capital position isn't great either. That's not necessarily a problem, if the timing of money flowing in is more favourable than money out, but it's still worth noting.
Outlook - hardly surprising that a PR company sounds upbeat, but for what it's worth, it does;
2016 was an outstanding year for M&C Saatchi. We continue to roll out our proven strategy of winning new business and starting new businesses and see positive momentum across our global network and business channels. The year has started well and we are confident that we will continue to make good progress in 2017 and beyond.
My opinion - I don't like these accounts at all. There are too many adjustments, and the share based payment charge that is buried in the notes looks very large.
Shareholders get a dividend yield of 2.3% based on the 2016 payout.
On a positive note, the top line growth looks good, with significant growth being reported in some territories.
For me personally, if I don't trust the accounts, then I don't buy the shares. This one fits into that category for me.
Seeing Machines (LON:SEE)
Share price: 3.7p (down 9.7% today)
No. shares: 1,486.5m
Market cap: £55.0m
Half year results - 6 months to 31 Dec 2016.
There's no getting away from the fact that these figures look grim. The company reports in Aussie dollars, a few key numbers for H1;
Revenue A$3.6m (prior year comparative of A$29.3m was a one-off, due to sale of rights to Caterpillar)
Loss before tax of A$14.1m (this is just for 6 months, remember)
Net cash of A$11.6m looks alarmingly low, however the company has raised more cash since the 31 Dec 2016 interim period end.
Fundraising - of about £16.4m was done in Jan 2017, which is about A$26.1m, less a chunk for costs.
If the company continues to rack up such big losses, then it's likely to deplete the enlarged cash pile fairly rapidly. There looks to be enough fuel in the tank for 2017 and into 2018 anyway.
Revenues from the fleet sector look to be disappointingly low, and slow to materialise.
My opinion - the fleet and automotive sectors look promising, e.g. 60 trials underway with haulage companies. There's no doubt the product works too - as it's tried & tested in the mining sector.
Therefore, owning this share is a leap of faith, hoping that the company will generate enough sales momentum in future to justify the current valuation. If sales really start to take off, then I imagine bullish forecasts are likely to excite investors, and see the valuation potentially roar upwards.
If sales remain in the doldrums, and cash burn continues at the present rather alarming rate, then yet another fundraising in 2018 would be on the cards.
I don't have a crystal ball, so have no idea how things will pan out. Personally, I don't really touch stuff like this any more (because shares like this usually generate losses). There needs to be a viable business model in place already for me to be interested. So with this company, I'd rather pay more, once the business model is proven, than jump in now whilst it's unproven, and shoulder the risk of it all falling flat.
Somero Enterprises Inc (LON:SOM)
Share price: 281.7p
No. shares: 56.2m
Market cap: £158.3m
(At the time of writing, I hold a long position in this share)
Final results - for the year ended 31 Dec 2016.
Graham has already reported on these excellent results, yesterday, here. So I'm just giving a second opinion. Somero is the world leader in laser-guided concrete laying equipment. It claims to have no serious competition at all, other than men with spades & pieces of wood. Whilst that may sound far-fetched, it does seem to hold water. As the company points out, anyone laying a concrete floor really only has one chance to get it right. If anything does go wrong, there's only a window of 1 hour to fix it, before the concrete sets. Hence why Somero has focused so strongly on top notch service, multilingual telephone support, etc.
Most of its activity & profit comes from the main USA market. Corporate taxes are currently high there, but if President Trump gets his way, then Somero shareholders may receive a boost. Also his plans to spend more on infrastructure augur well for this company.
The company's commentary sounds upbeat, and historically I feel that management very much fall into the trustworthy category - so the commentary can be taken at face value.
Net income (after tax) of $14.3m is up 23.4% on the prior year, an excellent result, and all organic growth. That compares with a market cap (measured in US dollars) of $196.3m, so a PER of 13.7.
Adjusted net income is higher, at $15.6m, which gives a PER of 12.6. So it's up to each investor to decide which figure you're more comfortable with. Both look good value, given that the company is performing so well.
Balance sheet - believe me, this is a fantastic balance sheet. I know about balance sheets, and this is a terrific balance sheet. Sorry, I was just channelling President Trump there, day-dreaming about whether there is scope for Somero to help build the foundations for his wall.
Being serious though, current assets are $38.7m (including $21.2m of cash), and total liabilities are only $9.5m. So that's an unassailable financial position.
Dividends - up a whopping 61% on prior year, for a total payout of 11.1 US cents (just under 9p per share). I make that a dividend yield of 3.2%.
The company has previously said that it intends paying out excess cash, so I hope there may be more decent divis to come. The possibility of a special divi is mentioned in the narrative;
The Board plans to review the Company's cash position alongside cash requirements for current business needs and future investment during the first half of 2017. The Board will then assess the level of excess cash that may be subject to distribution back to shareholders through a special dividend later in 2017.
My opinion - the key issue here is cyclicality. The market hasn't forgotten how performance fell off a cliff, and the company almost went bust back in 2008.
I doubt that scenario is likely to happen again, because Somero has a much stronger balance sheet now. Back then it was saddled with debt, now it is swimming in net cash.
No doubt the world will have another recession, but do you really see that happening any time soon? The opposite seems to actually be the case - with US & European economies improving. Plus Somero is a big potential beneficiary from Trump's policies, if they are enacted as he intends.
Therefore, I can't see any reason at all to sell my shares in Somero. It's cheap, has loads of cash, and importantly I think its markets will be much bigger this cycle than in previous cycles. The requirement for perfectly flat floors in warehouses is now much more important than in the past, due to eCommerce, and multi-level racking - where a slightly wonky floor could lead to instability, or collapse of racking systems, which are often more automated now.
So it looks to me like perfect market conditions for Somero, hence more to come, I suspect.
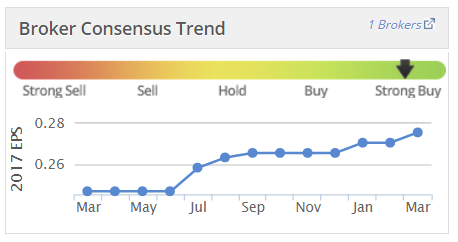
Stockopedia likes it too, with a StockRank of 98.
Note how the established trend is for brokers to push guidance up as the year goes on;
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

47 comments
Hi Paul,
I am a holder of Somero Enterprises Inc (LON:SOM) and have been very pleased with their performance, another excellent set of results you highlight above. Is there a reason that since these results you have sold out of Somero Enterprises Inc (LON:SOM) in "Beam me up Scotty"? I know it is not your personal portfolio but have there been further developments I have missed?
Thanks,
Peter
Talking to the old dears in my Mum's block, the only online estate agents they have heard of is PurpleBricks.
Someone sold a flat through them, and they've all heard.
This model is broken. You can now pay £1k and get the job done. Normal estate agents are finished.
Paul, loving the Donald Trump channelling!!
Thanks for the additional comments on Somero Enterprises Inc (LON:SOM) Paul. Do you think they are a potential takeover target this year?
Paul, now that you are back in the land of the living (!) how about a comment on FCCN? Graham wrote a rather cautious piece on their results, and the last we heard I do believe you were long of them. Clearly Marks has yet to change his spots, and probably never will, but do you think they are still worth holding?
Hi grumpy,
You already know my view on French Connection (LON:FCCN) - it's been the same for about the last 5 years!
Loss-making retail division, with leases slowly expiring.
That should leave a profitable wholesale & licensing business.
Although as Graham says, how much of the overheads are mixed?
It has cash, it's not going bust, the brand is valuable, so I like it (still holding)
That brand is very valuable. I think it could exit at a big multiple, but have been saying that for years.
It's a valuable brand. I see value here.
Regards, Paul.
Hi Paul, I'm interested by your comment that you would ask your broker to show you any research notes that have been put out on TFW. Up until about a year ago my broker could usually get hold of broker research notes on stocks that I was interested in, which he would forward on to me. However,he now says that the FSA have banned them from passing on broker research notes to clients and that he can get into trouble if he does so.
I am interested to know how your broker is able to pass you on research when mine says he will get into deep doodoo if he does ?
Cheers,Graham.
Hi Graham,
Just to chime in on this. Key voices in the market, like Paul, will get access to research because corporates want to make sure all key facts are at their disposal.
Also the brokers shouldn't really be doing this but historically it's been something they've offered to key clients. The reason is that broker research is written with disclaimers confirming it is only for "professional investors" and therefore it should only be viewable by clients who have been classified by the distributor as professional investors.
For most of us, it's a ridiculous requirement and another example of dogmatic regulation written by someone who doesn't understand markets. All it achieves is to deny access to proper analysis for the very investors that often make up the day-to-day liquidity in a share.
Unfortunately, it will become increasingly difficult to get access to broker notes as MiFID II is only 9 months away now and many Brokers are drastically reducing the list of who they send their research to. Cue shameless plug, but this is something we offer at Research Tree.
Cheers
R
Hi Rob,
Do you not have a list of requirements to prove you are a 'sophisticated investor' before you accept an application? I failed because I'm not a city worker or frequent trader, despite the fact that I consider myself to be reasonably well educated on the risks involved in equity investing, and the possible bias within research.
Other than that I applaud your attempt to bring research to the masses, and enjoy the naked fund manager's articles.
FWIW my opinion on Somero Enterprises Inc (LON:SOM) was positive. In fact I topped up. I was late to the party because they just looked too cheap - I thought something must be wrong with them! I only started buying at 255p at which point they still look cheap but I missed some great gains while on the sidelines.
Falling revenue in some parts of the world is a slight concern, but it's going well in the parts which make the bulk of the sales. For a company with net cash and growth they still look cheap - unless the global recession starts next week. Even then they have the buffers of cash at hand and high margins.
Thanks Doug,
Yes we do have regulatory steps we need to take in order to remain compliant. I was just having a grumble at how these regulations serve no practical purpose and actually makes things worse.
Cheers
R
As far as I can remember from reading the SOM results, the falling area revenues seemed to generally be in their smaller geographical reaches... and in many they optimistically seem to claim the pipeline is positive. The only tiny challenge I would say in their commentary is that can a 13% increase in revenue be described as "exceptional"? All the other metrics look good, especially the cash position.
This share is an example of my new investing strategy - I buy where a company looks good value and appears to be doing well, and then I buy more on further positive news... kind of a reverse to the falling dagger scenario. So far it is serving me pretty well...
The comments are even more valuable than the analysis...
Thanks
Hi Paul
I would also like to hear your thoughts on G4M's results as the slow down in growth over the last 2 TU's seemed to have spooked the market a little but they have since rallied strongly, being the mug that I am I sold close to the bottom.
Hi Paul,
Any thoughts on Purplebricks (LON:PURP) directors selling so many shares?
Hi herbie,
I'm a holder of PURP. The announcement yesterday certainly gave me pause as I never like to see Director sales after a big share rise.
A terrible example was Xcite Energy a number of years ago where Management sold significantly at the top shortly before announcing their oil discovery would take far far longer than market expectations to develop. As it happens, I doubt that field will ever be developed...
For PURP, the CEO reduced his stake from 15.3% to 13.9%, ie a 1.35% sale for a cool £11m. The CFO halved his stake taking about £3m out and then there were other smaller, less important share sales.
I know the recent £50m placing was very oversubscribed so I can image there may have been institutional demand for additional stock from those that didn't get the allocations they would have wanted.
Also given the shares have roughly doubled over the last year, the CFO may see this as a type of top-slicing whereby he takes £3m out but still has roughly the same level of "investment" remaining.
The key man, Michael Bruce, still holds 14% of the business and I expect could have easily sold more if he was trying to crystallise value ahead of bad news. Also, the institutions buying his stake would have been laser-focussed on the exact reasons for the share sale, and the upcoming outlook before agreeing to be the counterparty to the transaction, so I'm inclined to believe this isn't a red flag. Hope I'm not wrong.
Hi RMundy, thanks for that reply. Purplebricks (LON:PURP) is not a share I have ever held. I used to sell on large directors sales but a few recently have done well after sales, 2 I had were dotDigital (LON:DOTD) and accesso Technology (LON:ACSO) both have increased by about 60%. Although Solid State (LON:SOLI) did fall dramatically after director sales. So I find it difficult to judge.
I was expecting Purplebricks (LON:PURP) to have fallen today but are actually up. So you are probably right.
I agree with Rob.
To my mind, the Instis are going crazy for Purplebricks (LON:PURP) right now.
It's one of those stocks that looks unique, and I am v excited about.
Having said that, the Directors are selling, so I followed them today, and sold about 1/6th of my tiny personal holding - not that it matters.
Personally I'm also short of Foxtons & Countrywide, as their business models look totally bust.
Hence why PURP has a £800m mkt cap. It's nuts, but I wouldn't be surprised to see a zero on the end of it, if they crack a few states in US.
I googled all PURP's UK competitors, and they're the market leader. WAY ahead of the competition. Also doing Australia. Now trying USA - very ambitious, but the prize is massive. That's why the mkt cap is £800m. It's bonkers. We're in a bull market. Not difficult to see it being £8bn,
Just saying. I don't make the rules.
Regards, Paul.
Actually, looking at Countrywide (LON:CWD) - it has a really bad balance sheet.
Wish I had shorted it much more heavily.
I read the whole Annual Report for CWD, and concluded that these are old school, deluded people. If you think about their network of shops, long leases, and tons of debt, I could really see these deluded fools going bust!
Estate Agents are just shop windows. But we all look on Rightmove. I think they're likely to turn into coffee shops! Thousands of small shops need to close. That's a big problem.
How much coffee do we need? Your coffee has to be BETTER than usual.
Estate Agents are useless - actually you do nothing! Just introduce me to the seller, then we can do everything. I don't want persuasian, I'm more likely to pull out, if you persuade me. Actually, I'm looking at PurpleBricks property now, and I ignore their phone calls - they're irrelevant. They're amateur people asking me to take a survey, forget it!
Anyway, that's my view.
Cheese, PP,
Re: (LON:PURP) Purplebricks
Hi, Paul and Herbie,
Paul, I really like your late night/early morning contributions. They are direct and unequivocal.
I don’t disagree about the direction estate agency is moving. The writing is on the wall. I remember wondering why both Martinco and Foxtons listed in late 2013. The answer that I couldn’t see then is clear now.
My observation is only that Purplebricks (c. 60% of the online agency in this country) has a lot of competition.
A Google search of ‘sell house uk’ brought up these results: the first is Housesimple, then the competitors in order on the first page are sellmyhome, Purplebricks, and emoov. On page two, the relevant entries are Housesimple again (with price of £595 prominently displayed…PURP’s comparable price is £895 or £1119 in London), housenetwork, Tepilo and hatched (£495).
There seems to be a lot of competition. Almost all of it is better value from the consumer’s perspective.
http://hoa.org.uk/advice/guides-for-homeowners/i-am-selling/how-do-i-lower-my-estate-agent-fees-use-online-agents/ is a comparison site that ranks UK competitors by Trustpilot (PURP is ranked 6th, but with a very high score), by price achieved (ranked 2nd) and by price (ranked last).
Undoubtedly there is money to be made, and I assume that Purplebricks will make some of it, in this country and elsewhere, but if people search for houses to buy/rent on Rightmove/Zoopla/Mouseprice/etc. or the local equivalent, does it matter which company is acting as agent? Can one online estate agency corner the market? Is there something that makes Purplebricks different from its competitors that can’t be copied? I’m looking for the unique selling point. TV advertising spend will work for a while, as folk hear about the concept for the first time. (I’ve seen Housesimple’s TV ads, but I haven’t seen Purplebricks’.) How far down will Purplebricks' prices need to go to attract those that will simply go for the least expensive option with good reviews that does what is necessary?
Disclosure- long SVS
Hi Laurie, I think it does matter who you have acting for you, I take your point about being on Rightmove but if you read some of the negative reviews you can see what can go wrong, one said incorrect price so he had no viewings until near the 6 months deadline and the buyer was interested but then the contact was up and the sale was lost, another said he lost a buyer because the agent would not contact the buyer, others say impossible to contact the agents, another had wrong address or phone numbers etc.
I see one of those only charges £100. Not sure how they can make a profit from that.
I think Purplebricks (LON:PURP) will get customers from advertising and word of mouth, as their market share grows it could snowball. If Purp can break into the US market then the shares could really take off.
When you say you "sold 1/6th of your tiny holding" in PURP, I'm figuring your definition of "tiny" is rather different to some of your readers....
Greetings, Herbie,
Re: Purplebricks (LON:PURP)
https://www.settled.co.uk/blog/tepilo-review-vs-settled?gclid=CJzcuq_d29ICFYU4GwodshYIcw is a link that compares two UK competitors of Purplebricks. Both have a less expensive (in London) offering that places adds on Rightmove, Zoopla, etc. One has a higher Trustpilot score than Purplebricks. If I was selling a standard-ish house, I wouldn't start with Purplebricks. There are other competitors, too. Purplebricks will find that their margins are under pressure and that they are unlikely to control as much of the market as their share price implies.
It doesn't look to me like the size of the individual disruptors (Purplebricks/emoov/Settled/Tepilo/housesimple/etc.) is relevant, because they all place listings on the same sites (e.g. Rightmove).
I sold a non-standard house a few years ago. I felt that I needed an estate agent to deal with what could have been a tricky negotiation (it was). I found that I was able to negotiate a fee that was acceptable to me, and that was considerably lower than I expected.
I feel that there is still a place for the traditional agent, especially at the unusual, difficult or high end of the market, or for those who shouldn't be trying to sell their own house for whatever reason, but margins and volume are under increasing pressure.
disclosure- I hold a tiny amount (<1% of portfolio) of SVS
Hello Laurie, Glad your house sale went through ok. To be honest I don't think I have heard of Settled or Tepilo before. Had a quick look on Rightmove and can't see anything in my area, Purplebricks has quite a few. I agree that there is still a place for the traditional agent, especially at the higher end, it's the lower to mid range that is their market, it's agents such as Countrywide and maybe Foxtons that seem to be suffering. I slightly disagree about size, I know of Purplebricks not only because of reports on here but every time I switch on ITV they on on the adverts, if you don't have size I doubt you could afford TV advertising. I did read a report a while ago and all the tradional agent were suffering apart from Savills (LON:SVS). I don't hold any shares in any estate agents and never have done. I was tempted by Purplebricks (LON:PURP) but was not sure about them so never pushed the buy button.
Paul - I'm certain it's on your list, but I'd welcome your views on Somero, as I know you're a long time follower.
Hi Paul
I would be interested in whether you have any comments on GYM Group and whether you have revised your opinion in light of their recent results?
Graham's comments are interesting (positive) and he recently bought in.
Morning all,
I'm afraid that Seeing Machine no longer have a niche product - it's a diminishing retro-fit market. Fully integrated automated safety systems - from the likes of Bosch and Delphi are becoming the norm. As heavy plant / trucks are replaced they will contain many more safety features as standard.
MandarinMart
You do realise that SEE actually work with Bosch and other auto suppliers on their own "fully integrated automated safety systems" as well as the auto OEM'S directly? They've also been involved or are involved with Takata, Harman/Samsung, Panasonic, GM, BMW, Jaguar...According to one Youtube video, an interview the CEO gave with Zak Mir they are gearing up in their auto spinoff Fovio to supply a million units a year.
I do agree with Paul though, this all early stage stuff and the cash burn while waiting for things to come good can be the thorn in the side of smaller companies like SEE.
I have owned SEE previously but got out on basis that self driving cars are on their way and therefore this technology seems to be no longer required.
Accept that no country in the world has the transport infrastructure in place to totally support self driving cars. If you think that isn't true then I suggest you volunteer to take a driverless car on to some of the roads across the world often seen in videos like the worlds most dangerous roads. A supply of clean underpants will be needed although I doubt the driverless car would get very far. Both Governments and auto OEMS are well aware of the need for safety and for the driver to be able to take back control of the car. The eye tracking technology provided by the likes of SEE, Smarteye and Tobii seems to be the technology the auto OEM's have chosen to provide in cars, both driver and driverless, to ensure that the "drivers" of cars are paying attention, not distracted or falling asleep. The totally driverless car future probably won't be seen in the lifetime of anyone here, just as 40-50 years ago all the talk of a leisure society with us all working 10 hours a week (if that), driving to work in flying cars by now was drivel as well.
SevenPillars I accept that the infrastructure isn't there at the moment but it seems generally accepted that driverless cars will be with us much sooner than you suggest. Whether SEE is the tool they use in their cars has to be seen. But hey this is investment, the only right investor is the guy who ends up holding the money.
Oh, driverless cars are clearly coming, I just don't think a totally driverless future will happen in our lifetimes and given that the market for new cars around the world is getting towards 100million a year, cars that need drivers and safety systems will be around for a long time to come. Some parts of the world may never have the infrastructure to support driverless cars yet will still need millions of new cars every year. Any research on the safety aspect of cars in the future will show that eye tracking tech is a major part of the connected car to come for many OEM's whether in driver or driverless cars. The information is out there.
Well great SevenPillars if I held your views I would fill my boots with SEE. Good luck.
Btw for disclosure I hold Cloudcall and have done for some time. Andrew
Hi Paul, just seen the very encouraging news on Cloudcall that Blackrock have built a stake just over 3%. I may be wrong but I don't think they get involved in microcap stocks very often any more so that looks very promising and should the Company need a slight further fundraise that bodes well for getting it away without a discount.
Regards
Andrew
I see Avation (LON:AVAP) have opted to sell six of their ATR aircraft for net $31m proceeds rather than accept offers for the whole fleet of 22.
The share price dipped but seems to have come back a bit to be 3% down as I write.
I'm pleased with the decision, but I guess the market is disappointed there will be no special dividend.
The issue was that Avation didn't have any better way to quickly deploy the money if they sold the full 22 aircraft. There is a lot of money coming in to the aircraft leasing market looking for a return of some sort - a bit like the insurance market. Perhaps the Fed rate increase will begin to restore normality?
Avation do seem confident in using the proceeds from the six aircraft effectively. Their disciplined approach to building a high quality fleet combined with a willingness to do deals when opportunities arise appeals to me and I'll continue to hold.
I agree completely. The management have a long track record and a significant vested interest in the company. I prefer to see them utilize the money for the continued growth of the company than returning it to shareholders. I'm up 60% in the last couple of years on AVAP and will continue to hold long term
I believe that Avation (LON:AVAP) have made right call here regarding the ATR sales. Selling such a large proportion of their fleet may give them cash to offset their leverage but in my view just slides them back down the growth path that they see to have fought their way up. Happy to hold in a continuingly profitable entity.
Long on £avap
I have held this stock for many years and sit on a near 500% profit
Totally agree with Paul that at its current price it is fully valued but so are most other very well managed profitable companies!
Can anyone tell me when this will change?
Hi Benson
If you are interested in moving your profit into a similar (although not identical) company but with higher growth & lower P/E then can I recommend taking a look at Luceco, they had an IPO last year & have the USP of their own factory in China which allows them to undercut their competition.
Revenues are growing at approx. 30%, profits are expected to double this year & they are on a PEG of just 0.64.
Steve / Benson - Re. Luceco (LON:LUCE) Just a bit of caution about this stock. I remember looking at this share at the IPO stage. I wasn't keen on the amount of debt it was carrying and I don't believe it used the IPO proceeds to reduce it.
The StockReport shows a net debt of £46.7m against an OP of 11.5m , a ratio of 4. Anything above 3 - 3.5 is a red flag.
It doesn't mean to say that it is uninvestible, but a financial risk whose consequences you need to be aware of.
Regards, Ram
Hi Ramridge
Luceco sensibly did use some of the proceeds from the float to reduce net debt from £50m to £28.1m (net debt / EBITDA is down from 3x to 1.7x).
This isn't shown in Stcokopedia's figures yet as they are based on last years financials, this years are due out in the next couple of weeks.
Hopefully forums like this can help spot a buying opportunity where Stockopedia's figures are slightly out of date.
As you can probably gather I own Luceco.
Just been looking at Luceco (LON:LUCE) for the first. Yes debt did look high but as you say it's last years figures. A couple of things I'm not keen on is the spread for a mid cap is wide nearly 5% and their Headoffice is in Baker Street, London I don't understand why a company like this has to have their HQ in an expensive part of London, apart from that it's quite good but I will wait for the results to come out before investing.
Luceco's 2016 figures are released on the 3rd April, although they have already released a trading update saying the results will be in line with market expectations so I presume the 30% sales & 50% profit forecast growth figures on Stockopedia are correct.
I researched them after they were tipped in the Momentum tip sheet, which is produced by the same guys that do the SCSW which has a great track record & Paul often quotes - which is what put me onto it in the first place.
Another recently tipped share that also looks interesting but that I do not hold is Swallowfield (SWL)
Hi Steve, I did look at SCSW but their recent performance did not look too good and many of their tips I already knew about from here. Up to 2012 their performance was impressive, not sure if something has changed in the last few years or not.
Yes I have been looking at Swallowfield (LON:SWL) recently.
Hi Herbie
Yes not great, its up 30% since July which isn't too bad, but not quite in Paul's league.
I certainly wouldn't buy blindly from them but it has thrown up a couple of good shares & hence worth the subscription.
OK I have not got the latest figures only what's on the website which shows 2014 shares at 31/10/15 up 2%, the previous year was up 29%, 2012 was up 98%, 2011 up 110% and 2010 up 114%.
Its certainly been going for a good few years, I wonder if the original writer / researcher has retired, hence the fall in performance, I have only been a subscriber for approx. a year.
Wish I'd been a subscriber 2012 - 2014 !!