Small Cap Value Report (Thu 16 May 2024) - IDS, WG., BVIC, RBG, RNWH, ECEL, BT., HAT, FUTR, NEXS, VTU

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Companies Reporting
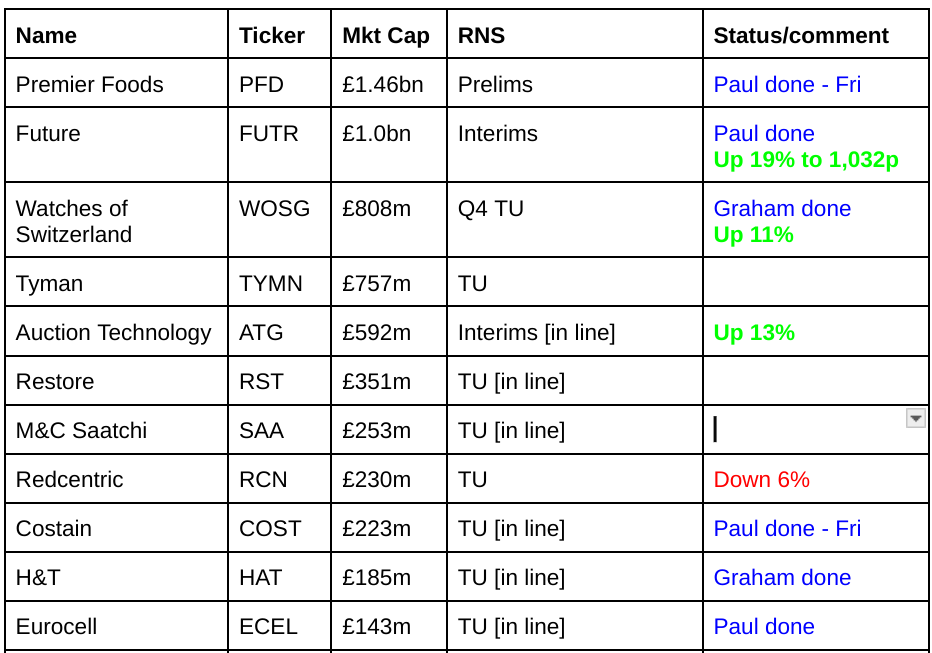
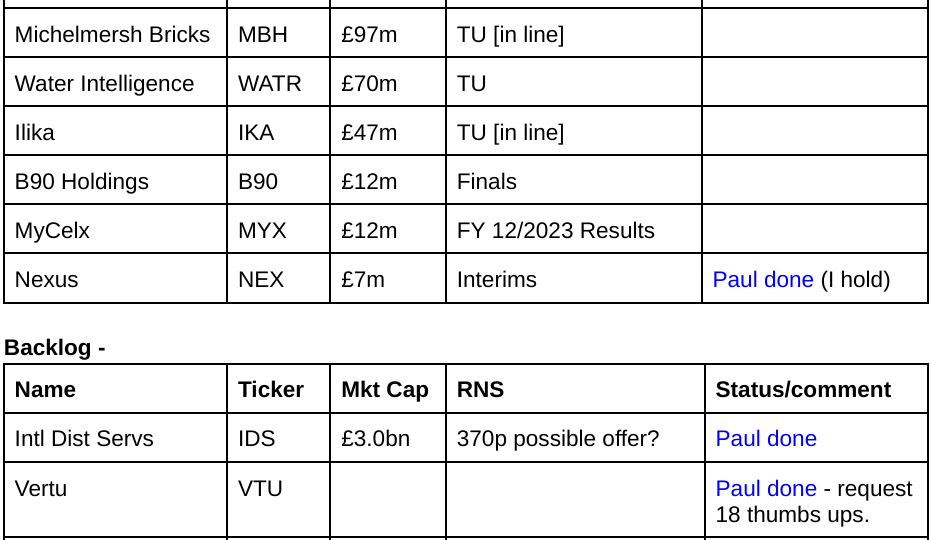
Other mid-morning movers (with news)
BT (LON:BT.A). - up 9% to 124p (£12bn) - FY 3/2024 Results - Paul - no view.
Ambitious plans from the new CEO at BT -
"This delivery and greater capex efficiency gives us the confidence to provide new guidance for significantly increased short term cash flow and sets out a path to more than double our normalised free cash flow over the next five years. This enhanced cash flow allows us to increase our dividend for FY24 by 3.9% to 8.0 pence per share. We're also setting a further £3bn of gross annualised cost savings to be reached by the end of FY29.
Huge net debt and giant pension contributions mean that the balance sheet has negative NTAV. Should it be paying such generous divis, when it has a mountain of debt? Anyway, this one’s above my pay grade, so let’s move on!
Nexus Infrastructure (LON:NEXS) (Paul holds) - up 15% to 95p (£8m) - Interim Results - Paul - AMBER/GREEN (but note de-listing risk, small & illiquid)
Nexus does groundworks for housebuilders, so obviously business is depressed at the moment.
A very small, and illiquid share, with 4 biggest shareholders in control with over 50%, so de-listing risk worries me (hence only a small position in my portfolio). The deep (balance sheet) value caught my eye recently. H1 figures today show revenue halved to £26m, but the loss before tax of £(1.5)m isn’t a disaster by any means, showing it must have stripped out a lot of costs. Order book has recovered strongly, and outlook says it has good visibility going into H2, so this looks an interesting potential cyclical recovery type trade. Great balance sheet includes entire market cap in net cash of £9.2m! NTAV dwarfs the market cap too, at £29m. Receivables look much too high at £24.6m though, needs clarifying, that’s almost the entire H1 revenues. No broker notes. IMC webinar is tomorrow at 1pm, so I might tune in to see if I’ve bought a pup or not! Could be an interesting one for nanocap investors to take a closer look at, let me know what you think.
Summaries of Main Sections
Eurocell (LON:ECEL) - 131p (£142m) - Trading Update - Paul - GREEN
Shrugs off challenging market conditions (revenue down 6%), and produces an in line with expectations update, helped by some cost reductions (eg raw materials, and energy). Buyback extended from £5m to £10m. There's lots to like here I reckon.
H & T (LON:HAT) - unchanged At 419.7p (£185m) - AGM Trading Update - Graham - GREEN
It’s a pleasant “in line” AGM trading update. The pawnbroking pledge book continues to grow as, evidently, consumer conditions still drive robust demand for alternative loans. But retail margins are also improving as expected. I remain a huge fan of this business and the stock remains attractive to me at PER of 7x.
Future (LON:FUTR) - up 19% to 1,032p (£1.19bn) - Half Year Results - Paul - GREEN
Nice to see our bullishness on FUTR vindicated, with shares up c.70% in the last 3 weeks! H1 results today come with an in line exps FY outlook. Balance sheet isn't the best, but cashflow is so strong that it doesn't matter. Buybacks also increased. Looks like a proper re-rating to me, rather than a spike up in price. Still decent value I'd say, now it looks as if growth is beginning to return.
Vertu Motors (LON:VTU) - 78.3p (£265m) - FY 2/2024 Results - Paul - AMBER/GREEN
Still looks reasonably priced, and we've always liked the considerable freehold property backing here. A takeover bid seems the most likely end result, although so far almost everything apart from VTU has been bid for, so what do I know?! I'm comfortable with AMBER/GREEN - moderately positive.
Watches of Switzerland (LON:WOSG) - up 10% to 371p (£889m) - Q4 FY24 Trading Update - Graham - AMBER/GREEN
A very nice update from this watch/jewellery retailer. In the short-term, performance is buoyed by strong growth in the US and by the success of its 2nd-hand Rolex product. In the long-term (to 2028), the company sees even better growth opportunities than it originally planned. I remain intrigued by this one.
Paul's Section:
First, a few quick comments from yesterday's other news -
International Distributions Services (LON:IDS) - up 16% y’day to 315p (£3.0bn) - possible 370p takeover bid - Paul - PINK
This group owns loss-making Royal Mail as a sideline, but its main value is in the profitable German distribution business GLS.
Czech billionaire Daniel Kretinsky already holds c.28%, and on 18/4/2024 his indicative 320p bid approach was declined. The latest news is he’s apparently prepared to pay an increased price of 360p + 10p divis. The internet came up with a brilliant quip - “The Czech’s in the post!”
IDS management has indicated they are minded to support this deal as a fair price, subject to various things.
Why did the share price only end yesterday at 315p, a long way short of the potential 370p bid? Presumably the market must see considerable obstacles to the deal actually happening, I don’t know. Or it could be a nice profit opportunity? Press reports talk about regulatory, pension funds, and unions needing to agree things. Good luck to anyone brave enough to take on Royal Mail!
John Wood (LON:WG.) - down 7% to 186p (£1.3bn) - Rejected 212p cash takeover - Paul - PINK
Just before yesterday’s market close, this engineering group announced its Board had rejected a possible 212p cash takeover bid from Sidara (slightly increased by 3% from a previous proposal). The Board said - “continued to fundamentally undervalue Wood and its future prospects.”
It’s not something we’ve looked at here before, so no view from me. But obviously the shares are attractive to a bidder that is prepared to pay more than the current share price, which is clearly a good place to us to be looking for value and doing more investigations of our own. As we’re seeing in the deluge of mid-cap bids, often the bidder raises the price, or other parties get involved. Exciting times!
Britvic (LON:BVIC) -up 11% y’day to 1,018p (£2.6bn) - Interims - Paul - AMBER
Market likes its H1 results. Adj EPS up 19% to 27p. Doing another buyback, of £75m. However, the balance sheet is horrible, with negative NTAV and far too much debt, and valuation looks pricey. So doesn’t appeal to me at all, on a value/GARP basis. Maybe people like the brands, or are valuing it some other way? Each to their own!
Revolution Bars (LON:RBG) - 1.5p (£3.5m) - Update - Paul - RED
Says that a wide-ranging FSP and restructuring process has failed to generate any bid interest in the company as a whole. That’s not a surprise, as it;s trying to do a complicated restructuring to ditch the loss-making sites. So it seems as if this FSP (formal sales process) might be a formality, so it can demonstrate to the court that all options have been explored, in order to justify clobbering the landlords of the closed sites, and releasing it from lease liabilities.
My view is that the backers of the £10m equity raise at 1p hold all the cards, as they’re not actually committed the money. They’ve effectively been given a call option to refinance RBG if the various conditions are met (such as court approval for the CVA, or similar). If those conditions are not met, they they can walk away - losing their existing equity, but not losing any of the additional pledged funds. That’s a much better situation than private investors, who if we buy now (or even just hold), then we’re potentially wiped out if anything goes wrong.
If the restructuring deal does happen, the dilution at 1p is so large, and leaves a still-indebted and not very good business. In a sector where it’s incredibly difficult to make any money at all, since wages costs have soared in recent years, and typically constitute about 35% of revenues, or c.50% of gross profit.
For these reasons, I’m happy to sit on the sidelines, as the upside isn’t clear enough to justify a potential 100% loss for small shareholders if anything goes wrong with this complicated restructuring. Overpaid management have demonstrated several times that they’re incompetent too. So why back poor management in the third fundraise in the last 4 years?
Renew Holdings (LON:RNWH) - 1,054p (£833m) - H1 Results - Paul - AMBER/GREEN
We’ve followed this contracting business for many years, and watched in amazement as it’s done a most unlikely major multibagger, in a sector that is often an investing graveyard (low margin contracting). The key to its success seems to have been just really good execution by management, and gradually increasing the operating margin from about 1% to 5% (I remember them setting out that aspiration, years ago), plus seemingly successful bolt-on acquisitions. Good H1 numbers show adj EPS up 14% to 31.3p. The commentary talks about its “high quality, low risk business model”. Confident full year outlook. Network Rail seems a key customer, with huge maintenance spend. No balance sheet support, with only £14m NTAV.
Paul’s view - I can’t argue with success! This is not a sector I invest in, but the brilliantly named Paul Scott (CEO of RNWH) has clearly demonstrated a stunning performance here over many years. Compare that with all the accident-prone “value” shares in this sector, and I can see why RNWH shareholders are happy to stick with the best. After such a strong run though, there must come a point where it makes sense to bank some profit perhaps?
Eurocell (LON:ECEL)
131p (£142m) - Trading Update - Paul - GREEN
Eurocell plc, the market leading, vertically integrated UK manufacturer, recycler and distributor of PVC window, door and roofline products, provides the following update for the first four months of 2024, in advance of the Annual General Meeting ("AGM") later today.
I wanted to have some building supplies & similar type companies on my 2024 shares ideas list, so included Headlam (LON:HEAD) (profit warning yesterday) and ECEL - partly because both have strong balance sheets, which means they can absorb any further downturn in trading. As we saw earlier this week from HEAD, trading is not yet recovering, in fact it has lurched down again. I was expecting a far worse share price reaction, so it seems that shares in this area might have the bad news already factored in, with investors looking through soft current trading for the eventual recovery in 2025, maybe even late 2024, who knows?
Today’s news from ECEL confirms conditions are still tough, but it seems to be coping alright -
Trading conditions in our key markets have remained challenging, with continuing macroeconomic uncertainty impacting activity levels in both the repair, maintenance and improvement ("RMI") and new build markets. However, we continue to focus on closely managing costs and cash flow and have seen some further reduction in raw material cost pricing in 2024.
As a result, our expectations for underlying profit before tax for the year remain unchanged.
We are on track with the delivery of the early stages of our new strategy. Our balance sheet is strong and the actions we have taken, including those on costs and cash flow, position us well to benefit when our end markets recover.
That’s a very different story from HEAD earlier this week (different products, I know), which lurched into a significant loss.
Note that broker forecast at ECEL has actually been rising in recent months, a fair bit too -
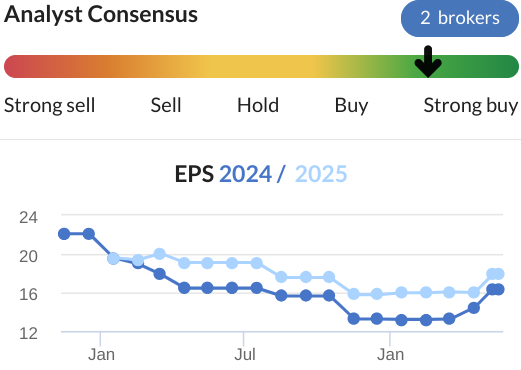
Share buyback - is being extended from £5m to £10m. That’s significant for a £142m market cap company. £4.2m has already been done, and some is being used to satisfy share options in the next 2 years. Let’s hope the options only vest if challenging performance targets are hit, and aren’t just free shares for happening to run the company when a cyclical upturn starts.
I’m impressed that ECEL has the financial clout to do significant buybacks, despite challenging market conditions.
Paul’s opinion - for investors who are prepared to be patient and wait for a cyclical recovery, I think ECEL looks excellent.
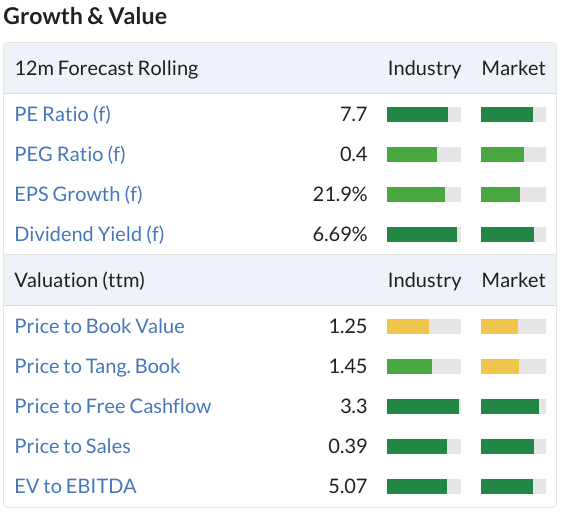
Stockopedia shows very attractive valuation measures (see below), together with an in line update today, cyclical recovery potential, generous divis and buybacks, and good balance sheet support, risk:reward strikes me as favourable - tons better than HEAD. So I’m happy to remain at GREEN.
Future (LON:FUTR)
Up 19% to 1,032p (£1.19bn) - Half Year Results - Paul - GREEN
Shares at this specialist media group have gone bananas in the last 3 weeks, up c.70%. I hope some readers caught this terrific move, as it’s been one of our favourite value shares here this year, with us flagging up the superb value, and wondering why the shares were so cheap, with GREENs on 7/12/2023, 7/2/2024, and 4/4/2024. Funny isn’t it, sometimes great value does just stare you in the face, with plenty of time to buy the shares too. Although in practice it’s not always that easy, as we wonder what we’ve missed that the market is negative about, when the shares seemed in a relentless downtrend.
Forecasts have been in a downtrend though, so clearly all is not perfect at FUTR -
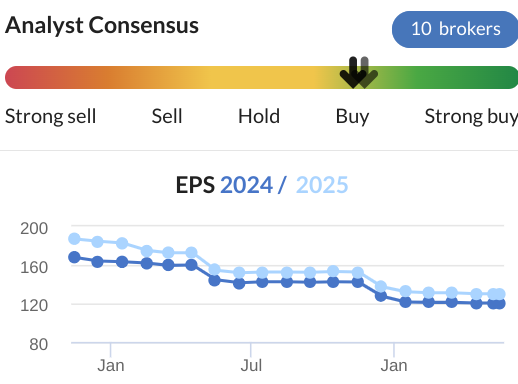
Key H1 numbers (6 months ended 31/3/2024) -
Revenue down 3% to £392m
Adj diluted EPS down 20% to 57.2p
Declines seem to be bottoming out -
The Group returned to year-on-year revenue growth in Q2 with organic revenue growth of +3%.
Net debt - as mentioned before, I don’t see this level of debt as being problematic, given how genuinely cash generative the group continues to be -
Leverage1 was unchanged at 1.25x (FY 2023: 1.25x) with net debt1 at the end of the half year of £296.7m (FY 2023: £327.2m). Total available debt facilities at the end of March 2024 were £650m (FY 2023: £900m).
Outlook - in line for this year -
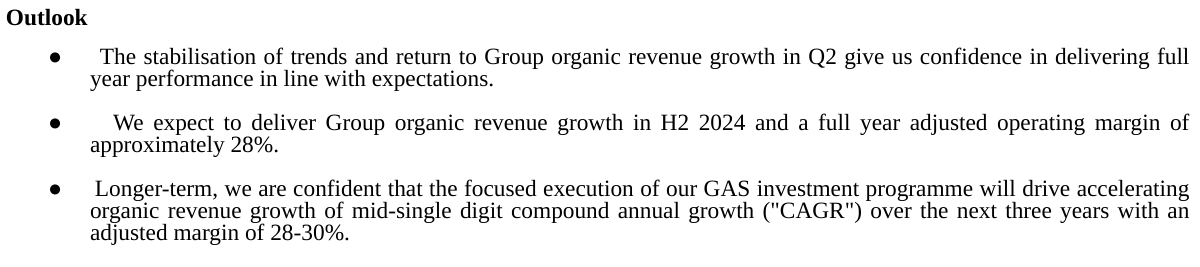
Balance sheet - in isolation this balance sheet looks stretched. NTAV is heavily negative, I’ve been kind and deleted deferred tax liabilities, but even then I get to a pretty horrible £(381)m NTAV. However, FUTR throws off so much cash, that the bank borrowings which make up most of the deficit on its balance sheet are comfortable to both service, and repay. So there isn’t a solvency problem in my view. This is a capital-light business model, with little in fixed assets, and nothing in inventories. So management has taken a view that it can carry almost £300m in net debt without causing any strain. I’d prefer if it was net cash, but never mind, can’t have everything, and we can adjust the valuation to take into account debt.
Cashflow statement - is very simple to understand. It generates loads of cashflow which was used to purchase its own shares (smart move given how depressed the share price was), and reduce bank debt. Note divis are only a token amount.
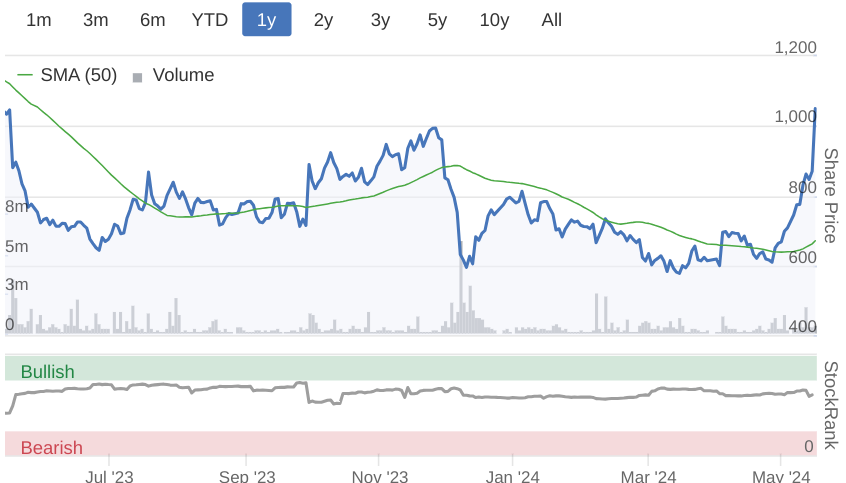
Paul’s opinion - even after an explosive upward move, the PER is still only about 8.6x likely 120p adj EPS for FY 9/2024. Hardly expensive. If we allow for the c.£300m net debt, then I would see the PER about 11-ish. Not expensive, especially given the high quality recurring cashflows this group generates. Outlook comments suggest we’ve maybe hit the bottom re earnings, and a recovery in advertising might now become evident perhaps? I don’t know anything about any impact (bad or good?) from cookies, maybe someone could explain that for me.
I was expecting to lower it from green to amber/green, given the 70% surge in share price, but as I think it remains good value (but not absurdly good value any more), I’ll happily stick at GREEN. This looks to me a radical change in market sentiment towards FUTR shares, rather than a short-term spike. Although nobody could be blamed for top-slicing after such a great run. Well done to holders! Pity I didn’t eat my own knitting (?), but never mind, I’m almost as happy seeing readers make a bob or two here!
Vertu Motors (LON:VTU)
78.3p (£265m) - FY 2/2024 Results - Paul - AMBER/GREEN
Vertu Motors, the UK automotive retailer with a network of 188 sales and aftersales outlets, announces its final results for the year ended 29 February 2024 ('Year').
Company’s headline -
Record revenues, substantial cash generation and increased dividend
Key numbers -
Adjusted profit before tax of £37.8m (FY23: £39.3m), on record revenues of £4.7 billion. Profit in line with current market expectations.
Adj EPS was 8.37p, so PER is 9.4x
Remember that H2 suffered when there was an unexpectedly sharp downturn in used car values, and other cost increases (especially wages and energy) have also made things tricky in the last couple of years. So I’m not sure if we should be looking for future earnings to increase, or not?
Outlook - lots of information in this, but overall it sounds OK to me -
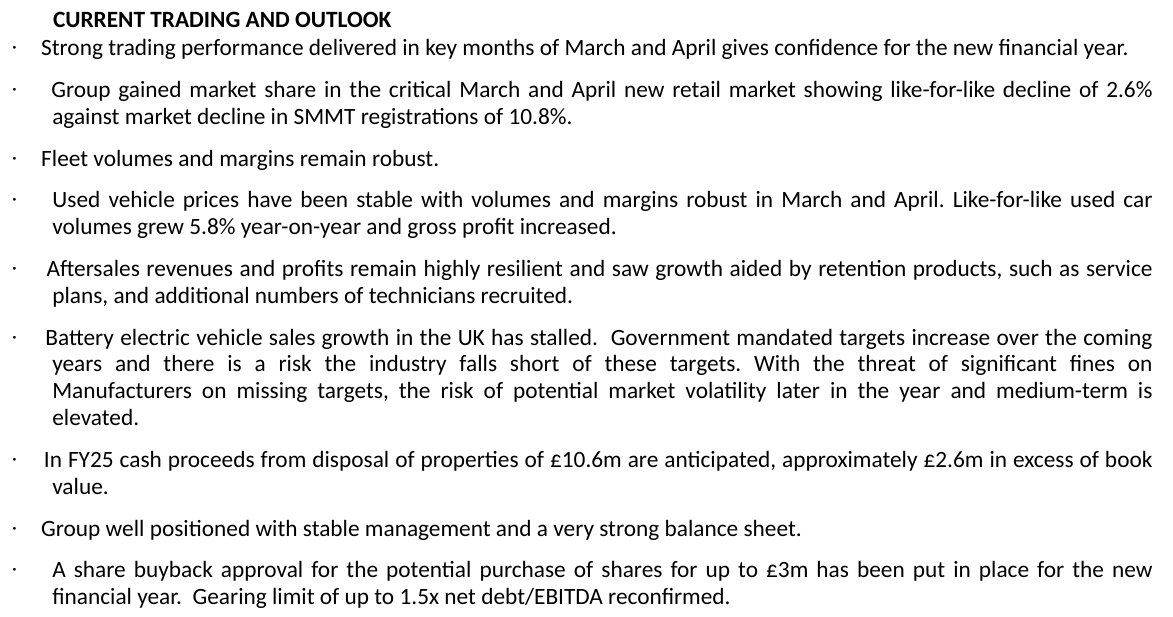
The Board is pleased with the Group's strong trading performance in the critical first two months of the new financial year. Overall, the performance was slightly ahead of the Board's expectations and expectations for the full year are unchanged.
Balance sheet - NAV is £353m, less intangible assets of £131m, gives NTAV of £222m, which supports most of the £265m market cap. As we’ve discussed before, VTU has large freehold property assets, which gives lovely downside protection. Although it hasn’t made any difference, since practically everything in the sector apart from VTU has received takeover bids! Although I see that Cinch (part of a large group called Constellation) now holds 9.1% of VTU, so wonder if a bid approach from them might be the end game here?
Paul’s view - with c.9p EPS expected for FY 2/2025, and taking into account the strong balance sheet with lots of freeholds, I think a fair price for this share might be c.100p? So it looks reasonable value at 78p. Probably the most interesting thing is the obvious potential for a takeover bid, if that came in at say 100-120p then it would be a reasonable exit I think.
There’s some uncertainty over some manufacturers moving to an agency model (commented on in this latest update), and also a deluge of Chinese manufacturers trying to sell us subsidised electric vehicles that not many people seem to want! I read recently that the US is apparently imposing 100% tariffs on Chinese EVs, so wonder if the EU might do something similar to protect the German manufacturers? There’s also the question of whether aftersales on EV will be as lucrative for the dealers, given the smaller number of moving parts? Lots of things for us to ponder.
Overall I feel most comfortable at moderately positive, AMBER/GREEN.
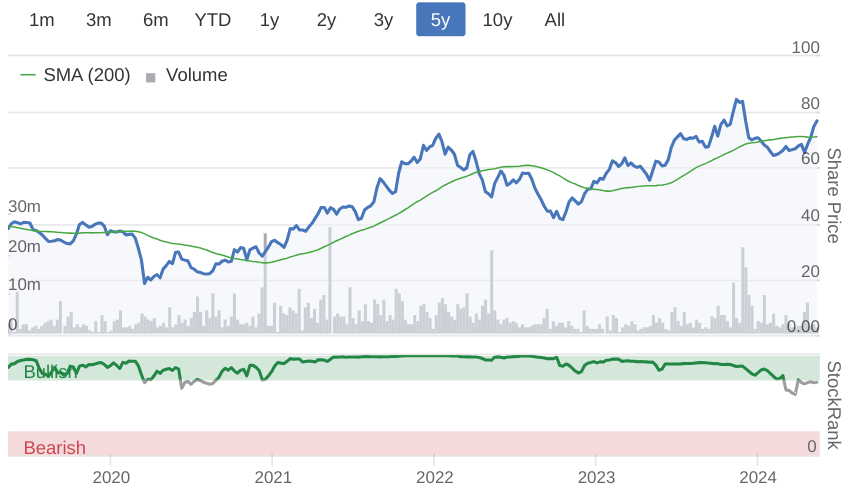
Not as stunningly cheap as it used to be, but still reasonable value -
Graham’s Section:
H & T (LON:HAT)
Unchanged At 419.7p (£185m) - AGM Trading Update - Graham - GREEN
The UK’s largest pawnbroker issues a trading update for the first four months of the year: it is in line with expectations.
Demand for pledge loans continues to be buoyant and April 2024 was a record month for lending. Consistent with last year, redemptions in March and April were higher than average as customers chose to collect their items, often to wear them at religious and family celebrations. This is expected to reverse in the coming months.
H&T’s overall pledge book is now £105m, up from £101m at the end of 2023.
H&T made an £11m acquisition in February that raised a few eyebrows - a “posh” pawnbroker whose average loan size is over £4,000. In the few months since then, there haven’t been any mishaps: the pledge book has performed “well”.
The short update concludes as follows:
Retail sales and foreign currency revenues are in line with forecasts, with retail margins improving as expected. Gold purchase and scrap revenues are benefitting from a strong gold price.
Three stores have been added to the store estate so far this calendar year, including Maxcroft, with one closure. The store estate currently stands at 280 stores.
Graham’s view
I’ve been very bullish on this one, most recently covering its annual results here.
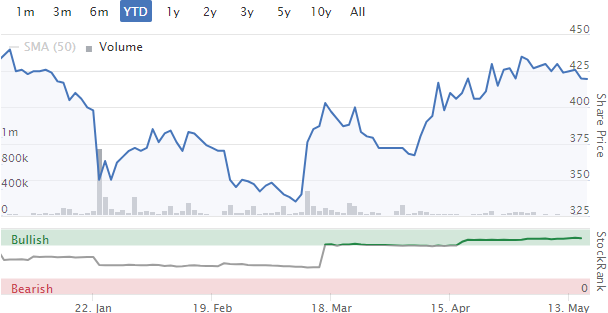
After an in-line update, there’s no need to change my view, although I see that the share price has been rising off those low levels reach in recent months:
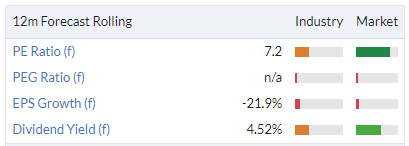
The PE Ratio is now the much more demanding 7x, instead of the 6x it was at before:
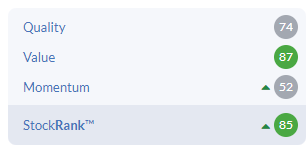
StockRanks like it too, especially from a Value perspective:
I continue to have a slight preference for H&T over Ramsdens, although I would say both are highly attractive. With H&T, you get an enormous pledge book (ten times bigger than the Ramsdens pledge book) offset by complementary activities such as jewellery retailing.
With Ramsdens, it’s more of a combined offering where each service is of roughly equal importance.
H&T opened a net 10 new stores in 2022, and then a net 11 new stores in 2023 (total 280).
Ramsdens opened a net 8 new stores in FY September 2023 and has 9 new stores planned for FY 2024 (current total 167).
So both companies are expanding in what I would describe as a controlled way, without taking on excessive risk.
It’s a matter of taste which one you prefer. Personally, I prefer H&T because of the pawnbroking focus.
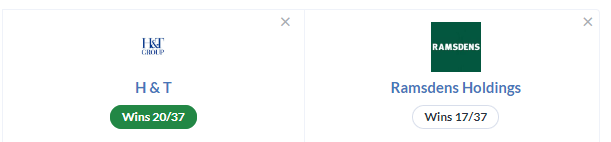
Stockopedia’s “Compare with…” tool also has a slight preference for H&T when you put them in a head-to-head battle:
Watches of Switzerland (LON:WOSG)
Up 10% to 371p (£889m) - Q4 FY24 Trading Update - Graham - AMBER/GREEN
Only a week ago I adjusted my stance on WOSG to AMBER/GREEN, as I thought the acquisition of Roberto Coin Inc in the United States seemed to be a promising one, and WOSG shares are on the floor compared to where they were:
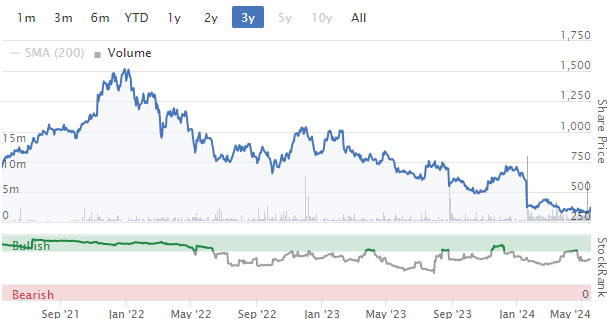
This has resulted in some superficially cheap earnings multiples, although of course you have to be very careful in the retail space as things can turn bad quickly.
Fortunately, things haven’t turned too bad for WOSG yet. Today we have a Q4 and full-year update (to April 2024).
CEO comment:
We finished the year strongly, with Q4 sales in line with guidance and ahead of consensus. Particularly pleasing was the performance in the US, with sales up 14% in the period…
Our acquisition of Roberto Coin Inc. (the exclusive North American distributor of Roberto Coin) dramatically accelerates our luxury branded jewellery strategy, and we see enormous potential in bringing together this iconic brand with our retailing expertise…”
Let’s cover the key bullet points for Q4:
Revenue £380m, +4% at constant currencies.
2nd hand Rolex offering (“certified pre-owned”) performing ahead of expectations.
Total pre-owned and vintage revenue doubled year-on-year.
Jewellery revenue was flat when measured at constant currencies; this is much improved versus minus 16% in Q3.
Q4 revenue was equally split between the US and UK/Europe, although with much stronger growth recently in the US. A nice backdrop for the recent acquisition.
The UK/Europe are impacted by “challenging macroeconomic conditions”, and in the UK the loss of VAT-free shopping for tourists has been a particular issue, one we’ve touched on before. Recent hopes that this decision would be reversed have been dashed, but perhaps it will stay on the agenda for future Budgets?
E-commerce continues to do very badly, down 20% on last year, one of the few areas where WOSG investors have received no good news to cheer for Q4.
Full-year results: zooming out from Q4 to look at the full-year to April 2024, it’s again a tale of two geographies. US revenues are up 11% at constant currencies, while UK/Europe revenue is down 5%.
Jewellery performed much worse than watches, and the company previously noted that “non-branded” jewellery was a major source of weakness. This theme continues today as WOSG says:
Luxury branded jewellery continues to significantly outperform in jewellery
With jewellery revenue as a whole down 13%, this implies that non-branded jewellery did very badly indeed!
Adj. EBIT for FY 2024 is expected from £133 - £136 million (previous year: £165m). Given the dramatic fall in the share price, you may have expected worse!
Net cash: has fallen to £1 million (last year: £16m); it would have risen if not for an acquisition.
Since year-end, the $130m Roberto Coin acquisition has been announced and WOSG has borrowed to fund that deal, seeing its leverage multiple rise to 0.8x.
Besides its financial debt, the company also has significant lease liabilities. So it can be argued now that the balance sheet is in risky territory. As I said last time: elevated risk for elevated rewards!
Long Range Plan: WOSG is still planning to double sales and Adjusted EBIT by the end of FY28, and are “confident” in these targets.
The 2nd-hand Rolex offering is an important part of this; its initial performance is ahead of expectations and it is now expected to outperform its previous targets.
Similarly, “we see further growth opportunities for Roberto Coin Inc. ahead of what was previously assumed within the LRP”.
Outlook for FY 2025: “cautiously optimistic”. Watch production is “conservative”, given recent volatility.
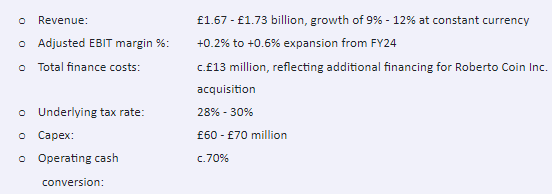
On a pre-IFRS 16 basis (i.e. treating rents as operating costs), we get the following guidance:
Graham’s view
I’m inclined to stay AMBER/GREEN on this one: I see very high rewards for shareholders if the company’s strategy succeeds, but I’m also cognisant of some important risk factors:
Retailing risk: exposed to consumer sentiment generally, with the ongoing cost of expensive leasehold properties.
Watch market risk: the value of luxury watches has been extraordinarily volatile in recent years, as we’ve discussed previously.
Financial risk: WOSG has borrowed to fund its recent US-based acquisition.
Are these risks priced in? I’m inclined to believe that they are, which is why I’m leaning towards a positive view on these shares:
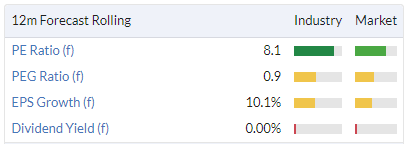
I still think of this stock as a recent float but it has been listed since 2019. It hasn’t paid a dividend yet but it remains very ambitious, and its top and bottom lines have grown impressively over this time. At a single-digit earnings multiple, I think it’s certainly worthy of further consideration
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

121 comments
For Mello2024 the two day schedule is now available https://melloevents.com/mello2... If you have never been before just use this code for a £30 try it and see if you like it ticket... NEW2MELLO24
Hi Graham, thank you for you analysis of H & T (LON:HAT) and comparison with Ramsdens Holdings (LON:RFX) .
The 3 main determinants of long term intrinsic value are Growth, Return on Capital and Risk. RFX beats H&T in all three measures, and for this reason i think RFX is better business, with higher future return expectations than H&T. I hold RFX.
I think one reason Ramsdens Holdings (LON:RFX) has a higher ROCE is that it simply operates more activities within each branch (currency, jewellery, pawnbroking, etc) whereas H & T (LON:HAT) is largely pawnbroking. Since each store will have similar fixed costs (rent, staff, energy) RFX should generate more profits per store.
Hi QARPY. I know very little about H & T (LON:HAT) or Ramsdens Holdings (LON:RFX) . But I do find your use of the comparison table that you use to evaluate long term intrinsic value to be very interesting. I like it because it gives a quick, easy, logical and quantitative way to compare companies in the same industry. When considering buying shares I always look at how expensive they are because that will affect the gains or losses that one would make after investing in it. So if we look at the 12m forward rolling PE for these two, we get H+T at 7.1 and RFX at 8.1. So H+T is the winner by that particular measure. As usual the better business is the more expensive one. So I have no opinion on which would be the better investment, and am only commenting because I can see some merit in your process.
I also look at PEG, Ramsdens Holdings (LON:RFX) is 3.3, H & T (LON:HAT) is not available because the EPS forecast for next results is down.
High Fliers may contradict your strategy of lower expense. I have lost out on many, waiting for certain stocks to get cheaper.
I think High Fliers outperform Value stocks.
Hi Rusty2. I could not agree with you more! My portfolio is mostly high flyers, for which I use the PEG ratio, which, as you point out is not applicable where EPS forecast is down. My use of the PE ratio is mostly to rule out very expensive shares, rather than to look for cheap ones. I would not normally be considering shares like H & T (LON:HAT) & Ramsdens Holdings (LON:RFX). As a result of QARPY's post I have created a screen looking for revenue growth and high ROCE with a sensible PEG.
Treatt (LON:TET) Treatt H1 analyst presentation from Tuesday including Q&A. The orange oil price has been a headwind and the loss of a coffee customer but they say they have a healthy orderbook giving confidence in hitting full-year expectations. Interim CEO & CFO. Video & podcast.
An interesting little side-note is that value investors Tweedy Browne have a holding, which is nice.
RNWH FWIW I bought shares in it about a year ago. Nice little result it's been, too. My reasoning is that I considered it a GARP share. Operating profits per share have been growing at around 15% pa over the last decade. Pretty good! Return on capital has been high. Fwd PE is 15, which is reasonable, and it has net cash. Works for me.
IG Design (LON:IGR) has hit £2!Cheers Paul.Going to be 'greedy' and hold unless i or someone else can find something not too complicated with too many moving parts business wise (well if i can find it nonetheless) better preferably at a discount.
Future (LON:FUTR) As a holder I was certainly surprised at the reaction today. Having read todays update I was thinking the share price would be unmoved or even slightly down after the recent 50% run up. Having looked into things a little deeper today, I would agree with Feta that the significant rise is all linked to the short position held on Future.
A £45mil share buyback was announced today, this is in addition to the current buyback, of which £13mil is still to be completed. Combined this leaves £57mil of shares to be bought back. The market cap at the time of writing is 1.2billion. The buyback therefore equates to 4.75% of the company.
The current short position is 2.75%, therefore easily covered by the buyback. With the company fundamentals stabilising and bullish follow up buyback announced, I would imagine the shorts are now running for the hills and selling out. You love to see it.
Future (LON:FUTR) not a holder but would be very pleased if the shorts are getting a good kicking and well done to any holders.
Think you will find the first buyback was completed on the 19th January this year. This first buy back helped the share price run up from around 750p to just under 1000p before getting sold down heavily due to a negative broker note (I forget which broker now). The companies average price on this first £45 million buyback was 795p.
Hi Clanger, thanks for that. "£35.9m was returned to shareholders during the period with £32.0m through the completed £45m share buyback programme launched in August 2023 (HY 2023: £nil)". Not sure how they can claim it's completed when they still had a chunk left to go, but you are correct!
Ahhhh "during the period"... it's been a long day...
Nexus Nexus Infrastructure (LON:NEXS) are my largest holding. Paul raises the risk of delisting and certainly delisting is always a risk with these nano caps particularly when, in this case, four shareholders have over 50%. Personally I think the risk is quite low here for a few reasons.
Firstly, they only listed in July 2017 and I don't see any condition change that would cause that to be revisited. Key players in that decision are still in the company. Mike Morris is a large shareholder and continues to be hugely influential; Dawn Hillman is the current CFO and Richard Kilner remains a non-exec director.
Secondly, while the business is now just the Tamdown division, they have invited us to look at what they have done already in organically growing businesses (Tri Connex and eSmart) which they sold and then returned £61m to shareholders in February 2023. Rinse and repeat, my words but that was the message in the last Investor Meet Company presentation. They are looking at the area of critical infrastructure. A listing can only help an expanding company and would enable return of funds as previously done.
Tamdown is a really good building contractor in the best part of the country for this industry, solid customer base and directors and managers well known in the industry, ref trade magazines, linkedin etc... Todays update shows margins improving which shows they have right-sized the business. I think they are a tight well organised business, I would like to see them continue to grow the order book and if they can get back to the past revenues of £100m or so and with better margins the things will be very interesting! I don't know about the high receivables, Paul, definitely one for the IMC tomorrow!
Is it a fatal drop for Bank of Georgia (LON:BGEO) in the last couple of days?
I would say an opportunity. You would need to watch the politics carefully though. I am watching TBC Bank (LON:TBCG) as well- now yielding 10% . They are in Georgia and Uzbekistan. Not bought yet but did buy a few Georgia Capital (LON:CGEO) on the slump.
Why on earth would the drop in Bank of Georgia (LON:BGEO) be fatal mburnett?
What’s going on is retail outflows in an illiquid stock brought about by the foreign influence law and demonstrations. It has thrust Georgia as a country into the spotlight negatively and as a result retail investors first response is usually a flight reflex. You can see that in the volumes traded.
You can buy this stock on 3* PER because of the geopolitical risk - in a development economy and given its capital position and high ROE it trades on three times the price.
The demonstrations and introduction of the law in question are unhelpful and may even result in sanctions against certain individuals but on its own changes very little. If that power got abused then it might. Was interesting that the Georgian prime minister met with the US and publicly expressed that they want to depend relationships with the US, not alienate - there is no anti west rhetoric : but given the region of the world that could be cynical. For me the question would be what would Georgia have to gain from veering too far towards Russia at this stage in their development and the answer is very little. It would be negative on most fronts. They have everything to gain from veering towards China though as much of their tourism and trade is coming from that direction. So my guess is that politically they are trying to tread a tightrope of not upsetting Russia given prevalence for violent reactions, keeping China sweet and not alienating Europe/US irreparably. The problem is in doing so they may well be alienating their own people.
As for Bank of Georgia (LON:BGEO) they now have a large operation in 3 countries (largest bank in Lithuania purchased recently) and have own funds that are very high. Emerging markets are volatile and illiquid though so you will see large swings, that’s just the nature of the game.
Davidjhill- A very good and concise summary of the situation.
Georgia - G Cap and Bank of Georgia
Really interesting how to view this and emotionally hard to navigate a share being decimated daily .
Emotion / mr market ate screaming run for the hills and market outflows are seeing contagion to what is probably a serious buying opportunity .
Buy when others are fearful to tread or something .
I was uncomfortably weighted to both these on the back of big gains in the past year so took a good kicking on paper z
The logical mind says
- not too much has actually changed in the day to day so it’s basically a 30% off sale so don’t be a muppet and get flushed out .
However then ask “has the business case changed” and the answer is probably yes . GEL currency may well get hammered by 15% so that’s a definite potential 15% hit to profits .
For anyone with balls of steel looks anazing entry points but hard to see a quick resolution as long time to the election so this is goi g to get bounced around by speculators and traders with click bait headlines and will probably not resolve itself for a long time .
In the end I actually have clipped my position by circa 20% which brings me to a full holding which I’m more comfortable with
I was quite lucky to start selling Georgia capital at 1350 last week but did have to take a few pain pills at 950 level to bring my holding down to what I calculated as “comfort “ level which is when I look At all my holdings and write down next to each what I’m happy with . Do this weekly and most weeks it’s “do nothing “
I’m pretty certain should have held tight and not get washed out with the masses but as I also needed cash out this week ( to buy 8000kg of coffee which is another story ) then may as well Just bank some profits
Bank of Georgia (LON:BGEO) Georgia Capital (LON:CGEO) - yes a difficult decision. I sold a week ago on the grounds that this type of political disruption is likely to be prolonged. Many investors got burnt when Russia invaded Ukraine. Ferrexpo (LON:FXPO) etc…had previously been excellent investments, so people may be justifiably nervous.
I would be really surprised to see either Bank of Georgia (LON:BGEO) or Georgia Capital (LON:CGEO) climb back rapidly after these disturbances. We don’t understand fully the ramifications of what may be going on, so for many people (myself included) that simply meant, sadly, yes the numbers look so very tempting, but in the wake of all this political uncertainty, I have done well here and it is time to move on to better opportunities elsewhere.
Not sure I have balls of steel but bought Georgia Capital (LON:CGEO) yesterday and TBC Bank (LON:TBCG) today. Georgia is an interesting emerging market. I do read a lot of the TBC reports on the economy etc and the online Georgia today. . I also buy-and enjoy-Georgian wines ! I had not been drinking before I purchased...
Hi planetx
I think the problem as you describe it was being uncomfortably overweight with some competing liquidity needs and probably temporarily losing sight of the Emerging Market aspect of both these stocks. Bank of Georgia (LON:BGEO) Georgia Capital (LON:CGEO)
Remember the psychology at play - in a fight or flight scenario retail investors choose flight almost all of the time. I’m not opining either way as to whether this is the right approach - that’s not for me to judge, but the herd stampede is a well rehearsed phenomena. So if a stock is illiquid and driven by retail then large volatile swings are the order of the day. So however much I like a stock I will size according to this principle. My approach is either to bail early or stay invested but on the basis of whether I think the flight is temporary.
For those worried about investing in Georgia why not invest in Kazakhstan instead? Comparing Bank of Georgia (LON:BGEO) and Halyk Bank AO (LON:HSBK) on Stockopedia the latter comes out on top with a win ratio of 25/34. Job done! Frying pan/fire? Ha.
Or indeed, Kaspi.kz AO (NSQ:KSPI), I hold. Throws off cash, like there's no tomorrow
Davidjhill Bank of Georgia (LON:BGEO) and Georgia
Are you aware that the key Oligarch pulling the political strings in the background is very much pro-Russia? The Foreign Control law may be just the first step in repression and control as happened in mother Russia. With two provinces invaded several years back it surely isn't a stretch to see Russia take this completely once their Ukraine adventure is resolved or comes to a standstill. Armenia/Azerbaijan next.
IMO this is why continued support for Ukraine is essential. And we should double Defence expenditure now.
Good luck to those who invest in Georgia. I just don't see the point in taking this level of risk with a fair wind for so much else in the markets at the moment.
Yes - I am aware of the Oligarch and Georgian Dream but very much pro Russian is a bit liberal with the actual state of play…..it’s much more nuanced than you make out, as is the Foreign control legislation.
And yes, entirely possible that if Russia is not stopped at Ukraine they spill over much further - in reality if that happens we are likely into a world war though at which point the only thing I want to own is gold and defence stocks.
In the intervening period I am happy to have a small portion of my portfolio in long term emerging plays and I hope that the rest of the world does not allow Russia attempts at domination.
Thanks for taking the time to reply. Your appetite for risk is clearly having gher than mine. Hope your cool,calm, logical approach pays off and if it doesn't the weighting should limit downside.
Our readings of the political situation there differ. I was referring mainly to the Oligarch , in my view effectively an instrument of the Russian state, rather than all of Golden Dream as pro-Russia. And the Foreign Control law is IMO the start of the slippery slope.
The attempted assassination of the Slovak PM another example of growing instability. He seems to be another "populist" leader feathering his own nest repealing anti-corruption legislation. Someone took exception though I wish they'd do it at the ballot box.
you might want to have a look at Incanthera who are listed on Aquis. Immupharma have a stake. Price is up today in advance of an investor presentation tonight..
re BT (LON:BT.A) (I own for my sins) I think it has some relevance to wider market trends mainly because there is a view that most of the gains from AI adoption will fall to old economy businesses that can strip away cost. IF you believe this then old economy laggards could find some shine... the magic number as always is FCF. Imperial Brands (LON:IMB) received the memo. FCF is important because it supports buybacks and dividends.
You basically have 10bn shares... so the increased divi costs £800m which is about half guidance of FCF 2025 £1.5bn...and compares to £2bn 2027 and £3bn 2030..... you can raise an eyebrow at this guidance .... or you can give away the company to private equity and let them do the job for you. It would suit them because it's an accounting mess, has an awful pension accounting situation, has a little too much debt.... For what's it's worth I thought the consumer and open reach numbers look ok... and business awful. Maybe International is finally going to get chopped. Either way, the plan being laid out, looks and feels like a private equity plan. Id rather these companies did the work whilst quoted personally but I can see why it's not to everyone's liking.
For sure, the trick is getting the mkt to value the FCF not the EPS. Accounting skullduggery or just what Private Equity do all the time? I'll let you decide... but back in the day.... a FCF yield above 8% was cheap.... the increased guidance from £1.3bn to £1.5bn puts BT (LON:BT.A) on 12.5%.... 10% would be150p. Looking further out 2027 is another 33% higher which assuming the FCF isn't consumed by pension and other specific items ! would also be compelling. Between 130-150 and a pathway back to 200 all seems reasonable to me.
On a one day view Allison did a good job. I would argue you are going to see more of this...especially as companies try and harness efficiencies from AI. So it will be interesting from that perspective alone.
French billionaire Patrick Drahi still has a substantial stake in BT i believe, despite his own company, Altice, being a bit of a mess as far as i've read.It was over 24% a year ago.I think he publicly refuted that he planned to cut any of his stake.Fingers crossed the company doesn't get sold under the country's feet like the water companies.This is money article 24//4/24 'Debt ridden Drahi won't hang up on BT'.
Secure Trust Bank (LON:STB) update looks solid. That was another I got from stocko like FUTR that has been an incredible ride on a large holding, mainly exited at 10.80 earlier as went through my target price
Fundementals on STB look strong to support a share price at least double the current value as I see it?
Here's an interesting large-cap for today.
Sage (LON:SGE) makes accounting software. It reports H1 results today, and did quite well. Revenues up 10% (that's impressive!), operating profits up 18%. Yet the share price is down 8.4%.
This, according to BUZZ-UK: "Stifel analysts say Sage's H1 underlying revenue of 1.15 billion pounds ($1.46 bln) came in slightly below consensus estimates of 1.17 bln pounds"
So a slight miss has caused a lot of damage. Mind you, the fwd PE is a hefty 30. It's got a Stockopedia quality score of 92. Returns on capital are 16%, good, and operating margins are around 20%, excellent. I'm just looking at the old figures on Stockopedia.
So, good quality share. The fly in the ointment, I think, is that the free cashflow has barely budged over the last 5 years, coupled with a high earnings multiple.
SGE doesn't appear in Nick Trains top 10 holdings of Lindsell Train Investment Trust (LON:LTI) , but I'm pretty confident it's in there somewhere.
It's been a bit of a rough ride for Nick this year. YTD, the shares are down 7%, against a rise of 8.7% for the ASX (All-Share). Ouch. 15% is a lot of ground to make up. I think the basic problem with his portfolio is not that the companies are of poor quality, but they're not especially dynamic, and they trade at quite high multiples.
Sage (LON:SGE)
- sage was first individual share i bought - back then i thought that any decent share that was down 66% from peak would soon be back at its peak - perhaps if i had known it would take 24 years to revisit the early 2000 highs i might have bouight something else. Hey ho at least it got their in the end.
I would say sage is a dependable plodder - certainly not cheap. Note they have donw quite wll last few years morphing away from perennial licence income sources to more SAS type incoem with monthly recurring fees. Making that transition can sometimes mean pain before the rewards flood in - they will certainly have had to invest alot in the sage cloud offering that is probably now the default basic choice for most rather than the old school sage50 - sage50 is alive and kicking though just about. So i would say if cashflow hasnt been great due to them investing in product development that could sort itself out as user base grows and devlopmnet spend as a % of income drops. unfortunately ref uk acountancy needs hmrc are the worst culrpit here comming up with nonsensical new rules that involve rewriting stuff one would never expect to rewrite. Eg small kitchen fitter now billing customer paying via cis - has to reverse charge the vat - they put the vat details on the sales invoice - but the contractor customer doesnt pay it over to subby - the contractor though must acounbt for vat that they are not paying directly to hmrc whilst at same time then allowing them to claim back the vat they didnt pay - try programming that logic into a 20 year old system easily !
Note when i say a dependable poldder long term any ongoing profit increase above inflation may get the job done - lets come back in 2048 and se if the price is up to 3000p shall we.
Thanks Mark. I was surprised at the large fall this morning given the numbers Sage (LON:SGE) posted. I have bought a few more shares for my portfolio today. This is a high-quality company, in my view.
As for Nick Train, Sage was a top 5 holding in his UK equity fund at the end of April. And he recently said that he thinks the company has 'transformative profit potential' over the next decade.
Quiet announcement from PayPoint (LON:PAY) of appointing a joint broker, Investec. To work alongside existing broker, Liberum.
Maybe its just for the additional shareholder and City engagement...
But maybe they have some acquisition plans cooking, or trying to fend off some advances (they do have a just under 30% shareholder, Asteriscos Patrimonial, who do what they do but in Spain and other countries).
Investec is a bit of an odd choice for a broker? More of a financial advisor maybe, for M&A?
(I hold in the Boon Fund)
Marlowe (LON:MRL) did pretty much the same thing on Monday, appointing Investec as joint broker. Assuming the spin off of one of their divisions goes through, they’re supposed to soon be smaller than they were before. So seems an odd time to add an extra broker.
Like you I’m hypothesising the reasons why.
PayPoint (LON:PAY) Yes, they actually use the expression “Joint Corporate Broker and Financial Advisor “ in their announcement heading.
Vistry (LON:VTY) update today
transformation to partnership model continues, gathering pace. share-buybacks stepping up also
Norcros (LON:NXR)
ok there is the good the bad and the ugly in the new broker note today
https://www.equitydevelopment....
the bad/ugly bit is the inclusion of other non underlying expenses ye 31/03/2024 of £19.3 mill - so pre tax now expected to be £10.2 mill with tax of £8.2 mill (ouch) and proiut after tax of only £2 mill.
On an initial inspection obviuously that looks pretty ugly but the broker note confirms the non underlying expenses include £15 mill non cash charge. So hopefully thats simply adjustment to intangibles-plant and assets ref Johnson Tiles which they are selling to management
so although this looks bad imho its probably actually ok news - they provide details ref disposal and its all fairly neutral - this unit wasnt really making much and is kinda being given away from nowt.
Onto the good they expect 2025 and 2026 numbers to show progress at approx £2 mill pa pre tax undelying basis - for company on pe of under 7 thats ok by me - (cant remember if thats as it was or not)
only had skim read wotha butchers for anyone interested here. Note the fcat the shares have popped a bit and teh p/e is still showinmg as under 7 cofnrims how cheap pe rating was a month or two back - who knows though perhaps it will be back at pe of under 6 again before we know it.
Hi rmillaree - just a reminder that ED is not, and never was, a broker cheers
Norcros (LON:NXR)
Hi rmillaree - just a reminder that ED is not, and never was, a broker cheers
Aplogies for my errror here i had not realised that was the case - i will try and ensure in future i dont make that mistake again.
Out of interest what is your preferred term here if i cross reference info collated by yourselves and put into tehn public domain?
one other question - with regard to the company and when they advise ref market expectations and the like , would the figures you publish be in in alignment normally with what they are saying? or is your stuff outside the scope completely with regard to waht teh company says are expectations ? i am aware if they are not officiually aligned that they might be aligned practicably speaking (by the company ) bearing in mind the company links this info on their website
must admit not sure what the difference is between brokers / analysts or other bucket(s) - time for another life lesson here.
Hope ED replies to your questions…will be interesting.
With reference to the post today by Rusty2 on Metals Exploration (LON:MTL) I can only think as Rusty2 suggests it is related to the RNS on 27 March about the dispute with the minority mezzanine lender runruno over the Interest Rate on the debt.
Metals Exploration (LON:MTL) say it is 7% and the lender 15%. It seems odd as surely the interest rate is clearly stated in the Agreement reached between the parties. I hold a very small position.
A different perspective on Metals Exploration (LON:MTL) ...
It’s had a stellar run, gaining 100% for those who held since late last year or even the start of 2024. Better gold miners (ie in Canada or USA) have not yet reacted in the same way to the gold price.
It’s still a junior miner, now looking to expand into exploration through takeover of YMC by taking out more debt and issue of options (to pay existing MTL directors!), this will likely eat the cash flow from Runruno over the medium term. At this stage in the Gold bull market, producers not explorers are preferred.
Personally, having been a holder since late 2023, I sold into the strength at ~4.7p, missing slight further gain as it peaked at 5.67p. I then recycled into Dundee Precious Metals (TSE:DPM) and Agnico Eagle Mines (Ontario) (TSE:AEM).
Metals Exploration (LON:MTL) may well go on to further gains but as a small cap gold miner that’s high on PI radars, expect volatility!
RBG Holdings (LON:RBGP) Paul highlighted the following on April 30:
Terrible 2023 results, and a diabolical balance sheet. However, turnaround actions have dealt with the main problems, and bank facilities renewed on reasonable terms. So I think there's a potentially good turnaround, possible multibagger here. It is higher risk though, not for widows or orphans.
I agreed with his assessment and bought a small position - rocketing up today (22%) on the back of no news?
Thank you Graham for your positive review of H & T (LON:HAT) - joint broker appointed today:
Appointment of Joint Broker
H&T Group plc, the UK's largest pawnbroker and a leading retailer of high quality new and pre-owned jewellery and watches, is pleased to announce the appointment of Canaccord Genuity Limited as Joint Broker, to work alongside Shore Capital, the Company's Nominated Adviser and Joint Broker, with immediate effect.
Hopefully get in front of a wider pool of potential investors now.
I've held Renew Holdings (LON:RNWH) for 11 years and only continued to add to that position throughout making it my 2nd largest position. In that time UK infrastructure has continued to worsen and requires continual further investment. I see no reason to change my view on the prospects for this Infrastructure Specialist going forward.
RE: Future (LON:FUTR)
I don’t know anything about any impact (bad or good?) from cookies, maybe someone could explain that for me.
Hi Paul
The banning of third-party cookies by Google on Chrome ought to be positive for Future - basically it makes it harder for content management platforms to track us as we browse and then serve us adverts relevant to what we're searching for.
Broadly, any company that already has strong brands online should win from this in two ways. Firstly, they attract eyeballs already, so they're less impacted by the ban than organisations trying to attract attention - basically it will be harder and more expensive for competitors to gain attention and traction. Secondly, as a magnet for eyeballs they now have prime advertising space, and first party data, that's very valuable.
Off the top of my head the likes of Rightmove (LON:RMV), Auto Trader (LON:AUTO) and Trustpilot (LON:TRST) ought also to be beneficiaries. Possibly ITV (LON:ITV) as well. And, obviously, Alphabet (NSQ:GOOGL), whose trove of first person data becomes even more valuable ...
timarr
Good to see you back Timarr, always respect your comments
Agreed Tony Tim is a top poster and great to see him back we just need to find where Wolf of small street is hiding now
Wolf hasn't commented since 20th March after being a SCVR staple. If you are reading Wolf, let us know you are well!
That was the day some posts got removed because of moderation.
Someone else said they were not going to post on here anymore.
Is Stockopedia experimenting with AI?
I did also wonder that Rusty as I've noticed that if someone got moderated and you replied to the moderated post even with something like "i'm having eggs for tea" the reply post got flagged and moderated also.
So same as you I did wonder if it was an out of control bot constantly moderating any replies in a particular thread.
Hi Ben, thank you for the concern , I'm very well. Spending this week on the Isle of Jura where the silence is fantastic.
Just catching up on the week's reports/comments this evening, really pleased to see everyone doing well in much more positive markets.
Lovely to see your name crop back up in here wolf, your contributions/comments have certainly been missed from myself
Enjoy the peace and quiet of God's country
Callum
Welcome back Timarr, I hope you are well, you always have interesting and insightful comments to make, I am delighted to hear from you again!
Google are still delaying the phase out yet again over issues with regulatory bodies such as the CMA and ICO .The earliest seems to be early 2025 now i've read.
Future (LON:FUTR) (I hold)
Hi Timarr
"they now have prime advertising space, and first party data, that's very valuable."
To strengthen this point, here is an excerpt from the results today (emphasis is mine):
"Today, only one third of our advertising inventory is sold directly or through premium programmatic at a yield which is four times the price of the open auction inventory, highlighting the tangible potential growth opportunities.
To drive these initiatives, we need to leverage our brands, leadership positions and our sales expertise.
These are already starting to pay off, with growth in our US yield, supported by more inventory being sold directly, as well as organic growth in US digital advertising in Q2."
Future (LON:FUTR) Apologies if I saw this on Stocko yesterday, but I read in a Guardian link that Ofgem were considering allowing lower prices for new customers in the energy market which will benefit Go Compare which is owned by Future:https://www.theguardian.com/mo...
Future (LON:FUTR) mentioned importance of first-party data in the April update:
https://www.stockopedia.com/co...
It doesn't matter if Google are delaying removal of cookies as big advertisers and players are already making plans well ahead of that. Google keeps on pushing back on removal whereas APPL and other browsers already have implemented.
At some point the CMA (Competition & Markets Authority) will hopefully show strong arm tactics with this frustration and start levying fines on them. Market will eventually work out the importance of FDP with a huge benefit for the likes of FUTR imo.
Reach (LON:RCH) is another major beneficiary of FDP. Amazon announced not so long ago uase of RCH data. No financials disclosed.
Watches of Switzerland (LON:WOSG) Looks like Graham will be getting round to this one, so wait for his more definitive view. Feels to me like a relief rally that things are finally not significantly worsening coupled with the reassurance that the US is still growing. That said, by my hasty calculations, EBIT guidance has been raised slightly at the midpoint of the revenue forecast, expecting £163m vs the past year's £139m. Allowing for some uncertainty, I think the rise of around 10% feels about right.
Good to see an up turn in fortunes for Watches of Switzerland (LON:WOSG. Given the recent acquisition of Roberto Coin (generated $30m Pbt 23) I'm anticipating Fy25 eps to be c45p. Put that on a Pe of 10-12 with improving market sentiment and I have a price target of c500p. Here's hoping!
Goldman Sachs raises Watches of Switzerland (LON:WOSG) price target to 566 pence - Buy
Somero Enterprises (LON:SOM)
Am I the only one who is totally confused about why Somero is hardly participating in the small cap shares moving up over the last few weeks? There's a generational change going on in the US right now. A huge amount of capital is pouring into the construction industry to build out the factories and high-tech plants needed for on-shoring of semi-conductor and green energy manufacturing. Surely, this has to lead to increased demand for Somero's products. Am I missing something?
Somero Enterprises (LON:SOM) l did wonder why it has fallen so much, recently, l know they paid a dividend in April but that does not account much of it.
Hi Gnome2, I don't think you're missing anything re. Somero Enterprises (LON:SOM) The market usually rates it cheaply probably because of the cyclicality of the business and its vulnerability to any downturn in the construction sector which could wipe out profits quite suddenly. The higher interest rates are a drag because the cost of money negatively impacts investments in the sectors it relies on. If / when interest rates start to come down, I would expect to see some moderate re-rating. It's also one where the rating tends to rise in a hot market.
It has been quite a good one to trade cyclically - sell when the P/E ratio starts rising to the higher teens and buying back when it's out of favour.
Personally I think it's a solid business and is one of my longer standing investments. The dividends are decent (albeit we have to give some up in the form of US withholding tax - for those who don't realise, this is a Florida based company listed in the UK).
To my mind it's a steady as she goes investment which will probably get taken over eventually but it's not really the type of company that will ever shoot the lights out.
Somero Enterprises (LON:SOM)
Yes, it's definitely cyclical and I wish I'd traded it more myself over the last few years. It's just the scale of the construction programs taking place in the US right now that doesn't seem to be being priced in. They've seen a reduction in revenues over the last year but I would have thought the outlook going forward must be a lot better. Maybe I'm over-estimating the extend that the company will benefit from the on-shoring, but it does seem to be right up their street. We shall see.
Somero Enterprises (LON:SOM)
Although money is pouring into US infrastructure, there appears to be a lack of drivers to move cement/ready mix concrete.
Buzzi SpA (BIT:BZU) confirmed this in their trading update last week.
My understanding was that this is delaying projects and suppressing any urgent need to purchase a Somero machine.
That should bode well for the company in the long run, but I couldn't see any catalyst for a large jump in sales in the short-to-medium term, which has probably contributed to the weak share price over the last couple of years.
---
On a similar note, I believe that it was Eagle Materials (NYQ:EXP) who stated that they are expecting work for the next 10+ years due to the money being spent on US infrastructure right now, so it's definitely an area I am keeping an eye on it.
A
Somero Enterprises (LON:SOM)
Am I the only one who is totally confused about why Somero is hardly participating in the small cap shares moving up over the last few weeks?
I am confused that anyone would expect Somero to do anything but bumble along on modest valuation - unless they are in sweet spot of upping expectations. imho it has probably spent the majority of the last 10 years on a very modest rating and i would say thats normal service. the fact this is an overseas company and the fact that divis are often paid with us tax deducted and the fact their sector is so niche and the fact it is construction - kinda confirms this is unlikely to be a company that ticks the box for investment inflows that would cause the shareprice to rise - simpler investments elsewhere. Certain companies tend to plough their lonely furough - i have 3 like this the other 2 being Norcros (LON:NXR) (similar but different reasons) and Northern Bear (LON:NTBR) (probably too damn small) - the only surprise to me is that the Norcros (LON:NXR) shareprice has actually popped up a bit recently - not that somero hasnt. If one is lonng term holder it doesnt matter - if one knows that share is unlikley to be up with events much the other option is to seel when price does spike and buy back in whe it reverts to the norm. I remember selling Somero at something like 475p a while back (as it was up with events) only for it to update the next day with a great ahead of expectations update and i could buy back in at the same price - so i bought back.
here's a generational change going on in the US right now. A huge amount of capital is pouring into the construction industry to build out the factories and high-tech plants needed for on-shoring of semi-conductor and green energy manufacturing. Surely, this has to lead to increased demand for Somero's products. Am I missing something?
You are missing the fact that a companies prospects may look at their best at the start of the "surge" - that surge in larger wharehouses has very much been going on for probably 3-4 years minimum by now - demand may still increase perhaps but they have already had this benefit - and the market might very well be looking forward and saying - how many more new warehouses will amazon need going forward if a decent % of expansion has already been done. Perhaps one for further research but i would expect growth in new large warehouses being built yoy is probably already down ona couple of years back even if numbers may be expected to increase still.
It probably doesnt expect that the company themselves expect flat revenues and lower profit - personally in understand that after their purple patch period - but others will likely be saying this company is going nowhere/backwards and to some extent thios year as things stand that is then case.
Somero Enterprises (LON:SOM)
The company tends to swing from single figure PE to high teens over the cycle so I suppose we’re at a lowish point at the moment. The catalyst that I see to move up to a higher rating is the current on-shoring of high-tech manufacturing. The warehouses were related to the boom in distribution centers to service online retail. That seems to be yesterday’s news now. The company mentioned the new factory building in the last outlook statement but it could be that it’s slow in affecting sales for the reasons suggested by abtan above.
By coincidence the Somero Enterprises (LON:SOM) share price starts to rise! I topped up today. Have been in and out of Somero Enterprises (LON:SOM) as the price varies. IMO we are at a mid to low point. I believe there is a shareholder meeting tomorrow. I wonder if there will be a statement like last year?
Graham, H & T (LON:HAT) only wins compared to Ramsdens Holdings (LON:RFX) because it is larger. It would be good if one could turn off some of the selections. I generally disregard the first 4.
Don’t understand all the concern expressed on Stocko of late re demise of UK markets. If Julia says don’t panic that’s good enough for me !
From BBC news:
“The chief executive of the London Stock Exchange has denied it is in crisis despite firms worth hundreds of billions of pounds quitting for the US.
Company bosses have told the BBC that the UK faces an “existential crisis” as big firms have either already left, are considering a move or have been bought by private foreign investors.
But Julia Hoggett said “there’s no sense of panic” as the UK "is already punching above its weight".
A Treasury spokesperson said the UK was "already one of the best places in the world to grow and secure investment" and it was working on ways "to improve the UK's competitiveness further”.
The Chancellor, Jeremy Hunt, will hold a summit of finance chiefs on Thursday to brainstorm how to boost the appeal of UK markets to domestic and international companies.”
easyJet (LON:EZJ) not a small cap but could read across to some small caps. Bigger than expected loss, shares down 6.7%. Has been some good comments about it on here recently. This must be disappointing. I was expecting better, l don't hold but was looking to.
I was a bit disappointed with easyJet (LON:EZJ) i mean losing £350 million instead of £347 million is neither here nor there but they should do better and go for the beat
I guess holidays share increase doesn't help as they are low £60 deposits where flight only is full payment at time of booking but still...
Would be interesting to read Paul or Graham's thoughts if they have time.
I'm holding still and think the potential is great, but what do I know..
easyJet (LON:EZJ) - for what it's worth - They will be adding 6 new destinations from Southend Airport from May next year. No doubt a blip for EZ but a big boost for Southend!
Mid cap Premier Foods (LON:PFD) preliminary results for y/e 30 March: "Full year ahead of expectations" so of course it's currently down by nearly half a percent (I hold). I didn't know there was an Angel Delight ice cream. Lots of brands I recognise. Presentation is on at the moment - graphs where the good money is going up and the bad money is going down. Suspension of pension deficit payments means more capital to spend on capex, M&A and dividends. Lower leverage than the target, which they are happy about. Now talking about different brands, so my mouth is watering. Exceedingly good...
Hi, is anyone awarw of the reason for the drop on Ocean Wilsons Holdings (LON:OCN) ?
XD of 85c today. About 67p. The rest? Dunno!!!
Paul Future (LON:FUTR) are now up 23%, you may want to have a look.?
Why are Stocko prices so delayed, took 30 minutes to move, on the big movers today, this is a common occurrence.
Yes I'm looking at Future (LON:FUTR) now. EDIT: section is now up.
Metals Exploration (LON:MTL) what is happening, shares down around 13% today, this after big falls this week. The interest on debt issue did not look a big problem.
Glad i didnt buy a few days or so ago - not available on t212 for some reason… probably a good thing
Would welcome anyone’s thoughts onHelios Towers (LON:HTWS
noticed two upgrades today
JEFFERIES RAISES HELIOS TOWERS PRICE TARGET TO 158 (154) PENCE - 'BUY'
BERENBERG RAISES HELIOS TOWERS PRICE TARGET TO 195 (185) PENCE - 'BUY'
Costain (LON:COST) Annual report out today and the valuation seems slightly too low. Market cap of about 225m, net cash of over 150m, free cash flow of 72m, net free cash flow of 40m..
Margins improving from 3.0% in 2023 to 3.5% in 2024.
Average net cash position in 4 months to end of April 2024 was 169m, compared to 122m for the same 4 months in 2023 - so no let up there !
Strip out the cash and P/E is less than 2. Stocko likes it. But the market is cautious.
I agree that Costain (LON:COST) looks cheap by any measure, but the problem for me is that they aren’t distributing any of these profits or free cash to shareholders. If they are so profitable then where are the divis? If they need to hold such large net cash balances to fund their business that’s not a great business and suggests that growth is highly cash consumptive. As some point you need to see cash coming back to investors. There may be share buybacks?? But the divi looks ludicrously low for a mature business generating so much cash.
Costain (COST) have a couple of impediments, imo, currently preventing payment of good dividends. They have a pension scheme deficit, which is expected to be resolved over the next couple of years, iirc, by agreed payments from profits. However, if dividends exceed the payment into the pension scheme annually over the next couple of years the pension scheme payment has to increase to match dividends, ie. increasing the dividend becomes proportionately more of a drain on cash.
The other element of the need to keep good cash balances is, imo, the nature of many of the contract award systems in place for the lucrative framework agreements which form a major part of their current and anticipated workload, combined with a recent painful past in their contracting history, and earlier painful periods. The adjudicators of framework presentations / proposals will all be both aware of the recent and perhaps older past difficulties and on occasions excessively cautious, perhaps, so Costain's cash reassures them.
No doubt as the past recedes, the cash builds, and the pension deficit disappears, dividends will improve substantially annually - hope so anyway.
Costain (LON:COST)
Construction is always complex despite the projects often seeming like they are simple repeat what you did on the last job, margins typically low, one error in bidding is a big loss, and as I was taught as a shiny new George Wimpey Group Trainee (1993) cash is king/queen/adjective of your choice! And most importantly Read the FULL Contract :)
So personally other than in the past when I got share options - all now sold, and what I might hold through ETFs e.g. Vanguard FTSE 250 UCITS ETF GBP Dis (LON:VMIG) and pension funds, I only take my salary from the industry and invest elsewhere. Due to my current role these are only generic comments rather than specific, I do not work for Costain or directly manage them day-to-day.
Several factors within here, one thing to ask is average daily cash, not period end - I would assume there will be window dressing.
The other questions to ask are what is upfront payments from Clients, so work still to be done? What is payments from Clients for work done but Costain are still to pay their supply chain? What is the level of disputes ongoing within all the contracts e.g. Costain have got paid by the Client but are arguing what they should pay the supply chain? Basically you need to understand what is money received but still to go out, and what is actually Costain's cash to do what they want with?
The other thing to think about is what is the cost of bidding for jobs, so therefore how much do you need to spend to win, major projects can cost several £million to bid, which is only recovered if you win the job. So things like win ratio need to be factored in too.
Frameworks good, high bid cost, lower margin, but multi-year income. Versus single projects, higher risk but potentially bigger margin if bid right.
Good luck
Tommy
8% jump in Auction Technology (LON:ATG) on no news?
Eh? Half year results on the list for review! Auction Technology (LON:ATG)
WOSG Q4 trading update sales in line with guidance....cautiously optimistic for 2025
May 16 (Reuters) - Watches of Switzerland Group PLC WOSG.L:
Paul/Graham
Appreciate you have a lot of companies reporting today, but would you be able to look at yesterdays results from Vertu Motors (LON:VTU) (I hold) at some point when you have time? I would be interested to hear your views.
Many thanks!
Morning Timbo,
Appreciate you have a lot of companies reporting today, but would you be able to look at yesterdays results from Vertu Motors (LON:VTU) (I hold) at some point when you have time? I would be interested to hear your views.
Seeing as you asked nicely, and your post got 18 thumbs, I'll check it out next :-)
Regards, Paul.
FUTR liked on what seems in line? Rallied sharply into this update. I must be missing something.
May 16 (Reuters) - Future (LON:FUTR) Future :
There are a few shorts still in it so I presume a squeeze. I think the main news was the increased buyback. GoCompare doing well but the rest of business not. It is cheap.
.
I will follow Paul Scott into Renew Holdings (LON:RNWH) :p
Renew Holdings (LON:RNWH) Is that Paul Scott the CEO of RNWH rather than Stocko's Paul Scott?
Diaceutics (LON:DXRX)
Announces 2 new Enterprise Wide engagements for £2.5m ARR with top 20 global pharma.
ARR was already 50% of total revenue, growing really fast.
Strong balance sheet, 80% GM, Family business and large shareholders.
Diaceutics is a family run biz operating in precision medicine. Clients are 21 of the top 30 global pharma companies. Also recently announced it was branching in to Europe and a partnership to sell its services in conjunction with KPMG in the US.
The US values these types of Medtech far more highly than we in the UK.
Unusually for me Stockopedia likes this one.
Results Tuesday
Might be worth keeping an eye on.
Been a holder for a while
Two New Enterprise-Wide Engagements | Company Announcement | Investegate
Michelmersh Brick Holdings (LON:MBH) and M&C Saatchi (LON:SAA)
Both trading in line and both have cash on the balance sheet. Happy to have added the former earlier this week and to continue to hold both.
Positive outlooks from easyJet (LON:EZJ) and TUI AG (LON:TUI) should bode well for Jet2 (LON:JET2) , which in my opinion is a better company, remains underappreciated and which I also hold.
One small comment on MBH; they are making more than they are delivering, for the second quarter in a row, if I understand their comments correctly. They are relying on a modest uptick in demand. Nevertheless a good company.....
My morning smallcap tweet: Declaration of bore
Water Intelligence (LON:WATR) ValiRx (LON:VAL) Redcentric (LON:RCN) Eurocell (LON:ECEL) Quantum Blockchain Technologies (LON:QBT) Diaceutics (LON:DXRX), Secure Trust Bank (LON:STB), Costain (LON:COST), Michelmersh Brick Holdings (LON:MBH), Ilika (LON:IKA), H & T (LON:HAT), Restore (LON:RST), M&C Saatchi (LON:SAA), Auction Technology (LON:ATG)
◄Water Intelligence (WATR)► Q1 rev up 6%. Adj pretax up 8%. In line? [SP=364 Cap=63m]
◄ValiRx (VAL)► gives current cash position after shareholder enquiries - c.£1.1m on May 15. [SP=1.9 Cap=3m]
◄Redcentric (RCN)► guides FY-Mar rev up 15% and adj EBITDA up 16%. Electricity savings lightly ahead of run rate expectations. [SP=144 Cap=228m]
◄Eurocell (ECEL)► AGM stmt - Jan-Apr rev down 6% but cost cuts mean U/L pretax expectations in line. [SP=131 Cap=143m]
◄Quantum Blockchain Technologies (QBT)► first preliminary settlement in Sipiem case. Gives co the rights to "all funds recovered, namely the €700,000 of this agreement and the balance amounting to €5.575m plus interest and augmentation for inflation." [SP=0.97 Cap=13m]
◄Diaceutics (DXRX)► two new enterprise-wide engagement engagements worth £2.5m ARR. [SP=103.5 Cap=88m]
In line: STB, COST, MBH, IKA, HAT, RST, SAA, ATG
Eurocell (LON:ECEL) increase in share buy back from 5 to 10 mil
An in-line update from H & T (LON:HAT) . I hold and will continue to hold. Steady, unexciting, hopefully safe.
An encouraging capital allocation policy from Pantheon International (LON:PIN) , suggesting an uptick in private equity activity, which is good for most of us.
Agreed fully. Have held H & T (LON:HAT) for nearly 10 years and probably returned about 90%. Never going to se the world alight but will compound nicely over time. It’s my biggest holding and would t mind trimming at some point but not at these levels
I like the new News format, you can actually read the document without having to click on the link .
But you can’t read on one page on a phone ? All i get is a narrow strip of the announcement and have to move it around. Am i missing something?
Same problem here - very difficult to read the news updates on mobile.
You can on mobile - Hit "Open in new tab" to see a formatted version of the news
Formatted too wide for my iPad so impossible to read unfortunately -love the idea!
It is fine on my iPad, maybe you need to look in the settings?
l remember changing my settings last year.
Thanks Rusty..Stocko settings or iPad?
Ipad. But actually a few of the larger RNS don't quite fit on my iPad either,
You can report it to Support.
Seems to work better in landscape than portrait for me
Michelmersh Brick Holdings (LON:MBH) in line with expectations
Nearly missed this, there were so many companies in the title and no comments,I thought it was an old report.
Excellent way to start the day, thanks for the effort.