Small Cap Value Report (Thu 16 Nov 2023) - HOTC, CPC, GLE, CMCX, CRST, DX., PRES, LIO, TYMN, KIE

Good morning, it's Paul & Graham here!
All done for today - a mammoth report! I've added some super-brief comments in the agenda section where I just had a very quick look.
Ed's webinar on multibaggers
Wasn't this excellent, last night?! If you didn't manage to watch live, then do check out the recording, which I think the team is planning to email out to those who registered.
I recognised all 10 of the multibaggers from 2013-2023, because we've written about all of them many times here over that period (our archive of SCVRs goes back to 2013). I have to say, it wasn't at all obvious at the time that any of them would go on to become multibaggers. In every case, management just executed very well over the long-term. There's not really any way to measure that in advance, this is the trouble!
However, Ed flagged some fascinating (and surprising!) insights into some of the common traits these multibaggers did possess early on. It's also very encouraging that a lot of the biggest UK multibaggers were mundane small caps on value ratings (at the start of their run), not sexy sectors or blue sky projects (although the £50m minimum market cap would have excluded those).
So the exciting thing is that the next batch of multibaggers are buried somewhere in these reports here & now! Let's hope we can spot them, and have the patience to hold (that's the really difficult bit!)
EDIT: a reminder that I started the SCVRs in 2013. So we have a full 10 year archive of all the multibagging shares. It's quite interesting to look back at how they were perceived before we knew they were going to be multibaggers!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
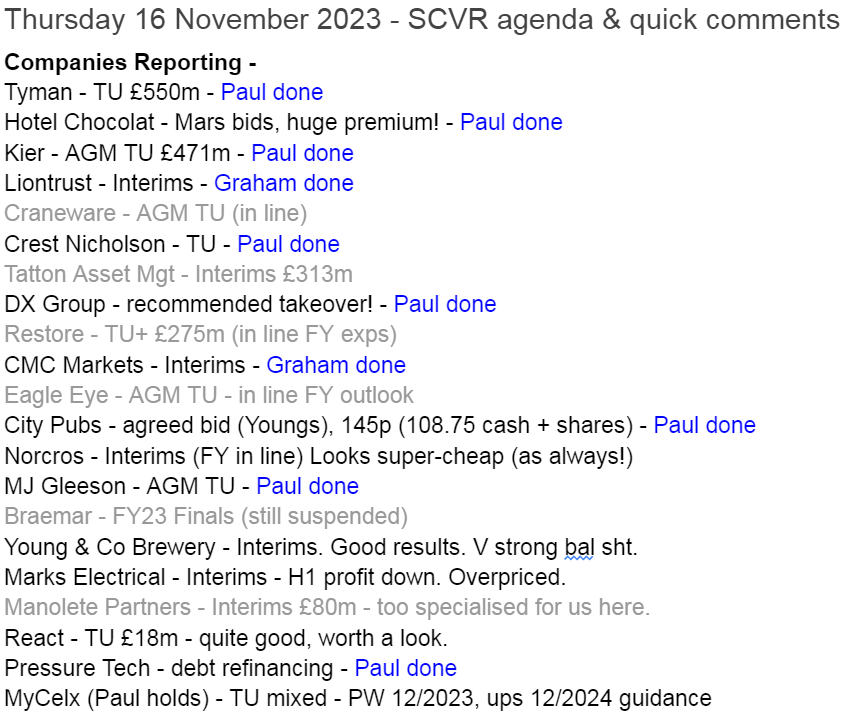
Oh my giddy aunt, have you seen the list today?! We'll get through as many as we can, but it won't be anywhere near all of these -
Summaries
Hotel Chocolat (LON:HOTC) - 139p (£191m) - Recommended Cash Acquisition - Paul
Blockbuster takeover bid at 375p, a 170% premium, from Mars. Congratulations to holders! HOTC didn't stack up as a standalone company, and performance in recent years has been poor. So this is a fabulous outcome, recognising the brand value.
City Pub (LON:CPC) - 99p (pre market) £103m - Recommended Acquisition - Paul
Another takeover bid, from larger brewery Youngs. It's offering a notional 145p, a decent 46% premium, 108.75p in cash, with the balance in new Youngs shares. It's still well below the pre-covid share price though, will that be enough to satisfy CPC shareholders into agreeing this deal?
MJ GLEESON (LON:GLE) - unch 455p (£266m) - Trading Update (AGM) - Paul - GREEN
In line trading update. I crunch the numbers below, and think this starter homes builder looks good for the medium to long-term. More than fully asset-backed, so patient shareholders don't really need to worry about the shorter term macro situation.
CMC Markets (LON:CMCX) - down 0.6% to 94.45p (£264m) - Interim Results (in line) - Graham - GREEN
This trading platform offers unchanged guidance for this financial year and says it remains comfortable with FY March 2025 guidance, too. Client trading is subdued and the company has made a small loss in H1 but I continue to view these shares as offering great value.
Crest Nicholson Holdings (LON:CRST) - down 1% to 187.5p (£482m) - Trading Update - Paul - GREEN
Striking a more cautious tone than Gleeson, this housebuilder lowers the range of possible profit outcomes for FY 10/2023 by up to 10%. Although that seems to be due to one particular problem project. It's trimming costs a little, and build cost inflation has reduced to low-mid single digits. Massive discount to NTAV is a big attraction, along with generous divis. Very appealing to value investors, I reckon.
DX (Group) (LON:DX.) - up 7% to 46.5p (£281m) - Recommended Cash Acquisition - Paul
A takeover bid was already known about, but it's now confirmed at 47.5p + 1p dividend. It's not particularly generous, but logistics companies don't tend to command high valuation multiples normally. A good turnaround has happened at DX in recent years. Although the exit price is way below the IPO price almost 10 years ago.
Pressure Technologies (LON:PRES) - up 7% to 28p (£10m) - Debt Refinancing - Paul - AMBER
This small engineering group today announces completion of a small refinancing by major shareholders which was pre-announced in Oct 2023. Nothing has changed, so no surprises here. I give my take on the situation below, a lot of which is educated guesswork necessarily, due to lack of information on the pending disposal of one division.
Liontrust Asset Management (LON:LIO) - down 0.6% to 94.45p (£264m) - Interim Results (in line) - Graham - GREEN
This trading platform offers unchanged guidance for this financial year and says it remains comfortable with FY March 2025 guidance, too. Client trading is subdued and the company has made a small loss in H1 but I continue to view these shares as offering great value.
Quick comments -
Tyman (LON:TYMN)
Down 2% to 273p (£534m) - Trading Update - Paul - GREEN
Tyman plc ("Tyman" or the "Group"), a leading international supplier of engineered fenestration components and access solutions to the construction industry, provides an update on trading for the period from 1 January 2023 to 31 October 2023
Expects FY 12/2023 adj operating profit to be “in line with market expectations”
*Company compiled analyst consensus of £83.6 million, with a range of £82.8 million - £84.3 million.
Challenging market conditions.
10 month revenue is down 10% (like-for-like), despite price rises, so volumes must be down well into the teens %.
Focus on cost-cutting & efficiency has protected profits well I think.
Strong cash generation (eg reducing inventories)
Net debt expected to be c.1.25x EBITDA by year end.
Paul’s opinion - this looks a resilient performance, given the cyclicality of its business.
I was amber/green when last looking at Tyman, see SCVR 25 July 2023 here. As TYMN shares are now 10% cheaper, and it’s still trading in line, I’m happy to go GREEN for a nice cheap recovery share, that’s also providing a healthy 5% dividend yield whilst you wait. Looks a decent business, worth doing some more research on this one I think.
Kier (LON:KIE)
Down 2% to 104p (£464m) - Trading Update (AGM) - Paul - GREEN
Shares in this construction/property/infrastructure group have been recovering nicely this year. We’ve not looked at it here for about 3 years.
FY 6/2023 results (announced 14 Sept 2023) look good, with £105m adj PBT, up 11%, on £3.4bn revenues. Adj EPS was 19.2p for a historic PER of only 5.4x
Finance costs stand out, absorbing about half operating profit.
Large, complicated balance sheet, with NTAV negative £(132)m.
Today’s update says FY 6/2024 has “started well”, above LY, in line with expectations. H2 weighting expected, same as LY. Re-confirms it intends resuming dividend payments this financial year. Order book is £10.5bn, plus long-term framework agreements.
Paul’s view - not a sector I invest in, as low margin contractors are only one bad contract away from trouble. However, on a quick once-over, I think this share looks appealingly cheap, comes with a nice forecast 5% yield, and seems to be trading well with a decent outlook. Worth a closer look, if you invest in this type of thing. I’ll go GREEN.
Paul’s Section:
Hotel Chocolat (LON:HOTC)
139p (£191m) - Recommended Cash Acquisition - Paul
Stunning news, get out your bunting!
Chocolate giant Mars is bidding a remarkable 375p cash (£534m total) for Hotel Chocolat, a deal which is agreed by HOTC management (who have controlling stakes).
This is an astonishing 170% premium to last night’s share price!
On both fundamentals and share price performance, HOTC has been a considerable disappointment, poorly managed, with failed overseas expansion, disappearing profits, and frequent profit warnings - as you can see below -
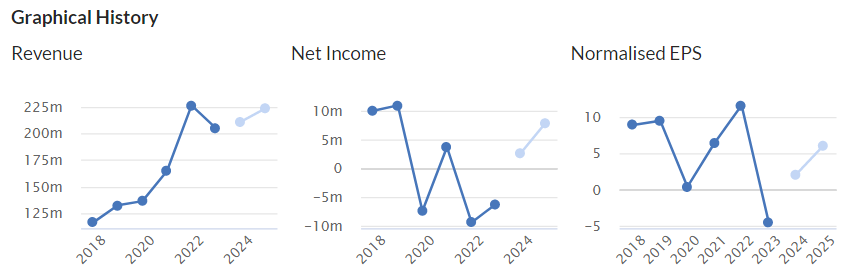
So why on earth is Mars buying it for £534m? It’s got to be for the value it sees in the brand. Properly managed, and with Mars financial strength, no doubt the Hotel Chocolat brand will be expanded greatly.
Mars has long admired Hotel Chocolat's impressive credentials as a contemporary, premium brand with a differentiated product offering, world-class product quality and strong direct-to-consumer capabilities through its physical store presence and sophisticated digital commerce platform.
Paul’s opinion - I’ve been negative in the last year on valuation, and fundamentals, because the figures & performance have been poor. So as a standalone company, HOTC didn’t make an appealing investment idea.
However this takeover bid goes to show that acquirers sometimes look beyond the numbers, and see value in other things, especially brands. So a good lesson learned there, that there can be value in companies beyond the pure numbers.
Hearty congratulations to patient holders here, a sparkling payday has arrived!
City Pub (LON:CPC)
99p (pre market) £103m - Recommended Acquisition - Paul
Another takeover bid!
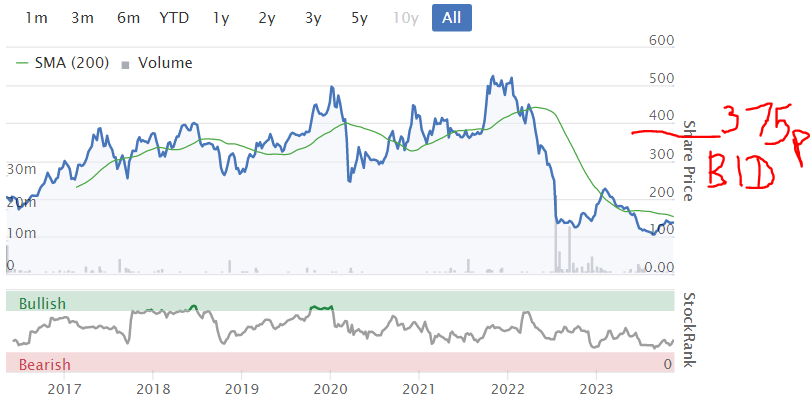
Young & Co's Brewery (LON:YNGA) (market cap: £649m) has agreed with management of City Pubs, to buy it for a notional 145p/share, comprising -
108.75p cash, and 0.032658 new Youngs A shares per each CPC share.
(1,110p/share * 0.032658 = 36.25 pence)
This is a 46% premium to last night’s closing CPC price, which had put in a recent spurt - possibly innocent, possibly some insider dealing, who knows?
Paul’s opinion - coincidentally, we were talking yesterday here about the hospitality sector coming alive again as real incomes turn positive for UK households, and bid interest in the sector after the surprise bid for Restaurant (LON:RTN) .
This bid for CPC reinforces that view, so the whole sector could be in play now maybe?
Will shareholders see a 46% premium as enough, given that this price is still well below the pre-pandemic share price?
Also, the shares element of the remuneration could prove a drag on the price of Youngs, as some CPC shareholders may not want a scrap of Youngs shares.
MJ GLEESON (LON:GLE)
Unch 455p (£266m) - Trading Update (AGM) - Paul - GREEN
Here is the announcement in full, all self-explanatory -
MJ Gleeson plc, the low-cost housebuilder and land promoter, is holding its Annual General Meeting later today at which James Thomson, Chairman, will make the following comments:
"Gleeson Homes has traded in line with the expectations set out in our September announcement.
Net reservation rates for the 9 weeks to 3 November 2023 increased to 0.47 per site per week (0.46 excluding bulk reservations), from 0.43 per site per week during the previous 9 weeks to 1 September 2023.
Mortgage rates have begun to stabilise and, against a more certain backdrop, we would expect buyer interest to pick up into the seasonally stronger Spring selling season.
Gleeson Land has completed the sale of one site since the start of the financial year.
The Board therefore currently expects that the results for FY2024 will be in line with market expectations.
We will provide a further update on 11 January 2024 following the conclusion of the half year."
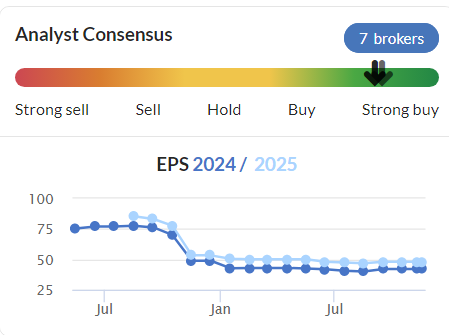
As you can see below, broker consensus has been static this calendar year, after sharp reductions in autumn 2022. So to report in line trading today does reassure nicely that things haven’t got any worse -
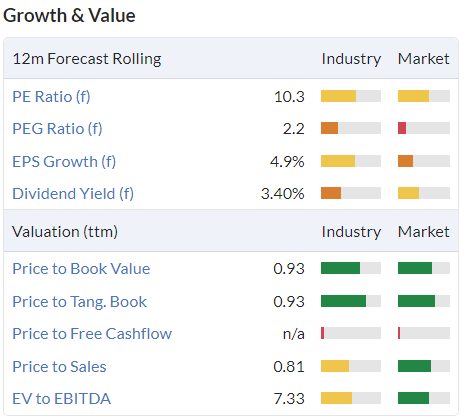
Valuation - the key numbers (below) for me are the PER of 10.3x which seems reasonable, but above all the net tangible asset backing - which is greater than the market cap, evidenced by a Price to Tang. Book of 0.93.
I think the chance of GLE needing to make write-offs against its tangible assets seems low, because its land and work-in-progress are so modestly valued to begin with - due to it building small, cheap starter homes in the Midlands & North.
The product is therefore affordable, which shouldn’t require any balance sheet cuts. A severe recession could change that though, but this seems a low probability scenario in my view.
Paul’s opinion - it’s been a bumpy ride for shareholders in house builders, but I remain positive on GLE (it was one of my 2023 top picks, which have done well in a tough market). GLE is up 32% YTD.
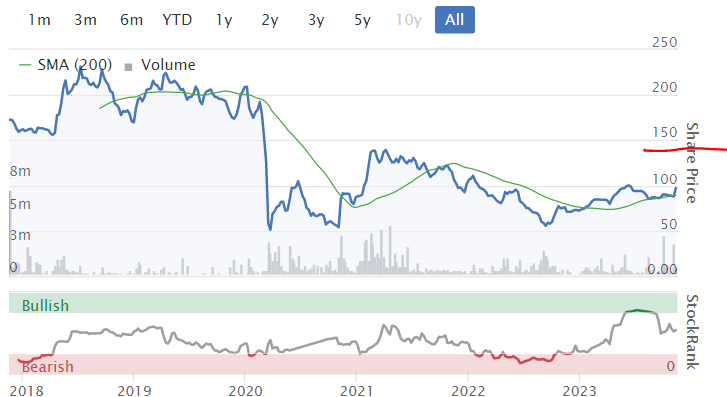
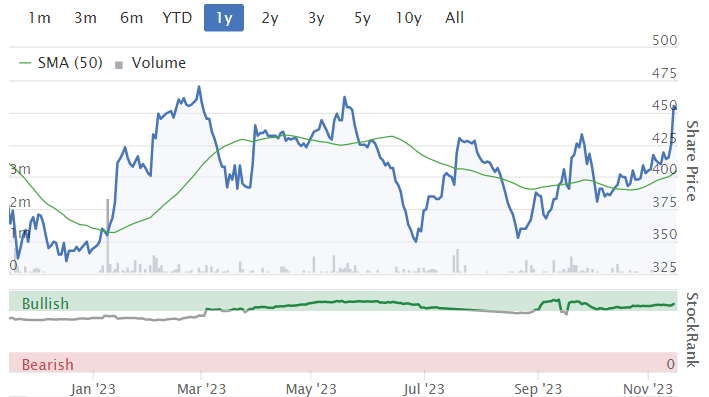
There was a sudden surge in share price yesterday, so we might see some short-term profit-taking perhaps, since today’s update was in line, rather than a beat. You can see below that it’s tended to be range-bound this year at 350-450p, as sentiment on the housing market and macro swings from gloom to hope, and back again!
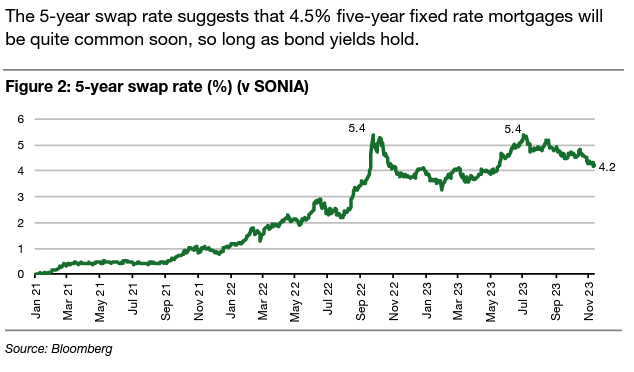
It seems to me that we’ve had pretty decisive economic data in the last fortnight which shows that inflation has fallen most of the way back down, and in election years (UK and USA), there’s bound to be political pressure to reduce interest rates in 2024, which financial markets (eg swaps) are already anticipating. Deals on mortgages have also been getting cheaper very recently. So the tide does seem to have turned, hopefully.
Therefore this seems a good time to be looking closely at cheap, strongly asset-backed housebuilders, and also the wider commercial property sector too, where a lot of shares could have strong recovery potential.
This looks an attractive 5-year chart below, and there’s only been very modest additional share issuance over this period.
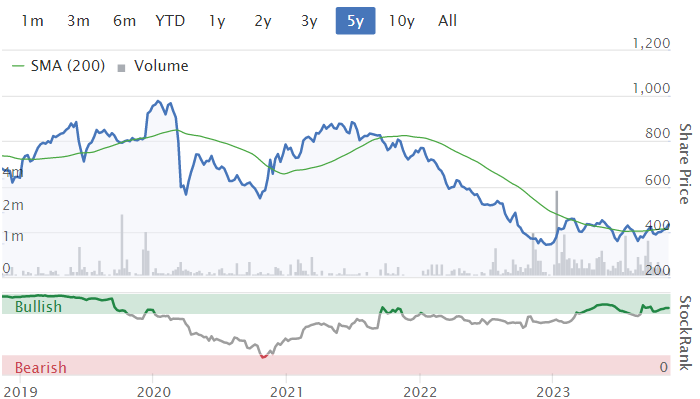
Medium & longer term, GLE shares remain attractive, in my view. Earnings have proven resilient this year, despite all the macro trouble, and it’s more than 100% asset-backed. That’s very appealing to value investors.
A wild card could be more Government support for first-time buyers, which would make sense when the sector is struggling, and would I think disproportionately benefit Gleeson, due to its products being low cost starter homes.
Overall, I remain positive, so it’s another thumbs up. This looks well set up for a medium term recovery - maybe 50-100% upside on this share, with patience?
EDIT: An update note has just come through from Liberum, many thanks to them and Research Tree.
Liberum leaves its estimates unchanged today at 42.5p EPS for FY 6/2024, which is consistent with the StockReport here.
I hope it's OK to copy this interesting graph on interest rate swaps, showing a more favourable driver for (lower) mortgage rates, from Liberum's note, with thanks -
Crest Nicholson Holdings (LON:CRST)
Down 1% to 187.5p (£482m) - Trading Update - Paul - GREEN
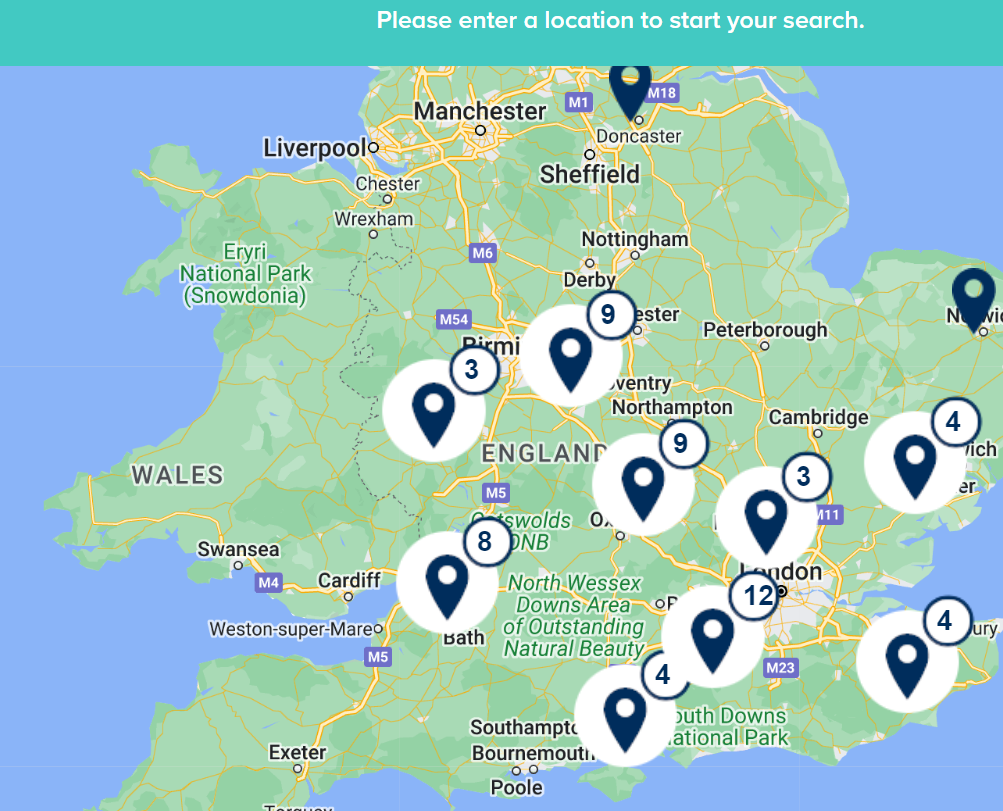
Another housebuilder, focused mainly on southern & central England - its website showing current locations -
.
Crest Nicholson today provides an update on trading for the year ending 31 October 2023 and a streamlining of Group operations for FY24.
This sounds a bit downbeat, if it’s the only positives they can find! -
STREAMLINING OPERATIONS IN RESPONSE TO MARKET CONDITIONS
STRONG LAND PORTFOLIO TO SUPPORT MEDIUM-TERM GROWTH AMBITIONS
Profit guidance - unfortunately, it doesn’t say whether this has changed from previous guidance, so I have to now waste time trying to find out what previous guidance was. It’s so annoying when companies do this.
FY23 Adjusted Profit Before Tax (APBT) expected to be in the range of £45.0m to £50.0m
OK, I’ve found the previous guidance (21 Aug 2023), which said adj PBT for FY 10/2023 was “expected to be around £50.0m”. So today’s update is a fall in profit guidance between 0% and 10%.
Outlook -
We expect the housing market will remain challenging as we head into 2024 with elevated interest rates remaining in place until inflation comes back down to its target level. In addition, the absence of any Government support for first time buyers, coupled with higher borrowing costs continues to impact affordability.
However, there are reasons to be optimistic with year-on-year inflation now halved and real wage growth starting to be felt in households across the UK. We have acquired some excellent sites that are at advanced stages in the planning process, leaving us well positioned to trade in whatever market conditions emerge.'
Problem project - Brightwells Yard, Farnham, had previously incurred a £4m extra build cost (on a zero margin project). Another £7m extra costs is announced today. So what’s gone wrong, this is a material loss. And why did CRST undertake a zero margin project in the first place? The site is nearing completion now.
Net cash is healthy at £64.9m. Like Gleeson, CRST has a superb balance sheet. The discount to NTAV is extraordinary here, with £848m NTAV at April 2023, compared with today’s £482m market cap! In other words, £366m of tangible assets are thrown in for free, which is astonishing. That seems to suggest the market is expecting deep cuts in the balance sheet value of land & work-in-progress. That seems a very extreme assumption. Although I can see that CRST’s locations look to be in higher house price areas than Gleesons, so the write-down risk would be higher than at GLE. Even so, this is a remarkably bearish valuation, that strikes me as excessively cautious.
Build cost inflation -
“is starting to reduce from mid-single digit percentages and we expect this to continue into FY24”
That sounds as if inflation is no longer a worry here, and the wider sector.
Paul’s opinion - this strikes a more cautious tone than Gleeson, but it sounds like the 0-10% reduction in profit guidance has been caused by one specific problem contract.
The main attraction to this share is the massive discount to NTAV.
With profitability still quite robust, despite tough macro, I think this share is well worth considering for further research, and a potential cyclical recovery candidate.
I wonder if the takeover mania will descend on some of the bargains in this sector? With such a deep discount to NTAV, I think CRST could be a sitting duck for a bid. and it has a fragmented shareholder base. Even at a 30% bid premium, a buyer would still be getting £216m of tangible assets for nothing!
Meanwhile, investors who hold, enjoy a 6.5% dividend yield.
This looks highly attractive risk:reward to me. GREEN.
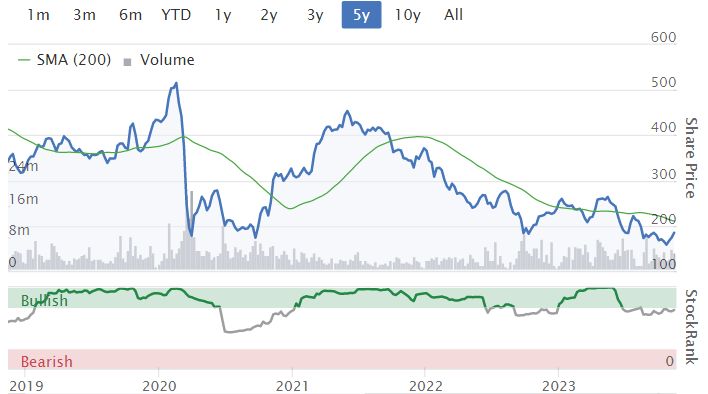
This 5-year chart looks like we're at or near a nice entry point maybe? Note there has not been any dilution over this period -
DX (Group) (LON:DX.)
Up 7% to 46.5p (£281m) - Recommended Cash Acquisition - Paul
Let’s make it a hat-trick - 3 takeovers in one day, remarkable stuff! Anyone doubting that the UK small/mid caps market is cheap, must surely be questioning their view by now?!
The share price at logistics group DX is only up 7% today on this news because we had already been told that a deal was in process.
The takeover price is 47.5p per DX share, plus a 1.0p dividend which shareholders would have received anyway, so it’s not really part of the acquisition price in my view.
It’s a 33% premium to the undisturbed share price before the offer period started on 9 Sept 2023.
Paul’s opinion - I don’t see this as a generous bid. DX has pulled off an excellent turnaround over the last 3 years or so, which we’ve flagged several times here, earlier this year.
Today’s RNS says it has 54.6% support, so this deal looks highly likely to go ahead, I imagine.
Pressure Technologies (LON:PRES)
Up 7% to 28p (£10m) - Debt Refinancing - Paul - AMBER
There doesn’t seem to be anything new in today’s announcement, just confirmation that the deal announced on 24 Oct 2023 has been finalised.
It’s tiny numbers, almost embarrassing that a listed company has to do a special deal to pay off £900k borrowings from Lloyds Bank.
Major shareholders Rockwood, and Peter Gyllenhammar, have lent £1.5m to PRES.
3% arrangement fee, 14.25% interest, and repayable in full when a pending disposal of PRES’s PMC division goes through next year hopefully.
Also warrants (like options) for 1.93m new shares at a strike price of 32p (a premium to the 28p current price). If exercised (at any time in next 5 years, even if the loan repaid), this would give PRES a fresh £620k in cash, in return for a 5% increase in the share count.
For wider read-across, PRES says how mainstream borrowing facilities from normal lenders, were not available. That should make us all shudder if we hold shares in any highly indebted companies that need to refinance any time soon - it sounds as if lending criteria are getting much tougher.
Paul’s opinion - looks interesting, and all eyes are on Rockwood at the moment, which seems to be working minor miracles in the small caps space. I mentioned Richard Staveley’s superb presentation on Mello this Tuesday - a must-watch for anyone who invests in small caps, basically telling us how it’s done! Or at least detailing one strategy which has worked very well, making Rockwood the top performing small caps fund.
I can’t give an opinion on PRES because I don’t have enough information. The key missing info is what price it is likely to get from disposing (if it can sell it) of the PMC division? That would then leave the Chesterfield Cylinders business, which I’ve always felt looked quite good, but has historically suffered from patchy, unreliable performance.
Also, it looks too small to be a standalone listed business, and with 3 dominant shareholders (the above, plus Schroders) holding well over 50%, I think delisting risk might be a little high here.
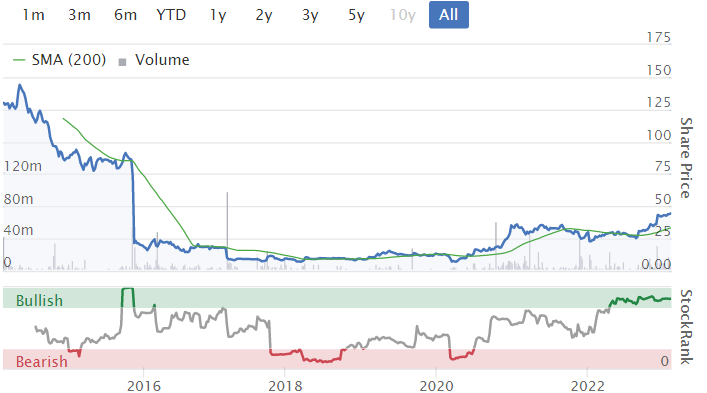
Or they could do something wonderful with it, and the shares could multibag (which they did before, in 2013), so who knows!?
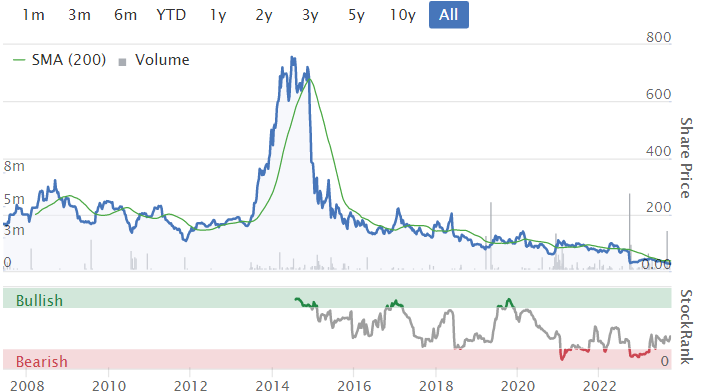
Note also the share count has almost tripled since 2017.
Singers seems to be forecasting a tiny profit in both FY 9/2023 and FY 9/2024. I worry that, with cash also tight, there’s little headroom here for any underperformance.
In a downside scenario, if the big shareholders are called on again to refinance it, I imagine they’re likely to completely screw small shareholders, as happened at Fulcrum Utility Services. So don’t ignore the risks here! That said, at the moment it looks as if the major shareholders are supportive of the share price, so it looks like they want to keep the listing and rebuild the share price.
If you want to read about what caused the huge spike in share price in 2013-14, it's all in our SCVR archive here, I covered this share a lot during that exciting time!
Graham’s Section:
CMC Markets (LON:CMCX)
Share price: 95.4p (pre-market)
Market cap: £267m
This spread betting and forex trading company has published interim results to the end of September.
Disclosure: I’m a shareholder in IG group (LON:IGG) who are competitors with CMC.
Key points from today’s update:
CMC Invest Singapore (stockbroking platform) was launched in September.
Various product upgrades including the availability of mutual funds on CMC Invest UK.
Operating cost guidance is unchanged for the current year at £240m (excluding bonuses). Opex is expected to decline “as projects are delivered and we pass the peak of the investment cycle”.
. And now for the financial result in H1. Sadly it is a small loss:
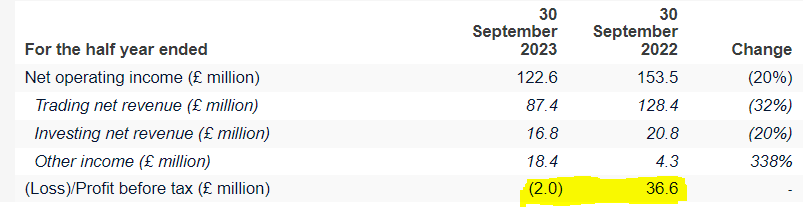
Operating leverage is extreme at CMC, as its operating expenses and net operating income can end up about the same when trading levels are subdued.
On the other hand, when clients are very active, the company roars into high levels of profitability. This is not one of those times.
For investors who can accept the volatility, the good news is that the company tends to have a very strong balance sheet to weather any storm. Own funds are reported today at £273 million, which is higher than the market cap as of last night’s close.
Check the balance sheet for further confirmation of the company’s strength, I see total equity of £359 million. Even if we write down both intangibles and PPE (property, plant and equipment) to zero, balance sheet equity is still nearly £300m.
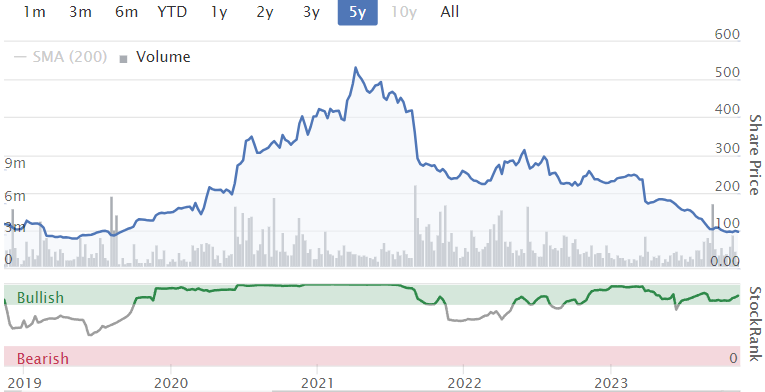
The company doesn’t normally trade this cheaply. The post-Covid slump has brought it here, with the shares down by nearly 80% from their peak:
Let’s go over some of the key aspects of the H1 performance at CMC.
Trading revenue down 32% and investing revenue down 20%: as many similar companies have reported, trading volumes have been very poor this year.
CMC refers to “lower client activity and the uncertain market conditions stemming from the inflationary and higher interest rate environment”.
“Other income” is up from £4m to £18m, thanks to higher interest rates.
I see that CMC’s stockbroking platform currently offers 2% interest on uninvested cash balances, although I don’t believe that there is any such offer from the spread betting or CFD platforms.
Active clients down 7% is no surprise. Revenue per active client also fell by 27%.
Interim dividend is just 1p (vs. 3.5p last year). That will only cost the company about £3m.
Snippets from the comments by CEO Lord Cruddas:
"I am pleased with the resilience the business has demonstrated in the first six months of the year in what has been a tough market environment, with low volatility offering fewer opportunities for clients of our trading business. Despite the subdued market conditions, we have seen continued commitment from our existing clients and positive engagement in our institutional business…
Our technology remains our competitive advantage and we are committed to a disciplined level of continuous investment, however with all that has been achieved over recent years the level of capital investment has now peaked.”
Outlook:
Full-year net operating income of £250m - £280m (versus opex of £240m plus bonuses). This is unchanged from the estimate given in the August trading update.
For the subsequent financial year, FY March 2025, the company expects net operating income in line with consensus forecasts: £302.6m according to CMC’s website.
A cost review is planned for H2.
Graham’s view
I’m a perma-bull on this stock and the share price movement says I’ve been wrong.
We have given this stock plenty of coverage:
August 2023: share price 104p (Paul)
July 2023: share price 147p (Graham)
June 2023: share price 160p (Roland)
January 2023: share price 243p (Graham)
October 2022: share price 222.5p (Graham)
Even with the share price having more than halved since reaching levels where I thought it offered decent value, I think I have to stubbornly remain positive on it.
Analyst consensus figures suggest nearly £40m PBT in FY March 2025 (the financial year starting in five months):
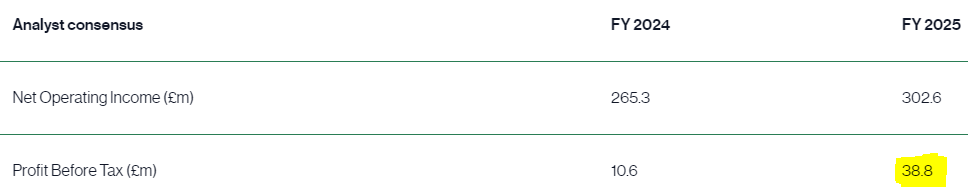
After 25% tax, that would be about £29m of net income.
So that puts the shares on a forward PER of less than 10x but remember that this company already has its entire market cap in liquid assets.
Also remember that in frenzied trading conditions, the company made profits of many times this level. The operational leverage here is key - increased revenues should again drop very efficiently into profits.
Finally, I think the product development here does set the company up very nicely for the future, with a competitive stockbroking platform now available in the UK, Australia and Singapore.
So I remain positive on this one, but I was also positive at over £2 per share so maybe I am just far too optimistic when it comes to this industry! Of course I also think that IG group (LON:IGG) (in which I have a long position) is undervalued.
Paul adds: I agree with Graham! Sure it's going through a tough patch, but the full liquid asset backing at CMCX, and the upside recovery potential on trading make this look very interesting indeed, taking a medium-term view.
Liontrust Asset Management (LON:LIO)
Share price: 584.6p (-3%)
Market cap: £380m
Liontrust Asset Management Plc… the independent fund management group, today announces its Half Year Report for the six months ended 30 September 2023.
This is another beaten-down sector. Liontrust shares are down by nearly 80% from their post-Covid peak:
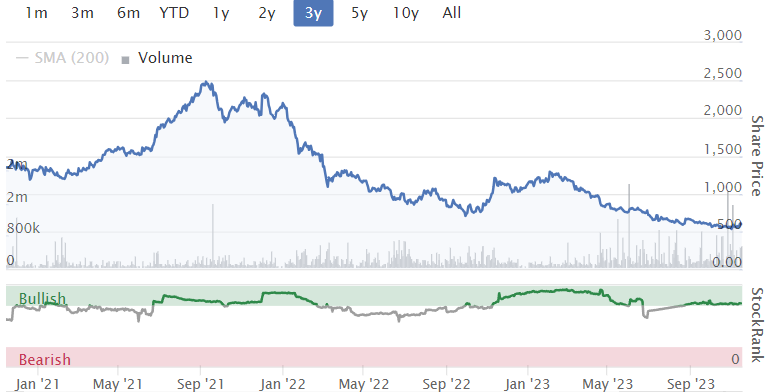
Let’s see what today’s interim results have in store for us:
Adjusted PBT £36m (H1 last year: £43m).
Performance fees were £6m (H1 last year: zero).
Statutory pre-tax loss £10m (H1 last year: profit £14m).
Assets under management fell by 12% over the six month period to £27.7 billion.
Net flows were negative £3.2 billion.
Mostly bad news, as expected.
Let’s spend a moment to reflect on the £10m statutory pre-tax loss. There are £46m of adjustments added onto this to get adjusted PBT.
Last year, there were “only” £29m of adjustments.
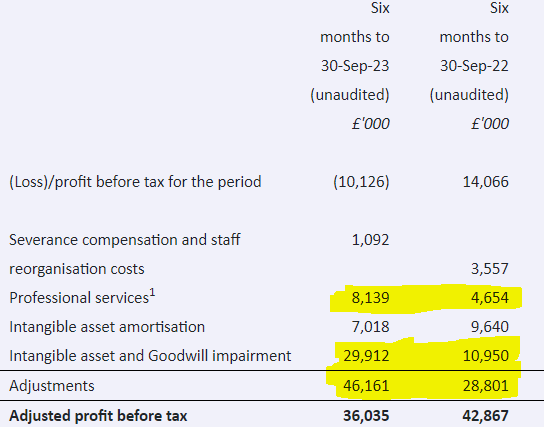
This year, Liontrust made an ill-fated attempt to purchase the Swiss fund manager GAM Investments. Costs for this are in “professional services”.
On top of that, the negative outflows at the acquired business Majedie required about £18m of goodwill impairment. Total impairments as you can see in the above table were almost £30m.
The impairments reflect the loss of value of acquired businesses and so it’s reasonable to treat these charges in a special category - they don’t reflect current losses. But they are still real losses for shareholders, as the goodwill on the balance sheet was supposed to represent the value acquired from previous M&A!
Let’s move on to the CEO’s comments:
"This has been a challenging period for the asset management sector, including Liontrust..
It is in this context that we need to view Liontrust's net outflows and the impairment of recent acquisitions. The majority of Liontrust's assets are invested in UK equities, which is an asset class that continues to be out of favour with investors. UK All Companies was the worst selling sector for net retail sales yet again in September 2023 (with net retail outflows of £884 million), which has been the case for 10 out of the past 11 months.
The impairment of recent acquisitions, which does not affect our net cash, reflects the sentiment towards UK equities, especially among institutional investors, which has negatively impacted the funds and mandates we inherited from the acquisition of Majedie Asset Management.
He goes on to outline various company developments and initiatives, saying there is particular focus on international distribution. I can only imagine how difficult it must be to make sales into Europe at this time.
The Chairman aptly remarks that “no company enjoys linear growth over many years”. He also points to Liontrust’s focus on the UK market, and on small and mid caps. And he defends the attempted purchase of GAM.
Graham’s view
I have said before that the entire fund management sector looks undervalued to me, and Liontrust is one of the cheapest in the sector.
Investors at the current share price get £73 of AuM per £1 invested in Liontrust stock.
In September 2021, AuM was £35.7 billion and the market cap was £1.3 billion. So you only got £27 of AuM per £1 invested in Liontrust.
So the AuM is not far off three times cheaper now than it was two years ago.
Of course the fear is that AuM will just keep falling, with the combination of outflows and a mid-cap market that is slow to recover.
While I do think that Liontrust shares are too cheap, it’s not my top pick in the sector by any means. I’m not sold on the company’s “Sustainable” investment strategies, which stretch the meaning of the word “sustainable” to the limits of credibility. Overall, Liontrust is not very well differentiated, in my view.
Also, their main response to adversity has been to attempt expansion through M&A. Would it not make more sense to simplify and to become as lean as possible, instead of adding more fat? Today’s impairments suggest that prior acquisitions haven’t worked out particularly well so far.
However, I do think that the company’s difficulties and mistakes are probably all priced in at the current level. All they need - and all we need! - is another bull market. A change in sentiment could see a tremendous recovery in the valuation here.
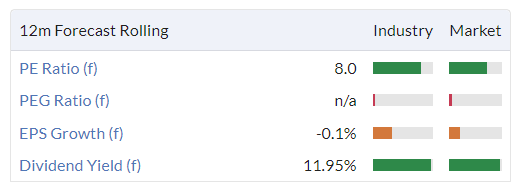
If you’re willing to accept the adjustments as being one-off, the company has just generated £36m of underlying PBT in six months. That’s in terrible market conditions. At a market cap of £380m, how can it not be cheap?
For what it’s worth, the company also has an NCAV (net current asset value) of £85m, with nearly £100m of cash and equivalents. Perhaps it should ultimately be acquired, instead of always being the acquirer?
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

124 comments
Tatton Asset Management (LON:TAM) - video recording of post-results Investor Presentation ***
Tatton Asset Management ran viewers through highlights of the period to 30th September which included strong net inflows and growth in revenues & profits, with adjusted operating margin hitting 50.7% - far above any comparables. Management provided a financial review and outlined the significant growth potential going forward. With strong tailwinds they detailed the opportunities and challenges around M&A with price expectations remaining high, while highlighting their organic growth in market share. An in-depth summary of investment performance was followed by questions from viewers. Full video here:
?si=4iIAz0oK8FD6W8AXPerhaps been covered here before or not.
MaxCyte (LON:MXCT) up today on Crispr Therapeutics AG (NMQ:CRSP) 1st ever CRSPR technology approval (revenue sharing agreement with Vertex Pharmaceuticals (NSQ:VRTX) and it happened in the UK too.It's a 'one and done 'treatment for sickle cell disease.It's not officially FDA approved in the US yet but has had a positive Adcom meeting, when the share was halted and positive Adcoms tend to correlate very strongly with FDA approval.
Perhaps under the radar and not profitable yet company.They're similar to Oxford Nanopore Technologies (LON:ONT) and Illumina (NSQ:ILMN) in the US in the fact that they are not a pharma/biotech company but produce the nuts and bolts equipment that pharma companies use to develop new drugs etc... And have development and/or revenue sharing agreements with a big range of pharma companies, particularly in the genetic engineering space.
MaxCyte (LON:MXCT) have revenue sharing agreement with Crispr Therapeutics AG (NMQ:CRSP) for both development and royalties.They have a US lisitng which gets more volume as usual with non profitable, revenue growth companies.
It was a popular 2021 investment and i do believe Cathie Wood owns some (good or bad ... make up your own mind!) and was growing revenue nicely pre inflation and biotech market slowly.Also the US stock listing gives it a huge advantage in terms of liquidity and the willingness of the US market to support biotech and non profitable companies, unlike the AIM, obviously.Anyone else holding?
I decided to go for a punt.Last earnings weren't great due to the general biotech market (Spdr S&P Biotech Etf (PCQ:XBI) .But the share price recovered fairly quickly.
I have held Crispr Therapeutics AG (NMQ:CRSP) for a couple of years now. I think it has huge upside potential mid-long term. I topped up recently after watching the Adcom meeting. I am confident in approval from the FDA at the start of December, although I think that is mainly priced in after the recent 50% bounce off the lows. Very volatile but multibagger/buyout by vertex but possible. Let's hope gene editing becomes the next AI and we make a fortune. Good luck.
Just a quick comment to say fair play to Paul on covering so many companies today.
I have no idea how you find the mental bandwidth. But just to let you know, in case it was ever in doubt, that we do appreciate all the efforts you, and Graham and Roland, put in.
That's very kind, thank you Jeremy! It was pleasing to get some positive feedback from you, just before I reward myself for today's work with a pint of Stella, and some fish 'n chips at my local 'spoons (I'm a recent convert!), The Mary Shelley (she wrote Frankenstein apparently and is buried underneath this particular branch of Wetherspoons) :-)
P.S. When I finally hang up my keyboard, maybe they should bury me under the local branch of Revolution Bars?! (guilty secret, I've just bought a few RBG shares yet again, as a complete punt, after watching the mgt webinar).
There's particularly high volume today (and up around 9% as I write) in Revolution Bars (LON:RBG). It may have been struggling a bit lately but I do think that there could be interest in £175m of sales at a sub £10m cap (+ debt of around £20m). I can See Rob P seeing this through to a sustainably profitable, if unspectacular business. The Peach deal could well prove to be the turning point.
Peach (trading well) could be sold to eliminate most of the bank debt, in downside scenario. That's probably why Nat West is so comfortable, and the only covenant now is minimum liquidity. So if this works, the upside all flows to equity. May not work though, so higher risk. I think it's not bad risk:reward, so I've gone back in at 3.6p. Chance of a zero? Maybe 0-20% at a guess, if Xmas is a disaster. Chance of a 2-5 bagger? Quite good, if it does well over Xmas, and consumers spend now real incomes are turning positive. Risky! Not for widows or orphans.
Mystery shopper report from 'spoons (Mary Shelley branch, Bournemouth) this afternoon after earning my stripes doing the SCVR -
Meal deal no.1 - Guinness and turkey Xmas dinner - absolutely bloody delicious! Total cost £15.50 including table service, and no tips.
Meal deal no.2 (I was hungry!) £12.01 for a cheese salad (also delicious, but small) and a pint -
It's 'spoons every time for me now!
Quick check on my latest investment on the way home - Revolution Bars (LON:RBG) (I hold) was empty-ish, but always lovely staff, happy to have a chat. Banks have relaxed covenants, just a minimum liquidity one now, and Xmas bookings up, so if they do OK over Xmas & NY, it could see leveraged upside to the tiny sliver of equity (£9m) maybe? Mgt saying that 76% gross margins mean big operational gearing once 18-30 age group start spending again. It's risky, could go either way.
Eating in 'spoons?? You should have been on the pier with Mary:
https://www.bbc.co.uk/iplayer/...
Don’t forget Paul the excellent Spoons on the waterside at Poole Quay. By far the most attractive location for any Spoons I have drank in.
And, many thanks for your superb work, enjoy your beer
£500m~ or w/e is pocket change to mars. i'll point out that it's been 100+ years at this point, and none of the (mars) family have felt the need to go public with the business
i don't think people realise how dominant they are; it isn't just chocolate, they have a stranglehold on chewing gums & pet foods as well
Thanks for your kind words RE the webinar, everyone. You can find a recording and the extended slide deck in a separate post here.
Leaky trading update from MJ GLEESON (LON:GLE) today given the SP rose on "no news" yesterday? [I hold]
Leaky trading update from MJ GLEESON (LON:GLE) today given the SP rose on "no news" yesterday? [I hold]
I agree that yesterday's surge in GLE was a bit odd. But today's update was only in line, so it's difficult to pin the blame on insider dealing!
Lots of housebuilders went up, yesterday because of inflation figures.
That smallcap bounce was very short lived!!
You'll always get a little profit taking when some shares are up 30,40,50% in 30 days. A few days weakness is fine as long as long as markets don't roll over again. Best part of the year so if there's to be a rally with proper legs you'd expect it in the next 2-3 months.
"Wasn't this excellent, last night?!"
Yes, it was very enlightening.
"I have to say, it wasn't at all obvious at the time that any of them would go on to become multibaggers. In every case, management just executed very well over the long-term. There's not really any way to measure that in advance, this is the trouble!"
I think that this is a good case for diversification. You need to have a good selection to pick up the ones in the "long tail".
It seems that one should keep things very simple and get lucky. It is something I have been pondering since the Algy Hall webinar, although I haven't had a chance to read his book. I do plan to, though. Simple criteria such as avg ROE>= 12.5%, Interest cover > 7, reasonable PE (say under 19), minimal share growth (keep annual compound under 3%), and a 5-year annual revenue growth rate of 5% over the last 6 years. Look in the small-caps for a simple business with a long runway.
"However, Ed flagged some fascinating (and surprising!) insights into some of the common traits these multibaggers did possess early on. It's also very encouraging that a lot of the biggest UK multibaggers were mundane small caps on value ratings (at the start of their run), not sexy sectors or blue sky projects (although the £50m minimum market cap would have excluded those). "
Also, one surprise worth mentioning is: don't sweat the operating margins. Some of the companies are in low-margin businesses. I heard an interesting comment from a fund manager some time ago. He said that he liked investing in value companies because they often became growth companies.
So perhaps one should hold a diverese range of businesses and hold forever unless there is serious deterioration like debt getting out of control or product obsolescense.
Food for thought.
Urgh, I've written so much already today, and I still have more to say. Time for a nap, though.
That is three agreed takeover bids in one day and 22 that I have counted in the last month. At this rate there will be no decent companies left on the market to invest in by the middle of May when our next investor conference is scheduled to take place so make the most of Mello London on the 29th and 30th November as half those companies may not be around for the next one....and that is actually a serious comment.
All these bids are not good for the long term health of the markets unless really good companies replace them and that means growth company IPO's at sensible prices not the dross that jumped in following the pandemic.
For those who want to join us at the end of the month there are some really good companies and funds to meet and watch presentations amongst these https://www.stockopedia.com/co...
Lots of Stockopedia friends to network with too.
David
LON:CMCX - this is ripe for a takeover bid I reckon - any thoughts
You are not wrong. Look at DOCS (I hold from this morning after watching the Webinar last night).
CMC Markets (LON:CMCX)
this is ripe for a takeover bid I reckon - any thoughts
unless there is soemthing we are missing here it may at fisrt sight seem almst a complete no brainer (if we use current price). For example igg could buy and they instantly get own funds amounting to the amount paid - so its kinda like they would be giving the business away for nowt other than the hassle of handing over then cash - presumably they could extract wad of that cash out if it wasnt needed in regulatory sense (it might be like that mind !!)
To me the main risks here are the black box element of what they do lined up with regulatory risk and risk of fraud/theft - i have to believe the money that matters believes there is a non zero chance of this company being wiped out in stroke with funds either being confiscated (money laundering issues could be enough) or counterparty risk - they are due in £184 million from "brokers" so there must be potential for something nuclear to happen in that regard or they could be hit by fraud or theft. Although they minimise chances of owt happening lets not kid ourselves it doesnt happen that what should have been there vanishes in a puff of smoke once in a full moon with listed companies.
Despite above concerns i would be happy to invest modicum amount here at current prices - the company has kinda been around long enough to prove itself by now in my eyes (i hope !!)
CMC Markets (LON:CMCX) Robbie has just informed us that he has bought some and also mentions takeover potential.
I dipped a toe in gently.
Tatton Asset Management (LON:TAM) the second asset manager I've looked at today. I need to go and look at some other industry now!
Far better results than Liontrust Asset Management (LON:LIO) that I looked at earlier, though on a completely different valuation to reflect that. Only really appear to be struggling in their mortgage division, though even then doing better than overall market. On my watchlist, though higher price than I want to pay at the moment. Management being stingy with precise guidance as well for results I've looked at recently.
Tatton Asset Management (LON:TAM) flying compared to all in this sector. Better growth, better margins. Does command a premium valuation as you say.
Burberry (LON:BRBY) in the doghouse dotay. Shares are down 8% as of writing, but they were nearly down 10% earlier on.
Operating margins down from 19.5% to 15.9%, which isn't so good. The CFO is confident of returning to 20% margins "in the medium-term", though. The news sources note: "were on track for their biggest one-day percentage loss since the height of pandemic-driven selloff in March 2020, after the company said it was being hit by a global slowdown in luxury spending."
I don't own any shares in BRBY )thankfully), but I'm keeping an eye on them out of curiosity sake.
BRBY products are popular in in China, and I feared that sales may have been clobbered there due to economic difficulties. It seemed to do OK, though. "Mainland China comparable store sales increased 15% in the half. Q2 fell 8% as spending shifted offshore with the Chinese customer group growing 25%". That surprised me. The actual disappointed came from the Americas.
BRBY now trades on a forward PE of 14, which seems OK for a good-quality business. I guess everything depends on if you think there's more pain to come.
It doesn't surprise me too much that BRBY had taken a dive this morning. In France, Louis Vuitton took a dive earlier this year, a sign of things to come. Diageo (LON:DGE) also dropped heavily not all that long ago, another sign that luxury brands are still economically sensitive and not an automatic right to print money.
What's a bit funny was that Nick Train had an interview earlier this month where he highlighted both DGE and BRBY. He expressed hesitancy of naming names because - famous last words - as soon as he mentioned something he risked it bombing. Sure enough, here we are. Oh well, it happens to the great and good, so we shouldn't be too hard on ourselves when we make what looks like in hindsight to have been obvious gaffs.
It will be interesting to see how this plays out. It's too early to tell, but DGE doesn't seem to be clawing back the fall it made earlier this year. We may need to wait a month or so to see whether the market shrugs off the drawdown. So maybe we shouldn't expect an immediate rebound from BRBY. It's worth keeping an eye on both charts, I guess, to see if sentiment changes for one, and then maybe anticipate a change for the other. Maybe wait and look for signs that analysts are becoming more positive and upgrading their estimates is a good way to play it.
Anyway, I'm invested in neither, but it's an interesting enough story to follow.
Well the only thing that matters to me is price, and it's done sweet fa for 10 years. Unless someone is selling above 22 and buying under 13 then it's been a waste of time.
Burberry (LON:BRBY) tends to track other luxury stocks with lower momentum, but with bigger swings in either direction owing to its poor diversification. As a long term investor, I wouldn’t touch it with a barge pole when I can own LVMH, Hermes and Ferrari, having picked them all up during market volatility. Burberry is the same price today as when I bought all three, interestingly at different times. None were attractively priced, let alone cheap, by UK standards at buy point. Meanwhile they are all up 80% since.
Burberry is a good trading stock only and anyone who thinks otherwise is kidding themselves - and that includes Nick Train.
Braemar (LON:BMS) - would be good if this could be covered by Paul or Graham. My take on a quick skim of the results and annual report (filed on their web-site) is that the restatement is not a particularly big deal and that no further skeletons have appeared. Outlook is good. Suspension should be lifted, maybe tomorrow, and we can see the markets reaction!
And as someone mentioned yesterday a decent dividend to come to boot.
Good morning Paul
I have been investing since 2016 and the SCVR has been a great learning tool for me. I didn't become a paying subscriber when the SCVR went behind a paywall, as I'm extremely tight. However, listening to your excellent podcasts has inspired me to become a paying subscriber. Keep up the fantastic work. Your analysis and insights are second to none.
I would say though, that you don't always practice what you preach. It sounds like you're very highly concentrated in Plexus, which strikes me as your typical story stock. RNS's since September have included:
Looks to me like the RNS's of a typical momentum trap (as per the Stockopedia style). If the tech is so good and the contracts so valuable, why hasn't Schlumberger just bought the company, it would be pocket change for them?
Appreciate you've done loads more research on this company than me and it wouldn't surprise me to see the share price continue to rise. But why put all your eggs in this one speculative basket when there are loads of other quality growth companies on sale at a discount?
Ed
Edward I wouldn't worry what other people are doing, better to just concentrate on making money your own way.
There wouldn't be much point to this discussion board though wolf of small street if everyone followed your advice
Sale of treasury shares below market value ; therefore one can assume that the people managing the company do not believe that it is worth more-and my question is :
Who has bought these shares?
Plexus Holdings (LON:POS) (I hold) - it actually sold some treasury shares at 20p recently, which was the market value at the time.
Plexus is very much a special situation, not a regular investment, hence why I don't mention it here much, as it will (understandably) look too speculative to most people here.
Hi EdwardJW,
Thank you for your kind comments, and I'm delighted you've rejoined Stockopedia, great stuff :-)
You're right, I definitely don't always practice what I preach!
I like special situations, and after doing a lot of research, I've decided to take a risk on Plexus Holdings (LON:POS) - definitely not for widows and orphans. For me, the upside potential far outweigh the downside risks.
It's absolutely not a "typical story stock", quite the opposite - look further back, and you'll find a profitable, cash generative company, with proven technology, that was valued at a peak of £300m in c.2015. Then the market fell away, and it's had a 7-year hiatus. Demand is now returning, with major industry & environmental tailwinds, which is what excites me. FY 6/2023 figures due out soon will show another c.£4m loss, but a major £8m contract which falls into FY 6/2024 is forecast to move it into (small) profits.
Finances are precarious, although debt all paid off, but mgt own 59% hence have stoically resisted dilution, and want to keep the listing (brings big benefits when dealing with global oilcos).
It's speculative for sure, but has already 10-bagged, and if the bull case plays out, I think it could 10-bag again. That's why it's my biggest holding.
Proven technology is the key point. Major contract £8m won. Operational cash burn now stopped. CEO determined to support it because he sees good times ahead. High risk, could go wrong. Mgt won't sell it unless someone (Schlumberger?) make a knockout offer - bear in mind mgt didn't sell when it was worth £300m. Methane leaks from O&G sector fast becoming THE environmental issue, as USA & now EU legislate to reduce methane leaks. Plexus is sitting there with proven tech that prevents wellhead leaks. It's not blue sky, Plexus products have been in operation for years, eg in North Sea, and have never leaked, the CEO claims.
I'll cover it properly when the next results come out shortly. Lots of downside risk, for sure. But the upside is really exciting I think. Time will tell, as always!
Might be mistaken ; but something in the back of my mind tells me that the management tried to sell this for about £30m but nobody was interested.
Might be mistaken ; but something in the back of my mind tells me that the management tried to sell this for about £30m but nobody was interested.
Sounds like you might be getting muddled up (again) with the sale of IP to Technip a few years ago. The non-compete clause has since expired, and Plexus (I hold) has re-entered the market with improved tech & new patents.
Muddled up again!
Thanks and good luck with your new investments.
Paul, I understand the investment case and I think the share is probably more likely to double from here than go zero.
But why go so concentrated on something which is still speculative? Why not put in 25% of your portfolio - still a very sizeable position - rather than the 60%+ it sounds like you're in for. Sounds like poor risk management to me. Buffet is an advocate of a concentrated portfolio but also advocates using Kelly criterion for his position sizing I believe.
Wolf of Small Street, yes I will/do. But if we all only commented on stocks we're personally invested in then it would be pretty boring. I'm more open to bear arguments on my stock picks and investing style than bull arguments. I addressed to Paul because he has given me pause for thought on my own stock picks and investing style, so I just wanted to pass on my concern.
Are you angling for a job as his personal financial advisor :-)
Hi EdwardJW,
- rather than the 60%+ it sounds like you're in for.
Where did this come from? I've never disclosed what % of my portfolio is in Plexus (I hold). It's nobody's business. My money, my choice what to do with it. Same with everyone.
I feel you're crossing a line with the above, so let's change the subject.
Thanks, Paul.
I thought you said on one of your podcasts that your portfolio was mainly Plexus at the moment.
Fair enough. Didn't intend to cause any offence.
The webcast last night was excellent though I will have to study it on more detail when the recording and deck are available. Thank you Ed.
I personally think that being on the end of a 10 bagger let alone a 100 bagger is as much about EQ as anything else and having the patience to hold. As well as having a bit (.5% of portfolio?) in several potential 10/100 baggers and then sitting tight. That said I think it will be a rare person who sees his £10,000 investment go to £50,000 in say three years who doesn’t top slice as a minimum. With hindsight it might look silly but at the time it would surely be good portfolio and sizing management.
In the dying seconds of the webinar I posted a comment that attendees might find the research by Alter Fox Capital of interest:
The Makings of a Multibager.
They examined every stock over $150m mkt cap, whose TSR greater than 350% in the five years to August 2020. It makes interesting reading.
https://static1.squarespace.co...
Regards
Michael.
A slightly tongue in cheek reply to your comment that “ I think it will be a rare person who sees his £10,000 investment” given there are also female investors on here and in multibaggers ;-)
I’ve held Games Workshop (LON:GAW) since 2015 and haven’t felt the need to tinker/trim apart from occasional small adds. I also held Burford Capital (LON:BUR) from 219p to c1900p (for the avoidance of doubt I certainly don’t get them all right and have had several stinkers including PAT & STU). Women can be decent investors too so I hope we are as welcome on here as men
But AG everyone here knows that you are a rare person. :-)
But in seriousness if it hadn’t been for a state of madness in March 2020 I would have held Games Workshop (LON:GAW) since Jan 2018. I sold the last part in March 2020 and started repurchasing in the July of the same year. Even with that blip it has been very good holding. 33% CAGR for the first period. The second is less exciting but still profitable and at the moment I can see no reason to sell.
Regards
Michael
Hi AstonGirl, can I ask, do you use stop losses? I'd be interested to know your style. I'm never going to get a 10 bagger as I'm too impatient, just my personality, but always interested in others experience.
Me too - been on some biggies over the years -left too early .Although best ever was in 1999 Atlantic Telecom Warrants ,paid 10p and sold 140p ...I'm living on past glories LOL !
You should be on a beach in Mauritius Saarf with that kind of winner not lurking on the small cap bulletin board with the rest of us.
Yes I do use stop losses. I realise that they’re controversial but they’ve got me out of some potentially large losses such as Trackwise, SCE & TRMR. On balance they work for me
*I did suspend them though during the 2018 fall and Covid dip as the falls were across the board
Patience is something I too need to work on….
Robbie Burns believes women ARE better investors!
Some years back HL looked at there client database on a male/female basis. They reported that only 15% of clients who were active investors were female but that the female clients outperformed the males by quite a bit. The only difference HL could identify was that the female clients traded a lot less. In other words the males cant resist fiddling and it is costing them money.
Pressure Technologies plc
I will appreciate if anyone knows the company well enough to provide us with some inside ; especially the value of their proposed division that is up for sale and any future numbers on revenues and operating margins.
It’s not every day that major shareholders are willing to pay 20-30% over market value for new equity.
Thanks
According to Staveley, PMC (the division earmarked for sale which is profitable) is worth anything from £3m-£10m. Difficult to predict future numbers because their contract wins, especially in the defence sector, are so lumpy. I think with PMC gone, costs are streamlined and they will focus on building up Chesterfield which has over 100 years of trading behind it and seems to be one of only a few world wide participants in this field.
Apologies in advance to those that dislike anecdotes from the larger cap space, but notable I think this morning that engineer Spirax-Sarco Engineering (LON:SPX) came out with a mild warning and the share price has hardly budged - and it's not exactly on a cheap rating. Similarly, Halma (LON:HLMA) is not exactly shooting the lights out and it's up a fair bit. Says something. In my eyes, a lot of our bigger (in a UK context) engineering businesses could get easily swallowed by still larger groups. In the current market, with all the takeover activity, it feels like there is some sort of floor/option value on the price of all but the worst quality stuff.
Spirax-Sarco Engineering (LON:SPX) Halma (LON:HLMA) In the current market, with all the takeover activity, it feels like there is some sort of floor/option value on the price of all but the worst quality stuff.
Well, they were 10% cheaper only a week or so ago! Caustic comment aside, the valuation of these is often misunderstood as simply too expensive. They and Diploma (LON:DPLM) fell hard at the start of inflation/interest rates to a point where they now have for some time been tracking the valuation of comparable diversified industrial quality compounders across the Atlantic. Ametek, Idex, Graco etc are essentially all the same buy and build proposition diversified across similar industries in the same economies. Niche products that perform a mission- critical role in the processes of secular growth companies, typically in the semiconductor, medtech, life science, oil and gas or energy transition fields. If you make a comparison today they are all on an EV/EBITDA of 17x falling to 14x over two years. Yes, they’re expensive compared to other industrials, but their earnings are historically more reliable and almost constantly growing. They look fairly valued if you have a transatlantic lens, if only because the valuations are so uniform.
Rockwood Strategic (LON:RKW) has done very well for me. Harwood are, in my view, really the only consistently successful show in town in the small cap space these days. They are opportunistic and are taking advantage of the small cap market in bad times (taking private) and good times (relisting companies such as Ten Pin and numerous health companies in Covid times).
I'm glad that I made an exception to my rule of not buying equities that don't pay a dividend for this, Oryx International Growth Fund (LON:OIG, North Atlantic Smaller Companies Investment Trust (LON:NAS) and Odyssean Investment Trust (LON:OIT) - all have performed very well and have much better stock selection ability than myself and most private investors. They know what they are looking for and if its not going to plan then they roll-up their sleeves and put someone into the company to sort it out.
I would go as far to say that I think that Christopher Mills is probably one of the best UK small-cap investors over a 30 year timeline..... if you look at the compounding returns of North Atlantic Smaller Companies Investment Trust (LON:NAS).
Both Richard Staveley of Rockwood and Christopher Mills are at the Mello London event at the end of this month so you can meet them personally. There will be some great speakers and presentations https://melloevents.com/mltick...
CMC Markets (LON:CMCX) price tends to respond really well in relation to forecast earnings. Personally I'd wait for a break of 102p but can see why people like it around current prices.
Norcros (LON:NXR)
Tailwinds have definately ended here as these h1 results are behind last years on most metrics (uk underlying profit was up though just wooo ) - factoring in the slowdown in their core uk market the uk results have actually held up ok - albeit probably aided for the fact that grant westfield only turned up 2 month into the 6 month period - they were nonethless record undelying operating profits in the uk. South Africa have had internal issues that have affected profits here - hopefully these issues will subside and i have no reason to believe sa profits cant bounce back.
looking beneath the bonnet as ever (when they dont have acquisitions) cashflow is excellent and ndet debt is £12 mill down on prior year debt at 1 * ebitda is more than manageable (i would be happy if they were buyiong back shares en masse at present)
ref the elephant of the pension issue - good progress here again - pension is still in surplus (per acounts) and amount has shown slight increase over prior periods. I tend to look at present value of scheme liabilities - if this figure keeps trending lower that confirms that future obligations are on the wane in real terms in todays money (note cash outflow may not have peaked yet) - in that regard figure is at what i think is a record low. I suspect high inflation flatters this figure but this is super mature pension scheme and the trend is clear this figure is down 44% since 2017 - so many peeps may not realise practicably speaking this issue is much less an issue than it was back then - even if the cash outflro to pesniion may not suggest that fcat.
present value Scheme liabilities at 31/3/2017 was £467 mill
present value of Scheme Liabilities 30/9/2023 was £260 mill
To me the higher this number the more their "scheme assets" need to generate "inflation matching" which aint easy - the lower this number trends the more comorftable i am that the future cash outflows are likely to come down in line with this figure (note thats very simplistic as short term cash outflow payemnst top pensioners may still be going up/staying stubbornly high short term)
All other warts and all wil be found by reading the update - i am still happy holder after this update.
Re Norcros (LON:NXR) - I also thought these decent results. Profits held up even as revenue fell back, reasonably blamed on contraction in UK RMI/new build markets and in SA load-shedding. This supports the claim to be moving to a better business (adhesive closed, eventually the tile business will close completely!). This bodes well for when (surely, eventually......) the UK housing building and RMI market bounce back.
In the meantime, cash generation means scope for more related acquisitions - heavily hinted at - steadily diluting the pension problem and increasing the scale/one stop shop story. Organically, they have a good rate of NPD, growth opportunities like House of Plumbing and seem to have scope and a plan for cross selling brands. I think they will beat current revenue forecasts for 2024 and 2025 absent complete melt down. Current forecast is further quite significant volume reductions. There is a 6%+ divi whilst we wait.
My only critical concern is that their competitive advantage and increasingly good margin structure (for a boring manufacturing business) is based on excellent sourcing in China. Any trade issue there (Taiwan?) would be a disaster. What's their plan B.
During Covid, the China links were a strength. In a geo-political crisis, I worry. I have raised a question on this in the InvestorMeetsCompany webinar coming up.
Net, £NXR is cheap, should be cheap - but may be too cheap. I certainly hope so.
Norcros (LON:NXR)
My only critical concern is that their competitive advantage and increasingly good margin structure (for a boring manufacturing business) is based on excellent sourcing in China. Any trade issue there (Taiwan?) would be a disaster. What's their plan B.
I think their competitive advantage is deliverance - i am guessing their large customers (there was specific comments loing these lines- ref Wickes, Topps Tiles and Screwfix) - probably get great convenience from dealing with the various norcros brands if they know they get the same t&c's , product reliability (to the best extent possible) etc from what norcros do. If their products work and are reliable and margin would be same with other stuff they obviously are kinda delivering - albeit organic grwoth has often been slightly aneamic - i was slightly shocked that thneir product vitality index was at over 25% ((proportion of turnover from products launched in the last three years) with standout launches in the period including)) - i would have guessed the issue might be that they didnt change with the times - they clearly do without makinag song and dance - albeit thats probably partly necessity not to lose out to better evolved cometitors - it does give me confidence though that their stuff is reelvant . Note this stat may be meaningless as it could be easy to fiddle - if teh new is the old with nut in a different place.
I would like to think the sourcing they have backup plans for - perfect question to be asked of the company rather than leaving for speculation , so great that you have sorted cheers - they must have learned soem leassons from supply chain issues over last 2 years. The reality is their planning was such that i think they may have had less issues in that regard than others perhaps - semi speculation on my part albeit that seems to tie in with your comments. I would agree over reliance on China is probably silly if that is where they are at - as long as they dont replace China for production for Taiwan thinking that is diversification if you know what i mean !!!!!!
Hey ho maybe one day this will get to p/e of over 10 and reward long term holders. In the meantime i have on odd occassions reinvested soem of my divis back into more holding - self imposed buyback type stuff.
One item on my wish list would be buyback "biggie" while current shareprice is in the gutter - silly paying 10pe for acquisition with equity when p/e they have is 5 - aleit even then they can bring stuff to the table. Cashflow is that prodiguous i am not against some extra short term debt in that regard,
A disappointing end of the road for DX (Group) (LON:DX.) which gets bought out at 47.5p (they say 48.5p but the 1p went ex div today anyway and has been deducted from the price).
Sold off far too cheap at just the wrong time in the market cycle in my view. All the hard work turning around the last managements mess was done and the business has a good clear road ahead so a pity shareholders won’t get any benefit of that.
With regard to the ex div date I can see that it is shown in various places as 16/11 but on the announcement it says that the div will be paid to holders on the register on 17/11. So if I sold my shares today I don't think I would receive the dividend?
Paid to the registered holder on record date but as soon as it goes ex dividend you should be entitled to it. Ie if you sold today the company will pay the dividend to the purchaser of your shares but they will in turn be responsible for paying that on to you after they receive it.
Best to check and confirm with your broker but that’s how a corporate action is supposed to work where ex dividend date and record date are different.
hi TS23
DX (Group) (LON:DX.)
The xd date is today 16/11.
For future reference, the xd date for all company dividends is always on a Thursday and the record date is always the following day.
The xd date is the one to focus on as regards being the first day of trading in shares ex-dividend.
Snazzy
Thank you for the write up on CMC Markets (LON:CMCX) Graham and for Paul's thoughts. I've stubbornly held onto this one, reinvesting the dividends. It is making all the right noises about future plans and expansion. Hopefully when the markets pick up this get up towards the 150p mark.
ECO Animal Health (LON:EAH) - I've held twice, firstly for a long time making a decent (albeit could have timed better) profit when Peter Lawrence was chair and secondly more recently, where I sold out for a very small profit on reflection on the minority interest point below. They have just done a very good capital markets day presentation (several hours) on their R&D programme that you should watch before investing. It's impressive. I have it on my watch list.
Despite liking the company I have one major concern that is not addressed to my liking. Most of their product is made in China and that is also their most profitable end market despite being very deprssed more recently. Unfortunately, they only own c51% of their Chinese subsidiary and so the vast majority of impressive headline profits is not actually theirs but a minority interest. Look at the EPS number at the bottom of the income statement for last year and you will see that most of the group's profits disappear to the minority interest. There are also restrictions on getting cash out of China, albeit they seem to manage that well. I'd be a buyer if this was not the case as they have some impressive IP but the product will continue to be made in China and therefore profits to shareholders somewhat diluted.
There will also be no dividends as the positive cash flows are being invested in the R&D pipeline for at least the next 2 or 3 years.
The bull case is that a larger company might buy them. Their pipeline is undoubtedly worth much more than the share price, so they remain a takeover target at the £2-3 level, I would say. But that has been the case for years. Maybe that was the point of the Capital Markets Day to be more transparent on the black box!
Another point I'd like to pick up from Ed's webinar yesterday ...
Looking at company meetings is a a good idea. The one I quite like is IMC (Investor Meet Company) https://www.investormeetcompan... It's not got an extensive list of companies on its roster, but it's worth checking. Companies will often give any meetings they will hold in their RNS. I'm vaguely aware of some other company that does a similar thing, but I don't think it was as good as the IMC site. They also store past meetings, so that it worth checking out.
I guess one problem is that it is far too easy for some people, like me, to be swayed by the CEO arguments. Other people may be more hard-headed than me. I like the narrative approach of the meetings. I have only seen a few meetings so far, but I have found them to be pitched right and informative. I haven't seen one yet that made me want to run to home as quickly as possible like Charlie after finding a golden ticket to Willy Wonka's factory.
You can often learn snippets about other industries, too. I saw the presentation from BLND (British Land) yesterday. Commercial property is something everybody seems to hate right now. The shares are at some of the lowest levels in 20 years. I mean, we all know the narratives, right? A nailed-on recession, Just Stop Everything, interest rates killing the property market, global boiling, Brexit has doomed us, and so on. We may also have heard about how badly Silicon Valley is right now, with office vacancy rates of 30%. I mean, good grief, if the tech capital of the world is imploding, what chance to we have here in overcast Blighty?
I'm not trying to sell the investment case for BLND (although I have a small holding), I'm just illustrating why things are not all doom and gloom.
BLND has some really good property in London, with actually good occupancy rates. Things like "last mile logistics" are in demand, especially in London. These are distribution centres in urban areas. They do "the last mile" to get goods to where they need to be.
The company didn't virtue-signal its woke credentials, but said that many many companies are seeking offices with high enivronmental ratings, and that it is able to satisfy client demand. Large space with good transport access and amenities are prized. BLND mentioned a large law firm that was seeking office space.
It also highlighted the demand for "tech campuses", you know, where high tech companies want to set up shop. I won't be able to find the Twitter reference now, but Britain is still one of the top tech countries. Imagine that!
The world doesn't stop and go into cyber-hibernation just because there's a recession. Companies still think strategically ahead, and invest accordingly. That's worth remembering.
Does anybody have an insight on ECO Animal Health (LON:EAH) ? I notice Schroders bought another 1% yesterday to take their interest up to 16%. It's exactly the sort of niche, cash rich high quality business I would like to own with international sales and on the face of it a huge runway. But the forecast earnings are so paltry! I just can't get my head around the numbers...
I held this for many years but unfortunately failed to take my gains and ended up taking a loss after exiting following one of their many profit warnings. I should have noted that the directors had a cracking track record for awarding themselves large options and selling en masse immediately they matured! They are heavily dependent on their main drug Aivlosin which seems an excellent product and keeps gaining new indications and territories. The main swing factor for the price (and for the Genus share price as well) is pork prices in China. These have been on the floor lately but the share price usually responds well when these start to move up.
Thank you Tiger Blue
According to my books, ECO Animal Health (LON:EAH) is an undervalued stock. It reached a high of 680p in 2017, with a PSR of 7.0 . Its average PSR since 1997 has been 3.03 (currently 0.87). In addition, its average PBV since 1997 has been 2.42 - it currently has a PBV of 0.89. Should this stock revert to the mean, it has the potential to advance significantly. I hope this helps. I hold.
Equals (LON:EQLS)
I may well be putting 2 and 2 together and coming out with a far greater total than 4 BUT. . .
http://newsfile.refinitiv.com/...
Equals have changed their Nomad with immediate effect this morning to Cannacord, who are known for their expertise in take overs :-)) . Maybe a possible sale is on the cards or perhaps its just because Equals felt the original 'up for sale' RNS was badly worded by the previous Nomad .
Had the same thought myself but put it down to wishful thinking (I put 2 and 2 together and made 175p!) Time will tell.
;-))
I don’t think there is anything significant to read into it. Cannacord were appointed joint broker in March. Peel Hunt, who were joint broker with them, have been ditched.
Talking about brand value, could Superdry (LON:SDRY) appeal to someone? Mtk cap £41m
Liontrust Asset Management (LON:LIO) half year results out. Not looking that great, though no drop in share price so far, maybe it's all discounted for already? Loss making at the moment due to large administration expenses from acquisitions and restructuring costs. I would appreciate peoples view on this?
Sound quite confident going forward, as most of the asset managers do, just waiting for sentiment to improve. I do note that Stockopedia estimates for full year revenue have been cut from £220M last time I looked to £188M now. (I hold)
Good morning Phil, firstly thanks for sharing your 'snapshot' summaries, I like the traffic lighting and note there's not much greenery for Liontrust Asset Management (LON:LIO) although I'm personally green on the dividend yield in the circumstances [I hold].
Liontrust rose on the tide with nearly everything else last week and if it stabilises above £6 then this may be a sign that the worst is over, nothing was said this morning that came as a shock and therefore perhaps previously priced in, but I was hoping for some sign that net outflows were abating. The recent SP rise is nothing to do with LIontrust performance therefore and more to do with macro and sentiment which probably backs up management's soothing (optimistic?) outlook.
I'm no expert on charts, perhaps Wolfie can comment more expertly, but if Liontrust's 1yr SP chart were a ski-slope the skier would be running out of momentum and wondering how to get back to the top. I notice also that aside of a flirtation at the time of the GAM exit the recent break above the 50 DMA is new territory for 2023.
I look forward to more of your snapshot reports over time.
TEIN
Morning Tein, thanks for the comment and the positive feedback. I agree with you on the dividend, very nice indeed, though I'll only put something as green if it is improving revenues or profits, hence no green today :(.
Yes they do seem to be struggling with outflows, more so than some other asset managers I believe. Though as you say when the markets turn positive I have no doubt the share price will start rising. I love your ski slope analogy, lets hope the skier has some poles. I'm quite positive on the chart, waiting for it to rise above the 150MA (purple line) and break resistance, I'll buy more when it enters the green box. Previous, poorly timed buy at the yellow circle. Will sell if it falls below 500.
Ski poles? Feels a bit more Eddie the Eagle at times!
I recently opened a small position in Liontrust Asset Management (LON:LIO) , thinking 'it couldn't get much worse' and that the dividend was an attractive distraction. I'm mostly a long-term holder in this type of company, but decided to offload it at a small loss today as the story looks increasingly grim and worse than my initial assumptions.
I broke my cardinal rule here, only to buy after good news, but got sucked into the recent momentum. Thankfully it was a tiny/starter position.
Todays results could certainly have been a lot better. I was expecting more of a fall today, which makes me think we are likely at or near the bottom with this share, but who knows.
Following the staggering HOTC bid premium I have dipped a toe this morning into Fevertree (LON:FEVR) . Again this is a stock that never looks cheap but it is a great brand and one that could easily attract attention and a significant premium on exit. Directors have also been buying here and the venerable Nick Train is a big supporter.
Fevertree Drinks (LON:FEVR) I don't currently hold but agree Tiger Blue's comment re brand, in UK eyes at least. Does anyone know if the brand attracts a premium rating in the USA?
I half expected it to feature in last night's excellent webinar.
I hold. Entered at 800, followed it all the way up, reduced the other side, then the traded sideways period and reduced again late 2022 but bought back too early. If only I could restrain my urge to buy the dip while the knife's still falling.
Has many of the features covered last night - simple, scaleable, low capital as effectively IP (moat) with manufacturing outsourced. Constraints on ingredients and bottles must be receding, so operational gearing should see cash and ROCE rise to previous levels.
Has many of the features covered last night - simple, scaleable, low capital as effectively IP (moat) with manufacturing outsourced. Constraints on ingredients and bottles must be receding, so operational gearing should see cash and ROCE rise to previous levels.
Assuming you’re talking Fevertree Drinks (LON:FEVR), why can’t I ever buy some in my local co-op? It’s constantly out of stock. Are they still struggling with distribution?
I suppose the minute the bottles reappear is my buy point!
Sorry, yes Fevertree Drinks (LON:FEVR)
Well I never expected that!
I hold Young's non voting shares, which are in my view the best way to invest in the company. The only difference between the voting Young & Co's Brewery (LON:YNGA) and non voting shares Young & Co's Brewery (LON:YNGN) is, to quote Andrew Hollingworth, that one doesn't get tea and biscuits at the AGM. In other words the non-voting shares as the name implies don't carry a vote. In all other respects they are equal to the voting equivalent, dividend entitlement, NAV etc. The non voting shares trade at a £2/£3 discount to the voting shares.
At last night's close the voting shares mid-price was £11.10 versus £8.50 for the non-voting equivalent. This morning Youngs have announced an interim divided of 10.88p and an NAV of £12.50. I will leave you to decide the merits of the two share classes, but I know which I prefer.
City Pub (LON:CPC) has agreed to be acquired by Youngs on the basis of :
Under the terms of the Transaction, each City Pubs Shareholder will be entitled to receive:
for each City Pubs Share: 108.75 pence in cash (the "Cash Consideration")
and
0.032658 new Young's A Shares (the "New Young's A Shares")
Based upon the Closing Price of a Young's A Share of 1,110 pence on the Last Practicable Date, the Transaction represents a total implied value of 145 pence per City Pubs Share, valuing the entire issued and to be issued ordinary share capital of City Pubs at approximately £162 million.
City Pub (LON:CPC) is certainly a good fit for Young and is stated as being earnings enhancing in the first full year of ownership. I haven't yet delved in to the detail in terms of how the proposed acquisition will impact NAV, but it increases debt in the short term, albeit Young's free cash flow is robust. Homework to do.
Rockwood Strategic (LON:RKW) I also hold Rockwood as mentioned yesterday and surprise, surprise City Pub Group is one of Mr Staveley's holdings. Harwood holds just over 5% of the company. What they will do with the Young's shares assuming the acquisition goes through we will have to wait and see.
Further on Rockwood Strategic (LON:RKW) I note that the funding of Pressure Technologies (LON:PRES) has completed and the latter has redeemed its Lloyd's bank loan. Again I hold Pressure Technologies (LON:PRES) . Despite the less than generous cost of funding from Messrs Mills and Gyllenhammer this is a positive outcome, I believe.
I agree a positive for Pressure Technologies (LON:PRES) , you have to think if the CMC is disposed of then the remaining Chesterfield business will be an attractive acquisition target for a larger engineering company . Rockwood have also taken a stake in Pennant International (LON:PEN) (I hold) a higher quality, higher margin business (in my opinion) that is also in the defence sector.
A critic in the past but major shareholders willing to take equity at 32p This should at least trade at this price…..
'one doesn't get tea and biscuits at the AGM'
I don't know if this is still the case after the death of John Young, but all Young's shareholders used to be entitled to unlimited beer at the AGM. There existed a dedicated band of supporters who owned a single share for this reason.
Tempted to pick up a few shares
HOTC a good example of why it's dangerous to be short small caps that have already taken a beating.
Unless you can get a guaranteed stop (which is unlikely a lot of the time) you're wearing a big risk.
Thank god I couldn't get a short on when I tried a couple of times as agreed with the recent write ups on here it felt overvalued.
It had rallied 40% fairly recently and i wondered why somewhat and had maintained its market cap too and not sold off.I looked at it just yesterday but thought i had a fair while to buy in if i wanted to!The chocolates are nice but pretty pricey.
Shorting small caps full stop is complete madness. Way too risky, nobody here should be doing it, in my opinion. As you correctly say Michael, a takeover bid at a big premium is a massive risk.
Lucian Mears told me that he once had a short on something he was convinced was about to go bust, at 1p per share. It then put out unexpected good news, and spiked up to 31p.
Something similar happened to another friend, who shorted a Chinese fraud, which was then suspended. He was forced to close the short at a price named by the Chinese fraudsters, and they relieved him of a small 7-figure sum I believe.
I shorted Thomas Cook a few years ago, when it was obviously about to go bust. It spiked up from 5p to about 14p, and I was forced to close the short at a heavy loss, and it went bust shortly afterwards.
It's a nightmare area, where even specialists get hung out to dry every now and then, so not worth taking the risk. As the old saying goes, the worst you can lose is 100% on a long. On a short, the potential loss is unlimited.
Oops ..I feel you've extracted a confession LOL ! I DO short small caps but I always use guaranteed stops - although the platforms usually have a limit that reduces the risk/reward. I learned the hard way....
I have also lot a packet on shorting small caps. In almost all cases i was right that they were basket cases but ig index in many cases will shut the short when it spikes up, locking in a massive loss. If the company goes bust they do not pay out for several years. I have one that is still not paid out 3 years after it went bust.
Yes thats right. Also the spread bet cos often raise margin to 100% when a share is suspended. Ive had to stump up loads of extra margin when a co went bust, and had to wait 3-6 months
Ah, I remember that on Thomas Cook. The Turkish businessman Neset Kockar.
I thought it was a big ramp and he'd exit into the liquidity he created, but turns out he 1) actually believed in the company and 2) couldn't read a balance sheet. Which was odd given his career.
I've had some success (and some failures too) shorting small caps but that was mainly last year when there was still a lot of hype in the market and the wheels had yet to fall off.
Very different risk/reward now.
I see yet another successful exit in the Richard Staveley portfolio (City Pub (LON:CPC) ), i've lost count of how many he is had in the last two years, he really is the best at engineering takeovers in the small cap sector.
If the full value of the brand asset can only be realised with the scale and expertise of the Mars corporation, shouldn’t the price paid for Hotel Chocolat (LON:HOTC) reflect this dynamic? Paying 40x FY26 earnings makes little sense to me given the balance of the negotiations, notwithstanding the attractiveness of the brand and its value to the acquirer. Hats off to management I suppose!
Market is littered with such examples. Look at TP Icap (LON:TCAP) for example. Bought Liquidnet for some similar earnings metric whilst they themselves traded on a PER of 7 or 8. Needed a heavily discounted rights issue to do the deal and much shareholder value transferred to the Liquidnet shareholders as a result.
In Mars case I suspect they want the Hotel Chocolat (LON:HOTC) brand and feel their marketing might can transform its international prospects. Given it is management held they were never going to get away with a cheeky bid but whether this deal ends up as a vanity project with growth anemic Compared to expectations who knows. It will probably just get buried in the group accounts if it does.
Reminds me of Coca Cola paying a big price for Costa Coffee. I don't care how the buyer does because I don't own them. What I want to know is who is next?
EDIT: mentioned below are
Fevertree Drinks (LON:FEVR)
Superdry (LON:SDRY)
Equals (LON:EQLS)
A lot of others have been mentioned recently and I made a Folio of them. Does this link work?
https://www.stockopedia.com/po...
Then there's sector consolidation, and I wonder about the Housebuilders where mergers might release under-rated surplus capital, and the Fund Managers with potential for consolidating (ie: cutting) fixed overhead costs.
Michael C the link isn't working for me.
Here's the list in Excel. I'm not recommending anything here, I just kept a note of other people's ideas about possible takeover situations. Doesn't seem to have been much use for predicting actual events so far!
Nice list Michael- I produced something similar for my own research. Many heads etc . and there are some fundamentally cheap Cos. on here. Cannot believe Hotel Chocolat (LON:HOTC) premium !? average is usually 30/40%
You could add Just (LON:JUST) that is why the shares have gone up recently. One foreign company looking to buy in that sector. The health sector has seen quite a few takeovers in the last 2 years. Ergomed (LON:ERGO), Dechra Pharmaceuticals (LON:DPH) and Emis being just 3. Emis is very obvious to me.
I had a thought today that Marstons might be a target at some stage. In the low interest rate environment there seemed to be some interest in heavily indebted pub chains with a decent asset base.
Obviously a decrease in interest rates and a revival in property valuations wold help.
Not a great fan of Marston's (LON:MARS) - but it might be worth monitoring for speculative T/O .
Norcros (LON:NXR) "Overlooked and undervalued" - initiation report
Norcros has leading positions in its market segments built upon strong brands, new product development, channel diversity and supply chain strengths. It is seeking to drive further market share gains organically by intensifying group synergy benefits and through M&A activity.
H1 results saw an 8.3% reported group revenue decline (or -4.1% on a constant currency, LFL basis) was substantially driven by lower demand in South Africa while the UK was broadly flat y-o-y. EBIT came in 2.7% lower (unchanged in constant currency) reflecting a better UK outturn – being the net effect of exiting Norcros Adhesives and two additional month’s contribution from Grant Westfield (GW) – more than offsetting adverse operational gearing in South Africa.
Norcros is profitable, strongly cash generative and moderately geared at 1x EV/EVITDA. We initiate coverage with our DCF analysis suggesting a fair value midpoint of 233p / share, giving c. 50% upside potential on a rerating.
Link to initiation here: https://www.equitydevelopment....
Marks Electrical (LON:MRK) "Market share gains and efficiency drive cash flow"
Results confirm 24.8% sales growth to £53.9m in H1, and despite lower EBITDA margins, Marks Electrical converted 145% of operating profit into cash (vs. 118% for the whole of FY2023), enabling a 0.30p unchanged interim dividend.
Margins, as expected, were reduced by the strategic decision to add integrated gas, electrical and television installation services to its next day delivery service, and increased wages for the company’s drivers. As a result, EBITDA margins were two percentage points lower than a year earlier at 4.3%. Importantly, gross product margins were almost unchanged – i.e. products were not discounted.
Market share improvements in both Major Domestic Appliances (MDA) and Consumer Electronics (CE) demonstrates the success of the company’s strategy. In H1 MDA share rose to 2.9% from 2.4%, while CE share increased from 0.3% to 0.5%. For online only, the MDA share was 5.4% and CE 0.9%. Given the substantial headroom the company enjoys in terms of awareness and reach, that over 1 in 20 UK online MDA orders are already put through Marks Electrical appears impressive.
Operating efficiency in terms of overhead costs improved in the six months. Inventory days reduced to 64 in FY2024H1 from 82 days a year earlier, and net cash rose by £0.9m to £10.9m in the past 6 months. The company generated a still impressive 37% return on capital employed in FY2024H1. With sustained robust sales growth, driven by consistent market share increases from an already meaningful level online and strong cash conversion, we retain our 150p fair value.
Link to report: https://www.equitydevelopment....
Tatton Asset Management (LON:TAM) "Sector-leading net flows, double-digit profit growth"
AUM grew 8% over H1-24 (to 30 Sep 23) from £12.7bn to £13.7bn. Net inflows totalled +£910m (7% of opening AUM), an inflow rate far above most peers, with some experiencing substantial outflows (see page 2). Investment performance contributed +£100m to AUM. Encouragingly, Tatton reports that the level of net inflows of H1 has continued into H2.
Revenue was up 10% y-o-y from £15.9m in H1-23 to £17.5m; adjusted operating profit (AOP) increased 11% from £8.0m to £8.9m; and AOP margin hit 50.7%, from an already-impressive 50.1% in H1-23. These margins are far above any comparable business (see page 7).
We highlight the significant growth potential going forward (detailed on pages 9-12): Tatton is in a growing market with significant tailwinds; it has a market-leading proposition and is gaining market share; it has a huge opportunity to grow AUM even without winning new clients (by increasing average AUM per client); and it can accelerate growth through strategic partnerships and acquisitions.
Our fundamental valuation is 580p per share, 18% above the current share price. We also flag that since the end of the bull market (end of 2021), investment/wealth managers and platforms have ‘de-rated’ significantly, with the median PER of a tracked peer group declining 47% from 27.6 to 14.6. We believe there is potential for a significant sector re-rating (see page 16).
Link to report: https://www.equitydevelopment....
And in the Tatton Asset Management (LON:TAM) analyst presentation this morning, company confirms it has hit its £15bn assets under management/influence target early- in March 2021 (when AUM was £9bn) it set out to reach a £15bn target by March 2024
Good morning Paul and Graham. You gave Braemar an Amber on the 22nd September Paul, we hold and I would appreciate your view on today's results and the likely share price movement when it begins trading again. Profit after tax down 67% after a £9.1 million goodwill impairment. Apart from that I'm reassured by everything else in the statement and hopeful on this investment resuming some growth.
I'm not sure we are any the wiser on what exactly has gone on at Braemar (LON:BMS):
As a result of the investigation, the Group has recognised a provision of £2.0m in relation to the uncertain obligations connected to a number of the transactions and commission obligations identified as part of the investigation. Of the £2.0m, £1.7m relates to historical unsettled commission payable, which was recorded in 2017 upon completion of the relevant contracts, which originated in 2013. This balance has been reclassified from trade payables to provisions during the year. While the board cannot forecast with certainty final outcomes in respect of these obligations, based on the Group's current information, the amount recognised is the current best estimate of the amount required to settle the obligations at the balance sheet date, taking into account the risks and uncertainties surrounding the obligations, including interpretation of specific laws and likelihood of settlement. Non-recurring costs of c£2.5m will be reported in FY24 regarding the investigation.
As the ultimate potential obligations and outcomes in relation to the transactions subject to the internal independent investigation are uncertain, there remains a risk that the final outcomes could materially impact the recognised balance. It is impracticable to provide sensitivity estimates of potential downside variances at this time.
Going Concern part merely adds to a list of concerns:
· The impact that the investigation and resulting delay in publishing the annual report and accounts could have on the performance and reputation of the business.
Hmm. The financial impact of all of this may turn out to be minor, but the absence of candour is troubling.
Whether it is rational to feel that way when BAE Systems (LON:BA.) and Glencore (LON:GLEN) may lurk in my portfolio is a debate for another day.
Hi JASVFS,
I don't think we'll have time to do Braemar (LON:BMS) - there's a huge to do list today, so I'm trying to pick off the simpler ones that we can review fairly quickly, and also BMS is still suspended I believe.
Sorry about that.
Regards, Paul.
I'd like to thank Ed for the recent webinar.
I'd just make one small request: can you but a link somewhere conspicuous for the webinar as I couldn't find it. I tried to register a couple of times to get the link, but I didn't get it.
I have a few reflecitons on the webinar.
The great performers that included FOUR, GAW, JDG, JET2: I owned all of them at one stage. I did "quite" well, but in the grand scheme of things I completely missed out on the much greater move. I owned GAW when it was cheap. People were pooh-poohing the idea at the time, as they said it was going nowhere. Succumbing to groupthink I sold the share. Big mistake!
I owned JDG, but I was pondering the fact that it was possibly too acquisitive, so I made a big mistake.
As regards FOUR, I got scared out when it had its profit warning a few years back.
JET2 (then Dart) I also did fairly well at, but I think I bailed when the share price tanked and it needed a rights issue. I always had in the back of my mind that airlines could make lousy businesses.
RNWH I've only owned since April. It's up 14% so far, which is OK. It's early days yet, mind. I only have a small position. The thing that is puting me off is that it has a CAGR of 5% of its shares in the last 6 years. They haven't issued any recently, so maybe that's a more comforting sign. I'm also a little put off by their operating margins. I note that in your seminar that you said one shouldn't be too offput by low margins. If they stick to their current business model I think they would be unlikely to be able to increase margins, though.
You also said that all of the multibaggers paid a dividend. I think that this is a very good point. As you said, paying dividends is a discipline. It is a sentiment that I first heard from Lord Lee, and it strikes me as a sensible one. And hey, who doesn't like a good divvie? I have debated this with my mate over in America, and he thinks I am being irrational. I for one am grateful for the old-fashioned British approach.
As regards women being good at investing - yes, it is something I have heard from elsewhere, too. Women tend to be much more down-to-earth in these matters, I think, going for much more secure bets which generally pays off. I remember, over a decade ago, my mum and dad were interested in investing a little money. My dad wanted to invest in Bowleven. Boy what a dog that turned out to be. I think it was tip in the Daily Mail or something. Anyway, fortunately that idea was ignored and we went with mum's idea of it being either Unilever or Astrazeneca. These turned out to be quite good choices, and vastly better than all that Bowleven nonsense. So yes, I think there is a definitely much underappreciated role that women can play in investment.
I'd say that although large-caps probably don't have the potential of the small-caps for growth, remember that they do have the potential for global reach. They can also benefit from the economies of scale. Take Experian (LON:EXPN) for example, which has returned approx. 9.7% pa in share price over the last decade (excluding dividends). That compares very favourably with the ASX (All-Share index) pf 0.3%. Or Boeing Co (NYQ:BA) which has grown at around 9.4%pa. Its dividend yield is around 3%, which I think is a little lower than its historical average.
As a additonal thought of the webinar, I'd say to look for companies with high dividend cover, say at least 2. "But it's not what you think", as they say in Youtube teaser titles. My point is not to do with safety (look for reasonable debt for that), but as an indication of expansion potential. What I mean by this is that it's not just ROE that determines share growth, but reinvestment opportunities. It needs to be able to plough that nice ROE into expansions.
Hotel Chocolat (LON:HOTC) well knock me down with a bar of Peruvian 80% chocolate, Mars are bidding 375p for Hotel Chocolat
We live in extraordinary times (& unlike Paul I do rather like the chocolate but that could be because I like almost all dark chocolate)
That's a hell of a price and underlines the virtue of owning companies where directors have big stakes in their companies, they're going to work hard to protect the value of their investment and never going to let it go cheap....
Ferrero must be quaking in their boots at Mars entering the luxury space with the opportunity to do a huge international roll out.
I tried to look at Mars' accounts, but remarkably turns out it's still owned by the secretive billionaire Mars family!
Here's the Wikipedia page for more info on Mars itself. $45bn revenues in 2022. 130k employees!
Ferrero bought Thorntons when it all went to rats. Similar to Hotel Chocolate model.