Small Cap Value Report (Thu 17 June 2021) - LGRS, VLX, OPTI, BWNG, CBOX, REC, SUMO, ANP

Good morning! It's Paul & Jack here with the SCVR for Thursday.
Timing - TBC - lots to cover today, so we'll be busy all morning. Today's report is now finished.
I really liked Jack's simple & clear disclaimer, so we'll use that every day, since newcomers may not know the format. That's when I remember to include it of course, so probably every other day.
Quick note - a friendly reminder that we don’t recommend any stocks. We aim to cover notable trading updates & results of the day and offer our opinions on them as possible candidates for further research if they pique your interest. We tend to stick to companies that have news out on the day, and market caps up to about £700m. We avoid the smallest, blue sky type companies, and a few specialist sectors (e.g. resources, pharma/biotech).
A central assumption is that readers then DYOR (do your own research) and discuss in the comments below. The comments, incidentally, sometimes add just as much value as the articles. We welcome all rational views, whether bull or bear!
Agenda -
Paul's section:
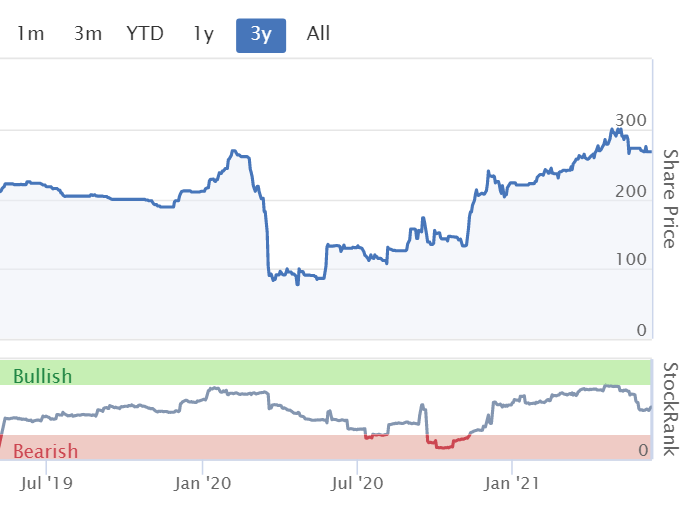
Loungers (LON:LGRS) - strong trading in 4 weeks since re-opening. This is a quality outfit, with strong management, not cheap , but it is good.
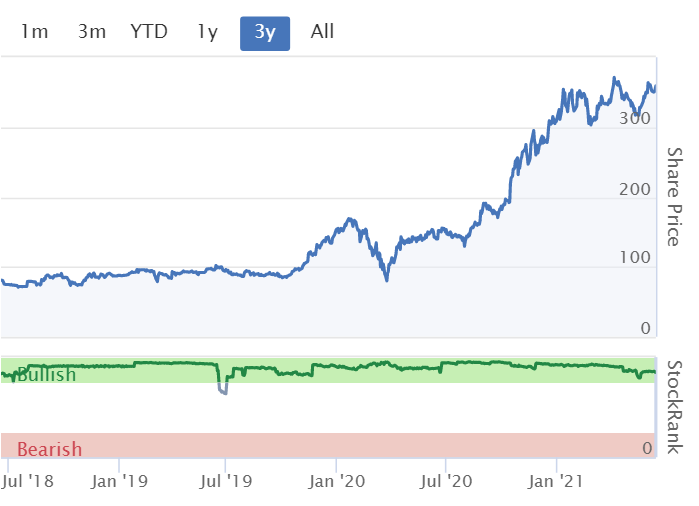
Volex (LON:VLX) (I hold) - strong results & outlook, beating expectations. However, I've re-worked the EPS figures using a normalised tax charge, and reality is a lot lower than the distorted (from a deferred tax credit) headline numbers. I'm not impressed. Everything else though does look good, so it remains in my personal coffee can (long term holds).
Optibiotix Health (LON:OPTI) - accounts for FY 12/2020 are finally published. Some progress has been made. The (paper) value of OPTI's shareholding in SBTX is the most interesting thing about this share. Best seen as a jam tomorrow special situation maybe?
N Brown (LON:BWNG) - in line Q1 trading update. No change to guidance. I've decided to ditch my position, due to the news covered in yesterday's SCVR re large increase in scope of legal action with Alllianz over historic disputed insurance products.
Cake Box Holdings (LON:CBOX) - data breach announced.
Jack's section:
Record (LON:REC) - FY profits down slightly and revenue flat. Change in leadership has had an impact. Share price has been strong recently but this is a profitable company investing for growth, so worth keeping tabs on.
Sumo (LON:SUMO) - the global video games market remains strong but individual company valuations are high and M&A activity is heating up. A lot of growth can be expected, but a lot of growth is also already priced in for certain stocks.
Anpario (LON:ANP) - promising consumer defensives company providing animal feed additives internationally. Again though, the shares are highly rated. Raw material price inflation and supply chain disruption flagged.
Paul’s Section
Loungers (LON:LGRS)
268p (yesterday’s close) - mkt cap £275m
Trading Update
Loungers, the operator of 173 neighbourhood café / bar / restaurants across England and Wales under the Lounge and Cosy Club brands, announces the following update.
New sites - 5 have been opened since 19 April 2021 (start of its new financial year). So this is a roll-out of an excellent format, and with highly rated management (according to my hospitality sector guru, who says they are the best in the sector).
Current trading - figures are only given for the period since indoor trading was allowed on 17 May 2021. For the 4 weeks since 17 May, sales have been +26.6% on the 2019 (before covid) comparator.
That strikes me as excellent, since there are still some restrictions in place, now due to end on 19 July.
The company says it’s “still early days” - an important point, as 4 weeks is too short a period to draw any longer term conclusions, as it benefits from pent-up demand, and the (partial) VAT reduction.
Directorspeak - positive, encouraged by performance.
Net debt - excellent disclosure here. NB all companies must tell us what their stretched creditors are, otherwise the cash/debt figures are misleading, so well done to Loungers here -
Net debt (excluding IFRS16 lease liabilities) at 18 April 2021 was £34.6m, with a further £12.9m of outstanding rent and deferred liabilities to HMRC.
My opinion - I mystery shopped a Loungers site recently, with a SCVR reader, and we were really impressed (Delfino in Poole). Everything was very well run, lovely food & drinks, outstanding staff. It had the feel of a well-oiled machine. Talking of well-oiled, so were we by the time our mystery shopping finished - the main mystery being how I got home.
Unfortunately I banked a profit on this share some time ago, after buying a few for my SIPP during the worst of the pandemic, confident that it would recover. Given strong re-opening trading, it’s tempting to buy back in. Pity the share is so illiquid though. I think this is a good long-term, tuck away forever type of share, even though the current valuation might seem a bit steep. Successful roll-outs do tend to command a premium, and it's justified here, in my view.
.
.
Volex (LON:VLX)
(I hold)
364p (up 2.5% at 08:27) - mkt cap £552m
Preliminary Results
Volex plc ('Volex'), a global provider of integrated manufacturing services and power products, today announces its preliminary results for the 52 weeks ended 4 April 2021 ('FY2021').
PR heading -
Strongest performance in 20 years underlines our potential
As you can see below, the financial highlights look impressive, especially considering the year in question would have seen a lot of disruption from the pandemic -

Adjusting items - to arrive at underlying results as presented - see note 3, $5.2m of this is acquired intangibles amortisation, which is fine - almost all companies & analysts adjust this out, because it’s just a non-cash book entry required by accounting standards relating to acquisitions (goodwill amortisation as it used to be called).
The other major adjustment is share-based payments, of $6.6m this year, and $8.7m last year. That’s more questionable as it’s management bonuses really, paid in shares. But on the other hand, that is separate from the actual trading performance of the business, so you could argue this either way.
Tax credit - Note that the 76.4% increase in underlying basic EPS is heavily flattered by a negative tax charge. Hence why there’s such a big difference between u/l PBT, and u/l EPS (much higher). When that happens it’s usually due to tax. Note 4 shows that a $10.94m deferred tax credit turns the $3.68m tax charge, into a $7.27m tax credit overall. To my mind, that should have been adjusted out in the underlying figures, which are misleading, since they include what is presumably a one-off tax book entry, and is not related to underlying trading in my view.
Re-working EPS -
Crunching the figures myself, using note 4 (tax), I work out EPS like this, normalising the tax charge:
$41.55m underlying PBT
Change the tax credit of $7.27m to a tax charge of $3.53m (to strip out deferred tax)
Gives $38.0m underlying profit after tax (i.e. earnings)
Divide by 162.5m diluted shares (taken from note 5)
Results in 23.4 cents normalised EPS (much lower than the 32.1 cents underlying basic EPS provided in the highlights). The StockReport shows consensus normalised EPS forecast of 22.0 cents. So we have a beat of about 6% against forecast, which is good, but nowhere near as good as the highlights section suggests, with the distorted figure of 32.1 cents). A big thumbs down for how Volex has presented this, which strikes me as misleading. We shouldn't have to dig through the notes & re-work EPS, to get the true picture. For a start, there isn't time between 7-8am, so people might have been buying early on a false impression of a massive EPS beat, which actually wasn't real, due to a tax credit.
Divide by 1.4 to convert dollars into sterling = 16.7p diluted EPS - I think this is the figure we should be using to value the company
What’s the upshot of this? What initially looked like a massive EPS beat, is actually a much lower beat. I feel the 32.1 cents figure provided in the highlights is a misleading figure.
Underlying operating margin up from 8.1% to 9.7%
Copper price - as mentioned before, the company can pass on price rises, so we don’t need to obsess over the copper price -
Covid-19 has had an impact on the cost of some of our raw materials. In the first half of FY2021, the price of copper dropped as there was uncertainty about global requirements. As demand improved in the second half of the year, copper prices increased. Our contracts with our power cord customers, where copper is a significant percentage of the bill of materials, allow us to pass these costs through to the customer, although there can be a short delay to allow the pricing changes to be implemented.
Acquisitions - Turkish power cords maker DE-KA looked an excellent deal. This has only contributed a few weeks into the FY 03/2021 profits, so should boost FY 03/2022 profits since it will contribute a full year. Hence EPS should go up again.
More acquisitions are in the pipeline, and Volex says it has access to funding.
Balance sheet - note the small pension deficits, including one acquired with DE-KA.
Due to the acquisitions strategy, note that goodwill & other intangibles have risen a lot. As has working capital, reflecting the fact that it’s a larger group now.
NAV is $183.9. Deduct intangibles totalling $105.1m, gives NTAV of $78.8m, which looks OK to me. So I have no issues with the balance sheet.
Cashflow statement - looks fine to me. The group is generating strong cashflows, which are being used mainly for acquisitions.
One item which does jar with me, is that $6.0m was paid in dividends, but a larger figure of $9.0m was spent buying shares for Director/employee share schemes. That doesn’t feel right to me, although you could argue that divis are low because the company is focusing on growth.
Note also that new loans of $37.2m were raised (and $3.1m repaid).
I don’t see the gearing as excessive, and net debt is negligible for the size of business, at only $7.2m (ignoring lease liabilities).
Outlook - sounds good -
· We have delivered a strong start to the new year across all regions with continued momentum in Electric Vehicles and Complex Industrial Technology
· There is an exciting pipeline of acquisition opportunities and strong financial flexibility
· The longer-term prospects for our business remain strong and we continue to invest in capacity and strengthening our capabilities with a particular focus on growth areas
As a result, the outlook for our business is positive with strong trading during the first two months of FY2022 and continued demand from our customer base as our strategy of strengthening our capabilities pays off. We have built a business with excellent customers and exceptional assets and are well placed to continue our drive for continuous improvement as we look to make targeted investments in order to deliver on our long-term growth plans and achieve our five year plan set out in October 2019 to achieve $650 million in revenues and $65 million of underlying operating profit by 2024."
My opinion - the misleading presentation of EPS has taken the shine off things for me. You can’t show an unusually high EPS figure of 32.1 cents, as underlying, when it’s not! Normalising the tax charge brings that materially lower to 23.4 cents. So slapped legs for management there!
Nevertheless, it’s still a “cracking” set of numbers, as the Chairman (with tons of skin in the game) promised us last year.
By my calculations, we should be looking at 20p+ EPS this year, due to the benefit of growth, and acquisitions. Hence at 367p currently, the PER of 18.4 looks perfectly reasonable.
There’s scope for more acquisitions, hence we should see forecasts go up further when more deals are announced.
Rising raw materials prices are not a problem, as they can be passed on - a key point to ask all companies about, as inflation rears its ugly head.
Overall then, it’s looking good, and continues to be a “coffee can” long-term hold share for my personal portfolio.
Note there is an InvestorMeetCompany presentation at noon today. They're usually recorded too.
It's been a superb turnaround in recent years, and although we might have to get used to a slower pace of share price rises in future, the outlook & valuation both seem reasonable to me.
.
.
Optibiotix Health (LON:OPTI)
47p (down 1% at 10:45) - mkt cap £41m
Final Results
We don’t have a happy history here at the SCVR, with this jam tomorrow company. I’ve been critical of it in the past - because the figures were rubbish, and all the puff about contract wins didn’t seem to convert into meaningful financial progress. Plus the CEO once sent me a rude, personally abusive email. But never mind, it’s understandable that people want to shoot the messenger, and anyway I don’t hold grudges, life’s too short.
Checking the archive here, I last looked at OPTI here on 18 Feb 2021, concluding that there were at last some signs of progress - it has been listed since 2011, so better late than never.
Final Results today are very late, being for FY 12/2020 -
Revenues £1.52m (up 104% on a 13-month prior period)
Cost reductions
Operating loss of £1.1m (improved from £(2.17)m prior year)
Big profits booked for disposal of an associate & gain on investments - totalling £7.17m profit
Profit before tax of £5.7m - how real, or rather realisable into cash, those profits are, is open to discussion.
OPTI’s core business looks as if it is making progress, albeit still loss-making. It’s not really of interest to me, because it’s taking too long to get anywhere, and revenues are still tiny.
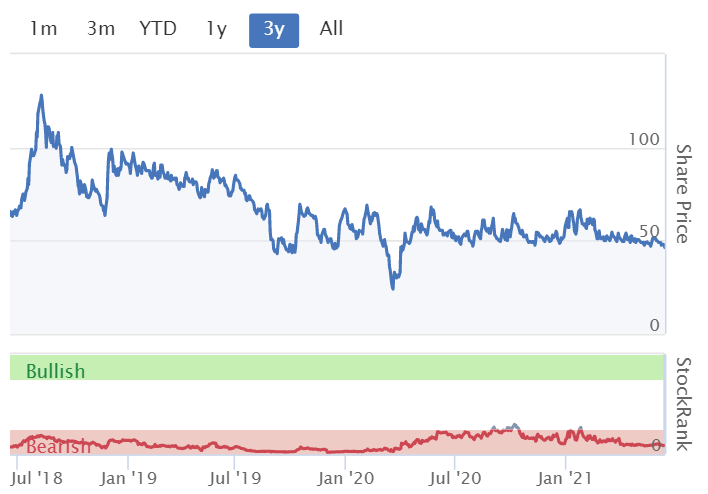
However, OPTI’s investment in a spin-off company called Skinbiotherapeutics (LON:SBTX) has shot up in value this year. Normally one jam tomorrow company spinning off another jam tomorrow company wouldn’t be of interest, but look at the share price of SBTX below, which now has a market cap of £98m - so we could see OPTI shares as a special situation where the main value could be its holding in SBTX - now (on paper) worth c.£25m, compared with OPTI’s market cap of £41m. Deduct the SBTX shareholding, and that values OPTI’s business (ex its SBTX investment) at c.£16m - still a lot for a loss-making company though -
NB. The chart below is for SBTX -

.
The company says it sold £901k-worth of SBTX shares after the year end, so this could provide a nice slush fund to keep OPTI’s cash burn going, and mean it doesn’t have to dilute its own shareholders to keep operating.
My main worry is that SBTX shares could just be in a speculative bubble, and end up being worth next-to-nothing, which is usually what happens in this type of situation, in my experience. I've seen that happen with junior resource stocks, where spin-off shareholdings end up almost worthless in the long run.
If OPTI could ditch its entire SBTX stake for cash, that would be a game-changer, giving it proper funding.
My opinion - it’s not of interest to me, but there are interesting elements to the story. The narrative is full of the usual ramping about future prospects. After 10 years of such gushing talk, does anyone actually believe it now? Maybe, who knows. OPTI's own share price looks stale at the moment, so plenty of previous bulls must have given up to chase fresher stories maybe? If they couldn't get the share price moving in the boom-time market conditions we've had since Oct 2020, then that leaves a lot to be desired.
.
.
N Brown (LON:BWNG)
(I've decided to sell my position here, as we were discussing yesterday)
Q1 trading is in line with expectations.
Full year guidance unchanged.
Hence not a lot to say beyond that.
I've decided to sit on the sidelines and watch, to see if the turnaround works or not. As we discussed yesterday here, I was rattled by the news yesterday of a large increase in the potential cost of a complex ongoing legal dispute with Allianz. This is a material uncertainty, and I've decided to take a hit, and sell up. On the basis that I can always buy back in at any time in the future, once there's greater clarity on the likely outcome of the legal action, and indeed how trading develops.
I'm prepared to risk missing out on a takeover bid, which does look possible, from the controlling family.
For me, I want to be guessing as little as possible, when holding investments. Hence I'd rather park my money in shares where there's a clearer picture about performance, and no worries about large ongoing legal claims. It was a mistake buying this in the first place, because I knew about the Allianz legal action but decided to ignore it. Part of the trouble, is that when our portfolios are doing really well, as in the last 6-7 months, then we often end up lowering our standards and buying lower quality shares, only to end up with losses on them. Lesson learned, I need to tighten up my buying criteria again.
.
Cake Box Holdings (LON:CBOX)
264p (down 8%) - mkt cap £106m
Statement re Share Price Movement
Another data breach, we reported on another company suffering the same thing yesterday.
Here is what it says today, in full -
The Company notes the recent share price movement in its shares. It confirms that it has recently emailed customers in relation to a data breach experienced in 2020 as a result of which personal and financial information may potentially have been accessed. The Company has taken the appropriate steps to investigate the incident, repair the compromised systems and identify those customers that may have been compromised. The Company has also further strengthened the security of its systems to prevent future breaches.
We have contacted any customers whose personal information was potentially exposed during the incident to provide them with support where required. We have also informed the relevant authorities.
The Company is in the process of finalising a date for its 2021 full year results with its auditors and expects to confirm a date shortly. The Company confirms that the data breach is not expected to have a material financial impact and as per the announcement on 12 April 2021, full year results are expected to be in line with market expections [sic].
My opinion - data breaches are commonplace these days. Unless there are serious complications, I'm starting to view plunges in share price from data breaches as potential buying opportunities. These things generally seem to blow over. Although it does introduce uncertainty. The risk is that the situation could be far worse than originally thought, with unforeseen liabilities cropping up. For a small cap cake maker, I can't imagine any multi-million lawsuits would be launched by its customers!
Jack's section
Record (LON:REC)
Share price: 87.39 (-5.42%)
Shares in issue: 199,054,325
Market cap: £174m
Record (LON:REC) is a currency management firm. It’s an external manager for institutions such as pension funds and foundations, which have significant currency exposures and require an outsourced currency specialist to either passively hedge those exposures or more actively manage them in order to generate alpha.
Its services include Bespoke Currency Hedging, Currency for Return, and additional currency solutions and consulting services. The business was established in 1983 by Neil Record who previously worked at the Bank of England. He is currently the chairman and largest shareholder.
This is a very high Quality stock, with a Q Rank of 94. You can read more about what goes into that Rank here, but the short version is it looks for longer term signs of profitability and financial health such as long term ROCE, long term gross profits to assets, and the Piotroski F-Score.
You can see the double digit ROCE over time on the StockReport:

But strong returns on capital are only really half the picture. You need growth as well. This looks to be more of a problem for Record.

Nevertheless, the shares have rerated strongly over the past year and the group has a 1Y relative strength of 128%, meaning it has comfortably outperformed the market.
Highlights:
- Revenues marginally down from £25.6m to £25.4m,
- Growth in management fees of 8% to £24.9m (2020: £23.1m),
- 37% increase in USD Assets Under Management Equivalent (AUME) to $80.1bn at 31 March 2021, including strong net inflows of $9.7bn for the year,
- 23% increase in GBP AUME to £58.1bn at 31 March 2021,
- Performance fees for the year of £0.1m (2020: £1.8m),
- Profit Before Tax (PBT) -19.5% to £6.2m,
- Operating profit margin down from 30% to 24%,
- Basic EPS of 2.75p per share (2020: 3.26p),
- Total ordinary dividend held at 2.30p per share,
- Special dividend for the year of 0.45p per share (2020: 0.41p)
- Robust financial position with net assets of £26.8m at 31 March 2021 (2020: £28.2m).
The results put Record on an FY21 PER of 33.6 paying out a total yield (including special) of a shade under 3%. It’s a little pricey but the yield is respectable and brokers are forecasting good growth for FY22. If Record hits that FY22 EPS target, the PE ratio would fall to a much more attractive 20.6x.
That would be a 68% increase in earnings per share and would be quite a departure from the historical growth rates, so I wonder what’s behind that.
An additional thought: raising fees by 8% is useful and suggests a degree of pricing power in Record’s services. Either that, or this is an unsustainable method of growth and Record will lose business to cheaper passive strategies. I’m hoping it’s the former and clients are willing to pay more for value-added services. Record has delivered its highest ever AUME of $80.1bn this year, including diverse inflows of $9.7bn so it looks as though the demand is there.
The balance sheet is conservative, with net assets of £26.8m including c£7m in cash and nearly £13m in money market instruments set against total liabilities of £6.8m.
Although the shares look pricey on these results alone, they are reasonably resilient given what has been a heavily disrupted year for many. The group has no debt, is cash generative, is investing for growth, and is paying out a special dividend.
In terms of new products, Record is close to launching the Record EM Sustainable Finance Fund, which has been developed in collaboration with a large Swiss Wealth Manager. Further investment has been put into IT infrastructure and technology. This modernisation work is continuing into the current year, with a further £0.8m investment anticipated.
There is a succession going on at Record. That’s a risk. The company says this is being managed but also adds that this ‘change in leadership has impacted on profits in the short term’. Progress has been made here with the restructuring of its Client Team and a change of CIO during the year
Commenting on the results, Neil Record comments:
As expected, the more immediate financial impact from implementing our wide ranging strategy in investing for growth has been a short-term decrease in profitability. However, looking forward, we start the year on our highest ever level of AUME, which is more diversified across our higher-margin products and provides us with an excellent platform for growth in FY-22. Added to this, we have been developing new products in collaboration with our clients, one of which, the innovative Record EM Sustainable Finance Fund, we anticipate launching by the end of this month alongside one of the largest Wealth Managers in Switzerland.
Conclusion
Record looks to be a company managed for the long term. Maintaining that culture is of key importance through this transition but it looks like it’s being carefully handled although profits have been impacted.
It has always generated high returns on capital, so the IT modernisation and the expansion of its product offering could be profitable growth drivers moving forward.
The growth in AUME is encouraging, as this comes in a tricky period where Record has had to deal with succession planning, Brexit repercussions, a global pandemic, and changes to its IT infrastructure. So I can imagine management is actually reasonably pleased with the outcome.
But the share price has been strong - it’s been a clear breakout and I wonder if the easy rerate has happened for now? The valuation makes me think twice so I’m watching from the sidelines.
As with more traditional asset managers, fees are based on AUM and so profits are presumably sensitive to the state of the financial markets.

That said, Record looks like a competent and innovative operator in a large market, investing in an increasingly diverse range of products which should allow it to capture more market share. If the share price softens I’ll become more interested. With Schroders also buying in recently, more institutions might be tempted to take a stake so that’s something to watch out for too.
Sumo (LON:SUMO)
Share price: 371.5p (-3.88%)
Shares in issue: 171,461,351
Market cap: £637m
Sumo (LON:SUMO) is a video games maker based in Sheffield. It now has four divisions: Sumo Digital, Pipeworks, Atomhawk and our recently created publishing division, Secret Mode.
The longer term dynamics in the video games sector are fantastic. As a media form, it is now more relevant than Hollywood and the film industry and that’s been a long time coming. If you look at how younger generations spend their time these days, it’s easy to see this trend continuing for many years.
The industry itself is maturing at pace and business models are evolving. It is becoming easier to build sustainably profitable enterprises in the sector. Back catalogues are now more easily monetisable and so IP is more valuable, which is as it should be. Game lives are extending with the help of post-launch improvements and support, so people are playing them for longer.
There’s less of a pressing need to find the next big hit (although this need still exists). And the UK has some fantastic talent in this sector with the likes of Sumo and Team17 (LON:TM17) .
It’s just the individual company valuations that can be hard to swallow. What’s more, there’s a lot of M&A in this hot sector at what could be frothy valuations. Sumo is not the only company of its type to trade at close to 10x earnings even as it approaches a £1bn market cap. That’s a fair amount of growth priced in.

But then there is a lot of growth to come. Some of these companies will be huge in ten years time and it will be worth paying up for the right stock. That requires vision and a bit of luck. It’s easier said than done.
The global video games market remains strong and the Group is performing in line with expectations in the year to date.
Sumo had an ‘extraordinary’ 2020, with 279 projects and 12 games including five Own-IP and its first major acquisition.
All divisions are trading well and the group is reviewing a considerable number of internally and externally sourced titles. The pipeline of new business development opportunities comprises a total contract value in excess of £500m, a significant increase on the £429m figure at 28 February 2021.
Its Own-IP title, Hood, launched in May and Sumo is now delivering the post launch plan including new content. Reviews so far appear to be mixed.
Little Orpheus, developed by The Chinese Room, has been awarded the Apple Design Award for ‘Delight and fun’ for its platforming, storytelling, music and for bringing console-like experience to an accessible game.
Pipeworks (a recent acquisition) will shortly open a new studio in Vancouver, which will be Sumo’s 14th studio.
Total headcount has increased from 1,043 at 31 December 2020 to 1,155 at 31 May 2021 and the acquisition pipeline remains strong. Sumo is pursuing a number of targets.
At 31 May 2021, the group had net cash of £8.0m up from £6.8m at 31 December 2020 following some earlier than forecast receipts.
That same day the group spent £5.5m funding the purchase of approximately 1.54m Sumo Group shares through the Employee Benefit Trust (the "Trust"), following the exercise of options under the Company's Long-Term Incentive Plan. These shares are to be held on the terms of the Trust to satisfy the vesting of options under the LTIP in the future.
Conclusion
Sumo looks well placed to take advantage of the strong growth in the global video games market.
But I’m slightly wary of the increased M&A activity. This is probably the most fraught use of capital allocation when it comes to generating long term shareholder value. It can be done, but in a ‘hot’ sector with high valuations, it strikes me as riskier still.
The board profiles suggest the CEO and CFO do have experience here, so hopefully they will be acquiring smartly.
I'm not invested in any video games makers (I last held Codemasters, which was bid for), although I understand the attractive industry dynamics. There could be a dip as lockdowns ease but that could just be short term noise.
There is clearly great potential, but expanding at pace and managing acquisitions brings execution risk. With valuations as they are there is little room for error, so I continue to wait.
Anpario (LON:ANP)
Share price: 677p (-1.88%)
Shares in issue: 23,180,083
Market cap: £156.9m
Anpario (LON:ANP) is an independent international manufacturer and distributor of natural animal feed additives for animal health, nutrition and biosecurity. Its additive technologies are sold in over 80 countries through established sales and distribution networks.
It sounds potentially attractive and the market thinks so too, with the shares having roughly doubled over the past year.

Again though, we stumble on valuation. The shares look expensive - a bit of a theme so far this morning. This can be justified by high growth potential, but the company does need to live up to that potential. And past growth has been steady not spectacular.

The company has delivered sales at a similar level to last year, which was strong as customers increased stock levels at the onset of the pandemic.
China is performing particularly well but South East Asia is weaker due to newer lockdowns and less tourism. The group is mitigating Brexit disruption with its new European stockholding hub.
In keeping with other industries, Anpario is ‘experiencing raw material price inflation and some disruption in our supply chains and global shipping operations.’ It looks like the company is able to pass these costs on via price increases but ‘expect[s] these challenges to continue until the last quarter of this year.’
The group notes its ‘unique formulation technology’ also benefits customers as it enables Anpario to offer more cost effective solutions than alternative competitor products.
Conclusion
Not one I know, but it looks at first glance to be one of the better listed companies out there. It’s got unique properties that add value for its customers, and the market is presumably large. I suspect there are good growth opps in such markets.
Clearly revenues are already international and the group’s sales and distribution networks are well established. The balance sheet is strong - net cash with barely anything in the way of liabilities barring £5m of payables - and cash generation is good. It regularly generates cash flow from operations in excess of earnings.
The only qualm is valuation, as noted above, especially when juxtaposed against the growth CAGRs. This looks like a good business - just one I would like to buy at a cheaper price.
I should probably set up a ‘Quality but Expensive’ watchlist for this type of opportunity. Perhaps others are already doing this?
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

57 comments
Paul, any reason why you never cover ORPH? Thanks.
Skinbiotherapeutics (LON:SBTX) - for us skin sufferers.
No interest in Optibiotix Health (LON:OPTI) but Shares magazine have 'suggested / DYOR etc' Skinbiotheraputics (they have the copyright on the name sorted anyways) about to market a new 'thing'. Croda are using the 'stuff' for 'something' so there you go - not 'jam' but a bit of skin cream.
Would be nice to see some fundamentals pick up but have set an alert at 70p and will see where it sits then. Takeover target if it does well seems to be the current market.
(SIPP and ISA in AJBell - but too expensive for trading).
PS. Ignore me Avon Rubber (LON:AVON) did not work out.
I did hold Optibiotix Health (LON:OPTI) but felt that it was too much hot air over a number of years, so despite the 25% holding in Skinbiotherapeutics (LON:SBTX) I sold out as I am looking to reduce risk in my PF and reduce holdings in micro-caps.
I have kept my small holding in Skinbiotherapeutics (LON:SBTX) despite it being another micro-cap I felt that the risk of holding on to see what happens with the Croada deal with regards to their Posiaris (badly spelled) cream which a recent trial showed was highly effective and potentially does have significant benefits for sufferers.
Volex (LON:VLX) (no position)
I'm always torn on this one.
Going through my personal notes I see that I yo-yo between believing that it's undervalued and worth a buy, and being so confused by the moving parts and unexplained entries, that I decide it's not worth the hassle.
Today it's the latter.
The below shows Year-on-Year revenue growth for the last few years.
Note that the $3,104 and $41,248 FY21 revenue figures for Ta Hsing and Servatron are estimates based on pre-acquisition annualised revenues, as only partial revenues are included in FY20.
(NB: the acquisition dates are on the far left side of the image. Both of these companies were mid-FY20 purchases).
Using this very simple assumption, growth in the underlying business is actually closer to 7.3%, and could be a catch up from the poor underlying revenues last year ($363m), which itself was down -2.3% on FY19 ($372m.)
So for me it's really unclear what the underlying growth truly looks like.
---
3 more things I noticed:
This seems high for a company with possibly tepid underling growth, which is valued at £540m.
I must admit to not doing more in-depth research beyond the notes above, so there may be explanations that I've missed or potential that I've overlooked.
Having said all the above, so long as customers further down the line aren't put off by the growing raw material costs, I imagine that the growth will continue, especially with annualised De-Ka revenues now included in the FY22 accounts.
It's one that I will continue to keep an eye on.
Cheers
A
VLX Volex : I listened to the Volex presentation and can confirm the unerring accuracy of your eps calculations. I suspect you may have listened in later as well? Anyway, the tax 'impact' added 8.9 cents to eps according to an answer from management to a question. Worth mentioning that they have further deferred tax which will be usable against future profits. I believe this does affect cash flow positively but the big drop in 'CF' this year principally seems to reflect the big increase in inventories subsequent to shipping delays and stockpiling during the pandemic. I also noticed just now a sizeable increase in receivables but we shouldn't forget that the consolidation of DE_KA will have had a big impact on the balance sheet but little on revenues and profits etc. It was finalised in February.
S-T trading sounds pretty good with some recovery starting in medical but I personally think we should be prepared for setbacks consequent on the acute chip shortage affecting auto production and possibly data centres. EV grid cables and data centre cables were big contributors to revenue growth. I know this has not yet been a factor and the company feels it is in some senses protected by their (apparently) excellent supply chain teams and large size.
Component manufacturers often have very volatile earnings profiles but Volex seems to me a very unusual company. Firstly, it is a British-based manufacturing enterprise that has been completely revamped by the current managemt- who in toto hold 26% of issued shares. Secondly, the addition of DE-KA mean the company will have three quite nicely balanced geographical revenue sources going forward - Asaia, N Am and now Europe. And they SEEM to be in a very strong competitive position especially in the smallish (ca 12% revenues last year) but rapidly growing market for EV grid cables and the high demand data centre business.
Must go now but (obviously as an holder) agree with the rough 20p eeps for this year and hopeful the story continues.
First time posting and would like to a big thank you to Paul and Jack for the SCVR each day great information. I am sure I saw Purplebricks (LON:PURP) part of this report some time ago but not seen it since. I have noticed their share price going down but their business is picking up was just wondering if anyone had any ideas on why the share is going down? I know the stamp duty relief is coming to an end but housing market seem still very bouyant at this time.
I think this is on market share concerns since the last RNS: the market is buoyant but those house sellers might be using more conventional estate agents or other online upstarts, like Strike.
Purplebricks (LON:PURP)
I read rumours about a month ago about a big seller trying to offload a chunk of their stock.
I'm not sure what happened with that (or who the seller was) as the share price recovered a few weeks ago before starting to fall again.
It could just be normal market gyrations. There doesn't seem to be much trading volume over the last few weeks.
A
I was also interested in Purplebricks (LON:PURP) but there are those who have access to the listings data from Zoopla, etc that knows what share of market they are getting, how many instructions they are securing, etc.
Maybe they are losing share, and/or their instructions volume over the last two months have been soft?
As a PI without that info access, I've decided too many others will have an information advantage over me in this share, so have decided not to have it on my radar to invest.
thank you all for comments.
Hi Jack
“ I should probably set up a ‘Quality but Expensive’ watchlist for this type of opportunity. Perhaps others are already doing this?”
Yes indeed. The top 5 by inverted Value Rank
Advanced Medical Solutions (LON:AMS)
Instem (LON:INS)
Tatton Asset Management (LON:TAM)
Anpario (LON:ANP)
Quartix Technologies (LON:QTX)
Happy to share as I won’t be buying them at current prices.
Cheers
Simon
Re £OPTI
The first RNS states it was founded in March 2012 - listing on AIM was 5th August 2014.
I did have a small holding at one point, but gave up on it a good while back.
£ANP Thanks for your comments Jack. I have held many years and like the way the business is run. Operational improvements last few years have led to better margins - top line growth is key and if the supply chain/raw material issues do not impact too much I expect strong performance in second half of 2021. An attractive acquisition would be nice, but have waited for this for a number of years now - at least they have not been tempted into overpaying just for the sake of doing a deal.
Paul. Thank you for the excellent summation of Volex (LON:VLX) results.
Another wonderful example of how it should be done. Just wished had the same ability.
I hold.
It will be interesting to see if Volex (LON:VLX) (I hold) maintain a consistent approach to the treatment of deferred tax when using the figures as comparatives for FY22. I hope they do and if they are also able to report growth then that will be tremendous. Like Paul, I am surprised that they haven't made an adjustment as the benefit can hardly be seen as "underlying".
Paul,
I would like to second Michael's appreciation of your work on Volex (LON:VLX) . Excellent, informative work.
Thank you.
Richard
Also agree about Paul’s update today on Volex (LON:VLX) especially so the section on re-working EPS. Paul’s ability to fine comb and analyse figures (and to see through Companies making figures sound better than they are) is extraordinary! Even more extraordinary is how somehow he combines that skill with the ability to write content and analysis of exceptional quality and detail at such a fast pace too. And not just on one Company but several!
Add to all that Jack’s excellent detailed analysis and comment and again at such a fast pace and Stockopedia is worth more than the current subscription for that alone. I’ve subscribed to the very good Small Company Share Watch for years, but it’s £199 a year for just 1 issue a month. And their comment focus is more on the story and not detailed financial analysis like that provided by Paul and Jack. And they tend not to comment on important things like pension deficits (e.g for Reach) in the way such things are covered here.
My investment performance has improved substantially since subscribing to Stockopedia, and the exceptional daily Small Company reports here (and sometimes some very good follow up reader comments) are a key reason why.
Thanks!
Morning Ken Mitchell. I subscribe to both, and agree with your comments on both. However, sometimes too much detail can lead one in a certain direction, which turns out to be false. Perhaps coincidental. I was put off investing in Reach by the comments on pension deficit here, whereas it was strongly recommended by SCSW and they bought it too for their portfolio.. It has done very well, ignoring the pension deficit. My fault, my decision, my loss, no blame attached to anyone other than me.
Yes absolutely Michael, I wish I had Paul's ability to.
At 7.00am this morning I read every word of the Volex - VLX, RNS. I was so excited that I started dreaming about a 100% ! rerating based on the numbers presented (LOL)
But as we know Paul is the Jedi Master at interpreting RNS, especially here with the misleading presentation of EPS.
Anyway, I am still very positive on this one indeed, and I am a patient holder with 8% of my portfolio tied up in VLX
Neville
Hi
Don’t generally make requests but will you be liking at £VLX.
Thank you.
Michael
Hey Michael,
Volex (LON:VLX) is already up! Paul's looked at it.
Sorry ignore. Now seen that Volex (LON:VLX) is in header.
Not relating to today's news, but does anyone have an idea why Cake Box Holdings (LON:CBOX) is getting hammered so hard over the last couple of days? Could be a good buying opportunity as i can't see how the company's conditions have changed.
Not relating to today's news, but does anyone have an idea why Cake Box Holdings (LON:CBOX) is getting hammered so hard over the last couple of days? Could be a good buying opportunity as i can't see how the company's conditions have changed.
It was mentioned yesterday in the SCVR comments section. Reports of a serious undeclared data breach, I'm surprised there' s been no announcement, if only to deny it.
timarr
I sold my Cakebox shares because of too many online comments of stale products being sold.
Cakebox weakness is it vulnerable to new competition from well known firms.
The CEO of course sold £6 million last year but said he was not related to the business
Cake Box Holdings PLC Statement re Share Price Movement - ADVFN
I disagree with Paul's sanguine view on the potential financial impact of this data breach.
I work in a large multinational company and our legal team are paranoid about customer data security, as any breaches could lead to fines up to 4% of global yearly revenues. Which is alot.
As customer privacy becomes more prominent and data breaches more frequent, there might come a point where the ICO is politically pressured to make some scapegoats. Granted, Cake Box Holdings (LON:CBOX) is a "small" company (in the grand scheme of things) and therefore unlikely to be used as a public scapegoat. But the threat of a big fine is very real.
On top of that, ICO might also impose Cake Box Holdings (LON:CBOX) to provide customers with some redress, either compensation or services like identity protection / monitoring for a year or two, which could cost quite a bit.
Here are my SCVR heat maps for today (prices as at ~9am).
I share these heatmaps with the intention of giving a visual indication of what is going on in the SCVR world: who’s reporting (and it's impact on the share price); and what’s moving more than 'normal'. There are no associated recommendations, implied or otherwise, just information. How, or indeed if, you choose to use that information is up to you. Please feel free to ignore them if you don't find them useful.
Please read my heat map thread for a great deal of explanation of how the heat maps are formed and how I use them to guide me with my research, and for a full key to the contents.
I very much welcome feedback so if you do have any feedback, not already covered in the heat map thread, it would be very helpful if you could post your comment in the heat map thread rather than the SCVR thread. The more specific and constructive the feed back is, the more that likely it is that I will be able to act upon it. Thank you all for the feedback so far.
Small / Micro Caps reporting today:
Big movers today in the SCVR world (moving more than a 20d EMA of the ATR against either yesterdays close, or today's open):
Warm regards, stay safe, and best of luck!
greensiax
Seeing Machines - I have owned this stock and sold on a previous climb before. I like the technology and their USP of huge data which would take any newcomer a long time to gather. I always thought they would be bought by a google or another tech giant for the data analytics. However you cannot ignore the cash burn and share dilution so far and are some way away from profit even after increasing adoption by the market
Andrew
Bought some Seeing Machines (LON:SEE) first thing. They make a product that tracks the drivers eyes in cars, to make sure they are paying attention to road and not falling asleep. As with all car safety products, adoption is slow (Surface Transforms (LON:SCE) was the same) but they seem to be getting traction now and announced today they will be in a number of GM vehicles. Feels to me like its reaching the point of mass adoption, where it will become expected in higher end cars. Chartwise, has been consolidating for ages, and probably needs to go past 12p to breakout, but I think it could do well from here as it moves from speculative tech to long term contender
Are they default tech in GM cars, or being offered as optional add-on tech?
If the latter, this is where I see (no pun intended!) Seeing Machines (LON:SEE) failing to crack the consumer market. Driver psychology is that they think they always know when they will hit the limit, in terms of awareness, and stop driving. However, we know that's not the case, given the big number of accidents every year. But will drivers pay extra for something they don't think they need...
From earlier this week, Ig Design (LON:IGR) full-year 2021 results presentation. Paul Fineman, CEO & Giles Willits, CFO present the results, which were robust despite Covid-19. Looking forward they have impressive targets to achieve $1.5bn+ revenue and to double adj EBITDA. Here they outline the strategy for that growth, and give more details on the year just gone. Video & podcast.
Separately, we have a few webinars:
Today, Thursday 17.6, 9am FY21 results for £NESF. Register here.
Tomorrow, Friday 18.6, 10am an investor presentation for £MBH. Register here.
And, next week we have the Stockopedia/PIWORLD StockSlam, with special guest Jack Brumby, alongside 10 other Slammers. Register here.
Loungers (LON:LGRS) - the two venues we are aware of have been very busy all day. Good range of food and drink and seemingly with plans to expand considerably in the future. I have been buying Paul's shares!
GN100 - why don't you attend the Volex (LON:VLX) presentation yourself? All you have to do is register for free here:
https://www.investormeetcompany.com/register
Volex (LON:VLX) Memory failure - I'm afraid. Fortunately, Paul's reply jogged my memory and I have registered for it.
Not sure if Sumo (LON:SUMO) still makes the "small cap" cut-off, but there is a RNS this morning only titled as "AGM Statement" which does contain a trading update:
"Following an extraordinary year in 2020, when the Group delivered 279 project milestones and launched or announced a total of 12 games, including five Own-IP, and completed its first major acquisition, the Board is pleased to report that the global video games market remains strong and that the Group is performing in line with expectations in the year to date.
Sumo Group now has four divisions, Sumo Digital, Pipeworks, Atomhawk and our recently created publishing division, Secret Mode. All divisions are trading well and we are encouraged by the early progress achieved at Secret Mode, which is reviewing a considerable number of internally and externally sourced titles. Overall, the pipeline of new business development opportunities now comprises a total contract value in excess of £500m, a significant increase on the £429m figure at 28 February 2021, which we reported in our Final Results 2020 announcement on 31 March 2021."
https://www.investegate.co.uk/...
many thanks for your thoughts Jack!
"But I’m slightly wary of the increased M&A activity. This is probably the most fraught use of capital allocation when it comes to generating long term shareholder value. It can be done, but in a ‘hot’ sector with high valuations, it strikes me as riskier still."
Agreed! In one of the investor presentations a while back, Sumo (LON:SUMO) management did highlight that by far the biggest challenge facing them (and the industry as a whole) is a shortage of technical talent ... there simply are not enough coders etc available for hire given the amount of available development work and the competition for these skills is fierce. In house training, recent university graduates etc take time before they become meaningfully productive in such a highly specialised field ... so I think, these bolt-on acquisitions are perhaps one way of addressing this challenge and getting highly skilled and experienced technical people working for the greater Sumo (LON:SUMO) quickly?
Does not make lots of integration any less risky in terms of actual execution of course, but the reasoning made sense to me.
The Open Orphan (LON:ORPH) update seems to pin all it's positivity on the performance in Q4 where it shows an operating profit and generated cash.
They have advised they aim to show a full year profit in 2021.
I would welcome thoughts on this.
Consistent with all their previous statements.
Open Orphan (LON:ORPH) any insight in to why the price has dropped 10%? I guess there must be something in the RNS results that is negative?
Open Orphan (LON:ORPH) HL shows this as 14% down and "Ex capitalisation" So my guess it's to do with the capitalisation aspect.
was already heavily flagged that last year accounts wouldn't look much since they are historic and cover a period of bringing the business together/restructuring etc. It was only in Q4 onwards where the business really moved into profitability and was generating strong revenues. Didn't surprise me to see a drop in share price at the start because generally people don't listen or pay proper attention and so there will inevitably be some knee jerk sellers.
I could be mistaken but I seem to remember in a presentation 3 or 4 months back that they said they were now doing in excess of £1m profit p/m so assuming that's correct then currently sitting on around 16* earnings and giving zero value to the demerger vehicle and data business.
Thanks David, I anticipated the results with a similar understanding.
Open Orphan (LON:ORPH) will be be holding a meeting on Investor Meet Company today at 6.00pm
https://www.investormeetcompan...
My morning smallcap tweet:
Seeing Machines (LON:SEE) Open Orphan (LON:ORPH) Filtronic (LON:FTC) Loungers (LON:LGRS) Midatech Pharma (LON:MTPH) Fulcrum Utility Services (LON:FCRM) Funding Circle Holdings (LON:FCH) Toople (LON:TOOP) Volex (LON:VLX), N Brown (LON:BWNG)
Seeing Machines (SEE) its Driver Monitoring System now an option on 5 more GM cars, [SP=9.5 Cap=361m]
Open Orphan (ORPH) FY(Dec) rev £22m, net loss £10.8m. Looks a miss. Can't find a trading update despute having 6 months to do so. ORPH coughs up an RNSs almost every week! Distribution in specie of Poolbeg: Poolbeg will list on AIM. [SP=35 Cap=235m]
Filtronic (FTC) guides FY(May) rev £15.6m, broadly in line, but EBITDA lightly ahead of market expectations. at £1.8m. [SP=11.58 Cap=25m]
Loungers (LGRS) rev since indoor opening up 27% LFL on 2019. [SP=268 Cap=275m]
Midatech Pharma (MTPH) breakthrough in vitro data on the successful encapsulation of a biologic using Q-Sphera technology. Also "ignificant progress across multiple other R&D programmes". [SP=22 Cap=14m]
Fulcrum Utility Services (FCRM) £5.5m contract for powering a new 22-hectare renewably heated vegetable growing facility. That's a greenhouse. [SP=33.15 Cap=74m]
Funding Circle (FCH) has sold the SME loans in its two US warehouses for c.£63m, a Fair Value gain of c.£4m. [SP=158 Cap=562m]
Toople (TOOP) H1(Mar). Outlook "trading has returned to more normalised levels and we are now beginning to see growth return to our sales leads and conversion rates. We expect this trend to continue and have increased our sales force head count by over 30%". [SP=0.06 Cap=2m]
Volex (VLX) FY(Apr). Outlook "strong start to the new year across all regions with continued momentum in Electric Vehicles and Complex Industrial Technology" [SP=354.5 Cap=558m]
In line: N Brown (LON:BWNG)
Halfords (LON:HFD)
Does the 5p final dividend suggest management think sp is a bit toppy and/or that profitability is significantly above sustainable?
Does a company with a secure profitable franchise position need a 'transformation plan'?
Are they signalling tentative symptoms of corporate 'long covid'?
VLX Reports Full Year
On first reading
Strongest performance in 20 years underlines our potential
Revenue_________________________ $443.3m $391.4m 13.3%
Underlying* operating profit ___$42.9m $31.6m 35.8%
Statutory operating profit_____ $30.7m $17.1m 79.5%
Underlying* profit before tax __$41.6m $30.4m 36.8%
Statutory profit before tax _____$29.4m $15.9m <b>84.9%</b>
Outlook-- We have delivered a strong start to the new
Dividend 2,2p XD 16 July Paid 29 July
A live presentation for analysts will be held online at 9.00 a.m. BST on 17 June 2021
Volex (LON:VLX) Can Paul or Jack get the live presentation? Would be good to hear if they can and report back
I'm working on Volex now. I was planning on reviewing the results here first, then attending the InvestorMeetCompany presentation at 12:00 today.
I for one would really appreciate that.
Seeing Machines (LON:SEE) confirmation of new models. Especially the news they're in Mercedes is massive.
The Volex (LON:VLX) results look good. Cash reserves have gone and they have taken on some debt. Some good acquisitions. Revenue and profit growth look good. Out look looks promising with an aim to get to $650 million in revenues and $65 million of underlying operating profit by 2024.
Yes, Volex (LON:VLX) results look good and beat consensus shown on the SR.
There is a presentation at noon on IMC.
Indeed, I'm surprised at the muted initial market reaction, as this looks a considerable beat by Volex (LON:VLX) . Also current trading strong. I'm goign to have to read the narrative in full, to make sure there's nothing untoward in there, because based on the numbers I would have expected the share price to be much stronger today & going forwards. Leave it with me!
* Volex Plc VLX.L : Canaccord Genuity raises target price to 440p from 430p
See the main article. Note the headline EPS figures is greatly boosted by a one-off negative deferred tax credit! Rather misleading. Still good, but not as good as it looked initially.