Small Cap Value Report (Thu 17 Nov 2022) - BEG, FIF, WATR, IKA, CRST

Good morning, it's Paul & Graham here!
Today's report is now finished. Sorry we had to cut a few corners today, due to Mello, but hopefully we still covered enough to keep you happy!
Autumn Statement day, which I'm listening to. I'll probably comment on in this weekend's podcast, once I've studied the detail. Here's a snapshot of what I jotted down during Hunt's speech -
- It's a half:half mixture of tax rises & spending cuts, totalling £55 bn.
- Investors are being hit with effectively the phasing out of both the dividend allowance (£2k to £1k, then £0.5k over 3 years), and the same for CGT allowance (£12.3k to £6k to £3k) - that's a nasty measure, which will particularly hurt small investors.
- High earners also hit, with the 45% rate of income tax threshold falling from £150k to £125k.
- Income tax personal allowances frozen for another 2 years, so a big continuing stealth tax there.
- Windfall taxes increasing from 25% to 35% for energy company profits, and a new 45% windfall tax on electricity generators, combined will raise £14bn next year.
- Business rates revaluation will go ahead in 2023, which he claims will help smaller shops & pubs pay less.
- Nuclear power prioritised, with Sizewell C going ahead.
- Largest ever increase in national living wage, to £10.42
- Pensions triple lock maintained, increasing it by £872, largest ever increase (but it would be, in £ terms)
Those struck me as the main points, but I'll look at the detail again at a later stage.
Agenda
Paul's Section:
Water Intelligence (LON:WATR) - a detailed Q3 update, which is in line with expectations for profit. Shares look expensive, but the track record of earnings growth is impressive. Probably priced about right. No divis.
Ilika (LON:IKA) [quick comment] today’s update looks awful. Expecting a £9m EBITDA loss for FY 4/2023, with projected £14m cash remaining at that year end. So the cash runway is looking like it will be back with the begging bowl (again) probably in late 2023 or early 2024. Ilika has been promising jam tomorrow as a listed company for 12 years now, but not delivered anything of commercial substance. Occasionally there’s a speculative mania in its shares, e.g. last year was the biggest ever. It’s down almost 90% from that peak now. The market cap is £43m even after today’s 40% fall. Anyone buying or holding this share needs to recognise it’s a total punt, so for optimistic gamblers only. [no section below]
Crest Nicholson Holdings (LON:CRST) [quick comment] Trading update today for FY 10/2022. PBT in line with guided range of £135-140m. Weaker trading in recent weeks (as I would expect). Good visibility of pipeline for FY 10/2023, but forward sales of 2,038 houses is well down on LY 2,502. Net cash throughout the year, and £276m at end Oct 2022 - that's half the market cap! Complains about planning delays. We've seen peak earnings in this sector, with forecasts for 2023 reducing sharply in recent months. Also note the 4% surcharge on profits over £25m, that will hit medium to larger housebuilders. My view - CRST looks stunningly cheap, even allowing for profits to fall a lot, and is more than fully backed by NTAV. Note the big increase in cladding remediation provision, in the last interims - another sector headwind. [no section below]
Graham's Section:
Begbies Traynor (LON:BEG) (£211m) - a reassuring H1 update from Begbies, who are “confident” of meeting full-year market expectations. Organic growth is not spelled out for us, and we will have to wait longer to see the unadjusted numbers, but the adjusted numbers are looking good for the year so far. This stock continues to offer many attractive features, including excellent leadership and counter-cyclicality. I suspect that its current valuation is about right but perhaps the coming wave of insolvencies and administrations can push it even further.
Finsbury Food (LON:FIF) (£117m) - trading has continued strongly at this maker of bread and cakes since its year-end in July. Sales are up 15.7% mostly thanks to inflationary price increases but also to a little volume growth. This company has been listed for many years and has had more than its fair share of challenges over that time. A modest price to earnings multiple makes sense here but with the positive trading momentum that is underway, shareholders can hope for something better than the current 8x.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Water Intelligence (LON:WATR)
688p (up 6% at 11:29)
Market cap £134m
Water Intelligence plc (AIM: WATR.L) ("Water Intelligence" or the "Group"), a leading multinational provider of precision, minimally-invasive leak detection and remediation solutions for both potable and non-potable water, is pleased to provide a trading update for the nine months ended 30 September 2022.
It’s in line with expectations -
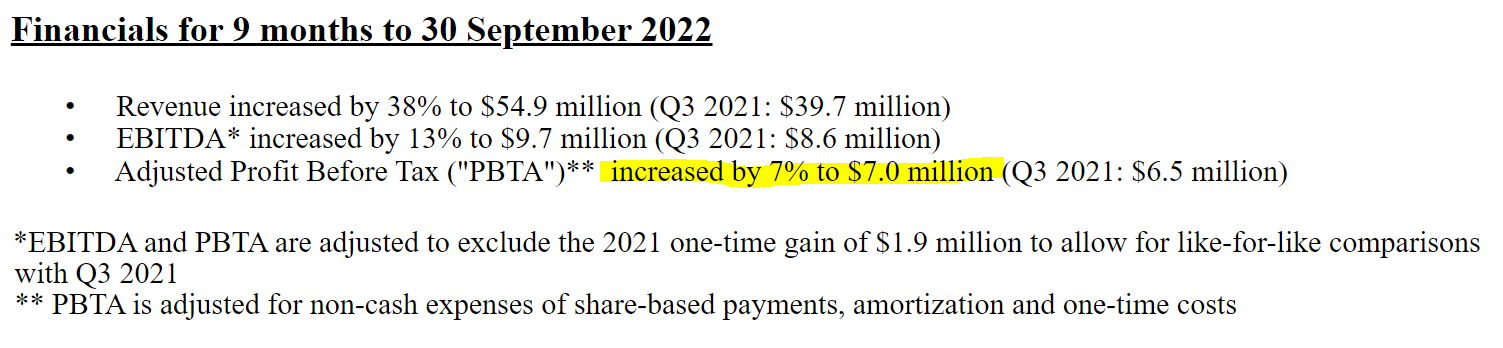
The Group is on track to be at the upper end of analyst expectations for revenue and to be in line with expectations with respect to profits for full year 2022.
Note below that revenues are up a lot, but profit is up a little -
Net cash of $4.5m
No dividends.
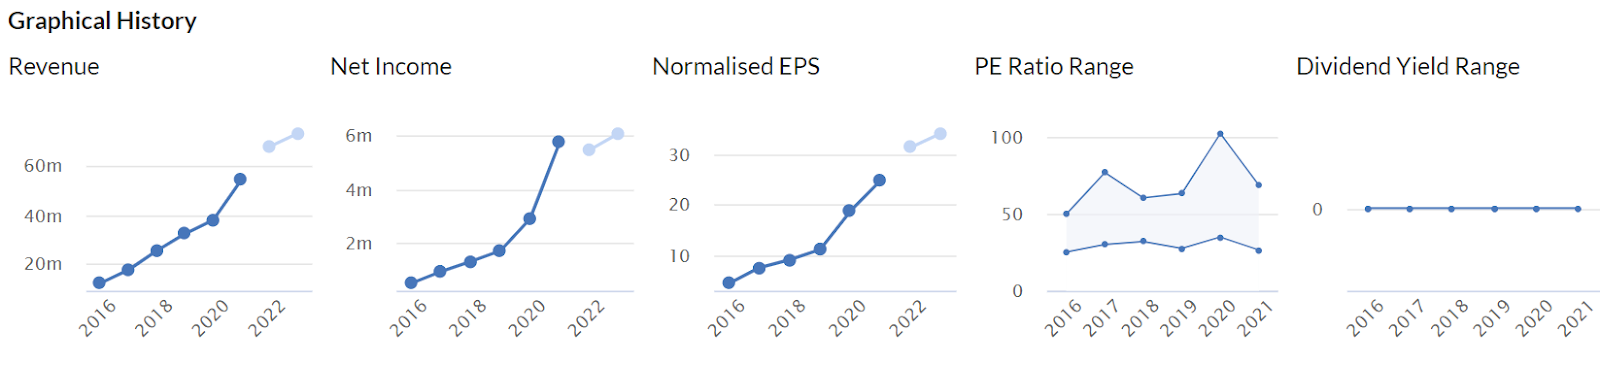
My opinion - it’s expensive, on a forward PER of about 24, but as you can see below, the track record of earnings growth is very impressive. So probably priced about right, in my view.
Graham’s Section:
Begbies Traynor (LON:BEG)
Share price: 136.75p (-0.2%)
Market cap: £211m
This morning we have a brief H1 update from this “business recovery, financial advisory and property services consultancy”.
The company is “confident of delivering market expectations for the full year”.
Headline numbers::
- Revenue +12% to £58.5m
- Adjusted PBT +13% to £9m
I also need to know organic revenue growth and reported (i.e. unadjusted) PBT, but we don’t get those numbers today. Begbies is highly acquisitive, and its numbers are heavily adjusted.
Net debt is thankfully low at £2.4m, despite over £7m in acquisition-related payments during the six-month period.
Divisional performance
- Business recovery/financial advisory: revenues +10%, with more insolvency appointments including “larger, mid-market insolvency and restructuring cases”. Begbies has 14% market share of the overall market, and 10% market share of administrations (measured not by revenues but by number of appointments).,
- Property advisory and transactional services: revenues +18%, “reflecting resilient income streams in a challenging economic environment”. This division brings in around a quarter of total revenues.
Comment by Ric Traynor (the largest shareholder in the business):
As corporate financial distress levels rise in a deteriorating economic environment, we anticipate continued momentum in activity levels in insolvency and restructuring and we are better placed than ever to take advantage of this with our expanded presence and enhanced service offering.
My view
When I read “confident of delivering market expectations”, I think: could there be a chance of an eventual earnings beat? After all, we have only just finished H1.
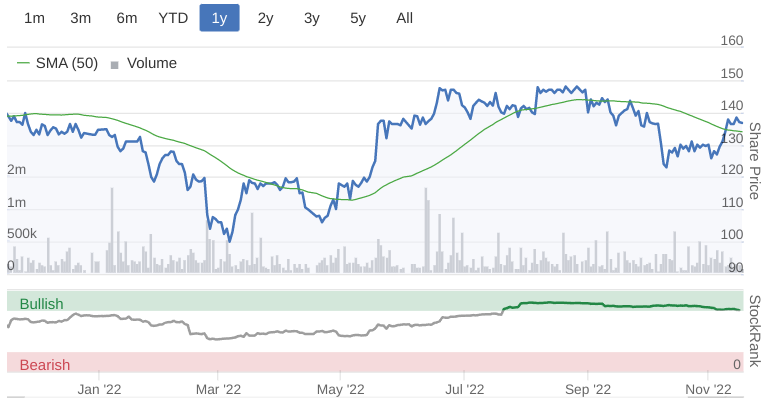
According to Equity Development this morning, their current year (FY April 2023) forecasts suggest £117.7m in revenues, £19.7m in adjusted PBT, and 10p of adjusted EPS.
The devil is in the detail and my own view on this stock remains influenced by my (perhaps excessive) caution in how I treat the adjustments to the numbers.
The earnings adjustments do show up when it comes to the company’s assets and equity: tangible balance sheet value was less than £10m as of April 2022.
And it is clearly a “people business” whose most important assets leave the building and go home every day.
But I accept that it does have real earnings power: for example, last year’s cash flow statement showed £18.1m in (after-tax) cash from operating activities, if we are willing to exclude some large acquisition-related payments.
I also remain of the view that this stock can provide a welcome counter-cyclical economic hedge for many investors.
And I’m reassured by the continued leadership (since 1989) of Ric Traynor, and by his continued presence as the largest shareholder. There’s no question about his alignment with investors.
At a market cap of around £200m and a share price of 136p, Begbies has achieved a respectable PE ratio of between 13x and 14x. Would we really want to pay multiples of 20x, for accountancy and advisory firms with fairly empty balance sheets? Personally, I don’t think so.
So these shares look fairly and fully valued to me. Even so, the economic winds could carry it higher in a recession and for that reason alone it remains interesting.
Finsbury Food (LON:FIF)
Share price: 90p (-1%)
Market cap: £117m
This “leading UK specialty bakery manufacturer of cake, bread and morning goods for both the retail and foodservice channels” has been holding its AGM this morning.
Paul covered their recent full-year results in detail here.
Today we have the following news:
The robust performance of the previous financial year to 2nd July 2022 has continued into the current financial year. Sales for the first four months of FY23 grew by 15.7% to £122.8m, driven by a mix of volume growth of 1.1% and price recovery of 14.6%. Our retail business continues to perform well, foodservice continued to bounce back, and our overseas division continued to see strong growth.
I wish every small company was so transparent in explaining where its revenue growth was coming from (volumes versus price inflation). At Finsbury, we can understand from the above that most of the recent revenue gains are derived from inflation, and that makes sense.
Food and beverage inflation is currently running at 16.4% according to the official numbers, so this all adds up.
There is no relief yet from these trends:
The macro-economic and cost inflation headwinds that we have had to face throughout the opening months of the new financial year have been at levels in excess of those experienced in FY22.
The solutions? “...revised commercial arrangements, operational improvements and other supply chain and overhead initiatives.”
Given the increased cost of living, and the need for consumers to get value for money, Finsbury thinks there could be a boost in supermarkets’ own label sales, which would be good for business.
My view
I won’t rehash Paul’s analysis of the finals, so there isn’t too much for me to add. I will reiterate that I think food and fuel-related stocks are a nice place to be invested when it comes to the inflation trend, as they should have little difficulty passing on increased costs to their customers (“revised commercial arrangements”, in Finsbury’s language). There are exceptions, but most food producers seem able to do this.
As it’s a commoditised industry, food manufacturers do tend to trade cheaply. So I agree with Paul that the likelihood of a PE re-rating is somewhat limited. Although having said that, FIF has achieved 12x-13x from time to time. That suggests up to a 50% boost from the current 8x, if trends remain positive.

Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

27 comments
Perhaps some one can help me being newish to investing and not the best maths person in the world. I'm looking at Severfield and from Stockopedia stock reports, plus Severfield balance sheet and even their last annual report they are reporting NO CASH. How do they operate with no cash. If im being thick please forgive me. I also do not know if i'm informed to a reply to this note or have to keep looking. Thank you
They have negative working capital.
hi Derek12
re Severfield (LON:SFR) - you are correct that on their latest balance sheet they do not have any cash balances. However they do have £9m of long term debt and £6m of short term debt (both net of lease liabilities). Hope that helps.
Snazzy
Wonder what's put a rocket up Mulberry (LON:MUL)? Can't see any news. Bid coming?
I heard someone bought a bag for his wife and daughter - given the price of them, that's what led to the SP increase! :-)
Titon holdings
Some stock available today at 77.5p. , doesn’t normally drop this low .
Sub 9m cap , stuffed with cash and freehold property and making profits .
Harwood and Jupiter have been building stakes .
Illiquid micro cap value trap so be warned but looks a good entry point .
The window ventilation they make has just become a regulatory requirement .
I’m liking it a lot and Harwood don’t mess around .
Titon Holdings (LON:TON) I hold. Had to add this so I could right click on the link and then chose to get it in a new tab. It's all about functionality really. Having checked, the Board have been in place for a matter of months, the float is low and the spread wide so tomorrows Taylor Wimpey (LON:TW.) dividend is likely to be added elsewhere.
Spread is wide yes , float is low yes - at the end of the day it’s a risky AIM micro cap and not to everyone’s taste and pretty high risk if yiu might need cash quickly
It definitely isn’t one for traders or speculators .
On the plus it’s easy to understand and the company is willing to engage with Pi , Booked myself in for a look round and was well received .
I’m happy enough as the share price is pretty much covered by property / cash and I’m a huge fan of Harwood so will follow where they go .
But I’m not going to keep it pretty low key for now and not put the kids inheritance into it .
They also seem to have had a bit of an ERP systems meltdown this summer which I have experience of and that should be a one off issue
It’s just a decent each way long term bet and I can understand the business .
planetx: re Titon Holdings (LON:TON) I don't see stake building by Jupiter in the past 12 months RNSs, only that they have just taken over as fund manager of Northern Trust. When were the RNS showing stake building by Jupiter?
Integrated Diagnostics Holdings (LON:IDHC)
I know there are a few of us that follow/hold this share. Q3 results this morning. They delivered a net loss over this quarter and a significantly reduced operating profit (from being very profitable up to this point). Reasons are two-fold: one a (one-time?) large charge to exchange Egyptian £s into dollars to pay the dividend (I assume this is a consequence of getting caught the wrong side of the large devaluation of the Egyptian £, although they don't say explicitly). Two: operating costs have gone up very significantly ahead of revenues. On point 2 they explicitly say that "despite the more than 50% depreciation in the EGP since March 2022, we have refrained from passing on the burden to our patients through price increases during the past months.". So in my opinion there is a significant risk that they will be barely profitable at the operating level next quarter. There is even less chance ( I would say zero) of them hitting the current broker forecasts.
Thanks, Robert W, for calling out these important details on Integrated Diagnostics Holdings (LON:IDHC) (I hold). Good growth, though.
Ilika (LON:IKA) - I think the only good news I can see out of this company today is that the bad news didn't look like it leaked very much to insiders.
But really disappointing otherwise. I doubt it has the cash that it needs to burn without a raise at a heavy discount to the 40% down today. I guess they could try and get through - but further bad news and they'll be selling even cheaper. £18m left with £10m p.a. burn.
FY23, 24 and 25 downgraded.
Was the CFO push or jumped? Seems unlikely to be his/her fault from the RNS
Anybody still got optimism on this one?
I am unable to judge whether Ilika (LON:IKA) actually has world class technology that makes it real player in the race for a solid state car battery ( for example). But regrettably I am fairly sure that even if it is world class Ilika is taking a very gentlemanly British pace to achieving what management appears to project as a jolly interesting solution to the problem, with a five year build to viable production business.
If it is the real deal then we need a fire breathing entrepreneur who can find a billion dollar backer and a burning desire to get insanely rich - as fast as possible. There are not a lot of Bezos/Musk/Zuckerberg types in British industry (more’s the pity) but IF the technology is good we sorely need one here. If the technology is not a world class solution then five years is far too long to decide.
The smaller batteries are more important. Get them going and they'll pay for Goliath.
Not a holder but have held in the past.
Yep - I think they should focus on the niche of the smaller ones, the big batteries are a massive capital sink with way more competition, that will be won by the Chinese. The medical scenario is one that is heavily regulated, that would suit the "steady as she goes" approach. There seems little fire in this one's belly.
Oh course the UK govt are backing a competitor (£100m) for multiples of the Ilika (LON:IKA) MCap. Oh wait - didn't that hit the buffers?
https://www.constructionnews.c...
The problem with Begbies Traynor (LON:BEG) is that the "wave" of insolvencies is always "coming" and "just around the corner". Granted, there's still been decent growth and their acquisitions have proven to be OK so far.
(I hold in the Boon fund)
I think as a people business, and having a friend who works for a similar company, is how flat out that you can make your staff work?
From my friend, poll of 1 obviously, he is flat out busy has been for a long time, his team are, and doesn't matter if more work comes in it just joins the queue. To grow you have to poach from someone, solves an immediate problem until one of yours goes the other way. So they tend not to bother with that approach.
A trickle coming in from the bottom, but takes years to get the experience and qualifications, so hence quickest way is just buy up the small local practices, keep the contacts with the solicitors that refer, and look after the existing teams so they don't want to leave.
Or to liken to my own trade, Construction, when the government announces that they are going to increase expenditure within a particular sector from £100m/year to £1bn/year it is like and who the beep has the staff to do this??? We do not want a wave, but it makes nice reading if you are trying to put a spurt on the SP.
Overall a happy holder, been in and out a bit, and just have to learn to ignore the short term stuff.
Tommy
Begbies Traynor (LON:BEG) I hold
totally agree, I don't doubt they have a solid revenue base and good expectations of uplift in the future but I've always looked at this on a p/e basis and thought "jam tomorrow" in terms of valuation Vs reality. The market seems to have lapped up the "just around the corner" narrative seemingly though..
the issue I see with begbies’ update is that revenue was only £58m. That’s a 12% increase on h2 2021, but is basically flat on h1 2022 (£57m), whereas the trend has been steady increases for each of the last 6 or 7 6-month interims.
I was expecting a decent increase in revenues versus the prior 6m. Perhaps they’re working at capacity for the workforce they have, or they just had smaller cases to deal with. We’ll see.
I still hold, as the economic landscape suggests they should do well for a while yet, but I was hoping for better.
This was interesting;
https://open.spotify.com/episode/3ZMM9tIandNwXkYhOniVS2?si=jANzY1TPQ42sYtyvkiJuOQ&utm_source=native-share-menu
In the middle there is a section on company dividends.
I'm a big fan of Freakonomics - they occasionally cover finance stuff and there has been good coverage of Crypto and also on a tangent, the art market. Fascinating.
Wynnstay
Looks a nice little acquisition
1.5 million for tamar as below .
Tamar generated revenues of £6.40m, and
a profit before tax of £0.42m. Net assets at 30 September 2021 were
£0.92m.
That looks a no brainer, not a huge deal so not sure why Wynnstay felt the need to raise 10 million (think it was that ) in the recent discounted fund raise .
Steady as she goes as always, great well run company just doing the day job, asset backed with cash, paying a dividend in a sector the economy needs .
Looks a bulletproof company and one of the best well run long term holds on AIM .
I like Wynnstay and they have benefitted from increased prices over the farm gate, but with food inflation close to peaking maybe it's a good time to take some profits?
The old farmer is as tight as they come and I note a downgrade in profits 2024, so Wynnstay can see this coming perhaps?
I don't hold TBF and I guess the above is what puts me off buying in.
They just have such a great track record of profits and dividends Im happy to sit and hold.
They dont seem to be valued on this years bumper profits at all but future profits which are in their forecasts at normalised levels .
As a 10 year hold I cant think of too many AIM shares with such a good track record, and the IHT cover is a key factor, and they just keep building and making these little additions at great prices , integrating into the overall and just building it nice and slowly.
Personally I think they will maintain higher profits than forecast and the "one off bumper" profits will not be as one off as speculated . But thats a "nice to have" and as a 10 year steady away sit and hold and forget about it holding its one of my favourites ,
"That looks a no brainer, not a huge deal so not sure why Wynnstay felt
the need to raise 10 million (think it was that ) in the recent
discounted fund raise ."
Seems like they didn't close a potential larger acquisition, from today's RNS:
"The acquisition of Tamar is the potential acquisition referred to in the
Company's announcement of 17 August. The second larger potential acquisition
referred to in the same announcement is no longer under consideration as
commercially acceptable terms were not reached. The Company continues to
review a number of acquisition opportunities that meet its strategic
priorities."
#BEG as the boys may be busy @Mello , here is the ED research note out on Begbies' positive H1 trading update today: https://www.equitydevelopment....