Small Cap Value Report (Thu 17 Oct 2019) - BEG, NXR, IGR

Good morning, it's Paul here.
Estimated time of completion - not sure yet, probably about 3pm. Update at 14:40 - today's report is now finished.
There's not much to report on today. I'll start by looking at trading updates from IG Design Group (IGR), and Norcros (NXR) - both of which I rate as decent companies.
** Breaking News **
The Govt & the EU say they have reached a deal on Brexit. The question now, is whether it will get through Parliament or not? If it does, then I think we could light the blue touchpaper for a recovery in small caps shares. Maybe.
Begbies Red Flag Report
The above is a clickable link through to this interesting report for Q3 (as are all words shown in blue, just in case anyone didn't already know that).
Unsurprisingly, this shows an increase in companies in financial distress.
No surprises on the sectors worst affected either;
... real estate and property, construction, retail and travel sectors the most severely affected.
I find it useful to read these reports, as it helps to put my investing in perspective. In particular by showing us which sectors are suffering, that might enable us to exit from something which could be building up to a profit warning.
Norcros (LON:NXR)
Share price: 223p (price unchanged today, at 11:24)
No. shares: 80.5m
Market cap: £179.5m
Norcros, a market leading supplier of high quality and innovative bathroom and kitchen products will announce its interim results for the 27-week period ended 6 October 2019 on 14 November 2019. In advance of this, the Group is providing the following trading update.
I would have expected a bathroom fittings company to be suffering at the moment, due to the generally wobbly economic outlook. That doesn't seem to be the case, which is encouraging for shareholders here;
Group underlying operating profit1 for the first half is expected to be in line with the Board's expectations, a resilient performance reflecting the Group's continuing success in winning share despite the challenging market conditions.
The stand-out growth in revenues of +24.5% in South Africa is purely due to the acquisition of House of Plumbing. LFL revenues were flat against last year's H1.
The UK eked out a LFL growth in revenue of 1.3%.
Net debt - has come down nicely;
Net debt is expected to be approximately £42m (2018: £53.5m), in line with expectations following the acquisition of House of Plumbing in the first half of the year.
Management has done a great job in recent years, in balancing the funding of acquisitions, pension scheme recovery payments, and divis for shareholders. All achieved without overly stretching the balance sheet.
Outlook - solid;
The robust performance in the first half against the backdrop of challenging conditions in our two main markets demonstrates the resilience of the Group's strategy and operating model. The fragmented nature of our markets continues to provide growth opportunities for the Group as we maintain our focus on winning market share.
The Board remains confident that the Group's leading market positions, portfolio of strong brands and financial strength will enable further progress in line with its expectations for the year to 31 March 2020.
Valuation - looks superficially very attractive, but we do have to adjust for the humongous pension schemes. Although checking the last accounts, note 7(a) discloses that the pension deficit payments were £2.6m in FY 03/2019. That's not actually too bad, and quite modest compared with £6.4m in dividends paid to shareholders. So maybe the pension deficit isn't as bad as some investors might perceive?
The valuation figures look very appealing, and quality isn't bad too;

The problem is that this share is permanently cheap. What would trigger a re-rating? Still, I would rather hold something that's permanently cheap, than something inexplicably expensive!
Stockopedia's computers absolutely love Norcros;
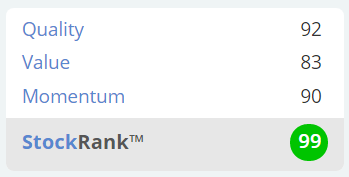
My opinion - the figures look great, this looks an excellent value share.
The trouble is, it never seems to re-rate, despite strong performance. So shareholders tend to get bored & drift away, when they spot something else with more immediate upside potential.
For the patient investor though, I see Norcros as being attractively valued, and you get a 4% (growing) divi yield while you wait.
There's economic & political risk from having operations in South Africa too.
Performance in the UK has so far been resilient, but there's no guarantee that will remain so.
Overall, this gets a thumbs up from me. It's a decent group, with good management, performing well, and dirt cheap!
IG Design (LON:IGR)
Share price: 620p (up 0.7% today, at 12:32)
No. shares: 78.6m
Market cap: £487.3m
IG Design Group plc, one of the world's leading designers, innovators and manufacturers of gift packaging, greetings, stationery, creative play products and giftware, announces a trading update for the first half of the financial year, which covers the six month period to 30 September 2019.
This group continues its excellent track record;
The Group is pleased to report a strong performance over the period; on track to meet full year market expectations, with the business delivering double digit year on year growth in revenue and operating profit.
The Group continues to deliver strong cash generation and as a result we expect year end average leverage1 to show further improvement against the prior year, reaching around 1.1x.
Note that the group has large swings in its leverage during the year, to cope with seasonal trading peaks. That raises the question of how we should value the shares? Personally, I would like companies to disclose the average daily net debt/cash figure. That is what should be used when calculating enterprise value. The problem with balance sheet figures, is that they're a snapshot on one day, and all good CFOs make sure that the figure is nicely window-dressed to look favourable on the balance sheet date. Hence why enterprise value can be quite a dangerous method of valuing companies.
Outlook - sounds good;
As the Company begins the second half of the year it continues to benefit from a strong order book together with major commercial and operational initiatives and investments throughout the Group, which will support the growth going into FY21.
Acquisitions - described as an active pipeline.
My opinion - IGR gets a thumbs up from me.
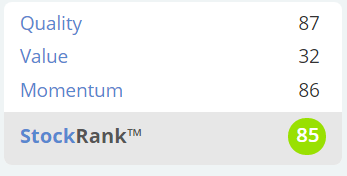
It's established an excellent track record, and there's no sign of that faltering. Hence I think the forward PER of 18.5 looks fully justified.
Stockopedia's computers also like it a lot;
That's it for today, see you tomorrow.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

20 comments
Hi GavSmith01,
Minor pedantic point - the header says 2017.
<CaptainMainwaring> Well spotted Smith! I was wondering how long it would be before anyone noticed my deliberate mistake! </CaptainMainwaring> ;-)
Best wishes, Paul.
Minor pedantic point - the header says 2017.
The problem with balance sheet figures, is that they're a snapshot on one day, and all good CFOs make sure that the figure is nicely window-dressed to look favourable on the balance sheet date.
I used to work for a business which for a number of years profited from a predictable annual windfall from increases in excise duty. This necessitated taking on additional stocks which were being carried at the year end and liquidated over a 3 month period thereafter. The balance sheet therefore showed a consistent high level of debt (to fund the additional stock) and a high stockholding. By changing the year end date these distortions were removed and the business suddenly appeared to be in better health. But nothing had changed except the date on the balance sheet. I therefore endorse Paul's comment that companies should show their average daily net debt/cash figure. However if it's not compulsory, or demanded by analysts, I suspect the only ones who would do this are those who would benefit from it and the ones which manipulate the year-end figures to show reduced debt would not do it.
"I therefore endorse Paul's comment that companies should show their average daily net debt/cash figure".
You can often get a good handle on this by looking at how much interest the company paid/received during the year.
"You can often get a good handle on this by looking at how much interest the company paid/received during the year."
Unfortunately that has become potentially more tricky following IFRS16. Take RTC (LON:RTC) interims for example. The "Financing expense" in the P&L for the 6 months has increased from (61) in previous H1 to (94) in the current H1. That seemed strange to me given that the balance sheet debt had reduced - it turns out that previous H1 is fully (61) debt interest, but current H1 is made up of (44) debt interest and (50) that is nominal (pretend?) interest on lease liabilities, that used to go through as part of administrative expenses previously, presumably as a simple rent payment.
“whether it will get through Parliament or not? If it does, then I think we could light the blue touchpaper for a recovery in small caps shares. Maybe....”
I think that this will be short lived as recession bites. I am therefore happy to stick to my “hell in a hand basket” strategy of 45% of portfolio invested in $AAZ and $RRE and the remaining (no pun intended!
PS (doesn’t seem possible to edit comments on the new site) I would add that I am not saying that these holdings are not uncomfortable at the moment.
Hi purpleski,
I think there's a lot of cash sitting on the sidelines, with investors who have just gone on a buying strike, until the outcome of Brexit became known.
Therefore, assuming Parliament agrees the deal this Saturday, then next week could see some investors start to put cash to work, in stocks that have been irrationally sold down this year.
I think we would also see a big boost to consumer confidence figures too. Given that the consumer is the major part of the economy, and on paper is looking healthy, with largely full employment combined with good real wages growth at the moment, then I could see the economy doing better than most people seem to currently expect.
Plenty of companies must have put investment decisions on hold due to Brexit. The handbrake there could therefore be released. Same with takeover bids for smaller companies - I wonder how many might be simmering on the back-burner, waiting for a Brexit outcome?
This could all create a scenario where some really bombed out shares might stage a decent recovery. I think that's the most likely scenario, but it's all guesswork really.
Regards, Paul.
Tatton Asset Management (LON:TAM) AUM up to £7bn. At these levels you're getting 25% growth at 16x and a yield of 4.4%. Acquisition announced in line with IPO strategy, making use of operational leverage. Coverage on the trading update can be found here: https://equitydevelopment.co.uk/edreader/?d=%3D%3DgN0YjM
Norcros (LON:NXR)
Paul
The problem is that this share is permanently cheap. What would trigger a re-rating? Still, I would rather hold something that's permanently cheap, than something inexplicably expensive!
I think we are in the middle of the re-rating now and the trigger is the much reduced materiality of the pension problem and also but slightly less so the confidence that acquisitions and debt levels are well managed and proving themselves.
The pension deficit at 31/3/2017 was 55 mill and the company had net profit of £13 mill
at 31/3/2019 deficit was £32 mill and net profit current year is expected to be £29 mill.
Ok debt is higher now than it was back then but by less than one years profits. Note those two pension deficit comparisons are probably skewed by revaluations that go up and down like a yo-yo
If they can post a clean year of higher profits ye 31/3/2020 with acquisitions fully bedded in and debt reducing - that simply leaves the minor quibbles about organic growth and high earnings from Africa which is probably a risk factor being a less developed company.
In summary this is a different beast to where it was 3 years ago and i would expect the re-rerating to be due it being a different beast and the market will eventually twig.
The shareprice is now well above the average of where it has been over the last 5 years and i think it did very recently reach a 5 year + high.
Interestingly it now shows up on Value Momentum screen , the Josef Lakonishok Momentum Screen and the Naked Trader-esque Screen (in Growth Investing).
I am not an expert in screens but i am guessing these 3 screens are all looking for positive momentum in the shareprice and they are seeing it here.
RE: Norcros (LON:NXR)
In summary this is a different beast to where it was 3 years ago and i would expect the re-rerating to be due it being a different beast and the market will eventually twig.
I'm not sure I buy this. Surely any re-rating will be down to bond yields increasing and the pension deficit melting away in a post Brexit world where interest rates are on an upward path. All they would need to do trading wise is just to plod along.
All the best, Si
Re £NXR - it remains cheap for good reason with 5 major 'risks' attached (£:$, Housing cyclical, (relatedly) wider UK economic cycle, exposure to South Africa, Pensions).
Of these only Pension is peaking as it will decline as scheme is closed , pensioners die off and the legacy scheme becomes a smaller part of group. All the others will likely remain and are mostly negative risks ie more likely to cause at least a temporary problem than not.
The only way it can re-rate much is if it is involved in successful M&A to create more operational leverage: its ambition is to near double to £600Mn pa by 2022 . This could be £NXR either doing more buying & integration of small family businesses, possibly in new geogs to leverage capabilities or, less likely, being acquired, say a building group wanting to reduce their own cyclical risk. It's bought well so far but I am not sure I want to rely on this.
I have held for several years and enjoyed some modest capital gains and steadily growing dividends but think it almost fully valued now given the ongoing risks. I sold some at 240p and will sell out completely if it reaches that again.
Any chance of a ramble on Alpha FX (LON:AFX) Paul looks expensive but keeps producing the goods with latest update saying will beat expectations for this year.
Thanks
Hi clarea,
Sorry, I don't cover financials, hence don't cover Alpha FX (LON:AFX) . It's necessary to restrict our sector coverage, to give a manageable number of companies to cover (which is approximately 600 at the last count - so quite a lot!)
Looking at AFX's StockReport, its track record (the historic graphs) looks very impressive.
Stockopedia sees it as very high quality, with strong momentum, but not cheap (poor value score).
Regards, Paul.
No worries Paul forgot probably more the kind of stock to give Graham a nudge about at a future date thanks for your daily efforts.
This is of interest if you're interested in private equity markets. This was filmed at Mello May 19, but has only just been made public.
Pantheon International (LON:PIN) is a fund giving exposure to private equity markets. In this 30 mins presentation Helen Steers gives a good overview of private equity v public markets. Whilst Andrew Lebus talks about the performance of the Patheon International fund over the last 30 years.
Norcros (LON:NXR)
Pleasing update from nxr that they are track to meet year end expectations at the half may mark (all 27 weeks of them).
Note there is minimal lfl growth of 0.9% but prior acquisitions are bedding in nicely and they had no notifiable lfl growth in first 13 weeks so slight uptick.
Debt is well in hand at £42 mill compared to £53.5 mill at same time last year - note in the last 12 months they have shelled out £12.1 cash mill on a new acquisition too .This reduction isn't quite as good as it seems though as they had debt down to £35.1 at 31/3/2019 one day before the £12.1m acquisition - so 6 month drop is a more meagre £5 mill practicably speaking.
Although they are only on target to meet expectations the stock numbers have slowed a slow and steady uptick in forecasts during the year.
PE remain 6.33 (could have sworn is was 6.7 when i got out of bed and looked this morning) so i will continue to hold in the long awaited for reversion to pe of 10 one pension deficit and debt is totally eliminated - i may be waiting some time.Main danger here is they pay over the odds for duff acquisition in the future.
Norcros (LON:NXR)
Nice cash flow generation
In 2019 generated 28.9m after tax and interest paid. Then spent 5.6m on capex and 6.4m on dividends, so dividend cover looks good. Net debt 35m and pensions deficit 31.6m which they have agreed to fund by paying 3.25m per year plus CPI into the pension.
Only question is, is organic growth tapped out and they have to make acquisitions to grow?
Norcros (LON:NXR)
Only question is, is organic growth tapped out and they have to make acquisitions to grow?
Good question - looking at last 3 years we have - 2.3% , 4.4% and 4.1% "constant currency lfl" so holding their head above water inflation wise although it may be that costs have increased at a higher % than this perhaps? all a bit tricky to work out detailed numbers in that regard with the acquisitions they have made. At least the numbers are above nothing !
2019
Group revenue for the year was £331.0m, 10.3% higher than the prior year on a reported basis, 11.6% higher on a constant currency basis and 2.3% higher on a like for like constant currency basis.
2018
Group revenue for the year was £300.1m, 10.7% higher than the prior year on a reported basis, 8.6% higher on a constant currency basis and 4.4% higher on a like for like constant currency basis.
2017
Group revenue for the year was 271.2m, 15.0% higher than the prior year on areported basis, 10.6% higher on a constant currency basis and 4.1% higher on a like for like constant currency basis
My morning smallcap tweet:
Alpha FX (LON:AFX), Grafton (LON:GFTU), Tissue Regenix (LON:TRX), Feedback (LON:FDBK), Mobile Streams (LON:MOS), Northern Bear (LON:NTBR), Discoverie (LON:DSCV)
Alpha FX Group (AFX) guides FY earnings ahead of current market expectations.
Grafton Group (GFTU) guides FY op profit (cont) 4-8% below mkt consensus.
Tissue Regenix (TRX) curse of H2 weighting - delay in increasing output means FY rev below market consensus by ~15% to 20%.
Feedback (FDBK) re new Bleepa product: "advanced discussions with NHS pilot sites whilst additionally pursuing a number of commercial opportunities within and outside the NHS, and hopes to commence pilot schemes in the near future."
Mobile Streams (MOS) CFO resigns from board but remains CFO! What is he up to?
Northern Bear (NTBR) directors will not tender their 16% to the external offeror (72p). I hold.
discoverIE (DSCV) £33m placing at 415p (4% discount) to fund £58m (+ £12m contingent) takeover.