Small Cap Value Report (Thu 17 Oct 2024) - MNDI, RTO, RNK, GBG, AJB

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
** New SCVR summary spreadsheet for calendar 2024 ** This is the live one! (updated 6/9/2024)
Archive - SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia. More stock screening strategies here (possible bargains?) - 21/9/2024.
Companies Reporting
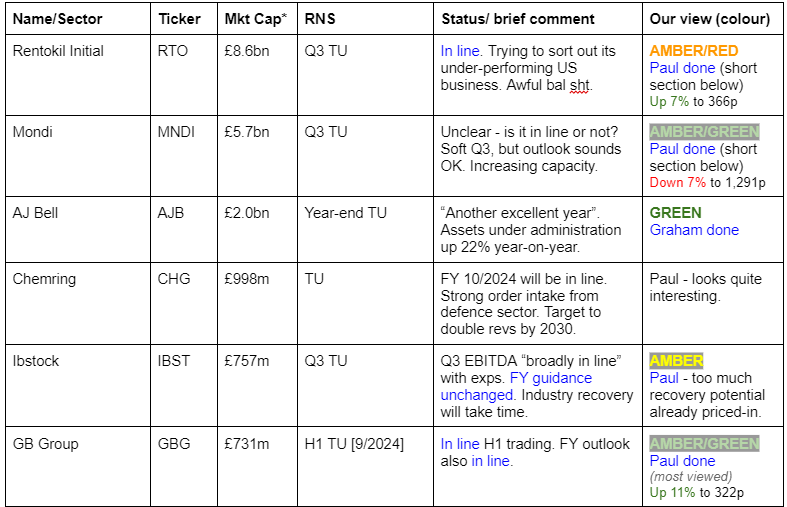
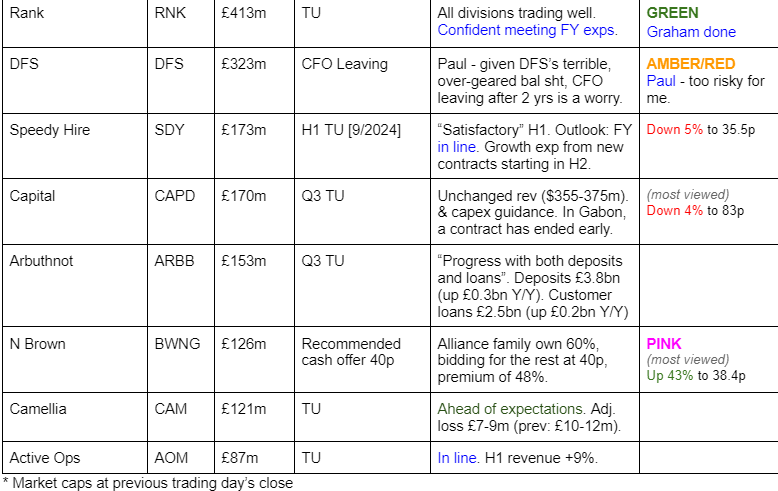
Summaries
Rank (LON:RNK) - down 1% to 87.1p (£408m) - Trading Statement - Graham - GREEN
This casino and bingo hall operator is confident of delivering profits in line with expectations, although it doesn’t provide readily available research notes or information re: estimates in the RNS. Even so, I’m a long-term fan and with revenue growth at 12% I’m excited about what it might achieve.
AJ Bell (LON:AJB) - down 1% to 476.5p (£1.97 billion) - Year-end trading update - Graham - GREEN
A confident update describing another “excellent” and “successful” year. Assets under administration rose 22% while in investment management, AUM rose 45%. At a PER of 23x it’s not cheap but I think it does deserve this rating so my stance is unchanged.
Paul's Section:
Other mid-morning movers (with news)
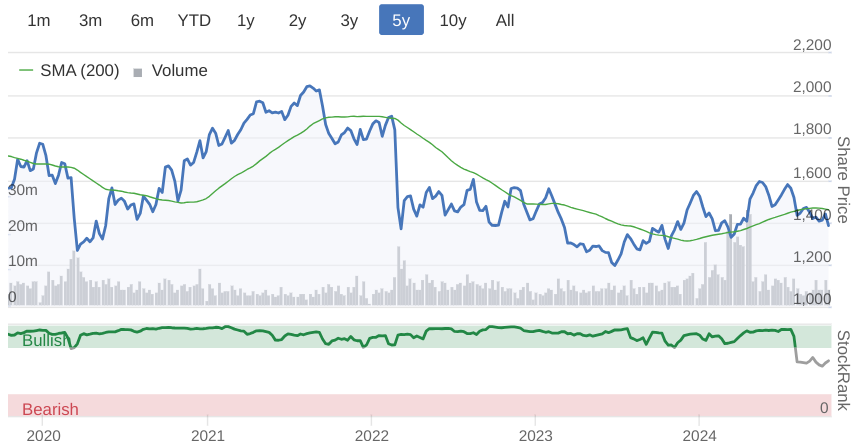
Mondi (LON:MNDI)
Down 7% to 1,291p (£5.71bn) - Q3 Trading Update - Paul - AMBER/GREEN
An adverse market reaction to a soft Q3 trading update from this paper/packaging group, which mentions “muted” market conditions. Annoyingly, it isn’t clear about performance or outlook vs market expectations.
“Underlying EBITDA for the quarter was, as expected, lower than the previous quarter, at €223 million (Q2 2024: €351 million). This was primarily due to more planned maintenance shuts and a forestry fair value loss, which together resulted in a difference between the third quarter and second quarter of approximately €90 million. This was in addition to softer seasonal demand and higher input costs.”
Outlook -
“In the fourth quarter there will be fewer planned maintenance shuts, and we expect the normal seasonal pick-up in demand.”
"Our expansionary projects remain on track... our organic growth investments are expected to deliver a meaningful EBITDA contribution from 2025.”
Paul’s view - just a quick review, I think MNDI shares look quite attractive for value investors. Reasonable PER of about 12x, good yield of c.4.4%, and solid asset backing. Profit margins seem to have been under pressure in recent years. Cyclical recovery possible? Not bad, so I’ll give it AMBER/GREEN.
Rentokil Initial (LON:RTO)
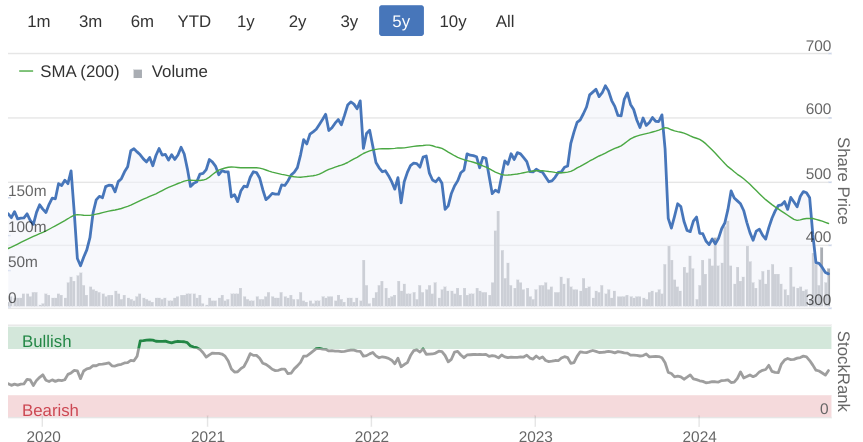
Up 7% to 366p (£8.6bn) - Q3 Trading Update - Paul - AMBER/RED
Guidance unchanged, so I’m struggling to see what justifies a 7% bounce today?
It sets out actions being taken to sort out its under-performing US business, also integration of the large Terminix acquisition.
“FY 24 revenue and margin guidance unchanged”
“Year-end leverage expected to be unchanged at 2.8x”
Paul’s view - this looks a bit of a mess, and broker forecasts continue to be in a downward trend. Management have wrecked the balance sheet with too many acquisitions, too much debt, and as a result NTAV is negative £3 billion! So definitely not of interest to me. It’s striking how cavalier some mid to large companies are re their balance sheets, and debt. Surprisingly, we often have to look at smaller companies to find more secure balance sheets with net cash.
Paul’s Section:
GB (LON:GBG)
Up 11% to 322p (£814m) - H1 Trading Update [in line] - Paul - AMBER/GREEN
“Today, GBG, (AIM: GBG) the expert in global identity fraud and location software, provides an update on its performance for the six months to 30 September 2024.”
Strong 1H25 results: FY25 outlook reiterated
This update sounds clear, and confident -
“The Board is pleased with the strategic progress and financial performance that GBG has delivered in the period. This performance is in line with our expectations and underpins the Board's confidence in reiterating its FY25 outlook.”
It’s perhaps surprising that an in line update has triggered an 11% share price rise today, but the context is that there had been a declining share price trend (possibly Budget fears related, as GBG is one of the larger shares on AIM?) Hence I think today’s solid update reassures the market that there’s nothing wrong with the company fundamentals -
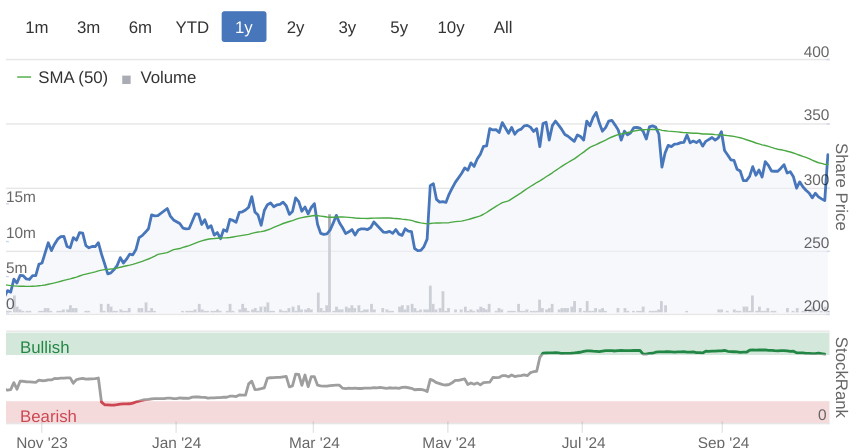
H1 revenue growth is modest, at +4.5% (constant currency) to £137m.
Cost-cutting has produced a good increase in profit margin -
“As a result of our revenue growth in the last six months and the continued benefit of our group-wide cost and simplification initiatives executed in the prior year, the first half adjusted operating profit¹ grew by approximately 21% to £29 million, representing a margin of 21.2%.”
Balance sheet -
“Our balance sheet remains strong…”
No it isn’t! Goodwill and other intangible assets total a huge £743m (at 3/2024). NAV is £625m, hence NTAV is negative £(118)m, a deficit that is funded by borrowings, with net debt at £80m (excl negligible lease liabilities) at 3/2024. It said with the full year results that debt reduction remains a priority, and it came down nicely in FY 3/2024 - demonstrating that GBG does generate good free cashflow to reduce debt.
Net debt has come down further now, so this issue is being dealt with and isn’t a deal-breaker for me, but it helps explain why the 1.6% yield is so modest -
“...with good progress in lowering net debt, which as at 30 September had reduced to around £72 million (31 March 2024: £80.9 million). This includes the FY24 final dividend payment of £10.6 million and a £5.0 million retranslation benefit given the relative strength of pound sterling since our FY24 results.”
It would be more accurate for the company to say we’ve got a weakish balance sheet, but it doesn’t matter because it's a capital-light business model, we get paid up-front by customers, and the debt is being paid down gradually, and is manageable at a fairly modest multiple of EBITDA. Hence my trust in the company & its commentary is lower-middle, due to this clumsy attempt to gloss over the balance sheet weakness.
Outlook - sounds OK, although the growth rate doesn’t excite. Is it realistic to expect higher growth in subdued macro conditions though? Maybe not. There could be a cyclical upturn in performance around the corner, in which case this share could be more attractive than it currently looks.
“With the strong progress achieved by the business in the last six months and positive momentum moving into the second half of the year, the Board reiterates its FY25 outlook. We expect to deliver mid-single-digit revenue growth on a constant currency basis, leading to high single-digit growth in adjusted operating profit.”
Valuation - no broker updates available today. Let’s go with the 17.1p broker consensus figure on the StockReport, which at 322p/shares gives us a PER of 18.8x. Given that net debt is c.10% of the market cap, I’m going to round that up to about 20x - which looks a fair price to me.
Historically GBG shares went crazy, and it became wildly overvalued after one of AIM’s best multibagging runs - indeed I can remember discussing this share over lunch with a friend called Mike, and we both thought it was quite good value at c.20p. But then nothing much happened for a couple of years, so I sold out of boredom. Another example of where a major multibagger wasn't at all obvious in advance of it multi-bagging (especially as a lot of the growth came from acquisitions).
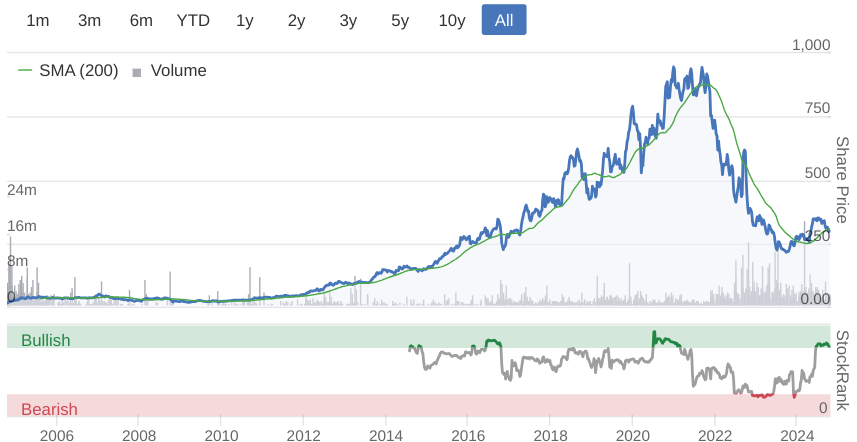
Paul’s opinion - we can now buy at about a third of the 2021 peak of c.950p - is it a bargain then? Not really, I think it’s just reset from an unrealistic over-valuation to something more reasonable. The growth is quite modest now (remember c.20% earnings growth in H1 was driven mainly by cost-cutting, which only happens once). Hence I think a PER of about 20x is a sensible valuation for a modestly growing, but decent quality company.
Cashflows are quite good too, so as debt reduces it might be able to pay more generous divis. That’s assuming management doesn't once again go on the acquisition trail.
Overall, I think this is a creditable performance in tough macro, so I should probably see this share modestly positively, let’s up it a notch to AMBER/GREEN.
Graham’s Section:
Rank (LON:RNK)
Down 1% to 87.1p (£408m) - Trading Statement - Graham - GREEN
Let’s catch up on progress at this casino and bingo hall operator.
Its financial year ends in June, so this is a Q1 update to September:
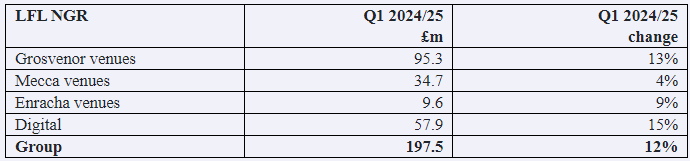
I’m glad to see the bull thesis continue to play out.
In August, at the full-year results, we discussed Rank returning to the dividend list for the first time since before Covid. Net debt became net cash, and adjusted operating profit more than doubled year-on-year to an impressive £46.5m. The unadjusted figure was £29.4m.
With the new financial year well underway, the positive momentum seems to be continuing.
Grosvenor casinos: the 13% improvement in net gaming revenue is driven by a 2% increase in visits and an 11% increase in spend per visit, with better than expected profit margins.
This casino business, and Rank as a whole, suffered badly during the inflationary period immediately after Covid. Rank’s energy and other costs were up, while customer spending was down.
Now that some time has passed, costs have been able to stabilise while at the same time, there is apparently some greater willingness to spend.
Mecca bingo: NGR rose due to increased spend per visit, but visits were down 1% due to sunny weather and England’s run in the Euros.
Digital: while I like this stock for its physical venues, there is no harm in seeing the Digital segment making a strong contribution and growing NGR at a slightly faster pace than the rest of the group.
Outlook: confident of delivering operating profit in line with expectations.
CEO comment:
"We have continued to build on the momentum that we have generated over the past year and a half, and I am very pleased with our start to this financial year. With all business units performing well, the double-digit growth in our Grosvenor venues and UK digital business is particularly encouraging, with customers clearly enjoying the improvements we are making across our land-based estate and to our digital offering. Rank is now a stronger and more sustainable business, and we are looking forward to the land-based legislative reforms coming to fruition in 2025."
Graham’s view
There’s no need to change my positive view on this one. Rank’s NGR is growing at an impressive pace and inflation is no longer the major problem that it was before, although cost pressures may remain particularly when it comes to wages.
The threat of changing legislation might never go away, but that’s par for the course when it comes to this sector. Rank is enjoying terrific underlying momentum, and I’m intrigued to see how far this will take it. At a modest earnings multiple, I continue to like this one.
AJ Bell (LON:AJB)
Down 1% to 476.5p (£1.97 billion) - Year-end trading update - Graham - GREEN
AJ Bell plc ("AJ Bell" or the "Company"), one of the UK's largest investment platforms, today issues a trading update in respect of its financial year ended 30 September 2024.
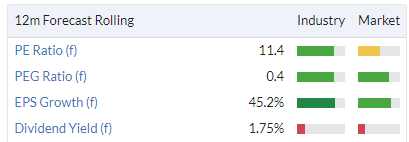
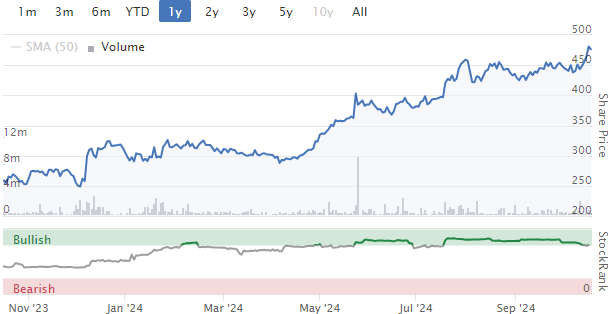
It’s a wonderful update from AJB. However, the stock tends to be highly rated and the good news will have been priced in already:
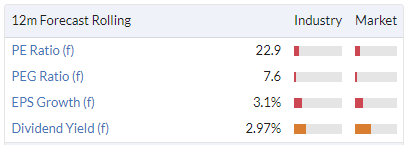
ABJ stock enjoys unusually high (but in my view well-deserved) earnings multiples for the UK financial sector:
Let’s cover some of the key bullet points:
Customer numbers up 66k or 14% to 542k.
In the platform business (not the investment management business), we have:
Assets under administration up 22% to £86.5 billion.
This was achieved through net inflows of £6.1 billion combined with favourable market movements of £9.5 billion.
In the investment management business, assets under management grew by 45% to £6.8 billion. Market movements also helped to boost this result, but it was mainly driven by positive net inflows of £1.5 billion.
CEO comment excerpt:
Our strategy is centred on our dual-channel platform which serves both the advised and D2C platform markets using a single technology platform and single operating model... Platform net inflows of over £6 billion demonstrates the benefit of serving both markets, while our efficient model drives strong profitability, enabling continual reinvestment in the business to support our long-term growth ambitions.
He also says that the upcoming Budget has caused “unhelpful uncertainty”; there has been “a noticeable change in both customer contributions to pensions and tax-free cash withdrawals”, although this doesn’t have a material impact on AJB.
Graham’s view
AJB is up by nearly 20% since I covered it in May, when I had a positive stance on it.
I should briefly mention the competition. Hargreaves Lansdown (LON:HL.) . (in which I no longer have a position) was not valued correctly by the stock market, and is therefore leaving at a PER of about 16x. I think it’s probably worth more than that, and the buyer obviously agrees with me (it’s a private equity consortium led by CVC).
It seems to me that AJB has been valued much more accurately by the market; it has consistently traded at a very significant premium to HL and even today it trades at a PER of 23x.
Like HL, it is wonderfully profitable:
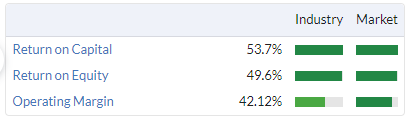
But not only is it wonderfully profitable, it also has the magic ingredient of rapid growth and (arguably) a best-in-class offering, with customers enjoying both competitive fees and a high level of service.
AJB stock passes 7 screens and they are not just momentum-based screens: the screens it passes are also based on quality, value and growth.
I could change my stance on this to AMBER/GREEN, given the valuation, but I’d rather stay GREEN until the rating starts to seriously overheat. A PER of >20x makes a lot of sense to me, given the attractions here, so I’m staying GREEN.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

68 comments
Marston's (LON:MARS)
https://www.marstonspubs.co.uk...
here is link to summary or yesterdays analys call.
They seem to be saying they can do £50 mill pa free cashflow soon (1. Free cash flow is cash flow after capex, before debt repayments and excluding disposals)
per the other place £30 mill mentioned this year
seems little tangible about debt reduction albeit pay down debt is number 2 on the list of proprities after
Invest in long-term organic growth
I am somewhast skeptical here as debt has come down very little overe the years if you remove the brewing sale proceeds.
If you could make £50 mil pa then perosnally i would have wanted to see them carry on paying debt down just to reduce the risk. Investing for growth seems more risky to me bearing in mind past results.
I dont think this update changes much - personally i would be well impressed if they could make £50 mp available to pay down debt or invest - that would certainly be a game changer.
Per the linked article they quote asset value of £2.1 bill and net debt £885 mill and NO material debt repayment due for 10 years - so if nothing else time is on their side to try and regain a fraction of their lost glories.
CGT - this seems more sensible than some reports:
Rachel Reeves set to raise capital gains tax rate on sales of shares in Budget (msn.com)
Speedy Hire (LON:SDY) - "Positioned for H2 growth" - new research note: https://www.equitydevelopment....
Consistent with Speedy’s AGM statement (on 5 September) H125 hire segment revenue is in line with the prior year and management expectations for the full year are unchanged. We expect a H1 bias to capex and, relatedly, a H2 bias to profitability both driven primarily by new business. Growth and margin expansion are key Velocity objectives; this should become increasingly visible as H2 progresses. H125 results are scheduled for 21 November.
Speedy’s share price has traded between 35p-40p range over the last quarter. Currently sitting at the lower end of this range, performance is now broadly in line with the FTSE All-Share Index YTD. With no material changes to underlying estimates, previous comments relating to low and rapidly compressing earnings multiples still apply. Reaffirmation of FY growth expectations at the H125 results announcement stage could be a catalyst for restoring share price momentum in our view. Ahead of that, our flat, unchanged dividend expectation offers a prospective 7.2% yield and our fair value is 51p.
Luceco (LON:LUCE) - some care required here perhaps? Wife of Hornby, the CEO, has just dumped 3million shares. Some other family members acquiring shares in an unrelated transfer. But Hornby has form here for those who have a long memory - on 24/11/2017 he sold 2million shares at 234p. Three weeks later Luceco (LON:LUCE) issued a trading update that saw the shares halve. Could just be sensible tax planning ahead of the budget but could also be related to shipping rates or weak trading. I haven't trusted Hornby since the previous dubious share sale so am not invested here but know that both Hornby's and the company's reputation has recovered since then, although the share price less so suggesting others may also have a long memory
Luceco (LON:LUCE) Interesting, I noticed this too, and was a shareholder back in Nov 2017 ( and still am) ! It appears Hornby has sold a nett number of 839,000, after taking into account the transfers to family members.
Could be just tax planning/timing re the budget/CGT etc ( although not an Aim issue as LUCE is on main market). Or could be using that as cover to sell without attracting too much attention to a possible peak in the share price. Who knows ? From all I have seen of him over the years and anecdotal info from people working for LUCE I have no reason at all to doubt his integrity. But I wont be topping up right now either.
I don't think the transfers to his daughters are related to the sale of 3m shares by his wife. I think he wants you to think that they are but the 3m is a sale by his wife not a transfer to their daughters.
I have a different opinion of Hornby's integrity having been assured by him directly back in December 2017 that it was just temporary trading softness. Indeed, the share price recovered significantly but that was some considerable time later. I note his background in private equity and suggest that a leopard may not change its spots.
Fair comment re the transfers
Sale of £4.5m very chunky
It will be v interesting to see what happens with the sp in due course
It’s also interesting that the market has LUCE shares up today . But like you I suspect , I am always now a huge cynic when it comes to big share sales by Directors for whatever reason is given
Luceco (LON:LUCE) Hornby seems more adept at trading his company's shares than he is at creating a consistently profitable business.
On 7/2/22 he sold 2.95m at 300p having timed a purchase of 1m 1/8/18 at 39.74p spectacularly well.
There's a Q3 trading update due at the beginning of November so we will know then if his wife is as adept at trading the company's shares as Hornby seems to be.
Having rung the bell at or close to the top a couple of times already by selling large personal holdings, I would be nervous that they're going for a hat-trick here. As you say, this is Main Market so BPR doesn't apply. And the gain is considerably less than it would have been a couple of years ago. Perhaps he isn't confident that the SP can attain those previous highs?. Because if it did it would wipe out any benefit from selling now before any increase in CGT.
As you can tell, I am sceptical and that's partly because I think they've tried to cover up a disposal by simultaneously announcing transfers to their daughters..
ME International (LON:MEGP) finally over 200p today, on decent volume.
Looks a runner. I hold.
I am on an InterRail trip, and every country I visit I look at the photo machines at station, and everyone has been ME International (LON:MEGP) although under a specific brand related to that country. Sadly not seen anybody having their photos taken, I wonder what the average use per day is of these booths? In Switzerland was CHF15 that's £13.30, reassuringly expensive. I note that like in UK, you get a code to enter on your passport application. Only a relatively short trip for me and it's cool here, so no need to try their laundry machines this trip.
Games Workshop (LON:GAW) I hold.
https://www.nottinghampost.com...
"Warhammer firm Games Workshop has revealed fresh plans for another new Nottingham factory as part of its major city expansion."
Senior reporter today. I don't know how fresh the reporter means with 'fresh plans'. Could be old news for clickbait. I'll email the company.
Seems it is fresh news - September 2024 was the application.
https://publicaccess.nottingha...
Serica Energy (LON:SQZ) go ex dividend in next 7 days (I hold) and with one of the best yields available and a low PE there's a lot to like. It is AIM listed and operates in the North Sea which the Government aren't issuing further licenses for of course. Not sure Paul or Graham have reviewed this one .
Paul and Graham rarely cover Oil or Mining shares. I’ve held Serica Energy (LON:SQZ) for a while now and thought it was a stunning bargain but that didn’t stop it falling to 30% below my buy price to just 114p a few weeks ago, and I risked an average down then. As you point out it’s on a low PE and stunning yield if the dividend is held.
The main reason for the big share price fall is Government policy on North Sea oil which must strike neutrals as bonkers. i.e abandon our valuable North Sea oil assets and import that oil instead and in the process cause heavy unemployment in the oil sector and lose huge revenues at a time when the Government is desperately trying to find hefty revenues! Add to that punitive windfall taxes that look sure to go higher still and we have the key reasons why Serica Energy (LON:SQZ) share price has fallen to such lows.
I also hold Harbour Energy (LON:HBR) who are facing exactly the same problems BUT they are solving them by diversifying beyond the North Sea. When they announced the news of their Wintershall Dea acquisition the Harbour Energy (LON:HBR) share price soared and unlike with Serica Energy (LON:SQZ) I hold at a useful profit. Serica Energy (LON:SQZ) can also diversify and that would probably lift the share price, depending on the wisdom/quality of their acquisition or tie up. I’m very happy to Crn ti use holding both, as the bad news looks largely priced in, and ehen Serica Energy (LON:SQZ) fell to just 114p recently it looked very very fully priced in.
And for both the very big dividends have been a big bonus. So both are well worth checking out. Serica Energy (LON:SQZ) we’re relatively upbeat despite all these hurdles in their latest update.
Wise (LON:WISE) :
Wise becomes first foreign firm to gain direct access to Japan's payment clearing network
Recent SP showing positive momentum. I hold.
removed
??
Appreciate your summary comments on Mondi (LON:MNDI) (I hold) which I know is outside your usual remit. Having watched Ed & Megan’s webinar on selling can’t make up my mind whether I’m a Rabbit, Assassin or Hunter! Already suffering this week with the ASML Holding NV (AMS:ASML) debacle. Took that as a buying opportunity (not working yet!) but not sure will do same with Mondi (LON:MNDI, probably revert to a Rabbit which appears to be my predominant trait!!!
Cairn Homes (LON:CRN) Help ! I was doing some research the other day on Stocko & cant find what someone said re CRN and the Irish government. Im sure it was in a discussion about VTY & someone saying they preferred CRN..... Anyone got a view on CRN either ? Thanks
This was to do with the Irish government recieving E14 billion in back tax from Apple and the Irish governement being supportive of their building industry.
I travel to Dublin regularly and their is a huge housing shortage and strong demand, so I see Cairn as a strong housing buy.
Quite a few clues in the recent 2024/25 Cairn trading outlook....
....."Despite this positive industry response there remains a significant structural undersupply of new homes with an estimated annual housing requirement of between 49,400 [and] 81,400 new homes required to 2050 in a high population growth scenario."
Chief Executive Officer Michael Stanley commented: "The company has delivered a stellar H1 performance across all key metrics, most importantly in housing delivery with our turnover increasing by 67% year-on-year.
It also reaffirmed its financial 2024 guidance of approximately 2,200 units; an operating profit of around EUR145 million; and a 15% return on equity. "2025 is expected to be another year of strong volume, revenue and profit growth as Cairn continues to leverage our exceptional scaled operating platform," Cairn Homes added.
Until recently, Cairn Homes featured on Jim Slaters guru Principle screen, so that was a good enough recommendation for me. Has been on an upward trajectory since.
A chunk of Cairn shares sold by the CEO this year.......
Thank you, thats the message ! Bought in now, fingers crossed
Hi Colin,
I made the comment that I would far prefer to invest in Cairn Homes (LON:CRN) based on a still attractive div which is about the same as Vistry (LON:VTY) which I held until about March this year. I have been topping up on the dips and it has excellent momentum and prospects. Together with a strong share buy back strategy, I think this has far better prospects than Vistry (LON:VTY) and pays the same to wait, especially as there may be a div cut in the offing? There is also the nailed down fact that the money is being spent by the Irish gov, rather than the what ifs in the UK.
As a slightly separate note, I hear today that HS2 is back on! So this should see some strong action in the next few years, my fave would probably be Kier (LON:KIE) especially when their debt is paid down (2026). Balfour Beatty (LON:BBY) would be worth a look too.
Thanks Viz and all other comments. Im convinced, im in now :-)
I don't know if this is relevant to Cairn Homes (LON:CRN) but, as background, there is a crisis in Ireland about houses being built with defective concrete blocks. It seems to trace back to the quarries. See https://4sonline.org/news_mana...
It’s not related to Cairn Homes. Back in the pre-crash days of the Celtic Tiger, developers were throwing up houses left, right & centre. During this frenzy a number of block manufacturers produced defective blocks which are now crumbling leaving householders with houses they can’t sell (and in some cases can’t live in) and unhappy about the terms of Govt compensation scheme. The issue is mainly in Co Donegal & in Co Mayo with some spill over to neighbouring counties.
Thanks Bill, very helpful
Found this article from December 2021
https://www.theguardian.com/wo...
Speedy Hire (LON:SDY) a brave budget punt and H2 should really be ok given contract wins etc.... but it's a brave one. V cheap v operationally geared, in a tough mkt but potentially winning business from HSS as an offset to mkt weakness. I don't own but today could be a nice entry.
Chemring (LON:CHG) In a sector which can only benefit from conflict and European defence rebuild... the last line of the statement is somewhat enticing as a tuck away stock... effectively doubling revenue by 2030 would appear to be a target with chances... agree with Paul that it looks interesting. In my experience individual quarters can be lumpy, so sizing needs to reflect this. On the watch list.
I think on the defence sector side long term growth is a real possibility and EU may need to do more if Trump is elected to protect themselves. I only hold Cohort (LON:CHRT) in this sector, I understand the concerns about investing in this space but at the same time a properly armed EU Military is a better guarantee of peace.
St James's Place (LON:STJ) might be worth some commentary given that it is under investigation. It reported today that its FUM (Funds Under Management) was $184.4b, and increase over the previous year. I would have thought that would have positive for the shares, but they are flat as I write.
In this sector would also be interesting to hear thoughts on £AJB. Their TU is out today and the share price graph is impressive
@ @ @ ok, AJ Bell (LON:AJB), it's looking good.
In terms of St James's Place (LON:STJ), have a look at the products they offer and the fees they charge (even now). Depending on your investiment timeline, you may want to consider how sustainable their previous introducer/affinity/high fee type business model is, in a world of low cost funds/trackers and the impact this might have on their business profitability (and ultimately AuM)....no position personally.
Hi Paul/Graham,
Is Vertu Motors (LON:VTU) still in the backlog to do from yesterday? Would be interested to hear your views.
Thanks
Arbuthnot Banking (LON:ARBB)
Decent Q3 TU from ARBB.
This small banking group often flies under the radar but is, in my view, well-run by an experienced senior management team and is a good-quality business. It seems to be performing solidly and is on a PE of around 5. Also the dividend yield is attractive at about 6.0%. It is small, but I think it is currently underrated.
I have held it for about six months but have followed it for a number of years.
Hargreaves Lansdown recently introduced an active savings platform. It consists of a group of banks where you can earn interest. You put money into HL's "hub" and then open an account from there. It's all pretty straightforward and doesn't involve jumping through a lot of hoops. It takes a couple of days for the money to go through, though. Arbuthnot is one bank on the platform and one that I opted for as it paid a good rate of interest. It is backed by the FSCS (Financial Services Compensation Scheme). You can check wihich banks are covered here: https://www.fscs.org.uk/check/...
So maybe there's a little earnings surprise in the making here.
Hi Mark
A word of caution.
I tried using the HL active savings. Once I invested some cash, then every time I wanted to log into HL I had to wait for a code to be sent to my phone and then enter the code. Only then could I access my investment accounts.
When I queried this procedure HL responded by saying they had to follow 'banking' online access controls rules, as the savings accounts were deemed a banking service. They could not separate the access away from my investment accounts.
This might have changed by now. But I extracted the savings monies right back into my investment accounts and closed the active savings account I had opted to use.
Normal access controls then resumed.
Regards
Howard
I would have thought the two factor authorisation code sent to the phone might be a benefit - not a problem. It is an additonal layer of security.
Am I missing something here
As an aside re. these various savings account access portals that have been springing up, including on HL, some of the fintechs - eg Lightyear with their 'vault' product, currently 5% (daily variable) - have made retail access to MMFs via faster payment pretty seamless now.
Seems perfectly sensible - or do you prefer slacker security and giving bad actors an easier route to your money ?
Arbuthnot Banking (LON:ARBB)
Cheers Ian B - great little summary thanks - I currently have no banking exposure since virgin got taken out so think I will do some digging here. Seems like all the banks command derisory or ratings nowadays - hey go many are black boxes just waiting to blow up - hopefully this one is a plodder similar to virgin
VM RANT INCOMING. I've got the ump with Virgin. I tried to change my mobile for security. VM said that I'd need to contact them personally. I did that, was kept waiting for around 20 minutes. I failed some kind of security check. So they put the phone down on me!
I switched the Clydesdale Bank because my local RBS closed down. Clydesdale was taken over by Virgin. Then Virgin closed the local branch. They've blotted their copy books more than enough times with me, so I'm heading for the exit.
(Former) high street banks are a race to the bottom. Perusal on Trustpilot will confirm just how dire they are. They close branches and rely on you using the internet. Online chat is mostly robots today and tend to take you around in circles. Phoning, if you can find the number, is a dismal experience.
High street banks are far too complacent, IMO. They rely on stickiness. I've said it before and I'll say it again: banks don't fail because they have branches. they fail because they make stupid financial decisions (2008!).
If anyone is dissatisfied with their current bank, it might be time to think about switching to the challenger banks that are cropping up. First Direct and Starling Bank come up as good contenders. I have my eyes on opening an account with the latter. Phone up their support line and see how long it takes to get through. Look at Trustpilot. There are other online banks that seem to acquit themselves well, but I'll leave that as an exercise to the reader.
Check out the FSCS website to see if you're covered. Ignore the ones that aren't. Revolut is mentioned a lot, but they're not FSCS protected. I also seem to recall some fuss over their practises. So you nix them, for example.
First Direct are good. Always have been. I am less positive about Starling after recent news ....
FCA fines Starling Bank £29m for failings in their financial crime systems and controls. The FCA has fined Starling Bank Limited £28,959,426 for financial crime failings related to its financial sanctions screening. It also repeatedly breached a requirement not to open accounts for high-risk customers
Agreed.Poor for a digital bank who you would think would be ahead of the curve on all of the latest know your customer, 'anti-scam' etc.. software integrations especially compared with the older, bulkier (just about still) highstreet brands probably more reliant on legacy software that's expensive to switch out. From their website 'We're a fully regulated digital bank, built from scratch with some of the world's best banking security. Codes, face and fingerprint recognition are just a few of the ways we help to keep your money safe.'
I phoned up First Direct. Apparently they do issue cheque books if you ask for it. I'm not sure how people cope without cheques, but there you go.
If anything good has come out of me being annoyed with Virgin it's that there is better stuff out there. Being more pro-active with getting the best savings rates is perhaps the way forward, too. The internet makes it better than ever.
It's the same old story. The banks offer reasonable rates in the beginning and then it tapers off. Virgin now offer only 1% on their deposit accounts, so coupled with other bones of contention, that was the end of that.
The Scottish Building Society was an odd bird. They had physical books. My dad sometimes wanted to top up his ISAs, but the agent (there's no branch here) said that he should open a new account. So he had a plethora of books, which was all rather nonsensical. There were two agents in my town, but they closed them both down. My dad complained to them about this, and they said that he could either do everything by post or visit the nearest branch, which happened to be 40 miles away. I told my dad to open up a Virgin deposit account and transfer all the money there. He thanked me recently, saying that it was a lot better than all the faff he was going through before.
I wonder if, to a large extent, banks are shooting themselves in the foot by closing all these branches. They say that "everyone" is getting online; but a lot of people are not interested. By forcing people online and causing them inconvenience, you're really just encouraging them to switch. that could be much better.
I remember cheques - heck even traveller's cheque - but online banking has been a thing now for 25+ years, online payment are so easy, why would you bother with such a backwards payment system as cheques this days ? What are the remaining use cases ?
From a customer vierwpoint you will be far from alone in taking the hump with virgin , like some of the other big banks they have had a nkack of managing to hiss of people who wouldnt normally moan on a daily basis.
Part of the attraction with the virgin shares was that they were taking a bunch of poorly run brands and trying to modernise - it was a far from finished project as i know they had a large branch estate and merging of the different brands - in that regard often change isnt always for the better in the short term for customers even if it is necessary long term for the busines to survive. also for those used to doing things the old school way well unfortunately often that simply isnt an option going forward - so people will often need to vote with their feet if they are unlucky enough to have their local necessary bank closed.
anyway nationwide have come along and taken the company off my hands now so its customer satisfaction now matters didly squat to me. I would expect nationwide should be a very safe paid of hands as the new owners but if they are still half way through a modernisation project and have now merged with nationwide that may still be strife for the customers who have hung around through the various name changes.
I’ve a number of products with Nationwide and always found them decent with good phone support, so hopefully you’ll see some improvement.
Unsure how the Virgin brand will be run going forward (even though they have emailed members to explain this). Worth checking if your accounts will qualify for the next Fairer Share payment. Only £100 but it’s money for nothing.
Try Monzo. I spoke to most of the challenger banks on behalf of several Ukrainian refugees we hosted, and we settled on Monzo. Personally, I bank with Royal Bank of Scotland and Bank of Scotland and cannot decide which is worse. My inherent laziness has prevented me moving before, but recent events of spectacular incompetence mean I am moving to Handlesbanken .... Swedish private banking for the mid-market. They have a half decent branch network and the usual online capabilities. They charge for accounts, but that is the direction of travel for their bot-driven competitors anyway. At least you have access to a human with Handlesbanken.
Individual Online Banking | Handelsbanken
Wouldn't touch Monzo with a 50 foot pole - they have been cancelling customer bank accounts without any explanation, see here; https://community.monzo.com/t/...
Big banks might be poor, but they don't de-bank you for no reason...
I read it .... I am not convinced there is any problem. Typical internet noise.
A certain Mr. Farage might take issue with that comment :-)
Arbuthnot Banking (LON:ARBB) agree a well-run and relatively simple bank with a solid track record. Always tends to look very cheap but not sure what could drive a re-rating? The wide spread had stopped me from investing in the past, but would be keen to take a position if this reduced. Worth noting that Sir Henry Angest holds 57% - he is in his 80s so would be interested to know what his long term plans are for his stake.
Hi Mark,
"Revolut is mentioned a lot, but they're not FSCS protected".
This is very true because it doesn't have a full banking licence, hence it cannot offer products such as mortgages and loans.
David.
"Revolut is mentioned a lot, but they're not FSCS protected".
This is very true
Thats actually only partly true or wrong/.misleading - for example if one has a savings account one may be covered by the FSCS via the parters they use - so i would say perhaaps no default FSCS but it may be that one might be covered.
https://help.revolut.com/help/...
Restore (LON:RST)
More director buying. CFO buys 25,000 shares at 256p.
This follows on purchases of 100,000 shares at 280p by the CEO, Charles Skinner and an initial purchase of 25,000 shares by CFO, Dan Baker in August
Good to see senior management spending their own money. I hold having bought a little lower down
. [Mispost by me. Please ignore]
Ibstock (LON:IBST)
Perhaps the green shoots of recovery for materials suppliers to the house building industry.
“We have seen some initial signs of improvement of recovering activity levels in the new build residential market”
It has to start at sometime!
My morning smallcap tweet: Green light for Brown takeover
One Heritage (LON:OHG) Capital (LON:CAPD) Avacta (LON:AVCT) N Brown (LON:BWNG) Novacyt SA (LON:NCYT) Sabien Technology (LON:SNT) Camellia (LON:CAM) Physiomics (LON:PYC) Augmentum Fintech (LON:AUGM) Frp Advisory (LON:FRP), Activeops (LON:AOM), Speedy Hire (LON:SDY), Rank (LON:RNK)
◄One Heritage (OHG)► the property developer changes its name to Zentra (ZNT) effective tomorrow. "The name "Zentra" was chosen to embody the values of balance, harmony, and focus, with "Zen" symbolising a sense of calm and mindful approach to property development." This sort of flatulent BS does nothing for my mood in the morning. [SP=2.06 Cap=1m]
◄Capital (CAPD)► Q3 rev up 18%. FY guidance unchanged at remains $355-$375m despite MSALABS subsidiary rev expected to be only ~$45m. [SP=86 Cap=169m]
◄Avacta (AVCT)► adds two novel preclinical anti-tumour assets, AVA6103 and AVA7100, to its pipeline of pre|CISION-enabled drug conjugates. [SP=64.6 Cap=234m]
◄N Brown (BWNG)► rec offer of 40p, a 48% premium. from director Joshua Alliance's Bidco. [SP=27 Cap=126m]
◄Novacyt (NCYT)► gets EU IVDR accreditation for Yourgene Cystic Fibrosis Base assay. [SP=55.6 Cap=46m]
◄Sabien Technology (SNT)► US Waste Plastics to Oil Project likely to "progress to execution in 2025, pending 3rd party funding of b.grn to resource the project, operational permitting and the completion of contractual negotiations". [SP=11.51 Cap=3m]
◄Camellia (CAM)► guides FY-Dec trading ahead of market expectations with adj loss £7-9m from a previous range of £10-12m. [SP=4373.6 Cap=121m]
◄Physiomics (PYC)► wins contract from existing client Cancer Research UK. No £££. [SP=0.66 Cap=1m]
◄Augmentum Fintech (AUGM)► sells Farewill to Diginity, in which investment co Castelnau has a controlling stake. Gets shares in Castelnau (CGL). [SP=99 Cap=166m]
◄FRP Advisory (FRP)► buys Globalview Advisors for 5.5m. [SP=136.5 Cap=348m]
In line: AOM, SDY, RNK
Good looking update from AJ Bell (LON:AJB) - no revenue/profit details but growth in customer numbers and assets under management looks excellent.
N Brown (LON:BWNG) - 40p cash offer
https://newsfile.refinitiv.com...
Reeves expected to focus rise in capital gains tax on share sales
Chancellor likely to increase CGT in her October 30 Budget as part of efforts to close a £40bn funding gap
https://archive.ph/bxa3v
If Reeves were only to increase CGT to 24% , I think most investors would be over the moon, considering rates as high as 39% have been floated
Live at 9.30am tomorrow (Friday 18th Oct) on Vox Markets' Exchange, I will be interviewing accomplished fund manager Adam Rackley of Dowgate Cape Wrath.
It's sure to be another fascinating conversation - including lots of stock ideas such as #APH, #MARS, #PZC, #COST, #ENQ, #ECEL, #GLE, #XPP, #WYN, #WJG, #TTG, #RWI & #SYNT
If you'd like to ask Adam any questions, then please feel free join us here on Youtube. Everyone is welcome.
Always worth a watch/listen, thanks Paul