Small Cap Value Report (Thu 18 August 2022) - MADE, AEO, ZYT, ANG, SPEC, IMMO, IUG

Good morning from Paul & Graham!
Agenda -
Paul's Section:
Brief comments (no sections below):
Aeorema Communications (LON:AEO) (82p - £7m) [no section bellow]- Too small for us to cover in detail, but thanks to members Dieselhead2 and tiswas, for flagging up in the comments section below a positive trading update from this live events company, now guiding FY 6/2022 results to be £12.2m revenues, and £830k+ profit before tax. The commentary sounds upbeat too. I know 4 of the >3% shareholders, all shrewdies! So this looks worth a closer look.
Intelligent Ultrasound (LON:IUG) (13p - £35m) [no section below] - I reviewed this serial loss-making company here in May 2022, and could see some appeal, but overall it looks too high risk. Looks like it could run out of cash in 2023. Dilution has been massive already, with a 10x increase in shares in issue in the last 6 years, as it remained relentlessly loss-making and cash-burning. Today’s interim results is more of the same. Good revenue growth, but some of that is a one-off big order from the NHS. Cash is down to £3.5m. Risk:reward doesn’t look good to me.
Full sections:
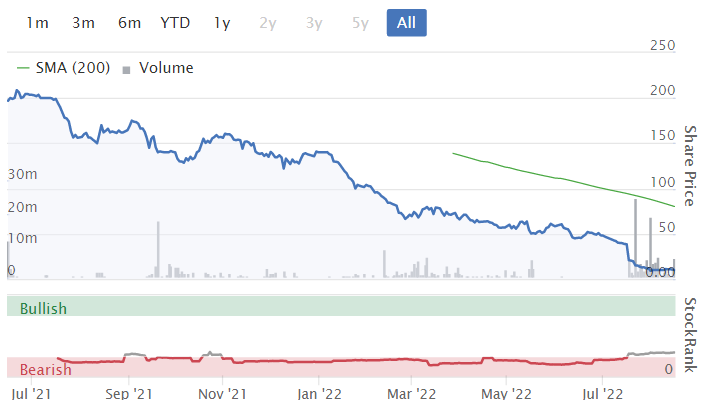
Made.Com (LON:MADE) - confirms press speculation that it is looking at a possible equity fundraising. It's been a disaster since floating just over a year ago, collapsing by 95% in price already. I don't see any way out of this, other than a deeply discounted placing, to keep the lights on into 2023. Longer term, unless it can drastically slash costs, it's difficult to see this becoming a viable business, so likely to disappear in 2023 I suspect. Hence it remains uninvestable for me. Pity, as it looked quite an interesting company originally, before growth collapsed.
Angling Direct (LON:ANG) - it's a profit warning, due to a variety of fairly predictable reasons. Although the dry weather here and in Europe has also had an adverse impact on fishing conditions. Forecasts are trimmed, with adj PBT now only £1.5m for FY 1/2023. It's the cash pile that is of most interest, which is almost 3/4 of the whole market cap! That nicely underpins this share, even if trading deteriorates further, which it might.
Immotion (LON:IMMO) - several readers have been discussing this VR entertainment company's trading update in the reader comments, which got me interested. I've had a look, and think there could be something interesting developing here. Although my main concerns are the possible need for more cash, and a growth rate that seems a little pedestrian so far, and limited mainly to aquariums. That said, I can see good potential here, if management are able to accelerate growth. Worth a closer look.
Graham's Section:
Zytronic (LON:ZYT) (£13m) - this maker of display touch screens publishes a revenue warning for FY Sep 2022. The final outcome for the year is unclear but the profit result may only marginally exceed last year. The contrarian in me finds this one interesting: it has nearly half of today’s market cap in cash and the results of the past two or three years have been hobbled by the closure of the casino and other industries, along with supply chain disruptions. The company abandoned its sales and marketing efforts but has now restarted them and I wonder if it might be able to make a partial recovery towards its pre-Covid profitability. Very little success is priced in at current levels, for investors who are able and willing to buy shares in companies of this tiny size.
Inspecs (LON:SPEC) (£228m) - this eyewear manufacturer delivers interim results that disappoint the market with a fall in underlying EBITDA compared to last year. However, the statutory numbers point to financial improvements and it looks like 2022 is shaping up to be a good year for the company. The disappointments relate to delays at a new manufacturing site and currency translation issues that don’t look serious to me. Of greater concern is the valuation: the stock is trading at a premium of around 100% to net asset value, and that’s before making any of the necessary deductions for intangible assets. How the company will justify this in the long-run is unclear.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Made.Com (LON:MADE)
9.9p (pre market open)
Market cap £39m
Background - we’ve been following this sorry tale here at the SCVR, with one profit warning after another.
The last profit warning which I reviewed here on 19 July was a disaster, with the anticipated loss before tax of £80m (per Liberum forecast) for FY 12/2022. This update also said the company was “considering options… to strengthen its balance sheet” - fairly obviously an equity fundraising, because nobody would be likely to want to lend to it, and anyway debt doesn’t strengthen the balance sheet, NAV remains the same.
There was £31.5m in net cash at June 2022, forecast to drop to £5-30m by Dec 2022. So not terminal yet, but clearly heading that way.
My conclusion in July was that the business model has not been proven, and the high risk of a placing made MADE shares uninvestable. That was when the share price was 38.5p, and it’s now lost three-quarters of that already depressed price.
Remember that MADE floated as recently as June 2021, at 200p, so it’s already in the 95% club at 9.9p per share. To be fair, it looked an interesting growth company back then, with the story being that it was disrupting the traditional furniture market, and attracting trendy younger customers to its digitally native, quirky furniture offerings often from independent designers. The relatively small trading losses were explained as being due to expenditure to drive rapid growth - fair enough, if that growth continues. The trouble is, growth has now gone sharply into reverse (mainly due to consumer demand softening, and supply chain problems), and losses ballooned, which will clearly result in the previously comfortable cash pile rapidly disappearing.
Sky News (it’s always them, isn’t it!) blew the whistle last night, saying that MADE has called in advisers from PriceWaterhouseCoopers to -
help shore up its balance sheet as it weighs plans for a share sale to raise approximately £50m…
to examine cost-cutting and other restructuring options.
...weighs plans for a share sale to raise approximately £50m.
The launch of a cash call is not thought to be imminent, but is said to be likely to take the form of a placing…
Response to press speculation -
This morning’s update from MADE confirms that it is looking at possibly doing an equity raise -
Further to the Q2 trading update published on 19 July 2022, MADE notes the recent press speculation regarding the possibility of the Group undertaking a capital raise.
As indicated in the Q2 trading update, MADE is considering all options to allow it to strengthen its balance sheet. MADE confirms that these options include a potential equity capital raise. MADE continues to consider its options and a further announcement will be made if and when appropriate.
My opinion - none of this is a surprise, because the company had already told the market in July that it was looking at doing a fundraising. Hence I don’t see why today’s confirmation of the obvious should move the share price (it's down c.10% to 9p in early trades). Although market makers tend to mark things down at the open, so they don’t get hit by sellers.
The key question is, will MADE survive? It’s obvious that deep cost-cutting is the only way forwards, but can the business still operate with much leaner costs? If marketing spend is slashed, then it would likely wither away, due to falling sales. Fulfilment costs look very high, on looking back to its 2021 results. This is looking increasingly like a badly-run challenger that floated on a wave of optimism, rather than good economics. Whereas the more shrewd, experienced old timers in the sector are now looking likely to out-last this challenger, long-term.
From this point, it all hinges on what the existing shareholders are prepared to do. If the institutional shareholders are happy to back a fundraising, then they might want to protect the value of their existing shares. Although that seems unlikely to me, given that the largest holder’s stake, Level Equity Management LLC with 16.6%, is only worth £6.5m, so hardly worth defending for a fund that has raised $3bn since inception. It has only made 2 investments in the UK, being a mainly US-focused investor specialising in growth & tech companies, so is probably suffering badly at the moment, I imagine.
Hence I think the most likely outcome here is a deeply discounted fundraising, anyone’s guess on price - 10p? 5p? 1p? It could be anything. It depends on who is putting in the cash that MADE clearly will need to survive in 2023. Also a plan to slash costs would also be necessary to tempt investors, I think.
Overall then, I continue to see this an uninvestable, and there’s little to no value in the existing equity, which is likely to be heavily diluted. There are 395m existing shares. So to raise £50m, at a discount (say 5p per share) would require the issuance of 1bn new shares, increasing the share count by 3.5 times. If the price is 1p per share, then 5bn new shares would need to be issued, increasing the share count by over 13 times. And even then, the refinanced business would still be haemorrhaging cash, and likely to run out of cash again further into 2023.
It might not be able to find anyone to invest, because at the moment that would look like pouring money down the drain.
A miracle could happen though. Maybe someone might take it over, but even then, the price would probably be a token amount. Hence this share is just for gamblers at this stage.
No wonder the IPO market is dead now. It looks like the 2020-21 crop of IPOs were so poor, that the city might have killed off the golden goose. With many institutions now licking their wounds from over-priced, opportunistic floats like MADE, who would come back for more?! Still, buyer beware as they say in Latin. Nobody is forced to buy into IPOs. I wonder how many fund managers will want to dump these failed IPO positions in the market, so they don't have to be disclosed on year end portfolio reports?
.
Angling Direct (LON:ANG)
30p (down 18% at 09:48)
Market cap £23m
Angling Direct plc (AIM: ANG), the leading omni-channel specialist fishing tackle and equipment retailer, provides an update on trading for the six months ended 31 July 2022 ('H1 23').
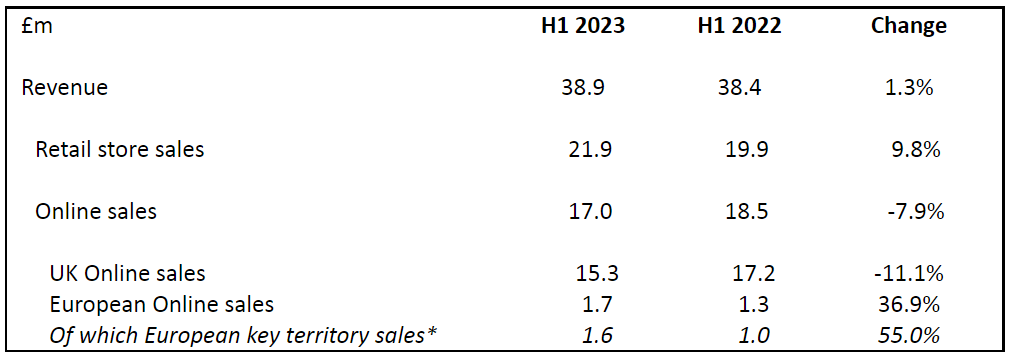
The highlights table provides a neat summary of H1 -
.
Note the shift towards physical stores, with online revenues down 7.9% - although still up 36% on the pre-pandemic level.
Total store sales rose +9.8%, and the more meaningful LFL growth (organic, i.e. before new store openings) was good, at +4.6%, helped by no more covid restrictions.
1 new store opened in H1, total now 43 sites.
Revenue growth trend from Q1 (Feb-Ap 22) to Q2 (May-Jul 22) deteriorated, from +5.4% to -1.6%
Net cash £17.1m at July 2022, amazingly that’s 74% of the market cap! A key bull point.
European expansion underway (attractive, highly fragmented market, ANG says), with a distribution centre opened in March 2022. Good growth, but from a low base.
Outlook - priority is to gain market share, in UK & Europe, implying that it’s not prioritising profitability as much.
Impact from cost of living pressures, consumer confidence, and cost inflation.
Dry summer has more recently impacted trading in August (adverse fishing conditions).
European heatwave has also impacted growth there.
Revised guidance - another one where they quote the meaningless EBITDA, it’s so annoying when companies do this, because EBITDA IS NOT PROFIT! -
As a result of these market headwinds the Group now expects to generate revenues marginally below current market expectations for FY 2023.
However, Pre-IFRS 16 EBITDA is now expected to be materially behind current market expectations for FY 2023 and in a range of between £3.0 million and £3.4 million.**
*Sales through German, French and Dutch native language websites
**Angling Direct believes that market expectations for the year ending 31 January 2023 prior to this announcement were revenue of £82.0 million and pre-IFRS 16 EBITDA of £4.3 million.
I don’t think that’s too bad. Guiding down from forecast EBITDA of £4.3m, to a range of £3.0-3.4m is disappointing, but not a disaster. The reasons given sound credible.
Many thanks to Singer for giving us more meaningful figures today. It forecasts using the bottom end of the company’s range for EBITDA, at £3.0m, which becomes £1.5m of adj PBT - this is the number I work on.
Adj EPS is 1.5p, so a PER of 20 at 30p per share. Not cheap, but remember when a three-quarters of the market cap is supported by its cash pile, then PER is not so appropriate.
Balance sheet - not reported today (other than the £17.1m net cash), so I’ve looked back to 31 Jan 2022.
ANG has a superb balance sheet. NAV is £36.4m, taking off £6.2m intangible assets, gives NTAV of £30.2m - that’s now about 31% greater than the market cap!
A lot of capital is tied up in inventories, at £16.3m, then there was a similar sized cash pile of £16.6m (now slightly higher, 6m later, at £17.1m).
The question is, whether the company is making good use of this capital, as it's only generating about a 5% return on NTAV (£1.5m profit before tax, on £30.2m NTAV)?
Trade payables are modest, at £8.7m, and the only other significant liabilities are the IFRS 16 lease entries, which net off to about nil versus the RoU asset - implying that pretty much all stores must be profitable, or at least not loss-making to any significant extent.
ANG clearly has surplus cash, which gives management firepower to do more acquisitions & continue expanding, and ride out a recession (whilst weaker competition goes bust maybe?), from a very comfortable position.
The main risk I see, is if management blow the cash on an unwise acquisition, but given their track record of being maybe too cautious, it’s probably not something to worry about. I can't help thinking that it might create more shareholder value to look at using the cash pile to buy an unrelated business in a lucrative sector, and build a mini-conglomerate? Or maybe buy another company that could be co-located in ANG's physical sites?
My opinion - this share is strikingly cheap, once you take into account its cash pile.
If management use the cash wisely, then there could be nice opportunities ahead to bolt on more earnings - e.g. from picking up assets from administrators (as e.g. Portmeirion (LON:PMP) announced this week), or opening new sites at very low rents.
Against that, it’s sensible to expect macro conditions to have some further downward pressure on sales in the more immediate future, possibly?
That said, despite today’s profit warning, it’s still trading profitably, and has a ton of surplus cash sitting on the balance sheet. Therefore I see this as a low risk way to get exposure to improving consumer confidence once we get through this cost of living crisis.
A key issue for online businesses (about half ANG is online) is online marketing costs, which seem to have shot up, as Google & Facebook (mainly) price gouge their customers to grab profit for themselves instead. These internet behemoths are like a global tax, flowing to the US. ANG doesn't mention this key issue today. I'm coming round to the view that having a hybrid operation - some stores, and some online business, may actually be a better idea, rather than online only, as operations can be merged in various ways (e.g. stores handling online returns, and dispatching goods where needed, rather than everything coming from a central warehouse). Plus if your customers are walking into a physical store, you can sell to them direct, rather than having to pay Facebook to give you access to customers.
ANG is not the best business in the world, but it looks OK, and above all has bulletproof finances, and a super-cheap valuation. So I like ANG, as a value investment. I appreciate it must be very frustrating to own this share, and see it relentlessly dropping. I know the feeling very well, but I think it's important not to sell in despair, as that would probably be at or near the low. We just have to be patient, and wait for good companies to interest other investors again.
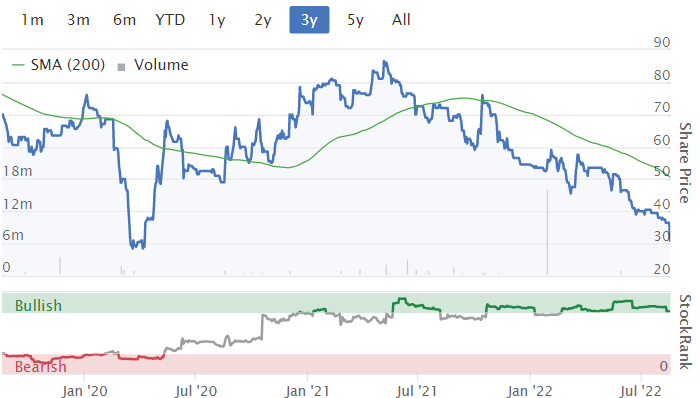
We're back down to the early pandemic low again, which seems very surprising, with the fall looking overdone to me -
.
Immotion (LON:IMMO)
3.4p (up 5% at 11:25)
Market cap £14m
Some interesting posts (from fwyburd, Fegger, and Monty9 - thanks to them) in the comments section below caught my eye, so thought I’d take a look.
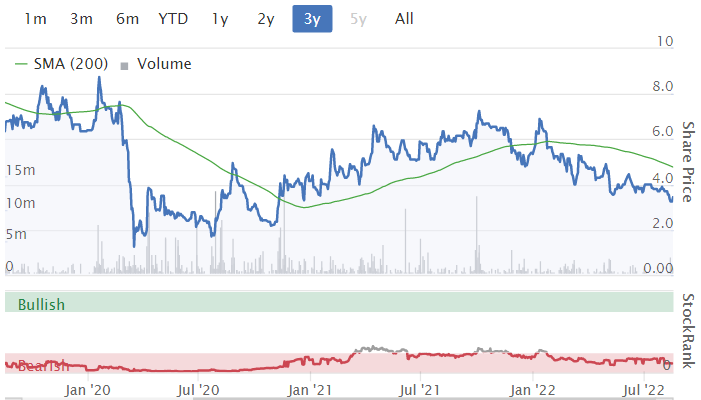
I’ve only previously looked at IMMO here once, in Dec 2020, and remember thinking it looked moderately interesting, but a bit early stage. Also obviously impacted by lockdowns, which are now abating for its indoor leisure activities, using Virtual Reality headsets.
I’ve had a quick look through the FY 12/2021 results, which show signs of something interesting happening (in H2 when pandemic restrictions were mostly lifted). Cash is getting tight, so they’ve decided to spin out the HBE and Uvisan startups, which require additional capital to develop them further. I doubt these are worth much, but could be a nice little bonus if IMMO is able to e.g. have a free carry, with an external investor providing the growth capital perhaps?
The focus is now on the core activity, Location Based Entertainment, e.g. providing immersive experiences at aquariums mainly, also zoos, etc. The revenue figures per headset (VR) are really impressive, over £20k per annum per headset. I think that might be gross, not the net figure that IMMO gets, it’s not clear? With only just over 400 headsets currently in operation, at a small number of sites in various countries (especially good to see the US being a main market) it’s easy to see how IMMO could really scale up this business, and have high margin, recurring revenues, with great operational gearing. I like this business model, and can see considerable potential! c.£10m revenues this year from c.400-500 headsets is pretty impressive. I reckon this is a business which could conceivably scale up say 10x over the long-term. That definitely gets me interested.
Here’s the latest update -
Immotion, the UK-based immersive entertainment group, is pleased to announce an update on recent trading.
H1 revenue up 91% to £4.4m (core business only) - but comparatives are soft, due to lockdowns. A better comparative would be H2 LY, which was £4.0m, so really just a 10% improvement in sequential half years.
“Very strong trading” currently, in July 2022, achieving £1.3m revenues (unaudited) - this is probably peak seasonality I would imagine.
Current trading in August 2022, “also started very strongly”.
Current portfolio is 54 locations, with 488 seats.
2 small installations done, at Chester Zoo (has anyone tried it?), and Legoland Philadelphia.
Pipeline doesn’t sound much, with only an expectation to “comfortably pass the 500 seat mark by the end of H2 2022” - I was hoping to see much more ambitious growth coming through.
“Advanced stage” discussions underway re spin out of 2 small, non-core operations. Possible upside here, but not a key reason to invest in IMMO.
Diary date - H1 results due out w/c 26 Sept 2022, so we’ll have a look at those in due course.
CEO comments - are upbeat, and I particularly like the comment re positive cashflow -
Martin Higginson, CEO of Immotion, commented: "The first six months of the year have shown solid year-on-year improvement and, with July exceeding all previous revenue numbers, the summer trading period is looking very encouraging.
"Demand for the Group's core LBE offering remains strong and, with solid operating cash flow generation from the key summer months, we are now well positioned for further installations and growth of the LBE estate."
My opinion - I like this company! There’s clear evidence that IMMO has found an interesting, and potentially lucrative niche in VR entertainment. Whether it can be scaled up, that’s the big question? At the moment, judging from its website, the sites seem to nearly all be aquariums. Although there’s also a gorilla trek, and a cartoon mermaid themed video about plastics in the sea.
Hopefully the actual roll-out of new sites (and enlarging existing ones) could be faster than indicated at the moment, I think it would take a material increase in the growth rate to get me more interested to a point where I’d want to allocate my scarce resources to this particular share. In a bull market, I would have bought some on a speculative basis.
I can see that each new site opened would add to the credibility of the company, acting as reference sites. The next thing we need to do, is look at customer reviews online, to see how these installations are being received by customers.
Overall, I think this looks potentially interesting, and worthy of a closer look, for more risk-tolerant, growth company small cap investors. We all need to have a little bit of fun in our portfolios! It looks to be close to breakeven now, so if it can break into profit, and not need another placing, that would be good.
.
Graham’s Section:
Zytronic (LON:ZYT)
Share price: 130p (-9%)
Market cap: £13m
I’m disappointed by how this company has performed in recent years: it was always a stock with lumpy revenues and its growth was always quite limited, but the revenue collapse over 2020 and 2021 took me, and the company, by surprise.
The company’s touch screens are used (for example) in casinos, and one of the effects of the response to Covid-19 was to cancel most of the orders that Zytronic would normally have received from this industry. Another was to disrupt the supply chains on which Zytronic relies.
And in addition to the problems caused by Covid-19, Zytronic has lost out on contracts related to ATM production. Long-term, the need for ATMs is reducing as more and more people go cashless. So even if these contracts had been won, they wouldn’t be a permanent source of profitability.
These major problems resulted in Zytronic becoming a much smaller business. Thankfully, the company did the right thing and reduced its share count: it offered £10m to shareholders in a tender offer at 145p (shareholders accepted £6.7m in aggregate) and also spent £2m on a buyback at an average price of 161p.
This was a cash-rich company and I’m glad to see that its funds weren’t wasted.
But what of the future? Let’s see what’s contained in today’s trading update:
As anticipated in the interim results statement issued on 17 May 2022, due to continued global economic disruptions, the availability and cost of both raw materials and electronic components have proven to be persistent challenges as the second half of FY22 has progressed. This has had a knock-on effect on the Group's customers and has resulted in a lower than anticipated level of order intake being observed over the second half to date.
The result is that revenues for FY September 2022 will only be 5% higher than last year’s £11.7m, i.e. revenues will be around £12.3m.
Forecasts published in May suggested that revenues would be £13.8m, an 18% increase on last year. So this is a significant miss.
And as for profits? “Although still a fluid consideration, profitability for the year is currently expected to be ahead of that reported at the pre-tax level for the year to 30 September 2021.”
Adjusted PBT was supposed to double from £500k to £1m and now it’s far from certain what the final outcome will be.
For an apparently ex-growth, publicly-listed company to be persistently unable to earn a meaningful profit is a worry - remember that the listing fees alone are a six-figure cost. This will be the third consecutive year without a meaningful profit (which I would define as over £1m in net income).
Cash - the year-end forecast is £6m, down from £7.5m at the interims. The company has been buying back its own shares and also talks of a working capital increase as sales and marketing activities resume “after a near two-year hiatus”. So for me, the decline in the cash is not a worry (obviously I would like to see the full-year financial statements to confirm this stance).
Outlook - management are still optimistic for future years:
With an improving log of opportunities and the ability to commit further resources to business development and project progression activities, management remains confident in the positioning, ongoing recovery, and longer-term growth prospects for the Group.
My view
I should mention that with a company this small, it would only be possible to purchase small amounts of it, and some of you may prefer to stick with larger companies as a rule.
Personally, I find this one quite interesting at the current level.
The enterprise value, using the latest cash balance forecast, is £7m. Maybe that’s fair given that adjusted PBT is likely to come in somewhere north of £500k. The question is whether management can turn things around and get this moving back in the direction of its pre-Covid profitability.
The ATM business looks like it is almost finished, but maybe there are still opportunities in casinos and in vending machines?
The key part of today’s update I would focus on is that the company says that its sales and marketing activities were essentially non-existent over the past two years (resuming after a “near two-year hiatus”).
If true, this means that the recent performance (especially considering the other Covid-related impacts) is not at all representative of what the Zytronic should be able to do in “normal” times.
With nearly half the market cap in cash, and the company having demonstrated a strong shareholder orientation by returning cash instead of wasting it during the bad years, maybe there is scope for patient shareholders to experience a nice recovery with limited downside risk?
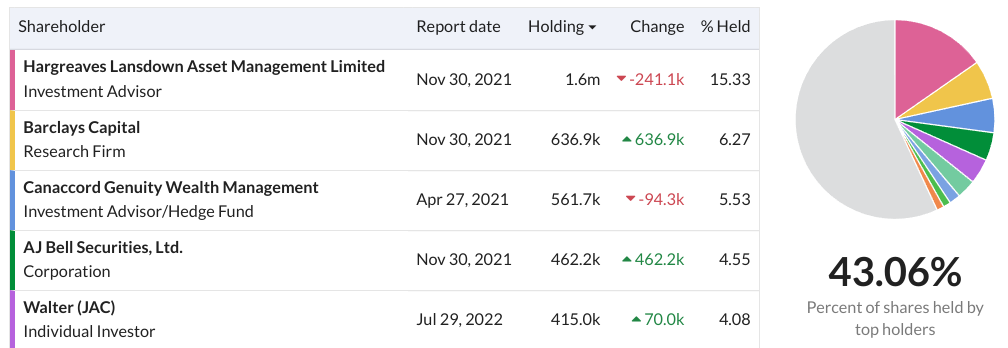
The major risk with a company this size is often delisting risk, if the big shareholders decided that it was no longer big enough to justify the listing. However, having checked out the top shareholders with the help of Stockopedia’s useful tool, I can’t see this one delisting any time soon:
Inspecs (LON:SPEC)
Share price: 224.5p (-6%)
Market cap: £228m ($273m)
This one IPO’d at 195p in 2020.
My IPO rule is simple: don’t buy them. I have seen so many of them go wrong, that I have learned to steer clear of them. The only time I broke the rule (I knew I was breaking it, at the time) was with DP Eurasia NV (LON:DPEU) and that experience only strengthened the rule.
I haven’t proven it numerically, but my experience is that nearly all IPOs trade at a very significant discount to their IPO price before too long. Maybe at a 50%+ discount, they are worth another look?
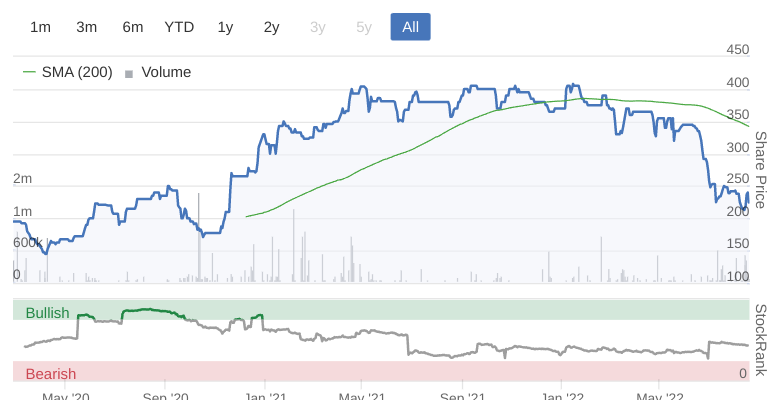
Inspecs is still trading above its IPO price - it even doubled in price at first, before coming back to earth:
It is “one of a handful of global companies which produce large volumes of the highest quality eyewear in-house for supply to the biggest retailers”.
Since listing, it has engaged in a spate of acquisitions, and is still digesting all of these additions to the business. If the strategy succeeds, there will be gains from increased negotiating power: Inspecs talks today of “Group companies working together to ensure enhanced distribution rates for our products”.
Financial headlines for H1:
- Revenue +10% to $138.4m (it was up nearly 16% at constant FX)
- Operating profit more than doubles to $5.8m
- Pre-tax profit $0.8m
- After-tax loss $2.8m
The company has three new factories: a relocated lens factory that is now fully operational, and two others (in Vietnam and Portugal) that are in development.
The underlying EBITDA figure, often the focus of City-based investors and analysts, failed to improve compared to H1 last year, and the CEO explains why:
- The lens factory “took longer than expected to reach optimal production following the move and as a result, we were not able to engage fully with our optical customers as delays were caused by infrastructure issues and the recalibration of machinery following the move”
- “…whilst our European business performed ahead of internal budget for the first half, our reported results were affected by a rapid decline in the Euro against the US Dollar.”
These are disappointments, sure, but the first is just a bump in the road while the second is an accounting issue that doesn’t necessarily hurt the business (depending on how revenues and expenses are spread geographically).
Net debt (excluding leases) falls to $26.2 million.
Outlook:
Our Group order books are ahead as of 30 June 2022 compared to 30 June 2021, and we enter the second half of the year in a good position. Whilst we remain cautious of the overall economic outlook for the UK and European market, we remain focused on executing a number of strategic priorities that will increase production, enabling us to bring innovative new products to market and continue to deliver shareholder value."
My view
Overall, this company has done well for investors since IPO and while today’s results have disappointed the market, they don’t signal any very serious problems to me.
My main question is around the company’s IP: does it have any proprietary, unique assets? Or is it better thought of as a manufacturer of commoditised products?
If it’s best thought of as a manufacturer, then we need to be careful with valuation. As a general principle, In the absence of IP, manufacturers shouldn’t trade far above their book values.
Inspecs has net assets of $134m according to today’s balance sheet, but this falls to just $15m if we exclude the large entries for goodwill and intangible assets. At a market cap equivalent to c. $270m there is a huge premium built in, and I’m not sure how it’s going to justify this.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

87 comments
Re Angling Direct (LON:ANG) - Like with so many consumer focused shares at the moment I think we need to be patient. It is doing the right thing, steadily opening physical stores whilst also establishing itself as the no UK fishing site online and thus growing share. Its hybrid model approach makes sense (cheap stores for live bait, chatting to fellow fishing enthusiasts instore, getting their emails for free!) whilst online is low cost to re-serve, cross- and up-sell and to serve those outside efficient catchment areas. The online part is key because look at the trend from the ONS graph below - structurally transactions are moving online. Covid was a blip up yes but in 10 years will be a bump
UK angling is an ageing/white/male sport but showing some signs of diversifying and creating new audiences, with some countervailing forces helping (healthier, longer lived retirees, mental health benefits of the outdoors increasingly seen). In short I can easily see its market holding at £600Mn in real terms for years to come (assuming we start looking after rivers and seas better).
Europe is said to be the same dynamic as the UK (I have to take this on trust) but even more fragmented and offline.
I see Angling Direct (LON:ANG) as the same as Gear4music Holdings (LON:G4M), a leading player in a slow growing niche slowly building a great online position and own label business in a consolidating market. Lots of cash and not going obsolete inventory means it can keep going with its strategy. At some point, all this will be highly valued again. Just may have to wait 3-5 years. With that non-trading perspective, a small profit miss is small fry.
I hold and may buy more if it gets any cheaper.
Hi Zipmanpeter,
What a fantastic post on Angling Direct (LON:ANG) thank you very much!
In particular your graph from the ONS very much supports what Next (LON:NXT) said recently, and my key argument about eCommerce being a good place to look for recovery shares, because the stock market is wrongly pricing these companies as ex-growth, when actually the pandemic pulled forward growth, with a hangover in 2021/2, and we should now start to see normal, structural growth resume. That's the big trigger for a possible sector re-rating from irrationally low levels.
Although declining consumer confidence (record low reported in today's papers) could mask the return of structural growth until into next year maybe, who knows?
I hadn't thought of the impact of filthy rivers (due to the scandal of criminal water companies pumping raw sewage into them) on fishing. That's another good point.
Best wishes, Paul.
Worst IPOs since Jan 2020 https://www.ft.com/content/a8e...
Seven worst based on first day's price: "MusicMagpie (-77.2%), Guild ESports (-79.5%), Victoria Plumbing (-80.6%), In The Style (-85.3%), Revolution Beauty (-88.4%) or Seraphine (-91.8%). But the IPO crapco title goes Parsley Box, an ambient ready-meal delivery thing, which is down an exciting 94.6% since arriving in March 2021" But Made.com is worst based on IPO price (200p), down 95.2%.
I see Boohoo (LON:BOO) has continued building its stake in Revolution Beauty (LON:REVB) . Its ownership is now up to 12%. The market doesn't seem to like it as Boohoo (LON:BOO) has slipped 4% today. I wonder where this will end?
I never held Made.Com (LON:MADE) but on the subject of IPO’s, I have been listening to the Berkshire AGMs on Spotify in the car and while running (possibly a bit sad but I, and even my wife, find the “Wazza and Chaza” show riveting listening and incredibly educational, to the extent I might now read the transcripts.). I have reached 2016 and in 2016 or 2015 Buffett turns to Munger (in the course of answering a question) “I don’t think we have ever invested in an IPO have we Charlie” and Charlie replies “no we never have”.
Of course we don’t have to slavishly follow Buffett but in general the buyer in an IPO is at a disadvantage the seller holds most of the cards I feel.
Regards
Michael.
The meetings are at
https://open.spotify.com/show/...
A link to the transcripts can be found here:
https://www.dropbox.com/sh/k42...
I think Berkshire bought shares in Snowflake at IPO in 2020 but they may have been adding to an existing holding bought when co was still private. It may also have had not much to do with Buffett or Munger, it could have been a decision of the guys who run Berkshire now who will eventually replace them.
Joe
Looks like you are right (though this is post the AGM I was listening to) https://www.fool.com/investing... but looking at the price since maybe Todd Coombs when asked the same question (have you ever invested in an IPO) in say 20 years time may reply "we did once in 2020, never again, I learnt my lesson".
Regards
Michael
More on UK IPO’s this year in the FT at:
https://www.ft.com/content/a8e...
which includes talk of Made.Com (LON:MADE)
Thank you Paul for having a look at £IMMO. I share your enthusiasm about its potential to grow revenues and think it's well worth keeping an eye on. I failed to buy a small position at the open and decided to wait until September.
Cheers
Francis
Am not sure if others have picked up on this in recent days, which is making me reassess some of these 'semi conductor shortage' depressed shares.
This from SP Angel.
Chips – the Semiconductor market appears to have gone from a significant shortage to a rapid build up in inventory levels
• Computer memory chips are reported to be in significant surplus, almost a first, as consumers cut back on high cost purchases.
• We also suspect that so many people bought new laptops and computers during the Covid lockdowns that there is little reason to replace this equipment this year.
• Automotive manufacturers should be relieved, but we strongly suspect they are still short of other types of chips, particularly for complex emissions and engine management systems.
So we are looking for companies operating in the B2B end, perhaps non-consumer end of the market who have reported a shortage of chips holding up production/sales. The only one off the top of my head is Concurrent Technologies (LON:CNC) - anyone else got any that may benefit from this supply chain loosening?
CNC - I hold
Graham, another source indicates that Zytronic (LON:ZYT) is owned in the majority by Institutions but why should they want this company to delist anyway? I continue to hold and persevere with it.
Zytronic (LON:ZYT)
Graham - thank you for your detailed commentary on ZYT. Seems we are largely on the same page?
'the company says that its sales and marketing activities were essentially non-existent over the past two years'
Yes, this is something that I have wondered about as well. I wondered why such a technology led company seems so dependant upon physical sales opportunities through events and trade shows. Until I considered how you would go about selling a 2m long multi-touch, multi-user interactive table top or wall screen over zoom? I've no doubt that they are trying hard - but for the high end high margin products I can see that physically trialling the product is key?
Another future opportunity is EV charging stations according to management. Between 10 and 20% of the forecast EV charging stations will be interactive (rather than just plug in and tap your card) - capable of advertising and selling as well. Just what all these people will be doing at charging stations is an emerging theme for quite a lot of businesses at the moment? One of ZYT recent product innovations is to include a payment certified touch keypad within their screen - removing the need for a separate keypad unit. Is it an opportunity? The new ATM? Or will we end up with instant charging? Physics and infrastructure make that somewhat unlikely in the short term?
With an EV (thats enterprise value this time) of around £7.7m at this year end on today 135p - and assuming profits of around 500k its trading on around 15x earnings. With reasonable improvement once OEM orders pickup it seems priced about right - but I like that these new product/market opportunities are essentially in for free.
cheers
Mark
I was concerned by the following comment by Zytronic (LON:ZYT) "This has had a knock-on effect on the Group's customers and has resulted in a lower than anticipated level of order intake being observed over the second half to date."
Revenue trends were also concerning:
1H22 £5.9m (1H21: £4.8m) +23%
2H22 (est) £5.8m (2H21: £6.9m) -16%
The second half appears to have gone into reverse from the growth seen in the first half and such changes make me nervous. Whilst ZYT says they have not been actively marketing, is the issue around customers not accepting the price increases and going to a competitor?
I acknowledge this is short-term and perhaps in the longer term, these issues will be ironed out. But I would like to see more defensibility around their business.
Hello Reacher,
Re: Zytronic (LON:ZYT)
you have ' 2H22 (est) £5.8m (2H21: £6.9m) -16%'
Yes that made me concerned.
However, for the FY 5% up on £11.7m is just under £12.3m? With H1 at £5.91m that leaves
H2 22 at just under £6.9m
or between -7% and -8% rather than -16%? Or have my big thumbs mixed up my calculator digits?
In any case, the result is the same, revenue has gone into reverse in H2, which is a shame after an excellent H1.
Not sure about the price and competition. My feeling is that once an OEM has engineered in the component they are less than comfortable with changing them at will. But thats just a gut feel.
In the presentation and Q&A management indicated that they were passing on price rises but being careful where it involved new business and/or large opportunities. Clearly there is some level of issue, but my current judgement is to trust management and accept their explanation that its down to OEM disruption and production.
However trusting management is a weak point and I could be wrong here. In any case current orders are primarily older products, my main interest is to see how the new products take off now that they are actively being sold,
cheers
Mark
Thanks Mark - that's useful narrative. And thank you for re-checking my numbers. The correct numbers are:
1H22 £5.9m (1H21: £4.8m) +23%
2H22 £6.4m (2H21: £6.9m) -7%
I previously held the view ZYT management had a good grip on the business and were conservative in capital allocation. I would want to see some stability in the level of orders. The step-up in marketing might help alleviate this and something I will look at.
I've enjoyed reading your Zytronic comments Graham, thank you, it seems I'm the patient shareholder! By the way, I've noted yours and Paul's comments about delisting risk previously and you're both right. I stubbornly didn't sell when Shore Capital delisted a few years ago as I thought it undervalued the company significantly. It did, good dividends help though before we have to one day ask their CFO if he'd like to buy our shares!
Somero Enterprises (LON:SOM) has broken out of its falling trend and is currently trying to break above the 200dMA. Some significant volume over the last few days. Looks good for 500p or even 540p if it can hold above.
Somero Enterprises (LON:SOM) possibly interesting info on US construction.
Non residential is up 79% might explain recent SP strength.
Typo in the top slide should be Jun 2021
Quite interesting data out from ONS on economic activity this morning.
A few things caught my eye:
pre-coronavirus (COVID-19) level, while the number of employers
proposing redundancies was 79% of their pre-coronavirus levels.' Although I read somewhere that unemployment tends to lag negative economic data?
Will you look at Capital (LON:CAPD) Paul and Graham. please. They are a very good mining support company with several extra strings to their bow.
Don't think these guys do mining or mining related. Don't miss there is a investor presentation which is just winding-up now . Link is in the RNS.
Mark Simpson covered Capital (LON:CAPD) in his finding value report. He holds and is bullish as am I.
To quote his article:
A well-known aphorism suggests that the people who really got rich during the gold rush were the providers of picks and shovels. Capital Limited is the ultimate mining “picks and shovels” company; it provides drilling and mining services, and analyses drill samples for miners, primarily in the gold sector.
£CAPD Yep. Modern day picks and shovels is an attractive idea. Not without risks though, given the target geography and there was also a $10m loss posted in the "investment portfolio" this morning which put a big dampener on an otherwise impressive set of first half figures. Anyone know what that is all about?
Capital (LON:CAPD) hold a portfolio of investments in miners - mainly gold miners and mainly their own customers I think. They said in the figures today that $26m of their revenue was from these companies in the last half (figure from recollection of what i read this morning). Anyway, gold miners in general have not done so well the last six months - counter-intuitive in an inflationary scenario but the price of fuel and chemicals for extracting metals have gone up while the price of gold has not. I don't know what's in their portfolio so I don't know if there have been any company specific issues.
I hold.
Thank you - very helpful. TBH sounds a big suspect to me investing in your customers. Any idea if this is common practise amongst mining service firms? I'd rather see them invest the funds in the core business given ROCE is nearly 20% or return it to shareholders via higher divs or a buy back.
My understanding is that in most cases they received equity as part of the drilling contract - these stakes generally had a minimal cost but have since appreciated strongly, so not as if they've been investing millions in these companies.
For info on Capital (LON:CAPD)
Berenberg analyst Richard Hatch raised the price target on Capital Limited (LN) to GBP1.73 (from GBP1.69) while maintaining a Buy rating.
Paul, I know one of your interests at the moment is online retailers who might be going 'cheap' on a longer-term view. I see Angling Direct (LON:ANG) is down significantly this morning. I have no value or insight to add but it's been on my list of stocks to look at - it'd be great if you get time to see whether this might now be a buying opportunity or if there is a more serious problem at this business especially following the website hack (I think?) a year or so ago.
I wonder whether the drought might also have an effect on Angling Direct (LON:ANG) going forward. Rivers/Lakes under strain with low levels of water might mean some restrictions going forward? Plus maybe it has just been too hot to sit outside fishing?
The fishing tackle trade had 2 fantastic 'lockdown' summers, it was one of the few outdoor pursuits allowed, coupled with very little travel and decent weather ( for fishing) meant a bonanza for most , although Angling Direct (LON:ANG) suffered with stock because wholesalers could sell everything they had to smaller retailers and Angling Direct (LON:ANG) were expecting/needing a discount. Now, like many trades in a similar position they have faced the perfect storm. The new Covid anglers have stopped going, too many other things to do and the diehards are being told that they should be spending more time with family, holidays etc. The cost of living is biting, not enough new product stock from China to entice impulse sales and also the worst possible weather for fishing.
On the positive side Angling Direct (LON:ANG) is a different business to 3 years ago, the new CEO is different class to the previous one who IMO was out of his depth. A lot of the independent retailer competition is of an age where most are retiring and not being replaced so as long as fishing remains popular Angling Direct (LON:ANG) could turn it round.
The cash pile at £ANG could be used to acquire manufacturing facilities/brands which I know is in managements sights from speaking with them. Looking at what private equity firms have attained in the US, they have acquired quite a few successful fishing brands and continue to do so, there is already a fair amount of consolidation in the industry. With ANG producing more of its own brand and adding to that consistently with further own brand launches on the horizon and past problems with getting stock from China, it seems within the realms of possibility in becoming more vertically integrated and gaining larger margins.
Morning PatrickL,
Yes I'll be looking at Angling Direct (LON:ANG) shortly.
Here's today's agenda, not sure if we'll get to all of these, but we'll try!
Hi Paul and Graham,
This is such a useful feature, I was looking at Inspecs (LON:SPEC) and was going to ask if one of you had time to take a look and now i have no need.
Thank you.
This is such a useful feature, I was looking at Inspecs (LON:SPEC) and was going to ask if one of you had time to take a look
Indeed. I’ve just read through the whole report. Last time the company was discussed I argued that you could buy the dominant EssilorLuxotica (I hold - a lot) for the same valuation. This proved a propitious warning (to myself) and I stayed clear. Now shares are more reasonably priced it seems worth a second look.
I’m not greatly impressed by the TU. Profit targets have been missed and cash generation is anaemic. There are factory problems, currency challenges and the economic outlook is very unfriendly. The claims of progress in areas like distribution, integration and planning are not at a stage where they can be verified in the numbers. On the other hand, the company’s problems are certainly not all of their own making, as they are primarily macro driven, or so we are told. It’s worth noting that the aforementioned EssilorLuxotica has not suffered to the same extent from demand issues. The company is also considering changing its reporting currency, currently USD, as the fall in the Euro has been a major contributing factor to the profit miss. My concern would be that they switch reporting currencies just as mean reversion sends the Euro higher!
This remains an attractive sector for vision-challenged investors like me and the company could yet enjoy strong operating leverage at a reasonable valuation as market conditions improve. It could also be a good take-out target for eyecare giants with big distribution networks. Looking forward to Graham’s review.
Thanks BnB, it was the possibilty of a bid at some time that made me look TBH.
R
agreed
Seconded. This was tipped in Sunday Times and seemed a rare one that passed my sniff test and I was a bit gutted to miss a 9% rise on Tuesday after about 5% on Monday sitting on my hands as more often than not these things fall back. Def the case here and agree update slightly disappointing
Seems about the right price around current levels. Maybe a bid at some point if it falls further but is it worth holding just for that now...no. So one for watch list. Thanks stocko
Inspecs (LON:SPEC) - Seconded. This was tipped in Sunday Times
I think Graham’s point about IP is a really good one. And the relative valuations of this business and EssilorLuxotica in the face of more challenging market conditions today really underlines the value of the eyewear behemoth’s multiple enduring luxury brands (Ray-Ban, Oakley, and most of the big fashion houses on licence), it’s dominance of lens technology IP and its globally significant distribution outlets (18,000 opticians and retail). Now that’s a moat.
Wynnstay
On he counter to my point below .
Fund raise that excludes PI will reduce the churn as you would hope institutions have committed to long term hold .
The “theft” or “value destruction” or “dilution” is around 1%. - based on they issued around 10% shares at a 10% discount so effectively they have nicked from me and passed to sone institution 1% of my invested value .
Ain’t going to kill me but I don’t like someone passing my wealth across apart from my good lady.
Share price mathematically should be 1% lower today to allow for this daylight robbery / legal transfer of wealth to happen .
On the plus side they 10 million quid to grow the business and make acquisitions and presumably they will be trying to do this by more than the “stolen” 1%.
Thus the counter argument is this is a buying opportunity as share price dip is greater than the 1% destruction calculation .
Can currently buy at 596.90 and sell at 593 so a pretty tight spread .
Not sure which way to jump as Wynnstay was the one company I was looking to increase on .
Heart says screw them and sell up .
Head says this is a decent buying opportunity .
Probably best to take the dog out .
Hi Plantx
I saw this too late last night on Wynnstay (LON:WYN) and was like thanks for all the support. I like the company, have done ok out of it to date and the decision to raise more funds and the narrative behind it does not make me feel like this is a what the beep, vanity purchase that means it changes my investment case...
Though I will write a letter to the CEO tonight, old fashioned paper one obviously, and obviously that it is a do not a lot option for the banks to just go to their mates and get a deal away at a discount, and how much off their fees did they give you for undertaking that option?
Especially when there are more options available the likes of Supermarket Income REIT (LON:SUPR) and Impact Healthcare REIT (LON:IHR) regularly raise but always give a chance to existing holders to by in, I just get a corporate action through Halifax and IWeb and say yes or no to buying more at the price offered, and unless it is an emergency, which this is not, the few extra days to even put something through primary bid (doesn't help me as in an ISA) at least gives you a chance to say yes.
Sometimes an old fashioned letter does have some effect, rather than yet another email.
Cheers
Tommy
Take the dog out and buy on dips
I notice that Mears (LON:MER) is up considerably today...they released an 'ahead of expectations' update a couple of weeks back and the sp actually went down a bit ! What accounts for todays rise ? Have they been tipped anyone know ?
Zytronic (LON:ZYT) released a profit warning today. My back of the envelope calcs show that it means H2 revenues look like 10% higher than H1, and potentially EPS is 30% higher at 4p, giving a full year of 7p. Below broker forecasts of 7.35p.
Clearly disappointing as now priced (pre open) at more than 20x earnings, which in today's market is a bit rich.
However, the hidden value is in NTAV, at 145p at HY results (and likely increased with the modest profit). And this figure is an understatement, as the land holdings they have are on the books at cost value from 2006. Ample cash in the balance sheet, potentially for another round of buybacks, as they have authority till Mar23.
Solid asset backing but lacklustre trading and potentially not the right management to make it work. My dilemma.
(I hold in the Boon Fund)
Actually, my mistake... On re-reading the Zytronic (LON:ZYT) trading update, it implies that H2 is going to be barely breakeven. So this gives a FY EPS of circa 3-4p. Very poor. This implies margins have collapsed in H2, which they don't explain at all.
RE: Zytronic (LON:ZYT)
This implies margins have collapsed in H2, which they don't explain at all.
I think they do, albeit indirectly: "the availability and cost of both raw materials and electronic components have proven to be persistent challenges as the second half of FY22 has progressed"
Their customers can't get the other components they need so they don't need Zytronic's display units. This suggests they have little visibility of forward orders or control over demand - which implies they've overproduced, meaning costs aren't matched to orders, hence margins have reduced.
I'd add them to the list of companies that have been overoptimistic about economic conditions - In fact I'd say at the moment that any company predicting that they'll make up numbers in the second half is pretty much signalling a profit warning. The wording here is interesting:
"Although still a fluid consideration, profitability for the year is currently expected to be ahead of that reported at the pre-tax level for the year to 30 September 2021."
So with only a few weeks to go they can't offer any certainty of profits.
timarr
I guess Zytronic (LON:ZYT) are frantically trying to get some clients to sign on the dotted line, to book in revenue before year end, which could swing the profits wildly when it's probably at breakeven at the moment.
Thank you Graham for your analysis. One thought that hasn't crossed my mind before is that they'll probably be better off as part of a larger, vertically integrated group. Makes a good strategic takeover, as NTAV is so strong, any acquirer is getting the business for a song, even if they come with a 30-40% bid premium. As post-covid growth gets more challenging and many companies have built up cash rich balance sheets, I wonder how many CFOs and CEOs will be tempted to use bolt on acquisitions, especially if synergies can be extracted, to add additional revenue and profits.
I held Zytronic (LON:ZYT) for a couple of years and sold out last year. Without digging out my notes, my recollection is that their sales were declining in the casino market because the companies they supplied to were losing out to an (Australian?) competitor. Then the pandemic hit. Worth checking out what the latest is on the sales to the manufacturers of slot machines and what's happening to their own market share.
PS Apologies, it seems Illiswilgig had already raised this point.
Zytronic (LON:ZYT)
'So with only a few weeks to go they can't offer any certainty of profits.'
Timarr - you are quite correct. Though they are offering reasonable confidence that it will exceed last years profits. Long term management here are quite cautious so I've no doubt having been bitten they will be twice shy right now.
ZYT management were clear on their recent IMC presentation that they have an average visibility of 4-6wks of order lead time from placement to delivery. With more than 4 weeks still remaining of the FY, certainty of profits would be hard to achieve?
There may well be an element of building for stock for smaller and faster moving items - but this is unlikely to be significant - at completed unit level anyway - as each OEM may be ordering very different sizes and configurations.
Another factor here is that ZYT's success is tied to the success of its OEM customers. It turns out that the rapid rise in revenue from gaming was actually due to the highly successful gaming table of just one OEM customer. Which is great while it lasts. But not when the product ends, as with the ATM's. Management think that their increased sales and marketing will lead to a wider base of cutomers reducing the reliance upon the success of any one OEM product.
cheers
Mark
My wife and I hold too Boon, I quite like the managements tell it as it is style. Market reaction so far seems mild and I would consider adding if it falls much further. I noticed a private investor bought 70,000 shares taking his holding to over 4% less than a month ago and you'd think he likes the hidden value you mention too.
Boon – thank you that’s a good summary. I’ve been looking at the figures and my forecasts and perhaps am a little more bearish in the short term on today’s profit warning. Though my longterm forecasts are not affected by this.
(Edit - in the time I've taken to write this - I've become outpaced by other posts - my apologise to Boon, Timarr and Graham if this is repeating your commentary).
Zytronic (LON:ZYT) (I hold) Trading Update (FY ending 30th Sept) and profit warning
Ooops. Profit warning. Another one that I should have seen coming.
First sentence sets the tone – global disruption, component shortages and price rises. ZYT looks to have navigated these challenges well. But unfortunately its OEM customers haven’t. They’ve made fewer units and consequently ordered fewer touchscreens from ZYT.
The 5% increase in revenue YoY is a substantial slow-down. H1 was 25% ahead. Which means that H2 will look more like a fall of around 7% in revenue. That will impact operating margins, as do rising component costs, energy and labour. H1 eps was 3p. FY eps greater than 3p puts H2 potentially not much higher than break-even? Hard to tell from the limited information.
Three things I note from this:
[1] ZYT remains a business in turnaround. Revenue remains far below the 20m+ pre-pandemic. The legacy ATM (financial) market has diminished rapidly – new products and market opportunities are large but will take time to build. ZYT has reset its cost base to a lower level – albeit that must now be increasing – and through a tender offer and subsequent buy-back has around 1/3 fewer shares.
[2] Coming out of the pandemic and lock-downs ZYT has generated new IP, launched new products into new market opportunities and increased its business development, sales and marketing effort – resulting in an increasing pipeline of prospects.
[3] ZYT has an average order visibility of 4 - 6 weeks lead time from order placement to dispatch for its OEM customers. The revenue fall in H2 is very disappointing, but can reverse very quickly assuming that the OEM’s do increase their manufacturing again - then ZYT orders will increase rapidly – as will any order intake from new prospects in the pipeline.
In the meantime the company remains profitable and cash rich. The £7.5m net cash at H1 reduces to £6m primarily through share buy-backs (now completed) and increase in inventories.
Why is it even listed? I’ve considered this as carefully as I can. The risk is not low with any micro-cap of this tiny size? This question was asked of management at the AGM – I didn’t hear the Q&A but the answer given is that their OEM customers prefer them to be listed, consequently ZYT management feel that the costs are outweighed by the sales and marketing advantage. There are no large shareholders on the register to take it private and long term management have small shareholdings. They are not overpaid and are competent management not entrepreneurs. There seems no reason for them to delist the shares in the short term? While the risk of delisting remains, and today’s profit warning doesn’t help the perception, in the medium to long term revenue and margins should rise rapidly as new products gain traction. A listing remains the best way for the value to be realised.
Of course, that’s the glass half full view. I often find that my glass turns out to half empty instead. I may well be talking my own book – so challenging views are most welcome!
I’d been expecting the shareprice to fall more quickly once the buy-backs completed. The silver lining to today’s profit warning is that the share’s may fall significantly – hopefully enough for me to topup as I consider that the long term opportunity, on which I have invested, is unaffected by the short-term impact upon ZYT’s OEM customers. Wish me luck!
Cheers
Mark
Good luck Illiswilgig, we're onboard with you!
Thanks JASVFS - the same to you on £ZYT - which seems to be holding up better than I'd anticipated today. Still there is always tomorrow! I remain waiting to top up, but in view of the large and illiquid spread I do want a lower price first,
cheers
Mark
The benefit of a good NTAV backing; without that I think Zytronic (LON:ZYT) would have fallen by at least 15-20%, given that it is quite a swinging cut to broker EPS forecasts expected and leaving it on a what will be a 30-40x PE rating in this day and age.
Having read through your detailed comment, I think its interesting what is not mentioned; no mention of traction of the new products / sectors, no mention of gaming sector sales and revenues. No mention of a bright order book outlook or pipeline.
(I hold in the Boon Fund)
Good morning Paul and Graham, could you include Aeorema on your list today please (AEO). Another upgrade on profits and opening of an Amsterdam office. Sadly I don't hold anymore! Shame also about the big spread (as wide as the Grand Canyon?!)
ATB DH2
Morning Dieselhead2,
Aeorema Communications (LON:AEO) is only £6m mkt cap so too small/illiquid for us here. Although I see it's up 12% at the open, so might be good. By all means post a synopsis, if you think it's good.
Thanks, Paul.
EDIT: OK I couldn't resist, so had a look. This looks quite good actually, the best bit being -
Further to the announcement of 13 July 2022, Aeorema wishes to update full
year guidance and now expects to report FY 2022 revenue (subject to audit) of
£12.2 million (previous FY 2022 guidance of £11.8 million, FY 2021 actual:
£5.09 million) and profits before tax (subject to audit) of no less than
£830,000 (previous FY 2022 guidance of £700,000...
It's an -
AIM-traded live events agency
So presumably now seeing a recovery from the pandemic. It also mentioned expansion in Europe, e.g.
The sheer scale of work completed in the final weeks of the financial year (YE
30 June 2022) primarily at Cannes Lions during June 2022 where Aeorema had its
largest ever presence with projects undertaken there increasing in scale
whilst on site, has had a further positive impact on expected profitability.
Overall, at a first glance, this does look quite interesting. As I say though, too small/illiquid for the SCVRs, but that's no reason why readers can't look at & discuss it yourselves here.
The website looks very poor. It needs some videos to show what it actually does, instead of text talking about immersive experiences. Maybe there's another website? I was looking here: http://www.aeorema.com
Paul
£AEO. Graham might want to make an exception and comment as I believe he was a former shareholder and commented on it a couple of years back?
Can I just add that they also have £1.6m cash so a cast iron balance sheet, are winning industry awards left right and centre and are expanding rapidly to meet demand.
As they build a higher profile I would be very surprised if they are still independent in 12 months time and I see a takeover price at least 50% higher.
I hold.
Thanks very much for your resume on AEO Paul. I have been cursing to myself each time I see a trading update/results from them, as I sold back in early Nov 21 (although it was at a nice premium). I have been waiting for a decent pull back to re-enter, but it never happens...! I know Alan Charlton was/is an investor and it was his comments on them on Mello Monday which piqued my interest a couple of years back. I live in hope of that re-trace, but suspect I will continue to be disappointed!
Your views on update from ANG if possible please?
Morning CHRI55,
I'll probably look at Angling Direct (LON:ANG) next, looks like a mild profit warning.
Regards, Paul.
[edit] ◄AO World (AO.)► FY-Mar. This Q1 broadly in-line with FY mgmt expectations, with revenues c. £1bn to £1.25bn (£1.6bn) and adj EBITDA £20m - £30m. Closure cash costs of German business £5m max, at the lower end of estimate of 0-£15m. I hold.
Thank you MrContrairian for your ongoing morning summaries. Most useful.
So £Alu issued an RNS on Tuesday to say it would do a results presentation (only) for sell-side analysts. I’ve asked if there can be one for retail shareholders but so far no response. Not only is this wrong, for a £50m market cap company that would benefit from more awareness/liquidity, it’s just plain madness. If there are other holders on here, would you consider asking too?
can’t get the £ thing to work, it was Alumasc.
Gotta use capital case letters to make the thingie work.
Good morning Paul and Graham
I wonder whether you or the community here have any view about Immotion (LON:IMMO) trading update today? It's a new one on me but in short it runs VR type immersive experiences at Leisure venues. Had an understandably terrible time during Covid but revenues seem to be strong with July being a record month (£1.3m). Looks like it might start making a real profit this year (having made £0.9m EBITDA in 2021 financial year from £9.5m t/over).
£13.5m market cap and very low stock rank of 13.
Anyone have any richer insights into them?
cheers
Francis
Don’t think management have received enough credit for their creation of 2 new businesses during covid which enabled Immotion to survive . Also had to cope with the sad death of a very significant individual in the company. Price has recently been weak . Company announced is divesting the 2 new businesses and we are waiting to hear news on this which is likely to be price significant . We are also waiting to hear figures from the recent Chinese licensing deal but management have indicated will be positive. I think investors would also have liked to see a quicker take up/rollout of the Zoo oriented Location offering. But Pittsburgh zoo has been launched recently so hope this will provide good case study and take up by other zoos . Management are small investor friendly and actually engage and reply on Advfn . In summary I am happy to hold and expect good progress in next 12 months in biz and share price
Thank you Fegger for your thoughts on £IMMO - that's why I love the community here.
I did try to buy a starter position this morning but it's (perhaps understandably) very illiquid.
Cheers
Francis
Immotion (LON:IMMO) I bought after a Mello presentation. It looks like a simple business model with the potential for great operational gearing on the back of a long roll out. A true global market not materially constrained by shipping costs or logistic issues. It has struggled to impress the markets but approaching profitability, that should sort itself out.
I think the rise today follows weakness approaching the trading update. Hopefully this will mark the watershed and the company will find more support.
Immotion (LON:IMMO). Just to reply to a couple of points Paul made above. It's not that useful to compare H2 2021 revenue to H1 2022 because of the seasonality in the business as school holidays mean June, July and August are the peak months and so there is a H2 bias, the company wouldn't provide the exact split when I asked but full year figures for 2022 should make this clear. 2021 is not a good example because of the impact of Covid.
The company also very usefully provided average weekly revenue per headset in the 2021 results £441 at partner sites and £284 at owned sites, which allows calculations to be made as the number of headsets increase and it will be interesting to see whether those figures increase slightly as installations mature.Also their broker W H Ireland have forecasts which say they can fund expansion from existing cash reserves, which don't include any proceeds from the sale of the HBE and Uvisan businesses. They could of course raise to increase the speed of rollouts but they seem to be doing fine as they are.
Finally, there is a useful vox markets interview with Martin Higginson, the CEO at https://t.co/ogqNwlMyon which provides some background on the data gathering at the large Milwaukee zoo installation, as well as the smaller pop-up at Chester zoo, which will inform discussions with prospective zoo customers
Increased guidance and dividend announced by Capital (LON:CAPD) today. I’m looking for this good news to provide the impetus for a breakout above 96p today.
Hello Revs8, I agree on your comments o Capital (LON:CAPD) which showed good results today. The positives are there for all to see. There is a presentation today at 0900 including Q & A. I wont be abel to make it. Hope someone will
https://www.lsegissuerservices.com/spark/CapitalDrillingLtd/events/db8bbc58-599b-4a60-aa07-abc49d7d187d
To all making comments on Capital (LON:CAPD), I was able to just get my breakfast in to wife's satisfaction to hear the final bit of Q &A.
The remaining Q&A content wasn't of much value, but they did mention an InvestorMeetCompany presentation at 0900 next Wed 24th.
When I went into IMC initially, it wasn't there but it is now, and I have registered and added some questions, specifically about 1. how much larger is the 2022 capex of 55m than their original plans for 2022; 2. they have previously mentioned broadening and expanding the business by tendering into other metals (e.g.copper?), presumably still in Africa, where they are self-declared specialists.
I do think they are a very well run company, and have broadened their customer numbers significantly in recent times. Centamin (LON:CEY) is still a very big one but they have recently B2Gold to their list of high quality customers.
Their lab business is a very welcome and unique add-on and the growth of this as a result of increasing the deal with the specialist provider is forecast to give very significant growth. I believe this is also valuable additional business because I believe the FD today said the margins on that were approx the same as for the bulk of their business.
The reduced - though unrealised - value of their investments is a drag but presumably as we come out of recession in due ccourse, then this will come back too.
I am a bit disappointed with the market response today given the very supportive figures for this half in the Trading Update. Thoughts?
Further to your comments Revs8, I wanted to get the link up quickly for Capital (LON:CAPD) meeting for others hopefully. More comment - it is so lowly rated for such a well run Africa gold mining support specialist. PE is very low. apart from fact that it is overseas, I guess a couple of negatives may be the write down - though unrealised - figure on investments, and the high capex now for 2022 of 55m. I cant remember whether that is much higher than expected at the last finals, if any figure was stated in the outlook then. I am looking forward to more contracts and especially if they can expand beyond gold which they have mentioned before.
re £CAP, the projected capex looks larger than previously indicated - the update mentions taking the rig count to 120, against 108 at the moment (from memory). What profit figure to take is a puzzle - they have taken investment positions in some of their customers, and the value naturally fluctuates by large amounts. Don't know whether the PER is too low - they are a contract driller for miners, with all the cyclicality that implies. But at the moment things look good. (I hold.)
Capital (LON:CAPD) I have a holding but don't underestimate political risk and (I think) customer concentration risk. The parts of W Africa especially in which they work is a little too close for comfort to the nearly unreported war going on. https://issafrica.org/pscrepor...
deleted
Wynnstay (LON:WYN) Placing
"Under the Placing, 1,900,000 new ordinary shares have been conditionally placed pursuant to the Placing at a price of 560 pence per Placing Share.
Shore Capital acted as sole bookrunner and sole broker in connection with the Placing. The Placing was significantly oversubscribed."
Why didn't they increase the price until it was just fully subscribed instead of oversubscribed.
Because it was a stitch up with the financial institutions investing at the expense of PI .
Just wrong
Big red flag for Wynnstay .
Discounted placings are a very difficult subject. In principle, it is clear that it favours one shareholder (or even non holder) over another for no objective reason. It is almost like paying a dividend to some shareholders who you like and withholding it from other shareholders of the same class that you happen not to care about. I did invest in the City fibre roll out of dark broadband cabling, which was operationy relatively successful. The problem was that every time the share price advanced, management issued a 25% discounted placing to it's favourite institutions and I was left nursing a loss. So I sold out and have maintained a bad attitude to discounted selective placings (and Citi Fibre) ever since.
having said that I was also a holder in Judges Scientific when they did a discounted institutional placing. David Circurel, the CEO, was challenged by a PI on this and he replied that he fully understood the concern but that sometimes, in order to attract the right shareholder into the company, it was necessary. He hoped this occasion would give the company a strong enough boost it would benefit everybody including private investors. Almost needless to say, just after the placing, the share price rose substantially and quickly.
Ultimately I formed the view that you have to decide whether or not to trust management. In the case of Judges scientific the answer was, of course, absolutely!