Small Cap Value Report (Thu 18 June 2020) - DLAR, NRR, RNO, VLX

Good morning, it's Paul here with Thursday's SCVR.
No preamble today, as I've run out of material.
In case you've not seen it, I added a section on Wincanton (LON:WIN) yesterday afternoon, to yesterday's report here.
Estimated timings - the main report has to be finished by 12:45, as the car needs to go back in for an MoT re-test. But I'm hoping to add a couple more sections later today. Today's report is now finished.
I'll start at 7am, and will start with the scheduled results from Newriver Reit (LON:NRR) (I'm long)
De La Rue (LON:DLAR)
A friend rang me yesterday afternoon, and ran through the bull case for DLAR. It sounds very good. Therefore, I think I've made a mistake by selling my 40k shares yesterday. Happily, it turns out that the open offer entitlement of 7 new shares for each 16 existing shares, was set at 8am yesterday. I sold after that time, therefore still have the entitlement. This means I'll be entitled to 17,500 new DLAR shares priced at 110p. The market price is currently 160p, therefore there's an instant profit of 50p * 17,500 = £8,750. Very nice indeed. I had intended opening a short on DLAR for 17,500 shares, to lock in the 50p profit (and then close it when the new shares come through), but my friend convinced me that would be another mistake. He's really very bullish on the potential for the company, with new contracts coming through now, and costs drastically reduced. He's normally very thorough with his research, and tends to make money overall from the market, so I've decided to take notice of his view, and stick with DLAR, with a view to buying more if it dips back down.
The problem I have, is that I look at so many companies here, that it's difficult to find the time/energy to really focus on the best ideas. Therefore I do tend to lean on my long-standing network of investor friends, and ask the shrewdest & sector-relevant people what they think of particular shares, as in this case. Over time, you gradually learn who usually gets things right more often than not, so they're the people to listen to.
.
Newriver Reit (LON:NRR)
Share price: 70.0p (down c.1% today, at 11:09)
No. shares: 306.1m
Market cap: £214.3m
(I'm long, at the time of writing, but have decided to sell - see below)
When covid struck, I scoured the sector for property REITs which could benefit from the re-opening of retail. There were 2 buying criteria for me;
- Strong balance sheet, with little debt (and loose covenants, long expiry, etc)
- Excessive discount to NTAV, such that even if property values dropped heavily, the shares would still be cheap
The two shares which met my criteria were Hammerson (LON:HMSO) (bought at 56p, since sold at avg. c.120p), and Newriver Reit (LON:NRR) (bought avg. 65p, sold half at about the same level).
The obvious problems with owning retail sites are;
- Tenants not paying rent, due to lockdown
- Tenant insolvencies likely to come thick & fast
- Rents are far too high, and need to come down, thereby reducing landlord's balance sheet valuation of properties & potentially triggering default with lending (that's the risk facing Intu Properties (LON:INTU) at the moment)
However, there's potential for the market to have thrown out the baby with the bathwater, as all retail property REITs have been slammed in price.
From today's results from NRR, all I'm really looking for, is;
- Confirmation that the company's balance sheet is still rock solid, with plenty of liquidity & no danger of breaching banking covenants. From my initial skim, this does indeed seem to be the case, and
- The discount to NTAV, even after anticipating further property write-downs, is still attractive
- What's going to happen with divis, and how do REITs retain their tax status if they're not complying with the requirement to pay out at least 90% of profits as dividends?
Liquidity - this sounds fine;
At 31 March 2020 we had £177 million of cash and credit facilities available to the Company which, together with our unencumbered balance sheet, gives us confidence in our ability to remain cash positive and debt covenant compliant even in a scenario of very significant cashflow disruption and valuation decline.
That's good, and isn't a surprise. The reason I bought this share, is because I'd checked out the balance sheet, and borrowing arrangement, and found them to be comfortable. Hence there's never really been any doubt that NRR should sail through this crisis without any risk to solvency, even in the event tenants were very slow in paying rents, and likely tenant insolvencies too.
A couple of other good features of NewRiver;
- Its retail tenants are focused on value retail, and quite a few were supermarkets, hence over one third remained open throughout covid.
- Its pubs portfolio valuation is underpinned by alternative use value - hence even if many tenants don't re-open, the pubs can be converted into residential, and hence keep most or all, of their book value (after a time lag to get planning consent, and convert them). The company has a history of being very active in developing its properties.
- Limited exposure to department stores, mid-market fashion, and casual dining.
Anyway, on to the results;
EPRA NAV - the key measure of net assets, at 201p per share. This is down 23% on prior year, a heavy reduction. I think we have to assume that NAV is likely to continue falling, as some tenants go bust, and empty units have to be re-let at lower rents. The current share price is only 70p, a huge discount to NAV. Therefore the market is anticipating a large further fall in property values, which might be overdone possibly?
Loan to value - another key measure for property companies. This has risen, because asset values have been reduced, and is now 47% at 31 March 2020, up from 37% prior year. Not in dangerous territory yet, but my concern here is that reduced property valuations in a downturn tend to lag behind reality. Therefore, LTV is likely to go above 50% this year I imagine, which would start to be a concern. The company mentions disposals, but what sort of valuation could be achieved in the current environment? It wants to get LTV below 40% through disposals. That's looking an uphill task, given that valuations are likely to take another leg down this year.
My opinion - I've only partially read the results statement. My initial feeling is that it looks solvent, with no worries about liquidity/cashflow. However, the increased LTV has spooked me a bit, so I've decided to step back onto the sidelines from now, and do some more thorough research/thinking, and buy back in at a later date if I'm satisfied that risk:reward is still favourable. Or not go back in, if I conclude otherwise.
The online results presentation is just about to start, so I'll tune it to that now.
.
NRR results presentation webinar
This was absolutely excellent. Management (CEO & CFO) ran through some presentation slides here. The whole thing came across very well, and management impressed me with their openness & honesty.
Then they did a comprehensive Q&A.
I jotted down the key points, as below, but only for things that are additional to what I've written above;
- Divis - no Q4, nor Q1 divis (Q1 is Apr-June 2020, new financial year). Firm intention to resume divis.
- REIT status - I asked how can they remain a REIT if not paying divis as required? Answer - REIT status is applied for annually. Have 12 months to file tax papers for FY 03/2020. Don't expect any problem with this. Company has "firm intention" to resume divis as soon as possible.
- Low rents - average is only £12.66 per square foot (that's really low, e.g. £12.7k p.a. rent for a 1,000 sq.ft. shop) - so more tenants should survive than at e.g. highly rented shopping centres.
- March quarter -75% of rents either collected, or alternatives agreed (although that is very broad in scope!)
- Pub estate - most have not paid rents, but trend is improving. All expected to open on 4th July.
- Business interruption insurance claim has been lodged.
- Retail portfolio - 60% now open, confident of improving rent collection
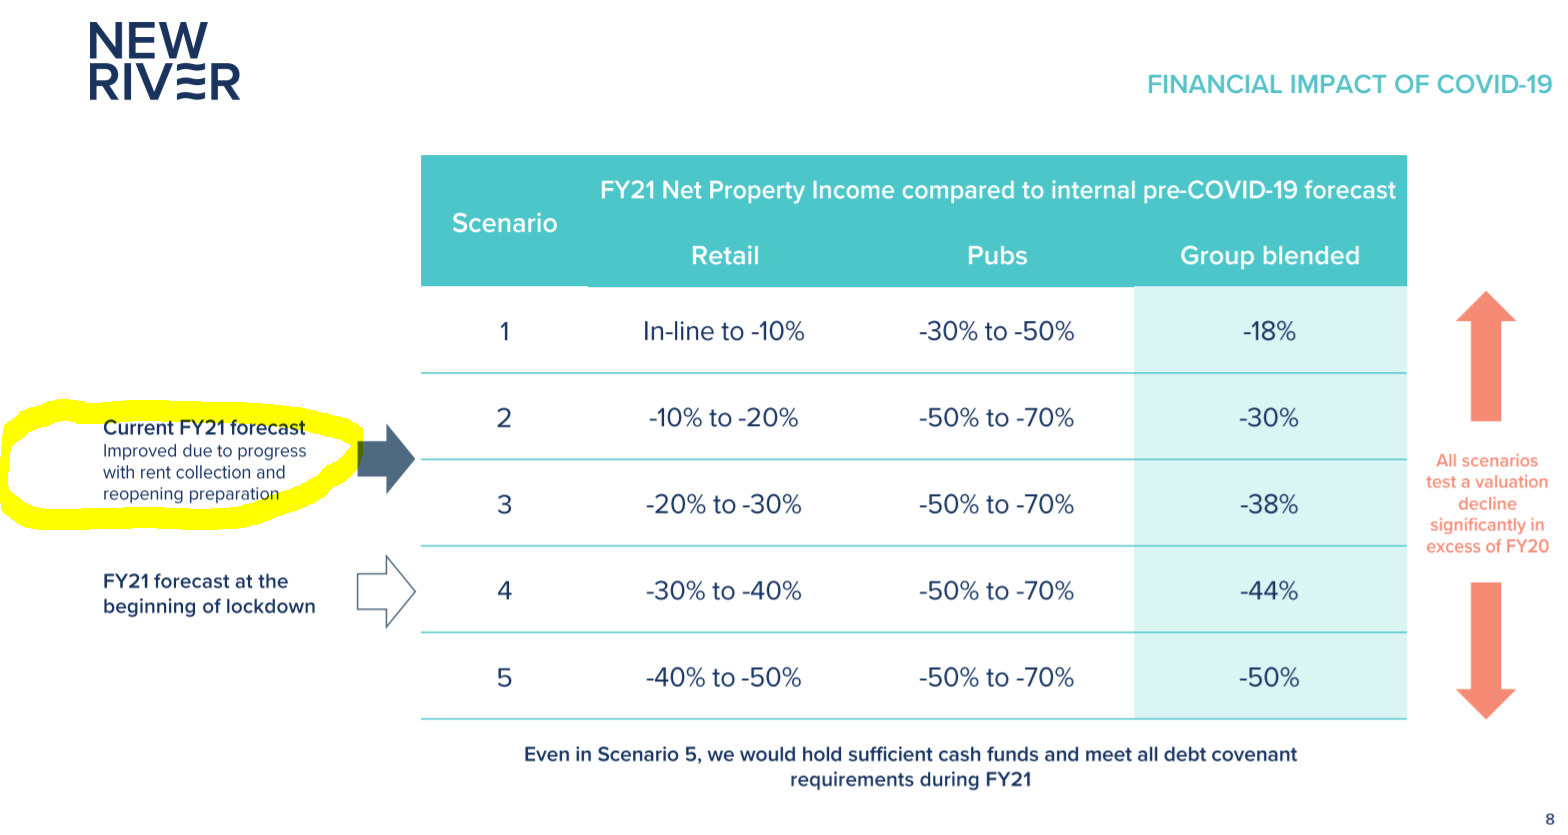
Scenario planning - key point - originally thought NRR would be c. scenario 4. Now think this has improved to somewhere between scenarios 2-3, see this slide;
.
- Refinancing - none until 2023 (and 2028 for bonds) - luckily they refinanced at the perfect time in 2019, with lenient covenants, and all debt is unsecured
- In all the above scenarios, would comply with covenants for FY 03/2021
- Pubs generally have outside space, and are wet-led, which is ideal for social distancing. 75% intend to re-open on 4 July
- Disposals - targeting £80-100m this year. £30m agreed so far. These are generally small, attractive assets, there is still demand from buyers.
- LTV covenant is key one. Set at 60-65%, so 47% level is not close. Would need a 22% further decline in property values, to reach that level - unlikely due to nature of assets - i.e. small, local shopping centres are more resilient, pubs have strong alternative use value. etc
- Great confidence in value of assets
- Created enormous goodwill by assisting tenants - 97% pub tenants say NRR met, or exceeded their expectations for support during covid
- UK pubs sector can bounce back
- Alternative use valuations are overall 12% below book value
Q&A
- Covenants - several questions asked about this. LTV is the key test, as have tons of headroom on others. Ensure we won't breach this, with more disposals. What happens if you do breach it? Have 90-day grace period to fix it. Would do more disposals, and ultimately might need a small placing. Don't expect this to happen.
- Alternative use - retail parks might turn into logistics centres. Also high demand for housing in towns. Pub portfolio - mgt are confident current valuations can be maintained. Shopping centres are the assets most likely to decline further in value. Would have to fall 30% further to trigger LTV covenant breach next year.
- Bonds - Fitch has reaffirmed BBB+ stable outlook
- Non-essential shops re-opening day on Monday this week, footfall was up 69% (remember all the centres were open anyway)
- Recession risk? Our tenants are mainly essential, or value-focused retailers. So should do relatively OK.
Conclusion - I was very impressed with management, who are clearly on the ball, and answered all questions thoroughly & openly. Nothing to hide, was my impression.
It largely addressed my concerns, and I'll probably be buying back into NRR shares shortly. It's often best to sleep on it, before making a decision I find, as presentations are always putting forward the most bullish points.
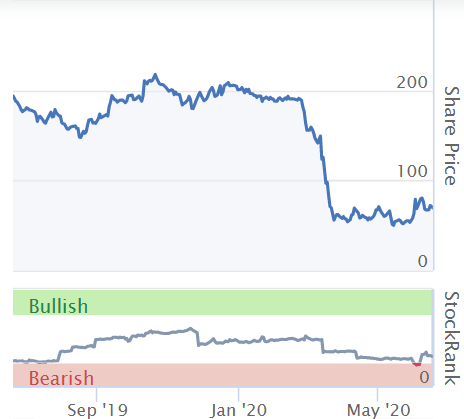
Chart below - there's not been much of a rebound so far, but I doubt the share price would get back to previous levels in full.
.
.
Renold (LON:RNO)
Director buying
I mentioned this one in this Tuesday's SCVR, as a high risk company with speculative upside, given a reassuring update.
Note that this has been followed up with some Director buying y'day and today.
I'll try to take a closer look over the weekend, but thought it worth flagging to readers also, for your own due diligence.
.
Volex (LON:VLX)
Share price: 151p (up 8% today, at 12:08)
No. shares: 151.8m
Market cap: £229.2m
It's so good to see many companies providing proper investor presentations online. I found the one for NRR (above) tremendously useful & informative. It also levels the playing field between institutions & private investors, giving us access to meetings online that previously were difficult or impossible for PIs to attend in person.
Volex is doing an online results presentation through the excellent Investor Meet Company platform. It's at 10:30am on 23 June, Tuesday next week.
I had a quick call with the chaps behind IMC last week, and I'm fully supportive of their plans to open up communications from companies to investors. It builds on the excellent work that others are doing, such as Tamzin & Tim at PIWorld, whose podcasts & videos are superb. Last night I listened to a 1 hour podcast from Idox (LON:IDOX) whilst going for a brisk constitutional along the seafront. I actually prefer audio to video content, as I can then multi-task whilst exercising, or cleaning, or whatever.
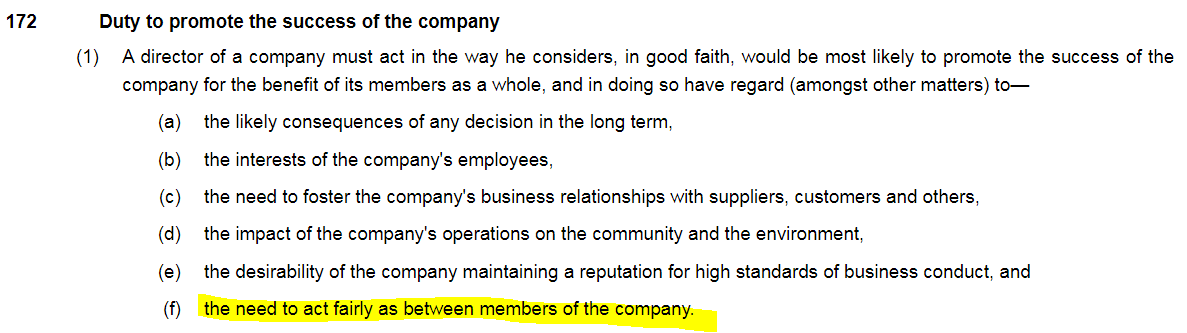
Well done to all companies & advisers who go down this route of giving presentations to the wider shareholder base, and other investors who might be interested in the company. To all other companies that are not giving online results presentations, why not? Surely by only giving presentations to institutions, and excluding other shareholders (members), you are in breach of S.172 of the Companies Act?
.
.
Clearly by doing this online presentation, Volex is honouring its legal obligations to all shareholders, so a hearty whoop whoop to Volex management!
I last looked at Volex here on 16 Apr 2020, and was impressed with its excellent update. Although I was nervous about chasing the price any higher at 138p. It's since continued rising, to 151p today.
To save time, I'll direct you to the N+1 Singer note on Research Tree. Key points;
Modestly ahead of expectations for EPS, at 17.3 US cents (up 36% on prior year - excellent stuff) - that's 13.8p in sterling, so a PER of 10.9 - it looks like I might have got confused by currency in my last report, although I thought I'd adjusted for that at the time. Maybe not.
Dividend - as mentioned last time, paying a 2p final divi sends a strong message that the company is coping well with covid
Net cash - is $31.6m as opposied to $31.7m in last trading update, just a rounding error, not a problem
Outlook - slightly hesitant in parts. Performed well up to May, although "now seeing areas of weakness" in medical equipment installations. Electric vehicles weak in Mar & Apr, but now recovering
Uncertain outlook, so not providing financial guidance for the current year, FY 03/2021.
My opinion - no change. I remain very impressed with the excellent turnaround at Volex, and it has a very good balance sheet too, so is financially secure.
The valuation looks reasonable, although an uncertain outlook is not great - but understandable in the current circumstances.
Overall - I like it - this seems a decent quality company, at a reasonable maybe cheap, valuation.
All done for today.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

89 comments
Looked at the Newriver Reit (LON:NRR) presentation slides, the value of the property portfolio was written down from £1.29Bn in Mar19 to £1.2Bn Mar20 so likely does not reflect the full impact of covid-19. Current market cap implies c. £800M property portfolio valuation at par to NAV and halving of the valuation from Mar20 levels would wipe out all shareholder equity.
I have just joined you and looking at the information on NNR and Volex, it is very good and I am impressed.
Excellent ping pong & information on Newriver Reit (LON:NRR). Its why the SCVR is so good, sometimes i do a lot of research but Paul is a machine and the output & comments generally excellent.
I hold Newriver Reit (LON:NRR) and generally do not double down but this time i will. The UK media & general feeling seems to be that the world has changed, but the world who are ahead of the UK on the C19 journey are showing it hasn't. People are still shopping, eating, drinking, and have not turned into reborn recluses, zoom or no zoom.
Entertainment exists as it does because thats what satisfies society, and has developed over 100s years, it will return to normal, (sorry highly likely too), so for me NNR is too cheap. We’ll see of course.
Paul. Many thanks for the excellent work on NRR today. I hold and have been buying more recently so your report made for encouraging reading. I saw their team at Mello in Derby a couple of years ago and I was impressed then. Things haven't gone their way, but the management is worth backing. I have every confidence that this will recover and once dividends resume, it will provide a very decent dividend at these distressed levels.
Yes, I second the thanks
I've been averaging down on this over the last few months and at the current price I'm am finally near parity. It may not return to pre covid-19 levels, but I'm willing to hold for the future dividends
Thank you for your late additional write up on Wincanton (LON:WIN) yesterday Paul. I think we both agree that the Accounting Standards for Pensions is broken, although I suspect for different reasons!
One of the things that has slightly put me off investing here is the Pension position, although ironically that is because it is too conservative, whist most "head for the hills" at the merest mention of it I suspect.
This could turn into a rather long post, so to keep it brief, the scheme is currently in surplus. It is often thought that reductions in interest rates lead to an increase in a defined benefit pension's scheme liabilities, and often (depending on what happens to the assets) an increase in a deficit. That is only part of the story.
The liabilities aren't actually discounted by interest rates (or Gilt yields) as is often thought. Instead they are discounted using the Corporate Bond Yield curve. Whilst interest rates have fallen due to the Covid-19 "crisis", whether that is policy rate, or Gilt yields, it is actually the case that Corporate Bond yields are relatively higher and as such the liabilities as discounted and valued under IAS19 have fallen.
Unusually this particular scheme is well hedged, with respect to interest rates, with a large percentage of the assets being held in Gilts. As a consequence of Gilts rallying and liabilities falling the scheme (as valued under IAS 19) has turned into a surplus. So we can agree IAS19 is a mockery, but in this instance the company actually is benefiting.
That's not to say you, and others, might prefer to judge the pension cost to the company on an alternative measure, and focus on the annual payments agreed towards "eliminating the deficit" as part of the Triennial Valuation framework. That is a real cash flow "from shareholders to pensioners" and currently (outside of the temporary Covid deferral) at approx. £18m that could otherwise have gone to shareholders as dividends (or at least partly). But that approach is a little like only looking at the P/L account, whilst ignoring the Balance Sheet, of the Pension Scheme, and we all know how important Balance Sheets are to you in terms of Company Analysis.
Anyway, it isn't important who is right or wrong about this, and which approach is correct, only that full analysis should be made as part of anyone's DYOR should they be considering investing here (or indeed elsewhere). What I would note though is that the last Triennial investment, that led to the annual £18m payment agreement between the company and its Pension Scheme, took place in Mar 2017, when a deficit on the scheme was valued that required "sorting out". Perhaps it will be fortunate for the company that the new Triennial valuation will be at March 2020, specifically when the scheme is benefiting from that positive movement in the credit spread trade (Assets long Gilts, Liabilities short Credit/Corporate Bonds).
As Covid passes, and that spread unwinds, the scheme will give back its "valuation gains", but the company might find itself in a position where because of the disappearance of the deficit at the time of its latest Triennial Valuation, it might have a lower obligation than the current annual £18m, freeing up cash flows for other purposes, be that investment, debt reduction, or indeed increased dividends.
Some prodigious output this week Paul, and I'm not just talking about your Jag's exhaust emissions.
Very helpful commentary on, among others, NRR. I have to say I'm finding it very hard to assess the merits of shares like this in today's environment. There are so many more moving parts and far less visibility than normal. I'm in 2 minds on this one, but your commentary greatly increases my chances of making an informed choice. Thanks.
INDIVIOR - Can anyone throw any light on developments at £INDV. On Monday this week they posted an announcement that a new investor called Kainos Opportunities Litigation Fund had acquired 5.13% holding. Just wondering if anything of significance is going on here...and who are they...?
Help me out here, please:-
Taylor Wimpey (LON:TW.)
https://www.stockopedia.com/share-prices/taylor-wimpey-LON:TW./news/ukaposs-taylor-wimpey-raises-522-mln-pounds-in-upsized-share-sale-urn:newsml:reuters.com:20200618:nL4N2DV1W2/
This is effectively a dilution of existing shareholders?
How bad is it?
It's an 11% increase in share capital but given it was done at 145p versus a price at the night before of 150p then it's not really dilutive. There is now an additional £500m of cash that they intend to spend on land where they see some attractive returns that were not available pre-covid. On the assumption that this is as lucrative as management seem to think then it's probably medium term positive for earnings and NAV in my view.
Thank you, David. Very good.
Taylor Wimpey (LON:TW.) now 138.9 to 140.9 and so its about 7% down.
As you say, reading the brief, The Management are topping up their land bank whilst the opportunity presents itself.
(I sold out my TW at 151 about a month ago to buy International Personal Finance (LON:IPF). but still hold Persimmon (LON:PSN) and Redrow (LON:RDW), and will buy in to TW again when I have the spare cash and see the share price looking cheap.)
UK. RE TW.Have you read the business update from June 5th. The strategy is pretty comprehensive and even mentions possible land acquisitions. Workers all back from furlough. Pre booked viewings full. The market seems to have decided to take the placing off the sp. I think the lesson I am discovering is dont bother participating in placings because the opportunity will arise to buy cheaper in the majority of cases, as I have gratefully been doing this morning and on other such occasions. Return of dividend next year economy permitting
Re TW
I was slightly incredulous about their bullish trading statement.
They could end up with a lot of stock, and, pardon the pun, no home for it to go to.
If there is a severe recession, my business partner (former Builder Regional F.D.) says the builders' asset value will drop.
Reality check: there isn't going to be housing bullrun and surge in the short term with so much of the economy wrecked by The Government's hysterical ill-considered overreaction to the flu bug.
I agree - I think there will be a surge in sales over the next month or so, (with estate agents closed over the last 3 months and backlog of houses waiting to go on the market). This may feel like the sector is "back to normal" or even better, but with many payoffs and uncertainty ahead, I'm not sure many people will be moving homes in the next 12 months - unless the government applies discounts to stamp duty, (although reducing taxes might not be on their agenda right now.)
Your concerns about NRR are misplaced. The covennat for the LTV is 60%. The managements said that the value of the entoire estate woudl have to fall 22% for the covenenat to be breached. They broke the estate fown into three pieces, retail parks, pubs and shopping centres. Retail parks are proving to be more resilient ias they can be driven to, used for logistics purpose and pick up of click and collect ordes (The US Big Box retailers like Home Depot showed similar characteristrics in 1Q results). Pubs are not only resilient but attractive assets (New River managed to sell six pubs post March, EBITDA in pubs had increased 5.9% before Covid struck, 70% of NRR pubs have outdoor facilities, overseas buying interest in pubs). So, the shopping centreas would have to fall in value a lot more, like 30%, to get to the 22% aggregate that breaches the covenant.
NRR LTV covenant is tested twice a year based on half year and full year results. NRR do not see a fall in value of teh scale that would breach covenants for the September date.
The LTV is being managed , paying down debt with assewt disposals. NRR@s properties are unsecured. this gives them a lot of flexibility. Fitch has confirmed the investment grade rating as of 1st April.
My view is things can only better. from here unless we get a huge second wave and are forced to lockdown.
Please read the report before putting a sell recommendation on this.
ValueWise
That seems far too harsh a judgement on Paul’s superb and detailed update on NRR today, and also too dogmatic. It’s a matter of opinion whether or not Paul’s concerns are misplaced and not a fact.
Also Paul does not tip shares, so did not “put a sell recommendation” on NRR. Telling readers he has sold is not a sell recommendation. Paul knows there are a lot of sophisticated investors reading his reports and contributing to the comments section who are able to make up their own minds on whether to buy, sell or hold.
And I thought his detailed write up on NRR and the analysis added after the results webinar, was superb. I like reading his initial thoughts too ahead of further analysis later. Sometimes those brief comments before he has had time to check in detail, can flag up a share well worth checking out.
Hi Ken
Do you hold these shares?
Yes Terry. I hold NRR. Sold the lot a good while ago and bought some back during the market rout. I had decided to wait for their update for whether or not to hold on or buy more. Going to stick with the smaller stake for now, but would be tempted to add more lower, or on clearer signs retail and pubs are returning to nearer normal.
He obviously didn't see & read the section about the NRR webinar, where I addressed all his points!
It's quite funny when someone fires off a reaction telling me to read the report properly, when he hasn't actually read my report properly! What a plonker!
The world is full of plonkers !
Ironic, coming from someone posting the same message twice.
I am bemused at your comment ValueWise. Paul said he was thinking of buying back in post the management call. He didn't put a sell recommendation on it, he merely stated that he sold his stock this morning on the results out of some nervousness but would attend the presentation which he did (as did I) and subsequently revised his opinion. I thought that was very fair and open.
Try reading my report again, properly this time, and you will see that I covered all the points you mention.
I don't put out any recommendations on any shares.
The world is full of plonkers !
"Please read the report before putting a sell recommendation on this".
I think we are all too polite on here sometimes. Read the NRR report? What do you think Paul does all day? How many hours do you think he spends on these reports? Ten minutes? I own NRR and it has fallen today. Possibly because the income funds are selling as they are also passing the dividend for the first quarter of 2021. But that is not the point. We all have our views on stocks we own and we may agree or disagree with Paul and Graham. Don't take it personally and kindly have some respect!
BoE has added £100B to QE
I think Private Equity (PE) may go after vulnerable Companies, but usually they will be after cash generative businesses with upside. I don't think Best Of The Best (LON:BOTB) is vulnerable, but sometimes owners feel it is time to step off the business escalator, or perhaps more to the point may not always feel they are the best people to drive the business onto the next level. PE is good at developing business plans, and bringing new people in. They are not always successful, but it is a law of averages.
They will pay well for a good opportunity, but they have investment committees that they have to satisfy, so would have to pass their judgement on the terms, so it is generally not just a punt. They may have businesses in their stable that may make a good match for a future onward sale or combining.
But they are not always experts ina particular filed and can be prone to fashionitis, as much as other investors, and I know one business bought by PE which was definitely overpaid, so they don't always get it right. They can get blinded by looking at cashflow/profit as proof of the strength of the business, but this can sometimes disguise underlying systemic issues, which they are not familiar enough with to recognise.
I have taken a small punt on Best Of The Best (LON:BOTB). Frankly I have a 50/50 experience (and I may be overstretching the success level!) of this ever paying off in these sort of scenarios.
It's an interesting situation and will be good to see how it plays out.
Personally I think they'll be bought out for a good premium. When you look at the growth & scalability of BOTB I don't think it's hard to see why it would attract some serious bids.
hi Ben, what sort of figure could you think BOTB could command?
Noting your comments on DLAR I followed you into BEG at around 36p. Great yield (at that price) counter-cyclical and a well run company respected by the market. Felt obliged to top slice a few but still holding the majority.
Blimey, when were Begbies Traynor shares 36p? I must have blinked and missed that!
Begbies Traynor (LON:BEG) could be had for below 30p as recently as 2013.
I bought on 3 separate occasions below 30p between 2011 and 2012, plus various other purchases at higher prices. Still holding, considering the attraction of it's counter cyclical characteristics.
Card Factory (LON:CARD)
I’m toying with the idea of doubling down on it for a breakout. Any comments?
I always like to have two separate apporaches supporting the same conclusion before i double down - so i would reecommend finding a nice shiny 2p coin and flipping it in the air - if it comes down heads that would back up your assertion and therefore go for it. If it lands tails that suggests the alignment of the tea leaves may be wrong (unless thats something to do with the current weakening of magnetic fields)- and that you should proceed with caution - lets hope its not a case of tales you lose and heads your opponent wins.
Going back to fundamentals i see the temptation here - however the debt is very high so there is nothing really to stop the shareprice trending down closer to zilch than it is now quickly if there is doubts that company may have enough cash to see it through the current issues - i am planted firmly on the sidelines at present despite having been tempted by the fact the shareprice is something like only 3 * historical peak earnings. Long term If we say earnings could bounce back to £40 mill and debt ends up at £200 mill (excluding leases) - thats 5 years of decent earnings needed to clear that burden completely.
The debt pile is pretty much what's stopped me buying in! They're Balance sheet is a right mess. Looking at the chart it does look like it could potentially break out though as you say so may be a decent trading opp.
I played a blinder here, bought high and sold low on Card Factory (LON:CARD) so missed the recent bounce.
There are obvious attractions to the company, it was profitable though dropped last year up to Christmas which started the rout.
The one on our little high street always seems busy when I have been in, I love the 10 for £1 offers a great way to cover kids birthdays and just have a few random cards in the draw for emergencies. Staff friendly and seem to be happy that they make a profit as a shop,
My one complaint (having bought for income and sold due to no obvious future income) was the fact they could have still paid a good dividend back in the day (say ~5%) all be it slightly reduced and be continuing the expansion and reducing debt at the same time...who knows what the management bonus KPIs were based on, but obviously involved high gearing!
Good morning,
I wonder if somebody can help me with a query I have concerning Duke Royalty (LON:DUKE), a company that Graham has written quite extensively about in these SCVRs. Yesterday it announced a dividend of 0.5p that will be paid in the form of a scrip only, with no option to elect cash:
https://www.investegate.co.uk/...
I am wracking my brain as to what the point is of this as surely every shareholder gets diluted by the same amount with no benefit to anybody and an administrative cost to the company. I'm sure there must be an explanation but I can't think of what it might be. Can anybody enlighten me at all please?
Many thanks,
Gostevie
Gostevie,
The main benefit of scrip dividends for companies is that there's no cash outflow. Shareholders who want the cash income can sell their new shares into the market.
I don't follow Duke Royalty (LON:DUKE) in detail but I believe some of their investments are in the travel/hospitality sector. So I guess they're trying to preserve cash at the moment.
Regards,
Roland
If a company pays a scrip dividend, the shareholders own the same percentage of the company as previously and the company has the same amount of cash as previously.
So there's no benefit at all in paying a scrip dividend. Any shareholder requiring cash can sell a proportion of the original holding.
Worse still, I believe scrip dividends are taxable, so anyone who holds the stock in a taxed account might have a tax bill.
Gostevie,
I think the benefit is that it keeps their dividend payment record intact. In a few years time, they will be able to claim that Duke Royalty (LON:DUKE) has paid a dividend every quarter since year [x]. No one will remember that at least one of those dividends was not "paid" at all, but was just an exercise in financial engineering.
Another company doing the same thing - issuing bonus shares is £RQIH announced earlier this month. .....
Another company doing the same thing - issuing bonus shares is Randall & Quilter Investment Holdings (LON:RQIH) announced earlier this month. .....
Yes, and very annoying it was as well especially as there was no explanation. Other than maintaining the fiction of an unbroken income stream it doesn't actually make any difference.
However, given that both Randall and Quilter still retain significant shareholdings my guess is that they see acquisition opportunities as a better home for their cash. Which makes sense given they raised £100m from the markets in March - why raise cash on one hand and then give it back to shareholders on the other? Companies that do that are a perpetual source of annoyance.
timarr
I'm not sure as to who I should reply to here but you will do ,Gostevie. Scrip dividends, bouus shares, there must be difference between the. Today Vistry (LON:VTY) announced it would make a bonus share award in lieu of a dividend in August and I'm hoping this is not a dilution.
William
Silver Moon this will be a dilution for people like myself who held Galliford Try Holdings (LON:GFRD) which then sold the Linden Homes business to Bovis who became Vistry (LON:VTY). The dividend you refer to was promised to Bovis shareholders who held shares before the acquisition. So the pre-acquisition shareholders get more shares and people like myself who became VTY holders due to the acquisition don't qualify.
The benefits for companies and why they provide scrip dividend with or with out an option to take cash has benefits for share holders as well as for the company. Accepting shares instead of cash dividends I have found a great way to save particularly in an ISA, since they became available. The current tax situation is quite simple.
I have used the interactive investor platform since 2011. Any profit in my trading account less expenses and losses attracts either Income Tax or CGT. There is no tax liability on ISA profits (YET) but neither are there any Tax reliefs. (Unless I have missed something)
£NRR thanks Paul, I got out of this share this week, as have been looking at their estate in more detail. They have a good pub division that will bounce back, they also have a development arm that will do fine too, however the biggest concern for me is the shopping centre arm, these shopping centres are not the prime shopping centres but the secondary stuff that I think will really struggle. The likes of Hammerson/ Land Sec / Intu have prime shopping centres and will have some leverage against CVA's / admin, where retailers will want to remain in those centres, the NRR centres will probably be more severely impacted with voids coming out of this.
Having just been on the Management and analysts call they would contend the opposite to your thinking JSLDUK. What appears to be happening is that local centres are performing better than prime. Also the point was made that the size of their assets means they can divest of them relatively easily whereas £500m type property sales are very difficult to achieve. Most of their tenants are health & supermarket type essentials too so far less voids than you are thinking.
One key takeaway for me is that they focus a lot on Alternative Use Asset pricing. ie if they closed everything down and repositioned the assets into residential tomorrow what would the NAV impact be. It's only 12% lower than existing NAV (so around 180p).
Thanks David, I wasn't on the call but good to know. Agree their centres will probably be propped up by supermarkets who never stopped trading + all their tenants will benefit from buiness rates holidays too, so hopefully they stand up well. I just still feel the strong centres will survive and thrive and the not so prime may find it harder, although again take your point that selling a small shopping centre in a small town will be easier than selling say Lakeside. I do however agree with the sentiment that retail will survive and some UK property REITs look very good value. I've brought in to Hammerson and Secure Income REIT. As feel both will come out the otherside well. But may kick myself for selling NRR too.
I think they made points like a lot of their customers walk to the shopping centres twice a week and know which shops they are going to use. Therefore footfall holds up better as no need to use public transport etc. They were up 67% week on week I think. The analysis seems to point to more local shopping and community in the immediate aftermath of covid lockdowns hence their pub estate, shopping centres etc should fare ok given they are very community focused. This theme came up a lot on the call.
I did buy Newriver Reit (LON:NRR) slightly higher than this as I think NAV will be under-pinned by alternative use valuations (180p) so I'd like to think 150p is reasonable value at a 20% discount to that. Management though seemed cautiously optimistic that current NAVs will go up rather than down, which was interesting. Pubs with gardens are opening soon and I suspect will be busy quickly as everyone is a bit stir crazy at home. That accounts for 70% of their pub portfolio.
LTV was fine for me. They want to reduce it back below 40% and have earmarked sales of £100m. There was debate on the call about how likely that was in the current environment but management pointed out they had already agreed £30m of sales at premiums (I think if memory serves correct) to EPRA NAV valuations.
Looks like divis will be reintroduced in Q2 so I've stuck mine in the ISA with a view to sell around the 150p mark or hold medium term for the income.
Paul & others - one thing I was trying to work out yesterday re £BOTB is whether this reference in their "for sale" announcement was unusual: ''any interested party participating in the process will not be required to be publicly identified as a result of this announcement". Should I be reading anything into this or is it standard practice? I'm completely naive on how these situations usually work.
Unusual in what way?
Imo they were just updating the market that they have been approached by 3rd parties in relation to selling the business.
I don’t think that’s unusual unless I’m missing something?
The bit of the RNS I was querying was 'The Takeover Panel has granted a dispensation from the requirements of Rules 2.4(a), 2.4(b) and 2.6(a) of the Code such that any interested party participating in the process will not be required to be publicly identified as a result of this announcement'
Is it more usual than unusual for the Takeover Panel to grant this dispensation in these situations?
This answers your question on the dispensation. My reading is that this is not normal but also not unusual
https://www.thetakeoverpanel.org.uk/wp-content/uploads/2008/11/PDF-of-Practice-Statement-No.31.pdf?_sm_au_=iVVcNMb9PNtMt0Kn
Re Best Of The Best (LON:BOTB) , William Hill (LON:WMH) and BetFred have been suggested as interested parties. My review of their financial position suggests that they would both struggle to raise the £185m that might be required.
I am guessing that it is PE that has either shown an interest or been approached. That might not result in an overly-generous offer. Considering that William and his wife would be looking at a payout of approximately £88m and Rupert of £28m at a take-out of £20, I don't think that they would be too fussed about holding out for any more.
If finnCap's 2021 forecast eps was designed to elicit an offer and is the best case scenario then £20 would be attractive. If it is the base case scenario and there were to be further upgrades as the year progresses (there have been at least 8 upgrades over the last four years), then eps of £1 may well be achievable and £20 doesn't look quite so generous. They would need to do revenues of about £35m to achieve that against finnCap's estimate of £28m.
The question is how much this could grow with overseas expansion. Non-UK revenues were only £2.8m out of a total of £17.8m last year. I have no idea whether this can grow substantially but my question would be why not?
One look at the accounts shows what a simple business this is. Some have inferred from the simplicity of the business that there is, consequently, no moat. I do find it extraordinary that something that is just a re-hash of all those competitions that ran in newspapers when I was younger could be talked about as being worth up to £200m. But I think that this represents the wholly justified premium for fantastic execution. The fact that we are talking about such a premium indicates to me that the moat is wider than it appears. Competitors do exist but William and Rupert have actually made this desirable by very clever marketing while also seeming to be that rare breed on AIM - reasonably trustworthy.
I think it may be hard to get PE to pay what this is worth so it may drag on. I am interested in others' opinions.
Disclosure: I am long from 280p
Good comments Mammyoko.
I wonder if someone like Bet 365 or similar may be sniffing around rather than PE? Would be a good bolt on acquisition for someone like 365.
or even Betway, who already have a gateway to their online gambling & casino on the BOTB website
Best Of The Best (LON:BOTB).From the current price, it would appear to my untutored eye that Mr Market either does not expect a sale to go through or that it would be at a significantly lower price than £20. Even at this distance would not a current price of £13 look skinny ?
In from £3.03 - and therefore generally excited !
Don't think the market has ever really had a clue about how to value Best Of The Best (LON:BOTB) - hence the recent upwards lurch in price on low volume. Given the small free float the instis have not been playing here and only the house broker covers it. So price discovery seems mostly about PI supply and demand.
For once, I think holders are in a that fortunate position where there is limited two-way business - it feels like this will be all one way provided the company continues to deliver. If someone wants to buy it, good - provided it's at a good price. The only risk is that William and Rupert sell it too cheaply because what's the odd £10 million on the price when you're sitting on tens of millions already? But given that this is now a pure online play and that growth looks to be accelerating, the only reason I can see for them cashing in is that they don't feel that they are capable of taking the business forwards. I can't see why they would think that sitting on a yacht in Monaco would be preferable to taking their baby on the next stage of its journey, though. William is a self-confessed petrol-head so seems to be in the perfect job.
Given that these shares are very tightly held and that all the indications are that the business is poised to grow rapidly I can see no reason for anyone to sell. How many other companies with similar growth potential and financial strength are there out there at the moment?
sorry, who is/ are PE?
Typically, and I believe in this case, a shortening of Private Equity.
Bidders probably just want to stay anonymous. No issue with that Imo.
Anyhow will be interesting to see how it all plays out.
Hi Paul would be interested in you thoughts on Volex results, note they are also using investor meet the company platform for presentation.
Hi Paul, can you (or anyone here!) comment on Alpha Real Trust (LON:ARTL), with Antler having gone over 30% as announced yesterday post-close and therefore presumably obliged to make an offer?
Many thanks in advance
Interesting write-up in Shares Magazine re Best Of The Best (LON:BOTB) today - then right underneath is a piece regarding PE sitting on a boatload of cash. Prophetic?
I'm still long.
Do you have the link? (If allowed on here!)
Is Blue Prism (LON:PRSM) worth a comment following H1 results?
Hi Gerard88
I don't own Blue Prism (LON:PRSM), and probably never will. But the numbers are quite eye-catching.
Half year revenue 68.2 million
Half year operating cash outflow 31.2 million
Half year cash outflow per customer £16,000
I am guessing revenue is all SAAS, with low up-front charges for implementation. In the nature of this sort of software, there is quite a lot of work to implement for each customer, which software companies used to charge for at the time the work was done. So the investment case is that those future SAAS revenues are large enough and robust enough to pay for the money being spent now?
Lots of emphasis on sales growth with Blue Prism (LON:PRSM) interim results but very little about profitability. No surprise given the 'eye-watering' losses this business continues to report and despite a significant pull back in the share price it still has a Market Cap in excess of £1 billion. The investors who put up the extra £100m must really believe that the business will be a winner long term. From reading this weeks Economist's Technology Quarterly the hype seems to be going out of the Artificial Intelligence bandwagon with specific reference to problems of implementation in many organisations. Unless the Blue Prism (LON:PRSM) platform is really something special and can resolve these issues will it ever achieve profitability?
Another vote for VLX please Paul.
As pointed out by others good figures from Volex (LON:VLX) , especially cash flow. I am not so happy about share based payments of $8.7m leaving operating profit of $17.1m and conveniently omitted from "underlying" figures.
Full marks to the company for discussing the results with PIs on the Investor Meet Company platform on 23 June.
Tough results out from NRR today; I'm a holder, down nearly 80%. Daft. Serves me right for not selling.
But; they feel like survivors to me, albeit badly wounded. It all depends upon whether semi-normal life can resume. Biggest issue for me is the LTV. As property values fall, the LTV rises. Pub values must be way down, as in previous big recessions. I think NRR will have to ride out a high LTV.
In my view these shares are good value at this price. I went to my local high street yesterday; it was deserted (no cafes and no loos). Then went to Homebase; had to give up the queue was too long, and the same with the local garage and convenience store. Conclusion; small edge of town developments with space and parking should survive. People want to shop there.
On the pub front I'm much more concerned. Surviving the winter is going to take real skill.
No divi until Covid becomes manageable, I think. I expect any vaccine to be a) late and b) partially effective. Best possibility is for everyone to get an asymptomatic infection.
The Buy High, hold until Low and then decide WTF to do is always hard. Thinking of my expertise with £CARD and Reach (LON:RCH) in the last 12 months with Card Factory (LON:CARD) up nearly 60% since I sold out.
As you say with Newriver Reit (LON:NRR) there are some really good assets backing up the business but the question of what happens with the pubs is a big one here, yes they can always be converted to residential but that takes a long time to get the local authority to re-categorize the usage and £££ and each one is likely to be a local developer so lots and lots of deals rather than just selling out a big chunk of the portfolio for a decent profit.
If you have time to muse on the house building sector I would be interested in your views on the Taylor Wimpey (LON:TW.) placing.
Does have me asking the question of what happened to the £0.5 billion of net cash at 31/12/19.
Phil
(No position)
Are Taylor Wimpey (LON:TW.) doing an offer through Primary Bid too?
Yes, they made 5m shares available through Primary Bid. It was announced and closed last night.
For UK Housebuilders including Taylor Wimpey the business model usually requires the continuous replenishment of the land bank. Where a housebuilder has purchased but not yet paid for land, this appears in liabilities as 'land creditors'
Taylor Wimpey ended 2019 with:
These numbers almost exactly balance out, explaining why Taylor Wimpey now needs new capital to purchase more land.
Taylor Wimpey (LON:TW.)
Hi
"These numbers almost exactly balance out, explaining why Taylor Wimpey now needs new capital to purchase more land."
Sort of my point - cash balances disclosed by house builders are largely illusionary. When the tide goes out........
It does, however, leave the point that they are using equity to by stock-in-trade which normally would be funded via the debt markets IMO. Implication is that risk capital was needed because what they are doing is risky.
Not saying this is bad - think £BKG (Berkeley Group) did something similar in 2008 (although can't remember if their buying of land in London involved an equity raise) which proved very profitable.
Phil
morning Paul. Volex posted some good results. Your thoughts. Operative profit increased by 46.3%
A reminder for the piworld Thursday webinar today 18.6.20 at 1pm. When, ex-Bond Trader, Paul Hawkins will be giving us the key criteria to assess, to invest in Corporate Bonds, titled: Everything you wanted to know about Corporate Bonds. I've had a sneak preview of content, and it's superb. Register here.
Next Thursday, instead of the usual educational webinar, we will have a results presentation by the CEO & CFO at Codemasters Group (LON:CDM), with Q&A. A great opportunity to hear what's going on in the Video Games Sector, and specifically at CDM. Register for one or both webinars here.
Hi Paul. Any chance of hearing your thoughts on £VLX’s full year results?
My morning smallcap tweet: Sales earthquake hits Tremor.
Avacta (LON:AVCT) Quadrise Fuels International (LON:QFI) Wincanton (LON:WIN) Tremor International (LON:TRMR) Michelmersh Brick Holdings (LON:MBH) Novacyt SA (LON:NCYT) Access Intelligence (LON:ACC) TP (LON:TPG) Corero Network Security (LON:CNS)
Avacta (AVCT) initial test shows co's Affimer reagents prevent a SARS-COV-2 model virus from entering human cells and therefore provide a potential therapy for COVID-19. In vitro test I assume.
Quadrise Fuels International (QFI) some progress on agreements for a commercial trial of MSAR at a US test plant to process up to 500 barrels of heavy crude oil per day.
Wincanton (WIN) wins contract to manage Morrisons transport and VMU operations in Bridgwater. 250 staff will be transferred. No £££.
Tremor (TRMR) trading has been severely impacted with clients cutting advertising budgets across all platforms. Guides H1 rev c. 28% lower than expected with adj EBITDA loss of c. $3-6m. "Whilst we are seeing month by month recovery, the ultimate impact of the COVID-19 pandemic on the global economy and Tremor remains uncertain, and therefore the Company is not giving FY guidance." Will accelerate share buyback.
Michelmersh Brick (MBH) rev year to May 25% down. Plants now fully operating.
Novacyt (NCYT) launches 3 products to support labs testing for covid: two RNA extraction kits and COVID-HT, a new test optimised for use in labs performing high volumes of tests.
Access Intelligence (ACC) guides H1 rev(May) up 50%. However co's "ability to generate new business in line with our original 2020 expectations remains unclear."
TP Group (TPG) €18m orders under framework contract with the European Space Agency, delivery to end 2022.
Corero Network Security (CNS) over $1.5m of new customer wins.
Corero Network Security (LON:CNS) - over $1.5m of new customer wins.
History
Selling partner increases stake to 10% in Dec 2019
19/12/2020 - $1.8 million of customer order secured
23/2/2020 - $1 million of customer wins
2/4/2020 - $2 million of customer wins
New CEO and FD join
Today - $1.5 million of customer wins
Pros
New contact wins around the world
Sticky customers to a fairly unique product
Future need is increasing
Growing Rev
Cash in the bank
Over 50 Employees
Cons
No new director dealings
Net profit minus
Low assets
Wide Spread
Is it as unique as I think it is?
Crude chart description
November19 - £3 (Floor)
February20 - £6
May20 - £5 (Higher low)
Break £6 and it's a future multi-bagger?
Re Corero Network Security (LON:CNS) - I've looked in the past. The product seems good but its been around for a while and they've struggled to break thro IT departments with it. Why is the time now? Obvs punters are happy to buy anything that mentions cyber security right now so maybe it can get magic dust too...but why does it have a sustained self funding (the dilution!) pathway now?
Corero Network Security (LON:CNS) - With the selling partner Juniper ($6B Mrk Cap) fairly recently increasing their stake, and fresh CEO and FD joining - it might look in hindsight to be the pivot point for takeoff. But if it was so amazing Juniper could have just purchased it all...
So I think there might be something here - I expect to see a lot more contract wins this year as DDoS attacks are only going up and going to be a permanent cost for every internet business in the future. But there must be a reason why Juniper didn't just buy it outright.
Hi Paul
Thanks again Paul for these comments on De La Rue (LON:DLAR). My own view yesterday was that this is a turnaround situation, and these usually work out better than expected, IF the CEO is any good AND there is a decent underlying business there in the first place. But . . . there is a lot to be said for exiting after such a sharp price movement.
Good morning Paul. Thanks for your early bird reports and excellent analysis. After the Boohoo business recently, I was wondering if you have had any thoughts on the prospect of Sosandar possibly being a takeover target?
Thanks.
Would have thought it would be better to wait until they are on their last legs and then buy them.
Whats to stop the £dlar sp dropping to the rights issue price just before or after and being able to buy possibly cheaper than 110p