Small Cap Value Report (Thu 18 May 2023) - BLV, STB, SDY, CTG, SRT, WRKS, MBH, SAG, IQE

Good morning from Paul and Roland!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
Agenda - lots to look at today, we'll do our best!
Summaries
Secure Trust Bank (LON:STB) unch at 634p (£121m) - Q1 trading update - Roland - AMBER
A solid first quarter update from this specialist lender, with net lending topping £3bn for the first time. The shares’ 65% discount to book value and high yield look tempting, but I think this bank could be riskier than it might seem at first glance.
Belvoir (LON:BLV) Up 1% to 205p (£77m) - AGM Trading Update - Paul - GREEN
A reassuring update, saying that FY 12/2023 so far is in line with expectations. Although note that those expectations have been lowered quite a bit in recent months, to reflect subdued property sales. However, lettings are buoyant, balancing things up nicely. Short-term BLV looks priced about right, but looks attractively good value, taking a longer term view.
Works co uk (LON:WRKS) up 10% to £32.9p (£20.3m) - FY trading update, in line - Roland - AMBER
Today’s trading update reports adjusted EBITDA in line with expectations, but my sums suggest margins may have fallen. I’m wary about The Works’ large store estate and slim profitability, but I’m encouraged by progress and can see some value.
Quick Comments
Speedy Hire (LON:SDY)
Up 5.8% to 34.0p (£154m) - completion of investigation - Roland - AMBER
The equipment hire group says that it’s completed an investigation into £20.4m of missing “non-itemised assets” such as scaffolding and fencing. Management has concluded that this loss resulted from problems with financial controls “over a number of years” and was not fraud. No further missing items have been found.
Roland’s view: I’m not sure that incompetence is all that preferable to dishonesty in this case, but it does look like this issue is now resolved. Speedy Hire shares have fallen by 20% since this problem was reported and the stock now yields more than 7%. Is there value here? Perhaps – but last month’s in-line trading update reported some recent “softening of demand”. I don’t see this business as a particularly high quality operator and it carries a fair amount of debt. In my view, Speedy Hire shares are probably fairly priced at current levels.
Christie (LON:CTG)
Down 12% to 133p (£35m) - Trading Statement - Paul - AMBER
The most important division within Christie (commercial property transactions) has experienced delays in lead times, causing a backlog in transactions. Credible-sounding reasons are given. This will push some deals from H1 into H2. An H2 weighting was previously flagged in its FY 12/2022 results & outlook, which I reviewed recently here. Overall expectations for trading in FY 12/2023 are unchanged, but surely that implies that it expects to clear the backlog in H2, which might not happen. So I suspect there is probably a risk that FY 12/2023 forecasts might need to be reduced a bit, perhaps?
Paul’s opinion - if you like the company, then a 12% dip today on something that sounds a temporary hiccup rather than a structural decline, could be an opportunity to top up? I can see some merit in this share, but not quite enough to go positive on it. Hence my view remains AMBER, but it’s not far off GREEN.
SRT Marine Systems (LON:SRT)
Up 19% to 55p (£99m) - $180m contract win - Paul - AMBER
There have been many false dawns in the 18 years this company has been listed on AIM, with an ever-growing pipeline for its coastal surveillance electronics, but only occasional and lumpy actual orders. Hence the financial track record is poor, and repeated fundraises required. However, bulls are having their day today, with a large $180m contract announced, which readers say is with Indonesia, funded with a UK export loan.
We've been discussing it below in the reader comments, with me taking a more cautious view (the upside looks already priced-into the £99m market cap, based on Finncap's forecasts issued this morning), whereas bulls on SRT think there's more upside. I can see merit in both bull and bear points, so my overall view is neutral. Good luck to holders!
Michelmersh Brick Holdings (LON:MBH)
unch at 92p (£88m) - AGM TU, in line - Roland - GREEN
Brick producer Michelmersh operates at the upper end of the market with a number of distinct brands. The company says it’s continued to add to its order book since March, with production volumes remaining in line with expectations. A newly-acquired facility is also performing well. The business is said to remain on-track to meet full-year expectations.
Roland’s view: there are obviously some macro risks here, but Michelmersh is a well-run business with a strong franchise and a decent balance sheet. The shares are down by over 30% from their 2021 peak and trade on nine times forecast earnings. I think Michelmersh looks reasonably priced, on a medium-term view.
Science (LON:SAG)
down 1% to 400p (£181m) - AGM TU, in line - Roland - GREEN
This services and engineering group operates in a range of market sectors. Today’s AGM update confirms that trading so far in 2023 has been in line with expectations. There’s been growth in services but some slowdown in consumer electronics, as excess market inventory is cleared. The integration of former AIM firm TP Group is said to be proceeding well.
Roland’s view: this small-cap benefits from owner management and seems to have a decent record of creating shareholder value. Profitability looks fairly attractive too, with operating margins and ROCE topping 10% since the pandemic. The shares look affordable to me, on 12 times earnings. I think this could be an interesting buy-and-hold stock.
Iqe (LON:IQE)
Down 15% to 20.1p (£163m before fundraise) - Fundraise at 20p - Paul - RED
I remember we caught the bull run in 2017 on this share, doing well on it here. However it’s been downhill ever since, and my harsh comments here on 16/1/23 and 9/3/23 questioned not only the high valuation, but whether it is even a viable business?
A placing has just been announced, 150m new shares (806m existing) to raise £30 before costs.
Paul’s opinion - this seems a really bad business model - it has to spend a lot of capital equipment, but then fails to generate any economic return from the products it makes. So what’s the point? Something pretty fundamental would need to change to convince me that this share is worth anything. Maybe there are new products, or contracts, that sort of thing? Maybe it needs a drastic turnaround & efficiency drive? I can't see any reason to get involved t this stage.
Paul’s Section:
Belvoir (LON:BLV)
204p (pre-market)
Market cap £76m
Belvoir Group PLC (AIM: BLV), a leading UK property franchise and financial services Group, provides the following update on current trading ahead of the Group's Annual General Meeting to be held at 10:00 a.m. today.
A reassuring update -
The Board is pleased to report that trading to date is in line with management's expectations for the year to 31 December 2023.
“Very resilient” performance, despite mini budget & higher interest rates.
High demand for rentals, and new lettings are on 10% higher rents.
8 franchisees have expanded using BLV’s “assisted acquisitions” process.
Franchise fees on lettings up 5% y-on-y.
Franchise fees on sales down only 4%, despite the market being down 15%.
Financial services (mortgage broking, etc) down 12%, but more than offset by TIME acquisition, so overall up 8% (gross profit).
Remortgage activity continuing, despite fall in house purchases.
“A degree of stability has returned to the mortgage market”
Outlook -
…there are signs that the fall in demand for property triggered last Autumn might be bottoming out. Mortgage approvals rose in both February and March, and recent indices suggesting that house prices are stabilizing will improve buyer confidence as the market enters its crucial Spring/Summer season.
Acquisitions -
With the Group now in a net cash position, it is well-placed to secure good quality earnings accretive businesses that are complementary to the Group.
Paul’s opinion - I remain keen on this share. It’s priced as a value share, but has actually established an excellent long-term growth track record, self-funded with hardly any dilution, and paying decent divis too.
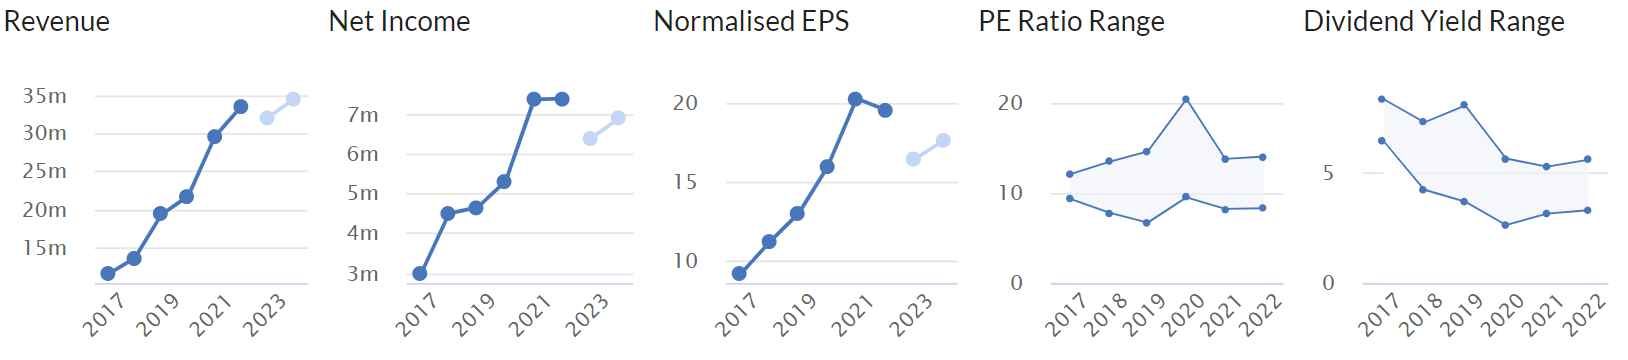
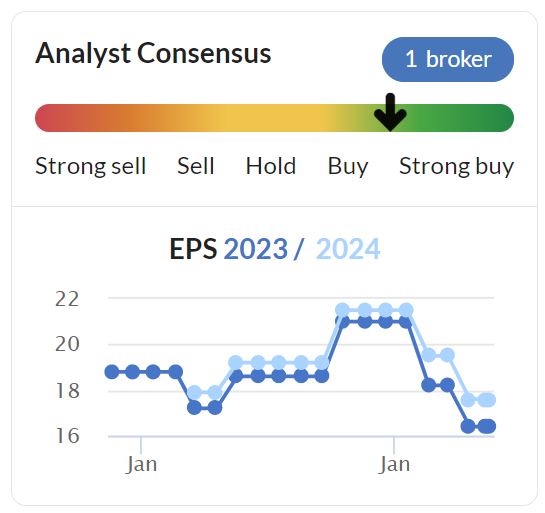
Broker estimates have been cut back a fair bit recently, to reflect current market conditions for housing transactions -
I’m looking forward to discussing the housing market in person with management, who will be attending Mello Chiswick next week.
The forward PER of 12 looks fine to me - maybe priced about right in the short-term, but probably providing an attractive long-term entry point, once earnings begin to rise again, both from an improving market, and from more acquisitions. Hence I maintain my positive, GREEN, view of this share.
Roland’s Section:
Secure Trust Bank (LON:STB)
Share price: 634p
Market cap: £118m
The Group has made a strong start to the year and is trading in line with management expectations
This specialist lender trades at a 65% discount to book value and offers a near-7% dividend yield, making it one of the cheapest banking stocks on the UK market.
Shares in this bank have fallen by around 40% this year as the market has turned cautious on small banks. I’m interested to see if this may have created a buying opportunity for small-cap investors.
Secure Trust Bank collects deposits through consumer savings products and lends them to business customers. Products include mortgages for buy-to-let landlords and consumer finance offerings for retailers (e.g. furniture) and motor retailers (V12 Vehicle Finance).
Thus while Secure Trust appears to be a business lender, it’s actually heavily exposed to consumer spending.
Today’s trading update strikes a reassuring tone, but I think potential investors shouldn’t underestimate the risks in this business.
Let’s take a look at the headlines.
Q1 highlights: Secure Trust has seen a recovery in business lending after a slow patch in the final quarter of last year, with total net lending reaching £3bn for the first time.
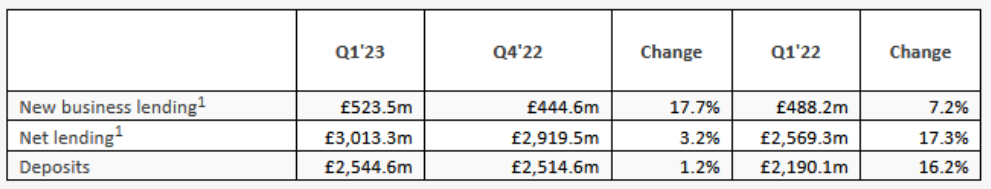
Net new business rose by 7.2% compared to the first quarter of 2022, “despite tightened lending criteria”.
Lending: management says that Secure Trust’s share of the retail finance market rose from 11.4% to 11.9%, suggesting the group has a strong franchise with consumer-facing businesses. However, retail finance lending only rose by 3.5% during the quarter.
This combination of numbers suggests to me that consumer spending may be slowing – gaining 0.5% of market share seems a big gain for a 3.5% increase in lending.
In contrast, Secure Trust’s share of the Vehicle Finance is just 1.1%, but lending in this business rose by 7.3% during the quarter. Clearly people are still buying used cars.
Property lending rose by 4.3% “as the pipeline from Q4’22 converted into new business” – presumably benefiting from more stable mortgage rates.
Funding: the company attracted £343m of new customer deposits in the quarter. Total balances were 1.2% higher than at the end of Q4 ‘22 and 16.2% higher than in Q1 ‘22.
A look at the bank’s website suggests customers can now get savings interest rates between 3.5% and 4.7%. I wonder if the overall cost of funding may have increased from the 1.9% figure reported in the 2022 results.
Capital: Secure Trust also issued £90m of new Tier 2 regulatory capital during the period, at a cost of 13.0%. These replace an earlier £50m security and are intended to increase the group’s lending capacity. The high interest rate reflects market sentiment towards small banks at the moment – and the risk that these securities could be wiped out in the event of a run of losses.
Trading performance/outlook: Chief executive David McCreadie says that “arrears across consumer finance have remained stable at low levels”.
The bank is continuing to make cost savings as planned and expects to report an improved cost:income ratio in 2023 (FY22: 55%).
Although the economic outlook is uncertain, Mr McCreadie remains “confident in delivering on our plans for the full year”.
Roland’s view: Secure Trust shares have value potential, trading at a discount of more than 60% to their last-reported book value. The stock’s near-7% yield is also tempting.
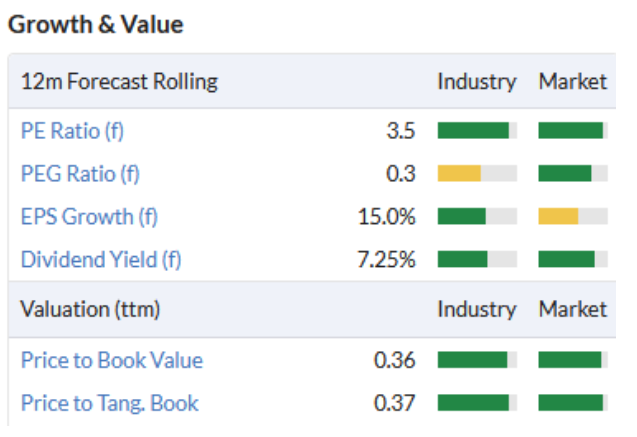
However, small lenders with exposure to property and consumer lending are not without risk at the moment. Secure Trust supports more than £3bn of lending with just over £300m of equity. So a 2.5% bad debt rate (£75m on £3bn) could wipe out a quarter of the bank’s equity value.
I think a sizable discount to book value is justified here, especially as the bank’s net interest margin fell from 6.1% to 5.7% last year. This fall took place during a period when most larger banks were reporting increased net interest margins.
I’d need to do a lot more research to decide if I was comfortable with the risks on STB’s balance sheet.
Finally, I think it’s worth noting that bank investors hunting for bargains can currently buy shares in Barclays (LON:BARC) at a 50% discount to book value with a 6% dividend yield. To me, this seems like a more attractive balance of risk and reward for most investors.
Works co uk (LON:WRKS)
Share price up 10.9% to 33p (09.00)
Market cap: £20m
The Company expects to report an Adjusted EBITDA result for FY23 in line with its compiled estimate of the market's forecast, which is approximately £9.0m.
This value retailer sells stationery, toys, arts and crafts materials and books. Today’s full-year trading update covers the 52 weeks to 30 April 2023 and appears to show a fairly encouraging performance.
The Works has been (yet another) disastrous IPO. But with the pandemic now past and the shares trading on a single-digit P/E with cash on hand, I think it’s possible this business could offer some value. Let’s take a closer look.
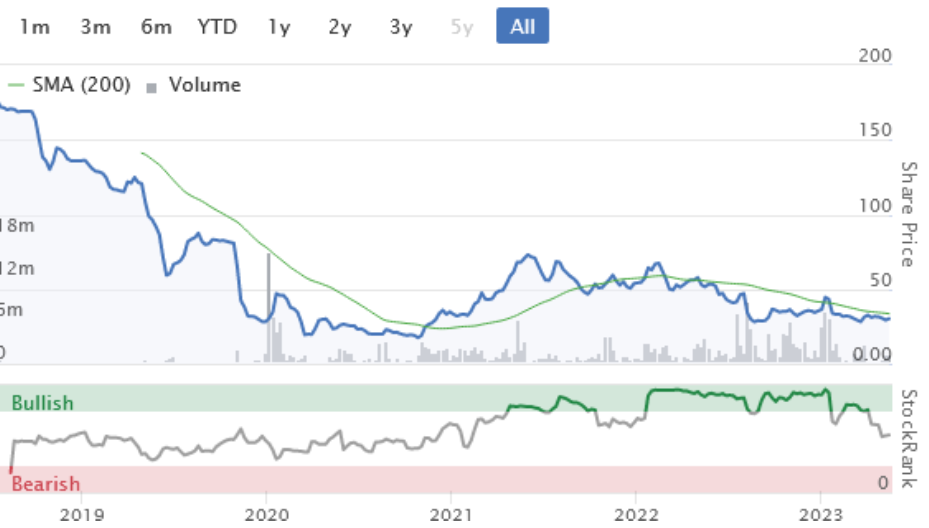
FY highlights: Full-year sales rose by 6.1% to £316.6m last year.
Stores generated 88.8% of sales, with a LFL increase of 7.5%
Online sales fell by 15%
Overall LFL sales growth of 4.2%
The Works revenue performance appears to be significantly ahead of market forecasts for a figure of £271m. But profit margins appear to have suffered – the company expects to report adjusted EBITDA of about £9m, which is only in line with market forecasts.
Year-end net cash (excluding leases) was said to be £10.2m (FY22: £16.3m). A £30m bank facility was undrawn.
Unfortunately, The Works hasn’t provided any guidance on real profits. There are no broker notes on Research Tree, either. But consensus forecasts shown on Stockopedia suggest a net profit of £1.4m this year, giving adjusted earnings of 3.6p per share. That’s a P/E of 9 after today’s gains.
A full-year dividend of 2.4p per share is forecast. This would cost £1.5m and provide a 7.5% yield. The company has previously said it will consider paying a final dividend, so this seems possible given the group’s cash balance, if not certain.
Trading outlook: trading is expected to continue improving in FY24, despite “challenging market conditions”.
The company says it is comfortable with current market forecasts for FY24 adjusted EBITDA of approximately £10m. This could translate to a 19% rise in earnings this year, according to Stockopedia data:
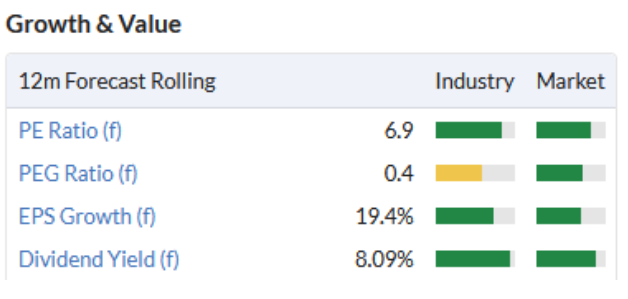
Roland’s view: I’m broadly encouraged by today’s update and agree that The Works’ value proposition could continue to perform relatively well in current market conditions.
However, I’m a little concerned about the risks entailed in the company’s large store estate and slim profit margins.
I estimate that today’s guidance could equate to an operating margin of about 1%. That’s at the lower end of the company’s historic range and doesn’t seem to leave much room for error.
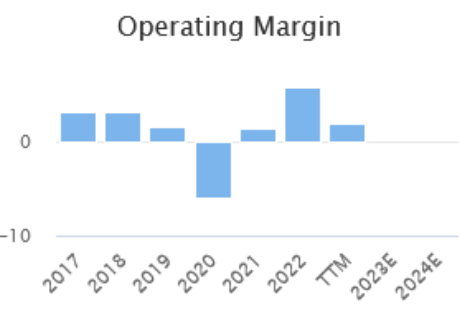
Checking back to the interim results, The Works had 500 stores in the UK and Ireland. These were represented on the balance sheet by almost £105m of lease liabilities.
The last impairment review on 1 May 2022 found 38 stores were loss-making at a budgeted EBITDA level and identified 30 that “were historically loss making”.
I will be keen to see if these figures have changed in this year’s FY results. The cost of supporting or exiting loss-making stores could easily erode profitability at the bottom line.
On balance, I think there are better quality choices elsewhere among value retailers. But I’m cautiously encouraged by The Works’ performance and will be interested to see the full accounts later this year.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

66 comments
Regarding Speedy Hire (LON:SDY) , I agree with Roland on incompetence and the big elephant in the room is the now CEO was the previous COO whom was in charge of such stock control processes and procedures.
There have been some comments made about WOSG recently. The general consensus being that they will struggle to continue their recent growth - and that much of the growth was a result of the Rolex watch bubble. Clearly there was a bubble in the grey market and used market and I am sure that will have some impact on sales / profitability. In the short term the stock may struggle, however, I think at the current valuation the long-term opportunity here is now looking quite compelling - because I see it as a long-term bet on the consumer / and not on Rolex prices! And if it is just a bet on the consumer - then surely it has a good chance of being a long-term winner.
We live in a world of consumerism and materialism. Everywhere you look, you are being offered a product or service - sold to you as being an important addition to your life that will make you happier and more fulfilled. It is quite a distasteful situation! However, this is not going to change, and in this capitalist world people will always aspire to have nicer items of higher quality. Watches and jewellery have always been a high demand item and imo this will never change. WOSG will surely benefit through natural demographics of upper and middle classes becoming wealthier and increasing in numbers. This along with their track record should see them in good stead. They understand their market very well. They have been very successful at opening flagship stores in the UK and are now expanding into the US and Europe. I see this as a great opportunity for a well run business. It is also a fairly 'easy' business to understand.
It is worth noting that most people do not buy Rolex watches. Although Rolex may be the best selling luxury watch brand, there are many other popular brands. If you look at the watches people wear, you will often see Cartier, Omega, IWC, Jaeger-Lecoultre, Longines, Tag, Rado, Breitling etc. The point being that very few people actually own a Rolex. Yet the demand for all luxury watches is very high (and fairly inflation proof). People do value having a high quality watch / piece of jewellery and I do not see this changing on a cultural level. So I think that the current economic weakness / consumer weakness will hurt the numbers for a while but the long term potential is still strong. Essentially I see the consumers appetite only growing over time - and WOSG I think can be trusted to target the correct locations globally to take advantage (as well as growing their digital offerings).
WOSG have also got an excellent reputation with their customers. The trust pilot score is 4.6/5 and the glassdoor score is 5/5. This is important because essentially this is their competitive edge. Most watches are sold around rrp so the prices are usually the same across all authorised dealers. WOSG offers a much more luxury shopping experience than your average smaller independent authorised dealer. The fit outs of the stores are impeccable and the whole process becomes a very enjoyable experience. Also if you are spending a lot on a watch or jewellery, then most people want to try it on first, and the appeal of a place like WOSG is obvious when you consider the high quality and vast range of stock, along with the high quality experience and customer service being offered from a 100% trusted source (which is usually not the case in the high end watch market where there are so many fake watches and bad actors).
So to conclude - I think WOSG know their market very well and have a quality proven business model for growth. If you believe they are a well run outfit, then the risk is the strength of 'the consumer' / or a change in human behaviour. I don't see the long term trend of materialism changing and at some point it is likely the consumer will return stronger and global economies will grow again. In this capitalist world of constant desire, I think WOSG are well placed for the years ahead. And a replication of the UK business across the US (which is a very fragmented market) and Europe offers quite a good growth runway for many years.
Just for some balance. The near term bear points could be:
Inflationary pressures (business costs growing)
Sizeable debt position (growing cost of servicing the debt)
Weaker consumer (unknown as to how long this will persist)
Unlucky / poor timing in terms of expansion and growing debt (in hindsight the growth objectives may have been a year or two early)
They offer interest free credit to customers and that will now become a cost to the business (so rate rises have hurt margins a bit)
Refurbs and expansions are expensive and are an ongoing cost to remaining best in class
Suspension of tax-free tourist shopping has also hurt sales. However this headwind may get reversed and would become a tailwind.
So overall I think that the share price will continue to be under pressure for the next few months. But longer term I think they have a good quality business and a strong and successful business model for the long term. If the price continues south from here I think it is well worth considering and researching further for a long term entry and hold position, longer term I take a contrarian view to the current market consensus.
cheers
Matt
All good points, although I have to say I see more upside in something like JD Sports Fashion (LON:JD.) which had good results yesterday and looks cheap given its growth prospects and track record. Shares many characteristics with Watches of Switzerland (LON:WOSG) - mutli channel retailer, premium brands, strong relationships with brand owners, global presence, etc.
JD Sports Fashion (LON:JD.) (I hold)
Hi Bouden54
I too was impressed with the results yesterday; plenty of cash generation, a net cash position and investment in new stores and logistical infrastructure, all of which was self-funded.
There was a big exceptional hit driven by brand impairments and a divestment of non-core assets. It's always hard seeing the red, but one would hope these are positive long-term steps in the right direction.
A
I see that Renold (LON:RNO) posed an rns this morning saying that the 6% Cumulative Preferences Shares ( @32ID ) will be paying out a dividend of £1 per share. Looking at the two stocks, there is quite a price difference with @32ID trading at 98p Bid and 118p Ask – which is a cavernous spread, (Renold (LON:RNO) 28p Bid and 29p Ask), however, it seems like the @32ID payout is almost 100% return in a div. I must be miss reading this somehow?
Stocko Page for @32ID https://www.stockopedia.com/pr...
@32ID RNS News Page: https://www.stockopedia.com/pr...
Renold announces that the Board has declared the half yearly payment of the
preference dividend in accordance with the terms of the 6 per cent. cumulative
preference stock of £1.00 each, equal to 3 pence per unit.
Andy Sav
Yes, I think you are misreading this (re Renold (LON:RNO) and its preference share.. The article you have referred to is from the news agency and they seemed to have misinterpreted (or poorly worded) the original press release. From the original press release (link below), the div is 3p every half year. The nominal value of the preference share is £1.
https://www.stockopedia.com/pr...
Renold (LON:RNO) Thanks both. That makes a lot more sense
Some decent sized director buys in Luceco (LON:LUCE) last few days.
I suspect theyre starting to see momentum building into the 2nd half. The fall in shipping costs/commodities/inflation should be starting to feed through
Afternoon gents. Is OTB still on your backlog? Quite a drop so keen to hear your thoughts.
If Boon picks up on this, I would love to know what you think of On Beach group (LON:OTB) (I hold) post easyJet (LON:EZJ) results from your travel industry perspective. It looks to me a little like Easyjet Holidays is starting to eat OTB's lunch. Would be great to get Paul's take on OTB results
It does look that way - the broker Stifel commented on this 4 weeks ago picking out Jet2 (LON:JET2) and easyJet (LON:EZJ) as winners at the expense of On Beach group (LON:OTB)
I will probably write a section on @OTB when I write my next monthly Boon Fund update.
I take the Easyjet update as positive; confirms that Holiday demand for summer is now locked in. Autumn onwards is the tricky bit still, but we won't get reliable forward booking data until the next month or so. But IMO the strong growth is wearing off, across the industry, but should still be 10-30% up YoY drive by more capacity. Those who couldn't go summer due to price or capacity will do autumn.
Airlines selling holiday packages is definitely a thorn and sizeable part of the market. However, it is small because of three things.
#1 While they can access cheaper flights inventory, they don't have the teams or volumes of bookings to get unique discounts on the hotels. Compared to OTB.
#2 Their site experience is so poor. Think when you came across a great airline website. If they can't even get it good for their main product (flights), their packages section is usually piss poor. Compared to OTB who specialise in this. Many customers will try an airline, get frustrated; lack of flight choices, lack of hotel choices, bad UX, hard to search, find info, book. Fears of bad Customer Service from airline call centres...
#3 Airlines selling packages are not new. And if they haven't caused problems for the likes of OTB and LoveHolidays so far, I can't see why they will going forwards.
Thanks Boon. Good to get your perspective
I remember we caught the bull run in 2017 on this share, doing well on it here. However it’s been downhill ever since, and my harsh comments here on 16/1/23 and 9/3/23 questioned not only the high valuation, but whether it is even a viable business?
And some of us here who worked in the industry warned in 2017 that compound semiconductors was a mugs game to be in. All of a sudden we had loads of supposed experts turn up, when in fact, they knew nothing about the long and desperately poor history of this technology. However, mention the magic "Apple" word and everyone starts making ludicrous predictions. Anyone who made money on Iqe (LON:IQE) got lucky. The Greater Fool Theory in full effect.
Report from the IIF:
“We estimate that around 14% of U.S. companies can be considered zombies, with a substantial portion of these in the healthcare and information technology sectors.”
I have a general question: when does Stockopedia update its Financial Summary? I've noticed annual results for a company published a week ago via RNS, but the summary has not been updated, for instance.
I have a general question: when does Stockopedia update its Financial Summary? I've noticed annual results for a company published a week ago via RNS, but the summary has not been updated, for instance.
Only a week!? I hold some companies where it takes 3 weeks or more for the StockReport to reflect the latest results. It's not good enough, is it? I have complained and apparently it's the data providers fault. How can you trust any screening results you get? There should at least be a flag showing the SR is not up to date in the same way corporate actions are flagged.
Sorry, Paul's not the only one who got out the wrong side this morning...
All the best, Si
OK, thanks for the heads-up on that. I had assumed that they'd be able to do it in a day or two. After all, what's the point of having a big backlog? Maybe some periods are cramped, though.
OK, thanks for the heads-up on that. I had assumed that they'd be able to do it in a day or two. After all, what's the point of having a big backlog? Maybe some periods are cramped, though.
Tbh I'm surprised you've only just noticed because it's been a perennial problem. I assume you mostly hold FTSE100 companies because there is a correlation i.e. the smaller the company market cap, the longer it takes for the SR to be updated. For some small companies it can take up to a month, in my experience.
I used the green button to point out that Futura Medical (LON:FUM) had not been updated a couple of weeks ago but it still hasn't now, six weeks after results announced, so you are not alone in having a moan.
YouGov (LON:YOU) taking off. Capital Markets day yesterday. Don't seem to need to raise capital, maybe a takeover.
Has been in a downtrend so don't know if sentiment has changed or just a good presentation to support the share. Sorry have not done further research.
Any chance of covering Niox - seem to be on a roll at the moment
Niox (LON:NIOX)
Niox is an interesting company, previously known as Circassia. In 2016 Paul Scott commented that CIR just seems to be a car crash jam tomorrow story stock. This comment was as a result of a failed cat allergy trial that led to a collapse in the share price. They had a range of immunotherapies and a drug called Trudoza, which I misread as Turdoza. They seem to have got rid of all the therapeutics and any liabilities arising from them and now concentrate on the Niox test machine (hence the name change) which measures FeNO (fractional exhaled Nitrous Oxide). This is a useful test for the diagnosis and monitoring of asthma. 90% of revenue is generated from consumables.
The trading update today is quite positive highlighting growth in various areas of the business. The total revenues for the first four months of the year increased by 21% compared to the same period in 2022, with the core clinical business growing strongly by 28%. There was strong growth in the EMEA and Asia markets, while the USA saw a 16% increase in revenues. Gross margins remained robust, and adjusted EBITDA for the first four months exceeded management expectations. The unaudited cash balance also improved. The accumulated deficit on the balance sheet for this company is an extraordinary £558million but a capital reorganisation means they may start to pay a dividend.
By eliminating the dross and focussing on something that actually works I think they are on the verge of delivering the jam that has been promised for so long. I am slightly worried by the fact that they are still using adjusted EBITDA as their yardstick though...
Niox (LON:NIOX) (no position)
Hi DWit199
Some brief comments on the accumulated deficit figure you mentioned of £558m.
1 - My notes say this was £435.2m at the end of 2022. I haven't double-checked whether i made a mistake, but I thought that I would mention it in case you want to investigate further.
2 - Additionally the company won't be able to use all of this.
Again from my notes, I've stated that 25% of this can be offset against future profits.
Sorry, I can't remember if this 25% figure is me guessing, or something the company stated.
That brings the tax benefits here down considerably.
I should caveat this second point with the fact that I'm not a tax-expert and perhaps there is more benefit here than I realise.
---
On a more general note, the results today implied that Research revenues were lower vs last year. They are though much smaller than the Clinical revenues and perhaps not as important
I have a funny feeling Michelmersh Brick Holdings (LON:MBH) is about to take off soon.
Today they released AGM statement. New acquisition Fab Speed is doing very well and company is on track to meet targets. Date for dividend going ex, will be 8th June. Overall dividend gives about 4.25%.
Considering the SP has been in a steady decline for the 2 years, this company has managed to continually grow year on year, though profit margins were down last year I would expect to see the margins increase again as the energy costs have come down and the company provides energy from solar panels installed. Also they deceased one of their production companies which only provided 3% of their revenues and had low profit margin. The site is being used to enhance the last acquisition Fab Speed, so this should help the bottom line.
The chart looks interesting imo. Volume has been declining since the results came out on 29/03/23, while the SP has been flat - an indication the SP is about to change. (Could be either way). Also the 50EMA is very close to the 200SMA, possible Golden cross about to happen. An entry above resistance at 101p would be the safe play, but you'd be buying in 11-12% higher than todays price but would then capture the majority of the turn around in the SP.
Anyway, just food for thought. I do own a small holding in this.
I hold Michelmersh Brick Holdings (LON:MBH) . I view them as a good value quality company with a deep moat (the onerous planning approval process for new quarries). But I am expecting to have to wait until there is another housing boom.
Michelmersh Brick Holdings (LON:MBH) (I hold)
Hi gmtrader
Thanks for your comment.
You mentioned that margins were down last year, but I must admit that I can't see where.
Gross Profit % was down for the full year (39.4% vs 40.6%), but by my workings they were actually stable at 41.0% in H2 in both 2021 and 2022.
I have a feeling that there will be margin pressure this year as energy prices are fixed at higher prices and price increases were lower than those made by competitors.
Nonetheless I remain cautiously optimistic.
A
Sorry, margins were down first half of last year due to energy prices. They made it up in second half as the energy prices dropped which makes me think this year should be better. Saying that, I’d imagine they will have to pay higher wages especially as they are short staffed like every where else. Still, they keep growing year on year and are always looking for more acquisitions as well as looking at ways to improve the business. I too am pretty optimistic and happy to collect the dividend. Michelmersh Brick Holdings (LON:MBH)
Abtan, check out the volume today.
Michelmersh Brick Holdings (LON:MBH)
Hi gmtrader
I do keep an eye on volume, but more out of curiosity than anything else.
Does the high volume here mean anything?
Or is it more a case of it could mean something?
Who really knows? Could be institutes buying or swapping shares from one ii to another which is probably the case as the sp hasn’t moved.
A tad too big for the SCVR but parhaps not for long, Future (LON:FUTR) Interims seem to have disappointed the market this morning. I don't hold but it was on the watchlist. I wonder if this could enter value territory at some point? If there are bulls in this stock I am interested in hearing the case?
And with all this talk of jam tomorrow / story stocks today, I present MyCelx Technologies (LON:MYX), who today announce yet another year of losses (seemingly a big miss vs cannacord forecasts, which must cast doubt on 2024's forecast profit), with little sign of change and likely needing funding in the not too distant future?
Future (LON:FUTR)
Hi Mark
Personally I think it already is in value territory and I significantly increased my very small holding this morning.
Revenues are relatively stable, due to acquisitions, and gross margins are still excellent at 48%, albeit this is down from 54% achieved in the same period last year.
Despite the organic slowdown, by my workings underlying free cash flow will be c.£200m for FY23, a similar level to last year. This is enough to fund more acquisitions whilst simultaneously reducing debt.
I personally would apply a minimum cash generation multiple of x15 and for prudence assume that cash generation drops to £150m.
This gives me a minimum target valuation of £2.3b vs a current EV of £1.5b.
A concern could be the current debt levels, but I believe that most of this could be paid off within a couple of years.
I also remain hopeful of price comparison revenues picking up again in the next couple of years, but this is not accounted for in my thoughts above.
A
chatgpt will eat them up.
Hi Ben
I'm assuming you're referring to Future (LON:FUTR)
Why do you think "chatgpt will eat them up?"
When reviewing Secure Trust Bank (LON:STB) , perhaps Roland would like to comment on the very expensive debt raise and the inherent wisdom of buy now, pay later, lending (at supposed 0% interest).
Bank of Georgia (LON:BGEO) am on holiday so catching up on news but saw their results yesterday and surprised no mention.
These are very good indeed and a bank generating ROE exceeding 20% trades on 3.5* earnings. That’s nuts especially with an 8% dividend yield to boot. Metrics are all good. Decent NIM, Tier 1 capital of 20% which is excellent and that ignores about another 5% that is held in the holding company and therefore excluded from the calcs. Cost of risk circa 1% which is good for that part of the world. Liquidity ratio well ahead of the 100% required. Funding sources well diversified so any run on bank highly unlikely in my view. Just look at liquid cash/investments. Cost/income ratio excellent.
Anyway, obviously one for the patient. They’ve more than doubled over last couple of years but a PER of 6 or 7 is more appropriate I’d have thought. With earnings approaching the 9 GBP p/share mark that would double them again and with likely dividend increases still yield 5%. Am surprised they haven’t traded up more post results tbh.
Bank of Georgia strength not really filtered through to Georgia Capital which despite owning circa. 20% of. Bank of Georgia hasn’t had the same rise .
Silly discount to NAV at Georgia capital but I think the market is waking up and it is starting to rerate having just punched through the 800p level .
I managed to get a decent top up at Georgia capital few weeks ago at 740p level when it had a 24 hour meltdown .
Think both are rock solid long term .holds assuming no geopolitical cataclysti event .
Genuit (LON:GEN)
Interesting to see that not all building materials suppliers are finding it tough to maintain performance. I interpret this as a combination of self-help - protecting margins through cost savings - and exposure to attractive segments with regulatory tailwinds, like ventilation. We’ve seen similar at Volution (LON:FAN.
If it’s a quiet day, you might want to take a look. I see attractive valuation and good upside on a rebound in construction. Analysts at Jefferies agree.
Thanks BnB,
Genuit (LON:GEN) looks quite interesting actually, and I see it's up today on news.
Will add it to the list! But there's a lot already on the list, so I can't guarantee we'll get round to it. Thanks for the suggestion, and synopsis!
Regards, Paul.
Sherborne Investors (Guernsey) C (LON:SIGC) Two pieces of news... a new CEO at the underlying turnaround investment, Navient (US ticker NAVI) which given E Bramson is on the board...I hope is helpful. Then today a slightly strange announcement from Sherborne that I think means this is the final turnaround target company. Therefore cash is cash and will be returned to investors as it flows back to the company. Could mean many things but suggests "stuff" is happening. The shares trade at a substantial (30%) discount.
My morning smallcap tweet: Jam today and tomorrow
Chill Brands (LON:CHLL) SRT Marine Systems (LON:SRT) Tanfield (LON:TAN) Christie (LON:CTG) ImmuPharma (LON:IMM) Nuformix (LON:NFX) Conygar Investment Co (LON:CIC) Speedy Hire (LON:SDY) Niox (LON:NIOX) Non-Standard Finance (LON:NSF) Genuit (LON:GEN) Mirada (LON:MIRA) Plant Health Care (LON:PHC) Myhealthchecked (LON:MHC), Fintel (LON:FNTL), Safestyle UK (LON:SFE), Redde Northgate (LON:REDD), Secure Trust Bank (LON:STB), Belvoir (LON:BLV), Michelmersh Brick Holdings (LON:MBH), Science (LON:SAG), Idox (LON:IDOX), Works co uk (LON:WRKS)
◄Chill Brands (CHLL)► engages a sales, distribution and marketing agent (The Vaping Group) to launch its range of nicotine-free vapour products to the UK market. "Confident that this partnership will significantly improve its commercial prospects and the near-term performance." [SP=7.28 Cap=17m]
◄SRT Marine Systems (SRT)► $180m contract to supply an integrated maritime surveillance and intelligence system to a national Coast Guard. Expected implementation period 2 years. [SP=46 Cap=84m]. I hold.
◄Tanfield (TAN)► improved performance of 49% owned Snorkel. [SP=2.58 Cap=5m]
◄Christie (CTG)► H2 weighting to even greater due to delays in transactions. FY guidance unchanged. [SP=147.1 Cap=39m]
◄Immupharma (IMM)► ositive guidance from the FDA Pre-IND meeting supports an IND application and a Phase 2/3 adaptive clinical trial of P140. [SP=3.09 Cap=10m]
◄Nuformix (NFX)► some progress on tests of NXP002 treatment of Idiopathic Pulmonary Fibrosis. [SP=0.25 Cap=2m]
◄Conygar Investment Company (CIC)► planning approval for next phase of The Island Quarter development in Nottingham. [SP=115 Cap=69m]
◄Speedy Hire (SDY)► £20m of missing non itemised items was not do to "underlying systemic fraud" but blames problems with controls and accounting procedures over many years. [SP=32.1 Cap=149m]
◄Niox (NIOX)► adj EBITDA for the first four months of the year well ahead of mgmt expectations. Rev up 21%. [SP=57.41 Cap=239m]
◄Non-Standard Finance (NSF)► largest shareholder, Alchemy pulls of planned placing so the Alternative Transaction (d4e) is more likely than the recapitalisation. A d4e will leave shares almost worthless. [SP=0.45 Cap=1m]
◄Genuit (GEN)► guides FY-Dec23 rev in line and op profit slightly ahead of consensus: EBIT forecasts £70 - £96m. Jan-Apr rev down 4%. [SP=298 Cap=736m]
◄Mirada (MIRA)► the tinpot TV software co proposes delisting after years of disappointment. Blames small free-float, inability to place shares and costs of listing. Guides FY-Mar rev c.$10.7m ($11m) and adj EBITDA c. £1.5m ($1.6m). "Marked progress in consolidating its position as a leading provider of Android TV-powered software in the industry." [SP=19.9 Cap=2m]
◄Plant Health Care (PHC)► consultation with shareholders concludes that co will remain listed and support for "further capital to accelerate organic growth, if justified by returns over the current plan". [SP=10 Cap=31m]
◄MyHealthChecked (MHC)► Boots will stock extended range of at-home self-testing products. [SP=23 Cap=12m]
In line: FNTL, SFE, REDD, STB, BLV, MBH, SAG, IDOX, WRKS
Redde Northgate (LON:REDD)
Solid trading update again today along with acquisition that should be earnings enhancing from the get go. Solid hold for me here at present as current rating is pretty undemanding , main good news is that there is no sign of drop off in earnings as vehicle prices normalise - that’s pretty unexpected based on good run they had with inflated second hand van values.
Thanks Rmillaree,
The acquisition today looks like a good move. Looking on Companies House at Fridgexpress (UK) Ltd, both the CEO and CFO of Redde Northgate (LON:REDD) were appointed to the Board of the Company on 5th May. So there is direct oversight of the new acquisition from the key team.
Fridgexpress has up to date filed accounts for the end March 2023, abbreviated but showing rapid expansion in fleet size during year ending 2023. There is no reported P&L or cashflow but the retained earnings increased by around £800k in the year just ended. So, seems solidly profitable and now directly managed by Martin Ward. Martin has done a good job with Redde Northgate (LON:REDD) and holds a sizable equity stake.
Anything happening at Volex (LON:VLX) ?
Sky News reports DeLaRue want to head hunt Nats Rothschild, and Volex (LON:VLX) announce this morning they are appointing Peel Hunt as an additional advisor.
2 + 2 probably making 6 but no smoke without
DLR have appointed a non exec chairman this morning, so won't be Mr.Rothschild!
Jam today!
$180m MDA System Contract Signed
https://www.investegate.co.uk/...
Well done SRT Marine Systems (LON:SRT) , my tip for 2023.
https://www.stockopedia.com/co...
You got lucky there, we've been waiting 18 years for SRT to win a big contract!!! It would be good to find some third-party confirmation that the contract is real. As I discovered to my cost this year, with WAND, contract win RNSs are not necessarily genuine, so it can be dangerous to value any company entirely on hopes for contract wins.
Difficult to share your scepticism Paul (I hold) - this has been a long evolving story and Simon Tucker and SRT Marine Systems (LON:SRT) are a vey genuine company. Government-related contracts take a long time to come about and don't get announced on a whim.
Worth looking back at what I and others said about them in September 2022.
Once in place thse relationships will last for many years and there'll be plenty of incremental and recurring revenue opportunities.
That's a disappointing response from you, Paul. Just because you got conned at WANdisco (LON:WAND) , it is neither reasonable nor appropriate to extrapolate that experience across the wider market. SRT Marine Systems (LON:SRT) are not spivvy chancers, and this contract is the culmination of many years of hard work by the management team there.
A bit of research would reveal that this contract is with Indonesia, who now join Saudi Arabia among SRT's national coast guard customers. A bit more research would reveal there are strong prospects in the pipeline for further national coast guard contracts, which have all become significantly more credible with the signing of this deal.
No need for an emotional reply.
I was just pointing out the general point that valuing companies entirely on contract wins does come with an element of risk, that's all. Also it won't be clear until figures are published, how much actual profit is going to be made on these contracts.
Nevertheless, It's good to see SRT hopefully coming good, after so many years of promising jam tomorrow.
In that regard it reminds me of Surface Transforms (LON:SCE) - sometimes this type of company can eventually deliver, after several generations of investors have been disappointed!
SRT Marine Systems (LON:SRT)
There will be a lot of profit coming through on this. Margins are good. Expect to see some big upgrades in broker notes. This is another step change for the business and is about double the previous largest contract. But once you win them you get service revenue and expansion for years. That’s 3 they’ve got in place now and I expect more.
Given the excellent progress in the transponder division too which pretty much now brings the group to break even these contracts add material profitability to the business. They key is to win 1 every year or so and expand the others. Assuming things are now in place for that I see SRT Marine Systems (LON:SRT) as seriously undervalued now. I hold
Morning David,
There's an update note (out today) from Finncap on SRT Marine Systems (LON:SRT)
It suggests quite low margins actually - gross margin of 33% in FY 3/2024, falling to 28% the following year.
This results in big revenues, but not especially big profits.
Hence the current share price of 55p is a fwd PER of about 8x, and that's factoring in all the growth.
It's cheap if you think that these forecasts are going to be beaten, but if not, then the current share price probably factors in the upside already, less a discount for risk, mkt cap is about £100m after all
For this reason, I'll probably be neutral overall on SRT.
Also, the almost complete lack of visibility over the years, and glacially slow decision-making from Govts, means nobody can forecast anything reliably. I note that this contract announced today had to be funded by the UK Govt!
Still, I don't want to upset the bulls too much, as today is your day, with a nice big contract win. Always good to discuss bull & bear points though. As I say, overall I can see merit in both, so am neutral.
Regards, Paul.
Numbers look very light from FinnCap. Need to go through my model when I get back but this looks like it’s set up to beat significantly over next couple of years. Either way it’s cheap.
Funding mechanism is nothing unusual for UK companies doing large inter governmental projects. Not sure why you’re cynical about that.
SRT Marine Systems (LON:SRT)
Paul does have very valid point here albeit perhaps cynicism here has got the better of him ref wording - (edit thankfully he has clarified his comments) . I think we all know the contract is real and genuine - however with contracts of this type all it takes is for the current incumbents of the position or whoever controls the purse strings above them to change their mind and it can all go up in a puff of smoke. I think from memory this exact thig has happened before where they have had contracts cancelled / delayed on them. So until cash turns up in their bank account one has to not get too carried away.Note i am not in any way knocking the good news here its simply fact of life in their business until the cash is in the bank the deal aint done and even then you hope that the system performs exactly as specified if you want to keep that money. The good news is , with shares like this if you do your research and get it right you may be rewarded as i can guarantee by now the market will be jaded with regard to positive news without matching signs of cashflow positivity and upbeat future prospects at the same time from this share.
"A bit more research would reveal there are strong prospects in the pipeline for further national coast guard contracts, which have all become significantly more credible with the signing of this deal.2
I dont think this company has ever lacked in prospects or credibility - the problem has been the lack of "real profits" from all the prior prospects. So nowt of real substance in this comment imho as no one has really doubted the potential - there would be no point evenb discussing teh share if one didnt see or concede that their could posibly be a strong bull case here.
Agreed - the problem for SRT Marine Systems (LON:SRT) has always been that the pipeline has taken a long while to mature. Far longer than anticipated.
So when a very large contract gets landed, following on from some smaller ones successfully delivered and subsequently expanded investors should be giving the company credit for that and start to price in the rest of the pipeline as management clearly now have a better grip over timing.
So it’s just a bit odd that suddenly there is a wave of cynicism, not that it matters much.
And as for cash - well, agreed. Cash is king and investors need to see that coming through as well. But given it is backed by the UK Government it’s less likely to get delayed and provides excellent credit quality for the company.
SRT Marine Systems (LON:SRT)
So it’s just a bit odd that suddenly there is a wave of cynicism, not that it matters much.
There is no sudden wave of cynicism - there has been pretty constant cynicism too for quite some time from plenty of peeps. Probably up to now rightly so as for many years company was promising profits that never turned up in reliable manner - perhaps thats all due to some over enthusiastic middle man in switzerland or a long run of incredibly bad luck i know not. So i think the positive peeps and negative peeps have been pretty consistent here. Its vital to point out to newbies here that contracts might not flow through to cash and this company has had history of having had decent contracts pulled - someone even mentioned they had delivered some goods only for contract to to reversed - good facts for nay potential investor to know.
This is the perfect opportunity for this company to get some good broker research delivered to investors outlining the "real reaility" of the good news ref number. Really company should have in advance had prior detailed research 2-3 years out ready for that to be updated immediately (today) based on the now signed contract. That would have inidcated to me a professional mangement who are living in the real world and providing what shareholders and potential shareholders info that need to assess contracts. I signed contract tells us little and imho its not my job to spend hours working oou numbers that i am damn sure they will have on paper in head office
IMHO if they now expect current profits to be higher than previously advised it would have been nice if they could have provided some confirmation or at least mentioned something along the lines of we will update ref current trading prospects on date x. On the plus side the positive momentum here is a big plus so hopefully loyal or new sharholders will both be rewarded.
Would be interetsed on seeing details of any update forecasts if they become available.
I also like to look at what management primise 2 years ahead against what they deliver. It would be easy peesy for most of this contract profit to be eaten up in megalomaniac ideas fro future profit streams - thats a tricky one as there could be great potential out there that they may now have ability to tap by reivesting these gains (if they turn up) into something bigger.
This is the perfect opportunity for this company to get some good broker research delivered to investors outlining the "real reaility" of the good news ref number. Really company should have in advance had prior detailed research 2-3 years out ready for that to be updated immediately (today) based on the now signed contract. That would have inidcated to me a professional mangement who are living in the real world and providing what shareholders and potential shareholders info that need to assess contracts.
You need to keep up, rmillaree! finnCap released a 14-page research note on SRT Marine Systems (LON:SRT) this morning, with forecasts out to 2025. This includes an upside scenario assuming continued contract momentum.
I have just updated the post I made in early February which may be useful to anyone wanting more background on SRT .. It’s here
https://www.stockopedia.com/co...
Paul you are being grumpy, although I can understand your cynicism. Call me naive but I like to look for the best in people if I can and the CEO of SRT seems an honest cove. If it pans out according to my very approx numbers they would be on a PE around 10 times two years out. I note Finncap have that at 7 times. For a growing business that seems a bit conservative and doesn't factor in the real potential for growth. I suspect they are cheap. Look forward to buying you a beer at Mello.
The share prise rise is 8p... *181m shares = £15m. Does this make sense? I always think the mkt is pretty good at this.....
$180m with 85% over 2 years ... $76m a year @ 28% margin = $21.5 ... £17m then knock of mobilisation costs etc wrapped up in what looks like £5m DA £12m ..tax it £9.6m ...so £9.6m + 0.9*£9.6m = an NPV of the contract of £18m .... compared to rise of £15m .... Im not sure you can put a PE on one contract but in time it may be appropriate. For now reaction looks about right ... a different way of looking at it but I agree with Paul.
In case anyone gives any credence to Paul's insinuation that the contract announced by SRT Marine Systems (LON:SRT) this morning may not be real, this is (translated) from the Twitter feed of the Indonesia Coast Guard today:
Bakamla RI Officially Uses National Maritime Security System (NMSS), in collaboration with SRT Marine System Plc.
In short, NMSS is a system used to carry out supervision and monitoring in real time in Indonesian territorial waters and Indonesian jurisdictions.
https://twitter.com/HumasBakam...
Congrats to holders ! Must have been worrying to watch at times - glad to see that it has come good.
A bit late but thanks for the excellent weekend Podcasts Paul