Small Cap Value Report (Thu 19 Jan 2023) - W7L, LIO, EXR, CURY, TIDE, STM, GFRD, TIFS, ACSO, IBST, GTLY, SMRT, BOO, JDG, FDEV, WAG, ZTF

Good morning from Paul & Graham!
I'll leave it there for today, but plenty more items to cover, so I'll be looking at those in tomorrow's report.
CEO interview - recorded yesterday afternoon, I had a very interesting Q&A with Sam Bazini, CEO of Warpaint London (LON:W7L) - loads of interesting points, and I think he comes across really well, as a straightforward entrepreneur. After a good recent run, I think W7L shares look fairly priced around 175p, but the company seems to have good long-term expansion plans. Above all, I like owner-managed, entrepreneurial companies with sound finances, that pay divis, and have common sense business models. So W7L ticks a lot of my boxes as a long-term investment, hence why it's on my watchlist. As always, DYOR.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Agenda -
We'll put our one sentence summaries on this spreadsheet below (as we started yesterday), which makes it more efficient for Graham & I to update the article, and hopefully also gives you a very quick reference point for the overview -
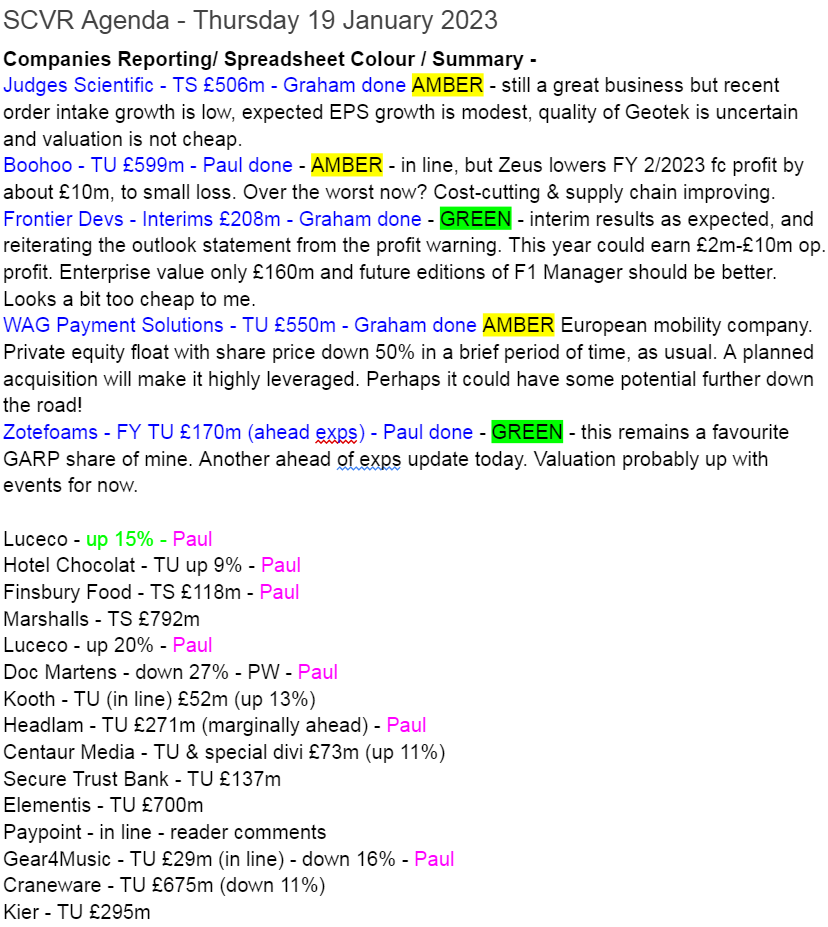
I'm starting to flag, so don't think we'll get those done today, but if I get a surge of energy this evening, might do some ready for tomorrow again. Lots of interesting stuff to cover, not enough hours in the day!
Paul's Section:
Here are 11 short sections from yesterday's news, which I prepared last night -
Liontrust Asset Management (LON:LIO) - TS £789m - Update to 31 Dec 2022. Assets under management rose 3% to £32.6bn over the quarter. Net outflows of £0.6bn. Paul’s view - this seems a good time to be looking at investing in fund management shares, many of which Graham has written about in previous reports. LIO looks quite good, on a lowish fwd PER of 12.4, with a lovely 5.9% dividend yield, it looks worth a closer look. Thumbs up.
ENGAGE XR Holdings (LON:EXR) - TU £13m - see SCVR for 12 Dec 2022, this share is a bargepole job - because it looks set to run out of cash imminently. Today is says there’s E2.2m cash left (end Dec 2022), and monthly cash burn expected to be E0.4m in H1 2023. Therefore, it’s set to run out of cash in May/June 2023. For me, this is uninvestable until it’s been refinanced. Too risky before that.
Currys (LON:CURY) - TU (up 11% y’day) - Peak trading update (10 weeks to 7 Jan 2023) pleased the market. It says UK is more profitable than forecast, but International less profitable. Reiterates guidance given on 15 Dec 2022 (which was a profit warning), of £100-125m adj PBT for FY 4/2023. I reported on its profit warning here, and decided it looks too high risk, due to dependence on massive trade creditors - the risk being that credit insurers might reduce or withdraw cover. It might all turn out to be fine, but potential investors need to understand this share is quite risky, and the big divis are on shaky foundations, so could be stopped if trading deteriorates. For now though, things seem to have stabilised, with previous reduced guidance now firmed up.
Crimson Tide (LON:TIDE) - TU £17m (smaller than expected loss) - quite an interesting update. FY 12/2022 revenues up >30% vs 2021. Running at a loss, but it has a sound balance sheet, with enough cash to finance this push for growth, I reckon. Record recurring revenues of £5.8m at year end. This looks potentially interesting, if it’s able to scale up a lot more. Attempting expansion into the USA, through a partner. Worth a closer look, I’ve had my eye on this company for a while, as it seems to have potential. £17m mkt cap looks ahead of events for the moment though.
STM (LON:STM) - TS £17m (down 5%) - guidance it gives for FY 12/2022 is: revenue £24.1m, and PBT of £1.7m+. Net cash of £14m stands out, for a company with a market cap of £17m! Unusual balance sheet with £24.1m asset and liability, which seems to relate to an insurance claim - need careful scrutiny. Have any readers looked into this share, it looks a potentially interesting special situation. I did research it a few years ago, when there was a flurry of interest, but I recall there being some odd aspects to the share, and investor interest fizzled out again. I might have met management at the time, and remember thinking it seemed complicated, something to do with a regulatory grey area on pensions called QROPS? Things might have moved on since then. A review is underway, to attempt to unlock shareholder value. One for special situations investors only, I’d say. The cash pile makes it potentially interesting though.
Galliford Try Holdings (LON:GFRD) - TU £192m - Construction group gives H1 update (to Dec 2022). Trading in line with expectations. Says it has managed supply chain, clients and macro effectively. Two recent acquisitions done. Cash pile looks really impressive, but check out the balance sheet - current assets of £465m (included £219m cash at end June 2022) is more than fully offset by current liabilities of £508m. So the cash has arisen from timing benefits on working capital, and is not surplus cash, the way I view things. NTAV was only £35m at June 2022, to further reinforce this point that the cash pile is a bit of a mirage - it’s come about because customers are generous, early payers. But as the company says, having no interest-bearing debt, and no pension liabilities, is a distinct advantage. Plus it can now earn interest on the cash pile, I imagine. The cash pile was £195m at end Dec 2022. I’d like to know the average daily cash balance, not just average month end cash (as disclosed today at £154m).
Outlook - £3.5bn order book gives good visibility. Robust pipeline.
Share buybacks underway, and forecast dividend yield is 5.5%.
My opinion - not for me, as it’s a very low margin contractor on big projects, which as we know can be high risk if something goes wrong. But this is a good update, so if you are prepared to invest in this sector, this is probably a fairly good choice, so I’ll give it a grudging thumbs up!
TI Fluid Systems (LON:TIFS) - TU £606m (down 14%) - looks to have made a new, all-time low today of 117p, since it floated in Oct 2017. I’ve never looked at the company properly, but Graham reviewed it here on 3 Nov 2022.
FY 12/2022 update guides in Euros: revenue E3.26bn, adj EBIT c.E180m. Adj free cashflow E80m, and net debt:adj EBITDA of 1.9x - that all sounds reasonable.
Note there’s a substantial finance charge, so EBIT (operating profit) is not telling the full picture.
The last balance sheet at June 2022 only had NTAV of E100m. There’s over E1.1bn in gross debt, partly offset by E499m cash. So debt covenants are very important. Overall, I’m not comfortable with this balance sheet, which introduces risk, particularly if trading continues to deteriorate. There also seems to be a pension deficit. Although the interims came with a clean going concern statement, so maybe I’m worrying too much about risk?
Outlook - market conditions to remain challenging, especially China. Material impairment charge expected for fixed assets & intangibles (non-cash though).
Broker consensus forecasts for both 2022 and 2023 have been in almost continuous decline for the last 18 months. Maybe it might be best to wait for forecasts to start rising, rather than gambling on a turnaround before it has happened?
My opinion - quite a large, and complicated business, with over 100 factories worldwide.
This could be an interesting turnaround, as car production returns to normal in future, possibly. I can see both bull & bear views as having validity, so will say I’m neutral. Amber for the spreadsheet.
accesso Technology (LON:ACSO) - new business momentum, it says - this ticketing/queuing software group has had a decent run - 4-bagging from the pandemic lows, including a strong spurt since the Oct 2022 lows, like many smaller caps. Yesterday’s update says it’s signed 18 new clients, and gives some examples, but doesn’t give any indication of the financial benefit, or size of these deals. We’re told that “2022 was a strong year for accesso…”, but no figures. So it’s more a PR release than a trading update.
My opinion - this update didn’t move the share price (well, a 1% fall), and the fwd PER of 38 times looks too aggressive to me. Why pay so much for a company with a patchy track record, that’s never paid any divis? The last reported balance sheet was very good, with a substantial cash pile, so it could pay divis if it wanted.
The shares are obviously a bet on a strong recovery in the leisure sector. To justify its £341m market cap, I think it needs to be producing numbers well ahead of current expectations. So we’ll see what happens. As things stand currently, I’m neutral on Accesso.
Ibstock (LON:IBST) - TU £650m - one of the listed brick makers. FY 12/2022 update - it says volumes declined in Q4 (as expected) vs LY, but a focus on price, margin, and costs, resulted in a “solid EBITDA margin performance”. Guidance for FY 12/2022 is now: revenues £510m (up 25% vs LY), adj EBITDA “modestly ahead” of expectations. Net debt of £46m (after growth capex spend of >£35m, and £30m share buyback).
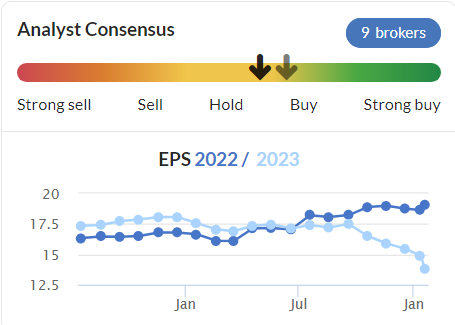
Outlook - expecting “more challenging” conditions in 2023. But sounds confident in the medium term. Note that broker consensus forecasts for 2023 have been plunging in recent months. Pension buy-in agreement agreed in Q4 - another one, after similar deals with TTG and Robinson.
My opinion - housebuilders are saying production is retrenching, so that’s bound to impact brick producers. So investors need to think about how you see the macro picture panning out. The 2023 forecasts are plunging, see below, which looks very similar to forecast earnings for the housebuilders too, unsurprisingly.
Gateley Holdings (LON:GTLY) - Interims 237m - one of the listed legal services shares, some of which have gone wrong. This one’s performed reasonably well since listing in 2015, with a positive trend on revenues & profits, and a good track record on divis (with a hiatus in 2020 re the pandemic), and quite a reasonable total shareholder return, adding the share price rise to the generous divis.
Interim results to 10/2022 were out yesterday. On the quickest of skims, the figures look OK to me, eg revenue up 22% to £76m in H1, and underlying adjusted PBT up 13% to £9.6m.
Outlook - says more challenging environment is beginning to emerge. Divis indicated at about 10p for the full year, so yield is 5.3%, assuming H2 performs in line.
Balance sheet looks OK, with about £40m NTAV, which includes the high receivables that is usual for this sector, but can be a worry as there are often write-offs needed, so correct provisioning is key.
My opinion - I tend not to invest in this sector, due to the conflict of interest between the fee earners, and outside shareholders. But the numbers for GTLY do look quite attractive.
Smartspace Software (LON:SMRT) - TU £13m (in line) - shares bounced 7% to 44.5p, on a trading update yesterday confirming that FY 1/2023 trading “continues to be in line with market expectations”. What’s odd is that it also announces a change of auditor, from RSM to Cooper Parry, “following the conclusion of a tender process”. It’s not at all normal to change auditors a fortnight before the year end. Normally the auditor would have already done some preliminary work, and be ready to come in for the final audit visit in just a few weeks time.
I’ve looked through the last 6 months’ announcements, and there doesn’t seem to be any indication that the auditors were to be changed. Indeed, on 5 July 2022 the outgoing auditor RSM, was confirmed by a 99.38% shareholder vote, to be re-appointed as the company’s auditor. So clearly there must have been a more recent falling out between SMRT and its auditor RSM. What caused that? Yesterday’s update says this -
RSM UK LLP has ceased to be the Company's auditor and has confirmed to the Company that there are no matters connected with its ceasing to hold office that need to be brought to the attention of the members or creditors of the Company for the purposes of section 519 of the Companies Act 2006.
It’s rare for an outgoing auditor to write such a letter, but it can happen. So that rules out the worst possible scenario, but it still unnerves me that the auditor is changing at this time - there must be something wrong for this to have happened, in my view.
I’m surprised the share price didn’t take a dive on this news actually. What do other people think?
Looking at the last interims, the balance sheet is looking a bit thin, and it’s still loss-making. Although there does seem to be a nice trend developing in recurring revenue growth. So it could be one to watch maybe?
On to today's news, obviously I had to start with this one! -
Boohoo (LON:BOO)
47p (pre market) - mkt cap £601m
Trading Statement - 4 months to 31 Dec 2022.
This seems a reassuring update, given the question marks over the whole eCommerce sector, which has crashed in the last 18 months, globally. Remember that the prior year comparatives are strong for online retailers, which is a headwind this year (as omicron boosted their sales LY). This is the opposite of physical retailers, who suffered during omicron in late 2021/early 2022, so they now have a tailwind of easy comparatives 2021 to beat in 2022. That’s an important distinction to bear in mind.
It’s difficult to compare to last year, as BOO has changed the phasing of its trading updates, and didn’t issue a 4 month update this time last year, but instead a 3 month update to 30 November (which showed +10% revenues).
Key points for 4 months to 31 Dec 2022 -
Revenue down -11% to £638m (but still +35% on pre-pandemic) - it says this is “in line with previous guidance” - which I’ve confirmed to a note from Zeus in Sept 2022.
All regions down a similar amount vs LY (last year). UK remains the main market, at 63% of total revenues.
Gross margin 49.7% - is a little lower than previous forecast of 50.9% - but I’m expecting this to improve as supply chains & freights costs normalise. There's a mix of retail & wholesale, so we need more detail to see the underlying trend.
Inventories down a striking 27% as supply chains loosen up, this is positive when many companies are struggling with excessive inventories.
Loads of liquidity headroom, over £300m of gross cash, but bear in mind this is more than offset by a mysterious loan (which people are assuming is provided by HSBC, but I cannot find any proof of that - if you have information on that, please leave a comment). It’s a strange set up, to draw down such a large loan, pay hefty interest on it, whilst the cash sits in the bank earning less interest presumably. We need more info on this - the costs, and terms (any covenants?) of the large borrowings.
Warehouse automation ongoing, should improve efficiency and boost bottom line. I remember a figure of £25m profit opportunity being previously mentioned.
Profit guidance - for FY 2/2023 - in line with market expectations, which is a relief for shareholders I imagine (I’m not currently holding personally).
Guidance is for 3.5% EBITDA margin, which translates into a £71.6m adj EBITDA (per Zeus, many thanks for the update note). Sounds fine, but bear in mind a heavy depreciation charge takes this to a small loss before tax of £(8.5)m. The last note I have from Zeus, dated 28 Sept 2022, shows a adj PBT of positive £1.1m, so actually forecasts have been reduced today, despite the company saying it’s traded in line.
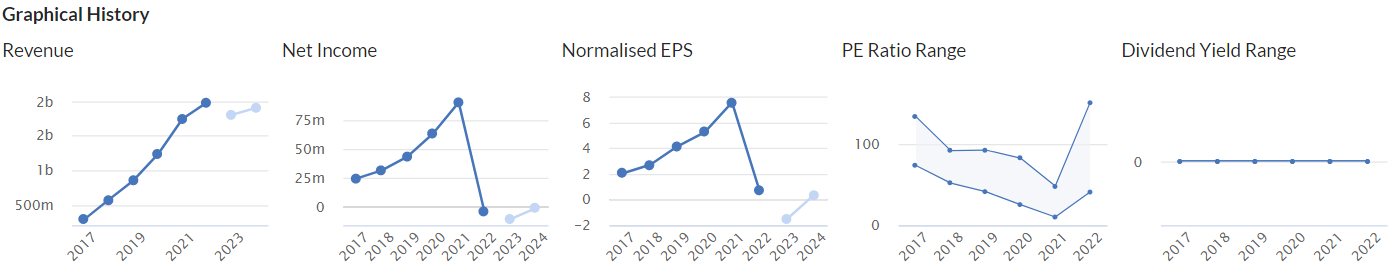
Clearly bumping along just below breakeven, is not a good performance, given the group’s previously superb track record of decent & growing profitability, which went horribly wrong in the last financial year, as the online fast fashion boom seemed to burst. That brought with it the horror show of investors of a collapse in earnings, combined with a collapse in the rating and investor confidence -
Outlook - it’s not all doom & gloom though, as I’ve always said, there are plenty of levers eCommerce businesses can pull (e.g. huge marketing spend, which can be cut any time, to conserve cash). Plus in BOO’s case I think it was spending freely on rapid expansion (eg warehouses), but the whole tone of the commentary today has now changed to being about cost control, which I like. That’s what’s needed to rebuild margins.
Plus there are now potential favourable tailwinds from supply chains and freight (timing and cost) normalising, which should allow an improvement in gross margins. Each 1% of margin rebuild adds £17.5m to the bottom line remember.
My opinion - this looks OK to me, as I was worried there might be more bad news, which there isn’t (other than a modest edging down of FY 2/2023 forecasts).
In overview, the group is now trading around breakeven, with sensible reasons to see potential for margin improvements, as supply chains normalise.
Remember it’s also been spending a lot on pushing the growth of the newly acquired Former Arcadia and Debenhams brands. It’s a pity we’re not given a split of the losses by brand. Also, as we've discovered with ASOS (LON:ASC) and THG (LON:THG) - when companies grow hugely, and very fast, all sorts of inefficiencies creep in, and it's a slow and painful process to remedy problems that were previously obscured by rapid growth and easy profits at BOO (as opposed to Asos & THG, which never made any meaningful profits).
How to value this share? The market cap is substantial at £601m, given that profits have completely evaporated, and now need to be rebuilt. Plus the looming presence of Chinese competitor Shein, which has taken some market share.
I’d like more clarity on the large loan that’s been drawn down - terms, and who is providing it?
Overall though, this update reassures me, and I think the downtrend in share price might have ended. Note that Asos had a spectacular (in % terms) rebound recently, and BOO could benefit from a potential short squeeze.
At the time of writing (08:05) it’s still in auction, so we’ll soon find out how the market reacts to this update. I think the worst is probably over for the share price, and there’s a chance of a nice rebound at some point. Longer term? I’m not sure how to value it at the moment, which is always the case for companies trading around breakeven.
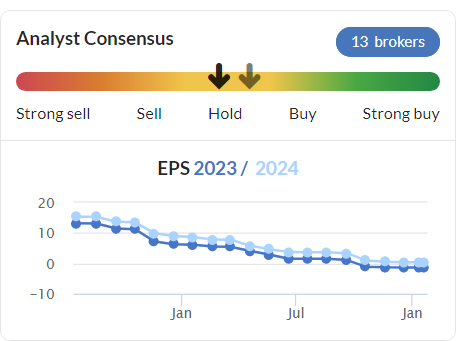
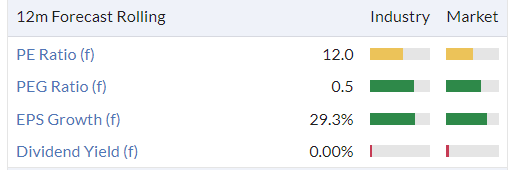
Negative trend in broker forecasts - but settling around breakeven?
.
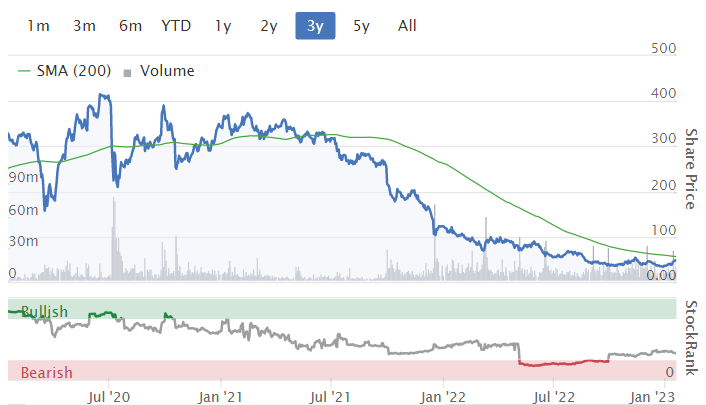
Stockopedia is unimpressed, with a low StockRank of 32.
Horrible chart over the last 3 years, along with sector peers -
Zotefoams (LON:ZTF)
365p (up 3% at 09:00) - mkt cap £175m
This is one of my favourite GARP shares for 2023 and beyond, covered in detail last year - here’s our archive of articles for background (or just click on “Discussion” tab of any company’s StockReport to call up discussion of that share).
My last review of ZTF was recently, here on 15 Dec 2022, on a positive, ahead of expectations trading update.
Here’s the latest news today -
19 January 2023 - Zotefoams, a world leader in cellular materials technology, today provides a trading update for the Group's financial year ended 31 December 2022 (unaudited).
Strong performance and record profits
Key points -
Ahead of market expectations (again!) due to a strong finish to the year.
FY 12/2022 revenue £127.4m, up 26% on 2021
(I’m pretty sure the revenue growth is all organic too, as there was no movement in the only £2.3m goodwill on the balance sheet - see note 12 to the 2021 Annual Report. A tiny acquisition in Nov 2022 looks to have been for know-how, not revenue/profit).
Impressive upgrade in profit expectations -
Profit before tax for the year is now expected to be not less than £12.0m (2021: £7.0m), which is ahead of current market expectations and represents a year-on-year increase of over 70%. This record profit figure is net of the segment loss in the MEL Business Unit increasing to £1.9m (2021: £0.7m), which reflects the continued investment in the development of ReZorce packaging technology.
Development of the mono-material ReZorce® packaging is progressing well and is currently a significant focus of the team.
Net debt - no figure provided, but it’s coming down nicely as a multiple of EBITDA, of 1.16x which looks fine. As I’ve mentioned before, the net debt isn’t a problem. It borrowed to finance modernisation of fixed assets, now largely done. Mgt have previously indicated that net debt will fall rapidly from internal cashflows. In any case, it owns the factory freeholds, so the bank has bulletproof security, hence why ZTF is able to borrow cheaply. So debt is a non-issue to me.
Diary date - 21 March 2023.
Broker updates - annoyingly there’s nothing. The company needs to arrange some broker coverage that’s accessible for private investors, I vaguely recall nagging them about this when I spoke to the CEO in late Oct 2022 - audio here, written summary here.
Working the figures out myself, if we assume 20% corp tax (same as in the H1 numbers), then the new guidance of £12.0m PBT becomes £9.6m PAT, divided by 48.6m shares = 19.8p EPS for FY 12/2022. That’s well above the 16.2p consensus forecast shown on the StockReport.
At 365p per share, I get a PER of 18.4x - that’s not cheap, maybe priced about right for now?
Also, to be more prudent, I’m factoring in the big rise in corporation tax, to 25%, so doing that would adjust EPS down to 18.5p EPS, or a PER of 19.7x
My opinion - unchanged, I remain positive on the prospects for this share, longer-term. I think the existing business is doing well, and has demonstrated a strong ability to pass on higher inflation to its customers.
Then there’s the potential excitement of the Re-Zorce blue sky project, in for free.
So I think this share seems a nice each-way bet, although personally I wouldn’t be interested in chasing the price up much higher in the short term, despite the good performance - but that’s up to each individual investor to decide.
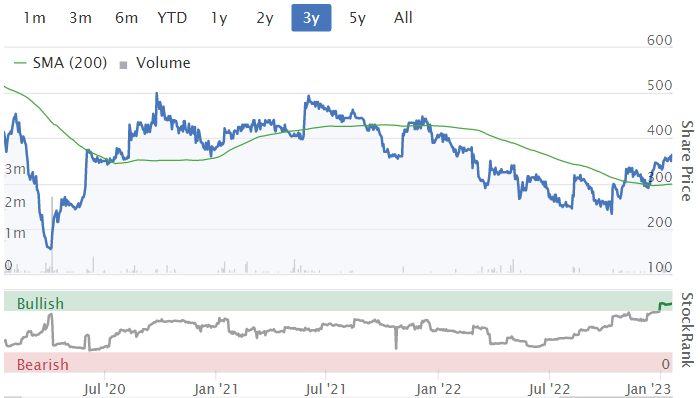
Note how the StockRank has been surging, and is now high -
Graham’s Section:
Judges Scientific (LON:JDG)
Share price: £79.50 (pre-market)
Market cap: £506m
We covered the interim results from this scientific instruments group here.
Today we have a full-year trading update for 2022. It is modestly ahead of expectations.
Key points:
Organic order intake +0.5% year-on-year
At the time of the interim results, this was reported as plus 4%. So there must have been a quite substantial softening in H2 (when measured against 2021’s performance).
Judges says:
Following a solid H1, Organic intake softened in the second half, but picked up strongly in December with the relaxation of China's Covid-19 restrictions.
Also, despite the weak growth in order intake, orders were still running higher than revenues.
This means that the order book increased from 19.8 weeks to 21.1 weeks.
(All of these figures are measured organically, i.e. a fair comparison between 2021 and 2022 after taking into account the acquisitions that took place.)
Speaking of revenues…
Organic revenues +8% year-on-year
Geotek: as anticipated, this large (up to £80m) acquisition hit its earnings targets in 2022, with the result that the sellers will receive the maximum earn-out (this is £35m in cash and shares).
Conclusion:
As a result of the solid Organic performance together with the first-year contribution from Geotek , the Board anticipates that Adjusted earnings per share for 2022 will be modestly ahead of current market expectations.
Estimates: Shore Capital have today increased their adjusted EPS estimates.
FY 2022 EPS increases 5% to 348p, and FY 2023 EPS increases 1% to 355p.
The FY 2023 estimate is held back by expected tax rises and the modest dilution from the Geotek earn-out.
My view
The order intake performance in H2 is clearly not great, but if you trust management (which I tend to do), then the reopening of China means that order intake will be better in 2023.
It has been a challenging year or so and Judges has lost some of its growth momentum, but the underlying fundamentals of the business haven’t changed too much.
One of the great imponderables for me is the long-term quality of Geotek as a business.
Judges have previously said that the addition of this business will reduce the return on invested capital of the group as a whole. We also know that its revenues can be lumpy, and that it relies on a small number of service contracts - how secure are they?
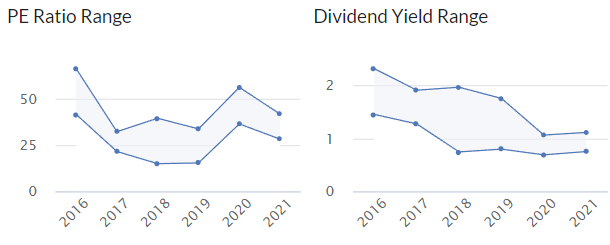
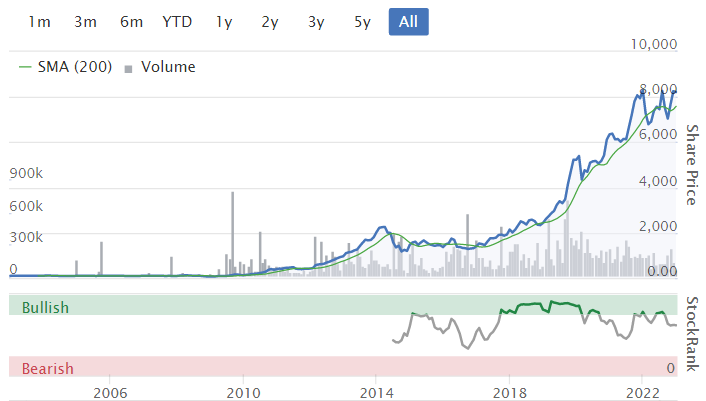
I do remain a fan of Judges as a long-term hold, and I remain optimistic that they will be able to carry out larger acquisitions than they did before, in order to “move the needle”. But for anyone hoping to time a better-than-average entry point, I’m not convinced that this is it:
Frontier Developments (LON:FDEV)
Share price: 521p (+11%)
Market cap: £205m
We covered an awful profit warning from Frontier Developments earlier this month - see here. FY May 2023 estimates for revenue fell from £135m to £100m, and for operating profit fell from £20m to £2m. The market cap swooned from £400m down towards the £200m mark.
Today we get the interim results for the period to November 2022. Key points:
Revenue £57m (previous year: £49m)
Operating profit £7m (previous year: loss £1m)
Net cash £43m (previous year: £34m), after payment of £9m to buy another games studio.
When considering the significant improvement in H1 performance compared to the prior year, remember that F1 Manager 2022 was launched in August 2022, i.e. during H1, and became the studio’s flagship title at that point.
The company also continues to monetise the existing titles Jurrasic World Evolution 2 and Planet Zoo.
Accounting profits were boosted not only by the launch of F1 Manager but also by the reduced amortisation of prior development expenses - this is an important accounting opinion, but it’s not a cash flow.
Trading update and outlook
The precise reason for the profit warning this month was that sales over the key Christmas period (i.e. after the H1 period ended in November) fell below expectations, not just for F1 Manager but for a host of other Frontier titles as well.
I don’t think there’s been any significant change since that last update, but let’s see what wording the company has come up with to describe its current prospects:
The outturn over the five remaining months of this financial year is dependent on a number of variables, including the timing and contribution from the scheduled Foundry releases and the macro-economic environment. The Board believes it is still possible to surpass last year's record revenue performance of £114 million, particularly if one of the upcoming Foundry titles is a conspicuous success. However, given the number of variables and the more challenging economic outlook, the Board have set a minimum expectation of delivering revenue of not less than £100 million in FY23.
This is similar to what they said before. But I note that the FDEV share price is up 10% today, so maybe investors are encouraged by the company’s insistence that revenues could still somehow beat last year’s number, if everything went favourably for them?
As for profitability:
The Board's expectation for revenue for FY23 of £100 million to £114 million, would deliver an IFRS operating profit in the range £2 million to £10 million.
And for FY 2024, the company is looking to achieve revenue growth of 5%, with the help of a new Warhammer game and the next annual edition of F1 Manager.
CEO comment - the CEO talks about improving the F1 game (“more accessible and engaging to a wider audience”), and this is a point that I think investors do need to bear in mind. This year’s release was only the very first in a series, and it’s possible that the sequel could be significantly better. Sequels are sometimes better than the originals!
Furthermore, it should be cheaper for Frontier to develop new editions of this game, as they only need to build on what they’ve already done. For example:
Significant outsource costs were incurred during the development of F1® Manager 2022, mainly during FY22, to deliver the large number of assets required for the twenty-two circuits which featured during the 2022 F1® season. The Group will continue to benefit from this initial investment, as the majority of those assets will be utilised in future F1® Manager titles.
So future editions of the game will in theory be cheaper to develop, and they will be better games that might appeal to more customers. What’s not to like!
My view
I’m torn between taking a neutral stance on this, or taking a more positive stance.
I think that taking a long-term stance on this, at the current market cap, I have to be positive: after all, the enterprise value is now just £160m. You only have to go back to January 2021 to find that this share was valued at £1.3 billion.
And what has changed since then? The first edition of F1 Manager didn’t go as well as hoped, but there will be another one.
The company themselves think that operating profit could be within a £2m - £10m range in FY 2023 - after a disappointing Christmas performance.
In better years, I can see this company earning £10m+, as it did in prior years on a lower revenue base than it currently enjoys.
So in my personal opinion, these shares now look like they could be in value territory.

WAG Payment Solutions (LON:WPS)
Share price: 80p (unchanged)
Market cap: £551m
This share has never been discussed previously on Stockopedia. It was floated by private equity not too long ago - October 2021 - at an offer price of 150p. Sellers were originally looking for 175p.
Here we are less than two years later and the shares are down by about 50%. So according to my IPO rule, we can now start studying it! (My IPO rule states that an IPO stock should not be studied for the first 2-3 years, unless the share price falls by 50%!)
WAG did make it into the FTSE-250 index at first, but it is now in the FTSE Small-Cap Index on the Main Market.
The company is registered in Prague and operates across Europe, providing a range of mobility products for commercial customers - fuel cards, toll boxes, fleet management services, etc.
Let’s see what today’s 2022 trading update has to say:
Total net revenue of at least €189m, up 24% year-on-year.
Organic net revenue, excluding acquisitions, of at least €181m, up 18% year-on-year and in line with guidance.
Acquisition - the company has agreed to buy Polish group Inelo for €306 million.
Inelo also provides fleet management solutions and does so in Poland, Slovenia, Croatia and Serbia. This deal would double the number of trucks connected to WAG’s platform.
I’m surprised to find that WPS is planning to fund this large deal without diluting shareholders, instead using its existing cash resources and bank borrowings. Leverage is going to exceed the top end of its normal targets as a result.
The outlook statement helps us to understand what the company is working towards:
In the year, we expanded our customer base, customer solutions and geographic presence with the new strategic partnership with JITpay, the acquisition of WebEye and the proposed acquisition of Inelo.
Together with the progress we made in developing our own digital capabilities, takes us one step closer to achieving our vision of creating a fully integrated digital end-to-end platform for our customers. Despite the challenging macroeconomic conditions, it is clear that our platform has the potential to transform the CRT industry for the better, and so we enter 2023 with confidence."
My view
I’ll have to stay neutral on this company for now but clearly there is going to be a degree of financial risk in the short-term as it completes the planned acquisition. Perhaps it could be worth studying in more detail in future? I’ll keep an open mind.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

49 comments
Seraphine (LON:BUMP) looks like a big takeover is coming tomorrow at 30p vs current price of 9.8p
https://news.sky.com/story/mat...
Paul, thank you for the interviews. The interview with Sam Bazini was fantastic as I love the companies with founders having substantial holding. Last 5 mins just made me buy the stock :).
According to Sky News Seraphine (LON:BUMP) is being taken private by Mayfair Equity at 30p a share a stonking 206% rise on todays close, well done lucky holders, not me (as long as you are not long term)
Maternitywear chain Seraphine to be taken private at fraction of IPO price | Business News | Sky News
Crikey that’s a bit of f luck I had a punt on these a few months ago at 10p then 9p, Cracked a bit and sold at 9p a few weeks but kept half .
Very nearly bough sone today .
That’s a super cheap deal really for Mayfair equity as this is s not too difficult turnaround .
Anyway it was always a punt.
Think Paul is holding too so we’ll done Paul he was reasonably vocal on this so that’s the Stockopedia subscription paid for .
Oh my word... I had a gamble on these at 7.9p just before Christmas. All thanks to Paul Scott, once he raised that the free float was only 700k of the at the time 5mil market cap, I thought it was worth a punt. Cheers Paul owe you a pint for that one!
Oh my word indeed. I had missed this news completely. Bought some in 2022 at 30p but having read Paul's comment took a punt and increased holding by 450% at 8.5p. Paul's owed lots of pints!
I love these interviews Paul. I’m only at the start of my investing journey but find these and your reports so helpful.
Thanks Dherb! :-)
Today’s £48m placing of shares in Ashstead Technology (AT.), the fast growing subsea technology group, deserves a mention. It is the third placing by its major shareholders since the company’s November 2021 IPO at 162p.
Each placing since the IPO has been done at progressively higher prices - July 2022 @£2.00, November 2022 @£2.60, and January 2023 @ £3.10. The latest placing is bigger than the previous two placings combined and has been done on a 5.8% discount – considerably tighter than previous placings.
The latest placing, just three days after an upbeat end-year trading statement covered by Paul, suggests that the company is building up a solid institutional following. I really hope that it does not mark “the end of the good news”, which can sometimes happen after the major shareholders, who brought a company to market, have taken the bulk of their profits and exited.
£48m placing of shares in Ashtead Technology (AT.)
I pointed to this last night in yesterday's SCVR and interesting to see Simon Thomson doing the same today in the IC recommending investors exploit any weakness. The relatively small discount achieved for such a sizeable bookbuild points to high interest from institutions.
Not a small cap I know but trading update from Dunelm (LON:DNLM) was very positive this morning. Even said PBT would be above market expectations and yet share price down 5%+. It seems across a lot of the retail market above expectation is bad, in line is very bad and below expectations is catastrophic. Does the market really believe the that the market leaders in their respective niches Dunelm (LON:DNLM) andNext (LON:NXT) are going to have a truly disastrous year?
The update from Aew UK Reit (LON:AEWU) is worrying. Their like-for-like property values, in just one quarter alone, was down -10.8%. I have not looked at this REIT before so don't know the composition of their properties, but such a big move in NAV in a quarter is very worrying.
If I was holding any REITs or property backed companies out there, especially those with loans, I'd be doing some intense analysis now, to ensure covenants aren't at risk. At a -10% decrease in valuations, and what is probably the start of the cycle with several more quarterly decreases to come, some REITs are probably facing a ticking time-bomb in terms of their covenants.
The statement today explains all that.
Their bench mark has dropped 14%.
the loan is fixed at 2.9% until 2027.
Soled some assets in the summer and bought cheaper in this quarter.
Pays 8 p dividends this year.
Worth reading.
I plan to add more.
Blimey, the benchmark has dropped -14%...!
Isn't that a steep drop over a quarter, for something like property? This is an area I don't know much about, but it sounds like flashing red alarms?
The CBRE data flagged a steep fall In property valuations in Q4 so this shouldn't have come as a total surprise (although AEWU fell a bit more than I was expecting - not holding fortunately!)
I am not a fan of REITs at all. Yes I like the idea of diversifying property holdings, yes I like the idea you have to pay 90% of your profit as a dividend and yes I like the increased transparency and flexibility. But in the end they are a play on interest rates. We have had years of falling rates and property has done well now it is going the other way. Do they diversify, well at times yes, but at key times they are equities whenyou don't want them to be. So I have never bought one and it would have to be a significant discount to assets to make me. I would rather take the lower liquidity of a property fund and get the diversification.
Camtab.
I disagree with you about Property Funds. I would never invest in one! If there are a lot of investors wanting to sell they can’t suddenly sell property to meet that sell demand so have to lock their investors in, and sometimes for many months too. They are inappropriate for Property imo.
Property Investment Trusts never lock in their investors. . Instead they go to huge discounts to NAV when the sector is out of favour and become bargain buys. Currently there are Commercial Property Trusts trading at nearly 50% discounts to NAV. E.g Tritax EuroBox (LON:EBOX) and £PSDL. I recently bought both of them. And Tritax EuroBox (LON:EBOX) also pays a 7% dividend. If these two were Property Funds, which always trade at NAV their share prices would be nearly double the current Phoenix Spree Deutschland (LON:PSDL) 242p and Tritax EuroBox (LON:EBOX) 65p prices.
I’ve held several Commercial Property Investment Trusts since they crashed in the 2020 covid crash. All of them pay big quarterly dividends and Ediston Property Investment (LON:EPIC) pay theirs monthly. And AEWU dividend at my buy price is 13%.
There's a good reason why plenty of property funds have been closing down. https://www.ftadviser.com/inve...
The main reason for the significant valuation change is the widening in the gilt curve, nothing to do with tenant quality or a change in mix. Certain areas like industrials were being priced all the way up to yields around 3% before the mini budget so naturally have had significant impacts.
There are still a lot of areas with significant value in my opinion - I hold Empiric Student Property (LON:ESP) , Ediston Property Investment (LON:EPIC) and Love Hemp (OFEX:LIFE)
Boohoo (LON:BOO)
Hi Paul
There was no P7-P10 update last year, but they did include these figures in the FY22 Final Results appendices:
https://otp.tools.investis.com...
From that it was interesting to work out a December-only (P10) view of revenues - these made up 11% of FY22's total revenues (see blue cell below.)
---
Another thing I noticed today was that if the company is to hit its FY23 revenue forecast announced today (-12% YOY revenue) then there would be a 25% decline in sales in Jan/Feb 2023 vs last year (P11-P12.)
I'm puzzled as to whether the negative outlook is due to:
Based on what they did in the past I have a feeling it might be more the latter...
Great analysis, thanks abtan! I might have to give you another hat-tip in this weekend's podcast! :-)
Excellent update again from Capital (LON:CAPD) - it is a modest beat against expectations, but in the nature of the business revenue visibility is good so they should anyway not be far adrift of forecast. Stockopedia gives this a forward PER of only 6.6, however, drilling services to miners is a notoriously cyclical business to be in. The trick will be to pick the selling point - at the moment the wind is set very fair for their mining customers. I hold.
Extraordinary output Paul. Very much appreciated, well done to you and Graham.
Morning Paul, just wanted to say what a great interview with Sam from Warpaint London (LON:W7L) . What a nice genuine guy he appears to be. I have been a holder for a few months now, and I believe the business to be in good hands. Thank you for sharing.
Hi Paul,
Thank you, for sharing the interview with Warpaint London (LON:W7L), much appreciated. Excellent insights into management thoughts about the business.
BSV
That's kind, thank you :-)
It was announced last night that Bakkavor (LON:BAKK) are moving from the FTSE SmallCap Index to the FTSE 250 index.
Today, their trading update says ‘Robust growth, performance in line with market expectations and strong balance sheet’.
Revenue exceeded £2bn for the first time, but profits are down year-on-year.
(I hold)
Hi
Luceco (LON:LUCE) the heading of this mornings RNS is ....
2022 full year trading update
Profit at the upper end of guidance - record cash generation
At time of this posting SP up +15%.
Some more extracts from RNS ...
2022 full year results
The Group expects to report full year revenue of c.£206m and Adjusted Operating Profit at the upper end of the previously guided range of £20-22m.
We expect to report pre-IFRS 16 net debt at 31 December 2022 of £24m (30 June 2022: £53.9m), equal to 0.8x Adjusted EBITDA (30 June 2022: 1.4x). This significant deleveraging was driven by record full year free cash flow of c.£30m.
The RNS has more detail here
https://www.investegate.co.uk/...
I interpret the SP rise this morning to relate to a) forward guidance to be towards an upper end, b) net debt reduction, c) Their customer's de-stocking moving to much lower levels, d) strong cash flow growth, e) inflation being less of a headwind and f) issues with China subsiding.
The RNS lists other factors if you are interested.
I hold a baby position but hope to build a larger position over time.
Note, the Group's final results for the year ended 31 December 2022 will be released on 21 March 2023.
Regards
Howard
This is the best update of the day that I have seen - most look pretty awful as one would expect -and follows a fairly calamitous fall in the share price from 500p (today up 25% at 130p) after a number of negative factors, principally wholesaler destocking, increased shipping costs and China concerns - most of its product is shipped from there. The debt build-up was largely caused by the purchase of a small EV infrastructure company and the need to finance inventory as destocking intensified. I am a rather sad holder but I do think it is a decent company and may be worth a look. It gets good returns on capital, has remained profitable and as Howard points out the cash flow and debt repayment have been remarkable.
Hi WDWombat
Thank you for the kind reference.
As I recall from previous updates Luceco (LON:LUCE) are also working to move some of their manufacturing away from China and into Poland. I expect their 25/01 Full Year update will elaborate on this project as well as much more detail.
Also, I noticed a US broadcast last night said EV sales are up 10% world wide, so I am hopeful the EV infrastructure company might make a good contribution as, again if I recall correctly, that purchase was said to be accretive.
Regards
Howard
Sorry to put on here but does anyone know any good European based ETF Bonds in Euros? Trying to find some nice dividend paying corporate bonds paying a regular income for the mother in law who's based in Europe. Something equivalent of a @SMIF would be good
Galliford Try Holdings (LON:GFRD) I had a quick look at this last night as I have heard several people (including fund managers) talking about how the net cash exceeds the market cap - that could obviously make it very attractive, although I came to the same conclusion as Paul that the cash is more than offset by payables so not really theirs. Always best to look at the balance sheet and NTAV to get the overall view of a company's financial position.
Surprisingly good full year update from Headlam (LON:HEAD) I say surprising because my expectations as a holder was for at best in line, if not slightly below.
As it turns out "Revenue and underlying profit before tax for the Period are both expected to be marginally ahead of market expectations ¹ ."
This is a result of good performances from the commercial sector and continental Europe together with cost price inflation and the positive impact of ongoing initiatives such as the revamped trade counter roll out and targeting of underrepresented sectors.
There is also news of an interesting acquisition and appointments. There is a presentation this afternoon on
https://www.investormeetcompan...
Centaur Media (LON:CAU) another portfolio holding had also updated the market. As far as I can make out it is trading in line, but unsurprisingly expresses caution about the year ahead. It finished the year with £16m cash and has unexpectedly declared a special divided of 3p per share, which on last nights closing price of 50p or thereabouts equates to 6% yield
"The Board believes in the long-term fundamentals of Centaur and, given the continued robust performance of the business in FY22 resulting in surplus cash, it is pleased to announce a special dividend of approximately £4.4m, equivalent to 3p per share.
This special dividend is in addition to Centaur's ordinary dividend policy which aims to distribute 40% of adjusted1 earnings after taxation, subject to a minimum aggregate total of 1p per share per year.
The special dividend will be paid on 10 February 2023 to shareholders on the register as at 27 January 2023."
Hi Paul. How do you manage to review so many companies? Awesome
Positive trading update this morning from Paypoint (LON:PAY). For reasons I never understand, this remains under the radar of most PIs.
Morning kuronagi,
Thanks for flagging, PayPoint (LON:PAY) it didn't come up on my initial sweep of the RNS, I'll add it to the list. It seems to just be an in line update, but there's loads of detail in the update. The key bit says -
Whilst the market background remains uncertain, our compelling characteristics of strong cash flow, resilient earnings and growth mean we remain confident of the progress we are making in the transformation of our business and delivering expectations for the year”
Its buying Appreciate I think.
Fwd PER of 9.0, and a expected divi yield of 8.0% do look attractive. Although in the past, I think investors have seen its earnings mostly a legacy business in decline. But it's still pumping out lovely profits & cashflows. Although EPS still below where it was say 5 years ago. So it's not likely to attract a high PER.
If there's time, I'll check it out in more detail, but we're super-busy today.
regards, Paul.
The take-over of Appreciate (LON:APP) should be completed by the end of this financial year so it is said. I hold.
Paul
A couple of more points on Paypoint. As you have noted, the financial numbers look good (low PER, high ROE, high dividend yield etc, high Stockopedia quality ranking). As a retired investment analyst, I also look at the quality of institutional shareholders (excellent - check it out yourself). I also look at the background of the key managers (again excellent - in my view). But one of the interesting aspects of Paypoint is the accumulation of shares by Astericos - a Spanish group. I have dug around without getting much further. This is what I posted on ADVFN last August
I have held PAY since 2019 when I was buying at over 1000p. Purchases since then have bought my average price down. PAY is now the largest of my small cap holdings. I am intrigued that no mention (or almost no mention) is made of the increasing ownership of Astericos Patrimonial. The last RNS showed an increase from 22% to 23%. I have dug around a fair amount but the AP web-site does not shed much light. My assumption is that (like me), AP see a very much undervalued company which is off the radar of small investors (no bad thing).
bend1pa (comment above) talks about the share trades. If, as I suspect, AP are accumulating shares, their brokers will be using small trades.
Look at the other significant shareholders. Several big-hitters. Serious investors.
What are the chances of a bid of around 1000p?
Kuronagi/Sturmey
PS. That was last August. PAY is no longer the largest of my 13 small cap holdings (many held for several years). Largest is now BVXP. 2nd largest is NTQ (micro cap oil services company of which I own over 1%). Note also that Astericos own over 26% of PAY
PayPoint (LON:PAY) is not under the radar on the SCVR, Graham has covered it in detail several times, most recently here: https://www.stockopedia.com/co...
Roger Lawson was (maybe still is) holding it and has written about it on his blog at least twice in the last year. However I recall he said at one point that he didn't fully understand the business.
I bought on 02/11/2022 at 582 feeling very confident about it. Then the takeover bid for Appreciate (LON:APP) was announced and the price fell. For the first time in my life I averaged down at 549. My chart-based trading rules took me out at 527 for a thumping loss. The takeover looks as though it might be stalling. I am tied up now so will look afresh at the whole thing later today.
Edited post:
The approval meeting for the takeover of Appreciate (LON:APP) by PayPoint (LON:PAY) is tomorrow. There could be fireworks because of circumstances which esteemed member Boon discovered and posted here on 10 January: 'Samson Rock has steadily built a 20% stake (in Appreciate)...... I realised that (1) 75% of shareholders need to vote for the takeover to go through, and (2) they have built up a 20% stake now, and (3) very few shareholders have given irrevocable support to Paypoint. Boon discussed several reasons why this might be so but another reason might be that (as some on here have said) holders of Appreciate might think the company is worth more as an independent than the cash bid by Paypoint. Samson Rock are short Paypoint and so are Jupiter. The announcement of the takeover dragged Paypoint's shares down. Quite a lot of moving parts here. My take is that if Paypoint is unable to secure 75% of the votes for the takeover it might decide to increase its offer, which would depress its sp even more, which may be the motive for the shorts.
Meanwhile, I mentioned Roger Lawson's comments on Paypoint - I found the principal one, 27 June 2022, where he wrote: 'You can spend a long time reading this Report without getting a very clear understanding of where the profits came from and their future prospects.'
Thanks for the mention, Michael C!
What are the rules around a takeover? If the Paypoint bid for Appreciate (LON:APP) is rejected in the GM tomorrow, can they immediately come back with a higher bid? Or is there a waiting period?
I was hoping Samson would have forced Paypoint to issue a new offer by now rather then let the vote go through. Because if it doesn't pass - then APP share price will drop, and Samson would be sitting on a big loss (until a higher offer is agreed).
Food for thought.
(I hold Appreciate in the Boon Fund)
Encouraging year end update from Zotefoams (LON:ZTF) (I hold) with 12% upgrade to PBT and revenue for 2022 that hits the 2023 target.
The particularly interesting part is that the company says that it’s development work in new recyclable materials for drinks cups and packaging (in the first instance) ReZorce, is progressing well, and indeed I see they won an award last month from the Institute of Materials, Minerals and Mining for it.
I know we always need to be wary of investing in stories, but this seems to be a well run and innovative company that has a great ‘story’ in there as a potential bonus.
Paul - re LON:SMRT, I think auditors being replaced are required to write a letter, either confirming there are no matters requiring to be drawn to attention of members/creditors or saying what does need to be drawn to their attention. So the former is actually best case.
Yes that's right, I mentioned this in the article. It's good that SMRT's outgoing auditor says there is nothing to draw to shareholders attention. However, in practice outgoing auditors nearly always say this. It's only when something really bad has happened that the auditors write a letter detailing it.
But something has clearly gone wrong, otherwise the auditor wouldn't be walking, or been sacked, right before the year end. That is not a planned move, whatever the company says about putting it out to tender. Something has clearly gone wrong, we just don't know what.
Thanks for highlighting this point, Paul. It smokes!
My morning smallcap tweet: The News Squeeze
Luceco (LON:LUCE) Home Reit (LON:HOME) Aew UK Reit (LON:AEWU) Zotefoams (LON:ZTF) CPPGroup (LON:CPP) Centaur Media (LON:CAU) ReNeuron (LON:RENE) Headlam (LON:HEAD) Capital (LON:CAPD) Judges Scientific (LON:JDG) C4X Discovery Holdings (LON:C4XD) Ilika (LON:IKA), Hotel Chocolat (LON:HOTC), Kier (LON:KIE), Arecor Therapeutics (LON:AREC), Boohoo (LON:BOO), Secure Trust Bank (LON:STB), Gear4music Holdings (LON:G4M), Kooth (LON:KOO), Finsbury Food (LON:FIF)
◄Luceco (LUCE)► guides FY-Dec rev £206m and adj op profit at the upper end of the previously guided range of £20-22m. "We remain appropriately cautious about near-term prospects until the unusually wide range of macroeconomic outcomes for 2023 begins to narrow." [SP=107.1 Cap=171m]
◄Home REIT (HOME)► won't get its audited FY out by end Jan. BDO has requested the provision of substantial data sets across what is a granular portfolio of over 2,400 properties. Appoints a specialist social housing property manager "to accelerate and further support the Investment Adviser's ongoing asset management and monitoring programme". [SP=38.7 Cap=301m]
◄AEW UK REIT (AEWU)► Dec NAV 104.93p/sh, down from 121.88p in Sept. "Following interest rate rises and the unfolding UK macro-economic backdrop, real estate valuations across all market sectors, in particular at the prime end of the industrial and warehousing sector, fell significantly during the quarter." [SP=105.27 Cap=167m]. I hold.
◄Zotefoams (ZTF)► guides FY-Dec rev up 26%, and pretax up 70%, both ahead of market expectations. [SP=352.5 Cap=171m]
◄CPPGroup (CPP)► guide FY-Dec rev(cont) up 19%. EBITDA c.£6.9m, above market expectations. "The Group's change management programme is a complex set of seven inter-dependent projects that is not expected to conclude before the end of the 2025 financial year. Inevitably, given the scale of the changes being implemented, there will be hiccups along the way, which in turn may lead to some adjustment to both targets and deadlines" [SP=112.4 Cap=10m]
◄Centaur Media (CAU)► guides FY-Dec rev £41m+ and adj EBITDA margin above 19.5%. In line? 3.3p special div. [SP=47.25 Cap=69m]
◄ReNeuron (RENE)► restructuring of the business, as expected. "Headcount has been reduced by 40%, the overall variable costs of the business lowered and, as a result, the cash runway now extends into 2024 with all resources being directed towards generating in vivo data and validating the Company's exosome delivery technology platform CustomEX". [SP=9.31 Cap=5m]
◄Headlam (HEAD)► guides FY-Dec rev and U/L pretax marginally ahead of market expectations which are on the co's website. [SP=330.55 Cap=267m]. I hold.
◄Capital (CAPD)► guides rev $290.3m cf guided $280-290m. Profit? Outlook "drilling business has a strong outlook entering 2023 with its highest rig count, robust utilisation and strong ARPOR". [SP=114.95 Cap=218m]
◄Judges Scientific (JDG)► guides FY-Dec rev up 8% organic. Adj EPS modestly ahead of market expectations. [SP=7900 Cap=503m]
◄C4X Discovery (C4XD)► MALT-1 inhibitor programme: demonstrated anti-cancer activity for one of its lead molecules in a preclinical xenograft study. It positions programme for partnering. [SP=16.72 Cap=42m]
◄Ilika (IKA)► H1-Oct rev flat at a miserable £0.2m, pretax loss £5m (£3.5m). You have to scroll a long way to see that. Headline: "Significant advancements for Stereax & Goliath, positioning the Group for commercialisation." [SP=42 Cap=66m]
In line: HOTC, KIE, AREC, BOO, STB, G4M, KOO, FIF
In line trading statement out of Secure Trust Bank (LON:STB) today. I read it as profits in line due to modest outperformance on trading profit minus slightly increased provisions & impairments. I still rate this as the cheapest stock available today. I hold. I suspect that growth has slowed down for now, due to cautious lending and the need to protect margins in an era of rising interest rates v some fixed rates on car loans. For me this is still a stock that I want to hold. Very cheap and a good, well covered, divi. But I'm an amateur investor.
High risk. Great if we avoid a recession, disaster if there is a recession. Loans go bad, wiping out the company.
Boohoo (LON:BOO) ? I see revenue falling, but net margin increasing which probably means end of year showing a very small profit or no profit at all. The company appears to have enough money to weather this storm and it looks like the worst of the storm is over, but surprises happen. I am still slowly buying into this and look forward to the distribution facility in the US opening which changes the proposition there to make it fast, not just fashion. Then further on I would like to see some manufacturing closer to the US market to reduce freight costs further. I would be surprised if this share does anything in the next year maybe two - but who knows, I know I don't.