Small Cap Value Report (Thu 19 Oct 2023) - MSLH, BWY, WTB, GMAA, OBI, OTMP, MCB, RNK, GBG

Good morning, it's Paul & Graham here!
Today's report is now finished.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Summaries
Marshalls (LON:MSLH) - Up 4% to 205p y’day (£520m) - Trading Statement - Paul - AMBER/RED
Q3 2023 update is in line with expectations, but these have been constantly falling. Debt remains a worry, although cost savings and property disposals have helped, plus more efficient management of working capital. Not expecting a recovery any time soon. It's not a bargain based on current forecasts, but could be cheap once an economic recovery kicks in.
Bellway (LON:BWY) - 2104p (£2.5bn) - Preliminary Results - Paul - AMBER/GREEN
I take a quick look below at this mid-cap housebuilder's FY 7/2023, which look quite good in the tough macro circumstances. In particular a staggeringly strong balance sheet gives £1bn of surplus above the market cap - a very cautious valuation. Obviously reservations & order book are well down, so forecasts factor in a big drop in earnings this year. It's difficult to ignore the value here, which allows for a housing market downturn already. Recovery could be in for free, for the patient investor maybe?
Whitbread (LON:WTB) - Not a small cap but… 3366p (£6.4bn) - H1 Results - Paul - GREEN
I had a quick look at the interim results, and was so impressed that I wanted to flag it up to our readers, despite being way above our usual £1bn upper limit! If I spot something good, I'll tell you, regardless of size. Premier Inns looks a goldmine. PER c.16x looks decent value for a business of this quality, also with a rock solid balance sheet with a load of freeholds.
Gama Aviation (LON:GMAA) - Up 69% to 88.5p - Large disposal - Paul - AMBER/GREEN
Yesterday's 69% share price rise caught my eye. It seems to have agreed a stunning disposal value from its US operation, and intends to return over half the increased share price to shareholders. Management who can achieve this value creation look worth backing maybe?
Ondine Biomedical (LON:OBI) -
An interesting-sounding update on its innovative product yesterday, but on closer inspection I discover that this heavy cash burner must be out of cash. I'll look again once it's refinanced.
OnTheMarket (LON:OTMP) (Paul holds) - Recommended takeover bid 110p cash - Paul (I hold)
An excellent outcome here, with a 56% premium agreed bid (more if we ignore the likely insider dealing that has chased up the share price in the last month). The buyer is a US sector giant, so watch out Rightmove (LON:RMV) - your cosy monopoly probably now has a serious challenger!
McBride (LON:MCB) - up 24% to 40.4p (£70m) - Trading update (ahead) - Graham - AMBER/RED
The cost of living crisis sees continued strong demand for private label products, boosting sales and earnings forecasts for McBride. Inflationary pressures persist but perhaps are beginning to cool. I would still take a very cautious approach given the debt position.
Rank (LON:RNK) - up 3% to 79.2p (£371m) - Trading Statement (in line) - Graham - GREEN
The market likes this “in line” statement. Like-for-like revenues are up 11%, beating inflation, including 13% growth at the key Grosvenor casino business. I’m hopeful that the positive momentum can continue - in boom years of the past, this company was incredibly profitable.
GB (LON:GBG) - up 11% to 241p (£608m) - H1 Trading Update [in line] - Paul - AMBER
Shares have reacted strongly to an in line update today. Digging into the detail, I can't get excited about GBG - which looks ex-growth, and isn't generating much cash. Still looks expensive to me, but this type of company is valued much more highly in the USA, so could it be yet another bid target?
Paul's Section:
Marshalls (LON:MSLH)
Up 4% to 205p y’day (£520m) - Trading Statement - Paul - AMBER/RED
Marshalls plc, a leading manufacturer of products for the built environment, provides the following trading update for the nine month period ended 30 September 2023.
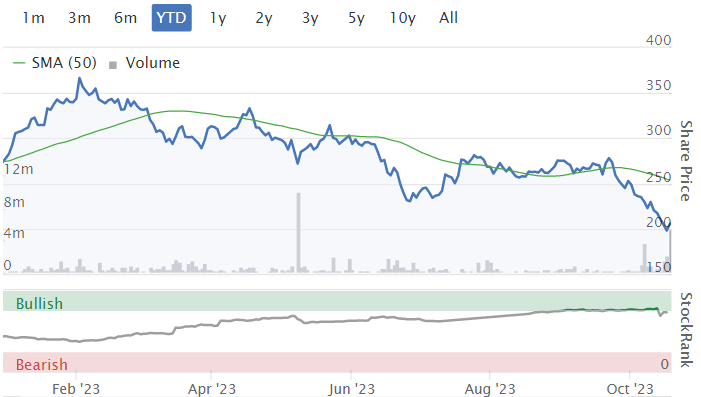
This is a strange one. We covered the series of profit warnings from MSLH a few months ago, and couldn’t understand why the share price had held up so well. That’s changed now, with a steep drop in October, as you can see -
For background, here’s our previous recent coverage -
9/5/2023: AMBER. Profit warning, down 15% to 252p. Softness in some products.
31/7/2023: AMBER. Another profit warning. Down 10% to 248p. Debt an increasing worry.
16/8/2023: AMBER/RED. Down 4% to 247p. Interims - no recovery expected until 2024. Paul - steering clear, more weakness likely, and debt a worry.
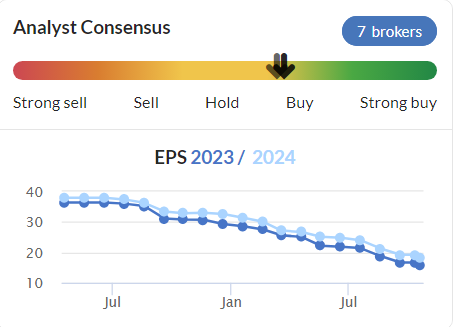
As you can see below, there’s a very poor trend on broker earnings forecasts - a brave decision for anyone to call the bottom here! -
Here’s the latest news -
Marshalls plc, a leading manufacturer of products for the built environment, provides the following trading update for the nine month period ended 30 September 2023.
Full year expectations remain unchanged
As you can see from this table below, LFL (ie. excluding acquisitions) revenue falls have moderated a little from -13% in H1, to -9% in Q3.
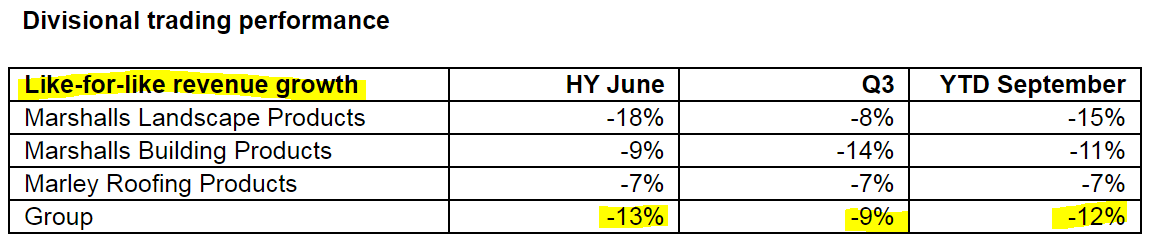
Total revenue (including the acquisition of Marley) is 3% down for the 9-months 2023 vs 2022.
Outlook -
The Board's expectations for the full year remain unchanged.
Trading in the third quarter was in-line with the Board's expectations which anticipated a sustained period of lower volumes. The Board does not expect any material changes in current trading patterns during the fourth quarter of the year and therefore remains confident of achieving a result that is in-line with its expectations for 2023.
I’m not quite sure how this squares with the steady reduction in broker forecasts in the last 3 months? It sounds like this is in line, but with lowered expectations. So not really in line with what previous forecasts were.
As before, we are thwarted by there not being any detailed broker forecasts available.
Cost-cutting - it says this is now largely done, saving £9m annualised.
Capex has also been reduced, and surplus land of £6m sold, with working capital savings also helping to reduce debt.
Says it has spare capacity ready for an upturn in demand.
Net debt - as mentioned before, this is a key issue. Some progress but it’s still not a comfortable position, given the trend of earnings downwards, in my view -
Balance sheet and liquidity
The Group's balance sheet remains robust, with pre-IFRS16 net debt of approximately £190 million at the end of September (September 2022: £222 million; June 2023 £185 million), with the year-on-year reduction reflecting the cash generative nature of the business and management's focus on working capital. The Board's ongoing priority is to reduce leverage and it remains confident of reporting a reduction in net debt at the full year.
The balance sheet is highly dependent on a £250m long-term bank loan, but apart from that it looks OK. I’m not ringing alarm bells on the debt at this stage. In the interim results, it said the adj EBITDA multiple was 1.6x at June 2023. However, if earnings forecasts continue falling, then there could come a point where bank debt & covenants could come more sharply into focus. Management is aware of that though, hence why they’re doing cost cutting, and trying to manage down debt.
Valuation - how do we value it? This is a bad year, due to macro factors. It’s forecast to do about 15p EPS this year, so put that on a PER of say 10x to be safe, and I get to 150p. That’s well below the current price of 205p.
Or we could assume that earnings will recover at some stage, maybe in 2024, who knows? That might see a recovery to 25-35p EPS, say over 2 years? In which case you could possibly value this share on a PER of 12, giving 300-420p, usefully above the current 205p price.
As it’s struggling to deleverage, I would assume the forecast 4.4% yield might be cut, or even passed for a year or two. I don’t like companies with uncomfortably high gearing paying divis.
Paul’s opinion - Marshalls doesn’t grab me particularly. However, like a lot of building supplies companies, everything seems to be lining up for a strong recovery in earnings and share prices, at some point. It’s only really the timing of that, that’s in question.
So I am sorely tempted to start building up some positions in this sector. I doubt whether Marshalls would be one of them though, as there look to be better bargains at the smaller caps end.
Bellway (LON:BWY)
2104p (£2.5bn) - Preliminary Results - Paul - AMBER/GREEN
This national housebuilder reported its FY 7/2023 results earlier this week, 17 Oct 2023.
I’ll keep this brief, as it’s more a mid-cap, but I like to follow housebuilders for general macro and market read-across.
FY 7/2023 figures look OK, considering tough market conditions -
Revenue down 4% to £3.4bn
Underlying PBT down 18% to £533m (impressive 15.6% margin)
Underlying EPS 328.1p = PER only 6.4x - because everyone is expecting future profits to fall of course.
Balance sheet - is stunning! Look at this - current assets of £5,035m, and current liabilities of £1,006! So c.£4bn just in net current assets.
Note there’s a hefty £404m in provisions in L-T creditors - probably to do with cladding remediation, see note 6.
Total NAV, also NTAV is £3.46bn, way above the market cap of £2.5bn. That’s almost a £1bn buffer in case land & work-in-progress need to be written down below cost. In other words, the stock market is pricing in a big drop in house prices. Although that
Outlook - forward sales are much lower than last year, at £1.23bn (1 Oct 2023), down 41% on a year earlier. It’s guiding FY 7/2024 completions of 7,500 homes, way down on 10,945 in FY 7/2023. A “wider than usual range of outcomes are possible”. Reduction in underlying operating profit margin of “at least 600 basis points” in FY 7/2024, so a drop from 16% to 10%. Although that may not necessarily need a write-down below cost for land & inventories, it could just entail lower future profit margins, but it depends on how large the drop in house prices is. It strikes me that inflation, and much higher wages, could do the job for us, without nominal house prices needing to fall much, because real (inflation adjusted) house prices have already fallen substantially.
Paul’s opinion - that bulletproof balance sheet really appeals to me, providing a substantial downside cushion for patient value investors.
Broker consensus earnings forecasts are still falling, so we could see a further deterioration in the profit outlook possibly? It seems to me that the bad macro news has been built into housebuilder share prices for quite a while now, and I think there’s a really good chance of a nice recovery from these levels, if we’re patient. No idea when though.
Whitbread (LON:WTB)
Not a small cap but… 3366p (£6.4bn) - H1 Results - Paul - GREEN
Have a look at this one, I’m just skim-reading the H1 results, which are tremendously impressive. In particular, Premier Inn looks an absolute goldmine - with structural benefits from little branded competition, and declining number of independent hotels. It’s doing big shareholder returns with buybacks. Confident outlook comments. Balance sheet is great, with £3.7bn NTAV, including lots of freeholds, and cash slightly exceeds all its borrowings (bonds). Stockopedia is showing a forward PER of 16.2x, which isn’t cheap, but this strikes me as a very impressive business, a bit like Greggs, but more sensibly priced. As a nice long-term, quality mid cap, I think Whitbread is worth a closer look, hence why I'm flagging it here.
Gama Aviation (LON:GMAA)
Up 69% to 88.5p - Large disposal - Paul - AMBER/GREEN
A remarkable announcement from this minnow aviation services group. It’s not one we’ve followed for quite a few years. It announced yesterday that it’s reached agreement to sell a subsidiary called Jet East for $131m, with net proceeds of c.$100m. If I’m reading this right, GMAA seems to have paid only $11.9m for Jet East in 2021. That seems to be a staggering return in under 3 years.
GMAA says it plans to return 55p+ per share to shareholders.
Paul’s view - nothing firm, as I haven’t done proper research on it. However, I just wanted to flag that this looks a very interesting special situation, worth doing some more work on it, if you have time. A management team that can generate such a great return, could be worth backing. Also, even after the 69% share price rise, it looks as if 62% or more of the current share price is coming back in some form of shareholder payout.
Ondine Biomedical (LON:OBI)
This share spiked up yesterday on a PR-style announcement that its Steriwave photodisinfection is highly effective against antibiotic-resistant bacteria. So I took a quick look at the numbers, and very quickly dismissed any idea of getting involved!
Main problem - cash burn. It had $13.1m at Dec 2022. That burned down to only $4.4m just 6 months later at June 2023. By my rough calculations, that probably means it’s got roughly nothing left by now.
It nonchalantly said in the Interim results (announced 25 Sept 2023) that it’s confident about being able to raise more cash from non-dilutive capital. For a heavily cash burning company that’s out of cash, I’d want more proof of a fundraise having been done, not assurances that they’ll be able to raise the money.
$260m accumulated losses, so this is quite a big project. But only $428k revenues in H1, and a $8.0m H1 loss.
Rather you than me - too risky at this stage, but if it successfully refinances, then I’d be interested in hearing more about the product, which sounds exciting
OnTheMarket (LON:OTMP) (Paul holds)
Recommended takeover bid 110p cash - Paul (I hold)
Excellent news here, with a 56% premium agreed takeover bid. Note that the share price has been inexplicably rising for the last month, so it looks like a bit of insider dealing might have been going on, possibly? It stood out like a sore thumb, when everything else has been falling every day, something going in the opposite direction for no apparent reason does catch your eye.
The 6 largest shareholders (including Harwood, Downing, Schroders, Herald), well-known institutions active in small caps, have all indicated support for the deal, so 29.5% is in the bag. I think it’s likely to go ahead, unless someone else gatecrashes the party with a higher offer.
The bidder is Nasdaq-listed CoStar, an online real estate company in the US, valued at an extraordinary £27bn (fwd PER of 57x), so I can why such a highly rated US company sees OTMP as a bargain.
Paul’s opinion - this looks a fair price, so I’ll be happy to sell my smallish position (I sold half of it a few weeks ago, doh! Never mind, half a win is still a win!).
I’ve been active in UK small caps for 25 years now, and I cannot ever remember another time when there’s been such a boom in takeover bids, yet market sentiment has been so bombed out. It’s usually the opposite! Another reason to be bullish about UK small caps - it’s not just commentators like me constantly saying small caps are oversold, this is being confirmed as correct from almost daily takeover bid announcements in small and mid caps.
Every takeover bid also injects fresh liquidity into this sick market, which helps the recovery process - since institutions get a liquidity event which enables them to cash out and pay their client redemptions, and a takeover bid also improves their funds’ performance figures. Whilst private investors receive a fresh pot of cash to deploy buying other bombed out, oversold small caps. Sooner or later, this is all going to set off another bull market. Remember also there’s a wall of money in cash savings, where the cautious have (sensibly!) parked their money to protect capital. Sooner or later at least some of those funds will be coming back into small caps, once FOMO kicks in, I reckon! As always, no idea when the bullish scenario plays out, but I strongly feel we’re not far from the bottom now. Especially as sentiment is so bad - could we be near capitulation? I reckon so, yes.
Note that the brilliant Christopher Mills of Harwood has been raving about how cheap OTMP was on several interviews this year, saying he simply couldn't understand the absurdly low valuation. He's always worth listening to, as an active manager who gets things done behind the scenes, and with a lifetime of experience building value for his fund. I don't like him having a dominant shareholding though, as small shareholders are sometimes disadvantaged in deals by the big boys.
Anyway, happy days, this deal has only boosted my portfolio by about 1%, but in current markets, I'll happily take that with grateful thanks!
EDIT - I see that sector dominator Rightmove (LON:RMV) is down 12% this morning to 506p - probably due to investor worry that suddenly an also-ran small competitor looks likely to transmogrify into a potentially well-funded competitor with a new £27bn market cap owner. What if OTMP's new owner decides to abolish fees to agents altogether (OTMP doesn't charge much to begin with), and does a massive advertising campaign? It's possible that Rightmove's network effect could be seriously damaged, or even destroyed with a determined & very well-funded competitor. Unlikely maybe, but a lot more possible after today.
GB (LON:GBG)
Up 11% to 241p (£608m) - H1 Trading Update [in line] - Paul - AMBER
GBG, (AIM: GBG) the experts in digital location, identity verification and fraud software, provides an update on its performance for the six months to 30 September 2023.
Revenue is flattish at £132.4m, and adj operating profit (excluding last year’s forex gain) is up 7% to £23.4m, achieved it sounds from cost-cutting.
It mentions a decline in revenues from cryptocurrency customers. Since I take a dim view of “cryptocurrencies” (aka a giant speculative bubble), then this makes me a little wary.
Outlook - doesn’t sound like a growth company, does it? Although in line is reassuring -
The ongoing focus on simplicity and efficiency underpins the Board's confidence that GBG will deliver its FY24 profit expectations.
Broker forecasts have been steadily declining -
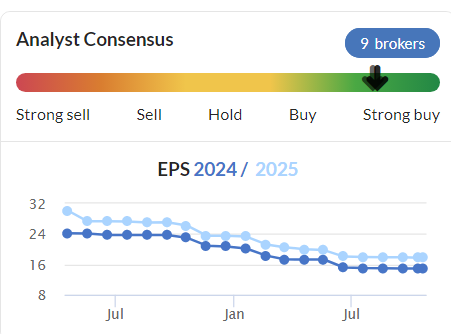
Balance sheet - I’ve had a look at the last one, Mar 2023, and I don’t like it.
NAV of £694m includes £851m intangible assets, after a huge acquisition splurge of £460m in FY 3/2022 alone. So NTAV was £(157)m, or if we’re being kind and deleting deferred tax, then it’s £(122)m.
Net debt sounds high at £105m (hardly changed from Mar 2023 to Sep 2023).
Does that matter though, given that it’s an asset light business model, and highly profitable? Maybe not, that’s your call. I prefer at least some asset backing, and net cash, preferably, but if a great business has a weaker balance sheet, it’s not necessarily a deal-breaker.
Cash generation - is not very good for a company valued at £608m.
I’ve looked back at the last 2 years accounts, and post-cash cash generation was £34m in FY 3/2023, and £45m the year before. Of that, finance costs consumed £6.4m in FY 3/2023, due to increased debt. There’s another £2.1m in lease costs to come off as well. So I make that only about £26m of genuine cashflow last year. This is why the dividend yield is only c.2%, because there’s considerable debt, and not a huge amount of cash generation.
Paul’s opinion - I was hoping to find an oversold, exciting growth company here. But it all looks a bit flat, so I’m not quite sure what the buyers today who’ve taken it up 11% are seeing? Maybe they’re still anchoring to the excessive bull market perception & valuation of this share? Hoping for a return to the glory multi-bagging days of yore -
.
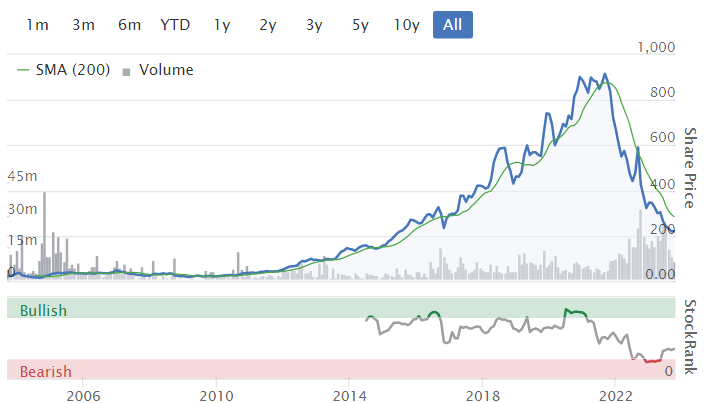
The StockReport here is showing a forward PER of 13.2x which does look quite attractive, although adjusting for the debt would probably take that up to something like 15-16x, less interesting.
The key question is where’s the growth going to come from? Paul Hill mentioned this stock recently on Mello, and made some good points about an increased need for fraud prevention & detection, since AI could clone our voices, etc, to hack into our bank accounts.
There are no broker notes available, which frustrates my wish to drill down more into the forecast numbers.
So based on what I’ve seen, I can’t see any reason to get involved here. Big write-offs last year suggest it overpaid for some of the acquisitions.
I’d like to hear more from the company, so how about they do some webinars, and get some research out to the private investor community? That might help.
I wonder if it might attract a bid from the US? They value companies like this on a much higher multiple, so that’s a possibility.
Graham’s Section:
McBride (LON:MCB)
Share price: 40.4p (+24%)
Market cap: £70m
McBride plc (the "Group"), the leading European manufacturer and supplier of private label and contract manufactured products for the domestic household and professional cleaning and hygiene markets, today provides the following trading update.
This is a highly indebted manufacturer whose shares have been priced as options on its debt load. Net debt was last seen in June 2023 at £166m (a number that includes some lease liabilities).
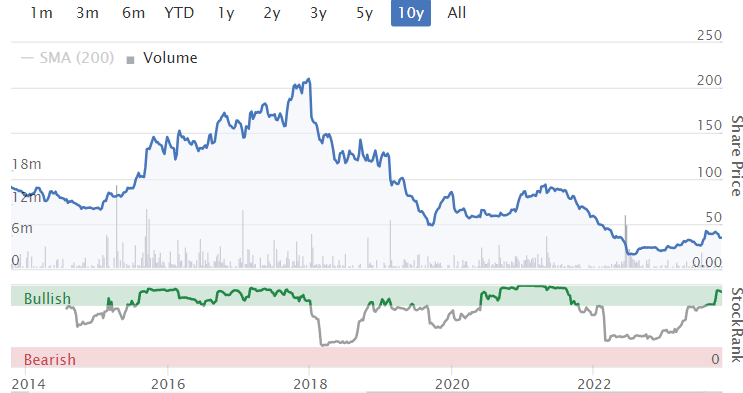
Despite its balance sheet difficulties, it has been trading well enough over the past year to see a significant bounce in equity valuation (though long-term charts paint a different picture!):
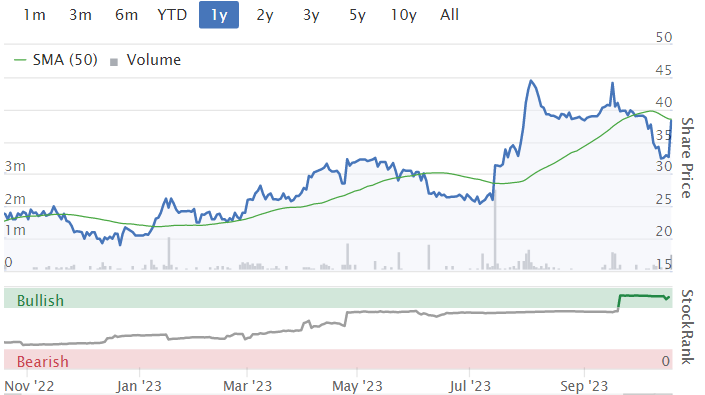
Today’s trading update for Q1 (July to September) has put another rocket under the shares, as it appears to be trading well through this difficult period.
Firstly, the volatile inflationary environment persists:
“While raw material and packaging material costs remain relatively stable, albeit at significantly higher levels than in previous financial years, other costs such as labour, energy and indirect cost inflation continue to be a source of upward cost pressure.”
But…
…the continued effect of increases in the cost of living on consumers has meant that demand levels continue to be driven by a shift towards private label products across all markets and as a result, the favourable trading environment and momentum of the second half of FY23 has continued into the first quarter of FY24.
The result:
Q1 volumes up 8% year-on-year
An additional £8m of EBITA, compared to internal forecasts.
Unfortunately, McBride’s internal forecasts go unmentioned in the RNS, and there is no recent broker research available on Research Tree. This is a Main Market listed company, so it doesn’t have a Nomad. Its joint corporate brokers are Investec and Peel Hunt, whose research is not widely available.
Graham’s view - feel free to ignore my view on McBride, as I wrote negatively about it both in January and in February. The sector didn’t interest me - commoditised cleaning products, and the company was loss-making at the time. Furthermore, the precarious debt situation required a “going concern” warning in the interim results, as the company acknowledged that there was a plausible scenario in which it would breach its banking covenants.
Given those facts again in the future, I would probably again take a negative stance!
However, McBride’s earnings forecasts have been trending higher in recent months:
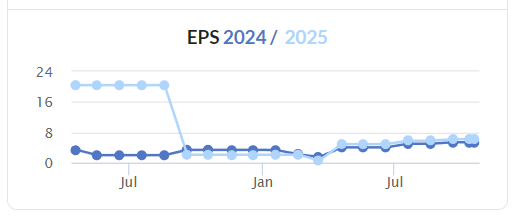
Checking the recently published full-year results for FY June 2023, I see that there was an adjusted operating profit of £13.5m, and an actual operating profit of £10.3m.
Out of those numbers, the company paid £11m of interest, plus very large exceptional costs and refinancing costs. Even excluding the exceptional items, therefore, the adjusted PBT was only around breakeven.
However, FY June 2024 was forecast to show a significant improvement on that performance, and it has just been significantly upgraded. Remember that revenues are running at over £900m p.a., so small changes in revenues and costs can have an enormous percentage impact on the bottom line.
Paul took an “AMBER/RED” stance on this one in July, and I tend to agree - it has done enough to survive for now, and hopefully it can deleverage in the current year. I still don’t view it as a high-quality business, and I still wouldn’t want to own it personally. But hopefully it can pull through for its shareholders.
Here is the long-term chart. Only recent buyers will be feeling very happy about its progress:
Paul adds: Very interesting, thanks Graham! I'm a little more enthused by today's update. £8m extra EBITA in just a quarter, is a big number when annualised, which you allude to. I think the speculative/precarious bull case just got a lot stronger. So for me, it's maybe even an AMBER now, but I can see why you're sticking at AMBER/RED due to balance sheet concerns remaining. Although I suspect dilution risk would now be a lot lower, as the bank will be able to see significant improvement in profit & hopefully cash generation. Could be a recovery bounce type of trade now? Not something I'd want as a long-term investment though. But I think risk:reward has just improved quite a lot.
Rank (LON:RNK)
Share price: 79.2p (+3%)
Market cap: £371m
Rank owns Grosvenor Casinos, Mecca and Enracha (in Spain) bingo halls, and a range of gambling websites.
I tentatively turned positive on it in August, thinking that the worst was probably behind it. It has had a torrid few years due to inflationary costs, fewer high net worth tourists, etc.
This Q1 (July to September) update is in line with expectations, but the market seems relieved.
Here is the table for like-for-like net gaming revenue (LFL NGR):
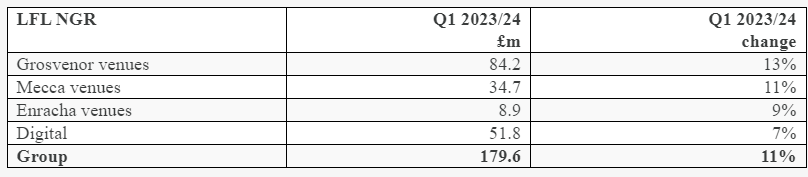
It’s great to see like-for-like revenues growing ahead of inflation. At Grosvenor, 13% growth has been driven by sites outside of London. Total site visits are up 9%, with a 4% increase in spend per visit.
Outlook:
The trading environment continues to be challenging with continuing high inflation and interest rates and consumer discretionary expenditure remaining under pressure. However, following a positive performance across our businesses in Q1, we are on track to deliver 2023/24 full year revenue and profit growth in line with expectations.
CEO comment: mentions that Rank is preparing for the “critical modernising reforms in the Government's review of the gambling legislation”. You can read more about possible changes here and here - they include slightly tighter rules around age verification checks in premises, and financial vulnerability checks for customers.
Graham’s view
I have no reason to change my view on this one. Results here are highly variable but in the good years pre-Covid it generated £30m+ of net income p.a. (and in the boom years, much more than that). I am happy to keep my positive stance given its low net debt, improving revenue trend and (hopefully) cooling inflationary cost pressures.
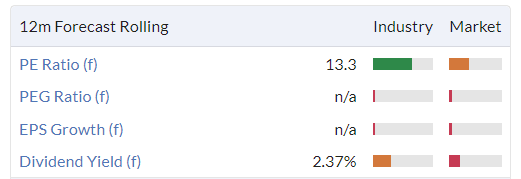
Even based on the current expected rate of profitability, it’s not overly expensive:
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

71 comments
https://breakingthenews.net/Ar...
Trading incident
Everything stuck in reverse maybe?
Anyone have experience trading Mountview Estates P.L.C. (LON:MTVW) ?
Was having a play around to see what sort of spreads within the bid-ask I could get.
IG : "market is currently unavailable to trade online". Cannot get a quote
AJ Bell: same message
What is going on? I've bought numerous small caps, some below £10m market cap, and this is the first time I've encountered that there is no live online quote from either online broker! I knew that MTVW is highly illiquid but would still expect some online quote for a £300m+ market cap. I even tried quantities as low as £1000!
Can't do any UK trades on IG, all are telephone only.
System is down.
Was it, I thought it was just the UK markets.
What a depressing market! However there is a positive. I've worked out I'd lose less money if I went out and bought a brand new car than invested the money in AIM stocks, and the car would be much more fun.
why not both? ;-)
I am!
Totally agree.I refuse to look at any red in my long term holds and after any purchases anymore!Hold/buy and forget if i like the company (unless something majorly changes like a going concern-although trying to avoid/filter out any debt laden companies).And keep the faith like Paul that when looking back in a few years time, i'll be glad i stuck the course.
In my software engineering days there was a solid rule of thumb that if something didn't work then making it more complicated lessened your likelihood of improving the situation. If Sosandar (LON:SOS) are struggling with their current business then making it a more complicated business does not inspire confidence. Now they have issues of managing and paying for stores, stock distribution, retail staff management, shrinkage....
epo001,
I certainly agree Sosandar (LON:SOS) were extremely unwise to issue an RNS stating that their strategy since inception has completely failed so they are going to try something radically different which they previously rejected.
Well that's how I read it.
yes they seem to be clutching at straws here re Sosandar (LON:SOS) , either they cannot struggle or fathom how to make further inroads with an online strategy, or this is a bit more of a vanity project where they want to be seen as having 'made it' by being seen on some high streets.
there is a lot to be said about omni, for click and collect, returns etc, but this certainly comes across as a desperate attempt to pivot their strategy, and the sell off suggests a lack of faith in the management to deliver.
I thought I'd give a shout out to Rentokil Initial (LON:RTO) , seeings as no-one has mentioned it today. Down 15% today to 508p. Ouch. BUZZ-UK picks up the news:
"Rentokil flags "softer consumer demand environment in North America ... that the region's full year performance is anticipated to be marginally below our previous expectations"
And down we go.
Actually, those BUZZ-UK articles that you can see in Stockopedia's company feed are useful. They provide a useful explanation without have do dive through all the documentation.
Let's have a quick shufty ... interest cover of 5.85 looks OK, but they have net debt of £3247m. TTM net profit is £293m. I only like investing in companies where net debt is less than 5X net profit. So this would rule it out for me as being too risky. Rolling PE is 23, which is punchy to say the least. Their operating profits are actually down over 2017. If I assume a FCFps of 21p (according to TTM) figures, and a share price of 502p, that gives a FCF yield of 4.2%. I don't see anything to excite me here.
Funnily enough, I was chatting with a guy on Twitter about RTO just the other day. I had an anecdote about RTO going back many years, probably more than a decade or two. I think it was with a small piece of correspondence I had with a trust, if I recall correctly, called Personal Assets Trust (LON:PNL) . At the time at least it was an old-school Scottish trust, if that helps conjures up an image.
They ran a concentrated portfolio of high quality growth companies. I pointed out to them that the company had negative net tangible asset and were quite acquisitive. I got a letter back (thanks for that!) saying that they were happy holding the company, and weren't going to change their position.
RTO is falter at some stage, so I felt vindicated in my concerns. I do note, though, that RTO has gone from 111p to 508p over a 20-year period, which is a repsectable performance. That's about 8%pa. Its dividend yield today is about 1.5%. I don't think it has ever been a big dividend payer, so let's say the total return has been about 9.5%pa. Pretty respectable, actually.
That still doesn't make it a "buy" in my books. I just thought folks would be interested in a bit of a story.
Yes, I'm also gobsmacked by the multiples that Rentokil Initial (LON:RTO) trades on, for a business that is very simple (fleet of vans and people all hunting or killing insects for businesses).
One would think the valuation would be much lower, given the maturity of this sector.
However, I will leave this tantalising bit of information. As our planet gets warmer, it becomes more conducive for bug infestations. Therefore there will be ever growing need for bug killers. So if you believe this macro tailwind, then potentially the valuation of RTO is palatable. And the debt becomes less of an issue, if there is solid growth momentum and they grow their way out of it.
These been a keeper for me over 7 years in that time despite a few ups and downs over all up 214+%, about 17% in last year - bedbugs coming feel still a keeper?
Rentokil Initial (LON:RTO)
Hi Mark
Thanks for bringing this up
This company was actually on my radar until about 18 months ago when a huge merger with Terminix was announced.
I believe the deal went through 12 months ago.
I haven't checked today's update, but I wonder if some of the figures you're looking at (well, TTM net profit) is accurate for the comparison with net debt that you're trying to make?
As a side note I've seen a Rentokil-style business in action and they charged a fortune for very quick and little work.
The sad thing is that they can charge whatever they like and get away with it, especially when it comes to hostels/hotels who are desperate to stop pests spreading. The valuation is punchy - even after today's fall - but perhaps it's justified?
I have a reminder to take a closer look in 2024, when I believe comparative numbers will look cleaner after last year's merger.
Cheers
A
Hi Graham,
On McBride I understand that EBITDA will be higher than its current market cap!
Management expected this to be around £45m (according to Peel Hunt estimates) , and with an increase of £8m in the first 3 months then this will easily be around £70m. Debt is gradually coming down as the revenues will be close to £1B.
I don’t think it’s a RED at all.
Thanks
Hi yiannos1,
Graham's not RED, he's AMBER/RED on McBride (LON:MCB) - which is saying that it's OK, but with some concerns (over excessive debt).
As I noted above in my "Paul adds..." bit, I can see a more positive angle on this, and today's update certainly improves the bull case considerably. So I'm leaning towards straightforward AMBER. Or maybe even slightly positive, as a trade for a recovery?
So overall, I think you could be right on this one. Looks like risk is receding, and the upside beginning to work. Fingers crossed!
Paul.
This is an interesting development at McBride (LON:MCB) as it suggests they're getting into the safer zone of their covenant tests. These had been holiday-ed to Sep24, but my last calcs were that they were awfully close to their Net Debt and net Interest Cover covenants.
I calculate H2-23 adj EBITDA at like £25m, so presuming management internal forecasts were already higher than this (say £30m for H1) then we're looking at maybe c£45m EBITDA for H1 and £90m for full year? This compares quite favourably to their £167m net debt, as it means they can comfortably be below 2x NetDebt/EBITDA by the time covenant tests resume. Maybe even at 1.6-1.7x.
The big downside risk, of course, is that they don't have lasting pricing power. They do now because Supply has yet to catch up to Demand in private label, so they're able to command pricing power in negotiations with supermarkets, pharmacies, etc. But this is temporary. Once supply catches up, they could struggle again.
I sold out last month at 39p, and the shares have drifted down since then, and even with today's +20% spike is back around 39p. I don't see a particular rush to get back in, but will be spending some time next week to re-analyse whether to get back in.
EV/EBITDA by this time next year could be like <2-3x which is an interesting prospect.
McBride (LON:MCB)
I think this share probably firmly deserves to be amder/red - if we take the viewpoint that these flags are useful for those less experienmced investors then on basic look at the balance sheet and the current profit levels this looks like a complete basket case - note thats not to say the company wont do well or trade its way out of the debt issue - i just think the debt / other liabilities are so large that its a risky play. I wont argeue with anyone who says future cashflow will be great and things will be better so i am not saying this isnta great investment.
If we look at expected annual profits per stocky figures show £11 profit per year.
At 30/6/2023 net debt was £164 million and in addition to this current trade and othe payables was £220 million.
Looking at the past since 2018 this company has not delivered more than £15 mill net profit per stocky figures.
i know its about the future not the past but this company to me looks like it has alor of work to do to ensure its not eitehr in hoc to its finance providers and aldo in hok to the "payables" peeps that are currently happy enough to provide them "credit". I think all high risk high reward shares probably should come withn some sort of red rating for this reason even if the prospects are pretty decent ref turnaround.
Payables are balanced by receivables and inventory and as long as the debt is coming down , then this will move higher and higher. I understand the risks , but you are looking at past financial accounts. This is a £1B revenue company now with its own labels.
It’s very rare you come across of a company that its EBITDA is (according to todays RNS) close or even higher than its market cap. Note also that this is not a high CAPEX company (less than £20m).
Thanks
McBride (LON:MCB)
Payables are balanced by receivables and inventory and as long as the debt is coming down , then this will move higher and higher. I understand the risks , but you are looking at past financial accounts. This is a £1B revenue company now with its own labels.
Thats fair comment - but these are items independent of each other to a certain degree. Ie if supplies withdrew credit how would mcbride cope? - you cant normally make customers pay faster and you need inventories to earn your crust - you could use invoice financing (maybe they do already?) but that comes at a cost.
Its not uncommon for this status quo to carry on if suppliers are happy with the situation - just pointing out imho it could be an issue if suppliers ever did get tetchy - this same situation has wiped out many listed company investments that i could reel off if you like.
Note payables exceeds receievables by £70 mill (which is presumably why you had to being invesntories into teh equation) - so they would need to dig into inventories to pay payables even if receivalbles paid up in full. I would be slightly happier if receivables matched payables.
I dont have any particular negative views on this comapnies ability to do well or manage its finances though - i will simply pointing out that from my persepctive amber/ref flags here makes complete sense even if the company has turned the corner for the better and may be undervalued.
Anything can happen in this difficult environment and the continuous rise in US bond yields.
Look at Equals , Billington and On the beach-all good growth companies that beat market estimates BUT all drifted back to where they have been trading prior to these upgrades. This means that the market lacks liquidity and long term investors.
As Paul said ‘fingers crossed’.
I watched the recording (here) of the Sosandar (LON:SOS) results and strategy PI interview yesterday. I was more impressed than I had expected to be.
The executive team felt confident in their new strategy to launch high-street shops. They have done a lot of research, from which these seemed to be the key points (All from memory - please check the presentation):
They seem to have a well researched strategy for the next phase of their growth and to be confident in it.
I'd welcome views from others who have watched the recording.
FREng
Unfortunately the market doesn’t agree with you. Totally disagrees actually.
The shops are just an excuse for another big fundraise!
sos
FREng
I was more impressed than I had expected to be.
i read the update and half watched the investor presentation and i could find zero explanation as to why the the turnover and profit forecasts have been slashed - why would any business throw away 3 million potential profit by pivoting what they do mid year?
Did you see any mention at all that trading had worsened ?- would love to find some aknowledgement from them that things have got worse - or some explanation as to why its all changed so much so quickly. The stuff really looks to me like smoke and mirrors without the transparency of them explaining the diffference between forecasts now and forecasts before yesterday.
In theory if they have plan to get to 10% margin on profits thats great - the finance guy though gave me absolutely zero confidence here that this strategy change was well thought out. Wouldnt say what they are paying in rent - ref payack per store 2-3 years seemeed like he was just chucking out best case scenarious. Why would they not do 12 month trial of 5 stores before going all chips in on tis new strategy?
I am not really taking any viewpoint on whether what theya re doing is right - for sure i dont know better than them - i dont really have a clue whether what tehy are doing makes sense or not. But it seems woeful communication if profits have vanished and sales have dropped off a cliff and they dont fully explain that.
They were askled why the stopped supplying John Lewis (was it?) and their explanation was pitiful.
IMHO they have overnight gone from sound profit making company into something where they think doing things completely different is the way forward whilst in the meantime not making the profits tehy would have done.
If the reality is results will not now match prior expectatiosn ref trading why didnt they clearly communicate that like they were probably obliged to do ?
Thanks FREng, interesting to get your perspective on Sosandar (LON:SOS) change in strategy, and big profit warning yesterday.
I also watched the PIWorld video, and I'm really struggling with this massive change in strategy. Suddenly it's not an online/wholesale business any more, but multi-channel, with them attempting to now open 50 stores, despite not having any experience in managing a retail chain (as far as I know).
Also, I just don't believe that they voluntarily threw away £3m of profit this year, in an attempt to re-educate customers to only pay full price. Why discard a profitable business model? It's more likely that demand has softened I think. Maybe they've made that worse by doing less discount-driven promotion?
So for me, everything's completely up in the air at the moment with SOS. Could it be a good long-term buying opportunity? Quite possibly actually. With the mkt cap now down to only about £30m, with £7m cash in the bank, it's not difficult to see that it might put in a low over the next few weeks.
I'm tempted to add to my (small) position, but have decided to just hold fire for the moment, and ponder risk:reward a bit more.
I think we do need a cooling off period after all Sosandar presentations, because they always tell us that everything is fantastic, and incredible, but there is sometimes no link at all between the narrative, and the numbers! They need to cool it, and make the communications more grown up, and less of a PR blitz.
Regards, Paul.
I'm afraid I sold out as I no longer understand the strategy (and I am not convinced they do either).
Hi FREng,
I have watched the last 'few' Sosandar (LON:SOS) presentations and I thought this one was different in as much that the CFO took most of the Q's, in the past the two CEOs couldn't wait to take a Q. From a body language stance I though they were 'rabbits in the headlights' I dont know how much Tamzim edited this but why did no-one quiz them on H1 24 own website orders being down 20% ? To me this figure which would cover summer party season, wedding season, holiday season etc was all I needed to put me off investing. Even if this figure reflects a rebalancing of sales thru new partners it shows to me there is not enough growth potential.
I thought I might offer a female spin on the presentation, as I am guessing most of the subscribers here are male.
I have two daughters, both in their 30's who fit Sosander's demographic. Both have made multiple purchases from Sosander in the past and I too have made the odd purchase. One says she would much prefer to shop in store before buying and is excited about the prospect of a store opening in Guildford (specifically mentioned in the presentation), the other prefers to order lots on line, try them on at her leisure in her own home and return anything that she doesn't like or doesn't fit. No mention was made in the presentations about returns which I am sure remain high, given that my second daughter ordered about ten items and returned all but 2 recently. This problem would be reduced with in store purchases. With regard to my purchases I have ordered far fewer products, but not made many returns. The product quality I find variable, as the fabrics are not all very pleasant, but sizing is generally fairly consistent, with some high street stores I can vary in size from 10, 12 or 14. The quality of the product is not as good as at Mint Velvet or Hobbs, which were two of the other companies mentioned in the presentation (I'm guessing Hobbs and Ted Baker may be 2 of their 3 comparators as both also sell via Next and M&S).
I was not surprised to hear that their margins were not as good from their own website, as I have never bought anything from there at full price. I have been getting emails virtually every day offering me at least 20% off, I raised this as a question at a previous presentation and the management were very dismissive of my point. I am surprised that people are buying at full price from M&S and Next haven't bothered to check the Sosander website themselves. However, in the last few days I have been receiving emails from Sosander about their party season offerings and these have NOT been offering the same discounts, so this confirms their stated strategy for improving the margin. Whether this will result in a further reduction in sales at their website we will have to wait and see.
I have a small (now even smaller) position in Sosandar (LON:SOS) .
Great insights. Many thanks. I was very surprised to hear about a scaled retail rollout. On the whole I am all for it in a targeted and precise manner.
As for the discounts, totally agree. It has been looking like Joules for far too long.
2 new international deals and I bet more to follow.
I have been adding. They are in a much better position that before.
Paul comment on OTMP "Note that the share price has been inexplicably rising for the last month...." Another share that has been doing this is LON:AVON (I hold). Up 30% in a month on an inline update in an awful market. Busted its 50 day ma big time - not that I'm a chartist. Not bad value either IMO but that can be said of many shares.
Hello Paul,
Regarding Whitbread (LON:WTB), H1 earnings are 146p, so is it reasonable to expect 280/290p full year? Quick glance doesn't look like any weighting to H1. Maybe someone will correct me?
So a forward PE of around 12/13, makes the investment case stronger.
Thanks for flagging!
Hi JohnDoe,
I have a feeling there is an H1 weighting with WTB, so you would need to check that out a bit more carefully. I've just checked actually, and in the 2 years before covid there was a heavy H1 weighting to profits. That seems to be the case for the most recent year, FY 3/2023 - a big profit in H1, then smaller profit in H2.
This seasonality should be taken into account in the broker forecasts. So this looks like a case where your doubling of H1 profits gives you an inflated full year number, so I would stick with the broker estimates here, and the fwd PER of 16.
Regards, Paul.
Thanks, I clearly can't read an income statement properly!
No worries! There's a marvellous feature buried in Stockopedia, where you can look at sequential half years, which I use a lot to check H1/H2 seasonality. Although we have to largely ignore the pandemic period.
Here is the half year analysis for Whitbread (LON:WTB) which I used to quickly check if there is H1:H2 seasonality.
You have to click on the "INTERIM" button near the top, which toggles between "ANNUAL" and "INTERIM". One of those great little buried features!
Interesting potential recovery play at Frontier Developments (LON:FDEV) if, and it's a big if, they hit these new broker forecasts.
Share price is trying to bottom after a horrific fall, joining the 90% club, Starting to look interesting tho, as is the gaming sector I think.
Hi Wolf,
Yes, Team17 (LON:TM17) looking interesting too.
CEO, COO and CFO have taken £11m in remuneration over the last three years at Frontier Developments (LON:FDEV) whilst the SP tanked over 90%!! Need a change of management here.
Thank you Paul I look forward to hearing your views on GB (LON:GBG) .Congratulations on OnTheMarket (LON:OTMP)
Kicking myself on not acting in July on the opportunity.
I don't understand the rise at GB (LON:GBG) . Net debt of £104.8 million, mkt cap £548m. I sold on the rise to 250p earlier.
All that cheap money we had over the last decade when we borrowed and spent like crazy!
Does this data include mortgages? If so I would have thought it's perfectly normal that debt levels are so high.
There is no real limit in how much money can be created via debt. The problem is the lack of GDP.
Anyone have a similar chart for the creditors. Even debt has a creditor, so who owns this debt?
Tatton Asset Management (LON:TAM) - "Growth rate head-and-shoulders above peers (again)"
AUM grew 8% over H1-24 (to 30 Sep 23) from £12.7bn to £13.7bn. Net inflows totalled £910m (7% of opening AUM), showing remarkable strength and consistency (H1-23: £907m, H2-23: £887m). This is even more impressive given the difficult economic and market environment which has hurt the growth of most sector peers, with some experiencing substantial outflows. Market and investment performance contributed £100m to AUM over the half-year.
‘Assets under influence’ (AUI), which includes the AUM of 8AM Global Limited (£1.1bn) in which Tatton owns a 50% stake, also grew 7% to £14.8bn. This brings the group within touching distance of its medium-term strategic AUI target of £15bn which it set out to achieve by March 2024.
Over H1-24, 51% of our forecast full-year AUM growth has been achieved (flows ahead, markets weaker) and we have left our forecasts unchanged, as well as our fundamental valuation of 580p, which is 22% above the current share price. We also flag that sector valuations have declined extremely sharply, and there is potential for a significant sector re-rating (see page 3 of report).
New research report with audio summary: https://www.equitydevelopment.co.uk/research/growth-rate-head-and-shoulders-above-peers-again
OnTheMarket (LON:OTMP) the question I ask about this takeover is why did Costar not simply swoop down and buy Rightmove (LON:RMV? Less upside for less risk perhaps, but far more accretive to earnings, and in a comparable monopolistic position to that which it enjoys in the US.
GB (LON:GBG) Trading Update out today and SP up 13% in early trades. I hold. I would welcome opinions from holders.
I spotted the move up on a TU for GB (LON:GBG) so will try to take a look at that one, which was on my radar anyway after big falls from a previous growth co star.
Inflation’s not the only squeeze on your pocket
If your finances are feeling a little tight, it is because they are. You are losing purchasing power to inflation of course – although less now that, for the first time in a long time, wages are rising slightly faster than prices.
But that’s nothing compared to what you are losing to an extraordinary rise in the UK tax burden.
Today’s September inflation figure would, under normal circumstances, have been used to uprate all income tax bands in most of the UK (Scotland dances to its own high tax tune). But this year, as for some years past and for some years to come, that isn’t happening. Instead, all bands are frozen until at least April 2028, under current plans.
The results are eyewatering. If the personal allowance had not been frozen since 2021, it would be set to rise to £15,225 in April. It will instead remain stuck at £12,570. The higher rate tax band would start at £60,886 (using numbers from investment platform AJ Bell). Instead it will be £50,270.
https://www.bloomberg.com/news/newsletters/2023-10-18/tax-inflation-is-squeezing-uk-consumers-too
1.2 trillion spent, income 1 trillion. Like everything, we have to pay - sooner or later. Now we are paying. I was in a room, not too long ago, and everyone was debating the economic situation. I asked - why not have zero debt? Personally, that's what I want - but our governments and by proxy, our populations want free stuff and our politicians give us what we want every election and the debt gets bigger. We - collectively - are getting what we wanted, we didn't consider the downside.
Hargreaves Lansdown (LON:HL.) update out. Flight to cash continues:
"Clients are looking to invest more in cash than risk-based investments, from our Active Savings offer, giving easy access to a range of banking partners, to Money Market Funds and short-dated bonds. Combining this with informative and relevant content provides our clients with a wide range of solutions to meet their saving and investment needs."
Interestingly AJ Bell (LON:AJB) reported on same day and look better on almost every front (slightly more expensive but think worth it for better growth trajectory)
What am I missing on Hargreaves Lansdown (LON:HL.) ? I hold as think it's a high quality business, great profit margins and increasing revenues - last FY trading update read really well. With the likes of St James's Place (LON:STJ) not being able to charge switching fees any longer I can see more money moving to HL.
Would love the communities view.
HL may have great margins, but compared with AJ Bell and Interactive Investor it has a long way to go. Share commissions far too much, plus regular investment policy very restrictive.. If i was opening an account today I wouldn't go to HL. Website is average.
That's the issue - they will probably keep the clients they've got (as switching is so costly and difficult) but can't see them getting too many new clients. There are other brokers who are a lot more competitive and I expect the likes of AJ Bell and Interactive Investor to continue to take market share.
Perhaps Hargreaves Lansdown (LON:HL.) do better in the corporate space rather than individual investors? When your employer signs you up to their pension scheme, you don't have any choice in the matter. If it's managed by HL, then that's the only option in town! That's why my SIPP is with them.
HL may have great margins, but compared with AJ Bell and Interactive Investor it has a long way to go. Share commissions far too much, plus regular investment policy very restrictive.. If i was opening an account today I wouldn't go to HL. Website is average.
Compared to what? The HL website is no worse than that of other brokers IMO. And the HL Mobile app is far better than AJ Bell's fairly rubbish effort - I use both by the way on a regular basis.
I understand that for a novice investor trading regularly and investing in small amounts, that HL's fees seem high, but personally I don't care whether the commission is £11.95 or free if I'm trading in clumps of £10k. No, what I want is good execution, and over the years I have found that to be the case far more often with HL than with ii and AJ Bell. And anyone including IG Sharedealing in this discussion is having a laugh - they are a total bunch of muppets who are absolutely useless if there's any kind of corporate action for one of your holdings. Even paying dividends correctly is s stretch for them.
New account growth is falling, revenue growth is falling. All very well people moving money into savings, on their site but Hargreaves Lansdown (LON:HL.) HL only make 0.25% on that. If I open a new savings account soon they will me £25, so on £10k,they will make nothing. Their share commissions are too high. I have moved most of my account to IG group (LON:IGG), on US shares it is free but for 0.5% forex fee, on UK shares, it is £3.I am considering opening a Interactive Brokers (NSQ:IBKR) ISA, I will only use HL for things that are not available on IG, such as some European stocks and funds. I have just moved a fair amount out of my share ISA cash into a cash ISA, not on HL, I got 5.8% fixed for 2 years.
Switching is getting easier. Last time only took about 3 weeks, a few years ago it took about 3 months to switch some cash from my HL ISA. I will be moving some money out of HL very soon.
Hargreaves Lansdown (LON:HL.)
Hi Rusty2
2 thoughts on the Active Savings returns:
I'm not sure if this applies to the Active Savings product as well, though I imagine there will be some benefit here from future rate rises.
There have been further Bank of England base rate rises since the June 30th Year End, so I would therefore expect the 0.25% figure you mentioned to have gone up.
(as a side note I calculated Active Savings return for HL as 0.19% for FY23, but perhaps my assumptions were incorrect.)
---
I also noticed that 'Cash Under Administration + Cash in Active Savings' remained relatively flat since year end at £20.9b - it's good to see this cash remain within the HL ecosystem.
Remaining Assets Under Administration increased from £113.1b to £113.9b, and this figure is up 10% since last year - looks good to me.
---
I'm a big fan of this company...but I don't like the material ramp-up in expenditure going on right now. Once that stops, I'll be more interested.
A
Yes better than moving the money away but not as good as share dealing, which was my point. The problem with HL, is you can't move share ISA cash into a cash ISA within HL.
I noticed some of the rates were lower, than you could get with the same providers direct, the differences were significant. The 0.25% is commission from the provider, I understand. They do say "We don't charge you directly, instead we charge our banking partners. This means the same or similar products offered directly by the banks and building societies may have different interest rates to those available on Active Savings."
The money does stay with HL? I thought it went to the provider?
HI Jedi
The short and simple answer is the market doesn't value the revenue on cash. It's high margin - very high. The market would appear to believe these assets will return to funds and equities at lower margin....and/or the margins simply unsustainable...because interest rates fall back towards zero. So in these results today they look propped up by cash and client growth is low esp Vs AJ Bell (LON:AJB) .... furthermore client cash balances have fallen in favour of active cash ( lower margins).... and whilst I agree the figures look ok, there is room to downgrade. Longer term the low PE on Hargreaves Lansdown (LON:HL.) is a bit of an illusion since it earns 200bp cash margin on idle money. It does not make Hargreaves Lansdown (LON:HL.) a bad business and prospects for a special dividend next year will attract attention into the finals.
FCA (apparently) used its "Consumer Duty" rules which include duty to ensure products represent "fair value" to pressure St James Place into removing switching fees. Not everyone is in the FCA's sights, I would guess there had been some complaints which caused the headlights to shine in their direction.
HL are not exactly the cheapest platform (ie for shares not bad but funds pricey) so expect there are some internal discussions going on there.
Personally while it might sound like a good idea, when you really think about it this fair value thing …. To comply a firm must benchmark itself against others in the market - well that’s the exact opposite of what the Competition and Markets Authority expect you to do !!!!. FCA say they don’t intend to stifle competition but if you are bringing a new product to market how do you judge risk / reward ? This should have been worded very differently to prevent market abuse as opposed to fair value.
Also the Consumer Duty is (source – Money Makers - J Davies podcast) making it more difficult for wealth managers to recommend Investment Trusts as (1) fees disclosure is disproportionately showing higher for IT’s and (2) wealth managers getting larger (Investec merger with Rathbones etc) means they have to offer standardised fund lists (so not to be seen to be acting in preference of a category of client which would be breach of Consumer Duty) which means there is pressure on Its to reach 400M size to attract wealth managers clients. Likely to be one of the main reasons for AIM’s poor performance (imho)
Welcome to communism FCA style !
Ref St James - they really were taking the hiss - i would like to think most companies would not levy triple set of fees for adding something into your pesnion - or is it 4 sets? - think i read it was somrthing like 4.5% upfront 0.5% annual - (possible topup fee after 2 years??) and then exit fee if you are not happy and want to leave anytime soon . I know peeps may sign up for something knowing what they are getting but thats a terrible way to show you are honest by screwing them over again if you dont deliver and they want to leave. I would like to think other companies dont act in this manner?
Well done Paul, you 've predicted OnTheMarket (LON:OTMP) take over.
Thanks Mo, I'm untangling my bunting as we speak! I'll be insufferable today LOL :-)
Yes, well done.
No doubt the estate agents will be looking forward to lower fees to list their properties.
Earlier in the week you expanded the colour coding but it is not reflected in the header explanatory notes section or today's picks. Just saying
Congrats to anyone holding OnTheMarket (LON:OTMP)
A pretty decent premium. Bodes well for potentially other takeovers in the UK, from US/CA companies where the valuations here must be pinch-yourself unbelievable compared to their local markets.
My morning smallcap tweet: Brags to riches
OnTheMarket (LON:OTMP) McBride (LON:MCB) Aew UK Reit (LON:AEWU) Hollywood Bowl (LON:BOWL) Mediazest (LON:MDZ) Saietta (LON:SED) Skinbiotherapeutics (LON:SBTX) Oxford Nanopore Technologies (LON:ONT), Gear4music (HOLDINGS) (LON:G4M)
◄OnTheMarket (OTMP)► 110p rec offer, a 56% premium. [SP=68.68 Cap=55m]
◄McBride (MCB)► Q1 vol up 8% and EBITDA c.£8m ahead of internal forecasts. Bemoans cost inflation, as if we weren't aware. [SP=32.84 Cap=57m]
◄AEW UK REIT (AEWU)► NAV at end Sept 106p/sh. NAV total return of 0.91% for the quarter. "Further gains in EPS are expected in the coming quarters as the ongoing programme of new lettings should provide a boost to income streams and a reduction in void costs." [SP=99.6 Cap=158m]
◄Hollywood Bowl (BOWL)► guides FY-Sep rev up 11% and EBITDA ahead of market expectations. Final div at least 7p. [SP=233.5 Cap=401m]
◄MediaZest (MDZ)► guides H2-Sep progress 'as expected'. However "some additional one-off costs associated with ongoing efforts to acquire businesses and expand the Group were incurred...These costs offset the improvement in operational results at a Group level." [SP=0.04 Cap=1m]
◄Saietta (SED)► delayed FY-Mar out, allowing unsuspension. Co "has resolved the frustrating technical accountancy issues around accounting for the post balance sheet event of the new agreements with Consolidated Metco". Outlook - "As Saietta has now secured contracts from a leading OEM, the Board has high confidence that a significant proportion of the material items in our sales pipeline will mature into commercial contracts within the current financial year". [SP=35 Cap=39m]
◄SkinBioTherapeutics (SBTX)► 1 yr extension to the collaboration contract with Sederma "to enable Sederma to complete and assess additional studies on SkinBiotix to investigate previously unseen beneficial properties". [SP=21.99 Cap=38m]
◄Oxford Nanopore Technologies (ONT)► multi-year joint development collaboration with Mayo Clinic to develop new clinical tests for diseases and improve patient care. [SP=190.2 Cap=1577m]
In line: G4M
https://news.sky.com/story/ont...OnTheMarket (LON:OTMP)