Small Cap Value Report (Thu 19 Sept 2024) - SUP, JDG, PMP, SFOR, SOS

Good morning from Paul & Graham!
As expected the USA cut interest rates with a sizeable 0.5% reduction yesterday, which is obviously good for equities (although largely already priced into indices perhaps, as it was widely expected). BBC report here. Where the Fed leads, the Bank of England tends to follow in due course.
"The US central bank has lowered interest rates for the first time in more than four years with a bigger than usual cut.
The Federal Reserve reduced the target for its key lending rate by 0.5 percentage points, to the range of 4.75%-5%."
Lots of bargains around in the UK small caps space after recent weakness, so personally I'm feeling very buoyant about the opportunities all around us in plain sight - so many small caps have sold off as much as 10-20% in recent weeks when there's no fundamental justification for that (tax selling possibly?), so I'm sniffing around for bargains and finding lots of them. I might run a screen on this actually and publish the results.
** Breaking News ** - UK interest rate held at 5.0%
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
** New SCVR summary spreadsheet for calendar 2024 ** This is the live one! (updated 6/9/2024)
Archive - SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia.
Companies Reporting
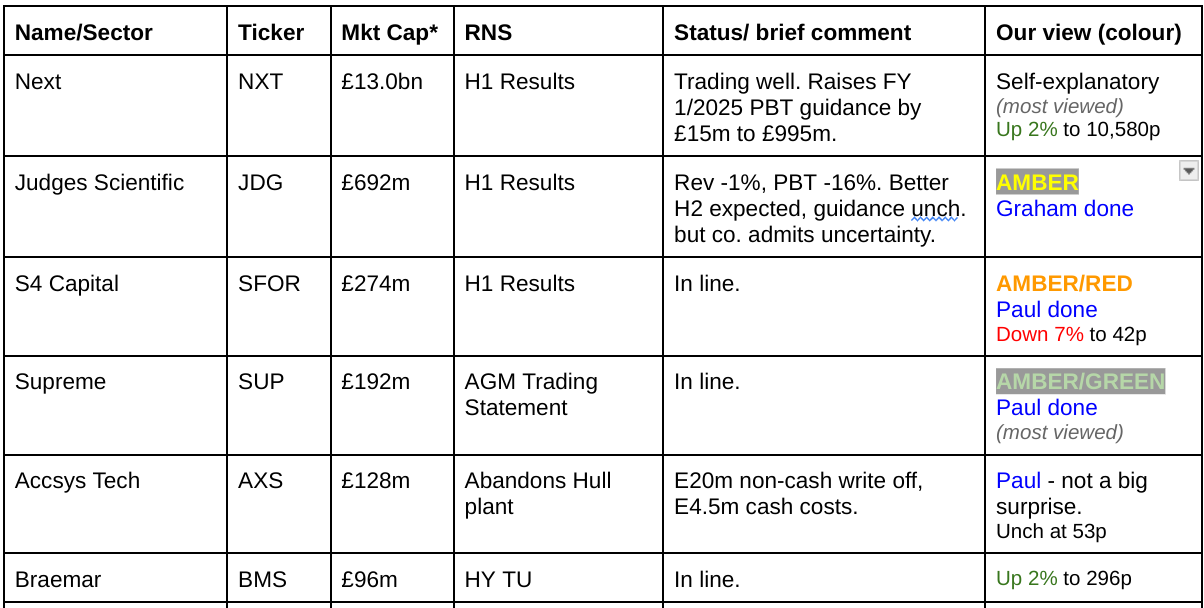
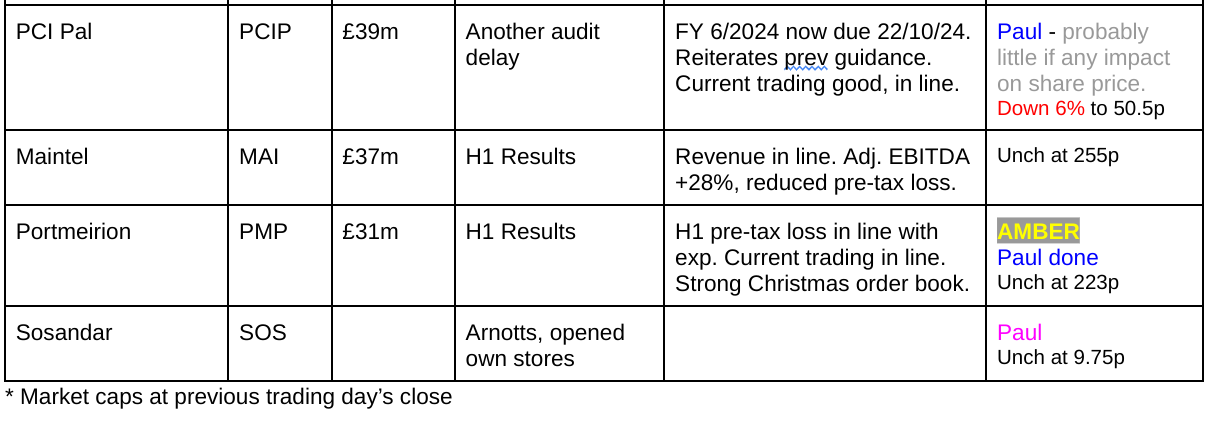
Summaries
Supreme (LON:SUP) - up 1% to 166p (£194m) - Trading Update (AGM) - Paul - AMBER/GREEN
I attempt to point out bull & bear points, let's hope it doesn't trigger people like this share usually does! In line update today, resulting in attractive value metrics, but that's because two-thirds of the EBITDA comes from vaping products. Good balance sheet, and more acquisitions in the pipeline. Overall I'll stick at a moderately positive view.
Judges Scientific (LON:JDG) - down 2.5% to £100.38 (£667m) - Interim Results - Graham - AMBER
Guidance is unchanged for a very strong H2 and a full-year adjusted PBT figure of £30m+, although a late profit warning remains very possible. I’m neutral on this for the same reasons as before: a high valuation (remember to take the debt level into account here), the absence of organic growth and my uncertainty around whether or not the company can continue to find meaningful, high-quality acquisition targets.
Portmeirion (LON:PMP) - unch 223p (£31m) - Interim Results - Paul - AMBER
A weak H1, as previously warned, due to problems in the important S.Korean market. Reassured on outlook, but I question if the forecasts are achievable - this share has a feint whiff of another profit warning gestating in my view. Balance sheet concern re over-stocking, but bank position now much improved, and going concern warnings have gone. So I reflect the reduced risk with a move up from amber/red to AMBER.
S4 Capital (LON:SFOR) - down 6% to 42.2p (£260m) - Interim Results - Paul - AMBER/RED
Hopes for a recovery here have been dashed by poor H1 results, with revenues declining and cost-cutting being necessary to keep things on an even keel. Awful balance sheet, and no signs of a trading recovery. Outlook sounds wobbly, and relies on a heavy H2 weighting to be in line with FY exps. Why get involved? It doesn't look a good business at all, but who knows it might recover at some stage maybe?
Sosandar (LON:SOS) - up 3% to 10.0p (£25m) - Launched in Arnotts, and 2 own stores - Paul - AMBER
Precious little information in an update saying the first 2 standalone Sosandar shops have opened.
Paul’s Section:
Sosandar (LON:SOS)
Up 3% to 10.0p (£25m) - Launched in Arnotts, and 2 own stores - Paul - AMBER
Sosandar plc (AIM: SOS), one of the fastest growing fashion brands in the UK, creating quality, trend-led products for women of all ages, is pleased to announce that it has launched in-store with Arnotts, the oldest and largest department store in Ireland.
Googling it (it’s been years since I visited Dublin), Arnotts is said to be the largest & most famous dept store in Dublin. So it’s nice that it will stock Sosandar goods (which are already on its website), but that’s not likely to move the overall dial much for SOS’s financial results.
More importantly I think, SOS has now opened two of its own, standalone shops, in Chelmsford & Marlow. I was expecting SOS to say that the new store openings have been a huge success (which might stimulate a surge in share price maybe?), but we’re not given any detail today other than a generic “fantastic”, which I would expect them to say regardless of how much money the stores have taken -
“The reception since opening has been nothing short of fantastic and we are grateful to the people of Chelmsford and Marlow for giving us such a wonderfully warm welcome.”
I tried to find a picture that is not subject to copyright, hopefully this is OK, published by Sosandar on its Facebook page -
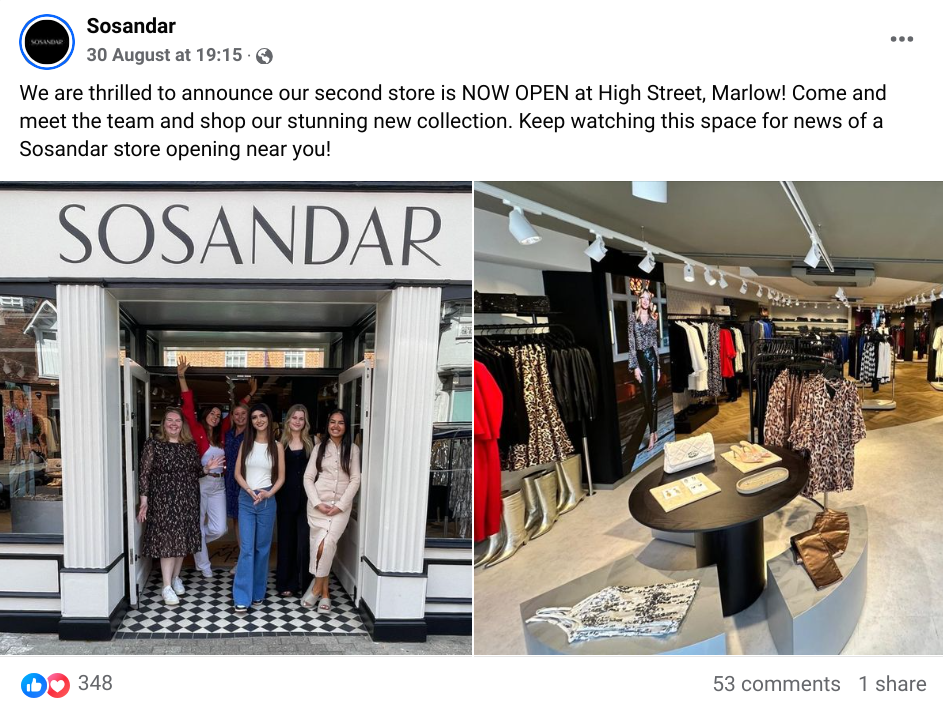
Paul’s opinion - we need some figures on how the new stores are trading, maybe it’s too early to say?
I feel the change of business model to be operating its own physical stores is a surprising development, but am open-minded about whether it’s likely to work or not? The advantage SOS has is that it knows exactly where existing online customers live, so can target shops in areas that are full of their customers already.
SOS is well financed, with a strong balance sheet, so it can afford to trial a few shops and see if it works or not.
For now, the jury is out I think, so it’s got to be AMBER as we await developments and trading updates.
Originally SOS floated at 15.1p, so it's not been great so far, but not a disaster either -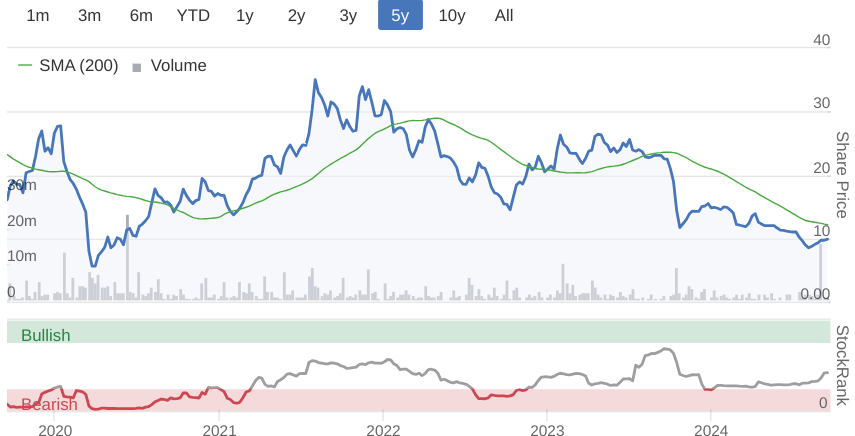
S4 Capital (LON:SFOR)
Down 6% to 42.2p (£260m) - Interim Results - Paul - AMBER/RED
This is another one I don’t rate. My previous notes had it at AMBER/RED twice this year, 27/3/2024, and 10/5/2024. The main things I don’t like are -
Sir Martin’s dash for growth means he probably overpaid for multiple acquisitions.
Multiple profit warnings in 2023.
Soft outlook comments this year.
Tech clients reducing spending on digital advertising (is AI sucking in the cash instead I wonder?)
Incomprehensible accounts relying on huge adjustments to produce possibly artificial profits.
Excessive debt, although long maturity so no immediate liquidity issues.
Weak balance sheet once intangibles written off.
Crazy share structure, with Sir Martin’s golden B share giving him total personal control (very bad practice).
Takeover/deal approaches came to nothing.
Not very appealing is it?! What about upside? That could come from a recovery in trading, and sentiment towards the shares. Possibly the excitement over Sir Martin’s astonishingly successful previous career at WPP might return? Can he sprinkle stardust on the shares again?
Interim Results - I can quickly review this, as the numbers are not good.
Net revenue down 16% to £376m.
Cost-cutting done, reducing staff costs (the main cost for this type of business).
I totally ignore the adjusted numbers, as they look ridiculous to me. The statutory loss before tax in H1 was £(17.2)m vs £(23.2)m H1 LY.
Balance sheet is awful. NAV of £878m contains intangible assets of £1,043m, so write those off and it’s a deficit NTAV of £(165)m funded by too much debt.
Cashflow is negative when all real world costs are taken into account (eg finance charges, rents, etc).
Outlook sounds weak, with more cost-cutting needed to keep EBITDA flat vs 2023. Heavy H2 weighting assumed in forecasts.
Paul’s opinion - I think Sir Martin has created a monster here, not in a good way.
It seems that the days of digital advertising being seen as a licence to print money, are long gone.
Definitely not for me, so I remain at AMBER/RED.
Surprisingly good StockRank, I have to disagree with the computers on this occasion -
Portmeirion (LON:PMP)
Unch 223p (£31m) - Interim Results - Paul - AMBER
Portmeirion Group PLC, the owner, designer, manufacturer and omni-channel retailer of leading homeware brands in global markets, is pleased to announce its results for the six months ended 30 June 2024.
Sales growth in US and UK, South Korea challenging as anticipated
Current trading in line with market expectations with a strong Christmas order book
I’m wary of PMP because their previous communications have been misleading - trying to gloss over profit warnings, then sneaking considerably reduced forecasts out via the broker. So the first port of call should always be the broker updates - which are OK today, forecast unchanged.
This raises the question that if I don’t trust management, do I want to buy the shares at any price? Probably not, so I’ll keep this section brief.
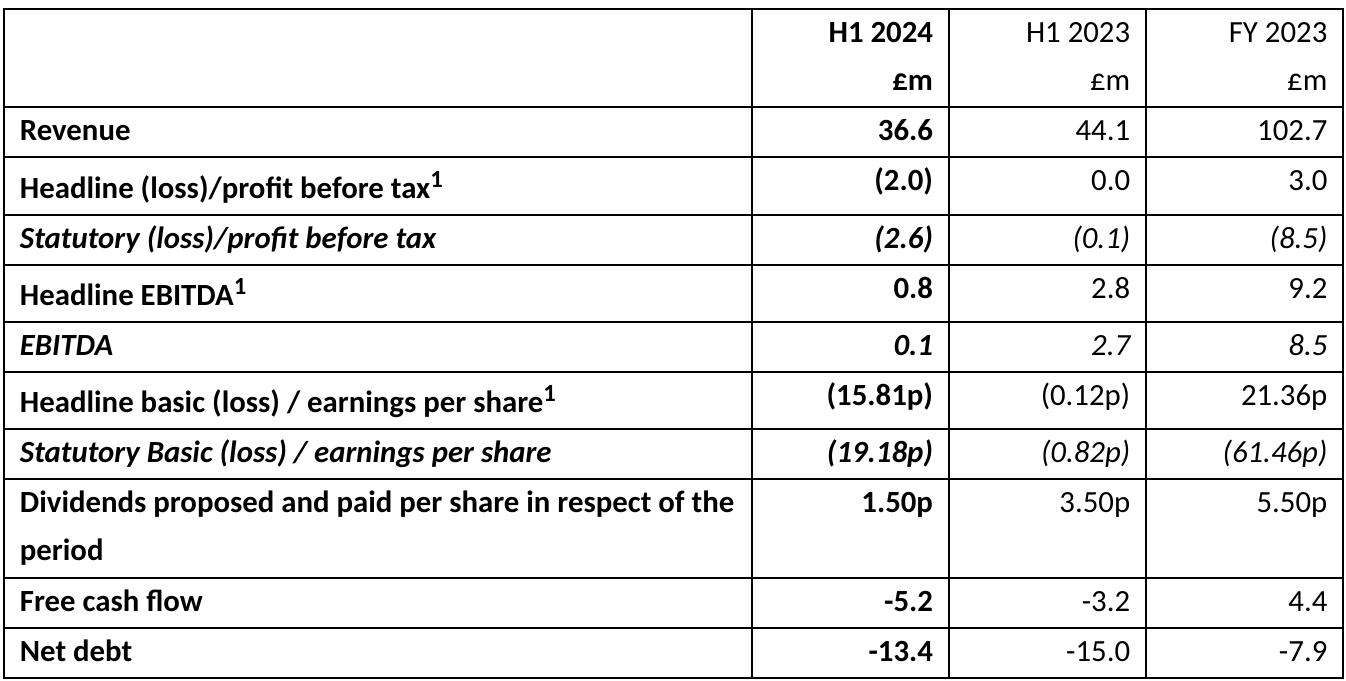
H1 is the seasonally quiet half, but it used to make a small profit or breakeven. Now it’s a loss in H1, c.£2m -
Singers (with thanks) has left its FY 12/2024 forecast unchanged at: £100.0m revenues (down from £102.7m in 2023) and adj PBT £4.5m. Adj EPS 24.5p.
Note that there was a £7.5m drop in revenues in H1, so this forecasts assumes most of that is recouped in H2, ending the year only £2.7m down Y-on-Y for revenues. That looks a tall order to me.
Interim dividend - has been cut from 3.5p last year to 1.5p this year. It shouldn’t be paying anything in divis, given the loss-making H1, this is a mistake.
Checking our records here -
2/2/2024 - Paul - AMBER - uneasy something might be going structurally wrong at PMP.
28/3/24 - Paul - AMBER/RED - Risky. Material uncertainty in going concern statement.
19/7/24- Paul - AMBER/RED - dependent on renewing bank facilities. Risky.
Bank facility - excellent news here today, which addresses my main concern over risk, although the detail needs to be checked -
“In August 2024, the Group signed a new 4+1 year term £30 million revolving credit facility with Barclays to consolidate and simplify our borrowing structure and provide adequate working capital headroom for the future. This replaces the Group's previous facilities totalling £24.5 million.”
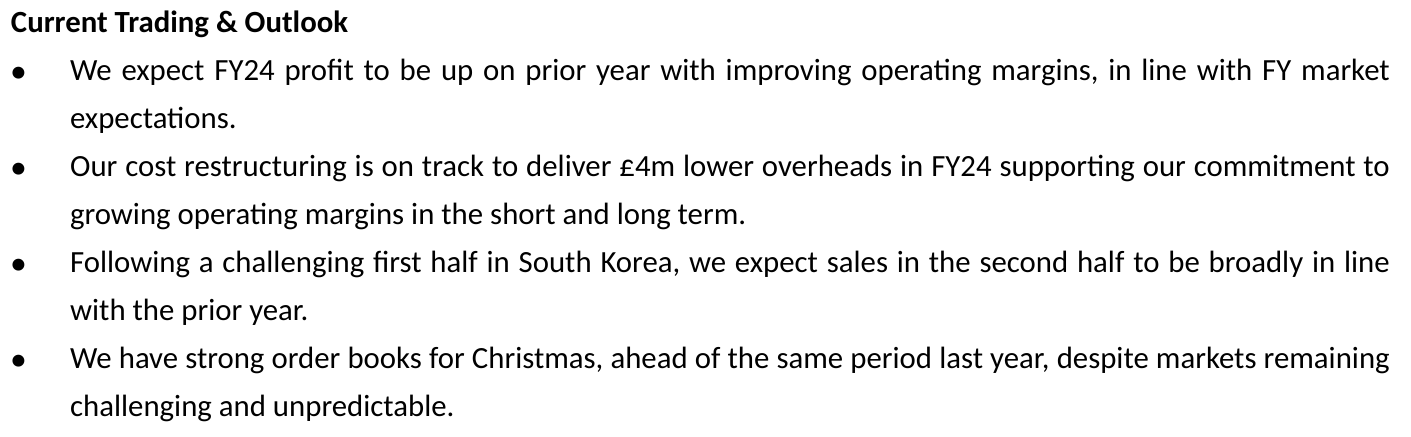
Outlook - sounds reasonable, if they can pull off the anticipated increased sales in H2 -
Balance sheet - overall it’s decent enough with NAV of £52m, and NTAV of £42m.
The problem remains excessive inventories, much too high at £40m, which required funding, through £13.4m net bank debt.
It’s fair to say that H1 period end shows higher inventories for the build up to peak Xmas sales in H2, but it’s still much too high. I suspect PMP has too many brands, with too many product lines, and probably plenty of slow-moving stuff within that, which would have to be sold at low margins to shift it.
For comparison (although different products/markets) Churchill China (LON:CHH) has about half the inventories of PMP, despite having similar H1 revenues.
Note also that PMP diversified unsuccessfully in the past, with poor acquisitions that destroyed shareholder value.
Going concern statement - this is now clean, due to the new bank facilities. Hence the “material uncertainty” warning has gone - very reassuring!
Paul’s opinion - I suspect there might be an H2 profit warning gestating, since the forecasts look unrealistic to me.
That said, the renewed bank facilities, and the now clean going concern statement have removed my main risk worries.
Hence I’m happy to up it from amber/red warning, to AMBER. For me, amber/red is automatic, if there’s a going concern warning. With that gone, risk is greatly reduced. I don’t know how the company is likely to trade, but it says Xmas order books are good. Whether that actually turns into an improved H2 performance, who knows?! Market cap is only £31m, so a sniff of improved trading could be nice for the share price. Equally, it might warn on profit again, so it’s up to you to decide which is the more likely scenario. For me, it’s a don’t know, hence AMBER. There's also the question of whether a stock market listing is worth the cost & management time?
Historically, PMP was a good quality business, making attractive margins, but it’s not any more. Maybe some of its customers have died over the years? It would be interesting to know the demographic of buyers, I suspect for some brands it's likely to be quite old. Not a very nice point, but something we do have to think about.
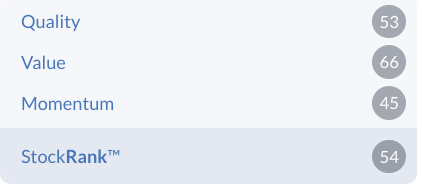
Stockopedia is also middling in its assessment -
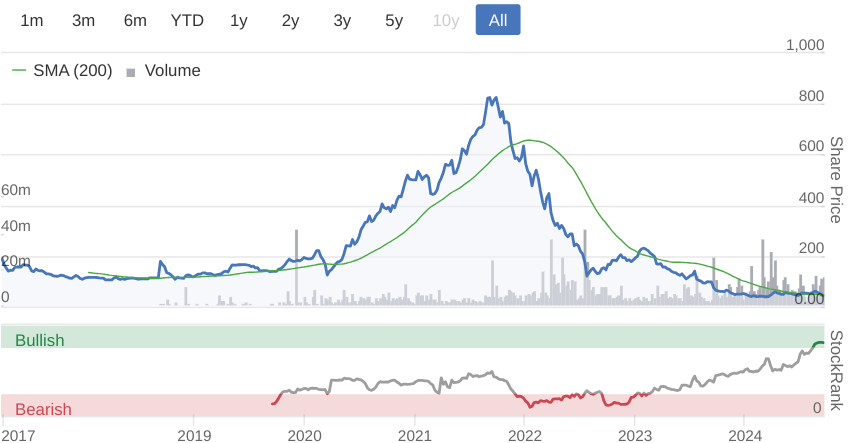
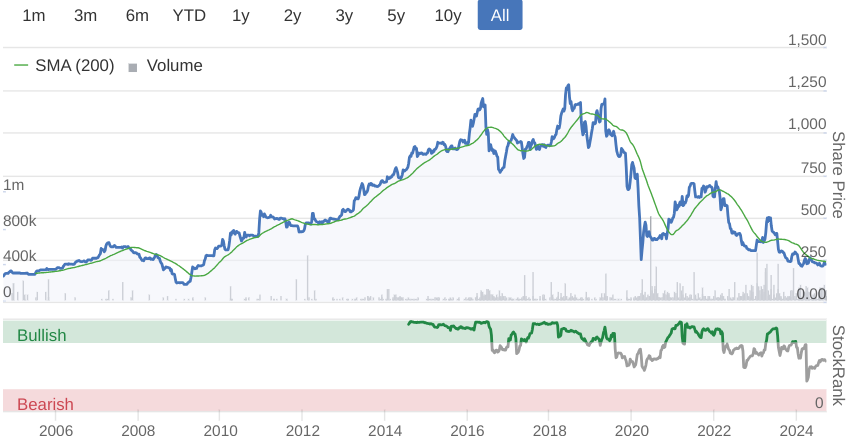
Zooming out on the chart, it difficult to avoid the obvious conclusion that this looks a structurally declining business - note the damage really happened in 2019, the year before the pandemic -
Supreme (LON:SUP)
Up 1% to 166p (£194m) - Trading Update (AGM) - Paul - AMBER/GREEN
Supreme (AIM: SUP), a leading manufacturer, supplier, and brand owner of fast-moving consumer goods…
This year is FY 3/2025.
Trading in line -
Following a solid start in H1 2025, Supreme expects trading for the year ended 31 March 2025 ("FY 2025") to be in line with market expectations1."
1 Company compiled analyst consensus for the year ending 31 March 2025 prior to release of this announcement was Adjusted EBITDA2 of £37 million
Broker updates - from ED and Shore today. I got to ED, as it’s directly commissioned by the company, so their forecasts are the company’s forecast in all but name. £37.0m EBITDA turns into £30.4m adj PBT and 19.5p adj diluted EPS (slightly down on 20.2p last year (which was itself a bumper year with very strong profit growth). So at 166p, the PER is 8.2x - cheap, but cheap for a reason, as the bulk of the profits come from vaping products.
ED shows that 64% of the group’s EBITDA will come from vaping products this year FY 3/2025, and 62% next year. So anyone trying to pass this off as a broader consumer products group - nice try, but it’s a vaping company. Hence a single digit PER is correct, in my opinion. You may differ, that’s what makes a market!
Over the coming years, SUP may well further diversify, and I’ve always been impressed with the entrepreneurial owner-manager at SUP, who has a proven knack of spotting lucrative product opportunities. So I imagine more of the same is likely. A recent acquisition was a soft drinks business.
More acquisitions coming -
“Acquisitions continue to underpin Supreme's growth ambitions, and the current M&A pipeline is strong with opportunities spanning multiple product verticals and markets.”
It says this today re vaping, for you to ponder and form your own view -
“The core lines within our Vaping category continue to perform well and we remain well positioned to comfortably manage the anticipated changes to the UK vaping market, having continued investment in rechargeable pod system vaping devices, adapted our flavour range and own-brand packaging, and ensured all retail partners enforce rigid age verification checks.
As an industry leader, Supreme acknowledges the wider concerns of underage vaping and remains fully supportive of proposed legislative changes in the UK. Details of the proactive measures that Supreme is taking to curb underage vaping are available to read in our latest Annual Report on our website.”
Paul’s opinion - an impressive business in some ways, just a pity about the main profit earner being vaping, which is inevitably going to limit the upside on this share, whatever we might individually think (let’s try not to get into the same argument again, but if you absolutely have to, then so be it!)
Valuation is obviously attractive, but given the main products, for me it feels priced about right.
There’s a useful divi yield close to 3%, and the balance sheet is sound. More acquisitions should help drive earnings, although note forecast profit is slightly down this year on the bumper numbers for FY 3/2024.
Shares have wobbled recently, and look superficially cheap, which they tend to be on an ongoing basis. I’ve previously been AMBER/GREEN (moderately positive) earlier this year, and am happy to stick with that again today. I can see why bulls like the numbers. But I also see why bears steer clear. Nobody is definitely right or wrong, they’re just different ways of viewing the same thing.
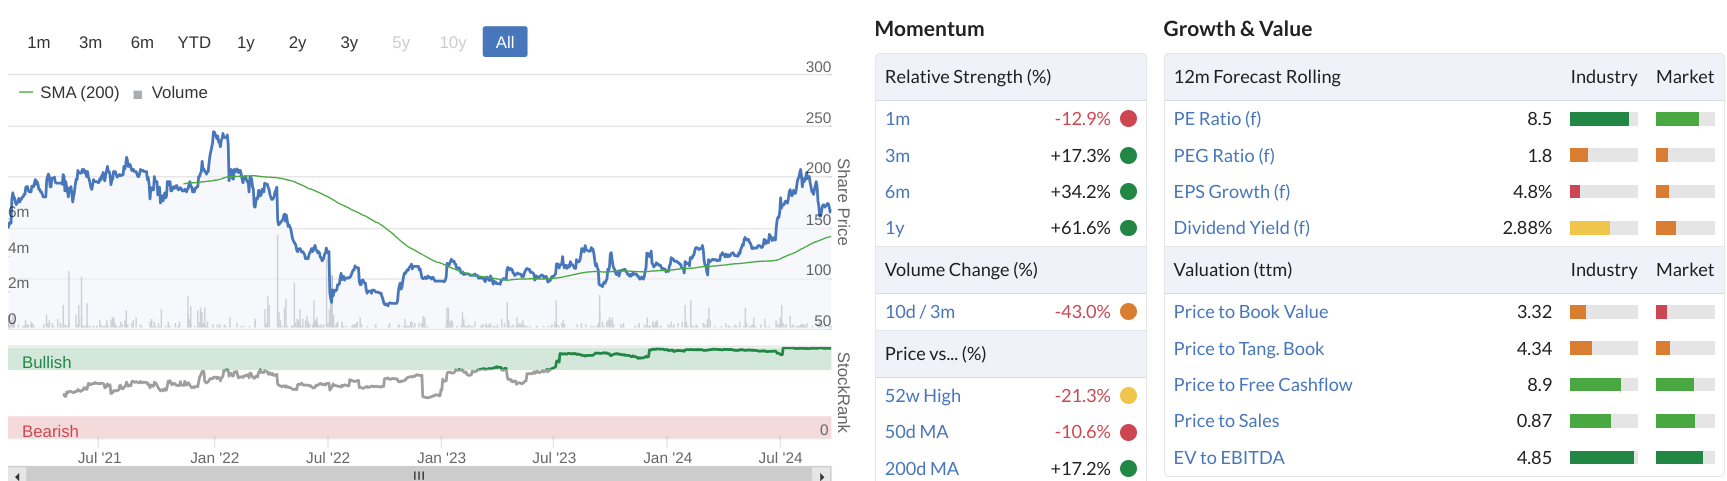
Chart below since it listed. Note the outstanding StockRank of 98.
Graham’s Section:
Judges Scientific (LON:JDG)
Down 2.5% to £100.38 (£667m) - Interim Results - Graham - AMBER
Judges Scientific, the group focused on acquiring and developing companies in the scientific instrument sector, announces its unaudited interim results for the six months ended 30 June 2024.
I’ve been a little worried about Judges in recent times, as organic growth has seemed to dry up along with a deterioration in its underlying quality. See my comments in March 2024.
The theme of weak growth is evident again in today’s interim results:
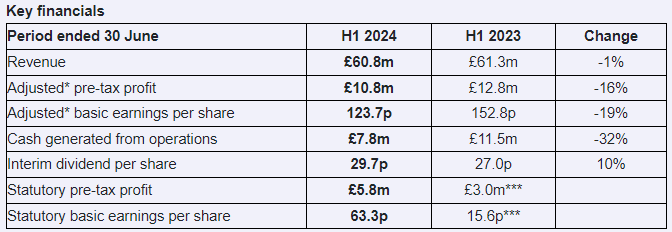
Organic growth is -3%, slightly worse than what is shown in the above table (some small acquisitions boosted total revenue).
As of the end of H1, the order book only extended to 17 weeks of business, the same as Dec 2023 but down from 22 weeks a year ago.
Net debt was £55m at the end of H1, and since then there has been a £12m acquisition.
The balance sheet shows net assets of £87m, but this figure falls below zero if you write off intangibles.
Outlook is unchanged, but the company says there are “continued challenging market conditions and short-term vulnerability to the timing of orders and revenue”. So a profit warning at some point in H2 would be no surprise at all, as orders/revenue could easily slip into next year. The small dip in the share price this morning looks about right to me, to help price this in.
Chairman comment:
As announced already, several of our Group businesses have experienced a challenging first half, driven by difficult market conditions and the deferral of some projects into H2 or 2025.
In spite of the trading disappointment, the Group has again demonstrated its resilience and its financial strength. With the completion of three acquisitions since the start of the year, the further strengthening of our management team, and a 10% increase to the interim dividend, we continue to build on our model of delivering long-term shareholder value."
Estimates: Panmure Liberum have kept their adj. PBT estimate for the current year unchanged at £30.7m, rising to £37.4m next year. So a much stronger H2 is expected.
Graham’s view
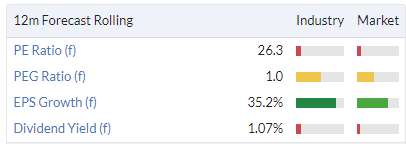
The company says that H1 2023 was a tough comparative period, as China emerged from lockdowns. I’m sure that’s true, but we have to remember that this stock is trading at a PER of 26x (according to Stocko calculations), and is carrying substantial debts, so we have to be more demanding than we might be with a lowly-rated, cash-rich business.
I do like what I hear about the recent £12m acquisition: Judges have paid six times adjusted EBIT for it, plus the value of freehold property attached. The acquired company (link) is involved in “manufacturing coating instruments and providing coating services.”
A point that I’ve raised repeatedly in relation to Judges, and where I’m still uncertain, concerns whether or not it will be able to continue finding high-quality acquisitions that move the needle.
In some ways, it is the victim of its own success: it was so good at making small acquisitions that it successfully compounded wealth for itself and its shareholders, and has become a much larger business:
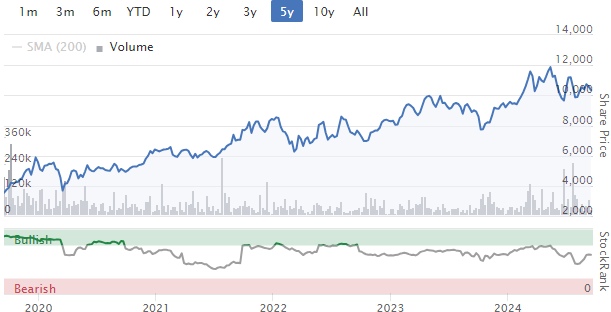
But does the old formula still apply, now that Judges is so much bigger?
I certainly don’t rule out the possibility that this is the second coming of Halma (LON:HLMA). Halma tends to trade very richly and that hasn’t prevented its shareholders from doing very well indeed.
But before taking a positive stance here, I’d like to see one reasonably large, successful acquisition to demonstrate that the company’s formula is still working.
The recent £12m acquisition sounds promising and yet £12m is less than 2% of the current market cap. Even if it succeeds, several acquisitions of this size would be needed to make a big difference to the value of the company.
Today’s financial results show what can happen without acquisitions, in a challenging economic environment: growth dries up and profits go into reverse. They have not been helped by a slowdown at Geotek, the flagship acquisition by Judges in recent years.
I’m therefore sticking with my neutral stance on Judges. I’m nervous about this stance, as I do think that the stock could continue to multi-bag for the long-term for its shareholders. But the market has occasionally provided good buying opportunities for this one and I hope I’ll be alert if/when this happens again.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

83 comments
I see Ireland is going to receive a windfall from Apple and intends to spend it on infrastructure and housing. Cairn Homes (LON:CRN) could benefit....https://www.cnbc.com/2024/10/0...
In reply to BnB,
Made Tech (LON:MTEC) £25.38m mkt cap, just won a contract with the DfE for £13.2m to deliver base line assessments in schools. Contract is for 4 years with an option to extend for another year. Possibility to win more DfE and NHS contracts to digitilyse services.
Van Elle Holdings (LON:VANL) £45.36m mkt cap. Super stock rank 97.
PE 9.2 Dividend yield 3.37%. Tailwinds: building / construction on course to increase, rail investment, especially the contracts won abroad in Canada, where the competition cant do what they can! Water, energy and wind turbine industries need their foundations/piling skills and services.
I hold Made Tech (LON:MTEC)
Sold Van Elle Holdings (LON:VANL)
Luceco (LON:LUCE) and Volex (LON:VLX) plus one big beast AstraZeneca (LON:AZN)
Avation (LON:AVAP)
Currys (LON:CURY)
Avation (LON:AVAP) I wish it will come good, there's lots of potential unrealised value (still...) but it happens to be the first on my cut list.
Shoe Zone (LON:SHOE) I've been trimming recently, so obviously the share price has recently had some strong action...
First on your cut list because it has been languishing? Maybe just patience needed....
Yes and also whilst I can see value, if the market doesn't, what's the point?
Because eventually it should?? I guess lots of undervalued assets behave like this until someone large enough sees value. ( I hold) Avation (LON:AVAP)
Happened to be in Marlow a while back when £SOS were still in the final throes of fitting out the new store. It certainly has a noticeable presence on the High S
I see there's an RNS just out on Plexus Holdings (LON:POS).....A certain Mr Paul Scott has gone above 3%.....
Just nice to see a Plexus Holdings (LON:POS) RNS -there’s been a bit of a news blackout on this share!
I see there's an RNS just out on Plexus Holdings (LON:POS).....A certain Mr Paul Scott has gone above 3%.....
With daily volume often failing to clear GBP 10k, a position as big as GBP 350k is certainly bold. I really like the story with this one. But there’s little reassurance to be found in the trading performance. And no liquidity to exit if it turns sour. Compelling though the use case may be for the tech, it just feels like a shot in the dark. Albeit one I hope comes good for holders, and especially Paul.
The lesson to myself on S4 Capital (LON:SFOR) (where I opened a fraction of a starter position at end August) - don't open a new position, forget to set a stop loss, and then go away on holiday. Since then it has dropped every single day bar one, so now on a 35% loss. I should sell and move on, but given that the lesson is costing me <£500 (at the moment) I've hung on so it reminds me to not be so lax in future!
Snap! 30% down! Hoping this is the bottom! Likely to be spanking my bottom! But teeth and claws have been deployed! Doh!
I know nothing is an exact science but when I'm following a stock and like it and the SCVR moves from Amber to Amber/Green I tend to take that as a buy signal. Certainly worked with Team17 (LON:TM17) +14% since I bought on Tuesday, happy days - Thanks Graham! :)
How about: Bloomsbury Publishing (LON:BMY) and Ashtead Technology Holdings (LON:AT.)
How about: Bloomsbury Publishing (LON:BMY) and Ashtead Technology Holdings(LON:AT.)
I don’t see the former as a bargain, but I’ve been topping up the latter, already a big position, and now much bigger.
Bloomsbury Publishing (LON:BMY) perhaps not an obvious bargain, but forecasts should be comfortably beaten in my view so cheaper than it looks (they have a tendency to put through big upgrades later in the year).
Ah yes I re-read the original post afterwards and did wonder if I might have been a bit hasty plumping for Bloomsbury Publishing (LON:BMY) but as Bouden54 hints at I'm hoping the recent pullback will show it as a bargain 'in hindsight' perhaps haha. Enjoying reading other contributions - most suggestions are on my watchlist too.
Smiths News (LON:SNWS) Reach (LON:RCH)
Portmerion
Pathetic management and inventory management .
Such a simple turnaround any strong FD could sort this out .
Stock turn should be a maximum of 4 , gives 25 million correct stock (if lean should be 20).
This would move debt from -13 to surplus of plus 7 cash .
Been there myself and too a new Fd to kick me in the knackers along the lines -
“Dave we are breachimg our bank covenants 2 million in debt and are going into “special measures”
We turnover 16 million
You have 8 million stock
Your stock turn should be 4 not 2.
All you need to do is drive the stock down to 4 million then we will have 2 to 2.5 million surplus and as you are 90% owner that can be paid out
Are you stupid or just lazy
Forget about margin for the next 6 months and get medievil on that stock list just drive it down .”
I said “is it that simple”
He said “yes”
Next day I broke our sales record by 180k with a 265k turnover day much to his delight . (Pro carbon with dura ace at 999 for anyone into bikes)
Took me 6 months
Barclays said probably one of the quickest and best turnarounds they had seen.
Took me 25 years to find a world class FD , had some right plonkers before finding “the one”
I loved my last FD
I would have bought two, possibly a third for spares, if you had made frames big enough for me!
The tall frame version of the Fairlight Strael is proving to be excellent by the way ;-)
I'll get it rebuilt on dura-ace next time you have a sale.
Everyone is presumably waiting with bated breath for Paul’s list of bargains. But why don’t we all construct one of our own this afternoon. Max 2 suggestions each. Try to stick to oversold likely short term winners, not deep value or eventual turnarounds. Here’s a couple of mid caps
4imprint (LON:FOUR)
Oxford Instruments (LON:OXIG)
Serica Energy (LON:SQZ)
Whitbread (LON:WTB)
Couple of ideas from me - Volex (LON:VLX) and Kitwave (LON:KITW) - both dropped quite a bit over past few weeks and feel like they could be due a 10-15% recovery.
Kitwave reported some soft trading over June due to the wet weather (and very hot weather last June which made for a particularly tough comparator) - interestingly, Next noted the same pattern in today's report, but also mentioned a strong weather-driven recovery in August/Sep - I suspect Kitwave could see a similar pattern which should help with the recovery.
+1 for Volex (LON:VLX) , H1 TU should be a month away so not long.
if you believe in Rezorce Zotefoams (LON:ZTF) would be a proper bargain here and limited d/s from underlying business.
Ocean Wilsons Holdings (LON:OCN) as a more left-field option with ongoing talks over selling Wilsons sons and sale should generate returns in excess of SP with investments in for free.
Zotefoams (LON:ZTF) dropping while awaiting news on the ReZorce trial/distribution licences? Arrow Exploration (LON:AXL) down with oil price fluctuation and news due on latest well next week. Apparently the management are in town today/tomorrow too if the BBs are to be believed.
I think that Paul's list might contain Plexus Holdings (LON:POS). Just a guess :)
My two suggestions, RBG Holdings (LON:RBGP), it just keeps dropping on news at all.
And Gulf Marine Services (LON:GMS), where I believe from recent updates, Seafox have given away their holdings to their own shareholders, with undertaking to hold what remains of their share holding. This should remove the overhang.
I hold both of my suggestions, but not Plexus Holdings (LON:POS)
Regards,
Jon
And Gulf Marine Services (LON:GMS), where I believe from recent updates, Seafox have given away their holdings to their own shareholders
Recent purchase for me. Looks good here.
I'd be a bit careful with RBG Holdings (LON:RBGP) - last time I looked I came to the conclusion it could go bust, although not looked at it recently so perhaps things have improved. A key concern I had was that the collapse in the share price could make it very difficult to compensate fee earners through share awards (which forms a big part of their package) - in turn that could lead to an exodus of staff and a bit of a death sprial. All the negative publicity must also surely have an impact on attracting clients.
It's a very small portion of my portfolio (and getting smaller), but thank you for the comment, it's an angle I hadn't considered.
4imprint (LON:FOUR) I totally agree. Looks great.
Oxford Instruments (LON:OXIG) downgrades to come due to FX perhaps? $ strength.
My 2 would be Victorian Plumbing (LON:VIC) and Reach (LON:RCH)
4imprint (LON:FOUR) I totally agree. Looks great
I’ve almost doubled my stake. Looks ridiculously cheap relative to history and in the context of expectations for a soft landing (which might not happen, of course).
Osb (LON:OSB)
Serica Energy (LON:SQZ)
PayPoint (LON:PAY) and Capital (LON:CAPD) are significant holdings that I’ve added to in this dip (I hope its a dip!).
My two pennoth
B&M European Value Retail SA (LON:BME) and Conduit Holdings (LON:CRE)
Each easily overlooked
My two pennoth
B&M European Value Retail SA (LON:BME)
I was attracted to this the other day. But then I saw what Temu et al have been doing to Dollar General (NYQ:DG) and Dollar Tree (NSQ:DLTR) and thought twice.
B&M European Value Retail SA (LON:BME) stopping night shift work competition from supermarkets and china temu etc
My 2 would be Beeks Financial Cloud (LON:BKS). I believe we are now into positive operational leverage and hopefully more significant Exchange contracts which will drive the share price upwards.
Animalcare (LON:ANCR). Hopefully the share price will rally off the back of H1 results next week. The balance sheet will be more robust with just over £32m of net cash which I'm sure Jenny the CEO will invest wisely.
Ok, sorry for being slightly off topic but hopefully I make someone laugh.
for months now I’ve been racking my brains trying to work out the meaning of Unch. I did wonder if it was a certain time of the day, somewhere perhaps between breakfast and brunch? Anyway, the penny finally dropped today.
Serica Energy (LON:SQZ)
The ultimate Milliband contrarian play, has been rallying hard last few sessions, I only got around to reading their results yesterday and have been buying it since then.
17% dividend yield, $131m net cash, $500m projected free cash flow over the next three years even with a higher windfall tax, plenty of director buying.
Energy stocks not normally my thing but this looks (looked?) very over-sold to me.....
I agree. Most if not all of the bad news is baked in to the price. Any softening of attitude by the U.K government on taxation and/or Serica invests its cash pile in regions where there are more realistic views on energy transition, could result in material upside to the SP.
Although oil shares like Serica Energy (LON:SQZ) and Harbour Energy (LON:HBR) are not covered here, they are on other threads, including this one:-
https://www.stockopedia.com/co...
Also a reply on that thread (where there have been some well balanced posts on the pros and cons of the Government’s North Sea oil policy) I included this paragraph on Serica Energy (LON:SQZ) . Coincidentally that price looks to be the extreme oversold low . And it was just 9 days ago, and it’s now 30% higher:-
“ Why I’ve not given up on Serica Energy (LON:SQZ) is because Starmer and Reeve are not idiots and Rachel Reeve is arguably one of the best qualified Chancellors for a long time, including her Bank of England experience. And though the media don’t cover it, surely the Government are getting endless pressure from the oil industry, including from Serica Energy (LON:SQZ) to see sense.
Hence I’m prepared to wait for the Budget and risk yet further share price fall between now and then.”
There’s a fair chance the big 17% dividend will be held.
Harbour Energy (LON:HBR) is another oil share I hold. Last December they announced their acquisition of Wintershall Dea, and the share price soared 30% on the day to 320p. It has now drifted back to 260p for no good reason afaiaa, and at this price the dividend is nearly 8%.
Here’s the link for the Wintershall update, which might prove “transformational.”
https://www.stockopedia.com/sh...
Serica - my biggest SIPP holding . Built my position over the last 2 months.
TERRY SMITH gave a really good interview over on Interactive Investor https://www.youtube.com/live/i... I urge you to check it out. I'll just pick out a couple of points.
Commenting on his lacklustre performance the last few years, he said that the fund is likely to underperform when interest rates go up. If I understand correctly, he thinks of his investing as a form of long-tail bond. So one would expect prices to go down as yields go up.
He touched on the subject of indexing and said that he does not really consider it passive investing. It's really a momentum strategy. As more money gets pumped into it, it tends to swell the faster-moving companies. It's a strategy that "works until it doesn't."
He said that the S&P beat over 90% of fund managers over the last few years. The inference he seems to draw is not that 90% of fund managers are useless, but that there has been huge momentum in big tech.
As money is increasingly put into indexing, the effects will be magnified. IIRC over half of funds are now in indexing. He doesn't know where the cut-off point is before bad things start happening, but he said that there are the most extreme differentials between high and low PE that he's seen, suggesting that indexing may already be at a dysfunctional stage.
Thanks for an interesting link. Terry Smith is always a good listen!
He mentions Fundsmith's recent underperformance wrt US index tracker as part due to so much being weighted made by the magnificent 7, e.g NVIDIA (NSQ:NVDA) Nvidia. I'm not sure if his logic is quite correct on this one.
I think it's true to say that any fund or any tracker, the bulk of the returns are generally made up of a handful of the best performing stocks. If so (I'm not totally sure) then this would be an argument in favour of holding index trackers. All the more so as Terry's fund's have fees and expenses around 0.9% higher than the cheapest US trackers.
On the way up yes, on the way down, no.
The point Terry Smith is making is that most index tracking funds are market cap weighted, not equal weighted - so the largest companies (not necessarily the best-performing except in the long term) have the most impact on index performance.
You therefore get a positive feedback loop - as a share price goes up so it's contribution to index performance is magnified (relative to other constituents).
In a period of directional markets this can result in momentum bias.
Yes. As momentum continues, share price increasingly becomes detached from fundamentals. The thing that Terry didn't state, so I'm adding my own sauce to the mix here, is that momentum has a tendency of feeding narrative in market psychology.
The Fed cut 50 bps, showing some steel I would say, risk seemed to be tilting slightly towards slow down.
If you need to cut then I fail to see the downside of going 50 bps, but only time will tell if they needed to cut. Wages remain strong argue the economic no landing crowd … and the other lot point to the Sahm Rule which most of us were oblivious to until recently … once employment deteriorates 50 bp we are “probably “ already in recessions.
Without doubt we remain in unprecedented times since we continue to emerge from the Covid fight. China is a material factor in global GDP and has emerged much weaker than thought. It seems to me the media spent most of the 00s doubting their growth and now they can’t believe China is so weak.
The Fed has a tough job and the whole world watches on so it takes some metal to move decisively and cut. I think (or hope) this favours out of favour value sectors - where most of the Uk market sits. The initial reaction which is fickle is positive - markets and Sterling up. Also in Asia markets reacted positively see HK, Japan etc the moves in bond markets were relatively muted which you would expect now. The risk will be twofold … big moves in either inflation or employment in the US …. But there is no reason to expect this yet. Until the beginning of October when more data emerges we would appear to have a clear run …
best of luck all and let’s hope markets crack on.
This is worth listening to. Steve Hanke is really smart in my view. He calls the Fed's interview "a spin room"!
As Peter Lynch would say: "If all the economists were laid end to end then that wouldn't be a bad thing."
Supreme (LON:SUP)
Interesting factoid…….. when they came to market in 2021 the revenues of the entire group were £92m and the share price was where it is today.
Today the non vaping revenues alone exceed £100m……….
I couldn't agree more david. The more I look at it, the more I think it is undervalued and I know management feel that this could go a lot, lot higher. I topped up recently and looking at any further weakness.
I haven’t commented on the Hostmore (LON:MORE) and Unbound debacle for some time now but yesterdays appointment of administrators prompts a further question. How did Electra Private Equity manage to mislead investors and get away with floating two failing businesses on the market? Surely the trading situations of these businesses, both launched onto the market post Covid, should not have deteriorated so fast as to lead to a total loss of equity value in such a short space of time. The private equity executives at Electra Private Equity must be laughing all the way to the bank. Be interesting to discover who those people are and steer well clear of any future businesses they may try to sell to investors!
Well the figures for MORE looked good at the time it was de-merged from Electra. I have it on good authority that they turned down a takeover bid at something like 130p/share, thinking it would attract a higher valuation as a standalone company.
But a lot has changed since MORE floated in late 2021. Primarily we had the huge shock of the energy crisis when Putin invaded Ukraine a few months later, causing a big spike up in inflation globally, which caused a big reduction in disposable household incomes. The hospitality sector has been smashed by the big rise in food & drink prices, energy costs, and 2 consecutive years of labour costs rising c.10%.
Combine that with MORE having too much debt and original management were pretty useless with hindsight, and it didn't manage to survive. I think a lot of members here flagged that TGI Fridays was a tired brand too, offering poor value for money. Something I confirmed with my mystery shops, and the notorious flat coke disappointing almost every customer in my local store (Bmth).
Hence why 2 years ago we turned negative here on MORE, because the facts had changed for the worse, and we continuously flagged it as RED thereafter.
I don't think your assertion of some kind of negligence or misleading behaviour by Electra holds water, because Electra had a good track record of realising value for its assets. The macro circumstances just changed and crippled the hospitality sector generally, there's hardly anyone making money from it now. Who could have predicted the Ukraine War, and inflation shooting up to 11%, etc?
Things change, that's why we have to change our views on shares on a daily basis.
Paul.
No criticism to you Paul, nor the reporting on either company, but do you not feel that Electra did some pretty aggressive window dressing with regard to both companies ?
Charlie Munger and Warren Buffet have private equity summed up perfectly .
“Private equity firms are typically very dishonest”
The worlds greatest investor got it spot on.
I do agree with the point on blacklisting the vampires that dumped this dross onto us .
But ultimately it was buyer beware and they timed it perfectly to pump and dump their utter dross at the peak of the bull market.
Their responsibility was not to buyers but to themselves and there investors so “they played a blinder”
How do you know when private equite is telling you lies ?
Easy “their mouth moves”
Home Reit (LON:HOME)
buyer beware and all that
its easy to roll back the clock - post covid i think there was no expectations that we would have rampant inflation that would destroy much of the sketchier dine out stuff - heck hostmore had to pay their royalty fee on top which very few dining out places need to pay.
the reality often with places like this is that it ends up that the ceo's probably is more interested in their salary and next job than trying to save the company onece the writing is on the wall.
Unbound does seem more odd but i think they needed to prove they could grow and keep good margins so was alwasy risky punt surely?
I think plenty commented right from the get go that the numbers they did start releasing (hostmore) were poor to begin with - so not as it there wasnt warning signs to run for the door.
I think this is more a general issue with companies floating stuff when they extract all the cash raised - why would you ever buy a new float when you know the seller will have been window dressing everything in the best light possible? - i do understand this was a well known brand that probably shoudlnt have failed with the start it had but ..
Time to move on … if mkts have a bad day and lose 2% … portfolios probably fall 2%. If a big holding (10%) misses numbers and falls 20% … portfolio falls 2%. And if a small cap goes bust and falls 100% … if it’s a 2% position or less then the portfolio impact is 2% or less. All of these falls are manageable. Four years later they will be forgotten. I’m sorry for your disappointment but losses should be manageable in a portfolio. If they are not then portfolio construction is to blame.
For more recent arrivals on here it may be worth observing that 10% for a large holding is probably at the punchier end of the spectrum!
2% is a large holding for me (& would mostly be liquid large caps), and for many of the stocks discussed here on the SCVR I may start with a 0.25%. There is plenty of discussion on diversification elsewhere on Stocko.
Of course what %s don't tell you is how much people have invested in absolute terms - which is what really matters, nor what % of their net worth they have invested in equities.
There is a huge range amongst the commenters on this forum - from £500 to £500,000 (and probably much higher) per holding I reckon. And even then some will be leveraged as well.....(Paul has kindly shared his experience of leverage here on Stocko and it is worth reading).
All for illustrative purposes to show losses are manageable - nothing more or less. I would counter however that the sums involved are in fact irrelevant.
I would counter however that the sums involved are in fact irrelevant.
Have you never discovered that you can't get a quote in size in a small cap stock and that you are unable to sell? Have you never pulled back from dealing in a small cap because the bid/offer spread was simply too wide?
Liquidity matters, and therefore absolute position size matters.
In fact it matters quite a lot if you have a pension scheme that is in net withdrawal.
If you have a chat with a certain Mr. Woodford, he will tell you all about keeping an eye on your position size vs liquidity.
I apologise I was just trying to show that a portfolio should be able to absorb losses - I make no comments re liquidity - which is obviously important.
On that I agree entirely.
I think it is a skill that be learned to some degree. Eventually you realise a small cap equity can just do +/-10% one day and it can often be meaningless.
Hostmore (LON:MORE) and Unbound were always part of my very speculative portfolio holdings. Together they represented a tiny fraction, a hardly measurable %, of my portfolio and one which I could afford to lose the 100% of value that has come to pass. My initial comment was not about personal disappointment but more a matter of principle as to the performance of the private equity sellers - a concern shared by contributors such as planetx in the comment above. As to portfolio construction you can be sure I am aware of the appropriate principles for sound portfolio management. Over exposure to the type of shares discussed on the SCVR is not a feature of my portfolio. Consequently I may not get rich quickly but I will certainly sleep better at night.
Hi Paul,
In your pod (great by the way!) you mentioned some bargain stocks but had forgotten your pad, would you be able to mention them here please? Or will you wait until you've done the screener you mention today?
Thanks
I'll see how I get on with today's news, and hopefully might come up with something for bargain share ideas later today. Leave it with me.
Paul …bargain share list idea is brilliant…I and hopefully many others have a few shares that are well up and although not wanting to sell the whole holdings would like to top slice and diversify into shares that will also go up in value and maybe even have a decent dividend (just as a nice chunk of icing on the cake)…..I have been trying to sift through the last month or so for up to date ideas that are also affordable …So a list of potentials would be a massive help ….Hope Gozo is as nice and Sunny as Devon ….
Penny.
If you and others want to see more info on dividend and bargain shares and a lot lot lot more, then a good way to find them is to access Stockopedia by using this link:-
https://www.stockopedia.com/di...
There are excellent threads on Stockopedia, but a lot of them see very few posts and follow up and eventually get lost for good. And it seems a lot of subscribers only seem to look at this thread going by some of the comments here. e.g like the supposed disappearance of yiannos…..when as you can see using the link above he’s stiil very active here.
Hi Paul,
As a relative Newbie to Investing and still going along a sometimes painful learning curve, it would also be interesting if possible to know the criteria check list you would use to develop your bargain list. Many thanks for all the work you put in each day.
#JDG Judges Scientific H1 results webinar today at 16..30 BST. Register here.
My morning smallcap tweet: The jam-tomorrow factory
Accsys Technologies (LON:AXS) Trakm8 Holdings (LON:TRAK) Skinbiotherapeutics (LON:SBTX) Feedback (LON:FDBK) Sosandar (LON:SOS) Roquefort Therapeutics (LON:ROQ) PCI- PAL (LON:PCIP) Energypathways (LON:EPP), Braemar (LON:BMS), Supreme (LON:SUP), S4 Capital (LON:SFOR), Public Policy Holding (LON:PPHC), Portmeirion (LON:PMP), Tandem (LON:TND), ENGAGE XR Holdings (LON:EXR) Judges Scientific (LON:JDG)
◄Accsys Technologies (AXS)► will discontinue the Tricoya plant in Hull. Non-cash impairment charge of c. €20m and an exceptional cash cost of c. €4.5m [SP=52 Cap=125m]
◄Trakm8 (TRAK)► AGM stmt: insurance biz taking longer than expected to improve but Fleet and Optimisation revs expected to be better than expected. Remains positive about securing the significant Optimisation contract mooted in FY results. FY outcome remains uncertain. [SP=6.12 Cap=3m]
◄SkinBioTherapeutics (SBTX)► final testing of SkinBiotix by Croda Beauty Care completed, with positive results. "Pilot-scale manufacturing at 600 litre scale is currently in progress and will generate the final product into samples which will be shared with a few key customers prior to launch. Full-scale production is scheduled for 2025.2 [SP=10.75 Cap=24m]
◄Feedback (FDBK)► collaboration agreement with a provider of primary care solutions "to explore the opportunities for a novel Neighborhood [sic] Diagnostics Solution to streamline NHS diagnostic and pathway referrals...This provides a route to rapidly scale the Bleepa solution and pathway approach". [SP=47.7 Cap=6m]
◄Sosandar (SOS)► has launched in-store with Arnotts, the largest department store in Ireland. Also SOS's first two stores have opened. [SP=9.57 Cap=24m]
◄Roquefort Therapeutic (ROQ)► STAT-6 siRNA has demonstrated efficacy in a validated in vitro experimental model of immunological disease. [SP=3.31 Cap=4m]
◄PCI-PAL (PCIP)► FY audit further delayed till c.22 Oct due to additional work required since the update on 28 Aug. Guides FY results and current trading in line. [SP=53.2 Cap=39m]. I hold.
◄EnergyPathways (EPP)► update on MESH infrastructure project, a natural gas and green hydrogen storage facility. [SP=2.1 Cap=3m]
In line: BMS, SUP, SFOR, PPHC, PMP, TND, EXR, JDG
Supreme (LON:SUP) - "AGM statement affirms market momentum" - new research note here: https://www.equitydevelopment....
In a statement to accompany today’s AGM, Supreme PLC Chairman Paul McDonald noted “record organic revenue and profit growth” for the year to 31 March 2024. The Group also closed the year debt-free. Subsequently, the Group has continued to build on positive trading momentum into H1 25, and, following a solid start, expects FY25 performance to be in line with market expectations.
Inclusive of the acquisition of Clearly Drink, Supreme reports that annualised sales from non-vaping products are expected to exceed £100m; this is in line with ED estimates. The Group also expects acquisitions to continue to offer opportunities for further diversification and to expand its market presence.
Our Fair Value of 225p/share indicates a FY26 EV/EBITDA of 7.3x, which remains at a discount to a range representative of peers across Supreme’s product categories.
Morning All,
Yes bargains to be had. So many false dawns already this year though, can't trust these markets!
AIM flat year on year, 3 year performance absolutely dreadful. Will turn, but when??
Think this 3 year bear market has gotten to me now...
Portmeirion seem to have dropped some crockery this morning JohnDoe2378, commiserations to holders, unless it's bottomed out in anticipation. We're still buying mainly on Stockopedia information but very carefully and patiently, you're right it's a tough market to call.
At least the debt facility has been renewed.That was Paul's major worry in terms of possible equity raise or similar in the last SCVR report on Portmeirion (LON:PMP) i believe? Not too many bears in the china shop today so far.... Here's hoping for a better xmas period, especially in the US.A little Santa Rally surely wouldn't go amiss!Should be a full 100 basis point cut by end of year currently over there.I'm not sure that will totally have folk out rushing to buy fancy crockery but you never know..!The US are famous for their Santa Rallies!No idea what's really going on in South Korea?Perhaps it just is all destocking.Haven't tried looking at the South Korean economy lately!!
Portmeirion (LON:PMP)
a few thoughts.
Something of a relief that H1 results are in line and expectations for the FY are maintained? Not sure why? Think its probably a mark of how unloved the company has become?
Statutory loss of 2.6m was a little less than I'd anticipated - a good sign as I'm not noted for being pessimistic? Otherwise fairly much as advertised with no further bad news. The 0.6m restructuring charge was modest under the circumstances (and in view of prior performance)
The 4m annual reduction in cost base is as much due to the longterm investment in production automation, energy efficieny and digital transformation as it is slashing costs (something which often tends not to be a long term advantage?)
Pleasant suprise that the company has switched away from Lloyds in August to a larger, simpler and more efficient RCF with Barclays.
Has the potential to be a good start for the new FD.
Slightly surprised by the 1.5p dividend - had been prepared to accept zero in the interests fo getting the debt down. As its not paid until December - it will be funded from the positive cashflow of the seasonal uplift.
The turnaround at Wax Lyrical continues to build - and impresses me. The combination with aromaworks and investment in the business seems to be very well judged?
US +5% sales increase (at const currency) is good progress under the current circumstances in the US? I look forward to seeing the breakdown by brand- seems possible that Nambe has reached a stable base if not turned around as well? As a high margin US brand I see Nambe as a key part of US future growth, but it needs the Wax Lyrical treatment?
The less said about South Korea the better? Not the first time this market has fallen over? Albeit this time due to the yo-yo of global shipping disruption leading to over stocking followed by the inflation spike leading to reduced demand and de-stocking rather than a reduction in underlying popularity of the product?
Intrigued to hear that some Spode production has been reshored to Stoke. Previously it has been said that the Stoke factory was not able to produce some types of china products - I hope that the investment in the plant and staff will continue to improve ability to reshore work and improve operating efficiences.
For me this is all about the margins. Very little sales growth needed - more about high gross margin product mix - so the continued launch of successful new products is key - as is the continued improvement in operational efficiency at Stoke and Wax Lyrical.
I previously caught Portmeirion (LON:PMP) in 2009 close to lows and it 10 bagged from there. Not saying it will happen again but the operational gearing is very high and only improved by the continued investments in plant and premium product.
Two broker notes out today, the shore capital (house broker - so effectively the market expectations referred to by management) note is free
https://www.research-tree.com
Seems that Portmeirion (LON:PMP) is still unloved by todays price reaction? No problem. That's just the way I like it.
Actually I'd quite like the share price quite a bit lower please. Am holding off adding in the hope that the share remains out of favour for a few months yet. So don't all pile in now :-)
10% margin (management has long touted 12%+) on £110m turnover would be £11m operating profit -
around 60p eps post tax -
not too demanding a medium term result? Share price at historic 12x would be around 720p up over 3x from today? For me - I think that's a conservative view! Clearly others differ.
Research note from Singer (can't see it as required a paid subscription) summary seems to agree as they note the NAV of 380p and that it's on arond half its long term average rating and that its a 15 year low with a much leaner cost base. Moves from Hold to Buy.
Just a few thoughts - could easily be wrong. Sadly I'm wrong more often than I am right. But it's what happens with the ones that work that counts for me?
Chasing a past 10 bagger is statistically not likely to work (see the excellent recent article by Mark Simpson). But the numbers don't reveal the work underway to improve the cost base and products - just because it's unlikely doesn't mean it can't happen. The current share price entirely discounts the turnaround being formed? But probably one for the contrarians, like me?
cheers
Mark
Thank you for that comprehensive comment on PMP illiswilgig, I'm a contrarian too, we've had more modest success with PMP than you've had previously with their shares and I've been monitoring them for a while for an entry point. Paul's given it Amber today and Planet X has given their FD some classic tips but imo that overlarge stockpile is going to see some financial breakage in shifting it. Good luck to you and other holders.
AIM flat year on year
I’m sorry to hear you’re finding it tough. Anyone investing across a mature selection of UK small and mid caps would hope to be up more than 20% YoY given the poor sentiment last September. The 50 or so UK stocks that make up a quarter of my fund have an average market cap below GBP1bn and are up c.25% YoY - and that would be 33% were it not for recent volatility. It’s the best performing geography this year for me. Why the fixation with AIM unless you’re letting the tax tail wag the capital dog?
And another - Accsys Technologies (LON:AXS) abandons the Hull Tricoya plant
https://www.accsysplc.com/app/...
As you say there are loads of bargains available in UK small caps. The only constant is change and they will have their day in the sun. As to when I don't know, but it will happen. Patience required.
Consistent with my earlier posts I have been buying/adding to the likes of Ramsdens Holdings (LON:RFX) Sanderson Design (LON:SDG) Eurocell (LON:ECEL) and Kier (LON:KIE).
For what its worth my largest positions remain fairly consistent Volex (LON:VLX) Avingtrans (LON:AVG) Sigmaroc (LON:SRC) Jet2 (LON:JET2) Property Franchise (LON:TPFG) and Journeo (LON:JNEO) . Year to-date, not exact but up around 15%. With a little good fortune helped by declining interest rates I hope for a much better performance come the year end.
It will be interesting to see what impact if any the 0.5% interest rate cut by the Fed has on the UK market
AIM really has a remarkable track record ,from 1000 at inception in 1996 to 742 , 28 years later. There surely can't have been a worse index anywhere in the developed world . However it's this kind of past performance which usually creates the biggest undervaluations. So many good companies on AIM available on single digit PE's, and that's with the economy probably operating below potential thanks to restrictive monetary policy
Morning jesseowens,
Exactly right. As Graham & I have demonstrated with our 2023 and 2024 shares ideas lists, if you screen out the rubbish, and focus on the good companies, you can make smashing returns from a portfolio of UK small caps, even in a flat/down overall market.
It's all about stock selection, and avoiding the (usually fairly obvious) banana skins, whilst accepting that a few things will go wrong, that's inevitable. But running the winners should more than offset the odd mistake.
I find saying no to about 90%+ of the share ideas that crop up, is a good discipline.
Avoiding stories, and just focusing on decent quality companies, churning out in line or ahead trading updates, with sound balance sheets having no need to raise more equity, little to no debt, etc. All basic stuff, that works!
And the dismal index, and investor dismay, just hands us buying opportunities if we're selective. I'd much rather carefully sift through a bombed out market, than chase glitzy glamour stocks in the US.
Horses for courses though, as my mentor always says, "Just do more of whatever works for you!"
Regards, Paul.