Small Cap Value Report (Thu 2 Feb 2023) - PRV, PCIP, SFE, SCS, SDRY, JHD

Good morning from Paul & Graham!
Today's report is now finished.
I've got to finish early today, so have started early, and will rattle out as many sections as possible! Anything missed today, I can always look at tomorrow.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Porvair (LON:PRV)
616p - mkt cap £285m
Porvair issued a positive trading update (“ahead of market forecasts”), which I briefly mentioned here on 9 Dec 2023. Key points were: revs up 18% (5% from forex), EPS ahead of forecasts, and net cash of £18.1m. That triggered a big vertical move up in the share price, some of which has since scrubbed off.
Here’s the latest news -
FY 11/2022 Results
Revenue up 18% (as expected) to £172.6m
Adj PBT £19.4m (up 31%) - impressive.
Adj basic and diluted EPS 23% higher at 33.2p (adjustments look only small)
Net cash £18.3m
Total divis for the year 5.7p - less than 1% yield, seems stingy, given plenty of cash, and this is only 17% of earnings. Why does the company need to hang on to the bulk of its earnings, I wonder? More acquisitions, possibly?
Outlook - comments a bit mixed, which is probably why the share price has moderated a little in recent days -
"As we move into 2023 the Board sees some reasons for caution in the near-term: supply chain dislocation, while diminishing, requires vigilance; inflationary pressures continue; the wider economic picture is uncertain and there is a likelihood of currency headwinds.
However, the Group order book finished the year at record levels despite clear signs of lead times returning to normal; the aerospace outlook is healthier than it has been since 2019; the petrochemical orderbook is encouraging; and recent new product introductions will support growth. Consistent investment in productivity over the last five years is improving operating margins and a strong balance sheet will support continued investment in 2023.
Porvair benefits from global growth trends including tightening environmental regulation; growth in analytical science; the need for clean water; carbon-efficient transportation; the replacement of plastic and steel by aluminium; and the drive for manufacturing process quality and efficiency. These trends have supported a consistent medium and long-term growth record and the Board is confident that this can continue."
Webcast - here’s the link for the video presentation, click on download, then input your contact details, and a video presentation comes up, with slides and commentary from the Directors. Very useful, thanks to Buchanan for making this available, very helpful. I very much like to hear management of all companies talking through the numbers & outlook in their own words. It often helps clarify in my mind: what the company does, and its outlook, and a feel for who management are, and if I want to back them or not. Although a generic warning is that the most “impressive”-sounding people are not always the most impressive performing! Although in this case, I think CEO Ben Stocks has a strong track record.
Pension deficit - the all-important actuarial valuation was completed in the year, and annual deficit recovery payments have increased to £2.1m (previously £1.6m), which is a significant although not excessive drain on cashflow, hence probably why the divis are not generous. This requires a downward adjustment to valuation, I feel, since the PER does not factor in pension cash outflows.
Balance sheet - is healthy, with NTAV at £53.2m (being NAV, minus goodwill & other intangible assets).
Given its healthy finances, I do think PRV should be nagged by shareholders to pay out more in divis. It certainly has much higher dividend paying capacity, which I think is more important than the actual yield at any point in time.
Cashflow statement - is healthy. The cash pile grew by £2.9m to £18.3m, after £4.8m capex, £5.0m debt paid off, and £2.5m paid in divis to shareholders. With debt now gone, you can see that the divis could be tripled by redirecting that cashflow in future. It's a decent, genuinely cash generative business.
My opinion - thumbs up from me - this is a good quality business, performing well.
In terms of valuation, it looks priced about right to me. We can’t expect the same strong earnings growth this year, so a forward PER of 19.3x looks up with events to me, and remember the pension cash outflows come out of this, so the adjusted PER would be in the low twenties, but you could argue that the cash pile offsets this, so I'll stick with the 19.3x PER as being a sensible way to value this share.
I think we have to be careful about paying PERs of 20+. That's an earnings yield of 5%. That might have been attractive in the 14 years of near-zero interest rates. But now base rates in the USA look to heading towards 5%, and in the UK maybe 4%, then that's changed the whole valuation dynamic for other assets. There's a risk that investors might chase valuations too high, because we're anchoring to previous valuations. A PER that used to be 20 when interest rates were zero, should arguably be something like 14 now, in my opinion. So be careful with highly rated shares, you might be over-paying!
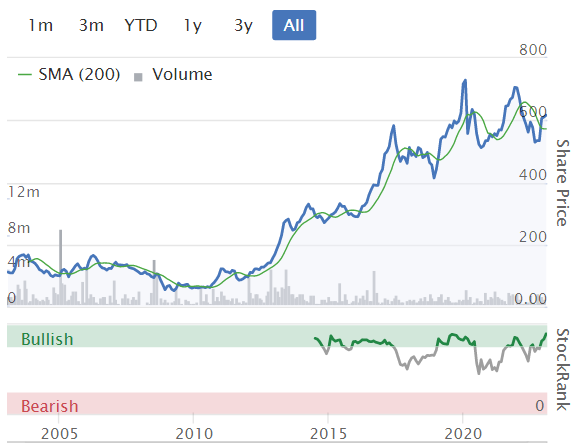
It’s been a 10-bagger since the 2009-10 lows. So for patient investors, I think this looks a decent long-term, core holding.
Stockopedia likes it too, with a StockRank of 89.
Graham’s Section:
PCI- PAL (LON:PCIP)
Share price: 57p (pre-market)
Market cap: £37m
This is a trading update for the H1 period to December.
PCI-PAL is ”the global cloud provider of secure payment solutions for business communications”.
Among other services, it enables customer service agents to take payments securely over the phone.
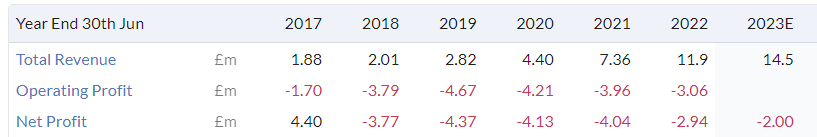
But despite impressive revenue growth over the years, profitability has been elusive:
The outlook for this financial year is confidently in line with expectations.
Here are the H1 highlights, with the EBITDA loss being the same as last year:
“revenue growth of 33% to £7.3 million (2021: £5.5m). Adjusted EBITDA loss for the period was better than management expectations at a loss of £0.6 million (2021: loss of £0.6m).”
116 new customer contracts in H1 contributing £1.5 million of new ACV (contracted annual recurring licence revenue)
I make that an average of £13,000 annual revenue per contract. Given the importance of the product - secure customer payments - it seems quite good value / possibly too cheap? Perhaps the alternative providers also have some very strong offerings, which limits PCI’s pricing power?
total expected annual recurring revenue from all contracted customers increased 29% to £14.7m.
Cash balance: £2.7m currently, although this is boosted by the timing of customer renewals. It was £1.9m in December. The company says it is headed for cash breakeven in H2 (we can presume the income statement will still be loss-making).
Intellectual property: the competition in this space must be fierce, and PCI-PAL and others have been engaged in various patent actions. From today’s update:
In April 2022 the Company announced the grant of its patent in the United States covering innovative integration methods for its Agent Assist solution. In particular this patent covers how PCI Pal's public cloud environment leverages modern voice IP capabilities to integrate to its customers and partners own networks in a light-touch, non-invasive, and cost-effective way. This patent has now also been granted in both Australia (AU2018349164) and, within the last month, the UK (GB2569772) respectively.
But at the same time, the company remains on the defensive, as it attempts to prove the invalidity of a competitor’s patent in a case being made against it.
My view
I’d love to be able to take a stronger view on this, but it strikes me that this company’s eventual success or failure does depend on its IP and whether or not it can defend its IP position. That’s what will generate pricing power and returns over the long-term.
Therefore, while it’s being accused of infringing another company’s IP, it’s difficult for me to have conviction in its long-term trajectory.
I consider the lack of profitability to be a secondary issue for a company of this small size, because its revenue growth is so excellent. So I’m neutral for now, pending clarity on the patent case.
James Halstead (LON:JHD)
Share price: 183p (+5%)
Market cap: £833m
We have an H1 update from this commercial flooring company. H1 PBT will be lower than last year, but expectations for the current year are “positive and unchanged”.
Revenues are up 8%-9% (important to keep pace with inflation, as input costs are up).
This is a very encouraging paragraph, which helps to explain the rising share price today:
In December the Company saw signs of reduced international freight costs and raw material costs. Energy costs remain at historically high levels but have not escalated, nor have our key European raw material suppliers faced production interruption as a result of the energy shortage.
I’ve tried to resist making too many inflation predictions, but I didn’t think inflation was going away any time soon. At least in the short-term, JHD are telling us that some of their important input costs have stabilised or reduced. So that’s some good news.
Additionally, stock levels have reduced (presumably due to confidence in the supply chain?) and that has improved the balance sheet.
In the most recent full-year results, the company said that stock had increased “as we sought to mitigate the risks associated with the potential inability to manufacture.” Inventory rose enormously from £61m to £112m, and this took a huge bite out of their cash balance. So if that is reversing, it’s terrific news from the standpoint of the company’s liquidity and flexibility.
My view
Flooring is not a sector I’ve had much luck with in the past, and I’m unlikely to ever get into it again.
That being said, I have to respect these quality metrics, and JHD’s very long record of profitability.

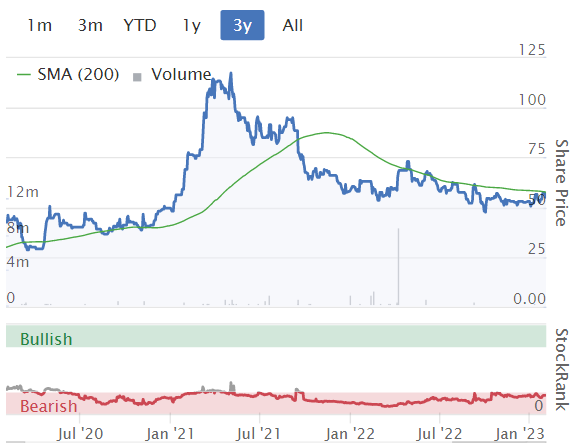
I also note the nice bullish screen that it passes. (For completeness, I should also note that it passes a bearish screen, too.)

Due to valuation, I’m neutral on the stock, but this does appear to be a company worthy of respect and possibly worth looking into as a candidate for long-term investment.
The shares have made little progress in recent years, and no longer appear to be as overvalued as they once did:

Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

24 comments
US markets are up strongly today, Meta Platforms (NSQ:META) up over 20%.
I had a new all-time high today, wonder how long that will last. Took a year to beat the last high.
Dianomi (LON:DNM) A review tomorrow? Yes please, especially with the SP increasing 32%
Re: NCC share price fall today. I would note that Odyssean Investment Trust has a relatively large holding in NCC and is engaging with the new CEO to implement a strategic review. Perhaps the market was a bit disappointed as there are plenty of initiatives mentioned in the results but not sure that this is really a strategic review. As regards the recent Porvair results, I would suggest that the company may not wish to increase its dividend as acquisitions play an important part of its strategy and it may want to retain cash for this purpose, particularly taking account of the company's management which I would describe as encouragingly conservative.
NCC (LON:NCC)
As Paul says in his review of Porvair (LON:PRV) it is good if companies webcast their presentation to analysts. NCC did that this mornng and it was particularly good in that it started with the new CEO (from 1/8/22) giving his impressions from the first 6 months in the job. You can see it here (registration needed).
Viewing "NCC Group Interim Results 2023" (investis-live.com)
....and it hasn't done the SP any harm:
Sorry if this sounds nonesense, i don't comment a lot on here. Just thinking aloud playing with a calculator.
When valuing a company should we be adding the expected earnings yields investors expect in low interest rate times to todays Interest rate of 4%
Random Company:Barratt Developments (LON:BDEV) todays price 471p.
In low interest rate times shareholders were happy with an earnings yield of c.7%
Adding the 4% interest rates today, should a shareholder now want c.11%?
With Est EPS FY23 of 68p this would give a (f)PE of around 6.1. Giving a price of 408p
Not Calculating the 4% interest rate hike into expected returns. A shareholder still aiming for historical earnings yield of 7% would be chasing a price target of 646p.
But, should shareholders accept times are different and lower their earnings yield expectations. What would that 11% come down to?
At todays price of 471 and est EPS of 68p giving a f(PE) of 6.92. Shareholders are expecting an Earnings Yield of 9.8%. Could that be the new norm?
you should adjust expected returns for changes in the risk free rate. ie RFR + stock specific risk premium tells you what you expect a company to return to compensate you from moving out of risk free assets into risky assets. On a like for like basis the latter doesn't change but in practice it does of course as a company becomes more or less risky over time.
But the RFR isn't todays 4% - the 10Y is a better proxy which is currently 3.2%. The 10Y wasn't zero either before this - it was hanging around the 1% level, so your change is actually more like 2% rather than 4%.
Activeops (LON:AOM) hmmm interesting goings on here. Looks like 1.7m shares changed hands at around 85p in 3 tranches. That's a big volume for this share. Unclear when the trades occurred (I presume delayed reporting given size) but price has been moving up in last 2 days so looks like an institution has purchased the holding from someone.
SCS (LON:SCS) trading update today - like-for-like order intake momentum improved significantly throughout the Period and the Group returned to growth of 2.6% in the last 10 weeks, which included the key winter sale.
Estate expansion by opening two new stores in Swindon and York, bringing the total UK store count to 100.
The balance sheet remains strong, with closing cash at 28 January 2023 of £76.9m and no debt.
The Group remains on track to meet full year market expectations.
This looked like an encouraging update today, balance sheet looks robust, on track to meet full year market expectations, dividend should be safe. No comment on margins over the winter sale period, so hopefully those have held up in line with expectations. A little uncertainty re Snugsofa costs / profitability in the short-term, but hopefully a lot of upside with that medium term. Views?
I've held SCS (LON:SCS) for around 18 months. Like the Grand Old Duke of York, the shares marched to the top of the hill then down again. (Or rather the reverse.)
Anyway, the useful point is just how valuable a rock solid balance sheet can be to investors. Rather than having to sell at a loss, I was (and am) happy to hold, meanwhile watching consistent share buy-backs.
A very similar scenario applies to Vertu Motors (LON:VTU) (I hold), and no doubt several other car retailers.
If I had held say DFS Furniture (LON:DFS) with its weak balance sheet, I'd have capitulated into selling in the face of falling sales and a falling share price.
As they (don't) say in Germany: Balance Sheet Uber Alles!
NCC (LON:NCC) half year update, not gone down well with the market, shares down 18%.
Reading the RNS the size of the drop this morning has surprised me unless there is something I am overlooking.
Yes NCC (LON:NCC) did look a bit too much, now recovered to -7.5%.
£ncc its a long time since SCVR have looked at this, its £520m mkt cap now, looks oversold for a mostly cyber company? would be useful if you could review this.
Morning! I don't think we'll have time today for NCC (LON:NCC) , as I have to finish early to get to an investor lunch a long drive away. But it's on the list for possible attention tomorrow, when you'll have my full, undivided attention :-)
Paul or Graham. If you get the chance can you have a look at Polarean Imaging (LON:POLX) as they RNS'd last night at 4.25pm re an FDA approval which is a significant milestone for them. Paul, I believe you mentioned several friends believe this company may be the real deal unlike many small pharma companies.
There is no TU, but some thoughts on balance sheet and funding and possibility of a fund raise would be helpful. I hold a trading position and would expect a spike this morning, but wary this may be used for a dilutive equity raise.
G
Morning greyster,
I had a quick look at Polarean Imaging (LON:POLX) and concluded that it's OK for cash in the short term, but will probably need another fundraise next year. So entirely possible that might happen later this year maybe? So yes, expect more dilution I think. That said, in the past the major shareholders have been supportive, and look credible industry players.
I think the POLX share price has been more a victim of a brutal de-rating of tech/speculative shares, from the inflated bubble valuations of 2021. Maybe some bored or forced sellers? Currently I think sentiment seems to be turning more bullish (whether it stays that way, we don't know), so more speculative shares could be worth considering at the moment. The best ones could recover some of the speculative froth, who knows?
I quite like POLX, and might consider a little flutter on it myself, once I've replenished my speculative pot.
Regards, Paul.
Paul, Thank you for swift response, appreciated.
Greyster
Hello Paul and Greyster, Polarean Imaging (LON:POLX) is doing some excellent work and has passed the test of the FDA, both with the equipment and with the oral gas application.
However, as we saw with Angle (LON:AGL) that is only part of the story. Next, the clinicians and / or the pharmas in the case off Angle (LON:AGL) have to buy into it big time for the funds to flow in and the next stages of development to take place. That hasn't happened with Angle (LON:AGL) and it brings up the difference between research results and clinical confidence.
Angle (LON:AGL) had a massive fund of support from researchers from Europe and the US but if the clinicians / pharmas don't buy in quickly enough.....well, we have seen with Angle (LON:AGL) what has happened.
It also reminds me some time ago of a company called Creo Medical Creo Medical (LON:CREO) which had developed a procedure which was likely to be the next best thing since sliced bread in the field of surgical endoscopy. I bought into it, mentioned it here and took a small holding. I then read comments here soon after from a retired surgeon who made the point that clinicians were very loath to change their behavior, and recommended I think again. I sold out for a tiny loss, and they have since joined the Minus 90% Club.
I wish I had thought about that when the SP of Angle (LON:AGL) were basking in the glory of FDA acceptance, but didn't until much later, to my cost.
Of course, Polarean Imaging (LON:POLX) may be of greater interest to companies like Medica (LON:MGP) who always seem to be complaining about shortage f staff etc and this may be a fillip to take both companies to the next level. Who knows?
My morning smallcap tweet: Magic Mirror on the wall, whch is the cheapest one of all?
Superdry (LON:SDRY) Streaks Gaming (LON:STK) Dianomi (LON:DNM) Peel Hunt (LON:PEEL) Immotion (LON:IMMO) Esken (LON:ESKN) Lords Trading (LON:LORD) £DGS Smarttech247 (LON:S247) PCI- PAL (LON:PCIP) Xpediator (LON:XPD), Ingenta (LON:ING), SCS (LON:SCS), James Halstead (LON:JHD), Safestyle UK (LON:SFE)
◄Superdry (SDRY)► CEO Dunkerton re rumour he considering taking it private, "No plans to do this at the moment.” RNS is a daft "Statement Regarding Superdry Plc". [SP=121.32 Cap=100m]
◄Streaks Gaming (STK)► ad partnership with FanDuel, the no 1 sportsbook in the US. STK is "a GPT-driven conversational gaming platform". How does that work? User: "What's the fastest way to lose money?" GPT3: "The fastest way to lose money is to gamble it away." Actual answer! ChatGPT gives more ways to lose money. including our favourite "Investing in high-risk, speculative ventures, such as penny stocks". [ SP=2.89 Cap=11m]
◄Dianomi (DNM)► guides FY-Dec in line but "recent report from e-Marketer suggested that publishers' advertising businesses are having a difficult start to the year, though indications of Q2 budgets are looking more positive...market forecasts...reduced to show modest levels of growth for this year". [SP=65.5 Cap=20m]
◄Peel Hunt (PEEL)► REX to relaunch as RetailBook with ollaboration with Hargreaves Lansdown, Jefferies, Numis and Rothschild. [SP=107 Cap=131m]
◄Immotion (IMMO)► new 3-year framework with Merlin covering the 26 sites at which Immotion has already installed or agreed to install a VR attraction. [edit] Also to return c.3p/sh and retain 1.5p from sale of Location Based Entertainment business for an EV of c.$25m. [SP=2.2 Cap=9m]
◄Esken (ESKN)► warns FY-Feb EBITDA of £20m £2m below guidance due to biomass plant customers having unplanned outages. [SP=5.9 Cap=59m]. I hold.
◄Lords Group Trading (LORD)► sells Lords at Home biz for £805k. It sells high quality homewares through five branches across West London. [SP=84 Cap=137m]
◄Dillistone (DGS)► guides FY-Dec broadly in line with market expectations before acquisition related items and other one-off adjustments. [SP=NA Cap=NA]
◄Smarttech247 (S247)► the Dec IPO wins contracts worth over $850k. [SP=29.15 Cap=NA]
◄PCI-PAL (PCIP)► guides H1-Dec rev up 33%. Adj EBITDA -£0.6m, better than management expectations. Guides FY in line. [SP=56.01 Cap=37m]
◄Xpediator (XPD)► guides FY-Dec rev c.£400m. Adj pretax expected to be significantly ahead of previous management guidance of £9m. [SP=38.54 Cap=55m]
In line: ING, SCS, JHD, SFE
I tried the immotion thing at blackpool tower (owned by merlin) last september and it was really good !
Kicking myself for having sold out of Immotion (LON:IMMO) with the view that they were exposed to a downturn in consumer spending and might need to fundraise. Lo and behold they've sold the VR attraction part of the business for $25m and plan a massive return of cash to shareholders. Just the sort of snapping up of businesses on low valuations that Paul has been talking about but how to spot them is the question. Up 65% as I write.
Hoping for a better outcome with Tekmar (LON:TGP) (I hold)
Hi Quilleron,
Yes I had Immotion (LON:IMMO) on my "vaguely watching, looks potentially interesting" watchlist.
I don't think anyone could have predicted a sale of the business for a premium price, so this one goes into the lucky tray, for a business that looked at risk of further dilution. A bit like my lucky break with Seraphine (LON:BUMP) - it's important not to congratulate ourselves too much when we get lucky from a risky share, as sooner or later the market will take the money back, when a future risky punt goes wrong, as lots of them tend to!
Regards, Paul.
P.S. Although well done to people who read the RNS early, and bought on the opening bell with IMMO, as that was skill not luck :-) Still worth considering now actually, given that it's intending to repay shareholders 3p, and you can buy only slightly above that right now.
Just looked at Immotion (LON:IMMO) and very tempted to take a (very small) nibble. Buy price currently 3.3p - of which I'll get about 3p back when the sales concludes, so I'm paying 0.3p for a company with a residual market value of about £1.5m that has some interesting products and £6.5m in cash? Superficially at least not expensive, if management make good use of that cash.