Small Cap Value Report (Thu 2 May 2024) - KITW, IPF, SNWS, RCH, KINO, SCE, AGFX. Briefs: TIFS, SHI, HSW, AXS, PGH, NAH

Good morning, it's Paul & Graham here as usual!
Today's report is now finished.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Companies Reporting
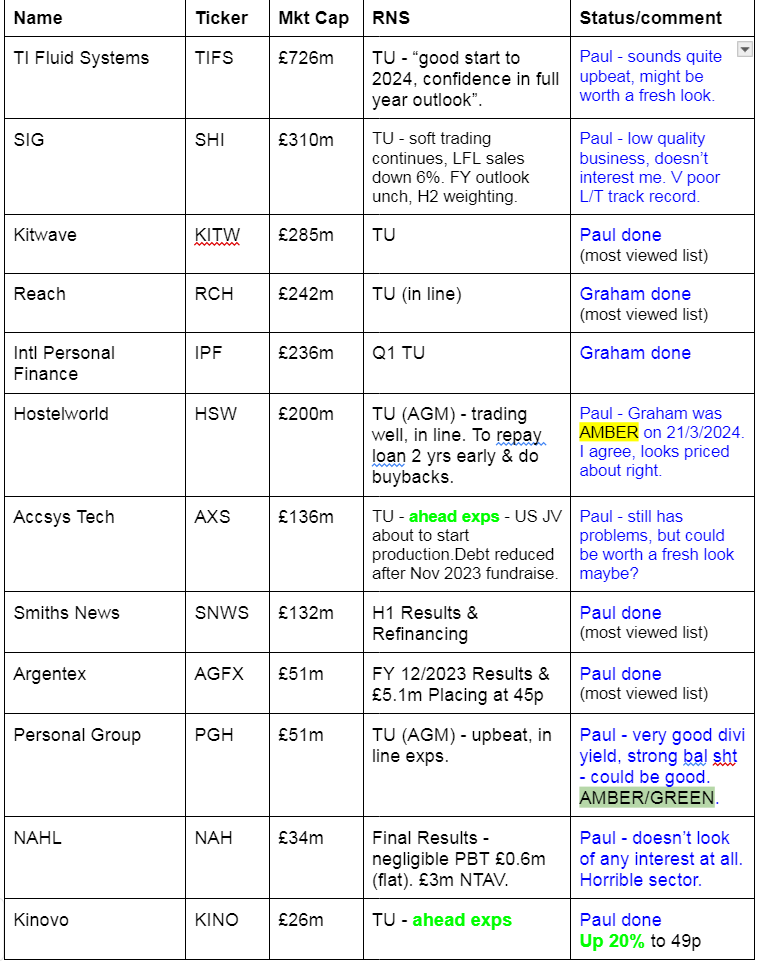
Other mid-morning movers (with news) -
Surface Transforms (LON:SCE) - down 64% to 1.03p - Equity raise at 1p - Paul - RED
Disastrous, but not entirely unexpected news last night of yet another emergency equity raise, following a catalogue of seemingly intractable problems in scaling up manufacturing of its ceramic brake discs.
Today it confirms conditionally raising £6.5m before costs, with c.650m new shares in placing/subscription.
The price was a hideous 66% discount to the already bombed-out 2.9p price beforehand.
There’s another 200m shares available to existing shareholders in an open offer (1 new per 1.76 existing shares). The current market price is 1.0p bid, 1.05p offer, and there seems to be plenty of buying today at 1.05p looking at the printed trades, so obviously a large sell order must be working in the background.
The new share count would look like this -
Existing shares: 352m
New placing/subs: 650m
Open offer: up to 200m
Total: between 1,002m - 1,202m, depending on take up of open offer.
Market cap at 1p = £10-12m.
David Bundred, Chairman of Surface Transforms commented:
"The Board obviously regrets the circumstances that have led to this distressed fund raising and completely understands the frustration and anger of shareholders. The Board is however now confident the combination of this £6.5m Placing, the £2m Open Offer and the £13m local authority loan is sufficient for working capital and capital expenditure needs over the next few years.
Trouble is, does anyone believe this latest assurance? I don’t. With this being very much the last chance saloon, I imagine any further cash requirements could result in de-listing, or insolvency.
Directors are subscribing for trifling amounts, and will only own 2.3% of the company after this fundraise. Interests clearly not aligned, with so little skin in the game. Performance hasn’t exactly been scintillating either.
Paul’s opinion - there are two ways of looking at SCE -
Bulls: With the existing equity now valued at only £3.5m, then new investors are getting the IP and the business opportunity for virtually nothing. If this project works, then the 1p investors could end up with a multibagger, due to the large pipeline & order book for what does seem an exciting product that is in demand.
Bears: So far, SCE has not been able to actually manufacture the product at any scale, beset with a catalogue of production problems. So why would all these problems suddenly get fixed, and with only £6.5m?
Overall, I think this is best seen as a complete punt, with money you can afford to lose. I have no idea how it will turn out, but personally I’m not optimistic, given the history. So I’ll stick at RED, and only move up once we have firm proof that production problems have been resolved. Then you could be onto a multibagger, so I can see the speculative appeal. I might buy a scrap, just so I can say “I hold” if it does multibag! It’s pure punting at this stage.
Argentex (LON:AGFX) - down 21% to 35.6p (£40m) - Fundraise & FY 12/2023 Results (profit warning?) - Paul - AMBER
Argentex Group PLC (AIM: AGFX) ("Argentex"), the provider of currency management and payment solutions to international institutions and corporates…
Proposed fundraise - at nil discount, 45p. I wonder if the investors might try to renegotiate, given today’s share price slump to 35.6p? Dilution not too bad, at 10% enlargement. Some existing large shareholders have indicated support, as have all the Directors.
FY 12/2023 Results - revenues down 1% to £49.9m. Profitability is confusing, as the LY figures are 9 months due to a change in year end. EPS is down, at 4.6p for 12m vs 6.2p for 9m LY. Note the tax charge is much higher in 2023 vs LY. I have to say, these numbers are not as bad as I was expecting considering the share price has been in freefall. Going concern statement is clean. Balance sheet looks fine to me, I don’t see any need to do a fundraise from the Dec 2023 figures, showing cash of £33m. Although the commentary mentions net cash as being £18.3m, so there must be some items netted off against cash. Ah yes here it is, they deduct £14.7m of client’s cash.
Outlook sounds problematic - saying FY 12/2024 is guided for revenues down about 10% to mid-£40s millions, and an EBITDA margin only in “low single digits”. After that, it says revenue growth would only be in single digits, but EBITDA margin increasing to high single digits. The fundraise will allow it to accelerate new product development, raising both revenue growth and EBITDA margins. I don’t have access to any broker research, and am not interested in spending the time building my own spreadsheet to work it out.
Paul’s opinion - it does look cheap, but that’s because it’s clearly being left behind by better performing rival Equals (LON:EQLS) . There are some very good reader comments below from people who have more experience of this sector than me, which reinforce my existing view that profits in this sector look quite flaky, with probably very little sustainable competitive advantage for anybody. After all, it’s only moving money around, so a race to the bottom on margins looks inevitable once rivals have caught up with any technical or service advantages. AGFX seems to have slipped behind rivals, and is paying the price, with profits collapsing. That makes me even more wary of this sector generally.
A more bullish view on AGFX might say it’s well financed (especially after the placing, if that goes ahead), and the market cap is now very modest. So if new management can get their act together, you could have a nice recovery trade on your hands. I don’t feel qualified to judge, so will sit on the fence with AMBER. I could be tempted to have a small flutter though, if spare funds emerge.
Summaries of Main Sections
Kitwave (LON:KITW) - 407p (pre-market) £285m - H1 Trading Update (in line) - Paul - AMBER/GREEN
An in line update for the full year, but it says H1 was soft due to bad weather affecting its hospitality-facing business. Larger than usual H2 weighting expected. With the shares up c.60% this YTD, I suspect some profit-taking is to be expected for now the valuation looks up with events. So I've shifted down a notch from green to AMBER/GREEN.
International Personal Finance (LON:IPF) - up 2% to 108p (£243m) - Q1 2024 Trading Update - Graham - GREEN
A pleasing update from subprime lender IPF with the company growing well, excluding Poland. Importantly, the impairment rate is below the level expected at this point. At a PE Ratio of only 5x and a dividend yield of 10%+, the risk/reward for IPF’s equity could be even better than its 12% retail bond.
Smiths News (LON:SNWS) - up 3% to 55.2p (£130m) - H1 Results & Refinancing - Paul - GREEN
A slight reduction in forecast profit FY 8/2024. However, outweighing that is the confident outlook, and bank refinancing that saves c.£0.4m pa in interest costs, and removes all restrictions in divis, allowing a c.20% rise in divis to a yield getting close to 10%. I think it's still good value, although we do have to bear in mind it's not likely to ever get a PER any higher than mid single digits probably.
Reach (LON:RCH) - up 7% to 79.8p (£254m) - Trading Update - Graham - GREEN
This update is “in line”, despite all metrics appearing to move in the wrong direction and a stunning 33% decline in page views. But the consensus operating profit figure for FY 2024 is a remarkable £97.6m. If Reach hits this target without putting too many costs into its adjustments, the stock is likely too cheap.
Kinovo (LON:KINO) - up 20% to 49p (£31m) - Trading Update (ahead exps) - Paul - AMBER/RED
Profit is £0.5m ahead of expectations for FY 3/2024. Legacy problems are gradually being resolved, and haven't got any worse this time. Balance sheet is weak, and creditors look stretched, so I think it needs an equity raise, and won't be able to pay meaningful divis for a while. Not enough upside to compensate me for taking the risk. Although I've moved it up from red to AMBER/RED, to reflect that things are improving.
Paul’s Section:
Kitwave (LON:KITW)
407p (pre-market) £285m - H1 Trading Update (in line) - Paul - AMBER/GREEN
Kitwave Group plc (AIM: KITW), the delivered wholesale business, today announces a pre-close trading update for the six-month period ended 30 April 2024 (the "Period').
It’s in line for the full year -
The Board is pleased to report that the Group continues to trade in line with current market expectations for the full year ending 31 October 2024. This performance will reflect both continued organic growth and the benefit from acquisitions made over the past 18 months.
However, H1 sounds soft - which I find a bit confusing -
Operating profit performance during the Period is expected to be slightly behind the prior year.
Due to -
Wet weather this year causing demand to drop in the higher margin foodservice division (hospitality sector).
“Increased investment in its infrastructure”, before benefit kicks in for H2.
H2 weighting being larger than usual this year probably won’t go down well with investors I suspect, especially after the shares have had such a good run recently -
Some of the benefits of these investments, in addition to the H2 inclusion of trade from the recent acquisition of Total Foodservice, will further increase this year's weighting of trading toward the second half of the year.
Acquisitions - 2 have been done, integration is going well. I like the acquisitions strategy here, as KITW buys what it knows, and uses that to fill in geographic gaps. It also mentions a “fragmented market”, so that sounds ideal for consolidation.
Overall - nice to know they’re confident -
Overall, the Board remains confident in the outlook of the Company.
"I am pleased to report that the Group has continued to make progress towards its operational and financial targets and that we remain confident of achieving a positive outcome for the full-year results.
Broker update - Canaccord helpfully updates today, leaving forecasts unchanged. It reckons 29.9p adj dil EPS for this year FY 10/204, only 4% up on LY actual, so that should be achievable. It also points out that there is a natural H2 weighting to profits at KITW every year.
At last night’s close of 407p, the current year PER is 13.6x, which looks about right to me.
Paul’s opinion - I’ve not looked at the share price yet, but suspect some shorter term investors might be tempted to bank profits after a very strong recent run. I think it’s gone from cheap, to fairly valued now. I was green on 28/2/2024 at 297p, but given we’re now being asked to pay 407p, for me that means it needs to come down a notch to AMBER/GREEN - nice company, but valuation up with events for the time being.
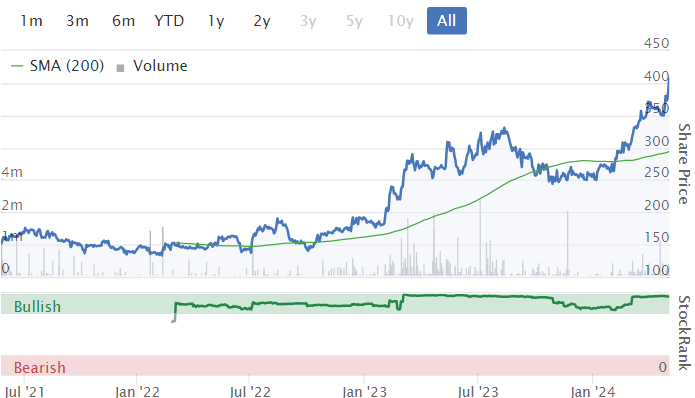
A successful 2021 IPO, and note that StockRanks like it, with a high score of 95 -
Smiths News (LON:SNWS)
Up 3% to 55.2p (£130m) - H1 Results & Refinancing - Paul - GREEN
Smiths News (LSE: SNWS), the leading distributor of newspapers, magazines and ancillary services to retailers across the UK, today announces unaudited interim results for the 26 weeks ended 24 February 2024 (the "period" or "HY2024").
The key highlights section covers the main points well -
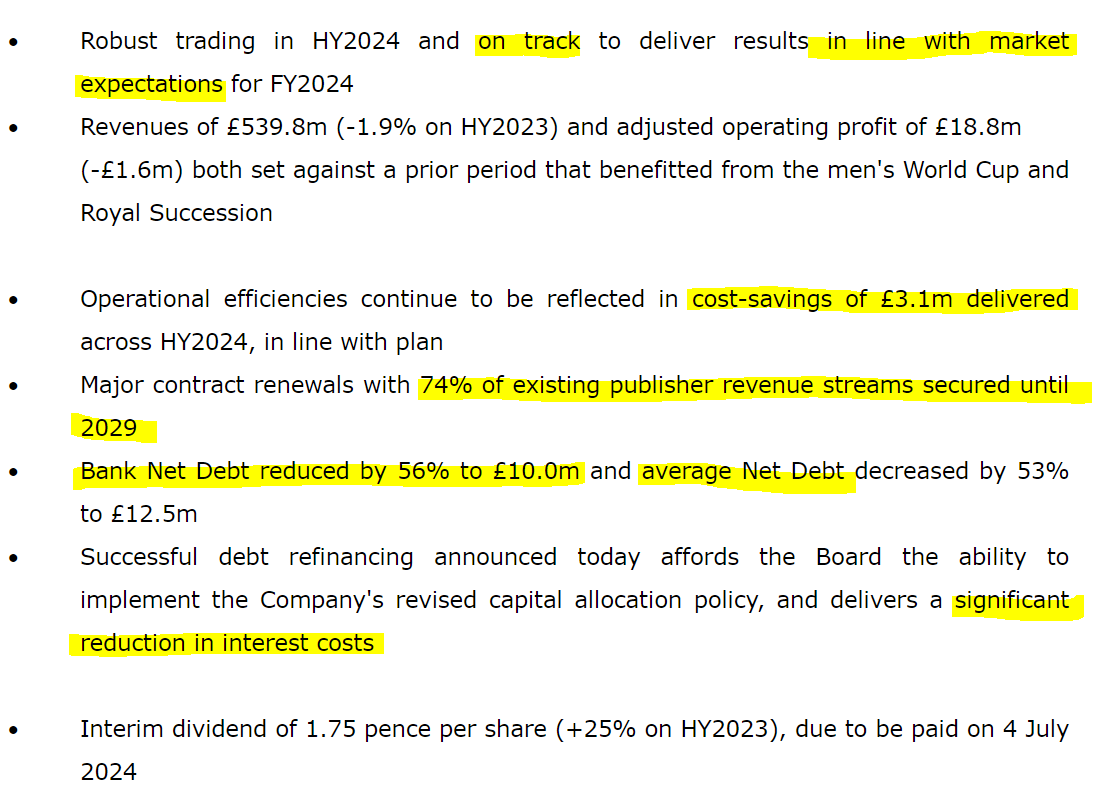
H1 EPS is down 12.5% to 4.9p - not great, as I was expecting profitability to be roughly flat.
Clean numbers, with hardly any adjustments.
Broker update - thanks to Canaccord, who trim FY 8/2024 from 10.0p to 9.8p. However, they’ve slightly raised the next 2 years, due to lower finance charges from the refinancing also announced today.
Valuation - PER of 5.6x FY 8/2024 earnings - low PER is because this is perceived as a slowly dying business, much like newspapers themselves, although both are lasting a lot longer than we thought maybe 10-15 years ago! And remaining strongly profitable too, thanks to round after round of cost-cutting each year.
Bank net debt reduction - great news here, at only £10.0m period end bank net debt has more than halved, not far from being eliminated altogether it seems (although there are likely to be large intra-month swings, depending on when a few big customers pay up, and SNWS itself does its payroll and supplier payment runs.
A big thumbs up for SNWS also reporting its Average Bank Net Debt of £12.5m. It’s wonderful to see a few companies beginning to report this key number, which gives a much more accurate view of the real world typical level of indebtedness. Bravo! Let’s see this from all companies please.
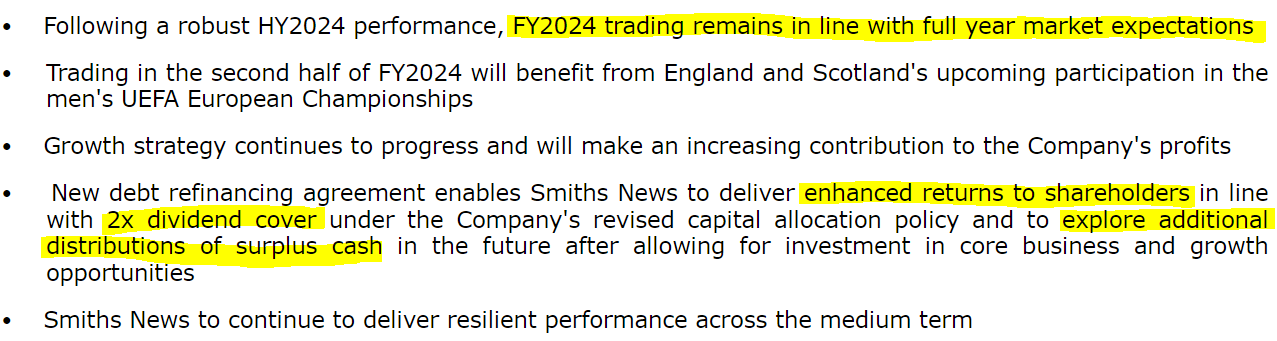
Outlook - sounds good I think - especially the prospect of bigger shareholder returns, although we already knew that looks achievable in future -
Balance sheet - was always this company’s weakness, but it’s reasonable now, with NTAV negative £(16)m, so it does still need a bank facility to plug that equity gap.
Cashflow statement - looks fine. Cash generation is used to pay interest and dividends basically. The larger cash pile last time was used to pay down £15m of a term loan. Although also note a hefty £3.3m was spent on buying shares for the employee benefit trust in H1, quite a large % of H1 profits are being given away to employees (probably management mostly) in this way.
Refinancing - revised bank facility with 2 of the existing syndicate lenders, HSBC and Santander.
£40m RCF + £10m “uncommitted accordion facility” - from googling the “uncommitted” term, this seems to be where the lender has discretion on whether or not it grants a request to use the accordion facility.
Useful saving in interest cost, new: 2.45% over SONIA, old: 4.0% over SONIA. Average net debt was £12.5m in H1, so this means a saving of about £194k in future interest cost per half year, so c.£0.4m interest saved in a year.
Three year term.
Key point - removal of restrictions on paying divis (previously capped at £10m pa, or c.4.2p/share pa)
Dividends - Canaccord reckons it’s likely to pay 5.3p in FY 8/2025, so that’s a lovely yield of 9.6%, twice covered by earnings.
Paul’s opinion - a superb turnaround which we’ve followed closely, and positively, here at the SCVR for quite a few years. It’s panned out exactly as management said it would.
The business seems more resilient than previously expected, and the finances are basically now sorted out and on normal, competitive terms.
It’s very tempting, now the yield is close to 10%, and it should be able to pay that for several more years to come.
I’d like to know more about the growth initiatives, and there’s scope for a possible upward re-rating if the distribution network can be repurposed in some way.
I have to remain GREEN, as the valuation is still attractive, although not as absurdly cheap as it has been in recent years after good gains more recently.
Kinovo (LON:KINO)
Up 20% to 49p (£31m) - Trading Update (ahead exps) - Paul - AMBER/RED
Kinovo Plc (AIM: KINO), the specialist property services Group that delivers compliance and sustainability solutions, is pleased to announce that it expects its results for the continuing business in the year ended 31 March 2024 to be ahead of prior expectations. Numbers presented are subject to audit.
Quite an interesting share, that I covered on -
9/2/2024 - RED at 55p - in line TU, but big legacy issues. Not cheap enough.
8/3/2024 - RED at 39p - core business trading in line, but legacy problems worsen again. Weak bal sht, so risk of dilution. Possible recovery trade maybe?
The core business actually looks quite good, and is profitable, but there are some major legacy issues relating to its accident-prone former subsidiary in building works, which requires expensive rectification work. The risk was that the bad legacy business liabilities could pull down the continuing, quite good business, so I flagged it as red previously due to the high risk.
Today’s news is encouraging, although I don’t think it justifies a 20% rise in share price just for beating EBITDA exps by £0.5m -
The Company expects to report an adjusted EBITDA, for the continuing business, of £6.7 million for FY24, 23% ahead of previous year (FY23: £5.5 million) and ahead of prior management expectations of £6.2 million, as disclosed on 9 February 2024, for the full year ending 31 March 2024.
Some work has slipped into FY 3/2025 due to client delays, but it says this was previously disclosed.
Legacy problems update - relating to DCB. 7 out of 9 sites have now been rectified. The 8th site is due to be completed in July 2024. Leaving 1 remaining problem site due to complete in 2026, so ongoing risk there for a couple more years, isn’t ideal. Says the liabilities are as disclosed on 8/3/2024, so it sounds as if these big problems are now largely resolved, we hope. Although Canaccord says the remaining costs are a hefty £8.6m.
Broker update - another note from Canaccord, they’re really being tremendously helpful today! It leaves forecasts unchanged, but at £0.5m below the company’s EBITDA guidance, so these figures are now understating reality, at £5.8m adj PBT, and 6.9p EPS.
Paul’s opinion - this type of business would usually attract a fairly low PER of maybe 10-12x. On 6.9p EPS that gives me a target share price of 69-83p, usefully above the 49p share price after today’s 20% surge. However, we need to deduct the cash costs of the £8.6m remediation costs on legacy mistakes, which I make 13.7p/share. That narrows the gap, to a target share price of 55-69p. That’s not enough upside to motivate me to want to buy at today’s 49p. Particularly when there are still risks here. Looking at the last balance sheet, I think the finances here are stretched, so it could do with an equity raise to repair the negative NTAV £(3.4)m balance sheet.
Given that trading is a little ahead, and the legacy problems are gradually being resolved, I think it might be safe to move from red to AMBER/RED. Good luck to holders, but personally I don’t see enough upside reward to get me interested in buying a fairly ordinary business, with legacy stuff still hanging around, when there are cleaner, better financed shares around on more attractive valuations.
I've just remembered that the major shareholder (just under 30%) tried to take it over at 56p in Aug 2023, but that fell through.
Graham’s Section:
International Personal Finance (LON:IPF)
Up 2% to 108p (£243m) - Q1 2024 Trading Update - Graham -GREEN
It’s a positive update from this lender:
Lending growth of 5%, excluding Poland (total lending down 3%).
Net receivables growth of 11%, excluding Poland (total receivables down 3%)..
“Robust customer repayment performance and excellent credit quality supports the Group's plans for stronger lending growth through the remainder of the year.”
As you may know from our previous coverage of this stock, new regulations (and different interpretations of those new regulations) have severely impacted IPF’s operations in Poland. Today the company reiterates its previous guidance that the situation in Poland will result in a £10m p.a. hit to profitability. Receivables in Poland are down 33% year-on-year.
CEO comment:
"We've made a very good start to the year and are progressing well against our 2024 financial plan. We delivered good customer lending and receivables growth in all our markets with the exception of Poland, where our actions to adapt our home credit business to the changing regulatory backdrop continue.
Credit quality remains excellent across all parts of the Group, and this provides us with a strong foundation to accelerate growth through the remainder of the year and capture the substantial long-term growth opportunities through delivery of our Next Gen strategy.
An important feature of IPF’s growth plan is that they are willing to allow their levels of impairment to rise, voluntarily taking on some more risk as a price worth paying for growth.
Fortunately their latest impairment rate (11.4%, up from 10.5% a year ago) is still “tracking better than our financial plan”, meaning that they can carry on with their intended growth plan for the rest of the year.
Romania, Hungary, Czech Republic: these countries, in the absence of any regulatory issues, saw an aggregate 9% year-on-year growth in their receivables.
Mexico: 8% growth in receivables. Impairment rates are very high in this country (31.3%) and IPF wants to see an improvement to 30% (still very high!).
IPF Digital: 7% growth in receivables, with very fast growth outside Poland (17%).
Funding: IPF has a bond maturing in November 2025 - see here. They are now looking at options to refinance it. The bond trades at 98 euro cents, suggesting to me that bond investors are relaxed about IPF’s prospects!
Regulatory update: nothing new here.
Outlook: concludes as follows:
We have a strong balance sheet and funding position, and are well positioned to deliver further good quality customer lending and receivables growth in 2024 and beyond whilst maintaining our progressive dividend policy.
Graham’s view
The dividend yield here is already over 10%, so it will be impressive if this keeps growing!
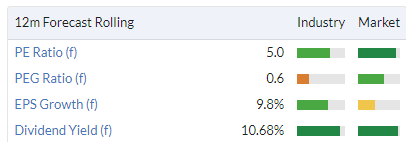
The yield is not the most remarkable aspect of IPF’s valuation, however: it’s the earnings multiple.
In the absence of any share buybacks (and why isn’t the company doing any?) I’d be inclined to reinvest at least a portion of IPF’s enormous dividends in IPF stock - it’s not as useful as a buyback by the company itself, but it’s the next best thing!
I’ve been positive on IPF for quite some time, and I won’t be changing my stance on it today. Flip the P/E around and you get an earnings yield of 20%: that strikes me as attractive for a share that everyone (including myself) will acknowledge does carry more than its fair share of risk, being a subprime lender in foreign locations.
At this market cap I think I would even prefer to buy IPF’s equity instead of its 12% retail bond maturing in 2027 (link).
Reach (LON:RCH)
Up 7% to 79.8p (£254m) - Trading Update - Graham - GREEN
Reach is “on track to deliver full year expectations”.
This is despite the company shrinking from every perspective. Reach describes the performance as “robust”:
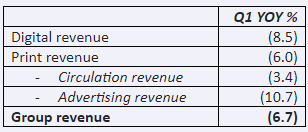
As previously flagged and discussed, news was “deprioritised” by social media platforms in 2023, particularly by Meta/Facebook, who decided that the news category was more trouble than it was worth.
The consequence for Reach is that page views fell by a staggering 33% year-on-year.
Digital: Reach has a “data-driven” strategy, trying to use customer data derived from customer registrations and customer behaviour. Data-driven revenues are now 45% of digital revenues (up from 39% a year ago).
Print: rising cover prices have saved the day here:
“...circulation revenues remain a predictable and reliable revenue stream with the expected volume decline mitigated by actions on cover prices and availability.”
Operating costs: the company is delivering a 5-6% reduction in costs.
Outlook: in line with expectations, being an adjusted operating profit of £97.6m.
CEO comment
Nothing too concrete here, but it’s an insight into management’s thinking:
"We have set the business up to succeed - the decision to take cost action early, alongside the continued implementation of the Customer Value Strategy is delivering a growing yield performance and driving results. This gives me confidence that we can continue to navigate current market conditions. With events like the European Football Championships, Olympics and elections round the corner we have the opportunity to generate high levels of interest by entertaining and informing our audiences with brilliant journalism.”
Graham’s view
I covered Reach’s full-year results in March.
The key point around the pension black hole at Reach is that it is not expected to last forever: Reach has to pay about £60m p.a. until 2027. But from 2028, contributions are expected to shrink dramatically, so that they should no longer drag on the valuation of the company's stock by then.
The phone hacking scandal is also likely to finish up its journey through the legal system very soon, with limited future liabilities for Reach (the remaining provision is only £18m).
Adjusting my calculations in March for today’s market cap, I get an increased enterprise value of c. £540m.
My impression is that management is running a tight ship, with a clear focus on profits and cash flow. Somehow, they continue to generate operating profits at a very high level, and pay a dividend of over 7p (the yield is over 10%!).
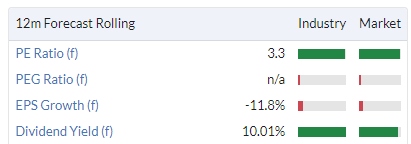
As always, the devil is in the details and I’ll be eager to make sure that they aren’t making large and unreasonable adjustments to their operating profit numbers, every time they publish results.
For now I’m happy to maintain my “thumbs up” position on this stock. It will be a fabulous achievement if they hit their forecasts this year, and it seems that they are on track to do so.
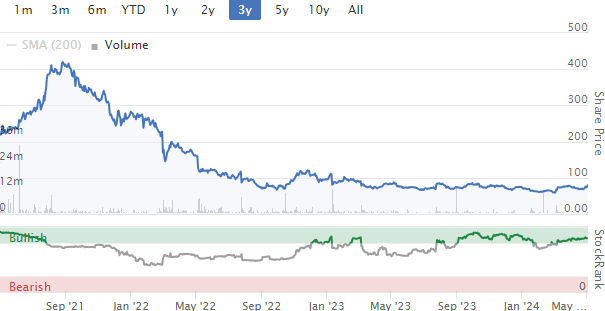
Personally, I view this as an example of a stock where paying the dividend makes little sense for the company. If they don’t think they are going to survive the pension contributions in rude health, they shouldn’t be paying it. But if they do think they are going to survive, then why pay £23m in annual dividends? For that price, they could reduce the share count by about 10% every year!
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

120 comments
Hi Paul,
your podcast is fantastic, and hi to everyone,
So, listening to Paul's Podcast, I heard him speaking about Petrofac (LON:PFC) , and I thought I would put a comment on this (first time). So, about 3 months ago, I was having coffee with an old friend, and he said, "You like stocks". He then went on to tell me that he had just come back from doing some freelance work for PFC. (he is an offshore medic) The company and the share price was in the toilet, but everyone on the rig was told that there was a big contract just about to be signed and they should buy stock in the company. He told me that he had bought shares and other people were using their savings to buy stock.
When I got home I had a look and called him to say I don't think that is a good idea and I would sell them if I was him. I then called him the following week and told him that the share price was down, and I would sell them. He said he wasn't buying any more, but he had spoken to people on the rig, and they were buying more because the price was lower.
I bought £25 just to remind me to keep an eye on it and I was very upset when I saw it finally go. Not for my £25 but for the people in that company who have been told that the is a contract that coming and they should buy stock. If you don’t know you shouldn’t get involved and you should definitely not give out advice.
So, I just want to remind people to make their own judgment, do their own research, and don’t bet their life savings on it.
Again, brilliant Podcast Paul, keep up the great work.
Dear Paul
Zoo Digital is up sixty percent since your critique of the business model looking back to last February I see that you were congratulating holders when the price was around two pounds whereas four weeks ago you seemed critical of the business model when the shares were thirty pence. I know that you do not make recommendations but the commentary seems to change depending on the price - good when it is high bad when it is low - is this common or am I missing something
The performance of a business is usually reflected in the share price, surely thats obvious. So of course when the price goes up 60% it's likely that there are now some positives that were not present previously. The commentary will become more positive to reflect that. It's like saying, you criticised how Liverpool played when they were 5th last season, but now fighting for the title you are saying they are playing well. I thought you said they were not a good team last year.
Dear Tom ..re Zoo Digital (LON:ZOO) I think you may be under at least 2 misapprehensions here:
1 that the share price means something important in the short term
2 that Paul is somehow infallible
Personally I think Zoo Digital (LON:ZOO) is uninvestable..at least until they consummate the Japanese acquisition they raised so much £ for before their business fell off a cliff
Morning Tombholliday,
Yes, our commentary changes with the trading updates. So if a company like ZOO reports strong trading, we reflect that in a better colour code. Then when the wheels fall off, and it looks close to going bust (as more recently) then yes we'll shift down to RED.
I think you're confusing us with tipsters, who try to predict the future, which is not what we do here. We're just reporting on the facts, figures, and forecasts on that day in particular.
ZOO has a weak business model I think. Many years of losses or breakeven, only one year of significant profits during the streaming boom, and then lost its cash pile and almost went bust during the Hollywood strikes. Do you expect me to ignore that, and speculate on a recovery?
We flag up the facts, and you can do the predictions & deeper analysis.
Hope that clarifies, and thank you for raising the question, which is fine - I don't object at all to people querying things., so I hope the moderators don't delete your post, it's a perfectly valid question to ask.
Sometimes high risk, poorly performing shares that we'll have flagged as RED, can do spectacular recoveries, so I hope ZOO manages that. More usually though, stuff we flag as red will continue to under-perform, and even go bust or de-list in many cases. That's why in aggregate, our RED marked shares have done badly, and our GREEN marked shares have done well. (based on data analysis by my pal Phil Hanson)
Paul.
Thanks Paul I struggle with the weak business model though when your supplier can switch you off as Zoo can to Disney because Disney run all the localisation of streaming product through Zoo Studio you have a strong business model - not infallible as was demonstrated by the writers strike but a strong one never the less
You can find all this in the accounts if you are interested
Anyone know what caused the Bank of Georgia (LON:BGEO) share to fall today?
Probably to do with this: https://www.bbc.co.uk/news/wor...
Sold Bank of Georgia (LON:BGEO) today after good gain because of increased political risk.
What goes up comes down, so said the Grand old Duke of York. Timing is the trick.
Appreciate this information managed to sell my shares first thing today before the fall
I sold Smiths News (LON:SNWS) today mainly based on history where the share price hits these price levels and has dropped back. I only bought end Jan '24 just for the yield and did not expect to see athe price increase so fast . So with a 10% gain decided to forgo the yield for now. If it drops back into the high 40p's will buy back in. I could be of course very wrong and the price will continue upwards, but happy with the turn. There are other stocks out there with high yields and possibly better growth prospects.
Warpaint London (LON:W7L) 6m placing by CEO and MD..
https://www.stockopedia.com/sh...
Is this going to mean a price drop for the morning? Hopefully not too bad & chance to top up? Warpaint London (LON:W7L)
I continue to hold Reach (LON:RCH) because I think the market is being a bit harsh with the company.
On the subject of buy backs my head likes them but my heart loves the dividend “cheques”. One can also imagine the headline (and the resulting decline in the share price, if they cut the dividend:
Reach cancels dividend!!
And buried in the text “…and instigates commitment to buy back 10% of the outstanding shares each year”.
Regards
Michael
I'm all out of AGFX, was on tenterhooks and hoped for the best, a restructure and new outlook without the old head, for me isn't a good look. They have to move forward, but currently lagging. The 20% dump hasn't made me want to buy more so as this is only a small percentage of my overall portfolio, I'm out.
There are *currently* better investments out there.
Anexo (LON:ANX) The phrase "sits in debtors ... uncollected" implies that the company has not received the cash payment for a significant portion of its reported profits. This means that while the company has recorded the profits on its income statement, the actual cash has not been collected from the customers. This can be a problem because:
Cash flow: If a company is not collecting its debts, it may face cash flow problems, as it has less money available to pay expenses, invest in growth, or distribute to shareholders.
Credit risk: A high level of uncollected debts may indicate that the company's customers are struggling to pay, which could lead to bad debts and losses if those debts become uncollectible.
Earnings quality: If a significant portion of a company's profits is tied up in uncollected debts, it raises questions about the quality and sustainability of those earnings.
Anexo (LON:ANX) thanks for that Funnymoney - this is funny money indeed!!
I'm really surprised you are allowed to report a profit on a transaction that you haven't been paid for!! This sounds misleading.
It's standard accounting practice.
ref. Anexo (LON:ANX)
Anexo will be at the Mello2024 investor conference along with 40 other companies,,,,six more announced today. They have a stand so you will be able to ask lots of private questions and fully understand how they operate.
Mello2024 investor conference takes place on the 22nd and 23rd May and Stockopedia will be there plus Paul Scott and all the BASH regulars. Do come and join us....another six companies added to the list today and another six to be announced on Monday.
We want to keep this important face to face engagement with companies going and it has been tough since Covid as many directors just want to do webinars as their only token offering to investors. If you want to ask private questions or check out body language it is impossible on webinars and investors need to network with each other too.
Please support us and encourage companies/ management teams you are in contact with to come along to Mello2024 in Chiswick on 22nd or 23rd May
Mello2024 – Mello Events
If you have never been to one of our two day conferences before then clearly you are missing a great opportunity to engage with management teams and also network with hundreds of likeminded investors so we are offering virgin tickets at just £30 for either of the days so that you can see what it is all about.....a big discount from £99.00 and if you do not agree having spent the day with us I will give you an annual pass to our virtual shows on top. I just want investors engaging with all these quality smaller companies. This offer is only if you have never attended before so please be fair to all those who pay much more.... Simply enter the code NEW2MELLO24 BUY NOW: https://www.tickettailor.com/events/melloeventslimited/1201351
Full info on this thread Stockopedia | Mello2024 conference...22nd and 23rd May | By carmensfella
Just a quick comment here - I went to Mello Chiswick in November last year for the first time. I would encourage readers to go - especially if you haven't been before. It was an absolutely fascinating and enjoyable 2 days and really worth the effort to go. The whole event is extremely professional and thoroughly well organised.
If you are umin and aarghin (Norfolkism) then please go, I promise you won't regret it!!
Disappointing that requests by myself and many others for a Northern venue have seemingly been ignored .
They have not been ignored at all and do remember the Mello conferences started in the East Midlands nearly ten years ago and we have held them in four venues away from London. Since the pandemic we have been trying to find our feet and get the attendances back to where they were so London has been the only viable option for us. However stay tuned as our 10th anniversary event is planned for back in Derby in November. So not ignored at all. We do need as many investors as possible to join us and show companies that face to face engagement is very important
Great news, thank you.
Card Factory (LON:CARD) share price almost given up all its gains since the positive update this week…. Very surprised given the reinstatement of the dividend
I'm not really surprised, look at the range over the past year. There are some large holders, who have reduced in the last 14 months. Maybe they are selling in the background? I sold half of my Card Factory (LON:CARD) at 110p, should have sold them all. Why does the dividend matter?
Card Factory (LON:CARD) Potentially introducing the stock to a different type of investor / income funds ?
Personally not bothered too much about dividend, but should bring in lots of new income investors. Also shows that the company is confident about its debt position. Reintroduction of dividends usually leads to share price bounce, so surprised no reaction with £CARD
I see Marshall Wace LLP - hedge fund - has a 0.51% short position on Card. I honestly don't know what Card has to do to convince the market that it's a worthwhile investment. Recent results speak for themselves and yet the SP continues to drift. I do question my judgement at times, but for the life of me I cannot understand why Card is so cheap. Maybe we are just going to have to be patient and wait for Telios to foxtrot oscar?
Card Factory (LON:CARD) This has been the pattern for at least the last year or so - weird falls on strong trading updates. No idea what's going on in background but seems very strange, as seems to be trading well and very cheap. Fairly confident value will come through in the end, but a fair bit of patience required with this one. Apparently Marshall Wace increased their short position yesterday, but scratching my head as to their rationale.
Aren't they a quant firm?Could just be part of some more overall strategy involving hedging and who knows what 'sophisticated strategies'.Although maybe they're just long Moonpig (LON:MOON).They state they're a long/short equity outfit predominantly on their website.Paul Marshall is also funding GB news' losses still.He's got his hands in a few pies.
Playing around with the numbers on Card Factory (LON:CARD) the table below is an indicator alone of potential dividends for FY ending 24-27. In short, your investment in 1 share of Card today should, according to my calcs, yield a dividend of 22.6p - 40.6p per share.
My assumptions were to bridge the 2024 FY to the 2027 forecast, with margin improvement to 14%, a 25% straight Corp tax rate; and an increase in shares in issue of 2m over the period. Dividend cover of 2-3 times then gives a range per year of the potential dividend pay-out with x2 being divi's covered twice to EPS and x3 covered 3 times - hence x3 is the lower dividend.
Food for thought.
On the topic of share buybacks, I would have thought Reach (LON:RCH) was one company where dividend distribution made good sense.
But Graham today writes “Personally, I view this as an example of a stock where paying the dividend makes little sense for the company. If they don’t think they are going to survive the pension contributions in rude health, they shouldn’t be paying it. But if they do think they are going to survive, then why pay £23m in annual dividends? For that price, they could reduce the share count by about 10% every year!”
I’m not sure I follow the logic….I’m happy to take the dividend (in an ISA) because the business itself is potentially in slow structural decline. I would rather takes 10% cash per year than end up with a bigger share of a company that is slowly dying. So the buyback/dividend argument must vary significantly between growth and value companies, I would have thought?
Dave
Reach (LON:RCH) should be reducing their debt and pension deficit rather than paying the money out to shareholders, IMO. Then they would be more likely to survive?
Reach (LON:RCH)
Sorry what debt Rusty?
They are broadly neutral on net cash.
You will find the actuarial numbers look very different when the triennial is actually updated and of course they are also filling that theoretical void over the next 3-4 years.
Hi David
They did have a small debt in their last published accounts.
Reach (LON:RCH) I am with Graham on this one - if they feel that they will survive they should start a buyback programme and cancel the dividend. Paying a dividend and then looking at the share price in a year much lower it is just bonkers. Perhaps a closer look over the pond will help on how CEO’s actually create shareholder value!
All the best
Hi Yiannos - with a share buyback though, how does one know that the share are going to be cancelled? If they aren't cancelled then you lose out both ways. (@Reach (LON:RCH))
Hi Dr Dave
Obviously we do assume they will be cancelled and enhance EPS.
All the best
Re: share buybacks. It sounds a little risky though just to assume they will be cancelled, if in fact they can also be held and used? Is there a legally-binding directive to cancel given at the time of the RNS?? If not I would prefer to have the cash myself rather than assume that directors will cancel all the shares bought back.
Is it perhaps one of the reasons why buybacks have become so fashionable, that it gives directors a couple of different options??
I am suggesting a scenario that reduces the sharecount and enhances EPS
We should not assume that the directors will cancel the shares that the business is buying back. Have they said that they will cancel them? If they have not said this then it very likely that they will give the shares to themselves as part of some cleverly disguised plan that they hope most of the owners of the business will not become aware of. Then they try to impose further deception upon us by claiming that the cost is an exceptional adjustment, that should be excluded from the adjusted EPS. In reality it is nothing like exceptional because it happens every year.
They might instead pay cash bonuses or issue new shares to cover LTIPs. Not sure either of those is better for shareholders than using bought in shares? It certainly doesn't make buy backs a sinister plot!
I am struggling to understand the logic behind this conversation.
Buybacks are announced and they state clearly in the RNS if the shares bought are going to be cancelled or not.
Graham has made a suggestion that Reach (LON:RCH) can buy about 10% of its market cap and CANCEL the shares instead of paying that £23m in dividends (if the board believes that the company will survive),
I agree with Graham.
Hope this is clear.
All the best
If Reach (LON:RCH) cancel the dividend and buyback instead I’ll sell at once. I sold Abrdn (LON:ABDN) around £4.60 a few years ago when they started a big buyback programme and they have been buying back every year since and now the share is down to £1.50! (I did buy ABDN again around £1.50 because they have maintained the dividend and yield is near 10%).
Big dividends have now made our portfolios self financing for the rest of my life. There is a case for buybacks, but shareholders don’t get real cash from them as they do with dividends. And the market is littered with shares that buyback heavily but the share price goes lower.
There are so many big dividend paying shares and Investment Trusts available at present and I go for those ahead of Companies preferring to buyback their shares,
E.g I bought Legal & General (LON:LGEN) at 155p. Dividend at that price is 15% and they eschew buybacks,
Hi ken
Although I agree with you that dividends are preferable to buybacks I think the situation is more nuanced than you’re suggesting.
Buybacks should only ever happen when a company is trading at a discount to its real value and only where the company has a reasonable expectation of continued growth, such that the buyback price is lower than the future price. Of course, the future is never exactly knowable, so there is always some risk, but that’s the nature of investing.
Bad buybacks – and I’ve seen many – are often done to the advantage of the incumbent management, as they boost EPS without increasing profits. This is usually connected to share options vesting. Well executed buybacks incentivise short-term holders to leave and reward longer term shareholders with more earnings for each share they hold. And this is a permanent advantage, rather than a temporary one.
In the end managements are employed to make the best use of capital – they can either reinvest in the business to grow it or return it to shareholders as dividends or in the form of buybacks. Either way it’s the same pool of earnings, it’s just distributed differently. If a company can generate an improvement in their return on capital and eps by reinvesting in the company rather than returning money to shareholders they should – it’s far the most efficient way of reusing earnings and will generally result in better returns to shareholders in the long term. Returning money to me just means I have to make the investing decision myself, if I'm not taking money out of my portfolio.
That said, there are strong reasons for wanting sustainable dividends. Dividends tend to be more stable than earnings, they are part of the contract between a company and its shareholders and they are usually a sign of a healthy business, especially where the company is also continuing to grow earnings per share over the cycle.
Nonetheless, I’ve seen investors become fixated on dividends to the point where they ignore the underlying health of the business. Back, pre-GFC, Lloyds was paying a near 10% dividend. The Motley Fool had a thriving board of happy Lloyds shareholders led by one particularly fluent poster who were all convinced that they had found investing heaven. Of course, they hadn’t, although they followed their leader into the abyss until Lloyds was worth pennies and he declared that he had most of his money in BTL property and departed.
It was sort of funny, but I knew a couple of people who lost tens of thousands, all because they’d focused on the dividend and not the underlying stability of the business. It’s very rare for a large company to yield anything like 10% without there being underlying problems that suggest that the payout isn’t sustainable.
So what can we make of the very high dividend yields on many larger UK stocks today particularly in the insurance and fund management sectors? Well, I suppose my answer to that is that I hold most of them. It seems to be me that these stocks offer a once in a generation discount to their real value, a discount that is being signalled by the high dividends on offer which in most cases appear to be sustainable, albeit they’re unlikely to grow much in the next few years – either because of low intrinsic growth or because companies are likely to focus recovering earnings on shoring up balance sheets and investing for growth.
Why are we seeing these discounts? Well, there appear to be a number of reasons – firstly higher interest rates tend to push up the dividends required on lower growth stocks, secondly the UK market as a whole is operating at a discount which seems largely related to external investors’ concerns over political instability and thirdly, many of the companies in question are operating in difficult sectors in a low point in the cycle. Fund managers in particular are suffering a double hit – falling share prices affect their AUM as well as influencing investors to pull out their funds (classically people withdraw money from stocks during bear markets and reinvest during bull ones). Of course, as markets start to recover this effect goes into reverse – we seem to be seeing the first evidence of this happening.
Broadly, though, I don’t expect the current opportunity to buy good, larger UK companies at a discount will continue for that much longer, barring some unforeseen geopolitical event. And the high dividends are a consequence of that discount. The future is more likely to look like the past than the present and the UK will continue to offer decent but lower growth companies offering dividends on average that run a little ahead of inflation. Other countries with bigger markets, deeper pools of capital and greedier entrepreneurs will likely see higher growth, albeit with significant localised volatility. Although, again, I expect to see more regulatory action against the mega-cap tech stocks that dominate world markets (and from which I have happily profited for a decade).
In general, I prefer dividends to buybacks, especially as I approach the age where I will need to take income from my portfolio. Selling shares to create a dividend, as is often recommended, requires judgement on my part – and if a share’s price falls I have to sell more shares to receive the same dividend: all too often this would mean selling at the wrong time. However, buybacks will continue – especially at larger companies, where the tax advantages for shareholders outweigh the benefits of special dividends. In smaller companies I rarely see the point of buybacks – if they can’t invest the funds to grow the business then return them to me.
Broadly then, I agree with you. But I don’t believe anyone should ever buy a stock purely because of the dividend. Dividends are a consequence of the operation of a company which should always be the priority concern. As returns revert back towards a more normal distribution – or, to put it another away – as share prices recover, investors who mistake today's unusual conditions for the norm and continue to seek excess dividends from larger cap UK stocks without doing the proper due diligence are likely to find themselves considerably poorer.
timarr
Excellent post timarr…I agree with every word of it…I also recall the Lloyds Banking (LON:LLOY) TMF discussion board back in the day when Jim Susan seemingly welcomed any reduction in the share price as an opportunity to re-invest dividends at a more attractive level….whilst ignoring the v real distress of the business.
I welcome dividends where the mgt of the business involved have thought carefully about the topic and formally expressed how the dividend payout is arrived at, Games Workshop (LON:GAW) is a good example..they automatically pay out all surplus cash to shareholders whilst retaining a fixed cash buffer for cautionary purposes
timarr
That’s one of the best, if not THE best, article or post I have ever read on buybacks and dividends. It’s balanced and so well argued, and I agree with nearly all of it.
So many of us, me included, take a too one sided view, and that’s already reflected in replies and posts after yours.
It’s only in recent years as dividend yields have got so remarkably high for reasons you’ve explained that I’ve got even more hooked on them.. These have to be sustainable and preferably increased year on year as has been the case with, say. Aviva (LON:AV.) and Legal & General (LON:LGEN) both of which I hold at a good profit, and Legal & General (LON:LGEN) now nearly 60% up and a near 15% dividend. I usually sell on a dividend cut and when any update hints at a cut or ignores the topic altogether.
I’ve also been influenced by Lord John Lee who now has a portfolio including shares paying 100% a year and more just in dividends. And though nowhere near that stage, our portfolios are now self financing thanks to so many regular big dividends flowing in. That’s a key target to aim for as we get older isn’t it? I.e to get to the stage where a portfolio can look after itself even during bear markets. £thousands a year in dividends mitigate the capital losses until the markets recover as they always do. And they provide funds for free for new portfolio buys. It’s the lack of any real cash that is my key gripe about buybacks.
I’m not totally anti buybacks. Again you’ve covered so well when they are good and when they aren’t. I gave Abrdn (LON:ABDN) as a classic example of when they aren’t and selling at the start of their buybacks over 5 years ago at £4.60 as the share price was already falling away and buying back in 2022 at about £1.50 for the 10% dividend should pay off. . At least the buybacks reduced the number of shares to help maintain the dividend.
Next (LON:NXT) is imo a classic example of a Company that has bought back wisely. They only buyback when believing the share is good value and have now more than halved the share count. And Next (LON:NXT) has been a great long term hold. I remember when it was 6p and decided not to buy at 30p thinking I had missed the boat! Now it’s £90.
One small final point about buybacks increasing eps. Yes, always. BUT eps still goes lower or even disappears if things go wrong and profits disappear or revert to losses. Buybacks don’t provide extra support for the share price then. There’s similar situation with dividends as they get cancelled. And both with Compsnies who bought back and who paid big dividends, it usually mean big capital losses too.
Your post deserves a much wider audience that it will get here.
Though, of course, a well executed buy back at a time when a share is undevalued will lead to future distributable cash being distributed to a smaller pool, should enhance future sustainable dividend paying ability.
Very well said and each case is completely different.
Excellent thread on this topic of share buybacks.
The thing that concerns me is the extent to which buybacks give management multiple options, only some of which may be in the interests of the shareholders.
In the last few days I have seen RNS on share buybacks that are accompanied by one of the following three phrases:
1. "Bought shares have been cancelled", leaving X shares in play (reassuring)
2. "The company intends to cancel the shares", (less reassuring, as presumably not legally binding?)
3. "The shares will be held in Treasury" (not reassuring at all, will they offer them internally at a discount? I would rather have had the cash)
Dave
If Reach (LON:RCH) cancels the dividend and declares a buyback and cancellation of these shares I will definitely buy.
All the best
They had £43m net debt, according to Stockopedia on the 2023 results. There is also the outstanding court settlement. Pension payments still has several years to run, to 2027.
You’ve got the wrong net debt Rusty.
Reach (LON:RCH) There was a very small Net debt position at y/e that goes back to positive net cash this year (after dividends and pension payments). Ie broadly neutral on net cash.
I'm going by Stockopedia figures. So they were wrong?
Unfortunately I'm a holder of Argentex (LON:AGFX) ( have had a run of bad announcements and profit warnings recently...) I was nervous when I saw that Rockwood Strategic (LON:RKW) sold down their stake in mid April (5% to 4.4%) as it was their enthusiasm for the turnaround story that made me do my own research and subsequently buy a few. I rate Richard Staveley highly and therefore without knowing the full facts got me into speculating that there was a divergence in opinion as to the new strategy and fundraise. I have read the RNS in full but would like the management to speak to investors directly via one of the excellent platforms to explain how they will actually create growth and value for shareholders. I am completely in two minds about this one - both tempted to buy in the market after the fall far below the 45p fundraising price (retail offer announced tomorrow) or sell up and move on. Hope for some better news in my other holdings soon! (investing can be a very lonely place when your stocks are not performing)
I hold a small amount too.I saw it as only a minor reduction in stake at the time, although unusual perhaps.I guess you never really know what is going on behind the scenes, although admittedly with some high profile leavers recently, there was some clues.You can't win em all and if they can make good with this new platform, things can still come good.It'll take time for sure though and definitely one for the back drawer for me.I'm consdering buying a few more, but i think i'll wait a few days/weeks possibly for the fundraise to settle out, share price to drift down a little due to sellers leaving and no new news.Or until the next trading update or 2 to see how they're progressing with the new product buildout.
Probably difficult to sell a larger amount in Argentex (LON:AGFX),this is the problem for fund managers in small caps. Their sale seemed to cause a drop in the share price, even trading small amounts is difficult, who is going to buy them?
Kitwave (LON:KITW) . Working in the industry, I agree they are right that weather and cost of living in Q1 24 has affected the industry - they are too large arguably to buck this trend. Future acquisitions is probably their path to out performance in this sector, but I struggle to get excited about essentially a distribution business with little to no defensive moat. At the same time, it means others have no moat and they can fight for share/ acquire without huge capex requirements. Shareholders have done well here and as they go national, they will come to the attention of others. Might be a target for Sysco (NYQ:SYY) or Bidfood in time?
Kitwave (LON:KITW) . I think the moat is a bit wider than you suggest because reliable supply, good service, and accurate billing are hard to get right. Just ask any Bookers customer. But I'm worried about the fragility of some of their customers. One hopes that their credit control is absolutely watertight. Holders should watch the cash flow statement and any hint of bad debts will be a big red flag. I bought in November after the share price drop when the founder retired, then the price hit my target quite quickly so I sold and haven't been tempted to buy again. Nice company, very well run, and if the price retreats I would buy again for another trade.
Surely, if you have a nice mix of growth, strong cash flow and decent profits, a combination of dividend (which others have pointed out you can reinvest in an ISA etc) and buy backs (you do not have to sell!) if affordable and within sensible perameters, is a bit of a no brainer investment.
Of course if there were sensible acquisitions which provide a better overall return than the above, it makes sense to see these as an alternative, though acquisitions carry with it their own risks.
Hi Trident, I wonder if you could edit your comment to tell us which company you're talking about! Ta,
Re IPF, I'd like to understand why some people, including Paul, are so enthusiastic about share buy-backs. Personally, I'm quite happy to be given part of a company's earnings in the form of dividends and then I'll be the one to decide where it's invested instead of the management taking the decision for me.
I'd like to understand why some people, including Paul, are so enthusiastic about share buy-backs
Firstly, if the companies you own can reinvest their profits at a higher rate of return than a) their cost of capital and b) the going rate on cash, then their share price is primed to compound extremely successfully. The key is to have invested in high-quality companies in the first place. It’s no good seeing share buybacks where profits are flatlined.
Secondly, tax! The CGT that one might pay on selling shares whose price has been boosted by share buyback is, at least for now, only chargeable at 20% - in contrast to dividends which can be taxed almost to 40% for higher tax payers. And there’s an additional benefit: the deferring of tax payments that occurs when buybacks are preferred to dividends allows those extra monies embedded in the share price to compound and further boost returns. But it should be noted this only works over longer periods.
Thirdly, dividends are not a free lunch. When a dividend is paid the share price falls to match the fall in enterprise value - cash has gone out of the business. In contrast when shares are bought back and cancelled, this increases earnings per share and hence supports, ie increases, the share price.
Remember you can take a dividend out of your growing, share-buybacking growth company at any time. Simply sell some shares and use the money as required. and only pay 20% tax.
If you hold within an ISA or SIPP then most of that does not apply.
If you hold within an ISA or SIPP then most of that does not apply.
What? The share price does not fall when dividends are paid if you hold it in an ISA? SIPPs eliminate the need to look for companies who compound their returns higher than their cost of capital? It’s only the tax angle that they help with.
I referring to the tax, CGT and dividend tax.
l think dividends are overrated.
I'd like to understand why some people, including Paul, are so enthusiastic about share buy-backs
If you have a great company going places with modest valuation and excess cash - its a fantastic tool for us shareholders to get larger piece of the pie. Shareholders in next own 10% plus more of the company than they did 5 years ago - keep the current rate of buybacks up over the next 20 years and the returns will be fantastic for shareholders - if they can keep earnings at levels they are now +in real tems
Most people who cricitice share buybacks - seem to cross refernce the perfomance of a crap business that has gone into reverse or has gone nowhere. In that regard if its a sketchy or poor business or one struggling to maintain earnings in real terms then share buy backs i would agree can be dreadful and make no sense.
imho the other time not to do buyback is if you have excessive debt - there is perhaps some logic to maintaining debt (redde plc perhaps ) - but i am not such a great fan of buybacks where the excess cash could perhaps be better invested somewhere obvious - to me if its a company increasing earnings in line with inflation plus and pe is 8 or so then not much better place to park ones cash than in buybacks geenrally though.
so first thing to do is look at the quality of earnings of the company doing the buyback and start from there.
thats without getting into the technical detail of benefits - hopefully BnB has highlight some useful stuff.
To be clear here most people like myself who are fans of buybacks would probably agree that buybacks arent always fantastic possibly for reasons above (see reasons above) - i dont find many who are against buybacks that will say - err rright that makes complete sense for this particualr company. eg for next presuming they are in fine fettle would anyone argue against the buybacks there ? - (perhaps their debt might be a tad high for some which would be fair comment).
Thanks a lot, rmillaree. Very useful.
Many thanks BnB for taking the time to explain this so comprehensively. Several of the advantages don't apply to me (e.g. CGT and income tax) as all my equity investments are in ISAs) but I now understand why some people are so enthusiastic.
I'm with you, John. I much prefer dividends to share buybacks. They are a clearer sign of the financial health of the business and they discipline management to generate cash on a consistent and sustainable basis to pay them each and every year.
Share buybacks might be ok in certain instances but too often they are simply an artificial way of propping up the share price when trading isn't great. Two things really bug me. One is companies who raise cash from shareholders and then return it via buybacks! The other is managements who say "we bought back shares because our company is undervalued ". I say let the market determine if the stock is undervalued.
Like you John, I want control of the cash that my investment is generating. I might reinvest dividends back in the same company, but alternatively I may have a better idea at that time or simply wish to diversify a bit.
Thanks for joining in, sparkler.
I can see that tax is more important to some people than others but, beyond that, the debate hasn't convinced me that the benefits of buybacks outweigh the benefits of giving the money to me.
So how much do the largest US stocks pay out in dividends? Maybe it is better for them to invest the money, in their business rather than pay it out to shareholders, some of whom may invest it in rival stocks.
Be careful to note BnB’s comment:-
…..when shares are bought back and cancelled……
There are plenty of companies that buy back shares and then keep them in reserve for director’s future share options. The only thing that compounds is the director’s bank balance.
For an extreme example look at Tremor / Nexxen International (NMQ:NEXN).
BoD masters at this practice gorging on 10's of millions of shareholders money through share buy backs/ director share options / director share sales cycle...
or even worse, buy back shares and then sell them to a director at a lower price - as was done by Mti Wireless Edge.
Always check the reason announced in the RNS for the share buy-back. There are just two, one for cancellation of the shares, the other for the keeping in Treasury to satisfy Corporate Greed.
https://www.cnbc.com/2018/08/3... get it from the master
Paul many thanks for covering Anexo (LON:ANX) yesterday. Very interesting to see such a disparity between the overall Stocko rank and your more detailed analysis. Forgive my ignorance but I didn't understand the phrase "reports huge profits, which then just sits in debtors on the balance sheet, uncollected." It was one of Simon Thompson's bargain shares for the year - you think he's picked another turkey?" (I hold!)
Simon Thomson has more turkeys than Father Christmas.
Journeo (LON:JNEO) 100%
hVIVO (LON:HVO) 150%
Gulf Marine Services (LON:GMS) 100%
Ashtead Technology Holdings (LON:AT.) 250%
These are some of these picks and their overall rise from his alpha report the last 12 months!
All the best
Smiths News (LON:SNWS) - Canaccord:
The current valuation is highly attractive, with a PER of 5.5x, a secure dividend yielding 10% and a FCF yield of 18%. We reiterate our BUY recommendation and increase our TP to 95p (from 85p), based on a cal’24E PER of c.9x, div. yield of c.6% and FCF yield of c.10%, implying 78% upside.
Half year report https://www.investegate.co.uk/...
Refinancing Agreement
https://www.investegate.co.uk/...
Just be aware, anyone trying to sell (and maybe buy - I haven't checked) on AJ BELL they are currently adding FX charges where there shouldn't be one. I've informed them.
Seems to be fixed now.
I saw the FX charge on a sale at AJ Bell this morning but it hadn't affected the actual contract value and it wasn't on the contract note 10 minutes later. So I guess it was at IT error but didn't affect anything.
My snapshot for Argentex (LON:AGFX). The growth has gone & they have a new five year plan, including developing a new alternative banking platform. A fund raise has also been announced to fund this, diluting shareholders by 10% (unless they take part) at the stocks all time low share price. I don't have the knowledge to know if this new product is a good idea or not, but I think it needs to work.
They are still growing client numbers, however average revenue per client fell by 10%. All blamed on lower volatility. The change in accounting dates has confused the numbers somewhat, but comparing 12 month periods revenue was down.
This morning’s results, strategic update and fund raise from Argentex (LON:AGFX) shed some light on the tough reality of the corporate FX / international payments business.
The Argentex (LON:AGFX) fund raise to invest in virtual IBANs (i.e. international, multi currency, bank accounts) mimics Equals (LON:EQLS) strategy and sees Argentex (LON:AGFX) re-position from an expensive, people intensive advisory business to IT platform based services.
These IT platforms enable automated cross border payments which, when combined with currency bank accounts (virtual IBAN), make it easier and cheaper for international businesses to manage different currencies across the various business units that they own in multiple countries.
In short, for corporate clients, payments are cheaper and quicker and you no longer need to leave £1m equivalent in every subsidiary bank account. Accounting, reconciliations and reporting can be automated too.
The key challenge is that to differentiate, the likes of Equals (LON:EQLS), Cornerstone FS (LON:CSFS) and Argentex (LON:AGFX) need to continually invest in product capability to increase the range of currencies, payment types and countries available to clients. Not to mention regulatory and legal compliance (including compliance with fraud, money laundering, sanctions, embargoes prevention, detection and reporting etc).
Ultimately though, competitors catch up and last year’s new offering is this year’s commoditised product with a resulting race to the bottom in pricing…....followed by strategic reviews, offers for sale and fund raises.
This is a lesson local and regional banks, from Santander to Lloyds, learned some time ago and, alongside increased regulatory capital requirements, helps explains why they've stood aside and relinquished market share.
The reason they relinquished ( lost ) market share was all to do with the spreads they charged and were simply uncompetitive. Another nail in the greedy banks coffins
I just wonder if digital currencies aren't going to remove the need for this sort of company. I hear over 80% of Yacht purchases these days are made in digital currency. Ferrari accept digi currency. The main thing holding this sector up has been the underlying banking structures services don't exist. Those are coming. Existing banks won't touch it because of the compliance risk and kyc issues. I just think the companies involved are running ahead. regulators etc have no idea what to do and as a result it is anyones guess where this will end up.
Kitwave (LON:KITW) not disastrous by any means but market probably expecting a lot more given the very strong run in the share price.
TI Fluid Systems (LON:TIFS) SP has been knocked due to expectation that car volumes are declining. It looks very good value. Yet the company posts an in line/ ahead of expectations statement today. It will be interesting to see how the market reacts. I hold.
Does this company fall within the remit of SCVR?
Reach (LON:RCH) steady as she goes, digital data driven revenue which I think will be a key driver of tapping hidden value in the company going up.
Smiths News (LON:SNWS) I think this is a really good update - more divis to come, less interest, more free cash flow, I could see this spurt up.
These were my biggest holdings in my portfolio until Filtronic (LON:FTC) and Beeks Financial Cloud (LON:BKS) overtook them. I will take the dog for a walk, think about it for a while and might double down.
Good morning, Argentex (LON:AGFX) announce 2023 results, strategic review results and plan including placing and retail offer. Hope you can find time to add an opinion on this one.
Interesting read across for EQLS from AGFX CEO comments:
"Our core FX business and associated brand strength provide a strong backbone, however we have identified a sizeable opportunity to reposition and diversify the business as a true Cross Border Financial Solutions expert. This will allow us to take advantage of the ongoing structural changes in the market and the rapid growth in demand for alternative transaction banking solutions. By diversifying the product offering and accelerating the move into Alternative Transaction Banking we can continue to leverage our reputation in FX, while expanding our addressable market, reducing volatility and improving visibility and margin."
Equals (LON:EQLS) are already powering ahead on margins, growth, etc.
So I'd expect any take over at a big premium for EQLS
Argentex (LON:AGFX)
"Our core FX business and associated brand strength provide a strong backbone,
i dont get it ? currently stocky has £74 mill revenue pencilled in for 2024 and they are NOW saying without fundraise it will only be £40 mill with peanuts in bottom line profit. Is this statement not complete fiction if their core business earnings are collapsing ? - i could understand if repositioning added to costs with little in extra salkes - but for turnover to be down such a huge % on what is presumably previously "profitable" sales suggests the core is rotten here ! unless i am missing something - i know very little about thos company i must admit.
I’ve repeatedly stated on here that I think Argentex is a POS – with apologies to shareholders in Plexus. It’s a competitive field they are in - and they lost. Whether the new CEO can build a successful product range from the ashes of its forerunner remains to be seen. Why risk it?
Argentex (LON:AGFX) Forecast earnings estimates were withdrawn when the old CEO was removed (October 2023). Stocko does not update such things. One can see that earnings are no longer updated when the analyst consensus graph shows a flat line.
There was an RNS in January updating the company's expectations for the year.
disclosure: I own a few
Argentex
I did warn everyone that I used to deal with the old CEO years ago and he was a bit of cheeky chappy spiv type salesman (ie typical currency broker ) and no credible CEO .
Unfortunately I do talk a lot of nonsense sometimes and maybe people thought I was joking .
Currency dealers and these FX brokers do seem a strange breed, to be fair the best dealers are probably just that - great dealers buying and selling currency .
My experience is a great dealer will ALWAYS beat the rates that the online broker / automated systems give you .
It’s quite an old school fun way to do business ,on our big transactions we literally ring up two dealers who are buying live in the market and when it’s a direct conversation you always get a few ticks better .
Hard to scale that type of business but I do think no matter what currency buying system pops up a good dealer will always give a better rate .
It’s about relationships , Id always love to buy currency from Harry Adams but I would not have him as CEO .
And banks are just a disgrace for ripping off customers for many years offering very non competitive rates and relying on status quo customers who haven’t realised they were getting terrible rates and the banks were profiteering .
So bravo to the currency dealers and platforms for showing us that when the tide goes out who isn’t wearing any pants .
Think that analogy makes sense .
Argentex (LON:AGFX)
Unfortunately I do talk a lot of nonsense sometimes and maybe people thought I was joking .
Personally i must say when people call out the board on this site or pass informaed comment on what might be subtle matters i love it , i think there have been some great posts over the last couple of years calling into question either the ethics of the board or the shady practices ref prospects (honesty) of companies or other items that would make one worry if its a dependable reliable company with proper moat/sustainable earnings - obviously some decent companies may come across as shady - but give me a decent honest board who tell you like it is and at least if you lose money you dont later feel like you have been lied to previously. so keep up the good work everyone who calls out what they see as sketchy - i for one always make a mental note even if that may not fully influence my decision whether to invest or not. always good to have full warts and all commentary. so keep up the great work planetx!
Cheers Laurie
Argentex (LON:AGFX)
Forecast earnings estimates were withdrawn when the old CEO was removed (October 2023).
ok that kind of makes sense that perhaps the difference between the numbers might have partly or wholly been factored in previously - on that basis probably best for people to ignore my prior comments completely , i wouldnt have posted if i had known that was the case - albeit if they were at the time expecting expeting that level of sales and on lfl basis they will only be £40 mill now thats a huge drop from where they could have ben back then - if that is not new news today though then that explains the glosing over of stuff - i would say its full on red and black flag alert here anyway for me - is the core business really a solid backbone if they are needing to pivot so much ? up until today i was wandering if this may have been over reaction with share price drop (kinda in pasing without me diving deep) not based on todays update though - not often i say i am out but i am out.
Hi Laurie, I don't know anything about Argentex, but I don't agree with your point that a flat line on the consensus earnings chart must mean that earnings forecasts are no longer being updated. It might mean that, but, on the other hand, it could just mean that the forecasts are still in place and have remained unchanged. It would be much better if Stocko could improve the chart to indicate which of these two possible scenarios was actually the case.
Argentex (LON:AGFX) it does look like there have no updates, the EPS forecasts have not changed at all for the next 2 years, with so much happening in this stock, that does look strange. Only one broker. They should have been reduced.
The last change on Stockopedia, was in June 2023, since then they have been flat.
Argentex (LON:AGFX)
I don't agree with your point that a flat line on the consensus earnings chart must mean that earnings forecasts are no longer being updated.
Ah, yes, I stand corrected. My apologies for the loose writing. May I update my comment to this:
One might become suspicious that earnings are not being updated when the analyst consensus graph shows a flat line.
And yes, I too think that it would be a positive development if the difference between unchanged forecasts and earnings not being updated was made obvious.
In addition to Cuddlesticks' eloquent earlier summary, may I add these arguments for and against Argentex? Half of the market capitalization is in cash. It has new licences in various jurisdictions. It is on an undemanding PE. The new CEO has reasonable form with this sort of business; he was the CEO of a company that is now a part of WorldPay. A combination of online platform and savvy telephone brokers is a reasonable business model. Mr Adams has been removed as CEO. [I have not dealt with him, but his online presentations gave me the same impression as planetx has expressed.] On the downside, earnings are reducing, the LLP situation does not seem to have been resolved, and there are competitors, execution risks, and the risk of bad debts. Commoditization is always a worry.
Disclosure: I own a few and have nibbled a bit more in the past hour. The position is sized appropriately for the risk involved; I am aware that I might regret my involvement.
Argentex (LON:AGFX)
It is on an undemanding PE.
what is the pe now though if practicably epaking they are only doung £40 mill of profitable sales of which less than 10% is turning to ebitda and presumably les of that tuening into bottom line profit. Ok the investment may pay rewards but i am not even convinced that in now the now pe is cheap on my very superficial look? - is the pe actually undemanding ?
Argentex (LON:AGFX)
...I am not even convinced that the pe is cheap on my very superficial look? - is the pe actually undemanding ?
---------------------
we expect FY24 revenues to be in the mid £40s million, with an EBITDA margin in the low single digits
The RNS says mid £40s rather than £40 million (10ish% revenue fall from FY23, surely more than 10% fall in profit), but I accept what you mean; the commentary is clear that profit is expected to reduce in the short term.
Why I think that AGFX is on an undemanding PE:
On FY23 stated earnings [I add back amortization and some depreciation, subtract most capex, subtract additional share-based payments, etc.—my calculations are all a bit vague as precise info is not in the RNS. Your assumptions will probably be slightly different.] I estimate current eps is slightly less than the headline figure of 4.6p. At a share price of <38p (my latest purchase price today…unfortunately my average price paid is somewhat higher), this doesn’t currently look terrible. Next year will (probably) be lower.
Long-term earnings have been uneven, but PAT has been above £6 million for more than half of the reported years. [My calculated figures are slightly lower, but I’ve used headline numbers.] 6 million is probably a reasonable long-term average to use for PAT for the existing business.
The market cap is now c. £41mil […hmmm…now 40ish million…]. There is £24 mil in own cash although this isn’t necessarily available for shareholders [e.g. £5.7 mil was in use as collateral at year end].
My valuation thinking: Average PAT c. £6 mil at the bargain PE of 10 is £60 million, plus say £10 million of the cash pile = £70 mil longer term reasonable value for the existing company = share price of c. 62ish.
N.B. This is obviously a back-of-an-envelope calculation. Use it at your peril.
Worries:
Just about everything --certainly all that has already been written by everyone here.
Additionally:
Will the new CEO move on if he doesn’t get the cash to fulfil his ambitions for the company?
Thanks, awashwi, for pointing out that the Chairman agreed to another job yesterday. It is a brave choice to become the new Chairman of the Post Office.
Larger shareholders and directors indicated that they would take part in the placing. With the share price 20% below the placing price, things don’t look good.
If more cash is not forthcoming, and the growth plan is abandoned, is it terrible that I can pick up an unexciting business at half price?
Argentex (LON:AGFX)
My valuation thinking: Average PAT c. £6 mil at the bargain PE of 10 is £60 million, plus say £10 million of the cash pile = £70 mil longer term reasonable value for the existing company = share price of c. 62ish.
are they today not saying that practicably spekaing EBITDA is low single digits though - say 5% of £50 mill = £2.5 mill EBITA - so below £2 mill net profit probably . how do you get to 6 mill? thats huge difference
you mention cash pile whilst they are proposing to raise cash - that suggests there is very little in the way of excess spare at present.
"And yes, I too think that it would be a positive development if the difference between unchanged forecasts and earnings not being updated was made obvious."
How would Stockopedia know that? They are just being fed the information. Doubt the supplier would know either.
Argentex (LON:AGFX) and in general
"it would be a positive development if the difference between unchanged forecasts and earnings not being updated was made obvious."
How would Stockopedia know that? They are just being fed the information. Doubt the supplier would know either.
-------------------------------------
I don't know how Stockopedia would know, but Ed might find a solution.
Sharepad removed forecasts some time ago so there could be a way of extracting the information from the given data.
Laurie. I will put this in as a request through the green blob.
I have submitted my request through the green blob.
Stockopedia have replied to my request by saying they "will add it to our list of future feature upgrades."
Discontinued Estimates left on Stockreports:
I have raised this in the past through the green button but feel I have been bashing my head against a brick wall.
On 10/10/22 I was told:
"As we go forward, we plan to handle stale estimates differently, for example, by highlighting them in a different colour - eg. a light shade of amber.
Removing them completely may be jarring for users".
On 31/3/23 I was told:
"Firstly let me empathise with you regarding the estimates. I agree that we need to adjust how we handle these stale estimates and internally we are communicating with the best way to action this going forward".
Perhaps if a lot more readers had a go through the green button we might get somewhere.
Why can't Stocko show the breakdown of the average forecast?
Just a list of brokers, their forecast EPS, and the last time they updated it. That will suffice - if anyone wanted to check to see the freshness, just click that little icon and get the full list of forecasts. Also shows the range of forecasts that goes into the average.
If there's some sort of investor regulation around research reports, then I'd be perfectly happy if the broker names were annonymised... just the EPS amount, and when last updated, would suffice!
Boon. That's a really good idea for Stocko to show us a list of brokers, their forecast EPS, and the last time they updated it.
Laurie. Thank you for your excellent clarification to "One might become suspicious that earnings are not being updated when the analyst consensus graph shows a flat line." I could not have put it better myself! Cheers.
Argentex (LON:AGFX)
Is this not simply the mother of all profit warnings from out of nowhere dressed up as something else ? - the current numbers on stocky seem to bear no relation to the expectations that the existing stuff would only be able to do £40 mill sales in 2024 - am i missing everything here it makes no sense to me that the figures can diverge so much ?
Financial Outlook
In the absence of additional financing, and as the Group focuses on repositioning and restructuring the business for profitable growth, the Directors expect FY24 revenues to be in the mid £40s million, with an EBITDA margin in the low single digits. In the medium term, the Directors expect the business to return to growth, delivering single digit revenue growth per annum, with high single digit EBITDA margins. In this base case scenario, revenues will remain volatile as the business remains significantly exposed to market FX volatility.
ARGENTEX (LON:AGFX)
Today’s figures and accompanying fund raising explains the weakness in recent days . The reduction by Rockwood last month also looks very well timed !
Given that the company was ; “Debt free and cash generative with net cash increasing by £2.1m in FY23 to £18.3m” I am concerned as to why additional cash is needed now .
The strategic review looks like a full house for BS bingo and the fact that the chairman has recently been appointed to another much higher profile position is another source of concern .
I had taken a position t what I thought was a good level but much as I hate taking a loss I see more reasons to worry than reasons to be cheerful from today’s announcements so have sold as there seem many more promising situations out there .
My morning smallcap tweet: Anything You Can Screw I Can Screw Better
Revolution Bars (LON:RBG) Argentex (LON:AGFX) Kinovo (LON:KINO) Accsys Technologies (LON:AXS) Batm Advanced Communications (LON:BVC) LifeSafe Holdings (LON:LIFS) Smiths News (LON:SNWS), Reach (LON:RCH), Hostelworld (LON:HSW), Personal group (LON:PGH), SIG (LON:SHI), Kitwave (LON:KITW)
◄Revolution Bars (RBG)► confirms meeting with Nightcap regarding a range of possible transactions including a possible offer for co. Nightcap is not participating in the Formal Sales Process. Nightcap doesn't have the cash to buy and sort out RBG! It'd be like two drunks propping up a bar. [SP=1.46 Cap=6m]
◄Argentex (AGFX)► FY-Dec. Strategic Review conclusion - co will "drive growth within our existing FX market whilst expanding into adjacent complementary markets, both domestically and internationally." £5.1m placing at 45p, a nil discount, for the acceleration of the development of its Alternative Banking Platform. [SP=45 Cap=51m]
◄Kinovo (KINO)► guides FY-Mar rev c. £64m and adj EBITDA-cont c.£6.7m, ahead of management expectations of £6.2m. [SP=40.75 Cap=26m]
◄Accsys Technologies (AXS)► guides FY-Mar adj EBITDA ahead of exp of €2.5m due to resilient Q4 and cost savings. [SP=55.76 Cap=134m]
◄BATM Advanced Communications (BVC)► gets €0.5m EU grant for the development of an advanced tuberculosis diagnostics solution. May be more at next stage. [SP=18.95 Cap=83m]
◄LifeSafe (LIFS)► to supply its Multi-Purpose Fluid to Trinity Fire & Security. Worth up to £1.3m over 3 years. [SP=12.4 Cap=3m]
◄Smiths News (SNWS)► trading in line. Refinances debt at lower rate. Divident limit removed - to adopt 2x div cover. Further returns to shareholders when appropriate. [SP=52.76 Cap=131m]. I hold.
In line: RCH, HSW, PGH, SHI, KITW
2 drunks propping each other up! lol.
CSSG Croma security
Looks like the company have confirmed they have received the first instalment of 500k from the sale of their vigilante division which was sold and there’s about about another 4.5 million to come .
First payment on time that’s nice .
Market cap now at 10 million .
But fagpacket / beer mat research
2m cash
4.5 million to come
10 million cap
Making 1 million a year
Good sector
Lots of assets / property balance sheet bsck up .
think this is turning into a nice company that has a simple buy and build mom n pop shops for cash add to their portfolio
Slightly overpaid management .
Has re rated a bit but Shoukd go further .
What is of note is that seemingly
- if vigilante had missed the first payment they would be obliged to do an RNS
- but if vigilante pay on time (quite key to company valuation metrics) they are not allowed to do an RNS
Having said that they aren’t a. tub thumping drum banging company and don’t seem too bothered about outward communication , which is in a way very good .
Probably likely to nudge up to 80p level in the next months as this is digested but never going to blow the doors off .
Quite a nice company to hold . Very secure holding
Though you could get locked in .
Morning - I'd be very interested in any views on NAHL (LON:NAH) results this morning, Paul and Graham.
Management seem to be doing a great job turning the business around. It is now producing £3.5m+ of cash per year and will make c.6p net profit (clean - they're really conservative). Allenby Capital (house broker) have a note out with forecasts for 11p of profit and accelerated cashflow next year, plus they are considering selling one of their divisions, which with operating profit of £4.5m, is likely worth c.£40m. All against a market cap of £33m and a SP of 71p.
What I find particularly interesting is that much of the profit and cashflow is high probability, due to both the nature of the businesses (non cyclical) but also that the internal law firm has been building up a book of WIP that is now paying out.
Massimo