Small Cap Value Report (Thu 2 Nov 2023) - EQLS, CER, NXT, ESP, TIFS

Good morning from Paul & Graham!
I'm sitting here in Bournemouth, surrounded by garden furniture, brought in to prevent them becoming airborne hazards as we brace for Storm Ciaran. One of my skylights has already started leaking water, so I've got a bad feeling about this.
As I woke up early, let's start with a joke which made me chuckle -
I was passing a pet shop, and saw an adorable kitten in the window, labelled "Netherlands kitten for sale".
I've never heard of a "Netherlands kitten", but my interest piqued, I went in, and enquired, "How Dutch is that moggie in the window?!"
(I'll get me coat. Acknowledgement: John Heald)
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Summaries
Equals (LON:EQLS) - up 14% to 117p y’day (216m) - Strategic Review - Paul - GREEN
An intriguing announcement at lunchtime yesterday, with this payments/forex company putting itself up for sale, and naming one trade, and one financial buyer that it has approached. I think this looks interesting, so have shifted up from amber to green. More detail below.
Cerillion (LON:CER) - 1,275p (y’day) £376m - Major new customer win… - Paul - GREEN
Very impressive, I wax lyrical below about one of my favourite shares.
Next (LON:NXT) - 7144p (£9.1bn) - Q3 Update (y'day) - Paul - AMBER
Not a small cap but... a quick look at yesterday's reassuring Q3 update, and small upgrade to profit guidance.
Empiric Student Property (LON:ESP) - up 2% to 87p (£525m) - Business & Trading Update - Graham - GREEN
This student accommodation REIT offers a positive-sounding update. Dynamic pricing has resulted in higher rental growth than previously reported for the current academic year. At a discount to NAV, this looks good to me. The LTV is cautious and its borrowing costs are low.
TI Fluid Systems (LON:TIFS) - up 6% to 131.6p (£682m) - Trading Update (in line) - Graham - GREEN
The recovery story continues at this automotive parts manufacturer. 2023 is shaping up to reach the performance levels of 2021 and hopefully the company can keep going from there and get margins back to where they were pre-Covid. Valuation is very cheap if they do this.
Paul’s Section:
Equals (LON:EQLS)
Up 14% to 117p y’day (216m) - Strategic Review - Paul - GREEN
This announcement was issued at lunchtime yesterday, and sounds interesting - the way I read this, the company has decided to put itself up for sale, and an official “Offer period” under takeover panel rules has started -
The Board of Equals Group plc ("Equals" or the "Company") (AIM: EQLS) notes the recent market speculation, and confirms that it is conducting a review of the Company's strategic options (the "Strategic Review").
As part of this process, the Company has contacted a limited number of potential counterparties including Fleetcor Europe Limited and Madison Dearborn Partners, LLC to assess whether such parties could put forward a proposal that would deliver greater value to Equals' shareholders than pursuing a standalone independent strategy. Any such proposal could include an offer for the entire issued and to be issued share capital of the Company.
A couple of points on the above -
The approaches seem to have been outbound, from Equals, not incoming.
Naming 2 potential counterparties (it’s not stated if this is with, or without their consent) suggests to me that there’s probably some interest, and maybe they agreed to be named? That’s guessing though.
Fleetcor - Wikipedia says that it’s a payment processing group. If you have a US subscription, the Stockopedia page for Fleetcor is here. It’s valued at nearly $17bn, and looks highly profitable. Equals would be a relatively inexpensive trade buy for it, so looks an obvious fit as an acquirer.
Madison Dearborn looks to be a US-based private equity fund manager, saying on its website that it invests in 5 focused industries, including financial services.
Current trading - sounds fine -
The Board remains confident in the long-term prospects of the business and believes that the Company is well positioned to create significant value for shareholders as an independent company. Current trading remains in line with the Board's expectations.
Paul’s opinion - not a sector that interests me personally, because it's difficult to create and maintain a lasting competitive advantage in forex/payments. But if I had to buy a forex/payments company it would probably be EQLS, which has impressed with its more recent results (although quite a chequered past with heavy losses until its breakthrough year in 2022).
EQLS management come across well on webinars, and seem to have created an interesting suite of services.
I think the valuation looked reasonable before this news, so speculating on a takeover happening at a premium could make sense here. That’s up to you, but I wouldn’t try to persuade you not to, as EQLS does look an interesting company that a bidder might be prepared to pay up for.
Hence I’m happy to shift from amber to GREEN, now we have bid interest adding to the potential upside. On top of a quite interesting company if it remains standalone.
According to Equals website, management only hold 2.6% of the equity. Although if they sell the company, presumably they might also benefit from cashing in share options as part of a deal?
I don’t know what Graham thinks, but he’s welcome to add a note below if he disagrees! EDIT: here we go -
Graham adds: I’m a bit more cautious on this, as I don’t see any confirmation that there is bid interest - only that Equals contacted various parties to see if they would be interested. To what extent the other parties are in fact interested is unclear. I suppose the longer it takes the two named parties to confirm they aren’t going to make an offer, the more interested they must be! But I also find it curious that management would actively go in search of a bid - why not let the bidders come knocking on the door? This RNS throws up more questions than answers for me. So while I am impressed by the company’s financial performance, my neutral stance as explained in September remains unchanged.
Cerillion (LON:CER)
1,275p (y’day) £376m - Major new customer win… - Paul - GREEN
Cerillion, the billing, charging and customer relationship management software solutions provider…
This is mainly focused on the telecoms sector. It’s one of our favourite GARP shares here at the SCVR, with me being GREEN on it on 15 May, 21 June, and 16 Oct (ahead exps update).
Today’s contract news sounds excellent, and “Tier-1” telco is interesting, as I think it’s more usual for contracts to be more medium-sized customers. That raises the exciting potential that CER is getting more established with the bigger telcos, as the industry migrates towards cloud-based software that CER specialises in.
This all sounds really encouraging I think -
The new customer contract was secured after a rigorous selection process, and work has commenced to replace the existing, separate legacy platforms with Cerillion's single, integrated solution. Cerillion will be supplying and implementing the core elements of its flagship solution, including billing, charging, fulfilment and product catalogue, on a SaaS basis, for an initial 5-year term. Over time, Cerillion believes that this new relationship has the potential to develop further.
Previously, CER has used a land & expand approach with selling additional things to customers once it’s established - which I very much like, as it’s proof that customers like its software. Customer relationships tend to be very sticky, and hence long-term.
This is another key advantage CER seems to have -
Key criteria in the selection process were the commercial, operational and financial advantages of Cerillion's 'out-of-the-box' product model. Cerillion's single product approach confers all the major benefits of a customised solution without the significant cost and integration risks associated with a bespoke approach. The ease with which Cerillion's software enables new products and packages to be brought to market was also a significant factor in the decision-making process for this new customer.
Louis Hall, CEO of Cerillion plc, said:
"We are delighted with this new customer win, which is with a Tier-1 European telecommunications provider. It is another indication that our model of providing a single, out-of-the box solution suite with powerful capabilities that are constantly updated - rather than customised bespoke solutions - is gaining increasing market awareness and appeal. We look forward to a productive and deepening relationship with our new client."
Paul’s opinion - remains highly positive.
Singers has issued an update today, via Research Tree (many thanks to both). This says that CER should be tracking in line or slightly ahead of existing FY 9/2024 forecasts, for 44.1p EPS.
The earnings growth since 2020 has been stellar (12.3p in FY 9/2020) to est.42.6p for FY 9/2023. Maybe 50p might be a more realistic expectation for FY 9/2024? I think the company likes to under-promise, and over-deliver, which we like!
I rarely find growth companies on rich valuations where I think it’s worth paying up, but this is one of the few.
There should be a good rise in share price today, but as we know, forced sellers often use liquidity to dump their shares. So anything can happen! Although I would imagine that even fund managers with big redemptions would probably be trying to hang on to this one. I bet it's had bid approaches too, but the founder CEO owns 30%, so any deal would have to be agreed by him, and at top dollar, I imagine.
A safe (but volatile) port in this year's small caps storm -
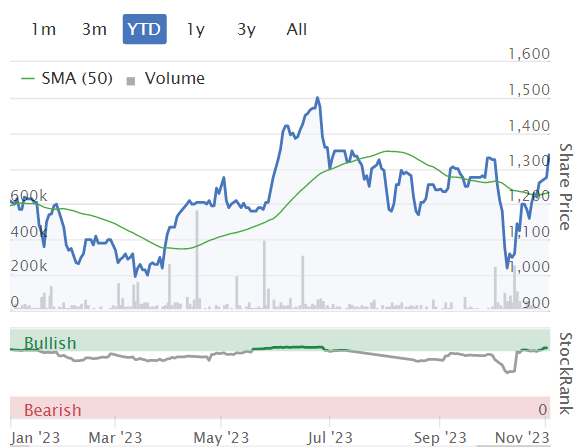
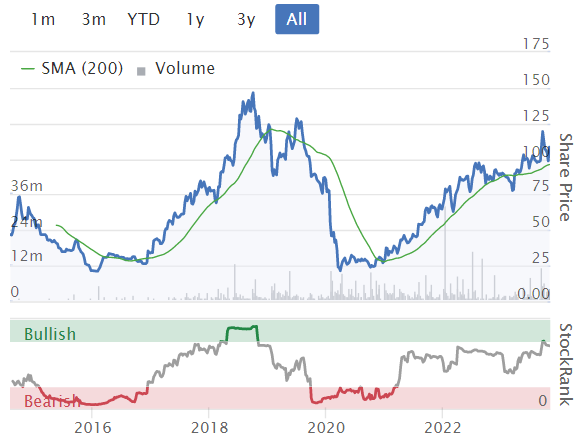
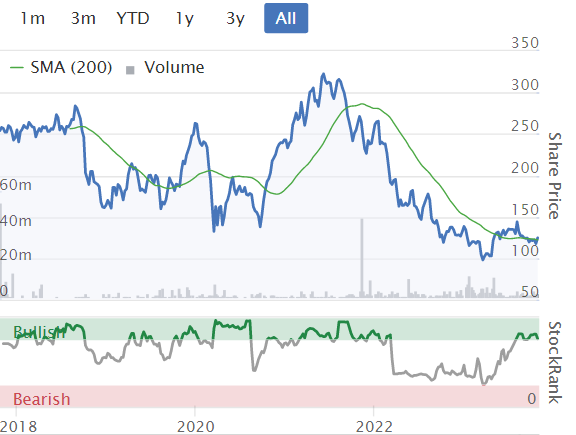
Zooming out, CER has already been a serious multibagger, and the good news keeps coming -
Next (LON:NXT)
7144p (£9.1bn) - Q3 Update - Paul - AMBER
I always try to find time for a quick comment on a few key mid/large caps in retail, and housebuilding usually. That’s because there’s often useful info for broader market read-across.
Next says -
Aug-Oct went better than expected, with full price sales up 4.0% vs LY (2.0% was guided)
Small increase in (usually prudent) FY 1/2024 profit guidance, up £10m to £885m (c.19% profit margin!!) - still a stunningly profitable business, in such a difficult sector where many competitors struggle to make any profit at all.
Online generated all the sales growth (both in Q3, and YTD) - very surprising, as the online-only fashion groups ASOS (LON:ASC) and Boohoo (LON:BOO) are reporting declining sales.
Weather - short-term this does affect sales, but average performance over time is a better indicator of consumer demand. I’m loving this graphic (simple and clear) -
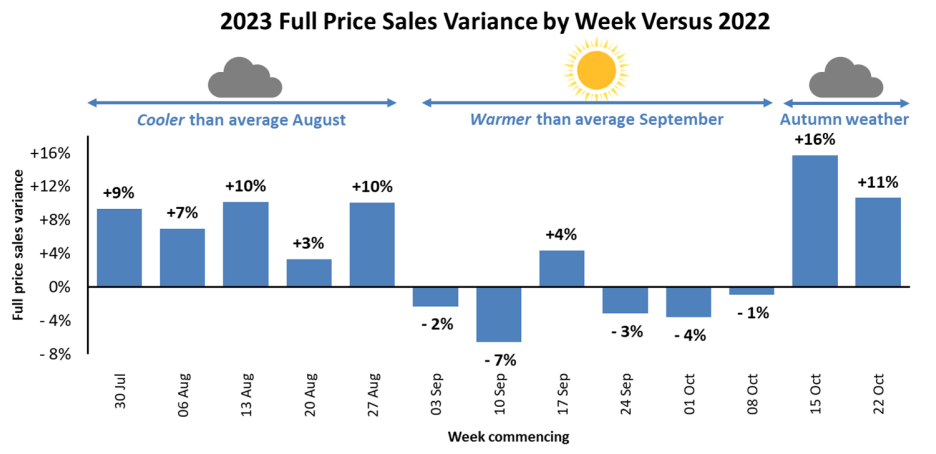
Paul’s opinion - a long-term favourite of mine, as the best in class clothing retailer.
Latest guidance (from Next) is 558p EPS (down c.3% on LY), so at 7,144p/share that’s a PER of 12.8x - good value for a high quality business, but maybe fair, considering that EPS is only really back to pre-pandemic levels, despite buybacks reducing the share count a bit each year.
Overall then, a wonderful business, but probably valued in the right ballpark for a UK company, but I wonder if it might attract bid interest from overseas at some point?
I keep this on my list of “crisis buys” - it often plunges on major unexpected macro events, but always recovers. I remember buying some on the morning of the Brexit vote shock, when markets collapsed (there were even some mid & large caps with no bids at all on the order book, in the first hour! It was crazy).
Is there any macro read-across from the above? I suppose it reassures and confirms that with inflation now having fallen below average wage rises, that the squeeze on consumer incomes has slightly eased. So now might be an interesting time to consider a fresh look at sectors that have suffered. Although Next is such a quality business, it seems to sail through all crises with barely a scratch, and each crisis wipes out a bit more competition (and gives Next the opportunity to buy brands for tuppence-halfpenny). I wonder if Superdry (LON:SDRY) might eventually end up in Next’s stable?
Graham’s Section:
Empiric Student Property (LON:ESP)
Share price: 87p (+2%)
Market cap: £525m
Empiric Student Property plc (ticker: ESP), the owner and operator of premium, studio-led, student accommodation across the UK, is pleased to provide a business and trading update as at 02 November 2023.
This REIT has impressed me with perfect occupancy, significant rental price increases, and a conservatively geared balance sheet (see comments in August).
The stock has been steady in recent times::
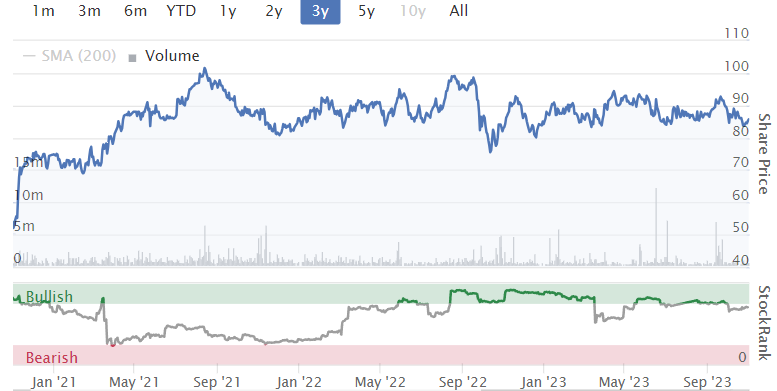
All of the themes that have impressed me with it are evident once again in today’s update.
Performance highlights:
99% revenue occupancy for 2023/24 (this means full occupancy!)
LfL growth in rents at 10.5% for 2023/2024, even higher than previously reported.
Minimum LfL growth in rents of 5% targeted for 2024/2025.
2023/2024: the upward revision to rental growth is due to “a higher level of late cancellation and rebooking activity, crystallising further the benefits of dynamic pricing”.
For the current academic year, UK students are 50% of total, while 31% are Chinese.
2024/2025: it still seems rather early to be posting predictions about rental growth for next year. But hopefully (from a shareholder point of view) there will be rental growth of closer to 10% once again. It seems that student accommodation remains in very short supply relative to the demand - here are the CEO’s comments:
"The booking cycle for academic year 2023/24 has exceeded all expectations, with the estate effectively full and like-for-like rental growth above ten per cent…
"Underpinned by the continued attractiveness of the UKs Top Tier Universities, the demand for high quality student accommodation remains strong. With demand and supply imbalance expected to continue for the foreseeable future, our premium accommodation offering and high quality customer service, positions us well for growth within this resilient and growing market."
Acquisitions/disposals: on the acquisition side, £40m+ of properties are under offer. On the disposal side, £24m+ of properties are under offer.
Balance sheet: the key figures here are very attractive to me. LTV (loan to value) is now only 28%, below ESP’s long-term target of 35%. And the weighted average cost of debt is cheap at 4.4%. Although it will pick up slightly:
As previously announced, we expect to amalgamate and refinance all 2024 and 2025 maturities in early 2024. Following refinancing, based on current forward interest rates, we anticipate the weighted average cost of debt to be within the range of 4.5 to 4.7 per cent
Earnings and dividends: last year, the company generated “EPRA earnings” (recurring earnings for a real estate business) of 3.4p per share. For the current year, they now expect to earn 4p per share. This allows for a new dividend target of 3.5p (previously 3.25p). Dividends are paid quarterly.
I think that brokers had already pencilled in about 4p of EPS this year - the StockReport shows an EPS forecast of 4.08p.
Outlook
For the academic year 2024/25 we expect revenue occupancy to remain strong. We will target like-for-like weekly rental growth of at least 5 per cent, offsetting the impact of ongoing inflationary pressure and we expect to deliver a gross margin above 70 per cent.
Gross margin last year was 67.1%, and 58.8% the year before that. Less profitable non-core properties have been disposed of, leaving a more profitable core.
Graham’s view
I remain very impressed by this company’s performance, both in terms of occupancy/rents and also margins and profits.
Net assets as of June 2023 were £715m (c. £1.1bn of assets, c. £400m of borrowings). It would make more sense to me if this company was trading closer to NAV, so I remain positive on it.
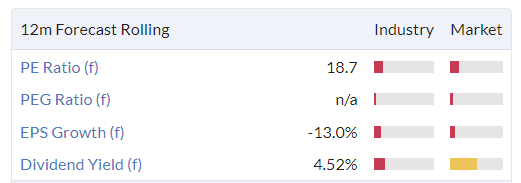
The StockRank is not convinced yet, seeing it as expensive from a P/E point of view (although it does rate the company’s Quality as being above average):
TI Fluid Systems (LON:TIFS)
Share price: 131.6p (+6%)
Market cap: £682m (€782m)
TI Fluid Systems plc (TIFS), a global industry leader in highly engineered automotive fluid storage, carrying, delivery and thermal management systems for light vehicles issues, a trading update for the third quarter and nine months ended 30 September 2023.
Listed since 2017, this company’s share price has struggled as the company has fallen into unprofitability. It is also carrying substantial debts. See my comments in August.
Here are the main points from today’s Q3 update. They are confident in the full year outlook, i.e. performance should be in line with expectations.
Revenue growth year-to-date: 12.4% at constant currencies (8.9% at actual exchange rates). Q3 revenue growth 7% at constant currencies. Euro strength is a headwind against reported revenues. Excluding that headwind, it looks like TIFS are outperforming the broader markets in which they operate.
Year-to-date revenue is now €2.62 billion, including 15% growth in the largest region which is “Europe & Africa”.
New BEV deals worth €819m (to be generated over multiple years).
Profits/cash flow: the company now expects its adjusted EBITDA margin to expand back over 7% this year. This was 7.2% in 2021 before falling to 5.5% in 2022. Regardless of your views on EBITDA, it can’t be a bad thing to see this profit margin improve.
Adjusted free cash flow conversion is expected to be “approximately 30% of adjusted EBITDA”. Checking 2022, I see that they only achieved 23.5% free cash flow conversion. It was 33% in 2021. So again, it looks like they are recovering back to 2021 performance levels.
CEO comment: ignoring the corporate-speak, the main point is that they are looking to get margins back to proper levels:
As we outlined at our Capital Markets Day in September, we are Taking the Turn to a successful future. Our strategy is focused on capitalising on the opportunities of electrification while leveraging the strengths of our conventional portfolio. In doing so, we will drive sustainable growth and return to double-digit adjusted EBIT margins in the medium term."
Graham’s view
On revenues of €3.6 billion, a double-digit adjusted EBIT margin would mean adjusted EBIT of €360m+. The current market cap is little over twice that.
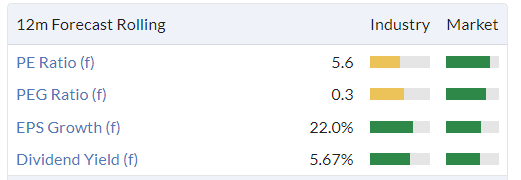
I’m going to maintain my positive stance on this one, acknowledging that there are some major risks faced by investors here. The company’s debt continues to concern me although the company itself seems more relaxed, pointing to a 1.7x leverage multiple as of September (net debt/adjusted EBITDA).
For healthy companies, that leverage multiple would normally be considered quite safe. That is the view of TIFS, as it continues to pay dividends and buy back its own shares:
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

62 comments
Porvair (LON:PRV) 4 trades totalling 1388 shares of which three were buys and one sell of 85 shares according to Sharepad.
Result, the shares close down 4.7%. Absolutely bonkers. Talk about dysfunctional markets; you couldn't make it up.
I hold and have been adding.
Re EQLS - the company mentioned it has contacted other companies and not the other way around. So I'm not sure why the shares jumped on the news. If neither co is interested then the price goes back to the undisturbed?
(I have no position)
If anything it sounds a little desperate. Why would you look to sell if the business prospects are great?
If anything it sounds a little desperate. Why would you look to sell if the business prospects are great?
You might be right in this case. But every one of the businesses I sold went on to grow profits for years under new ownership. Sometimes you just want a new challenge/fancy a big lump sum in short order/eye up a couple of years sabbatical/have a tax bill to pay.
It wasn't intended for public distribution - It was a LEAK!
Normal course of business disrutpted by a leak - resulted in the necessity for an announcement under MAR.
The takeover of Instem (LON:INS) has now been voted through. It was much closer than I expected. Hat tip again to Mammyoko for bringing it to our attention. I decided to sell on the news to reinvest elsewhere.
Instem (LON:INS) - glad you were able to take advantage of that one. Lots of mispricings around in this thin market
Me too. Thanks mammyoko.
Instem (LON:INS)
My thanks too mammyoko :)
Shell (LON:SHEL) results out today, sending the shares up nearly 2%. Crude is at $81 a barrel, and it's difficult to predict where next. Green projects like wind farms seem disappointing, with BP disclosing a writedown on those projects recently.
I think Britain needs a clear energy policy rather than the muddle we have now. At the moment it seems that the politicians are just saying what it is they think a particular group want to hear. You either see petrol as important to the economy, in which case the honest approach is to scrap ULEZ and windfall taxes, or else you go with the climate crisis side, and act accordingly. I'd just like to add that Aberdeen, often called the "Oil Capital of Europe", is introducing a ULEZ zone. That whole city is built on the back of oil, an irony that nobody seems to mention, but should.
The problem is that windfall taxes discourage investment. Shell seems to have a deft solution to the problem: don't invest more, but buy back shares. They bought back around 5% last financial year, with more of the same this year.
The PE is around 8, with a P/FCF of 5. If you assume that $80 a barrel is "about right", then shareholders will actually do quite well, I think. "If" being the operative word.
I would be surprised if ULEZ significantly reduces petrol consumption. Most people I know round where I live have replaced an old diesel car with a slightly younger petrol car which does not have a much better mpg. The boost to car manufacture will also increase CO2. A lot of so called green initiatives - cycle lanes, 20 mph zones, etc - could well increase congestion and hence increase CO2 emissions. The green rationale for them only makes sense if they persuade people to stop driving altogether.
Like bankruptcy, the transition to electric cars will happen slowly for a while yet. And then very suddenly.
The whole wind manufacturing sector has been a bit of a disaster lately and taken writedowns lately.Danish Orsted were the last company to back out of 2 US projects after Siemens Energy, which took on Siemens Gamesa, was rumored to be needing german state support a few days ago after needing to take potential billion figure writedown for faulty parts only a few months ago they said.
BP and Shell are on lower multiples than their US counterparts.Just a couple of years ago they would have commanded a premium for their green projects perhaps..
Latest retail fund sales info for Sept.
Lots more detailed info here - https://www.theia.org/industry...
Equity outflows continue. Recent share price rises will probably reverse as funds have to keep selling to meet redemptions.
I clearly missed the memo as I put most of my cash back into equities over the last week, partly prompted by the thought that it's darkest before dawn and Paul's observation that those not invested might regret it as when markets turn they often take off at pace.
Wolf's charts yesterday on AIM growth from previous slumps certainly reinforced this (confirmation bias).
Some went back into stocks I'd been stopped out or taken profits on - BP (LON:BP.) Glencore (LON:GLEN) Impax Asset Management (LON:IPX) and HgCapital Trust (LON:HGT)
Most went into new positions or topping up oversold stocks - Hikma Pharmaceuticals (LON:HIK), Polar Capital Holdings (LON:POLR) , Solid State (LON:SOLI) , Vistry (LON:VTY) , Yu (LON:YU.)
The market gains over the last couple of days has shown how quickly the markets could bounce. Certainly not claiming to be a timing genius, and Hikma Pharmaceuticals (LON:HIK) has taken a bit of a dip.
Decent amount of money flowing into fixed income though this year - bond focused fund managers such as £MNG should be doing well, indeed they've reported positive flows this year.
As expected, BoE rate remains at 5.25%
EDIT
per BBC: "The Bank of England rate is on hold again, but it also appears that so is British economic growth. In its latest set of forecasts the Bank forecasts economic stagnation from now through next year until 2025 - a grim backdrop for the general election due in that period.
While it is not predicting recession, the Bank has notably lowered its forecasts. Just over half of the impact of the series of rate rises since late 2021 is yet to filter across the economy.
The full effect will land on households by 2025 as mortgage holders roll off low fixed rate mortgages.
The prime minister’s target to get the economy growing by the end of the year is now in doubt, even as his promise to halve inflation will be met. Inflation is set to fall very sharply when new figures are announced in a fortnight.
But this new forecast shows that after that, inflation will remain higher than previously forecast, well above target around 3%, throughout next year.
This is why the Bank has decided to make crystal clear that current levels of interest rates are here for an “extended period” of time."
As expected, BoE rate remains at 5.25%
Full details here: https://www.bankofengland.co.u...
Don’t take what officials say at face value. The reality is that this is all a confidence game and all central bankers know it. I remember speaking with a prominent European central banker at a dinner back in the euro crisis in 2012 who were hugely frustrated at the German Bild undermining every tool they brought out to calm markets. Each time they had to bring a bigger bazooka…..
So all that is happening here is central bankers are breathing a sigh of relief that inflation is coming back down. They know the likely direction of rates travel is now down from here as economies struggle to grow but they can’t signal that even remotely to the market, as confidence needs to be maintained that rates are high until inflation is tamed. That is why you are also seeing 10Y yields drop quite dramatically today.
Of course higher inflation erodes debt so that helps governments given the amount of that floating around which in its own right could create another crisis, but that’s for another day.
Re Equals (LON:EQLS) has anyone seen where this “recent market speculation” occurred?
I’m obviously not in the loop as I missed it entirely
Betaville I think. Which leads to the question did someone connected to the company leak it.
It was here Betaville around midday,
It is all very interesting. They did a presentation on our Mello Monday just a couple of weeks ago and are due to present at MelloLondon at the end of November so are planning ahead. Maybe one of their large shareholders (one was selling down) has ruffled feathers and is seeking a deal to be done?
All may be revealed by the end of the month at Chiswick https://melloevents.com/mltick...
Adtech group Tremor triggers fresh City shockwave with US move Tremor International (LON:TRMR)
https://news.sky.com/story/adt...
"Tremor already has a US listing through equity instruments known as American Depositary Receipts (ADRs), which it launched in June 2021."
My belief is that if there is strong buying in the ADRs, it should have a corresponding effect on the share price of the UK primary listing? As ADRs and the primary listing price should be in sync?
ADRs and UK share price will be in sync but Americans don't trade ADRs particularly. Yes they have access but generally trade stocks on the index. Thus the idea behind it will be to put Tremor International (LON:TRMR) into the mainstream US market as a primary listing and thus Americans will view it as an American company and trade it accordingly.
There is some merit to this, and in the case of Tremor International (LON:TRMR) it is far more a US business than it is UK. Yes, it has a HQ in Israel and was originally founded there but in reality its executives are all based in the US and its business is largely operated from the US and most of its clients similarly. Of course ultimately only if the underlying revenue and profits come through from execution of the business plan will value really be realised
Not sure what is moving the dial on UK mid and small caps today, but it is a welcome change to what has usually been the case over the last 24 months or thereabouts.
BoE base rate decision at midday, but the 3 month Outlook may be more interesting, let's see how the market reacts. This rise could sell off if perceived negatively. Or could be the start of a more prolonged rally if the outlook is (relatively) positive
Sanderson Design (LON:SDG)
Just watched the webinar presentation of the recent interims available on the company's website. I have to say that CEO, Lisa Montague is impressive in terms of articulating the strategies to mitigate current headwinds and those for future growth. Despite the economic malaise I think the medium term outlook for Sanderson Design (LON:SDG) is very promising.
I would caveat the above by saying that I hold, but hope that I have avoided the dreaded confirmation bias. Given the depressed share price I would be happy to add, but as always more investment ideas/opportunities than available funds.
FTSE 250 up 3.2%
As Obi-Wan Kenobi said- That's a percentage rise I've not seen in a long time.
#EQLS
In the event anyone would like to ask me any investment related questions - say even wrt my thoughts on Equals' Strategic Review.
Then I'll happily try to answer them LIVE here at 9.30am tomorrow.
Disclosure: Equals is the largest position in my portfolio.
Equals (LON:EQLS)
I believe Paul Hill has a pretty large holding in Equals. He must be slightly sweating as to what's happening here as speculation post the RNS swings from favourable to unfavourable because of the odd signal it seems to send?
Zoo Digital (LON:ZOO) Independent non-exec chairman Gillian Wilmot bought around 163k shares on-market at roughly UK£0.37 per share. This transaction increased Gillian's direct individual holding by 5x at the time of the trade. Trade date 27/10/2023
Off topic slightly but does anyone know anything about Good Energy (LON:GOOD) please?
Strikes me that it could be another Yu (LON:YU.) which I am still kicking myself for missing at 350p a few months back but I’m unclear as to whether Good Energy (LON:GOOD) are taking all the hedging risk or whether they lay some or all of this off.
I haven’t done a lot of digging on it yet so have no view but it popped up on my radar and I’m wondering if anyone else has analysed it in detail?
I was looking at it the other day, and my impression is that they make all decisions about hedging themselves. My source was the Interim Results to 30/06 which is on YouTube.
They do not hedge anything
Thanks. By that do you mean they are exposed if prices fall (ie fixing costs at a customer level but exposed to falling commodity prices) and vice Verda benefit if prices rise. Or do you mean neither customer pricing or commodity purchasing is fixed (ie both sides floating)?
They deal in PPA contracts.
At the moment that are paying more for energy than they actually charge their customers; thus the extraordinary profits from last year.
Gotcha - thanks. thats helpful. so I had better dig into this in more detail then - less attractive based on that
Next is quality, but the read-across is to buy ABF/Primark?
Re Equals (LON:EQLS) announcement yesterday:
“the Company has contacted a limited number of potential counterparties including Fleetcor Europe Limited and Madison Dearborn Partners, LLC to assess whether such parties could put forward a proposal that would deliver greater value to Equals' shareholders than pursuing a standalone independent strategy.”
My interpretation is that they have been approached at various times in the past by these and possibly other counterparties to see if they were interested in selling.
Now the Group is more mature, profitable but still growing, a buyers valuation should be higher compared to when the business was less mature.
In addition, Equals (LON:EQLS) is at the early stage of EU expansion. Whilst this has value for EQLS on a stand alone basis, it may have less value to a larger buyer that already has or does not want EU expansion. So, to me, it make sense to have conversations at this time.
A key point to note is the difference in the business model between Equals (LON:EQLS) and Argentex (LON:AGFX) / Alpha International (LON:ALPH). Equals (LON:EQLS) revenue is driven more by FX payments flowing through tech and is far less reliant on advisory fees i.e. Equals (LON:EQLS) doesn’t need as many expensive consultants.
This means margins and returns Equals (LON:EQLS) should continue to improve as the business scales and revenue grows. I hold.
I've never heard of a "Netherlands kitten", but my interest piqued, I
went in, and enquired, "How Dutch is that moggie in the window?!"
Paul, please don't give up the day job!
As a Brit living in the Netherlands, I’d just like to express my feelings about that kind of humour. I found it to be highly effective.
I don't own any FX companies because in fairness I don't understand them well enough. Also it seemed to me somewhat of a crowded trade of late, although I suspect goings on at Argentex (LON:AGFX) may have dampened enthusiasm.
With regard to Equals (LON:EQLS) my initial thought was why would a company that appears to be performing well effectively hoist the for sale sign? Whatever the outcome I wish holders well.
I do however hold Oakley Capital Investments (LON:OCI) which I have followed for a long time and you can't accuse directors of not eating their own cooking. Two more director purchases announced this morning for a total of around £400,000.
Also a sizeable director purchase at Eurocell (LON:ECEL) of £100,000. I don't hold but on my watchlist should funds become available.
Next Monday at 5pm we have a webinar with Huddled Group (HUD) CEO, Martin Higginson. He is a veteran entrepreneur, see more here.
The Huddled businesses include Discount Dragon & Beer Monster, a consumer website selling discounted branded groceries, beverages, and alcohol: surplus stock, mis-packaged, or close-to-expiry items. It’s growing fast from £75k revenue in August 2022 to > £500k in October 2023. Timing is good with the cost of living crises and the benefit of reducing food waste.
Separately, they have incorporated the two home entertainment Let’s Explore brands under Huddled: Vodiac and Let’s Explore. Christmas is the peak season for these two.
It’s very small, Market Cap £7.5m but with cash of about £5m. Stonehage Fleming have 20%. Martin Higginson, CEO 12.5%. Herald 6.8%.
The webinar is a Q&A with me followed by investor questions. For full disclosure, we are paid to do this. I appreciate it’s a micro-cap.
We’d love to see you, Monday 6th November, 5pm, register here: https://bit.ly/HUD_acquisition_intro_webinar
BTW Grey Goose gin is on offer now and I think there’s a further discount for shareholders! https://discountdragon.co.uk/
Just tried searching for gins on the website and it is not user friendly. You press the promotion button for gins and it brings up all alcohols and doesnt allow you to limit to gins. Even the overall search button doesnt allow to limit to all gins and actually take a look at them and their pricing individually. Very disappointing as a shareholder.
Equals
Been thinking about the situation in naming the parties and raising the flag .
On reflection I think this is a very good thing to do from a management teams perspective who have a business to run and job to do .
My old mate Sir Dave Brailsford used to say to me when I was in a flap “you can only control the controlllaboes”
As a clearly good and strong management who have a very credible business they will be working on 3-5 year timescales with deliverables and targets .
By doing this now they flush out a bid or they don’t , if they don’t then they can focus on what they need to do .
Potential buyers trust me absorb the energy and focus out of a business especially a well run and lean one .
I once had a PE buyer lined up but at the time we were overstocked, overdrawn and had a real job on our hands to trade hard through a sticky period . For sure their advisors would have come in and absorbed all our time only to tell us what we already knew . So I said “give me 6 -8 months” as we have a very specific and targetted plan and we need to move from 8 million stock to 4 million and banking from. Minus 2 to plus 2 and after that we can talk but right now we cannot have any distraction so no thanks and of course after that your due diligence team will love us
So I think really good both ways Equals are doing this shows a good management team taking control of the business .
Meaningless announcement by the management and this is the reason I am out now.
Plotting their own takeover as soon as they realised the growth is not sustainable.
Good luck to all holders.
Yiannos
That is the alternate reading of the situation.
I just have a good feeling about the management so I’m favouring the alternative version .
But you could be right .
I’m with you on this Planetx - potential bidders absorb a horrible amount of time, energy and brainpower of management. Having also sold businesses I know just how distracting that can be.
I don’t think Equals (LON:EQLS) had any intention of announcing that they had talked to the parties. Their hand was forced because the discussions were leaked and they had to bring out a hurried rns.
All boards should be periodically looking at creating the best shareholder value and for most companies that involves understanding what others are prepared to pay. Then they have to determine whether a sale is better than remaining independent.
In most instances shareholders never hear about those periodic reviews but as a PLC if they leak they are forced under MAR rules to disclose to the market. So I actually would read nothing into this RNS other than the board doing it’s job, hampered by an unfortunate disclosure leak. They should be looking at who leaked confidential discussions though for certain.
If management are keen sellers a little higher.... seems like a red flag ...and a risky move to go public Id say.
[duplicate removed]
My morning smallcap tweet: Investment shed of hope
Streaksai (LON:STK) Ethernity Networks (LON:ENET) Ocean Harvest Technology (LON:OHT) Cerillion (LON:CER) Empiric Student Property (LON:ESP) X5 Retail NV (LON:FIVE) Kin and Carta (LON:KCT)
◄StreaksAI (STK)► launch of 'Streaks Companion' AI chatbot allowing for "sophisticated humanlike companionship, mentorship and digital assistant services" CEO trills ""With the launch of Streaks Companion, we are not just delivering a product, but an experience".
Here's a brief demo:
"How do I stop losing my shirt on AIM shares?
Chatbot: "stop getting sucked into story stocks like StreakAI, you shmuck." [SP=1.1 Cap=4m]
[edit] Hey, that's pretty impressive. I'm going to buy some!
◄Ethernity Networks (ENET)► wins $475k contract with Tier 1 military aerospace customer to be paid in Nov and Dec. [SP=3.18 Cap=5m]
◄Ocean Harvest Technology (OHT)► study of OceanFeed shows mortality reduced significantly from 49% to 33% and weight gain in chickens. [SP=9.24 Cap=12m]
◄Cerillion (CER)► wins 5 yr contract, worth an initial €12.4m. [SP=1275 Cap=376m]
◄Empiric Student Property (ESP)► trading: 99% revenue occupancy, LFL av. rent up 10.5%. Guides FY23 EPRA EPS 4p and FY div 3.5p. [SP=85.3 Cap=515m]. I hold.
◄X5 Retail (FIVE)► acquisition of 71 stores operated by the Amba retail chain in the Khabarovsk Territory. [SP=NA Cap=NA]
◄Kin and Carta (KCT)► FY-July. Outlook - "Assuming no further material headwinds...we expect modest H1'24 growth over H2'23. Whilst visibility of H2'24 is limited, we expect continued modest sequential growth in H2'24. We therefore expect flat to low single digit total net revenue growth in FY24". [SP=107 Cap=190m]
Always good to start the day with a smile.
Morning Paul, any thoughts onEquals (LON:EQLS) , seems odd to put up the sale sign when I thought the company was trading well and appears to be in a profitable niche sector which the larger players are ignoring for now.
Yup, I've posted my thoughts above. Looks interesting.
Thanks Paul , low valuation may be frustrating management. However wherever I look I see bargains with good sound companies and bombed out share prices. Am hoping for a rebound in the first 1/2 2024 and remain fully invested as shares can rise or fall dramatically. Hopefully now the former
Equals (LON:EQLS) - not a holder and somewhat cynical about this company. While it may have a good product, it has rarely made anything in the way of meaningful profits and chose to rename itself from the perennial disappointer that was FairFX at least partly to shed that previous image. Management have consistently claimed that it is undervalued but it has nearly always looked poor value in comparison to its more direct competitor Argentex (LON:AGFX) rather than the much better quality company Alpha International (LON:ALPH) .
This is such an unusual RNS after two unsurprisingly profitable years with post-Covid tailwinds that the timing looks very opportunistic to me. The risk, obviously, is that if they don't generate any interest the share price is likely to fall back to a reappraisal of the company on a standalone basis. While they are forecasting increasing profits they have previous form in terms of failing to meet forecasts.
Argentex (LON:AGFX) (I also don't hold but have in the past before selling in 2020 ) has always looked a much better quality business purely on the numbers which has been consistently reflected in a higher Stocko quality score. Yes, they have lost both founders in somewhat mysterious circumstances, but Peter Beckwith is behind this one and he's an astute operator.
I don't intend buying either as I don't think that either will emulate Alpha International (LON:ALPH) but, if I had to choose at these prices, I would say that the risk/reward seems to be better at Argentex (LON:AGFX) even if there is an overhang from Harry Adams and a disagreement over strategy.
For full disclosure,. I do own Ramsdens Holdings (LON:RFX) in this space which I think is a better quality business than both.
I think you have to really believe in Equals (LON:EQLS) profit forecasts to believe that this company won't disappoint in the future as it has done in the past. The fact they're so publicly putting it up for sale might indicate that they don't have the same confidence in market forecasts as current holders need to have to justify the current multiple.
Naming two (in their eyes) potential acquirers at this stage is not something that I've come across before. Presumably they must have obtained permission to do so? Suggesting they are already in some form of limited discussions with these two parties. But it is very clumsily worded if so. Also, is anybody aware of any speculation in the market? Pretty likely for it to be aired here if there had been any. All looks rather desperate to me.
I am a holder. My counter to what you are saying would be that:
The CEO and CFO come across as super-professional and super on-top of what they are doing - far more on top of what is going on than most of the companies I work with and def more so than Argentex.
Growing the "jaws" - i.e. profits rising much faster than revenues.
They expect the fastest growth part (solutions) to grow from 30 to 50% of revenue in the next 12-18 months. - that would make a big difference
Good strong strategy and have executed on strategy to date (by which I mean the last 24 months).
More focus on larger enterprises now they have APIs
All of this is the direct opposite of Argentex.
Of course I have been wrong before and will no doubt be wrong again....
All fair points. However, Ian Strafford-Taylor has been CEO throughout the incarnation of this company as FairFX and its reincarnation as Equals so was as responsible for its previous strategy which failed to yield meaningful profits as he has been for its current one which has, latterly, yielded some profits.
I have followed this company pretty closely prior to and during the time I was a holder of Argentex (LON:AGFX) and the end objective of selling out has been a recurrent theme rather than that of building a business for the future. So, it doesn't surprise me that after a bare two years of profit, he is once again taking about selling the company.
I have no axe to grind here having never held this company partly because I was less enthusiastic about Strafford-Taylor than you. The CFO is an M&A guy and his perilous loading up of Entain with debt put me off ever investing there either.
The Equals announcement is just bizarre. I have to say that I would err on the side of caution here as well on the premise that if management obfuscate - the RNS raises many more questions than it answers - it is done deliberately and for no good reason.
If there was 'market speculation' it was in some airless dark trading corner.