Small Cap Value Report (Thu 21 Dec 2023) - SRT, CARR

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Summaries
SRT Marine Systems (LON:SRT) - 41.5p (y’day’s close) £80m - Equity fundraise - Paul - AMBER/RED
The financial position looked weak last time I reviewed SRT in Nov 2023, so the £10.5m fundraise announced today is welcome at reducing risk somewhat. I particularly like the £7m coming from a "strategic investor" in the sector. Overall, this company is erratic and has almost no visibility, so I'm still leaning towards a moderately negative view (but improved from red last time, to reflect the improved cash position).
Carr's (LON:CARR) - up 2% to 96.44p (£91m) - Full Year Results - Graham - AMBER
Expectations are unchanged at this group of agricultural and engineering businesses. The engineering order book has grown but profits are flat for now, while agricultural business is seeing reduced volumes and profits as inflation curbs demand. Quality seems average here.
Paul’s Section:
SRT Marine Systems (LON:SRT)
41.5p (y’day’s close) £80m - Equity fundraise - Paul - AMBER/RED
SRT, the AIM-quoted developer and supplier of maritime surveillance systems and navigation safety products, announces a strategic investment and conditional fundraising of up to approximately £10.5 million (before expenses) comprising a Subscription, Placing and Retail Offer (together the "Fundraising").
The net proceeds of the Fundraising are expected to fund working capital to strengthen the Company's balance sheet and facilitate the growth of both the surveillance systems and navigation transceivers businesses, with the outlook for these business as expected and reported in the Company's half year report on 20th November 2023.
The price is 35p, a discount of c.16% to last night’s closing price of 41.5p.
There are 3 elements to the fundraise -
Placing of £3m, with 8.57m new shares.
Subscription from a “strategic investor” for 20m new shares, raising £7m.
Retail offer for 1.43m new shares to raise £0.5m.
Who is the strategic investor? It’s Ocean Infinity, “a highly reputable marine technology company…”
Oliver Plunkett, CEO of Ocean Infinity, commented:
"Ocean Infinity is at the forefront of robotic technology deployed to gather data from the oceans. Creating a close and proactive relationship with SRT allows us together to offer clients a complete data solution, from acquisition to insights, for managing and securing coastal territories and beyond."
Dilution ? Not too bad -
Assuming full take-up of the Retail Offer, the New Ordinary Shares will represent approximately 13.48 per cent. of the Enlarged Share Capital.
Paul’s opinion - I flagged the considerable risks at SRT here on 20 Nov 2023, with a RED view, noting the £9.7m debt within current liabilities. So this £10.5m fundraise, after costs, will only offset that debt.
Recent interim results were poor, and current forecasts assume a gigantic H2 weighting in FY 3/2024 - which looks risky. This company is no stranger to missing forecasts.
Given the almost complete lack of visibility, it’s not possible to value SRT shares accurately, in my view. It’s had the occasional good year in the past, but then sunk back into losses subsequently. So how much can we rely on the expected profit this year?
On the plus side, I very much like that a £7m investment is coming from a strategic investor, in the same sector. That validates SRT considerably, in my view.
Given that short term funding issues are now resolved, I’m happy to shift upwards from RED to AMBER/RED, to reflect the range of possible outcomes here, and the great difficulty in predicting what the future holds, given the erratic performance of the past, very long delays in securing contracts, extreme H2 weighting baked into FY 3/2024 forecasts, etc.
Definitely a share for optimists only!
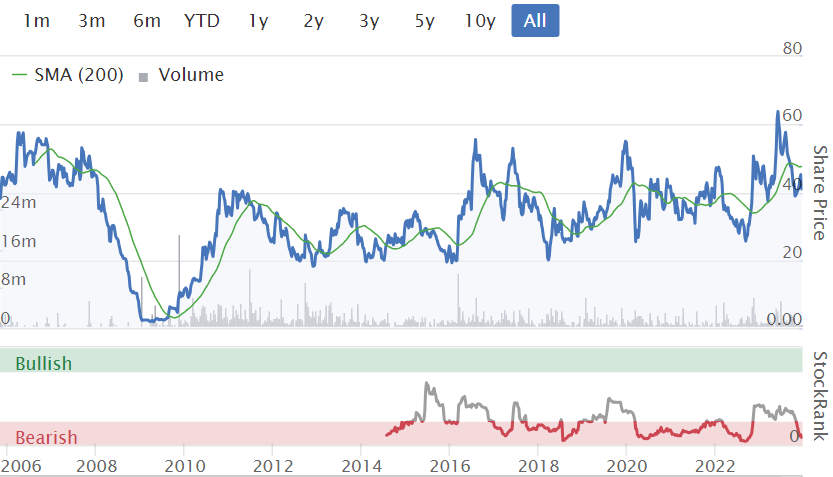
SRT shares have zig-zagged sideways for 18 years, with the same story -
Graham’s Section:
Carr's (LON:CARR)
Share price: 96.44p (+2%)
Market cap: £91m
Carr's Group plc (CARR.L), (''Carr's, the ''Company'', or the ''Group'') the Speciality Agriculture and Engineering Group, announces its audited results for the year ended 2 September 2023.
These results sadly show profits moving in the wrong direction:

Engineering: adjusted operating profit is only slightly lower than last year at £5.3m. The order book is strong at £60m (last year: £41m).
Specialty Agriculture: adjusted operating profit falls from £9.2m to £5.6m. There’s high inflation in this sector - so input prices are up, sale prices up, revenues up, and volumes down as the high prices suppress demand.
Here’s an overview given by the company of inflation in the agriculture sector. It sounds extraordinary:
In the UK, costs of the principal ingredient of feed blocks, sugar cane molasses, have increased by 70% over the past three years, which, with increases in other ingredients along with energy and labour, has necessitated a 45% increase in selling prices over the past two years. When combined with 45% increases in other feed costs, a 180% uplift in fertiliser prices and 60% on diesel, livestock customers limited their expenditure, particularly impacting UK sales volumes during a mild autumn in 2022 and winter 2022-23 that supported continued grazing for longer than usual. Feed block volumes sold in the UK were down by 18% on FY22, a situation consistent at all distributors.
Volumes in the US are down too, impacted by inflation and by three years of drought.
Adjusting items: the statutory results are £6m worse than the adjusted results.
£6m of adjustments include:
£0.9m amortisation
£0.6m restructuring/closure costs
£0.6m cloud-based ERP system
£3.8m goodwill and other impairments, triggered by higher rates.
If someone wanted to ignore the goodwill impairment I could understand that.
The other items are more questionable in my mind, especially the installation of a new ERP system. Companies need new software systems all the time!
So in my view the results aren’t “clean” and the adjusted numbers are too optimistic.
Net cash at year-end is £4m.
Outlook:
Trading conditions in agriculture remain challenging and the Board expects this to continue through the current financial year, while retaining confidence in prospects improving in the medium to long term. The Engineering division delivered a strong second half performance during FY23 and the order book levels will enable year-on-year growth during FY24, while also providing renewed confidence beyond the current financial year. At this early stage in the new financial year expectations for FY24 remain unchanged.
Graham’s view
This one seems priced about right to me.
I managed to avoid looking up the market cap before studying these results, so I was able to ask myself what it might be worth before knowing what the market thought! I came up with around £50m as a minimum valuation - a cheap multiple against the adjusted results, but more stretching if you don’t allow some or all of the adjustments.
It turns out that the market cap is c. £90m. It’s a more generous valuation than I’d want to pay for it, but it’s not outrageous:

The SCVR archives describe how this company has had some accounting difficulties in recent times, which even resulted in its shares being suspended.
While that issue should now be firmly behind it, more fundamentally I still don’t see signs of above-average quality here, either quantitatively or in terms of the company’s operations. Investors have plenty of engineering companies to choose from. And the fall in profits in this group’s agriculture division doesn’t inspire much confidence.
Come to think of it, I’m still unclear as to why these engineering and agriculture businesses should remain under the same corporate roof!
I’ll stick with a neutral stance on this one.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

103 comments
That would possibly explain why (IC journalists) they appear a touch out of their comfort zone evaluating equities.
IC writer Robin Hardy, a former fund manager, wrote on 24 November that a recovery in house builders was months, or even years, away. Guess what happened next. But we all get it wrong. I was a coin toss away from selling ANSYS (NSQ:ANSS) on Thursday afternoon. Yesterday a bid emerged.
No one seems to understand their accounting processes. I held but got out six months ago once I realised this. For me it looks highly doubtful that this level of income can be maintained without erosion of capital. I wouldn't be surprised if there were an uncomfortable day of reckoning. Looks, smells and barks like a Dog.
hi doctor dave
Which company are you referring to?
Snazzy
Whoops sorry Diversified Energy (LON:DEC)
Diversified's strategic partner is Oaktree Capital. They are a very tough hedge fund to deal with. From memory their commitment is $1bn if which $370m has been deployed.
There would need to be a lot of people in cahoots with Diversified if they were fiddling numbers. Clearly its not impossible but with the ESG sphincter police everywhere, it's a lot easier to say no to them.
The letter that was sent to them was by 4 Democrats out of a 52 member committee. They waited till the day of the listing. Not remotely suspicious...the price action was also highly suspicious for 2 or 3 months as if someone knew something. US senators are notorious Insider dealers imo. Nancy Pelosi must be the greatest investor of all time....
Something weird has clearly been going on. I have no idea what it is but basing an attack on information 2years out of date is also suspicious.
Anyway time will tell us the answers.
Same guy from Dubai buying up Revolution Bars (LON:RBG) appears to be buying a decent stake in Saga (LON:SAGA) too - just announced today. Interesting. If he builds up a bit more then Saga (LON:SAGA) is going to become super illiquid given DeHahn’s stake. The travel business should be blowing the doors off and as the insurance cycle turns this could get spiked up quite quickly. One of mine for 2024 but lets see how it plays out.
tinyBuild (LON:TBLD)
Has anyone looked at Tinybuild today? I've only just seen they're trading at 4p Post the rise with a fully underwritten placing at 5p. Underwritten by the CEO and biggest shareholder.
Big news for Harbour Energy (LON:HBR) big reverse takeover will it be approved.
Thanks santa. Hope this continues to rerate. Issuing new shares at £3.60 so some 20% higher than current price. But it looked decent value without the new deal at that piece IMHO
Been an exceptional week even on some larger caps
SCS (LON:SCS) looks like voted through & takeover going ahead. Was hoping an improved offer might have appeared late in the game
Capital (LON:CAPD)
( I took a small stake a few days ago ) put out an encouraging RNS this morning. It’s a worthwhile read for anyone interested. Briefly it’s the largest contract win in MsaLab’s history and probably more importantly provides a beachhead for them into the Americas. (5 year contract expected to generate £30m in revenue p.a.) MsaLabs currently contributes about £40m or about 12% of Capital's revenue. ( So this is a pretty big contract win ) They appear to be quite bullish on their prospects in the Americas and have newly appointed a CEO for the Americas. The rest of Capital’s business seems to be doing very well and growing. Capital has featured recently in Roland’s articles 5 easy rules to find good small cap stocks and 5 UK shares at 52 week lows to consider buying
I’ve considered Capital to be undervalued for sometime, perhaps this is the catalyst that they need for a rerating ? I wonder.
Thanks for highlighting. I agree Capital (LON:CAPD) looks interesting and I've held in the past. From what I can tell the labs side of the business is not currently profitable so not sure if this new contract will be earnings enhancing any time soon? Would be interested to understand the level of profits they might expect from this side of the business once it scales up. The only thing that slightly puts me off is there were some big director sales a few months ago - might not be anything to worry about, but at least something worth highlighting.
Thanks for your comments ,
Yes, I agree it appears quite difficult to ascertain how profitable the labs side of Capital (LON:CAPD) business will be. The best I could figure out was that in 1921 labs revenue of £12m gave a pretax loss of £244600 and in 1922 revenue of £26.6m gave a pretax profit of £985000. 2023 revenue looks as if it should be closer to £40m, which is expected to increase by a further £30 million going forward. In addition it looks as if Capital is planning for an increase in its PhotonAssay units from the current 10 to 21 by end 2025. Of this increase in units I think 3 will be used for the new contract therefore I assume that they are quite confident of further business. I would expect this to enhance profits quite nicely.
Apologies my 1921 and 1922 years should be 2021 and 2022 . I must be getting old.
I've been doing some research on Carr's (LON:CARR) . I agree with Graham that the quality is only average, despite the impressive history of former businesses of Carr's Milling, McVities and Carr's biscuits. all of which have been exited. Neverthess, its market cap is below book value, management has changed and Harwood are at 10%.
I'm interested in NWF (LON:NWF) and Wynnstay (LON:WYN) at the moment as well, and am a long-term holder in Wynnstay. All agricultural businesses are suffering a hang-over from last year and are getting ever closer to a bargain. I think these two are higher quality - I liked what I saw at NWF more than Carr's.
Carr's (LON:CARR) looks a possible break up candidate, paricularly with new management and Harwood. I was put-off a tad by the complexity of the business - multiple operations in different countries, so not an easy thing to break-up, I suppose a demerger might be an option? They also have had multiple accounting difficulties and there a few more minor restatemnts with today's results.
I'm interested in NWF (LON:NWF) and Wynnstay (LON:WYN) at the moment
Hi topvest. I think this might be the first time that I’m aware of our radars coinciding. We have had very contrasting macro outlooks this year (still do, I think) and fish in different waters. But I have been eying up Wynnstay myself. The name is really a commodity play and I would only enter when/if I sense a rotation away from my home territory of tech. The CIO of my bank insists that we are ALWAYS in either a tech bull market or a commodities one, but NEVER both at once. That might be an oversimplification but it is excellent food for thought.
I don’t think WYNN is quite cheap enough yet. But the dividend yield %ge is nearly as high today as it was in the c.300p lows of 2020. If the SP falls another tenth the trailing yield goes to 5% by my calculations and there’s the buy point.
Maybe ;-)
What are your thoughts?
BnB - I would broadly agree with you on Wynnstay (LON:WYN) - On a dividend valuation (with growth at 5%) I had 340p down as a target top-up buy-price for a 10% annual return. It may nudge down a tad lower, but is unlikely to hit £3 in my view, absent a further detrioration in trading.
I have 325p as my target for WYNN with a dividend-based calculation of fair value at 413p at a 9% discount rate, so a c.20% margin of safety. But I would not rule out 300p happening. I think another poor update is a real possibility.
Very experienced people appointed by Nanoco (LON:NANO) ; a company that is one of the most undervalued in the small cap sector-FEB2024 cash more then the current market cap!
Good afternoon Yiannos. As you know I support your continued posting on this board because you often provide useful commentary, so please don't take this personally.
You mentioned Nanoco (LON:NANO) recently, on 14 November and 4 December and I renewed my lapsed research at that time. I have now spent too much time on this company, but sadly for me the answer has always been to not invest. In case anyone is enticed by Nanoco, the brief history is that they have been a jam tomorrow company since inception but they developed some very clever tech which I barely understand concerning cadmium-free Quantum Dots. Lack of any sales revenue meant that hopes became centered on a patent infringement case against Samsung which NANO won but on terms which disappointed everyone except Samsung who paid $150m (IIRC) for the right to use the tech any way they wanted. The questions are how long will the Samsung settlement money last (a lot is slated for distributions) and will anyone pay enough money for NANO's dots or licenses to use their IP to keep them afloat when the cash from the settlement runs out? The first commercial order was received in November but no numbers were released in the RNS which said: 'Demand is expected to grow gradually, enabling Nanoco to deliver the goal of being self-financing during CY25. Earlier adoption in more applications, or by more end users, has the potential to accelerate that expectation. If the infra-red sensing technology is adopted in high volume, mass market products, demand for Nanoco materials has the potential to grow very rapidly beyond CY25.' Two new NEDs have been appointed with relevant experience but there are competitors (for example https://quantumscis.com/about/ ) and there is no news yet about Samsung, Apple, or anyone else buying NANO's dots for exciting new consumer products which is where volume production and profits were originally supposed to come from. All this is open to interpretation but my view is that this is still a jam tomorrow business.
I have been very clear in Nanoco (LON:NANO) from the start.
FEB24 cash is above its market cap and for me this is a clear buying opportunity. They have stated that they will pay between £33m-£40m back to shareholders and I believe this should be in the form of a tender offer ; for example 1 for every 3 shares at 35p!
After this the company will still have £20 for the next 3 years in order to achieve its revenues targets and cash flow objectives.
First I always look for stocks that I will not lose money and then I invest-the case here is that I will lose money only if Samsung goes bust by FEB24(will they?NO).
I have also clearly stated that the company has been looking at 19 infringers and one of them is at an early stage for being approached or eventually being sued (like the Samsung case!).
As for the jam tomorrow statement I am sceptical myself and I tend to agree with you , but the IP and the successful team that won them the Samsung case must be worth at least some millions.
Have also in mind that If it wasn’t for an activist investor that got it completely wrong for being careless and too optimistic this should have been trading north of 30p.
Great opportunity for investment.
Thanks
What is the actual Samsung amount?
I see a group of shareholders are not at all happy with how it has been handled.
""Nanoco had settled on terms substantially less favourable
than its prior statements had led shareholders to believe, and
on less favourable terms than our clients understand had been
previously offered by Samsung,""
It’s one shareholder that bought at 50p+ and wants his money back!
Christopher Mills has been supportive of the board and the management team (just mentioning him as he seems to be very popular here-personally I do not pay attention).
The amount is in all my previous statements (£59m) and has been hedged as well as it is paid in dollars and it is above the current market cap.
DYOR
Thanks
I’ve met this company 3 times over the past 20 years and you are always blinded by extreme mgmt optimism (delusion) which is never supported by actual delivery.
Which is?
Carr's (LON:CARR) another Harwood Capital holding, this was discussed recently in a Christopher Mills interview.
On the subject of LON:CARR I am inclined to agree with Graham's comments on adjustments. The ERP system is cloud based so there will be an annual subscription - so were talking implementation costs - which should be amortised! Much better they play a straight bat after what has been a poor run. That said, quite like Carr's - OK balance sheet and a very safe industry IMO.
Carr's (LON:CARR) I think it could be broken up, my guess fairly likely. The interesting part seems to the nuclear robotics. I only a small recent starter position.
Interestingly, the Harwood nominee to the board is now "Executive Director of Transformation". Is suspect the break up is not if but when. I have a small holding.
Dewhurst (LON:DWHA) (or Dewhurst (LON:DWHT) prelims out today.
Very under-the-radar this company (it says something when even the most excellent MrContrarian ignores you) , although there has been some discussion over the years on this forum.
Unremarkable results, operating profit c. 12% behind last year's once you adjust for the cyber incident. Best described as a company for the patient investor.....
There was one bit in the statement that I thought I would bring to your attention - simply to highlight just how bloody complex pension liabilities can be, and why higher rates are not the only variable.
Pension Scheme Deficit
The Company paid a total of £1.6 million deficit reduction contributions into the pension scheme this year and despite this the scheme deficit still increased by £0.3 million to £2.1 million (2022: £1.8 million).
The main reason for the increase was an underperformance of the pension scheme assets, which was partially offset by the liability discount rate increasing from 5.25% to 5.50% at the year-end and increased mortality rates. Recent increases in mortality rates were initially associated with Covid-19, but unfortunately these are now being sustained primarily due to other causes. As a result the changes are being reflected in actuarial rates for future expectations of life expectancy.
It is the mortality comments that grabbed my attention, and which have relevance to other schemes (sadly, pensioners dying early is good for business, and possibly also a tailwind for the Treasury). If mortality remains elevated at higher levels then we could see some big swings in liabilities elsewhere.
DEC
Is the dividend really 25% and PE 4.5%
there must be a catch here. I hold and it has halved over the last year.
Any comments would be appreciated.
I've been a holder in DEC in the past. But I am extremely wary of any stock that promises a dividend at these levels. It rarely ever lasts. I can't remember a single asset that I've owned that has paid a level of dividend like this for long. It's a HUGE red flag and I'll be avoiding until the ramifications of the latest inquiry are known. Something does not seem right. Besides which - the technicals of this stock are shocking and technicals always trump fundamentals - I dislike buying an asset that drops continually. Yes, the stock could fly up, but on the other hand, it could keep declining, because cheap stocks can always get cheaper.
I have covered this last week and I believe the current dividend is not sustainable and not covered by future earnings.
Also Biden administration implying that they should be basically banned as they are just using old wells.
There was a Bloomberg report earlier this week stating that DEC has not put sufficient costs in its balance sheet for old well shut down / clean up. Given the age of their wells and the number they close down each year this looks like a red flag and caused a15% drop on the day the report emerged.
I am holder still (small amount) though I did consider selling on Tuesday after the report) - on the flip side (1) I do not see how their auditors would allow them to not cover their expected future costs correctly in the balance sheet (2) They have been closing many wells per year for several years so surely they understand the costs and so do their auditors.
Dividend% calculated has been rising all year as their share price has fallen but they continue to pay it and report good earnings (though Stockopedia now has their earnings below an amount sufficient to cover the dividend). Next dividend is due March.
The Bloomberg report was actually from a couple of years ago and the letter appears to be a rehash of that. Peel Hunt (and other brokers) think a big over reaction.
Diversified Energy target reiterated by house broker after US letter | OTC:DIEN (proactiveinvestors.co.uk)
These are old wells that need plugging by someone and seems far better for Diversified Energy (LON:DEC) to be doing this as part of their responsibilities as new owners rather than them being abandoned altogether - the company cover this in a lot of detail in recent presentations, essentially presenting themselves as part of the solution.
Suggestions they should be banned makes no sense - if they're abandoned who would then cover the cost of plugging them? The main risk is that the cost of plugging them is massively understated and the company won't be able to meet these liabilities - without a detailed understanding of the industry it's impossible to say either way.
Note that DEC is very hard to analyse as they use a lot of complex derivatives to hedge their gas exposure - because of large MtM movements, this leads to big swings in their headline earnings. The earnings on the Stocko report are essentially meaningless and I not use this to gauge whether their dividends are sustainable. I haven't studied the company in detail but from my initial analysis I believe the dividends are covered by cashflow and are sustainable.
The bottom line is - I don't trust them with my money. It seems very suspicious that they 'win' an ESG prize just before listing on the NYSE and then this disaster appears! Clearly the award is not worth anything; it's just corporate BS games.
I simply do not trust them, that an out-of-the-blue, mandatory, lowball offer will not be made for the company and shareholders will be screwed and management will somehow be associated with it. It's happened too many times for me to count. Small investors always lose.
Hi, LuckyDip. If you (and any others) want to look into this seriously, The Oak Bloke has commented better than I. Try https://theoakbloke.substack.c... and then read his other pieces on DEC. All I can add is that, having been invested for a while and considerably underwater, I'm not selling. They are doing a good job cleaning up the wells, eeking out more gas than the majors would have, through workovers and leak detection/closing. It's far better environmentally to do what they are doing than drill new wells; and we need gas for a while as the US closes down coal. They have their own clean-up company that is now contracting for States on their 'orphan wells', i.e. those simply abandoned by others. And their recent cost of well closure is lower than forecast. And no, you don't have to set aside that money 20 years ahead of time.
They continue to buy back their own shares. And they have committed to the next div already. And the CEO is heavily invested. All factors for a recovery.
Revolution Bars (LON:RBG) Revolution Bars Group Plc was informed on 19 December 2023 by Artemis Investment Management LLP that its shareholding as on 18 December 2023 was 4,784,313 representing 2.07% of the ordinary shares held.
http://newsfile.refinitiv.com/getnewsfile/v1/story?guid=urn:newsml:reuters.com:20231221:nRSU6255Xa&default-theme=true
According to Stockopedia they used to have 18m shares (although not sure major shareholders list has been updated since March)
Revolution Beauty (LON:REVB)
No research is available at the moment but there is a capital markets day in early January.
I expect them to achieve £210 revenues for the current financial year and an upgrade in EBITDA after the the strong improvement in H1.
An improvement in gross margin in 49.5% and after an exceptional costs of £13m then they can achieve about £30m FCF pa.
Market cap only £105m and in a three year forward revenues of £300m this seems to be undervalued.
Big seller in the market at the moment and FCA still to decide about the ongoing investigation for the delay of FY22 results.
DYOR
PS Personally I do not hold at the moment.
After a 2.5 year Bear Market, how much could smallcap stocks & the #FTSE #AIM index rise in 2024?
Well assuming a 10% increase in earnings and a 25% multiple re-rating (re catchup trade - see chart below).
Then I wouldn't be too surprised, if smallcaps climbed >35% next year.
Then I wouldn't be too surprised, if smallcaps climbed >35% next year.
The question is whether growth will return to the UK economy and liquidity to UK stocks sub FTSE100. Those are the prerequisites for a small cap bull. Does your answer give you the same confidence as the chart?
We deserve a nice bull run now!
Am i the only one who quite enjoys depressed prices ? if i am still adding more funds in rather taking out (i gues the majority are perhaps in that boat ?) is it not better for us that prices are depressed? i know we all love paper gains but looking at some of the gains over covid some em were clearly fantasy stuff with the benefit of hindsight (that i didnt have). I gues the sensible crowd are the ones who cash out at the peaks and move to cash and earn great savings rates.
Not if you are fully invested in loss making stocks, fortunately there has a rally in the last 2 months, otherwise another poor year in the UK markets.
Not all prices are depressed though, I have been taking some profits, on ones that look peaky, such as Rolls-Royce Holdings (LON:RR.) Cerillion (LON:CER) Chemring (LON:CHG) Warpaint London (LON:W7L) , struggling to find stocks to invest in at the moment.
struggling to find stocks to invest in at the moment.
I kinda know what you mean - i have some decent cash coming in from £TEG. presuming takeover goes ahead I had kinda made up my mind to go with Jet2 as my next investemnt waiting for soem cash to turn up but that thats up 30% in 2 months approx . seems like the good uns always just get away from me just before i buy em sigh.
Yes a lot of shares have had a good run lately, Wise (LON:WISE) Bioventix (LON:BVXP) Good Energy (LON:GOOD) Yu (LON:YU.) On Beach group (LON:OTB) Journeo (LON:JNEO) IQGeo (LON:IQG) Redrow (LON:RDW) Cavendish Financial (LON:CAV) Howden Joinery (LON:HWDN) Bloomsbury Publishing (LON:BMY), to name a few, I'm expecting there will be a pullback on some next year. I do holdJet2 (LON:JET2). ME International (LON:MEGP) looks good value now, I hold.
Hi Rusty. Agree on MEGP. Bought it yesterday.
It depends on your hunting ground but I have found a few attractively priced cyclicals of late, VP (LON:VP.) and Brickability (LON:BRCK) to name a couple. Amongst growth compounders, 4imprint (LON:FOUR) is the cheapest I’ve ever known after pulling back on fears of a slowdown that may not happen and Volution (LON:FAN) remains under-appreciated. Left field choice would be Keywords Studios (LON:KWS) - a screaming buy if those that see the name as a beneficiary of AI, not a victim, are correct. I’m veering towards that view and have a position.
With takeover situations like Ten Entertainment (LON:TEG) I would consider selling now and switching to a new position - it feels like quite a big opportunity cost right now given small cap share prices could climb quite sharply over next few months.
You’re not the only one rmillaree. Since opting for buy during big market falls and selling or top slicing in bull markets my investment performance improved massively.
I’ve been doing that this Century and took full advantage of the buy opportunity after 3 bad years in 2003, and then in late 2008 at peak of banking crisis, and then again in 2020 and then the Truss/Kwartang farce fall, and since then especially oversold Investment Trusts including big dividend paying Commercial Property Trusts.
So many investors get too gung ho and confident in bull markets and end up buying ahead of big falls and are then either too scared to buy after big falls or won’t buy for fear of even bigger falls ahead. That risk IS justified…….but we can rarely time our buys to get in right at the bottom and may indeed suffer paper losses for a while. BUT those losses are soon recovered if buying good quality shares and Investment Trusts when the bounce at last comes.
e.g take shares like Aviva (LON:AV.) Legal & General (LON:LGEN) M&G (LON:MNG) and Phoenix group (LON:PHNX) . I know people who panic sold near what turned out to be the recent low, instead of checking thoroughly to see if it was an excellent top up opportunity. FTSE shares like AVIVA and LGEN paying an 8% to 9% dividend at the recent low, that they are confident of increasing too are so often gift horses and not sells. Ditto some of those Commercial Property Trusts also paying 10% dividends and in one or two cases increasing them too.
And the same applies to the many oversold “green” rated small company shares covered so well here. All previous bear markets have ended and so surely will this one, and the bottom might well have already been seen.
I think my portfolio aligns quite a lot with yours, Ken. I just bought more Chesnara (LON:CSN) , which hasn't responded yet. Very careful build-up company, I believe, div just over 9% and growing at c. 3% p.a. I don't go for high excitement growth shares, but if this gets from 260 - 340p over the next 2 years, for a still 7% yield in an environment where cash is likely back under 3%, that's a 30% gain, plus nearly %19 div. Even half of that is 12% total return for two years. I feel I can sleep on that.
Not that the PE Trusts will likely be worse, or GCP Infrastructure Investments (LON:GCP) .
Even if Labour get in???
Surely that’s a certainty and I suspect markets believe this . Probably they also believe that Labour cannot possibly be worse than the incumbents. What we don’t want is a hung parliament
Without wanting to get political, Labour appear fairly moderate at the moment and Rachel Reeves has a City background so you'd hope they'd be reasonably supportive of UK companies.
I don’t want to get in to a political debate, but sometimes coalitions can ( and did here) lead to compromise decisions instead of disastrous ones from single party Government. So fwiw I don’t think a coalition Government would be market negative. Nor historically have Labour Governments caused significant UK market underperformance. And it wasn’t a Labour Prime Minister who said “f**k business.”
Agree with you that Chesnara (LON:CSN) looks a bargain. I’ve held it for a good while but am 10% down, excluding the big dividend.
It’s not surprising that I’m down as Chesnara at 259p is almost at multi year low and almost back to the rock bottom March 2020 low. That’s despite solid Results AND an 18 year record of dividend increases!
So unless there’s surprise bad news, Chesnara looks a stunning bargain buy that’s been well and truly left behind during the recent market bounce.
I hope Labour don't get in ...
Hargreaves Services (LON:HSP)
Mixed update, but there remains plenty of value on offer despite the more pronounced slow down at HRMS, the German recycling subsidiary. Debt is confined to leasing obligations of £28.8m with the closure of the defined benefits pension scheme at a significantly lower cost than originally anticipated, scheduled for early in the New Year. This combined with the release of £7m on an annual basis from HRMS is allowing an increase in the dividend from 21p to 36p. There has also be good progress regarding its renewable energy land assets
"The period has also seen good progress with the permitting, development and commissioning of the Group's portfolio of renewable energy land assets, with the first package of assets likely to go to market in the financial year ending 31 May 2025."
The above has helped cushion the share price fall as Singer have downgraded PBT by 30% for the year ending May 24. On this basis the shares trade on a forward PE of 11 and yield of 8%, or thereabouts.
Harwood own close to 30% of the shares that trade at a significant discount to NAV of somewhere close to 700p and I wouldn't bet against Christopher Mills and his team realising a price much greater than is currently attributed to the equity over time.
I have a modest holding and shall remain patient.
Hargreaves Services (LON:HSP) Agreed and same here, modest holding and remaining patient. Buys look like they are overtaking sells now I think so SP may not be affected that much but who knows. Will be very interested in Paul's opinion later though as always.
Re Hargreaves Services (LON:HSP)
I have held since start of Jan 2021 mainly due to the potential break up value of this business. If I had a criticism of the usually superb, down to earth management team, it would be this announcement made as recently as 25th Oct at the AGM
Hargreaves Services plc (AIM: HSP), a diversified group delivering services to
the industrial and property sectors, will hold its Annual General Meeting
("AGM") today at 11am. Ahead of the meeting, the Group's Chair, Roger
McDowell, has issued the following statement:
"Having resumed the Chair, I am pleased to confirm that all three business
sectors, Services, Hargreaves Land and HRMS, are trading in line with the
Board's expectations.
I too will continue to hold, not least because that dividend is c9%!
GlobalData (LON:DATA) I hold
Fascinating strategic deal done today - Inflexion buy 40% of just the Healthcare division valuing that division at £1.15bn
The other two divisions are where 65% of the business is so suggests a full enterprise value of around £3.2bn for the overall business (after the 40% mis stripped out). Even after todays announcement the shares trade at less than half that. The deal also removes all debt for the company and means they have net cash of circa £200m. So now we have a highly cash generative business with net cash and proven valuations well in excess of current market cap. Certainly de-risks things
It's certainly an interesting situation. Here we have a billion pound company listed on AIM with a CEO who owns nearly 60% of the shares and yet the company is apparently massively undervalued with a great growth track record. Nobody seems interested in talking about the company either. So what does all of this add up to? I don't know!
The CEO at GlobalData (LON:DATA) has done this before - he made hundreds of millions in a previous venture so has a very strong track record and knows what he is doing. I suspect this hasn’t been talked about much for 2 key reasons - firstly it is in a slightly odd market cap window at £1bn (ie not a small cap but not really a big cap either : so a mid-cap with most of the ownership in CEOs hands) - the move up to £1.5-2bn will help it with institutions and trackers. The second is that tech was out of fashion and the fear was the multiples would keep de-rating.
I think what we are seeing now is that the CEO is taking valuation into his own hands with deals such as this one. I also think you will see him take his share ownership down below 50% to allow for better liquidity.
Anyway - think this one has a 50-100% upside over next 12-18 months so happy to hold it here
I agree that it is a great deal; however, healthcare represents 50% of the EBITDA (35% of revenue) and is arguably the jewel in the crown for GlobalData.
Smartspace Software (LON:SMRT) SMART METERING SYSTEMS: Shareholders controlling 17 per cent of the company, including the company’s founders, have said they will reject a £1.4 billion offer from the US private equity group KKR for the metering company. “PrimeStone and the founders are disappointed with the offer price and intend to vote against … the offer,” they said in a statement to the stock exchange.
Smart Metering Systems (LON:SMS) I think is the company you mean?
No it is Smartspace Software (LON:SMRT) I meant but I cut and pasted the comment from a Times email they sent! I missed the fact that they’d got it he name wrong, so good spot you! It’s very confusing when two companies with similar names and tickers report news on the same day! The shareholders are voting against the current bid from KKR for the co.
Smartspace Software (LON:SMRT) has a mcap of £20m.
Oh God I’m going back to bed until the New Year….you’re absolutely right!
Hargreaves Services (LON:HSP) trading statement today would win a prize for being opaque. With their shareholders, I would have expected better.....
Hargreaves Services (LON:HSP) following on from yesterday's talk about fund managers, Harwood Capital are a major shareholder, with over 28%. I don't think Chris Mills has mentioned it recently in his interviews.
It is also Paul Scott's watchlist, so maybe he can comment on it?
Why are Stocko showing this only down 4%, when it has been down over 10%, for most of the last hour?
Good morning, Paul. My first post on Stockopedia having joined at the start of this year… I’ve been listening to your podcast for a couple of years and it’s simply brilliant. Stockopedia has entirely changed my approach to investing and my overall returns have skyrocketed, mainly due to avoiding (what I previously hadn’t seen as) high risk stocks - one such example is SRT, which used to hold after being tipped by Simon Thomspon. Keep up the great work! Rich
Simon Thompson tips are a red flag to me.
I can give you 100 examples of Simon Thompson and shares that he covered that sky rocketed.
It’s about doing your own research , not following anyone blindly, and especially not blaming anyone else if you lose money.
If you have followed Paul two years ago you would have probably been wiped out-If I am not mistaken he has admitted that he lost about £2m.
Thanks
If you have followed Paul two years ago you would have probably been wiped out-If I am not mistaken he has admitted that he lost about £2m.
I lost more without even following his trades!
He makes alot of big mistakes, just use the information to help your own research!!
I joined Stockopedia about a year or so ago, It has helped my stock picking immensely. Like a lot of people I tripled my portfolio in that last bull market and lost all the profit in about a year.
The daily stock report is really helpful for avoiding risky stocks and Stockopedia itself a fantastic research tool.
My one big loss this year has been Eneraqua Technologies (LON:ETP) The main thing I have gleaned from that one is don't much notice of management interviews. Sage advice from the Naked Trader there.
One of the changes I’ve made is not blindly following anyone into a stock and relying solely on my own research, which Stockopedia and Paul strongly advocate for. But you still glean good ideas from others and Paul is great for that!
Totally agree and that’s why I read his views all the time.
The loss was from spread betting accounts in 2022. I understand his straight trades were more successful and his list published at the start of this year has done well.
I don't follow paul blindly, but have learned hugely from his commentary and approach, and value his honesty.
I also value comments from other contributors but would suggest we all try to be as civil as possible.
David
Simon Thomson's tips rise in price before they are published, which is suspicious. It also means that you can never buy at the price he recommended. Best to avoid.
You are making accusations not based on true facts-ST sends an email to the subscribers after the close or during the trading and immediately prices are marked up by MM or AI.
This is what’s happening.
Thanks
ST sends an email to the subscribers after the close or during the trading and immediately prices are marked up by MM or AI
This is my impression. If you are super quick you an catch the rise halfway up. Although it's better just to wait for things to settle down as you can usually pick stuff up cheaper a week or two later. Me, I ignore ST's tips. Most of them are poor quality businesses recycled over and over, eg MTI Wireless Edge (LON:MWE) Venture Life (LON:VLG) etc with just the odd beauty like hVIVO (LON:HVO) thrown in.
Actually BnB I think there are quite a few nuggets in STs work but no one gets everything right all of the time. All of us have had plenty of stinkers we’d prefer not to brag about - I know I have. The key, like all tip sheets, is to use them solely as idea generators - much like here, but often with a more in depth case study published to go through and analyse assumptions. There is an arb trade with ST though - usually if you catch the digital publication then you can get in before the price moves as IC readers pile in and then get out again a few days later, but this also tends to depend on size and liquidity of the stock he’s talking about so you have to apply sense to that approach as well.
The other thing is that the IC following generates liquidity so I have found that even if the price subsequently drifts on no/weaker news flow then an update from ST can generate the liquidity and price increase to get out if unconvinced.
Excellent David.
Thanks
ST is a total nonsense. He tips microcaps, takes a virtual position on his spreadsheet at offer price before his tip is public and then claims his performance is good after ramping the price by the liquidity push his tip creates.
His analysis is shallow and poorly informed...often he will regurgitate lines from the company PR process as if analysis - Venture Life (LON:VLG) tip a classic example (a company that has treated shareholders badly, provided dodgy accounting so as to furnish claims of some sort of brand growth early in covid and then raised equity at peak of hype cycle to then invest in at best mediocre way)
...ohh, and the execs also got to cash in a lot of their equity in the placing...which they've now reset with more for another run at pocketing profit from punters. No surprise this team has in past and I believe currently recruited the promotional services of Mr Paul Hill, a more frequent visitor to these pages as clearly he sees a monetisation opportunity in you guys
PIs would do well to ignore his nonsense and do their own work
And I say Crestchic (LON:LOAD^B23)
I can't say for sure but would imagine that Simon Thompson has to adhere to some obligation whereby his recommendations are held confidential until they are published.
Likewise, he will probably have to agree not to trade shares in a defined period up to publication.
Brokers used to have a similar restriction whereby you could not personally buy or sell without checking with Compliance if in house broker research was due to be published on the stock.
The problem is usually as yiannos 1 says. Market Makers also read tip sheets.
The bigger problem with tipsters and influencers is those who trade then publish. Small illiquid shares can be moved quite easily in the right market conditions with realtively small volumes.
This is what he should do. But because he does not say that he follows this, i can only assume that he dows not follow this procedure. Caveat emptor!
I understand that Investors chronicle bans writers from buying any equities
That would possibly explain why they appear a touch out of their comfort zone evaluating equities..Phil Oakley (not that one) apart
I met him once when he was working in a cocktail bar.
Ugh! SRT Marine Systems (LON:SRT) ...the gift that keeps on taking.
Here's a good write-up on Ocean Infinity/ Clake
https://blog.geogarage.com/202...
'Underwater' MDA ....coming to a business near you ?
GLA. I hold
The inflation data made interesting reading with falling costs for second hand cars and maintenance.
This is good news for insurers. Saga (LON:SAGA) jumped accordingly.
I wonder if this combined with the improved travel figures could finally be a turning point for Saga.
My morning smallcap tweet: Xmas cracker #1: What's green and swallows anything? Answer below.
SRT Marine Systems (LON:SRT) tinyBuild (LON:TBLD) Hargreaves Services (LON:HSP) Guild Esports (LON:GILD) Water Intelligence (LON:WATR) Novacyt SA (LON:NCYT) CAP XX (LON:CPX) LifeSafe Holdings (LON:LIFS) Concurrent Technologies (LON:CNC) Capital (LON:CAPD) Jaywing (LON:JWNG) Hipgnosis Songs Fund (LON:SONG)
◄SRT Marine Systems (SRT)► yet another placing and retail offer at 35p, a 16% discount, for working cap and growth. SHOW ME THE JAM! [SP=41.9 Cap=81m]. I hold.
◄tinyBuild (TBLD)► $14m (max) placing and OO at 5p, a 100% premium!. Cash need for claims settlement, dev and working cap. Guides FY23 rev $40-50m. [SP=2.6 Cap=5m]
◄Hargreaves Services (HSP)► guides H1-Nov trading mixed. Raw Material Services weak, land sales slow but Services ahead of mgmt exp. Hikes FY div target to 36p, up over 70%. Expects to divest pension scheme for £9m max, £7m less than guided. [SP=435 Cap=142m]. I hold.
◄Guild Esports (GILD)► partnership with eNDX, an esports player-focused virtual trading platform, to add players from the GILD's Counter-Strike rosters into eNDX's tradable pool. GILD to get commission. [SP=0.8 Cap=6m]
◄Water Intelligence (WATR)► $5m hike to credit facility, for acquisitions. [SP=415 Cap=72m]
◄Novacyt (NCYT)► disposal of its laboratory in Taiwan is delayed beyond end 2023 due to slow approvals process. [SP=64.12 Cap=52m]
◄CAP-XX (CPX)► guides H1-Dec rev up 35%. Order intake up 30%. In line? [SP=0.78 Cap=6m]
◄LifeSafe (LIFS)► £400k placing at 16p, a 22% discount, for working cap and additional resource for the new wholesale and industrial products. [SP=19.56 Cap=5m]
◄Concurrent Technologies (CNC)► wins £2.2m 5 yr contract from a European defence Prime Contractor. [SP=77.3 Cap=66m]
◄Capital (CAPD)► wins c.$140m 5 yr laboratory services contract. [SP=78 Cap=151m]
◄Jaywing (JWNG)► H1-Sep rev down 0.5%. Pretax -£1.4m (+£200k). U/L adj EBITDA is great though. Outlook confident but cautious given the backdrop of ongoing economic and geopolitical uncertainty. [SP=3.9 Cap=4m]
◄Hipgnosis Songs Fund (SONG)► H1-Sept NAV 142.49p/sh and 136.53p at 19 Dec. Investment adviser has refused to allow for correspondence on its heavily caveated valuation to be published. It initially refused to provide an opinion at all! [SP=70 Cap=841m]
A: An AIM IPO buyer.
Had the pleasure of speaking to David Hale, former proprietary trader and author of Cash Rules.
It's a crazy (and precautionary!) tale.
Many thanks Michael
When convenient, I don't suppose you might also be able to load the interview on to Spotify?
Xmas listening whilst walking in the rain.
I think that may be beyond my current technological capabilities Paul but I'll certainly have a try! Thanks for the feedback.
In the Lickey's? I've been know to take in Paul's excellent podcast while walking there myself!
Brilliant interview Michael and the book is brilliant as well written by David Hale
Ouch. Properly painful listening. Thanks for sharing and thanks to both of you for being so honest.
#TBLD
Games developer tinyBuild (LON:TBLD) plans to raise at least $10m at 5p/share - representing a 100% PREMIUM to yesterday's close of 2.5p.
Indeed rather than a normal placing, is this in fact similar to a takeover? It feels so given the astronomical premium?
In fact if CEO/founder Alex Nichiporchik (who has under written the placing) managed to increase his existing stake of 37.8% . Then theoretically I guess he & this other insider friends/shareholders could possibly delist the stock in 2024. And effectively take the company private at a knock down price!
tinyBuild (LON:TBLD)
It’s only an astronomical premium if you ignore the past shareprice performance - this share was above the raising price less than 30 days ago. I doubt any long term holders will be chuffed with dilution being generated at 5p a share when similar raising 6 months ago might have been achieved with 90% less dilution !!!!
tinyBuild (LON:TBLD) Shame the company came to the market at exactly the wrong time in the cycle and experienced the mangement issues to boot.I don't hold but glad to see the founder staying optimistic (well i'd like to imagine him like that!) still backing the business.However what else can he do i guess...
Frontier Developments (LON:FDEV) (i hold a small amount) caught a bit of a bid today too after the continued selling recently post last update, followed by the fairly substantial, chunky directors' buys.There has been some shorting shenanigans in there too i'm sure (apparently there was a £250,000 sell at the open when it was around £1.50 a share, just before the directors' purchases a few days later).Although the company's recent performance has hardly helped!