Small Cap Value Report (Thu 21 Mar 2024) - XPF, JDG, XLM, HSW. Quick: GTC, POLN, SBDS

Good morning from Paul & Graham.
Right to reply - XP Factory (LON:XPF) - we're always happy to talk to companies if they think we've got something wrong in the SCVRs. I had a call yesterday from a rather miffed CEO of this experiential leisure company. He said that the deficit on the lease entries on its balance sheet was due to netting off landlord contributions (creditors - for rent-free periods and reverse premiums) against the Right of Use Asset. That sounds plausible, so I've asked for more information, and will publish that here when it comes through. Just wanted to flag it straight away.
Here we are, XPF's CFO explains the lease entries - many thanks for this - it certainly puts a much better picture on the lease entries on XPF's balance sheet. So my apologies for jumping to an incorrect assumption about these entries in yesterday's report. I think we're all learning as we go along re IFRS 16, which almost everyone agrees is a terrible accounting standard, a big backward step!
Subject: Response to Paul Scott's comment
Whilst I will leave you to form you own opinions on the XP Factory performance, there is at least one factual inaccuracy in your comment which I believe is misleading. You state that the “balance sheet shows a large deficit on the lease entries, suggesting BOOM must have a significant number of loss-making sites”. The company has been the beneficiary of significant cash contributions from landlords on the majority of its Boom sites and on some Escape Hunt sites. Under IFRS 16, these landlord incentives are netted off against the Right of Use asset. Ordinarily, at the lease inception, the right of use asset would exactly set off the leasehold liability. However, when a landlord contribution is received, the Right of Use Asset is reduced by the contribution, meaning it will be smaller than the lease liability. Once the lease commences, the lease and the right of use asset will amortise down and slightly different rates, depending on the rental payment profile, which will lead to a further mismatch. However, the substantial majority of the difference in the case of XP Factory is due the cash benefit from landlord contributions – ie a benefit to the company. It has nothing to do with the performance of the individual sites, which within Boom generated an 18% EBITDA margin – 23% in H2 - after fully accounted rent charges as set out in the statement.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
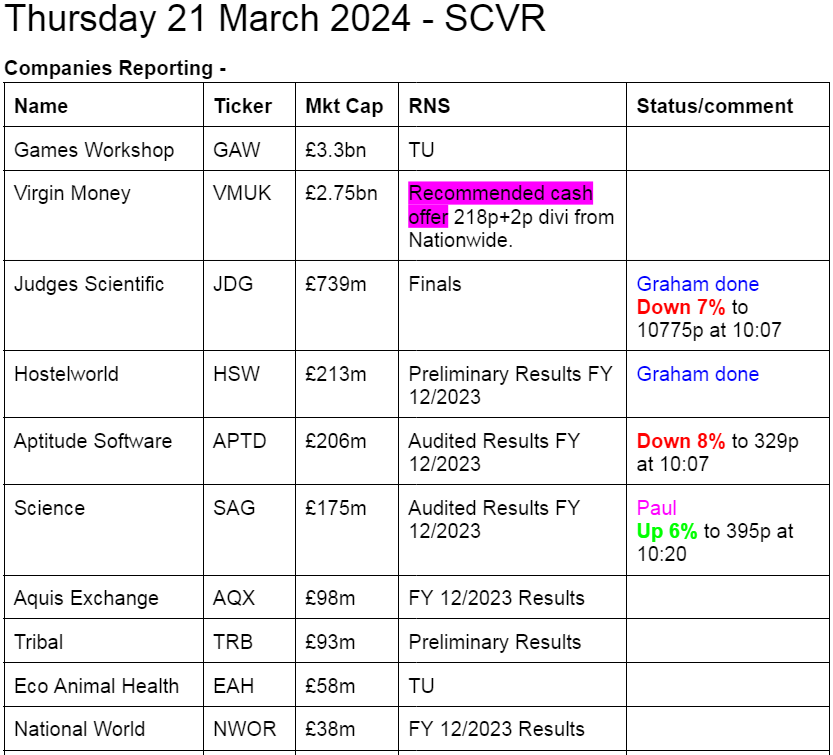
Other mid-morning movers (with news) -
Getech (LON:GTC) - up 15% to 9.5p (£6m) - Trading & Technology Update - Paul - AMBER
A serial disappointer over many years, losses almost every year. I don’t understand why it’s listed. Today it says 2024 has started well. ARR has risen to £2.9m. Reducing costs by £2m pa sounds sensible, as previously announced in Sept 2023 H1 results (heavy loss). I doubt investors would be interested in any more fundraises. It’s hoping to reach positive EBITDA and cashflow. Mentions property assets. Had £3m NTAV at June 2023. No mention of current cash position in today’s update. Looks like it might survive, but I doubt this company can scale up - it’s spent almost 20 years trying, and got nowhere.
Pollen Street (LON:POLN) - up 12% to 600p (£343m) - positive reaction to 2023 Results and increased future guidance from this “alternative asset manager” founded in 2013 and floated recently in Jan 2024. We haven’t looked at it properly in the SCVR yet. Says its AuM will exceed £4bn in 2024, and aspiration is to grow to £10bn within 4-5 years. Raising cash for private equity funds. Announces £30m share buyback today. Sounds quite interesting.
Silver Bullet Data Services (LON:SBDS) - up 8% to 160p £28m) - Contract wins & renewals worth £1.7m with Greene King and Heineken. It’s not clear if these were already in the forecasts or not. No recent broker notes available. Interesting-sounding company with impressive client list, in a fashionable investing area - mentions AI 4 times in today’s announcement. Shares have c.6-bagged since summer 2023, impressive! I did a quick review here on 27/2/2024. I suspect it’s going to need another fundraise, but maybe from a position of strength?
Summaries of main sections
Judges Scientific (LON:JDG) - down 6% to £108.9p (£721m) - Final Results - Graham - AMBER
Judges says it is “comfortable” with market expectations, and brokers have nudged up estimates for 2024. However, order intake is marginally behind 2023. More fundamentally, I’m concerned about the deterioration of quality metrics and a sky-high valuation.
XLMedia (LON:XLM) - up 62% to 10.1p (£26m) - Sale of assets for up to $42.5m - Paul - AMBER
A large disposal has put a rocket under XLM shares today. This transforms its stretched balance sheet into a cash positive situation with an intention of making a shareholder return with some of the cash. Not a very good business though, and XLM shares are still down 95% from the peak. Still at least long-suffering shareholders have something to celebrate today.
Hostelworld (LON:HSW) - down 2% to 167.5p (£207m) - Preliminary Results - Graham - AMBER
Excellent results from Hostelworld, as expected. The company can hopefully look forward to a future with low debt levels and sustainably positive net income and cash flow. I compare valuations with the owner of Booking.com and decide that a neutral stance is justified.
Paul's Section:
XLMedia (LON:XLM)
Up 62% to 10.1p (£26m) - Sale of assets for up to $42.5m - Paul - AMBER
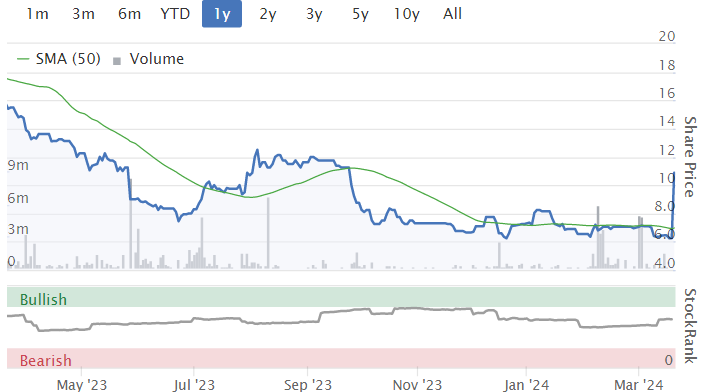
The share price of this digital media company have gone bananas after a large cash disposal was announced at about 10:50 today. “Binding agreement” to sell some of its gambling-related marketing sites to Gambling.com Group Ltd. $35.0m cash net of costs (£27.5m) - $20m 1/4/2024, $10m in six months, and $7.5m in one year. Instalments do make me a bit nervous. Plus a potential $5.0m earnout. Gosh the £29.4m initial payments are more than the market cap, after I adjusted it up for the +62% share price. Could there be further upside I wonder? Looks possible. It mentions “transition costs”, but doesn’t quantify that.
Use of the cash -
The Group intends to use the proceeds of the Transaction to cover asset transition costs, pay the final deferred US acquisition payment [$4m] and settle outstanding tax provisions [Cavendish est. $5m] and provide working capital to support the North America business while returning cash to shareholders.
Cavendish reckons the remaining group will produce c.$5m EBITDA annually. We haven’t yet got forecasts for the remaining group, but adj PBT was previously forecast to be less than half EBITDA, so it doesn’t look like there will be much genuine profit in the continuing business. After the various costs above it looks like there should be about £20m cash left over, so my guess would be that they might return say half of that to shareholders, which would work out at about 3.8p per share. Not madly exciting.
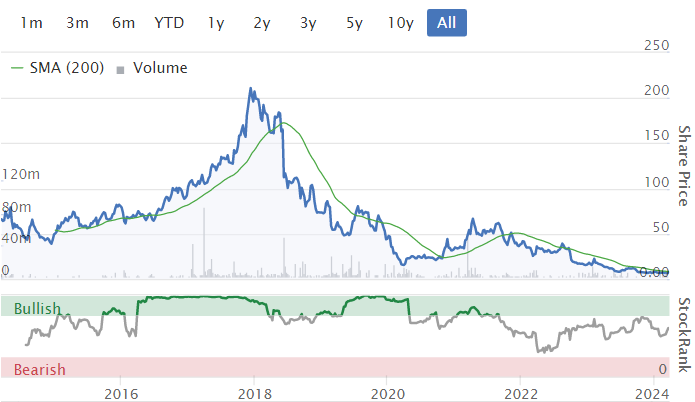
Paul’s quick view - when I last looked at XLM on 29/9/2023, I flagged up its weak balance sheet, so colour coded it amber/red. Also the shares have been a dismal performer since the late 2017 peak, down 95% since then. Profits largely evaporated, and divis stopped in 2019. There’s rarely any sustainability to companies like this in digital advertising, they make a few years of bumper profits by exploiting some online advertising algorithms that are then changed by Google or whatever, and profits collapse - that’s happened to many similar companies.
Today’s news is game-changing for the balance sheet, so I don’t need to keep a risk warning on this share any more. Also the deal done gives a useful benchmark that might mean its remaining business could be better than I thought, and worth more maybe? So I’m happy to go up to AMBER.
Incidentally, I was expecting to see big Director selling, but it's the opposite, all buys since 2019.
A nice move today -
Zoom out though, and it doesn't even register on the scale! -
Graham’s Section:
Judges Scientific (LON:JDG)
Share price: £108.90 (-6%)
Market cap: £721m
Judges Scientific (AIM:JDG), a group focused on acquiring and developing companies in the scientific instrument sector, announces its final results for the year ended 31 December 2023.
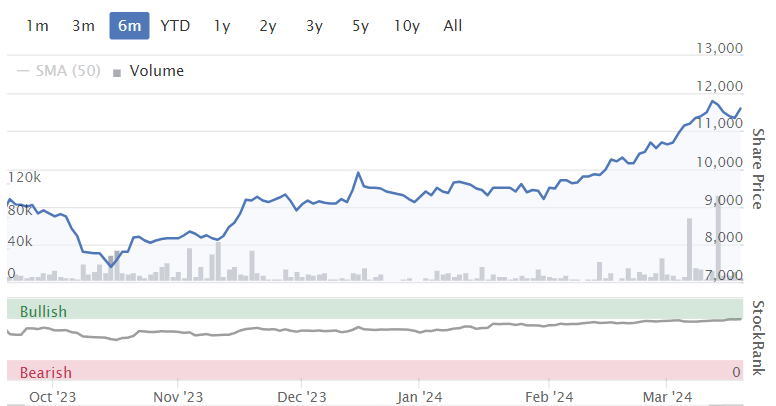
This share enjoyed tremendous momentum over the past six months:
These are fine results published today, at least in terms of the adjusted numbers, and seem to be ahead of expectations (e.g. vs. the StockReport and also ahead of the prevailing estimates from WH Ireland).
Revenue +20% to £136m (organic revenue +15%). Estimate was £130m.
Adjusted PBT +12% to £31.7m. Estimate was £30.5m.
Net debt reduces from £52m to £45m.
Full-year dividend is 95p, up 17%.
The unadjusted figures are where the results fall down:
Actual PBT is down 16% to £13.4m.
Actual earnings per share is down 26% to 145.8p.
The company has added a new line to its financial highlights this year, “Tax on Adjusted Earnings” (which is up +41%), so this is clearly something that it’s anxious to point out to investors. I don’t think the new corporate tax rate is sufficient to account for all of the increase in the tax charge, but it could account for most of it.
Outlook
The Board is “comfortable with current market expectations”:
Commencing 2024 with a solid Organic order book.
Timing of next Geotek Coring expedition and its revenue recognition in 2024 remains uncertain.
Supply chain now returned to normal.
YTD Organic orders marginally behind 2023 comparative period, which included exceptionally large post-lockdown contribution from China.
Estimates
WH Ireland have slightly nudged up their estimates for 2024, and are now looking for adj. PBT of £33.8 (previously £33.5m).
CEO comment from David Cicurel explains the headwinds facing EPS:
A full year of Geotek and two small acquisitions in the spring contributed to the Group's performance. As previously noted, this and the Organic achievements were largely absorbed by higher tax rates, increased borrowing costs and some dilution from the issue of new shares in respect of half of the Geotek earn-out.
During 2023, Judges had to pay £35m in an earn-out for Geotek, half in cash and half in shares.
Mr Cicurel also has a view on the outlook:
For the immediate future, the new year has started with a healthy order book; order intake for the first eleven weeks of the year has been marginally below the 2023 comparative which included an exceptionally large post-lockdown contribution from China. At this point, we are still envisaging another coring expedition during the course of 2024, however, Geotek has not yet contracted for this expedition and there is uncertainty regarding its timing and the amount of any related revenue to be recognised in 2024.
Graham’s view
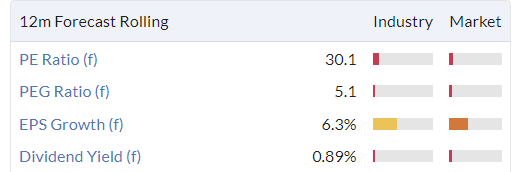
I tend to view Judges as an A* star company but with a valuation that usually matches it. Whenever I have thought that the Judges share price has offered value in the past, I’ve said so, but usually it doesn’t seem to offer much value.
That remains the case today:
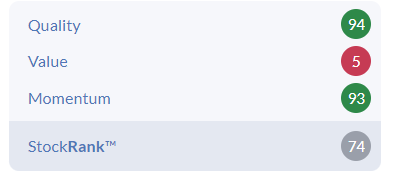
The StockRanks tell the story, categorising it as a High Flyer:
However, I’m a little concerned that the underlying quality of Judges might have dipped slightly in recent years.
The £80m acquisition of Geotek saw the company paying a high price for a company with volatile revenue recognition / lumpy orders and that was likely going to drag Judges’ quality metrics lower. It also agreed to dilute shareholders as part of the deal (not a typical part of the Judges strategy).
Judges calculates its own “Return on Total Invested Capital” (ROTIC) every year. Due to the negative impact of the Geotek acquisition, it estimates its ROTIC at 22.7% for 2023 and 20.6% for 2022. These aren’t bad numbers but they aren’t the sparkling figures that Judges shareholders might be used to or expect.
I also have to be fair when it comes to adjusting items: for most companies, I take a dim view when there is a large gap between adjusted and actual measures of profitability.
Judges has reported £18m (pre-tax) of adjusting items for 2023, up from £12m for 2022. Most of this is amortisation of intangibles. Another large item relates to the increased market value of the Judges shares being paid out for the Geotek earn-out. These are acceptable items to adjust, but it’s something to be aware of.
The Judges balance sheet shows net assets of £83m, but after deducting intangibles and goodwill this number goes to zero.
I’ve always been price-sensitive when it comes to this share: there are times when I think it offers excellent value (rare) and there are times when I think it offers poor value (much more common). At its current valuation, I’m afraid I see poor value on offer here.
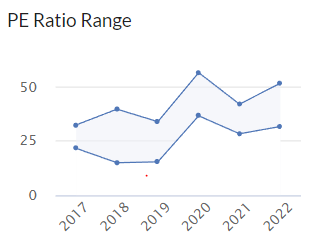
I still wouldn’t give it the thumbs down - it’s dangerous to do that to a company which has a long-term record of compounding value. But for a business with much more average quality metrics than it has ever had before, and which is likely going to have increased difficulty finding acquisitions that can move the needle in future, the current valuation makes little sense to me.
Hostelworld (LON:HSW)
Share price: 167.5p (-2%)
Market cap: £207m / €242m
Hostelworld, a leading global OTA focused on the hostel market, is pleased to announce its preliminary results for the year ended 31 December 2023.
We covered the full-year trading update for this company in January.
As we reported then, post-Covid momentum at this travel company has been tremendous and has taken its metrics to record highs:
6.5m bookings, up 37%.
GMV (gross value of bookings) €619m, up 32%.
Net revenue €93m, up 34%.
Marketing as a percentage of revenue falls from 58% to 50% (an important measure of profitability since marketing is the key expense).
Other operating expenses, excluding exceptional items, as a percentage of revenue fall from 35% to 27%.
So we get the following impressive progress in terms of profitability:
Adjusted EBITDA €18m (2022: €1.3m)
Net income €5m (2022: loss of €17m)
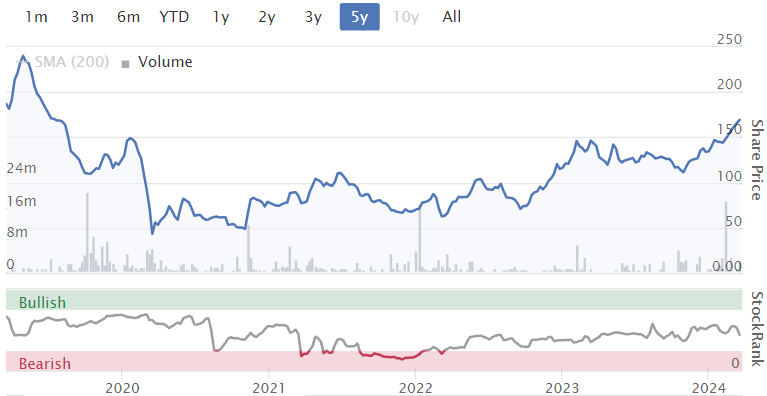
The financial recovery has been reflected in the long-term evolution of the share price. Remember that this was a healthy, profitable company pre-Covid.
Net debt: this company was struggling under the weight of excessive debt a few years ago, but that is no longer the case. In 2023, net debt fell from €22m to €12m. And since the beginning of 2024, an outstanding RCF has been fully repaid.
The remaining term loan only charges interest at 2.65% over EURIBOR (the margin has reduced as the company has deleveraged).
There is also c. €10m owed in back taxes which will be paid over the next three years.
CEO comment:
"I am very pleased to report another strong year of strategic progress for Hostelworld, which is reflected in our results. Over 2023 we grew market share, delivered record revenues, and increased operating leverage through a combination of reduced marketing spend (as a percentage of revenue) and continued operating cost discipline to deliver €18.4m EBITDA, which exceeded our guidance range of €17.5m - €18.0m.
Outlook
"With our record performance in 2023 and substantial progress in strengthening our balance sheet, I believe we are strongly positioned to deliver against our medium-term financial commitments published at our Capital Markets Day in November 2022. We have started 2024 with strong momentum, and I feel confident that we will continue our track record of profitable growth and value creation for our shareholders."
Social network?
The interesting strategy to create a social network for hostel travellers continues: the company offers city-based and hostel-based chat rooms, theme-based chat rooms, and local event catalogues, making it easier for people to meet each other on their travels. The Hostelworld social network now has over 1 million members.
While I don’t see this product threatening Facebook any time soon, I do think it’s an innovative idea that could differentiate Hostelworld from its rivals in the online hostel booking space.
Graham’s view
I remain deeply impressed by the financial recovery at Hostelworld, and intrigued by what their social network strategy might achieve in the long-term.
Would I buy these shares at the current level? The market cap is equivalent to 13x adjusted EBITDA, which to me is a little hot. Adding on net debt would bring the adjusted EBITDA multiple closer to 14x.
We do have a stock we can easily compare it with: Booking Holdings, the owner of booking.com and other similar websites. Booking.com is not limited only to hostels but let’s compare some metrics anyway:
Price to sales. Booking Holdings 5.7x, Hostelworld 2.8x
Price to 2023 EBITDA. Booking Holdings 17x, Hostelworld 13x.
On that basis, maybe Hostelworld is not so expensive? But it’s a much smaller company and less diversified than Booking Holdings, so Hostelworld probably should trade at a discount.
On balance, I’m going to take a neutral stance on Hostelworld.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

124 comments
Paul you gave Amber in a quick comment on Getech in March, and questioned why it's listed, it's almost embarrassing to ask Stockopedia subscribers but as long term sufferers, does it make any sense to add 10,000 or 20,000 shares to an already big number in today's retail offer? We are going green steadily but we still have a few dogs yelping at the bottom of our portfolio to feed or shoot.
The consensus forecast shown on here for Hostelworld (LON:HSW) is so far behind the curve that the EPS forecast for 2024 was actually achieved in 2023! (Figures are in euro cents: forecast for 2023 = 5.4 cents, actual adjusted figure for 2023 = 9.9 cents, forecast for 2024 = 9.9 cents.) What a shambles! I always expect forecasts to be inaccurate, but this takes things to a whole new level!
Thanks for the XLMedia comments Paul, we had some profits along the way but I stupidly held on to too many shares thinking the American strategy might pay off well. Today's announcement, and Getech's lessens the self-inflicted pain slightly. If any of your Stockopedia subscribers find investing easy, I'm afraid I'm not your best pupil. In my defence and thanks to you and Graham, our top 5 holdings by value are all Green.
Quick heads up on Avon Protection (LON:AVON) which appears to be breaking out of a base (along with many others). I’ve taken out a position. Could be a fake out but theoretical target is +40%.
Im afraid I just don't get Avon Protection (LON:AVON) at this price - fwd PER of 27 seems way too high for a fallen star. I'm a buyer at 800p but not here. That doesn't mean it can't grow into its share price but a lot of the turnaround appears baked into the price so if it doesn't meet or exceed forecasts I expect it can fall quite a lot.... But then what do I know, I thought Rolls-Royce Holdings (LON:RR.) was expensive at 330p - to be fair I think its even more expensive here and I haven't a clue why brokers are raising forecasts to well over 500p. Its already on a PER of 27 and that would make it closer to 40* - who pays that for an engineering business?? Feels like once the hot money is done it has a big drop to consolidate, I don't ever remember this business on that rich a multiple, but you never know. Maybe Avon Protection (LON:AVON) also has a few too many buyer commentators and will suffer a similar fate.
I can buy MS International (LON:MSI) on circa 10* PER also in defence with foundry and petrol station fit outs thrown in. Both of those should be doing well in this environment. One is 4* the comparative valuation.........not for me. Or MPAC (LON:MPAC) on 11* another high quality engineering business.
On Avon Protection (LON:AVON) I have very little knowledge of the business and I’m breaking a few of my rules, hence an entry position. But! So many times I find the charts “tea leaves” know more than all the analysts in the world, and this chart says there is good news on the way….
Or the market is just looking for places to invest and likes Avon Protection (LON:AVON)
National World (LON:NWOR) Figures seem good to me. Don't know what was expected. Generated cash of £8m last year. £10m 0f cash p/e about 5. No pension. Further opportunities. Local news surely can't be left to the BBC ? There must be a future for an independent local news source !
Montgomery has an interesting past and has made some mistakes, but he knows about newspapers especially local papers.
Looks like Montgomery is preparing a bid for the Daily Telegraph, a paper whose online version is rapidly heading downwards in quality towards Montgomery's current offerings: so might be a good fit. It is shame to see what he has done to the Scotsman and Yorkshire Post online and his "interesting past" keeps me well away. The other thing I intensely dislike is the deluge of poorly directed advertising that hits you when you alight on any of National World's many regional websites.
National World (LON:NWOR) looks very cheap Deegee - problem is that Montgomerie seems to run it mainly for his wealth rather than other shareholders - lots of nil paid options to dilute other shareholders for what has been a terrible share price performance that has halved.......... not sure his interests are aligned in any shape or form with private investors really. Lots of greed but little in the way of share price performance.......shame really, handled better it could be a great play but the greed levels put a lot of people off.
Eagle Eye Solutions (LON:EYE) Paul gave a good write-up on Tuesday (19th) SCVR on the day of H124 results when he spoke to management. Here is the analyst presentation from that morning video & podcast. They are on a medium term(?) target to reach the £100m revenue at 25% EBITDA margin, as laid out at the capital markets day a few weeks ago (no time frame was given.) They subscribe to the rule of 40, so a powerful compounder.
Revenue +20%. 78% recurring revenue. Organic growth c 10%. Untied Nots (acquired Jan22) contributing £2.1m. ARR +26%. The sales pipeline is 2.5x v this time last year. Gross Profit +23%, PTPa +49% EBITDA margin (adj) 24.4%.
The cash outflow £1.3m to £9m reflects the seasonality, they expect cash inflow during H2.
I suspect EagleAI is where the real future growth will come from, which is testimony to the happy integration of Untied Nots.
Topped up my Eurocell (LON:ECEL) holding yesterday on SP weakness. Price and volume seem to be gaining momentum today.
I think I'm in good company as Eurocell was selected by Paul as one of his Paul's Top 20 Value/GARP Share Ideas for 2024.
"Softer trading in 2023 (profit warning 5/9/2023) saw profits fall, but should benefit from a return to more normal conditions in due course. Hence I see a potential 50-100% upside on this share, once its markets normalise. In the meantime the strong balance sheet means it can afford to pay generous divis, with the yield c.6.3%.
No sign of a trading recovery yet, so we might need to be patient."
ECO Animal Health (LON:EAH) - I used to hold this, but lost faith. For me it's too jam tomorrow with most of the profits disappearing in China through the minority interest or in R&D. No prospect of any dividend for a few years. Good pipeline of development projects, but too far off getting a real return for my liking. It was much better when Peter Lawrence was the chair. He was obviously the smart one as he sold big chunks at multiples of todays price. Good luck anyway.
Graham. I liked your comparison of Hostelworld with Booking.com, which I’ve held for 5 years. The key metric with Booking is cashflow, which it throws off in huge lumps, typically buying back virtually 10% of the market cap almost every year. Now that's a shareholder return! And it’s good to see both valued on about 6% FCF yield. I would point out however that the travel giant’s operating and FCF margins are vastly superior, fully justifying a significant premium before we even consider the greater resilience that its scale, market dominance and track record demand.
3i (LON:III) flying again today on the Action update. Action is a seriously impressive discount retailer. I wonder whether they will eventually take on the UK? 3i is becoming a one company investment trust. Good discipline on running your winners as not many PE house's do that. Its a 12 bagger before dividends for me.
I bought for 134 in 2009 so I'm with you on this one!!
Just wanted to put in a shout out for ME Group. I have been down in Somerset this week and driving through Cheddar I saw a pretty grubby petrol station with a clothes washing unit on the side. It offered an 8kg and 18kg wash and 18kg dry option. I really needed to clean some stuff so I did, cost approx £10 for wash and dry. I noted it was busy every time I drove by afterwards. I only mention it because I have liked the company for ages but never really seen anything they do. Now I understand why as it kind of blends in with the background and is quite small scale I guess. But excellent service I felt.
Good to hear Camtab - If I recall each laundry machine grosses over £15k per annum so bodes well as they expand their estate. Long and strong.
Saw one at the services on the M6, was being used by truckers to clean their gear. Quite handy for them I can imagine
Interesting/useful crib sheet for valuing stocks (see below).
For me though, DCF projections combined with a scenario analysis, peer-group multiples & FCF yields are usually the best.
That said for startups, the accuracy of building detailed cash flow models is pretty non-existent given the likely broad-brush assumptions.
Note: SAM = serviceable addressable market.
That is really quite nice Paul ... Thx for sharing.
#xlm as expected this beast undervalued.$35m for non core slower moving part of business (c35m). That puts the other 65% of the business, US, the high growth arm valuation north of $50m. This sale underpins confidence in the US valuation and implies at least 2x upside imo. NFA DYOR
Science (LON:SAG) audited results for FY23 (I hold)
Good to see discussion of SAG on here. I’m still working through the results – but here are a few initial thoughts.
Statutory results down 47% to £5.5m (£10.5m) primarily due to the amortisation of acquired goodwill with the 70% of TP Group in January 2023, and the remeasurement of the equity value of the 30% they already owned.
Acquisition of TP Group
TP Group had been under-performing for years, primarily due to too much debt, too many loss-making development ventures and an expensive board. Under Science Group management, prior to the acquisition, loss-making subsidiaries were sold off before the two remaining divisions, Aerospace and Defence consulting services and Submarine Atmosphere Management Systems (CSM2) were acquired by SAG.TPG contributed £66m of revenue and £6.2m of adjusted operating profits in the 11months since acquisition.
The turnaround in Submarine Atmosphere Management, following renegotiation of long-term contracts, investment by SAG and secondment of SAG management is impressive – albeit the 2023 figures may be flattered by the blend of products versus services and support – the long term future for growth in revenue and profitability looks good.
Profitability at TPGS with £45m of revenue and £2.6m adj op profit (note 15 Business Combinations) is well below SAG’s own margins, the prospects for this business look very good in terms of future revenue and profitability growth.
At least in terms of revenue SAG is now over 50% aerospace and defence related, which is a remarkable change and looks to be a well timed, if lucky, move given the growing global prospects for defence spending? There is also the potential that SAG’s existing US consulting business acts as a catalyst for generating US arospace and defence revenue and profits in combination with TPGS and CSM2
Frontier Technologies
The loss making audio semi-conductor and module designer and maker acquired in 2019. Turned around by SAG and became highly profitable. Though the 2022 very high profits were – in hindsight – the product of global chip shortages and short-term price rises. Followed in 2023 by global destocking. Frontier is highly operationally leveraged. When audio chip and module returns – and of course nobody knows when that will be – then Frontier will benefit from the operational leverage. In the meantime product development at Frontier has been fully funded by SAG.
Science Group - R&D IP led strategy - Sagentia
Some may remember that Science Group used to be known as Sagentia, and primarily invested in R&D, Technology consultancy and generating IP. Sagentia Innovation still operates from SAG headquarters, Harston Mill, near Cambridge. Frontier Technologies is also now co-located at Harston Mill. The generation of IP which can be profitably exploited remains core to Science Group long term identity? In that sense, neither Frontier, nor CSM2 are a change to Science Group long term strategy, both are niche-market leaders based upon their own IP and IP development.
Following the near-death experience of Sagentia, Martyn Radcliffe (current executive chairman) invested to become ?40%? shareholder and turned the company around. Once profitable the company has acquired a series of science based, R&D and technology consulting businesses. Martyn Radcliffe remains the largest shareholder with over 20%. In that sense the current strategy and direction of Science Group remains that of Martyn Radcliffe as ‘founder’ management. It won’t be to everyone’s taste, but the long-term record for shareholders is very good and I see no reason for that to stop – indeed with the TPG acquisition and aerospace and defence business I see good reasons for it to accelerate.
Properties
The properties of Harston Mill(Cambridge) and Great Burgh (Leatherhead) until recently were held within operating companies – when they were moved into a separate property subsidiary. A sale and lease-back for short term gain is not really in the style of management? Worth noting that the companies existing long-term is at a very low rate and secured against the properties. In that sense the company is already taking advantage of its property assets and will be earning a higher rate of interest on its current cash balances than on its property related long-term debt?
Shareholder Based Payments (SBP)
Before somebody points it out - I'd like to comment on the SBP of £2m on profits of £5.5m. Excessive? I can see it might seem like that. Not so excessive against the adj operating profits of £20.5m but still £2m that should flow to shareholders - if that's the way you see it? When evaluating incentives, I tend to think of Charlie Mungers words ' Never, ever think of something else when you should be thinking of the power of incentives'. As an ex-rocket scientist I used to look at a spacecraft as a heap of technology. Until I realised it took a great team to turn the heap of technology into a positive outcome and outperformance? I view SBP's as a pre-payment by shareholders against future outperformance. Unfortunately it's often wasted by greedy self-obsessed directors. Undoubtedly SAG is a people business and it remains to be seen whether the directors are placing the incentives where they will work best. Martyn Radcliffe's position as executive chairman and largest shareholder gives me some confidence that is the case - but it's always a tricky business trusting the management?
Chairman Statement on Valuation
It’s not Martyn Radcliffe’s style to complain. I take it more as a warning. Historically Science Group has raised capital in placing to make acquisitions. It did the same with TPG – even though it busy buying back the shares now (that’s the benefit of long term ‘founder’ mentality aligning with shareholders?). I see that the chairman is simply observing that the current low valuation of Science Group materially constrains it’s ability to raise funds for acquisitions. Not in the UK, where valuations are also low – but what about the US? It would make sense for Science Group to make more US acquisitions in the longer term. If UK valuations don’t improve in the meantime then a US valuation for Science Group would fix that problem? Not the only company thinking that way?
Outlook
Consensus forecasts for FY24 this morning are £112m revenue and 32.2p adj eps. Today’s FY23 of £113m revenue and 33p adj eps are higher than that. Before accounting for the full year (12/11 months) of TPG figures. Forecasts will need to rise. I’ve not yet revised my calculations. But with a finger in the air I’d expect around 5% or more rise in revenues, more like 10% in (adj) profits – and that’s before accounting for any turnaround at Frontier, which would turbo-charge the uplift.
The 60% rise in dividend is appreciated. And helps to underscore the healthy cash position and good outlook for the company.
Martyn Radcliffe doesn’t tend to hang around. I expect further progress this year.
Cheers
Mark ( Science (LON:SAG) is my fifth largest holding at 6% of my 12 company UK small and micro-cap portfolio – after MS International (LON:MSI) Macfarlane (LON:MACF) Vianet (LON:VNET) Celebrus Technologies (LON:CLBS) )
Super analysis Mark. Lots of interesting background too. I used to own TPG and was happy to see SAG pick up the pieces and chuck out the self serving management. Maybe SAG needs a US listing to be properly appreciated.
Just a quick update and thanks to those that bought my novel, Pigs Get Slaughtered, over the last couple of days. Another 11 sales, so we're up at around £50 raised for Zane's highly deserving charity. Every little helps, but I can't help thinking we're just scratching the surface here. All the royalties for this month are going to the charity, so for every e-book that's sold at £4-99, it raises about £2 for the charity.
Paul and Graham's epic daily coverage attracts thousands of reads every day and this crime novel about a private investor is custom made for the readership here. I encourage everyone to take a look, and for a very modest price of £4-99 you'll get a great read and be making a contribution to a charity that Paul knows well and can be trusted to make the most of every penny raised. Thanks for your help.
Book:
https://mybook.to/PigsGetSlaughtered
Audiobook:
https://play.google.com/store/...?
https://www.audiobooks.com/aud...
https://www.barnesandnoble.com...
Paperback copy ordered easily from Amazon.
ZANE is a superb small charity. Well run on a tightly controlled budget and doing an amazing job.
Thanks for your support Cricketfan. I hope you enjoy the book and please leave a review.
Got the kindle version yesterday but have another book to finish before I read it. I'll leave a review once I've read it.
Just bought it :)
I bought the book on Amazon. I’m about half way through at the moment and have to say that I’m really enjoying it. I think this is your first published novel so I have to say Well Done!
Gudge, Thanks for your feedback and I'm glad you're enjoying the book. Please leave a review on Amazon when you finish it.
Morning Paul
I seem to recollect that you were intending to do an interview with the CEO of the Property Franchise (LON:TPFG) . Were you able to do so? If so can you direct me to the link please.
Best wishes
Jonno Paul made a comment in his last but one podcast which I assume you listen to every week ?
Hi Caper
Yes, I listen to Paul's weekly podcast, but obviously missed the reference to the Property Franchise (LON:TPFG) . Will follow it up.
All the best
Thanks Caper4/jonno. Thought I'd have a listen too... I've just found it at pretty much exactly 5 mins in. If I've worked this link correctly, it should go straight to that point. Yes, it was worth listening to. Must pay more attention!
(I held BLV and now hold Property Franchise (LON:TPFG) after the merger.)
Responding to sheeza on Serica Energy (LON:SQZ) which I hold it is worth mentioning that the Company will benefit from 2 acquisitions in 2023 namely Tailwind and a 30% stake in Jersey Oil and Gas (LON:JOG) . In the first case they benefitted from tax losses acquired and in the second case any costs in Developing the asset will be eligible for 91% tax relief.
Taxing SQZ at 75% on North Sea Assets shows that Politicians and Civil Servants who advise them have very little understanding of reality. Surely profits generated in our own jurisdiction should be treated differently to profits generated in other countries.
As to maintaining the Dividend I think the tax calculations are too complex to be able to make a clear judgement as a Shareholder.
I can't find it but in a company report it was said that "we don't like paying tax" and that says enough for myself, I hold Serica Energy (LON:SQZ) happily.
Thank you for your comment on Getech Paul, you are right, we've been holding for those 20 years and apart from the odd rally it's another one in our dog basket. We've stopped feeding it but it's not getting kicked out yet. You might notice my earlier post about XLMedia and want to put your Doc Martens back on with that one too, I can take it.
I've been tracking Getech (LON:GTC) for a few years, also held for a while (luckily, sold out in the early 2021 share price surge).
For me, they have a solid product, for oil and gas exploration. However, it is such a niche market, they should have sold out to a bigger O&G supplier/vendor.
They then decided to make a go into the hydrogen storage market. I've not been tracking closely, but does this look to be a dud now?
I have no doubt that they can keep plodding along, in their main business line. But whether it can scale up to be sustainable profitable, and with a public listing, is debatable.
There are some clever investors on here and I would really appreciate any quick comments on XLMedia's announcement about having agreed a deal to sell their European and Canadian assets for $42.5 million. I think one of our dogs just barked loudly?
XLMedia (LON:XLM)
Potentially yes - i think they have probably pulled a rabbit out of the hat here. However they are selling stuff with decently positive EBITDA - so does that then potentially leave them with IP generating little to no profit or perhaps loss making. So first question is what would they expect 12 month net profit would be after disposal of the EU stuff.
second question would be how much excess cash would be left with at that date - could this perhaps match the marekt cap or be in excess of market cap.
If they have cash matching marfet cap and us facing business paid for in full making money then this could potentially be a nice deep value play.
info per release today says tehn folowing which does sound like decent wad of the proceeds may be gone ?
"The Board believes the sale of these assets, which is approximately two times the current market capitalisation of the whole company, is an excellent outcome for XLMedia and its shareholders. Importantly, this transaction will allow the Company to clear legacy liabilities, provide working capital andreturn cash to shareholders."
To be fair to this company although things have clearly not worked out it does seem like they have been trying to deliver over the years - some hopefully some reward for long suffering shareholders here.
Cavendish
Significant Asset Disposal for $42.5m Total Consideration
XLMedia (LON:XLM) has announced the sale of its Europe and Canada sports and gaming assets to Gambling.com Group for a total consideration of $42.5m ($37.5m fixed, $5m earnout). The sale is in-line with its recently stated strategy to maximise value for shareholders including the disposal of assets where opportunities arise. The proceeds will be used to settle outstanding tax and acquisition liabilities, invest in the US business and return significant sums to shareholders. Applying peer multiples to the remaining business and adding the cash from the disposal gives a market cap estimate of £48m, representing c.200% upside.
Fair play to management at XP Factory (LON:XPF) getting in contact to clarify the financial statement. It's been such a disappointment to me, still feels like they are plastering over cracks all the time, I am king of getting sucked into a story and don't know if it's that, or I'm just losing patience at the crucial moment when the share price will finally find a bottom.
I first bought Escape hunt at 30p November 2021, apparently they have done nothing but deliver but I'm still down over 50%. Bad timing I guess, but I don't want to wait another 2 years for a turn around when there are so many other opportunities out there at the moment
Hi NewInvestor1972. I would recommend reading One Up on Wall Street by the acclaimed investor Peter Lynch. It's been a while since I read it so my memory is hazy but he discusses the idea of using our real life experience to spot investment opportunities. I recall about 15 years ago just noticing the incredible proliferation of MacBooks and iPhones everywhere I went but sadly I didn't translate that into a timely investment in Apple (NSQ:AAPL) .
The converse can be true too and what I have witnessed over the last several years is an absolute proliferation of "experiential leisure" on the High Street, presumably taking advantage of favourable leases as retail businesses fall by the wayside. It feels like a decade ago when the casual dining sector flourished like a rash, outbidding rivals for increasingly contested patches of real estate and then fell away under the weight of overcapacity and under utilisation. Experiential leisure feels like it might be repeating this trajectory.
I've seen darts and pool bars come and go and whenever I walk past these multitudes of experiential places, they are rarely busy, apart from central London perhaps. I just cannot see that there are nearly enough stag and hen parties, team building outings etc. to support these levels of axe throwing, and escape rooming.
Hardly any of this existed twenty years ago and the country is in far more straightened times so XP Factory (LON:XPF) and their ilk just don't pass the common sense test for me.
Personally I want to invest in businesses that will likely still be around in a decade or longer and I would be astonished if these businesses are. To me, it looks and smells like a transitional fad but of course that is only my perception and I could easily be proven wrong.
Good luck whatever you decide but IMHO, your funds would be far better deployed in a different and more sustainable sector.
If I remember rightly, Jim Slater too was a big advocate of investing in sectors that you are interested in. Can’t remember which of his books however.
Serica Energy (LON:SQZ) is due to report earnings next month. I am unclear whether the Government's 'excess' profit tax on North Sea oil will allow SQZ to maintain its dividend. Can somebody tell me, please?
Ho. Hum. Perhaps nobody knows (or everybody but me). Price may move sharply either way on the day? Directors have bought over £450k shares this year.
Serica Energy (LON:SQZ) Well, the CEO wouldn't be drawn on that subject when he did an InvestorMeets presentation and added he wasn't allowed to. All we can do is weigh the evidence of director buys and broker forecasts from Stocko which probably indicates no reduction imho.
Thanks, Sams
Sheeza for what it's worth I'm a holder of Serica Energy since 2014 (or was). I think the revenue they will report will be fairly accurate as they're transparent about how much revenue they are "extracting". The dividend is very generous and based on the historical high oil price so will probably continue but not to such a large % i think (my subjective view it's worth mentioning) . For me the elephant in the room is how the next government will manage NS fields and energy policy. The recent sell off down to 168 suggests sentiment is not good. i tried to find some figures on Tax allowances but couldn't find a specific figure. The bulls look at future workover and new fields, and might say shortage of industry investment will become apparent. The bears might say , oil is dropping/stabilising short term, politics look risky, where has the cash pile gone, the previous king maker is stepping down. I've sold out and now am suffering serious FOMO as it has been a great "oily" and pays a formidable dividend with a good stock rank. my decision was based on public's attitude to fossil fuels, plus most likely a labour government who haven't declared their hand yet. However, I strongly believe energy will always be a volatile topic in UK and hence price will follow. Serica Energy (LON:SQZ) now have a more even mix of Gas and oil with the latest tailwind acquisition and drills to add revenue in the nxt 18 mnths. I'll keep an eye on it and political intentions in manifestoes, before deciding whether to rebuy or not. Can't help thinking I'm overthinking it with my sale (about 8% or portfolio).... watch it shoot up LOL. Good luck
It's a shame that Stocko doesn't have an area on Energy and or mining , but I guess as it's data driven, you don't get the competitive advantage of these speculative business's potential by reading the historic data!
I think a lot will depend on how much of the Tailwind tax losses BOD feel can be utilised against profits. Before the deal there was a lot of discussion on the forums about this and I must confess I aired my significant doubts as the Tailwind tax losses amounted to many millions and I was sure would be subject to significant HMRC scrutiny.
Hostelworld (LON:HSW) Today reveals preliminary results for 2023 with adj EPS at 9.91 Euro cents against a forecast of 5.4 Euro cents. They say they have started 2024 with strong momentum.
Hostelworld (LON:HSW) I hold and have topped up on today's results. They now have a presentation on their 2023 results on their investor relations website.
Pollen Street (LON:POLN) I agree that results are interesting today. Is this another Intermediate Capital (LON:ICP) in the making? Complex results because of reverse into an investment company, but its the alternative asset manager that interests me. It doubled its profitability in the year. In a few years time the investment manager results will > the investment company. Large dividend. £30m buy-back announced. Excellent growth in private credit and private equity assets. Using the balance sheet to seed new funds. NAV is 912p but that includes goodwill from the acquisition and its is a leveraged balance sheet. Anyone else holding this potential multi-bagger?
Originally bought Honeycomb Investment Trust in 2021 for the healthy dividend (8%). This then evolved into Pollen Street (LON:POLN) in late 2022. Back in March 2022, this MoneyWeek Article provided a good summary of the then planned merger/evolution as well as warning of the possible dangers ahead. Although the SP dropped sharply, the healthy dividends continued (albeit slightly reduced) and given the recent positivity in news and SP rises, I shall be back in positive territory before long!
Stocko is showing dotDigital (LON:DOTD) down 34% I am hoping that this is an error but anyone know?
There was one cancelled trade at 9:01 for 57.4p. It seems to be trading normally now.
DOTD seems to be back to normal, thank you. Heart rate returned to a safe level!
SI Trade this morning ?
My snapshot for Judges Scientific (LON:JDG) full year results. They talk a lot about how well they've done in the past, which there is no doubt of, though there's little to shout about in the near future in my opinion. Revenue growth for next year supposed to be only 1-2%, well below prior levels and a few fairly negative comments on market environment throughout the report.
There's no doubt its a very strong business with excellent growth so far and impressive 15% organic revenue growth this year. But are they going to struggle for the next year or two? Maybe I'm taking the wrong message from these results, but they didn't fill me with confidence. The stock is on my watchlist but have never owned.
Any counter points very welcome.
They talk a lot about how well they've done in the past, which there is no doubt of, though there's little to shout about in the near future in my opinion. Revenue growth for next year supposed to be only 1-2%, well below prior levels and a fair few fairly negative comments on market environment throughout the report.
Prices move relative to expectations. I think we can agree that these have been set nice and low. I’ve top sliced this name a few times and it has always been a mistake.
I agree they certainly haven't missed on expectations and with a long term view any pull back is probably a great buying opportunity. The main question I guess is whether they bounce straight back to a higher growth rate in 2025? If not then a P/E around 30 could be argued is too high.
Good review Phil P, I like the colour coding and the opinion interspersed with the quotes.
Historically I didn't buy good quality companies because the p/e ratio was nearly always too high. An interesting piece of work from Terry Smith in one of his annual letters at Fundmith (I hold) changed my mind when he showed that the initial buying price of companies that could compound (particularly reinvest their cashflow to generate returns above their cost of capital) over many years could have very high to justify their return.
I bought into Judges Scientific (LON:JDG) about 3 ago and it seemed so expensive then. However the management seem to be excellent and as I have added over that period it has continued to grow. I was tempted to top slice at 11,800p (actually tempted at everything above 10,300p), but resisted just before results and I am slightly underweight from where I would like to be. I think there will be a further buying opportunity if the Geotek expedition doesn't happen in FY24.
Final point, I am guessing that governments around the world will do everything they can to get interest rates down, and to heck with inflation - that just reduces the value of their massive debts. If this guess is correct, that will give a tailwind to these great quality companies. Other examples: Halma (LON:HLMA), Diploma (LON:DPLM) , Spirax-Sarco Engineering (LON:SPX), Diageo (LON:DGED), (I hold all of these). I am also taking a chance with Renold (LON:RNO) and Wilmington (LON:WIL) , that they can do the same.
Other examples (of quality beside Judges) : Halma(LON:HLMA), Diploma (LON:DPLM) , Spirax-Sarco Engineering (LON:SPX), Diageo(LON:DGED), (I hold all of these). I am also taking a chance with Renold (LON:RNO)and Wilmington (LON:WIL)
Good selection there. I own the lot with the exception of Renold, which is one I’ve never researched sufficiently. The one observation I can make is that, in contrast to all the others you’ve mentioned, it is decidedly not a quality compounder. Perhaps that’s why I’ve never seriously investigated
BnB: Fair point re Renold (LON:RNO), I've recently taken a starter position and recognise I'm taking a chance - trying to get in early.
Just looking at back at my notes. I like the adjusted profit growth and the % return on sales. At the moment there is a substantial pension deficit which after a detailed crawl through the annual report, I think will start to reduce. Putting the pension cash cost back into the P&L gives me an adjusted forecast eps of 4p for FY24 which gives a p/e of c.9.5, which I think is quite good value v % operating margin. My key question is what happens in FY25, their current eps forecast (Stocko) (before pension) is down by 10% and I'm not sure why. I'm hoping they are being cautious, (I like cautious and then overdelivery).
I don't like the fact that they don't stress the importance of organic revenue growth, which is my view is the license to make acquisitions. Also in my opinion, the financial reporting is more opaque than my preference.
Finally my guess is that we will get a wave of pension fund revaluations which are based on higher interest rates than their valuations done 3 years ago. One of the few benefits of inflation from a shareholder perspective is that pension payments will not have kept up the substantial inflation over the last 3 years.
I'd be interested in your view if you have the time to take a look.
Renold (LON:RNO) I'd be interested in your view if you have the time to take a look.
When I look at stocks, 95% of the time I am looking for a quality compounder and the remaining 5% (ie recently) for a cyclical rebounder. I have a bespoke layout on Sharepad under the financial tab - for Sharepad users it is the "custom" sub-tab. There I've designed it to display under a variety of headings the likes of revenue and earnings, dividends, valuation multiples, debt ratios, returns on capital/margins, free cash flow. Sharepad lets you drag any data row, typically going back to 2010, into an instant chart on the same page - very useful. There are several placeholders for the charts but the one instant chart that is always loaded is for revenue. If that chart doesn't rise in a beautiful arc from bottom left to top right then, no matter how good the potential investment, the company is not a quality compounder - and Renold fails this test miserably.
That does not make it a poor investment today, but I would have to categorise it as a cyclical stock with a good self-help story. These can be good winners over short periods of a year or two and Renold has certainly rewarded investors of late. It's optically cheap still but the picture is clouded by the pension. As I'm not an accountant, but rather a reader of management, strategy, technological progress and of end-market demand, this puts it in the too complicated box for me. And someone else will have to make the big money that my limitations prevent me enjoying. I like Avingtrans (LON:AVG) far more because I can better see what management are trying to achieve in terms of moving with the times. It was also very attractively priced a month or so ago and that is when I was fortunate enough to have some spare cash from a disposal.
Thanks BnB for taking the time to reply - very interesting perspective.
Hi BNB, I've just started with Sharepad so would be interested in the design of the bespoke layout you mention.
I’ll see if I can upload a screenshot. The custom page is infinitely configurable so you could start with something similar and then migrate from there into your preferred data layout
Here you go. I just failed to squeeze a couple of lines in at the bottom of the screen grab
FCF ps
FCF for firm
Net borrowing
The design layout gives you complete freedom to arrange as you see fit and include anything that you deem relevant. I could tidy it up a bit by removing some of the redundant rows: do we really need EV/turnover as well as price to turnover? However, you sometimes find interesting discrepancies which remind you that the presence of cash or debt is distorting the enterprise value. You’ll notice the lack of balance sheet information. I’m happy for that to stay on the dedicated balance sheet tab since, with the vast majority of my investments, the balance sheet data is pretty much redundant – they’re mostly swimming in cash. But that’s just my investing style.
PS special prize if anyone can guess the company featured!
Thanks very much for that.
Think it’s Games Workshop (LON:GAW). Rare beast of growing revenues and high dividend payout ratio stands out to me from your graphic.
Think it’s Games Workshop (LON:GAW).
Well played that contestant.
Lower interest rates won't though help companies with pension deficits, it will probably make those look much worse. For a company like Renold (LON:RNO) (which I like a lot as a resilient business except for its balance sheet!), I think their pension deficit dwarfs their net bank debt - and that's even on the typically more generous accounting basis compared to the valuation basis the pension trustees or insurance buy-out providers would normally look at. I'd be more cautious in that regard.
M48: You might be right, I'm not an expert on the accounting for pension funds. The latest net deficit at 30/9/23 is £62m (FY22: £87m), which I agree is substantial compared to their market cap of £81m.
For Renold (LON:RNO), it's worth reading Note 18: Retirement Benefit Obligations in their accounts. It is complex and has a number of features that are different to other pension funds. I do my eps calculations after charging back the cash cost of the pension and I like the risk reward balance enough to take a starter position. The next triennial valuation date is 5 April 2025, so any change will impact from FY26. So the key question here is interest rate forecasts from 5 April 2025 vs 5 April 2022, while the valuations are being prepared.
The only point I would make re insurance buy-outs is that insurance companies are building in future profits and obviously huge uncertainty, so this is not the true cost of continuing to pay down a closed pension scheme if it is kept within the company..
Hi Matin, I totally agree on having to pay up for high quality companies. I've just had a look and over 50% of my holdings are on PE's of over 30, though a lot of these are US stocks. I think you need to have the growth rates to back that up though. If growth rates start falling then I would say the PE should reduce along with it. I found the guidance of only 1-2% revenue growth for this year a bit concerning, considering their growth in the past, which has commanded a higher PE. However they have certainly proven over the past decade or more that they know what they're doing so hopefully it's just a temporary slow down.
I also like this sector with Diploma & Judges on my watchlist. I've owned Halma & Renold in the past as well. You've got a nice selection there, for what it's worth I also think they'll do well over the next few years.
Thanks for your reply. Re Judges Scientific (LON:JDG), I really like the management and their focus on the things that matter in an acquisitive company is virtually a mirror image of my own view. They have a history of under-promising and over-delivering, which is fine with me. Will the price be lower at some time in future? Probably, but I am happy to hold because I believe that the management will deliver long term growth.
Like you, I have a number of high p/e US stocks, but I do struggle with both the level of these p/e's and the amount of compensation the management take.
Selling shares which get to a high p/e is my biggest failure - they get to a p/e which I think is ridiculous. I sell, then watch the price go sailing upwards. Sage (LON:SGE) was a good example of this.
Just realised this got cut from the bottom
Not small cap but the ahead results from Next (LON:NXT) I am hoping bodes well for Marks and Spencer (LON:MKS) - we know the latter food business is running well but the Next (LON:NXT) results suggest the rest of the business may be doing a little better than they had conservatively flagged to market. Wonder if there could be a decent size beat on the cards? I see its risen 10p today but on a PER of just 10 and dividend reliability returning I’m quite keen on Marks and Spencer (LON:MKS) to continue its recovery.
Unless Next (LON:NXT) is taking market share from Marks and Spencer (LON:MKS) in clothing and homeware...strong food may not be enough
Yeah but I don’t think so. Marks and Spencer (LON:MKS) was starting from a low base having underperformed for years - more likely they are taking market share from others as its offering has become on trend in its demographic again.
I think this FT article describes the competitive environment across M&S's sectors pretty well and calls out the competition M&S faces from both Next and Primary
https://www.ft.com/content/691...
I got it as one of my freebies!
Stunning results from Next (LON:NXT) and I also hold Marks and Spencer (LON:MKS) which is in the middle of a successful turnaround. I know the M&S food business quite well as I used to supply them. The poor merchandising and quality in the clothing side always put me off buying the shares, but this has turned a very sharp corner and now looks very attractive. Marks and Spencer (LON:MKS) is at the start of a long journey and I think there is a lot more to come.
Next (LON:NXT) are hoovering up retail brands and their fulfilment / online platform looks like it is capable of delivering a new period of growth through partnering with some pretty impressive European and US retail brands. I also noted today the stunning results from privately held Dutch retailer Target. The way in is through 3i (LON:III) who own nearly half the equity.
There ought to be a special award for David Ciclitira of LVCG who managed to take a shell, add an operating business, and somehow make the share price go lower than it was when it was a shell.
However, him and his wife have done very well as directors of the business. You'd need to be a real schmuck to give that business any money with his track record but sadly I think he'll find some more.
Science (LON:SAG) I hold
Full year results this morning. Revenue up, adjusted operating profit up, adjusted EPS up, 60% increase in dividend.
"Science Group retains an asset-rich balance sheet, including significant cash resources and freehold property." net funds £18m despite acquisition costs and share buy backs.
This comment by the Chair intrigued me
"...the relative valuation of the company against both UK and international comparators may prove a material constraint. The Board will therefore consider all options to address this disparity and deliver value to shareholders."
Perhaps Paul or Graham could take a look?
Science (LON:SAG) I think Paul has a very favourable opinion of this company with strong fundamentals however it sounds like the board of directors as are a lot of private investors completely brassed off with the valuations of UK market stocks, no wonder so many are wishing to exit or invest abroad.
Science
Looks solid but hard to see a catalyst unless management do something .
One thing jumps out is the freehold looks understated on balance sheet by around 15 million
It’s on balance sheet at 20 million yet brings in annual income of 4.2 million .
Bit of hidden value there
Could sell the real estate and lease it back that would put 35 million in the coffers which they could pay to shareholders .
Management look a bit safe and conservative which is all good but then bemoan a valuation that is safe and conservative ?
I think this may be hinting at a move to US platform where multiples are greater, allowing equity raising for acquisitions requiring greater multiples, rather than being constrained by UK valuations.
Just a guess
re. Science (LON:SAG) . Given the freehold assets on the balance sheet, the nice rental income, the conservative accounting (no capitalisation of R&D) and the relatively low valuation, I wonder if this is looking like a prime candidate for a takeover bid maybe?
I like the Science (LON:SAG) core consultancy business and numbers from that look strong today. However, in the last two or three years they have made two strange acquisitions. Firstly Frontier which makes DAB radio chips, which started really well under the Science (LON:SAG) ownership but appears to have crashed and burned this year. Secondly, TP Group which was an underperforming Aerospace & Defence stock. The former appeared to have no synergy with Science (LON:SAG) and the latter only some overlap. I am struggling to see the logic behind these two deals, especially as they were both hostile takeovers of poorly performing businesses.
Centamin (LON:CEY) results solid. Would anticipate a good continued run for the stock from here given the gold price momentum.
The SP has formed a huge base which is indicative the company putting right all the operational aspects which caused its share price to plummet several years ago. If gold prices remain high, combined with possible new prospects, I am expecting the SP to regain the highs of the past., which is why it’s one of my larger holdings.
There also seems to be more political stability now in Egypt, given the recent IMF bailout. Well, at least for a year or two. So that reduces the geopolitical risk for a while for Centamin (LON:CEY) ..
Judges Scientific (LON:JDG) Continue to execute in their inimitable style. FY23 slightly ahead of expectations. FY24 line with forecasts, solid orderbook (normalised post CV19). Continues strong cash generation. The divi now 95p, almost the same price they IPOd at.
Join management for a webinar today 21.3 at 4.45pm, register here.
Secure Trust Bank (LON:STB) FY23 results overview video and podcast. Broadly in line on an adjusted basis. Still on track to hit £4bn net loan book at 14-16% rtn on average equity; and to achieve £5m pa cost savings by the end FY24.
Pebble (LON:PEBB) FY23 results webinar with management this afternoon 21.3, 3pm, register here. FY23 results released on Tuesday and shares rallied after a big sell off with PW November 2023. FY23 numbers in line with revised expectations. ARR +12%. GP margin 34.1%. Cash £15.9m. Revenue and EBITDA down c 10% on FY22. facilisgroup is the high margin digital offering and Brand Addition the more traditional promotional products business.
Why are Judges Scientific (LON:JDG) shares down 10% then?
Why are Judges Scientific (LON:JDG) shares down 10% then?
Now only down 5% but warranted because they had run up too high at 30x fcPER. They normally trade at about 26x, in line with quality life science names. Arguably therefore still a little overpriced relative to the norm.
Looking at the figures of Judges Scientific (LON:JDG) the basic EPS is well down. Tax went up 41% for some reason.
Tamzin's comments did not seem to tie up with the market reaction.
Regarding Judges Scientific (LON:JDG) (I hold):
In addition to BnB's important point already, they are also flagging again that "Timing of next Geotek Coring expedition and its revenue recognition in 2024 remains uncertain." The Coring expedition is in expectations for the current year as per the Outlook statement, so some doubt about that.
Key question is to what degree that coring expedition is in expectations for the current year. I have only skimmed the announcement, so I'm not sure whether that question is answered.
I seem to recall that Liberum states that the coring revenues are not in the forecast so there could be upside if they come through this year
I seem to recall that Liberum states that the coring revenues are not in the forecast so there could be upside if they come through this year
That's interesting, I edited my post after I read in the Outlook statement:
"At this point, we are still envisaging another coring expedition during the course of 2024, however, Geotek has not yet contracted for this expedition and there is uncertainty regarding its timing and the amount of any related revenue to be recognised in 2024."
Reading through the report there doesn't seem to be much growth happening next year and they make quite a few negative comments on the market environment. That may be enough to put people off for now being as its on quite a high P/E
Positive spin on STB results Tamzin? According to Stocko estimates that’s a big miss on expected profits and a big dividend cut. Oops.
Secure Trust Bank (LON:STB) I think you need to look at adjusted EPS which was 172p and in line. However, 32p dividend feels pretty poor - that's a payout ratio of less than 20%. If they paid out half of adjusted profits, this would be on a double digit yield. CET1 ratio fallen quite a lot from 14% to 12.7% - driven by increased lending - this is quite thin and explains the dividend cut.
For Judges Scientific (LON:JDG) (I hold), my focus is on adjusted eps which is 374.6p v 363.8p (LY) (+3.0%) and forecast as per Stocko of 362p. Adjustments are described below, both seem very reasonable to me, but that is an individual judgement.
"Adjusting items
£18.3m of pre-tax adjusting items were recorded in 2023 (2022: £12.3m). The two main constituents were £11.8m of amortisation of the intangible assets recognised upon acquisition (2022: £8.4m), primarily arising as a result of the acquisition of Geotek, together with a £4.0m charge primarily relating to the difference between the market value of the new Judges shares issued for the equity component of the Geotek earn-out compared 31 December 2022 share price. IFRS prohibits adjusting the total acquisition consideration for the post-acquisition change in share price so it is instead recorded as an expense."
Corporation tax has increased from 19% to 25%, although only part year in Judges' case but on annual basis this is a 32% increase in tax. Next (LON:NXT) publish a pre-tax eps increase which is helpful to understand the performance of the underlying business. For Next (LON:NXT) (Jan y/e), the improvement in pre-tax eps vs LY is 4.5%pt higher than the post-tax eps. For Judges Scientific (LON:JDG) , it's probably fair to add about 4% pt, giving an estimate of pre-tax eps up 7% on LY, not bad.
According to the Gamma Communications (LON:GAMA) Financial Calendar on their company website, they are releasing their FY 23 results this coming Monday 25th March
Downing ? (Avingtrans RNS)
I thought Downing were closing their small cap fund so presumably selling down .
Just noticed they increased on Avingtrans to over 4% (up about 0.8%)
Anyone know timelines etc on Downing as in theory it’s a bit of selling pressure on their Holdings .
Or did I miss something .
Morning planetX
Downing has severaI strings to its bow and I suspect that Avingtrans (LON:AVG) is not held in the Downing Strategic Micro-Cap Investment Trust (LON:DSM) , which is in wind down.
Interestingly Avingtrans (LON:AVG) bought Booths Industries, part of the Redhall Group from the administrators when the latter failed. Redhall Group was heavily backed by Downing that suffered a complete loss of capital on the investment.
There is an interesting podcast with Judith MacKenzie & Rosemary Banyard talking through their worst investments (it is a series of 7 or 8 and the latest one with Judith's covers this exact issue - total loss of capital with Redhall.). The others are also interesting about multiple topics, but this latest one is very pertinent.
Really interesting and very refreshing to hear Investment Managers being so honest and open about their worst mistakes.
Link below to the series - Fund your Retirement
https://www.fundyourretirement...
Downing Strategic Micro-Cap Investment Trust (LON:DSM) Issue and redemption of B shares on 4 April for the first payout.
Re AVG - perhaps Downing are buying it in DORE which is their renewable energy fund.
Downing Strategic Micro-Cap Investment Trust (LON:DSM)
I wondered about this too Planetx.
DSM is only worth £30m. Here is the portfolio at beginning March:
My morning smallcap tweet: Live Company back from the dead
Live (LON:LVCG) Aptitude Software (LON:APTD) OPG Power Ventures (LON:OPG) Aukett Swanke (LON:AUK) Intercede (LON:IGP) ValiRx (LON:VAL) Pollen Street (LON:POLN) Getech (LON:GTC) Silver Bullet Data Services (LON:SBDS) Feedback (LON:FDBK) Tribal (LON:TRB) National World (LON:NWOR), ECO Animal Health (LON:EAH), Games Workshop (LON:GAW), Aquis Exchange (LON:AQX), Judges Scientific (LON:JDG)
◄Live Company (LVCG)► cash crisis resolved for now as chmn provides £1.77m total convertible, strike 6p. Pays some creditors in shares (at 3p) and sells majority interest in StartArt. £352k placing at 1p. Existing businesses expected to be funded for this year. [SP=NA Cap=NA]
◄Aptitude Software (APTD)► FY-Dec. Warns: "[Macro] trends will moderate headline revenue this year and profitability is now expected to be in line with 2023 performance, before returning to more normalised growth in 2025 and beyond." WIll return £20m max over 3 years via divs and £6m max buyback. [SP=370.25 Cap=212m]
◄OPG Power Ventures (OPG)► sells solar assets for £291k. Paid £2k. [SP=10.7 Cap=43m]
◄Aukett Swanke (AUK)► buys assets of RTS out of liquidation for £37k plus £50k max contingent. RTS provided master system integration and smart building software to commercial properties in the UK. Also £425k subscription at 1p, 9% discount. 1:1 warrants at 1p. FY-Sep out on 28 Mar. [SP=1.2 Cap=4m]
◄Intercede (IGP)► launches its Multi-Factor Authentication MyID MFA product, version 5 . [SP=95.5 Cap=56m]
◄ValiRx (VAL)► agreement with Imperial College London to evaluate research relating to novel therapeutic candidates for cancer treatment. [SP=3.75 Cap=5m]
◄Pollen Street (POLN)► £30m max buyback. [SP=534 Cap=NA]
◄Getech (GTC)► first 2 months of FY24 rev up c.40%. In line? VP of Guff, Max Cliché notes "By leaning on the collective knowledge base of its geological team, Getech is leveraging AI and ML..." [SP=8.25 Cap=6m]
◄Silver Bullet Data Services (SBDS)► contract wins and renewals with Heineken and Greene King worth £1.7m. I'll drink to that. [SP=147.5 Cap=26m]
◄Feedback (FDBK)► gets £50k for a further Community Diagnostic Centre ("CDC") pathway pilot with the Oldham CDC. CEO says ""We are gaining momentum in the CDC space following the funding support released by NHSE." [SP=120 Cap=16m]
◄Tribal (TRB)► FY-Dec rev "head of market expectations as at January". Div level decision deferred "given the uncertainty around the likely outcome of the dispute with NTU". Likely to be declared as interim div. Current trading in line. [SP=41.5 Cap=88m]
◄National World (NWOR)► FY-Dec adj EBITDA £9.5m, 6% above expectations. Outlook: Q1 EBITDA slightly higher than internal expectations but rev slightly lower. [SP=14.25 Cap=38m]
In line: EAH, GAW, AQX, JDG
ECO Animal Health (LON:EAH) - "Sustained demand and continuing progress" (link to research note: https://www.equitydevelopment.co.uk/research/sustained-demand-and-continuing-progress)
For the year ended 31 March 2024, Eco Animal Health reports progress in both the second half and Q4, underpinned by demand for the Group’s proprietary Aivlosin® antibacterial treatment for gastrointestinal and respiratory diseases in pigs and poultry. The Group reports sustained demand for Aivlosin® across the territories it targets, which we note are worldwide: China, Japan and SE Asia, the Americas and Europe. The Group expects FY24 revenue to be in line with a market consensus estimate of £88.7m.
Following the November Capital Markets event we reviewed the contribution to valuation of the product development pipeline, particularly in light of the strong track record established by Aivlosin® . Our resulting Fair Value range was 137p - 146p. This contrasts with the current share price, and suggests that the potential contribution to earnings of the product development pipeline deserves far closer attention.
PSA: Equity Dev only has forecast EPS of 1.55p for FY24, compared to forecast aggregate on stocko of 2.02p for ECO Animal Health (LON:EAH). Probably one or two stale broker forecasts on Stocko still hanging around, keeping the average high.
Coincidentally, I just published a long write-up yesterday on Eco Animal Health, not knowing a TU was coming out today. I'd argued that in a full China sales recovery, we could see EPS around 8.7p to 9.8p (given strong gross margins), making this a sub-10x PE which is a bargain. And that's not even taking into account the potential value of the vaccines.
Overall, I think the current share price is undervaluing too much of the recovery AND new business potential here. Neither might happen, but even if only one of the two comes true, there will be a re-rating of the shares.
I've bought in this morning. The recent plunge in SP was due to fears about further weakness in China demand due to plunging pork prices. It looks like they've weathered that well. Pork prices have recovered in the last few weeks.
(I now hold in the Boon Fund)
Morning Boon, where do I find your write-up on ECO Animal Health (LON:EAH)?
On my Substack - search for the "Boon Fund substack" on Substack or Google. There's also a link from my Stockopedia profile page.
One thing to be careful with at ECO Animal Health (LON:EAH) is potential regulatory issues aimed at reducing antibiotic resistance. A lot of revenue comes from the antibiotics given to pigs. It is possible that US or Euro governments could put in measures to cut the amount of antibiotics given to healthy animals as a preventative measure rather than a treatment. The likelihood of this would be further increased if there was an antibiotic resistant strain that made big headlines. Global food shortages might make governments unlikely to do this, but it is something to be wary of as it would destroy the profits of the company.
That is true, something to keep monitoring, the regulatory threat, for ECO Animal Health (LON:EAH) .
Hopefully, at the moment it seems like the regulatory environment is quite relaxed - they got FDA approval for new indications / usage recently (pregnant sows?) and their commentary is upbeat on more expanded use cases approved to come.
The other key thing to watch out for is the competitive space - generic competition of Aivlosin. However, they are also taking some market share from other antibiotics I believe? So its a quite a fluid competitive environment it feels like.
Capita (LON:CPI) are holding a webinar for private investors today at 12.00pm. Meet new CEO Adolfo Hernandez, who along with Stephanie Little Deputy Director of IR will provide an update on performance following the publication of the FY23 results which were released on 6 March.
Register: https://us02web.zoom.us/webinar/register/3017089804350/WN_EXZu7R8ERaWUP3JcYL9h4Q
....and as is usual for Twitter he has been balanced and moderate in his comments (not) ....
Great news guys.
It appears after the Fed's dovish comments last night wrt US interest cuts, the markets are off to the races again this morning.
Indeed with UK inflation (Core 4.5% in Feb'24 ex food/energy/tobacco/alcohol) cooling too, I suspect the Bank of England may also have a similarly positive message at 12noon today.
Meaning (in theory) smallcap stocks SHOULD resume their well-overdue, pre-Xmas recovery.
PeterSchiff reckons Commodities are about to rip:
https://twitter.com/PeterSchif...
PeterSchiff reckons Commodities are about to rip:
https://twitter.com/PeterSchif...
He also thinks inflation maybe 20%. by the end of this year. Never heard of him but he already has zero credibility.
A perma bear who is right once every 20 years.