Small Cap Value Report (Thu 21 Sept 2023) - WIN, PDG, MYX, KETL, FNX

Good morning from Paul & Graham!
Today's report is now finished.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
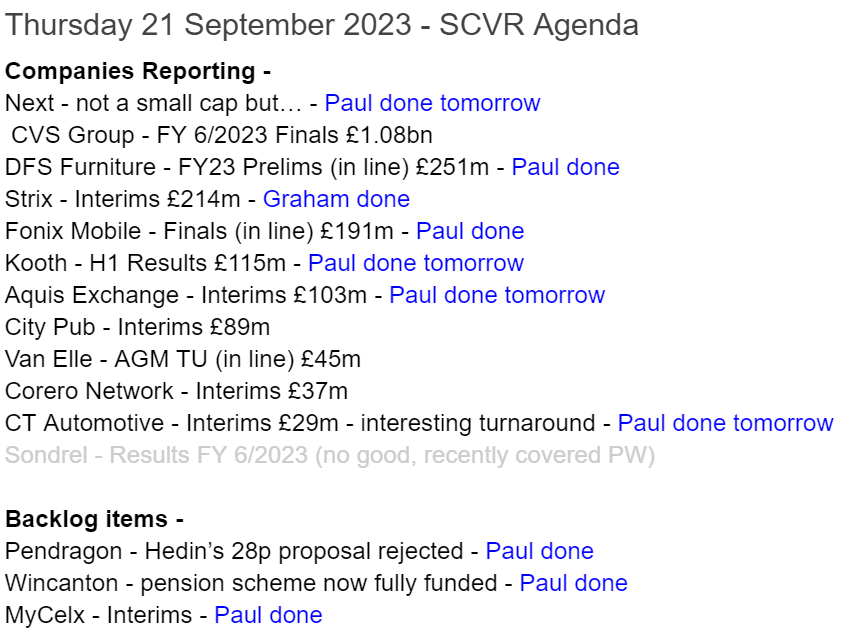
Sorry we didn't get very far today, so I'll park today's report, and have a fresh look at some more agenda items tomorrow.
Summaries
Pendragon (LON:PDG) - up 14% to 27p (£377m) - Hedin takeover proposal - Paul - GREEN
Largest shareholder Hedin counters management proposals with an indicative 28p cash takeover bid, rejected by PDG management. I discuss the bull and bear points of both proposals below.
Wincanton (LON:WIN) - up 16% to 283p (£352m) - Update on pension scheme - Paul - GREEN
This has been on the cards for a while (mentioned here in Jan 2023 as a catalyst for the shares to rebound) - the pension scheme is fully funded for now, with the 2023 triennial valuation seeing the deficit completely eliminated (but possible it could come back in future). This results in a huge cashflow saving for WIN, and could open the door to higher divis. I remain positive on this cheap, well-run logistics group.
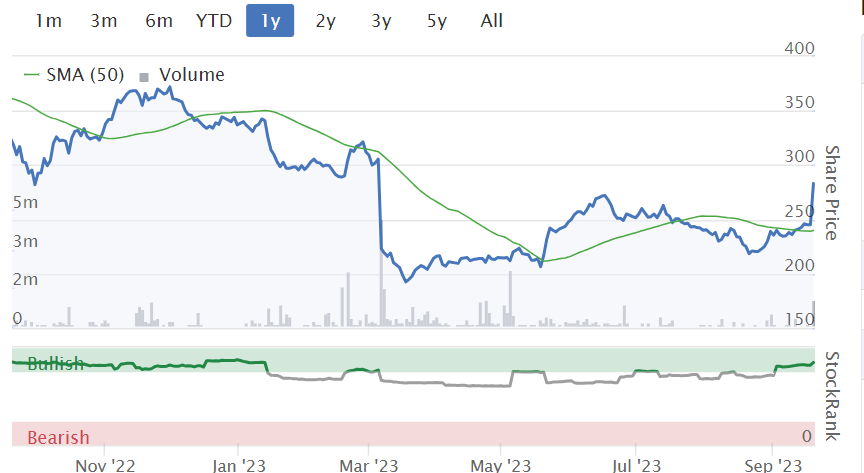
MyCelx Technologies (LON:MYX) - up 31% to 63.5p (£14m) - Interim Results - Paul - AMBER/GREEN
High risk, speculative idea - an old one has resurfaced from years ago, when it looked to have interesting tech to clean up polluted air & water. Still loss-making, and needs another cash raise I think, but there's good growth, narrower losses, and very bullish outlook comments. Huge potential market. Let me know what you think - strikes me as an interesting speculative idea, for risk-takers only.
Strix (LON:KETL) - down 40% to 54.5p (£119m) - Interim Results (profit warning) - Graham - AMBER
This stock hits an all-time low after it reveals poor results. Brokers have cut their forecasts for the rest of the year. Commentary by management is confusing and offers little comfort that they have control over the situation, and the leverage multiple is near the covenant limit.
Fonix Mobile (LON:FNX) - unch 192p (£191m) - Final Results 6/2023 - Paul - GREEN
Smashing figures, a really impressive niche business, that generates cash and pays divis. Expansion into Ireland has worked well, and further international expansion intrigues me as a possibility. It's difficult to ignore the quality here, thumbs up from Paul.
Paul's Section
Pendragon (LON:PDG)
Up 14% to 27p (£377m) - Hedin takeover proposal - Paul - GREEN
On Monday this week (18 Sept) I reviewed here PDG’s announcement that it has agreed to sell its main car dealer business to US car dealer Lithia in a deal that would result in a 16.5p dividend, and PDG then becoming a SaaS company operating its Pinewood Tech software business on a standalone basis. It looked quite a good deal, with Pinewood looking a nice business, which could then re-rate in the market. However I did worry that the disposal to Lithia of the core business looked as if it might be under-valuing the business.
The biggest PDG shareholder Hedin at 27.6%, did not give its approval to the deal.
The latest news came at 15:06 yesterday saying that Hedin had tabled an alternative deal, for it to buy PDG for 28p cash, subject to raising external debt funding, and doing due diligence. PDG’s Board has unanimously rejected this deal.
Paul’s view - a fascinating situation, which I missed unfortunately, having sold my PDG shares just before the deals were announced, oh well never mind. It’s difficult to say which is the better deal. I worry that management’s deal sells off the core business too cheaply, but quite like the focus on its software business and expansion into the USA.
Whereas the 28p proposal from Hedin also has attractions, in allowing shareholders to potentially cash out cleanly. Maybe if they sweeten it to 30p+ then management might capitulate?
It’s unusual to see management operating effectively in conflict with their largest shareholder at 27.6%. If Hedin’s advisers are on the phones, and are persuasive, it wouldn’t surprise me if they persuade other institutions to pull the rug from under management, and accept the Hedin deal. All fascinating stuff! With the market price now at 27p, small shareholders also have the option to bank your profits now if you want, or hold on in the hope for a sweetened deal from either party.
Wincanton (LON:WIN)
Up 16% to 283p (£352m) - Update on pension scheme - Paul - GREEN
This logistics company has staged an impressive recovery over the years, trading its way out of what looked an insolvent balance sheet years ago.
Excellent news today re the pension scheme’s triennial valuation on an actuarial basis. This is the much stricter valuation basis which pension trustees use to determine the cash payments required from the company to repair pension deficits. Clearly these actuarial numbers are what investors should focus on, ignoring the much more lenient accounting basis pension deficits/surpluses which are included in company accounts.
It’s a highly unsatisfactory situation at the moment, with two sets of rules for accounting for pension schemes, which confuses and misleads many investors. Always focus on the actuarial numbers, as that drives real-world cash requirements. There can be massive differences between the two sets of rules, so this stuff is very important to properly understand.
Great news yesterday - the previous 2020 actuarial valuation showed a huge deficit of £154m. This has now gone! The 2023 triennial valuation is now a £3.9m surplus.
This results in -
The Group and the Trustees have agreed that no further contributions are currently payable into the Scheme as a consequence of the 2023 valuation.
Prior conditions around shareholder distributions have been removed.
This is a massive saving on what would have been the case previously -
Previously, contributions for the year ending 31 March 2024 would have been £23.6m and £25m per annum from April 2024 to March 2027, growing in line with the Retail Prices Index.
The pension schemes haven’t disappeared though. So it is possible that in a negative scenario, some future pension deficit payments might conceivably re-emerge. For now though, it looks as if investors can probably forget about this issue, and enjoy the likely increase in divis.
Paul’s opinion - very good news, but not unexpected. I pointed out here on 13 Jan 2023 that the pension scheme was nearly fully funded - “Large pension scheme is a key issue, and could trigger a shares re-rating if it’s resolved (previously indicated it’s nearly fully funded). I remain positive, thumbs up - shares look cheap to me, for a decent, resilient business.”
There was a profit warning on 7 March 2023, due to the loss of a lucrative large contract with HMRC, but we stuck with our GREEN view of WIN throughout 2023 to date, due to the excellent value, good divis, and the pension scheme being close to fully funded.
With today’s good news confirming the pension scheme is now no longer a drag on cashflows or divis, that reinforces my positive view of WIN, so I’ll remain at GREEN.
MyCelx Technologies (LON:MYX)
Up 31% to 63.5p (£14m) - Interim Results - Paul - AMBER/GREEN
I researched this company with some investor friends many years ago, and we concluded that it has interesting technology, for cleaning up industrial pollution of water and air, with apparently some proprietary IP. However, financial performance has been weak generally, with the occasional good year as a one-off. So I think we must have sold up and moved on.
It caught my eye yesterday on the top % risers list, so I had a very quick skim of interim results to June 2023.
There are some signs of life here I think, so it might be worth a closer look for people who like more speculative ideas. Shares are very illiquid, with a wide spread.
H1 revenue $5.6m (up an impressive 51%), gross margin also up, at 45%. EBITDA loss has narrowed to $0.9m from $2.1m in H1 LY.
Cash looks tight at $1.4m, so I imagine another placing will be needed at some stage, but perhaps could be done on reasonable terms now that the company is producing more appealing numbers?
Commentary & outlook sounds super-bullish, talking about large markets, with big positives driving environmental cleanups. Says it has the best available tech.
Paul’s view - I’m intrigued by this, and will do some more digging. There could be a nice re-rating here, on a similar basis to the one I recently found with Plexus Holdings (LON:POS) (I hold) that has quadrupled in the last month, with the market catching up on previously ignored positive newsflow. MYX looks worth a closer look I think, but only for risk-takers.
Fonix Mobile (LON:FNX)
Unch 192p (£191m) - Final Results 6/2023 - Paul - GREEN
For background, this niche software/services company provides the technology behind TV viewer voting, so think reality TV, charity fundraisings, etc. Clients tend to be very loyal, because Fonix services never go wrong, and so switching to an untried competitor has only downside risk for the TV companies.
These types of TV shows run year after year, and I recall that Fonix says it has never lost a customer to a competitor, dominating this niche in the UK, and possibly also going the same way with its recent entry into Ireland.
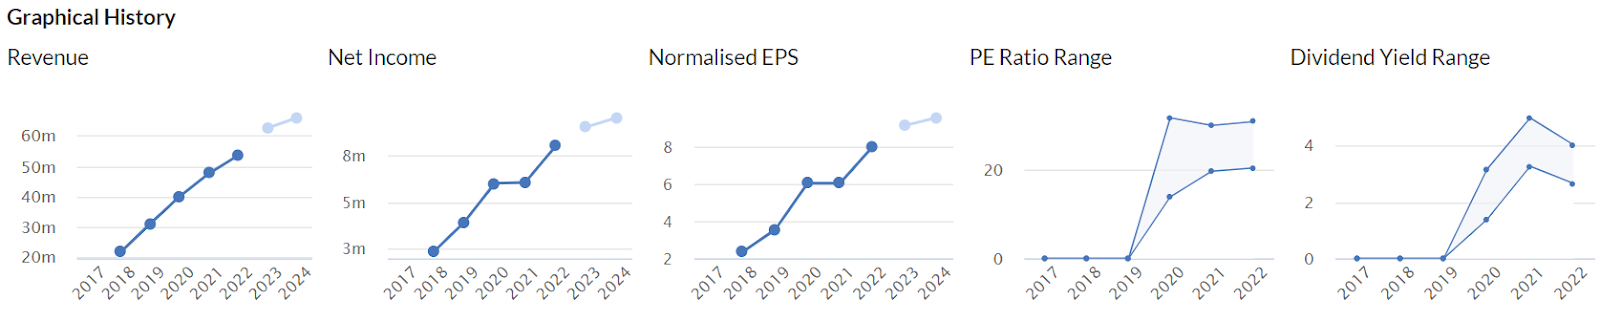
Since listing in Oct 2020, Fonix doesn’t seem to have put a foot wrong, and I think has earned its fairly punchy rating, due to an impressive track record as you can see on the Stocko graphs below. Note also the cash generation and generous divis, from its capital-light business model - lots of boxes are getting ticked here! -
FY 6/2023 key numbers -
Revenue £64.9m (up an impressive 21%)
99% of revenue is “repeating” in nature
Adj PBT £11.0m (up 13.5%) - note adjustments are small, and the profit margin is healthy.
Adj EPS 8.9p (up 10%) - PER of 21.6x - not cheap, but what do you expect for a quality business?!
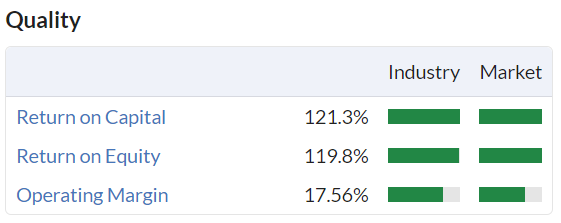
Dividends - 2.36p interim paid, 4.89p final proposed = 7.25p total, yielding 3.8%
International expansion - this is the most interesting bit. Fonix launched in Ireland, and went from a standing start to 10% of total group gross profit, in one leap in FY 6/2023. The commentary says this very successful launch is now a blueprint for further expansion into other countries, which it says can be done with minimal additional costs. This is very interesting!
Outlook - strong start to FY 6/2024, in line with expectations.
Share based payments - companies are splitting very clearly into the hall of shame (Directors lining their pockets with multimillion charge to the P&L - eg Eagle Eye Solutions (LON:EYE) [I hold] springs to mind as a recent example), and the all of fame - eg Warpaint London (LON:W7L) recently, and I am happy to say Fonix too - only share-based payments charge of £125k for FY 6/2023, and £100k LY. Well done!
Balance sheet - hardly any fixed assets at all. It’s just working capital, with money going in & out. So NTAV of £8.2m is fine, it’s not an asset-based business.
Cashflow statement - couldn’t be simpler - it generates plenty of cash, and pays it out in divis. That’s pretty much it!
Paul’s opinion - as you’ve probably gathered, I really like this company's fundamentals.
I’m trying to think what could go wrong. Is the tech old hat, and could it be overtaken by something internet-based? Just because they’ve never lost any clients before, doesn’t guarantee that an aggressive new competitor might not surface and take business away. What about catastrophic systems failure from eg hacking? It must be an ever-present risk for time-critical, high volume revenue generation when TV shows go into voting mode.
Overall though, I think once again this company impresses me with its clean numbers, decent growth, and the potential for new territories to open up. Is it worth a PER of about 20? Definitely, I’d say. This could be a really nice little share to just tuck away and forget, collect in your divis, and who knows it might manage to expand overseas and see a step-change in performance over time? Something could go wrong that I haven't thought of though, so there's always risk, with everything.
Note management has plenty of skin in the game, another plus point.
Graham’s Section:
Strix (LON:KETL)
Share price: 54.5p (-40%)
Market cap: £119m
This producer of kettle safety controls, and various other related products, has issued interim results.
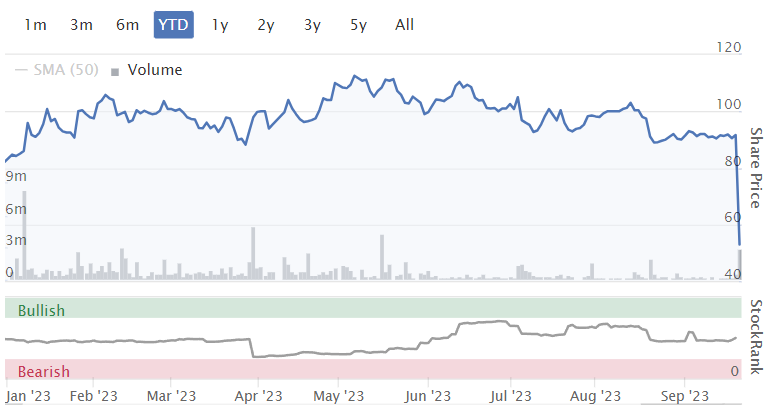
Commiserations to anyone holding this one overnight, as the shares have hit an all-time low:
Revenues are up significantly, thanks to acquisitions, but profits are significantly lower:
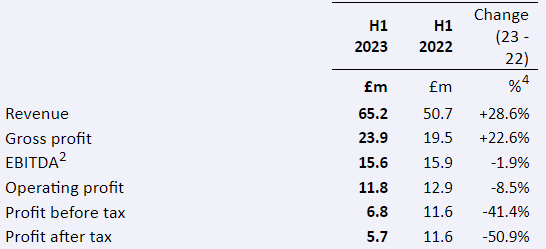
The numbers in this table have already been adjusted - actual PBT is only £4.9m (down from £7.9m last year).
Let’s try to make sense of what has happened:
Kettle controls: revenue down 17.2% to £28.9m, “with the cost of living crisis and the Russia/Ukraine conflict being the key negative drivers in regulated markets”.
Premium filtration systems: includes the acquired Billi businesses. This segment makes a new contribution of £21.5m to revenues in H1. Billi is being “successfully integrated in line with plan”.
Consumer goods: revenues down 6% to £14.9m, “driven primarily by softening of the appliances category market”.
So the existing segments - Kettle controls and Consumer goods - both saw significant revenue declines, and Strix’s overall revenue growth is purely a function of the Billi acquisition.
Net debt grew from £61m a year ago to £93m.
Leverage multiple (net debt/adjusted EBITDA) rises to 2.66x, which is towards the upper end of what would normally be considered prudent. This multiple was 2.2x at the time of the company’s full-year results (discussed here). The company is now seeking to get it back below 1.5x.
Given that leverage is currently too high, the interim dividend gets cut to just 0.9p (interim dividend last year: 2.75p).
Additionally, the company again pledges that “there will be no further M&A activity or investment into new factory builds, with significantly reduced capex and working capital over the medium term”.
It was precisely because the company promised to cease M&A and to reduce capex that I refrained from giving this stock the thumbs down earlier this year. It would be far more investable if the debt was under control.
Note that the debt covenant requires a leverage multiple of less than 2.75x. So there is very little room between that and the actual multiple of 2.66x.
The company is paying a floating rate on its main credit facility (3.5% plus the overnight rate). Finance costs jumped to £5m in H1 this year - more than 50% of the company’s operating profit was needed to service its debt.
Strategy
The company has new “Strategic Business Objectives”, and they are all based on revenue and gross profit targets. It could be worse - sometimes companies don’t even have a gross profit target, and end up gunning almost purely for higher revenues.
I don’t think investors should get too excited about these objectives. The company is clearly struggling to generate much in the way of bottom-line profits and these targets don’t focus on that problem.
The CEO comments, including outlook comments, are confusing to me.
"The continued macro headwinds have resulted in a reduction in demand in kettle controls in the key export regulated markets of UK and Germany during H1 and a slower than anticipated recovery. Whilst recent order rates are tracking in a positive direction, we now anticipate the path to a return of normalised growth to take longer and for there to be a decrease in the short term revenues within this category. The Group's second half of the year is always stronger than the first and weighted to Q4 driven by the replenishment of stock and normal seasonal uplift, the performance required in Q4 to achieve the full year outcome is lower than in 2022 and 2021.
If kettle control order rates are truly tracking in a positive direction, then why are revenues going to keep falling and why won’t it be getting back to “normalised” growth any time soon? And if the performance required in Q4 to hit 2023 targets is lower than before, then why have brokers cut their estimates for 2023?
I think these outlook statements have been overly dressed up, to the point where they simply don’t provide any real clarity or meaning to the reader.
Zeus have cut their adj. PBT estimate for 2023 by 22% to £23m, and have cut the 2024 estimate by 17% to £28m.
Graham’s view
I’m still reluctant to give this stock the thumbs down, because they have proven in the past that they have an ability to generate cash, and they should in theory be able to reduce their debt load.
Underlying cash generation in H1 was once again not that bad: £13.1m of net cash from operations, minus about £6m of capex and development spending, so about £7m in total.
However, that is before interest expense. Interest costs are now eating up substantial amounts of operating profit (on the income statement) and free cash flow (on the cash flow statement).
It’s not yet distressed, but in my opinion it’s clearly showing signs of vulnerability to financial distress, e.g. if macro conditions worsen further or if management makes tactical errors with cash management.
I also think that the poor outlook and the poor performance of kettle controls - whose prospects have been downplayed by management for some time - raise fundamental questions about the quality of the business. What are investors supposed to be excited about, when they buy Strix shares?
Are they supposed to be excited about future acquisitions, when the acquisitions carried out so far have led to the company’s profit shrinking and to a near-breach of banking covenants?
I’m going to (perhaps generously) leave my stance on this as neutral.
Paul adds: I think Graham's being very kind to Strix! I've never liked this share, it somehow doesn't pass the "sniff test" for me, and with debt now problematic and expensive, reading Graham's review above makes me want to run for the hills! So for me it's a firm RED! But as always, the writers here have our own independent opinions, and we love bull:bear debate, if it's kept civil :-)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

63 comments
Strix (LON:KETL) - full investor presentation video now available - webinar with Strix Group plc (Interim Results & Capital Markets Day - September 2023).
?si=J9Poc931VlsatWwYMark Bartlett (CEO), Raudres Wong (CFO) and Harry Kyriacou (CCO & Managing Director, Consumer Goods) discussed:
- the performance in Kettle Controls where improvement is slower than anticipated
- the transformational and EBITDA contributing acquisition of Billi
- highlighted the plan to reduce net debt / EBITDA to below 1.5x in the medium term
- discussed areas of new product development
- outlined the strategic business objectives for the group to end 2026.
See the full video (divided into chapters for ease of viewing) here:
The concern I have with #KETL is the product itself. I think the kitchen market is moving towards boiling water taps, which are much more energy efficient and cheaper to run than traditional kettles. Additionally, due to their efficiency they provide boiling water instantaneously and save time. Long term is there a market for Kettles?
Kettles will be around for a long time. Many people can't afford to fit these fancy taps. Also you need to replace the filters around every 6 months, more in hard water areas, these cost around £30.
Cost of fitting? You can buy a kettle from around £10.
Rockwood
On fire this week
They hold Finsbury food and also Gallford Try both up 20% ish
And Filtronic
NAV should be up maybe 3% next week
Got to respect Richard Staveley who also topped up this week in Rockwood .
I was invested but no IHT so sold, now I must confess I follow his moves but cherry pick the ones I like .
Trustpilot (LON:TRST)
Ok lets get back to something more serious Mr Wolf. Any thoughts on the rather large Director Purchases here? The new CEO Adrian Blair is now in situ and Zillah Byng-Thorne, former transformative CEO of Future PLC is buying significant amounts of shares, since being appointed to the board of NED's. (I NOW HOLD)
Nothing I could add really, Graham's written some excellent stuff on Trustpilot (LON:TRST)
Technically it looks fantastic. Inverse head and shoulders. Bowl with director buying. May pull back to 200d moving average around 90p first but I suspect this will breakout. Very similar to On Beach group (LON:OTB) which also had director buying and a gap up. Can tell a lot from a gap up, by how much price pulls back. If there's demand you can see it clearly.
Inverse Head and Shoulders
And you're talking to me about sorcerers ways....! Thanks for the info Wolf - I also like On The Beach but yet to take the plunge - so to speak
Norfolk were you in Norwich driving around possibly a week or so back seem to remember following a motor (possibly ford kuga ) that had "norfolk & good" on the back made me think of you, as although always a norfolk boy haven't come across this term before other than on your moniker.
Regards Andy
Well Andy, I do drive around Norwich and Norfolk but that would be in a Company transit van. Whereabouts are you in Norfolk?
Poringland
I'm in Brundall - the other side of the river
A £40m market cap company with declining revenues and basically no future , might take part in the sale of another company that will probably fetch about £600m.
I think the regulator is fast asleep. These announcements from plc’s should not be allowed unless proof of funds is provided.
Hi Paul/Graham thanks for the write ups as ever
RE Fonix Mobile (LON:FNX) I note that this time the have actually lost some clients! but hopefully not a big impact...
· Active customer count at 122 customers at the Year end with additional newly transacting customers, including C4, RTÉ and Wireless Ireland offset by the loss of some small bulk messaging and charity clients. 23 new customer contracts signed in the Year, many of which will start transacting in the year ahead.5
Cab Payments Holdings (LON:CABP) has been in a steep decline since floating at 335p. Entered FTSE 250 on Monday.
Forecasts:
EPS - 2023 20p, 2024 31p
P/E - 12.7 / 8.23
Cazenove has a target of 410p; Canaccord going for 585p
Are investors giving this a wide berth because of the emerging market risks where it does business?
If FTSE 250 moves ahead then trackers will have to buy. Any views?
Paul - the tags are being weird; it is showing Eagle Eye Solutions (LON:EYE) & Warpaint London (LON:W7L) on the sidebar, two companies you looked at yesterday. Strix (LON:KETL) & Fonix Mobile (LON:FNX) are displaying correctly
if you have the time, could you take a look at Springfield Properties (LON:SPR)?
i made a comment yesterday (they released full year results statement) noting that it got battered while other housebuilders all soared, price wise. thanks!
Now don't spoil a good day by letting Bailey out to speak to the press.
'Now don't spoil a good day by letting Bailey speak'
fixed that a bit for you ;)
Haha. This is my favourite quote so far, really it's just a common sense decision, not the destruction of the death star.
"Nick Leeming, chairman of estate agent Jackson-Stops, said: “This might be the dawn of a new era, ushering a hopeful period of stability for mortgage holders.”
lolol
if you/they/anyone wants actual stability for mortgage holders, then i'd suggest having/offering mortgage terms of 10, 20, 30 years...
you know, the amount of time people usually end up living in a house and paying some or all of their mortgage off
can't have that though; that would be a DAWN! of a NEW ERA!
DON’T BE TOO PROUD OF THIS TECHNOLOGICAL TERROR YOU’VE CONSTRUCTED. THE ABILITY TO DESTROY A PLANET IS INSIGNIFICANT NEXT TO THE POWER OF THE FORCE. Darth Norfolk
Don't try to frighten me with your sorcerer's ways, Norfolk.
I find your lack of faith disturbing, Wolf!
You know how Paul said add value? I really think we're doing it :)
You don't get this on advfn.
Darth Vader only uses empirical evidence.
At last a glimmer of hope the B0E is starting to think for itself, not just captured by internal groupthink and their internal economic models. Let's hope this continues. More important than any particular month's interest rate decision.
Regarding stability, I think they need to be LESS predictable on rate decisions. There's an unspoken rule - maybe subconscious - that it is bad to reverse direction or go on a rate path that medium term looks zig zag. It's that rule which contributed to rates being far too low for too long and hence makes the current situation worse.
Hi Paul
You have said many a time that you regard yourself as a good stock analyst but not a good money manager/ portfolio manager. On the basis of your recent chat with Paul Hill in which you indicated your 6x return over the last 10-11 years in your closed SIPP account, I beg to differ on the later point. That is an excellent performance from what I assume to be predominantly UK stocks.
An article by your good self drawing out a few key points as to how you achieved that would I am sure be a very well received by many readers here. Without disclosing £ amounts it would be fascinating to hear about: how much “trading” you do; position sizing on your biggest few winners (and losers); diversification levels over the years ; portfolio volatility over the years.
Obviously, unless you’ve kept great records, then digging around into the trading history on your account could make such a piece a time consuming exercise to pull together, so even just a few snippets from memory would be interesting. Don’t want to distract you from the SCVR day job! cheers
you raise a fair point bert!
namely: those who have realised that a SIPP is actually an incredible investment vehicle for individual stocks (vs the traditional actively managed funds, or more recently, passive/tracker funds) due to it's tax deferred nature + natural long term time horizon i.e you can't access it early barring some well established examples
your main hurdle, aside from having to be a good STONK picker, will be the grossly high charges that UK platforms levy on you for buying/selling individual securities
you see this in the US also. peter thiel and ted welscher (manages berkshire's investments alongside warren buffett and ted combs) did something similar with their 401ks/IRA accounts, to the tune of hundreds of millions/billions
although while welscher was legit and did it properly (he's better than buffett, frankly), thiel was very cheeky IIRC, with some serious loophole exploiting...
Mycelx. MyCelx Technologies (LON:MYX)
Whilst the companies financials look nothing special, it is what they are trying to solve that *could* make this company a multibagger. The issue is PFAS/PFOS which is used in teflon and a load of other products.
As Time magazine put it, this could cost more for the companies involved than the cigarette settlements of a few years ago. North of $200bn. https://time.com/6292482/legal...
The best way to understand the PFAS issue and the potential it brings to MYX is to watch the film "Dark Waters" (2019). Big budget legal movie (in the same manner as Erin Brockovich) about tracking down and going after Dupont. Quite scary. Especially how Du Pont knew back in 1962 it would cause birth defects and cancers after testing on their own staff. As the end of the film makes clear this isn't just a USA issue. This product has been made and used all over the world. The film is currently available on Netflix.
The film is about Du Pont (who came to a $1.2bn cleanup settlement), but the really big fish is 3M, who, have just come to a $10bn settlement to clean up PFOS.
The relevance to Mycelx is that it has started paid trials for filtering PFAS/PFOS in the USA and clearing up existing leaching from landfills. The trials seem to show MYX tech works.
Once the trials are complete and data analysed I would not be surprised if Dupont or 3M or others just buy MYX.
I had heard about MYX before, but it was only when, by chance, I watched the film one night that I was both horrified and then saw the opportunity that MYX had. I knew nothing about PFOS/PFAS before and couldn't believe it.
The main issue with MYX is cash burn. Cash is tight and inventory that can be sold is limited. Can they scale up without a raise ? Or maybe a partner comes in with a strategic stake and cash injection or they just get taken out.
My current thought is that once the trials are complete and data analysed I would not be surprised if Dupont or 3M or others just buy MYX. The water treatment side for the oil industry being used in the middle East is also potentially huge. The latest project enables processed waste water to be used directly in irrigation systems. Would Sclumberger be interested in that ?
Whilst the companies financials look nothing special, it is what they are trying to solve that *could* make this company a multibagger. The issue is PFAS/PFOS which is used in teflon and a load of other products.
Acknowledging that the market is indeed very large but that no one has the definitive and validated answer yet, does MyCelx have a better chance of proving its technology than, say, Veolia, the world’s largest water utility https://www.veoliawatertech.co... Or, to look at research on a much smaller scale, my son’s PhD thesis concerns the removal of chemical contaminants from groundwater using a functionalised cloth (chemical filter), which capitalises on the mutual attraction of charged elements.
This feels to me a bit like buying Zotefoams for their blue-sky recyclable plastic cups. Every relevant participant is trying to find the silver bullet, and no doubt trials are in progress worldwide by numerous entities.
Drip by drip: 6 companies helping to protect the world’s water
MYX is one of the 6
https://www.voxmarkets.co.uk/a...
Mycelx is an interesting company although the financials look pretty awful and they will almost certainly need to raise additonal finance. I speak as an environmental/agricultural chemist and MRSC (although I am now a dilettante farmer). I was not aware of Mycelx until the above posts but my interest is piqued. I think BnB has hit the nail on the head so to speak. The size of the market is not in question, but what is unique about Mycelx?
I am just plowing through their patents and those filed by their competitors; will talk to the RSC Environmental Chemistry Group and talk to some of their customers to come to a view as to whether or not they have something investable.
I would go and visit them, but they don't have an office in the UK. They appear to be a US company which rather raises the question why not list on NASDAQ?
Anyone can read the Mycelx patents for themselves here: https://worldwide.espacenet.co..
...a interesting one for sure.
Tough update from Strix (LON:KETL) today as profitability has declined on all measures.
- customers ordering frequently but in lower volumes
- dividend reduced to focus on reduction of debt
- The £6m reduction in Kettle Controls EBITDA offset the £5.2m contribution of Billi.
There is a CMD to accommpany results (register here https://www.equitydevelopment....) and this includes several new strategic objectives, with a plan to the end of FY26. The goals are:
- an uplift in revenues between FY22 and FY26 of 93% to £206m
- gross profit to £80m, equating to an unchanged margin of 38.8%.
Full note here: https://www.equitydevelopment....
Maybe Strix (LON:KETL) becomes vulnerable to an approach, Volex (LON:VLX) territory? The trade knows Strix make quality products, though might be getting undercut. Opportunity for rationalisation and scale benefits. [I hold neither]
In today's H1 results Corero Network Security
- delivered double digit growth in order intake, revenue and ARR .
- they don't need to come back to the market for more funding and
- have attractive operational gearing.
In our valuation:
- we assume a conservative 10% rev growth rate in FY23/FY24 (below both historical growth rates for CNS AND market forecasts
- We don't factor in any contribution from major new partnership agreements like the one from Akamai which should have a material impact
Our fair value is double the current share price
Full note here: https://www.equitydevelopment....
Presentation today at 11am https://www.equitydevelopment....
Wincanton (LON:WIN)
The pension schemes haven’t disappeared though. So it is possible that in a negative scenario, some future pension deficit payments might conceivably re-emerge. For now though, it looks as if investors can probably forget about this issue, and enjoy the likely increase in divis.
Apologies for being complete skeptic here but is it perhaps not "more likely than not" that the pension company will be back with the begging bowl in 3 years time if the company is making zero contributions in the next 3 years. From experience most of these schemes need continuial top up until the company confirms thats deffo not the case (quite rare) . Obviously they had paid so much in last few years they perhaps deserve some sort of freebie but it strikes me that they are most likely only getting the freebie due to the fact they have paid somewhat excessive amounts for the last few years compared to other similar companies.
The scheme surplus quoted is virtually nil practicably speaking so if i was a gambling man i would gamble on in being more likely than not that the payments would restart in 3 years time (on the basis of other companies doing similar to "break even") . In summary is this not more like a payment break for 3 years rather than situation sorted with regard to "being put on backburner". Looks like this is also what i would call a "large scheme" with assets and liabilities approx £1 billion
Note i fully agree its massive change with regard to the company investibility having the extra cashflow being made available for the next 3 years and i would think it unlikely that paymentys would go back to prior excessive levels. So i firmly agree this is a bit of agame changer here.
Just seems like this company has gone from overpaying to perhaps not paying enough in one fowl swoop - whereas other companies have toodled along paying something sensible. Hopefully if payments do restart in 3 years they will only come back as the toodling variety.
Fair play to the pension fund here grabbing the company fairly by the short and curlies - i never like the thought that companies are paying dividends and the like while not doing the right thing by pension pots - heres looking at you PG.
Rmillaree - you would hope that the Trustees having done a good job getting the fund into Actuarial surplus would now hedge and match liabilities fully.
As long as they do this properly there should be minimal risk of the scheme moving into material deficit again.
If they don’t hedge then agreed they could end up back in deficit but they will likely hedge or sell it. I suspect the latter but let’s see.
No position either way but just a general thought on pension schemes in general
I think the problem here is how liabilities in the future are measured, which bounces around depending upon long term interest rates. A couple of years ago, I wanted to move a final salary scheme into my own SIPP and as part of my calculations set out the potential pension payments over the next forty years and compared it taking the same cash from a SIPP. Obviously the numbers vary wildly depending upon your assumed investment returns compared to inflation. The key financial question came down to the age at which I run out of money compared to my view of the age at which I die. An early death and the SIPP was a good financial decision and a long life, the final salary scheme was perhaps better depending on financial returns. Of course this isn't advice and there are other factors to take into account.
For a pension fund, these liability cashflows weighted up using mortality tables are the numbers that would be interesting to see for a pension fund, how they have changed compared to the previous year, together with the outcomes under different assumptions around inflation and interest rates. But unfortunately everything is hidden by using a discount rate (which is highly sensitive) to turn a multi year cashflow into one liability number.
Depending on the assumptions, these outcomes would be wildly different, really demonstarting that a company should have no business taking on these risks when their employees now have a long life expectancy after they retire.
Of course high inflation probably erodes the value of a pension, (as private pension funds usually have a limit for their annual increase) particularly if you assume that over time investment returns catch up closer to inflation. So I think we are a sweet spot for companies to move their pension funds elsewhere.
But of course, think of the profit margins that the insurance companies have to build in to cover these uncertainties when they offer a buyout to these corporates. That why there are differences in whether these plans are really in surplus or deficit. Who really knows? And that's where my knowledge ends, as I have no understanding of how an insurance company releases multi year future profits to its P&L, but can imagine that there is considerable flexibility, so don't invest in them,.
I would pretty much 100% agree with your thoughts here.
My specific concerns are that even though everyone says high interest rates are good - are pension companies able to get high returns on scheme assets in that period so they are earning enough buck so as to cover reasonably high annual increased. I would have zero faith that genrally speaking these pension funds wil be able to do that so i would alwasy default to presuming further top ups may be needed from the ultimate reponsible party. The f act most companies with these schemes pay in most years suggests that periods of paying nowt and nowt but temporary relief till the the yearly payout start to subside.
What is somewhat scary is that even companies with "very mature pension schemes" still take forever for payouts to dropoff. I hold large (for me) holding in Norcros they have mature (super mature?) scheme with average age of members of 78 and even for that scheme the yearly payouts arent dropping of yet. Hopefully for 78 years olds there is slightly less variability in how long they live - so forecasting payouts should be simple. I view Norcros pension as quite big but the scheme liabilities are less than 1/3 of what Wincanton has so on any risk basis Wincanton still seems very inherently risky as an investment.
James Fisher And Sons (LON:FSJ) Interims today.
Roland commented this time last year "this family-owned marine services group is going through tough times. Today’s half-year results appear to include (another) profit warning and a rather mixed trading outlook. However, I think the foundations are being put in place for a turnaround. I’d be interested to learn more here, as I think there are some attractive elements to this business".
These interims seem IMO to indicate that the foundations referred to are in place and a turnaround is underway with some success, albeit slowly.
Nice to see all 3 divisions recording sales growth. Net debt slightly down. Outlook inline. Profits up or down depending on what measure, but I guess that's what you get in the early stages of a tidy up?
Views welcome. I hold.
The turnaround at James Fisher (FSJ) seems to be well on track judging by the latest interims. Revenues, having stagnated for the last four years, have started growing at a good double digit rate (plus 17%) led by the energy division, the biggest of FSJ’s three divisions, which saw revenues rise 26%.
However, margins and return on capital employed remain pitifully low, and debt uncomfortably high. Marine, FSJ’s traditional business, is the only one of the three divisions to be exceeding the group’s medium term target of operating margins of 10% and return on capital employed (ROCE) of 15%.
The scale of the turnaround needed is highlighted by the fact that in 2018 FSJ’s group margin was 11% and its ROCE was 12.2%. By 2022 group margins had fallen to 3.7% and ROCE was down to 3.9%. At the latest half year the group’s operating margin improved modestly to 5.6% and ROCE rose to 4.7%.
Today’s presentation via a zoom call with analysts was uninspiring. Jean Vernet, the new chief executive, gave a low key presentation and Duncan Kennedy, the outgoing CFO who is working out his notice, is not one of the world’s great communicators.
However, the fact that FSJ’s revenues have started growing again at a double digit, combined with the recent debt refinancing, and the revamping of Fisher’s top management team with a new FD soon to join the relatively new CEO suggests that the company’s long overdue turnaround is finally under way.
The presence on the shareholder register of experienced small cap investors, such as Schroders (9.9%), Aberforth Partners (5.1%), Odyssean Investment Trust (5.0%) and Montanaro (2.9%) also suggests that several serious investors retain confidence in the ability of Fisher’s new management team to turn this company round.
I’d suggest establishing just how firm a number this £4m provision is given how keen the PE buyers of JFN were to leave it with James Fisher
James Fisher And Sons (LON:FSJ) is very much under the radar at the moment. New chairman, new CEO, new CFO. New heads (external appointments) for two of their three divisions. The CEO Jean Vernet seems solid. He espouses 'Lean Six Sigma' which is 'a team-focused managerial approach that seeks to improve performance by eliminating resource waste and defects. It combines Six Sigma methods and tools with the lean manufacturing/lean enterprise philosophy.' I agree a gradual turnaround is underway. There is huge potential upside, particularly as there has been no dilution of the share count. I hold
Re: James Fisher And Sons (LON:FSJ) Interims.
Hello Mark, thanks for commenting on the FSJ interims today. You invite views. Here's mine.
In one shape or form I've been a shareholder in James Fisher for over 20 years. Mostly been a good and very profitable ride from 70p to over £20. Except that I hung on too long. Not for the first time and possibly not the last. Recently I've been selling and now only have a small residual holding.
Why? Put simply its become clear that the recovery will not be simple and quite possibly end up far short of its performance in 2018/2019? The massive pile of debt - quite a lot of which has been self-inflicted is one part of the problem. But recent decisions don't help in my view. Particularly the rushed disposal - without acquiring waivers from the lenders - of the nuclear division for £3 plus £3.5m in loans to a VC who has now placed it into administration where its being wound down. FSJ still retains parent company guarantees against which its just taken another £4m provision whilst it seeks to 'mitigate' the claims?
Also the recently announced Indonesian $100m submarine rescue contract has been awared to a UK firm - not to FSJ , but to SMP Ltd. Some ferreting out reveals that their new management buy-in has been led by the team previously at FSJ! I regard the defence division (formerly specialist technical) as essentially gutted at this point.
With the previous mis-allocation of capital in marine support and then the loss of key staff from EDS, followed by the onerous charter in Energy - and today a futher onerous charter (They chartered 2 ships this year) I have less confidence in management decision making here. And being surrounded by other opportunities where I have greater conviction in management - I've been selling. Quite possibly at the wrong time - but I have to go where I have conviction? Been a big learning lesson for me certainly.
To be fair, I do think that a lot of hard work has been done. I very much hope that they achieve a successful turnaround for the company. I think there is money to be made here by investors - just not mine. I think that getting the margins back up is going to prove quite a struggle and am less convinced that will result in rapidly rising share price back to where it used to be. It's not the same company it was, perhaps more commercial, but also operating in more competitive and commercial markets than it has previously?
cheers
Mark
thanks to all for these views on James Fisher And Sons (LON:FSJ). A good mix of opinions. FWIW I am giving the management the benefit of the doubt, and will be watching for evidence of what illiswig rightly highlights as concerning issues.
See punters favourite Harvest Minerals (LON:HMI) has hit the rocks.
Good luck getting a placing away.
Watched a presentation with the Aussie hot air boss,there were so many questions from private investors, they seemed to love it. This is why I don't believe anything CEOs says outside of an RNS
Next (LON:NXT) raises its guidance for the third time in 4 months. Talk of the death of retail might be a bit premature?
Online Q1 was -1.6%.
Online Q2 was +10%
Just heard on the radio than only 35% of its sales take place in an actual shop.
PS. In the Netherlands, the high streets are booming. Very little empty retail space. The contrast with the UK high street is striking. What needs to be done?
On the continent many streets are full of shops with living accommodation over them which is filled by people actually living there often including families…This gives a local customer base to all of the retail outlets plus added income as the whole of the property is fully utilised…..In the UK we have a tendency to see towns and cities as ‘ Shops only’ and the flats and apartments above are often just empty or run down storage space ….Instead we would rather allow the use of good agricultural land go to the developers and be swallowed by houses or out of town retail parks . We need to change the attitude towards inner town living …While not every bodies idea of the ideal place to live for some such a policy would reinvigorate town/city centres and if successful could make such areas the ‘in’ place to live…..
The issue here is imho vey much lack of action from the powers that be to "encourage" or "force" property owners not to let property lie derelict or unused. Its like a cancer that once a few shops are boarded up then the cycle of decline has started. It would be easy for powers that be to force landowners to make premsies available or take action say after 6 months.
Rather strangely i live in seaside town that was very run down with many shops boarded up in the late nintees early noughties - our town main shopping street is nowqadays thriving with small independent shops - i think they are partly open opey due to the fact the street itself does not now have many boarded up shops. Its a simple principle here that the powers that be simply dont even make an effort to solve what is pretty easy issue generally - if you dont use shop let soemone else use rent free !
In some respects i suspect lessees and landlords alike wouldnt be that unhappy if they cant find a tenant that there was a formal mechanism in place for that building to be used by someone on rent free basis. More action may be needed for really run down areas but your average high street needs firm action to ensure that the street doesnt have continual downward spiral of decline.
The lack of plan up to now makes teh job soemwhat harder than it should have been - its pretty obvious 5 years ago many "shops" open then would not be viabvle in 5 years with move to online sales.
Note online sellers should pick up part of the tab here if costs are involved.
Please could you have a look at CT Automotive (LON:CTA)? On a quick look these results look very good, but I'm aware that it is a "sucker stock" so concerned about the reality. I own a little bit based on the high founder ownership and the last trading statement.
On a further look the negatives appear to be:
Hi Funnymoney,
I had quite a close look at CT Automotive (LON:CTA) here on 16 June 2023, where I flagged that it had refinanced, and had reported a turnaround back into profit, there's a fair bit of detail in that report. I concluded GREEN that it seemed a good turnaround. Very much off the radar though, and people perceive it as a failed IPO. So I'm hoping to get time to update readers on today's numbers (which look good at an initial quick glance) later this morning or early afternoon.
It's very illiquid though. I dabbled in the shares myself, but when I wanted to sell them to buy something more compelling, it proved very difficult indeed!
Regards, Paul.
My morning smallcap tweet: Taking shareholders on a woe trip
Real Good Food (LON:RGD) Light Science Technologies Holdings (LON:LST) Trakm8 Holdings (LON:TRAK) Filtronic (LON:FTC) Strix (LON:KETL) Velocys (LON:VLS) Sondrel (Holdings) (LON:SND) Neometals (LON:NMT) Streaksai (LON:STK), Fonix Mobile (LON:FNX), DFS Furniture (LON:DFS)
◄Real Good Food (RGD)► FY-Mar terrible as expected with rev down 20% and pretax -£9m. Current trading: "demand is higher than last year and despite sales being broadly the same due to cash constraints, EBITDA is better." [SP=1.01 Cap=1m]
◄Light Science Technologies (LST)► gets £210k grant for 3 yrs work on Transformative Reduced Input Potatoes. [SP=2.91 Cap=10m]
◄Trakm8 (TRAK)► AGM stmt - guides FY rev miss but profit in line due to insurance capacity and pricing issues offset by the lower cost base. [SP=18 Cap=9m]
◄Filtronic (FTC)► wins $4.25m contract win with a leading global provider of satellite communications equipment. Expected to be recognised in FY24. [SP=15.59 Cap=34m]
◄Strix (KETL)► FY-June rev up 29% but pretax £6.8m down 41%. Slashed div to 0.9p (2.75p) as it focuses on debt reduction. "The continued macro headwinds have resulted in a reduction in demand in kettle controls in the key export regulated markets of UK and Germany during H1 and a slower than anticipated recovery." Expects short term rev fall within this category. Announces objective of £206m rev and gross profit £80m by end FY26. [SP=90.73 Cap=198m]
◄Velosys (VLS)► H1-June. "Results for the full year are expected to trend in line with results reported for HY1 with an increase in revenue expected to be seen in 2024 following completion of the project funding and as the pipeline crystallises." Cash will last to Dec but completion of the conditional CLN funding led by Carbon Direct Capital will significantly extend the working capital runway. [SP=1.4 Cap=23m]
◄Sondrel (SND)► has delivered prototypes for three ASIC projects. Customer production volume forecasts for these ASIC projects totals US$170m. [SP=14.39 Cap=13m]
◄Neometals (NMT)► gets Australian Patent for the key process steps of its lithium-ion battery recycling process . [SP=22 Cap=224m]
◄StreaksAI (STK)► launches Streaks Idols "a social product and AI character generator which offers a range of customisable AI-powered chatbots capable of sophisticated humanlike interaction". Demo versions include Henry VIII and Socrates. I tried to find these demos but the co's website https://www.playstreaks.com/ has nothing but "We're under construction. Please check back for an update soon." A Mr Bean avatar would suit this recent IPO. [SP=1.85 Cap=7m]
In line: FNX, DFS
Hi MrContrarian
◄Strix (KETL)► FY-June rev up 29% but pretax £6.8m down 41%. Slashed div to 0.9p (2.75p) as it focuses on debt reduction. "The continued macro headwinds have resulted in a reduction in demand in kettle controls in the key export regulated markets of UK and Germany during H1 and a slower than anticipated recovery." Expects short term rev fall within this category. Announces objective of £206m rev and gross profit £80m by end FY26. [SP=90.73 Cap=198m]
Strix (LON:KETL) down over -35% on the open.
I do not hold.
Regards
Howard
Strix (LON:KETL) Brokers cut PBT + eps over 20%
Looks very high risk to me " the Group's net debt increased to £93.1m (FY 2022: £87.4m). This represents a net debt/adjusted EBITDA ratio (calculated on a trailing twelve-month basis) of 2.66x which complies with the Company's debt covenant threshold of 2.75 times"
Strix (LON:KETL) Gone off the boil?
(kettle) chips are down for Strix (LON:KETL) ?
Strix is Billi no mates today
In hindsight, maybe lockdowns caused many people to reassess their home kitchen equipment needs and upgrade things like kettles? (also more money to spend).
Or is this Strix (LON:KETL) weakness more structural - competitor products chipping away at their big market share?
Thanks for letting us know about StreaksAI, MrContrarian.
At last we have a rival to NVIDIA (NSQ:NVDA) in the UK.
Filtronic
Nice 3.4m order from he who cannot be named
That would be either be Elon Musk or Valdemort .
The smart mo day is on Elon Musk .
Unless they ate one and the ssme .
Anyway Filtronic seem to be on a serious roll with sone very well regarded protected technology .
Filtronic (LON:FTC) a recent addition by savvy Mr Staveley to his Rockwood Strategic (LON:RKW) investment trust.
This seems quite an interesting development.
ASOS (LON:ASC)
ASOS plc ("ASOS" or the "Company") is pleased to announce the appointment of
William Barker as Non-Executive Director.
William is the founder and CEO of Camelot Capital Partners LLC ("Camelot
Partners"), a California-based investment management company. William is also
the Executive Chairman of Tapi Carpets & Floors, Executive Chairman of
Synnovia, a UK manufacturing conglomerate and is also a founding investor and
board member of Re:Build Manufacturing. Previously William was an advisor to
Tony Hsieh, the founder of Zappos.
Camelot Partners holds 16,722,381 ordinary shares in the Company, representing
14.02% of the Company's issued share capital. Given William's relationship
with Camelot Partners., a significant shareholder, in accordance with the UK
Corporate Governance Code 2018 William joins the Board as a Non-Independent
Non-executive Director.