Small Cap Value Report (Thu 22 April 2021) - G4M, SOLI, TRI, SFR

Good morning, it's Paul & Jack here with the SCVR for Thursday. Sorry I forgot to put up the placeholder at 7am, so we're running a little late.
Timing - TBC
Agenda -
Paul:
Gear4music Holdings (LON:G4M) (I hold) - another positive trading update, and brokers upgrade forecasts again. I explain why this is one of my favourite "coffee can" (long term hold) investments.
Trifast (LON:TRI) - positive year end FY 03/2021 update. Lots of interesting detail. Looks a decent company, but as with so many things at the moment, recent share price rises mean the price looks up with events.
Jack:
Solid State (LON:SOLI) - full year results to be 'ahead of the recently upgraded consensus forecasts' for this maker of rugged technology parts. Shares currently at near all-time highs.
Severfield (LON:SFR) - full year results expected to be comfortably above management's previous expectations.
Paul’s Section
Gear4music Holdings (LON:G4M)
(I hold)
835p (up 5% at 08:07) - mkt cap £175m
Gear4music (Holdings) plc ("Gear4music" or "the Group"), the largest UK based online retailer of musical instruments and music equipment, today announces a year-end trading update covering the 12 months to 31 March 2021.
To recap, this online business has been putting out a series of ahead of expectations updates over the last year. No doubt a beneficiary of lockdowns, but also a focus on margin improvement has seen a step change in profitability in the last year.
I reported on its last, and impressive, update here on 25 Feb 2021.
Today’s update - is another “ahead of expectations” update.
Two things strike me from the sales table below -
Firstly that Europe & RoW has now inched ahead of UK sales. Is the stock market really valuing this share as a European eCommerce business (and potentially global)? The market cap of £175m doesn’t strike me as aggressive at all, and there could be scope for a re-rating possibly, once people factor in that it’s growing into becoming a potentially global business.
Secondly, these numbers below are really quite small. £78.7m sales in the UK, and similar for Europe/RoW, must only be a smallish market share of large markets. Hence I see much more growth potential - a long runway for continued growth for many years to come, which is a key factor I look for with shares.

.
Longer term growth (all organic, remember) is shown in the Stockopedia graphical history below. Bear in mind that the broker consensus forecasts shown (lighter blobs) are too low. We’ve already worked out last time, that FY 03/2021 was heading for over 50p EPS, usefully higher than the 40p shown here. Also, it seems extremely pessimistic to anticipate that EPS would more than halve to just 21p in FY 03/2022. So I expect forecasts to be raised considerably over time. Although we don’t really know to what extent lockdowns boosted the numbers, and how much was structural, permanent growth.
.

.
EBITDA - the most recent forecast, helpfully provided by N+1 Singer, is for Adj EBITDA of £18.2m, or £16.7m pre IFRS 16.
Today, G4M says it traded ahead of expectations, and will deliver “not less than £19.0m” in EBITDA. Unfortunately it doesn’t state whether this is pre, or post IFRS 16. I’m assuming it’s post, so that means £19.0m actual, vs £18.2m forecast, so it’s a c.4% beat - not bad, coming right at the end of the financial year (FY 03/2021). The latest lockdown will have no doubt helped somewhat.
Revenues - actual of £157.5m, a slight beat against forecast of £157.0m
Gross margin - a revised strategy to go after better gross margins, rather than revenue growth at any price, has worked brilliantly. See the lovely progression in gross margin -
Gross margin improved by 360bps to 29.5% (FY20: 25.9%; FY19: 22.8%)
This may seem a low gross margin (compared with say fashion, which is over 50% usually), but bear in mind that G4M has higher average transaction value, of over £100. Also the returns rate is much lower than fashion eCommerce.
As the business grows, then its biggest controllable cost, digital marketing spend, gradually falls as a percentage of sales, providing operational gearing. This is why it’s so difficult for smaller competitors to keep up - they can’t keep up with the bigger, more efficient marketing spend of the bigger players, so I imagine consolidation in the sector could happen.
Net debt - seems to have been eliminated, moving into net cash. Impressive!
Net cash of £2.4m at 31 March 2021 (net debt at 31 March 2020 and 31 March 2019: £5.5m and £7.5m respectively)
Bank facility - a new £35m bank facility has been agreed with HSBC. This is intriguing, because it’s on a much larger scale than previous borrowings. It sounds as if the company’s ambitions are growing -
As part of the Group's ongoing strategy, the new enlarged banking facility will help us to accelerate our longer-term ambitions. As we lay the foundations in FY22 for the next stage of our growth journey, in addition to establishing new sales verticals, we will further strengthen our European distribution network, accelerate investment into our e-commerce platform, and consider acquisition opportunities as they arise.
Current trading - sounds encouraging, despite tougher comparatives now kicking in -
Whilst it is still very early in the new financial year, we are pleased with FY22 trading to date, relative to the exceptional period of trading during April FY21.
We also remain mindful of the ongoing global pandemic and operational challenges posed by Brexit, but are confident that we have appropriate plans in place to mitigate their effects.
Updated broker notes - thanks again to N+1 Singer, an updated note has just come through. It has upgraded FY 03/2021 by 6%, to 55.8p EPS - at 835p per share the PER is just 15 - surely that rating is too low? It depends whether this year has been a one-off, or is (at least in part) sustainable?
N+1 seems to be assuming that most of this year’s profit growth is due to lockdowns. They helped for sure, especially in Q1 as G4M comments today, but I reckon most of the growth this year might have been structural. If I’m right, then the forecast for FY 03/2022 could be way too low. Singers are pencilling in a crash in EPS from 54.6p to just 20.0p. Although it has annotated its own note (something I've not seen before), highlighting the the FY 03/2022 forecasts with the words “Conservative assumptions....” . Singers is going to re-appraise its forecasts in June. So my money is on a series of uplifts to the very low forecasts as this year progresses.
As I’ve been typing this, another broker update has come through from Progressive. It has a slightly lower EPS forecast for FY 03/2021, of 53.6p. For the new year FY 03/2022, it has 26.4p EPS. Are earnings really going to halve? I doubt it. Personally I think something in the 30-40p EPS range seems more realistic, but time will tell. Put that on a PER of 30, and I think this share is worth 900-1200p as things stand now, with future growth likely to take that higher.
Scuttlebutt - my family are professional musicians, so I pick their brains about G4M occasionally. In a recent discussion, they said that many musicians in the UK have experienced border delays & extra costs when buying things from the EU (e.g. market leader Thomann). Apparently the problem is that, with small imports, there are multiple shipments from many companies, in a single lorry. If any one of those parcels, or pallets, has got the paperwork wrong, then the whole lorry load is held up. So customers have had goods stuck in lorries for a week or two, causing general consternation.
My brother said that, as a result of this, when he is asked by schools, pupils, etc, where they should buy their musical instruments & accessories, he now suggests they buy everything from Gear4Music (he’s not working on commission from me, I hasten to add!). G4M’s speed of delivery (next day on most things), and excellent customer service, plus not having to worry about border delays, make it a no-brainer to buy everything from G4M now, according to my brother.
Border problems going the other way (exporting into the EU from the UK) isn’t a big problem for G4M, because it set up 2 distribution hubs in Germany & Sweden, well before Brexit. It can therefore import directly into the EU from the Far East, by-passing the UK completely, as well as sending bulk shipments from the UK. So G4M should be able to manage these issues better than UK companies with no EU physical presence.
This is set up very well, and has opened the doors for G4M to become a much larger company - I’m thinking in terms of this company being £500m+ revenues in a few years’ time.
My opinion - this is pretty much a perfect “coffee can” share (100 Baggers book by Christopher Mayer, a book that many of us find very interesting & thought-provoking). It ticks all the right boxes, e.g.
- Entrepreneurial management, with lots of skin in the game (founder Andrew Wass still owns 30%)
- Management are good capital allocators & safe hands
- High ROCE
- Long growth runway, in large markets (international)
- Self-funding growth, so no requirement to raise more equity
- Little to no debt, but opportunity to make acquisitions or otherwise accelerate growth using borrowing facilities
Those are all very attractive qualities. That you can buy this share on just 15 times earnings, seems crazy to me. But I’m basing that view on my assumption that the predicted slowdown on lockdowns ending could be largely offset by continuing structural growth. Plus of course remember that physical music re-starting (bands being able to meet up again, gigs resuming), means that many product categories should now see a resumption of growth which was limited by lockdown.
I wonder how many physical music shops are likely to survive, especially after the prolonged shutdowns? Also, no physical retailer can stock the huge number of product lines required to be a one-stop shop, that is only viable online.
Hence my opinion on G4M is that it’s a terrific, coffee can (hold forever) share, and looks good value to me. Today’s update further reinforces my high conviction levels on this share.
As always, I have absolutely no idea about, and don’t really care, what the short term share price does. I’m thinking this is a 5+ year hold, and should be a very much larger business by then.
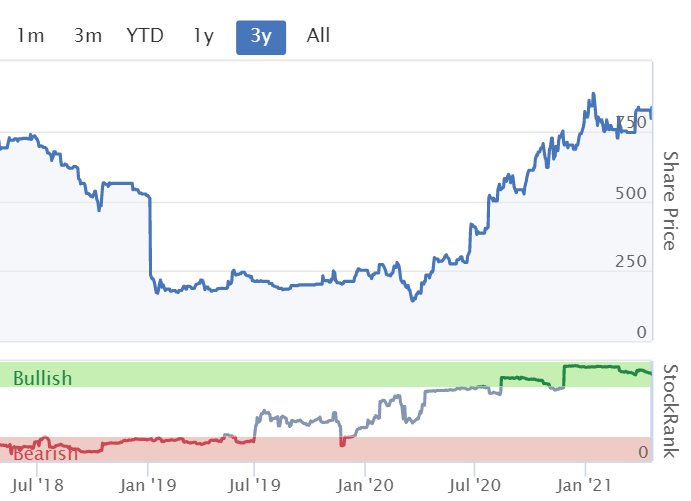
It's interesting to see on the 3-year chart below, how the StockRank system began to move from red, into green, well before the big move up in share price. It must have spotted something, so a dramatic & sustained improvement in StockRank is worth investigating further, I'd say.
.
.
Trifast (LON:TRI)
165p (up 2%, at 11:25) - mkt cap £223m
Leading international specialist in the design, engineering, manufacture, and distribution of high quality industrial and Category 'C' components principally to major global assembly industries …
issues the following unaudited Trading Update covering the Group's financial year ended 31 March 2021
"Our fastenings enable innovation today to build a better tomorrow"
When I think about it, I agree with Trifast that innovative fastenings build a better tomorrow. Or at least a tomorrow where my white goods hopefully won’t fall apart on a 1200 rpm spin.
Trifast’s update today is very similar to most companies reporting at the moment - i.e. a steady recovery in trading, and more-or-less back to normal.
Q4 (Jan-Mar 2021) even saw revenues up >7% on prior year.
Profitability -
As a result of this strong performance, we expect FY2021 to exit ahead of current market expectations on an underlying basis (before IFRS2 presentational changes, as noted below).
Other points -
- Global logistical challenges have continued to have an impact
- Short term margin impact expected from higher priced/shortages of steel - a common theme which does raise the possibility of cost-push inflation in the wider economy, as has been widely discussed by financial commentators
- Cost savings made
- Strong cash generation
- M&A opportunities increase
- Problems with delivery of “Project Atlas” business improvement measures - being reviewed for budget & timetable
Outlook - sounds quite positive to me -
Demand has returned to our traditional end markets and we are already actively working with new and existing customers across a number of new high growth markets, including Electric Vehicle & battery technology, 5G infrastructure and healthcare.
The Group's return to sustained growth since September 2020, in addition to a very strong pipeline and high activity levels across all our key sectors, means we are looking ahead with confidence although, we remain mindful of macro level headwinds including future possible pandemic related restrictions.
Broker update - many thanks to Finncap for a forecasts update note today. It’s predicting 6.2p adj EPS for FY 03/2021 - a PER of 26.6 times, and 7.3p for the new year just started FY 03/2022 - which drops the PER to a still rather punchy 22.6 times.
My opinion - it’s had a great run, but I can’t see why anyone would think it’s worth holding at this valuation, unless you believe it has loads more upside to smash the forecasts.
It’s an OK business, but I think there are probably better investing opportunities elsewhere.
It was interesting to hear Trifast mention growth markets like EVs, 5G, etc. This reminds me of the exposure Volex (LON:VLX) (I hold) has to those sectors, and is seeing strong growth there. I think VLX looks a better bet, as it's on a lower PER than TRI, but strikes me as a higher quality company with more obvious growth drivers.
Trifast's share count rose from 122m to 136m during the pandemic, dilution of 11%. We need to take that into account when looking at the chart. So 11% more shares in issue means that, when valuing the whole company, 200p on the chart before the fundraising is now the same valuation as 178p today. Taking that into account, the share price is now effectively back to its pre-covid level.
Note the high StockRank below - middle-ranking, but almost into the green - maybe it could move into the green zone when broker updates are fed into the system shortly?
.

.
Jack’s section
Solid State (LON:SOLI)
Share price: 879p (+4.64%)
Shares in issue: 8,553,504
Market cap: £75.2m
Solid State (LON:SOLI) has spent much of the past few years as a high StockRank stock, so it’s nice to see the share price finally break out and today we see it at nearly all-time highs.
For pretty much as long as I’ve known it, this one’s been flagged as a Super Stock.
Solid State is a long-standing AIM constituent is a specialist design-in distributor to the electronics industry, manufacturing technology for use in harsh environments. The company has particular expertise in industrial and ‘ruggedised’ computing, along with battery power solutions, communications including antennas and secure radio systems, electronic components and displays.

The group's mantra is - 'Trusted technology for demanding applications' and it specialises in complex engineering challenges often requiring design-in support and component sourcing for computing, power, communications, electronic, electro-mechanical and opto-electronic products.
Established in 1971 and admitted to AIM in June 1996, Solid has made 12 acquisitions since 2002, and is worth considering for, among other things, its long track record of steady revenue growth:

And, while the shares are not as attractively priced as they were six months ago, they’re also not as expensive as a lot of other valuations you might encounter at the minute - particularly when compared to other stocks in the Machinery, Equipment & Components industrial group.

Trading update for the 12 months to 31 March 2021
Solid State expects to announce results ahead of the recently upgraded consensus forecasts, following a final month of trading that benefitted from demand pulled forward and a strong contribution ‘from the two businesses acquired at the end of February’.
These businesses are Active Silicon, acquired for an initial net consideration of just £2.7m on annual revenue of £5.5m (with up to £1m more to be paid in earn outs), and Willow Technologies, purchased for an initial net consideration of £5.5m with a further max earn out of £3.5m. This group has annual revenue of £10.3m.
So at first glance these look like canny opportunistic purchases made from a position of relative strength during the Covid disruption - exactly the kind of event prospective shareholders might be looking out for.
Solid says its new acquisitions have integrated well so far, and commercial synergies are increasingly being realised, ‘with exciting prospects being advanced’.
Since its update to the market on 22 February 2021 trading ‘has continued to be encouraging’, with stable order flow and strong invoiced sales in March, driven by component shortages and customer stocking to mitigate supply chain risks.
We’re seeing this sort of supply chain disruption across different industries as a result of Covid. The question is who’s benefiting and who is scrabbling around paying through the nose for vital parts.
It looks like Solid, for now, is in the former camp. The company comments:
Market conditions across the electronics industry are expected to be impacted by supply chain challenges and component shortages for several months, and customers have been encouraged to pay increased attention to forecasting and adequacy of forward order cover. The Board is pleased to report that we have seen particularly strong order intake post year end to start FY21/22, building confidence in the outlook for the current year.
The group is experiencing shortened customer order schedules and reduced visibility, though.
To this point, Solid State’s open order book on a like for like basis on 31 March 2021 was down year-on-year to £33.7m (31 March 2020: £39.9m) due to the shortened customer order cycles. Including acquisitions however, the order book is £41.3m.
Foreign exchange headwinds are also a factor, but the group notes that this has so far been mitigated by invoicing in the same currency as the supply chain cost. Freight costs are running at a premium to the historical average as well - again, something other operators have commented on.
At 31 March 2021 the group had net cash (excluding deferred and contingent considerations and IFRS16 lease obligations) of approximately £3.1m. A good sign given Solid spent a net £8.2m on acquisitions late in the year.
Conclusion
These are very encouraging results from Solid State and the new acquisitions sound promising.
On that note, yes the share price has been strong recently, but the company has just added around £16m of annual revenues at undemanding multiples, and organic trading is good on top of that.
The group has a long operating track record that gives potential investors good visibility over its past operations, and we can see that it generates consistently good profitability metrics. Although the chart looks like a downward trend, these are ROCE figures comfortably in the teens over time.

The rate of growth has perhaps been an issue in the past, but broker consensus is a Strong Buy and the forecasts are building in some good earnings momentum over the next year or two.
And Solid’s performance over Covid is to be commended - this year exceeds the prior year, which was itself a record. So even after a rerating in the share price, this one could have good longer term potential as a potential Quality compounder if it can maintain growth rates.

Severfield (LON:SFR)
Share price: 81.4p (+7.39%)
Shares in issue: 308,221,462
Market cap: £250.9m
£SEVR has been listed on the Main Market of the London Stock Exchange since 1995 and has a long and successful history of handling steelwork projects across multiple sectors, from the highly complex to basic structural work.
The company also has an established foothold in the developing Indian market with strong production capability.
This kind of company suffers from cyclicality, no matter how well run, and so the first consideration should be the group’s financial health. Severfield does tend to carry some debt but interest payments are typically well covered by earnings.
See interest payments over time and TTM interest cover below.


Revenue took a tumble back in 2013 though and this coincided with an increase in shares in issue. The group made a net loss of £23.1m in this year.


So reading between the lines, it looks like shareholders have had to bail Severfield out before, which is something to bear in mind. To Severfield’s credit more recently, it has maintained a net funds position throughout the pandemic, with plenty of cash headroom and has not needed support under any employee-related government schemes.
And, with the UK economy unlocking, the next couple of years could potentially be a good time for the wider construction sector.
Severfield says trading is good and, based on a strong H2, expects to deliver a full year result which is comfortably above management's previous expectations.
The group is winning high-quality work, with a strong order book of £315m, ‘which supports trading throughout the 2022 financial year and beyond’, and has a pipeline of opportunities in the UK, Europe and India.
In the UK and Europe, Severfield's factories and sites are fully operational and the group has been trading at pre-pandemic levels since the beginning of Q2 of the 2021 financial year. The UK and Europe order book stood at £315m as at 1 April 2021 (1 November 2020: £287m).
A good H2 leaves the group well-positioned with a strong future workload for the 2022 financial year and beyond. 80% of this order book represents projects in the UK, with the remaining 20% representing projects for delivery in Europe and the Republic of Ireland.
Severfield’s Indian joint venture ('JSSL') has continued its recovery after a difficult first half, the company has maintained a largely break-even profit position in H2.
JSSL's order book as at 1 April 2021 was £104m (1 November 2020: £98m), with 90% of that representing higher margin commercial work. However, Severfield is mindful of the ‘evolving COVID-19 backdrop in India.’
Year-end net funds (on a pre-IFRS 16 basis) were c.£4m, representing cash of c.£25m offset by the outstanding acquisition loans for Harry Peers of £9m and DAM Structures of £12m.
Conclusion
Severfield has a long operating track record and proven expertise in managing complex projects. Its sector is inherently risky though, with volatile margins, potentially large and lumpy contracts, and counterparty risks. You only need one or two projects to fall through for the picture to change dramatically.
I would be mindful of the volatility that can be expected from this type of business model, but, interestingly, Stockopedia has Severfield as a Balanced RiskRating, so clearly my caution here is not borne out by the observed share price volatility.
Severfield says it is ‘well-placed to win work in the diverse range of market sectors and geographies in which we operate and across a wide client base, providing us with extra resilience and the ability to increase our market share in the future’. So perhaps it is building more resilience into its operations than it might have had in the past.
And then the more immediate picture, in the UK at least, could be promising, while Severfield’s recent acquisition of DAM Structures brings earlier construction project involvement and significantly strengthens its presence in the rail/transport sector.
Small Cap Cyclical Value has been a good spot to be in recently. Severfield fits that profile, so if you are looking to increase your exposure to this part of the market then this looks to be a well run outfit with some good trading momentum behind it.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

50 comments
I am really pleased to see more references to RoCE in company notes. I am not sure as to why there are sometimes wide variations in company released RoCE and Stockopedia numbers (I noticed a big deviation yesterday, probably on TATE or ULVR) but I think this is a key measure of a company's profitability, if by no means the only one. Lots of fund managers simply don't look at price/earnings ratios now but if you want to understand why RoCE is so important may I direct you to a 16 March 2013 FT article by Terry Smith. I am sorry I can't give you a link to this but the main point is that the RoCE should exceed the cost of capital. And whilst the latter calculation is a little tricky, Smith asserts that 'as an investor you should only be truly interested in companies whose returns are so high that they exceed any feasibly cost of capital". This is not the philosopher's stone but it is extremely useful.
Gear4music Holdings (LON:G4M) (no position)
Here are the updated year-on-year growth rates for those interested,
UK
+18% growth in Q4 (January-March 2021).
Given the +10% growth in Q3, I'm assuming this higher Q4 growth rate is indeed Brexit-related, or maybe it's the pro's buying items before things start opening up again?
On a similar note some might be interested to see this post from Thomann.
https://www.thomann.de/blog/en...
From a little more research it does seem like the UK is ripe for domination unless Thomann deem it worth their while to set up a warehouse in the UK.
Given their size I can't imagine this being a problem for them and my only query is why they haven't bothered to do so yet.
Note that as of a few years ago Thomann claimed to have the largest warehouse in Europe.
https://www.musicradar.com/new...
Europe
Just +11% year-on-year growth in the EU in Q4, despite most of the area being in lockdown.
Q3 growth was a whopping +50% so that's quite a climbdown.
---
I'm personally still not sure what to make of this company. The last financial year has clearly been a good one for them, but those slowing growth rates and the re-opening of the UK make me wonder what will happen in the next couple of years.
I'll be waiting for more details when final results are published.
GLAH
Cheers
A
Looks as though Dignity (LON:DTY) has lost its. The Phoenix 29% shareholder resolutions to sack the incumbent Chairman and replace him with their own nominee were both passed today, albeit only with the backing of a minority of non-Phoenix shareholders.
https://www.investegate.co.uk/...
As a consequence the majority of the non-Execs have resigned and it looks as though the FD is also on the way out after a 3 month handover. An effective way of achieving a hostile takeover without having to pay for the company.
Only been involved in one similar situation when the Bowleven board were removed in an activist coup a few years ago and that hasn’t worked out too well for the residual shareholders. Interested to see whether/how Phoenix better execute this one (I hold a small position).
Gus.
Animalcare (LON:ANCR) I’m still a little perplexed why Animalcare seems to be unwilling or unable to present its investment case to the public. It has just gained EU approval for Daxocox, a drug with a European market that it estimates to be some £130m. At the same time, it has reached a distribution agreement with one of the largest animal health care companies in the world.
Considering that many businesses struggled to survive the COVID pandemic, it had a relatively strong 2020 and appears poised to benefit from the global trend of increased companion animal ownership. Yet it does not appear to use a PR company and rarely presents at any of the events designed to reach private investors. And, yes, I’m a shareholder.
Animalcare (LON:ANCR)
Yet it does not appear to use a PR company and rarely presents at any of the events designed to reach private investors. And, yes, I’m a shareholder.
I know some get wound up by this attitude , i for one find is quite refreshing that some companies simply get on with doing business and not spening money on self publication. You probably do have a point though if they have any need to raise funds for expansion - hey ho the recent chart seems to back up my opinion that letting the numbers speak for themselves should normally do the job (i will pretend i didn't change the chart date range from the default period to much longer timeframe.
Animalcare (LON:ANCR) Someone told me about working on stillness of your mind when I stated that having invested in £KOO , they are so quiet...there is no news, nothing from the latter until TU day and results day. Sounds like Animalcare (LON:ANCR) is in a similar boat. No IR, not much media (at the time), bulletin boards are completely dead.....just stillness.....so let's do it simultaneously ..."breathe and say "ohhhhmmmmmmmmmm with me"....
Re: Animalcare (LON:ANCR)
There’s little point in spending time, effort and money in drumming up the share price unless the company needs to issue new shares and raise capital or the management want to offload their own inflated shares. Lack of investor PR effort is actually a good sign, management have got better more profitable things to do. I hold Eco Animal Health (LON:EAH) which peddles similar wares and also makes minimal investor PR effort.
Hi Paul,
I think your Family comments re Gear4music Holdings (LON:G4M) are spot on, I'm a Professional Sound Engineer by trade, Most of my colleagues are starting to shy away from Thomann as well, since Brexit in January I have heard many complaints re delays etc. Gear4Music provide very competitive pricing and great customer service. I have been using them over lockdown and very impressed. I do actually need to put my money where my mouth is and pick up some shares!
Hi noisyboy9,
That's great, thanks for confirming my scuttlebutt about UK customers deserting Thomann and buying from Gear4music Holdings (LON:G4M) (I hold) instead, since Brexit.
I've decided to bite the bullet, and dump some of my Bigdish (LON:DISH) to raise cash to buy more Gear4music Holdings (LON:G4M) . It's never easy to throw in the towel (partially anyway) on something that hasn't worked, but more important to focus on things with more reliable upside potential, in my opinion.
Regards, Paul.
Given that Gear4music Holdings (LON:G4M) is looking to expand internationally and Thomann is their principal European Union competitor, it would be interesting to hear what continental European musicians think of both
maybe the meme investing crowd will jump on board Gear4music Holdings (LON:G4M) as a trendy cannabis play. You heard it here first.
Just to echo comments, I had a similar experience, was about to hit purchase on my order from Thoman.de earlier this year and noticed a small comment at checkout about VAT, I hadn't given it (Bexit) a second thought until that point.
This is what Thoman and their customers had to say about it
https://www.thomann.de/blog/en...
I found it easier to use a UK supplier in the end which ended up being GAK.co.uk (Vs Andertons & G4M - too expensive, PMT Online - no stock, DV247 - vague about delivery times - as an idea on the landscape on competitors)
Going on that blog entry - well it all gets a bit argumentative on there but it does seem for a large portion of people that Thoman is no longer a viable option.
Hi Paul & Others,
Regarding your comment in Gear4music Holdings (LON:G4M) - It's interesting to see on the 3-year chart below, how the StockRank system began to move from red, into green, well before the big move up in share price.
Is there any way to monitor this sort of change over time? The only solution I can find is to create screens that compare the current stock rank with the previous days.
Thanks
Phil
MGNS Morgan Sindall - I hold - Up 12.8% today..... was today's news that good?
Any thoughts guys?
Perhaps not, but Morgan Sindall (LON:MGNS) is such a quality company and still good value, strong balance sheet and very well placed to benefit from the increased infrastructure spending. Normally would trim on such a rise but happy to let this run.
Thanks, Bouden54 that's very reassuring, so we do not take profits we just hold on.
Love it when a plan comes together.
The results heralded in the Byotrol (LON:BYOT) trading statement this morning were a bit behind my expectations; in particular, net cash was about £1.5m lower than I had projected. Approximately £0.5m of that was due to higher inventories, which is fine. I would like to understand the remaining gap better but will have to wait until the prelims are published to do so.
I haven't had time to update my valuation model yet, but expect it to produce a result close to the current price. That perhaps misses the point, in any case, since my valuation is based on the 18 months following the last published figures, whereas the timeline for Byotrol delivering real value is probably three years plus.
What these results do do is underpin the current valuation and limit downside. Byotrol is a small (<£28m market cap at the time of writing), profitable business with a strong balance sheet. As such, even if it fails to progress as I hope, its downside is limited (or, more accurately, well-protected) at current levels. Upside, if things go right, is perhaps unquantifiable beyond stating that it is highly material.
That's the kind of biased bet I like.
I held very briefly but sold them when the perceived link of covid hanging around surfaces was proven to be largely false so I could no longer see the benefit - which could easily be me doing poor research on their product line. I'll definitely keep an eye on them. Cheers for info.
£BYOT - I expected them to do better in H2....which was probably underwhelming given they smashed H1 out of the park. Therefore rather surprised with the frenzy SP action. I don't hold.
Hi Paul, any chance of reviewing Touchstar (LON:TST),2020 results just announced. To be fair the prospects are all based on the CEO commentary rather than the figures. But its increased cash alot, has no debt I can see and is now making a small profit. IMO its in a very good market coming out of Covid, as helps warehouse and logistic efficiency.
Still be good to have your comments.....
Keep up the great work you both do.
Hi Oaktree,
Re Touchstar (LON:TST) (I hold) after today's drop, the market cap is only £6m, so I thought it would be better not to write up a section in the main report, on something so small & difficult to buy/sell due to lack of liquidity, and below our usual very low cut-off of £10m market cap.
I've held this share for about 3 years personally, and have been slowly watching it creeping back up, to within a whisker of my original purchase price. The company has always seemed to have promise, and it reminds me a bit of Crimson Tide (LON:TIDE) which makes similar products & software.
TST results today are OK - it's moved from losses to breakeven, not bad in a covid year. The liquidity situation looks OK, with a reasonable balance sheet for a micro cap.
My only disappointment today was the outlook comments, which seem to suggest that business won't meaningfully improve until 2022. I was hoping for a faster recovery & more encouraging signs of growth.
Also the commentary today from the Chairman or CEO was quite irritating I thought.
Overall then, I can't see anything to get excited about, so have parked my little shareholding back into the "forget about it for another year, something might happen" tray!
Regards, Paul.
Thanks Paul, useful comments as usual.
It be nice to get our timing right, but thats just not how the stockmarket works much of the time.
Hold the right shares and good things happen though..........in time.
Thanks again
Oaktree
Inspired Energy (LON:INSE) FY20 results presentation just published (from a couple of weeks ago). Mark Dickinson, CEO & Paul Conner, CFO present results for the period ending 31 December 2020, and outline the rational for the rename to Inspired PLC, to better reflect the Group as a technology enabled service provider for energy procurement, utility cost optimisation and sustainability enhancement in the UK and Ireland. Video & Podcast.
Separately, tomorrow, we'll have a tremendous interview with Edmund Shing discussing how to get your kids interested in investing.
No surprise that the only time my 16yr old daughter has asked about the stock market was for Gamestop despite me trying to get her interested in her ISA and SIPP which is actually real. Bloody Gen Z ('shutup boomer' as she would say).
Here are my SCVR heat maps for today (prices as at ~10am).
I share these heatmaps with the intention of giving a visual indication of what is going on in the SCVR world: who’s reporting (and it's impact on the share price); and what’s moving more than 'normal'. There are no associated recommendations, implied or otherwise, just information. How, or indeed if, you choose to use that information is up to you.
Please read my [heat map thread] for more (non-SCVR specific) heat maps, and an explanation of how I use heatmaps to guide me with my research.
I have added a MarCap category to the heat maps, along with a high spread indicator. The key to the symbol heat maps is now:
The heat maps are also now sorted alphabetically by EPIC.
Small / Micro Caps reporting today:
Big movers today in the SCVR world (moving more than a 20d EMA of the ATR against either yesterdays close, or today's open):
Warm regards, stay safe, and best of luck!
greensiax
Very innovative development by the management team at £SDG. Collaboration with Maro Itoje to promote the Sanderson brand ahead of its 160th anniversary. Maro Itoje is a very articulate young man and superb rugby player. Rugby Union and art/interior design are not an obvious an combination, but I believe it will be a successful collaboration for both parties.
I had to google rugby player Maro Itoje, to find out who he is, after reading the Sanderson Design (LON:SDG) announcement (I hold).
I was delighted with my google search results (see below), and am now highly motivated to do some more research! ;-)
Shearwater (LON:SWG)
This is interesting stock for bottom fishers. Must admit i am not really convinced by this company yet - despite having a modest holding here. News today is positive , they are in a "sexy" sector although their use of the phrase "digital resliance" sounds plain stupid to me. My overall impresion here is that there are some cobbled together entities that really aren't making any real profits - however these entities do so some promise - their core market should really be growing so IF they are good at what they do AND can turn a decent margin. Being honest i remain so unconvinced i probably should have thrown this out with the bathwater but for now i am still here and perhaps the company will surprise me on the upside.
Note they have some spare cash in the kitty ready for acquisitions so part of the upside here is the completely unknown brucie bonus's coming our way ref acquisitions - i guess their cunning plan is sdomewhat akin to Judges Scientific - that plan probably doens't help if no real profits are being generated and the shareprice is bombed out.
On the plus side if we ignore depeciation and amortisation the company does make some real cash - its kinda fake in some respects as this income was bought , for anyone who buys now the histroy doesnt really matter as long as what is here now is trending in the right direction. I always like bottom line after tax profit but here i really think the pre amortisation figure is what we should be looking at. Note amortisation is £1.4 milion in H1 so its a bit of game changer whether you use pre or post amortisation totals - one really poor one not so poor.
The stocky numbers of £3.00 million expected for 2022 show that there is some cunning plan for everything to trend in the right direction - i suspect these numbers could be compoletely out of date and may be with amortisation adjusted back out anyway. So i will ignore tis promising number and hope that there is some broker or similar coverage that lets us know what to expect in the future. With companie slike this decent numbers 18-24 months in the future but now now always worry me.
Considering they were 30% down on revenues at the last update, I think they turned in a pretty decent performance to finish nearly level, ahead of expectations, improved balance sheet and paying off deferred VAT. They have a £3.5 million mobile phone contract brought forward from next year as well as some pretty decent clients from earlier in the year. Always a lot of very good initiatives (charities, carbon neutral stance)on their website with an array of industry awards. It's a tough industry but they must be doing something right to get these sort of contracts
Shearwater (LON:SWG)
Considering they were 30% down on revenues at the last update, I think they turned in a pretty decent performance to finish nearly level,
Deffo agreed - my worry here is that this company really won't deliver anything meaningful profits wise - to a certain extent i think the market agreed. I
They have a £3.5 million mobile phone contract brought forward from next year as well as some pretty decent clients from earlier in the year.
In some respects i am not sure if this good news - they previous said we have a good underpinned start to 2020 with this contract - they have now used part of that sum presumbaly to hit current year targets (ok they did beat) - but to the extent that revenues are booked early that good start to 2022 no longer exists. I don't like multiple mentions of the same thing being used for different purposes - we are where we are though and i would always rather book revenue asap - its just not anythuing we didnt already have fully baked into current forecasts and 2022 forecasts should now really be lowered all other things being equal perhaps ?.
Always a lot of very good initiatives (charities, carbon neutral stance)on their website with an array of industry awards. It's a tough industry but they must be doing something right to get these sort of contracts
I know nothing about how genuine the awards are but can you advise whether these are real awards handed out for outstanding acheivment or are they one of those awards where industry insiders make up their own awards and hadn them out to themselves while being pally with themselves and whoever is dishing out the awards - the proof of the pudding here is have the company contributed cash towards ensuring they have received these awards ? - hmmmm
It's a tough industry but they must be doing something right to get these sort of contracts
Yes my hope is that they are not simply getting contrats because they are providing the services at close to cost price to the customer - i want to see real bottom line profits being generated before i am a happy shareholders and these don't exist yet - "here's hoping that will change" as Susan would say.
Hi Millaree. Thanks for your in depth scrutiny of my post:) I'm not going to answer it all by any means. In fact it such a good and valid interrogation I think you should email it direct to David Williams! I have on several occasions. Not that I get much out of him.
The website has a clutter of information. I did find this as an example, make of it what you will:
Pentest’s Research team recently competed at Pwn2Own Tokyo 2020, one of the world’s largest hacking contests. This iteration of Pwn2Own was based around connected consumer devices and participants had two months in which to find vulnerabilities within a set list of devices/software. Findings would then be submitted to the competition organisers, with the most impressive exploits going through to compete at the live event.
Pentest managed to get through to the live event and on November 6th, successfully demonstrated a working exploit of a Western Digital My Cloud Pro Series PR4100 NAS device, earning Pentest a $10,000 prize.
Right at the beginning of the pandemic they offered their services pro bono to a London uni to assist in the development of a covid tracking system (possibly best not to mention that). It seems to me their community spirit is vey much at odds with the suspicion surrounding their competence in takeovers and paying too much.
The fact is their cash position improved last year and again this year, albeit small partly through cost control and running a more efficient business. I like what I've seen of Phil Higgins (podcast) I think he's doing an excellent job. Very competent and expert in his field. I believe they have built a good framework of companies, with one still to be added which again causes investor angst. They stressed they want to buy a good company to add value not a basket case that needs fixing. Fairly obvious I suppose but possibly a reaction to previous criticism. I did ask David about some of the comings and goings of investors, and clearly there has been quite a turnaround. What on earth was accompany like Spreadex doing on the investor sheet? They didn't stay long, but we agreed it was encouraging to see Schroder's take a 5% stake at around todays price I think in January.
Its an early stage company, and like many others the pandemic stemmed their ambitions temporarily but for me the evidence so far suggests they have built a good framework to make something of this.
Shearwater (LON:SWG)
Pentest managed to get through to the live event and on November 6th, successfully demonstrated a working exploit of a Western Digital My Cloud Pro Series PR4100 NAS device, earning Pentest a $10,000 prize.
can't knock this acheivment and some of the stuff on site is fine.
The thing is though sometime some of these awards are more akin to something incestuous rather than any real sign of acheivment - is it any coincidence that when we look at the homepage for the company who dishes ou the "computer security awards" - that the first advert you see on their website at the top left hand is for "Shearwater Group" - hmmm. The fact that they pay for this space bears no rleation to whether they win an award?
look at the following site and see how many of the "main sponsors" just happened to win an award last year - i would be kinda susprised if you can find a sponsor that didn;t win something - lol
https://computingsecurityaward...
Note i am talking generally here and to be fair to whoever puts together the awards process that takes time and effort and needs to be paid for by someone somewhere - an dthe sponorship is entirely transparent on the website.
Note i am not knocking any of the awards - even if its a sponsored event i would still like to thing there is some merit for the handing out of stuff - i am just slightly careful not to highlight this situation as being positive as it can look very much as if they have directly paid to have that badghe even if that is fact from the case.
I take your point. It is a very effective form of PR though. I know someone who won the same newspaper award for 20 years without anyone questioning it. Of course its incestuous. That's how google knows what we want to buy before we do!
These would be a great candidate for Tamzin to get on to hear the management team.
They've spend £60 million on acquisitions and managed to halve the value of them, so hardly value creation! It is a sexy business and not one I know but agree with the latter post that the array of awards they keep winning must mean something. I'm not too fussed about the amortisation. It is after all cash already spent. If they are capitalising development costs that is another matter. £25 million in losses so no tax going to be paid for a while. I've bought some this morning. There is clearly and has been a seller around. I can't see why once they are cleared that 200p plus is not achievable.
You'll never make it as a ramper rmillaree ;-)
You made Shearwater (LON:SWG) sound so unappealing that I felt compelled to have a look!
I didn't get very far.
The stocko profile starts with "Shearwater Group Plc, formerly Aurum Mining Plc"
What kind of madness is that?
Just from a quick skim of the news it looks to me as if this is to a large part an investment vehicle for the chairman David Williams. Who " has over thirty-six years' experience in investment markets" and apparently has been at the head of 15 companies.
Companies house in fact shows him having 52 current or former directorships.
The balance sheet pretty much entirely consists of intangibles.
It's totally beyond my ken to know whether any of this makes sense or not.
Well maybe, but David Williams was involved for some time whilst they were a miner. He increased his shareholding back in April 2015 when he became chair. I can't find reference to when he originally acquired shares but the April 15 announcement refers to him as long term shareholder.
I might be reading this completely wrongly but it puts me in mind of Active Energy (LON:AEG)
(formerly Cinpart, formerly Buckland Group) which is on at least the third iteration of what type of business it is. Which has not been a good journey for it shareholders over the years.
Gromley. Arum mining is a complete red herring. They have no interest in it now. There is still a gold mine from it operating in Spain under a different name, probably making a fortune now! Its quite common practice on Aim to buy an existing bombed out company to takeover and use as a shell company to start up other enteprises. HEIQ I believe did just that tail end of last year. Presumably its cheaper route perhaps than an IPO.
On a slightly different note, the directors have also bought quite a lot of stock. They took a big part in the placing last year and Higgins maxed out several family ISAs a few months back, admittedly by rearranging his holdings rather than buying new stock, but he could have bought other investments you would have thought if not so confident
Interested in opinions on SWG. Finally get its act together?
Broker Progressive Equity Research's free note on Gear4music Holdings (LON:G4M) this morning upgrades FY21 to 53.6p - another upgrade. FY22 has been left unchanged for quite some time now at 26.4p so I am not sure how reliable that is but they're clearly pricing in a small revenue reduction and a fall in margins as people buy other things as society starts to unlock.
One thing to query is looking at the broker note the international growth was at 11% for Q4 compared to 51% for Q3 - whereas UK growth was actually higher than Q3. Is that because of different lockdown situations outside the UK or is it some knock on effect of Brexit - either sales brought forward in Q3 to get ahead of border controls or the new systems are hampering sales? I would have thought it's more to do with lockdowns given Gear4music Holdings (LON:G4M) has European distribution sites but it would be good to probe that.
Q1 was very strong last year with 68% growth so FY22 Q1 might look a bit ugly by comparison which may create a buying opportunity.
(I hold).
The broker forecasts for FY22 are out of date. I understand they’ve been left untouched so I wouldn’t read anything into them. I’m afraid from a broker perspective we are in the dark on that one.
I’m not looking for strong YoY growth. Even Small single digit annual %age growth now has an operational gearing effect and increasingly drops to the bottom line so EPS can go up considerably.
I hold and can’t see myself letting go anytime soon.
https://www.stockopedia.com/co...
Gear4music Holdings (LON:G4M) Balancing Covid-19 boost to longer-term structural trends, valuation updated.
BSV
Morning Paul,
Would you be able to look at Ince (LON:INCE) thank you !!
Elliot
Another vote for a review of Ince. The trading update shows revenues slightly up on the year despite the impact of the early lockdowns on the shipping industry. I thought that was quite a reasonable performance but the price has dropped this morning, so wondering what I missed.
Looks to have made back nearly all of the drop this morning
Looks better. You have to wonder at a world where coming through a pandemic and major economic turmoil merely unscathed is seen as disappointing.
PS I should've mention earlier I hold.
Begbies Traynor (LON:BEG)
Latest Red Flag report out - record levels of distressed businesses.
Phil
We're definitely in a risk-on environment where dire forward looking metrics don't raise many eyebrows :) SP barely moved for the first two hours this morning. FT article comments is full of sceptics playing down this report.
+42% increase of companies in distress in Q1 2020 (pre COVID) to Q1 2021
This itself is a big acceleration on the last quarter (Q4 vs Q4), which was +27.5%
While Begbies Traynor (LON:BEG) has definitely been crying "wolf" for 2-3 years now with its Red Flag report and rising distress that hasn't materialised into huge number of insolvencies. But at some point, these are going to feed through to more business for Begbies Traynor (LON:BEG) even if its not at the huge +27.5%, +42% YoY numbers.
Offers good support for broker forecasts for FY Apr22 of +28% revenues. And note that some of that revenues growth will also be from acquisitions made recently, so the forecast looks a bit low IMO and due an upgrade. In fact, if you look at the EPS graph, that EPS upgrade momentum has already started with Begbies.
(I hold)
My morning smallcap tweet: Gear revs up
Solid State (LON:SOLI) Byotrol (LON:BYOT) Time Finance (LON:TIME) Animalcare (LON:ANCR) Shearwater (LON:SWG) Bidstack (LON:BIDS) Getech (LON:GTC) INCE (LON:INCE) Spectra Systems (LON:SPSY) Trifast (LON:TRI) Severfield (LON:SFR) £G4M0 Touchstar (LON:TST), Starcrest Education The Belt & Road (LON:OBOR)
Solid State (SOLI) guides FY(Mar) ahead of recently upgraded consensus forecasts. Order book £41.3m (inc acquisitions) or £33.7m LFL (£39.9m) reflecting a continuation of shortened customer order cycles. [SP=842 Cap=72m]
Byotrol (BYOT) guides FY(Mar) broadly in-line with market expectations with rev over £11m and adj EBITDA over £1.7m (£6.1m and £0.3m respectively). Co remains highly confident in continued growth in the market, [SP=6.1 Cap=27m]
Time Finance (TIME) arrears below pre-pandemic levels and forbearance down 90% from June 2020 peak. [SP=27.99 Cap=25m]
Animalcare (ANCR) Daxocox (osteoarthritis-related breakthrough pain in dogs) approved for use by EU and UK. Co plans to launch Daxocox early in H2 into an initial addressable European market estimated to be in the region of £130m. [SP=274 Cap=165m]
Shearwater (SWG) guides FY(Mar) U/L EBITDA £3.6 (£3.4m), ahead of market expectations on rev down 4%. H2 rev up 24%. [SP=137 Cap=33m]
Bidstack (BIDS) AGM stmt: FY rev will continue to be significantly H2 weighted. [SP=5.44 Cap=21m]
GETECH (GTC) licence renewals worth £375k. Also new orders worth c.£350k. Confident FY in line. [SP=23 Cap=15m]
Ince (INCE) guides FY(Mar) rev up 1%. Outlook 'positive'. [SP=80 Cap=59m]
Spectra Systems (SPSY) wins $1m orders: Canadian lottery contract and renewal with a long term US lottery customer. [SP=182.2 Cap=83m]. I hold.
Trifast (TRI) guides FY(Mar) ahead of market expectations of rev c.£175m and U/L pretax c.£11m (before IFRS2 changes). "Demand has returned to our traditional end markets and we are already actively working with new and existing customers across a number of new high growth markets, including Electric Vehicle & battery technology, 5G infrastructure and healthcare. The Group's return to sustained growth since September 2020, in addition to a very strong pipeline and high activity levels across all our key sectors, means we are looking ahead with confidence." [SP=161 Cap=219m]
Severfield (SFR) guides FY(Mar) comfortably above management expectations (no figs). Order book of £315m, "which supports trading throughout the 2022 financial year and beyond." [SP=77.8 Cap=240m]
Gear4music (G4M0 guides FY(Mar) rev up 31%, EBITDA £19m (£7.8m), ahead of market expectations. Outlook "pleased with FY22 trading to date, relative to the exceptional period of trading during April 2020." [SP=NA Cap=NA]
Touchstar (TST) FY20 begins with the famous Mike Tyson quote "Everyone has a plan until they get hit", leaving out the crucial "...in the face". If you're a boxer of course you expect to get hit. Rev down 11.5%, above mgmt expectation. Prospects 'encouraging'. [SP=80.1 Cap=7m]
In line: Starcrest Education The Belt & Road (LON:OBOR) [edit] I checked I didn't type the ticker wrong. No, the co is called "Starcrest Education The Belt & Road Limited".